Small Cap Value Report (Fri 12 July 2024) - CRST, TIDE, GFRD. Brief: SYS1, PMI, VANL, ASHM, N91, DOCS, SPR, WKP, BYIT, DPP, IKA, TON

Good morning from Paul!
All done for the day, and the week. Have a lovely weekend everyone!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
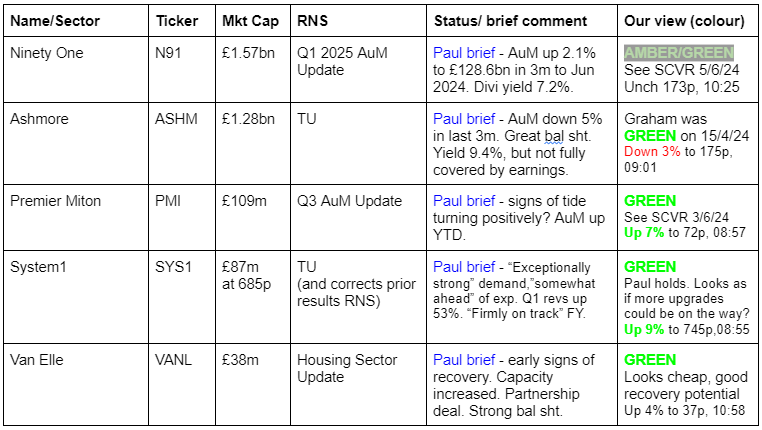
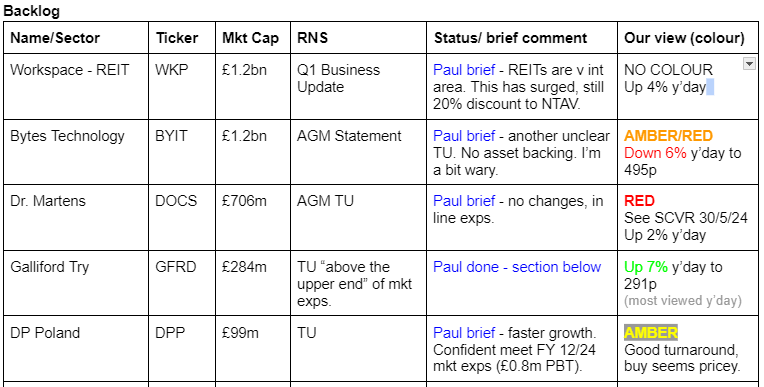
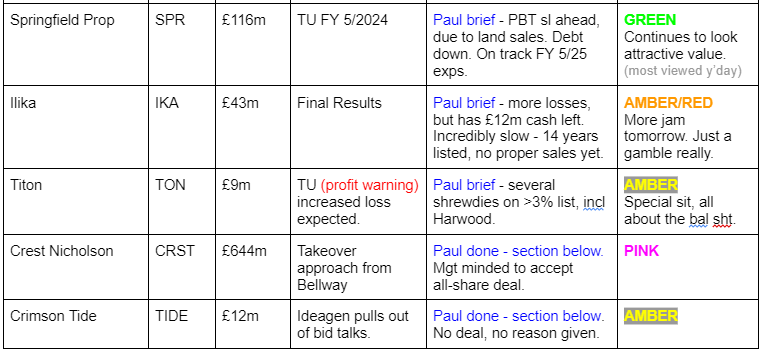
I've set myself a challenge, so see if I can do quickish comments on all the items we didn't cover yesterday - edit: success!
Please note, "Paul brief..." in blue below means that I'm not planning on adding any additional comments.
We're continually tweaking & trying to improve the format of this table below, hopefully people like the changes. It's also really useful for us, the writers, so we can keep track of our work, and prioritise better.
Summaries
Crest Nicholson Holdings (LON:CRST) - 251p (£644m) - Statement re revised (takeover) proposal - Paul - PINK
Looks likely that all-share takeover by larger rival Bellway (LON:BWY) could go ahead, as CRST management have now indicated their support.
Crimson Tide (LON:TIDE) - down 33% y’day to 180p (£12m) - No offer from Ideagen - Paul - AMBER
Takeover talks with Ideagen fell through yesterday, with no reason given.
Galliford Try Holdings (LON:GFRD) - up c.9% y’day (£308m) - Trading Update - Paul - AMBER
Our first look for a while. Good TU yesterday, above top end of market expectations. Very low margins, which it hopes to increase. Cash position is entirely due to favourable timing, with almost nothing in NTAV overall. Ambitious long-term 2030 targets would be bullish if achieved. Overall, I can't get excited, and think it looks priced about right after a big recent rise.
Paul’s Section:
Crest Nicholson Holdings (LON:CRST)
251p (£644m) - Statement re revised (takeover) proposal - Paul - PINK
As usual with takeover situations, forms 8.3 and the like clutter the list of RNSs. Wouldn’t it be good if the Stocko techies could add a button on the news page for each company that gives the option to hide news clutter like this?!
Large housebuilder Bellway (LON:BWY) approached mid-size houseuilder Crest Nicholson Holdings (LON:CRST) about a possible all-share takeover deal in June 2024, which CRST management rejected. Bellway has improved its indicative offer, which is now 0.099 new Bellway shares for each CRST share. Bellway shares were 2644p last night, so that values CRST at 262p (this will obviously vary, as BWY shares change in price).
There’s a small sweetener of a 1p divi that’s already in the pipeline, so not really a sweetener as shareholders would get it anyway, and a 3p special divi on top.
I’m not keen on all share deals, as it can create an overhang of sellers. However, in this case BWY is larger and more liquid than CRST, so it could be a benefit and the CRST element (which has always been accident-prone) could re-rate. CRST shareholders would own 18% of the combined group.
Bellway shares are still at a discount to NTAV, of 0.92x tangible book (per the StockReport).
CRST shares are at a larger discount, at 0.80x, but CRST has had a series of problems, so it makes sense that it would be on a lower rating.
The offer price is a 28% premium to the undisturbed price before deal talks were announced in June.
CRST Directors have confirmed agreement to this potential deal, and would recommend it.
Paul’s view - I can see the logic for this deal, which is subject to various things, so isn’t necessarily going to happen, although I’d guess that it seems likely to proceed. With a chance that a higher competing offer from someone else is possible.
Crimson Tide (LON:TIDE)
Down 33% y’day to 180p (£12m) - No offer from Ideagen - Paul - AMBER
This comes off my pink takeover list, as Ideagen has walked away from talks, with no reason provided.
TIDE reminds us that its recent results showed a return to “operational profitability”, and that it has cash of £2.6m.
Checking those numbers, TIDE made a loss after tax of £(0.3)m for FY 12/2023, improved from £(1.24)m loss in 2022.
Checkit also approached TIDE re a takeover bid with an all-share proposal in June, after previous approaches going back to Jan 2024, which TIDE rejected as being on unattractive terms. I like its balance sheet, which is robust, and included £3.25m cash (and no borrowings) at 31/12/2023. Looks like the cash pile has gone down by c.£625k since the year end, which is concerning.
Paul's view - the mpro5 product at TIDE does look interesting. Management strike me as a little odd. It's been listed for a very long time, and failed to scale up or make meaningful profits.
Galliford Try Holdings (LON:GFRD)
Up c.9% to 296p y’day (£308m) - Trading Update - Paul - AMBER
Galliford Try Holdings plc, the UK construction group, today provides an update on trading for the year ended 30 June 2024. The Group expects to announce its results for the full year on 19 September 2024.
Shares here have had a lovely surge recently, and we’re overdue a look at this one, not having covered it properly for a while.
There’s a positive trend on the broker consensus - although as a very low margin business doing mainly big infrastructure construction projects, profit can be volatile - hence why valuing it on a PER basis could be problematic (PER is better suited to companies with more predictable & consistent earnings) -

Yesterday’s news reads positively, although note that the forecast PBT is only about 1.9% of mid-range forecast revenue. So it wouldn’t take a lot of unexpected costs to badly hurt, or even eliminate profit in future. Do I want to pay £308m market cap for a business that’s only eked out c.£29m PBT in a good year, on c. £1.6bn revenues? No.

Broker update - many thanks to Panmure Liberum, with an update note yesterday. It's raised adj EPS by 3% to 22.2p, a PER of 13.8x. Long-term, it reckons that if the ambitious 2030 targets are hit, then earnings could triple - that's your bull case on this share in a nutshell!
Cash & Balance Sheet - it’s good that they report average month end cash (although average [working] daily cash is the gold standard for reporting), of £155m (with a spike up at the year end to £227m).
It’s worth reminding people that the cash pile comes entirely from favourable working capital timing (getting paid before it pays liabilities). So the net current asset position when last reported at 31/12/2023 was an overall deficit on working capital -

The total balance sheet at 31/12/2023 was £102.3m NAV, reducing to a negligible NTAV of £3.5m after removing intangible assets.
So is this a strong balance sheet? Actually, no. It just benefits from generous payment terms from its customers. This means the superficially great cash position is quite flaky. It could vanish if Govt policy changes, to be less generous in payment terms to contractors. I’m not saying that will happen, just flagging the risk, and that if you’re valuing this share on a low EV valuation, I think you’re making a fundamental error. But it’s open to discussion, different investors see the numbers in different ways.
Targets - this is where it gets more interesting. These latest targets are ambitious, but if they even get close to achieving these 2030 targets, then the share price would surely be a lot higher in 6 years’ time. Trouble is, with plenty of competition, how are they going to win business on higher margins when it's competitively tendered? -

Outlook - it sees plenty of pipeline opportunities. It predominantly operates in public & regulated sectors. Examples are given of projects secured in 2024 YTD (or where it is partly involved so the bigger numbers below won’t all flow to GFRD) -

Paul’s view - I can’t get excited about GFRD, I’m afraid. Very low margin contracting businesses rarely interest me, although as we saw with Renew Holdings (LON:RNWH) (15-bagger from 2010 to 2017!) there can be stand-out performers hidden in the sector. It’s very difficult to find the big winners though, as there’s nothing obvious about them. You only find out after the event that the winners executed well, and did lots of good acquisitions. Meanwhile far more companies in this sector execute badly, and destroy shareholder value. There are plenty that have gone bust over the years. So very much a needle in a haystack type of sector, although I think this sector might be coming back into fashion with some investors - a nice tailwind.
There seems to be a good momentum trade going on here, so it might appeal to some investors/traders.
Balancing up the pros & cons, I can’t get above AMBER, but good luck to holders. It’s trading quite well, has a good outlook and visibility, which has been reflected in a strong share price of late.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

106 comments
"Profitable growth" survey - let's try this again! My original survey on this last Monday failed, since Survey Monkey only allows 25 replies, before it starts charging exorbitant fees! So I've set up a free google form instead.
"Let me know your views on the use of this phrase "profitable growth", which recently we seem to be reading in so many results/trading updates. Which comes closest to your view?"
Options; strongly positive, positive, neutral, negative, strongly negative + your comments box (optional)
Click here to reply to my new survey on the phrase "profitable growth".
Grateful for your responses and comments! I'll publish the results next week after a few days flagging it in the SCVR.
This post is mainly to see if the survey works! Assuming it does, please go ahead and add your replies. EDIT: yes it's working, so reply away! It's intended for Stockopedia subscribers only, so please don't share elsewhere for the time being. I might widen it out later, once we've got all your responses in. Thanks!
Thanks! Paul.
PS. If this survey format works, I might do more ad hoc surveys, as it seems an interesting idea, and a good way to let the City know our reactions to things they do, their communications, etc.
EDIT: It's not collecting your data or email address, this is purely for general interest, with no commercial aspect to it, and is purely my personal idea, not an official Stockopedia thing.
Jet2 (LON:JET2) - article in ThisIsMoney says Jet2 has scored very highly in a customer service report. I followed the link & downloaded the report, which looks bona fide as far as I can tell, from the Institute of Customer Service, available here. (Reminds me a bit of the fictitious "Institute for Studies" that was always quoted in adult comic Viz, when they made up statistics!)
Jet2 Holidays comes 4th top, and Jet2 (airline) comes 14th.
The nearest competitors in tourism were -
32nd (joint) Booking.com 80.7 score
32nd (joint) Premier Inn 80.7
41st Holiday Inn 80.2
43rd Marriott 80.1
No other airlines were in the top 50. Here are the tourism companies in the survey -
Quite interesting I thought, given that I liked JET2's figures on Friday.
Maybe readers could "mystery fly" Jet2 and let us know what you think!
Regards, Paul.
Jet2 are my go to airline. Consistently great service. Helpful and polite staff. Check in is fast and efficient. Aircraft new and clean. Good website and app. The polar opposite to Ryan Scare.
Have flown with Jet2 (LON:JET2) numerous times and have enjoyed Jet2 holidays also. Great service with a smile! Never had an issue and always found their staff top notch.
Won't be long until I can mystery fly Jet2.com - local press says they're bringing forward the launch date at Bournemouth Airport from April to Feb 2025. I love regional airports, Bou'mth is brilliant - 15 min cab ride from my flat, modest queue of about 20 mins for security, then you just wait for the flight in an open area with a pub, couple of shops, plenty of seating, wifi, loos, etc. Couldn't be easier! It's relaxing, unlike the hassle of getting to, and navigating, a large airport. On arrival, no queue, just one baggage carousel, then a short cab ride home.
So I'm looking forward to mystery flying Jet2. The Canary Islands is the obvious destination for some winter sun, but given the "Tourists go home" activism, not sure I'd actually want to go there. Whereas I always feel welcome in Gozo. Some people have even started recognising me when I return, which is nice (OK it's the landlord of the local bar in Xhagra).
Paul.
Hi Paul
Can I recommend Madeira to you as a winter (or all-round) destination? Amazing tropical vegetation at sea level rising to Scottish gorse and heather by halfway up the impressive mountains. The range and beauty of the flowers is unmatched! Funchal, the main town is lovely. Food is cheap and delicious. And the scenery, particularly on the north coast, is wild and spectacular, although beaches are lacking, being basically a huge volcanic rock thrusting out of the Atlantic. It’s not an upmarket destination like Sardinia or Capri but there is very little in the way of high rise developments. Tenerife it is not!
If you can get there from Bournemouth airport, I highly recommend.
Good idea, Madeira's lovely! My 2nd favourite island after Gozo :-)
Jet2 are flying there from B'mth next year I think, so I might add to Jet2's cash pile now and book in advance.
Good idea, Madeira's lovely! My 2nd favourite island after Gozo :-)
For a pint, I’ll let you know my favourite!
Paul I hold Jet2 (LON:JET2) and have mystery shopped them a number of times and they are my first choice. I have just returned from Greece and flew with TUI AG (ETR:TUI1) as their flights were unfortunately £100pp cheaper on this occasion but can confirm there were a numerous full flights going from there with Jet2 (LON:JET2) . The experience was good but not as good as Jet2 (LON:JET2) in my opinion. My daughter is off to Ibiza with them in August (assuming shes sober enough for the flight) and I have returned home to find a letter offering 10% off flights booked by the start of August for up to the end of October so perhaps a sign they are experiencing later bookings as suggested in their numbers.
Stock picking is a probability game.
The whole point of stocko is based around the supposition that if you buy a high SR stocks they will probably do better than picking at random. And the SR history shows this (in the uk).
In the same way the SCVR green ranked stocks are supposed to do better than picking at random. So far this seems to be the case.
My question is whether they beat the high Stock Ranked shares. It looks like they do but it is early years.
To anyone who wants a better picking method, please work one out and tell us about it.
Back in 2011 and 17 I thought I knew better.. ..and both times got it v.v. badly wrong.
My interpretation has been that the SCVR colour coding with a strong focus on balance sheet fundamentals has been very appropriate and successful in the higher interest and other challenging market conditions of the last two and a bit years. The Stock Ranks have seemingly not been as successful in earlier years probably because of the momentum component but that has changed recently so it will be interesting to continue to follow both strategies. I really appreciate and use both in helping me to make my investing decisions.
Hi alkmund,
Interesting point, it will indeed be interesting to see how mine & Graham's value/GARP approach will work in a bull market. Certainly I would expect some more risky shares to do well, and multibag in a bull market, as mentioned in my podcast this weekend. However plenty more will do badly and need more placings, so who knows how it will average out?
I've filtered for orange colour on my/Phil Hanson's spreadsheet, and it shows interesting results. Remember "orange" is a flag that there are significant problems at a company, and hence higher risk to be aware of. It's a warning of higher risk, not a view that the shares will necessarily to badly.
However, it's interesting to see how many "orange" shares have then attracted takeover bids! So maybe orange is also a flag that the company could be vulnerable to a takeover approach, since it's troubled but possibly cheap?
Although look at the full list, and orange seems more predictive for the smaller companies, where orange is often a sign of more trouble to come -
NB. To view the above pictures more clearly, right-click and select "Open image in new tab"
I need to add a market cap field to this spreadsheet.
Here is the spreadsheet itself, so you can copy it & manipulate/add to the data in any way you like. There's probably a lot of useful insights buried in that data, which covers everything we wrote about in the SCVRs between July 2023 and March 2024, so it's not a complete view of the entire market, obviously. If we think something is complete rubbish, we just ignore it altogether, so that could be why most shares are up.
Overall, AMBER/REDs are still positive, but below the other 3 better colours. If you strip out the two stand-outs, MCB and HOTC, then AMBER/RED is flat at 0.4%. So it still works quite well on average, but the results are much better than I was expecting.
So maybe I should be less cautious about balance sheet risk in future, as markets improve? All interesting to discuss!
Regards, Paul.
Hi Paul
Thank you for your very helpful reply and the extra food for thought in it. Even some companies on the red list, eg Synthomer (LON:SYNT) and Dr Martens (LON:DOCS) have had some considerable increases from significant lows, so if/ when interest rates start to come down they may become the takeover bids of tomorrow, assuming that their share prices don't rise fast enough to discourage it. I hold small positions in both for "experimental purposes" only.
Best regards, Alkmund
Hey Paul. Hope you’re having a good weekend. I would be very interested if you could do an interview with Simon Thompson. I know a lot of people do not like his tips as he gets quite a few bad ones but I feel it is a little unfair. I feel his tips give good insight to companies but as you know, no one really knows how a company will perform in the future or whether directors are being honest. No one gets everything right. It would be interesting to get an insight into how he goes about his research. Anyway, just an idea of someone who you could interview if at all it could be done. Keep up all your hard work. It’s appreciated.
Hi gmtrader,
That sounds like it might be a good idea for Paul Hill's interviews.
"I would be very interested if you could do an interview with Simon Thompson."
I want to do more CEO interviews, but we're so busy writing the SCVRs, podcasts, spreadsheets, etc, there just isn't any remaining bandwidth unfortunately.
I met Simon Thompson at an investment dinner, when I turned up already steaming, having been to a previous function, so I can't remember much about him. Other than that he's a quiet & thoughtful man, quite shy. He tends to believe everything mgt say to him, which is dangerous as we know! Comes up with loads of interesting share ideas.
I don't like the whole concept of "tipping", telling people when to buy & when to sell. I've always deliberatively avoided that approach, hence why we just research share ideas here, then firmly throw the ideas over to the readership to research properly and in more depth, and make your own decisions on what/when to buy/sell.
Regards, Paul.
I agree with that about tipping. Too many factors involved. We’ll keep doing what you enjoy doing! Thanks for the reply.
Having spotted the prospects for Renew Holdings (LON:RNWH) bought, held and added for 11 years, I am happy to hold another ‘low margin contractor’ in Galliford Try Holdings (LON:GFRD). Notably the share price is now up 69% since the last amber SCVR review in March 2023. There is going to be a significant amount of spend in the infrastructure sector over the next 5 years and they are a beneficiary of that pipeline. Contractors are normally paid on monthly valuation, which means there isn’t too much cash out at any one time. A sign of this improvement is the ROCE has been steadily improving over the last few years - the ability for a contractor to repeatedly turn that margin over in the year is equally as important as the margin itself.
Morning TraderMArk72,
Well done you, that's a great result on Renew Holdings (LON:RNWH) . I remember it well, discussing it with David Stredder. The bull case was that new management came in, with a strategy to increase the profit margin from a dismal 1%, to 5%. They've actually overshot that, and hit 6.6% in FY 9/2023. Combined with seemingly good acquisitions, that's transformed the company and the share price.
However, none of that was obvious in the early days. Many companies set ambitious targets, and fail to meet them. Also RNWH had a dangerously stretched balance sheet for several years, a long while back (it's fine now), so if anything serious had gone wrong, they would have been toast, or need an emergency placing.
So I'm curious to ask you why you thought the plan would work? Did you meet management? What other attractive things did you see in RNWH, as it never struck me as particularly attractive, so I obviously missed something important!
As regards Galliford Try Holdings (LON:GFRD) I should emphasise that our AMBER view is definitely not negative. It's effectively giving a share a clean bill of health. As I mentioned in a recent podcast, the track record of our traffic lights is that there's not a huge overall difference between GREEN, AMBER/GREEN, and AMBER in performance. It really tails off at AMBER/RED. Therefore the data shows that people should focus on all three categories, GREEN, AMBER/GREEN, and AMBER, as statistically all 3 have done well (from the snapshot of July 2023- Mar 2024 on the spreadsheet put together kindly by Phil Hanson).
Here are the current figures -
Note that AMBER/RED was heavily boosted by 2 exceptional situations, McBride (LON:MCB) and Hotel Chocolat. Take those out, and A/R drops to only +0.4%
The other interesting thing in this data is that companies which warned on profits have overall done OK. This is because many have recovered strongly, and there have been some takeover bids after profit warnings. The larger the market cap, the more likely a share is to recover from a profit warning, is what this data seems to be saying -
How about Yu (LON:YU.) another low margin stock, that has 10 bagged within the last 2 years? You gave it an amber/red rating.
Thanks for that Rusty2.
As you can see from the table above, our colour coding system works overall. Within that, of course you'll be able to pick on individual stocks which have done well or badly. But you can't argue with our overall successful result, as it's fact!
Obviously we're not time travellers from the future, so we don't know how individual stocks will perform. In any case, our reviews are of the facts & figures on a particular day. We're not trying to predict the future. Surprised I have to explain that to you, since you've been around here for a while, but I know you like to have a little dig at me every now and then.
The issue with Yu (LON:YU.) has always been whether or not it will be able to sustain bumper profits once the energy crisis has normalised. You can make your own mind up on that. I remain sceptical, but well done to people who made a nice profit on it.
YU has previously done a boom & bust, have a look at its history (2018).
P.S. I've just checked the facts, and we were actually AMBER on YU the last 3 times we mentioned it, 20/3/2024, 23/2/2024, and 25/1/2024, covering the bull & bear points. Prior to that I was AMBER/RED on 25/7/2023. Check out the archive, I think most people would agree they're balanced reviews, recognising the positives (and the downside risks).
Great work Paul, Graham and the rest of the team. Proven successful results.
It’s inevitable that a red or amber can go on to do well (e.g like via a transformational contract win) and a green to do badly on something like shock new bad news. It’s the subsequent overall performance of red/amber/green shares that matters and not one off specific examples of a red that has done well or a green that hasn’t. I find the colour system a great help.
Yes it is inevitable that some red/amber stocks do well and there are a number however l would not expect a 10 bagger to be in there. Paul said "Note that AMBER/RED was heavily boosted by 2 exceptional situations, McBride (LON:MCB) and Hotel Chocolat. Take those out, and A/R drops to only +0.4%"
I could not see Yu (LON:YU.) in the results. It had already 3 bagged by the time Paul first reviewed it, don't know why it was not reviewed before, it had been covered by others on Stockopedia.
Some very good thoughts. As its a weekend I'll add my tuppence h'appenny?
Yes it is inevitable that some red/amber stocks do well and there are a number however l would not expect a 10 bagger to be in there
I think we differ on this as it's where I'd most expect to find 10-bagger hiding in plain sight.
Why?
Something like half the gain of a 10 bagger tends to come from the re-rating of the earnings multiple. (that was a finding from the Stockopedia - makings of a multibagger )
Or to put it around the other way - to get a 10 bagger (or more) the earnings multiple is most likely to be very low. That doesn't happen without a reason. These companies are riskier than those rated amber or green so great care needs to be taken (not that I always manage that) and there will be something significant wrong to deserve the poor rating. Just not terminal and preferably obscuring the opportunity.
Paul said "Note that AMBER/RED was heavily boosted by 2 exceptional situations, McBride (LON:MCB) and Hotel Chocolat. Take those out, and A/R drops to only +0.4%"
I think this is what I'm trying to say. If you exclude the near 10 bagger - McBride (LON:MCB) - then the rest do very poorly? It's a risky place to be playing if you get it wrong? But the rewards of getting it right (with the right position sizing) can hugely outweigh the costs of those that go wrong?
To pick another example close to my heart. In 2020 MS International (LON:MSI) was generally said to be uninvestable around here, despite having a balance sheet stuffed with cash and property, a history of profits and dividends, long term investment in product development and being buying back its shares at the time..
The stock rank in October 2020 was 19 !
The share price 116p
The reason for the poor sentiment? Directors excessive remuneration, owning more than 50% of the business, lack of forecasts and poor shareholder communications.
None of these negatives necessarily impacted the future potential performance of the company and they aren't entirely negative points - but I wasn't immune to that thinking. They were difficult days. So I bought a lot less than I would have without the negatives - but then without the negatives its highly unlikely the price would have been so low?
The SCVR next covered it in 2022 when Graham took a contrarian more positive view of prospects - with the share price by then at 300p - calling the lack of shareholder engagement 'endearing'.
This week the shareprice hit 1150, officially a 10 bagger?
I'm not advising others to do what I do - it's a much riskier pond to paddle in than the green/amber high stock rank companies. I just happen to enjoy searching through the discards for the occasional flawed gem, though its taken decades and much elbow grease to start to learn to tell the difference?
cheers
Mark
I don't mind at all that companies I invest in are not covered or covered negatively in the SCVR, for me it goes with the territory - and I am always grateful for negative commentary I've learnt to my great cost to pay attention to how others see the risks - they are generally right. What tends to get missed is mostly the opportunity.
Hi Mark,
I'm always wary of posts like this, when people claim we missed a big winner, as often other people's interpretation of what was actually said in the SCVRs are inaccurate!
I've checked back, and as you say, after a long absence of coverage of MSI, Graham wrote a clearly positive piece on it here 30/6/2022 at 300p. It even quotes you! His piece concluded -
"Overall, I retain a positive view on MSI. It has a StockRank of 90, as the Stockopedia computers also find plenty to like"
Next, Graham looked at MSI here on 7/12/2022, with the summary clearly very positive -
"MS International (LON:MSI) (£61m) - excellent H1 results from this very quiet, family-controlled group of businesses. Even after nearly 30 years of consecutive dividends to its shareholders, MSI’s cash balance (£24m) remains formidable as a percentage of its market cap. Today’s strong results (PBT of £3.5m) were achieved without any contribution from the company’s Defence division, which will hopefully be able to make meaningful profits in the years ahead with the help of a large US Navy contract. I love finding quirky businesses like this which quietly do a good job for their shareholders. MSI gets the thumbs up from me."
Shortly afterwards I wrote this on 23/12/2022 -
"MS International (LON:MSI) [quick comment] - more good news for shareholders, with a big contract win announced today - overseas customer, buying an anti-drone gun. It’s £22.4m, expected to be recognised in calendar 2023, so straddling FY 4/2023 and FY 4/2024 by the sounds of it. Revenues in recent years have been between £50-80m, so this looks a material deal. I don’t know what the profit margin would be on this product. If it works well, there could be follow-on sales (this is the first sale of this new gun). Graham has mentioned MSI positively here twice, in June, and earlier in Dec, and from memory I think this one was a mystery share in one of my recent podcasts. After today’s announcements, I imagine shareholders will be holding tightly, with good reason. Thumbs up from me. (no section below)"
Then on 10/7/2023 at 540p I wrote a more detailed review, and picked up some shares personally. Our colour-coding had been introduced by then, and I concluded GREEN.
So it's fair to say that the SCVR has been all over MSI, reporting positively since 300p! (helped by your reader comments at the time, as we thanked you for).
You said it was considered uninvestable prior to that, but I can't see anything of the sort from me or Graham. This piece from Graham on 6/6/2018 seems balanced, and he says it's on his watchlist.
On another point, unlike Graham, I certainly don't find MSI's approach to investor communications as in the least bit endearing. Companies with a listing have a duty to keep the owners properly informed. Instead MSI behaves like a private company, giving out little information. Although there is the issue of defence-related items being sensitive. Although you and other investors I know seem to find a remarkable amount of detail in the industry press, etc. Although what is effectively inside information should be announced by the company to the stock market. And it should be a requirement to issue realistic broker forecasts, for all companies.
But the overall thrust of your post above is that you took a contrarian view of a stock that wasn't covered in the SCVRs, or that we reported negatively on. Yet that's clearly not accurate! As I've shown above, we were positive on MSI as soon as the big defence orders started to be announced at c.300p! Which was the first tangible evidence that its performance was improving, and it's 4-bagged since then. I remain a happy holder personally!
Paul.
MS International (LON:MSI)
Paul,
Ooops!
Now I'm in trouble! And embarrassed!
Huge apologies - if thats not too grovelling :-) because I think we're at cross purposes. Entirely my fault - I can see on re-reading my comment.
It was not my intention to criticise you or the SCVR and I don't think I did 'claim we missed a big winner'?
Could not be further from my intention. What I wrote was:
In 2020 MS International (LON:MSI) was generally said to be uninvestable around here,
'around here' was not code for the SCVR, you or Jack (at the time) as the company was not covered by the SCVR in 2020. I meant Stockpedia more widely. Sorry for not being clear.
The context is important. I mentioned MSI in response to the original poster comment:
it is inevitable that some red/amber stocks do well and there are a number however l would not expect a 10 bagger to be in there
I beg to differ as I find the amber/red zone to be a fruitful place to hunt for turnarounds with good prospects at very depressed prices. Very risky though.
and the OP also quoted you
Paul said "Note that AMBER/RED was heavily boosted by 2 exceptional situations, McBride (LON:MCB) and Hotel Chocolat. Take those out, and A/R drops to only +0.4%"
With which I agreed. As it kind of makes my point? The occasional very high reward company starting from a depressed price transforms an otherwise poor result for the amber/red zone. The combination of outsize upside and position sizing is what Lee Freeman-Shor (very interesting interview with him on Peter/Conkers Investing matters podcast recently but I digress.....) refers to as the 'hunter/connoisseur' combination when a relatively low success rate (30%) but combined with runninng winners leads to successful results. Though to be honest I think he'd have fired me most years :-)
I mentioned MSI as a good example of this. I didn't claim it was missed by the SCVR which wasn't my point - but for the price to be severely depressed then it does have to be widely out of favour - and that generally means investors see problems. Real problems. In the case of MSI that was reader discussions on the SCVR (untagged) and the stocko algorithms which awarded the company a rank of 19 and a style of value trap - aka loser.
It was my intention to point out that turnarounds with good prospects that are out of favour with investors for whatever reason - can allow a very depressed price.
Which is important in the context of a 10-bagger because by the time sentiment and the stocko algorithms catch up a good part of the gain has already happened. One of Eds conclusions from making of a multi-bagger - that a relatively cheap entry is often the case - which allows earnings multiple re-rating to deliver a lot of the upside. The corollary of this is that you have to hunt down amongst companies with severely depressed share prices.
By mid 2022 sentiment was turning. The US Naval tender positive result was first referred to in the July 2020 AR, albeit obliquely, and success and first order of 7 systems was first announced in the July 2021 results. As in a former life I've had experience of winning US DoD/NASA IDIQ tenders I caught the reference and implications a lot earlier than many could. By mid2022 the re-rating was almost 3x - and almost half-way (arithmetically) to 10-bagger, with another 3.33x taking it to 10x this week. If MSI had not been so out of favour (largely of its own making) with investors at the time it would not be 10x now? Same for Mcbride. But I know more about MSI which is why I mentioned it. Not to castigate the SCVR honest! Quite the reverse which is why I quoted Grahams review in June2022. Perhaps I should have been much more positive here - because Graham did catch it very well.
Hope I've been a little clearer this time? Bottom line is as a contrarian I regularly have to go against the 'general view', I tend to spend more time analysing your amber and amber/red ratings - than I do the greens - because by the time its green - if I hold - its confirmation or if I don't I've likely missed the boart? I've never been good at buying into rising prices. I don't often get it right, and I do value all the commentary especially negative - as I am often stepping into places with real risks and should not be feeling dumb, fat and happy when I do?
cheers
Mark
Thanks Mark, that all makes sense now! :-)
Yes I agree, AMBER/RED will definitely contain some potentially lucrative turnarounds, but plenty of dogs too. And lots of takeover bids, so you're right to flag that they shouldn't be automatic avoids, as there will be some nuggets of gold buried in the dross!
Also I think AMBER/RED is more a warning flag that there are higher risks.
It's been a useful & interesting discussion, thanks to all who have contributed!
Best wishes, Paul.
Rusty2,
The spreadsheet which generates the colour-coding scores was set up by my friend Phil Hanson. He selected the dates, from 3/7/2023 to 29/2/2024.
It should show all sections in the SCVRs between those dates.
I've checked YU., and it only appears once, here on 23/2/2024, when we were AMBER on it, at 1335p. It's currently 1680p.
Other AMBER mentions of YU were on 20/3/2024 and 26/3/2024, but those were both after the spreadsheet cut-off date of 29/2/2024, and were also both AMBER.
What I'm perplexed about is that mentions of YU on 25/1/2024 (Roland, AMBER at 1243p) and 25/7/2023 - me A/R at 790p, were not picked up by the spreadsheet. I don't know why, but one possibility is that the transfer of data into the spreadsheet might not have liked tickers with a full stop in them, as I noticed that Fireangel FA. has not transferred into the spreadsheet at all. But there again, why did one mention of YU. get into the spreadsheet, but not the others? I have no idea, as I didn't create the spreadsheet.
None of that would have made a material difference to the results anyway.
As to why YU isn't on the spreadsheet during the period it multibagged? Fairly simple - that pre-dates the spreadsheet start date of 3/7/2023.
You seem a bit fixated about YU! If you read all our articles on it, they're well-balanced - recognising the upsides, but also pointing out possible bear/risks. As we've mentioned here before, riskier shares can occasionally be seriously good performers, once a turnaround happens, or risk factors recede.
YU had a bonanza in 2023, that seems to be continuing in 2024. Can it continue, is the big question mark over this energy supplier? You seem to like it, so maybe you can explain how it suddenly started making big profits during the energy crisis, and why you think that will continue once the market has normalised?
Anyway, that's enough time wasted on this, let's get back to enjoying our weekends!
Paul.
Thanks for the response Paul and the clarification on the colour coding. I meant no criticism. I enjoy reading your analysis as it often flags things I’ve missed. My only comment would be that pretty much every time I read review of a contractor reporting - it always seems to be dismissed on the basis of the low margin - as a Civil Engineer I perhaps take it too personally!
With respect to Renew Holdings (LON:RNWH, I got to know management personally through two subsidiaries VHE and Totty Construction when they were Montpellier Group in the early 2000s and worked on projects with them up to the GFC. My first purchase wasnt until May 2013 and it is the only company I own which I have only ever accumulated and not never sold in that time. I cant recall at the time what the specific trigger was to buy the first position but I suspect it would have been some positive newsflow and my thoughts on valuation at the time on which I took an initial position. I have had seen no reason to sell in that time and still see them adding value.
My background is in contracting, then housebuilding and now land trading, infrastructure delivery and remediation. I have sat on both sides of the fence as part of a contracting team and now employing contractors so perhaps I’m able to pick up on some of the nuances having an understanding of how they operate and staying in touch through industry contacts in my network. You are correct, contractors are low margin, pretty much always have been and rely entirely on regular contract payments and cash turn where things can and do go horribly wrong and they can be cyclical. I often get a sense of this where we tender work. In boom times we get tender declines where a contractor has too much work on to tender and it gets returned. Then there are other times where contractors are calling us to see if we have any work coming out and the tender return is obvious they are cutting their margin to keep the lights on. These are the times the red flag comes out for me and is soon followed by a wider downturn.
My current view is that the macro picture for infrastructure spend is huge and necessary and there are a number of diversified contractors with large exposure to water, rail, highways and energy who will benefit in what are likely to be large value frameworks and contracts with improving margins. I’m more inclined to look forward at these prospects when evaluating them.
Thanks TraderMark72, for that detailed & very informative reply, much appreciated. Just goes to show the value of your sector expertise.
Hi Paul,
I have been venturing outside of my core area of knowledge since October 2023, and looking at Graham and your "Green" shares. I have done more research and applied some basic criteria for selecting a share to buy.
So far I have bought 76 "Greens", all roughly the same amount, and if my stats are correct, you have given 288 Greens (some are obviously repeat Greens), so I have selected 26% of the greens.
I still hold 56 shares, they have produced a 13.8% return. I benchmark against FTSE 100 (always have, I am not going to change now) although I believe you are correct to benchmark against AIM, but had I invested in FTSE 100 at same time, that would have produced a 2.2% gain, so over a 10% point outperformance. So in other words, the Greens I selected have outperformed the FTSE 100 by 6.25. Very happy with that.
Have sold 20 shares, sometimes if they are down 20% (I always sell a share if it goes down 20%), Graham or Paul have moved down to Amber/Green from Green, and on a few occasions because I have a big bill to pay or need to rejig money between my accounts (I don't like more than 85K in one account, a hassle, but if the worst comes, I hope the government bails me out!). These 20 shares have produced a 5.5% return, against a FTSE 100 performance (if would have bought and sold at same time) of 6.5%, so an under performance of 1% point.
Overall, 12.6% return, FTSE 100 equivalent move, 4.2%. I have ignored any dividends paid, but included all trade and stamp duty paid, held shares are mid prices from Google (so if sold would be lower due spread cost and trade cost).
So I am very happy with Graham and Pauls green recommendations, I am also learning about new areas I would not have considered in past, which I think will help me invest more wisely in future. When I get to 12 months of selecting Greens, I will do a fuller report showing what I have learned to the SCVR.
All best,
Orval
Thanks Orval,
NB we never make "recommendations". We're just giving personal opinions, based on fairly quick reviews. It's up to you to then do the clever bit, and do the deeper research on each share.
But as the data shows, on both our 2023 and 2024 top share ideas spreadsheets, both Graham and my ideas have done extremely well both years, beating all indices by a large margin. Let's hope we can make it a hat trick in 2025!
As we go into a bull market though, expect some riskier shares to do well. So there's a fair chance our safety first value/GARP approach might not perform as well in markets that are chasing more speculative, and turnarounds, which often happens in new bull markets.
I'm slightly tweaking my approach (only a little!) to be a bit more generous toward turnarounds.
Anyway, we'll all be geniuses in the next bull market (which has already started), so let's enjoy it!
Regards, Paul.
Sorry Paul, that was a slip/error by me, fully understand that you are only analysing the current fundamentals. Yes I do more research. When I have "skin in the game", albeit only a small holding, I pay much more attention than putting a share on a watch list. I have added considerably to some holdings, notably W7L, I would never have thought of investing in a cosmetics company and glad you marked this Green which drew my attention to it.
As for speculative and turnarounds, I know it's possible to make money here, but to me you need to have much better acumen and insight than I possess, I know my weaknesses. I will stick to companies which have solid balance sheets, think that I can understand the company and market it's in, and operate at reasonable profit margins. I have found over the years that selecting investments is more about avoiding mistakes than picking winners, and that when you make a mistake (and I made quite a few), you eat humble pie, get out, and learn from it.
Paul, Graham,
what you don’t hear so much about is how much you may have made people stop and think about a stock, whether it be one to buy or in some cases one not to buy, based on your forensic views of the fundamentals. There must be a lot of people saved from buying companies where the bad fundamentals especially hidden ones have meant it would/could be a bad investment (especially for novices like me). But you don’t hear so much about that?
I have learned and am still learning so much from you and Graham, so please keep up the good work! Oh, and you also make it fun!
Regards,
Graham .
Good points, and thanks Graham for your kind comments! :-)
Morning Mark,
Like you I purchased Galliford Try Holdings (LON:GFRD) relatively early at around 167P. I top sliced yesterday at 301p, but retain a good size position. The future looks bright but have used some of the proceeds to add to my position in Van Elle Holdings (LON:VANL) which should also be a beneficiary from infrastructure spend and a recovery in house building and construction.
I shall add back to Galliford Try Holdings (LON:GFRD) should the share price retrace a little.
Thanks to yiannos1 for pointing out Synectics (LON:SNX) has been reviewed by Simon Thompson in Investor chronicle. Well worth a read, highlighting it as under valued. It does point out that Downing are winding down their pf and so they will have about 10% stake to sell which could keep the price down for a while allowing investors to buy in. He has put at 280p price target on the share and says even at that price it is still undervalued compared to other companies.
The SP did break out today but only a little and there is strong resistance at current price. Technically it is looking good with a nice cup and handle pattern formed.
if any one is interested in reading the alpha report from investor chronicles you can get an introductory offer of £12 for 12 weeks. And you can cancel any time.
It should benefit Victoria (LON:VCP) Likewise (LON:LIKE) and Headlam (LON:HEAD) As they supply independent retailers.
Personal opinion
But Victoria (LON:VCP) is a zero if you take a moment and study their accounts.
All the best
Agreed Yiannos - every time I have looked at Victoria (LON:VCP) the levels of debt just put me completely off. They somehow have managed to have very high ratings historically and I just do not understand why.
It’s more than that David……
Have a look when you can about the ex banker Geoff Wilding and Qasim Karim.
Enjoy…..
All the best
Now I do not know how accurate this info is, but I spoke to an ex-employee at James Cropper (LON:CRPR) last night, who was a little drunk, and according to him the paper division lost quite a large contract about 2 months ago. I think it was one that supplied Boots. He also mentioned they had layed off with voluntary redundancy a lot of employees. Then he mentioned they had changed the shift rotations from 3 nights to 5 nights and now find themselves short of staff and are now employing back. Sounds like a bit of a mess. As I said though, this may not be that accurate info, so take it with a pinch of salt.
And don't forget... the current CEO of James Cropper (LON:CRPR) used to be the MD of the Paper division over the last few years, which is the division that is performing worst now...!
to be fair, the paper division has always been very low margins, its a very competitive market, hence why James Cropper (LON:CRPR) are very specialized. But it doesn't take much for the paper side to go from a small profit to a loss.
Lots of truths come out when you're a little tipsy!
Pod Point group (LON:PODP) Energy Flex outlined at this week's Capital Markets video & podcast.
Taking advantage of the variable costs of energy at different times of day so customers get cheaper energy, the grid achieves Net Zero and PodPoint generates recurring revenue from their chargers.
Also, we see the new management team.
Huge volume at Made Tech (LON:MTEC). Institutional buying going on here? Recent progress was discussed in a previous SCVR. EV is only £20m against a mkt cap of £28m!
A read across from TPX Impact results:
"The current pipeline of new business opportunities is robust and despite the phasing effect of an early General Election, has not diminished the appetite for the digital transformation services"
Made Tech (LON:MTEC). One im looking to top up on - A lot of people are looking to the housebuilding sector to take advantage of labour coming in, I believe Made Tech (LON:MTEC) has even greater potential to make huge profits on new contracts.
Carpetright at risk of going into administration.
Any risk to Likewise (LON:LIKE) or Headlam (LON:HEAD) ? Do either have big trade exposure to Carpetright?
Likewise (LON:LIKE) I am pretty certain don't. Headlam were chasing this type of distribution to SCS and Tapi etc but Carpetright had their own major distribution centre. Unless Headlam manufactured for them which is highly unlikely. SCS I believe are withdrawing from flooring.
Live on Vox Markets at 10am Monday (15th July), I will be interviewing legendary UK small/midcap fund manager Gervais Williams of Premier Miton Investors.
Here we're planning to cover lots of fascinating stock ideas including: #CMCX, #YU, #ZPHR, #SUP, #ELCO, #IHC, #GFRD, #LORD, #CML, #CYAN, #CNC many more.
Alongside of course, trying to answer any questions that you might have.
So please feel free join us here on Youtube. Everyone is welcome.
Lots to discuss – including post match analysis.
I notice from looking at the Stockopedia Chart view for MS International (LON:MSI) that a very large share sale spike appeared yesterday. I’m on my phone so I can’t see what quantity it represents but it looks significant and yet the share price has responded with a sharp upwards move coincident with the sale.
I’ve not ever seen this before - usually a large red spike on the chart coincides with a reduction in the share price as one would expect.
I’m curious if anybody else noticed this or is able to explain the anomaly?
MS International (LON:MSI) Sharepad has the 300k trade as unknown it was a mid price 1100 with bid 1070 offer 1105
RNS yesterday afternoon:
https://www.stockopedia.com/sh...
MS International (LON:MSI) bought 300k of their shares from 'a shareholder' at 1100p and placed into treasury to satisfy future options.
Has the effect of reducing future dilution and is earnings enhancing in future, financially positive if you expect the share price to continue to rise, and by saving dividend on the shares in treasury.
If the shareholder was selling into the market in small quantities then it also significantly reduces shares on offer in the market - the rise in the shareprice might seem to signal that?
cheers
Mark
Thanks Mark. Every day is a schoolday:-)
A disappointing quarterly update from Ashmore (LON:ASHM) today.
Looks like a copy+paste of the usual from the last few quarters... investors pulling out money... investment performance struggling in absolute terms, but still "ahead of benchmark/industry".... commentary is the same broken record "EM is exceptional value, tide will turn..."
The interesting thing is that the SP drop today so far is very muted, suggesting that maybe all the bad news has been priced in?
I am a suffering shareholder... but at least have had some chunky dividends to temper half my capital losses so far.
Hi is there a place in stokopedia where you can find good volatile stocks for spread bettin on day/week trading timeframe
Hi Rajeshver. If you go to Browse and then select Risk Ratings, and look at those stocks rated as Highly Speculative, that’s Stockopedia’s proxy for volatility.
A general question. I do some software based API trading with Alpaca Markets in the US, the ability to manage positions and set stop losses is outstanding. I hold a small portfolio in here, but I'm seeing great results pulling screens from Stocko or momentum screens and automating the stop loss and position rotation.
No UK brokers seem to have a working API, but are there any with tools such as trailing stop losses which don't expire or a decent way to automate trades? IBKR support trailing stops, but there appears no way to automate them and they get cancelled when corporate events occur (e.g. dividends). The same with Interactive Investor and again you need to set them up by hand on individual positions.
The IBKR API simply does not work (I've 20 years experience with API integrations and this is, I think the only place I've failed with an API ).
Equally I struggle to get data out on an automated basis to report on things.
Overall I feel like the biggest barrier to growth in my trading and investing is the platforms ability to manage positions and automate purchases and sales. Compared the US market where there are loads of options this must be damaging liquidity in the UK market.
Has anyone found a better way to manage things?
Share Centre had some great tools for setting limits but unfortunately their more sophisticated tools were ditched when they were taken over by Interactive Investor
For IBKR, have you looked at this https://groups.io/g/twsapi
I do not want to use the API to place trades. But it certainly works for streaming real-time positions and margins data into Excel.
Wow ROSEBANK INDUSTRIES (LON:ROSE) share price rise is a bit of a joke!
£50m in cash and now valued at £120m so if you are buying here you need management create 150% of value before you even start getting your money back! Who on earth is buying at these prices?
Yes the rise is staggering. At this price - and with no target / deal on the table, it’s just a punt, and as was said the other day on the board, they’ll tap the markets for more cash once / when they find their first acquisition. The team involved certainly don’t need the money, and are well over the age where they could sit back and count their cash. I’d think of it as a little flutter in preparation of putting more serious cash in once they find something to buy.
Are the management team worth the premium? Who knows. I remember the days of Wassall, where most of the ex-Hanson team got together. They did extremely well, then sold up and started £MRO.
For those interested in financial history, this makes a fascinating read: https://www.encyclopedia.com/b...
Or you could just buy Avingtrans (LON:AVG) - similar in ethos and much cheaper!
Kistos Holdings (LON:KIST) did similarly (bagged) before their first deal (CEO previously had public market success and grew and sold Rockrose Energy (LON:RRE^I20) ) and ofcourse the huge temporary spike in gas prices due to Russia's invasion of Ukraine.The tech entrepreneur Vin Murria took a substantial position in a shell a few years ago and the shell company multibagged before any acquisitions too.Great short term trade for those willing to take the risk.Shame Martin Sorrell hasn't repeated the trick so far for S4 Capital (LON:SFOR) holders.
Interesting to see Beeks Financial Cloud (LON:BKS) starting to motor. I suspect this may just be a rise into the results and will lead to some selling post results mind. I’m expecting in-line with some good growth but I’m unclear as to why people are buying now. It could be that they are expecting the large new contract subject to regulatory approval being ratified but frankly that will happen whenever the regulator gets to it and then they will need to announce so I doubt there will be any more colour than already provided in the results.
Anyway not complaining about the rise - I see Beeks Financial Cloud (LON:BKS) as a great growth story so moving back towards all time highs is good news. Let’s see, maybe I’m wrong on it being a pre results rally.
A few have mentioned the update being earlier then usual, suggesting maybe there is something important to share.
Thanks Ben - I’d be sceptical about that personally. Under MAR rules anything price sensitive needs to be released immediately so they can’t hold anything back unless they time a contract signature to be same day as an update. I wonder if people might be disappointed if nothing new arises then. Not that it changes my fundamental view either way.
Could always be fomo.Happened with On Beach group (LON:OTB) earlier this year going into results.Beeks Financial Cloud (LON:BKS) is a popular share currently with eyes on it and its share price imo.Not suggesting obviously results aren't good or the company isn't good.
As its a slow Friday, here's a plug for a Signet group that I'm part of, in case anyone is interested in joining!
Signet is a group for private investors to learn, network, and get support from other PIs. They run regular in-person and virtual meetups across the UK.
I joined recently, and have just been to my second Signet meetup. I've found it very useful, to connect with other PIs in person. You can get feedback on your share ideas, discover new ones from others in the group, and there's usually an in-depth topic or presentation each session for learning.
The group meetup that I'm part of is new, having formed only 3 months ago, and probably could accommodate one or two more joiners. We meet Wednesday evenings in central London near Piccadilly Circus, once a month.
If you're interested, send me a message on Twitter (my link is in my profile), or contact Signet directly via their website.
Hi Boon
I am a member of Sharesoc and your post has prompted me to join Signet. The monthly Wednesday evening meet up in central London would suit me and once my membership details come through I will endeavour to join the group.
All the best.
I'm a member but was shaken out of attending during covid. London evenings are good for me too.
Van Elle Holdings (LON:VANL)
Further to my post in reply to planetX earlier this week on the company and my view that it is too cheap, despite the malaise in the housing and construction sectors and their potential for recovery, this mornings announcement by Van Elle Holdings (LON:VANL) makes interesting reading. The company will be an early beneficiary from the recovery in house building when it arrives and given the new Government's narrative it surely must be on the near term horizon.
I hold having bought a good sized position at the current price. Richard Staveley at Rockwood also believes that it is too cheap and holds 5.6% of the company according to the recent investor meet company presentation. Time will tell if I am correct.
"Van Elle Holdings plc, the UK's largest ground engineering contractor, announces a contract award, a new strategic collaboration and completion of an investment in its precast pile factory.
Contract award and strategic collaboration
The Group has been awarded a scheme by Keepmoat at the former Boots site in Nottingham, reflecting its balanced exposure to partnership housing alongside open-market housebuilding. The scheme is worth up to £3m across several phases and is the largest single scheme awarded to its Housing division in the last 12 months. This will be the 15th project over the last three years that Van Elle has delivered for Keepmoat.
This project will create a blueprint for a new strategic collaboration between Van Elle and M&J Evans; the UK's largest groundworker in the housing sector, with a complementary, national capability. Under the agreement, Van Elle and M&J Evans will work closely together nationally on a customer-led basis to offer a more efficient, joined-up delivery model for housebuilders.
Investment in precast pile factory expansion
The Group also announces it has completed a capacity expansion project at the precast pile factory at its headquarters in Kirkby in Ashfield, Nottinghamshire. The expanded factory, which is capable of 24-hour manufacturing and utilises low carbon blended concrete mixes, sits alongside the Smartfoot precast beam factory. This investment increases production capacity by over 30%, positioning the business well to benefit from the expected growing demand in the housing sector over the mid-term.
Chief Executive Officer, Mark Cutler commented:
"We are encouraged by the new Government's commitment to accelerate the delivery of newbuild housing. We are ready to support incremental demand with our expanded capacity and breadth of expertise, including our precast modular Smartfoot foundation solution, which offers proven benefits compared to traditional methods. Although we anticipate housebuilding volumes to remain subdued in the immediate future, orders in Housing for the year to date are up 20% compared to last year. We believe the Company is well positioned to play a leading partner role with a range of blue-chip customers, with whom we enjoy high levels of repeat business."
You beat me to it! I too bought some Van Elle Holdings (LON:VANL) recently - a return purchase, having held them some years ago and concluded there was no catalyst for growth.
This is striking isn't it?
Although we anticipate housebuilding volumes to remain subdued in the immediate future, orders in Housing for the year to date are up 20% compared to last year.
That's a significant increase, in advance of any impact on housebuilding from the new government's policies. I am anticipating a cyclical uplift for Van Elle Holdings (LON:VANL) especially in 2025 and 2026.
Van Elle Holdings (LON:VANL) I hold too. Van Elle has the highest Stockopedia ranking of Rockwood's 20 current holdings just lacking on the momentum score although that might now be picking up.
Edit: Being a bit of a Richard Staveley fan boy I keep a Stocko Folio with Rockwood's stocks in. For interest they are Van Elle Holdings (LON:VANL) Galliford Try Holdings (LON:GFRD) National World (LON:NWOR) Capital (LON:CAPD) Trifast (LON:TRI) Flowtech Fluidpower (LON:FLO) STV (LON:STVG) Argentex (LON:AGFX) Pressure Technologies (LON:PRES) Hostmore (LON:MORE) Titon Holdings (LON:TON) Restore (LON:RST) Centaur Media (LON:CAU) Funding Circle Holdings (LON:FCH) Filtronic (LON:FTC) M&C Saatchi (LON:SAA) James Fisher And Sons (LON:FSJ) RM (LON:RM.) Pennant International (LON:PEN) Capita (LON:CPI)
Speaking for myself life is too short to be in your list Peter T, in the Past most of it has failed my input. There has to be better than this out there and so there is.
Silver
Good morning Paul and Graham, I can see you've got Ninety One on your reporting list, we hold and if you get time Graham I'd be interested in your reaction to today's update stating AuM have risen by £2 billion since March. You gave it Amber/Green on June 5th.
I hold Ninety One (LON:N91)
Hi Charles,
I hold Ninety One (LON:N91)
And... ?!
What do you think about it then?
Regards, Paul.
Hi JASVFS,
With it being a Friday, Graham's off (he does Mon-Thu), so Sod's Law three fund managers publish updates today! I've just had a quick look at each, referred back to Graham's previous notes, checked their figures on the StockReport, and given a brief comment in the "companies reporting" table above, so that will have to do for now.
I was thinking about lowering ASHM from green to amber/green, but didn't want to break the consistency in Graham's absence. We can ask him on Monday if he still adheres to his previous views. Also when I checked ASHM's superb balance sheet, and very high yield (although not now fully covered by earnings), it still supports a green view, although the continuing fund outflows is a worry.
Regards, Paul.
Impressive Q1 results from System1 (LON:SYS1) with sales up over 50%.
I am reminded of an “illustrative” slide from their Feb 24 Capital Markets day where System1 (LON:SYS1) projected the operational gearing effect of doubling their sales thereby quadrupling their EBITDA.
Not many companies would be confident, or rash enough to float this possibility, but SYS1 were. I agree with Paul that further upgrades are likely.
It is the classic example of the "SaaS" business model; that the platform/data has a fixed cost, and every additional subscription just has the revenue flowing to the bottom line.
Now, it doesn't work quite as simplistic as that... there's Biz Dev, Sales, and Marketing costs. All of which increases when you start to chase the normal clients after the enthusiastic early adopters. Each incremental new client costs more to acquire than the previous one, usually.
And you could say that System1 (LON:SYS1) has moved on from the enthusiast early adopters, given that it was 5 of top 10 USA advertisers already (I think I remember that correctly?)
Indeed, management allude in last update they need to recruit heavily, to keep up the client acquisition growth.
-------
Still, very impressive growth numbers still, probably one of the best growth stories at the moment in the UK market?
(I hold in the Boon Fund)
Ugh !! I sold System1 (LON:SYS1) about 2 years ago when they were £2 and warning on profits continuously. Not a large position then but annoying to see it up almost 4* since nonetheless ;-)
Looks like a good growth story - will have to see if it dips and I might revisit
Commiserations on System1 David, we don't hold but my friend Maynard Paton does, you might find his Q2 portfolio update interesting on his website.
I liked Maynard's recent in-depth post on System1 (LON:SYS1) . He thinks it could go to 1500p...! And that was before the latest numbers were published, so he might be even more bullish now...
On the flip side, an ex-management ex-insider (now disgruntled) with a big stake, Stefan Barden, sold 2% at like 500p in June? So even those with superior knowledge can't accurately predict what the current value of the company should be...
Thanks JASVFS - I will take a look. Unlikely id buy here but you never know on a drop
System1 (LON:SYS1)
Ugh !! I sold System1 (LON:SYS1) about 2 years ago when they were £2
thats always the a tricky one - companies that are moving from doing not alot to delivering what has promised as the golden land. Sometimes it takes longer and sometimes its simple false promises and sometimes they get lucky and hit a purple patch and end up back where they were (loopup !!). all we can really do is watch like and hawk aned act accordingly - but the reality is its all guesswork as to whether a company will deliver the promised land or not. Its always easy looking back with hindsight to say i always knew they would come good (or not).
IMHO thats were stocky comes in very well providing differening range of opinions so that hopefully we have some useful logical (or not so logical) thoughts laid out to give us a chance.
Van Elle Holdings (LON:VANL)
Very positive update from Van Elle this morning, there is clearly a big seller there but a lot of shares have been changing hands yesterday and today.
A new collaboration with M&J Evans, an existing collaboration with Galliford Try, major capex to boost capacity by 30% completed but best of all housing orders up 20% year on year and I think this is only the beginning of a new cycle in housing starts.
Combine all of that with Director buying, net cash on the balance sheet and an EV/EBITDA of about 3x it starts to look pretty compelling.
I know Jonno likes it, i've also been buying, just thought I would put it out there......
Quite something to see the UK, especially Small caps , up strongly yesterday while the Nasdaq got battered. I think most investors have been conditioned to think this is is literally impossible over the last few years. A period of outperformance for UK small caps would lead to a lot of inflows. A perfect trifecta of low valuations, an improving economy and falling interest rates is within reach !
Yesterday's comments section included a debate about "crystallising" SIPPs, putting them in part or whole into "drawdown", and the approach to how and when to take 25% tax-free lump sum entitlements. Apologies: I'm not sure of how to post a link to the actual discussion but a long thread developed from a posting by Michael C yesterday @ 11:34 am
Interest in crystallising pensions has, in part, been prompted by anxiety that the new government might potentially seek to: (i) re-introduce the Life Time Allowance ("LTA"); and/or (ii) reduce the 25% tax-free lump sum (currently capped at £268,275, its real value being eroded by inflation going forward).
How serious a threat is this? During the run up to the election there were soft assurances that neither would happen, well certainly not immediately. Who really knows and for those with SIPP balances exceeding the old LTA limit this a material issue/risk.
Unfortunately, most internet brokerage SIPP product providers insist that that the tax-free lump sum is taken at the point of crystallisation - resulting in funds leaving the tax-free wrapper and becoming liable to income tax/CGT but also coming into scope for IHT. So, sub-optimal unless there is a pressing need for cash, such as repayment of a mortgage.
An alternative offered by some brokerage SIPP plans is to take Uncrystallised Funds Pension Lump Sums ("UFPLS"). While flexible that requires you to not only take the tax-free element but the 75% balance which is immediately taxable, so not great if you continue to work and are a higher rate taxpayer. The remainder of the fund also remains uncrystallised so no preemptive action to defend against (i) and (ii) above is actually taken.
Taking the 25% tax-free lump free sum isn't a mandatory requirement and many unit-based/insurance SIPP providers offer more flexibility, allowing the 25% to remain invested until such time that an income is taken from the drawdown account or it is accessed via UFPLS. While Curtis Banks/Suffolk Life allows 25% deferrment for holdings of its pre-2020 SIPP product this doesnt apply to all its range, and Hargreaves and AJ Bell have a policy that required the 25% to be taken upon crystallistion (no doubt the alternative giving them operation and/or administrative challenges and additional costs).
Is anyone aware of a self-select brokerage SIPP product which allows the flexibility of deferment of the 25% lump-free sum? I posted a similar question in the brokers and service proviers section yesterday (see >>>>> https://www.stockopedia.com/co... ) but thought it worth re-posting today given the debate in the SCVR comments yesterday.
Appreciate any suggestions, and thanks in advance, and everyone enjoy the weekend which looms into view.
If it helps - my wife is with HL and has earlier this year taken the crystallised route to drip feed the tax free sum so don't understand the confusion here.
My understanding from watching some good youtube videos on this subject is that there are four ways to access your pension. Take the whole lot out and get 25% tax-free (daft).
Take the 25% tax-free in one go, not the best option.
UFPLS, you decide how much you need each year and 25% will be tax-free, 75% taxed.
FAD, you decide how much you need each year and take the amount out which will be tax-free but an amount four times that will then be placed in drawdown, and you keep doing that until all the pension is in drawdown, and then you start paying tax.
FAD is more tax efficient to begin with, but you may end up paying more tax later on than with UFPLS.
Most take FAD. I intend to.
The cash you can take at 0% tax is now limited to 268k and likely to stay that way (at least not likely to be more generous).
You pay a marginal rate X% now.
What do think your marginal rate will be in the future? - significantly higher or lower than it is now?
Worth thinking about. But... easy to over think.
I have to make the decision in a couple of years and will probably go for FAD. I should remain a normal rate taxpayer throughout, unless my portfolio does really well, and I want to draw more out.
Superdry (LON:SDRY) leaving the london stock market today
"Distressed fashion chain Superdry PLC (LSE:SDRY) will have its last day of trading on the London Stock Exchange today, bringing its listing to an end after 14 years."
Crest Nicholson Holdings (LON:CRST)
Paul, if Bellway get Crst at this sort of price they have done a great deal. Crst share price is not far off an all time low , despite the bid , looking at the all time share chart. Farnham has gone badly wrong for Crst , and expensively, but it is being resolved if one believes management. I hold and am expecting a higher offer.
“As usual with takeover situations, forms 8.3 and the like clutter the list of RNSs. Wouldn’t it be good if the Stocko techies could add a button on the news page for each company that gives the option to hide news clutter like this?!”
Yes Please …
Surprisingly I don’t believe the RNS system has categorisation so you need to filter on keywords. I some thru OpenAi to try and pick out things of interest, but there is no way to for example just pickup trading updates.
Like much of UK stock trading it’s all very 1985!
This reminds me of the 'traffic light' system described on pages 123-126 of Robbie Burns's Naked Trader. The ADVFN website gives the option of highlighting phrases.
A long time ago I made a suggestion, which many agreed with, to improve search facilities on Stocko. A goldmine of information is archived with no easy means of finding the nuggets. If you search discussions, you can only get results for the company name if it appears in the title as tagged by the author, but you still have to search the article using CTRL F
Is it beyond the realms of possibility to index the whole archive using some off the shelf software so that if I search for "lemons" for instance, I will find any article which has that word inside. Hopefully including logical operators like AND, OR , NOT
Make my dream come true Ed, get your IT experts to get their heads together.
You could also add "Transaction in own shares" to any RNS declutter filter.
Also exclude all news on selected stocks. I had Barclays (LON:BARC) once, they were issuing around 20 RNS a day. Also still getting news on stocks l no longer hold.
I think you can do this with Sharepad.
My morning smallcap tweet: Bust pipe part
Pipehawk (LON:PIP), System1 (LON:SYS1)
◄PipeHawk (PIP)► as mooted, subsidiary QM Systems selects administrators. PIP reiterates that this "will not impact PipeHawk's broader group of companies and the Board believes that the remainder of the Group will be able to continue to trade as a going concern". [SP=2 Cap=1m]
In line: SYS1
Maybe your software code is now too intelligent and cognisant that it needs to take a lazy summer Friday off too like its human counterparts :)
The Time to Buy UK Small Caps May Be Here
Cape Wrath Capital’s Adam Rackley explains why on this week’s Merryn Talks Money
https://archive.ph/kQtkB
Hi EParo, thanks for the link - just listened to it over lunch and it was an interesting podcast. Starts at around 14 minutes for anyone interested.
Key takeaways for myself as a fairly novice investor:
* Huge amount of value in the UK small cap sector.
* Do not invest in small caps during recession/bear market - large caps do better
* Value investor must believe in "mean reversion" and that market will turn at some point in time.
* In talking to US investors, they believe UK market is undervalued.
* Investing in individual companies is as much an art as it is a science.
He mentioned two companies they recently invested in:
Marstons & Watkin Jones.
Lot more information so worth a listen to.
Regards