Small Cap Value Report (Fri 12 May 2023) - ECEL, THG

Good morning from Paul!
UK interest rates rose yet again yesterday, but as expected. I can feel another rant coming on for tomorrow's podcast.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
With it being a Friday, I'm off to a leisurely start. This is what I'm planning on looking at first -
Eurocell (LON:ECEL)
Down 12% to 112p
Market cap £126m
Trading Update (profit warning)
Eurocell plc, the market leading, vertically integrated UK manufacturer, recycler and distributor of innovative window, door and roofline PVC products, provides the following update for the first four months of 2023.
The current financial year is FY 12/2022.
I like this company, but am wary of the building supplies sector generally, as we’ve been discussing in recent weeks, with the brick suppliers reporting strangely upbeat trading, which was contradicted by a recent profit warning from Marshalls (LON:MSLH) . With housing starts sharply down this year, and repair/maintenance activity also said to be subdued, further profit warnings in the sector do seem quite likely. ECEL mentions both those points today, reinforcing a negative current sector outlook for building supplies companies.
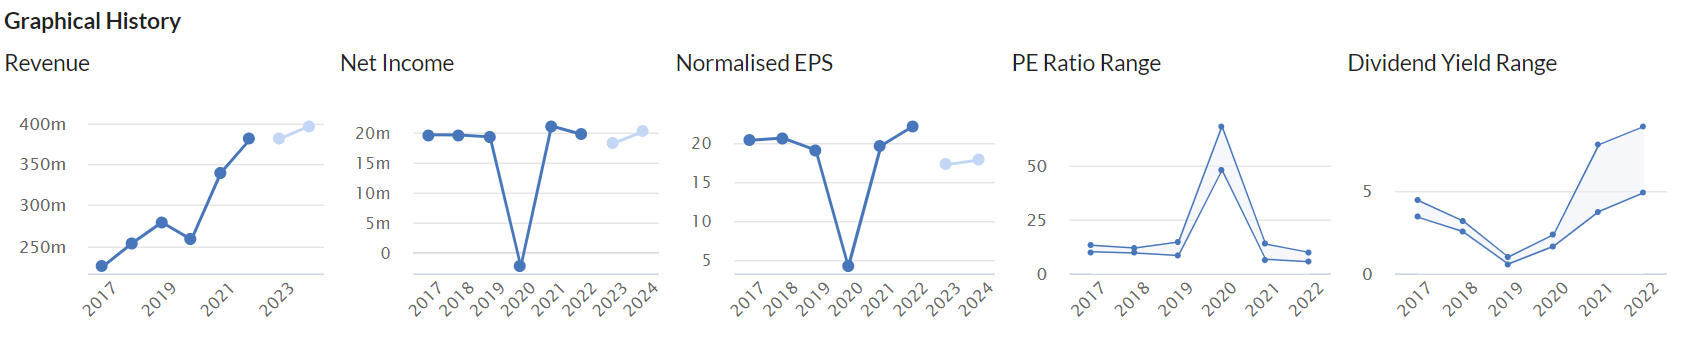
But, at some point I think we’ll have a nice entry point for several decent companies in this sector. After all, trading is likely to recover at some stage, and when we own shares in a company, we’re not just buying this year’s earnings, but all future earnings. Hence Eurocell shares have just got more attractive to me, hitting a new all-time low today, for a business that historically has been reliable at generating EPS of c.20p, and paying nice divis of around 9p pa.
This is what it says today (for Jan-Apr 2023) -
Revenues down 2% against “very strong” prior year comparative.
Volumes of product sold down, partly offset by price rises.
Inflation - electricity cost is noted as a particular cost increase (hedged forwards 12-months)
Passing on cost increases, but competitive pressure on margins.
Latest industry data shows a greater decline of -17% (previously -11%) in new housebuilding in 2023, before recovering in 2024.
H2 weighting expected in 2023, so interims likely to look bad (as 2022 saw a strong H1) - with lower costs feeding through to benefit H2 2023.
Overall -
Taking the above factors into account, we now expect adjusted profit before tax for 2023 to come in below current market expectations (1).
(1) Eurocell-calculated analyst consensus profit before tax forecast for 2023 of £22.0 million.
How much below? We’re not told and I haven’t yet seen any broker updates, so it’s pure guesswork at this stage. I’ll go with maybe something like 12-15p EPS this year, possibly? Then a rebound to nearer 15-20p next year. I’m just guessing there, based on the tone of the announcement today.
Broker forecasts have already been cut a fair bit, so it’s disappointing that ECEL is missing this lowered forecast -
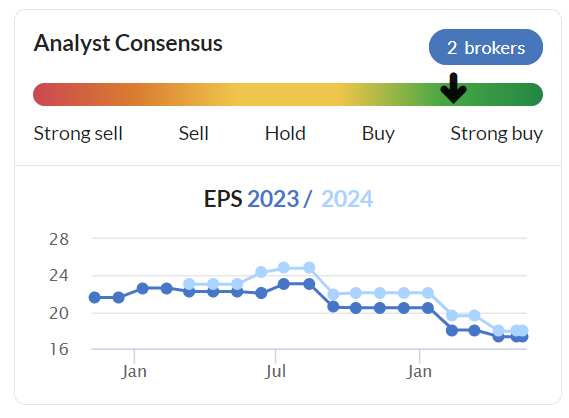
(as of last night, so the darker line and probably 2024 as well, will drop again once updates come throug i the coming days, hopefully)
Outlook - good points here, and a reminder that it’s often the tough decisions that are taken in downturns that result in a better, leaner, and more profitable business in an economic recovery -
Our balance sheet is strong and the actions we have taken and plan to implement will improve our efficiency and resilience, and position us well to benefit when our end markets recover.
Is the balance sheet strong? Yes, it’s good actually, with £98m NTAV at 12/2022. Only modest net bank debt of £14.4m (ecluding leases). So shareholders don’t have to worry about dilution or insolvency risk.
A new CEO started yesterday, as planned.
Paul’s opinion - I’ve been looking for a good value entry point in Eurocell, so will ponder whether it’s time to buy a small starter position here or not. I think this is a fundamentally good company, with sound finances, and under-performance seems obviously macro-driven, rather than anything specifically going wrong at the company.
That said, buying after a profit warning can often be a mistake, with shares continuing to drift, so maybe it’s better to continue watching from the sidelines? Who knows!?
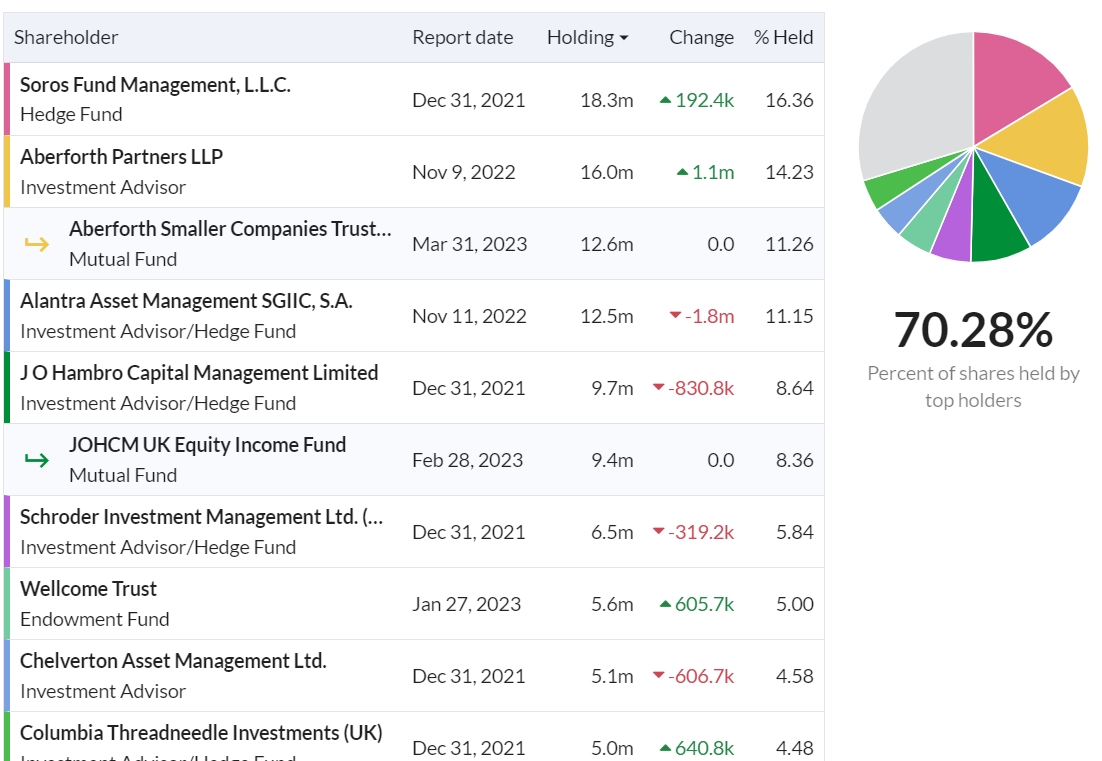
The shareholder register is quite concentrated, with 5 institutions owning just over half -
THG (LON:THG)
Down 9% to 68p
Market cap £919m
This heavily loss-making eCommerce business was floated at a crazy price in the recent tech boom, and is still valued at almost a £billion at today’s bombed out price -
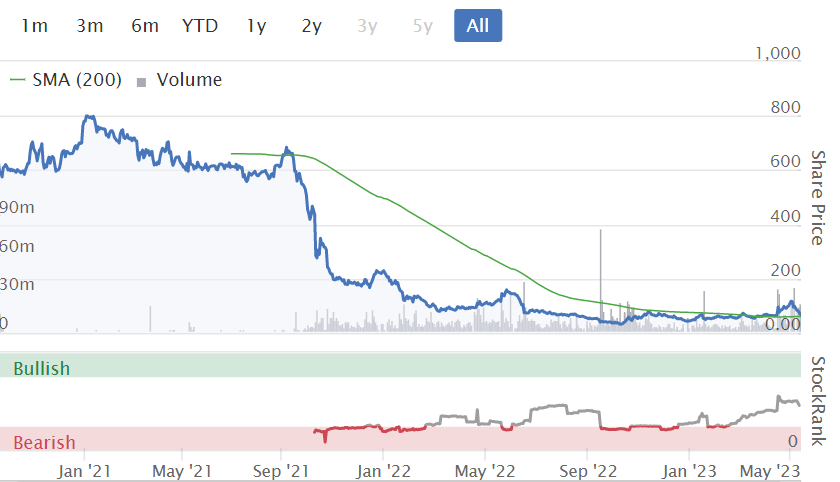
This is despite it never having made any significant, or sustained profits.
I looked at the accounts for FY 12/2022, published on 18 April 2023, but unfortunately my notes seem to have got lost in the system. Taking another quick look now, the 2022 results are truly awful. Massive losses, and a rapidly declining balance sheet, now with negligible NTAV. Awful cashflow too. Unless performance improves, this share could end up at zero in my view.
The day before results were announced, THG announced that it had received a preliminary bid approach from Apollo, causing a spike up in share price, which is clearer on this YTD share price chart -
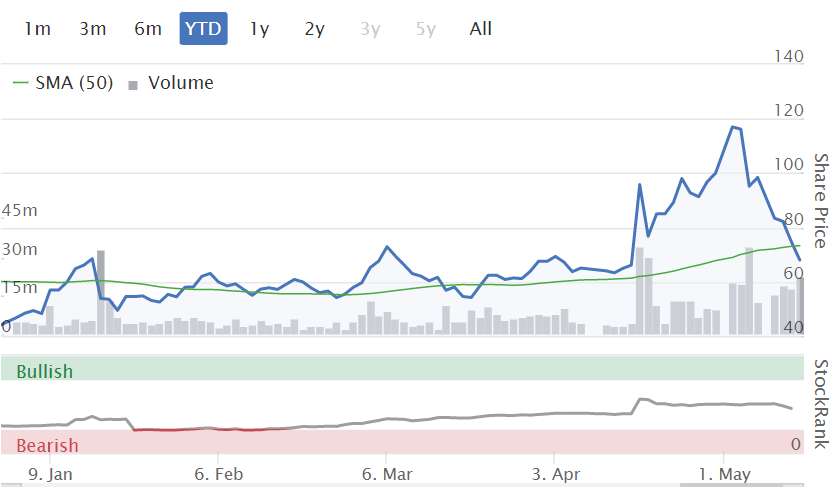
Anyway, today we’re told that bid talks with Apollo have been terminated, because its indicative offer was too low. Major shareholders were consulted, and holders of over 50% of the shares rejected the deal. That’s annoying, because the big shareholders know what price was offered, but the rest of us don’t. That strikes me as a false market, and it breaches the general principle of all information being available to all shareholders simultaneously.
There’s also some jam tomorrow commentary today about trading - it makes positive noises about current trading, saying this further supports full year guidance. But look what’s happened to broker forecasts! -
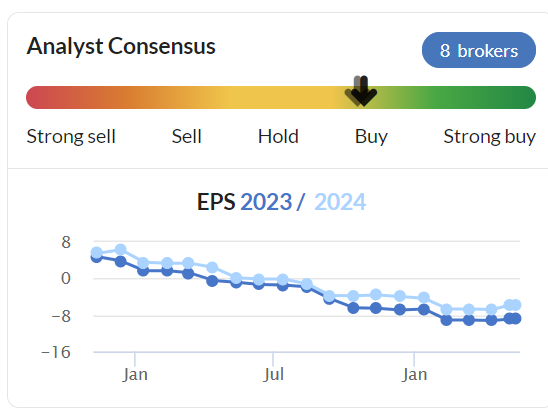
Continued losses. Remember that THG’s accounting is ludicrous - it focuses on adj EBITDA which is pure fantasy, and bears no relation at all to real world cashflows.
It reckons that THG will be cashflow neutral (on what definition, I wonder?) in 2023.
Outlook/aspirations it says -
The Company reiterates its expectations to deliver positive free cash flow in FY 2024 and adjusted EBITDA margins of around 9.0% over the medium term.
Falling price of whey (a key ingredient) is helping margins. And on £2bn of revenues, each 1% margin improvement is £20m more profit to the bottom line. So if this turnaround gains traction, then the shares could become interesting - that's clearly what bulls are betting on.
Paul’s opinion - extremely negative. To date, the whole thing has been hype, with no sign of this being a viable business.
Management needs to turn it around, before the money runs out. Note that in 2022, THG went from a net cash position of £44m to a net bank debt position of £181m!
We now have evidence that a potential acquirer wasn’t prepared to pay what management & major shareholders wanted, but we’re not given any idea what price that was. Maybe it will get leaked out through broker notes?
Anyway, it’s all academic, because I wouldn’t go near this share at pretty much any price.
It will be interesting to see if management is able to turn this around. It reminds me a bit of Asos - another former stock market darling that actually turned out to be a pretty rubbish business, once the hype wore off.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

74 comments
Re wind power...I'm happy with it and happy to have more...
...however it is categorically not the solution and it is scientifically as well as economically illiterate to believe so. In fact, I would go as far as to say that policy support for more wind is a waste of time, resource and capital. Wind is a nice to have where the non-manipulated economics supports it. Fortunately, the UK is one the most ideal locations in world for wind power due to climate and geography so unaided 'private capital' has the ability to make productive investment here. BUT wind generation should bear the full marginal cost of its use. That means grid alterations to accommodate this very diffuse and variable energy source, storage solutions, pricing and managing the over saturation of generation markets driving down price for energy when wind is over abundant and cost of its intermittency to the system (when the wind doesn't blow the system/society requires 100% alt generation capability). These issues are not seriously discussed (yet) by policymakers and proponents of wind...tho that process is starting globally. They seriously limit the societal value of lots of wind generation and particularly disable it as anything other than a marginal energy source.
I view wind as a sort of hybrid of energy storage plus surplus energy generation capability. Storage as it takes energy and materials (both carbon input intensive) and 'stores' it in turbines and supporting infrastructure to be released at later point (when the wind enables it). Then where the turbine and infrastructure outlives the total energy input cost to make it it then gives us bonus excess energy. Its hard to know for sure how much excess energy return on energy input we get but it is clearly much less than alternative very energy dense sources (note, energy return on energy invested is the key criteria...our affluence as a society is 100% dependent on it...if you don't understand this point you need to give it very serious contemplation).
Nuke is the best energy dense alternative we have. Carbon sources have been deteriorating as our reserves of it are less high quality as we move through them. To be over simplistic, 50+ years ago we got something like 100 barrels of oil for every 1 barrel invested in producing it. But today new oil sources come in at a much lower energy return on energy invested, though still significantly better than wind if full costs loaded onto wind eg, full back up generation and/or long term power storage (...which tbc we are nowhere near solving at a societal scale).
So, I could go on in more depth and be a greater bore....but wind is not our solution. It can be a contribution but it is by definition marginal in absence of a huge leap forward in storage - many weeks, possibly months, back up required and in a super dense format...material science may get there but we are probably significantly further away from that than we are from solving fusion generation...just to give a comparable panacea.
Really our only viable scalable alternative to carbon based energy for grid power that we currently have the knowledge and capability to build is nuclear. FYI I've got c.25% of my portfolio exposed to this but actually not for the 'nuclear renaissance' that I view to be near certain and is actually happening globally but as nuclear power is a deep capital cycle play and just maintaining and fuelling current generation abilities has been super underinvested in, meaning that significant price rises are required to produce enough fuel to replace fuel used...the renaissance in nuke as a true energy alternative if/when it happens is potentially just mega speculative upside. Nuke is the greenest AND safest energy source available to us (...if we take facts scientifically rather than emotional reasoning that is).
As for other alternatives, we should invest heavily in geothermal and tidal rather than wind or solar. The UK is fortunate as the proximity and shape of our coastline means that tidal potential is 'abundant' in UK. In geothermal we are less luck as its not near surface. Both require significant leaps in tech. Tidal potential is probably relatively limited. But geothermal is pretty unlimited if we can develop the technology/materials to withstand heat and pressure 2km plus in the earth's crust. Geothermal is v exciting at the point we work out how to harness it. IMO this is an engineering problem we will undoubtedly solve if we seek to do so....whereas batteries of scale and power may always prove out of reach
Could you email our MPs please as they do not seem to understand the implications of net zero mostly achieved by sun and wind.
Haha. I'm a member of a party and I emailed the leadership about my lack of support for their approach to energy. I'm still waiting on a response...
Some director buying at Luceco (LON:LUCE) has lifted the share price in the afternoon.
Sosandar (LON:SOS)
I have noticed broker EPS estimates falling in recent weeks for Sosandar on Stocko, and today they have fallen further. Does anyone know what this relates to? Has there been a broker note issued/has management told the house broker to reduce their forecasts? Thanks all
The last broker note on Research Tree was dated 12 April. This does not reduce valuation but does suggest that short term profits may be affected by increased investment to support long term growth. Not sure if that is the source of the changes you mention or if something else has happened more recently which has not been covered by the analysts who publish through Research Tree. I cannot, of course, divulge any more about the Research Tree content but suffice it to say that on 12 April there was a clear buy recommendation.
Thank you. However, it looks like there was another EPS downgrade issued on Sosandar (LON:SOS) today as per stocko
I can't see the print on the 4th May, nothing to do with Sosandar (LON:SOS), seem to be a lot off site problems at the moment.
Sosandar (LON:SOS) 12 May (today) downgrade for reference
Maybe. Check margins against other etailers. This drifts. It will be news driven. LTBH IMO.
Wailing and gnashing re lack of industrial policy entirely appropriate...the 'free market' does not exist and without considerable embedded advantage or protectionism/mercantilism/state championing (not the same thing but similar goals) its very hard to sustain productive industrial capacity. US is example of former with its superb and broad natural resource advantage over any other nation of size globally. Germany and China are twinnies on the latter.
The UK fairs relatively well on the innovation front. Obvs not (in)production innovation (a la German mittlestand par excellence!) but early stage and 'pure' innovation. Is there a natural advantage to this? Hard to be sure but perhaps english language, time zone and the longest history of science/industry in the world? Dunno
UK should choose where to fight for some ground on industrialisation. I'd suggest chip manufacture ain't the patch to fight over. The capital intensity of cutting edge chip manufacture is off the charts. Taiwan and South Korea have expended a huge amount of their emergence capital on this industry and trying to replicate them would be like someone seeking to replicate from scratch London as a global financial centre. Only the US and China have the scale to go for it...and only the US the resource and capability...and I suspect the US will fail barring the exigency created by a Taiwan war (not the threat of it). I don't know exact figures but we're talking +++$100bn to get started. Lower quality chips easier to produce...but its a commoditised game so its not an investment to make to make money (and a lot of low cost but capable labour needed...so its found increasingly in places like Indonesia). But UK is rather better placed to be key in global chip development game due to a highly evolved chip and application design capability (obvs we all know the Arm story but there are many others eg Sondrel (Holdings) (LON:SND) )
The UK should also skip battery production as a supported industry as it too requires remarkable capital depth that we really shouldn't waste our limited capital formation ability on. Again we are in the hunt from a research and development perspective and we may be able to lead and develop some technologies (eg a novel, cheap and scalable sodium battery capability has been developed in UK and sold to India's Reliance for development....makes sense as low cost labour is needed for fabrication, just like in low end chips). So a high end seat at the table is available to UK thro research and development and we should fund that.
The other thing about batteries is that we really don't know where this industry is going. The hubbub is all EVs and batteries replacing carbon...but the reality is that we are very far away from this capability being scalable and good enough to come anywhere near fulfilling our mobile non grid energy requirements. And the resource intensity of the move to EV, battery is mind-bending and so far we've kind of assumed the magic of the free market will solve the problems...I'm sceptical...I believe there will a major and highly disruptive tech leap to be had first and that is likely to blow current battery tech out of the water...ie a lot of wasted capital
A negative side effect of high end R&D is that it won't show up in investment and productivity figures in the same way that iterative productive engineering of the German variety does...but it does produce pockets of high revenue and income (plus royalties and capital gains). This positive to the UK economy is systematically overlooked in commentary...and drive by trashing.
Where could UK focus industrial policy? Building from what we have and requires less capital depth/creation than say chips or batteries we have life sciences, defence, AI, nuke, food/crop science etc. The govt could more aggressively and directly aid the funding of biotech development as happens in US...same goes for defence, AI, nuke. This is not an exhaustive list just areas I'm aware of or have interest in. For example, small modular reactors are looking like they are going to be big in future (literally make them in a factory and then drop them into a community for always on power...its safe too!!). UKG could have got behind the Rolls-Royce Holdings (LON:RR.) SMR which was a leader in the pact but being caught due to lack of relative funding and support
TBC I'm not claiming any development economics expertise...but those are my views based on a fairly broad global and industry experience and fair bit of personal reading.
PS I think a great trap for UK is comparison with Germany. Germany is a wonder in many ways but is a super mercantilist economy and for that reasons highly vulnerable to periods of change in the global economy. I fully expect it to suffer severely at some point for over production and under consumption....the UK's propensity to consume is in fact a great positive in a world with too many mercantilist regimes (China, Germany, Japan, much of northern Europe, etc). UK is better looking at the Italian industrial economy (pre gutting by the EU due to overpriced euro for Italian needs). Much small scale specialist production...Germany has much of this too but is dominated by the mega industrial chains of autos and chemicals upon which the future of the German economy relies (precarious IMO)
A very thought provoking post.
Although perhaps I view the situation slightly differently, a lot of what you have put chimes with me. My view is that trying to catch up on things that are already lost is not efficient. Much better to try and to move straight to the next stepwise technological advance. In addition to your list I would add automation, genetics and a wide range of renewables.
As a country we have lost much of the manufacturing base that existed when I was doing my sandwich course back in the day. The level of investment required to regain that level of expertise is not possible, especially in the private sector. Luckily there are a few areas of strength that are left, and you mention Rolls Royce, Renishaw and quite a lot of biotech (but that is not my area of expertise). I have watched the slow theft of companies’ intellectual property by the ‘outsourcing’ model popular over the last 30 years. And it is not only in the UK, European, and US firms have all been jumping on the bandwagon of cheap labour at the expense of losing their long term competitive edge. It wasn’t long ago that a Chinese customer that my project manager visited showed no shame in displaying carbon copies of our equipment whilst pointing out the defects in our own.
In my experience the type of R&D that we are talking about here is a hit and miss affair, where one has to be willing to accept that only a small percentage of the time and money invested actually bears fruit. This is why most of it is done by large companies where the budget is available, and at the first sign of an unfavourable RNS, well, the scissors have to come out and snip, snip.
It is my opinion that the UK does have an innovative streak that is difficult to quantify, perhaps a level of individualism (which is why I think that the UK music sector is so strong). In recent history it has proven difficult to harness this innovation, and I fear that it will only become more difficult if our next generation do not have the necessary exposure (and I mean work with) the most cutting edge technologies available – that in my opinion is where the future lies, and perhaps where our government (of any colour) could help out.
I would say that as another available axis, our historical links (good & bad ;o) with India might be a point of strength that would be difficult to match for many other countries. Maybe where China is falling off, India is hungry to take its place. We could always ask our prime ministers wife to pick up where Mrs Truss left off …
To me, the obvious answer to our moribund economy is wind power - and lots of it, with a meaningful tilt to offshore but a recognition that onshore is not a blight but an asset to communities, perhaps through local participation in production. Strong economies derive directly from energy abundance and we have exceptional natural resources in this regard. The North Sea states have huge potential to form of nexus of energy generation, distribution and expertise that is as significant to Europe as Arabian Gulf or US oil and gas are today, and which, together with appropriate back-up, would assure our energy security in perpetuity. Yet it takes as much as 5 years to even get a project approved. Global giants are queuing up to participate and some of them are even British! To think it’s only a matter of planning policy. Madness!
It is already happening, Dogger Bank will be the largest offshore wind farm in the world, the first part is due to start production this summer and the completion is due to be in 2026. There are many other offshore windfarms in the pipeline. Wind in the last quarter over took gas for the first time ever in electric production.
All of which is encouraging and I’m well aware. But why the obstructive planning grind and when will those in the south of England accept that wind turbines are a social and economic good? How about some statutory regional variations in electricity cost according to generative capacity to sharpen people’s focus? The SW peninsular excepted, it’s not even as though there’s any decent English scenery to blight south of Derbyshire! ;-)
Hi Paul,
Excellent analysis on THG , and, in my opinion, there is no way that management will turn this around before they run out of money.
Yep
Some weekend viewing from this week. The Treatt (LON:TET) Interim results presentation given to Analysts on Tuesday, with the Q&A video & podcast. They are more stable and good growth in Citrus, Coffee and China. Price increases offset inflationary growth and supported margins. Cash flow strong. Edison believe the risk is to the upside.
On Wednesday, we had the Robert Forrester Show, when Vertu Motors (LON:VTU) CEO and Karen Anderson, CFO presented and answered all questions on the webinar. It's such a good overview of the automotive sector and how it's changing. With a PE of just 6 it seems too cheap but so is all the automotive retailers. Video & podcast.
Next week, Cerillion (LON:CER) will announce H1 results on Monday, 15 May. On Friday 19th May at 1.15pm, we are hosting Louis Hall, CEO & Andrew Dickson, CFO for a webinar with your questions. it's been a fantastic holding for shareholders. Anyone who doesn't know it, I highly recommend Paul's interview with Louis from last November, here. Join us for the webinar by registering here.
Vertu Motors (LON:VTU) (I hold) - thanks Tamzin, what a great presentation and Q&A. One of the things I like about the combative Robert Forrester is that his team has to be really sharp to keep up with him, and in Karen Anderson you have exactly that in my opinion. Her presentation was excellent - there are a lot of moving parts to Vertu and she seems to be firmly behind the wheel (excuse the puns) on the numbers. Well done for making a results presentation so entertaining. Maybe you should lanuch a 'results presentation of the year' award!
Robert Forrester is a no nonsense straight talking leader who inspires confidence.
Hi All
When I have logged out and then gone back to the site it shows me a LOGOUT tab instead of a LOGIN tab. I have to hit the LOGOUT tab before I can login again?
Anyone else have this issue?
I'm on android BTW
Yep, me too...been having to long in afresh every time for the last few months...very irritating!
Me too, only started happening the last few days
yes, been a thing for me too for months!
to add - it's happening on a mac, so macOS
For interest on THG (LON:THG), Matthew Moulding likes posting comments on Linkedin and here is today's on the rejection of the Apollo bid.
https://www.linkedin.com/posts...
I agree on the false market comment.
searching for clues whether the market is good value or not I looked at the directors buy list in this week Investors' Chronicle. 22 buys and only 1 sell.
Not the most reliable indicator but still worth taking not!
Good point about the brick manufacturers reporting solid trading , in sharp contrast to the wider building supply sector. I've been giving this quite a bit of thought since I own both Michelmersh Brick Holdings (LON:MBH) and Brickability (LON:BRCK)
My rationale for holding these is the somewhat unique characteristics of the brick market - constrained UK brick supply seems to give them a lot more pricing power than the likes of Eurocell (LON:ECEL) which based on today's update clearly has limited pricing power.
To make up the shortfall of UK bricks, the indsusty is reliant on imports. Given their bulky nature imports are obviously more expensive and if demand falls you'd expect this to be initially absorbed by lower imports. So in theory this should provide UK brick companies with a good cushion against lower demand.
I'm no expert on the sector so debating whether to hold on to these 2 names. I guess valuations are very cheap, and long term fundamentals good given the need for more housing, so will probably keep them both for now and just try and ignore any short term volatility.
We have Forterra (LON:FORT) going ex-dividend 15 June with a juicy 10.1p dividend (5%+) which looks like a nice offering in this sector as well.
Ashtead Technology Holdings (LON:AT.) Just an FYI for anyone with a free morning and an interest in this company: They are about to present their Full Year Results at 11h00 today on the InvestorMeetCompany platform https://presentations.investor...
(i hold)
Chairman and CFO of Eurocell (LON:ECEL) didnt seem too concerned last month......not huge buys, but not insignficant either:
My sympathies to holders but what I’m struck by today is a pair of articles in the FT from the editorial team and no less a figure than Emmanuel Macron on the bold steps being taken by sovereign governments such as France and Germany to boost industrial performance and access to vital technologies. Meanwhile the biggest news in UK stocks today is of an underperforming plastic-polluting conservatory maker in a directionless economy.
For subscribers, the article on German chip fabrication capacity is both interesting and balanced on the opportunities and risks. Meanwhile, where is our industrial strategy?
'Meanwhile, where is our industrial strategy?'
The strategy has been the same for many years and recently has become explicit.
The industrial strategy is - Not to have one.
The main advantage is that the industrial strategy itself cannot be a failure. So the minister can't be blamed when picking winners turns out to be rewarding failure. Battery strategy a flop? That's ok, we only invested in the land, wait for another country to buy it up. And best of all, should by any chance anything work out well, we can claim the credit and tax it swiftly. It's incredibly efficient so the Treasury likes it, and saves a massive amount of carbon footprint in that monitoring, updating and printing it is simple.
Can't see where it could go wrong.............:-)
Reading todays report and comments I had to double check it wasn't Friday 13th. Agenda for SCVR is all bad news and comment is all about software issues. OH and it's raining cats and dogs. Happy w/e all
Eurocell (LON:ECEL) not a lot to get excited about in that TU.. guess it's all about 2024 now
Or is it time to buy on softened prices when there is a mild profit warning on this and other likewise sound, well-financed businesses?
Which is what I've just done - taking a modest stake. There is a narrative out there that the country is broken and we are all doomed - I just don't see it on the ground. The demand overhang on residential property is huge and it is only a question of when it will recover. Thanks to Paul and others for their input. On my calcs the current price of 111p gives a yield of 10%+ btw.
Eurocell (LON:ECEL). To be honest I'm annoyed about this one because it's obvious investors have been misled. I'll explain. On the 16th March 2023 the CEO said this:
"We continue to take market share and have increased the run rate on new
fabricator account acquisitions, with our pipeline of other potential new
customers remaining healthy. Market share gains are further supported by the
impact of maturing branches and a widening product range, all underpinned by
very high product availability and increasingly efficient operations.
"For the current year, the latest construction industry forecasts((5))
recognise the currently challenging market conditions and ongoing
macroeconomic uncertainty. However, we have acted swiftly on cost to prepare
the business for 2023 and we expect our strategy to enable us to optimise
performance in our markets."
The trading update is up to the period of 30th April 2023 (6 weeks later) that mentions some significant issues that contradict their forward guidance. My gut feel is he's misled the market.
These are the key points:
* ECEL forecasts adj profit before tax for 2023 to come in
below current market expectations
** Co posts 2% decline in group sales for four months to
April 30
** Says trading volumes during four-month period fell due to
weakness in repair, maintenance and improvement (RMI) and
building plastics division
** ECEL continues to experience cost inflation, particularly
for electricity, co says
** Co adds feedstock prices for its recycling plants are
higher than in 2022, while PVC resin prices have "fallen back
slightly this year but remain volatile"
Eurocell (LON:ECEL) Well he did buy some shares recently, so I'm not sure he did mislead, if he knew that why buy the shares? Other directors were also buying shares in April, 23.
I don't hold but have considered it in the past.
I'm reducing my holdings in this sector. Tyman (LON:TYMN) update is out soon, be interesting to see how they are doing.
There’s nothing misleading that I see in the statements quoted. He talks about market share gains, not outperformance vs targets. And experienced investors will understand that “a focus on market share gains” is a euphemism for making the best of trading below earlier expectations.
Anyone else on android have to log out and log back in again every time you want to get on the Stocko app? Gets annoying when you go on 20 times a day
Yes, it seems to be a recent change.
BSV
Im on Apple but got a lot of funny screens yesterday and also frozen screens.
Also does my head in!
Yes, and on IOS
I've just complained about it.See below.
"Hi xxxxThanks for reaching out.Sorry you, and others, have come across the issue. We are aware of it as you rightly point out, you are not the only one.. I am told (on good authority) that our development team is nearing the end of a project to upgrade our user authentication system, which should resolve this issue of click throughs not working once and for all.In the meantime, it may be worth you actively logging out of the site (i.e. clicking "Log Out") - which should reset your cookies - and then logging back in again. This may help.Once again I apologise for the inconvenience and thank you (and others) in advance for your understanding."
It is the same on Apple. It is irritating.
Its been happening on my desktop too for the past few days, and I'm using Chrome.
They need to develop a proper app
Its becoming a common problem.somebody has amended a program
Thought it was just me (qualified Luddite). Have you tried reporting it to Stockopedia?
It already has and Stocko have responded, see other posts below.
Re: Accessing Stocko App on Android
For me, I have to click 'Log On' every time, and when I do, it takes me to the Home page (my log-on settings are set to 'remember this computer/phone').
Yes, reported and apparently they are trying to fix it.
Short term fix, that seems to work here is to reclick the link (mine is to https://www.stockopedia.com/di...) once you get the "logout" page, which then takes me to where I want to go, with out logging out and in again.
I click on favourites link in bookmark bar and goes straight to page
Anyone else getting alert emails, nearly 24 hours late? Had 2 this morning for alerts that happened yesterday morning.
I haven't had anything through on Eurocell by email this morning, a little frustrating as I missed the RNS and probably would have attempted to sell (my admittedly very small position) at the open had I had chance to read it. When I went on Stocko after the open the alerts were showing, yet no emails.
I didn't realise how big my holding was , that's a bit of a kick in the balls today, especially with so much value out there ATM
Really sounds like poor planning/cost management.
Or is it time to buy on softened prices when there is a mild profit warning on this and other likewise sound, well-financed businesses?
I think you could be right Jayman, I'll continue to hold
Yes - emails arriving in the middle of the night (UK time). Very odd.
Yes, have had a problem with alert emails arriving from a few hours late up to 20 hours late, for the last 3 days. Reported it yesterday and received an apology and assurance that the technical team were aware of the issue and were working on a fix.
Yes - some of the alerts coming early morning - day after.... But no problems with Stocko on Safari with my Apple minimac desktop as Guybrush mentions above
I'm using an iPad, been having problems for some time but been getting worse recently. Only site I have problems with.
Hi Rusty
I alerted (no pun intended) them last night and have had an explanatory email from Ed early this morning. Now a site wide message . I hope they can fix this soon but at least some speedy communication from Ed
Steve
Following up on ken mitchell's comment yesterday re: Stockopedia's dividend figures being wrong too often.
I was in touch with Stockopedia about 3 stocks where the the dividend ps TTM number was wrong. But if you skip through to the dividend page the individual dividends are there. Presumably it's just a matter of the computer adding up either 2 or 4 numbers.
The stocks were Alternative Income REIT (LON:AIRE) , Volta Finance (LON:VTAS) and Riverstone Credit Opportunities Income (LON:RCOI) . I assume there are quite a few more.
I complained on about April 21st and they just keep stalling.
It doesn't really matter to me as i hold these and have gone to the dividend page and done the simple addition myself.
However, the point is that if subscriber were doing a screen on Dividend Yield TTM, some stocks would be missing.
Now we've all paid for this service and if we point out simple errors, i think Stocko should correct them in a timely manner.
Anyone any views or comments about how we can get this improved?
It is indeed annoying - my answer - I have another tab open with the dreaded HL - where dividend is easy to view (and no need for an account or login!)
Question:
Please can anyone confirm my understanding that starting this month there's a Bank Holiday every Monday, thereby reducing the number of loss making share trading days to just four per week?
If this is the case then I wish you all a restful long weekend; see you back here on Tuesday.
TEIN
Many a true word TEIN. Our beloved country seems to be emulating the fall of the Roman empire in that there isn't a lot to chose between contenders for government so the masses are maybe voting for more bank holidays and caring more about football than work prospects.
Does anyone know, why a investment fund would buy circa 3% of Sureserve (LON:SUR) when it’s half way through being taken over? As one did a few days ago.
I might be missing something, but surely it indicates they are expecting a higher bid- or they will just get their money back?
Arbitrage. They presumably have bought for very slightly less than the amount they expect to get.
Holders will sell for slightly less to free up money today rather than whenever.
My morning smallcap tweet: Horsing around in the city stables
Eden Research (LON:EDEN) Us Solar Fund (LON:USF) THG (LON:THG) Fireangel Safety Technology (LON:FA.) Blackbird (LON:BIRD) Eurocell (LON:ECEL)
◄Eden Research (EDEN)► another step on the ultra-marathon to profit. Gets regulatory approvals for Cedroz in California and Mevalone in Florida. [SP=4.3 Cap=16m]
◄US Solar Fund (USF)► has failed to far to get an acceptable offer for US assets. Also has rejected an offer for co. Terminates Formal Sale Process. [SP=0.78 Cap=263m]
◄THG (THG)► ends takeover talks with Apollo because indicative offer rejected by holders. "Profitability and cashflow improvements delivered during the first quarter of FY 2023, have continued in Q2...remains on track to be cashflow positive in 2024." [SP=81.75 Cap=1062m]
◄FireAngel Safety Technology (FA.)► £1.5m Middle East contract. [SP=7.25 Cap=13m]
◄Blackbird (BIRD)► A&E Television Networks gives notice to cancel contract at end June. Was 10% of rev in 2022. [SP=10 Cap=37m]
◄Eurocell (ECEL)► warns FY23 adj pretax below market expectations of £22m. Jan-Feb rev down 2%. [SP=129.5 Cap=145m]