Small Cap Value Report ( Fri 12 Nov 2021) - CGS, WRKS, AVON

Hello, it's Paul & Jack with the SCVR -
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda -
Castings (LON:CGS) - good H1 recovery but various headwinds mean the company is struggling to translate a strong pipeline as vehicle customers suffer from the semiconductor shortage. Castings looks like a sensibly run business with a strong balance sheet, so it should be able to navigate these conditions, but profitable growth has been lacking for some time.
Works Co Uk (LON:WRKS) - a better than expected revenue performance offsets rising freight costs, leaving the group on course to meet original expectations for FY22. There's a huge store estate here given the small market cap and a possible value opportunity given the valuation, but I'm unsure of the fundamental profitability of the business model.
Avon Protection (LON:AVON) - commiserations to holders after a brutal 40%+ share price drop this morning. The affected business area accounts for c12% of forecast FY22 revenue so there is a chance the reaction is overdone but shifts in sentiment like this can take a long time to undo, so I don't think there's any rush for onlookers to jump in. Final results now expected in December.
.
Jack’s section
Castings (LON:CGS)
Share price: 370p (+0.54%)
Shares in issue: 43,632,068
Market cap: £161.4m
This is an iron casting and machining group. It’s got a strong balance sheet and invests in its businesses plus, as we see today, management is admirably upfront about its challenges. Growth has been a bit of an issue, but it seems sensibly run so I can see why some longer term investors might gravitate towards it.
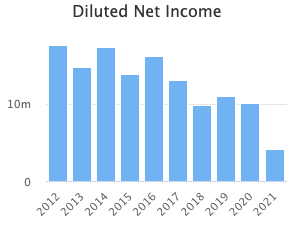
Highlights:
- Sales +67.1% to £69.8m,
- Gross profit +170.6% to £13.9m,
- Operating profit up from a loss of -£678k to +£5.4m,
- Diluted earnings per share up from a loss of -1.16p to +10.03p,
- Interim dividend of 3.66p.
These figures look like a strong recovery from Covid disruption but Castings says that, after a strong start to the period, supply chain disruption and the semiconductor shortage means that commercial vehicle customers are struggling to build enough heavy trucks to meet demand.
With the OEMs having to reduce truck build rates to below their order intake levels, group sales were reduced from the last two weeks of June and into the second quarter. This segment accounts for 70% of group revenue.
This dynamic became more evident in the last two weeks of June and into Q2. Castings says ‘Whilst forward demand schedules from our customers have remained high throughout the period, the conversion rate to actual sales has been significantly below what we would normally expect.’ While the group has increased inventory and production levels, it has been further hampered by labour recruitment difficulties.
In fact, Castings had to close the machining business for a week at the end of September.
Raw material prices have continued to rise throughout the period which, with the time lag in the associated sales price increase, has continued to put pressure on margins.
Foundry operations - output here was up 69% to 24,300 tonnes and revenue grew by 68% to £68.1m. Profit increased from £0.8m to £5.3m, although margins have been affected by fluctuating demand and rising raw material prices. Investment continues here.
Machining operations - CNC Speedwell revenue grew by 32% to £1.6m, and a profit of £0.1m is reported (H1 2020: -£2.1m). Significantly lower levels of demand in Q2 had a ‘particularly negative’ impact on results. Again, the company continues to invest here (£0.3m in the period).
Balance sheet - looks solid, with £34.6m of cash compared to current liabilities of £24.5m. Net tangible assets of £128.8m and no debt, so that’s a strong pass.
Conclusion
There are two separate points here. Number one, there has been a very encouraging recovery from Covid disruption. Number two, business is now being impacted by post-Covid disruption. Assuming these headwinds reduce at some point, then the strong balance sheet should see Castings through and the company and its sites appear well invested. How the share price reacts in the short term is another matter.
The group says raw materials prices have increased, impacting margins. Sales reduced in the last two weeks of June and into Q2 as vehicle customers struggle to source parts, the strong pipeline is currently difficult to convert, and labour scarcity means its machining business had to close for a week.
You can’t say this company doesn’t say it how it is. Putting those challenges to one side for a second, the H1 figures are actually very positive and margins improved in the period. How much impact the current dynamics have on those recovered margins remains to be seen, which makes the situation tricky to assess.
In the comments below, Yellowstone points to a webinar today at midday here. I’m sure management will give more colour at that point.
For now, the pipeline is busy and the balance sheet is strong, so the outlook could be worse for this particular company. It looks like it’s run sensibly and management pulls no punches. But it’s been struggling for growth for some time and this latest update suggests there are currently more attractive opportunities out there, in my view.
Perhaps if, in six months time, the share price has come down a bit and conditions begin to improve then there could be a good value trade here, but I’d want a cheaper price (and more visibility on the trading conditions) given that profits have been coming down for some time.
Works Co Uk (LON:WRKS)
Share price: 55p (-3.51%)
Shares in issue: 62,500,000
Market cap: £34.4m
Works is a multi-channel retailer of gifts, arts, crafts, and some other faddy things like fidget spinners. The group has a surprisingly large estate of more than 500 stores, which is obviously a lot for a £34m market cap company.
The shares have rerated and are of interest to the community, which perhaps senses a continued rerating as customers head back to shops.

The upcoming Christmas period is extremely important for retailers like Works, so a good performance over the next couple of months could make a big difference. Brokers rate it a strong buy, but Works has had a rough start to listed life and has disappointed in the past.

It has generated low margins in the past, so for all its revenue and store count, turning a profit appears to be a challenge. I think low margin businesses are particularly vulnerable with cost inflation and supply chain disruption running rampant.
Overall, taking into account the stronger than expected trading during H1 FY22 and the higher freight costs and, assuming that our strategies to ensure the availability of stock to customers in the lead up to Christmas continue to be successful, the Board anticipates that the full year result for FY22 will be in line with its original expectations.
Trading has been stronger than expected, with a two-year LFL sales up 14.5% and total two-year sales growth of 17.9%. Online sales were close to double those in the comparable FY20 period. The board consequently expects full year results to be in line with original expectations, despite higher freight costs.
Net cash (excluding leases) improved by £17m to £17.8m ahead of the peak trading period. This improvement includes favourable timing differences of approximately £10, which should unwind. The group has managed its supply chain issues and expects to have adequate stock levels heading into Christmas.
The new strategy outlined in July 2021 includes de-emphasising new store openings and focusing on profitable digital growth and driving improvements through the existing store estate. The product range has been improved, as has stock management and space management in stores.
Three new stores were opened, five were closed, and four were relocated. That leaves the group trading from some 526 stores at the end of H1 FY22.
Consumer demand has also been strong, perhaps due to staycations and a strong 'back to school' performance. There are also signs that customers are shopping early for Christmas and, ‘whilst the impact of this on H1 FY22 was small, we hope it is a positive indicator that strong demand will continue into the peak Christmas trading period.’
Conclusion
Online sales have doubled but no actual numbers are given. Two-year like-for-likes are up by 14.5%, which is encouraging. The company was struggling before Covid though, and I’m not sure about the longer term prospects for this concept. The margins have just been too low in the past.
The shares still remain well below the IPO level.

With a single digit forecast PER and a trailing twelve month price to free cash flow multiple of just 1.3x, there does seem to be value here. But I’m just not sure about the economics of the enterprise.

There’s not enough information here to sway me one way or the other, although if consensus forecasts are met, then there is a value case to be made. Perhaps a continued rerating if the backdrop remains favourable, but longer term I’m not so sure of the prospects. The poor historical operating margins put me off.
Avon Protection (LON:AVON)
Share price: 1,094.27p (-42.62%)
Shares in issue: 31,023,292
Market cap: £339.5m
I’m surprised to see this one so firmly back in SCVR territory. Not long ago, Avon was touted as a particularly high quality growth company and it had the valuation premium to match. Towards the end of last year the shares were trading at c4,600p, making for a market cap of £1.4bn.
Today, less than a year later, they are some 76% down on that level. It just goes to show how quickly perceptions can change. Commiserations to holders. We all end up seeing something like this at some point, unless you’re disciplined with your stop losses.

Avon retains its high Quality Rank (currently 87) but there has been a slightly alarming deterioration in margins.

The shares are down by more than 40% this morning so I’m curious about this announcement.
Following the contract awards for the U.S. Defense Logistics Agency ("DLA") Enhanced Small Arms Protective Inserts ("ESAPI") and U.S. Army Vital Torso Protection ("VTP") ESAPI body armor plates, we have been engaged with our customers to complete the necessary product approval processes. Disappointingly, the VTP ESAPI plates have encountered a failure in First Article Testing which will significantly delay the likely approval timetable for this product.
Separately, we have experienced further delays in obtaining final product approvals for the DLA ESAPI body armor plates, with approvals for this product now expected in the second quarter of our financial year ending 30 September 2022 ("FY22").
This has led to a strategic review of the recently acquired body armour business.
The FY22 revenue guidance included approximately $40m of body armor revenue but clearly this is no longer the case. Body armour revenue ‘in FY22 and beyond’ will be significantly reduced.
Avon’s respiratory protection and helmet product portfolios are unaffected.
This also leads to a delay in FY21 results ‘to allow for a review of the carrying value of the assets related to the body armor business and the additional audit work arising from this post balance sheet event.’ The revised results date is expected to be in December.
Conclusion
FY22 revenue was expected to be £239m, so the affected $40m represents about 12% of that. It’s a brutal reaction today and it pays, if possible, to analyse the developments objectively as such reactions can overshoot. Still, such severe drops can weigh on sentiment for some time, so I don’t think there’s any rush to come to a conclusion on the revised prospects.
The group had been ramping up production of its body armour products, so it feels like this failed test has come quite late on in the process. Unfortunately, that raises some questions around testing rigour and due diligence on the products of the acquired business.
BlackRock and two directors were buying reasonable amounts of stock as recently as 24th September, and the most recent broker research note is subtitled ‘Confirming the growth path’, so it looks like the severity of these events has taken everyone by surprise.
This is a useful case study in what can go wrong with High Flyers when the business prospects begin to diverge from market sentiment. We can see that diluted normalised EPS has been struggling to push on as far back as FY18 even though the share price went from strength to strength in that period.

With the benefit of hindsight, problems have been growing ever since 3M was acquired in early 2020 and it seems like the bad news has leaked out over quite a long period of time. That makes me wary, especially when coupled with a lack of meaningful growth over the past few years.
On the one hand, the fall could be overdone but on the other, selling the old milk business and committing to what now looks to be faulty product lines could prove to be a drastic strategic misstep. As such, I’m not going near the shares right now until we have more detail in the delayed final results.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

116 comments
Paul,
Can you look a recent interims for CyanConnode -- currently spiking up
Re. Avon Protection (LON:AVON) , I would suggest that the signs were there close to the top back in 2019 when adjusted results diverged significantly from statutory results. There were multiple adjustments in the 2019 FY results, but the largest one was £5.4m written off in exiting the fire protection market, so this clearly isn't the first time they've struggled at a new line of business.
However, I think they are starting to look a bit interesting again, surely there's nothing left to go wrong anymore!?
Oops, my apologies, got that wrong - amazing how memory can play tricks with dates! The 2019 FY results with the fire protection exit adjustment actually marked the start of the big rise from £20 to £40, it was the 2020 FY results that marked close to the top, with even larger adjusted vs. statutory gap, but most of the adjustments to do with the acquisitions, and hence maybe reasonable as long as they don't mess up the acquisitions.
Given I have positions in Avon Protection (LON:AVON) and Tremor International (LON:TRMR) which both seemed to think today is Friday 13th, not the 12th and on a day when the FTSE100 index is down about 0.5% I opened my summary folio at close of business to find ….. it was up (albeit only a bit) on the day. Some unlikely gains out of left field seem to have saved what looked like being a pretty s***ty day. I guess that’s the benefit of diversification. TGIF ….. good weekend to all.
Gus.
Commiserations Gus, we have all been there at some point. My cardinal sin was to buy shares in a company called Aero Inventory that went bust, principally due to too much debt accompanied by some management shenanigans if I remember rightly. It was a very heavy capex business. Tough lesson to learn, but ever since l have steered clear of debt burdened companies and those where heavy capex is necessary for the operation of the business.
The well worn phrase 'What can possibly go wrong' is part of my thinking process when weighing an investment case and I still manage to get it wrong on occasion.
Perhaps the clearest example yet of how useless the investors chronicle is. Avon Protection (LON:AVON) was tipped as a buy in Nov 20 at a price of 4240p (on an eye watering valuation at that time), tipped again in Jan 21 at 3140, then again in May at 3328p, and again at the start of November at 1915p. Today they finally moved to a hold at 900p. Thanks for that IC (don't hold AVON but thought this was quite amusing).
IC tend to support their tips all the way down, rather than admit they got the original tip wrong. Seen it many times. Then crow about the winners.
I have seen that in this column many times in fairness.
But this is not a tipping site and I don’t recall the writers, crowing about their winners.
Are you talking about the writers of the reports or members posting?
Doesn’t beat IC’s phenomenal vision to tip Patisserie Valerie the evening before the shares were suspended!
I couldn't get myself to swallow Avon Protection (LON:AVON) previous sky high valuation and it sat on my watch list but it looks more interesting now. I think AIM listed companies like this with defensive (pun intended) qualities are often chased to giddy SPs due to the IHT reliefs available. Games Workshop (LON:GAW) is probably another example of this. Downside is when sentiment turns the SP decline can be brutal.
Isn't that IHT relief only available for the AIM listed? I think the big fall at Avon is more to do with reputational damage they've done with their biggest customer.
Ok, except neither Avon Protection (LON:AVON) (no position) or Games Workshop (LON:GAW) (I hold) are AIM listed companies...
Keep looking at Games Workshop (LON:GAW) but can’t bring myself to pay the multiple.
I really like Warhammer+ as a concept and I’ve been spending a small fortune in store recently upgrading an old army to Primaris- but I just remember the Robbie Burns story about Cafe Nero and I remember how they made about £2k worth of purchases with them worthless overnight when they binned WHFB. It’s literally taken me 7years or so to forgive them for that!
Tremor International (LON:TRMR) Wow!! how to shoot yourself in the foot.......
Release great results 15% ahead of expectations, have a webcast where you tell everyone how excited you are for the business future, discuss how you will be doing a lot of roadshows in coming 3 months to introduce a new wave of investors to this exciting business............ and then..........
release an RNS the following day saying the the CEO, CFO & COO have all sold a bunch of shares to the value of $1.2m as part of a non discretionary share sale scheme !! That's not exactly the signals eager investors will be looking for and now the stock is 20% off its high post results!!
To be fair CEO has a lousy track record of sales timing - did a load down at 200p but nonetheless an explanation as to why the sales are taking place may be more reassuring.
I have asked their 3 sets of IR/financial PR but whether I will get a reply......
Tremor International (LON:TRMR)
davidjhill
Wow!! how to shoot yourself in the foot.......
The directors havent shot themselves in the foot exactly as their exit price was before the huge drop today (presumably on this news?) - more shooting shareholders in the foot i would say than themselves.
Is this situation spookily like BOTB - hmmmmm. I guess the future newsflow will decide that one.
In their defence they need to sell sometime and presumably the decision to sell was before they knew the news yesterday was good (hmmm cough cough) - to me selling immediately after trading update is the "fairest" time to sell - although if the decision to sell yesterday has been made sufficiently far in advance does it matter? hmmmm
Remember it's a "non discretionary" sale so there was no recent decision involved. I'm not 100% up on the US rules but I believe at some point in the past the board will have authorised the sale of a set number of shares and then appoints a broker who is responsible for executing it based on their own decision criteria. That way as a director you are never "inside" when any sale is made as you have no control over the timing. They have all sold more over recent months in the same manner. Some just a couple of weeks back before the Q3 results.
If anyone knows the exact manner in which this director share sale scheme works in the US that would be useful info.
But this tells us there is an order in the market to sell by the directors (all of them!) but we don't know how many or why. They were openly very bullish on prospects and growth and the undervalued nature of the stock on the webcast, so why sell at all? Why not hold them until the market recognises the value?
Now it could be for tax purposes after stock based compensation that is being dripped in? It could be that more stock options are due to exercise and they only want to hold a certain amount of stock? If it were a single director it could be for personal reasons - but in this case it is all of them at the same time so it is coordinated.
Not telling existing or new investors the rationale has hammered the stock though. Until today I felt the stock was very cheap - now I'm wondering what the directors know that I don't. I'm fine with them taking chips off the table for diversification or tax purposes or a divorce etc. What I don't like is a coordinated sale accompanied by silence even if they do still have a lot of shares remaining in ownership.
LON:TRMR I was put off by the director sales prior to the US listing and that gave me pause for thought when the results came out. The forward looking statement was quite negative in my view given that it is in a growth space.
Regarding Paul's section he posted re Volex (LON:VLX) at 03 54 this morning so is probably having a nap now.
https://www.stockopedia.com/co...
£Avon have seen a huge drop and I have basically set up to buy some of it drops under 900p as that is where I think the risk and reward are fair value.
Considering the recent director purchases, within the last ten weeks, it would appear that this is also a massive surprise to them.
Whilst current management is now struggling to retain credibility, my view is this will lead to change which will see the price recover sufficiently to warrant the decision to purchase , with less than 1% of portfolio value being used.
I can also understand the leave well alone argument as well
Jack's section.
Paul's sectioned.
£VLSV.L has turned a very big corner. Yes, it has taken it's time. This is carbon sustainable aviation. It will produce carbon negative fuel, and it will be commercially available as early as 2026.
Projected revenues forecast to bring in $3 billion over the course of the offtake agreements.
Hi Paul, was wondering do you still hold Volex?
Doubt it. He's on about strike 15 already...
Another reference point while picking over the bones of the Avon Protection (LON:AVON) announcement; they paid 3M $91m (plus a possible $25m contingency fee that I don’t believe has been/will be paid) for the acquisition in January 2020. Today’s fall has taken about £250m/$340m off the company’s market cap which has already been dragged down largely attributed to problems in the ballistics/body armour business segment (although other issues were reported in the earnings updates on 13/10 and 24/9). Even writing off the business at nil value and attributing the same again in closure costs would only account for about half of today’s decline in market cap, suggesting perhaps that Mr Market maybe thinks a large chunk of the rest of the business is toast. I don’t agree with that analysis but that’s what the share price seems to be saying.
Gus.
I respectfully disagree. Mr Market is saying that you as a management team no longer have credibility and as your ability to forecast has been called into question so we're going to assume all your other forecasts are questionable. We're going to value on trailing not forward earnings until you can restore trust. I imagine a lot of people are wondering if Team Wendy is a duffer too.
Agree that Avon Protection (LON:AVON) have now got a question mark around their due diligence on the acquisition of Team Wendy. Management's capability in serious doubt. This may have much further to fall. One to avoid imo (ex holder and not tempted at any price).
Re: Avon Protection (LON:AVON)
Not questioning that this is an almighty cock-up, and, based on today's price action, clearly something of a surprise to many investors (including Directors who purchased on 24th September).
But I would like to make the case that the correction is arguably overdone, possibly at least partly based on the fact that the markets are thinner on Fridays?
This has been a very professionally managed company over a number of years. Talk of writing off the entire body armour business seems, to me, a little premature. Not impossible, but much more likely to be a worst case scenario.
Based on some very rough calculations, I could see an EPS of 50p for FY22. Does it merit a P/E of around 19 at current levels? I would suggest that that isn't excessive given the long-held belief that the company could attract interest from US bidders and given the nature of its IP.
I sold on the bell this morning at 1236 having bought in recently at 1837 but have just bought back in at 963. I have no idea whether that will turn out to be a mistake, but, having followed this company and invested in it at various points over the last fifteen years or so, it has consistently scored highly on quality metrics. Just as there could be some delayed selling next week from holders who have decided to exit at any price, it would not surprise me if this firmed a bit from here when normal liquidity returns next week.
Re: Avon Protection (LON:AVON)
Before anybody else points it out, I accept that selling at 1237 and buying back at 963 in the space of a few hours is not completely rational behaviour. When I sold this morning, I did not anticipate that the price would fall a further 25% over the course of the day. While I felt that a mark-down of 35% was justified, I am not convinced that a markdown of more than 50% is based upon my assessment of the risk/reward.
Well done on getting 1237 to be fair, I could get a deal done until it had dropped to 1129 despite putting a sale order in pre-market. Maybe that was my mistake and I should’ve done it live as soon as the auction finished.
Anyway, seems rational to me, you now have 25% more shares than yesterday so if it recovers you’ll always be 25% better off.
Re-reading the Avon Protection (LON:AVON) RNS with my rose-tinted specs firmly in place, it says this about the VTP ESAPI plates - '[they] have encountered a failure in First Article Testing which will significantly delay the likely approval timetable for this product' and this about he DLA ESAPI body armor plates 'approvals for this product now expected in the second quarter of our financial year ending 30 September 2022 ("FY22")'. Obviously, there is a risk that approvals don't come through. But there is also the possibility that approvals will just be delayed and that the orders will, consequently, flow through, but at a later date. There is a risk that orders are lost but, optimistically, they may just be delayed. We don't have enough information at the moment to assess whether this is delayed or lost revenue. Or whether there will be penalties. The inference is that the strategic update will announce the sale of the body armour business but that may not necessarily be the case.
Just trying to find some positives from a situation that is fraught with uncertainty.
regarding Avon Protection (LON:AVON) and in fact any other company that gives out a profits warning, this was a big mistake by Avon and not just a small profits warning. So do not expect the market to be rational with the sp. The Sp has been dropping for a year indicating something wrong. There was no quick bounce back yesterday which would indicate most investors do not believe this will recover quickly. There are definitely patterns when a company gives out a profits warning and with a major warning the market will want to see proof of a turn around. Typically, when a profit warning happens in a trading update, there is often another fall come the results as investors are spooked once again by the results caused by the warning. This seems to happen over and over. The last company I saw do this was Venture Life (LON:VLG) which you can go check out. Ofc, it all depends on how bad the update is, and Avon Protection (LON:AVON) gave a stinker, giving little details and only loss of forecast revenues and no actual figures of capex lost. This error should not have happened as their in house testing should of made sure it passed the tests. I believe confidence in the bod running Avon Protection (LON:AVON) is lost. As I mentioned yesterday, let the dust settle and wait on future news to come out. Investors do not know enough about this at the moment.
The IC online article on Argentex (LON:AGFX) was on 8th November so there may be another reason for today's spike.
Argentex (LON:AGFX) Probably the fact that the magazine is received today and a lot won’t use their website but rely on the mag.
Guy's, you have been asked many times to put the company you are referring too in your post and still many don't bother. eg "There was a positive mention in today's IC" Why should I keep having to scroll back to see what on earth you are talking about? It's simple just put the ticker.
The comments are threaded. Use the tools.
Use the ticker as per advise on every SCVR header " include the company name/ticker, otherwise people won't necessarily know what company you are referring to."
Todays forum is a right dogs dinner.
I have just looked at threaded view and they are still all over the shop.
I hate using threaded view.
*shrugs*
Half the comments, even if you put the ticker, they make no sense without the context of what they're replying to. Standalone comments it makes sense to put the ticker, replies, what's the point?
It makes a lot more sense if you know which stock is being talked about!
Those in glass houses etc
I do so agree! Even if you click on a ''In reply to....'' link (if there is one) that takes you to a totally different place in the comments section when you return, which is just as infuriating.
BringBackThe DownVoteButton
It would seem a simple upgrade for the system to block "Add Comment" and "Add Reply" if there is no £ticker. (unless the comment includes 'no £ticker' !)
Paypoint (LON:PAY) shares down 8% on no news. Anyone able to shed any light on this fall? Maybe a broker downgrading?
Argentex (LON:AGFX) Not sure what is behind the 6.% rise today, volume also picking up.
The Case for Argentex
There was a positive mention in todays Investors Chronicle.
Ah, that explains it. As with IC mentions sometimes, it could be a temporary spike, but I plan to continue holding longer term.
The rise today will be from the “buy” recommendation from IC.
Avon Protection (LON:AVON) Seems there are a few investors wanting to catch a falling knife here. Why not wait until the dust settles. History usually shows the sp will continue to fall for some time and will likely fall again on this news when the results are published.
Agree with AVON - from experience I've learned there is no need to rush in here. These situations don't tend to see a proper recovery until there are clear signs that the issues are behind them and company is back on track. In other words wait a few months if needed until we see some positive trading updates. You won't catch the very bottom with this approach, but I've found this to be a much more profitable strategy.
I bailed out in August at 1850p following previous profit warnings. I originally bought in at 900p and topped up at 3200p. Broke even on the sale. I just didn't like the route Management were going with increased risks in total USA exposure following Milkplus sale and acquisition of Team Wendy. Balance sheet moved from strong creditor position to net debt and much confusion in translating various comparisons and forecasts when they changed from reporting in £ to $. All became a bit more complex. Big question marks about product reliabilty with failed testing, mostly emanating from previous acquisition. Management competence now very much in question. Add to this a $80m pension deficit (broke my usual golden rule of never investing in companies with a sizeable pension deficit) which is a considerable cash drain on profits and all told one to avoid for me. I wont be going in again at any price with this management team remaining in place.
Isnt the business that has blown up for Avon Protection (LON:AVON) the same business that they bought from $MMM a few years back? I remember at the time Terry Smith saying that $MMM had done a bad deal because their share price went down on the day it was announced and shares of Avon Protection (LON:AVON) went up. Now we see that view is completely wrong. It just goes to show that judging M&A on short-term share price reactions is foolish. It now looks like $MMM played a blinder in exiting that business.
Well - what did they know before they sold it is the question the lawyers will be asking. This could get very messy...
Its a fair question IGot.
Just had a look - the deal was done in Aug 2019, well over two years ago. It will be hard to make a legal challenge (which themselves are extremely rare) after that period of time, although they absolutely need to investigate why that purchase has gone so badly wrong.
Might be better off not incurring both cost and management time on a possible legal battle ?
Well, I just look at what's happened to Mike Lynch and think these things can drag on a long time.
You are probably correct in thinking that it's not worth going over old ground. Hopefully the strategic review will get to the bottom of what's gone wrong and the appropriate actions follow from there.
But these gov contracts take a long time and the development of the body armor must have been in progress in 2019?
So maybe back in 2019 3M knew there were potential hurdles/issues ahead to meet specs.
Of course this is always the issue with an M&A strategy. The buyers will always know less than the sellers. In this case Avon Protection (LON:AVON) management have shown they have made a complete mistake with the acquisition.
Next few sets of accounts will be messy. Also this does no good for Avon reputation for future procurement. The whole industry will know they royally screwed up the specs on this one, and it seems quite late in the process? As a buyer you'd now think twice procuring from Avon.
Hi Paul
Did you have any joy with the enquires into Hostmore (LON:MORE) & Electra Private Equity (LON:ELTA) (I Hold both)? I am particularly keen to understand the relative net cash/debt positions & where the Sentinel sale proceeds reside.
Best wishes Steve
I think Paul is having a (premature) TGIF moment!
PAUL
Why were your comments removed this morning (10:24 am). What was so bad that stocko removes it?
The censorship is offensive, the original comments made me laugh.
Stocko operate a "3 strikes and you're out" policy. I hope Paul isn’t in any danger of being banned!!!!
Given Jack covered all the shares this morning he's either banned or still sobering up.
Both, probably…!
I did think his comments sounded a bit like the stuff I come out with; being still 1/2 cut the morning after a good sesh the night before :)
Renold (LON:RNO) Link to Interview Directors Talk with Robert Purcell CEO
https://www.directorstalkinter...
A PIWORLD interview with Jeremy McKeown on the current investing landscape v history; and where he's investing. Since the 60s he says all currencies (except perhaps Swiss) have lost 90% of their value. With inflation he draws analogies with the 40s and 50s. Today he says regulation has neutered the banking industry. Good comments on value v growth investing - does anyone buy a stock not thinking it's good value?! A terrific listen. Video & podcast.
Join us today for the Tracsis (LON:TRCS) FY results webinar with CEO & CFO followed by Qs. Register here.
Future webinars:
Ig Design (LON:IGR) H1 results: 23rd November, 1pm. Register here.
Tpximpact Holdings (LON:TPX) (formerly The Panoply) H1 results: 2nd December, 11am. Register here.
I have just watched the Volex (LON:VLX) presentation. What I didn't realise was that they announced the acquisition of DEKA yesterday. It has a turnover of 44m euros and an operating margin of 14% which will likely be enhanced by the buying power of Volex.
I think Volex was perhaps overhyped and a correction was perhaps due. However, it seems it was overdone and the long term prospects for Volex seem excellent.
I plan to hold as a coffee can stock.
Volex (LON:VLX) completed the DE-KA acquisition in February.?? The original announcement was exactly a year ago.
https://www.stockopedia.com/sh...
https://www.stockopedia.com/sh...
Brilliant. Have I just listened to last years presentation? :-)
£WATR another fund raise this morning which is sadly not open to private investors.
It's a small discount and probably quite likely you will be able to get that in the market today as it adjusts to the funding round.
I just checked the prices now, 1250p to buy despite shares down 1.6%, spread is wide. I can sell for 1211p.
Lol, where's the ticker?
#doasIsaynotasIdo
Water Intelligence (LON:WATR) Yes I miss some, but I don't do it all the time.
Who cares if the Water Intelligence (LON:WATR) fundraising is not open to private investors? It's at a tiny discount (4%) and private investors have had ample opportunity to buy in the market at well below the placing price in the last couple of months, should they have been interested.
I'm actually very pleased that they are able to transact a sizeable fundraising at such a high price, and also happy that the placing is with institutional investors. I think it is important to get a few more core institutional shareholders in the business.
"Who cares if the Water Intelligence (LON:WATR) fundraising is not open to private investors? "
Who cares? Any investor that has been excluded & hence treated less preferentially than the other existing/potential owners of Water Intelligence (LON:WATR) .
"..private investors have had ample opportunity to buy in the market at well below the placing price in the last couple of months, should they have been interested."
Same is true for institutional investors.
You could have bought Water Intelligence (LON:WATR) shares at 1200p on 29 October, yet you're whinging about being excluded from the opportunity to buy at 1200p now, two weeks later, when the investment story is essentially unchanged.
I don't disagree that there are many instances where placings egregiously disadvantage PIs. However, this is not one of them, with the placing price involving a discount of just 4% to a market price that has more than doubled over the past year.
So, yes, I agree that the fundraising framework in the UK needs reform to make it fairer for all market participants. However, this is a poor example to highlight in support of those ambitions. As a knowledgable existing shareholder in Water Intelligence I do not feel at all disadvantaged by this fundraising and I think it is mistake to conflate this particular placing with the argument to change the wider process.
The spread is quite wide on Water Intelligence (LON:WATR), even now I have to pay 1250p per share. Again PIs are excluded from share discounts, it should be the same for all investors.
The RNS also says "Should the level of demand through the Bookbuild be significantly greater thanthe £10 million target, certain Directors and/or senior management of the
Company may be prepared to sell a limited number of ordinary shares to help
meet such demand."
If the Directors sell a lot of shares, there may be a price reaction that provides a further buying opportunity.
Volex (LON:VLX) - Following on from the shambles yesterday - the web host Investormeetcompany has re-jigged the presentation and it is now on their website.
Volex (LON:VLX) - I can't find the video on the Volex or Investor site, can you link it please ?
Found it now - you may need to register https://www.investormeetcompan...
o
I struggled through the live IMC Volex (LON:VLX) (I Hold) presentation yesterday. I was impressed by how cool management remained and the open answers given to questions. I particularly enjoyed Nat Rothschild’s closing remark that the difficulties highlighted the need to move to 400 gigabit data cables!
Castings (LON:CGS) Castings posted their interim results this morning and as indicated by an earlier trading statement demand recovered strongly but was impacted in the second quarter by variable orders from their OEM customers due to semi-conductor shortages impacting their production schedules. They have also experienced prices increases to their scrap metal and difficulties in the labour market.
Despite these headwinds, revenues rose 67%, gross margin recovered to 20% and net margin to 7.8%. The machining division posted a profit for the first time in a while. Looking into the second half truck demand remains strong but the underling OEM issues with semiconductors haven’t been completely worked through yet.
Castings has a very well invested foundry and is benefiting from the automation improvements made over the past years. It also has a very strong balance sheet with net cash of 20% of the market cap. This positions the company well to withstand any short term difficult trading conditions.
There is a webinar for private investors on 18 November at 12pm. Register here to attend
Harwood Capital have disclosed a (new) 16.2% holding in perennial Crufts candidate Spaceandpeople (LON:SAL) this morning. (I think it’s a new holding, not entirely clear - please shout if you know better). They usually have a nose for hidden value so interested to see if anything comes of it.
https://www.investegate.co.uk/...
Gus.
£Sal I can't see from that announcement how much they paid. Any ideas folks?
Harwood aren’t on the £SAL shareholders list on the Stocko report so I guess it is new. The top holders listed are all individual investors, not seen that before, with no institutional holdings at all until now. At only £2m market cap I guess there’s limited downside.
The forecasts for Spaceandpeople (LON:SAL) look almost fanciful. What is going on? Pre COVID they were doing roughly £10m of turnover and now forecast £140m with £3-4m of profit.
While a 16% holding is significant for them in pounds and pence it is peanuts.
A speculative punt on the return of retail or a strategic investment based on an in depth understanding of where the business is going?
If Harwood have someone lined up who thinks they know what to do with Spaceandpeople (LON:SAL) then there could be a good return for them. I expect they will look to take it private.
I assume those Stocko forecast numbers are garbage.
There is no buying or selling. Its just the Strategic Trust has changed managers to Harwood. So this RNS is just to disclose this.
Spaceandpeople (LON:SAL)
Apologies, my bad. Going to the Spaceandpeople (LON:SAL) website, it shows Gresham House had a 16% holding as of June 30th, 2021 so not a new position. https://www.spaceandpeople.co..... For some reason it wasn’t shown as a major shareholder on the Stocko report under the major shareholders list, hence my confusion that it was a new position. Something seems to have pricked up interest in the share price in the last couple of days though.
Gus.
re Spaceandpeople (LON:SAL) (I hold), the bid price I am seeing moved from 9 to 10 over the past few days, and jumped to 12.5 this morning. Just on a name change for one of their shareholders? The market is of course thin to the point of non-existence.
RE: Castings (LON:CGS)
It's a good company, albeit not the sort of thing I'd ever want to invest in due to the low returns on capital. However, unlike many others the company doesn't varnish the truth so it's always an interesting read. Their update today summarises the challenges facing businesses:
After a strong start, the current period has been impacted by supply chain disruption affecting our commercial vehicle customers, which represent 70% of group revenue. As a result of these issues (particularly in respect of semiconductors), the OEMs have been unable to build sufficient heavy trucks to satisfy the high demand in the market.
Group despatch weight during the first quarter of the financial year was in line with recent years before COVID-19. However, with the OEMs having to reduce truck build rates to below their order intake levels, group sales were reduced from the last two weeks of June and into the second quarter.
Whilst forward demand schedules from our customers have remained high throughout the period, the conversion rate to actual sales has been significantly below what we would normally expect. In an attempt to cut across these fluctuations and remain efficient, higher production levels were retained and inventory levels increased. However, this has been hampered by labour recruitment difficulties and, as a result, we closed the machining business for a week at the end of September.
Raw material prices have continued to rise throughout the period which, with the time lag in the associated sales price increase, has continued to put pressure on margins.
https://www.londonstockexchang...
Beyond that the results aren't bad as they've bounced back from CV-19 restrictions. The balance sheet is strong, they'll easily be able to ride out the disruption. Weaker companies won't be so lucky.
timarr
Morning Paul/Jack - Kettle's on !
Could you have a look at Works Co Uk (LON:WRKS) if you get time - Looks set to do 7.2p EPS (confirms in-line today) this year on a PER of 8 - Confirms Net Cash of £17m (£10.0m expected to unwind during the H2), let's call it £7m against a Mkt Cap of £36m (up from ~£1m previously).
Thanks!
Avon Protection (LON:AVON) have this morning issued a worrying Body Armor (sic) Strategic Review. Assume the brace position everyone?
Time to dig out the profit warning survival guide.
If I remember correctly the immediate action on receiving a profit warning is “sell”. If you like the stock you’ll probably get a chance buy it back cheaper over the coming weeks.
Market wisdom generally stated profit warnings come in threes, I believe this is the second one so there’s likely going to be another at the end of the strategic review.
I imagine the lawyers will be circling as this has come from a recently acquired part of the business so in time there may be recoverables and a better business going forward. But we don’t worry about that today.
Disclosure, I have a tiny Avon position because I failed to heed the profit warning survival guide and thought I’d buy the dip. I have put a pre market open sell order in to dump them asap.
If I remember correctly the immediate action on receiving a profit warning is “sell”. If you like the stock you’ll probably get a chance buy it back cheaper over the coming weeks.
This is the third major profit warning in a year, along with a couple of small ones, so could, by the rule of three, be a good entry in the medium term.
A huge drop of 42% this morning, this is now firmly within the scope of the SCVR. I intend to do a lot of digging into this to put it through my wringer. I would be interested to hear the thoughts of others. I used to hold many moons ago but looks like the narrative has changed somewhat.
I’ve just seen the live share price, it is a capitulation!
You can say that again ! It's dropped by about 35%-40% the last time I looked and now must be back in the SCVR for Paul / Jack to do a write up on it.
Avon Protection (LON:AVON) : 37% down before 9am. Eeek!
"Our FY22 revenue guidance included approximately $40 million of body armor
revenue. In light of the above, the financial contribution from our body armor
business in FY22 and beyond will be significantly reduced, with the ultimate
impact, including any associated cost savings, depending on the outcome of the
review process."
If you wipe of £30m ($40 ) from the 2022 total revenue estimate of £239m, then is a drop of 12% in revenue. I guess, if they pull out of the body armor market completely, then, it impacts future growth, but not seeing a justification for a 37% drop in the price?
Yes that’s the conclusion I came to also regarding #AVON (ie an overreaction) hence an entrance from me this morning.
I would be cautious. Some will have hit sell on the open, but some PIs wont see this news until lunch or saturday. Institutional holders will probably need to 'meet' before deciding what to do. Knowledge is transmitted instantly, but that email is read at leisure.
If the current price is an undeniable overreaction (825 . -43.26% as at now) feel free.
However, on average (i think) the price will fall further in the short - medium term. Momentum is a thing.
The PER is still 19.3, Expectation of no growth implies PER about 10-12.
My process involves establishing how much I will invest, then putting 25% in as close to the news as possible in case it's all a head fake, which I did this morning, then dribbling the remaining 75% in over a month. 25% a week works fine if there's no other imperative.
This gets an optimal entry which is of great value if shares then appreciate by high single to low double percentages. But it should be said that, for the long term investor, if the shares eventually recover hard on a change in the narrative or fall precipitously on further profit warnings, it doesn't make the same difference - the important thing is to have bought or not!
Avon Protection (LON:AVON) : 37% down before 9am. Eeek!
"Our FY22 revenue guidance included approximately $40 million of body armor
revenue. In light of the above, the financial contribution from our body armor
business in FY22 and beyond will be significantly reduced, with the ultimate
impact, including any associated cost savings, depending on the outcome of the
review process."
If you wipe of £30m ($40 ) from the 2022 total revenue estimate of £239m, then is a drop of 12% in revenue. I guess, if they pull out of the body armor market completely, then, it impacts future growth, but not seeing a justification for a 37% drop in the price?
A £30m drop in revenue without any associated cost savings (unlikely but possible) would equal a 60% drop in profit, hence the big fall. Over a longer period and assuming no reputational damage, however, the effect might be closer to the low teens %ge you envisage.
Hi Andy Sav.
Contrary to accepted wisdom about profit warnings, I agree with your take on the Avon Protection (LON:AVON) RNS and have bought some at 1100p-ish. Long term holder, I’m now back at the price I bought in 5 years ago (having been up over 4x at one point). Body armour is a relatively small part of the whole and an area of growth but the helmet and respirator bits are fine (other than the damage to overall reputation and possible knock on effect with the US military, its main customer). At this level the business is vulnerable to a takeover but if it keeps its independence I still think its long term prospects are decent. High risk.
Gus.
Agreed. My entry was around £20 and I’ve topped up a smidgeon with a view to restoring my stake to its previous size over the next few days of price discovery.
Am thinking of dipping in too- am most intrigued by the size of the capitulation. As I write the daily volume is 1500% of its average size. That is seismic.....think I'll see how it progresses for the rest of today.
AVON
I would be very surprised if the business did not already have a pretty good handle on the total financial impact of this business segment. And if they haven't then they really should have, seeing as it came in as an acquisition and with all the focus on the division over the last 12 months.
Having made this announcement, in my view it is very unlikely that the results of the review will be in any way positive. Their main job will be to assess the impact on the coming this year’s accounts of how much to write off and hence the short delay in announcing them.
The shock business review, the delay to the accounts and a potential failed acquisition, all on top of a year of warnings and share price slide do not show the management in a good light at all and I guess many shareholders have consequently given up on them.
Avon Protection (LON:AVON)
The shock business review, the delay to the accounts and a potential failed acquisition, all on top of a year of warnings and share price slide do not show the management in a good light at all and I guess many shareholders have consequently given up on them.
I am no expert on auditing but if a material event has happened at or near the end of the financial year i see that as simply being unlucky timing that beyond the control of the directors. Seems pretty obvious that the as yet unfinalised figures for 30/9/2021 will now have a different spin - so i for one would not default to placing any blame on directors for this mechanical isue if that is what it is. In some respects tackling the issue head on and adressing the accounts numbers promptly seems very responsible directorship to me - many companies bury their head in the sand pretending there are no issues when there clearly are (Staffline being prime example. Note i am solely talking about the new issues and knock on consequences - i dont know enough about the company to have an opinion if they "should have seen this coming" earlier.
at the risk of looking stupid/silly - todays comment is a bit cryptic. Can anyone enlighten me?
A recent news article connected to £RMG highlights that the FTSE100 is very cheap at the moment according to JP Morgan but at the same time Credit Suisse downgraded the UK small cap market. Should we currently be looking towards the larger cap stocks
I’ve copied the comment on the small caps here. Full article is connected to £RMG news feed. Any thoughts?
”Credit Suisse downgraded UK small cap companies to
underweight last week, saying their higher valuations compared
to large caps were unwarranted due to lower expectations of
manufacturing and economic growth. urn:newsml:reuters.com:*:nL4N2RT1T4
(Reporting by Siddarth S in Bengaluru, additional reporting by
Muvija M; Editing by Sachin Ravikumar and Shailesh Kuber)
((Siddarth.s@thomsonreuters.com;))”
I should add that I don’t agree with Credit Suisse. I think there is value across the whole uk market. Should have said this originally.