Small Cap Value Report (Fri 13 Jan 2023) - REVB, GLE, LIKE, WIN, DIA

Good morning, just from Paul, as Graham doesn't work on Fridays (usually quiet for news). I've got a long list of backlog items, so I'll be putting in a full 6 hours today, to cover as many companies as I can by usual finish time of 13:00. Plus of course whatever news is delivered fresh on today's RNS.
That's it from us for this week. Have a lovely weekend, and as usual I'll be podcasting tomorrow.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda
Paul is writing all of today's report.
Long sections:
Revolution Beauty (LON:REVB) - a fascinating update today, following investigation of financial irregularities discovered in the accounts. Shares have been suspended since Sept 2022, but it sounds as if there's light at the end of a tunnel, with the company still solvent, and bank being supportive. Everyone should read today's announcement, as it details how the figures were fiddled. (more detail below)
MJ GLEESON (LON:GLE) [I hold] - a trading update that (as expected) reflects consumer caution, with a significantly reduced Dec 2022 (interim period end) closing order book. Cancellation rate has improved in last 6 weeks, but new reservations down 25%. Hence expect a soft H2 to June 2023 - which is now reflected in more realistic broker forecasts, and a bombed out share price. With an immaculate, ungeared balance sheet, and a remarkably low valuation (well below NTAV), I think this share offers a lovely medium-term buying opportunity, to hold through any market volatility. Short-term obviously things could be more challenging - that's why it's so cheap! the whole sector looks cheap actually. If you expect a major bear market in house prices, then they're not cheap. So this depends on your macro view. Thumbs up overall (more detail below).
Likewise (LON:LIKE) - I've reviewed its FY 12/2022 trading update (from yesterday) - in line with (reduced) expectations. Looks quite an interesting growth company. I'll give it a tentative thumbs up for the growth potential and decent balance sheet, although profitability is only marginal at this stage. Needs more research. (more detail below)
Short Sections:
Wincanton (LON:WIN)
331p (down 3% at 10:31) - mkt cap £412m
Q3 update (Oct-Dec 2022) - trading in line with expectations in all 4 segments. Makes the point that higher inflation means some customers are seeing lower volumes of goods shifted (not good for a logistics company, which is paid by volume, not value).
New business pipeline increasing. Inflation is increasing costs & limiting growth. I seem to recall WIN mostly has open book contracts with its customers (so has proven ability to pass on cost increases), although it doesn’t mention this today. Expects difficult conditions to continue in FY 3/2024.
My opinion - a subdued update today, but the key thing is it’s still trading in line with expectations, despite headwinds, and seems to be able to cope with whatever market conditions are thrown at it. Large pension scheme is a key issue, and could trigger a shares re-rating if it’s resolved (previously indicated it’s nearly fully funded). I remain positive, thumbs up - shares look cheap to me, for a decent, resilient business.
EDIT: I've just seen an update note from Liberum (many thanks) which refers to "headwinds building" for FY 3/2024, and reduces its profit forecast by 6%. That's a drop from 40.4p to 38.0p, so I suppose you could argue this is a mild profit warning for next year, or rather an adjustment downwards of forecasts (as it relates to next year, I won't add it to my profit warning spreadsheet). Still looks cheap to me though, so I'm not particularly worried by trimming forecasts for next year - and of course, doing it in advance like this, makes the company less likely to miss forecasts in future (a proper profit warning).
Dialight (LON:DIA)
260p (down 19%) - mkt cap £85m
FY 12/2022 trading update - says the seasonally key month of Dec saw lower than expected revenues, lower demand & order deferrals. Revised guidance is £5m underlying operating profit, below previous (not stated, so I have to waste time looking for it now). Having looked atthe last 4 results & trading updates, I still can’t find what previous expectations were! All it said is that “further strong progress” was expected for 2022, implying considerably more than the £4.5m u/l operating profit actual for FY 12/2021. DIA delivered £3.1m in H1, so the latest guidance suggests a fall to £1.9m in H2 2022.
Stockopedia consensus is for £4.8m PAT for 2022, so that would gross up to say £6m assuming a tax rate of about 20%. That’s not much different to the £5m guidance provided today. Although there was £1.4m in finance costs in 2021, so assuming the same this year, I reckon previous operating profit guidance must have been about £7.5m. That’s been lowered to £5m today, so a one third profit miss, I estimate. The company could have just told us the figure, but declined to do so - this lack of openness is annoying, who writes these things?! They’re wasting everones’ time, making us work out for ourselves a number that they already have at their fingertips. Which doesn’t make me more amenable to viewing the share positively, because they’ve introduced unnecessary confusion.
Net debt is almost unchanged at £20.9m, and it talks about focusing on working capital reduction in 2023, to reduce debt.
It mentions “Sanmina litigation”, which I haven’t looked into, but £1.2m costs in 2022 suggests it’s not a minor consideration.
My opinion - this company continues to be accident-prone, there always seems to be something going wrong, turnaround actions, etc. I’ve been following it for years. It strikes me as too unpredictable, so almost impossible to value. So I have to give it a thumbs down unfortunately, but that’s based on a quick review, not in-depth research, as with most shares we cover here.
Revolution Beauty (LON:REVB)
Outcome of Independent Investigation
This is a fascinating update, which everyone should read, because it details how previous management cooked the books, in order to meet targets. I’ll read it more thoroughly later, but wanted to flag it initially here as being very interesting, after a quick skim.
The good news (I think?) is that the company doesn’t sound as if it’s bust, and has continuing bank support.
Shares have been suspended since 1 Sep 2022, and the delayed FY 5/2022 accounts need to be published (once the delayed audit has been completed). Today’s update says REVB is working with its NOMAD towards lifting the suspension of the shares asap.
Current trading doesn’t sound great, but comments are not very specific.
My opinion - at first sight, this sounds as if REVB shares could return from suspension, and the business survive. Although expect big write-offs to correct the accounts for the dodgy previous entries. Plus of course likely substantial fees from the accountants and lawyers who’ve had a field day on this one.
Another interesting angle is the takeover potential, as Boohoo (LON:BOO) grabbed a 26.5% stake just before the shares were suspended. REVB product & brand make an obviously good fit with BOO’s customers. Although note that now discredited former management are also major shareholders, so it’s unclear how that will work - I think they might be able to block a takeover bid.
Overall, this is a timely reminder that we cannot necessarily rely on published accounts or forecasts. It’s easy to cook the books, and today’s update nicely explains some of the tricks that were used to inflate profits here at REVB.
I would add that the bodies are usually buried somewhere on the balance sheet - this is why excessive-looking receivables and inventories are so important to spot, as they’re often signs of trouble. Indeed, I’m pleased to say that I spotted and flagged the issue of excessive inventories here on 2 Aug 2022. So our balance sheet checks are very important at trying to spot, and avoid trouble. The share price had already collapsed by then, but the issue was in plain sight from the interim accounts which were published much earlier, on 24 Nov 2021. So I do think investors could, and should, have spotted the problems building here, long before the share price collapsed, if they’d checked the balance sheet.
MJ GLEESON (LON:GLE) (I hold)
386p (up 1% at 08:49)
Market cap £224m
Housebuilders all look cheap at the moment, because the stock market has been factoring in a decline in sales and profits, due to widely reported macro factors (higher interest rates, the mini budget that saw mortgage rates spike up, squeeze on household incomes from high inflation, lower confidence, and signs that house prices have begun to fall). All sounds terrible, but I think shares might have overshot on the downside.
Reasons to be cheerful on the sector are primarily balance sheet related - unlike previous recessions, this time around the housebuilders are mostly debt-free, and have huge land & WIP assets. So they’ll be able to ride out any downturn with no worries about solvency or having to raise fresh equity.
Also, the UK has a widely reported, and seemingly chronic shortage of housing, unlikely to change any time soon, due to population growth and a log-jammed planning system, with complexity and delays that entrenches the strong position of the main householders.
Why Gleeson? This is what a friend asked me at a recent lunch, when there are larger housebuilders on similarly low valuations. I prefer Gleeson because -
- Other housebuilder shares have bounced strongly from recent lows, whereas GLE only began rising a few days ago - so a catch up gain to be had maybe?
- Gleeson supplies houses right at the bottom end - average selling price is only £170k (for small houses, not flats) so there’s strong demand, and good affordability, even for a couple earning minimum wage, as the company often reminds us. I think this probably makes Gleeson less likely to suffer from any fall in prices that could be worse in more expensive markets in the South of England for example.
Latest news today - nobody’s going to be expecting good news! So the only question today is how bad is the short-term impact of the macro factors?
In the circumstances, I’m pleasantly surprised (but that could be unconscious bias, as I recently bought a few shares personally, and we all know that our minds can play tricks on us, no matter how analytical we like to think we are).
MJ Gleeson plc, the low-cost housebuilder and land promoter, provides a trading update for the half-year ended 31 December 2022 (the "period"). The Company will report results for the period on Thursday, 16 February 2023.
Key points only (there’s more detail in the RNS) -
New CEO Graham Prothero started on 1 Jan 2023, as planned.
H1 completions 894 homes (down only 4% vs H1 LY)
Selling prices “remained stable”
Cancellation rates - improved a lot in the last 6 weeks to 6.5 per week, down from 11.5 per week in the previous 6 weeks to mid-Nov. That’s encouraging - suggesting maybe a panic withdrawal of buyers could now be abating?
Reservations - soft in last 6 weeks 22.5 per week, down 25% on last year.
Working capital - is being “tightly managed”
Net cash £13.5m (down from £38.2m a year earlier) - I’ve checked the last accounts, and a £105m undrawn bank facility is available until Oct 2024. See the going concern note in the last accounts, which models a severe but plausible scenario, and remains within covenants.
Forward order book - is down a lot, suggesting a tough H2 is likely, at only 319 plots (LY: 616 plots).
Outlook -
However, we are cautiously optimistic of a recovery during 2023, due to a number of factors, including that mortgage rates continue to fall from the highs experienced in October 2022, and the need for low-cost, high-quality homes remains acute. A couple earning the National Living Wage (which is set to increase by 9.7% on 1 April 2023) can still afford to buy a home on any one of our sites. In addition, there continues to be growing interest from new customers who might previously have considered a more expensive property built by another developer but in the current economic environment are attracted by Gleeson's more affordable price points.
As previously stated, the outturn for the current financial year is dependent upon the pace of recovery in the housing market over the coming months. A further update will be provided with the interim results on 16 February 2023.
Broker forecasts - were slow in coming down (larger housebuilders saw forecasts coming down starting in about July 2022), but now look more realistic -

Balance sheet - last reported on 30 June 2022 is ridiculously strong. No intangibles, and no interest-bearing debt, and NTAV of £272m. Even if you halve the value of its inventories (land & work-in-progress, at cost), NAV would still be fine at £129m NTAV. If GLE ever did get into financial trouble, then we’d all have much bigger problems than worrying about this share price! (since everything else would have collapsed).
Housebuilders are in a nice position, in that, in extremis, they can just stop buying land, and operate for cash by selling and not replacing each house that they build. There’s a huge margin of safety with this share, on fundamentals, in my opinion. Hence shareholders really don’t need to worry about the current downturn, as we’ll make money sooner or later, by just riding it out, with no worries about downside risk on fundamentals in the meantime. That’s very appealing to me. The share price though, could do anything, but I don't see that as risk, because I'm not going to sell. I'm just thinking out loud here, not lecturing!
My opinion - I’m happy with this update. The market has already priced-in a poor year for housebuilders (many seem to have June year ends). They’re tremendously well asset-backed, so it’s just a question of waiting a year or two maybe, for a recovery, and simply ignoring the share price between now and then. That may not suit everybody’s investing approach, because often people obsess about the short term share price, but it’s ideal for me.
As you can see from the sector list on Stockopedia below, many housebuilders are currently valued at below their own tangible net asset value (and remember all the partly or newly built houses are on the balance sheet at just cost, which should be well below the subsequent selling price). This is quite rare, to be able to buy shares below NTAV. It effectively prices in a significant downturn in house prices, which would need write-downs of land and inventories, as can happen in a severe market downturn. It’s lovely that this downside scenario is already priced-in, if (as with me) you believe there probably won’t be a major or prolonged downturn in house prices in the affordable areas that Gleeson serves. Nominal incomes are rising strongly due to inflation, which usually pulls up house prices, sooner or later.
If we sit on the sidelines and wait for a market recovery, then we could miss the boat. It’s people who are bold, and buy when things look terrible, at really low valuations, that subsequently do well, if they have the patience to ignore price volatility. In any case, it’s not a binary decision to buy or sell any share. So for the more nervous, maybe taking an initial small position, then watching/monitoring events, could be a good strategy - that’s what I’ve done with Gleeson - a small starter position, and then I’ll see how things develop.
FY 6/2023 results are likely to be poor, but everyone already knows that, and it’s in the price I think. Hence overall, a thumbs up from me, taking a medium-term view. I have no idea what the short-term share price will do - consult a chartist, or your tea leaves for that!
Gleeson is one of my top value/GARP watchlist picks for 2023, and disclosed on my spreadsheet here (I suggest bookmarking it, if you’re interested, to save me having to constantly put in the link). It updates the prices in real-time, which is quite useful to see performance. Although the idea is they’re intended as investments, not trades, so there will be some inevitable profit warnings, which is why I’ve picked things with strong balance sheets that won’t need to raise fresh equity, even in a downturn.
The housebuilders sector table below is a clickable link. It's fun to look at whole sectors, and you can then play around with different columns to display, StockRanks, and click on the column headers to sort by any variable you wish. This can throw up interesting shares to research. Although note that extreme cheapness usually means there's something wrong!
.

Likewise (LON:LIKE)
20.5p - mkt cap £50m
Likewise Group plc (AIM:LIKE), the fast growing UK floor coverings distributor…
… is pleased to announce that Total Sales Revenue for the year ended 31 December 2022 increased by 103.9% to £124.4 million following a progressive Q4 increase of 107.0%. Like for like Sales improved by 26.6% in Q4 culminating in 25.7% for the full year.
Valley Wholesale Carpets Limited ("Valley"), acquired in January 2022, has performed to original expectations in an undoubtedly challenging market and we are therefore very pleased with the contribution from Valley to Sales and Profitability.
The above sounds good. Stockopedia shows a broker consensus for £120m revenues, so the actual of £124.4m is nearly 4% ahead of expectations, good news.
Profitability - is in line with expectations, with the wording very similar to the last update (in line with exps) on 1 Dec 2022 (which I didn’t cover here, as it didn’t contain anything new).
The Group is on target to achieve the current market expectations and is confident in reaching its medium term objectives.
Whilst encouraging, the context is that LIKE lowered expectations with a profit warning which I covered here on 28 Oct 2022. That was my first proper look at LIKE shares, and despite the profit warning, I came away pleasantly surprised with its strong balance sheet (including £21m freehold property), and a small net cash position.
Broker consensus shows only 1.1p EPS for FY 12/2022 (£1.7m PAT), and 1.0p EPS for FY 12/2023 (£2.5m PAT).
Note that the share count rose due to a 35p placing in Dec 2021, to fund an acquisition. So there might be more dilution if further significant acquisitions are made.
The company is being run for rapid growth, rather than maximising immediate profitability. I’m fine with a growth strategy, providing there is a credible pathway to higher margins and profitability in future. So that’s the key area for research. Is management creating a lean, efficient organisation, or a shambles of overlapping acquisitions with duplicated costs (which arguably seems to have been what CEO Tony Brewer left behind when he moved on from Headlam!)
Investor presentation - was recorded yesterday, and is available now as a video on InvestorMeetCompany (IMC), so that’s down on my list for weekend viewing. I really enjoy results webinars, it’s so helpful to see management explain any business in their own words.
Larger competitor Headlam (LON:HEAD) which is one of my favourite value shares, are also doing a presentation on IMC, on 19 Jan 2023, so it will be interesting to watch & take notes on both, to compare. Although not back-to-back viewing, as that runs the risk of it all merging into one confusing hybrid in my mind - Headlam becomes bedlam!
My opinion - I’m not ready to switch my value allegiance from HEAD to LIKE in the carpet distribution sector. HEAD still has very attractive valuation measures, despite a strong recent rebound from the lows of Oct 2022 - not company-specific, as the last 3 months have seen an (almost) everything rally, which may or may not hold, depending on what individual companies report.
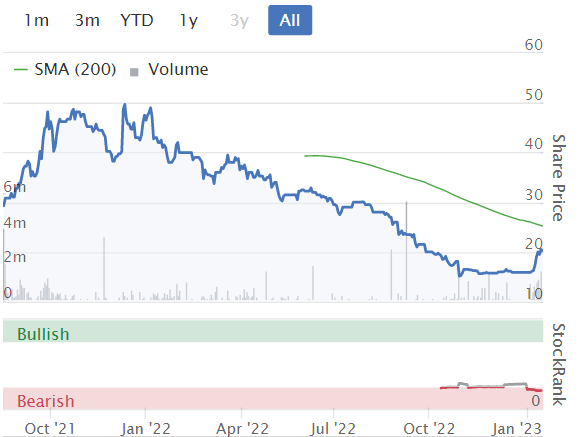
So far, so good with LIKE though. It listed in Aug 2021, and so far seems to have performed quite well. One for my watch list I think, or even a small, speculative initial purchase, although I don’t see the valuation as particularly cheap - looking at the chart, investors seemed to get over-excited about it after the initial float, with a painful reset over the last year to a more realistic valuation.
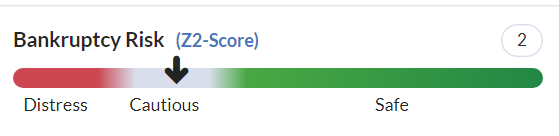
It's coming up on a shorting screen, which I think is probably a false alarm, but reminds us to check (and monitor) trading, and the balance sheet -
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

33 comments
Year in review
Hi everyone this is my year in review as a young investor at age 23. It’s a little late but I’ve been thinking a lot about what I have learnt over the course of 2022. lots of you have a wealth of experience, so any comment on what I have to say here will be greatly appreciated.
My first though in reviewing my year is that it’s my first bear market and how much I have learnt in it, firstly I have learnt the hard way that companies need good cash piles at least 3-6 months of cost in the bank to help them in trickier economic times such as this.
My second lesson has been using lots of different methods of working out value and working out a rough average has been useful. Using methods such as discount cash flow to work out an intrinsic value while at the same time using price earning and the value of a company’s asset, IP or brand to come to a conclusion has been this year has been lesson I’m going carry on with, less story and lots more of a maths based approach.
Thirdly, just reading and watching more whether it be both books and articles. YouTube videos on how to work out a value of a company or a podcast on the Psychology of buying value when everyone else is selling and looking long term. Along with hard learnt lessons this year this is how I feel I have improved as a long term investor.
My final lesson of the year was with the war in Ukraine it has taught me that when headlines are negative its a great thing to buy into. In October we had the failure of truss and all the market melt down that went with it. People where talking about nuclear weapons in Ukraine with Ben Wallace flying of to Washington and what at the time felt like never ending growing inflation number and a failing economy. But since then and it’s only been three months and there is political and economic stability, Putin didn’t use nuclear weapons and has been pushed back out of Kherson and is being mauled everywhere in the battlefield. Inflation seems to be peaking off and we are in recession but it doesn’t yet seem to be as bad as it was predicted especially within the housing market. Looking at the all share for example it hit a low of around 3700 on the 13th of October and is now on the 11th of January 4222. I added to positions in stocks such as Agronomics, lords trading and Eqauls During this time it has been good for my portfolio but I learned that having the courage to buy through the head,Ines and look long term has been my key lesson for this year.
Thanks everyone
Olly
Hi Olly
I’m no expert…no one really is…but I tend to concentrate on buying businesses that are conservatively financed & focussed on long term success…by so doing I avoid the need to think about macro…because that imho is a big fat waste of my time
It works for me
Thanks for that rhomboid1. When you say conservatively financed, are you looking for companies with little or no debt or large cash reserves or anything along those lines
On Appreciate (LON:APP) would like to hear thoughts from others on this takeover situation.
So the GM is going to be on the 20th Jan, and votes for this takeover are due in on the 16th Jan (Monday!)
So far, a very low percentage of irrevocable votes for the deal have been declared. On top of that, a fund that specialises in buying shares in takeover candidates, Samson Rock, has amassed 20% of the shares. Clearly almost enough to be a blocking vote, given that 75% of shareholders need to vote yes to have this takeover pass through.
And yet... there has been no news on an increased offer, etc.
Samson Rock has been accumulating shares since November (when the offer was announced), buying shares between 5-8% discount to the offer price. It might be that they're just arbitraging the price here (5-8% gain for a few months holding). But it seems like at a 20% stake, they are intending more.
Thoughts?
(I hold in the Boon Fund)
I've no investment in Appreciate (LON:APP) , but I do have an investment in Crestchic (LON:LOAD) where Samson Rock are now up to 10.68%.
Pardon my ignorance, but is the threshold 75% of issued shares, or 75% of those who vote? If the latter, 20% is approaching a blocking stake - especially if nominee accounts only vote those shares for which they have instructions - not always the case in my hazy recollection.
I thought I'd try to see what they have done in the past - but drawn a blank. Their website appears to need a login. And they are such a prolific issuer of Form 8.3 that it's impossible to see anything at a quick look.
So does anyone know if they have previously taken the relatively small price arbitrage, or have any examples of where they have sought to stir things up?
Revolution beauty is an interesting story and set of circumstances. I have some experience of the work done by the audit firm and the audit partner involved. I can say that although the red flags may have been obvious, identifying all of the matters investigated would not have been so clear, and the work done by the audit team, lead by the partner, would have been excellent to identify this awful abuse of directors power.
when reviewing the accounts we should, I would suggest, also take a little time to at least scan the audit report, to see the matters identified by the auditors as being significant areas of risk.
Regarding Likewise (LON:LIKE) - Tony Brewer was actually the Headlam (LON:HEAD) CEO until 2016. Likewise is a Headlam version 2.0.
MJ GLEESON (LON:GLE) - looking at my 'tea leaves' I'll wait for the next golden cross 50 passing the 100 (normally 200 safer but later to the party). 500p looks a reasonable support/resistance level so will set a price alert for 450p. Can also set a moving average crossover alert in stocko so make some notes and forget about.
Revolution Beauty (LON:REVB)
Fascinating stuff ref this section
The investigation identified a number of other personal loans made by Adam
Minto to a number of senior managers of the Group and certain of the Group's
non-executive directors (at the time),
Wowsers - this seems so wrong on many levels from a non experts viewpoint ref non-executive directors - surely the whole point of the neds's is that they need to be "independent" of the company and unbiased - is there any chance here someone been breaking the law? or commiting offences related to their directorships.
If ned's are allowed to do other stuff connected with company - why is that allowed ? i just don't see how they can fulfill the role they are engaged to do if their viewpoint is not objective and independent of the day to day running of then business. Certainly receiving loans from directors of the company seems plain wrong. Beyond crazy particulalry bearing in mind the other stuff that was obviously not done ethically.
If this is allowed then perhaps for slightly sketchy companies probing directors directly before investing may be the only way to go.
I don't know about the UK, but in the company I work for, which is US based, we get regular training on the illegality of 'channel stuffing' which is considered fraud. I can't see how the authorities don't get called in here.
Revolution Beauty (LON:REVB) Can someone please explain, is "Cooking the Books" the same as Fraud?
Practicably speaking i would say its very similar.
Obviously with these being different terms there may be some overlap where some cooking the books may not amount to fraud and some perhaps does. Unfortunately i suspect there is alot of minor cooking the books that goes on with listed companies.
Note some provisions are subjectively "estimated" and some accounting methods can be chosen "subjectively" froma list of options.
An example
Company directors can make a provision at year end for supplier returns - they choose "reasonable" basis for making these provisions - ultimately its subjective and hard to prove one is lying if they come up with plausible cock and bull story that is not known to be cock and bull at the time.
Also one may have choice of options ref stock writeoffs or depreciation rates used.
One can go from ultra conservative to ultra aggessive on both the above measures.
Its probably quite easy to go ultra aggressive and get that past auditors - in some respects if directors are trying to minimnise returns provisions and minmise stock w/offs - they are trying to maximise profits - to me this is cooking the books if they are not using honest fair and reasonable cals. They may not be doing anything techncially wrong though if the numbers used are agreed with auditors - note some peeps may call these adjustments window dressinga and not cooking the books. The reality is any directors that are looking to "maximise profits" rather than "get true values" probably are cooking the books even if that variety of cooking the books is deemed to absolutley fine by auditors.
It all stinks a little bit - any company that apears to be pushing the aggessive boundaries in any sense should come with red flags - as its so easy to manipUlate the numbers as one sees fit.
Hi not sure it’s quiet as “ easy” as you suggest to get past the auditors. So changes to depreciation rates, would require disclosure in the accounts. Change in stock provisioning policy, would require explanation, and as in this case potentially a pya, to ensure yony consistency. Sure there are some judgment areas, but nowadays, they are very few.
in revolution case, I dont believe there was fraud, just a deliberate attempt to mislead by generating transactions that made no commercial sense, in an environment, that seemed to be”poisoned” by a number of personal loans, possibly given so as to buy off those that should have been challenging. Utter failure by the NED’s for starters!
Agree that Housebuilders as a sector now seem oversold versus medium term prospects Paul
Personally I like Taylor Wimpey (LON:TW.) because they have close to £1bn of net cash (around 25% of their market cap) and a very solid landbank. Redrow (LON:RDW) similar in that vein.
My bigger picture view is that businesses like these will, as you say, operate on a cash basis for the next 6-12 months and not spend on new land. Indeed Taylor Wimpey (LON:TW.) basically said as much in todays update. That should mean the good quality ones remain profitable and will continue with decent dividends, albeit that I expect margins to drop during the year before rising next.
The thing that would worry me slightly about MJ GLEESON (LON:GLE) in the short term is that inflation effects and particularly household energy costs unfortunately hit the poorest hardest, and so I see the bottom end of the housing market as most vulnerable in the next couple of years. I've spoken to a number of estate agents recently and interesting at the top end of the market in desirable locations they are still selling at record prices (because half of buyers are cash and sellers aren't dropping asking prices because they don't have to move). At the bottom end of the market and first time buying there is more downward pressure. MJ GLEESON (LON:GLE) net cash isn't great - not a lot of protection there albeit they have borrowing capacity. But given interest rates utilising that facility will also eat margins and limit profit. I would say they are at the riskier end but agree if mortgage rates stabilise below here and inflation drops quickly they could easily see a 50% rebound.
Morning Paul,
Cracking job from you and Graham this week in covering so many companies - it's been hard to keep up! The new s/sheet is ace, really simple to use and gives a super holistic view of what's been covered during the week...thanks again for creating this.
Just finished listening to last weeks podcast and whilst not a frequent contributor, you inspired me to write a summary of 2022 performance. It's both cathartic writing and well as reading about other experiences.
Overall, I was down 10% for the year.
My stinkers were:
Boohoo (LON:BOO): still unsure why I held on so long. Maybe because I bought some tracksuit bottoms and liked them. I hope Robbie Burns doesn't read this - my behaviour was very un-spock like(!) but a great learning
CMC Markets (LON:CMCX): I still hold a few but should have sold on the first profit warning
My stonkers (those that didn't completely tank!):
Calnex Solutions (LON:CLX): held up nicely and has started 2023 well
iEnergizer (LON:IBPO): dropped back a little in Q4 but I continue to hold and think could be a takeover prospect given previous sale process
Fonix Mobile (LON:FNX): continues to do well (2023 NAPS pick), in an interesting space with plenty of runway for expansion
Anyhow, wishing you and everyone else a successful 2023. Keep up the fabulous work, it's appreciated.
Rich
It's ok Rich, I didn't read it!
That’s a relief! It was reading NT v5 whilst sat on a sun lounger that made me think “what the hell am I doing”!!
(I definitely don't know anything about your boo hoo trade.) I was on hols a while back and saw a bloke on a sun lounger reading NT. I went up to him and said "why are you reading that crap book?" He got the surprise of his life - he looked at me and at the pic then back again. He moved the book over his bits as I think he got embarrassed because he was wearing rather tight speedos.
Nah, I was just pleased to see you !!
It was VERY impressive Gibbo. Though obviously not in my ballpark.
Reading across from JD Sports Fashion (LON:JD.) announcement (young people have lots of money to spend on trainers apparently) I feel full employment is more important than inflation. So I feel MJ GLEESON (LON:GLE) should be okay assuming we don't have a severe downturn.
Hopefully then, MJ GLEESON (LON:GLE) builds where the jobs are since commuting far takes all the fun out of buying a cheap new home. I hold.
Thoughts on Wincanton (LON:WIN) - not the greatest of statements but still in line. £62m profit for £400m MC. The pension point is interesting, sucking up £20m p.a. if that can go in say the next 2 years, it is worth c16p per share!
Thanks for flagging, Q3 update from Wincanton (LON:WIN) didn't come up on my newsfeed for some reason. I'll check it out. It's a top pick for 2023 on my watchlist - really nice company, but as you say, pension scheme is the big thing that could drive a re-rating if it's resolved favourably.
Anyone else having problems getting into IG trading platforms today?
Nope, working ok for me
Revolution Beauty (LON:REVB) I did try to highlight potential issues with this on 25 Nov 2021 "Revolution Beauty (LON:REVB) with a search for #REVB and "Three easy steps to destroy investors trust as a publicly listed company". No advice intended or veracity implied, just may be of interest."
I can't find the REVB article you're referring to. Any chance of a link please?
It appears to be under "REVB search on twitter" Paul
Revolution Beauty (LON:REVB) Go to Twitter and enter "Three easy steps to destroy". You will find an article by Paul@investmentideen - I think related party transactions are always a red flag and assume I don't have enough knowledge to de-risk. Others may do things differently.
More housebuilder reports today, this time MJ GLEESON (LON:GLE) and Taylor Wimpey (LON:TW.) . There seems to be a clear pattern emerging of an approximate halving in reservation rates across the industry. Mortgage interest rates seem to have settled back at close to 4%, which seems reasonable for the medium term, but is very obviously a lot more expensive than previous rates. However 4% is perhaps in line with longer term inflation? So a net rate of zero?
I think the housing bounce yesterday was premature and we're all going to have to get used to higher interest rates. UK government debt is yielding much less than inflation, whereas some emerging market debt is yielding more than inflation. This ultimately drives interest rates, in the absence of QE, I believe.
We've had a decade and more of funny money distorting rates so maybe +/- 4% is the new low? A relief for savers in any event.
The outlier MJ GLEESON (LON:GLE) becomes even more interesting at this time because one might assume their target lower income but striving first time buyer is most impacted by the rising cost of money; however noting that they claim to target key workers, who, while perhaps unhappy with the rate of their wage growth, are often relatively secure in their employment - that should help in mortgage applications and consequently help limit cancellation rates on plot reservations. I also see parallels with value retail and the possibility of home seekers trading down to Gleeson price points. All that said Gleeson's update today is a bit short on detail, (I hold).
I'm sure GLE will be a point of interest on your backlog list of companies reporting this week Paul! Thanks for all your and Graham's output and considerable enthusiasm for the task.
The findings of the independent investigation on Revolution Beauty Group are quite disturbing.
Well done to the auditors BDO LLP for flagging these issues.