Small Cap Value Report (Fri 13 May 2022) - TTG, FCRM, FIH

Good morning! Paul & Jack here.
Agenda -
Paul's Section:
TT electronics (LON:TTG) - an in line update for FY 12/2022, after good trading in the first 4 months. Order intake looks particularly strong, and inflation is being managed well. There is an H2 weighting expected for one division. Looks excellent value, with a decent divi yield, so a thumbs up from me.
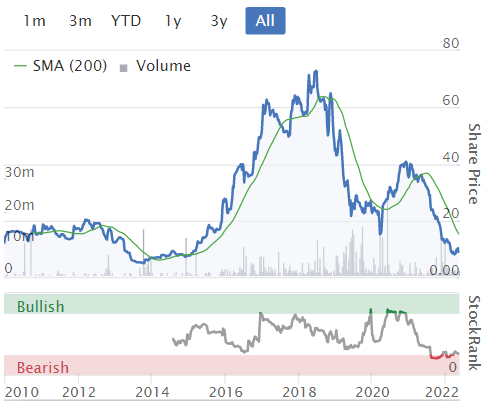
Fulcrum Utility Services (LON:FCRM) - a tale of woes today, due to problems in the energy supply market. However, a big fundraising at 12p in Dec 2021 means the business is cash-rich, and has other assets. 7p share price now could be an opportunity, but special situations investors who can put in the time to properly understand risk:reward of this business model. Shrewdies, Harwood Capital, are involved, which means there's probably an opportunity here.
Jack's section:
FIH (LON:FIH) - curious mix of businesses tracing its origins back to 1851. A recovery is on the cards, and potentially some operational gearing. The group has property, too. But the stock is illiquid and there has been minimal share price appreciation for a long time, so you have to weigh up whether or not it’s worth investing time into.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
TT electronics (LON:TTG)
176p (last night’s close)
Market cap £311m
TT Electronics plc ("TT", "the Group"), a global provider of engineered electronics for performance critical applications, publishes the following trading update on the Group's performance for the four months to the end of April 2022 (the 'period'), ahead of the AGM taking place later today.
Continued strong order intake, with full year outlook unchanged
Key points -
Group revenue was 6 per cent higher than the previous year on a constant currency basis and 5 per cent higher on an organic1 basis.
Order intake continues to run well ahead of revenue with book to bill for the four months running at 151 per cent.
Acquisition (Ferranti) going well.
Cost inflation -
Our well-established self-help initiatives and our decisive action on pricing continue to effectively offset current cost inflation.
H2 weighting for power & connectivity division - so interims might disappoint possibly?
Net debt expected to increase at half year, then normalise for year end. This is due to stocking up, and supply chain shortages.
Outlook -
Whilst macroeconomic conditions remain uncertain, the year has started well, with continued growth in our end markets, and good execution against the well-documented challenges.
Accordingly, management's outlook for the year as a whole is unchanged.
Valuation - with confirmation today that performance is in line with expectations, then we should be able to rely on the forecasts which produce a forward PER of only 9.4
Also note the decent dividend yield -

.
My opinion - the key point for me, is that demand is clearly strong. A book to bill ratio of 151% in the year to date looks very good. It’s a pity they don’t give the size of the order book in this announcement, but clearly it would have risen. Although I wonder if customers might be stocking up, to ensure their own production continues smoothly?
Supply chain disruption, especially in electronics, is well known, and sooner or later will get resolved. That’s why the share price has been so weak, and could provide a buying opportunity, maybe?
In conclusion, I think TTG looks attractively priced right now, for investors who are happy to hold for the long term. In the short term, obviously macro uncertainties are a big current issue - which is why share prices are much cheaper.
Although bears might point out that the share price has gone nowhere in the last 20 years, so the only benefit of owning this share is the divis, arguably. So maybe it’s cheap for this reason?
.

.
Fulcrum Utility Services (LON:FCRM)
7.0p (down 23% at 08:50)
Market cap £28m
We rarely cover this share here, because we came to the conclusion several years ago that it wasn’t a good business. Performance seemed to collapse well before the pandemic, and the best part of the business was sold off.
There’s nothing else of interest reporting today, so let’s see what’s going on with FCRM.
Fulcrum Utility Services Limited, a leading independent provider of essential utility services including multi-utility connections, electric vehicle charging infrastructure, renewable energy infrastructure and smart metering solutions, provides a trading update today for its financial year ended 31 March 2022.
Key points & my comments -
Revenue £57.4m for FY 3/2022
Adj EBITDA of £0.5m (it did £1.0m in H1, so H2 is £0.5mloss-making)
Order book has softened
Problem contract has been terminated
Chaos in energy sector is causing problems
Interim CEO appointed in Jan 2022 is a turnaround specialist
New CFO from Feb 2022
Acquisition opportunities being looked at
Refinanced in Dec 2021, at 12p per share with £20m placing + £1.2m open offer, so cash position is now strong
2 major shareholders include Harwood, a shrewd, well-known activist investor
My opinion - this looks quite an interesting special situation, which would need a lot more research to properly understand. What I like is that the balance sheet is now strong (post placing at 12p), but we can now buy in the market at just 7p. That could be an opportunity.
Worth taking a closer look, for experienced special situation investors.
.
.
Jack's section
FIH (LON:FIH)
Share price: 248p (-4.8%)
Shares in issue: 12,519,900
Market cap: £31m
Full year trading update to 31 March 2022
These results were published on Tuesday.
Market liquidity seems to be abysmal at the moment and FIH, with its £31m market cap, is no exception. It looks like you can currently buy about £700 worth reliably at market prices, with a spread of 1,600bps, which almost makes it not worth bothering about.
But that situation could improve for investors at some point, in which case it wouldn’t hurt to have covered the company once or twice. At first glance though, it’s hard to get too excited by the historical performance.

This is an international specialist services group with businesses in the Falkland Islands and UK. There are three businesses:
- The Falkland Islands Company (FIC) provides essential services to the people of the Falklands and was established by Royal Charter in 1852. Activities include retailing, property, automotive, insurance, tourism shipping and fishing agency services.
- The Portsmouth Harbour Ferry Company (PHFC) operates a passenger ferry service across Portsmouth Harbour.
- MOMART provides market leading specialist international arts logistics and storage services.
Trading activity is back to pre-pandemic levels and the board now expects to report an underlying pre-tax profit that will significantly exceed market expectations.
The cash balance at 31 March 2022 was c£9.5m. Bank loans were £14.2m (£14.6m at 30 September 2021) and included a £12.7m long-term mortgage on a freehold property at Leyton purchased in December 2018 for £19.6m.
Stuart Munro, CEO of FIH, comments:
We believe the outlook for the Group remains positive. Further opportunities to work with the Falkland Islands Government and the UK Ministry of Defence are being explored by FIC and a return of tourists in the austral spring would further boost trading. In parallel, costs are being carefully managed in Momart and PHFC in line with their ongoing trading recovery.
Conclusion
The last time we covered this ‘eccentric mix of businesses’ was in 2013 (!) so it’s about time we updated our views. There’s little in the way of equity dilution over the years, and a good chunk of debt is property mortgage, so the company looks secure.

Property can be attractive in terms of hidden value and downside protection, but the company has precious little to show by way of share price appreciation over time.

Dividends have also been choppy.

It might be worth a look for investors scouring the market for neglected and hidden value, but the shares look like they are so illiquid that it’s hard to see this stock appealing to a lot of people. Small free float too, at c39%. The business is interesting though, in the sense that it probably has a fascinating history, dating back as it does to 1851.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

20 comments
I note with interest that Zytronic (LON:ZYT) are releasing HY results on the 17th May, and also announced they will do an investor presentation on Investor Meet Company on the 23rd May. Did a scan through RNS announcements back to 2019, and this is the first time they're doing a public PI investor presentation.
I infer that the results to be announced on the 17th May will be good? The fact that they are also doing an aggressive buyback at the moment supports that theory, along with great footfall stats coming out of Las Vegas calendar YTD (where they make quite a bit of money selling displays to gaming operators there).
Anyone sitting on the fence and on a watchlist, Monday will be the last day to buy before results announced at 7am on Tuesday.
(I hold in the Boon Fund)
On Fulcrum Utility Services (LON:FCRM) I was pleasantly surprised that you (Paul) decided to write this tiddler up! I'm a suffering shareholder, having gotten in at 14p. Luckily, it was only a starter position, was less than 2% of my portfolio when I bought, and now much less.
I'm very puzzled as to what's happening here. Clearly Harwood and Bayford, the two largest shareholders and acting in concert, think there is some value. They've been in since pre-COVID in early 2020, having made a bid (26p) back then. And then also investing heavily during the recent December placing at 12p. They'd forced a change of management, and have ears on the board, so clearly knew what they were investing in when they dumped in extra money at the fundraising.
Yet, 5-6 months on, we have yet more disappointment, with no real good news coming out of the company.
They had a record high order book as at Oct21 - so it would be interesting to see what's happened. They were talking about the macro-economic opportunity of local I&C upgrades/new installs to support electric car charging "stations" and the likes. This "opportunity" is conspicuously missing from this latest trading statement.
There's a good amount of NTAV here, as well as enough cash for a bit, and what I can see will eventually be a take-private by Harwood or Bayford. They will of course offer the customary premium to ensure minority shareholders don't complain, probably like a 20-30% to a bombed out share-price. But I never expected it to get this low, otherwise would have bailed at 12p during the time of the fundraising. If Harwood were to offer 9p now they would most likely get a steal, but most shareholders would probably bite their hand off.
(I hold in the Boon Fund - unsure what to do)
I notice Hostmore (LON:MORE) continues to slide steeply. Not checked for recent news - it may just be market sentiment towards the discretionary eating out sector.
got to say, it’s been a while since I’ve seen a vomiting camel.
For some light entertainment on a quiet Friday – the inventor of a new chart pattern comes clean.
https://www.ft.com/video/2452d265-ef0e-4f7f-b0b2-ca1dc076ff33
Hi JimMcLad
Great vid :)
Regards
Howard
Shucks Howard – I can’t take the credit. John Authers mentioned it this morning in his brief before he showed numerous other ‘serious’ charts which suggest we’re not out of the woods yet :(
Thanks Jim - very amusing video. Quite a few of my holdings have entered the 'splat zone' in recent weeks :-)
After a decent rise the 'two mountain top' with neckline (300p) is as good a 'stop loss' as any other 'rule'. Got 20p to go IMO and may look at shorting to hedge.
Hi Jack, Great write up on LON:FIH. I've held them since 2014 and am, with a bit of judicious top slicing and buying back, just in the black. I would/should have sold out but am a bit nostalgic about them (I know never a good thing for an investor).
One thing worth noting is that the Falklands has huge off shore Oil and Gas reserves, if exploration/development ever started up again there would be a huge uptick in the price as FIH would service the Oil Explorers.
On the buy volume, I've never had a issue buying or selling a couple of thousand through Barclays. Maybe everyone is holding on for the next results.
hi Berksbee - FIH (LON:FIH) Never come across this one before. Just had a read of the history - quite fascinating short read. An eclectic mix of businesses but too small / illiquid and a sporadic yield to interest me. Can see why you became nostalgic about the business though - good luck with your investment / trading on this one.
Thankyou for your write up on TTG Paul. Whilst I don't hold them, I do hold Volex, so hopefully a positive read across for them too....
DH2.
hi Paul, if it is quiet today and if possible, I wondered if you had any thoughts on the update from Unbound (LON:UBG) from yesterday.
"Strong performance in Q1" "Challenging external outlook continues" "Costs are being tightly managed with marketing, variable and fixed cost
efficiencies being delivered as revenue continues to grow" "The Group's full year outlook remains unchanged"
We know the conditions at the moment are ugly out there, the update feels reassuring in that they are in control and keeping their head above water until the waves subside a bit.
Interesting and perhaps predictable partner brand growth into new areas to expand their cross selling options against their database of 30% of the uk female market.
Overall, it feels encouraging I think. Would have liked to have seen some £ numbers.
Also second for £UBG which did give some numbers (vs LY Rev +10%, %GM up, emails now >1Mn). They also said retail "especially pleasing". Overall, full year f'ct unchanged - not surprising after 1 quarter perhaps but not reflective of what share price has done of late. I think the cost-of-living storm will be less intense in their core harbour (mass affluent older females) with some straightforward cross-selling opportunities that will send a signal about long term possibilities.
The majority of these older customers probably own their own home , up in value many thousands of pounds, pay next to no tax or NI and spend on very modestly on food but have declining health and mobility etc. Bluntly, they also in 'run down' mode - in that frame, spending £50 on a pair of shoes that promise more comfort and a chance to move better doesn't seem to be the first saving to make.
At the current price, we have to assume a collapse in demand or an jump in costs that cant be passed on. None of that is visible yet. (I hold )
I also hope Paul will have tine to cover £UBG.
That “strong Quarter1” included double digit increase in revenues AND increase in gross margin. Also one of the “partners” is £MKS.
Market cap is only £13 million. Share price has fallen from £1.20 to just 33p. The retail sector is under the cosh (including Marks and Spencer (LON:MKS) Down nearly 50% from the peak in January) but is the extreme 70% fall in the Unbound share price overdone?
if I'm reading the stock report correctly for Unbound (LON:UBG) , currently SP is around 50% of the last reported negative net debt, and there's a negative ev to ebitda figure.
bodes well for a re rate if the world doesn't cave in.
I don't think the stock report figures for £UBG (I hold) are entirely correct unfortunately. From the last set of results I believe net debt was around £8m, which will probably be nearer £6m now with the recent disposal of the property. Still looks good overall though, expecting to see pretty decent op. margins here over the next couple of years off forecast revenues of £60m-£70m. I was slightly concerned by the debt levels, but on balance market cap of £13m seems far too cheap to me.
Hi,
Sorry I didn't get round to looking at Unbound (LON:UBG) (I hold) - I've been on a mini-break late this week, doing rambling around the countryside with a big group of friends - necessary to recharge human contact, fresh air, and some exercise. So I had to rush down a full english at 7am, and then rattle out 2 quick company sections here, then spend the rest of the day walking & talking nonsense to lovely friends! (I'm very good at that!!)
With UBG, I don't know what to think. Clearly the demerger strategy from Electra has been a total flop. It's not clear though, whether that's down to bad timing, bad execution, or whether we might have been sold a pup?
As always, we can only ever work on the information provided, I've never claimed to be clairvoyant.
Apologies to everyone (like me) who has suffered big paper losses on Electra. I cannot see anything wrong with either business, MORE or UBG, so the bombed out share price is not a bid that I want to accept. Hence I'm happy to completely ignore the current share price.
Nobody likes to see paper losses, so I apologise to everyone who is currently nursing a heavy loss on MORE and UBG, as indeed I am. We're trying to help each other make money, so it's really painful when our best ideas lose people money (in the short term). We're not tipsters, we're just trying to flag up interesting shares. So as always, it's your decision whether to stick with anything that has gone down in price.
But it's horrible, and I still want to apologise. My stuff has done really badly in the last year or so. That's just the way it goes sometimes.
Best wishes, Paul.
GMS- Full year results confirm the recovery on track. Might be a multi bagger for equity holders as very high level of debt falls. Still undecided on whether to raise $50m of new equity or issue warrants (11% dilution at 6p). Higher utilisation of the 13 vessels at higher rates should continue given activity in Middle East. stock for the higher risk investors.