Small Cap Value Report (Fri 13 Oct 2023) - HFD, FIF, D4T4, VCP, TFW, MRK, STM, ETP, AVON

Good morning from Paul!
This is my last report from Gozo, am flying back to the UK tomorrow evening.
Today's report is now finished! Podcast this weekend as usual, not sure if it will be Saturday or Sunday, due to travelling.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries - I won't do any today, see sections below.
Paul's Section:
Here's something I prepared earlier -
Halfords (LON:HFD)
Up 19% to 216p y’day - Betaville rumour - Paul - AMBER
Once again the absurdity of the rules on disclosure of takeover approaches is shown. A subscription website called Betaville tips people off about price sensitive information, which personally I think should not be legal.
It apparently revealed that Halfords has received bid approaches, and I think a figure of 271p was mentioned. Although ThomsonReuters appears to have now pulled this initial report, which apparently came via Sharecast.
If Halfords has been in bid talks with a credible buyer or buyers, then the shares have been in a false market, which is what I strongly object to with the ridiculous UK takeover rules. It’s not right to keep shareholders in the dark. Required disclosure is only driven by someone randomly leaking details to the press, then companies have to comment. This is absurd.
Obviously speculative, or fanciful bid approaches shouldn’t need to be disclosed, but credible ones should - because it is clearly price-sensitive information, that should not be traded on subscription websites - surely that’s insider dealing, which is illegal?! We play by the rules here on Stockopedia, and never gossip about inside information. Shouldn’t everyone have to do that too? Otherwise what's the point of having these rules?
Is Halfords any good? We don’t have a strong view either way here, with me & Graham having reviewed it 3 times this year, coming out as AMBER each time -
23 June (211p) it issued FY 3/2023 results which were OK, but towards the lower end of the forecast range. Outlook was mixed. PER of 11.2x looked about right at the time.
6 Sept (191p) in line TU. Graham flagged low margins, and thought it priced fairly.
Is it credible as a takeover target? Given that we had a very unexpected bid for Restaurant (LON:RTN) today, I’d say anything is possible! I can see strategic value in Halfords, which dominates its retail niche, and also has successfully developed a services business (MoT, repair, tyre centres) which is now a significant part of the group, and can easily be grown with many potential bolt-on acquisitions.So yes, I think it’s credible as a potential bid target, although must admit the thought hadn’t occurred to me before.
Good luck to holders here, whatever happens! As we all keep saying, all these bid approaches reinforce the fact that UK shares are cheap. Each successful bid injects more liquidity into the market, so could be seen as part of the solution for low valuations maybe?
EDIT at 08:55 - no statement from HFD management as yet - Thomson Reuters news feed said last night that a Halfords spokesperson says they don't comment on rumours. I see the share price has reversed, down 8% to 199p at the time of writing, giving up about half of yesterday's surge on the bid rumour. Quite interesting to watch.
Finsbury Food (LON:FIF) - 109.5p (£143m) - SKY News re Fidelity - Paul
Interesting piece on Sky News, saying that 10% shareholder Fidelity has come out against the 110p takeover bid from DBay, saying that the premium is too small, and it undervalues a decent business, valuing it on only 11x forward earnings.
I completely agree, and noted in the SCVR of 20 Sept that I thought the deal wasn’t enough. If companies want to take over a listed company, they need to pay up, not try and pull off an opportunistic, low ball offer. So I hope shareholders reject the deal, or force DBay to come up with a more sensible price. I’d say 120p+ would be more realistic.
D4t4 Solutions (LON:D4T4) is changing its rather daft name to “Celebrus Technologies” - which is the name of its core product. That makes sense to me. If approved by shareholders at a GM on 9 Nov, then the ticker will also change, to CLBS.
Victoria (LON:VCP) - quite a rollercoaster ride for shareholders in this acquisitive, highly indebted floorcoverings group. I’ve covered this a lot recently, with the initial highly critical FT article flagging concerns over the audit report. Then VCP itself issuing a strong rebuttal shortly afterwards. Shares spikes down sharply on the FT news, but then rallied to a full recovery. This has only proven temporary, as it’s slipped all the way back down again to 400p now.
As mentioned before, I’m wary of VCP’s weak, overly indebted balance sheet, whilst recognising that the shares have been a stunning long-term multibagger. I’ve decided to steer clear, to be on the safe side, and view it as AMBER/RED.
FW Thorpe (LON:TFW)
Down 2% to 380p (£446m) - FY 6/2023 Results - Paul - AMBER
This owner-managed specialist lighting group has been a stunning multibagger over the last c.20 years. However in recent years its growth hasn’t been exciting enough to justify a PER of over 20x, in my view. Definitely not more recently, when everything else has got so much cheaper.
Preliminary results for FY 6/2023 came out yesterday, with shares ending the day down 2%, having recovered most of the earlier 7% intra-day loss. It’s thinly traded for a £446m market cap company though, because shares are tightly held by the controlling family.
The figures look good to me - £26.9m PBT (up 12%), giving 18.7p EPS (up 9%). That’s a PER of 20.3x - quite an aggressive valuation for fairly sedate earnings growth. Although any growth in a tough macro environment is good.
In line current trading. Outlook comments read like an internal memo, chastising under-performing parts of the group - great stuff! Some caution, with “orders slightly lower”, and “some evidence of projects slowing”, revenue growth to be slower than in recent years, but helped by margin improvements.
Very strong balance sheet with £89m NTAV, and £35m cash (less a small bit of debt).
Cashflow is very clean, with £32m post-tax cash generation, all spent on a mixture of capex, acquisitions and dividends.
Paul’s opinion - a very nice group, that’s generating high margin profits & cashflows, and using it to pay modest divis, and make acquisitions.
The valuation looks full to me, especially given the cautious outlook comments. In a stock market full of bargains, this is looking too expensive for my taste, although I do like the business, management, and great long-term track record. So maybe it’s a coffee can share to buy & forget, and come back in 20 years to find yourself rich?! That’s what’s happened over the last 20 years with TFW shares,after all! Mind you, business models change so fast these days, nobody has any idea what the world will be like in 20 years’ time. If we’re all wandering around with metaverse headsets strapped to our faces, then we may not need any lighting at all!
Marks Electrical (LON:MRK)
Down 6% to 103p (£108m) - Trading Update - Paul - AMBER/RED
This fast-growing online electrical retailer updates us on the 6 months to 30 Sept 2023.
It’s more of the same really - key points being impressive organic revenue growth of +25%, to £53.9% in H1. Market share gains. Strong start to October.
Not so good is - higher than expected cost pressures impacted H1 margins, but pressure expected to ease in H2. Is this a profit warning? It dodges the question of how it’s trading vs market expectations, which is not good enough - that’s the key information we need from a trading update, so to omit it is most unsatisfactory. The nearest we get is “Continued trading momentum” in the headline. Also “Strong first half trading period” in the first bullet point, but that refers to revenues, not profit. So I think this update raises more questions than it answers.
Healthy net cash position of £10.9m.
To answer my own question, is this a profit warning today, the answer is yes! Cavendish has reduced FY 3/2024 forecast EBITDA from £9.3m to £8.1m, and adj EPS is now forecast at only 4.4p. The StockReport is currently showing broker consensus of 5.47p, so this is a significant reduction in forecasts.
Paul’s opinion - I’m seriously unimpressed, with how a profit warning has been glossed over in this update, instead being released through lower broker forecasts. I find that misleading. It also means, despite all the upbeat talk and growth in revenues, MRK is set to deliver a second year of reduced profits. The share price of 103p is 23.4x the new, reduced forecast EPS. This thing is way too expensive now, I think. It could grow into the valuation though, and I do like management and strategy here, but a cunningly concealed profit warning has not impressed me, and nor has the aggressive valuation. It’s only worth about half the current share price to me, so I won’t be getting involved.
STM (LON:STM) - 57.5p (£34m) - Recommended takeover - Paul
I forgot to mention this the other day, so am flagging it up now, so it gets recorded as another takeover on my summary spreadsheet (for quick reference).
The takeover price is 60p cash, plus an unusual extra - “Deferred Consideration Units” which might be worth up to an additional 7p each.
60p is a big premium of 118% to the price just before bid interest was previously announced, which strikes me as a cracking deal, for a peculiar little company that specialises in controversial QROPS - overseas pensions for UK ex pats. I remember researching, and meeting the company years ago. It looked cheap, but had question marks over it, possibly resolved now, I don’t know as I lost interest in it ages ago.
It seems to have 36% support so far.
I see the bidder seems to be something to do with financier Edi Truell, who wowed us at Mello years ago with a presentation on the billions and trillions that Tungsten was going to generate from its automated invoice processing. Turns out he wildly overpaid for Tungsten, and it was a multi-year disappointment, but eventually got bought out. I expect STM shareholders are likely to grab this generous offer with grateful thanks.
Looking at the Stockopedia shareholder list, I can see some value investor blasts from the past, including Peter Gyllenhammar, and David Barry, who both specialise in deep value special situation micro caps. So nice to see them get a decent win here. I think some friends of mine hold this one too, so it's always good to see mates make a bob or two!
Eneraqua Technologies (LON:ETP)
39p (£13m) - Profit Warning - Paul - RED
This energy and water (hence the name) related business looked good when it first floated in Oct 2021 (alarm bells re 2021!), with a lovely trend of growing revenues and profits. The share price remained robust throughout 2022. I remember listening to a podcast version of its results webinar in late 2022, whilst going for a brisk walk, and thinking to myself that it sounded quite a good company.
Checking our notes here, I was AMBER on 13/3/2023, noting that the mild profit warning for FY 1/2023 seemed to be mitigated by claimed high visibility for FY 1/2024.
That all went out of the window on 23/5/2023, when ETP plunged 36% to 168p on good FY 1/2023 results, but a big profit warning for FY 1/2024 was cunningly buried in the outlook comments. In the SCVR for 23 May, I thundered that this announcement seemed highly misleading, and I went RED due to completely losing trust in the company, and its rapidly deteriorating performance.
It’s since collapsed to just 39p, so let’s take a look with fresh eyes. There might be a bargain here in the wreckage of this 2021 float, especially if institutions are selling out at any price. £13m market cap is peanuts compared with the growth & profits it delivered in FY 1/2022 and FY 1/2023 - if it can get back on track, even partially, then there could be nice upside maybe?
Offsetting that, is the harsh reality that many shares which are disappointing in this bear market look cheap, then they look really cheap, then insanely cheap, then some new disaster is announced! Turns out they weren’t cheap after all.
Also, what is its solvency like? Are we looking at covenant breaches and an emergency placing?
H1 Results -
Revenue £26.0m (up 7%)
Small H1 adj loss before tax of £(0.4)m, vs £3.0m profit in H1 LY. Disappointing, but not a disaster I’d say.
Net cash of £0.5m, slightly better than a year earlier. So it would need some bank facility to give it headroom.
Massive “order book” of £146m, but only c.25% expected to be delivered in H2. So how real are these orders?
Outlook - this is the killer. It says order delays mean that revenues & profit for FY 1/2024 will be “substantially below market expectations”. Also FY 1/2025 forecasts need to be lowered.
It still expects a (presumably small) profit for FY 1/2024 and net cash at the year end.
It blames order delays on public sector housing having to tighten budgets to deal with cladding, and other things.
Is it likely to go bust or need a placing?
Balance sheet - a giant number jumps out at me, £26.8m receivables - that’s all of H1 revenue (although receivables includes VAT and revenue doesn’t, so not quite).
Note 6 gives a breakdown, and says that £16.2m is prepayments and accrued income - so this is the money owed (not paid yet), for revenues booked to the P&L. It’s just a ridiculous number that stands out like a sore thumb. The commentary says that 83% of this £16.2m has been collected as cash by 30 Sept, and the rest “due in the coming weeks”. Sorry, I just don’t believe it. Surely if all that cash had come in, then the outlook statement would state that our cash balance has now risen to £10m, or whatever, but I can’t see anything like that.
NTAV is about £16m.
Paul’s opinion - I’ll stick my neck out here, and say that the balance sheet seems so outlandish, that I don’t believe these figures are real, or at the very least there is a high risk of a big write-off being needed against excessive receivables.. Remember these are not audited, they’re unaudited interim results.
I think it’s booked a load of revenue, which hasn’t been paid for - which is why receivables are so huge relative to revenues. We’ve only got their word for the cash coming in later, and given that I don’t trust the company, as mentioned here back in May, their word doesn’t convince me. Another possibility is that they might be persuading customers to press ahead with orders in return for extended payment terms (hence high receivables)?
Overall though, I would not consider investing in this share, at any price, until we have audited figures in 2024, confirming that the receivables have actually turned into cash.
I did some more digging last night, into the FY 1/2023 Annual Report, and it mentions the excessive receivables, saying -
An enhanced assurance process introduced by the Government in November 2022 was initially under-resourced caused backlogs in the approval process of completed projects increasing the level of accrued income at the year end. The issue is now unwinding following additional resourcing by the Government in the approval process. Following the period end, 54% of accrued income has unwound and been received as cash by the Company…
As previously stated, the working capital position at year end is unwinding as expected with 54% of accrued income converting into cash post period end.
The trouble is, the receivables figure did not drop much between Jan 2023 and July 2023, only falling from £29.2m to £26.8m. So it looks as if the reassurance in the last Annual Report about most of the deferred income turning into cash has actually not made much difference - receivables remains excessive.
Something similar is said in the interim results, about collecting in the cash post period end -
The Company returned to a net cash position at the end of H1 FY24. As at 30 September, over 83% of the accrued income had been collected as cash with the remaining balance due in the coming weeks. Overall, we expect to end FY24 in profit and with a net cash positive position.
If so, why aren’t they telling us what the current, presumably substantially higher cash position is? I reckon probably because it isn’t substantially higher, and the cash hasn’t been collected. Or, accrued income that’s been paid has just been replaced with freshly booked accrued income, so an ongoing problem of ETP apparently having to wait a long time for customers to approve projects for invoicing, let alone receiving payment! If the company is to be believed of course. I can’t recall ever seeing a similar problem at other companies supplying projects to the public sector. Actually they usually get paid promptly, often on agreed stage payments, sometimes up-front. So this just doesn’t stack up for me.
Although the FY 1/2023 Annual Report contains no concerns expressed by the auditors.
It’s got to be a continuing RED for me, completely uninvestable at this stage, but hope I’m wrong for the sake of shareholders. There could be a nasty write-off coming, if the massive receivables turn out to sales booked, but where the cash is uncollectable. The problem seems to have emerged in H2 last year, when receivables shot up from an already high £13.1m, to a ridiculous £29.2m at 31 Jan 2023. Why get involved? Why take the risk?
Avon Protection (LON:AVON)
Up 7% to 716p - Trading Update - Paul - AMBER
This might be worth a fresh look, as the market has responded positively to today’s reassuring update, and the chart might be putting in an attempt at changing direction, who knows? Often similar rebounds get snuffed out though, in this very difficult market.
The recent rebound barely registers on the 5-year chart, as you can see here -
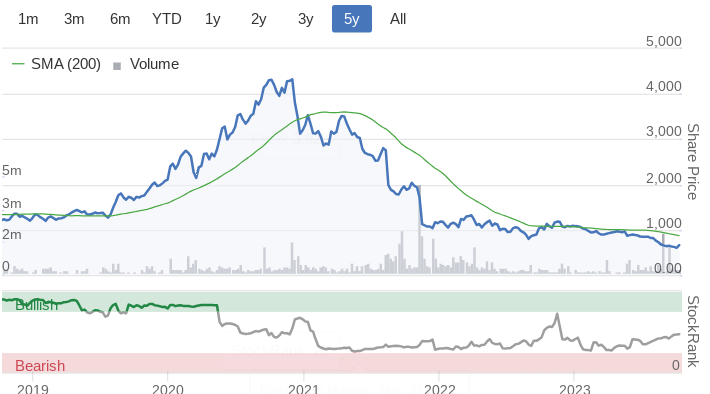
Note there hasn’t been any dilution from share issuance over this timeframe, which is a nice positive - so theoretically if company performance recovers, then it’s possible the shares could seriously re-rate again.
Trouble is, profitability collapsed, and seemed to start that plunge before the pandemic, I seem to remember there being problems, and restructuring at AVON, but it’s not one I follow closely.
Today’s update -
Avon Protection announces a trading update for the financial year ended 30 September 2023 ("FY 2023") ahead of the publication of its Year End Results on 21 November 2023.
This sounds quite good -
"Full year performance in line with expectations, with a stronger H2 reflecting good strategic progress"
“As expected, trading in the second half of 2023 was stronger than in the first half, with order book growth and higher underlying earnings.”
The year end order book is up 10% vs a year ago.
Debt sounds a bit warm, but with encouraging news about year end receivables turning into cash afterwards -
Net debt:EBITDA on a covenant basis at the end of FY 2023 is expected to have reduced to around 2.0 times, compared to 2.6 times at the end of H1 2023. This improvement is the result of our successful exit from the Armour business and the improved profitability in the second half of the year.
The year end net debt position on a covenant basis is now expected to be approximately $65m, as a result of the timing of cash receipts from the shipment of several large orders in the last month of the financial year. We expect the receivables associated with these orders to be paid during the first quarter of the 2024 financial year, which will further reduce net debt by up to $20m.
It’s changing reporting to two divisions - respiratory protection, and head protection. I think it sold off the old cow milking business, maybe that would have been called udder protection? Or could have just been filed under “udder”? Sorry, I couldn’t resist.
Paul’s opinion - no strong view either way, as I haven’t researched it properly.
This update seems to show things getting back on track. What puts me off a bit, is debt being a bit warm still maybe, and the lumpiness of the business with regards to large contracts - so possibly more of a share to trade the ups and downs rather than hold long-term?
Anyway, the reassuring tone, and in line with expectations performance for FY 9/2023, could make it worth readers taking a closer look, possibly? It would help if the company ensured that broker notes were available for us, but there’s nothing recent on Research Tree.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

57 comments
Podcast done - no mystery share this week, but plenty of profit warnings!
SCVR Summary Spreadsheet - Anyone with this link can view, you don't need to ask permission to edit it, as only I can edit it!
Talking of which, since I adopted the reader suggestion for colour-coding profit warnings as BLACK on my spreadsheet, at the start of October, it's been striking how many there have been - see screenshot below.
I have included "hidden" profit warnings - ie where they try to sound upbeat, but the broker reduces forecasts on the sly.
Every cell has a pop-up summary of the SCVR comments - I included one in this screenshot from Eneraqua.
Also, I'm not doing them good to bad, left to right, to help people with colour-blindness. So I start off in column B with the GREEN opinion shares first, then move to amber, then RED and profit warnings on the right. Hopefully this helps everyone who struggles with colours.
"Also, I'm not doing them good to bad"
Typo, sorry! Of course the word "not" is incorrect. I AM doing them good to bad, left to right. Sorry for any confusion!
FTSE250 is now trading at the same level it was in 2015 !!
Actually a lot lower in real terms once you factor in inflation over last 8 years - probably at least 30% down!
And the £ is worth less as well against the US$? Should have invested more in the US markets. Easy with hindsight.
What about the dividend income though?
Just checked and was surprised that the FTSE 250 is now yielding 5.5% - a few years ago it was more like 3%. Suggests there is definitely value on offer for patient investors who can put up with short-term volatility.
Excellent news. We should celebrate
Vanguard 250 UCITS ETF nice and liquid
Anyone else having problems trading on IG group (LON:IGG) platform, trading platform won't load, this started last night on my account.
I've held LON:AVON for a long time so I thought I would add my input. A (once) very successful and highly rated outfit that sold gas mask/high tech helmets and had a dairy business. They sold the dairy business and made a disastrous purchase of a body armour business (I think off 3M). They've finally exited the body armour business and all costs relating to are now paid. What we are now back to is a gasmask/helmet business that has a very high barrier to entry and is profitable. The balance sheet is starting to improve, they have a very large order backlog and events in Gaza might be adding to sentiments. All of this will drive the share price up IMO. Finally there is a chance of a bid approach at this level.
Yes, Avon Protection (LON:AVON) certainly scored an own goal in buying that body armour business otherwise. It's come a long way since golf grips, tit liners, tennis racker rubber, windscreen wipers, hovercraft skirts, inflatable rubber boats and a host of other interesting things. Maybe they still do but I got sold off along with Avon Tyres but do hold its shares hoping that moat stays safe.
Avon Protection (LON:AVON) probably should be part of a large defense manufacturer, in the safety of a diversified group. To ride out any lumpyness of demand for their niche, single category product.
it might help Avon Protection (LON:AVON) if they had a completely uncorrelated but similarly large income stream…perhaps milking parlour related
Hi
Looks like Avon Protection (LON:AVON) is experiencing quite a sustained SP recovery from its quite sustained falls. Up over +9% today, as I type
This news feed summary ......
BUZZ-UK's Avon Protection hits over 7-week high on strong annual performance
 Avon Protection
News9:30 am** Shares of Avon Protection Plc AVON.L rise as much as6.4% to 702p, highest since Aug. 23
** Maker of respiratory protection equipment for military,
law enforcement and fire personnel confirms FY23 performance has
come in line with expectations
** Says H2 trading stronger than H1, with further order book
growth and higher underlying earnings
** Adds order book as of Sept.30 up 10% vs prior year, with
strong demand for helmets
** Stock set to post best day since November 2022, if trend
holds
** Currently, stock up 5%, trimming YTD losses to ~35%
RNS here
https://www.investegate.co.uk/...
I do not hold but have held in the past.
Regards
Howard
Wincanton (LON:WIN) Have not seen any RNS announcements on this but they have lost another contract. Have no idea what that means in terms of trading performance but would imagine it will have some impact. I'm not a holder but thought others on here may be.
See here for details: https://motortransport.co.uk/b...
Does seem odd. New was known late Sept https://blackmorevale.net/winc... I hold.
Yes, that does seem odd. Article is dated 6 Oct and only landed in my inbox today. If it was public knowledge in late September, should not have an effect now. Thanks for letting me know.
Thanks MrContrarian, although I never though my local freesheet (the BVM) would ever serve as a source of market intelligence! I hold too.
Wincanton (LON:WIN) put out a trading update on the 10th October - no hint of any loss of contracts. I added to my shareholding on the day. I had been watching carefully since March (when a major HMRC contract was lost) for any new major contract losses. I decided to give it 6 months after March to reassure myself. After the 10th October I decided it was safe to stick my head above the parapet. I would not have bought the second tranche had I known of this latest loss. Disingenuous behaviour from Wincanton I would say. I have never seen so many companies in the past, being quite so economical with the truth and cherry picking what figures and facts they report, as has been the case this year. I am becoming more cynical by the day of business leaders and company directors. Window dressing taken to extremes by companies of all sizes and persuasions. Oftentimes company reports wax on extremely positively - it takes lots of scrutiny to realise that, for example, statutary profit has declined, or has ceased to exist, And don't get me going on share options, bonuses, awards etc, even when in many cases shareholders have suffered prolonged capital losses with no dividends. Not many companies strive for clarity and simplicity in their various RNS s and reprts,
obfuscation/ˌɒbfʌˈskeɪʃn,ˌɒbfəˈskeɪʃn/ is widely practised as routine
noun
The action of making something obscure, unclear, or unintelligible."when confronted with sharp questions they resort to obfuscation"
Good luck all. Remain cynical and questioning. It weren't like that when I were a lad.
Retired accountant. Blue2guit.
I couldn’t agree more with you.
Wincanton (LON:WIN)
Disingenuous behaviour from Wincanton I would say. I have never seen so many companies in the past, being quite so economical with the truth and cherry picking what figures and facts they report, as has been the case this year. I am becoming more cynical by the day of business leaders and company directors.
Its good to be skeptical but its perfectly posible that this contract ending might either already have been baked into forecasts or might not affect the current forecasts -materially if they feel that a contract ending doesnt affect the overall performance of the business "materially" imho no need to say owt - infact they have pretty much explained in their most recent update that they are still on track compared to prior expectations (albeit dreaded h2 weighting) - they mention new contract wins in thne update - presumably they havent all been delcared - so not declaring contracts ending seems conssitent with not shouting from the rooftops ref new contracts. In sumamry if its as it was overall as it seems to be not sure why you are getting so upset.
I would agree some companies are economical with the truth - to me the trick is spotting your genuine board compared to your spivy type board. cant specificaly comme
In soem respects i only wnat to know about material contracts starting or ending that move the needle - albeit ideally company will hopefully update ref any material events as appropiate when appropriate to do so.
If there is any lesson to be learned here its probably that before you hit the buy button you doa google search as appropriate with regard to teh company you wnat to buy - would have been quite easy for you to find out the recent update that was apready in teh public domain.
Headlam (LON:HEAD)
Brokers have today further downgraded FY '23 PBT from £15.7m to £11.9m.
This is almost a 25% downgrade sneaked out under the radar.
I can't say this comes as a surprise but surely a downgrade of this size warrants an RNS and is effectively another profit warning.
Not impressed by this rather underhand tactic.
(I hold)
Snazzy
two things really stand out Headlam (LON:HEAD)
1. LIKE is making an impact that the company fail to recognise or have buried their heads in the sand about.
2. Directors fail to purchase in any great quantity, and that leads the way.
Headlam (LON:HEAD)
When did this broker last update ? (EDIR see link below)
this seems shockingly awful if there has been no new news since the 05/09/2023 update.
When did this broker last update ? all i could guess would be that if it was a really long time ago they might not have updated since an earlier update that warned - that makes little sense though.
Only other thing i could think would be if their estimates are higher than other brokers estimates then it would make sense they would be reducing there estimates to match the current markey expectations.
per company 05/09/2023
Current trading and outlook
Full year 2023 expectations unchanged
ok i have looked at info on company website and it seems that if the company has released no new news this is a prettyy shocking turn of events.
https://www.headlam.com/invest...
If i held here and this looks as sneaky as it is i would probbaly sell first and ask questions later. I suspect once the market realises wahts up the price will react acordingly.
Final stab at working out whats up - perhaps brokers have looked at news from competitors and made apprropriate adjustemnts ? - perhaps they emailed the company and got a wishy washy reponse that was so sketchy the only logical thing to presume is that things are getting worse and company has not as of yet released that news - that would be their guess?
Does anyone know how it works here ? seems fine for broker to put their head above the water but should the company not be on the ball enough to update the market that trading has got worse or that trading remains on track and therefore throwing teh broker under the bus.
Looking at prior years data the problem with selling is could they be near the bottom if earnings will bounce back at some stage.
Headlam (LON:HEAD)
snazzy
Brokers have today further downgraded FY '23 PBT from £15.7m to £11.9m.
Are you certain they have done this ? it couldnt be some confusion between profit before tax and profit after tax could it - with tax rate now being 25% tax could explain the difference if perhaps something has got lost in translation ?
hi rmillaree
Headlam (LON:HEAD)
Are you certain they have done this ? it couldnt be some confusion
between profit before tax and profit after tax could it - with tax rate
now being 25% tax could explain the difference if perhaps something has
got lost in translation ?
I picked this up from an alert today on Sharepad. They have updated their PBT forecast for FY '23 (to 31/12/23) from £15.7m to £11.9m (now down 67% yoy) in line with the alert.
No doubt this will at some stage be updated on the company's website where it still shows the previous underlying PBT broker forecasts dated 5/9/23 (date of release of H1 results) by Panmure Gordon and Peel Hunt with a consensus underlying PBT of £15.7m.
For us private investors it is particularly underhand as there is no broker research available on Research Tree.
Snazzy
Great spot, thanks Snazzytime.
You raise a very good point - what is a profit warning? As you say, a big drop in broker forecasts is effectively the same thing as a profit warning, it's just that they have anticipated the drop in earnings, and slipped it out via broker forecasts, before issuing a trading update at a later date that can claim to be in line with expectations!
The water is certainly quite muddy, but we need to be constantly checking that neat little broker consensus chart on the StockReport.
Thanks very much for flagging re Headlam (LON:HEAD)
Regards, Paul.
Paul, Stockopedia need to update the information, there are several stocks, where they are showing forecasts for 2022, even though the full results for 2023 have been published, although not on Stockopedia, if you look at Greggs (LON:GRG) and 4imprint (LON:FOUR) you should see what I mean. This is a known and reported issue since around April, 2023 but still not resolved.
Hi Paul,
I quite agree that it pays to keep checking the broker consensus chart on the StockReport - one of the first things I tend to check on a stock - but do you (or anyone) happen to know how long it takes for a new broker forecast to be included on the chart?
Thanks for all your great input (written & podcast). Graham & Roland too.
Pritch
I've seen the average broker forecast updated within 24 hours, and in some times it takes a couple of days (or even not even picked up / included!)
The process is very opaque I find - we don't get to drill down to individual broker forecasts, when was it last updated, etc.
So much so that I'm not really sure I trust the broker forecasts, unless its for a mega-cap with like 10+ broker data points.
I setup a simple screen to check for any changes every day. You can customise this to check your portfolio, FTSE 250 etc
Obviously best if you can buy before they appear on this list but these tend to have the best, short term at least, price movements.
Fantastic idea, thanks Wolfie! I might have a play with screens to set up something similar. In the last bull market I did have a very good screen that searched for GARP stocks and also included recent broker upgrades as a screening factor, and it proved very successful... for a while!
I have a couple of reflections on Algy Hall's talk which he touched on.
One was that he said that growth often destroys. It very much reminded me of Premier Foods (LON:PFD). It aimed to build a portfolio of quality consumer brands. So it acquired a lot of brands from the big boys, so probably Unilever and others. They were fairly tired brands, so I guess they were happy to offload. The money for that had to be obtained from somewhere, and the only way they can do that was by debt.
EPS went up nicely, and so did the PE attached to it. But, well, as you might have guessed, the debt burden became gigantic, growth faltered, and the whole edifice collapsed. Fortunately, it was down, but not out, and still continues today. It seems to be on the mend, having brought itself back from the brink. It's operations are improving nicely, and it's earning a decent operating margin. It has even reinstated dividends.
Another company is Dignity, the funeral home. It was mentioned in Phil Oakley's book as a quality company. He was happy with the debt level at the time he wrote the book. In hindsight, that turned out not to be such a great idea.
Another concept Algy talked about were companies that just paid out their divvies, and weren't necessarily considered great companies, but managed to do well.
One company that sprang to mind was Games Workshop (LON:GAW). I talked about that many years ago. Earnings had been reasonably flat for awhile, and I said that I thought it had good returns on capital and margins. I was actually scorned for that. I did sell some time after. HUGE MISTAKE, as we now know.
It got me thinking that a very simple screen for quality at reasonably price might be a good idea: ROE > 12.5, operating margins > 10%, interest cover> 10, and reasonable PE. This gives you a good combination of quality, decent returns and safety.
One company I'd like to mention here is BAE Systems (LON:BA.), which I bought in Nov 2021 for 575p. I bought it simply because it was high on the StockRank. In all respects it was one of those boring companies, meh, this isn't going anywhere.
Things can surprise. It's gone from a fairly boring just-give-us-the-dividends to one where we should see some fairly good growth in the next few years. It announce a record order backlog back in Feb, and it seems reasonable to suppose that the backlog will only get bigger when it reports next time.
Aside: It almost seems that we have two different markets at the moment: the big caps, which are holding their own, and the mid- and small- caps, which have been in downtrend since September 2021. This is longer that the 2008 meltdown.
I spoke to my American pal yesterday. He's cynical about US economic policy and informed that GAAP actually stands for "Growth At Any Price." Hope that cheers everyone up.
Mark, that is interesting, what you say about BAE Systems (LON:BA.) which I hold. Made me look up my records. Since first buying in 2011 I bought another 9 times, unfortunately selling 4 times. I used the profits among others to diversify into awful very Small Caps, my mistake, should have kept on buying BAE Systems and 'kept forever' and as it stands the best may be yet to come. Games Workshop (LON:GAW) I had watched and missed its low point in the Covid crisis, bought some well up in the upturn but it had to go at the end-of-July peak. Maybe I'll catch GAW on its next dip which surely will come again. Meanwhile, my focus is on Hummingbird Resources (LON:HUM) which I recently doubled-down on (for the third time) by selling my old dog NAHL (LON:NAH) even though that is springing into new life.
Hummingbird Resources (LON:HUM) I bought some more after watching the CEO interview with Zak Mir where he basically gave positive guidance -I'm sure that's why the stock has had a move up.
Thanks. I'll take a look at HUM.
I did hear of a buy on a bulletin board who had held BA for donkey years, and said that he was more than happy with his holding (not surprising).
There's also a British guy on Youtube that seems to invest only in Footsie companies. I think he's quite a young guy, maybe started investing about a decade a go, something like that. He's has taken a slow and steady approach to things, and his income has grown nicely year by year. I have no doubt he will continue to do extremely well as he has a good approach.
FW Thorpe (LON:TFW) Thanks for covering Paul. As a long term holder I tend to look through rose tinted spectacles at TFW., Dividends and Special Dividends really add up over the years. Thorpe always has plenty of cash and with no acquisitions contemplated in the near term at least there may well
be scope for another special next year.
For US inflation comments J Authers does the job perfectly. His newsletter is free and brilliant.
Remember the jobless recovery?...post GFC...then, where have all the workers gone ? Post Covid....as we switch from CPI data obsession to the more traditional non farm payrolls over the next 6 months, will we experience the reverse? A slow down without job loss. This is basically a soft landing, which apparently no one believes in. No view here. It does look like CPI data should behave better in Q1 next year.
Debt levels are high, we know this, so inflation credibility to hold rates as low as possible is crucial. The UK seem to get it... now. The FTSE 100 has ticked up, back into positive territory for the year without much impact on small and midcap, yet. But as we have discussed so much this year.... Pauls list, being fresh this year...is not tied up in the problems at Milton and Co as they offload their positions to meet redemptions....hmmm So the incentive is there for fund managers to disappear to a new home, and not be saddled with historic portfolios and get themselves back into Bonus Island. It's annoying...but it's also part of the process. It probably means large funds doing badly will probably carry on doing badly for a while. Creative destruction is powerful in fund management. It does sow the seeds of recovery. 2003-04 was life changing for some of those who jumped and yielded the v high return. So keep an eye on PM departures if you own funds.
Seems to me the decent returns Pauls list has generated is showing the way for a good recovery. Im not calling a recovery, that would be crazy...with everything going on...but the investment backdrop may be better than the indices suggest. Buying cheap stuff and waiting should be a good strategy...
My year will no doubt swing on Navient (NSQ:NAVI) results in 10 days which will directly affect the Sherborne Investors (Guernsey) C (LON:SIGC) NAV...hoping for good news. No change in positioning really...pretty fully invested with a little more cash...the pathway to muddling through feels a little clearer...famous last words no doubt. Oh Yellow Cake (LON:YCA) got a decent right up in IC for those that care...I own obviously.
Good luck all.
Ed Bramson's 'turnaround' vehicle Sherborne Investors (Guernsey) C (LON:SIGC) is now in the 'end-game', having (a) got its man in place and (b) agreed that it won't re-invest in another turnaround when this one is 'monetised'.
It still seems 'early doors' at Navient (NSQ:NAVI) , the new CEO only in place a few months, I'm somewhat surprised at the comment that your 'whole world will swing on results in the next 10 days'? Have I missed something...or just misunderstood?
TIA
It's a fair point... maybe the Q3s remain too early to announce progress but I would argue it's either now or in January with the finals. The time is there or there abouts and its a decent position for me. I said my year would swing not my whole world...we are nearly two years into this investment so not really early days to me...I would suggest it's time to get on with things...but I guess we will see one way or another in a weeks time.
Halfords (LON:HFD) Hi Paul thanks for all your work, greatly appreciated!
On this Betaville story, I am a user and I checked the story yesterday when it was mentioned and there is nothing on the website at all. Again this morning there is nothing. As an fyi the website is free to use with some articles behind a pay wall but important to note that the headline is always there for all to see just you cannot read the full article.
Sounds like go old ramping by mentioning a decent website that people would believe. I know it's early for a rant but this is the sort of stuff the FCA could easily find out who traded it and investigate - but will they, I doubt it..
A very similar situation happened to RS (LON:RS1) about two weeks ago. Price rocketed from c. 700p up to c. 800p on the day, since settled in the range. No bid approach to date, so I assume it was just a ramp.
Maybe the article has been pulled then, but as you say, it wouldn't have appeared on the free bit anyway. I got my info from what ThomsonReuters reported yesterday, but as mentioned in the article, they seem to have pulled it too.
My comments on Betaville stand - I've never liked its modus operandi, spreading gossip and takeover rumours, and charging a fee for the hot latest stories. Totally spivvy. You never know if their stories are accurate (which they sometimes are), or a planted story to pump & dump a share price. Highly unsatisfactory.
Completely agree. Where is the regulation ?
I think that’s harsh Paul, I know Ben a bit from days gone by and he’s a very good journalist, he researches his stories well and is definitely not a gung ho gossip monger. He relates some stories in the marketplace but the stories which he calls “Raw” are generally on the money but he’s sometimes very early. Kleinman is normally bang on with his stuff on Sky but of course he has big brother leaning over his shoulder so he needs it to be 100%, Betaville is a one man band. Certainly I’m not disagreeing with your comments on the overall picture regarding takeover announcements and companies not admitting an approach, there has to be more regulation so shareholders aren’t being hoodwinked.
I'm sure Ben is lovely, but he's peddling inside information!
Fantastic effort this morning Paul, thanks very much especially the section on Eneraqua Technologies (LON:ETP) . I was quite interested in this company but the recent ceo video was unimpressive and only indicated the sharp drop in revenue at the very end. This company is only a risky punt now as I don’t believe in the numbers
Eneraqua Technologies (LON:ETP) - a possible explanation. of course, is that the additional assurance checks implemented by the Government on projects that have not been adequately staffed may still be an issue. That would allow for the statements about post year-end collection to be correct - cash outstanding at the end of the year was collected as described but new projects in H1 have replaced them. Of course, that doesn't explain why they don't give the cash balance at the end of September but I suppose that it may not be much better as new projects have replaced the debts that have now been collected. If the problem is as they say it is - additional quality assurance checks that aren't being properly staffed - then it could be an ongoing problem until staffing is resolved. I'm which case, they should say that.
7,979,457 shares sold in last 2 days
Major holders ex website for info
This information on this page was last updated on 13th July 2023. Number of Shares in Issue: 33,222,130
SHARE HOLDER
NUMBER
%
Anila Dhanak
4,147,327
12.48
David Routledge
3,725,485
11.21
Ian McLeod
3,691,065
11.11
Drew Johnson
3,125,485
9.41
James Waring
2,485,339
7.48
Charles Stanley Group
1,870,571
5.63
Slater Investments Ltd
1,685,920
5.07
Gary Copeland
1,675,613
5.04
Mitesh Dhanak
1,625,100
4.89
Care to tell us who you are talking about?
Eneraqua Technologies (LON:ETP)
rns out Charles Stanley a seller -
PUGUGLY: You're one of the oldest Stocko members, since 2010!
You must be quite excited about @Eneraqua Technologies (LON:ETP) - 3 of your 8 comments since 2010 were made today, and on this share!
Care to share your view on this company?
Always worth hearing from the quietest people in the room, when they have a topic they're really passionate about!
Was pleased to see in yesterday's RNS the proposed name-change of D4t4 Solutions (LON:D4T4) from what was more akin to the AI R2D2 robot than a business company. I hold and shall remain with CLBS for the foreseeable future.
My morning smallcap tweet: ChartyMcChartFace
Instem (LON:INS) Christie (LON:CTG) Celadon Pharmaceuticals (LON:CEL) Loungers (LON:LGRS), Avon Protection (LON:AVON)
◄Instem (INS)► offerer say 833p rec offer will not be raised. [SP=820.49 Cap=188m]
◄Christie (CTG)► warns FY23 op profit only 0 to £1m. Expects some transaction delays. [SP=96 Cap=25m]
◄Celadon Pharmaceuticals (CEL)► £1m placing and subscription at 125p, a 2% discount, for working cap. Also seeking issue of converts. [SP=128 Cap=79m]
◄Loungers (LGRS)► 24 week trading: rev up 22%, LFL rev up 7.7% from 5.7% in first 12 weeks. "Inflationary pressures continue to diminish in line with our expectations." CEO 'delighted'. In line? [SP=187 Cap=194m]
In line: AVON
Morning Paul,
A lot of work there above, many thanks!
I remember looking at STM (LON:STM) a while back, but losing interest in it.
Also was looking at Marks Electrical (LON:MRK), will not be investing now!
Regards