Small Cap Value Report (Fri 14 Apr 2023) - TIDE, IOM, STCM, NETW, DPH, SDRY, AO., 888

Good morning from Gozo*! Just Paul here today, with it being a Friday.
I've done a few catch up items to get us off to a flying start below.
Update at 13:20 - I'm going to do one more company, 888, then wrap up.
Update at 14:56 - right that's me done for the day, and the week! Have a lovely weekend, and remember I'll be podcasting tomorrow, so tune in for the next thrilling instalments!
(* don't be jealous, it's windy & overcast here!)
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
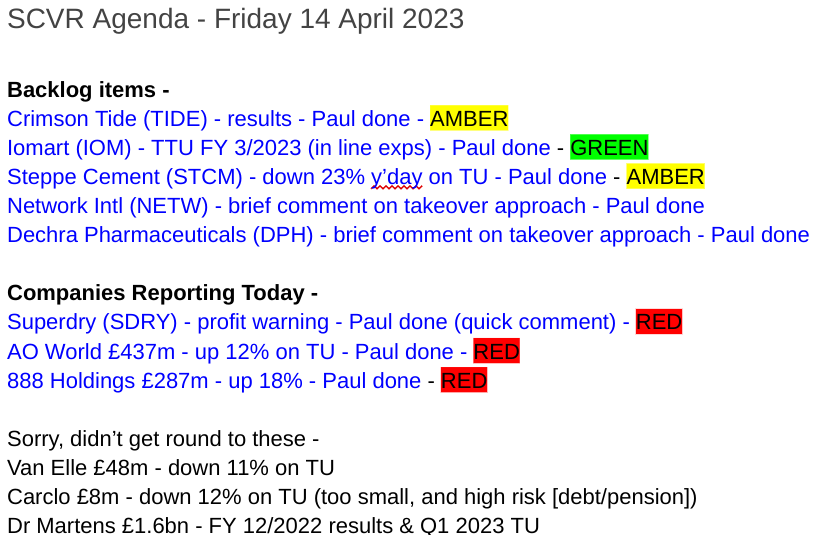
Main section summaries
AO World (LON:AO.)
Up 12% to 75.5p (£437m) - TU FY 3/2023 (top end of guidance) - Paul - RED
Another good trading update, with adj EBITDA at top end of previous guidance, at £45m. The trouble is, this only translates into about £4m real profits (PBT) by my calculations. Good news on bank borrowings though - these were cleared by year end 3/2023, with small net cash. And £80m RCF renewed until 2026. So considerable improvements, but still a very poor quality business, trading a whisker above breakeven. So it's a thumbs down from me at this valuation. Although as mentioned here last time, the shares clearly have momentum, so could be a nice trade, but it's built on flimsy foundations (as was proven with previous bull runs with this share). More detail below.
888 Holdings (LON:888)
888 Holdings (LON:888) - 74.4p (up 20% at 14:35) (£335m) - FY 12/2022 results & Q1 TU - Paul - RED
A complicated special situation, due to a disastrous balance sheet, laden with excessive debt.
Shares have bounced nicely today, due to in line 2022 results, and an encouraging Q1 update. Ignore the nonsense EBITDA figures, as heavy debt interest, and a large depreciation charge, mean that there's no actual profit. Net debt of £1.7bn dwarfs the £335m market cap, so investors need to understand special situations, and debt, otherwise it's just a trading punt. Very high risk, so has to be RED from me, thumbs down. Could multi-bag if the debt issues recede, or it could end up having to dilute, or even go bust, if things go badly. I'm just flagging up the risks, so you're aware and can take the facts into account in your decision-making. I'm not trying to predict what's going to happen, as I don't know. More detail below.
Quick comments -
(no sections below)
Superdry (LON:SDRY)
107p (£88m) pre market open - Profit warning - Paul - RED
Withdraws guidance for “broadly breakeven” (i.e. a small loss) in FY 4/2023. Says it is “challenging” to determine what FY 4/2023 losses will be - no wonder, since the auditors have been publicly flagging, for years, that its accounts department is totally incompetent.
Retail sales in Feb & Mar below expectations. Wholesale “continues to be challenging”.
Sale of IP in Far East not completed yet, shareholder circular expected in May. Lender has relaxed covenants, but sounds dependent on this deal completing, a key uncertainty I would say. Large cost savings of £35m identified (seems very high, how realistic is that? Potential equity raise for 20% of existing shares, so that would only be c.16m shares, say at £1 or less, maybe up to £16m - not a massive worry I’d say, if they stick to that level of dilution. Enthusiastic founder CEO, Julian Dunkerton, says he’ll “fully support” up to 20% of the fundraise, which is c.£3.2m.
Jam tomorrow - expecting a big uplift in profit in the medium term.
Paul’s opinion - as regulars know, I’m sceptical about this share. The over-promotional CEO has been promising a turnaround, brand reset, for a long time, but it’s just not working so far. Accounting/audit, and funding problems haven’t gone away. The smallish placing being considered might help, but I wonder at what price?
This is increasingly looking like Joules to me - great brand, lots of promise, but poorly managed. Lots of punters seem to like speculating on this share, but personally I want to see much more firm evidence of a turnaround before getting involved. Also, I wouldn’t touch it unless both the placing has been done (price uncertainty), and the £34m (net) IP sale in the Far East completes - that deal seems almost too good to be true, so I want the money in the bank before seeing this share as acceptable risk. Having said all the above, nobody can question the commitment and determination of the founder to turn it around. Overall, it could go either way. Something tells me the outcome is likely to be spectacular, but I can’t decide if it’s going to be awful, or a multibagger! I’m leaning more towards awful at the moment, but things might change for the better, who knows?
Crimson Tide (LON:TIDE)
3.1p (£20m) - Preliminary results - Paul - AMBER
Results came out 2 days ago. It’s a tiny software company, with an interesting-looking product called mpro5. A more aggressive growth strategy was adopted 2 years ago, after a placing (£6m at 3.0p). For FY 12/2022: revenue up 30% to £5.4m, mostly recurring (ARR at end year was £5.8m). Loss after tax was £(1.1)m. Sound balance sheet with cash of £3.6m, no debt.
The bull case is interesting - winning contracts with big organisations, and has a foothold in USA via Cisco.
Bear case is that it’s been around a long time, with only limited progress.
Paul’s opinion - I wouldn’t pay £20m for it at this stage. Management didn't inspire me on recent IMC webinar, it all felt a bit flat. Although could be a bid target, to quickly bolt on what looks like a decent product. Product seems similar to Touchstar (LON:TST) and Smartspace Software (LON:SMRT) . Might be worth a look for sector experts, who understand the product and the competitive landscape. Is it special, or just an also-ran?
iomart (LON:IOM)
121p (£134m) - Trading update FY 3/2023 (in line) - Paul - GREEN
I don’t recall ever looking at this cloud computing software company before. Graham reported on it here in Oct 2022, on a mild profit warning.
This week it issued a reassuring TU for FY 3/2023 - profits in line with expectations (in middle of analysts range). Guidance is £115m revenues, and £14.6m adj PBT - note the decent profit margin there. 92% of revenues are recurring, with stable customer renewals.
Outlook sounds OK - stronger bookings in H2, so good momentum for the new year just started, FY 3/2024. £7m hit from higher energy prices in Fy 3/2023, but largely passed on to customers, a good sign. This headwind could maybe become a tailwind now, as energy prices plunge. Balance sheet is rather flimsy, with only £4m NTAV at interims results.
Paul’s opinion - looks quite good. A decent business, on a value rating - PER only 11.2, and good dividend yield of 4.6%. Doing your own research, I suppose a key question would be whether all-powerful Amazon might erode its customer base over time?
Steppe Cement (LON:STCM)
Dropped 23% to 34p y’day (£74m) - Q1 update FY 12/2023 - Paul - AMBER
I looked at this Kazakhstan cement producer here on 16 Jan 2023. However strange it might seem to be listed in London, a good characteristic is that the divis paid have been generous since 2018. Also some Director buying. So it doesn't seem to be a fraud, unlike a lot of overseas companies listing in the UK in the past (which is why I nearly always steer clear of overseas companies on AIM).
Q1 was not so good, with Q1 revenues down 22% on last year. Partly macro demand factors, but also logistical problems with overloaded trains, so priority given to transporting other more essential products. Uncertain demand due to geopolitical situation.
Paul’s opinion - I rarely touch overseas companies that list in London,, as there’s usually something wrong with them. The history of good divis from STCM means it could be one of the good ones possibly? Investors would need to understand properly how the sharp drop in sales would feed through to profits/cashflows/divis? Is it temporary or a longer-term problem? I’ve got no idea, so will just say I’m neutral on this share.
Takeover approaches
A couple of mid-caps have received bid approaches, so I’ll mention them here for background interest, and to get them onto my spreadsheet which records takeover approaches. In both cases, they’re mid-cap growth companies, showing that there’s still appetite for deals in that space particularly, despite big rises in interest rates & banking turmoil -
Network International Holdings (LON:NETW) - confirmed yesterday afternoon that it is in discussions with a consortium of CVC Capital Partners, and Francisco Partners, about a possible offer for the company. I’m not familiar with NETW, but looking at its StockReport, it looks a good business, with a high profit margin, strong growth, and high quality scores. Looking at the valuation, and the chart, I wouldn’t be surprised if a bid comes in above the current level, so this share looks quite interesting.
Dechra Pharmaceuticals (LON:DPH) - again, not something we cover here, as it’s too big & a specialist sector. Last night, after hours, it announced a possible takeover approach at 4070p cash (47% premium to 2776p close last night). Possible bidder is EQT and Abu Dhabi Inv Auth. DPH’s Board says minded to recommend it, if possible bid becomes firm. The total value of a bid at 4070p would be £4.65bn.
AO World (LON:AO.)
Up 12% to 75.5p
Market cap £437m
AO World plc ("the Company" or "AO"), a leading online electrical retailer, today issues the following trading update for the 12 months to 31 March 2023.
Guiding to the top-end of the previously issued profit range
Revolving Credit Facility renewed
Revenues for FY 3/2023 £1.13bn, an impressive 32% of online electricals spend for “Major Domestic Appliances” (MDA).
Previous guidance (see SCVR 28 Feb 2023) was raised to a range between £37.5m to £45.0m. So it’s now today saying guidance is “around the top end” of that range, very good, so that’s c.£45m adj EBITDA.
The big problem is of course that adj EBITDA is a nonsense number! Consider that in H1, adj EBITDA was £8.8m positive. But profit before tax was a loss of £(11.6)m. That’s a huge £20.4m difference between adj EBITDA and real profits, PBT, just in a half year! Double that, to c.41m, and it means the fully year’s healthy-looking £45m adj EBITDA turns into a paltry £4m PBT. So this is a business that is actually trading a whisker above breakeven, with a profit margin of just 0.4% of revenues. Why would anyone be interested in investing in that? Let alone value it at £437m?
The only reason I can come up with, is maybe investors hope the profit margin can be improved in future? There are actually quite good reasons to imagine that might happen. Sterling has improved strongly against the dollar, which makes imported good cheaper in sterling terms. Also, there’s been a massive reduction in freight costs, so bulky items like fridge/freezers, coming in probably mostly from the Far East, will be very much cheaper to import now, once hedges have worked through.
Hence I can see that there’s an argument for assuming AO might be able to improve margins this year and in future.
Although as we saw when I looked at smaller, growing competitor, Marks Electrical (LON:MRK) in yesterday’s report, MRK is trouncing AO for profitability, generating a much better profit margin, and MRK doesn’t have any of AO’s on-balance-sheet risk from commissions on extended warranties.
Net debt - looks good, with a small net cash position expected to be reported at end March 2023. An £80m RCF has been renewed with a syndicate of 3 major UK banks, to April 2026 - so the previously precarious financial position now looks fully sorted, greatly reducing the risks for investors.
Paul’s opinion - I can see that the share price has momentum, and the newsflow is improving. So as mentioned last time, there’s a good chance this share could keep rising. But be aware of the risks, and that it’s all built of very wobbly foundations, in my view - negligible actual, real world profits, and a lurking risk that the large balance sheet entries re warranties could turn nasty at some point.
I would back MRK as a long-term, growing, better quality player in this space. Whereas I see AO as just a momentum trade on improving sentiment, but with little substance behind it.
Good luck whatever you decide!
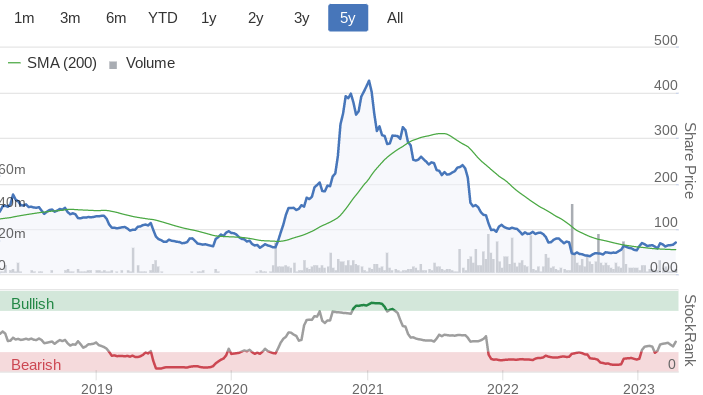
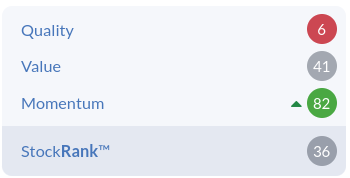
As usual, the StockRank system expresses everything I've said above in just 4 numbers! Here we are - a very low quality business, that's not cheap, but has great momentum -
888 Holdings (LON:888)
74.4p (up 20% at 14:35) -
FY 12/2022 results & Q1 TU - Paul - RED
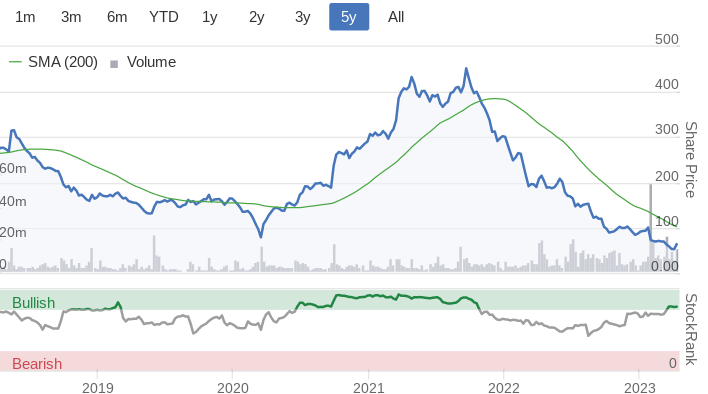
We’ve covered this gambling group before - it’s a special situation, which made an insanely high risk, debt-fuelled acquisition in July 2022 of William Hill’s non-US operations. That has left things in a real mess, with net debt now 5.6x EBITDA. So no divis until that is reduced to 3x. Very low PER, but that’s because it has £1.73bn of net debt! (only £89m of which is leases) Although interest costs are fixed for 3+ years on 70% of that, it says today.
The good news is that FY 12/2022 results out today are in line with expectations. Also an encouraging Q1 for 2023. Middle East problems seem to be getting resolved. EBITDA figures are absolute nonsense, because there are large depreciation and finance charges - e.g. £218m EBITDA for 2022 turned into a £121m loss before tax! (although that includes £93m of exceptional costs).
The accounts are complex, so it’s very difficult to work out what’s going on, and would be at least a whole day’s work I think.
Balance sheet is one of the worst I’ve ever seen. £159m NAV, but that includes £2.2bn in intangible assets. So the NTAV is negative by about £2bn, which is close to the £1.7bn net debt. In other words, the entire business is funded by debt. It’s difficult to see how the debt maturities which are not until 2027-8 will be handled, but maybe that’s sufficiently far in the future that equity holders might not be worrying about it yet?
The 7.8% bonds for 2028 are trading below par, at 86 - not a disaster, but maybe our bond experts could comment on this with more expertise than me?
Paul’s view - quite an extreme special situation. Not a safe long-term investment, but could be an interesting trading share, because there’s so much leverage, combined with a bombed out share price, that a lasting improvement in performance might violently resuscitate the shares, possibly?
Investors need to focus primarily on the debt covenants, as any breach could end up turning equity to dust. Also, what free cashflow will the enlarged group generate, and is that enough to get debt down to more sensible levels? If the share price recovers strongly, then management would be well advised to strengthen the balance sheet with an equity raise.
Please be careful with this one, it’s definitely not a regular investment. High risk, potentially high reward? Time will tell!
Management who presided over this debt-fuelled acquisition in 2022 should be barred from being Directors again, in my opinion. It looks like a similar approach that the numpties in charge of Cineworld adopted, with disastrous end results.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

68 comments
A different thought on Steppe Cement (LON:STCM)
I hold, this is small now <1% but this is a longer term play one is my ISA with reinvestment, one is Mum's ISA drawing income.
The ownership and listing are complex and for most would be a walk away, but hence the 1% not 5-10%. I have bought and sold, so now in the red, but overall happy to continue holding, even though yesterday broke the 20% sell rule, today brought it back in and I have only just looked so cannot do anything until Monday anyway.
I work in Construction, so without going into the political beast that is HS2, UK Construction PLC bumbles along, sometimes making a boom year or blowing up companies, ROK, Carillion etcetera. Why mention Aberdeen Western Bypass for the fans of Galliford Try Holdings (LON:GFRD) they survived but a useful lesson on how much the cost of one bad project can be DYOR.
Last year I was doing some free consultancy with my previous company for a small start up trying to access an opportunity in the Eastern Europe market. When you look at the basic information the growth was something like 8% per year it was a what the beep are we doing operating in the UK??? Even after slow down it is still 3-4% for 2023. Then when you moved further into the former Republics, the growth was even greater and accelerating.
I can remember being sent to Poland in 2002, there was I think 20km of motorway in the whole country! My company was bidding to build 400km. Take a look at what is being built in the Balkans currently in terms of major infrastructure.
I will not get into the interesting economics of the Caspian Oilfields and how that plays out, or the expat money coming home (think of Ireland in the past) but Kazakhstan has many parts, as well as the "Great Game" going on.
We complain we cannot get Polish or Bulgarian labour for the UK Construction sector as they now get paid more at home so why work away? They complain they cannot get Lithuanian or Kazakh labour as they now get paid more at home.
So yes there are many challenges, but you wonder when a government that says slow domestic construction through the winter period, you do not want to pour concrete below 2C ideally, keep people warm and keep the heating costs affordable? Hmmm, could we send Sir Godfrey out to take some ideas? Not back to the days of King Coal, but maybe someone thinking what is more important right now?
Simply this is a country that is growing, expanding, has decades of underspending on infrastructure, has oil revenue, an educated population, there is the opportunity.
This is not one I would add to the "Coffee Can", or "Hundred to One" part of the portfolio.
But it is in the I can understand what Steppe Cement (LON:STCM) do, I can understand the basic economics of the local construction sector within the country and neighbouring countries, I can live with the ownership structure, I can see the opportunity for the next few years, and appreciate the wider geopolitical risk. Look at Ferrexpo (LON:FXPO) as a case study which I do not hold, having sold.
Ok time to move on.
Tommy
Is there something I'm missing here, 888 holdings shows total liabilities of 217m on the interims on the stockopedia balance sheet (not 1.7 billion - I may have missed something so would be good to know !)
IIRC it's because Stockopedia hasn't yet updated the figures from e.g the year ending Dec 2022
Which is when they took on the massive amounts of debt!
Thanks ! Just wanted this highlighting - hopefully the stockopedia balance sheets can be updated sooner in the future
Hi Sina G,
hopefully the stockopedia balance sheets can be updated sooner in the future
The 2022 figures for 888 Holdings (LON:888) were only published today! So they should update overnight on Stockopedia, or early next week.
Regards, Paul.
Paul, I wish your view on Stockopedia's prompt updates were correct. In many cases there are significant time lags between RNS and update. This could be due to Stocko's dependence on outside organisations (Thompson Reuters?) to update their numbers?
This may be too late (Sunday evening) to be read.
Richard
I think that's a valid point. How/when does Stocko update these figures? After both interims and finals I assume. There's no other way they could do it presumably.
Yes that's right Pinemartin. As with all financial websites, the historic accounts information is updated promptly on Stockopedia when it is published by companies on the RNS.
This is why it's so important to do the manual side of things too - i.e. looking through the RNS for each company, to see the more recent updates (trading updates, takeover bids, placings, etc) that will not be reflected in the published accounts yet.
Or, just read the SCVRs (and broker notes), because we've done that work for you! ;-)
Regards, Paul.
888 Holdings (LON:888)
Is there something I'm missing here, 888 holdings shows total liabilities of 217m on the interims on the stockopedia balance sheet (not 1.7 billion - I may have missed something so would be good to know !)
If it isnt making sense you probably havent twigged that the wiliam hill acquisition didnt complete till 1/7/2022 after the interims date (probably no coincidence) - so company is a different beast now to what it was on 30/6/2022.
Concerning 888 Holdings (LON:888) why does the Quality rank show as 87 and the StockRank at 78 given your dire warning and debt laden situation?
Hi Pinemartin,
It's because 888 Holdings (LON:888) has only recently (Dec 2022) trashed its balance sheet with a massive acquisition, financed mainly with debt.
So if you look back at historic numbers, even the interims from mid-2022, its finances look fine, with minimal debt.
It will be interesting to see how the StockRank for 888 changes next week, as the horrific new debt numbers come through!
Regards, Paul.
Thanks Paul - Yes, that will be interesting! Thanks for the response.
Another day another takeover, this time Dechra Pharmaceuticals (LON:DPH) .
London listed stocks remind me of those soft-centre boxes of chocolates we used to have at Christmas. The best tasting one's (coffee, orange for me!) were chosen first. In the end you had a few left, all of them everyone's pet hate (Nougat - yuk!).
It's not good for the UK or London or UK based investors. From a selfish personal standpoint it would help to be allowed to hold US dollars in an ISA so that the US stock market was accessible without excessive currency costs.
Far better though would be to incentivise companies to retain their London listing. How? Cant see stamp duty being the major issue, but pushing pension funds/insurers/banks etc to invest a minimum portion of their assets in London listing? Sounds a bit dirigiste but would it work?
Some trade in Sosandar (LON:SOS) since mid morning. Was it tipped in IC?
It’s perfectly obvious to me. I sold a quarter of my holding yesterday as it was far too large a percentage part of my holdings. That’s why. Some heard I had sold some…
nothing in IC that I can see but almost 10% up today so it does feel like a tip somewhere.
I suspect it's a reaction to yesterdays results and subsequent research notes who think the shares are worth 48p
Gemfields (LON:GEM) has finalised its dividend at 2.295p (current spread 18-18.50 not yet XD Good value?
I guess with cash showing at $102m against a £217m market capitalisation, there has to be something here, I guess like all smaller miners unloved?
Tommy
ps. I hold (Mum's ISA aka Pension income)
Dr Martens (LON:DOCS) posted a trading update today. A bit of a mixed bag with the company reporting an increase in Direct to Consumer (DTC) sales in the EMEA region, but not so much in the US. They appear to have resolved the operational issues with their LA distribution centre in the States, but they've had to open three other 'temporary' centres to do so. This has cost them £15m, not the £8m -£11m originally forecast. They also mention a slowdown in wholesale compared to last year. However, they are still making a profit and have modest debt. Does anybody have any thoughts? I also wonder if this is a better potential investment than AO World (LON:AO.) which also reported a positive sounding trading update today.
Dr Martens (LON:DOCS) (no position)
Hi Derbion
I thought today's update was quite good, much better than I was expecting at least.
Unfortunately I didn't see the company announce their debt or working capital positions, though they did state their year end cash balance, which looked healthy.
I'm still mulling over what I think a fair buy in price would be, though I remain wary of single brand companies and the risk of declining appeal.
A
Good points.
I was in San Diego this January with work, shortly after the announcement of the difficulties in US distribution, and "mystery shopped" the Dr Martens (LON:DOCS) shop at the local mall when seeing it. The shop was very small compared to most in the mall and was nicely arranged with great iconic British related images and was playing complementary music too. The stall was really busy compared to any of the others I passed (Lululemon, Prada etc). I am in my 50s, still wear the shoes (not now all the time) and was so impressed I bought shares and have added since my return. Clearly I now own and am enthusiastic, but I thought it worth sharing my insight from that recent US visit today with Dr Martens again in the news.
Treatt- Last year Tea & FX were largely responsible for SP weakness. There is a huge opportunity in cold brew coffee. Difficult to produce authentic taste due to instability of coffee oxidisation although looks like Treatt have very interesting proven solution. Most of Treatt ingredients are 0.2% of finished product but coffee 25%. beverages are recession resilient- affordable impulse purchases. Mega trends, natural products, sugar reduction, provenance, RTD cocktails & seltzers, China( 6% sales & recent new order) & cold brew coffee( tea & coffee 10% sales). New UK facility has 2-3x capacity & there are joint development projects.
Over the last week, we've published a few results or update presentations, below.
Tracsis (LON:TRCS) H123 results for period end to 31.1.23 video & podcast. Revenue growth in Rail Technology & Services Division +69%, this looks a very dynamic part of the business especially with the US opportunities, some of which is driven by regulation, and there is very little competition. Referenceability by what they've done in the UK. A good overview of their strategy and strong track record. Outlook in line for the full year.
Sosandar (LON:SOS) full year 23 trading update webinar. This is a short overview but mainly Q&A with some good questions. Video & podcast.
Inspired (LON:INSE) Full year results for period end to 31.12.22 video & podcast. They have transitioned to help corporate businesses delivery net-zero, beyond the utilities cost control. Revenue +31% aEBITDA +6%, Cash generated from operations +113%. For full year 23 they guide that they'll achieve 12-15% EBITDA growth and 80-90% cash conversion.
I think there's a few of us got stuck with WANdisco (LON:WAND) - Ive been looking for news of how investigation progressing - After all it should not be too difficult to establish the facts and who is to blame but cannot find any info that Fraud Squat are investigating let alone made arrests. Anyone with any input please ?
I did a post on WANdisco (LON:WAND) at Christmas saying with the benefit of my years of IT experience it was pants. I hope I saved a few, I remember a lot of thumbs up apart from bohenie if I recall. If only I'd listened to the negativity on Yourgene Health (LON:YGEN) . You can't win 'em all.
Yes - I was the fool who held on - crazy but we all learn over time....
And what's up with £SPECS - another 10% gainer with no news out there... although it certainly warrants a lift back up!
Inspecs (LON:SPEC) is illiquid and Cockney Rebel was waxing lyrical on it on the podcast he did with Paul, so I suspect there has been bit of buying off the back of that.
Similar with Portmeirion (LON:PMP) where he likes it, Paul holds and now Simon Thomson at the IC tipped it. That chatter has pushed it up a quid. I'd like to buy some but I'm loathe to now until the froth/chatter has died down.
Well my great investment insight today is.... Big Dog for the National this year. Frankly I have no idea whether we are going to be having a recession or not which seems central to any investment decision thereafter. This idea people keep posting about UK markets are much more lowly valued than overseas seems to me completely misguided, there are many reasons for that and if markets fall they will fall across the board.
@Steppe Cement (LON:STCM) I have no experience of this company but I have held another Kazak company Central Asia Metals (LON:CAML) for a few years and the London based management have always impressed me with their openness and honesty. A well covered dividend has helped too and the fact they are probably the cheapest copper producer with a cash pile to expand their activities with an acquisition somewhere. The political situation has settled down with the Russian army demonstrating they are not invincible and the old USSR satellite countries looking to form relationships elsewhere.
CAML management are transparent however China and Russia are trying to take control of the Kazak govt.It has become a more unstable country over the last 3 years.CAML might be tempted to sell their Copper mine in Kazak and concentrate on adding to their Macedonian mine in other stable countries. I remain a holder along with Atalaya Mining who are based in Spain.
Ha! Me too!
Kaz is a massive country roughly equal to Pakistan and India together with an ethnic mix and varied trading partners. The largest influence is Russia but since independence this has lessened and recent elections were held to change laws to reduce a risk of a repeat of the instability of a year ago. Largest export markets are Italy, China, Russia, Netherlands and France in that order covering 50%.
https://www.britannica.com/pla...
https://www.reuters.com/world/...
As it's another dull Friday.. and markets are a bit ho hum at the moment I will give Pauls interview with cockney rebel a little push.
Im not saying I agree with all but it's a good listen with some interesting stocks. At this time of year running your winners ...or other peoples winners even.... often yields results. It goes without saying that UK equities and US equities are in very different places valuation wise. I agree you don't have to invest in "all" the market to make money... so a common theme here is you can ignore recession and market correction risk....to a degree. In the absence of a major risk off event the natural drift of things tends to be up not down. Please don't take this the wrong way....my defence against this risk...is to own things I will not sell. It doesn`t guarantee a successful outcome over any discreet time period though. The podcast focusses a lot on turnaround in retail - which does fit my value bent - a sector I often prefer to rent not own though! ie never overstay your welcome.
Wishing you all well and hope you've squeezed some gains from the positive mkt returns so far this year.
Market commentators (not tipsters I hasten to add)...Cockney Rebel is brilliant at turnaround situations in bull or especially bear turning into into bull market but much poorer in bear markets. Paul is brilliant in raging bull markets but less so in poor ones and gets caught out in bull turning to bear markets. I feel the Naked Trader is best overall because he mixes long term core quality stocks which he rarely trades but trades long in bull markets and short in bear markets - he's par excellence at identifying shorts. He just goes with the overall market flow.
He is the most difficult to replicate because, apart from a few very basic rules (not too much debt, making a profit etc) he just uses his instinct - am amazed at how little research he does yet makes money consistently
Robbie will be smiling as he inputs on here occasionally - how much did he pay you to say that ;)
The one big thing that NT does that most don't (and I include myself there - prob too much ego!!) which sets his performance up is cutting losses quickly when a trade is either not working or he is concerned about trading environment. That means he needs less winners to achieve good performance because he doesn't take 30/40/50% losses and hold on to perennial losers. Remember a 50% loss means you have to double the remaining capital just to breakeven.
unfortunately he didn't pay me for comment but I live in hope....he's a successful follower of the great but little known marxist French Philosopher Paul Lafargue .
I should have added that I'm very grateful to all 3 commentators for their insights as I have learnt so much from them - am poorer yet wiser now!
I went to one of NT's (Robbie) seminars in a hotel near Heathrow some years ago and he is a big fan of reviewing level 2 order book before making a decision. I think he looks at the volume of buy/sell orders above and below the current price. For example if there are a lot of unfulfilled buy orders just below the current price, even the price falls it has a lot of support so unlikely to fall much further. I am by no means an expert on the mechanics of this though.
Level 2 doesn't help much on Setsqx (most AIM ) stocks though. You can see which MM's are quoting and their spreads but that's it. There is a "Full Quote" link on Stockreport pages, next to the company name in blue,which gives a delayed idea of EMS , bid size and ask size.
I have also attended some of Robbie's seminar's I agree he can scan through potential stocks quickly with his standard checks max 3x debt to profit etc, where he is mustard as others have said is ruthlessly cutting losers and knowing when to pyramid up on winners.
The advanced day is well worth a visit as its more to do with the set up's of entering and exiting possible trades.
this matters to traders not investors. I look at the prices daily but make more decisions on price movements on weekly or longer basis,
Wasn’t cockney rebel the guy who was mad on MADE?
I think that was Richard Leonard not Cockney Rebel.
No it was Richard Leonard. I like Richard Leonard but I thought at the time (I think it was a PI world interview) that MADE was a odd call.
Morning Paul ,
it was one Sunday afternoon about 18 months ago that I have visited the Trafford Centre and I was watching about 75-100 people shopping at Zara and then just opposite , but on the bottom floor , trying to see for about an hour if anyone bought anything from Superdry (one did!).
It’s definitely looking like Joules?
It certainly is.
Enjoy your holidays and the lovely mediterranean weather that I miss so much.
I sold Dechra Pharmaceuticals (LON:DPH) last month due to lack of divi cover :(
We live with Sod’s Law.
I sold Tesco last month and bought Smurfit.
Since then Tesco is up 10% and Smurfit is down 10%.
Sod's Law = Murphey was an optimist!
STAFFLINE (STAF)
Not invested here but on my watch list.
Some very heavy buying by Henry Spain investments which I believe is run by renowned deep value investor Glenn Arnold .
He mentioned he was building a stake in something a week ago .
Superficially it looks very cheap on a turnover to valuation ratio .
I’m probably going to give it s wide berth because just don’t like any company involved in recruitment / staff .
Anyone got a positive view or know more about it ?
Staffline (LON:STAF)
I met the board back in around 2016 with a view to selling them one of my businesses. A more sorry lot I have never encountered. Like middle management of a midlands local council. Utterly clueless - which might go some way to explain its well-known financial difficulties later in the decade. The current CEO is made of stronger stuff and has an excellent recruitment track record in IT. Why he wants to run one of the lowest margin, price-taking, blue collar, non-specialist recruiters is beyond me. The money must be effing good. The rest of the board is strong on irrelevant blue chip experience and very weak indeed on essential recruitment sector nous. Notwithstanding the CEO’s strong background, I don’t feel comfortable with the mix of the board at all. Indeed, I don’t like the name one bit but I’m a snob on margins across all investment sectors and an inveterate one within recruitment. However, at some point the stock will fly on cyclical tailwinds and that point may be approaching within the next 12 months. But when that happens, SThree (LON:STEM) and Robert Walters (LON:RWA) will also take off and owners of those don’t have to worry about what they own in the mean time.
Great feedback thanks
Thanks BnB , great post and useful info.
Interesting review thank you BnB for Staffline (LON:STAF) and its management board.
It isn't so many years ago that this was hailed by Paul Scott - for good reason - as a well managed company with the ability to generate final results faster than anyone else. The CEO at the time some while later stepped down , became a NED for a little while and then sold out all his shares. I think the SP at the time was around £10 - yes £10! I wont say there was any jiggery pokery but the current SP bars very little relationship to that at the time, and circumstances have not IMHO changed enough to justify the fall from grace! Clearly the successful CEO didnt spend a lot of time on securing a well based succession plan prior to stepping down!
The model at the time, and presumably hasnt changed much, was quite a lever one, in that they operated from customer premises thereby reducing overheads to a considerable expense versus other comparable operations.
Certainly Brexit and Covid were not friendly circumstances, especially the former which must have affected labour source dramatically.
The other side of their businesses which was significant at the time was in job finding schemes backed by government, which then fell away as government support fell too.
I cannot see where Mr Arnold can make swinging savings - as explained it is not that kind of business model - nor are there likely to be government funds a plenty to support job creation schemes, but he may have other rabbits up his sleeve.
I am not a shareholder though have been in the past in better times.
Staffline (LON:STAF)
I wont say there was any jiggery pokery but the current SP bars very little relationship to that at the time, and circumstances have not IMHO changed enough to justify the fall from grace! Clearly the successful CEO didnt spend a lot of time on securing a well based succession plan prior to stepping down!
I could be wrong but i suspect all the issues of stafline started when they moved again from their bread and butter work into more exotic contracts where there wasnt simple margin applied to their "earned crust" - i suspect its taken till now for that crapola to be sorted. So to me things very much did change for ther riskier that could have worked outr great but itr didnt
I suspect the more exotic stuff was also the reason for the accounting irregularities - as ever well paid bosses dont have much to lose by shooting for the moon - if it dont work they are off onto their next well paid venture whatever.
Note i could be wromg in my assuptions here i am posting from memory of an old geezer
The model at the time, and presumably hasnt changed much, was quite a (c?)lever one, in that they operated from customer premises thereby reducing overheads to a considerable expense versus other comparable operations.
You'd think. But actually premises are a negligible cost for successful recruiters when you consider that almost every workstation is (theoretically) a profit generator. In my recruitment ventures, my strategy was to take the most prestigious city centre premises with the best access to retail and nightlife - and hang the expense. Surprise, surprise, high earning, big spending, rain-making superstar consultants want to work where the bright lights are, not in some suburban business park!
The only expense that registers is that of the consultant teams, where the trick is to pay enough fixed wage to be reasonable yet to offer very generous variable rewards on high productivity. It sounds simple but so many entrepreneurs worry about the costs instead of the top line. We had the best paid consultants in the land - and the biggest profit margin.
What is useful about the on-premise model, adopted by many recruiters, is that it puts a presence on site, to which all new requirements go first, if not exclusively. It's very effective for keeping out the competition. However, it tends to go hand in hand with a low margin approach.
Hi planetx,
Somewhat off topic, but I seem to recall that you're a fan of Titon Holdings (LON:TON) . I saw that last week the CEO stepped down with immediate effect and that consequently Harwood upped it's stake to 20% from just under 9%. What do you make of this?
Titon (TON) .
Commented on this few days ago .
I like it and in fact increased my holding this week .
They need a turnaround CEO with a bit of oomph and I dont think the last CEO was that person.
Rockwood getting involved is very positive.
The real estate is understated significantly its I believe worth 7 million which pretty much underpins he SP.
It does remind me of Crestchic a little, the South Korean division they should try to divest itself of for a chunk of cash and that is on the basis they have little ability to influence it.
The UK company had a disastrous implememtation of am operating system that hit them hard, been there done that and Im told thars sorted .
There is headwinds at the moment Im sure with builders slowing on new projects plus wage inflation.
On the positive the implementation of trickle vents to improve ventilation has not only come to be a legal requirement but is also a rising tide as the recent sad death of a toddler has highlighted, this needs sorting.
Ultimately by my fag packet its 50% below its asset value and a Benjamin Graham play.
Bit of a cigar butt maybe.
Ive done very well following Rockwood so think they will now be the stimulus here to unlock that value ,
If you can buy in the 70-75p range I think good entry point,
There is a 5% shareholder clearly selling down, she seems to be the wife (widow?) of a previous and distant CEO so thats no problem once she has gone I think we may get a spike upwards .
Sorry, I missed your comment a few day ago - I should have checked before posting. Thanks for replying (again). As Paul Scott has mentioned in his podcast, the quality of some of the posters on here is top notch and I count you as one such poster. As always, your posts are balanced and considered. Once again, thank you for sharing your thoughts - much appreciated. I will dig a little deeper into this stock over the weekend.
Thanks for that, dont know about top notch but balanced hopefully,
Im into a lot of very small microcaps which is quite risky but I keep them at a risk level that Im very comfortable with
Good morning Paul, re Steppe Cement, we are holders, a small holding which was on profit till yesterday. Being underwater in cement has bad connotations and they certainly didn't gild the lily with their report. We'll stick with them for now and monitor the geopolitical situation!
Likewise. Lets hope it makes some good foundations and we aren't stuck in them.
Superdry (LON:SDRY) goes from bad to worse. Guidance withdrawn. Equity raise coming.
https://www.investegate.co.uk/...
Superdry (LON:SDRY) - I'm about to type up my notes, aiming to get that up by 8am...
EDIT - did it! my take on SDRY profit warning went up at 07:58! Will be interesting to see how much it falls today! A fair bit (nicely vague!) would be my guess.
Superdry (LON:SDRY) My first thought was to wait until after the raise and then buy some on the basis that the business may have been put into better shape by then. On a separate note, I'm beginning to think that AO World (LON:AO.) might have changed its spots and could be a multi-bagger. Always the risk they go back to their old ways though....
My morning smallcap tweet: An RNS enema to unblock profits
Superdry (LON:SDRY) Non-Standard Finance (LON:NSF) Industrials REIT (LON:MLI) Carclo (LON:CAR) AO World (LON:AO.) Creo Medical (LON:CREO), Van Elle Holdings (LON:VANL)
◄Superdry (SDRY)► guides FY23 rev only £615-635m and withdraws ‘broadly breakeven' profit guidance due to poor Feb-Mar. Partly blames cost-of-living crisis and weather. Wholesale performance continues to lag the rest of the group. Plans initial cost savings of over £35m by end FY24. Considering an equity raise of up to 20% of cap. [SP=106.8 Cap=88m]
◄Non-Standard Finance (NSF)► agrees provisional terms for £71m d4e. Current shareholders will be dilutes to negligible value unless they participate in the equity raise.Trading still encouraging. "Collections performance remains ahead of expectation and delinquency performance has returned to historically normal levels." [SP=0.43 Cap=1m]
◄Industrials REIT (MLI)► rec offer of 168p, as mooted. [SP=163 Cap=11165m]
◄Carclo (CAR)► guides FY-Mar rv down but reduction in net debt compared to end H1. "Cash-intensive top-line growth strategy was unsustainable in the current economic climate. Focussing on "on margin expansion through operational excellence and balance sheet strengthening via cash generation". [SP=13 Cap=10m]
◄AO World (AO.)► guides FY-Mar rev in line and profit at top end of Feb's guidance. £80m revolving credit facility renewed. [SP=67.35 Cap=389m]
◄Creo Medical (CREO)► buys final 5% of Albyn Medical for €1.2m since earn-out terms met. [SP=27.5 Cap=96m]
In line: VANL