Small Cap Value Report (Fri 14 Jan 2022) - SNR, QUIZ, XAR, SMRT, CINE, EQLS, SENS

Good morning, it's Paul & Jack here with the last SCVR for this week. Today's report is now finished.
Jack & I are going to trial an end of week podcast this afternoon. If it's any good, I'll publish a link to it here later today, probably this evening.
EDIT: Here it is, the first (and maybe last!) SCVR Podcast.
Agenda -
Paul's section:
Quiz (LON:QUIZ) (I hold) - small and illiquid. This ladieswear retailer is recovering well. December trading and year-to-date (FY 3/2022) is in line with mgt expectations. Not the best business in the world, but with shops now on short leases & cheap turnover rents, it should move back into profit in calendar 2022. Plenty of cash in the bank, which is up to £6m. So this is a value/turnaround micro cap situation, which I imagine won't appeal to most readers.
Xaar (LON:XAR) - trading update from yesterday. H2 moved into profit, recouping the losses in H1. Commentary sounds upbeat, and has plenty of net cash. I don't know how to value this share, due to erratic performance.
Cineworld (LON:CINE) - Q4 trading update, which glosses over the desperate debt position. Extremely high risk of heavy dilution or insolvency.
Equals (LON:EQLS) - a short section from earlier this week.
Sensyne Health (LON:SENS) - top faller today, down 69%. It's a high cash burner, and has almost run out of cash. I see if this was predictable (it was, it was obvious from the accounts), and compare it with the dot.com boom & bust from 1998-2002. Conditions now seem uncannily similar for speculative tech/growth.
Jack's section:
Senior (LON:SNR) - group says full year will be in line with expectations. Net debt reduced by £49m to £80m, cash flow positive, new contracts announced, and notes the start of a recovery in its markets. Margins were falling pre-Covid, but might subsequent restructuring and cost-cutting arrest that trend? It’s beginning to look a little more interesting now.
Smartspace Software (LON:SMRT) - short in line update ahead of more detailed announcement next month. Micro cap, so a lack of liquidity. Forecasts have been considerably downgraded over the past year. There’s still a lot to prove, so I don’t see any rush to jump in.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section
Quiz (LON:QUIZ) (I hold)
15.7p (yesterday’s close) - mkt cap £20m
QUIZ, the omni-channel fashion brand, is pleased to announce an update on trading for the period between 1 December 2021 to 31 December 2021 ("the Period") and its current cash position.
No surprises here, the recovery continues. QUIZ is a ladieswear retailer, which specialises in special occasionwear (weddings, parties, etc) - the worst possible niche to be in when the pandemic struck.
What’s interesting, is that QUIZ did a pre-pack administration in mid-2020, which enabled it to exit all unprofitable stores. The remaining stores are now on turnover rents, which has halved the rents payable, and made them flexible - so that in quiet months little rent is payable, and in busier months the rent goes up. This is a wonderful structure (I’ve got a lot of experience of turnover rents, as in my CFO days, “Pilot” operated about 50 sites on turnover rents, and 100 on conventional leases. 49 of the turnover rent sites made a profit, but lots of the conventional leases resulted in losses).
QUIZ also has a well developed online offering, although in the past it relied too heavily on third parties, e.g. Debenhams (where a lot of its physical concessions used to be based). Hence the demise of Debs has hit QUIZ quite hard.
This is what it says today -
Dec 2021 revenues +20% on last year at £8.8m for the month
Stores/concessions +64% (LFL revenues are now “broadly consistent” with pre-covid levels)
Online down 26%, but this is due to termination of 3rd party arrangements, own website revenues (higher margin) are flat
Gross margins good, at pre covid level (checking back, this was c.60% - which is high)
Year-to-date revenues (9m to end Dec 2021) £61.0m (+88% on last year, which was harder hit with lockdowns)
Note that April & May 2021 were impacted by some covid restrictions on gatherings, so the £61m YTD revenues will be somewhat below normalised, unrestricted trading. I estimate that this should be a £80-100m p.a. Revenues, and profitable, business post-covid. Which makes the £20m market cap look interesting, with possible upside?
International (Ireland & franchises) - up 11% to £1.5m for the month of December.
Pandemic - impacted Dec revenues, and increased customer returns rate, as people cancelled parties, especially in the 2nd half of the month. So not a bad outcome in the circumstances.
The Board was pleased with the performance achieved in the Period given the challenging trading conditions, notably the widespread cancellation of social events and the introduction of formal restrictions on social activities in Scotland, Wales, and across Ireland following the continued rise in COVID-19 cases throughout December. For the same reason, footfall during the second half of the Period was also notably reduced. This impacted demand for, and increased customers' returns of, QUIZ's partywear products in the second half of the Period.
Cash - liquidity is fine, with £6.0m cash at 13 Jan 2022 (a seasonal high, in my experience), plus undrawn £2.9m bank facility, due to expire in Sept 2022. It has been renewed in the past with no issues, and there are no covenants on the bank facility, so clearly there is a supportive bank (the founding family are wealthy, so that’s probably why the bank perceives little risk).
Outlook - rather odd wording, and doesn’t include any footnote as to what expectations are, so could have been clearer -
The Group is encouraged by the positive performance delivered during the Period, which highlights the strength and awareness of the QUIZ brand, and the growing customer demand for its trademark dressy and occasion wear offering.
The Board remains confident that, in the absence of any further substantial disruption from COVID-19, this demand will support continued profitable revenue growth and deliver a full year to 31 March 2022 performance in line with Board expectations.
Valuation - the last note I have is from early Dec 2021, which forecasts £74m revenue for FY 3/2022, and a loss of £(2.9)m. Not great, but my impression is that management see this year as a transitional year, when the company has still been impacted by covid (esp. April & May 2021), and has been in recovery mode.
It’s forecast to move into a profit of £0.9m for FY 3/2023 (forecast raised in early Dec 2021), doubling to £1.8m in FY 3/2024. I’m hoping to see upside on those forecasts.
My opinion -
If there are no more restrictions, then the business should enjoy a sustained period of buoyant demand for partywear - with a store portfolio now operating on cheap, flexible leases (average length on signing is only 2 years). They want to build up online through own website sales, which is higher margin. Then the international, and franchising operations could be useful contributors too.
All in all, I think it’s a potentially promising business, which has been highly profitable in the past, before things went wrong (pre covid, it has to be said). At £20m market cap, it looks a cheap recovery situation to me, with very experienced management.
What went wrong pre-covid? From what I can gather, it’s down to this -
- Over-reliance on third parties, e.g. Debenhams used to be about a quarter of revenues, and was highly profitable, that’s gone now. Hopefully QUIZ could recover some business, with Boohoo (I hold) online version of Debenhams in future.
- Mistakes over product historically - wrong product, and in wrong quantities. Improvements have since been made to the buying/merchandising team
- Onerous leases - which have since been ditched in the pre-pack administration in 2020, so won’t be a problem any more, as the company is only signing short, and cheap turnover-based leases now.
With those issues sorted, and a much lower cost base for the store rents, high gross margins, and not much physical competition left in some towns, QUIZ has everything to play for. Note that Next said in its recent trading update that demand for partywear is coming back, and Sosandar (I hold) said something similar. Hence QUIZ's niche is now a good place to be.
This should be a profitable business in future, which the company alludes to today in a rather oddly worded outlook section.
As I’ve said before, this is not the best business in the world, but it does look cheap, for a credible, securely financed recovery situation. My price target is 40-50p per share, with a 2-year view. As always, that’s not set in stone, and would change if the facts change.
Note the shares are illiquid, and tightly held (founding family still owns about 50%, and I’m told are totally committed to turning it around, and haven’t taken it private when it was very cheap).
Due to the share price going up, and other things going down, it’s become a top 3 holding for me personally.
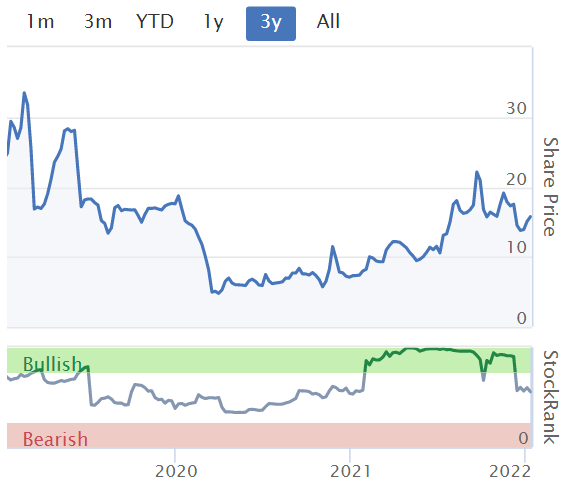
The 3-year chart looks encouraging, and reflects gradually improving fundamentals since the pandemic began. Initially it was all about just survival, which the restructuring in mid-2020 dealt with. Since then, it's about gradual recovery. So far, so good.
.
.
Xaar (LON:XAR)
1847p (up 3% at 11:21) - mkt cap £144m
Xaar plc ("Xaar", "the Group" or "the Company"), the leading inkjet printing technology group, today announces a trading update for the year ended 31 December 2021.
Strong end to the year -

.
H1 revenue was £26.3m, so that makes H2 £32.7m, a useful uplift.
H1 adj loss before tax was £(2.3)m, so H2 must be at least £2.3m positive, to create a profit for the full year.
The rest of the update talks positively about operational progress, and supply chain improvements - e.g. stocking up on key components.
Cash position looks strong, with £25.2m net cash at 31 Dec 2021 - boosted by receipt of £9.3m “initial consideration” from divestment of Xaar 3D.
Outlook -
"We ended the year well with an improved second half performance which shows the positive momentum we have in the business . Strong order intake over the last few months gives us confidence of maintaining this momentum into 2022. The investment in working capital gives increased certainty in our ability to maintain supply to our customers throughout the year, a year in which we expect to see further growth. We will continue to invest in capability and capacity to drive growth and deliver further opportunities to grow the business and accelerate our strategy."
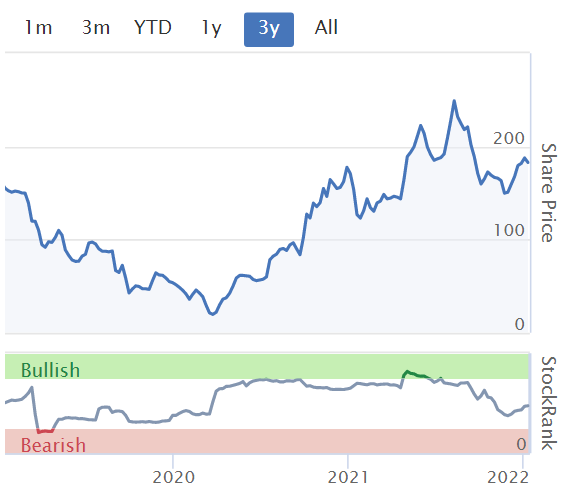
My opinion - no current view, as I wouldn’t know where to start in valuing this share. I've followed XAR since it listed, in the late 1990s, and have made good money on it a couple of times, when products have hit a sweet spot and the shares rocketed. Only to come back down again when those products (e.g. Chinese ceramic tile printers) succumbed to competitive pressure. A reminder that growth is not necessarily forever, and products often have a life cycle before larger competitors come up with something better/cheaper.
Current performance doesn’t justify a market cap of £146m (at 186p per share), so investors must see good potential for future profits to improve.
Performance has been feast & famine in the past, so it’s a very difficult company to assess from the numbers, it would need much more detailed research on the products, the competition, etc.
Investors have enjoyed a fantastic % gain since the Mar 2020 low, but it's not likely to deliver the same % gain again.
.
.
Cineworld (LON:CINE)
38.7p (flat, at 10:37) - mkt cap £533m
Cineworld, the second largest cinema exhibitor in the world with operations in 10 countries including the United States and the United Kingdom and 751 sites and 9,188 screens globally, today provides the following update on trading across the Group for the six months to 31 December 2021.
Revenues have “steadily grown”, although still quite volatile, and below pre-pandemic levels. The timings of film releases, and varying covid restrictions, are given as reasons, so it’s not back to normal yet -

.
Positive cashflow -
As a result of this improvement in revenue and the cost measures implemented, the Group generated positive cash flow in Q4 2021.
Remember that this company is drowning in debt, so it needs to generate huge cashflows, just to service, let alone repay, its debt.
Cineplex legal action - the company lost a large legal case (previously announced), which has resulted in damages (£730m) which could bankrupt the company in my opinion. It’s lodged an appeal.
Diary date - 17 March 2022 for FY 12/2021 results. That’s when the full horror of the balance sheet will be revealed, which is glossed over in trading updates.
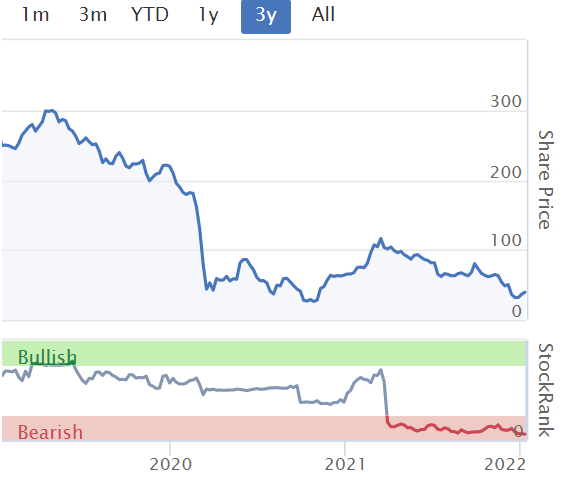
My opinion - this company is teetering on the brink of insolvency. I ran through the numbers here on 15 Dec 2021 - total debt is now over $5bn!
Plus the legal case it lost has incurred £730m damages. So if CINE loses its appeal, that could tip it over the edge.
If things turn out well, this share could recover, but the risk of a large, or total wipe out of equity, looks very high indeed. The holders of debt are in the driving seat, and equity holders could end up being an afterthought, if the debt holders play aggressively, and force a big debt for equity swap. Or take control completely, who knows? It's very much a special situation, where I feel private investors are at an informational disadvantage - we don't know what's being said behind closed doors, nor what the debt holders are likely to do.
Why take the risk?
I don’t know what the outcome is likely to be. All I’m flagging is that this is one of the highest risk shares of its size on the UK market, due to excessive debt. If you have a punt on it, just be aware that the downside scenarios are very grim, and it could be a 100% loss. So this is very much not a simple re-opening trade recovery situation, it's much more complex, and high risk. So buyer beware, and only risk money you can afford to lose.
.
.
Equals (LON:EQLS)
Up 9% to 73p (on Weds 12 Jan 2022)
Equals (AIM:EQLS), the fintech payments group focused on the SME marketplace, is pleased to announce a strong trading performance for the financial year ended 31 December 2021 ('FY-21') resulting in unaudited revenue of £44.1 million, an increase of 52% on FY-20.
Earnings are only in line with mgt expectations though.
Cash - has £13.2m at end Dec 2021.
Current trading - continued strong trend from late 2021.
“Managing costs proactively” - mentions payroll, and utilities.
Spending 20-25% of payroll on product development, should drop below 20% in 2023
Planning to increase sales & marketing spending
Expecting a recovery in “travel money” revenues.
My opinion - none, as I haven’t researched the company. Jack wrote up its positive trading update here on 8 Dec 2021.
I’ve been meaning to look at this company for a while, as a friend flagged it as an interesting growth company, that looks to be tipping into profitability, after poor performance in the past.
Do any readers know EQLS, and have a view?
.
.
Sensyne Health (LON:SENS)
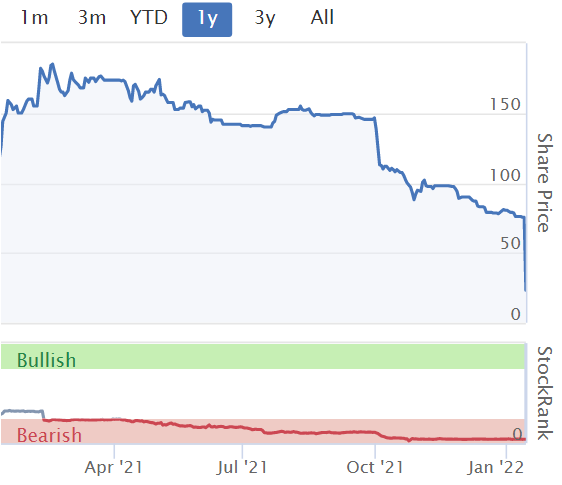
24p (down 68% at 12:10) - mkt cap £40m
We’ve never covered this company before here at the SCVR, because it’s a heavily loss-making jam tomorrow type of company.
It’s come up on the top % fallers list, so I’ve taken a quick look.
There’s a lengthy explanation of what’s gone wrong, but in a nutshell, it’s run out of cash (only £2.8m left, but it’s a heavy cash burner), and says it’s about to cease trading in early February, without an emergency fundraise.
Institutional shareholders have signed a “non-binding term sheet” for a £6.35m loan, and a further possible £5.0m loan, with a 25% repayment premium in lieu of interest by the looks of it. No dilution from loans, but there is dilution from warrants exercisable at 10p, for up to 17.7% of the company.
The company is also in a FSP (formal sales process), hoping to sell itself before it goes bust by the looks of it. Why would anyone pay anything for the equity? It’s often the case, in distressed situations, that a buyer negotiates with the debt holders, gets them to take a haircut, and wipes out the equity completely. The key point being that equity ranks behind debt in law.
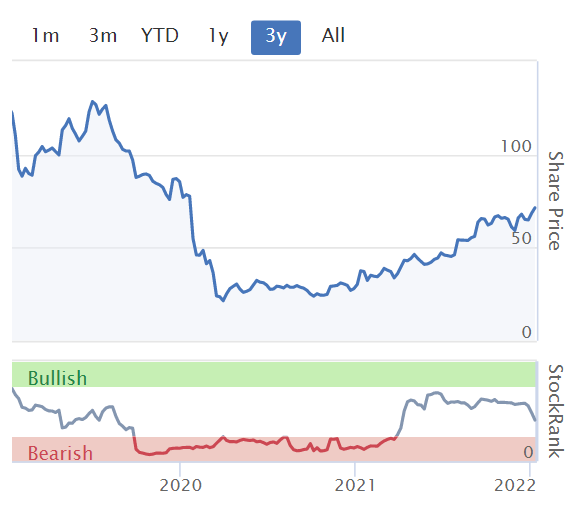
Therefore I think a price of 0p is looking a high probability here.
It says there is a substantial debtor, being chased for payment. So the company might be able to save the day by collecting in that money. Maybe they should offer the debtor a discount, to cough up quickly?
Were the problems predictable? Very much so. Looking at the FY 4/2021 accounts, the company ran up a loss for the year of £(28.4)m before tax. Admin, and R&D expenses totalled £31m, which dwarfs gross profit of £5.9m.
There was £23.6m cash at 30 April 2021, but that was below the annual operational cash burn shown on the cashflow statement. Hence, without another fundraise after April 2021, it was obvious that the company would run out of cash about now.
Further, note 2 (going concern) to the FY 4/2021 accounts specifically explains that there is a “material uncertainty” over the company’s viability (which is generally stated on a 12 month basis from signing of the accounts). It said this at the conclusion -
In the scenario of the Group and the Company not being able to generate any new revenues, we would need to seek alternative sources of funding to the support the Group and the Company through a combination of some, or all, of the following: equity offerings, collaborations, strategic alliances, grants, debt financings, and marketing, distribution of licensing arrangements. Although we consider that there are strong grounds for believing that such funding could be secured, as demonstrated by the successful fund raise in January 2021, there can be no guarantee that would be the case. While the Group and the Company believes it will be able to enter into new commercial agreements to generate new revenues or secure alternative sources of funding within the next 12 months, there can be no assurances that the Group and the Company will be able to do so on a timely basis, or at all. These circumstances mean a material uncertainty exists that may cast significant doubt on the entity's ability to continue as a going concern.
The downside scenario played out, and it has indeed run out of cash. Demonstrating how important it is for investors to read going concern notes & take them seriously.
The new debt being raised from institutions, looks to be only enough to keep the lights on for a few more months. That they're offering debt, not fresh equity funding, also speaks volumes.
My opinion - this is a great example of why I try to avoid investing in any heavy cash burning company. If I do, then my rule of thumb is to only invest if there’s at least 2 years’ cash burn sitting in the bank account.
Companies that rely on round after round of fresh financing can, sooner or later, run into a brick wall when shareholders refuse to pour in any more money.
There’s a fantastic book on that, highly recommended, called Boo Hoo: A dot.com Story from Concept to Catastrophe, by Ernst Malmsten, an early internet startup star, who came a cropper in the dot.com crash of 2000.
Here’s the wikipedia page about Boo.com. NB. this has nothing to do with Boohoo (LON:BOO) (I hold), it’s a completely different company & people.
Younger readers need to read up on the dot.com boom & bust of 1998-2002, which peaked in early 2000, as we’re arguably seeing something similar, on a much larger scale, right now!
So many things are similar (and I’m thinking mainly in the USA) -
- Lots of massively over-valued IPOs of barely profitable, or loss-making high growth tech companies
- Animal spirits running out of control
- Cocky, often young, management who seem dynamic & clever, but turn out to be full of BS and financially clueless (e.g. Adam Neumann of Wework - another fantastic story that’s worth reading up on)
- Multiple speculative bubbles based around new technology (e.g. Bitcoin, cloud, apps, etc)
- Valuations detached from reality, and new metrics invented to justify nosebleed valuations
- Growth expectations assumed to be open-ended, when actually they turn out to have limits
The good bit, is that value shares tend to come back into fashion, when growth valuations blow up, as people stop chasing speculative stuff, and focus more on solid earnings & divis. Personally, I regard some reasonably-priced mega tech shares as value/GARP shares (specifically Google & Facebook (I hold), which are not expensive, particularly when you factor in that they’re expensing a lot of startup losses from venture capital type activities within the group).
The only hope for SENS now seems to be that someone might buy it in the FSP, and/or the large debtor (no figure provided today) might be collected in. But that could still end up being a 0p outcome for shareholders.
Personally, if I held, I’d ditch them at any price based on today’s news, and learn from the experience - not to hold any cash burning company, which is going to run out of cash imminently - easily checked by some basic time spent reading the accounts.
.
.
Jack’s section
Senior (LON:SNR)
Share price: 141.9p (pre-open)
Shares in issue: 419,418,082
Market cap: £595.2m
Senior’s an international manufacturer of high technology components and systems for the worldwide aerospace & defence, land vehicle and power & energy markets. It’s a decent size, with operations in 12 countries and pre-Covid annual revenues of more than £1bn.
Aerospace is traditionally the group’s largest segment. Clearly, Covid has hit trading.

Today’s update suggests a recovery is in sight however, and the group has managed to get through the past year or two with no equity dilution.
It’s an in line trading update for the full year - consensus estimates suggest around £661m of revenue and a net loss of £3.11m (set to improve to net profit of £13.5m the following year). Senior itself says revenue is now expected to come in at around £659m.
The Aerospace division is expected to be around 12% lower on a constant currency (cc) basis, while Flextronics revenue is up 10% cc, with improved profitability in both divisions.
The group has generated positive net cash flow of £58m, and net debt is ‘modestly’ better than expectations at c£80m (down by £49m).
Restructuring and cost cutting has improved profitability, while the group notes a recovery in core markets including civil aerospace.
Conclusion
I’m not familiar with Senior, so if anyone else knows it well feel free to jump in.
FY19 revenue was £1.11bn and diluted net income was just over £50m, meaning a 4.5% profit margin. That’s on the low side, but if the group can bounce back to FY19 levels then the 12.2p of normalised EPS generated in that year would value the group at 11.6x recovered earnings. Reasonable, but not an outright bargain.
Good cash conversion though, with free cash flow often in excess of reported earnings per share in the past.
There hasn’t been any equity dilution - in fact, shares in issue have fallen slightly over the past five or so years from 423m to 418m. Perhaps the shares could get back above the £2 mark then, assuming the current recovery persists.

I can’t see any obvious reason for the drop in 2018. Perhaps just the valuation getting ahead of itself? While revenue had been steadily increasing pre-Covid, profits were not keeping up, so perhaps that’s the reason.

There’s a chance that might change with this recovery, given the cost-cutting and restructuring initiatives, so it’s potentially worth checking to see if this is now a fundamentally more profitable enterprise on the cusp of recovery. Meanwhile, the big risk of equity dilution looks to have reduced.
Senior announced a couple of contract wins a few days ago with Honda and Boeing (see here and here), which is encouraging. I’m still neutral for now, but this is becoming more interesting.
Smartspace Software (LON:SMRT)
Share price: 74.3p
Shares in issue: 28,941,234
Market cap: £21.5m
Very short update today. For context, Smartspace owns software that helps flexible work offices run their operations (‘integrated space management software’). It’s very small and illiquid.
The shares had last year before disappointing the market on trading. Profit guidance has been considerably lowered, as have broker EPS forecasts.

The same lack of liquidity that led to the rise has seen the shares subsequently fall from 182.5p to 74.3p.

Trading update for the 11 months to 31 December
Smartspace expects results to be in line with expectations of revenue of c£5.2m and adjusted EBITDA losses of not more than £2.7m. Group cash stands at £2.8m.
That’s it. We’ll have a more detailed update sometime in the middle of February.
Conclusion
Not much to say here, for now. The growth story has taken a knock, as has investor confidence. It’s very small at c£20m market cap with a track record of net losses and sentiment is poor after the downgrades.
The shares have settled in the 70-80p range and there has been a small level of buying this year, but it’s negligible really. Happy to sit on the sidelines ahead of a more detailed update next month.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

86 comments
Weekly summary typed up, with audio file of our first SCVR weekly summary podcast here.
Companies mentioned below & timings
(green = out-perform trading update, red = profit warning or financially distressed balance sheet)
01:49 – Quiz (QUIZ) (Paul holds) £20m – Xmas trading update, in line with exps. Interesting turnaround.
02:18 – Senior (SNR) £591m – In line update. Jack thinks it looks potentially interesting.
03:15 – Xaar (XAR) £157m – Moved into profit in H2. No opinion from us.
03:42 – Smartspace (SMRT) £22m – in line with exps trading update. Small, and loss making. We’re lukewarm.
05:19 – Bear market in US for speculative tech. Impact of lockdowns. Flow of PI money in/out UK market.
06:45 – Cineworld (CINE) £554m – update doesn’t mention elephant in room – $5bn debt pile! Very high risk of heavy dilution or insolvency.
07:30 – Sensyne Health (SENS) £35m – has run out of money. Shares down 69%. Very high risk of equity wipeout.
08:15 – Equals (EQLS) £142m – earnings in line with exps. Good revenue growth, but high valuation.
10:57 – Asos (ASC) £2,340m – in line update, surprisingly good, given supply chain issues impacting sector.
11:08 – Card Factory (CARD) £188m – good current year update, but profit warning for next year, due to huge increase in costs (£30m)
11:57 – Royal Mail (RMG) £4,950m – Should we be worried about wage inflation?
12:36 – Circassia (CIR) £180m – scraped into a small positive EBITDA for first time, ahead of mkt exps. But valuation a concern.
14:53 – Countryside Properties (CSP) £1,810m – shares down heavily on profit warning. Poor figures & CEO walks the plank.
15:15 – Science Group (SAG) £205m – positive trading update. Figures look good, a decent GARP share (growth at reasonable price)
15:48 – Finsbury Food (FIF) £127m – reassuring trading update. Valuation looks reasonable. Mitigated cost increases so far.
16:06 – Quixant (QXT) £118m – Jack likes this ahead of expectations update.
17:42 – Accrol (ACRL) £71m – another profit warning, due to delays in passing on more cost increases. Paul is sceptical of the business model.
18:07 – Portmeirion (PMP) £99m – positive trading update, profits 9% ahead of exps.
19:00 Gateley (GTLY) £264m – Interim results. “Strong position to deliver” mkt exps for the full year. Jack prefers this legal firm to Knights Group (KGH). Paul briefly mentions RBGP – another legal group with impressive CEO.
20:47 – MPAC £111m – year end trading update is in line with exps. Positive outlook, with increased order book & pipeline. Don’t ignore the huge pension scheme though.
23:30 – Shoe Zone (SHOE) (Paul holds) £71m – good results for FY 9/2021. Helped by Govt support measures, and release of provisions relating to closed shops.
24:44 – Robert Walters (RWA) £660m – another profit upgrade. Jack continues to like this share.
26:50 – Cambridge Cognition (COG) (Paul holds) – contract win.
26:55 Unbound Group/ Electra Private Equity (Paul holds) – decent current trading for Hotter Shoes, it’s operating business.
27:05 – Audioboom (BOOM) – turnaround continues, with another positive trading update. Valuation now looks high though, for modest profitability.
27:20 – Tortilla Mexican Grill (MEX) £72m – strong finish to 2021, results “materially ahead”.
29:59 – Nightcap (NGHT) £38m – strong trading in Dec, and 70% of Xmas bookings deferred into 2022, not cancelled. Suggests hospitality sector could have a better Jan/Feb than imagined? Lots of new bars planned. Cash position is gross, not net (misleading).
Paul,
Ha! That's brilliant, thank you - and one thing I thought would really be helpful for me - but I really did not want to ask for more :-)
cheers
Mark
This is fantastic, I'll look forward to hearing more of these in the future! Thanks.
Brilliant Idea, keep up the good work providing you both do not burn yourselves out and again Many Thanks
Bruce
Thank you for the Podcast. I don't normally find podcast chats to be very helpful - but this one fits into my Saturday morning review of the week like a glove - very useful to have your input at the same time - I've already noted a couple of ideas to follow up which got buried in the week. So thank you for doing this - and I'll certainly be listening if you find the time to do it again,
cheers
Mark
Really enjoyed the podcast Paul and Jack - thanks for taking the time to do it - hope you consider continuing to do this if time allows.
Excellent Podcast format. Please continue
Actually it was 30 mins. Even better!
podcast was an excellent recap on the week. Great effort to keep rattling through and keep it to 40 mins. Hope you can do it regularly. Many thanks Paul and Jack.
Paul & Jack,.
I am such a great fan of what you guys do and find it mind-boggling the sheer quantity of your output, let alone the quality.
Accordingly, whilst we are entitled to give our opinion here, though only if we are a paid-up subscriber, some on here in my view, are complete idiots, in the way they criticsize you and Jack. and as a result, I find their negative attitude disgraceful and I wish they would feck off for good. TS
End of week Podcast!!!
Fantastic, can’t wait. Always aware of just how much ‘stuff’ you chaps get through in such a short space of time makes me reluctant to ask for more so delighted to see this being tried.
Thanks so much for all you all do.
Couple of updates on my portfolio holdings this week that I thought was worth sharing.
Tmt Investments (LON:TMT) gave a portfolio update on Monday, with the most notable being a new funding round for their largest holding Bolt, which was led by Fidelity and Seqouia at a valuation 56% above that of the last funding round, leading to a $37.2m uplift in the value of TMT's investment and adding around $1.18 onto the NAV. Additionally there were other strong valuation updates for smaller holdings such as Workiz (+300%) and Hinterview (+35%) alongside a number of new investments and follow-on investments. Yesterday one of the company's holdings EstateGuru also announced they would be launching their P2P commercial property lending platform in the UK soon following FCA approval. Using the latest share price for Backblaze, I put the shares at a 13% discount to the $8.95 (noting that they have previously in 2021 traded at a 20-30% premium to NAV).
Frontier Ip (LON:FIPP) also put out two updates, first an announcement that one of their portfolio companies Celerum - a company that uses nature-inspired computing in AI to improve operational efficiency of logistics and supply chains - had launched their first commercial product and won an order from a large road haulier for the software in the North of England (no £'s). They also put out a trading update, noting that they were expecting to beat management expectations and that they were starting to sell down some of their holding in Exscientia , which listed in the US in October. Using the latest Exscientia share price, which is now c20% below the IPO price, the shares still sit at an 8% discount to the 107p NAV, which seems harsh given progress made with Celerum and The Vaccine Group over the period.
Equals (LON:EQLS)
Bought some of these yesterday. Had hoped to get them sub 70p but market is very tight for stock so I bit the bullet and paid 75p. Doesn't seem to be much stock around. Noticed some very large blocks of trades going through so seems some institution ownership changes. Schroders bought over 5% yesterday by looks of things.
Looks like a superb company with lots of growth still to come and management allude to a bit of a horizontal growth strategy where they can offer new complimentary services to the existing and growing company base.
Downing like it and see fair value well above 100p. The Paul Hill interview linked below on Vox Markets does a good summary.
Creightons (LON:CRL) H1 22 results presentation by the management team, given 12.1.22. To replace the £14.6m revenue from the 2021 hygiene sales for the FY is pretty impressive growth from their core markets. They are uber excited about Emma Hardie, acquired recently, and the new markets and margins that accesses for them. Their aspirations for 2024 haven't changed: Rev £100m; EBITDA 12.5% Branded sales: £40m Digital (branded) £25m Contract manufacturing £30m+ and private label £30m. IMO they are just at the beginning of a transition from low margin FMCG to high margin growth, when the market wants this too, look at Olaplex ($OLPX). Video & podcast.
I do think Creightons (LON:CRL) would help themselves if they also made sensible projections as to the (considerable) extent to which they expect to increase the shareholder count over this period. They are very keen to highlight how much they plan to grow sales and EBITDA, and do a good job of this, but I am notonly interested in much they plan to grow the business... ...with salary increases and bigger bonuses one potential result. We need to get some sensible input on what will happen to EPS where the increases will not be quite so exponential, as they issue significant numbers of shares for acquisitions and in staff bonuses.
As was mentioned in the latest video, they also, very definitely, need some broker coverage. Not just for the reasons given but so that financial forecasts aren't leaked out, in very bad practice, outside the realm of RNSes, albeit in well produced PIWorld videos.
Its just incredibly bad management practice. They wanted to be treated as top quality professionals but in this respect behave like complete amateurs. If they want their forecasts/targets to be treated seriously, put them in RNSes, or get broker coverage... ...and then supplement this with PIWorld videos. Don't continue to defy good practice in this regard.
All IMHO.
Yeah, they treat shareholders like dirt. Got a long history of it. Interest in the company owners doesn't seem a priority for them.
Afternoon all
Anyone have any idea what's happening at Avingtrans (Avingtrans (LON:AVG))? Jumped up 23% on no news. Presumably something has got out somewhere....
Fortunately, I hold!
Avingtrans (LON:AVG) Price shot up at 12 noon, but I'm getting 454p to buy price on my platform, seems strange. Can't find any news.
Price is now back down to around 454p, so maybe this is a system glitch?
Level 2 has Avingtrans (LON:AVG) @ 430-455p up 0.57p. An aution takes place at 12 noon so maybe something happened to the orderbook.
EDIT: a buy occurred @ 545p at 12:19 so that seems to be a mistake.
Trade input at 545p rather than 454p. Just a wrong print
well that's annoying...
Looking on Level 2 there was a buy of 532 shares @£5.45 at 12:19. I think it must be a typo as transaction before at 12:02 was @£4.55 and the one after at 13:41 was at £4.54
Happy New Year Paul. Glad to see you looking happy and healthy on the video. The new facial hair gives you something of a "distinguished Victorian gentleman" look. Some sort of friendly Dickensian character or something.
I am curious as to why you say that Quiz (LON:QUIZ) isn't "the best business in the world". I am not claiming it is, but you don't say that about any other companies and I wondered what it was about Quiz that makes you say that.
To me, it's actually (now) quite a nice little company. It's in a niche that's going to do very well in the next 2-3 years, is well funded and has a management who knw what they are doing and have a sizeable stake in the company. That all feel positive?
Genuinely just curious.
hi Paul,
Have you seen this interview yet from Paul Hill on Equals (LON:EQLS) ?
Looks very positive I don’t hold but would be interested in buying at maybe 70p if it drops a little currently it’s hitting resistance.
Sorry wrong link.
Crystal Amber hold 20.7% which, following the decision to close down, will come into play. This might surpress the sp, depending on how and when CA sell their stake.
Paul or Jack d you have any thoughts on Sensyne Health. Announcements lead by good progress in orders, then for sale put on company and finally capital raise via Instis. Good fortune means I am not in it although I love the idea of collecting patient data and using it in health care. Does n't seem much to base any idea of the company maybe worth if they can find a seller. The capital raise is maybe short to medium term as many negotiations been put back by Covid. At nearly 70% down today I cannot help feel there might be an opportunity here but not brave enough to take it as I can't work out what I think it is worth.
Hi camtab,
Coincidentally, I've just published a section on Sensyne Health (LON:SENS) as it comes up as the biggest daily faller today.
It's bust basically. I think the equity is worth nothing. Unless they find a buyer in the FSP, but why would anyone bail out the equity holders?
Regards, Paul.
Thankyou Paul. I have been hurt too often recently due to my weakness for story stocks so consider this a lucky escape. Helpful to have someone say "don't be a wally" in such a nice way! All the best for 2022.
One of the best drivers of my improved results in the last few years has been reading what Paul writes and effectively allowing him to talk me out of story stocks. Paul Scott - the voice of reason! Many thanks Paul, keep up the good work!
Hi Fishcake, agree 100% that Paul is the voice of reason in business hours, however....
Sometimes when he lets his hair down after hours and has had a few "sehrebrts", you can't even understand his postings - But we wouldn't have him any other way
I did say that I would assess CAML yesterday. The thread from yesterday has become a bit protracted and narrowed, i.e. the typing column narrows and becomes harder to read, so I will post here if that is okay.
Kazakhstan and Macedonia - unrest in Kazak, you would need to form your own view. I think that energy price unrest will be a global occurence this year. France will probably take to the streets re energy prices quite soon now (gilets jauns). Copper, zinc and lead is what CAML extract.
Big upgrades and a very large acqusition made in 2017 to 2018. Part funded by share issuing, although the share issuing was proportionately smaller than the acqusition, big debt issue as well to part fund the upgrade and the acqusition. the size of the business was effectively doubled.
The debt has almost gone now, the tangible equity growth added to the dividend is over 11% of the current MCap, payouts expected to increase once the debt is gone, which is expected to have happened in 2021. Not risk free, but a real wealth generating business.
For holders of Thinksmart (LON:TSL) the General Meeting today approved the Board Resolution by an overwhelming margin in favour 99.79%
I notice less than 50% actually voted as only holders of 48.5 million Shares voted out of 106 million Shares in issue.
RNS out at 11.37 today.
hi Jack
Senior (LON:SNR) - I think you will find the 2018 problems were largely related to the knock on effect of the Boeing 737 MAX crash.
hi Jack
£SNR I think you'll find that the 2018 problems were largely a knock on effect of the Boeing 737 Max crashes.
Jack,
you wrote a nice piece on EQUALS in early December and since then it has bettered!
would you be interested to do another review?
greatly appreciated
Hi jayrannejad,
Equals (LON:EQLS) - you've just reminded me, I wrote up a short section on this the other day, and forgot to publish it! I'll add this to today's article now.
Regards, Paul.
Quiz is the obvious brand to bring on board if you think partywear will be a growth area this year. Next have done so and have now got over 200 products from them which is encouraging plus other big sites such as Very and New Look. Together wth family experience and backing happy to hold through 2022.
hi Paul - Picking up on your comments about Quiz (LON:QUIZ) - as we agreed last year to increase the Mkt Cap of companies analysed to £750m - would it not be an idea to up the min size now - personally I would go for £50m but perhaps I would be heavily shouted down so maybe £30m...?
No need to read anything about micro caps Bohenie if you don't want to. My vote is for Paul to write about anything he thinks is of interest, please.
Point taken and thanks to Paul for the explanation below.
Hi bohenie,
hi Paul - Picking up on your comments about Quiz (LON:QUIZ) - as we agreed last year to increase the Mkt Cap of companies analysed to £750m - would it not be an idea to up the min size now - personally I would go for £50m but perhaps I would be heavily shouted down so maybe £30m...?
I'm happy with things as they are. As the explanatory notes say, we generally look at market caps up to about £700m, but if we think a share is interesting, we'll go above that sometimes.
At the smaller end, we hardly ever mention anything below £10m mkt cap. But again, if something is interesting, then we might cover it.
It might help if I reiterate the process that Jack & I use each morning to decide which shares to write about.
We have a shared googledoc, where we together, from 7am, make a list of every company reporting (excluding miners, biotech, etc) with mkt caps from £10-700m. We also add anything else that looks particularly interesting.
We skim read the announcements, to pick out the ones that are either profit warnings, or out-performs, as they are the most price sensitive. MrC's daily update is a big help here, thanks MrC! :-)
Other items we focus on are stocks that are widely held by readers, and shares that we personally know well (as we can rattle off sections on them quickly).
Obviously I look first at shares I hold personally, as everyone else does. If I've looked at them & taken notes, then it makes sense to publish my notes, as typing them up doesn't take too long.
We then look at any broker notes which come through for shares we're covering, and also we look at the largest % daily movers to see if there's anything that's moved a lot, and we might have missed a key announcement.
We also review MrC's brilliant early morning summaries, and we read all the reader comments, to see if the community has flagged up anything interesting for us to look at.
So it's quite an involved process, and carefully thought through. You'll find that we tend to cover about 5 companies per day, which gives me time to take a more in depth look at a couple, with Jack rattling out a couple of sections early, to give you something to chew on!
Generally we eschew the smallest companies, so these days it's fairly rare for us to cover the real tiddlers at £10m-ish. We usually put a note next to them in our list, saying "too small/illiquid". Or we might just do a short section on something really small. To answer your criticism, we don't actually cover many companies below even £50m market cap - which you can confirm by looking back through some recent reports. We're aware that liquidity matters for readers.
QUIZ gets a big mention today, because it's a top 3 holding for me personally, and I'm watching my investment closely. So since I've done the work anyway, might as well type it up. Remember I'm a professional investor, and do the writing on the side, which recycles research work I'm doing anyway for my own purposes.
Hope that helps clarify things.
Best wishes, Paul.
EDIT: Here's Paul/Jack list on our googledoc for one day this week, for a real example of how we plan the SCVR for the day -
Actually, thinking about it, maybe we could publish our list each day in the reports?
As you can see above, if the trading update (TU) is just in line with expectations, then it's usually a waste of time us looking at it, because there's not likely to be anything price-sensitive.
Trian Investors 1 (LON:TI1) I know some of your like special situations on here. This looks very interesting. Trian are an activist investor (with good track record and seem to be well regarded) who take stakes in public companies and push for change.
The fund is currently all is invested in US plumbing supplier Ferguson (LON:FERG) - looking at recent charts and trading updates this share has been preforming superbly.
Based on comments at the last interims, it seems Trian are now ready to move on - Ferguson have implemented most of their suggestions and share price roughly doubled.
This morning's RNS showed TI1 NAV per share was 217p as at end of Dec. The share price currently stands at 134p - a 38% discount!
In terms of what happens next, my guess would be they pursue another target once they move on from Ferguson. Some patience is therefore required - may be a while before shareholders get their capital returned. But on any measure this looks very compelling value.
I see James Halstead (LON:JHD) is up 6.5% just because of a share split ( 2 for 1). Who knew it was that easy eh? How does that fit in with efficient market theory?
Maybe they should do it again next month.
MPAC ??
Can you explain further Mpac (LON:MPAC) ??
I hold
Regards
Michael
there was a bid at £2 for Senior sometime ago. That may happen again!
As mentioned yesterday, here is PIWORLD Sell it to the City January 2022. Richard Crow (@RebelHQ) comes back to defend his title against Daniel Jones and Leo Hendry (@leoinvestorUK). Each deliver a 10 minute pitch to Andy Brough, Schroders, Judith MacKenzie, Downing and Stephen English, Stellar Asset Management. Excellent presentations cover Shoe Zone (LON:SHOE), Synthomer (LON:SYNT) and Capital (LON:CAPD), followed by penetrating Q&A. Then, the Fund Managers deliver their verdict on the pitch and the stock. Who has Sold it to the City this time? And, who will ultimately win the prize lunch with one of these fund managers? Great fun and insight. This was recorded on Monday, the day before Shoe Zone (LON:SHOE) FY results. What a great call!
Please get in touch via the PIWORLD contact page, to put yourself forward to pitch at the next Sell it to the City. We’d love any investors to come forward, especially younger investors who might be trying to get into the City. What better opportunity to get your name known and to add the experience to your CV? For those with more years, it’s a great challenge, and forces us to really analyse that prize holding and get top Fund Manager feedback. The idea is to find a hidden gem that these Fund Managers know little about or have missed in their own research, and to have a bit of fun.
Next week we have the Stockopedia/PIWORLD stockslam, live on Wednesday 19 January, 6pm. Do join us. 10 investors present their best stock idea to the live audience who ask their questions, then a recording will go out the following Friday. Register here.
Also, next week, find out what's going on at Accrol with their H1 results. Join the webinar on Thursday 20 January, 12.45. Register here.
Thanks for that Tamzin. Accrol Group (LON:ACRL) that should be a laugh a minute. Question No 1 - when the directors sold a bundle at the beginning of the year, what did they know that others didnt. Probably just a lucky guess I would imagine.
I’m more concerned by the government’s inability to stand up to the blob and the high taxes that ensue from this
Does anyone else share my concerns that the combined effects of Brexit, Covid and Government mismanagement of both those and the economy are pushing the UK towards a prolonged and, possibly, permanent decline that might make the UK economy and stock market poor investments for the foreseeable future?
I currently have shares in about 60, mostly, UK companies and I'm considering selling most of my UK shares and finding somewhere else for my cash.
No.
I currently have shares in about 60, mostly, UK companies and I'm considering selling most of my UK shares and finding somewhere else for my cash
I believe the UK is in a long term decline, politically, economically, socially and demographically. Consequently I favour UK companies whose earnings are exposed to the rest of the world. But they only form 20% of my portfolio, the balance of which is mostly US and Europe. So you could look elsewhere or concentrate on UK-listed firms with global reach, from Experian to AstraZeneca to Renishaw and many smaller ones besides.
Most mining stocks are listed here but operate overseas. BRWM
I don’t think we’re in absolute long term decline. I think we’re headed for long term slow growth and “comparative decline”, while countries in Asia will become the worldwide economic powerhouses. I’d also say this is similar to many western economies, so to include Brexit in your argument just sounds like a bit of a political rant.
Thanks for that BnB and bryan1311. I take the point about investing in companies in the USA and Europe and UK companies with a global reach. I attempt to do so but am dismayed at the recent decline in the value of my portfolio. I have a few US shares but I clearly need to look outside the UK more than I do. I admit to being anti Brexit but only because of the damage I expected it to do to the UK. While the effects of Covid have also affected the situation, Brexit remains a big part of our economic problem. and is likely to remain so for a long time.
Let's try to avoid straying into politics here, it never ends well, and is so boring.
Although in terms of factual information, I'm struggling to think of any company in my remit (about 500 smaller listed UK companies) that has mentioned Brexit as a significant or long term problem. Several have said that it's increased administration, and they've had to raise prices selling into the EU, or open a warehouse within the EU (e.g. £g4M (I hold) opening new warehouses in Spain & Ireland recently).
People perhaps forget that companies rapidly adapt to whatever the world throws at them.
Most people are not rational on this issue, I find, it's become too emotive.
People who supported Brexit see positives, and that none of the prophecies of catastrophe actually happened.
People who opposed it, latch onto every negative & teething problem, and it reinforces their existing view that they were right to oppose it.
So really, there's something for everyone! We all think we were right! Happy days :-)
Regards, Paul.
Thank you Paul for a very balanced reply.
Obviously there are companies that have suffered from Brexit and possibly some that see a benefit, but really that's not a good way of assessing the issue. We haven't even seen all of the changes implemented yet. The group best placed to give an independent assessment of the total economic impact is the Office for Budget Responsibility. In 2021 they said their estimate of the long term impact was a loss of 4% of GDP. That's the best estimate we've got and it's a significant cost. We lose approx £90 billion pa in output and £36 billion in tax revenues i.e. about £700 million a week (in contrast to claims of £350 million a week extra).
So, sorry Paul, but saying that it all depends who you talk to, is not really appropriate. As we stand today, the best evidence says that there are clear economic costs. That's not to say the decision was wrong, there may be social changes that people value, it's not all about the economics. Even on the economics the picture may change. Perhaps in the future we'll see a revolution in our economy that somehow wouldn't have been possible within the EU. But from where we stand today, the best evidence available says that there are clear economic costs to Brexit.
Well done for making Paul's point.
OBR forecasts don't mean a thing. You can tweak the variables in a spreadsheet to show anything you want.
The whole point of the OBR is that what they "want" is to provide an independent and dependable forecast of government finances. It's all too easy for you to dismiss them without backing up your claims with evidence. But let's set the OBR aside if you don't think they have any merit and go back to basics because I'm interested to know what your opinion is based on.
Many of the costs of Brexit are obvious. Companies can reorganise as you say, they can move operations and jobs to the EU, they can pass on higher costs to customers because everyone has the same issues. Companies don't have to take a long term hit, but the costs to the UK economy of these actions are unavoidable. Meanwhile, frictions in trade have been known for centuries to be detrimental to growth. Equally, the constraints on labour supply, while they have an individual benefit for UK low skilled labour, will only reduce output. All of these things and others present clear costs to the economy. So for Brexit to be positive for the economy, there have to be clear offsetting benefits. These seem much harder to identify, but you must be able to see them if you think they offset the obvious costs. So what are they exactly? If there really is a plausible case I would genuinely like to hear it because I have not heard it set out so far.
Hi Meldraw,
No doubt, Brexit has affected a number of businesses negatively, additional cost or making the business unviable. It's important to factor this into your investment decisions.
Good luck with 2022.
BSV
Perhaps Meldrew could spend sometime dwelling on the number of negatively effected shares in his portfolio, 60 seems to be a lot. My right wing portfolio of 30 shares is at an all-time high and all UK listed shares. Try trimming out the dross, it might allow the performers to shine through.
Dear Slopsjon,
Best to direct your advice to the intended. In this case Meldrew. I don't think portfolio's can be right-wing, just the owner.
All the best
BSV
I think I directed the post in the right direction. I noticed you edited your previous post.
Nope!
I feel like you are living in a different country to me Meldrew (first name Victor by any chance ?) I am not saying life isn't tough for some but with no mass unermployment , unlimited bods happy to come to our country to work or better themselves low interest rates and a reasonable provision for most people who are struggling (i would agree things like energy prices doubling need addressing for the poorest). I would say compared to the dark days of the 80's when i grew up jobs are more plentiful , living accomodation is much better , we have a reasonable minimum wage and reasonably cheap food - i think we are well placed if you ignore the fact we dont balance the books and have a huge deficit , you probably do have a point that we have not "looked after our pennies and lived within our means" but i simply don't see much if any sign that this country is in terminal decline - obviously if you want to go looking for problems you will easily find them by the buckeload but most bods i know are working and getting by just fine even if they do grumble.
As to whether the prospects are good for uk shares - perhaps there are better prospects elsewhere but i would say for companies the economy at present isnt a disaster due to teh above reasons.
Specifically Ref Brexit - how has the uk suffered ?, most peeps i know are quite happy that as workers they have a bit more pricing power post brexit - thats probably the majority of the population - pre brexit many skilled trades had a horrendous period with their pay rates coming under pressure from bods coming in form overseas happy to work for minimum wage and happy to take full tax credits extracted ouyt of teh country for the kids they had left back at home ! - must admit i didn't vote for brexit as personally i didnt want to be reponsible for putting someone out of a job (there will have been job losses due to brexit) - but must admit from my point of view it has been anything but the disaster we were told it would be (all imho).
Hi rmillaree.
I used to employ Hungarians.
They were good workers, but they didn't contribute much to the UK economy, as the vast majority of the wages they earned were sent back to their families in Hungary.
They would live very frugally, often in basic low standard accommodation.
They were happy to work for less than British employees, as they didn't have the outgoings and commitments that the majority of workers in the UK had. This resulted in home grown personnel being undercut and had the negative effect of lowering wages here.
That was one of the main reasons why the vote went against the people that voted to remain in the EU, especially here in Wales where I reside.
News flash - British and European workers both earning minimum wage.
How they chose to spend it up to them.
BSV
LOL - If workers have pricing power, we don't need a minimum wage.
BSV
If a significant number of market participants are convinced the UK is in long term decline then valuations should already reflect this. Then if this fear proves to be overstated, holders of UK focussed securities will see the benefits in time. Whether the UK is in long term decline or not definitely falls into the "too hard to judge" category.
Another issue is where else to put your money. Europe has plenty of long term, well reported economic difficulties. It's also arguable that the US faces pretty significant political and economic risks in the coming years. Invest 50% of my portfolio in China? No thanks to that either. You can make the bear case about any country and it's respective stock exchanges, but serious fears usually get priced in pretty quickly. Geographic diversification protects from regional black swans.
It is not so the much UK is in decline just that other nations are catching up and may prove to be better investments. UK is still a good investment location.
If I can't stock pick well in the UK, then there is less chance I could for another market I'm less familiar with.
BSV
We should also consider that the opposite may be true. If a significant number of market participants are convinced the UK will thrive post-Brexit then valuations could already be reflecting this. Then if this optimism proves to be overstated, holders of UK focussed securities could be disappointed.
My impressions from my investing friends and social media observations generally, is that the investment community was broadly pro-Brexit, so I fear this scenario is more likely.
Coincidentally, this link came to my inbox today. The title "Two-thirds of manufacturers say Brexit has hampered business" seems at odds with a much more upbeat feel I got when I read through the article. Note it specifically relates to the manufacturing industry.
https://www.imeche.org/news/ne...
Yes I agree with this, who knows how all the market participants are positioned. I was more just pointing out at times I find it is a bit pointless trying to second guess the market on these types of wide-reaching issues. One thing to try and outsmart the market with research on a small cap stock, another entirely to out-research the market on global politics and macroeconomics.
Interesting that you post the imeche article, I received the same email today and thought it might be helpful given this topic of discussion. No real surprise that many manufacturers have had brexit related issues. I always felt the "brexit positives" if you will were more likely around looser financial regulation rather than aiding industry.
This is complicated.
In the short term, trading less with people a few miles away at a time when it has become v. expensive to trade with people a long way away can be seen as a less than smart move.
In the medium term, economic growth is supposedly aligned with population growth / the average age of the workforce, not Europe may be a good move.
In the long term, some studies show proximity to resources is seen as a key driver for economic growth (coal / gold / people / knowledge/ legal system)
In the very long term the value of everything = 0.
So, who knows?
Or
This is simple
You are saving to buy things (food / a car / your child's education / etc / etc) All these things are (probably) denominated in GBP. It sort of makes send to match liabilities in GBP with assets in GBP.
You have assets in UK based companies. When you bought them you thought you would do better in them than a tracker. You are a subscriber here. That indicates you still hold that view in the large. One of the main advantages we have is that we live here and so have better access to information. None of those advantages are going away.
So, carry on.
Personally I don't think our government's management is any worse than that of the EU or the US and will not be altering my investments.
Following on from yesterday's comments about inflations.
Do anyone know anything about Alternative Income REIT? It seems that even the brokers, Peel Hunt, haven’t written on it.
Look at this announcement:
https://otp.tools.investis.com/clients/uk/aew_reit_long_plc/rns/regulatory-story.aspx?cid=2253&newsid=1531762
The relevant bits:
"The portfolio has a long term, secure and attractive income flow with predominantly indexed linked rent reviews, and a very strong rent collection history. The portfolio has a weighted average unexpired lease term of 17.4 years to the earlier of break and expiry and 19.6 years to expiry”
"87% of the portfolio's income stream is reviewed periodically, on an upward only basis, in line with inflation. 65% is indexed to RPI and 22% is indexed to CPI.”
"Rent reviews are a key feature of the Company's asset management programme and are expected to deliver enhanced income and capital growth:
· 55% of the portfolio's contracted rent is due to be reviewed during the year to June 2022. There are 8 indexed annual reviews (expected increases averaging 2% to 3.5%), 2 indexed 3/5 yearly reviews (expected increases averaging 19% to 20%) and 1 lease expiry.
· 57% of the portfolio's contracted rent is due to be reviewed during the year to June 2023. There will be 8 indexed annual reviews (expected increases averaging 2% to 3.5%), 4 indexed 3/5 yearly reviews (expected increases averaging 7.5% to 9%) and 2 lease expiries/tenant's breaks."
So at 74p, it’s a yield of 7.4%, reasonably safe for 18 years and basically indexed linked.
What am i missing?
Of course, i hold.
I have just replaced our side fence as it had reached end of life and the contractor told me that the annual January price increase in the fencing materials will be 13% this year! As far back as he can remember the annual increase has been a few percent.
only 13% … just replaced some fence posts for paddocks. Last year they were £5.50 yesterday I had to pay £13.50
I met the manager of Asda pharmacy who said most of the over the counter medicine (pain killers like iboprufen) and cough medicine prices have gone up by up to 50%.
Agree with the attractions you mention.
Potential detractors;
- it is very small compared to other REITs, net asset value of £69m at last year end announcement(30/06/21)
- small size means the running expenses eat into rents that much more. Ongoing running expenses at 1.27% of NAV per announcement
- this leaves an uncovered dividend with cover at 85%
The board has made a concerted effort to reduce running expenses, but basically it needs a fund raise to materially increase its size, which is harder to execute given the discount to NAV.
I hold.
ChrisW.
You’re not missing anything with £AIRE. It’s one of several UK Commercial Property Investment Trusts paying excellent and sometimes growing Dividends. The AIC website is excellent for all Investment Trusts and this link will bring up Alternative Income Reit (LON:AIRE) and others in the UK Commercial Property sector. It reveals current dividend yields, current discounts or premiums to NAV, 1, 3 and 5 year share price performance and much more! And then clicking on each individual Trust brings up a wealth of information as long as that Trust subscribes to AIC as the vast majority of Investment Trusts do.
https://www.theaic.co.uk/aic/f...
One thing you have missed was the superb buying opportunity in 2020 when some of these Trusts were on 40% discounts to NAV and with dividend yields as high as 13% (AEWU then). At that time Unit Trust Property Funds we’re locking their investors in, but Property Investment Trusts don’t do that and the wave of selling just means they go to exceptionally wide discounts to NAV to give wonderful buy opportunities. You can see the sometimes big 1 year gains using the above link.
On that dip I bought AEWU, AIRE, EPIC (they pay their dividend monthly and a further dividend increase likely soon) SERE (in Europe Commercial Property sector and now paying big specials on top of regular dividend) SREI and RGL. All of them and others are still worth checking out.
“Morning dump into the toilet of trading”
Made me laugh or rather LOL as the kids say. Keep up the great work Mr C!
Mr C you have “trumped” yesterday!