Small Cap Value Report (Fri 14 June 2024) - CRST/BWY, MPE, GPH

Good morning from Paul & Graham (Paul is still travelling, we may hear from him later!).
Ok, we're all done for now!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Summaries
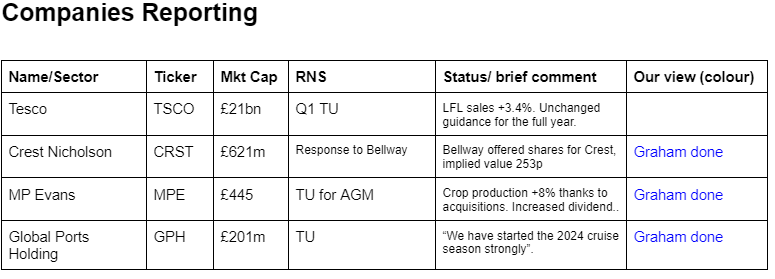
Crest Nicholson Holdings (LON:CRST) - up 10% to 233.5p (£600m) - Response to announcement by Bellway - Graham - GREEN
A day after the latest profit warning from Crest, we learn Bellway has been interested in picking this one up. The indicated prices do strike me as opportunistic, and I agree with Crest’s decision to reject them. However, bid interest does give me the confidence to nudge up my stance on this to be outright positive.
M P Evans (LON:MPE) - up 0.6% to 845p (£448m) - Trading Statement - Graham - AMBER/GREEN
A pleasant AGM trading update that reiterates some news while also providing the latest information on fruit processing, palm oil production and sales prices. I view this as a decent agricultural stock. With minority interests bought out and an ongoing share buyback, there are reasonable prospects for EPS growth.
Global Ports Holding (LON:GPH) - down 8% to 241p (£184m) - Trading Statement and Delisting - Graham - AMBER/RED
The majority shareholder wishes to take this one private, and might offer three dollars per share. This one seems very complicated and risky to my eyes, and with a delisting likely to be imminent, I would give it a miss.
Graham's Section
Crest Nicholson Holdings (LON:CRST)
Up 10% to 233.5p (£600m) - Response to announcement by Bellway - Graham - GREEN
It’s funny how quickly your views in the market can be proven right or wrong - sometimes on the same day!
We covered Crest Nicholson’s latest profit warning in yesterday’s report.
Last night at 5.45pm, in response to press speculation, Bellway (LON:BWY) announced that it had made a (non-binding) offer for Crest Nicholson on 7th May.
Key features of the offer:
An all-share offer, BWY shares for CRST shares.
CRST shareholders would hold 17.1% of the enlarged group.
Implied value of 253p per CRST share, a 30% premium to CRST share price at the time.
Rationale from Bellway:
The Board of Bellway believes that there is compelling strategic and financial rationale for a combination of Bellway and Crest Nicholson which would bring together the strength of each business with complementary brands to reinforce Bellway's position as a leading UK housebuilder, while enabling Crest Nicholson shareholders to benefit from the scale of the combined business, a reduced risk profile, lower indebtedness and an enhanced landbank to capitalise on the long-term structural growth opportunity in the UK housing market. In addition, the Board of Bellway believes a combination would deliver significant operational synergies and support sustainable shareholder returns through the cycle.
This morning we have a response from Crest Nicholson.
They point out that based on last night’s close, the implied premium is only 18.8%.
Their view: the offer “significantly undervalued” Crest.
Additionally, they reveal a previous offer was made in April, with a slightly worse exchange rate between BWY and CRST shares. This was thought to “fundamentally” undervalue Crest.
They provide a brief insight into their thinking:
As outlined in its half year results on 13 June 2024 for the period ended 30 April 2024, Crest Nicholson remains confident in its standalone prospects, in particular given conclusion of the review of provisions for completed development sites supported by external consultants, its highly attractive land portfolio and the new leadership of Martyn Clark.
Graham’s view
In yesterday’s analysis, we looked at possible catalysts and reasons that the Crest Nicholson share price might improve towards its tangible NAV (£774m, or 301p per share). Takeover activity was mentioned - but of course it’s not easy to predict the timing of deals if you don’t have insider knowledge.
If I was a shareholder or Board member of Crest, I would be holding out for 301p+. Why sell the assets to Bellway at a discount to TNAV? Bellway is perfectly placed to extract synergies, develop the landbank and to generate at least TNAV from Crest’s assets, using its economies of scale (it’s about four times bigger than Crest). It should be willing to pay a fair price for this.
Therefore, I agree with the rejection of Bellway’s recent offers.
Crest is adamant that it has finished the review of provisions needed for prior work, and about the attractiveness of its land portfolio. That being the case, there is no reason for them to sell up at a discount.
And from Bellway’s point of view, surely a price around NAV would still be a profitable deal for it?
I’m going to nudge up my stance on this from AMBER/GREEN to GREEN. My reasoning is that we now have external validation of the attractiveness of Crest’s assets to potential acquirers, although of course it remains to be seen whether or not Bellway will pay full price for them. But the bid interest does allow me to look past recent difficulties and take a positive stance here.
M P Evans (LON:MPE)
Up 0.6% to 845p (£448m) - Trading Statement - Graham - AMBER/GREEN
We occasionally mention this one, e.g. Paul looked at it back in September. It produces palm oil in Indonesia, so it’s not your typical domestic stock!
Key points from today’s AGM update:
Fruit processed up 8% to 631,400 tonnes.
Rapid growth “has abated to some degree in recent months”.
Growth has been supported by acquisitions: “whilst yield from these estates remains relatively low, significant progress is being made to improve agronomic standards”.
MPE operates six palm-oil mills, with total palm oil production up 10% in the first five months of the year.
Prices: the average crude palm oil price was down slightly on last year ($997 vs. $1,001).
Acquisition: MPE has bought out the minority stakes in most of its Indonesian subsidiaries, for a total cost of $14m. I think these stakes were all held by one individual. It should be good news but I’d be interested to know more about the backstory - why did MP Evans feel that they needed to have a local partner originally and why do they not need a local partner now?
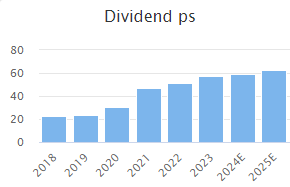
Dividend: 45p total dividend for 2023 (vs. 42.5p for the previous year).
Graham’s view
I have viewed this as a decent agricultural stock - it has been around for a long time, generating profits and rising dividends.
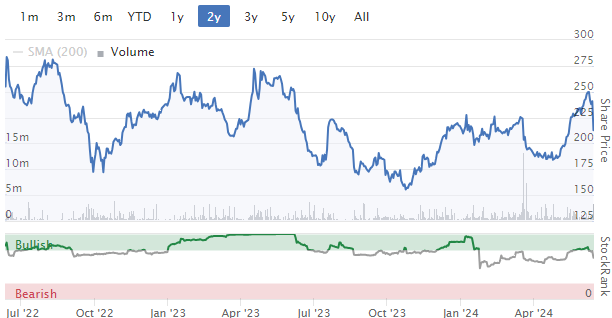
The most recent balance sheet value was $467m (excluding intangibles and minority shareholders), or £367m, and the market cap does currently trade at a premium to that.
But something that caught my eye here was the company’s decision to start buying back its shares. It originally announced this in June 2022.
In 2022, it spent nearly $5m on buybacks.
In 2023, it spent nearly $10m on buybacks.
In March 2024, it announced the extension of its existing buyback programme, saying that it now had a GBP £2m budget to buy shares until June 2024. It said:
The Board maintains the view that its overall business and its assets are currently undervalued, with the current enterprise value being below the independent valuation of its assets.
The Group's robust balance sheet continues to provide the opportunity to repurchase shares at advantageous levels that will be earnings enhancing.
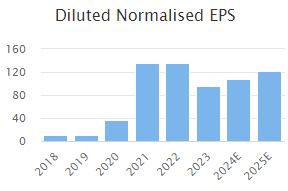
Here are the latest valuation metrics. There's a nice yield even before considering that funds are being returned to shareholders through buybacks, too:
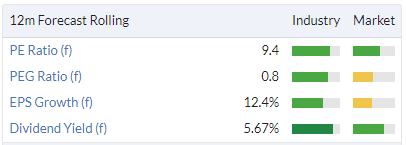
As usual, I get interested when I see a “value” stock buying back its own shares - because the long-run effects on earnings per share can be very nice indeed.
Of course in the short-term, the crude palm oil price is more important. But I think that in the long-run, this could continue to be a nice stock to hold.
Global Ports Holding (LON:GPH)
Down 8% to 241p (£184m) - Trading Statement and Delisting - Graham - AMBER/RED
Strange goings on here today at GPH, “the world’s largest independent cruise port operator”.
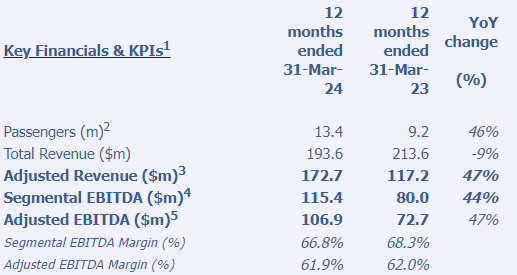
First thing this morning we had a trading update. Here’s an excerpt from the table, with seemingly good progress:
The Co-Founder, CEO and Chairman says:
"The 2024 Reporting Period was one of significant achievement for Global Ports Holding. We successfully expanded our cruise port network, completed our largest-ever investment project, and increased our shareholding at a number of key ports. In addition, we strengthened our balance sheet through a successful investment-grade-rated issuance of secured private placement notes and extended the concession length at a number of ports.
We have started the 2024 cruise season strongly and we are well positioned to be a key enabler and beneficiary of the cruise industry's continued growth and success in the years ahead."
It should be noted that this company is carrying significant net debt: $674m (excluding leases) as of March 2024. This is much larger than the number shown for September 2023 ($561m), when Paul covered it last.
Bond issuance: the company has been active in the debt markets and issued two bonds for a total $145m that are (just) investment grade, with a rating of BBB-. They are long-term, amortising over 21 and 15 years respectively.
Dilution: the majority shareholder of GPH increased its stake with an additional 5.1 million shares, “in partial satisfaction of the debt owed”. This majority shareholder has a 59% holding in GPH, according to the StockReport.
The trading statement did not seem overly dramatic, but it was followed up around 11:30am with the following:
GIH as the controlling shareholder is convinced of the merits of moving the business into private ownership and intends to seek delisting of the Company and taking it private. Although as a standard listed company delisting can be implemented through a decision by the board of directors of the Company and neither a shareholder vote nor a squeeze-out is required, GIH is considering a possible cash offer of US$3.00 per share (the "Offer Price"), to be implemented by GIH's wholly owned subsidiary, Global Ports Holding B.V. ("Bidco"), for the issued and to be issued share capital of the Company not already owned by Bidco, as a liquidity opportunity in conjunction with the delisting. GIH and Bidco are in discussions with potential providers of funding. There can be no certainty that an offer will be made.
Three dollars per share equates to about 236p, and as I type this the share price of GPH is still marginally above this level. But there is no certainty that this offer will even be made! And if not, then shareholders will be left holding a private company.
Graham’s view
I’m going to leave Paul’s AMBER/RED stance on this one unchanged. This is really a Turkish company to my eyes, not a domestic stock, and with a majority shareholder who is no longer interested in the public listing.
Of course that could very well mean that the shares are a bargain, and the majority shareholder no longer wishes to share the company’s success with minority investors. But at the end of the day, it’s the majority shareholder who decides the price (if any) they wish to pay to buy the others out.
Too complicated for me, and with some major risk factors (huge debts, the presence of the majority shareholder, and foreign risk). So I agree that this should be treated with great caution.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

77 comments
Paul, Thanks for your very instructive 'Loom' webinars ,a marvelous educational tool and professionally used. From the dialogue i got the impression one could actually access the Phil Hanson spread sheet, if so , where can i link to it. Extremely useful & appreciate both of you spending private time to create and also your Daily reports.
Try this Funderstruck https://docs.google.com/spread...
And a Happy Father's Day to all relevant Stockopersons. Got TWO cups of coffee in bed today it's a bonanza.
Greencore (LON:GNC) product recall due to e.coli hope this doesn’t impact my or fellow holders’ holdings too much on Monday. I would think they are insured for this. No RNS yet.
“Some sandwiches, wraps and salads have been recalled from major supermarkets following an E.coli outbreak .
Greencore Group, which makes these products for Aldi , Asda , Sainsbury's and other shops, says there may have been possible contamination with E. coli. Food Standards Agency has today issued an alert to inform consumers of the recall of the items, most of which are pre-packed sandwiches containing salad leaves.”
https://apple.news/AdwP9DWXLSO...
James Cropper (LON:CRPR) Bank covenants amended until end of the year as Paul punted in a previous SCVR.Could be a great new Labour policy green energy, homegrown play if the company gets its act together and some green investment is pulled forward!Also no doubt that part of the business could well trade on a generous p/e or p/s even.Y/e results due in July.
James Cropper (LON:CRPR) very much has all its eggs in the hydrogen basket, in terms of green/renewal energy. I don't know enough about hydrogen to make an informed opinion, but from what I have read in the mass media, it has lost a bit of momentum after a few years of optimism?
I have CRPR on my watchlist as I think it is a cheaply valued, except for the bank debt and covenant risk, which today has been mitigated in the short term.
Don't think the Packaging side of the business is out of the woods yet, so my expectations is not a very optimistic outlook in July's results, but potentially some good noises about progress made, enquiries/new business pipeline improving.
Some unusual price action over at Renold (LON:RNO) this afternoon. The price has dropped 8% in the past half an hour. This appears from what I can see to be based on no news, however whenever something drops around 2pm I always assume it is in some way linked to something happening over the pond in the US. Is anyone aware of any data or earnings releases to drive this kind of swift decline?
A lot of small and mid caps getting hit hard. Looks to me like the FOMO that was starting to propel valuations to more reasonable levels has gone into reverse and we have retail pulling money again . Who knows on what fears!
UK 10 year almost back down to 4% again so you’d expect smaller shares to rally rather than fall but quite the opposite is happening.
I have held RNO for a while- seems from time to time these sharp movements occur, then price recovers. I am not aware of any news out.
Renold (LON:RNO) I always assume a large trade has gone through and that we will see the print later.
There's good volume going through with a rejection to the downside implying there is support here.
More importantly how do we feel about the valuation at this price? I still think it offers value, less than before but with positive trading updates i feel the wind is in its sails and i like the small exposure it has to defences contracts.
Renold (LON:RNO) is up sharply over the past couple of months. There are a lot of people who I suspect are sitting on significant profits. I decided to cash in some of mine in the middle of last week, still holding half I've had since 2020. I suspect I'm not alone. I doubt it's any more than a pull back. I still expect to see further progress over the next year or two, as the pension deficit is reduced further and we should start dividends restarting.
Hi,
Does anyone know why (LON:AT.) has fallen over 20% in the past month and today ?
Thanks
I don't follow Ashtead Technology Holdings (LON:AT.) but from what I understand, they provide subsea equipment and expertise to the oil & gas industry, so (at least in the UK) their revenues are based upon the investments made in the North Sea. For some people, the view is that the level of government support / taxation might limit some companies going ahead with some of the potential projects. It has also had a pretty strong run for a while now as well.. no ?
Ashtead Technology Holdings (LON:AT.) have been flying high and only rated on Stocko as 51, but popular on SCVR and in a very good space.
Market seems to be correcting - maybe no cuts to interest rates
or because voting papers got delivered today. Of course fossil fuels and the support industries will do very well - lol. I'm buying candles and extra quilts.
MPE If I'm not mistaken, I heard some time ago that MPE commissioned its own valuation report on its shares. So the buybacks are less likely to be haphazard institutional imperative, but a belief that the shares are actually undervalued.
If I understand it correctly the Crest NAV is based on cost or permanently held properties' revaluations. There is nothing included for the future profits to be made by building on the sites held for development -which is understandable since those are not easily defined Nonetheless in a takeover situation I suggest these have a value in excess of cost (unless land prices have fallen ) to reflect both the savings to the acquirer in acquiring a ready land pool and also say a reasonable estimate of future profits to be made from the land bank, discounted for risk and time. This would obviously be an estimate but still is in all probability a higher value than NAV could be justified.
Hello Star, as the NAV is based on financial statements, then it would flow from the valuation or cost (depending on which accounting model is used) of properties and land in their current condition. A buyer could therefore take a very different view to NAV to say nothing of any perceived synergies (normally cost savings) of combining the two businesses.
Card Factory (LON:CARD) down at 89p a true sign of a stock market that has failed
Their current share price is absurd. Singers report this week target price 145p; and even the doomsayer's at UBS upgraded to 116p this week (from 107p). TTM PE now 6.1 - yes SIX POINT 1 for a company showing demonstrable revenue and earnings growth and with a current 5% dividend yield. Absolutely ridiculous.
Their EV/EBITDA is now 3.58! The PCPI Index for EV/EBITDA multiple in private equity deals is currently 9.4 - go figure for a public company!?
If we applied the same multiple Card would be priced at over £3!
We all know Teleios are selling - but even so this is beyond a joke.
100% sure private equity will take this out for an absolute song in due course.....
As an aside I do hope the Exec team outline a demonstrable plan at the AGM next week....
Hi Tamos
Thank you for alerting me to this price for Card Factory (LON:CARD) . I had a biggish holding before and sold out on results day. Buying back in today! This time at a substantially lower SP
Hurrah
Guessing you're a holder of Card Factory (LON:CARD), Tamos?
Please, tell us why you think the stock market has failed, using Card Factory as an example... don't leave us on a cliff-edge with a statement like that!
Card Factory (LON:CARD) Have put this out there out a couple of times and not got a response - will try one more time. Card has a huge amount (£80 million) of trade and other payables on the balance sheet which makes the bs significantly negative. Does anyone have an explanation for these? Shares are univestible for me until I understand this - everything else looks good.
Just seen this question as I was travelling. There does not seem to be any issue with the size of the payables at Card Factory (LON:CARD) . If you go to the annual report you can see in the notes a breakdown of the payables. The significant amounts are accrued payables for wages which represents about one month of their wages bill - what you might expect in a company paying monthly. The payables are also at around a month, quite usual, and the other items like VAT and other taxes are also at unremarkable levels. Does this address your concerns?
Really appreciate the response - I hadn't looked at the annual report. I still don't think it is great though - they make the cash/borrowing situation appear significantly better than it is - they owe £80 million in the next 12 months, some of it presumably much sooner than that v PBT of £65 million. It's not clear how much of that £80 million has gone through the P&L already (more would be better). Most companies I look at have current assets > current liabilities. In CARD's case it is heavily the other way so if they stopped trading tomorrow, they would have to find cash equivalent to pretty much a whole year's profits. I fully admit that I am on the edge of my accounting expertise here but I given I don't understand I won't be investing. Good luck to those how do!
This post will probably get hammered but I don’t share Graham’s assumptions about buybacks, and especially so this assumption which Graham uses a lot, to promote the M P Evans (LON:MPE) buybacks today:-
“Here are the latest valuation metrics. There's a nice yield even before considering that funds are being returned to shareholders through buybacks, too:”
Funds are not returned to shareholders via buybacks unless the share price subsequently goes higher, and even then it might have gone higher anyway.. Dividends do give investors real money. Buybacks often don’t. Buybacks increase the eps (good for Directors if their bonus payments are based on eps) but there’s nothing to prevent the share price falling and PE ratio also falling, while eps increases.
And for a share like M P Evans (LON:MPE) the future palm oil price is far more likely to affect the share price performance than these buybacks will.
Interesting thoughts Ken. When a company buys back its shares, then it is using its own money to buy something off shareholders - I'm not sure how it can be argued that money is not being transferred from the company to shareholders? Granted that most shareholders aren't receiving anything, but shareholders who are selling are getting paid in full. Meanwhile, the shareholders who don't sell get the long-term benefit of a higher % ownership in the business.
I do agree that the palm oil price is more important to MPE's performance in the short-run than the share count. MPE recognise that themselves, and they don't make awards based on short-term EPS. From their most recent remuneration report:
"In a very long-term business like that of M.P. Evans, three-year cycles would not necessarily reflect the Group’s investment and development profile, and vesting could be heavily influenced by macro-factors such as commodity prices"
So presume they don’t see any see growth opportunities. They could reduce debt, or just have a nice cash pile for any opportunities that arise or diversify outside Indonesia, improve sustainability etc. So enhancing employees bonus it is then.
Apologies Graham - had not read the article, they have been doing some of that stuff. Other than reducing the one country political geo risk. But they have to stick with their knitting and not venture outside their expertise/moat.
For some reason this was popular back in the day - probably covid and ukraine - less food supplies but hold for a reason, unfortunately did not keep a note.
Lesson for all - keep a note WHY especially if want to top up, average down or just get the hell out.
One Question is if I sold today would I go back in - palm oil its a No from me. Wako Joko Indonesia does not help.
Plus of course it don't not need to be a sell, but reduce exposure if still like the story. Story's change. Don't fall in love. (message to self).
Thanks for that interesting reply Graham.
On your key point that you’re not sure how it can be argued that money is not being returned to shareholders, you’ve hit on a key negative about buybacks in saying that shareholders who are selling are getting paid in full. That’s true but that’s another thing with buybacks in that they reward those wanting to sell as they’ve got a willing buyer for their shares. I sometimes use the news of a big buyback as a good sell oppprtunity to take advantage of this.
And don’t buybacks in rewarding those who want to sell increase the chances of heavier selling than there would be otherwise, and so the risks of share price falling too?
What matters for investors that stay invested is the effect of the buybacks for them, and imo too often it not the “reward” or “return of money to shareholders” that Directors and commentators claim they are.
To give just 2 of many such examples from shares I held at the time:-
1. Stuart Rose repeatedly claimed that he had rewarded Marks and Spencer (LON:MKS) shareholders with a £2 billion buyback starting at £4. The share price has never again reached that price. Those getting out near to £4 were the ones rewarded and not those who stuck with their holding g as the falls were relentless.
2 Whitbread (LON:WTB) decided to return almost the entire proceeds of their sale of Costa Coffee to Coca Cola (around £2 billion from memory) to their shareholders via buybacks. As with Marks, the share price fell and has never again reached the buyback prices. And again those selling were the ones most rewarded.
So I much prefer special dividends (now the standard for Mining Companies like Rio Tinto (LON:RIO) after their share prices fell so far after £multi billion buybacks, so they quietly ditched them) to buybacks.
But I also agree that some buybacks are effective if undertaken at bargain share prices. Next (LON:NXT) is the classic example of successful buybacks, and they’ve halved the share count. It’s the sometimes spurious claims about them that are so questionable, chief of which is the supposed reward to shareholders when the share never again reaches the buyback price.
lbtw…I sold my long term holding in Marks and Spencer (LON:MKS) at a significant loss a long time after Stuart Rose went for that £2 billion one, but bought back when the share price fell under £1…..and this time it looks like their recovery is for real. Their food stores are buzzing these days.
I also sold Whitbread (LON:WTB) when they wasted their Costa sale proceeds and haven’t held since.
Hi Graham you say re: buybacks that "shareholders who are selling are getting paid in full" but surely that happens only if the price has actually adjusted to take account of the reduced share count. The price may not adjust.
Hi Ken
I don’t have a view on M P Evans (LON:MPE) but I do have a view on share buybacks.
Generally speaking I don’t like them and would much rather have an enhanced dividend. I especially don’t like them when a company is carrying debt. And then there is the not so small matter of whether the company are buying shares at a good price (easier to assess for investment trusts with marked to market pricing) - most of them are simply pound cost averaging, so maybe a good price, maybe not. There is also the issue of whether the shares bought back will be cancelled or held in treasury and if the latter, for what purpose?
With an enhanced dividend shareholders get to decide the best use of the cash which may or may not be to reinvest the dividends in the same company. But surely that largely depends on whether the company represents a compelling investment opportunity.
I appreciate this is a minority view especially among city types but hey, differences of opinion is what makes a market.
Cheers
Simon
I agree that special dividends are a more effective use of company funds to reward shareholders. Many private investors hold them tax free in ISA & SIPPS and often reinvest their dividends. Buybacks in my view trigger more selling, particularly where funds are repaying redemptions and can lead to unnecessary share price erosion.
Apple (NSQ:AAPL) do a lot of buybacks. Their shares are at a near all time high.
l think you will find most of the largest US stocks have done large buybacks recently and their shares have gone up. They pay no or low dividends.
Dividends need to be taken out of the equation. Chick feed.
It’s Saturday the 15th and Legal & General (LON:LGEN) has put out an RNS with information which is relevant to opinion on buy backs. It intends to buy back 10% of its issued shares. I hold Legal and General and had I known this in the first week of June I would have sold all my holding at circa 250 pence. I might have bought back in at 225 pence just one week later in that 10% dip and this is where the buy back would have become a pay-back for a PI like myself. As it is I will just have to stay long and reap the reduced dividends rather than a special dividend seeing as the company must have money to spare. This is not a rare example but is food for thought.
Re: buybacks. Added to which, buybacks can be opaque. The shares may not be cancelled but "held in Treasury" and then wheeled out at a future date and used again. Buybacks only benefit shareholders if the share price adjusts to the reduced number of shares in circulation. This may take a long time, or not happen at all. It's all the rage at the moment, but really should only be used when a company is really sure that the existing shares price is seriously undervaluing the stock. Given that everybody is doing it now, that can hardly be the case! Give me the cash thanks.
Raspberry PI Holdings (LON:RPI) currently up 20% on first trading day for ordinary retail investors post ipo.
Peel Hunt (LON:PEEL) The boss of broker Peel Hunt said a ‘switch has been flicked’ in the City after a bumper float this week lifted hopes of a recovery for London listings.
Steven Fine said that there were ‘tentative signs... that a recovery is under way.I think a switch has been flicked in terms of sentiment,’ he told the Financial Times.
Steven Fine was slagging off the UK stock market 2 years ago; so now he has a change of heart. Bully for him. Also, one swallow does not make a summer.
People are allowed to change their minds over time. 2 years is a sufficient amount of time?
If I didn't have a "change of heart" over time about the shares I track and invest in, I'd never sell after buying, nor vice versa.
I'm always puzzled why people criticise others that change their opinions. Is the expectation that one sticks to an opinion (note that I didn't say "promise") for their rest of their lives?
RPI I'm a complete fanboy of Pi's, so take what I say with a pinch of salt. I was asleep at the wheel, so didn't subscribe to the flotation. I have been thinking of buying a small holding, but boy have the shares gotten off to a great start. Maybe I'll consider buying at some kind of pullback.
It's early days for the floatation of course, but at least it provides some light into a market that is seems boring. We have here a genuine tech company making actual money, with genuine growth prospects, not some jam tomorrow AIM crud.
Hello Graham, I was wondering if you were going to look at the M P Evans (LON:MPE) trading update. I used to hold. The only metric it doesn’t pass on my screen is Piotroski F-factor >= 6, but at 4 it is still something I’d look at again. I’d be glad to hear your thoughts as I don’t have balance sheet analysis skills; I rely on the Stocko metrics.
Hi Indie, MPE is covered now! Cheers. G
Thank you, Graham, great stuff as ever!
Palace Capital (LON:PCA) Do any other shareholders have a view on the tender at 250p for 23% of one's holding. Latest NAV was 262p. Post the tender my figures suggest only a 1p improvement in NAV- though my calculations may be wrong. Net assets are £97.8m less the tender £21.67 m divided by reduced share capital of 28.892m. Corrections to above appreciated as I am uncertain whether to tender or not.
Given the 7% discount to the tender price I will tender 50% and buy 23% of them now at market price. I am overweight in PCA so if I get more than 23% this would slightly reduce my weighting. The allocation will I assume depend on what Peter Gyllenhammar AB do with their 13.03% stake.
Is the tender offer live ? Haven’t received anything official yet ?
The tender offer should be live now, but it'll probably take time to filter through to corporate actions in the various stockbrokers. It closes on the 9th July, so plenty of time for this to happen, and the money won't be made available until after that date.
There are always dangers that the offer will not go ahead, but it seems unlikely. In which case it's a fairly decent way to reduce the cost of holding, it is fairly close to a win/win situation at the moment. I guess the share price could drop after the tender, but you could always rebuy any shares you've tendered (if you're in it for the long haul).
Harworth (LON:HWG)
Planning permission secured for the development of a 1.5 million square feet brownfield site at a major rail intersection. Harworth (LON:HWG) is another example of a UK small cap with competent management and a sound balance sheet that continues to do what it says on the tin, but as usual most UK pension funds and institutions are disinterested.
It has no funding requirements with the most recent LTV 8.4% and NAV in excess of 200p versus a share price of 140p or thereabouts. It is held family portfolios and been added to around 110p.
"Harworth Group plc, a leading regenerator of land and property for sustainable development and investment, announces that it has secured a resolution to grant planning permission1 from North Yorkshire Council's Strategic Planning Committee for the development of a major rail-connected industrial and logistics hub at its 185 acre Gascoigne Interchange site in Leeds.
The approved plans will see the development of up to 1.5 million sq. ft. of industrial and logistics space, in line with the Group's strategy to increase its direct development of industrial and logistics space from its extensive landbank, and has the potential to deliver up to £190 million gross development value (GDV). The proposal is the delivery of seven units, ranging from 57,000 sq. ft. to 1.0 million sq. ft., all built to Grade A specification, with Harworth expecting to start on site in 2025.
The brownfield site is one of Harworth's next-generation of development sites and is situated in Selby, to the east of Leeds and adjacent to Sherburn Industrial Estate. It is one of the most strategically located, rail-connected sites in the region, enabling future occupiers to utilise the existing main line rail connection from the site for a wide variety of uses, including low carbon freight movement.
The site, which is accessed via Junction 42 of the A1(M), has an extensive collection of rail sidings on either side of Network Rail's Leeds to Hull main line route, with current operational connections into the northern and southern plots on the site.
The rail access to the north of the site offers scope to create a dedicated railhead serving the buildings on site, with the ability to handle containers, bulk commodities or next-generation express freight services, and puts most of the UK within three hours of the site.
The plots to the south of the site benefit from 1,200 metres of frontage onto the main line with connections at either end capable of accommodating a major intermodal terminal for on-site and off-site customers."
Yes the land developers could do well if there really is a push to get more homes built under Labour - Henry Boot (LON:BOOT) is another one that might be worth considering.
Georgia Capital
Been thinking about this .
On reflection a heads you win tails you win play .
If the country moves towards Europe which was the previous basis for growth etc then that was viewed positively
However if the “Russian law “ issue goes ahead then even with a pro Russian stance there would be inward flows of wealth boosting the economy .
My current thinking is both scenarios are actually ok for Georgia capital.
I put 1/3 of the money back in this morning that I sold a few weeks ago .
This was a full holding for me that I reduced to half over a week or so as the situation evolved , Will start to go back in in the next period on the realisation that there is upside whichever the outcome .
Georgia Capital (LON:CGEO)
Bank of Georgia (LON:BGEO) If the Russian law goes ahead…
Then delisting issues will start to emerge…..
All the best
There is a lot of rubbish written about this Russian Law. It isn’t a Russian Law at all - there are a number of laws in force in various countries that are not dissimilar. The “fear” is that because Russia abused the same law to crush dissident voices the same could be used in Georgia given the Venn diagram cross over. Doing so would breach democratic rights which is what the EU is fearful over but there is no actual suggestion it will be used in a such a way. The Georgian Dream met the U.S. to discuss this and how they could tighten ties with the U.S. rather than weaken them.
The law applies to foreign funding in NGOs not banks listed on a foreign stock exchanges so comments about delisting issues if the law is passed are misleading in my view.
People are also forgetting that Georgia parliament is actually democratically elected.
I do know very well the law as I have made the effort to read about it when things started getting out of hand in Georgia.
I am certainly not misleading anyone. We have different opinions that’s all and you must have figured it by now that I do read and respect your comments.
If the law passes and only on ESG concerns there will be pressure on any European funds (including the UK) to exit.
All the best
Love you two guys keep it nice.
Do we hold now, or do we Go know. As currently don't hold - this is becoming speculative high risk etc.
hi Yiannos - yes, we just have different opinions on this one. I think your de-listing comments are a bit of an over reach that's all.
The law itself isn't going to cause any country specific sanctions and whether it passes is actually not really in doubt. It clearly will. The elections in 5 months time will determine whether it stays.
It isn't a "Russian" law - it has been painted that way and latched onto by the media. There is concern about its potential for abuse so that's a risk we have to watch.
Bank of Georgia (LON:BGEO) now also has Armeria bank. That combined with its own funds really makes this a different risk position than investors on here make out.
There are alarmist comments about Russia invading (no sign of that - Putin does not have the capacity to fight war on two fronts) - might be different if he wins in Ukraine but we have to hope that isn't the case else most of Europe may become un-investable for fear of cross border war.
There is fear that Georgia is going Russian - also no sign of that. Current ruling party have said they want better relations with the US not worse.
There is fear of nationalisation - why? This is a democratic country - it holds free elections and operates a capitalist economy. That sort of talk (not you Yiannos) is alarmist in my view and appears quite groundless.
Then the fear of sanctions - if there are they will be directed at individuals not companies or the country itself.
So there are geo-political risks, including unrest for sure, - you are paying just 2.5* PER because of that. There will be likely volatility leading up to elections too but you can pay a much much higher risk premium for other things on UK and US stock markets but some investors don't seem to realise or appreciate that and latch onto the emotion rather than the risk/reward profile.
I have no issues with people preferring to invest elsewhere but for the last 10 years plus I've heard the same comments as the below trotted out fairly continuously. In that time the stock has paid out over half its market cap in dividends and risen 300% even after the more recent falls. Its long term return has trounced most of the market.
There could well be an edict from Putin, as was Polymetal International wiped out.
I think that you are ignoring several possible outcomes here.
What happens if after the law comes into affect and there is a general uprising by the population, who it would appear dont want the law and the Russians use this as opportunity to occupy the rest of the country. Remember they already have troops occupying 20% of Georgia. Will companies based in Georgia but listed in the West be nationalised? Will your investment be wiped out?
The Georgian economy is booming because it is being used to by pass EU/Western sanctions on Russia. At the moment the EU is turning a blind eye to this in the hope that Georgia will become an EU member. I cant imagine that this will continue if demonstrations are brutally quashed especially if Russian forces are involved. Sanctions would be imposed and the economy will shrink. There would be inflows of wealth to a very selected members of the population not to the country as a whole.
Why would you want to add all this extra risk to an investment?
Mmmm
I initially bought Georgia capital and bank of Georgia after the Ukraine invasion on the basis Putin hadn’t invaded Georgia
The shares 3-4 bagged following the over reaction of the market .
This feels like market over reaction and most countries seem to have a similar law to the “Russian law” .
Think I’ll let this playout and follow my instincts and go against the market sentiment .
It seems a logical law to have in place to me. Western governments are against it as they don't want to be exposed as the ones funding the NGOs and stirring up trouble, while publicly blaming Russia for 'interference'.
Agree af20001. I’m also not entirely clear on how the ‘Russian Law’ differs from the US Foreign Agents Registration Act.
https://crsreports.congress.go...
But the response of the West re further sanctions on Georgia is a clear risk for investors, as a shareholder in Evraz, I’ll personally be steering clear of Bank of Georgia (LON:BGEO) & Georgia Capital (LON:CGEO) . Good luck to holders though.
Evraz (LON:EVR) AGM in London next week.
Bank of Georgia (LON:BGEO) and Georgia Capital (LON:CGEO) need surely to fall further before the investment risk here is justified? (I held)
Actually I take that back for Georgia Capital (LON:CGEO) which seems now to be lurking in the mud at the bottom of the Ocean and worthy of further investigation.
I agree with the sentiment. However, the Georgian economy was registering 6% growth well before Russian invasion of Ukraine and various sanctions busting strategies, only some of which were managed through Georgia and the Georgian banking system. Some of the largest sanctions evaders are in NATO ; Turkey for one.
I mean yes - Nat West could never get nationalised right??? Oh hang on - we don’t need to go that far back……….
Georgia is booming because of tourism and particularly the Chinese - not avoiding sanctions.
I don’t mean to be rude but you seem to be playing out every worst possible scenario and applying it as probable in this case! I doubt you do that to the rest of your portfolio where you probably have different but equally probable risks.
I would urge some caution regarding anything in Georgia right now. There is simply no way, any of us can understand the complexities of Georgian politics sitting where we do. I am not long back from Georgia and our (wife and I) Georgian friends are extremely nervous of the future. They don't really understand the full extent of Russian meddling in their political system and one of them works in politics, two in business and the other teaches at the University.
One thing to bear in mind is that 100,000 young, mostly tech sector, Russians left Russia for Georgia in 2022 to avoid the draft they thought was coming (but never did for their middle class educated Moscow-centric demographic). The data I have access to, based on official Georgian Government data, shows that about 30,000 Russians have left Georgia last year. They have not successfully integrated into Georgian society where many regard them with deep suspicion and some envy as they have been able to out compete locals for scarce housing resources. Other Georgians regard them as a fifth column. To be clear, the Russians I have spoken to support Russia's invasion of Ukraine ... they just don't want to participate.
Apart from the obvious political stress and unknown outcome; the 30,000 departees represents GDP that has just left the country. A lot of them had retail and business accounts in the Georgian banking system.
I am not pretending to know the future. I have no clue what will happen, but my lack of insight is why Bank of Georgia (LON:BGEO) is not an investment for me. I wish you luck with your investment.
Actually I partly agree on Bank of Georgia
But I’m less convinced on Georgia capital which has a huge value in non Bank of Georgia holding , This alone I think “worth” twice the market cap (700 million by memory)
This is hospitals / infrastructure etc so valid assets and businesses .
Notwithstanding the doomsday scenario I just don’t see too much downside on Georgia capital and pretty much there is a huge amount of bad news already baked into the share price .
These infrastructure assets will not be affected much by any Russian influx / outflux let alone a Russian law and civil unrest so it is sentiment that has rocked the share price
The market is “voting” against Georgia Capital on sentiment and fear .
But the “weight” of the business assets are largely unchanged in the non Bank of Georgia assets .
Gets all the safe cash out of Russia. Gets the silk route from China to the EU. EU wants it in its haven.
DYOR.
My morning smallcap tweet: A dog with two fails
REGTECH OPEN PROJECT (LON:RTOP) Aptamer (LON:APTA) CPPGroup (LON:CPP) Global Ports Holding (LON:GPH) Keywords Studios (LON:KWS)
◄RegTech Open Project (RTOP)► to the surprise of the gullible everywhere, Zamboni stalling again on payment. $1.5m won't be paid today. [SP=4.5 Cap=3m]
◄Aptamer (APTA)► partnership with Microsaic Systems for Optimer-enabled water monitoring. [SP=0.72 Cap=3m]
◄CPP (CPP)► sells legacy operations in Italy for €0.5m. [SP=169.16 Cap=15m]
◄Global Ports Holding (GPH)► guides FY-Mar rev down 9% and adj EBITDA up 47%. CO has started the 2024 cruise season strongly. [SP=263 Cap=201m]
◄Keywords Studios (KWS)► PUSU offer deadline extended to 28 June. [SP=2149.97 Cap=1716m]
◄Notes► SP & cap are 20m delayed
Friday the thirteenth?
Shorelee knot?!?
Paul has never escaped the eagle eye;-)
As it’s my 60th birthday i am pretty confident that it is the 14th today….unless i had too much pre birthday wine last night.
Happy birthday!
Humph, youngster. On my 60th birthday I stood on the Great Wall of China. All the photos were black and white 8-(
Take over offer for Crest Nicholson Holdings (LON:CRST) from Bellway (LON:BWY) 253p share rejected by board months ago after yesterday fall people in know would of been buying, offer should of been disclosed.