Small Cap Value Report (Fri 15 Dec 2017) - UCG, LUCE, FUL, BOTB, CVR

Good morning!
Apologies for the break in service over the past couple of days.
Best,
Graham
(Please note that I hold shares in UCG)
United Carpets (LON:UCG)
- Share price: 8.6p (unch.)
- No.of shares: 81.4 million
- Market cap: £7 million
I thought I might briefly mention this chain of carpet stores as it's something I've held a position in for a while, and it might be relevant to those of you interested in Carpetright (LON:CPR), SCS (LON:SCS) and others in this sector.
The market cap is very small here, only £7 million, and it's a tiny company, so I'm certainly not suggesting that anybody else should buy shares in it.
Fortunately, the like-for-like revenue performance remained stubbornly resilient, up 2.9%. This is despite overall revenues falling, as the mix of stores became a little bit more heavily weighted towards franchisees rather than corporate-owned stores, compared to a year ago.
It earns a higher return on franchise stores, so that doesn't bother me at all.
To support its growing online activities and the Beds operations, there was a slight increase in distribution and administrative expenses.
Overall, then, operating profit reduced by about 7.5% to £590k.
Outlook statement is very nice. It acknowledges the extent of economic uncertainty which prevails, while also noting that like-for-like performance continues to improve:
Trading in October was similar to the first half before improving strongly in November. Like for like sales for the 10 weeks since the period end to 7 December 2017 show further improvement on the first half performance.
We have started the lead up to Christmas well, which places the Group in a good position for the year. The market remains unpredictable and so our focus will continue to be on protecting our position through maintaining margins and focusing on our delivery of quality and value to our customers. We do see incremental opportunities to expand the business looking ahead into 2018 through the addition of new stores and development of new trading formats but fundamentally the focus is on good execution across our existing business.
My opinion
While not totally relaxed about it, I'm a happy holder here.
It has net funds of £1.6 million, so that on an enterprise value basis, it's even cheaper than it first appears. The EV/EBITDA ratio is less than 3x, which is perhaps about as cheap as you will ever find an undistressed stock to be. And thanks to the franchise model, it earns a fantastic return on capital of c. 27%.
This is not a high-tech business by any means but management are highly competent and I'll happily stick around for the foreseeable future, at least until something dramatically changes.
In terms of the outlook for other companies selling carpets and beds, maybe they are attractive contrarian plays after all?
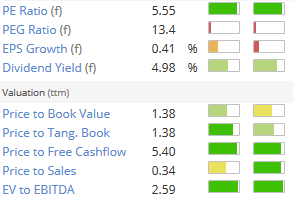
Luceco (LON:LUCE)
- Share price: 135p (-42%)
- No. of shares: 160.8 million
- Market cap: £217 million
It's a nasty share price reaction for this LED lighting manufacturer.
Luceco doesn't waste any time in resetting market expectations, and does so with great clarity, so it deserves credit for that.
The Group has seen gross margins weaken during the second half of the year and will now deliver gross margin of approximately 33%, leading to a £3.5m reduction in profit after tax to £13.2m, versus current market expectations of £16.7m.
Regrettably, the gross margin weakness was not identified sooner due to an incorrect assessment of the value of the Group's stock. The Group's Financial Controller has resigned as a result of this error.
Gross margin last year was just shy of 36%. Margin of 33% is more in line with what was earned in 2015.
The company blames exchange rates and commodity prices for the deterioration, but says that efficiency savings and overhead reductions will help things to recover, and it will hedge the RMB versus USD exchange rate to a greater extent in future.
Without inside information, it's impossible to know exactly what the error was. Incorrectly valuing stock presumably means that the company thought the stock it was selling was less expensive to produce than it really was, and I guess this was due to failing to update cost prices when exchange rates moved?
Luceco (LON:LUCE) only joined the market in October last year, and this looks like the customary wobble which we expect from a newly-listed company in the first year or two.
The IPO was at 130p, and the share price had grown by almost 80% on top of that. So today's share price reaction is a resetting of market expectations to where they were at IPO, basically.
The expected reduction in profit after tax is only about 20%, which is not so terribly serious in my book.
The issue might just be that the stock was priced for good growth, at a PE ratio of c. 18x, up until today. We find out today that current earnings are lower and that there will be a little bit of time before performance recovers, so the share price gets the double whammy of a lower multiple on a learning earnings forecast.
There is also the inevitable loss of trust when something like this happens. Luceco's financial year-end is December, so mid-December is quite late in the day to reset expectations. While investors will hope that this is just a one-off event (and personally, I suspect that it is), the loss of trust when a company fails to forecast results properly, is inevitably going to heap further misery on the share price.
Readers have also noted that the CEO sold 2 million shares a few weeks ago. While he still holds a very large number of shares, that may have left a bad taste in investors' mouths after today's news.
Conclusion
Personally, I'm going to put this on my watchlist now, because I liked the company when I analysed it before, and the only thing which put me off was the optimistic valuation. This might be back in value territory around here.
Momentum will certainly take a hit, but the Value Rank should hopefully improve in the days ahead.
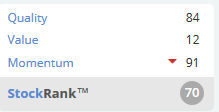
Fulham Shore (LON:FUL)
- Share price: 11.375p (-3.2%)
- No. of shares: 571.4 million
- Market cap: £65 million
During this section of the report, please remember that I am always biased against the pubs and restaurants sector. Fulham Shore operates The Real Greek restaurants and Franco Manca pizzerias.
During this latest six-month period, Fulham Shore opened eleven new outlets, of which one of them is in Italy. It opened another three since period-end, bringing the entire estate to 58 in the UK.
Borrowings have increased by almost £7 million (versus a year ago) to £9.7 million. As noted in the comments, most of the funds used to invest during this latest period came from borrowing, not from operating cash flow. So the roll-out is being debt-financed rather than self-funded.
This next paragraph is fairly explicit. In simple terms, the company isn't growing as quickly as previously planned, and probably won't grow in the future as quickly as was previously planned:
Some of our planned openings this year have been delayed by as much as six months as we seek better deals from landlords thus protracting lease negotiations. These delays have had the beneficial side-effect of improving our cash position and lessening our peak borrowings. We will keep under review our opening programme for the rest of the current and following financial years. We intend that our new restaurants will be selected to give us an average return on capital at the higher end of the scale previously recorded.
Mentioning the cash position and peak borrowings is important, as the company had c. £5 million headroom on its debt facility at period-end. The peak headroom can't be any bigger than that, and might be materially smaller than that. The amount of available capital has thus become a factor in the planned roll-out.
Performance at the pre-2017 estate has deteriorated, for which the company blames inflation, poor consumer confidence, a weakening economy, and rising costs. Those reasons are sort of worrying to me, because they imply that if the economy stays weak or gets weaker, then there is nothing the company will be able to do about it. This is why I generally steer clear of pubs and restaurants.
My opinion
I don't see any like-for-like figures, but the text is clear enough that they were poor for many of the company's existing sites, though they do remain profitable.
The existing sites should logically be in the easiest locations, while the new sites should be in the slightly more marginal/risky locations. With the existing sites doing poorly, and with new sites not doing well enough to justify or enable continuing the roll-out at the planned pace, trading has noticeably worsened here.
That being the case, and given the increased use of debt, I would be inclined to put this on a very cheap earnings multiple - single digits, without a doubt. I would also want to see a strong dividend yield, but the company doesn't pay one.
So this share price looks wrong to me. I regularly make mistakes, however, so good luck if you are a holder here.
Best Of The Best (LON:BOTB)
- Share price: 237.5p (fell 24% on Wednesday)
- No. of shares: 10.1 million
- Market cap: £24 million
Update on VAT Claim and Share Buyback
I'm catching up with this widely-followed share which reported some news on Wednesday.
BOTB started out running car competitions in airports, and has morphed into a company whose operations are principally online.
The airport activities were great for building the company's initial reputation and customer list, but the strategy for some time now has been to focus on growing online activities.
This has led to a change in tax regime, as the company is now in the business of offering "remote gambling" services.
This means it needs to sign up for Remote Gaming Duty - see here for HMRC information. My head is still spinning after reading the tax rules for Remote Gaming Duty on freeplays. The bottom line is that this will cost 15% of profits.
My understanding of how this works (bear in mind that I am not a tax advisor) is that betting duty is paid on gross profits. By traditional standards, that would be considered unjust, as it means that loss-making companies can still end up paying a form of tax on their income. In general, no other industry has to pay tax on gross profits. But gambling has been singled out for special treatment because of the ethical concerns which people have.
Anyway, Best Of The Best (LON:BOTB) reports that registering for Remote Gaming Duty will have a serious impact on its operating margins. It will try to recover overpaid VAT, and will then be subject to RGD rather than VAT.
Quote:
The impact on profit in the current financial year is expected to be mitigated by the old tax regime's ongoing application in H1 and a solid start to H2 and therefore the Company confirms that it expects to report profits before tax of not less than £1.4m (2017: £1.5m). The impact on FY19 is expected to be more pronounced, with forecasted profits before tax of not less than £1.2m.
For PBT to start moving in the opposite direction, rather than rising in line with the growing business, is clearly a great disappointment for investors.
On the other hand, the business still has plenty of attractive features. This profit warning purely relates to taxation, and no other factor.
Management are still heavily invested, and the company is now engaging in share buybacks in the open market, which will further increase management's stake unless they actively choose to lighten their holdings. I would expect them to take the company private, if the share price became too low.
On the other hand, if you don't trust the management team, there is the risk that they could attempt to de-list the company with a weak buyout offer for remaining minority shareholders.
I don't see any reason not to trust the management in this case, but investors have been burned by companies doing that before and are right to worry.
Overall, I'm not in any particular rush to buy shares here. If I already held shares, I would be a bit more concerned about their illiquidity, and I'd be disappointed about the tax regime news. But presumably I wouldn't own the shares in the first place if I didn't trust the management team - and I don't think that Wednesday's news gives any reason not to trust them. So I'd probably continue to hold!
Conviviality (LON:CVR)
- Share price: 386p (+2%)
- No. of shares: 175 million
- Market cap: £677 million
Proposed acquisition and placing
I've been a sceptic of this low-margin, acquisitive, debt-ridden alcohol wholesaler and retailer for some time.
I've got to hand it to Conviviality today, though - this deal seems like a great little bit of opportunism.
You might recall that I recently covered McColl's Retail (LON:MCLS), noting that one of their suppliers had gone bust.
That's the basis of this opportunity, as the supplier in question, through one of its subsidiaries, owns Central Convenience (see here), which describes itself as "the UK's fastest growing convenience store chain", and was evidently put up for sale as part of the administration process.
Conviviality's Bargain Booze subsidiary is now picking it up for £25 million, subject to acceptance of the offer. If so, it will buy it with new shares issued at 375p.
That will add a great bit of scale onto Bargain Booze. It will mean 127 new convenience stores (Bargain Booze currently has just over 600 stores). The company touts the additional economies of scale arising from the potential combination, which are quite believable:
The directors of the Company (the "Directors") believe that potential exists for operational, buying and distribution synergies to be realised from the proposed combination of Central Convenience and Conviviality Retail.
I'm still sceptical of Conviviality as a whole, and Central Convenience only earned EBITDA (unaudited) of £3.5 million in the most recent financial year, making the £25 million deal size rather big on simple valuation grounds.
However, the synergies should indeed be considerable, and the share price is sufficiently high that Conviviality can raise the necessary funds with minimal dilution to shareholders. So it's probably a smart move.
That's all for today. Thanks for your comments!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

115 comments
Luceco (LON:LUCE)
The big mystery to me is why the CFO is still there - has he no responsibility for what happened on his watch?
Adds credence to the profit warning/ share sale issue.
Phil
Re Luceco (LON:LUCE)
From RNS on 20th Feb ......the CFO gets the push (several months after the Fin Controller). No further restatements or trading updates recently so it looks as if this may be a functional Finance issue vs a business wide issue. Looks as if CFO search started before Xmas and the CEO can now move with replacement on hand. New guys CV looks good and relevant although CFO is a step up.
Now at <2/3rds original IPO price(78p vs 130p), Luceco (LON:LUCE) look good value bet for the mid to long term . Long term customer contacts through powercords plus LED factory set up and LED sales building in a good market. Will probably take 18 months to recover so probably I will be too early if I buy today!
"The Board of Luceco, the manufacturer and distributor of high quality and innovative LED lighting products, wiring accessories and portable power products, announces today that David Main has stepped down as Chief Financial Officer and from the Board to pursue other opportunities and that Matthew (Matt) Webb has been appointed Chief Financial Officer with immediate effect.
Matt joins from FTSE 100 listed multinational building materials distribution company Ferguson plc,"
I agree it’s an attractive valuation GARP stock now, the risk is ‘Matt’ gets in & discovers other ‘one off’ issues , you can bet he’ll have the drains up looking for them as from now on he owns any’issues’ himself.
Will be interesting to see if the final accounts contain a prior year adjustment or whether the issue all relates to 2017.
As rhomboid notes there is also now a risk of a bit of kitchen sinking going on.
Phil
Luceco (LON:LUCE)
New CFO hit the ground running.
"The shortfall relates primarily to continued margin pressure and the treatment of certain costs which had been earmarked for capitalisation but are now being taken through the profit and loss account".
Hope that's it - what do they say about profit warnings coming in threes? There does seem to be something going on with LED - Dialight (LON:DIA)
Phil
There are three main rules when listing.
Rule 1 is :don't disappoint by having a warning just after listing
Rule 2: Don't use the listing to sell off shares and then have a profits warning
Rule 3: See rule 1
Is anyone revisiting LUCE LN at this level (~70p) ? FY18 P/E 8.5. It looks like it may have fallen too far, yet it keeps falling. Apart from the disaster mistake in December which they have been honest about, I can't see why it keeps getting punished....? - not a holder at present.
Graham, since I didn't include a please on my request for Luceco (LON:LUCE) and Fulham Shore (LON:FUL), I will say thank you now for the coverage. Have exited Fulham Shore (LON:FUL) today. Painful, but it was in the richer half's account! Might need to buy some flowers on the way home!
On Luceco (LON:LUCE) - others know company better than me but I feel this is a one off. Having been an auditor, have seen plenty of exchange rate errors in my time and can happen. Given PE ownership, I would think the financial management is generally quite strong - taken a small position to (richer half's account :)). Thanks again for the excellent analysis and have a fantastic weekend
Hi Simoan
It would be a shame to lose your insightful comments so please don't absent yourself from the blog.
I am a significant holder of Luceco (LON:LUCE) and have spent the day trying to work out where I went wrong. If Hornby is a crook, then he isn't a very competent one. He still has 31m shares so is down £31m on the day. Ok, so he managed to shift 2m at 234 on 24th November - one month after his lock-in expired. But, it should be noted that Hornby only sold 1.2m shares at IPO. Not exactly exiting at the top. Brand, the EPIC guy, only sold a third of his holding at IPO and still holds 8m. EPIC still hold 24% of their pre-IPO 57% holding. All are down a good amount on the day.
I don't believe for one moment that the reason given is the actual one. Like others, I suspect that Hornby knew something if not all. Curiously, the Group FC, Ian Pritchard resigned from Luceco PLC on 24th September - well before this RNS and before Hornby's sale. You can see that from the Companies House filing.
I think the problems here are down to the increase in the copper price (which affects the wiring accessories business which is 47% of the total), the (smallish) movement in the USD/CNY from 6.84 to 6.60 (with a nastier dip to 6.47 in September) and a write-off of obsolete inventory. I have to admit that of these three reasons, I should have been aware of the latter - the stock to sales ratio had gone up to 29%, but it had been that high in previous years. I don't follow the copper market or the USD/CNY rates so I am hot holding myself responsible for missing those red flags.
If Hornby can be believed (and I admit there are a few reasons why he may not be, including most obviously the seeming conflation of the resignation of the Group FC with this 'discovery'), then this remains a fast-growing company with sales growing at an annual pace in excess of 20%. That leaves plenty of room for PBT to grow if the copper price and the exchange rates stabilise.
The latest forecasts from Numis are for 8.5p FY17 and 10.5p FY18. If sales hold up and there are no further balance-sheet write-offs, then I think FY18 could be up to 11.5p. On this basis and (perhaps generously) ascribing a p/e ratio of 15 to recognise the potential growth, then a fair value would be closer to 175p.
Of course, any further information or continued market froth-evaporation could mean that it is some time before it reaches fair value. Maybe naively, I see this as incompetence rather than manipulation. Ultimately, they sell widgets so there are a limited number of moving parts. It isn't a complicated business and there are no revenue recognition funnies.
The sell-off today is easily explicable - the share was looking expensive, the communication was unexpected, clumsy and not entirely credible, the market is thin before Christmas and this now looks ex-growth. The RSI is down at 12.26 on Stocko, so perhaps over-sold?
This may test today's intra-day lows depending on who wants out but don't beat yourself up about not spotting the red flags as I don't think they were very prominent in this case.
Regards,
Mark
Re Luceco (LON:LUCE) - Searching at Companies House I see no resignation filing - the Company number shows as 05254883 - is that correct ?
tx
Steve
Financial Controller is non board level, one notch down from FD so no reporting requirements
United carpets does look cheap but also fairly exposed to cyclical consumer discretionary slowdown. I'd like to better understand resilience of business and operating leverage. Roughly speaking it looks like gross profits only have to decrease c.10% for business to be barely break even operating profit given admin. costs. In a real recession I would expect gross profits to fall a long way below that. Cash buffer obviously helps but I'd be interested to see real stress testing scenarios.
Hi Graham, would have a chance to review the recent news from Idox please? Andrew
Creightons (LON:CRL) have dropped 30% since their H1 results 4 weeks ago. They now look a bargain and I was about to top up and tried to think what may have this been caused by. It then hit me that they could have been suppliers to Palmer and Harvey, the UK's biggest wholesaler to the FMCG trade and who ceased trading 28th November.
They may well be owed money however the receivers were allowing suppliers to reclaim stock but getting this back doesn't mean you can sell it on other than perhaps at a large discount? Their products have a long shelf life. Creightons (LON:CRL) have not made any statement about the share price drop.
I think I will hold off awhile to see if anything is forthcoming
Creightons (LON:CRL) did not have business with Palmer and Havey, so that is not a concern.
Many thanks
I didn't buy any more and the have gone up about 20% since Friday but it doesn't take many buyers/sellers in a company this size to move the price.
So this share price looks wrong to me. I regularly make mistakes, however, so good luck if you are a holder here.
Great to see such honesty, Graham! I make mistakes too, and holding Fulham Shore (LON:FUL) for longer than I should have is the latest. Luckily I only had a very small holding. Given how poor the results were, I was amazed I was able to sell them for 11.5p this morning. I like the concept, and the management are very experienced, but the increase in debt shows the roll-out has gone badly wrong and looks like it was also badly timed with lease costs for new premises now reducing. Frankly, I'm amazed the price has held up so well today but what do I know... there are so many things defying gravity at the moment!
All the best, Si
Hi Graham - re. Conviviality (LON:CVR)
EV/ EBITDA for the acquisition comes to (25m/3.5 = ) 7, whilst CVR's EV/ EBITDA comes to (758m/61=) 12 in round terms. So that implies a relative good deal on this basis.
However I can't find myself being excited by this deal as it is small for CVR. It represents only 5% approx. of current CVR revenues or EBITDA.
Hi Ram! You're right of course about the relative merits. My issue is that I've been thinking that Conviviality (LON:CVR) itself is overvalued for a good while. G
Fulham Shore (LON:FUL) - I disagree with the analysis here.
Why would you want to see a strong dividend yield from a company growing 20% (even after the reduced roll-out)? Why pay a dividend when you can reinvest capital at 25-30% ROCE? The dividend comment doesnt make sense to me. Show me a capital intensive roll-out growing at 40% in most recent period paying a decent divi.
"The existing sites should logically be in the easiest locations, while the new sites should be in the slightly more marginal/risky locations". I disagree again. Existing sites are in and around London and new sites are ex-London (e.g. Bristol, Edinburgh, Oxford, Manchester, etc). I don't know whether this makes them riskier - may be? Management has said before that the Real Greek is performing better outside London. I am not sure about Franco Manca. I also know that London is highly competitive with a huge offering of alternatives. May be there is less competition outside London?
What is correct is that this is an operationally geared (and now financially geared) company with fixed costs trading in a weak consumer environment with highly promotive competition (Prezzo, Pizza Express etc discounting heavily).
What's important is can they continue opening restaurants at incremental ROCE of 25-30%? Management commentary suggests new sites will actually be at the top of the historical range due to landlord contributions and lower rent levels. If they can deploy capital at these rates and you can buy the existing business at sub 8x EBITDA, then the stock is very cheap right now IMO.
Barring a further strong deterioration in trading obviously.
Fulham Shore (LON:FUL). Let me start by saying I am a holder, but that (not for the first time) I can't remember what I was thinking of when I bought (this won't happen again as I now keep a journal - recommended).
Dividend: The lack of a dividend is just another indication that they are consuming cash to grow. Of course they are right not to pay a dividend in these circumstances. The real question is do you really want to own a company that apparently needs to consume all its cashflow investing in more sites just to make up for falling LFLs, and only grew overall due to an unsustainable increase in debt. In contrast Revolution Bars (LON:RBG) (at least in theory) are able to grow from cashflow and pay a dividend.
Locations: As I understand it, a typical rollout story goes as follows (warning: this is a cynical generalisation):
1) Establish and perfect a successful format with a good customer reputation / buzz.
2) Expand to carefully selected locations - those with plenty of suitable customers but where costs are proportionate
3) Excellent sustained growth - share price grows to a premium rating
4) To maintain growth and justify share rating, continue expanding by moving into marginal locations / paying premium prices in good locations / opening close to other existing locations.
5) Price rises further. Founders sell out
6) Return on new sites is below that expected. LFLs fall due to cannibalisation and falling reputation.
7) Share price collapses. (optional: company taken private, marginal sites closed, company turned around.)
So, yes, in general the first locations (stage 1 & 2) are the best and the later ones (stage 4) are riskier. However, it seems to me that, by limiting themselves geographically to the London area, Fulham Shore (LON:FUL) did not complete stage 2 before going onto stage 4. As you say, Bristol and Oxford are not (generally) marginal locations, would normally be opened in stage 2 and should perform well. If there is any hope for this share, that is it.
Consumer environment: As I understand it, Prezzo, Pizza Express operate high price, high discount model whereas Fullham Shore offer everyday value. So there is a niche there.
High ROCE would normally quickly result in positive cashflow. I doubt they are measuring their cashflow wrong.
There are a lot of big assumptions and opinions here. I am not sure what backs them up.
"a company that apparently needs to consume all its cashflow investing in more sites just to make up for falling LFLs"
They are not doing it to make up for LFLs. They are doing it because of attractive economics. David Page and his management team own more of this share than any of us - they want to create value (as they have done in the past). If you want to dispute the economics, thats a different argument.
"In contrast Revolution Bars (LON:RBG) (at least in theory) are able to grow from cashflow and pay a dividend."
Revolution Bars was growing their estate by single digits. Fulham Shore grew its estate 50% in the last period. Big difference?
"The 1-7 crystal ball game plan"
I can name a lot of roll-outs that have created huge amounts of value over many years (Patisserie Valerie, Chipotle, Pizza Express in 90s). Others havent. There is no one size fits all. Look at the management team. Look at their incentives. Look at the business. Look at the competiiton. Then we can talk about what is a reasonable outlook.
"High ROCE would normally quickly result in positive cashflow."
Not true. It depends on how much capital you spend. If you are growing 40-50%, its unlikely you'll be generating positive cash flow unless you have truly exceptional economics (unheard of in restaurant business - ive only seen Patisserie Valerie and Chipotle before the blow up come close)
yeah every AIMer that IPOs is for suckers...like Boohoo.Com (LON:BOO): IPO for 50p in March 2014 onto AIM, whatever happened to that? There is a trick in timing the exit of PEs but there are fairly good characteristic price action patterns to follow, some have catalysts that help
generalisations are generally untrue
Graham, Paul and Stockopedia
Sorry to post this question here and hope ok as I have posted below the video interview as well at https://www.stockopedia.com/content/video-ask-me-anything-with-paul-scott-amp-graham-neary-252398/
Though I am not a full time PI Paul said at minute 7” 40’ that his aim is to track all UK small caps and that he looks at trading updates and results everyday (I assume through RNS announcements).
If you are reading this Paul/Graham how do you filter for RNS’S from only small caps? Looking at Vox markets and Investegate you can only filter by market. Is there a service that offers more control on what RNS’s one sees. or does anybody else know of one?
Thank you.
Michael
Re: Tracking all smallcap results
I think the answers you'll get are:
1) https://www.investegate.co.uk/Watchlist.aspx
2) https://www.voxmarkets.co.uk/
3) For just results / trading updates: Scan https://investegate.co.uk/index.aspx?limit=-1 at 07:01 ignoring any known large caps or anything that sounds like a resource stock or investment company [insert obligatory whine about Character (LON:CCT) here].
Stockopedia have made noises at various times about improving their news service.
Hi Michael, I've heard that Vox is good for filtering RNS announcements. Personally, I skim all the RNS headlines for news on companies in general, and set up email alerts for the specific companies which I own and am most interested in (a much smaller subset of companies).
There is probably a better way of doing things, that's just me. Good question!
Graham
Thanks Graham.
If I find somewhere that offers filters I will let you know. I wonder if there is a way of doing it through Google Finance or Yahoo Finance.
Best
Michael
Google Finance don't even support portfolios any more or provide a screener.
I wont bother with Google. Thx.
Purpleski if you add a ticker to your watchlist on investegate you will get an email every time that company issues an RNS. Investegate there is a tab for AIM but I don't think you can filter by actual mcap.
Thanks Runthejoules. Yes I have a few on my watch list that I have manually added but was thinking more a long the lines of tools like one has when you create a screen
Mkt Cap < 500m
Mkt Cap > 20m
Exclude Sector - Miners
For example.
It surprises me that nobody offers paid or unpaid. Maybe one can do it if you have a Bloomberg? I am not shelling out for one of those!!
I am hoping that Stockopedia might be offering a RNS service on the redesigned site.
Thank you.
Michael
MIchael,
You could;
- Run your screen in Stocko
- mark all stocks and transfer them to a temp folio
- click the news tab and hey presto!
It sounds like a faff but would take seconds to run once setup..
btw Google finance is still around; https://finance.google.co.uk/finance
Hi Briga
That is pretty clever. Thank you. I think that will work.
I am still surprised that one can not filter by Mkt Cap or other criteria on services that provide RNS's.
Thank you,
KR
Michael
Hi purpleski.
It may not be exactly what you’re after, but if you set up a simple Stockopedia portfolio with the market cap parameters you’re looking for (screen for the stocks you want then copy into a portfolio rather than individually select stocks one by one) and then look at the “news” tab at about 7.30am or so every morning this will give you inter alia the RNS headlines for the day for that list of companies. The timeliness of the RNS news feed seems to have improved quite a bit in the last year or so and you can usually view relevant releases well before the market opens. It also offers comment from some other news sources as well.
Not sure if there’s a limit for the number of companies you can hold in a single portfolio but I have one with about 150 stocks in it and this works fine.
Gus.
Thanks Gus. Will have a look at this idea.
Sorry - my bad. Didn’t read the entire thread down to Brigra’s suggested fix in #84 (which I duplicated). Blame the jet lag ...
Gus.
purple,
Had an e-mail from Ed, ?yesterday in the little green thingie bottom right of screen, asking for suggestions on how to improve the site. Go for it! Seadoc
As Paul maybe not around today, I believe he uses Investegate, presume he sets it up for each small cap he is interested, note some sectors he does not cover. Investegate works quite well but I've had a few glitches, such as advising the wrong companies or late notifications. Seems to have been ok recently. But you can check all your selected companies by just going into the site. You could give it a try, it's free.
Except that currencies regularly move by more than 10% per year, let alone across 5 years.
https://www.exchangerates.org.uk/news/17056/2016-year-in-review-euro.html
Here you'll see in part 1, that the EUR moved more than 10% against the USD in CY 2015.
And in part 2 you'll see the £ moved more than 10% against the USD in CY 2015.
We tried pegging exchange rates. It didn't end well.
Two more questions:
1) Luceco (LON:LUCE) - Why on earth would anybody buy into an AIM IPO?
2) Fulham Shore (LON:FUL) - Why do companies in this sector routinely fail to provide LFL figures?
(OK, these are rhetorical questions, the answers being: 1) We don't, and 2) Because they're really bad)
Hey, if you don't think it is appropriate to reply, I'd really appreciate a quick private message telling me why I'm talking nonsense as well giving me the downvote.
Thanks, Leo
What is the average 12/24 month return on AIM IPOs?
What is the average 12/24 month return on AIM IPOs?
A good (and fair) question - I can't find any research on this. E&Y produce a quarterly "IPO eye" publication which includes figures on average first day change and change from issue date to the the end of the period (i.e. between 0 and 12 months):
Q1-Q4 2016: 9.4% first day, 34.5% from issue to end Q4: http://www.ey.com/Publication/...
Q1-Q2 2017: 3.5% first day, 7.5% from issue to end Q2: http://www.ey.com/Publication/...
Q1-Q3 2017: 8.2% first day, 12.8% from issue to end Q3: http://www.ey.com/Publication/...
E&Y don't say, so I assume these are to mid-market prices. Of course you're only paying a half-spread if buying at IPO and selling to the market.
Based on the above and anecdotal examples of "IPOs gone bad", I'd like to "rephrase" my rhetorical question on AIM IPOs:
Q) Who on earth would buy into an AIM IPO and sell out after 9 months? A: Smarter people than I.
Q) Who on earth would buy or hold a AIM IPO 9 months after issue to about 24 months after issue? A: Better stockpickers than I.
I will try to knock up a google spreadsheet with some real figures.
[Regarding Boohoo.Com (LON:BOO), the 12 and 24 month return was bad, and if you sold at the wrong time it was terrible]
Leo
Interesting figures.
When looking at the day 1 returns, you need to take into account the “adverse selection risk”. That is if you went in blindly for say £1,000 in every IPO, you would receive little or no allocation on the hot deals, while you could receive a “generous” or even the full £1,000 on the deals that will trade down on day 1.
Obviously, the return following the first day of trading there is no such bias, as a private investor, you will be able to buy as much as you want on the first day of trading (at market price).
About a third of AIM stocks fail within 5 years of listing, there's a paper somewhere along the lines of "Is AIM a Casino?", although it's getting a bit old now. The leading indicators of a good company are a long track record (so 5 years or more), company size (the bigger the better) and the quality of the Nomad. Technology companies have a particularly bad record.
But you do have to pick and choose. For every Accrol Group (LON:ACRL) there's a Watkin Jones (LON:WJG) or Cerillion (LON:CER) or Bioventix (LON:BVXP) or Ramsdens Holdings (LON:RFX). There have been lots and lots of successful AIM stocks, the challenge is to pick your way through the dross while recognising you'll get things wrong occasionally.
timarr
Best Of The Best (LON:BOTB), Best of the Best. The management should have known about the tax changes. If it was a surprise the quality of the management is questionable.
Len
Whilst most AIM IPO's turn out to be bad investments, especially when PE funds are the sellers, some can be good. You still need to analyse each one.
With Luceco (LON:LUCE), the firm was floated because it had become too big relatively for the PE fund EPE Special Opportunities (LON:ESO) which was a major shareholder. EPE Special Opportunities (LON:ESO) have still retained a significant holding in Luceco (LON:LUCE), so their interests are still aligned with other shareholders.
As for today's update, IMO it is a one-off that has been communicated, with figures, to the market.
My own belief if that the c.47% fall is an over-reaction, but Luceco (LON:LUCE) won't be able to justify its previous premium rating with such blunders.
I used to wait with Aim IPO`s for 6 months before looking at them but have noticed that an IPO with an attractive growth story that rises in the initial days following flotation then the price can keep rising as buyers rush in to jump onboard and then as it hits momentum stockscreens a new wave of buyers come in.People will often buy even if the stock has a wide spread which means the stock can go ballistic
Companies such as Luceco (LON:LUCE) should always be expecting their inventories to decline in value (Steve Jobs was not kidding when he said that that computer inventories go down at 2% per week).
Luceco's inventory was alarmingly high anyway so the clear out will be costly.
United Carpets (LON:UCG) - If you're interested which end of the market they cater for, here's a google streetview of my nearest store:
https://goo.gl/YZukyu
Even more so than BOTB, I have to ask why this is listed? Surely the management + family could afford to buy the other shareholders out? I can't believe they are listed to give them more respectability (as is given by BOTB as a reason) - yes this is an industry notorious for going bankrupt with customer's money, but I doubt many of their customers even know they are listed and the more savvy would just use a credit card. (In contrast, I much prefer to use quoted airlines because of the consequential costs caused by a failure). Perhaps they get lower credit card handling fees to reflect lower compensation risk?
But I can't argue with the numbers. I can't remember ever having seen anything like it.
yes, I agree I haven't been able to find out the real reason why the United Carpets (LON:UCG) controlling shareholders are happy to put up with the listing expenses and faff for such a small market cap share.
But they have been listed since 2005, and have a good record of paying dividends in the last few years.
Re: £Luceco
currency volatility due to brexit is killing british manufacturing margins and will do so for the next two years
How can you write up a 3/5 year business plan for a bank loan etc. if there is a real chance that the pound can move 10% in either direction
Well, in some part you do what they have now said they intend to do, "increase its foreign exchange and commodity price hedging activities".
This may be of interest to some http://www.bbc.com/capital/story/20130628-how-companies-avoid-currency-risk
There are others in the community who invest in non-GBP stocks and funds, I read about a couple the other day. And, even they mention having hedging in place to ensure performance is not affected.
It would appear that a few schoolboy errors have been made here with Luceco (LON:LUCE).
Which now actually seems to be in bargain territory, especially if you can believe "with margins expected to recover to long term expectations in H2 2018" and " revenue forecasts for 2017 and 2018 remain in line with market expectations".
I had previously posted about the Shares Magazine Growth & Innovation forum on 30 Jan 18 only to realise that the companies listed at the time were last year's attendees. The event seems to be taking shape with confirmed attendees including Cambridge Cognition Holdings (LON:COG), Cloudcall (LON:CALL), CML Microsystems (LON:CML), Collagen Solutions (LON:COS), Corero Network Security (LON:CNS), Cyanconnode Holdings (LON:CYAN), EU Supply (LON:EUSP), Fairfx (LON:FFX), Jaywing (LON:JWNG), MedaPhor (LON:MED), Mercia Technologies (LON:MERC), Plastics Capital (LON:PLA), Smart Metering Systems (LON:SMS), Totally (LON:TLY) and Yu (LON:YU.) plus 5 further companies. Gervais Williams of Miton (LON:MGR) and Richard Penny of Legal & General (LON:LGEN) will also be guest speakers.
https://www.sharesmagazine.co.uk/events/event/growth-innovation-forum-2018
Many thanks for the requests, I am now covering Luceco (LON:LUCE) and Fulham Shore (LON:FUL).
Chairman's explanation of delays in store openings to negotiate better deals and helping minimise peak debt sounds like rationalisation not strategy. Indeed, Chairman David Page's writing style noticeably more conservative and less self confident than previously - no list of what weak operators characteristics were.
it might be worth pointing out that in the last 12m or so, Fulham Shore (LON:FUL) has appointed a financial PR firm and that future announcements will contain an additional voice, that of the PR firm, who will quite likely be advising their client to put things in the same terms that any other quoted company would be expected to, rather than just blast stuff out in the accustomed style.
I think that both Franco Manca and The Real Greek are winning concepts and a shakeout in the industry might mean the the Group emerges from the shakeout a long-term winner. Does this story end with a market cap under £70m?
Asagi (no position)
I don't see any linkage between what LUCE announced today and the ongoing issues at Dialight.
In fact Dialight's issues may be a mild positive.
On the other hand Luceco Chairman looks to be a lightweight.
Luceco (LON:LUCE) for me as well if possible it has been on my watchlist for while now having owned in the past. Noted the recent price weakness so held off on buying and the profit warning from Dialight made think it may be a short last few days.
If it's quiet and you want to pick up Best Of The Best (LON:BOTB) from the other day then I would not object!
Done it Paraic! Cheers
Luceco (LON:LUCE) - assuming the £13.2m adjusted PAT is accurate (and given the auditors will already be in there doing interim audit testing and pre-close work, we ought to be able to assume that for now), then using 160.8m shares in issue from Stocko, gives a historic p/e of around 14 at current price levels. Given they have some control over their input costs due to their China manufacturing facility and assuming the CEO can be believed about H2 FY18 margin recovery implies that this could be a one-off stock write-off making them look cheap.
Of course, if the CEO is a complete crook then all bets are off. But it would seem that he still has plenty of skin in the game (20% of shares). This is a long-standing business, albeit it has moved into new markets. Some of their communications seem clumsy and clearly their finance department isn't fit for purpose. This is selling widgets so can't see any revenue recognition issues and revenue is growing.
I've dumped my Luceco (LON:LUCE)... I'm a sell-on-bad-news-buy-on-good-news girl. Considering this 'irregularity' has suddenly come up, I wonder what other skeletons are in the closet...
Also request Fulham Shore (LON:FUL). This was a big hope for me 12 months ago on a 3-5 yrs basis as I thought the the concepts behind both Franca Manca (innovation in big and ageing sit-down pizza market) and The Real Greek (new and ownable chain cuisine) were strong. I also thought it was a good time to be a new, designed to be efficient (small sites, few menu items etc) operation under experienced mgt and establishing a brand in tough times ready to bloom when the cycle turned.
Now not so sure! % Gross margins have dropped 2.7% to 42.8% and like-for-for like sales are down in suburban restaurants (again, no exact data given!). With a strong concept, I would have expected growth in market share leading to positive like for like in a market with lots of choices like pizza.
Net outcome is that net roll out growth in outlets +10 to 57 is now not self funded but largely came from taking on debt: being self funded roll out was a key basis of appeal previously! Chairman's explanation of delays in store openings to negotiate better deals and helping minimise peak debt sounds like rationalisation not strategy. Indeed, Chairman David Page's writing style noticeably more conservative and less self confident than previously - no list of what weak operators characteristics were.
I still hold but am going to re-read section on behavioural biases for self harm including anchoring!! I think I may now be hoping rather than expecting mid term success.
Burford Capital (LON:BUR) are down around 4% today on the below announcement; can't fathom it, it looks very positive to me.
Burford's fund business
Burford announced the acquisition of GKC, the largest fund manager in the litigation finance sector, a year ago. That acquisition provided Burford with the ability to access private as well as public capital to meet the needs of its clients and broaden the sources of funding to finance its continuing growth.
Successful acquisition
The acquisition has been a success. Burford rapidly integrated GKC and now operates the business as a single unified platform. GKC is now known as Burford Capital Investment Management LLC, which serves as the US Securities and Exchange Commission-registered investment manager for all Burford investment funds, including those raised by GKC.
Fully integrated
Burford's industry-leading legal investment team, into which GKC's staff has been assimilated, now operates on a single cross-platform basis, reviewing all potential investments regardless of their source of capital and managing all ongoing investments. Burford uses a single Investment Committee to review all commitments of new capital to any strategy.
$16 million in 2017 fund income already contributed
Financially, the funds business has contributed management fee income and early performance fee income. In 2017, we expect to earn approximately $13 million in management fees from the funds. In addition, we expect approximately $3 million in performance fees to be released in 2017, a figure larger and earlier than our original expectations. The performance to date of the funds business has exceeded our expectations at the point of acquisition.
In addition to that direct fund income, Burford has also benefited from a further $2.9 million in income from the successful resolution of an investment originally held on GKC's balance sheet and purchased directly by Burford as part of the GKC acquisition.
Early success from new complex strategies fund
We were pleased to raise a new $500 million fund for complex strategies in June 2017. Our complex strategies investments have already enjoyed early success. We have made six investments to date, committing $311 million of capital, a more rapid pace than we were originally projecting. One of the investments has already resolved, generating $3.8 million in gross profit on an investment of $22.8 million, for a gross IRR of more than 200%.
Other funds show multi-year financial potential
As to our other funds, 24 resolved investments in the three Partners funds and associated sidecars have generated a 64% return on invested capital to date with an average duration of 1.6 years, producing a gross IRR of 52%. The three Partners funds presently have 53 ongoing investments.
Re Burford Capital (LON:BUR) - Its because 3 of Gerchen Keller (GKC) directors are "disengaging". Surprising if the price didn't drop I suppose.
But they are still "Senior Advisers to Burford and continue to serve on the Burford Investment Committee while stepping back from their operating roles. In their new positions, they will continue to lend their insights to the business while also being able to pursue other ventures, although they will remain subject to non-compete and non-solicitation agreements until December 2020 and a lock-up on their Burford stock until December 2019."
Is Gercher a major part of Burford Capital (LON:BUR), seems to be less than 10% of the profits? The only other thing although it's not that clear from the figures, the margins may have slipped " As to our other funds, 24 resolved investments in the three Partners funds and associated sidecars have generated a 64% return on invested capital to date with an average duration of 1.6 years" that's only 40% pa. Current op.margin is 76.8% in latest figures on Stocko.
Sounds to me like they are just moving from executive to non-executive roles, so for me that's not such a big deal and with the lock ins and non-compete clauses I can't really see much financial downside in the near term from these changes.
On margins, I think it's the sidecar vehicles they are specifically referring to rather than the business as a whole. The sidecars generate lower returns because they use off balance sheet funding so I don't think they are talking about a deterioration of margins either for the main business or the GKC funds, and the ROIC/IRR figures quoted in the RNS are not comparable to the operating margins in their income statement.
Looking back at the GKC acquisition RNS they were quoting 1.4% management fees + a weighted average performance fee of 23%, with management fees expected to generate $21m over 3 years from the 3 funds. Today they say they have generated $13m in 2017 alone, so that looks to me like a considerable upgrade on previous expectations, which is consistent with the narrative about 'exceeding expectations at the point of acquisition'.
re: Burford Capital (LON:BUR) I believe Liberum have moved from BUY to HOLD. There are some useful posts (for a change) over on ADFN.
This may be a entry point but I suspect if may fall a bit further first.
D.
Hargreaves Lansdown are a long-term buyer of Burford Capital (LON:BUR) for what it's worth...
Graham - if you're looking at LED lighting in the form of Luceco (LON:LUCE) perhaps you could also comment on the warning yesterday afternoon from Dialight (LON:DIA)
Thanks
Dialight (LON:DIA) 's warning was because of production problems, so maybe Luceco (LON:LUCE) will benefit.
Maybe LPA Group will benefit most from both of the above's problems???
Luceco and Fulham shore. Been looking at luceco, not bought as too expensive, could be an opportunity. Hold Fulham shore, surprised that results are satisfactory given: slow down in store openings (not bad given environment), no visibility over results and declining margins! Also intrigued by reference to next 24 months in the outlook - are they going bust? Ok balance sheet I think but valuation getting stretched given operating performance. Tempted to get out at decent size loss - would have expected bigger drop in morning. But I love the pizza!!
Anyone else think SCVR has grown so big, popular and useful it might be time for Ed to add another staff member, or up Graham's hours, for when Paul is ill or otherwise engaged?
If you agree with this, please promote the idea.
Nobody will read it, as this is a few days behind from California and you post regularly.
Why not make matylda and MrContrarian 'official'? They have automatic scans for RNS announcements.
To my mind they provide a useful service, drawing subscribers' attention to news. In depth analysis could follow on an officially irregular basis.
There is too much dependence on Paul and Graham.
Investors on a DYOR need to make their own decisions.
Sure the SCVR tribune is extremely useful but 'No one can do your push-ups for you.'
Luceco (LON:LUCE) - he still has 31m shares so down the best part of £25m himself today. I think it should do 8.5p to 9.0p of normalised EPS. Maintaining revenue guidance and with control over its own supply costs due to facility in China, there are reasonable grounds for believing that they can recoup some of the gross margin reduction. Inventory was clearly too high but this isn't the fashion industry so this is an accounting error rather than a commercial one. I would think that fair value is closer to 175p if the forecast eps for FY18 is around 11.5p and a reduction in the P/E to 15
Luceco (LON:LUCE) - Perhaps he (the CEO) should sell a couple of dozen more shares and buy some glasses and calculators for the guys working in stock control!
Luceco (LON:LUCE), Maybe he should investigated for insider dealing, selling 2m shares just a few weeks before a profit warning, looks very suspicious to me.
Well considering it's less than 10% of his overall holding, doesn't actually look so smart or suspicious to me.
Luceco (LON:LUCE) So how many would he have to sell before you are suspicious?
Luceco (LON:LUCE) So how many would he have to sell before you are suspicious?
It's all very well berating others about holding a share after a big director sell with your 20:20 hindsight bias glasses on, but what do you do? Take your current biggest conviction long position, whatever it is, let's say an RNS comes out in 10 minutes time saying the CEO has dumped 10% of his stock. What do you do? Sell the lot?
All the best, Si
simoan,
He's not berating anyone, and not challenging anyone about holding a share after a big director sell.
He is just questioning the legitimacy of the transaction, something I think he is quite right to do.
He's not berating anyone, and not challenging anyone about holding a share after a big director sell.
Well, I was reading in combination with a snide comment further up the thread to give it more context. On a day when some readers of this board have taken a hit with a completely unforeseeable profit warning, it would be nice to see a bit more empathy from other contributors, rather than some clever arse comments based entirely on hindsight.
He is just questioning the legitimacy of the transaction, something I think he is quite right to do.
Yes, I agree, but as someone that claims to follow the company and previously held, it would be nice if he'd made the point at the time of the share sale! Clearly he would have sold. I'm getting increasingly fed up with all the brilliant investors here who seem to buy at the bottom, sell at the top and are never holding anything when there's a profit warning. Talk about too good to be true. It's very kind of them to grace us all with their presence...
I guess I need to take a break from reading this blog, so I'm taking a self-imposed holiday. Hopefully Paul will be back before I am!
All the best, Si
Sorry to see you go. I value your comments, but I know where you are coming from. Fortunately there are also a lot of very good, balanced and honest contributors here too.Hope you will review your decision after a large scotch (or whatever your tipple is!)
I was not berating anybody, I was asking a question. I did not even know they are a holder. If a CEO sells £4.6m of shares then yes I would consider my holdings. If I was a holder of Luceco (LON:LUCE) I would probably have sold, actually I sold out some time before this.
Re Luceco (LON:LUCE) Simon - Am not sure Herbie's comment implies gloating, merely that £4.7M is a lot more than merely play-money for most of us, and the Luceco (LON:LUCE) CEO should not have made any sale ahead of the profit warning, given that he did so in the knowledge of the FC's resignation weeks earlier (which he subsequently ascribes in the PW to the exchange-rate error). I agree with you, in general, hold-or-sell decisions are difficult when the CEO only sells 10% of his holding, and ordinarily that would not necessarily sound alarm bells since there are many reasons he might want cash (buying a house; a divorce settlement etc), but he should not have made any sale ahead of the PW.
CEO sold to settle tax liability, I believe.
Re Luceco (LON:LUCE) CEO share sale just prior to the company issuing a profit warning: could he not have waited a few weeks till after the profit warning? If not, it seems appropriate that the company bring forward their trading statement and profit warning. It seems most unlikely they were not aware of their deteriorating outlook, even if they were unaware of the accounting error. Thus I struggle to see this as forgivable. To me this seems an outrageous, under-hand act by a CEO with contempt for shareholders. If I am wrong in this I would have expected a full explanation from the company as to why this wasn't the insider trading it looks like.
I think the abrupt firing of the financial controller suggests this was quite a sudden event. The company took action as soon as it was uncovered. Think Tesco accounting scandal - financial black holes are often very sudden events in my experience! I really doubt the CEO would sell with that knowledge because it would be so likely to invite investigation.
Re Luceco (LON:LUCE) perhaps you are right that there was no funny business, though I am sceptical that the threat of investigation is a serious deterrent since we hear from shine66 (comment 96 above) that FCA figures show there are an average of only two convictions per year for insider trading despite it being widely acknowledged among City workers that it is a perpetual and widespread problem. Also, surely the Company knew at the time of the CEO's sale that the trading outlook was deteriorating? Maybe the CEO has done nothing wrong other than account for his actions and explain how there was nothing at all under-hand or contemptuous of shareholders? I can't know for sure - obviously I'm speculating, but I think it looks bad and should have been fully explained (and I speak as a LUCE shareholder), though you are welcome to take a different view of course.
Re Luceco (LON:LUCE) I am inclined to agree with riosurfer. In my experience of these things - and I have been an accountant and auditor - the company explanation rings true and the sequence of events seems understandable. A stock valuation problems caused by failing to unpdate standard costing for currency valuation changes would be both a significant effect and a surprising bombshell. The effect would be quickly evaluated.
Taking this on board, I felt the reaction was too severe for what was a 20% (ish) hit to bottom line and by my analysis, a one off. I backed up my belief and bought in. Unfortunately I caught the falling knife (what again ?), so I am still underwater.
I think we are due an Operational Update RNS any time now (maybe Friday's, completely not insider trading, price action was related to this ?) so I will be interested to see if I was lucky or naïve !
Re Luceco (LON:LUCE) you may well be right, particularly with regard to the stock-valuation issue. However, is there still not a case to answer, or explain, with regard to deteriorating trading outlook and worsening exchange rates? If it were really necessary to sell so close to releasing a trading statement, I haven't seen the explanation as to why it was indeed necessary, and I still don't see how or why the Company's outlook changed materially between the time of the sale and the day of the trading statement. If there has been nothing untoward, and given that the sale looks to be either merely a matter of chance and unfortunate timing or else illegal, I would have expected a detailed explanation from the Company as to why it is the former, not the latter. Instead I am left wondering what new information the Company had during this period that made their trading outlook (the stock-valuation issue notwithstanding) deteriorate markedly in the short time following the sale.
That said, clearly I am a little conflicted over Luceco (LON:LUCE) since, despite my reservations over the CEO's share sale, I felt, as you did, that the fall in share price following the profit warning was over-done (particularly if the CEO's share sale was simply due to unfortunate timing) leaving a company earning high margins and high returns at a much nicer price, and I bought in for that reason. If nothing else, I thought there might be opportunity for a short-term trade, even if I were suspicious of management, though I hope to be able to take long-term positions with such small stuff. Anyway, my cunning plan (and yours) is yet to bear fruit, or look as though it might do. I hope we both end up pleasantly surprised by this one, but I'm glad I have other plans too.
'Unfortunate timing'- very fortunate if you ask me. So shortly after listing this company has blotted its copybook and probably permanently. That said the sell off looked to be overdone and seems linked to a fund exiting.
Re Luceco (LON:LUCE) 'unfortunate timing' of CEO's share sale: Ha, ha, yes I quite agree, hayashi. We're a pair of irredeemable cynics, are we not?!
Funny how experience in the stock market - and particularly the way company managements treat outsiders, and private investors in particular - does that to you!
Luceco (LON:LUCE) - I don't know but as I said selling less than 10% of his overall holding doesn't actually look so smart or suspicious to me. Further consideration could be given to the fact the reason seems legitimate and he still holds a hell of a lot of shares which are currently worth almost half their previous value.
I guess if he had sold half his holding then I would say it would be suspicious and without wanting to get into any kind of argument here, yes, 49% would be suspicious too.
Thanks, Luceco (LON:LUCE) it is interesting the way you look at it in percentage terms, I have always looked at the amounts, if he had say he had 20,000 shares and he sold 10,000 shares I probably would not take much notice but any large sales (over £100k) I will be considering my position. As the shares have not done anything in the last 6 months it maybe a queue to sell. I think for directors to sell huge amounts is difficult. I'm just suspicious of large sales a short time before a profit warning.
Re Luceco (LON:LUCE) suspicious share sale a few weeks ahead of profit warning, okay, I take your point, but 4.7 million quid is a lot more than pocket money to most of us. He sold in the knowledge of the FC's resignation, which he ascribes to the FC's exchange-rate error and hence late warning of reduced profits. That being so, he should not have extracted nearly £5M play-money ahead of coming clean to the market. How can that be justified? Seems more than sufficient grounds for investigation by the police and financial authorities to me.
Sthree please Graham
+1 for Fulham Shore (LON:FUL) please. I hold a small slice (sorry!). I used to hold some Ceres Power Holdings (LON:CWR) once upon a time so still watching that as well.
LUCE : the error is found, one month after CEO sells £4.7M stock.
Some people ignore directors selling.
Luceco (LON:LUCE)
Nicely set up for a six AM knock on the door and, 'just a few questions for you, sir, shouldn't take long'.
Re Luceco (LON:LUCE) suspicious share sale by CEO, does that ever happen: i.e. investigation by AIM Regulation, FSA & the Met Police Serious Fraud Office)? Doesn't seem to - case in point: current Telit Communications (LON:TCM) CEO, Yosi Fait, though the question needs to be asked in this case. (I have no position in either company.)
I came across a response from the FCA in 2016 to a freedom of information request on the subject. Their own figures show a whopping two convictions per year on average for insider trading.
Well danyou, I bought some at 138.5p, wish I'd got in right at the beginning, mms trying to hit a few stops I would imagine £LUCE
I don’t understand the dramatic SP fall in LUCE. A head has rolled, the problem is a one off, sales are growing and it is still making a healthy profit. Falling knife or buying opportunity?
there somes to be a correction happning in most UK stocks. some are starting to look like good values. most drops are on no news.
im thinking its time top get in on a few stocks for upsides, but cant decide whether now is good time or a little further correction to still happen. But Uk seems to be looking like good value
Morning all! Luceco (LON:LUCE) & Fulham Shore (LON:FUL) seconded. Is this a BTFD opportunity for either of them? Also wondered if readers had opinions on ValiRx (LON:VAL) which has yo-yoed up & down recently, as cures for cancer will do.
Pleased about offtake agreement & investment from China for Bacanora Minerals (LON:BCN) (sorry, it's a lithium producer!) after vacillating sideways for about 2 years.
Good morning Graham, it would be good to get your take on Fulham Shore (LON:FUL).
Many thanks
Francis
Any chance you can make more sense of the Luceco (LON:LUCE) profit warning than me? Appears to be a stock write-off
Luceco (LON:LUCE) It reads to me that they failed to recognise that as a result of exchange rate changes they were paying more for product.
Sounds bizarre, but I can imagine a single embedded exchange rate assumption in a complex spreadsheet or somesuch. A head has rolled, rightfully so I would imagine.
Luceco (LON:LUCE) another SCSW tip that doesn't seem to have gone to plan.
I appear to have been given thumbs down and reported for this. Not entirely sure why.
SCSW, is NOT the same as Paul and Graham's SCVR, Luceco (LON:LUCE) clearly hasn't gone to plan and a few others suggested by Small Company Share Watch (SCSW) have had similar problems.
Yes and IDOX is another of several recent SCSW tips that have crashed and burned. I have cancelled my subscription. Much better to do my own research instead of paying SCSW to lose money for me. I have learnt my lesson the hard way.
My morning smallcap tweet:
Telit Communications (LON:TCM), WH Ireland (LON:WHI), Hornby (LON:HRN), Plant Impact (LON:PIM), Gaming Realms (LON:GMR), Ceres Power Holdings (LON:CWR)
Telit Communications (TCM) FY trading in line. Cost cutting- "Telit intends over time to reduce the number of its R&D centres and that any future growth in R&D spend will be focused in low-cost centres. The Group is also reducing its sales and general administrative cost base...reduce its cash operating expenses in the coming financial year by more than $10m, some 7% less...10% annuualised." Will cost $9m cash plus $16m non-cash writedown. Negotiating waiver of potential breaches of its covenants as at 31 December 2017. and to amend covenants.
W.H. Ireland Group (WHI) Warns. Recent 12 months rev up, expects this momentum to continue but "Costs associated with the transition to the new model and MIFID II regulatory changes were higher than anticipated...have adversely affected profitabilit. Duplicated costs incurred during the period will decline significantly in 2018." No numbers! Have to wait to 29 Jan for them to find a calculator. Extended FY runs to end March.
Hornby (HRN) CFO leaves end Dec. External candidate is new CFO.
Plant Impact (PIM) New Brazil distributor for products other than Veritas. CFO appointed.
Gaming Realms (GMR) 10 year services agreement with Jackpotjoy for the supply of various real money services including Slingo . Borrows £3.5m from Jackpotjoy as a 5y secured convertible. Maximum dilution is 12%.
Ceres Power (CWR) H1 trading. Guides rev up 80% to £3m. Signs Technology Assessment Agreement with a leading global OEM. "Ceres will provide the SteelCell® technology at the stack and system level for evaluation for combined heat and power applications. If successful, this would lead on to a Joint Development with the OEM partner in 2018."