Small Cap Value Report (Fri 15 Dec 2023) - WINE

Good morning just from Paul today as it's Friday.
Podcast update - boring companies today, so I thought it was a better use of time to record my overdue 4-8 Dec 2023 podcast instead, which is here. The mystery share is Future (LON:FUTR) - disclosure - I hold a small entry level position.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Agenda - very quiet for news today, so far -
Summaries -
Naked Wines (LON:WINE) - up 6% to 45.5p (at 08:38) (£34m) - Half-year report - Paul - RED
I trawl through the H1 figures, which seem to show a business that's shrinking, but trading around breakeven on a realistic basis. Balance sheet is massively over-stocked with a wine lake. If this can be turned into cash, then survival could happen. In the meantime, there's a material uncertainty going concern statement over the bank covenants, and a facility that needs to be refinanced. So high risk. But as I mentioned last month, also a potentially interesting, high risk punt for the gamblers amongst us!
Paul’s Section:
Naked Wines (LON:WINE)
Up 6% to 45.5p (at 08:38) (£34m) - Half-year report - Paul - RED
This subscription wine service has gone badly wrong, with us reviewing it negatively every time this year. However, on the most recent profit warning I did wonder whether it might be getting into punting territory? -
SCVR 8/11/2023 - RED - Another profit warning, looks in trouble. But at 29p tempting for a high risk punt.
That’s worked out quite well in the last month, with a 48% share price rise.
Will today’s interim results be a cold shower for shareholders, or provide a further boost on recovery hopes? Let’s have a look.
As you can see from the headline below, WINE has a history of being very PR-focused (and not actually doing what it said it would do, with repeated profit warnings & a disastrous long-term track record) -
Half Year Results for the 26 weeks ended 2 October 2023
Doing what we said we would
H1 revenues £132.3m (down 20% on H1 LY)
Adj operating profit £2.2m (down 52%)
Lots of adjustments again of £10.9m (H1 LY £4.8m)
Statutory loss before tax £(9.7)m - a big deterioration from £(0.2)m in H1 LY - but the culprit for the loss is costs which are one-offs in nature, and non-cash (goodwill write-off mostly).
Using adj PBT, I see this as just above breakeven, at about £1.2m, so not a disaster.
Adjustments to profit - are these reasonable? Surprisingly perhaps, I think yes. The £10.9m adjustments relate mainly to impairment of intangible assets, and some problem property leases. So in terms of the underlying trading of the business, I think adjusted profit measures actually are reasonable.
Inventory write-offs - this was a big concern of mine previously, as inventories are excessive, which can often hide unsaleable stock that needs to be written off. A £7.9m provision was made in H1 LY, but this time it actually reverses £0.8m of that provision, which is reassuring (assuming the figures are accurate - remember that interim figures are not audited).
Going concern statement contains a lot of information, but seems to conclude negatively, with a “material uncertainty”.
Balance sheet - is complicated! The main issue remains that there’s way too much in inventories, which has gone up again to £162m (from £138m 6 months earlier). There’s also £27m in “inventory stage payments to winemakers” - a prepayment within receivables. £34m of cash, takes the total current assets to an excessive £228m.
How is this financed? What worries me is that £80m is owed to “Angels” - customers. So where has their £80m gone? There’s only £34m in cash, which you could argue has come from the £30m of borrowings. So essentially the clients’ cash has been spent on wine, and prepayments to the winemakers. That could turn out to be OK, if the wines can be sold at a profit. Or it could turn out to be dead money, tied up in unsaleable wines. Or, what happens if customers want to take their money out?! It's been spent, so that could be a big problem, particularly if the borrowing facilities are withdrawn (which would use up the remaining cash pile to repay then). We just don’t know at this stage how this is going to turn out, but it looks potentially problematic to me.
Cashflow statement - cashflow is still negative, but nowhere near as bad as the LY H1 comparative. It looks as if the figures are stabilising, but what investors really need to see in future, is a big reduction in the inventories, which hasn’t happened yet, but management assures us that actions have been taken to reduce inventories in future. Let's hope they're given enough time to achieve this.
Outlook - it says today guidance for FY 3/2024 (it falls into the first few days of April 2024) is for adj operating profit of £2-6m. However, I think this is really going to be nearer breakeven due to this -
We also anticipate incurring one-off cash costs of the order £5m in H2 to drive inventory and cost reduction initiatives
Recent trading and outlook
Since we gave an update on trading patterns on 7 November, performance has been satisfactory. November and December are critical trading months given the high levels of sales in advance of the holidays. Customer order volumes in November and December to date have been consistent with our forecast. Net cash (excluding lease liabilities) at the end of November was £7.1m, up from £2.8m at the half year reporting point.
Within the going concern statement it says -
However, we will continue to report a material uncertainty in our going concern assessment as trading remains volatile and we still need to conclude some supplier discussions, but I'm confident we have the headroom to weather any plausible future scenario from here.
This relates to possible breach of bank covenants -
The directors' baseline case forecast, and their severe but plausible downside scenario forecast indicate that the covenants will be met throughout the going concern period. However, the headroom on the severe but plausible downside scenario forecast is limited and actual financial performance has been adverse to budget in recent financial periods. Factoring in the potential reoccurrence of this variance into the severe but plausible downside scenario would result in a covenant breach. In addition, the Group's ability to continue to generate sufficient cash flows and complete the planned actions with external stakeholders in the forecasted period continues to give rise to uncertainty over the Group's ability to meet its covenants in the going concern period.
It is hoping to refinance on more favourable terms, sounds like possible asset-backed borrowing.
Inventory reduction - this is encouraging, and suggests it might be able to gradually get inventories down to levels that don’t stretch the balance sheet so much -

Paul’s opinion - this is best seen as a complicated, quite risky, special situation. I'm not a psychic fortune teller, so I cannot predict how things will turn out in future here, it could go either way.
I’ve tried to cover the main points above, but there’s a lot more detail in the interims. Summarising, I think the balance sheet is still solvent, with decent NTAV of £83m, way above the market cap of £34m. However, it has far too much tied up in inventories, so this is the biggest issue. If WINE can turn a lot of its wine lake into cash, then that would straighten things out nicely.
The material uncertainty in going concern is a major worry, and it sounds as if a refinancing is necessary, which may or may not be successful.
Is there a decent business in here, struggling to become visible? Not really. In reality I think it’s trading around breakeven this year, and revenues are falling because of customer attrition not being replaced with new customers at anything like enough pace.
Is it likely to go bust? I don’t think so actually, but it’s one of a range of possibilities.
Could it become a bid target? Again, that’s possible, if some private equity firm imagines it could overhaul the strategy to make the business more profitable.
My view remains that this share is an interesting, high risk punt, but only for gamblers really.
Overall, the H1 numbers are not as bad as I was expecting, and there’s a chance management could turn things around, if they’re successful in turning bloated inventories into cash. Although with revenue falling at 20%, this could be a business in danger of gradually withering away. I wouldn’t want to guess whether the outcome is good, bad, or something in between, it’s too uncertain. Hence due to the high risk, I’ll stick at RED for now.
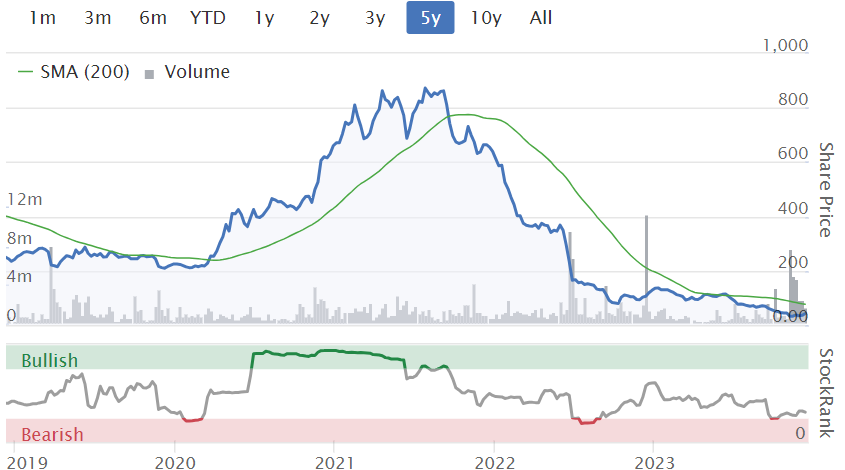
The pandemic boom you can see below was driven by Yanks, who imagined that WINE had invented a global platform, or was it an ecosystem, I can't remember -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

31 comments
Fair point and thanks Monty Carlo - a very poor historical track record, versus the likes of other "perma bears" such as Capital Gearing Trust (LON:CGT) and Personal Assets Trust (LON:PNL) , but the data is certainly interesting and thought provoking. I suspect we all hope they are not eventually correct!
I personally am still cautious for 2024 though given the yield curve inversion and its high level of accuracy in predicting a recession.
Money supply in the US is negative for the first time in 78 years. Of course, this has to be put in context of all the money printing stupidity, but there has to be a reasonably high risk of a hard landing in 2024 in my view. UK money supply is also very negative, and its not been negative since records began.
Equity markets are screaming buy on chart signals, and FOMA is taking hold. It will be interesting to see what happens after the Santa Rally. At least its put me, and many others I suspect, into a positive 2023 calendar year result after a difficult 2022.
This is really worth reading: https://www.hussmanfunds.com/c...
Yes, but best to read it after you've observed that Mr. Hussman must feel under some pressure to explain these performance stats for his growth fund. That doesn't mean he is wrong, but do bear it in mind.
Whilst I spotted the storm in a teacup earlier this week regarding other publications.....I am still going to draw your attention to an article elsewhere.
FT Alphaville's Robin Wigglesworth has put out a longer piece today under the headline "A quant winter's tale". Easy to find.
It is partly drawn from his book, but I think it is an excellent piece worthy of your attention if you are curious about investors who take a very different approach to most contributors here.
Monty. Thanks for a very interesting link.
Thanks, very interesting.
Thanks Monty- one of my best mates did this stuff successfully.
Just looking at Card Factory (LON:CARD) chart (I hold btw) and it has a triple top at around 117p so if this current spike breaks above that it should prove decisive and act as strong support on way back as well. Psychologically looks like an interesting set up.
I loaded up again yesterday. For the life of me the SP is just too low!!!!
I think it is just the perception of a large seller creating an overhang. Despite the rise to 117p recently I didn’t see any announcements of a reduction in shareholding as it dropped again to 98p so perhaps they are not selling total stake. If people perceive someone selling into strength though it can hamper gains.
I think last notifiable trade by Teleios was end Sept (notification 29/9) when they cut from 14.9% to 11.7%.
That was about £35m worth of shares when I looked the other day.
The flows are not currently supportive, but if/when the tide turns that is not a big number from an institutional perspective. Given the time lag permitted in putting out the RNS, by the time we find out the overhang has cleared the share price will have already reflect the news.
Card Factory (LON:CARD) has not fallen back so far, this time, so there is hope, it will break out, helped by Santa. I hold also.
If not, is this one to trade, sell around 112p, then buy on the pullback.
Did anybody else read wine lake and then do Homer Simpson's voice 'mmmmm wine lake'? No? Just me then. As it's a Friday in December, I might go swimming in a wine lake tonight.
Hi Paul
Don’t really disagree with anything you’ve said on Naked Wines (LON:WINE) but I’d probably pull you up on your comments about “what if customers all withdraw their money”.
In reality they won’t. The subscription service is really people putting £10 or £20 a month in and then spending that after a few months on a case of wine. So there won’t be any large balances in that £80m figure from Angels. I’m in that number and mine is currently £60. Am I about to try and withdraw that - no. If I thought they were going bust anytime soon I’d just buy a case and cancel the subscription. It’s not a bank where there might be a run as investors lose confidence.
however, that said I don’t, and have never, owned shares in Naked Wines (LON:WINE) despite being a customer. The wines are ok but if you like wine most are still a bit ‘meh’. Suitable for every day but frankly for the same price Wine Society are so much better imo. I will probably cancel my Naked subscription at some point next year. It’s a shame because the model does quite a lot of good for producers but I’m just not convinced that has translated well to buyers.
Naked Wines (LON:WINE) I don’t own but I like to understand what some of the reasons are why businesses can fail or in this case get themselves into a very precarious position. perhaps a lesson that can be learnt from what happened to naked wines over the past few years is that growth and in particular very fast growth can create huge risk and fragility within a business as much as it can create opportunity. In nakeds case it’s clear that the accelerated growth produced from the pandemic was sowing the seeds for the issues it faced today and actually produced a much more fragile and risky business than what it was pre pandemic.
That coupled with quality of management snd execution which in nakeds case with Rowan gormley the founder having left the stage before this period, the business had a manager at the helm who had no - to little skin in the game as well as a lack of retail / business experience, I would think it much more unlikely for a business run by an owner manager or family to have allowed itself to have taken on so much inventory risk and inefficiency if it was its life’s work on the line and it knew the business inside out (so management and its incentives are critical). Central to a retail business in my view is an almost fanatical focus on turning stock as fast as possible and minimising the build up of inventory. Similar to what can be seen at ASOS its warehouses became a place to store excess inventory when in reality those facilities should act as nothing more than handover / fulfilment center.
So essentially growth and particularly very fast growth can create huge risk and instability. And tge quality of management and the ownership dynamic / incentives of that management is key and has to be aligned with shareholders and the long term resilience of the business.
I think companies have a certain natural size.
Naked Wines (LON:WINE) offers - or used to offer - a few hundred cases from a small maker to its clients. Once it got big they started to sell out in minutes. This annoyed the customers (me). Once they started buying from larger producers - or taking over majestic - what is their usp that beats supermarkets (cheaper) the wine society ( co-op selling mid to high end) laithwaites (never understood) and wine merchants (upper to high end specialists). As such I see the business - if it survives - slowly shrinking to its size in about 2008.
Hi David,
Don’t really disagree with anything you’ve said on Naked Wines (LON:WINE) but I’d probably pull you up on your comments about “what if customers all withdraw their money”.
In reality they won’t.
Point taken. But when revenue declines, the positive working capital cycle does reverse. So it could burn cash as sales reduce.
Regards, Paul.
Many Angels are probably blissfully unaware of the profitability, or otherwise, of the underlying Business.
"If I thought they were going bust anytime soon I’d just buy a case and cancel the subscription. It’s not a bank where there might be a run as investors lose confidence."
I was an Angel for about a year, but did exactly what you theorise, above & cancelled, bought a final case & the Business returned my Balance.
For me it was a set of results about a year ago that weren't pretty (they are no better today) that made me consider whether I would get my cash back worst-case scenario, it was that as I get older I'm drinking less as my threshold is lower so my subscription was accumulating faster than I could drink the stuff, it was also that at my expertise level, Naked Wines (LON:WINE), Laithwaites and Majestic are all much of a muchness. Why should I subscribe monthly, and tie up cash when I could just rock up at either of the latter two and buy a dozen similar bottles when it suited me?
Unless it has an edge over the other two that I am unaware of, I don't think that the Subscription model works any more.
Hipgnosis Songs Fund (LON:SONG) this should put the cat amongst the pigeons with the naughty goings on and bombed out share price! Can’t wait for him to dig in!
“The Board of Hipgnosis is pleased to announce the appointment of Christopher Mills as an Independent Non-Executive Director of the Company effective immediately.”
Arix Bioscience (LON:ARIX) - I wrote to Arix Bioscience (I hold) a month ago complaining about the terms of their proposed takeover by RTW Biotech Opportunities (LON:RTW) . The takeover is at an effective 130p against a NAV of 180p odd, of which about 60p is cash which Arix is not planning to distribute but to give to RTW.
I did not expect a reply, but to my surprise, they have written back offering a meeting with their CEO Rob Lyne on Monday 18 December at 11am (to be confirmed). It will probably be by zoom or teams (again tbc).
Are there any members of the Stocko community who hold Arix Bioscience (LON:ARIX) who would like to join this meeting?
If yes, please contact me on richard at mutlow.net (the at symbol has another function and won’t work!)
Regards to all,
Ricardow
Charles Mitchell wrote about this and said: 'I am just about over the terrible deal the board of Arix Bioscience (LON:ARIX) did with RTW Biotech Opportunities (LON:RTW)' . If you leave a comment on this thread I think he will see it.
All: The linked thread is the best one on Investment Trusts so far and some of us are supporting Charles with a request for regular weekly blog on Investment Trusts, similar to the SCVR, run by members. If anyone thinks this is a good idea please post on the thread linked above.
Hi ricardo. I have already had a video call with Rob. It was clarifying in that Arix did not welcome this deal, it was forced onto them. I am sure you will find it interesting. Charles
Many thanks, Charles
Hi ya Paul, just wondering if Sosandar (LON:SOS) 1/2 year update (from Tue) is on the backlog to review? Not much chat around it in Tue, so maybe investors have moved on for the mo. I'm sticking with it as a long term play. I might just be a bit of a romantic but I'm thinking a move in to high end high streets might be a good play. Albeit it was a deviation from the initial plan and normally a red flag. Many Thanks Andy
Hi Andy,
Just to acknowledge your message re Sosandar (LON:SOS) - I'm still thinking about that one, I'll try to comment when I have something useful to say!
Best wishes, Paul.
Is there a list of funds which invest mainly in AIM companies? The FTSE AIM All Share Index (FTSE:AXX) has crossed the 120d moving average indicating a buy signal.
Hi eParo, There’s some discussion of this in Ed’s article yesterday on this topic which you might find helpful
Alumasc (LON:ALU) have got the green light for their acquisition of Arp Group. This seems like a solid business to me, and although they have headwinds in the construction industry, they seem to be weathering (hah geddit) it just fine.
edit: oh, i dont hold ... and wish I did !
Alumasc (LON:ALU) - yes very good news for their rainwater systems division - quite transformational. It's on my watch list for 2024. I'm not buying cyclicals yet, but this group has some good niche positions. Experienced management as well. Made a big mistake with Levolux a few years back, but otherwise solid with 3 good divisions.
My morning smallcap tweet: In the Bleak Midwinter Outlook Statement
XLMedia (LON:XLM) Getech (LON:GTC) Naked Wines (LON:WINE) Leeds (LON:LDSG) Chamberlin (LON:CMH) Abingdon Health (LON:ABDX)
◄XLMedia (XLM)► warns FY-Dec rev only $50-52m an adj EBITDA $12-14m. "While there is still opportunity to generate significant revenues in the remainder of the year now that December acquisition budgets have been confirmed, it is now unlikely that this will fully compensate for mid-period shortfalls and, consequently, North American revenues will now fall below previous forecasts." [SP=7.36 Cap=19m]
◄Getech (GTC)► warns FY-Dec rev £4-4.4m due to a number of projects delayed to FY24. [SP=7.25 Cap=5m]
◄Naked Wines (WINE)► H1-Oct headlined "Doing what we said we would". Which is continuing to shrink and lose money. Huzzah! Rev down 20%, pretax -£9.7m (-£0.2m). In line it seems. "We are moving towards a period of sustained cash generation....Our mission is to change the way the whole wine industry works for the better. In the last financial year we served more than 792,000 Angels..." Hark The Herald Angels Swig. [SP=41.45 Cap=31m]
◄Leeds (LDSG)► proposes selling its trading subsidiary, Hemmers-Itex Textil Import Export for £657k. Blames years of losses. Leeds will retain three properties worth £5.2m. Becomes cash shell. Holders will vote. [SP=8 Cap=3m]
◄Chamberlin (CMH)► Co's Scunthorpe foundry winning orders after focussing on supplying the renewable offshore energy market. Nov order intake over £1.85m for the first time. No change to FY24 exp. [SP=2.4 Cap=3m]
◄Abingdon Health (ABDX)► AGM stmt: guides H1 rev up. In line? Details in Jan. [SP=8.53 Cap=10m]
Brilliant Mr C -Hark The Herald Angels Swig :)
"Doing what we said we would". Which is continuing to shrink and lose money. Huzzah!