Small Cap Value Report (Fri 15 Mar 2024) - CAPD, BKG, BOOM, FAN, BOY. Brief: CTO, NEXN

Good morning from Paul!
Today's report is now finished. Have a lovely weekend!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Paul's 2023 share ideas, with live prices.
New SCVR summary spreadsheet from July 2023 to date, updated at weekends (very useful quick reference tool, search for ticker using CTRL+F). Hover over cell for pop-up notes.
Frozen SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
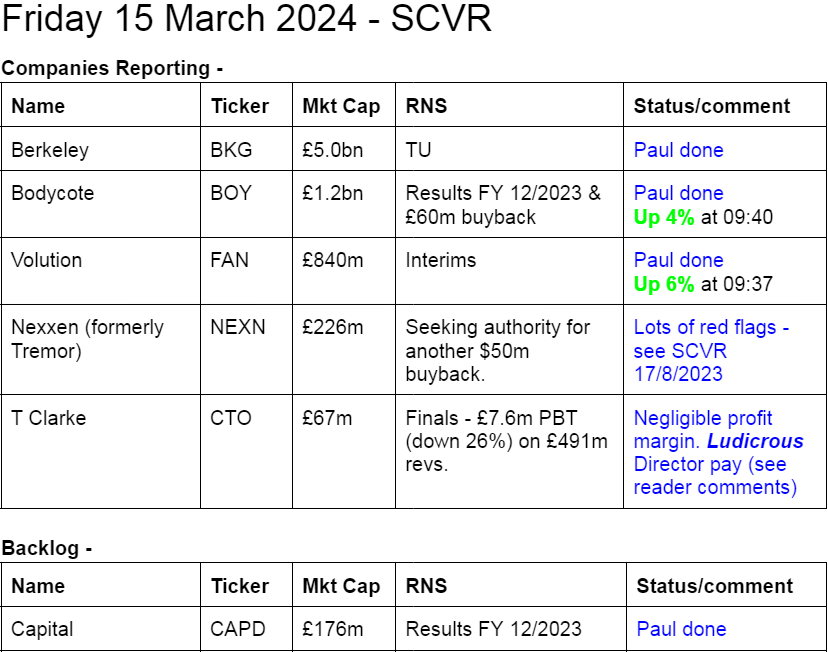
Other mid-morning movers (with news) -
Audioboom (LON:BOOM) - up 6% to 270p (£44m) - Reach announcement - announcements marked “Reach” are PR releases, for information and/or to ramp the share price often ahead of fundraisings, a cynic might say. Today BOOM says it’s now 4th in the US podcast ranker, based on audience numbers. A change to Apple iOS17 has reduced industry-wide downloads by 32%. BOOM says this is good, providing more accurate consumption data.
Paul’s view - remains negative on the fundamentals, see our extensive archive on BOOM’s poor track record. However at just £44m mkt cap, someone might see strategic value in the company, possibly? This share price doesn’t tend to be linked to its business fundamentals, which remain poor. So I’ll go with AMBER/RED, as anything could happen, and ad markets could recover. Last H1 results were terrible due to a big onerous contract. Might need another placing at some stage, but didn’t look critical, with £5.3m net cash at June 2023.
Summaries of main sections
Capital (LON:CAPD) - 91p (£176m) - FY 12/2023 Results - Paul - GREEN
I have a quick look, following a reader request yesterday. Low PER, strong balance sheet, and upbeat outlook make this seem interesting at a first glance. Although profit/cashflow seems to end up being spent on heavy capex, with only modest shareholder returns.
Berkeley group (LON:BKG) - 4,677p (pre-market) £5.0bn - Trading Update - Paul - AMBER
In line trading update today. Interesting that house prices are firm, and ahead of plan, whilst volumes remain a third down on LY. I was hoping for more recovery signs. Price possibly up with events for now, but medium term recovery seems likely.
Volution (LON:FAN) - up 6% to 450p (£891m) - H1 Results [slightly ahead] - Paul - GREEN
Decent H1 numbers, and FY 7/2024 outlook is slightly ahead. Very good PBT margin indicates pricing power. Liberum increases its forecast a tad. Valuation still looks reasonable to me, and I see potential upside on modestly set forecasts, as its end markets may be about to begin a cyclical recovery perhaps? Balance sheet not the best after multiple acquisitions, but not a deal-breaker. Overall, I like it.
Bodycote (LON:BOY) - Up 3% to 653p (£1.25bn) - FY 12/2023 Results - Paul - GREEN
This is my first ever look at Bodycote, so I might have missed something. It looks a remarkably good business, at a bargain price. So well worth you taking a closer look I'd say. Post a comment if you know the company, I'm interested to hear your views - it almost looks too good to be true on my initial review. So maybe there's some lurking problem I'm not aware of?
Paul's Section:
Capital (LON:CAPD)
91p (£176m) - FY 12/2023 Results (y'day) - Paul - GREEN
This was a late reader request last night, so I had a quick glance, and think it might be worth a closer look (ie. I can see some attractive traits, but haven’t done in-depth work to be certain it’s good).
CAPD calls itself a “complete mining services provider” for exploration & drilling, lead & haul services, fleet maintenance,and geochemical analysis.
Fixed assets are large on the balance sheet, so it must be renting out kit I assume, and capex is heavy ($69m in 2023), resulting in fairly modest distributions to shareholders with a 2.6c final dividend + 1.3c interim paid in Oct 2023 (forecast yield 2.9% per StockReport).
Revenue in FY 12/2023 was $318m (up 10%)
Good operating margin, with $60.3m operating profit, up 1%
Note it is also building up an investment portfolio, so that needs more work, it was $47.2m at Dec 2023.
Net debt of $69.8m doesn’t look excessive vs fixed assets or profits.
EPS was either up, or down, depending on whether you take into a large investment gain in 2022. Ignoring that, basic EPS was 19.1c in 2023, so 14.9p = PER 6.1 - obviously an attractively low rating, with possible upside if earnings can continue growing.
Outlook - all sound upbeat, and guides revenues of $355-375m (2023: $318m). Gravy [Edit: Eh?! Where did "gravy" come from LOL?!] Capex again is guided at $70-80m. Various growth projects mentioned.
Paul’s opinion - worth a closer look, as I’ve only had time for a very quick glance. The low PER and strong balance sheet (NTAV is well above mkt cap) combined with decent quality scores on the StockReport, and high StockRank of 94, all point towards this looking interesting. Maybe some readers could elaborate in the comments if you know it better than I do?
Downsides? Vagaries & cyclicality of the mining sector, and uninspiring shareholder returns.
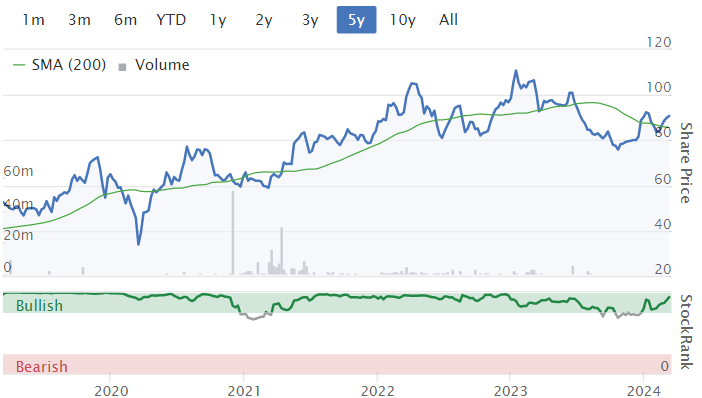
5-year chart - pretty good, considering this includes the pandemic -
Berkeley group (LON:BKG)
4,677p (pre-market) £5.0bn - Trading Update - Paul - AMBER
A large housebuilder, year end is FY 4/2024.
I’m watching this sector because it’s a good indicator of the health of the economy & consumer confidence overall, and a lot of things are at least partly triggered by housing transactions, eg building supplies, carpets, furniture, DIY spending, etc. Although as we saw during the pandemic, if people can’t move, they often do up their existing homes.
Today’s update covers the 10 months to 29 Feb 2024, my summary of the main points -
Says its business model is unique in long-term regeneration of brownfield (ie previously used land, as opposed to greenfield) sites.
Trading in line with consensus of £550m PBT FY 4/2024.
Reaffirms guidance for £1.5bn PBT for the 3 years to 4/2026 - which implies no annual profit growth in the next 2 years, so this looks a soft target, I hope mgt aren’t going to bank huge bonuses for beating an easy target?
Visibility good - all sale secured for FY 4/2024, and >70% sales FY 4/2025 also “secured” (definition is what? Exchanged contracts, or just sales agreed?)
Sales rates consistent with H1, ie a third down on LY.
Enquiry levels are good from potential home buyers.
Pricing “stable”, and above plan.
Build cost inflation now negligible.
Net cash at year end should be higher than at H1 (£422m)
Extended bank facilities to Feb 2029, at £800m gives loads of financial headroom.
Target shareholder annual returns of £283m, with £227m due to be paid by Sept 2024.
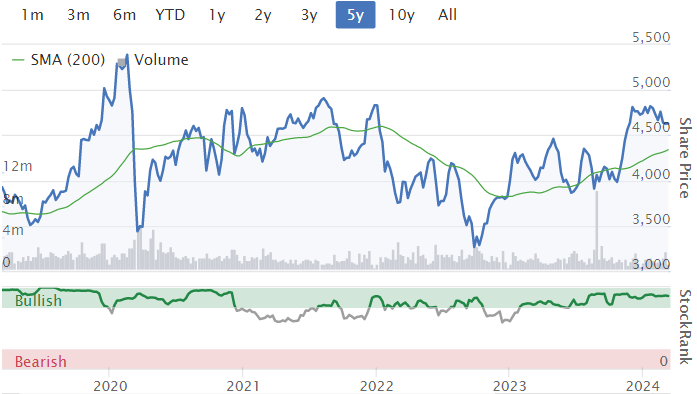
Paul’s view - nothing much to get excited about here. I was expecting more bullish talk about recovery. That said, BKG has remained decently profitable, despite volumes having dropped by a third due to well-known macro factors. Its profit seems to have been in a downward trend since 2018, so I don’t think this would be my first pick in the sector.
Will a new Govt allow housebuilders to continue making huge profits from throwing up jerry-built new houses, and rewarding shareholders so generously? That worry, combined with a strong sector-wide recovery in share prices since last autumn, means I’m not personally interested in chasing this sector any higher for now. That said, there seems little doubt the cycle has bottomed out and hence earnings look set to begin improving. So I can also see the bull argument.
Volution (LON:FAN)
Up 6% to 450p (£891m) - H1 Results [slightly ahead] - Paul - GREEN
Volution Group plc ("Volution" or "the Group" or "the Company", LSE: FAN), a leading international designer and manufacturer of energy efficient indoor air quality solutions, today announces its unaudited interim financial results for the six months ended 31 January 2024.
Checking our archive here, Graham and I have been GREEN on this share 3 times since July 2023, including coveted podcast “mystery share” status on 5/10/2023 at 370p/ share.
Marking its own homework, FAN headlines its H1 results with this -
Strong earnings growth, provides confidence of further progress in the second half of the year
Some H1 numbers -
Revenue up 6% to £173m (almost all the growth has come from 3 recent acquisitions)
Adj PBT up 10% to 35.0m (very impressive 20.2% PBT margin - clear pricing power here)
Adj basic EPS up 10.5% to 13.7p
Adjustments are fine, all relating to acquisitions (mainly goodwill amortisation), so I’m perfectly happy with the adjusted numbers.
FY outlook - looks good -
"Our strong performance in the first half, together with the tailwind from our three recent acquisitions, gives the Board confidence in delivering adjusted earnings per share for the current financial year slightly ahead of consensus1.
1. Bloomberg consensus adjusted earnings per share forecast for the year ending 31 July 2024 is 26.1p.
Crystal clear reporting there, and with a helpful footnote - marvellous! Why can’t all companies be this transparent? Often because they’re trying to cover up something untoward, a cynic might quip!
Valuation - the PER is 17.2x on the previously guided FY 7/2024 consensus of 26.1p, so if they achieve slightly more, I’d guess at c.27p, which improves the PER to 16.7x.
There might be further upside in FY 7/2025 as markets possibly improve?
Ah I’ve just read an update from Liberum (many thanks) which raises its FY 7/2024 forecast to 27.0p coincidentally the same as my total guess!
Future years’ forecasts are left almost unchanged at 28.3p (FY 7/2025) and 29.8p (FY 7/2026). I’m encouraged that hardly any improvement in earnings is forecast, as that should leave scope for future upgrades, and reduce the risk of 30% crashes on profit warnings. Hopefully.
Net debt (excl leases, as always here) is £54.2m (6.1% of the mkt cap), almost unchanged from a year earlier. That might sound a lot to a small cap investor, but it’s only 0.7x adj EBITDA (quite low), which is the measure that banks, and private equity seem to use.
Balance sheet - notable for the very large intangible assets from multiple acquistions of £257m. Take these off and NTAV isn’t good, at negative £(22)m. So I disagree with management saying their balance sheet “remains strong”, when it isn’t. Maybe I should drop into their office in Crawley, and go through the numbers with them?! I think it would be more accurate to say that the business relies on bank debt, but it’s at a fairly safe level (providing profits/cashflow don’t fall off a cliff in future).
Note it makes a presentational error of including lease debts within borrowings in a single line, instead of splitting them out on the face of the balance sheet, otherwise debt looks worse than it really is.
“Refund liabilities” is an oddity, at £12.2m within current liabilities, but not large enough to make me want to investigate further. Why is it making provision for refunds though?
Overall then, the balance sheet is not strong, it relies on debt. However the debt levels are not a concern, so it’s OK.
Cashflow statement - looks really good, and remember these are only half year numbers. It generated a lot of cash, has very little capex. Most of the cashflow was spent (roughly equally about £8-10m on each) on dividends, debt reduction, and acquisitions.
To me, this means the company has, if it were to stop acquisitions and repaying debt, the ability to pay a dividend yield of c.6% in a steady state (it’s currently paying c.2% yield).
Or put another way, it’s generating enough cash to keep paying modest divis, and making smallish bolt on acquisitions, and reduce debt, all at the same time. Pretty good!
Paul’s opinion - I like FAN. It looks a good QARP (quality at reasonable price) share.

Hopefully it should see end markets gradually improve, although I think it seems to have put in a creditable performance given tough macro over the last few years.
I’m happy to stick with GREEN again.
It’s the sort of thing that could be a bid target for a US buyer, I imagine.
Bodycote (LON:BOY)
Up 3% to 653p (£1.25bn) - FY 12/2023 Results - Paul - GREEN
A new one for the SCVR, as I continue my push into mid-caps. Roland seems to like it - see the general Stockopedia archive here.
A quick glance at the StockReport shows me it’s worth investigating (modest PER, reasonable yield, balance sheet support, high StockRank, and fairly good quality measures).
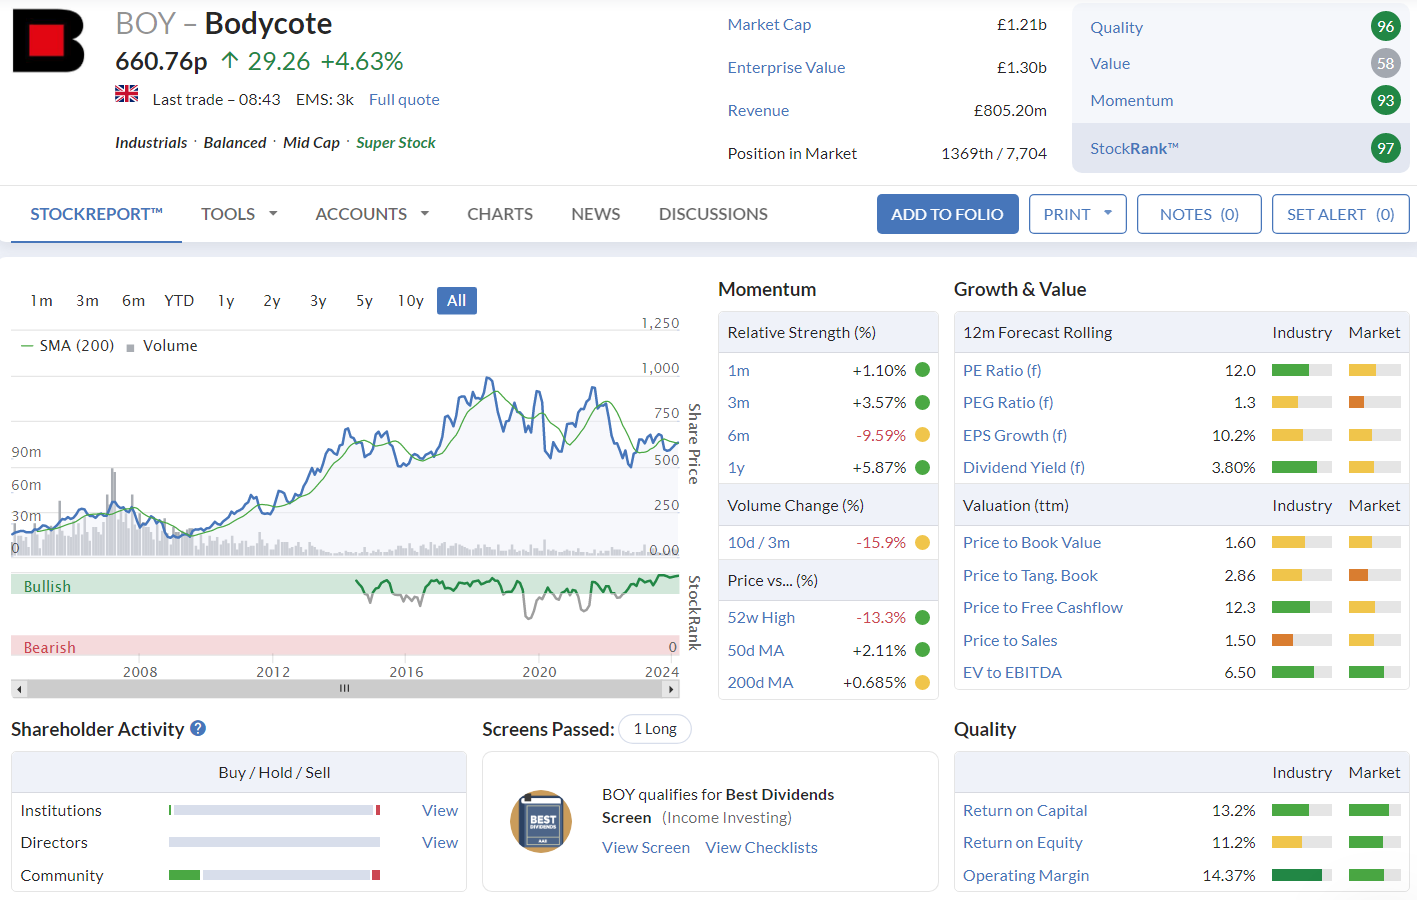
What does Bodycote do? From its corporate website -
The leading provider of heat treatment and specialist thermal processing services worldwide
Heat treatment encompasses a variety of techniques and specialist engineering processes which improve the properties of metals and alloys and extend the life of components and is a vital part of any manufacturing process.
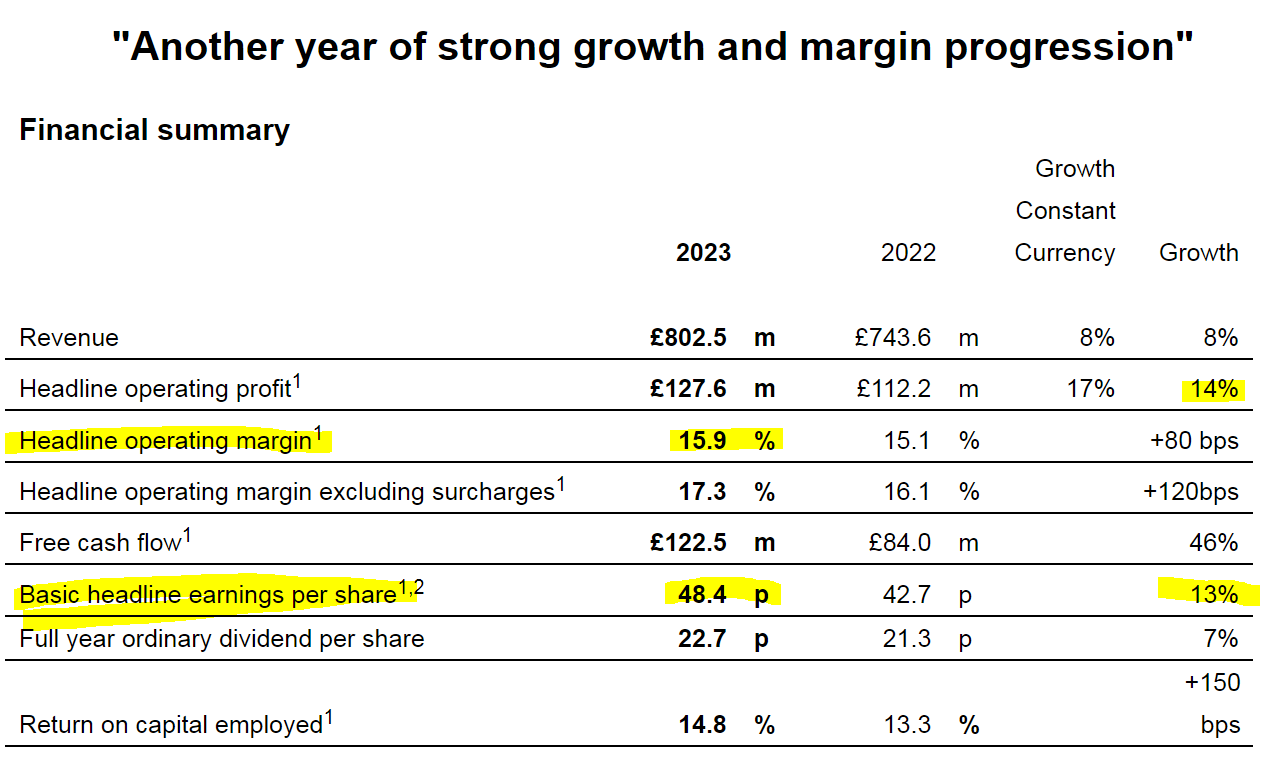
I don’t understand anything about its activities, but the numbers below are telling me that this is a good quality business, with pricing power, that nicely grew its profit in 2023 despite tough macro -
Other things I like -
Significant margin improvement; on track to achieve margins in excess of 20% over the medium term…
Disciplined capital allocation resulting in the £52m acquisition of Lake City in January 2024 and a £60m buyback commencing 15 March 2024…
Outlook -
Despite macroeconomic uncertainty we expect to deliver further progress in 2024. We anticipate a reduction in the level of energy surcharges, reflecting further normalisation of energy prices.
2024 should see us take another step towards our medium term margin target of more than 20%.
The Board remains confident in the Group's prospects for continued profitable growth.
Pity about the use of the meaningless catchphrase “profitable growth”, never mind.
What’s the catch here?!
Is there massive debt? No, it has net cash of £12.6m (excl leases), £51.7m net debt including leases.
Is there a pension deficit? Doesn’t seem to be anything significant, just £11m in non-current liabilities.
Balance sheet - NAV £792m, less £333m intangible assets, gives a very healthy £459m NTAV. So its large £505m PPE (fixed assets) are almost all owned outright, with equity.
Inventories seem negligible for the size of business, at only £29.5m, which I’m guessing must be because it does things to customer components, instead of taking inventory risk itself. That’s a lovely business model!
Nothing else of concern, this balance sheet is excellent.
Paul’s opinion - I’ve run out of time now, but have to say I’m bowled over by this. Why hasn’t anyone taken it over? The numbers make BOY shares appear significantly undervalued, so I must have missed something.
With this sort of value & quality available in a mid-cap, it does make me wonder why I’m bothering with small caps!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

78 comments
Bodycote ticks all the boxes. Beneish score suggests possible earnings manipulation around interpretation of gross margin.
Thanks Paul for another enjoyable and informative podcast. Even though I'm reading all of the individual reports during the week as best I can while holding down a full time job, I find these podcasts a very useful recap and it often leads me to research shares over the weekend I may have skipped over otherwise. When things get very busy the podcast also allows me to keep in touch with the markets even when there is little time to read and research. I think the decision to start reviewing mid-caps is great - there are some stonking bargains out there at the moment in mid-cap land, often without the inherent risks of many small caps. The mystery share Bodycote (LON:BOY) being a prime example, it's going on my buy list along with Gamma Communications (LON:GAMA) and Mears (LON:MER) this week.
Another enjoyable podcast to accompany my Sunday walk thanks Paul. Bodycote (LON:BOY) is the mystery share I think? Also you might have accidentally invented a new term at the end there 'micro-cack'!
LOL that's right , Bodycote (LON:BOY) was the podcast mystery share.
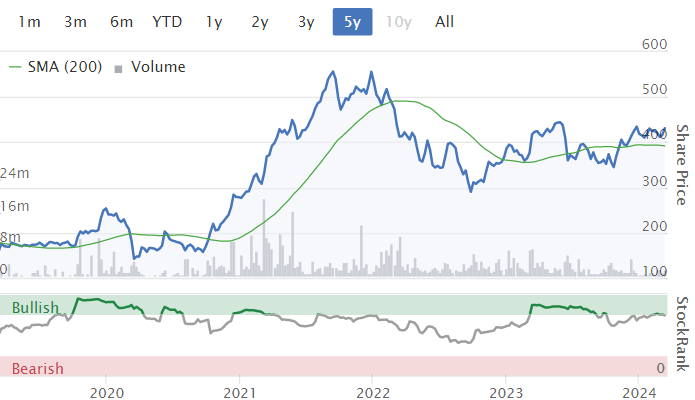
Bodycote (LON:BOY) I bought in December when I was rooting out cyclicals for a potential rebound. Though its chart bears witness to vacillating investor interest, it’s a solid performer with good quality metrics. Happy to hold and wait.
I held Tclarke (LON:CTO) around the financial crash on the basis lead electrical engineers for London Olympics stadium would bring them out the other side much stronger than the competition. If I am right they just bought a big ivory tower for head quarters. The type of HQ Lords Hanson and White would sniff out like the child catcher in Chitty Chitty Bang Bang before stripping the board and the property.
They were a favourite share of Lord Lee at the time.
I've followed CTO for many years. The argument (from the PR & others) years ago (when they nearly went bust after 2008) was that they kept on a highly skilled workforce, and would benefit when things recovered with much higher margins.
It hasn't happened.
It's run almost entirely for the benefit of the greedy (and average quality) Directors. Compare Dirs Rem with mkt cap!
Hi Paul, I have held Bodycote for a number of years. A cracking company. Probably the sector is not really "sexy" enough to attract too much interest
Bodycote (LON:BOY)
When I saw the headline figures in this morning's prelims, my thoughts were very similar to that of Paul. Gee these look very good and the shares are available on modest metrics. I read Paul's comments and watched the interviews that Paul Hill did with Roland and fund manager Jean Roche of Schroders. I then went back through the headline numbers in the prelims and they still looked very good. To conclude I read the recent commentary (Jan 2024) in Investors Chronicle which was positive. I appreciate that not all are fans of IC, but the more information I can glean the better.
Currently the demand in aerospace, defence and oil and gas is more than offsetting the softness in automotive. Regarding the latter, the company states that it is pivoting towards EVs, where it sees opportunities. The fact that Bodycote (LON:BOY) was able to pass through energy costs etc to its customers, suggests to me that it has a degree of pricing power.
Headline operating margin is reported as 15.9% if this can be increased to 20% in the medium term on increased revenue, then all things being equal, it should have a very positive effect on earnings. At around 650p Bodycote (LON:BOY) appears to me to be a buying opportunity
What I have yet to do is to go through the prelims in detail. Anyway for better or worse I have bought an opening position at 656p. To fund this I have taken the opportunity presented by the today's near 20% rise in Pressure Technologies (LON:PRES) and sold at just over 40p, for a reasonable gain. I like the latter but think that close to a 25% increase over the last two days is a little frothy. I will look to buy back in if the opportunity presents itself. This maintains my predominantly UK small cap portfolio at 27 companies.
Hopefully I haven't gone off half baked and missed any nasties in Bodycote (LON:BOY) prelims that I am now off to digest in full.
All the best
Pressure Technologies (LON:PRES)
A turnaround story going in the right direction. Successful restructurings always turn to be multi baggers. Caught my eye when the biggest shareholders put fresh money in the company to save it and they were willing to exercise warrants at 32p when the price was actually trading lower.
I hold although I rarely do get involved with such illiquid and low market cap. Most shares are held by few institutions and will easily go much higher on positive news.
Another McBride (LON:MCB) in my opinion and still early days in its recovery cycle.
I will probably see many from here at the AGM.
All the best
Bodycote (LON:BOY) I first bought in 2008 for 125p, and topped up twice subsequently, so my initial investment has increased 5.3x. Passable. The business has never given me cause for concern, apart from feeling dull and pedestrian. On reflection I will settle for that, and will continue to hold.
Richard
I'll take dull, pedestrian, slowly rising and paying a bit out on the way any day of the week! Thank Richard!
Mamy thanks indeed Paul for taking prelim look at Bodycote (LON:BOY) . I too have been watching this for a bit and scratching my head as to why this was semeingly too cheap. I don't hold (yet). I'd welcome any sceptical views.
I came across this headline from 13 March which holders of JD or FRAS might be interested in: "Adidas posts first loss in 30 years and warns on US"
It "warned sales in North America would fall again as sportswear retailers in the U.S. struggle with high inventories."
Source: https://www.reuters.com/busine...
Yet Adidas shares go up?
And JD Sports Fashion (LON:JD.) down 6%
Must be l&g selling down Nestle to buy into Adidas due to their superior ESG agneda !
Adidas has been battling to right itself after it cut ties with Kanye West in October 2022, suspending sales of the highly profitable Yeezy sneaker line.
Seems a bit odd about the US, Dick's Sporting Goods (NYQ:DKS) which sells similar products, had a really good last quarter and the shares are well up.
Costain (LON:COST) have been named by Net Zero Teesside Power (NZT Power) and the Northern Endurance Partnership (NEP) joint ventures, as one of nine specialist partners for engineering, procurement, and construction contracts with a combined value of around £4bn.
Costain's involvement is to oversee and manage the engineering procurement and construction of the onshore CO2 gathering system and associated utilities serving the East Coast Cluster. The contracts are subject to the receipt of regulatory clearances and final investment decisions (FID) being taken in September 2024 or earlier.
They have a foot in the door, having completed the front end design, so let’s hope the get a decent slice of the action when the contracts are let.
https://www.londonstockexchang...
Costain (LON:COST) : more PR release than anything.... an RCS release...
Plus "one of nine specialist partners"...!
Even taking £4bn project value equally over 9, and probably over several years....
and then "subject to regulatory clearances and final investment decisions to be made in Sep24...!
My two cents that it is showing an example of the strategic path that Costain is following. But this is definitely not a material contract... yet...
Scottish Mortgage Investment Trust (LON:SMT) is to treble share buybacks to at least £1bn over the next two years as the board of the Baillie Gifford global growth trust makes a ‘concerted’ effort to reduce its damaging double-digit discount.
https://citywire.com/investmen...
Good morning Paul,
Thanks for commenting on CAPD. Much appreciated.
I agree with Revs8 that the sample testing business is a credible growth story and seems to be developing nicely. I would add that the company has successfully begun to diversify geographically into developed economies which should improve its longer-term quality of earnings.
I have been invested in CAPD for about 18 months and have been surprised by the extent to which it has been overlooked by the market. It seems well-managed, has plans for growth and is a solid financial performer with a clear commitment to disciplined capital allocation.
Peter Stokes, the CEO, led a good presentation of the results on the London Stock Exchange online platform yesterday morning which I enjoyed watching.
Capital (LON:CAPD)
Feels like the market regards this as a serial disappointment. Never quite manages to deliver the promise whether that be through contract/delivery risk (Centamin always seemed to be a worry but looks fine now), geopolitical risk (unstable African exposure - currently Sudan, Mali and the coups), or Investment risk with the exchange of revenue from drilling for equity (to get the drill contracts?) not paying back.
Hopefully that is all changing now with the focus shifted to Tier One mining projects (possibly lower margin?), in more stable jurisdictions (US latest) and encompassing more of their offer (Chrysos assay, drill and heavy transport). 2 of the 3 main investments are now listed, though with mixed performance, and they can hopefully exit these profitability in due course.
All these things seem to take longer to achieve than the patience of the average investor lasts. Sp struggling to regain annual highs, divi while we wait mediocre compared with what's available elsewhere. I like what they are doing but this seems to fall between stools. Neither an out and out growth share more an income share.
Perhaps if Predictive gets bought out by a major this year at a decent price, Sudan/Mali situation with Perseus improves and the Assay labs start making contribution things will look more promising later in the year. Fingers crossed and still holding, though conviction waning....
Capital (LON:CAPD)
*Neither growth NOR income
Can't edit on mobile, apologies
Tip: If you turn your mobile to landscape view you get the edit facility for the first hour as on a pc.
Not on my Motorola. Tried previously. Thanks anyway.
When I asked why I couldn't see the Edit Pencil in landscape on my mobile phone, I got this reply:
"Having investigated this, the edit icon will appear at resolutions greater than 768 pixels wide. This works for a large number of mobiles (in Landscape) however unfortunately your iPhone SE has maximum dimensions of 667 pixels, so it doesn't appear."
Capital (LON:CAPD)
Fundamentally disagree with your "clear commitment to disciplined capital allocation."
This is the problem and why big PI's and II's do not get involved. Both would love to invest in a "picks and shovels" gold operation but this is precisely what is not offered. If you buy in here you get exposure to a big monetary number of risky gold shares in the @ $50m investment portfolio. Just look at the impact it continues to have on the P&L.
They invested over $9m into the portfolio during 2023 when they had huge capital commitments.
Really not sure shareholders are a primary concern at Capital (LON:CAPD) .
Personally think this is a lifestyle company run for the directors.
BWDIK.
I don't understand what Capital (LON:CAPD) is trying to do. Is it an investment vehicle, or is it a miner provider? Why is there a big investment portfolio sitting inside the company? Very odd business model. I hold but will probably exit after the current gold rally as I don't understand the model. Can anyone explain?
Re Paul Hills note below and the alarming disparity to US valuations. Its about time our leaders got back to backing business and entrepreneurs, like proper backing rather than half hearted measurers and pandering to the latest pressure group, wokeness or PC speak. Its like they all gathered around whilst watching the iceberg melt away. There is still a blob of ice on the surface but the damage is done below the water line and meanwhile nothing changes.
Bodycote (LON:BOY)
£1.2bn Mkt Cap, 2023 results and £60m share buyback announced today. Solid growing company with improving margins. I hold.
With more than 165 accredited facilities in 22 countries, Bodycote is the world's largest provider of thermal processing services. Through Specialist Technologies and classical heat treatment, Bodycote improves the properties of metals and alloys, extending the life of vital components for a wide range of industries, including aerospace, defence, automotive, power generation, medical, oil & gas, construction, and transportation.
Bodycote plc
Full year results for year ended 31 December 2023
"Another year of strong growth and margin progression"
Financial summary
2023
2022
Growth Constant
Currency
Growth
Revenue
£802.5
m
£743.6
m
8%
8%
Headline operating profit1
£127.6
m
£112.2
m
17%
14%
Headline operating margin1
15.9
%
15.1
%
+80 bps
Headline operating margin excluding surcharges1
17.3
%
16.1
%
+120bps
Free cash flow1
£122.5
m
£84.0
m
46%
Basic headline earnings per share1,2
48.4
p
42.7
p
13%
Full year ordinary dividend per share
22.7
p
21.3
p
7%
Return on capital employed1
14.8
%
13.3
%
+150 bps
Additional statutory measures
2023
2022
Operating profit
£119.2
m
£102.0
m
Operating margin
14.9
%
13.7
%
Profit after tax
£86.8
m
£74.3
m
Net cash from operating activities
£191.6
m
£142.9
m
Basic earnings per share
45.1
p
38.6
p
Tclarke (LON:CTO) FY results out & show record revenue but margins thinner than their high tech electrical wire
What gets me is that they look to be a company run for the management
Todays results show that compensation for ‘key management’ was £6m
The company only then made an operating profit pre tax of £7.6m
Thanks AstonGirl. That's a great point about executive remuneration, which many of us here have been very unhappy about for 20+ years, yet it continues escalating. Whilst the focus in the media is often on the pay of top FTSE 100 bosses, a fund manager interview I heard recently said that this is only a pin-prick in relation to the huge profits of those groups.
Whereas you rightly point out that at small caps, the cost of the Board can be a very high percentage of the profit before their remuneration. And what about all the companies that rack up losses every year, yet the Board cheerfully draw generous salaries, bonuses, and even share options! What happened to "sweat equity", where people work for next-to-nothing but are rewarded at a later stage from creating shareholder value?
Unfortunately, there is a managerial class who are fleecing us on a daily basis! No wonder people are becoming increasingly dejected about UK small caps (which actually excites me, as it means capitulation throws irrational bargains at me to profit from!). That's the plan anyway, but like all plans, it doesn't always work! ;-)
Regards, Paul.
The latest example of corporate largesse I noticed was that shareholders in RELX are expected to pay for the preparation of the personal tax returns of the directors.
Considering their share price gain I do not mind
Good grief, I've just looked up the Director remuneration for marginally profitable electrical contractor Tclarke (LON:CTO) - it's actually quite horrendous that they can get away with this - from the latest (2022) Annual Report -
I met CEO Mark Lawrence on a site visit a few years ago, and he's a nice enough fella, pretty similar to many of the other blokes you see on a building site. I didn't realise he was the CEO until about halfway through the visit. He must smile at himself in the mirror every day, thinking about how on earth he managed to earn £1.65m in 2022.
Shareholders in CTO are being robbed in broad daylight, in my opinion. A private owner would probably only pay the board one tenth of these salaries.
Really shocking.
Wow - good spot Paul and Astongirl. I won’t be investing in Tclarke (LON:CTO) anytime soon (ever). I’m all for appropriately incentivised pay structures but what on earth are their RemCom doing allowing that sort of remuneration for the size of the business? That’s the sort of comp I might expect to see in a business generating 20* the level of profits.
Who is voting for this at the AGM too?
Hi Paul
Tclarke (LON:CTO) - another point to bear in mind with such outrageous director remuneration is the effect on the guys & gals at the coal face......... Who will be able to see the huge sums being taken away by management - not good for morale & team building
….and let’s not forget the Nov 22 RNS that told us that £40m of revenue was being ‘reprogrammed’ into 2023. Wouldn’t have got close to the £500m target last year without it. In my book, they are a deceitful bunch as well as aggregiously overpaid.
Although I would tend to agree with the criticism on this thread of over generous payments to management generally, I'm not so convinced in the case of Clarke (CTO). If you look at the £6m it is spread between about 15 people, iirc, and the majority of the payment is bonus payment with reasonably demanding targets achieved.
This was my immediate take on today's results, fwliw.
The margins in electrical contracting have always seemed to me to be about the same as those in civil engineering contracting which I worked in for decades.
The reason behind my optimism about Clarke's future performance (and I'm not normally optimistic) might be partly explained by the following:-
Their resilience in extremely tough times was well demonstrated about ten years ago, when several severe industry wide factors, and one unique to Clarke, really tested them.
Changing suppliers and subcontractors in the middle of a job, as explained in the November T/U is a huge step which shows real determination to keep to a deadline. It also shows real expertise in running contracts from the top to the bottom of the organisation. In the same T/U they revealed that they had settled accounts quickly and early on some contracts where presumably they were not confident of their client's solvency, which no doubt reduced their income for the year, but was, imo, a wise move.
Thinking this morning about the contracts I ran, or priced and ran, or did major subcontracts on, a few stood out as exceptionally profitable. The five contracts which spring first to mind as highly and exceptionally profitable fell into two categories. Two were projects where on time completion was of such paramount importance that the client would throw money at you for overcoming programme impediments, such as unexpected ground conditions or major design changes, as they were encountered. The others were projects where as the contractor I understood such matters as the soil conditions far better at time of tender than the multiple design engineers and consultants involved over a prolonged period before issue of tenders.
The worldwide race to build data centres strikes me as fitting the first category, where timely completion no matter what, is likely to be well rewarded, and the "clever building" stuff at which Clarke are clearly very accomplished seems to me to fit the second category. Both these categories of work are burgeoning in Clarke's order book. So my expectation is that the run of the mill work, which is still a substantial but reducing proportion of the workload, will continue to average out at or around the 3% margin, but the margins on the two categories mentioned earlier in this paragraph will considerably exceed the norm and drag up the average to well in excess of 3%.
Hope so anyway as a shareholder!
I made a note on Tclarke (LON:CTO) on 6/6/23;
"Presented at mello then locked shareholders out of a fundraise. Avoid."
That would have been something I read in the comments here so it certainly does look like it's very much management before shareholders.
A double avoid.
Volution (LON:FAN) excellent RNS today, IMHO.
All financials show as positive
EPS slightly ahead of consensus.
Strong performance from UK residential despite weakness in new builds, what will happen when new builds turn the corner?
Significant new product launches in first six months.
On a slow day, is this one a winner?
Very nice summary, thanks GloucesterBob - you've motivated me to look at Volution (LON:FAN) next!
Fully agree - It's on reasonable PEG & PE ratios with a high ROIC, at what has to be the low part of the cycle. Have to think that the regulatory tailwind will only increase in future too. I have this one as a secular growth stock on a low value - one for the next 10 years. As you might guess I hold of course so am biased.
Hi Paul. Thanks for covering Capital (LON:CAPD) (I hold). The big attraction for me is the growth of MSALABS which appears to be a technology that will save miners a fortune in testing samples (which is a compulsory part of the operation)(they are investing in building testing labs for the larger miners). They don’t own the IP (it’s licensed and they claim a strong partnership with the IP owner) but once they build a lab there is an obvious locked in customer.
The core business providing the other mining services also appears to be robust but it is the labs that makes me believe there is a growth story unfolding here.
My morning smallcap tweet: Blue-sky burnout
Graft Polymer (UK) (LON:GPL) Tclarke (LON:CTO) Bank of Georgia (LON:BGEO) Digital 9 Infrastructure (LON:DGI9) Nexxen International (LON:NEXN) Biome Technologies (LON:BIOM) Sareum Holdings (LON:SAR) R8 Capital Investments (LON:MODE)
◄Graft Polymer (GPL)► a new NED lends £100k at 10% pcm (214% PA). Convertible "at a price and time agreed between the lenders and the Company". Two NEDs resign. Very difficult trading conditions making cash extremely constrained. [SP=0.5 Cap=1m]
◄TClarke (CTO)► FY-Dec rev £491m, missing guidance of £500m+. Outlook bullish. [SP=128.49 Cap=68m]
◄Bank of Georgia (BGEO)► further GEL 100m (c.£30m) buyback. [SP=5180 Cap=2372m]
◄Digital 9 Infrastructure (DGI9)► Verne Global sale completes, avoiding cash crisis. [SP=23.5 Cap=203m]. I hold.
◄Nexxen (NEXN)► to seek authorisation from creditors for an additional $50m buyback. [SP=189 Cap=332m]
◄Biome Technologies (BIOM)► £536k order for legacy Stanelco div. Completes this FY and "will contribute towards our Group expectations". [SP=95.5 Cap=4m]
◄Sareum (SAR)► get EU patent that "safeguards SDC‐1801, its medical applications particularly in the treatment of autoimmune diseases, and certain methods of synthesis". [SP=23.9 Cap=17m]
◄R8 Capital Investments (MODE)► acquisition of Redwood Financial Partners delayed to end Aug. [SP=2.2 Cap=2m]
Avtandil Namicheishvili, the deputy CEO at Georgia Capital (LON:CGEO) sold 1.3 million in shares yesterday. I recognise he still holds a lot more than this (around 10million) so I'm not too concerned, everyone needs a bit of cash from time to time. However, it does seem an odd time to sell, with the stark disparity between the valuation at Bank of Georgia (LON:BGEO). Be interested to see if it opens lower today or if the market brushes this off.
The directors at Georgia Capital (LON:CGEO) use the shares as part of their remuneration. They sell from time to time - this has been consistent through time. Same as Bank of Georgia (LON:BGEO) and has never signalled toppy valuations. Just seems to be something they do as far as I can see.
Thanks David, I'm a new holder to the share, jumping on board in the last month in part thanks to the investment case shared by yourself and others. Always good to get reassurance from those who have longer holds and more knowledge around the companies history.
To give you an example the Deputy CEO at Bank of Georgia (LON:BGEO) sold 1286 shares at £25.75 back in Nov 22 - 18 months later the shares are double. There are quite a few of these examples over the last 5-10 years with both these companies. So whilst director sales are nominally interesting I personally don’t pay much attention day to day. If it were most or all of their holding it would make me think more carefully mind as that might signal a change.
He probably got the shares for nothing anyway. I see there are a lot free Bank of Georgia (LON:BGEO) shares being given to directors. These will be treated like bonuses.
It’s part of the compensation structure Rusty. All banks are pretty much obligated to give a large portion of senior risk takers bonus in equity these days irrespective of whether they want to. So less cash more equity - usually post vesting execs then cash some in (either to pay the tax associated or just to utilise the cash).
That’s another reason why I don’t pay much attention to relatively small day to day director sales.
According to Schroders, almost every UK sector currently trades at a material discount compared to its US peer. The median being 36%.
Sure, America's economy is more dynamic & innovative than Britain's. Yet equally, the valuation gap still looks far too extreme.
Unfortunately investors are reducing there UK holdings and buying overseas. International investors are giving the UK a cold shoulder. The 36% could move over 40%. There will be further bargain basement acquit ions but what are the potential triggers to change sentiment? Maybe a change in Government?
Hi Steven
Why do you believe a change in Government might materially change this?
I ask given that:
1. there is little blue-water between Labour and Tory in many respects in terms of economic consensus; and
2. the competitive position of London as a financial centre and listing venue isn’t high up on Labour’s priorities; and that
3. Labour is likely to tweak their fiscal “rules” to justify increased deficit-financed spending with a shifting of the tax burden towards taxing capital which is neither investor nor capital-market friendly (nobody really believes they won’t increase CGT rates and nobody apart from Rachel Reeves believes this will sustainably produce greater revenue medium term).
Of course it would be helpful to know more of Labour’s plans, but that’s not possible as either:
1. they’re refusing to say what they’ve already decided; or
2. more concerningly they don’t have a strategy or plan agreed; or
3. their unspoken plans are already hitting the sharp rocks of reality due to ill conception - e.g. insights gained from Rachel Reeves mistaken belief that NIC funded the NHS or indeed entirely funded the cost of the State pension while in the world of reality it does neither
In sort the discount will only be narrowed when London is viewed as a place for companies to have a listing, raise capital and do business. This requires government policies to promote these aims and more generally foster a business friendly environment. Sadly we continue to move away from that and a Labour government will undermine the position of London further.
The major problem facing the UK is the lack of growth. Who ever gets in after the next general elections is going to have to tackle the productivity issue. The Conservatives have failed It maybe wishful thinking Labour will be any different. But a new Government has an opportunity in its first year to give some harsh medicine and implement radical change.
Growth solves all sorts of economic ills.
But we need to look at the UK growth record in its proper context of the experience of other comparable countries . . . And the UK growth story compares favourably since 2008/9 or the onset of Covid.
The trouble is most comparable economies have been constrained by low growth, the exception being the US.
So the question you really need to ask is what would Labour have to do to actively promote growth? and in the UK that would also need to address underlying inhibitors of low investment and productivity gains. In respect of those increased taxation of investors or companies won’t be helpful. I would also question however well-intentioned government action is it often fails to translate into the desired outcomes. Perhaps best create the conditions where investment pays and wealth and job creation are its outflows. the idea that government is a better director investor than the market economy and businesses is misguided to the point of being fanciful.
So the question you really need to ask is what would Labour have to do to actively promote growth?
Well, the obvious answer is rejoin the EU! Easier said than done, and the LP aren't going move quickly on that. But they don't have the depth of divison on the issue that the Tories do, So small moves towards a more rational relationship with the EU are likely, and moves to ease trade as far as possible from the outside. Doing what's needed, and rejoining, will not happen quickly, but steps can be taken to create conditions for future remembership and ease trade costs in the meantime.
I couldn’t agree more with all these views and this is the only solution to revive the LSE.
with a shifting of the tax burden towards taxing capital which is neither investor nor capital-market friendly
i wander if this is good for the economy though and that could be could for shares ?- tax the rich with idle funds sat there not doing much. If we say the alternative is taxing your average person who then have less to spend - i wanderf waht is ten lesser evil. Some might say that would stifle investment but there doesnt seem to be any shortage of funds to invest in capoital stuff in then uk.
Three things to promote growth.
1 make the rest of the country's public transport equal to Londons
Lots of people just cannot get to a good job and employers choose london because they know there are a lot of potential employees who can get ti that job.
2 make houses cheaper much cheaper.
It distorts the economy. Lots of money goes into housing when it shouldgo into building businesses. Because housing is seen as a 1 way bet
3 adult education
Help people over the age of 18 to get new skills. You don't stop learning new stuff when you start work just don't tend to learn new stuff outside your current job.
As neither party are proposing any of that and it is al pretty obvious i don't see this as political (outside making houses cheaper)
Getting political I have a lot of time for Gary stephensons views on tax (tax non salary income and assets more than salary income). Though I suspect they may not be too popular here and it would hit me too and again is not proposed by any of the main parties.
Getting political I have a lot of time for Gary stephensons views on tax (tax non salary income and assets more than salary income). Though I suspect they may not be too popular here and it would hit me too and again is not proposed by any of the main parties.
Wrong forum, wrong audience.
Hi Snazzy
With respect to a shift of taxation onto returns from capital (gains and dividends) and corporate profits is highly relevant to all investors, potentially impacts how companies might raise funding, and the operation of our markets.
In this regard the ideological drivers for such changes is less important it’s the impacts and medium-term outcomes.
I suspect Labour truly believe you can increase can taxes rates without affecting the economy or in time the tax “take”, which isn’t how the world works. In reality increased taxation means people spend less money and consume and invest less.
Given a few years Labour will find that while it’s possible to tax something to death they’re unable to tax the UK into prosperity.
There will be consequences for investors, companies needing funding and the broader economy.
Clearly, all welcome lower taxes. But taxation is what funds the essential services and infrastructure that allow growth - transport infrastructure, health and education, to provide a healthy educated workforce, defence .....One of the reasons growth has been so poor, and the Tories themselves have had to raise taxation to it's highest level since the war is the clamp down on growth that resulted from the Cameron/Osborne austerity years.
Those are good points to promote growth Andrew. I would also add making energy cheaper as a major way to promote growth. If the government had a rational strategy to accelerate the transition to renewable energy whilst exploiting natural gas and oil until this transition is further advanced, then that would help growth. Cheaper energy would also be electorally popular. One reason US companies do so well is because some forms of energy are cheaper over there. I speak as a subscriber to a wind farm in Ayrshire which could have been made ready to produce green electricity months ago but can not start up because a lack of strategic planning means that the local electricity grid does not have sufficient capacity to distribute the electricity.
There will be further bargain basement acquit ions but what are the potential triggers to change sentiment? Maybe a change in Government?
Recently I have been thinking the very same thing, whilst I would prefer a conservative government (this lot are not proper Tories) a change to Labour could be the catalyst needed to change sentiment, because apparently the undervaluation of the UK Markets started with Brexit. And as we all know Cameron called for the Referendum and apparently Boris got Brexit done ? So maybe the conservatives just need to be punished to change the sentiment towards UK Equities.
For nearly ten years it has been so easy to drop out of benchmark, ride currency weakness and generate “alpha” overseas. Don’t underestimate currencies role. Despite an election this year, which the conservatives are expected to lose to a moderate labour leader, this “could” compare well to both Europe and US. A relatively stable UK might become a positive and the scale of money returning home could help feed this. To me it just feels like the UK could weather the storm of a weaker market backdrop quite well - just like 2022… but all just guess work really… happy holder of undervalued assets.
I’m a happy buyer of undervalued businesses .
Not sure why I would want to buy an overvalued business .
All you have to find is a good business .
Not sure what the problem is .
Agreed so long as you’re not buying ex-growth.
we have plenty if innovative growth companies but the problem that fewer of these are listed
Hi planetx,
You need to find a business that grows year after year and there are only a handful listed here (especially in small caps).
Serious liquidity issues and the fall of the currency also discourage foreign investments. Don’t forget that the cable rate was over 1.50 before Brexit.
I have never seen so many cheap companies in all my investing career (20 plus years) aside from small moments of time caused by external shocks. It's always darkest before the dawn...
Paul thanks for sharing. Out of interest was there any comment about a discount to our European neighbours? Just curious
May look cheap but many UK stocks are carrying a lot of debt, whilst many US stocks don't have any debt and have plenty of cash. The spreads are a lot wider on UK shares, as well.
Thanks Paul Hil I'd be interested to read the original article or paper this came from, do you have a link?
My main reflection is that the price itself is not a problem unless you need to sell. I am about 10 years out from retirement, so buying rather than selling. Low valuations are good.
BUT if the reason for the low valuations is that the market believes growth prospects for the companies in these sectors are poor, and if the market is right, then we should be worried. For what it's worth, I agree with you that there is a gap with the US that would be justified and that it's probably less than 36%. But it's striking how many companies I own are buying back their shares rather than re-investing in the business. That may improve EPS but it's not a sign of confidence in the future. Much better if they were using the cash to innovate or build market share.
Here you go guys
https://www.schroders.com/en/g...
So it because of Brexit? Shares in UK are even cheaper, if you take into account the fall in the £. But then investors in the UK have lost because of the fall in the UK, although it has recovered somewhat recently.
It is interesting that the discounts are larger in low growth sectors. The reason given for the discount is that it reflects better growth potential, this does not seem to be true.