Small Cap Value Report (Fri 16 Feb 2024) - GLE, POS, XPP

Good morning from Paul!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Paul's 2023 share ideas, with live prices.
New SCVR summary spreadsheet from July 2023 to date, updated at weekends (very useful quick reference tool, search for ticker using CTRL+F). Hover over cell for pop-up notes.
Frozen SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Quiet for news again today, so I'll do a few catch up items -
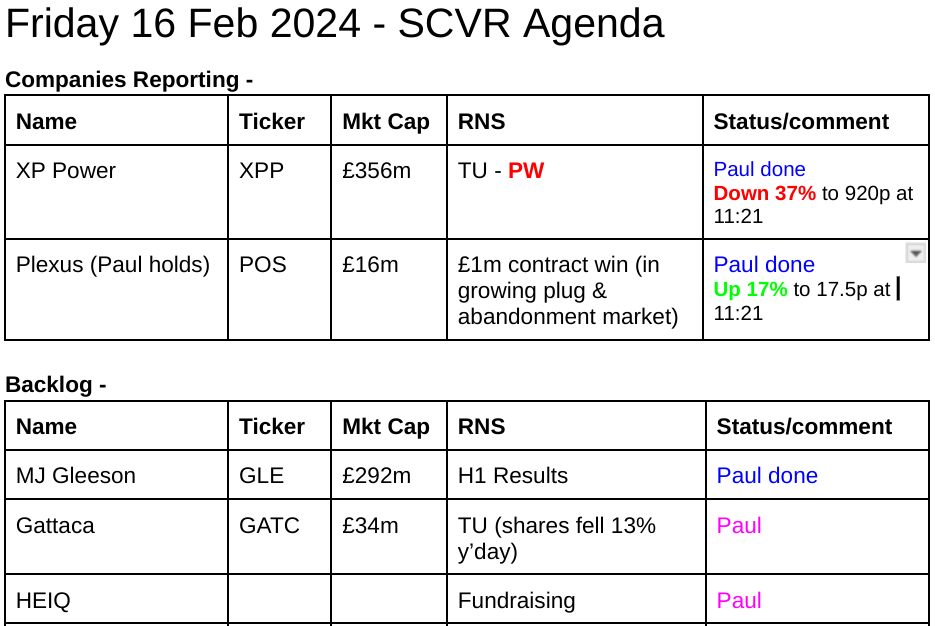
Other mid-morning movers (with news) -
Fiske (LON:FKE) - up 29% to 60p (£7m) - Interims from this tiny wealth mgt company. £429k PBT in H1, much improved on LY. Strong bal sheet, with £4.1m net cash. Upbeat commentary. Investment in “Euroclear”. This actually looks quite interesting, worth a closer look for microcap investors.
Audioboom (LON:BOOM) - up 8% to 258p (£42m) - Non-regulatory RNS Reach, trumpets growth in audience numbers for its podcasts. 38.6m monthly downloads in Jan 2024, up 9% on Q4 2023 average. See our archive for the negatives too, including expensive mistakes made on legacy contracts, and mgt greed.
Summaries
MJ GLEESON (LON:GLE) - down 1% to 496p (£289m) - H1 Results - Paul - AMBER/GREEN
Interim results to Dec 2023 are poor, as expected, but trading is in line with recently lowered expectations FY 6/2024. Not the amazing bargain it was a year ago, but still good value in my opinion. Share price is 100% backed by tangible net assets. As with other housebuilders, the outlook comments suggest the housing market is beginning to recover.
Plexus Holdings (LON:POS) (Paul holds) - 15p (pre-market) £16m - £1m contract win - Paul - GREEN
I'm biased, as this is by far my largest personal portfolio position, but hopefully I'm still being objective, or trying to anyway. A £1m contract win announcement today is significant as it's in the plug & abandonment area, which Plexus has been saying offers plenty of opportunities in the N.Sea especially. Contract wins need to keep flowing, but this is a positive step forward I think. Risk of dilution has greatly reduced, given $5.2m cash received from SLB recently for a perpetual licence for use in non-core areas. Higher risk, so not for widows or orphans.
XP Power (LON:XPP) - down 37% to 950p (at 11:57) - £224m - Trading Update (PW) - Paul - BLACK (profit warning flag) - AMBER/RED on fundamentals
This seems quite a substantial drop in 2024 earnings, but we're not told directly, and no broker notes are available. I've been able to join the dots, and estimate that 2024 EPS could come in as low as 32p, down two thirds on previous forecasts. I don't like the look of this, show am shifting down from amber to AMBER/RED.
Paul’s Section:
MJ GLEESON (LON:GLE)
Down 1% y'day to 496p (£289m) - H1 Results - Paul - AMBER/GREEN
Results for the half year ended 31 December 2023
"The results for the half year reflect a robust performance given conditions in the housing market during 2023. Gleeson Homes entered the second half of the year with a strong forward order book and we are seeing encouraging signs of recovery in reservation rates.
We’ve reviewed this affordable housing builder many times in recent years. The big discount to NTAV, and more defensive characteristics of building low cost housing, persuaded me to add Gleesons to my top 20 share ideas for 2023. Despite considerably uncertainty at the time, this idea is now looking good at +44% since the start of 2023, with our entry price being luckily at the 5-year low.
Despite a strong rise in share price, the 5-year chart is making me wonder if this could be the early stages of a new bull run? Particularly as GLE has such a strong balance sheet (like most other housebuilders) that it didn’t need to issue fresh equity either during the pandemic, or in the energy/cost of living/Truss/interest rates crises.
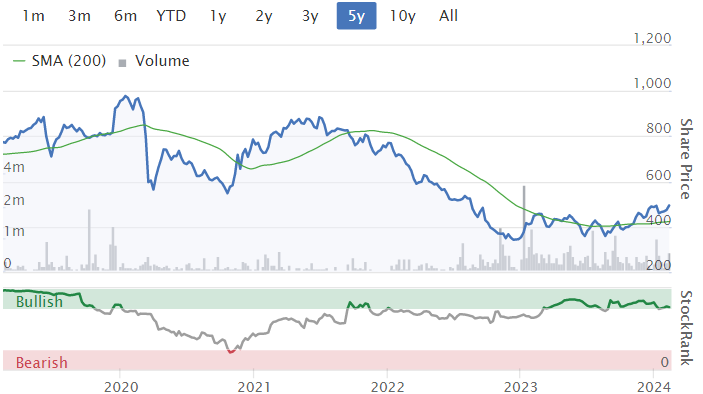
GLE did however blot its copy book recently, with a profit warning which I reviewed here on 9 Jan 2024, Liberum slashed forecast EPS for FY 6/2024 by 22% and by 26% for FY 6/2025, yet amazingly this didn’t seem to trouble the market much, if at all.
GLE did have a big discount to NTAV, but that has now been eradicated by the share price rise, and the StockReport shows shares now trading at about par with NTAV - which is actually still quite attractive, given that it seems likely we’re entering the start of an improvement in housing market transactions again, and household nominal incomes are in some cases 15-20% higher than they were 2 years ago. Which means that more people can afford to, and probably are regaining the confidence to think about buying an affordable new starter home.
H1 results (Dec 2023), key numbers -
Revenue down 11.4% to £151.5m
Profit before tax down 55% to £7.2m
Basic EPS down 56% to 9.6p
H1 divi down 20% to 4.0p
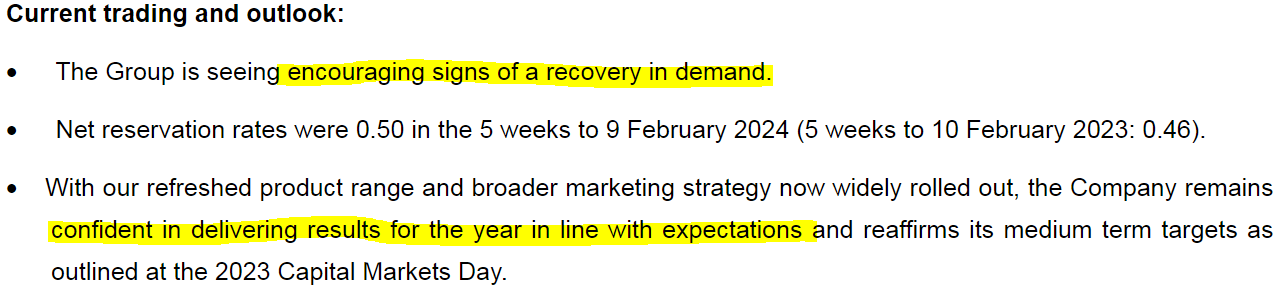
Broker consensus seems to be 33.7p EPS for FY 6/2024, implying a significant H2 bias, given that H1 was only 9.6p EPS.
At 496p/ share, the PER is 14.7x, which isn’t cheap, but we could be looking at earnings being at or near the low point in the cycle, but nobody knows for sure. Hence PERs do tend to look highish at a cyclical low for earnings.
Balance sheet - as is the sector norm at the moment, the balance sheet is ludicrously strong, and hardly has any gearing. Net debt was only £18.7m.
NAV of £287m becomes NTAV of £287m, because there are no intangible assets on the balance sheet. This is almost identical to the £289m market cap, so owning shares in GLE means it’s fully asset-backed. The big asset being inventories of £358m - being houses under construction, plus land, most of which should turn into cash within a reasonable timescale, likely to produce a profit on top of the book cost.
Paul’s opinion - I think GLE still looks very good risk:reward. Buyers in early 2023 have made a very nice profit to date, which they deserve for taking a perceived risk when everyone else was in panic mode, but they were actually buying pound notes for 70p! (the discount to NTAV at the time).
I think the easy money has maybe been made now, but with the housing market cycle now clearly on an improving trend, which we’re hearing from everyone in the sector, I think picking up GLE shares at par with NTAV still looks an attractive option, for more patient investors maybe?
I had a wobble when the profit warning hit on 9/1/2024, dipping to amber to be on the safe side. However, skimming these latest numbers & narrative, it strikes me as reassuring. Also I think the desperate need for affordable housing, and likely stimulus measures from whoever is running the country going forwards, combined with inflation now being down to 4% and lower interest rates seeming quite likely, which is good for housing affordability, I think I’ll move up a notch to AMBER/GREEN. Not as cheap as it was, but this still looks an attractive, and I think pretty safe share to consider for further, deeper research. The sector has had a very nice rebound in the last 3 months, so I don’t know what immediate upside there might be, or whether these shares might need to consolidate for a while? That’s more a consideration for traders, than for my reviews of the fundamentals here.
Plexus Holdings (LON:POS) (Paul holds)
15p (pre-market) £16m - £1m contract win - Paul - GREEN
As mentioned before, this is by far my largest personal portfolio holding, so obviously that makes me heavily biased (but hopefully still objective).
Good news to have a decent-sized £1m+ contract win announced today. Note that revenues in recent years have only been c.£2m pa, so a £1m contract win today is quite material to the historical numbers.
I assume this is another rental + services deal, as it mentions the contract starting for 9 months from Q2 (calendar, I assume) 2024. The company has said before that contracts often expand once they start, as happened with the special contract which was initially announced as £5m, but soon grew to £8m (this was the trigger for me buying into POS shares last summer). So maybe this latest deal might also expand? Who knows, that's just me speculating.
Plexus have been saying for a while that they see big opportunities in plug & abandonment of expired oil/gas wells, a growing area, so I feel that today's news confirms & validates what it's being saying.
I don't fully understand how this contract links to the SLB deal, does anyone know?
"Exact™ Adjustable Wellheads and Centric Mudline Systems are part of the Plexus licence/collaboration agreement with SLB..."
Once again, this news reinforces my view that Plexus is proven tech, and the company is coming alive again, due to demand driven by methane leak becoming a big environmental issue, and also it seems Plexus is making progress in P&A.
All for £16m market cap, and with the cash situation sorted out, with only 5% dilution from the sale of treasury shares.
Management have protected small shareholders from what could easily have been ruinous dilution, using their own money.
There are useful research notes from Cavendish, available on Research Tree, for more information. Due to 2 large one-off deals, it is forecasting revenues to rise almost 10x in FY 6/2024, and after years of losses, a return to profit of £3.5m. That’s obviously why the shares have multibagged in the last year.
Not for widows & orphans that’s for sure, but the company is now in a very much better position today than it was a year ago, with net cash now.
Very volatile share price, indicates that the market doesn't really know how to value this share yet -
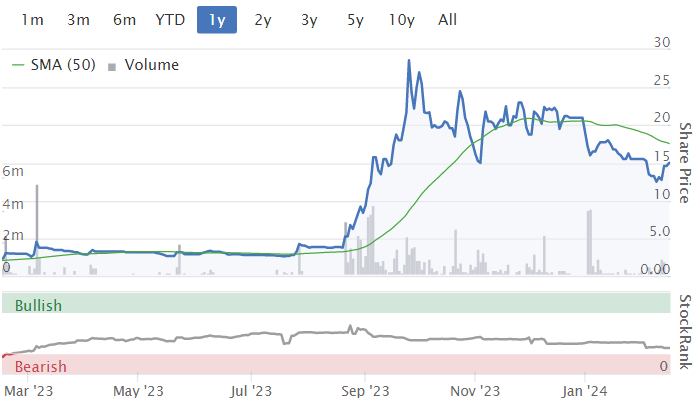
Low StockRank, as I would expect from a company that has generated multi-year losses. Although that should change when the (forecast to be £3.5m profit) FY 6/2024 results are published in the autumn.
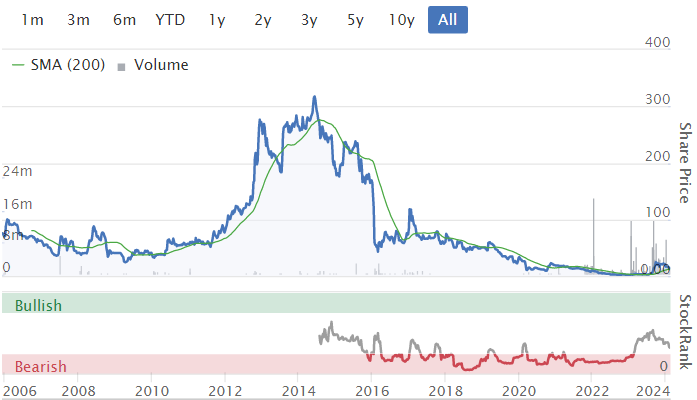
Zooming out, the company's heyday saw it valued at c.£300m (and with a similar number of shares in issue as today). I can remember writing about Plexus here c.10 years ago, but dropped coverage once industry & political headwinds saw oil & gas exploration in the N.Sea dry up in 2015-16 -
XP Power (LON:XPP)
Down 37% to 950p (at 11:57) - £224m - Trading Update (PW) - Paul - BLACK (profit warning flag) - AMBER/RED on fundamentals
XP Power, one of the world's leading developers and manufacturers of critical power control solutions for the Industrial Technology, Healthcare and Semiconductor Manufacturing Equipment sectors, provides an initial view of the outlook for the year ending 31 December 2024 ("2024" or "the year").
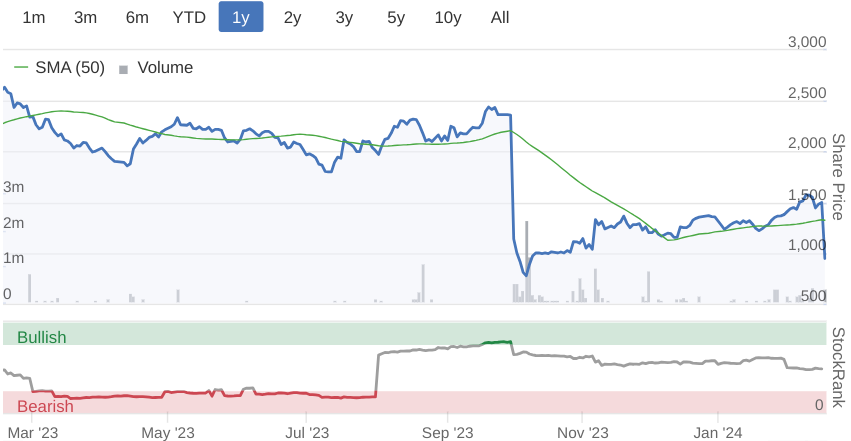
As you can see below on the 12-month chart, unfortunately XPP has today given up almost all the recovery in share price since its last bombshell profit warning just over 3 months ago. That necessitated an emergency equity fundraise with dilution of 20% additional shares being issued at a surprisingly generous price of 1150p - indicating good support from institutions. That was part of a package involving relaxed banking terms. Since then, investors had been giving the shares the benefit of the doubt.
However today’s latest bombshell once again shows that the share price chart is frequently not all-knowing, and we now know had detached from how the company was actually trading, which happens a lot. Otherwise we wouldn’t get vertical moves up or down in share prices.
Here’s today’s profit warning, for FY 12/2024 -
The Board has concluded that there is likely to be a shortfall in revenue in 2024, leaving the outlook for 2024 significantly below market expectations. This is based on recent order intake, revenue performance and discussions with customers, particularly within the Healthcare and Industrial Technology sectors, which confirm unusual, temporarily soft demand conditions and destocking. These softer trends have also emerged within our direct industry peers.
De-stocking again, that’s a theme we’re hearing from quite a lot of companies at the moment.
Cost-cutting - it says today that more savings have been identified.
Audit adjustments (costs) of £4m have been discovered which reduce 2023 profit.
Outlook -
In general, we expect the weakness we are currently seeing to be relatively short lived and indeed there have been some more encouraging signals from certain customers, especially for 2025, in recent weeks. The timing and speed of the recovery is hard to predict however. We expect 2024 to be significantly second half weighted with an improvement in trading as the year progresses.
Broker updates - infuriatingly, we don’t have access to any broker updates, so is often the case with some companies, private investors are left in the dark, whilst professionals and institutions can deal with better information than we have.
“Significantly below” market expectations covers a wide range of possibilities, so I have no way to quantify the impact of this latest profit warning.
We’ll just have to wait until broker consensus figures update next week, or if any readers have seen any broker updates today, perhaps you could kindly post a reader comment with the revised FY 12/2024 EPS forecasts?
Edison’s forecast (from 11/1/2024) was 2023 EPS of 111p (down 31% on 2022), and a further drop to 94p in 2024. We’re now told it will be “significantly below” that 94p level, so what’s everyone’s guess? 50p maybe? Worse?? Who knows, we haven’t been given enough information.
Therefore at present this share is impossible to value.
The market price crashing about 36% (at 12:51) and having made little attempt at rallying today, suggests to me that we’re probably looking at deep cuts to 2024 forecasts.
Liquidity - this section might allow me to work out the impact on profit -
The Group's cash generation toward the end of 2023 was ahead of expectations, as reflected in the year-end net debt position of £112.7m, and we expect this to continue in 2024 with net debt below our prior assumption.
A trading performance in line with the Board's expectations would leave net debt/EBITDA at 31 December 2024 at or below 2.5x versus a covenant limit of 3.5x. The Group maintains significant levels of liquidity.
If I assume that net debt might reduce to say £100m by end 2024, then this implies EBITDA of about £40m in 2024. The last Edison note forecasted £59.7m for FY 12/2024. This turned into £28.2m normalised PBT.
If I assume that the £30.5m difference between EBITDA and PBT remains the same, then this suggests adj PBT for 2024 would now be c.£10m. Take off 25% tax, that’s £7.5m PAT, which divided by 23.7m, turns into my estimate of only 32p EPS for 2024 - two thirds down on the existing forecast.
Paul’s opinion - XPP had a good long-term track record, so it’s perplexing to see it delivering now multiple profit warnings, and seemingly only limited visibility.
I need to see the full accounts, and updated broker forecasts, before being able to accurately assess this.
Looking back at the last fundraise, it was still expected to have quite heavy net debt afterwards. So with a further drop in profitability, gearing might rear its ugly head again as a problem, although the company says today it expects to stay within bank covenants . If another equity raise is expected, I’d be surprised if institutions were as generous on price as last time.
For this reason, two profit warnings, and potential problems with debt resurfacing, plus what looks like a deep reduction in 2024 forecasts, I’m going to shift us down from amber to AMBER/RED. But I’ll happily revise that once we have more information.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

94 comments
Hi, about a couple of weeks ago there was a wholesale company being discussed. Can anyone remind me what it was called?
Was it Kitwave KITW. It's done quite well this month.
Yep that's the one...many thanks Barry, much appreciated.
Was it Kitwave (LON:KITW) ? Results due on 27th February 2024.
will the XP Power (LON:XPP) update have a negative read across for Volex (LON:VLX) given they mentioned destocking in the healthcare and industrial sectors - where Volex also has exposure to?
will the XP Power (LON:XPP) update have a negative read across for Volex(LON:VLX) given they mentioned destocking in the healthcare and industrial sectors - where Volex also has exposure to?
Maybe. Who knows? But inventory destocking is hardly a new development. It’s been going on for about a year now, moving from sector to sector.
Re Volex (LON:VLX) any potential decrease in those sectors will likely be more than made up by increases in cabling for data centres due to AI
Bank of Georgia (LON:BGEO) 4000p seems to be a real psychological barrier. Every time it goes above it retreats just below. Wonder if the potential purchase of ArmeniaBank will finally give it the push it needs. Regional diversification particularly if earnings enhancing seems to be resonating well - good move up on the RNS yesterday
Bank of Georgia (LON:BGEO)
Yeah. Bit frustrating. However, the imminent full year results could do it. Noticed this:-
https://newsfile.refinitiv.com...
If you prorate the Q3 result uplift to group profits it gives full year group profits of GEL 1,410m - which is a sizable beat on the GEL 1,261m showing on the stock report. Highly simplistic but fingers crossed.
A.
Bank of Georgia (LON:BGEO) doesn’t make sense to me that a regional bank has a market cap about 15% of its own country’s GDP.
I am very much interested , and , If anyone knows , on how their Central Bank works (regulatory framework) , how they calculate NPL’s and how long it takes to take people that are behind to court etc etc etc.
I am asking as I have seen these massive market caps (that did not make financial sense) in relation to their GDP’s in the Eurozone. They all ended up have no value and had to be recapitalised for at least 3 times (every time the previous shareholders ended up worthless).
I am not claiming that this is the case here. I do not know how their Central Bank operates.
Thanks
Hi Yiannos
Bank of Georgia (LON:BGEO) - you need to look at own funds. They are very large compared to market cap, they have high liquidity, little to no exposure to long dated securities and a strong Tier 1 capital base. Capital adequacy is some 20%+ so low leverage.
CoR is important on the NPLs and this is also low. Their lending is conservative so annual CoR is 2.4%. This has been consistent for years - well over a decade since I’ve followed them and given the average roll off of loans will be circa 3 years this tells us it is broadly accurate over time.
If the Georgian economy tanks then clearly they will be impacted but no real signs of this from a macro perspective. Strong GDP growth and low inflation - oh how I wish that was the UK !!!!
They operate a lean machine with Cost to income of sub 30% as well.
This is a well run organisation that is a market leader in a strong economy that actively and properly manages its risk, in my opinion at least. I suspect diversification to Armenia could re-rate the shares - current valuation reflects the Georgia country risk but if Bank of Georgia (LON:BGEO) becomes a regional bank that discount could change.
Dividend yield is around 8% as well which is nice. To be fair I bought around 1000p maybe almost 10 years ago now (when adjusted for the Georgia Capital (LON:CGEO) spin off) so my dividend on cost is around 30% (just goes to show power of compound!!!)
TBC Bank (LON:TBCG) came out with 4th quater figures today. Slightly down but due to one off tax charge. On a similar rating to Bank of Georgia (LON:BGEO) Any views on this one?
I’ve briefly looked at TBC Bank (LON:TBCG) before and concluded it was also on a low rating but inferior to Bank of Georgia (LON:BGEO). As I also own Georgia Capital (LON:CGEO) there’s only so much country exposure I want so had no inclination to switch. So not one I know in any granular detail I’m afraid.
Thanks David, I hold all three and used to hold Georgia Healthcare before it was taken over by Georgia Capital (LON:CGEO) . Slightly put off by the indicated small decline in earnings for Bank of Georgia (LON:BGEO) for 2004 but as with Bloomsbury Publishing (LON:BMY) this may just be a case of not keeping up with events by analysts.
My mentor used to say that they break on the fourth attempt.
Accumulated a position in MicroSalt (LON:SALT) this morning after researching the business and watching their recent presentation on Investor Meet Company. Still early days but I grasp the potential in this product to significantly reduce sodium intake (a hot topic in human health / heart disease) while still providing the flavour profile of regular table salt. Patent protected process on a product that is gaining commercial traction with multinational food companies. Also like the fact it seemingly has benefits for food production since in simple terms it doesn't bounce off the food during application e.g. when producing crisps and nuts. Still early days and no forecasts available yet but I wanted to get in before too late. SP has more than doubled since this floated at the beginning of the month and up another 20% today - investors are catching on. Also has a strong management team / BOD with significant industry relevant experience in major food companies.
MicroSalt (LON:SALT) It’s worth ~£50m but after 8 years, sales ~ $500k and losses are mounting, with little cash left. Numerous low sodium salt competitors already exist. Risk from majority holder dumping stock. Add this to the very low Stocko rating I'd be very nervous about backing this on the basis of an Investor Meet Company presentation.
Thanks for your comments FM. In terms of sales - commercial traction is evident with commercial-volume orders now being placed by Fortune 500 pharmacy / food retailers with multiple other major US and multi-national food companies in various stages of commercial testing and negotiations. On the 'little cash left' point they raised £3.1M on admission to AIM on Feb 1 so this is not correct. The numerous low sodium salt competitors you mention are using potassium chloride or other added chemicals that leave a bitter aftertaste (key competitive advantage of MicroSalt). The low Stocko rating is irrelevant for a newly listed company like this - it has to be judged on other available info. There is even a warning at the top of the Stocko page saying security is newly listed and all data should be viewed as preliminary. I'm not backing this purely on the basis of the IMC presentation - that is one piece of useful content though that helps to form a picture. It's high risk for sure and not for everyone but willing to take the risk with a modest position for the potential upside.
Nice to see Natwest (LON:NWG) see some strong gains today after 2023 final results were released. I bought this in the midst of the Nigel Farage drama last year because I thought the valuation was looking ridiculously cheap and it was just shrot term drama. It still does look ridiculously cheap, but then so does every UK bank at the moment. Only a small part of the portfolio because I'm not going to pretend I understand how to properly value a UK bank.
Anyway, 26% dividend growth from last year and a 7%+ forecast dividend yield from NWG means its nice to hold regardless.
Natwest (LON:NWG) results must be why Lloyds Banking (LON:LLOY) up nearly 4%. On the other hand it is more likely to be the fact that I sold Lloyds Banking (LON:LLOY) this morning! It has been a poor performer over the last four years. Unfortunately purchased just before Covid hit and has never recovered or anywhere near. With the additional 'fly in the ointment' of Lloyds Banking (LON:LLOY) being the biggest player in motor finance (35% share reputedly) and the FCA investigation into Discretionary Commissions being a potentially big issue (particularly now Martin Lewis is hyping it up) decided time to exit. I expect the impact will not be in the Close Brothers (LON:CBG) meltdown category yesterday but I'm taking no chances. I'm with Terry Smith and steering clear of banks from now on!
Sold my Plexus Holdings (LON:POS) today for a 35% profit in only 5 days as not a serious holding for me and just something to keep interested in while my main portfolio treads water. But the reason for posting is to show that this site throws up these unknown companies giving solid reasoning why you should make further investigations. Appreciate the recent price rise was a bit underhand without any warning, but where else are you going to find this information for the small annual cost. This one transaction has paid for my yearly subscription and ongoing direct debit to ZANE. Thanks to Paul and Graham,
If your interested in what is happening in the Irish housebuilders market Glenveagh Properties (LON:GLV) (I hold) have a webcast Feb 28th (https://protect-eu.mimecast.c...
Hi Charles. Have clicked on your link for GLV webcast 28th Feb but it doesn't come up. Can you give the complete link please?
Glenveagh Properties (LON:GLV)
Looks as if it went wrong by putting brackets around. If you remove them you get
https//protect-eu.mimecast.com/s/j8wYCLvPxhRvGoGfqCy0q?domain=channel.royalcast.com
but don't know why that isn't clickable!
Ah - brackets put in by Stocko so perhaps it thinks it a dodgy site. I didn't get any warnings that I do sometimes from Firefox but you click and paste at your own risk!
Ah - cut out the middleman -
https://channel.royalcast.com/...
I'm amused by the the Dialight (DIA) RNS this morning. The ceo has been fired but it's dressed up to read that she woke up this morning and after mutual agreement with other Board members decided to leave the company immediately. Failed spin. Difficult to form a view as to her merits or otherwise.
I had an interesting phone call early this morning : Looks like over 75% of retail investors and small institutions are short on the DAX index against major investment institutions. This figure is not as high on the FTSE100 but seems to be getting there!
Other things being equal(no surprises in the Middle East) and it seems to me that there will be a big short squeeze sometime between now and early summer.
I do not hold any positions-not involved in leverage.
Yiannos
For the northern pig farmer in me can you explain what the implications are as my brain is grinding to a halt processing what this actually means .
I’m guessing its -
Your suggestion that retail and small institutions are sat on the sidelines with cash (not fully invested) that this money will get deployed as confidence grows and there will be a strong market as money comes back into shares .
Think that’s right isn’t it ?
I’m no economist and I didn’t read many books as I was too busy buying and selling stuff .
I believe that Yiannos1 is suggesting that more than being sat on the sidelines, retail and small institutions have large short positions which will presumably be carrying expensively and if markets can even inch higher then these shorts will need to cover...
Hi Planetx,
Couldn’t have explained it better than Cancun did.
They will destroy them as I have seen this before. Takes time to build-probably we will see after all new all time highs on the FTSE100 (early summer?sooner?who knows?)
Nothing to do with the small cap sector-hopefully it will follow.
All the best
You learn something new every day.
Never been into short positions and leverage, tried it a few times got my arse well and truly smacked and decided that hurt too much .
Decided I’ll stick to the dominatrix after that experience of a good caning .
Shorting needs to be managed super carefully planetx so you are wise not to unless you are well aware of what you are doing.
For example if you short something you think will go bust and it does you may still be required to close your position. There have been several cases where its costs people a ton of money to close out.
Or you could find a massive short squeeze such as the meme stocks in the US a couple of years ago. Heavily shorted these guys were taking massive losses closing out as the stocks raced ever higher.
So not a game for leverage and you have to be aware you can be caught offside with almost unlimited losses.
Even the famed Jim Chanos of Enron shorting fame fairly recently shut up shop unfortunately.I like listening to his opinions still, but it was admittedly a bad move betting against the cult of Musk.Okay, he is involved with the US market mostly, but he did make $100 million shorting Wirecard not too long ago though.I think his fund's AUM ended with barely $200 million down from $6 billion in 2008.
I am not involved-never have-never will-too much leverage-still good to know how they work and how they move the spot markets-after all that’s why they are called futures and options.
For example next week we have the results of NVIDIA (NSQ:NVDA) (I think on the 21st) and the options market suggests at least a 10% swing (either direction).
Sylvania Platinum (LON:SLP) announcement of uplift in mineral resource estimates.
Volspruit North JORC MRE (Indicated):
The MRE represents a 10% increase in the indicated tonnage from the previously reported MRE (October 2022) resulting from a more defined geological modelling exercise that has also resulted in the 4E grade improving by 4%; and o The addition of Rh estimates has improved the overall grade by approximately 7%.
Volspruit South JORC MRE (Inferred):
This MRE is the first one completed since the mineralised zones have been redefined and, as expected, it reports approximately a third of the tonnages at almost double the grades previously reported by Integrated Geological Solutions (Pty) Ltd ("IGS") in 2012.
A positive development, given the recent SP movement. I hold
Sylvania Platinum (LON:SLP) looks too cheap but don't forget the political risk, it is in S. Africa and could still go lower.
Tui TUI AG (LON:TUI)
On Tuesday 13 Feb Tui shareholders voted in favour of delisting from LSE and only have one listing in Frankfurt.
Does anyone know what happens to existing shareholders shares, do they get equivalent shares in euros quoted on the Frankfurt stock exchange or does one have to sell one’s shares before delisting in June 24?
If your broker offers european listed shares, i would assume they would deal with the transfer process automatically for you.I know Jarvis Securities (LON:JIM) don't for example.But i'd be surprised if all of the large brokers like Hargreaves Lansdown (LON:HL.) and banks wouldn't as they charge and earn enough!!
It will depend who you hold them with.
A suggestion, go and do some analysis of TUI and JET2, and see why you wouldnt switch from tne German tour operator to the UK tour operator.
Not immediately relevant to small caps, but this may existentially affect many companies and workers over the next few years:
OpenAI (creators of ChatGPT) has just released a new text-to-video model called Sora. It shows a huge jump in capability compared to anything else publicly released so far and has stunned even close followers of AI progress.
In case you’re not familiar with these models, all you need to do with them is give a text description of what you want to see (e.g. “A dog eating a burger in McDonald’s”) and the AI will produce a video from that description.
Just 18 months ago the state-of-the-art models could only produce a few seconds of video and the results didn’t look that great (although it seemed very impressive at the time). This tech is moving so fast It’s becoming impossible to predict what might happen over the next few years.
The link below will take you to the Sora home page. Note that there are several short videos in each section (there are arrows above each video to scroll through the examples). Underneath each video you will see the text prompt that was given to the AI to produce the clip.
Make sure you check out the second video in the third section where the text prompt is: “Reflections in the window of a train traveling through the Tokyo suburbs”. There is enormous complexity in that scene, and It’s remarkable to think that this is completely AI generated.
https://openai.com/sora
The reaction to Sora in a number of Reddit groups has been one of dismay. Those working in the VFX industry, for example, believe that the writing is on the wall for their careers, and the same is true of videographers and many individuals in the advertising sector.
Soon we won’t be able to believe anything we see on video. What this means for news reporting, CCTV evidence in courts etc. remains to be seen.
Luthrin, The quality of the videos produced by Sora is absolutely staggering! If such capabilities to produce videos from text become commonplace then we will not be able to believe our eyes anymore. What will happen to democracy if anybody could so easily produce extremely realistic fake news so quickly and easily? I expect Sora will have safeguards around this, but in the future other companies may not be so altruistic.
Hi WarrenStar & Luthrin
For anyone trying to keep up with the AI space. This person is worth a follow on X (Twitter), he posts frequent updates of releases and capabilities.
This is today's post for example see the 11 posts (Tweets).
Huge moves by Google and others in this space.
https://twitter.com/rowancheun...
Regards
Howard
In related news Google have also announced an update to their Gemini model. https://blog.google/technology... This is very interesting because it has a very large context window - currently 128,000 tokens, but they have a model in private preview with 1m tokens.
One of the big limitations with current models is the size of the context window. This limits how much information you can feed into the prompt of the Large Language Model.
There are various workarounds for this - you may have heard people mention RAG (Retrieval Augmented Generation) . With RAG you take a document and chop it up into chunks. When someone asks a question you find chunks that might match what the user is asking about and then feed those into the prompt. The problem with this is that if you don't match up the chunks to the question very well you don't get a very good answer.
With a very large context window you can just feed all the data into the prompt - and Google are claiming that their model is able to accurately answer questions with these massive prompts. Previously there have been issues with feeding in too much data where the model can get confused.
1 million tokens is around 700,000 words. To put that into context for any geeks - that's would let you feed the Lord of The Rings trilogy + The Hobbit with room to spare.
They are also talking about having a model with 10 million tokens...
Anybody else take umbrage at yesterday's RNS from hVIVO (LON:HVO) ? CFO awarded a LTIP based on 3 year TSR with a reference price of 17p, against yesterday's share price of 27p. Taking the mickey would be a polite way of describing it!
Not really grumpy. The CFO has been in place for a bit and has been doing a decent job. We are talking about 500k worth of stock effectively as incentive and in order to fully vest the CAGR has to be 22.5%
500k on a 180m company is about 0.2% in share options. Not really dilution
I think in the UK we sometimes expect C suite execs to work for nothing as small shareholders. Have you checked the CFOs total remuneration package? I don’t think you’ll find it excessive and he’s being rewarded for steering the company to strong shareholder growth……. Why take umbrage to that?
I can understand peoples ire at the package of someone like Druker at Nexxen International (LON:NEXN) but for a CFO getting 500k at hVIVO (LON:HVO) when the total comp is not overly generous….really?
But as a general principle surely LTIPs should be awarded with a reference price reflecting the current price at the time they are awarded?
The price has come up a long way in the last month or so grumpy - the LTIP scheme will have taken a bit of time to put in place, agreed with Remcom etc. and the reference price has most likely been set at either his joining date or before the recent upgrades in trading. So he is most likely being rewarded for recent history because the scheme wasn’t there, rather than getting that for free and then being given a 27p price to work from.
Given the amount and trading performance since he’s been in place I have no problem with this. I want him to be incentivised too.
Should have taken more options on hVIVO (LON:HVO) the performance he had. They do not create value for nothing. They get paid well for that. They should do. Got out early at 23p. Still very good return. But I believe it should go higher.
Thanks David for your comments on Poolbeg Pharma (LON:POLB) last month- it was around 8p. I bought the other day after the CEO sold a big position from hVIVO (LON:HVO).
Thanks
I have no objection to rewarding the CFO's efforts, but to set a target three years out of approximately 31 pence, when the shares have breached 30p at times in the last few weeks, doesn't appear to me to incentivise very much. And it is "sold" to us as an incentive.
Reach (LON:RCH) held a very small amount for some big divis, but some digging about this morning shows that some recent volume has gone in here and is not far off its 50d MA (any chartists here today?).
Thinking of topping up as all the bad news is out in the open and has been priced in. Could a move to digital age, data scraping and start disposing assets lead to a higher rating? Pension will be sorted in the next few years (tailwinds with increased interest rates?).
Also, anecdotally, everyone in my town seems to read papers, young and old, in fact there's a queue system in the library and my local has started to order more newspapers, my kids still love magazines. The wind down of the paper business is going to last a lot longer than people think and by that time, I can see a well oiled tech company ready to provide good cashflow.
In holiday mode as about to go to Seville and have some times on my hands to ruminate and if I didn't have quite a big stake in Smiths News (LON:SNWS) I would equally be topping up here in a heartbeat.
Reach (LON:RCH)
Do you have any evidence to suggest pension will be sorted in next few years - I looked last week and they still had 1.8 billion of scheme liabilities on the balance sheet. Huge difference between not having to make payments now and pension going away. If it could go away I am 100% convinced they would offload to specialist provider. The fact the liability is still there suggests no me no third party provider wants to be on the hook for that 1.8 bill liability as things stand,
rmillaree - have a read at pension liability I have read this that there's around £50m per year that will need to be put aside pa until 2028.
There will be a revaluation in March, but I also remember reading last year around this time from someone who knows pensions that it didn't appear to be as bad as most commentators predict(ed) but cannot find where I read this.
Reach (LON:RCH)
There will be a revaluation in March, but I also remember reading last year around this time from someone who knows pensions that it didn't appear to be as bad as most commentators predict(ed) but cannot find where I read this.
I wouldnt argue with this logic - however that misses the point completely they have £1.8 billion of liabilities that arent going away any time soon (unless someone will take on the scheme). all the experts are saying is that yeah cashflow will probably not me an issue medium term or its likely payments may drop later - ask anyone who knows whether this could possibly be a potential ticking timebomb if scheme assets dont perfom well or peeps live longer than expected or inflation goes the wrong way for them and they would say - yeah i dont think it will be an issue but you might be right that this could be an issue. Focus on how large that £1.8 billion number is !!
I i do know for sure is that any company like this would at the first available opportunity pay a decent wad of cash to get this noose around their neck of the balance sheet - the fact they havent offloaded the pesnion scheme suggests the price they would be charged is more than the company can afford or if they can afford it it would work out as bad deal for current shareholders. Ie if pension went and was replaced with £300 mill of debt would then market value the company more or less ?
Note i am not trying to be negative ref this share but imho it seems plainly nonsensical to say pension is no biggie or "has been sorted" when its clearly still as present as it always has been. I am happy to be corrected by any specialist in the field who says otherwise if i may be wrong.
That just isn’t true rmillaree.
The pension providers won’t take schemes that are in deficit and Reach (LON:RCH) remains in technical deficit.
The repayments over next 3 years will put the scheme into surplus. Once that happens there will be plenty of buyers of the scheme,. The likes of Phoenix group (LON:PHNX) and Just (LON:JUST) and others buy schemes of £1bn+ happily but they do so from a position of actuarial surplus.
You really can’t just go banding about the liability total without taking into account the assets. You’re just cherry picking to support an argument that is fundamentally incorrect I’m afraid.
Given the rise in IR it is quite possible that actuarial surplus is hit early. We can’t really predict that accurately though as we don’t know how much hedging has taken place.
Its dangerous to rely too much on anecdotes. From the UK Press Gazette:
"Circulation of the UK’s regional print daily newspapers fell by an average of 21% year-on-year in the first six months of 2023, according to the latest ABC figures."
As more people read a 'paper in a library, less copies are sold and so the circulation falls. Readership may not drop so fast, as each library copy will be read by several people. But noone knows how many and advertisers aren't interested in reaching people who can't/won't buy their own newspaper and read it in the library instead.
Reach seems to be doing relatively better, circulation wise. It reported a 3.3% drop in circulation revenue in its last TU but a 8.9% drop in advertising revenue and a worrying 13.7% drop in digital revenue.I don't hold.
Jeff - these are reasonable observations. I would note that I remember going to the library back in the day with my dad and the OAPS taking hours to read the papers whilst using the warmth of the library was happening in the 90's so this isn't a new phenomenon per se.
Regional daily print papers, I have never really understood the point of, my father in law still gets the Shropshire Star - I believe they print 4 times a day, 5 days a week, which is a bit overkill, nothing really happens in Shropshire that requires that amount of updating on a daily basis. A move to once a week would seem sensible and may even increase the amount of readers?
Whilst there has been a drop of advertising revenue, I would counter that the data they hold is valuable and aren't listed as an asset and are growing strongly:
While overall revenue is falling, Reach said the money it makes from data-driven activities now makes up 42% of digital revenues, up from 24% a year earlier.
This includes adverts that use data gathered when customers create an account, or their behaviour. It also includes affiliates, partnerships and ecommerce revenues.
It is cheap but high risk because the pension liability could jump up , which makes sense. So a small percentage holding is fine but a large percentage would be dangerous.
Sorry Epitychia - but this doesn’t make sense at all from a pension perspective.
Actuarial revaluations happen every 3 years. Reach (LON:RCH) next one is due shortly which means the actuarial assumptions that were used to come up with the deficit that the company is currently paying down were based on Interest Rates from almost 3 years ago - ie zero. Given the effect rising rates have on pension schemes the actuarial deficit will be less. Possibly a lot less (poss even a surplus) but this depends on a variety of factors.
Once the scheme hits surplus they can offload it to a specialist pension run off company. Then it will be gone completely. I can’t imagine, given the angst it seems to give investors, that the board won’t offload it as soon as this happens. I certainly would.
Reach (LON:RCH)
"Once the scheme hits surplus they can offload it to a specialist pension run off company. Then it will be gone completely."
Not quite that simple, the pension run-off company will want a margin of safety (i.e. they'll want paying to take the risk and expect to make a profit on the transaction), and given the size of Reach's scheme in relation to it's market cap that will likely be a non-trivial sum to find.
All eyes for the revaluation in March. I suspect that higher interest rates will have had a big impact on this. I may have talked myself into increasing a stake before this point.
Hi Viz,
Higher interest rates means high inflation so higher contributions needed to be paid in-not that simple-very complicated issue-the government should have sorted out this mess long time ago.
Still I think it should be regarded as a loan that is gradually being paid. Newspapers have at least 15-20 years in them.
I do not hold Reach (LON:RCH) . Firstly I think it is not one pension but different ones that will be valued separately and then it has to do with the quality of these ( don’t know that). I do agree that they have to pay something to offload them though-not necessarily a non trivial sum.
Should be regarded as a loan that is comfortably being paid down-too much talking about these pension deficits from investors and asset managers-unless they know something that we don’t.
Again this is not really an accurate reflection of the pension run off market ISAallowance. It all very much depends on how the pension fund is constructed, what and to what level hedging is in place, how long the run off is likely to be etc.
In Reach (LON:RCH) case I’ve tried to calculate this before but we just don’t have sufficient info. There is definitely long term hedging in place though.
The next triennial will be the determinant of how quickly this can move off the books but the market for run offs is highly competitive these days.
Reach (LON:RCH)
Have the company given any recent guidance here as to whether they might be able to offload at some stage? i expect have asked the question or at least might have some idea of how much it would cost and or when they might be able to offload. In the absence of any specific expert opinion its not a noose around their neck i am presumig it is very much a noose around their neck - would really helpful to know how it would cost them to get shot or when that might be acheivable
Obviously if the pension hits a surplus that is great, but what if the deficit gets bigger? BTW the pension lost approaching 1 billion when gilts sold off last year. High risk means it could be great or could be a disaster.
Can you show us please where , when and how they lost this £1B? Reach (LON:RCH)
Thanks
Reach (LON:RCH)
Epitychia is clearly talking nonsense with the £1 billion loss figures - not sure if that’s industry hit not just reach or typo. Will be interesting to see if they may have taken a hit in that regard so it is worthwhile point to raise - my understanding was companies that were not forced sellers shouldn’t really be affected long term as those that hold gilts to maturity get what it says on the tin. The gilts issue does highlight the inherent risk - so if steep drop in value did force them to sell at low point that would have been bad.
XP Power (LON:XPP) - I am struck by the company’s painting of their end markets, healthcare, semiconductor capital equipment and industrial technology, being in significant retrenchment when my holdings in all of those areas are announcing orders at record levels. Something doesn’t add up. How many PWs is this now?
Giving the firm the benefit of the doubt, and accepting that their positioning in those markets might be unfortunate, e.g. in lagging analog industrial semiconductor capital equipment, then an analysis of the balance sheet by Paul would come in very helpful. My thinking is that the last time the stock plunged these depths of price was before the issue of new shares which secured the balance sheet and was in reality a distressed price. If the company’s viability is no longer in question, then this could in fact be a good opportunity, albeit a company that is struggling operationally. If you have time please, Paul. But do cover names of more interest to you first. Thank you
The commentary does make you think, especially the bit "These softer trends have also emerged within our direct industry peers". I don't know the company well but looking at their products I wonder how differentiated they can be. I thought a cause might be if they are selling a lot through distributors (e.g. channel destocking) but the last annual report implies this is only 12% so I don't think this is the whole answer. Funny one, but it's pricked my ears in terms of read-across to other companies.
XP Power (LON:XPP) - it was only last month they issued a confident TU that led to several broker upgrades. Are management incompetent?
XP Power (LON:XPP)
i dont get any of the goings on here either - this was a really well run company for many years so its simply weird that things would go so wrong .
All i can think is sometimes companies can be in a very big hole ref debt/going cocern notes/banking covenants.In such cases if the future is sketchy and they paint a negative picture on forecasts / prospects that can sometimes be like signalling their own death warrant there and then. If you take glass firmly full outlook and hand that over to relevant parties that have you by the short and curlies that may give you the important "time" factor to sort - sometimes companies just need time to get back on track. If they go to the bank though and say no recovery until 18 months time being cautious , the bank or auditors may take it upon themselves to force action which at minimum would probably be severe dilution. Whereas if they paint rosy picture that judgment day may come when things are better.
In summary i always worry when companies need to paint the rosiest picture possible as the alternative for us shareholders (i dont hold here but used to) is normally losing chunk of tehn business we own to someone else.
This is sketchy argument i am puting forward , the downside is if you do do that and things dont go exactly as best case scenario later then the truth will ultimately out. I would say xpp are not alone in finding material worsening of trade recently.
I note they say they are ahead of expectations ref cash so at face value not sure they needed to paint an over rosy picture but i would say its possible that cashflow is better only due to shortfall in expected sales - lower sales can often result in positive cashflow.
all idle speculation on my part - it is reasonably clear they arent in a great place
XP Power (LON:XPP) - The commentary does make you think, especially the bit "These softer trends have also emerged within our direct industry peers".
I'm picking up some signs of weakness at Advanced Energy - a $4bn US competitor and the most natural comparison - a 10% drop in revenues recorded for CY23 and another 10% drop expected in the current year. Earnings were expected to stay flat as of last week's quarterly update. Those are analyst figures as the company is not providing full year guidance. Shares fell 5% on the day. I wondered if the more resilient expectations - I hesitate to say performance until the year is out - has a geographical element. But XPP has a bigger proportion of revenues in the US. So perhaps their relative weakness is down to a combination of increased operating leverage and maybe customers getting nervous about the balance sheet and moving orders elsewhere. In any case I'm tempted to give XPP's narrative -but not management's execution - the benefit of the doubt. And a generous interpretation might be that management were simply too hasty in predicting an upturn in the cycle, quite possibly out of expediency (covenant negotiations).
Quod necessitas cogit, defendit
Following your reference BnB to Advanced Energy Industries (NSQ:AEIS, found myself comparing its chart with XP Power (LON:XPP. Notable I think back in the GFC, they both started to suffer (in the chart at least) around July 07 which was some months earlier than many other industrials. Hoping history doesn’t repeat but thinking possibly they’re some sort of lead indicator to watch - which would make sense to the extent big industrial equipment tends to need power in situ.
Some read across. Earlier this month Renishaw (LON:RSW) (I hold in addition to XP Power (LON:XPP) ) reported sales down 5% and eps down 26% and expecting 4-16% improvement in H2. At least they are expanding their factory footprint by another 50% and confident about the long term future.
I was more concerned about the reported accounting blunder in the RNS this morning, particularly following software issues they had a few years back.
This morning apparently Japan is now in recession.
I think things are more fragile out there than is apparent particularly if end markets are related to China.
"Retail sales volumes in the United Kingdom rebounded by 0.7% year-on-year in January 2024, following a sharp fall of 2.4% in December and surprising market expectations of a 1.4% decline. It was the largest increase in retail trade since March 2022. source: Office for National Statistics"
My morning smallcap tweet: What the Heiq?
Microsaic Systems (LON:MSYS) Plexus Holdings (LON:POS) Hemogenyx Pharmaceuticals (LON:HEMO) XP Power (LON:XPP) Heiq (LON:HEIQ)
◄Microsaic (MSYS)► update on integration of Modern Water. [SP=1.3 Cap=2m]
◄Plexus (POS)► wins £1m nine month order for equipment and services for multiple plug and abandonment activities. [SP=15.08 Cap=16m]
◄Hemogenyx Pharmaceuticals (HEMO)► shows in vivo that its Chimeric Bait Receptor can be delivered into the brain via programmed microglial cells for the potential treatment of brain cancers and certain neurodegenerative diseases. "This major breakthrough in the method of delivery of our CBR into the brain is a unique tool." [SP=3.15 Cap=37m]
◄XP Power (XPP)► warns FY-Dec 24 significantly below market expectations, based on recent order intake, revenue performance and discussions with customers. Net debt below mgmt exp. [SP=1498 Cap=355m]
◄Heiq (HEIQ)► Heiq auditor takes a hike. £0.68m placing at 8.7p, a nil discount. Also €1.97m in converts with an 8.7p strike. The converts are just a dodge so that it can raise funds pending a GM. Will buy a new factory. Guides FY23 rev $41m, in line with mkt exp but EBITDA below expectations. Outlook - "widespread consensus in the industry that H2 2024 will see consumer confidence improve, inventories reduce to historical averages, and the industry will grow again from today's stabilized [sic] low levels". Extends FY by 6 months. [SP=8.7 Cap=12m]
Welcome back MrC.
Welcome back!!
Champagne breakfast Paul? Assuming you are still all in on Plexus Holdings (LON:POS) .
Also on a day when there is news of a huge methane leak in Kazakhstan
https://www.bbc.co.uk/news/wor...
Plexus Holdings (LON:POS) Paul has added a comment on ADVFN this morning.
I can’t believe it’s actually Paul. The reason is that he has expressed here a negative view on ADVFN forum and X on multiple occasions (something that he is 100% correct).
Plexus Holdings (LON:POS) is a renting business now and we have to see their margins and CAPEX first before making any concrete investment decision.
All the best to all shareholders.
Agree about the generally poor quality of the ADVFN posts. But Paul poses a valid question about this contract and it’s link with the SLB agreement. There is a chance that someone reading this board may have expert knowledge and reply.
I don’t think it’s Paul.
Paul in OCT 2020 wrote in his morning report about ADVFN :
“The company has been resolutely averse to making sustainable profits…….. Therefore the only hope for shareholders is that someone might want to buy it for the user base(the vast majority of whom seem to be multiple handles for certifiable lunatics). Anyone who has looked at the bulletin boards on advfn will know what I mean”
He posts quite regularly on the Plexus board.
Yes I do post on the Plexus Holdings (LON:POS) board on advfn, because there are several knowledgeable posters there, who've been around for a while and know the company's history. Also I didn't want to clog up the reports here with a speculative share, and no doubt be accused of ramping.
I've listened to all your podcasts and read all your reports on Plexus Holdings (LON:POS) and found them quite balanced TBH given you have such a large position. Today's announcement gave me confidence to top up my own position at a recently depressed price. Let's hope this is the foothills of more to come!
I sought some contract clarification from Plexus this morning and recieved the following reply this afternoon...
Plexus have two License Agreements with SLB Cameron. One between Plexus and SLB regarding Production Wellhead applications using our POS-GRIP Technology and one between SLB and Plexus using their EXACT and CENTRIC Exploration Wellhead and Mudline Technology.
The EXACT Wellhead technology will be used on the recent RNS announcement regarding P&A operations.
I am not clear about the differnce between POS GRIP and the EXACT wellhead technologies, but both sound like a very close collaboration between Plexus and SLB.
The reason is that he has expressed here a negative view on ADVFN forum and X on multiple occasions
advfn is kinda like a "necessary evil" - although it contains a whole load of crapola (i always say that a companies prospects are inversely proportional to the number of posts on advfn.)
what you do get in amongst the dross (and certain threads can be reasonably free of dross is some newsflow and conversation the individual company threads on stocky never get used much so if you want to discuss companies prospects or see whats up with other unfortuantely its more practicable to do on advfn. For anyone who likes to keep up to date with possible tittle tattle and more advfn can be useful.
Had a brief look-Not sure if I was on the right page but they are talking about Liberal Democrats , Covid masks , free lunch and a couple of other messages using abusive language.
If you are looking at Plexus Holdings (LON:POS) on ADVFN then you need to be aware that there are a number of threads with that ticker. The title of the correct one is "Plexus Holdings 2022 - Wellhead Systems for Oil and Gas Engineering". It looks like it wont always be top of the list because one of the other POS threads is quite well frequented.
Some of the company boards are full of poisonous comments but others which tend to be the smaller companies and therefore less popular have pleasant commentators who are very happy to answer questions. Can be helpful to explain a sharp share price move.
Agreed - i do frequent the other place for that reason.
Paul does post on ADVFN occasionally as Paulypilot.
There are very good threads there on shares and Trusts not popular with the crowds. The more rubbish the share the more idiotic the sometimes hundreds of posts a day there are. So ADVFN is a very good guide for rubbish shares to avoid.
For Investment Trust fans ADVN is often very good. e.g for Commercial Property REITs both under the codes for each one and also the catch all “The Commercial Property thread,” where as is the case here there are posters who used to work in Investment Trust sector.
Here there is a good Investment Trust thread. There are so many Trusts at extraordinarily bargain prices at present on big discounts (and much wider than normal) and because if the extreme share price falls, paying huge covered dividends too. Here’s the link for the Invrstment Trust thread:-
https://www.stockopedia.com/co...
Some of the posters on the advfn POS board say they live in the Aberdeen area and work in the O&G industry, and have some interesting things to say.