Small Cap Value Report (Fri 16 June 2023) - TSCO, MER, CTA, PEEL, TPK

Good morning, it's just Paul here with you today, with it being Friday.
Today's report is now finished. Have a lovely weekend, let's hope the warm weather continues (with some heavy showers overnight, for the garden!)
It's been great having Roland here this week, covering for Graham's holiday, so many thanks to Roland. Also I saw that Roland did an interview with Paul Hill, which I listened to last night - lots of interesting (mostly mid cap) share ideas. Here it is -
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
As it's quiet for small cap news today, I'll stray into larger territory too (our usual £1bn upper market cap limit already covers about 40% of mid caps anyway) -
Tesco (LON:TSCO)
265p (£19.0bn)
Q1 Trading Statement (13 weeks to 27 May 2023) -
“Strong performance” across the business.
LFL sales up 8.2%, including +9.0% in the UK - roughly matching inflation.
Inflation -
There are encouraging early signs that inflation is starting to ease across the market and we will keep working tirelessly to ensure customers receive the best possible value at Tesco.
Outlook -
We are well-positioned for the months ahead and are reiterating our guidance for the full year."
We expect to be able to deliver a broadly flat level of retail adjusted operating profit in 2023/24 and retail free cash flow within our target range of £1.4bn to £1.8bn. We expect Bank adjusted operating profit of between £130m and £160m.
Paul’s opinion - none really, as I don’t tend to invest in supermarkets. I just thought it would be interesting on a quiet day for news, to see how the sector giant (27% market share) is trading. The market cap of £19.0bn doesn’t make it too big to receive a takeover bid from abroad. Competitors Morrisons and ASDA are both saddled with excessive debt, or at least their owners are, following leveraged buyouts, which might indirectly help Tesco maybe? Tescos share price is back to where it was 20 years ago, with the main attraction being dividends, which are currently 4.2%, and the PER is 11.9x - probably about right.
Mears (LON:MER)
263p (pre market) (£290m) - Trading Update - Paul - GREEN - EDIT: (ended the day up 8%)
Mears (LSE: MER), the leading provider of services to the Housing sector in the UK…
Background - checking my SCVR summary spreadsheet, our most recent comments on Mears have been -
28 April 2023 - Mears - up 6% to 222p (£245m) - Good results from FY 12/2022. In line current trading. Modest valuation & sound finances. Paul likes it. (GREEN)
8 Dec 2022 - Mears - Looks good - positive TU. Cheap. Generous divis. Thumbs up. (GREEN)
So I’m starting out today with a positive view of the company. What’s the latest?
Trading Update
Continued strong momentum
It’s good news! -
...is pleased to report that the Group has experienced strong trading in the first five months of its financial year, with continued elevated revenues, improving operating margins and excellent cash performance. As a result of this continued strong momentum, the Board expects full year profits to be materially ahead of current market expectations.
Materially ahead usually means about 10%+ ahead. Why can’t they publish profit guidance (in a range if necessary)? Plenty of other companies do, and that’s best practice. Start the year with a wide range, then gradually adjust, and narrow the range as the year progresses.
Particularly as in this case, I can’t find any broker notes on Research Tree.
So I’ll have to guess instead.
Here’s the wonderful little graph from the StockReport, showing the trend of broker consensus EPS forecasts - as you can see, the FY 12/2023 (darker line) was raised from 20.9p to 23.39p in May 2023.
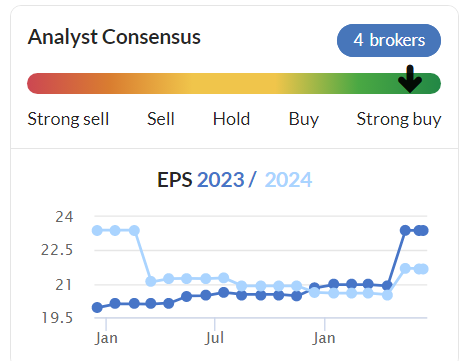
So if they’re now saying “materially ahead”, then that suggests to me something like 26p is now on the cards. That’s a big increase, and very impressive.
Valuation - this sector tends not to command high valuations, but I think a PER of at least 12x is fair. That suggests 312p share price target is reasonable. The current price is 263p, which says to me there could be a fairly easy 19% upside on this share. Plus 4.2% divis whilst you wait.
I’ve also commented before how I like the balance sheet at Mears, and have no concerns over dilution or solvency.
Paul’s opinion - this looks very good! So a continued thumbs up. Despite the share price having performed well recently, it seems to me there could be further upside. Although in this nervous market, we often see people banking gains.
I would have liked some explanation on what is driving the big increase in earnings expectations for FY 12/2023, from c.20p a while ago, to around 26p now? Are those factors one-offs, or sustainable?
At this modest valuation though, I’d say it looks well worth doing some more detailed research on Mears, so a thumbs up from me, on a quick review.
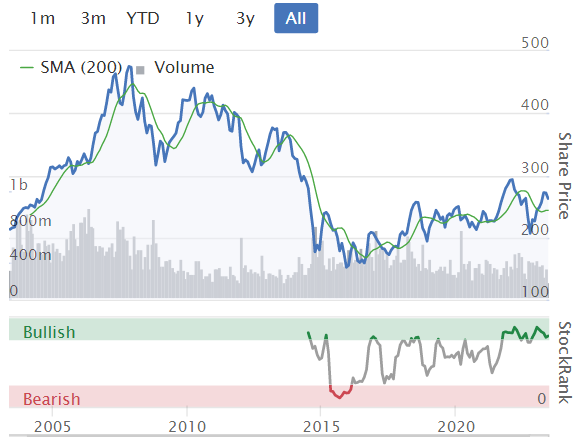
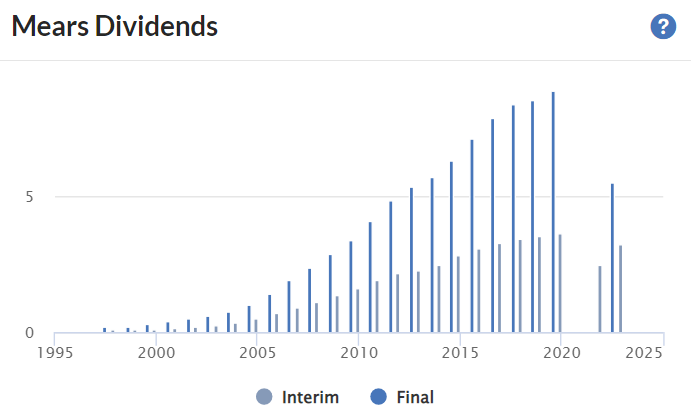
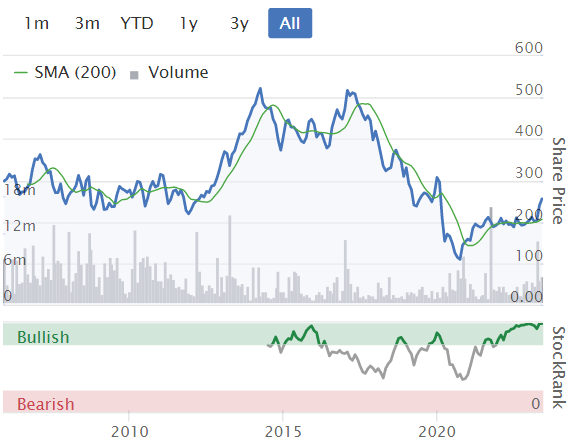
An uninspiring long-term track record, although the total return (adding divis) would be a lot better.
.
CT Automotive (LON:CTA)
Up 16% to 40.5p (£30m) - FY 12/2022 Results - Paul - GREEN
CT Automotive, a leading designer, developer and supplier of interior components to the global automotive industry, today announces its results for the year ended 31 December 2022 ("FY22").
CT Automotive is engaged in the design, development and manufacture of bespoke automotive interior finishes (for example dashboard panels and fascia finishes) and kinematic assemblies (for example air registers, arm rests, deployable cup holders and storage systems), as well as their associated tooling, for the world's leading automotive original equipment suppliers ("OEMs") and global Tier One manufacturers.
The Group is headquartered in the UK with a low-cost manufacturing footprint. Key production facilities are located in Shenzhen and Ganzhou, China complemented by additional manufacturing facilities in Mexico, Turkey and the Czech Republic.
CT Automotive's operating model enables it to pursue a price leadership strategy, supplying high quality parts to customers at a lower overall landed cost than competitors.
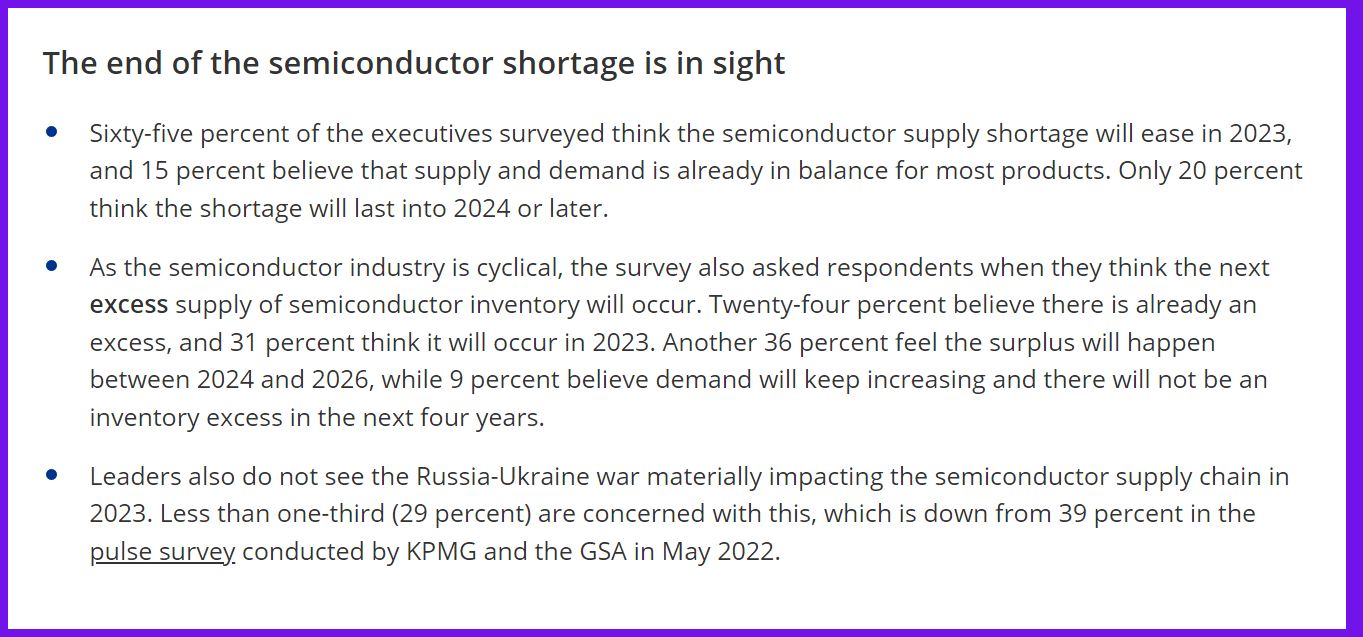
This was a disastrous float in Dec 2021, which developed serious problems shortly afterwards, due mainly to car production being so disrupted by the global shortage of semiconductors. Previously nicely profitable, it lurched into heavy losses, and had to do a placing recently at 34p, to keep the lights on.
For background, my last notes on this (28 April 2023) commented - CT Automotive - 43p (£22m) - disastrous float. Now loss-making. Does a discounted placing. But possible recovery from carmakers on-shoring? Paul's keeping an eye on it.
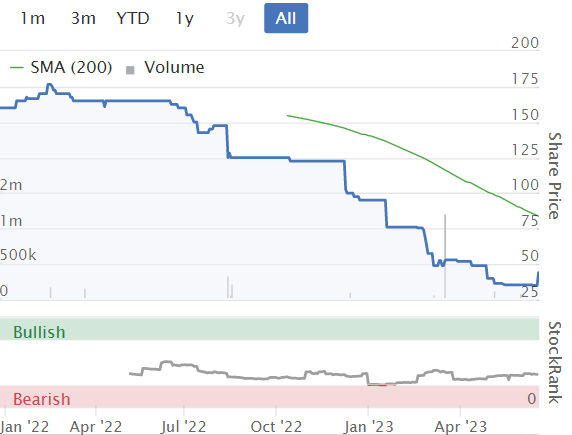
The fundraise in April was at 34p.
There’s a strong bounce today, so let’s see what’s going on! I’m more interested in the outlook, than the historic numbers, as it’s outlook that will drive any recovery!
Audited Results for the year ended 31 December 2022
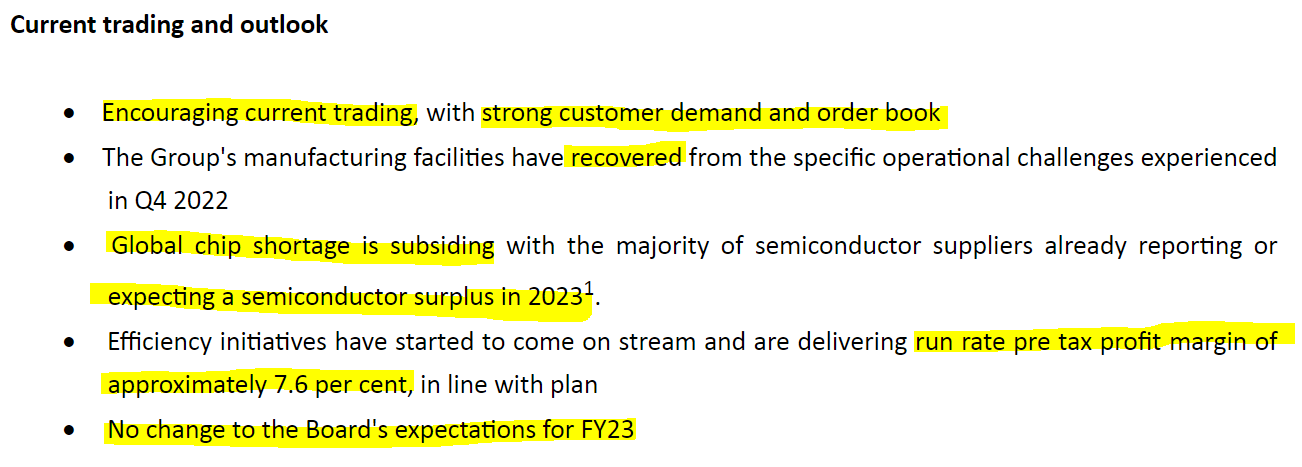
Encouraging trading in 2023 - well positioned as operating conditions stabilise
Current trading -
Trading in FY23 to date has been encouraging as market conditions have improved, with increasing stability and visibility from customers. Meanwhile, our roadmap to drive further efficiencies in the business is on track. While macroeconomic uncertainty remains, the Board remains confident of achieving its expectations for FY23 and delivering significant growth in the medium-term."
Outlook - in more detail, some very interesting comments here -
The report referenced from KPMG is very interesting, here’s an excerpt re the likely coming surplus of semiconductors -
Profit margins - this is the most important sentence in the outlook comments, so let’s circle back to it -
Efficiency initiatives have started to come on stream and are delivering run rate pre tax profit margin of approximately 7.6 per cent, in line with plan
I can’t find any broker notes, but Stockopedia shows consensus revenue forecast for FY 12/2023 of $130m. So a 7.6% PBT margin implies profit of $9.9m, or £7.7m.
If achieved, that would be a strong recovery from the heavy losses in 2022, and would make the £30m market cap look much too low.
This is starting to look interesting!
Turning £7.7m profit into EPS, I would deduct 25% corporation tax, so £5.8m PAT, and divide that by 73.6m shares currently in issue = 7.8p EPS for FY 12/2023. Put that on a PER of say 10-12, and we would be at a theoretical share price of 78-94p - or about double the current price.
Risk - with bank facilities. Although given strong current trading, this risk should be receding, we hope - but it’s still important to consider that this share still looks higher risk, unless & until properly committed bank facilities are secured -
HSBC facilities
The Group uses HSBC post-despatch trade loans and invoice financing facilities as an additional working capital lever. These facilities have been committed for 12 months since the IPO, however starting from January 2023 the facilities are provided on a rolling 3-months basis, and these are expected to be renewed going forward in light of the current trading and the post year end fundraise. As at 31 December 2022 the amounts drawn on the Group's trade loans and invoice finance facilities were $16.7m (FY21: $16.5m) against a total facility of c.$22m. The Directors believe that should the HSBC facilities be withdrawn, alternative funding options would be available to the Group.
Going concern note - very interesting, these are essential reading. It says the group could cope with a downside scenario similar to 2008, and a withdrawal of bank facilities, through taking mitigating actions over working capital.
So maybe it’s not high risk after all?
FY 12/2022 Results -
Look awful as expected, as it was such a badly disrupted year.
Revenue $124.3m
Extremely low gross margin of only 12%
EBITDA negative $(7.1)m, Loss before tax of $(18.8)m. Another year of trading like that, and the company would probably be bust. But it says above that 2023 has returned to profits, so everything hinges on that being correct.
Balance sheet - fixed assets (PPE) seem low at $7.3m, I was expecting to see a more capital-intensive balance sheet.
Working capital: current assets of $59m, current liabilities of $67m (including borrowings of $17m).
Overall, NAV crashed from $27.3m at end 2021, to just $2.6m at end 2022. Note also there have been some accounting errors that have been corrected, which might be why the CFO was changed recently?
Intangible assets of $1.8m, once deducted, bring NTAV down to just under $1m, so negligible asset backing overall.
Although note the post year-end equity raise will have boosted NTAV by $9.1m (after fees), so NTAV should now be about $10m, and on a rising trend if indeed the company is now profitable, as it claims.
Overall then, if the bank renews facilities, the company should be fine.
Paul’s opinion - when previously commenting on this company, it looked a basket case. However, after a recent placing, and what seems to be dramatically improved, and now profitable trading in 2023, I think this is now looking a potentially interesting, and cheap turnaround story.
Still not without risk, but I’ll push the boat out, and go GREEN on this for a recovery, as my sums above suggest it could have c.100% upside from the current 40p share price.
But definitely not one for widows or orphans, and please be sure to DYOR, as this does still look higher (but probably receding) risk.
I also like the angle on the re-shoring trend, and its low cost production model, with the new Mexico facility reducing the reliance on China production.
Views from readers please!
Here's the chart since if floated in late Dec 2021. Note that the share count was 50.9m on floating, but has now gone up to 73.6m after the recent placing, Note that Directors own 32%, and its website shows main country of operation as China! It floated at 147p - admission document is here.
This presentation from management is 8 months old now, but it's still useful as it runs through what went wrong in 2022 -
Peel Hunt (LON:PEEL)
Down 2% to 100p (£123m) - FY 3/2023 Results - Paul - AMBER/GREEN
Graham normally looks at this big name broker/investment bank, with legendary quality research that we cannot get access to.
Checking the archive here -
1 Dec 2022 - poor results in a tough sector, breakeven H1. Bal sht good, Graham says could be approaching value (at 79p)? GREEN
3 Apr 2023 - Down 3% to 103p (£126m) - weak TU - will be a loss for FY 3/2023. Graham is neutral, after recent share price recovery. AMBER
Obviously the macro & markets position has worsened quite a lot over that period too. In particular IPOs in the UK look dead in the water for now, an important source of income for investment banks, and fundraisings generally are depressed at the moment. Small-mid cap fund managers might also be struggling with redemptions, so far from ideal conditions.
However, that’s arguably the time to buy highly cyclical shares like this - when they’re cheap, providing costs have been cut, and the balance sheet remains tough, and that things like lease liabilities are not too onerous.
Key numbers for FY 3/2023 -
Revenues down 37% to £82.3m
Swung to a small loss of £(1.5)m before tax, vs a £41.2m (not a typo!) profit LY (last year).
Outlook - green shoots of recovery? Maybe just a bud?!
Whilst the macro-economic backdrop may remain challenging for some time, we have seen a gradual improvement in our M&A pipeline since the start of FY24, with UK mid-cap valuations remaining attractive, and are seeing tentative signs of a pick-up in capital markets activity. We will continue to progress our strategic priorities whilst prudently managing the business through this period of downturn. As consolidation amongst UK-focused investment banking and financial advisory businesses accelerates, we remain confident that our consistent model of delivering a joined-up and agile service, providing our clients with trusted and impartial advice, will position us well to take advantage of opportunities that may arise.
Balance sheet - profitability doesn’t really matter too much at this stage, as it’s at a cyclical low probably, and should come back in a recovery, in due course. It’s the financial strength that matters most now, to determine how financially sound Peel Hunt is, whilst you wait for a trading recovery.
The good news is that the middle section of the balance sheet (working capital) looks really healthy, with a net current assets position of £101m. What does this number mean? If you imagine the business ceased trading, and just wound down all its working capital, then there would be £101m in cash at the end of that process, which would only take a few months, under a year anyway (simplified, obviously in reality there would be shut down costs).
This £101m net working capital supports most of the £123m market cap, so there’s strong asset backing here.
Also, very small losses on the P&L won’t make a significant dent in the asset backing. Whereas if it was say, losing £20m+ each year, then that would result in the same amount reducing working capital, as the debit (losses) on the P&L is has to be matched by a credit (reduced net assets) on the balance sheet, in order for the double-entry bookkeeping to balance.
I should add that there’s a £15m loan in long-term creditors, so arguably we should deduct that from the £101m net working capital, to give a truer net working capital position of £86m.
In other words, the business itself is really only being valued at £123m mkt cap, less £86m working capital, so about £37m - which seems cheap given the scale of profits that might be made in future, when markets are back to normal.
Paul’s opinion - I think this is cheap enough to be AMBER/GREEN - in other worse, not trading well at present, but with significant upside longer-term. The shareholder register looks very fragmented - so I imagine lots are probably owned by employees and/or ex-employees?
The sector needs consolidation, so maybe PEEL could pick up some also-rans if they get into financial trouble?
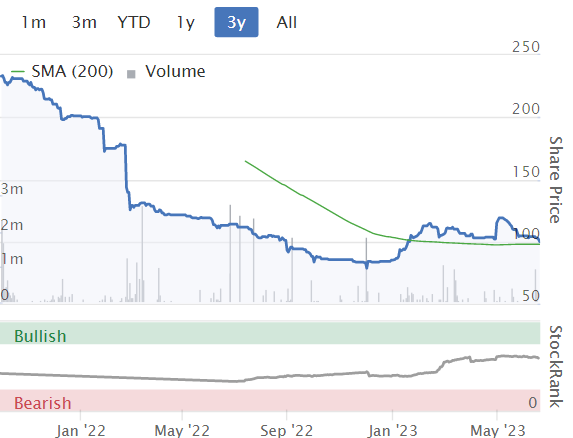
Another corked bottle from 2021's vintage IPOs -
Travis Perkins (LON:TPK)
Down 6% to 818p (£1.73bn) - Trading Update - Paul - AMBER
I’ve never looked at this building products distributor, other than to mention that it span off Wickes (LON:WIX) (in the news today!).
Today, TPK says -
In light of ongoing challenging market conditions, full year adjusted operating profit now expected to be around £240m. The Group delivered a resilient performance in the first quarter but has not seen the anticipated easing of market conditions in the second quarter to date.
New build & domestic RMI markets - impacted by higher interest rates, inflation, and weaker consumer confidence.
Other markets (commercial, industrial, infrastructure & public sector housing) - more resilient.
Paul’s opinion - unfortunately, TPK does not explain how its latest guidance of £240m compares with previous guidance. On doing some rummaging, I can see that its update on 25 April 2023 contained a footnote, saying guidance was for £272m adj operating profit. So today is a 12% downgrade in this performance measure.
Last year’s adj operating profit was £295m.
The trouble is, adj operating profit is not a good measure of profits, because finance costs came to £49m last year, which takes away quite a chunk of operating profit. Hence adj PBT would be down more than 12%.
Clearly this is a disappointment, and I’m surprised the share price is only down 6% today.
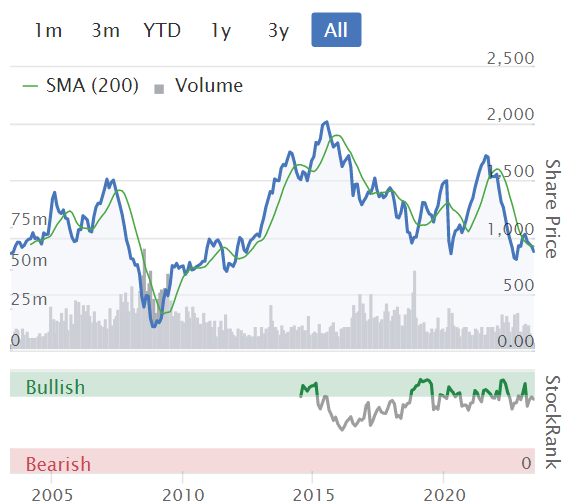
Long-term, this share has gone sideways for 20 years, so the only reason to hold it long-term has been for the divis, and also it might be a share for traders to buy the dips, and sell the rallies?
At some point, the building products sector could be a nice place to invest for a recovery.
I don’t have any strong view on TPK, on an initial, quick review, so I’ll be neutral. AMBER.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

67 comments
Wickes (LON:WIX) It will be interesting to see if bod buy on a drop in the sp.
Burning the midnight oil here in Bournemouth, I've updated my summary spreadsheet for this week's SCVRs, for people who find this useful.
(if you don't find it useful, then please ignore this post)
Anyone know why DGI9 is flying today? Thanks
Regarding the comments on Wickes (LON:WIX) I have been trying to put this into context. It broke out on twitter in the last 24 hours with "boycottwickes" being highlighted as one of the biggest trends. This just shows the power of twitter and the like. The Daily Mail has picked it up saying it happened yesterday.
Don't believe everything you read in the Daily Mail - it happened on May 11th and the whole 7 hour online conference was put on youtube. The comments were in fact a reflection of reaction to the Wickes float in the Brighton Pride march in August 22. For those who want to see the original it is below. His comments on the 90% start 5h40m50s in and his comment on the 10% start 5h46m45s in. They are part of a half hour panel discussion on 'The Role of Senior Leaders in Trans+ Inclusion':
It happened on the 11th but the youtube video is unlisted so no one could view it unless you had a link. Why is he taking part in discussions with a group who dont want this material shared online?
Again, hes the COO of a bloody builders merchants. Just sell some cement and drainage pipe, keep your opinions on customers to yourself.
Anyway in the end the market will decide, as it always does.
Comment elsewhere on Peel Hunt (LON:PEEL) results: '....under which circumstances Peel Hunt would advise its own clients to release results on a Friday!'
The market decided long ago ..... setting alert at 170.
Whatever your views, bit of light relief from Spectator: "If you’re in the paint-flogging business, stick to flogging paint. And if your customers object to being scolded and disdained, it’s not because they’re bigots but because they don’t want a sermon on gender identity every time they buy emulsion."
For the record I accessed the youtube video via a google at lunchtime. Pinknews have now removed it, presumably because of today's twitter activity. This is a pity because I found it helpful to listen to all of what he said, 85% of which was about looking after their own staff and 15% about the float at Brighton Pride last summer and reactions to it. That made me remember just how easy it is to pluck a couple of half sentences out of context and make a tabloid headline.
What do you call a woke droid from star wars?
R2-Me2
What do you call a wolf that is woke?
An aware wolf.
They are just jokes on a hot dull afternoon. Okay. If you are a wolf or a droid don't be offended!!
My alarm clock is woke.
Just wanted to share "I HATE THESE MARKETS"!!!
I did ask this question a few days ago but no-one replied.
I am interested to know what interest rate can a company achieve on deposit on cash balances of £20 -100 million.
TIA
We get 4.19% on £1 million deposits with HSBC
interesting, thank you.
Any idea if there is a cap on the amount you can have at that rate.
Obviously its not for me !! But I am looking at companies with large cash holdings that £1m + interest income pa would make a material difference to their profits.
A very strange interview by Wickes coo given to the modestly named 'Pink news trans summit'
General gist was 90% of people are 'just slightly ignorant' ,some are 'bigots' and 'not welcome in our stores anymore'
At a time when profits are dropping its an interesting strategy. Time will tell if this has a positive effect on sales.
I do find it all very bizarre, I find someone's sexuality to be probably one of the most boring characteristics. Far more interested in their views and hobbies etc. Looking forward to when it all goes away and we can carry on as we did before.
Yes, there seems to be hysteria in the air. Odd that the media is so obsessed with sex, thought we had moved on from this and grown up.
What an absolute fool! I think that takes Wickes (LON:WIX) off my list of potential buys. I very much believe all companies should stay out of all contentious social, political, religious matters. It's none of their business, and they're only likely to upset & annoy many customers - not a clever move when macro conditions are tough. Actually not a clever move, full stop!
Go woke, go broke, as they say. Recently demonstrated by Bud Light, whose sales in America have crashed after they used some bizarre trans person, who seems to me the total opposite of who their typical customer would be! Which muppet thought that was a good idea? They've cost the company billions.
I think this shows that CEOs need to keep a very careful eye on what the marketing people are doing, to avoid brand damage by getting into controversial areas that they shouldn't be exploring at all. Companies are there to sell us stuff, not to project their (usually fake!) social values.
Has the world actually gone mad? It's looking that way to me.
It looks like they have been infected with the Woke virus!
"Woke, lefties and snowflakes are terms often used by awful people to describe people that actually want to make the world a better place and actually care."
Hi Roger,
That's as maybe, but what we're actually discussing here is the damage companies do to themselves (and hence their shareholders) if they foolishly stray into controversial areas of politics, social issues, religion, etc.
Companies need to avoid unnecessary controversies.
I agree that "woke" is one of those words that can mean completely different things to different people. But we're talking about business here, so let's keep it focused on the key point, we can rant about everything else on this wider topic on Twitter!
I'm specifically worried that reported loose words from the COO of Wickes, insulting most of his customers, could damage the business, hence I'm now less likely to buy shares in WIX.
Regards, Paul.
I wasn't responding to your post Paul.
Hi Paul, couldn't agree more with your comments. Comments such as the Wicks CEO's just unessessarily alienate customers, who then go elsewhere. Definitely not good business practice.
Morning Mr Busy covering lots of ground (that's my Indian name for you Sir) And rather touches on the off topic of the day - Can I actually say Indian name any more, is it now meant to be indigenous native or similar, I'm sure I can't say red as that reflects colour?
However back on topic and to the commercial point of Muppets and good ideas - What collective design/marketing group in M&S Marks and Spencer (LON:MKS) decided a few years ago to fill their stores with long leg slim fit trousers as my son would wear but wouldn't be seen dead in the store buying AND then also reduce inventory of the "sell all the time trousers", I go in time after time to replace when I need a new pair
Same group think issue, same result - poor sales
Wow that is crazy . Completely off topic but as it's Friday I shall tell you that the best pedestrian crossing lights I have seen had an animated green man walking with a countdown clock. As time runs out the man speeds up until he's sprinting. Pleased to report that when he goes red he is still safely vertical - so presumably made it.
While in Welington, NZ, they appear to have kapa haka figures :)
https://www.stuff.co.nz/domini...
It's catching on!
what is woke
Sutters just gave us an example, at least not doing what a young relative of a friend of mine is doing. That girl from New Zealand is combining a holiday with slow-marching and mixing with like people on visits from the West Country to London. A well-known prophet of long ago was known to exclaim "forgive them Father for they know not what they do".
Will have a go. A woke person tends to white, middle class and left leaning. Jumps on a cause to show virtue, easily takes offence on behalf of others and for views of others they consider intolerant. Lucky, sold Wickes recently .
Woke people typically think disparities and social issues are explained by some -ism, which must be eradicated.
E.g.
women (whatever they are) and men must be equally represented at senior levels within business and renumerated equally. Any other outcome is, apparantly, indicative of sexism, discrimination against women and a patriarchal society.
That kind of thing.
Hi Zipmanpeter,
All very nice, but I think you've missed my point, which is this - that companies need to be super-careful in all their communications these days, because social media amplifies & distorts everything. Before you know it, you've got customers boycotting companies that are perceived as taking one-sided views in social controversies that have become horribly toxic, sadly.
On a personal level, of course I'm delighted to see diversity & inclusivity, providing the main emphasis is still on people being the best & most suitable for the job, and not tokenism. The City in particular is a horrible closed shop, where privately educated people give internships to their mates' kids, and many roles are probably never advertised, so they go to an elite few. Hence I applaud efforts by firms to recruit & train from a wider pool, including disadvantaged - we need more of this, definitely.
The main reason I didn't go into the City when younger, was because I figured out it was horribly homophobic, which is a pity, as I would have enjoyed & benefitted from a stint in the City. Never mind, things are vastly better now, thankfully.
Regards, Paul.
Hi Paul,
I thought I had self-censored and withdrawn my comment in time to avoid a discussion (on a subject that does not interest me) but you obviously saw my post.
I didn't miss your point (corporates should be careful in what they say; it can impact sales and the share price). I agree it has always been so, even if social media speeds it up. I also agree it would be stupid to simply call his customers "ignorant" but he didn't. Even the Daily Mail (buried in the article) says more completely he said "most of the population is in a 'sort of slightly ignorant but mostly kind position'. " Unless we want our corporates completely silent and unengaged, distortions like this will occur if a media feeding frenzy hits.
But remember, inclusivity was a Wickes board level strategy (presumably to attract and differentiate with scarce young staff and customers who are moving away from DIY). We could have discussed whether it's a good one or not for a DIY/trade company (probably not the best!) and it has not been brilliantly executed here but I think no fundamental of Wickes has been affected.
My starting point was that the topic as introduced was poorly researched or argued and I felt you, as the chief writer and "thought leader", leant into it at the same level.
I like this site best when it focuses on the analysis and numbers - although market inefficiency is a requirement for stock picking - and I love your writing style.
So if Wickes falls 30% in the next week due to a boycott by small shareholders, I will add it to my buy list but for no altruistic reason.
Have a great weekend and I'll still be a subscriber next week :)
Thanks Zipmanpeter, but I think we're still talking at cross purposes. I don't care about the specifics of the Wickes case. What matters is that loose talk by management (not for the first time) has potentially damaged the business. That concerns me as a potential investor.
This is a good example of where over-enthusiastic corporate woke-washing can backfire badly - regardless of the nuances of what was actually said - the press latch onto any loose talk, and blow it out of proportion. That's why companies have to be so careful not to trigger this sort of problem.
Sensible companies stick to their knitting, whilst having a healthy & diverse workplace, which naturally delivers benefits. Shouting about it too loudly causes problems I think.
Wickes has crossed a line before - e.g. many gay people (myself included) found their messaging at Pride last year to be completely inappropriate, and meddling in complex issues that don't concern them at all.
B&Q will be picking up a little extra business from Wickes, because they have wisely kept out of contentious social issues.
That is of concern to me, as I had WIX on my watchlist of shares that I wanted to buy. Now I'm not so sure, as I think management competence is now a serious question mark.
Regards, Paul.
Well done Wolf and Paul, you've turbocharged the sometimes pedestrian Friday SCVR!
I think to comment on Bud, haven't management admitted 40 years of careful brand building was undone in 40 days? This week I think Bud Light has been knocked off #1 spot after dramatic falls in sales.
From Ratners to Budweiser it never pays to disrespect the core established customer base in pursuit of new customers or the illusion of virtue.
Do you have a link to the interview? All I can find is this: https://www.thepinknews.com/20... which seems fairly boring and not very controversial.
Change name from Wickes to Wokes?
Honestly, I don't think it's anything to do with being "woke" - it's just good business.
Do we really want our board, senior exec team, managers etc.. - all to be made up of cookie-cutter middle-aged white men who all think the same way?
We keep talking about how important it is to get more women involved in investing and business, but honestly, a bit of self-reflection on why they don't want to be involved would really help people.
The blokey dismissal as "woke nonsense" of anything that even remotely smells of inclusivity and diversity is a bit daft.
Hi iamflimflam1,
No that article is fine. The problems with Wickes have emerged on Twitter, where the COO of Wickes is quoted as saying this, from an attendee at a trans conference -
The panel also featured the Chief Operating Office of Wickes, the large home improvement retailer, Fraser Longden. Longden shockingly called anyone who disagrees with him on this topic “bigots” before saying that they are “not welcome in our stores anymore”. He also claimed that 90% of the population are “just slightly ignorant”. These offensive, divisive and discriminatory remarks are an absolute outrage. I wonder how the majority of Wickes’ customers would feel, knowing its senior management holds them in such disdain?
(source: https://www.jamesesses.com/p/t... )
Regards, Paul.
EDIT: I see that #BoycottWickes is now trending on Twitter. This is the danger if senior management make reckless public statements - in the social media world, it can have an immediate, damaging impact, and spread fast. Companies need to be so careful, regardless of the rights or wrongs of the issue they've meddled in.
I don't want to belabour this too much as it's getting a bit off-topic. But I had a quick scan through the transcript of the video and I don't think he said that.
I suspect that there's been some very creative interpretation and combination of cherry-picked phrases from different parts of what he said to get maximum shock value.
The marketing team in Wickes are going to get a valuable lesson in managing coms over the next few days.
Reminds me of Gerard Ratner's comment that he "sold crap" at the annual IoD . It took less than a minute to almost destroy the Ratner jewelry chain. I worked in the City at the time and we were long Ratners.
Inclusion is not something you should need to signal to the World .... it should just quietly be like kindness, integrity and a work ethic.
I used to know someone who was in the same cycling club as Gerald Ratner. When he went out on one of the Sunday rides his chauffeur would follow the group in his Rolls Royce and when Ratner grew too tired to keep up he would put his bike into the boot of the Rolls and return home.
The story here if anyone is interested. https://www.dailymail.co.uk/ne...
Personally Id make him walk the plank for this. Obviously newspapers will exaggerate as much as possible for effect but this is still business stupidity on a grand scale. Even the basic numbers dont make sense, there arent enough alphabet people to replace the customers he'll have pissed off.
Maybe it wont have much impact on sales, who knows. 99% certain it wont improve sales thats for sure. More concerning is why a COO has such poor judgement he thinks he can use a shareholder owned builders merchants as leverage for his own personal little cultural crusade.
Aside from the recent errosion of the Bud Light brand by a stupid ad using Dylan Mulvaney, anyone remember Ratners? In an ill chosen joke, the Ratner's head compared its tacky jewelry to a Marks and Spencers prawn sandwich. He successful ended the brand in one fell swoop.
Corporates should either just shut-up on virtue signalling on LGBT issues and focus on treating their customers, workers and shareholders properly. Or be genuinely brave and take a stand in overseas countries which don't have our tolerance.
As a gay person and Unilever shareholder, I'd love to see them adding a tiny Rainbow emblem onto their Dove or Magnum brands as sold in Saudi Arabia etc. That might do some actual good to people being actully opressed. But then again it would take actual guts from the corporates - so it won''t be holding my breath on that one!
Hi Mark L.!
That reminds me, Gerald Ratner's autobiography is brilliant, highly recommended - it's called "The Rise and Fall ... and Rise Again" I listened to the audiobook version, which is manageable at 6h 35m. He narrates it himself. I might re-download it and listen again actually, as I've forgotten most of it. I was planning on listening to Meghan Markle's (now cancelled) podcasts on Spotify this afternoon, but on reflection, Ratner is probably going to be more entertaining!!
I think he still protests his innocence about the speech in 1991. But as always, what is perceived to be true, isn't always actually true!
Regards, Paul.
As a post script, I did download Gerald Ratner's autobiog again, and it had me hooting with laughter right from the start.
Ratner says (sounding miserable) something like this - "People ask me if I regret making those comments about Ratners jewellery in the 1991 speech?"
(raising voice to a medium shout) "Of course I bloody regret that speech! It cost me my £600k pa salary, wiped £500m off the value of Ratners, and lost me the only job I ever wanted and enjoyed!"
Incidentally, I also managed to listen this afternoon to an hour of Meghan Markle's interview with her dear friend Serena Williams. It was in equal measure nauseatingly Hollywood, whilst also making some great points about how ambitious women like Serena are treated worse than ambitious men.
You see! It's always interesting to challenge yourself, and listen to lots of different opinions, I find! A bit like the SCVR reader comments :-)
Right, back to Friday night TV - I'm binge-watching Keeping Up Appearances.... "RichARD!!!!!"
Best wishes, Paul.
Love it .... what an ingenious idea!
Record (LON:REC)
FY results were due to be announced today but no RNS this morning.
Something sinister about to surface?
I dont think so, it was just an error, quite a few sites had 16/6 but the 'real' date should have been 30/6 . Their Financial Calendar has had this date for some time now. Hope this helps.
Financial Calendar - Record Financial Group (recordfg.com)
Record (LON:REC)
30th of June was the date given in their RNS of 28/4.
mrlMarlowe (LON:MRL) sky report potential sale of low margin subsidiaries for a sum of almost current market cap.
could be interesting as it would wipe out debt which I think has been holding back stock.
Trading statement and augm Monday we may find out more. I hold
AO World (LON:AO.) I see Frasers is building on the stake it bought from Odeys. Prelude to full bid?
Mears (LON:MER) in its annual report says that revenues have been 'largely driven' by a long term contract housing asylum seekers. Asylum numbers are not likely to diminish anytime soon. Cheap for its FCF generation, so an attractive Value stock.
It is an ill wind that blows no good: not my invention but worth quoting anew.
I hold Mears (LON:MER)
I'm loving the headline: Small Cap Value Report - Tesco!
Haha, yes I do like to disorientate people occasionally by throwing in something larger! Seriously, it only took me 10 mins to review Tesco's TU, and I still managed to get a section on Mears (LON:MER) up before 8am too.
My morning smallcap tweet: The emperor's new curated carbon-neutral transformational apparel
ValiRx (LON:VAL) Sealand Capital Galaxy (LON:SCGL) Mears (LON:MER) Genedrive (LON:GDR) OnTheMarket (LON:OTMP) GSTechnologies (LON:GST)
◄ValiRx (VAL)► evaluation agreement with Hokkaido University will now cease. "The profile of the product has been found to be unsuitable for further development at this stage." [SP=9.17 Cap=9m]
◄Sealand Capital Galaxy (SCGL)► unsuspended as it had published its FY acccounts. But that was on 6 June. Why the delay? [SP=0.14 Cap=1m]
◄Mears (MER)► guides FY-Dec profit materially ahead of market expectations. [SP=262.18 Cap=289m]
◄genedrive (GDR)► multi-partner grant awarded for the validation of its CYP2C19 ID Kit in time critical NHS settings. [SP=17.4 Cap=17m]
◄OnTheMarket (OTMP)► launches Your Property Services, "a sales and lettings data nurturing service to help estate agents generate additional revenue and win more instructions through valuations." Nurturing? What guff! [SP=62 Cap=48m]
◄GSTechnologies (GST)► FCA has not yet reached a decision regarding Regulatory Sandbox application for stablecoin. Other divisions in line. [SP=1.2 Cap=21m]
Mears (LON:MER) forecasting results substantially ahead of expectations. As did Warpaint London (LON:W7L) yesterday - two of the 2023 NAPS selections.
Thanks, I'll look at Mears (LON:MER) next, sounds good!
Good for Mears (LON:MER) holders but in the short space of time since 28 April, they’ve gone from trading in line with expectations and now just 7 weeks later the year will be materially ahead. For this type of business, you wouldn’t think it could turn that quickly. Share price has rallied in between suggesting some knew but they just hadn’t told the market.