Small Cap Value Report (Fri 17 June 2022) - Macro, BOO, HFD, ASC

Good morning, it's just Paul here today. It's usually quiet for news on Fridays, so I'm planning on looking back at the carnage in the retailing sector yesterday.
Today's report is now finished. Lots of terrific reader comments this week, which is great to see, many thanks to all contributors.
Agenda -
Paul's thoughts on the current macro/markets.
Retailers that reported yesterday -
Boohoo (LON:BOO) (I hold) - an in line trading update was punished as if it had been a profit warning. Obviously ignore me, as I've been wrong on this share to date. However, there are lots of things being done behind the scenes to improve future performance. Now the last pandemic lockdown boosted prior year comparatives have washed through, we'll begin to see comparable performance on a like-for-like basis (i.e. against softer comps). This could result in a return to structural growth. Or it might not, we'll have to wait and see. I think the share price has overshot on the downside, whilst accepting fully that fundamentals have deteriorated considerably due to a variety of sector headwinds.
Halfords (LON:HFD) - strong results for FY 3/2022, but as I would expect, it's more cautious for FY 3/2023. The 27% share price fall yesterday seems excessive to me, given that we all know that consumer sentiment is softening. Could be a buying opportunity, for longer term investors. Balance sheet looks OK, but I'd prefer to see the company conserving cash going into a possible recession, rather than paying out generous divis & doing heavy capex.
ASOS (LON:ASC) - Profit guidance for FY 8/2022 is now only £20-60m. On £4bn revenues, that's effectively breakeven. Gross margin only 44% in Q3. Not good at all, but that's reflected in a dramatically lower market cap than when it was a growth darling. Some hefty Director buying today though.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section:
General thoughts
As always, this is just me thinking out loud, and starting a discussion. I certainly don't think that I'm some great source of wisdom, as one particularly barbed reader comment claimed a while back!
The macro bad news is getting considerably worse, seemingly every day, as we all know. I must apologise for not realising how serious the market falls would be. It’s certainly caught me out, at least the severity of market falls anyway.
We knew all these negative factors were coming, and they were in full view - central banks tightening, QE ending (even partially reversing possibly), higher inflation, continuing supply chain disruption, etc. It’s just that markets have previously taken all this stuff in their stride, so investors generally (including me) seemed to assume it would be the same this time. Maybe we were overconfident from all the profits made in late 2020 to mid-2021?
Anyway, speaking personally, I was far too complacent, in deciding to ride out any temporary downturn, which with hindsight was clearly a terrible decision. However, I can’t change what’s in the past, and have to deal with reality as it is now - i.e. a considerably smaller portfolio, and the anguish that comes with it, which I'm sure most readers will also be suffering from. It's horrible, but losses are part of this process unfortunately.
My view is that it’s probably too late to sell, and I’ll miss a recovery - shares often bottom out and start recovering before the bad news has ended.
Also, shares are the longest term investments - with no expiry date - so we’re meant to be long-term owners of businesses, not speculators on short term prices. Markets are more like a giant casino these days though, which does tend to exaggerate moves both up and down.
I’ve made a few adjustments to my long-term portfolio (SIPP) - I got cold feet about Joules (LON:JOUL) (I hold) because on a daily basis I get emails from them, offering 30-50% off. Also the last trading update made it clear the company is over-stocked, and is being run for cash, to (hopefully) avoid having to do another placing. It’s proven hopeless at managing supply chain problems, and the CEO is leaving. It's the lack of pricing power that worries me most - if it can't get full price for existing stock, then it won't be able to raise prices to cope with higher cost inflation. On the plus side, the freehold HQ could be refinanced, which might enable it to avoid a placing. Anyway, adding in a much tougher consumer backdrop, and I decided it was too early to have a big position in JOUL, so have reduced it to a small position. My intention being to buy back in greater size once there’s some evidence of a turnaround - difficult to imagine in the current environment.
Apart from that, B2B shares are holding up better than B2C, so I’m happy with big positions in Beeks Financial Cloud (LON:BKS) and Cambridge Cognition Holdings (LON:COG) . Anything like that, which has a strong tailwind, due to offering a service that’s in high demand from companies which are not affected by consumers reining in household spending, looks solid in these difficult times.
Apart from that, the market is also throwing up some amazing bargains right now, for value investors. In a couple of years’ time, it’s easy to imagine plenty of shares in our universe here being double or triple the current price.
We went through a similar thing in 2020, when the markets crashed because of covid. Panic selling & buying back later only works if you sell early, and buy back early. How many people can get the timing right, repeatedly? Not many, I reckon.
Also, people only like to brag about the successes on social media, and go silent when things are going badly. Silent, or lashing out at others, through frustration at losses. That’s unsurprising, because it’s painful seeing our portfolios shrinking. My SIPP is now down 35% year to date, and down about 43% from its all-time high. That hurts for sure, but I don’t have any plans to withdraw any money for the foreseeable future, so it doesn’t actually matter that much. It’ll come back up again, providing I’m invested in fundamentally sound companies, which is what I keep reminding myself.
If you’re a trader (which lots of people are, without even realising it), then good luck with ducking in & out of things. That’s not who these reports are aimed at, we’re just trying to assess company fundamentals here, and then it’s up to readers to decide what & when to buy or sell, as it’s your money - hence your choice.
FWIW, my current view has obviously become more bearish in the short term, because the macro stuff has got a lot worse. What looked like a short blip with higher inflation (similar to what we had after sterling plunged in 2016, which the market shook off), now looks like much more entrenched inflation. The Bank of England are now saying inflation is likely to peak at 11%. If energy costs fall back again (which they often do after big spikes), then inflation could gradually reduce. Although the evidence is that further big price rises for food in particular are in the pipeline, due to higher fertiliser costs, and other disruption as a result of Russia’s invasion of Ukraine. Lots of unknown factors.
The problem with inflation is that, once it’s embedded in the minds of workers & companies, it becomes a self-reinforcing cycle. We’re already seeing ominous echoes of the 1970s, with higher energy costs, and industrial action resuming. It’s difficult to blame people for wanting a 9% pay rise, since that only allows them to stand still in disposable income. The trouble is, few employers can absorb a 9% pay rise for staff, which means profits fall, a lot once operational gearing is taken into account. It's lovely on the way up, but brutal on the way down.
As we’ve discussed here before (writers & reader comments), pricing power is key for company profits. So I’m scrutinising trading updates to see what is said about this. Most companies are using the word “mitigating”, which obviously only means partial recovery of higher costs.
Also, as we’ve been discussing, many broker forecasts now look far too high, so we’re likely to see a deluge of profit warnings, as expectations are reset to factor in what looks like a much higher probability of a recession. With operational gearing, many companies profits could be badly hit, by even a relatively small drop in revenues. That’s why share prices have fallen so much in cyclical sectors. It frustrates me that they then fall again, when entirely predictable bad news comes out, but that’s what is happening.
On the upside, we’ve seen some spectacular rebounds from shares which oversold to irrationally low levels. Although often these big spikes up don’t seem to hold, and people sell into the rallies - not a good sign. Hence maybe it’s best to lighten the load on big rallies, rather than buying for breakouts which probably won’t last?
Takeover bids is another area where I think we could see a lot of activity. US investors in particular seem to be keen on buying up cheap UK companies. Also, founders who have deep pockets are probably wondering why they bother with a stock market listing - I can’t see Boohoo (LON:BOO) (I hold) remaining listed, if the share price stays this low. It’s a lot of hassle & cost being listed, and if there’s no benefit, then companies might decide to go private instead.
Summarising then, my current view is that we’re in a phase where earnings expectations need to come down a lot. The market has already priced-in this point for many small caps, but we then see further lurches down when companies warn on profits against estimates that pre-date the current batch of much worse macro figures. So please, come on brokers, slash those forecasts, and let’s have realistic numbers for companies to report against. It’s much better to dial the forecasts down, and then put out an in line with expectations update, than cling on to overly optimistic forecasts and then issue a profit warning - which often do lasting damage to investor sentiment.
What to do next? Well, personally I don’t see the point in selling now. I think everything I’m invested in are fundamentally good companies, and my focus on strong balance sheets mean that there shouldn’t be any solvency issues with my larger positions. That’s absolutely vital now that economic clouds are overhead, and interest rates set to rise considerably from the still ludicrously low current level. Banks turn tougher when interest rates rise, because problem accounts are accruing more interest charges, so the problems get bigger with each passing day. Hence giving a delinquent borrower plenty of time to trade their way out of trouble may not work any more. That means banks are now far more likely to pull the plug, than be relaxed. That’s a key point if you punt on companies that have highly indebted balance sheets. Such companies might need a big, highly dilutive placing, and we’ll be the last to know about it. Or worst case, could be placed into administration. I’ll keep my eyes peeled for that kind of situation, and warn you when I see danger - a key point of these reports. We can’t predict which shares will rise or fall, but we can warn you about company risks, and avoiding potential insolvencies - there are nearly always obvious telltale signs. Although Patisserie Valerie is one example of where a seemingly good business turned out to be publishing false accounts. That one was almost impossible to spot.
Good luck, whatever you decide to do with your own money. I know lots of people in cash at the moment, at least partially, and they’ve been very much right. However, at some point that cash has to do something, because it’s currently losing about 1% per month in purchasing power. So a stock market rally could happen, and be quite rapid, when cash comes back into the market. That catalyst for that? I reckon central banks might stop tightening, once they realise they’ve pushed major economies into recession, and inflation peaked. No idea when that might be. Hopefully some resolution of the terrible war would help (hopefully a coup to consign the evil Putin to the history books - although with such a rotten regime, his replacement could be similar or even worse?)
Lots to ponder, and tough times likely to persist for some time, I imagine. However, as I saw in 2000-2, 2007-9, and again with covid in 2020-2021, these major sell-offs lay the groundwork for fabulous bull markets afterwards, where bombed out valuations turn into big multibaggers in some cases. It’s important to remember that during the downturns, so that we don’t make bad decisions fuelled by panic & fear, then miss out on the big subsequent gains.
.
Re-mortgaging
My mind keeps wandering back to this. I might have mentioned it before, but looking at last weekend’s papers, I was staggered at how low the 5-year fixed rate mortgages are still, at just 3% annual interest rate. This makes no sense to me at all, with inflation at something like 8-9%, and set to rise to 11%. To be able to refinance your mortgage at just 3%, and have that rate locked in for 5 years looks a stunning deal, for both low cost, and peace of mind.
Therefore, it seems to me that any readers with a mortgage and no redemption penalty, could bag a remarkable deal, if you move fast (such insanely good deals are rapidly being pulled). Obviously no advice intended, I'm just flagging up a potential opportunity.
A few years of higher inflation could effectively scrub off maybe 20% of your mortgage, in real terms. In the past, that would have meant punishing interest rates of something like 9-12%. So to be able to borrow now at 3%, fixed for 5 years, despite inflation about to hit double digits seems to me a stunning proposition - worth grabbing quickly before it’s gone, after taking professional advice.
.
Retailers reporting yesterday
Boohoo (LON:BOO) (I hold)
60p
Market cap £763m
I never imagined BOO would come back (roughly) into our market cap range for small caps again. Again, profuse apologies for getting this one wrong (so far anyway). Collectively we must have lost many millions on it, which is awful - it upsets me to think about it, as we're all here to try to help each other make money, not lose it.
Let’s recap on why this share has performed so badly? Firstly, it’s a sector move, not specific to BOO.
This chart below shows the 5-year performance of Boohoo, Asos, Gear4Music (not fashion, but an etailer), and US based FarFetch. As you can see, Boohoo and Farfetch out-performed in the middle to right side of the 5 year period, but more recently have plummeted, down to pretty much the same end point for all of them - Boohoo down 72%, Asos worse still at down 85%, G4M down 77%, and FarFetch down 77%.
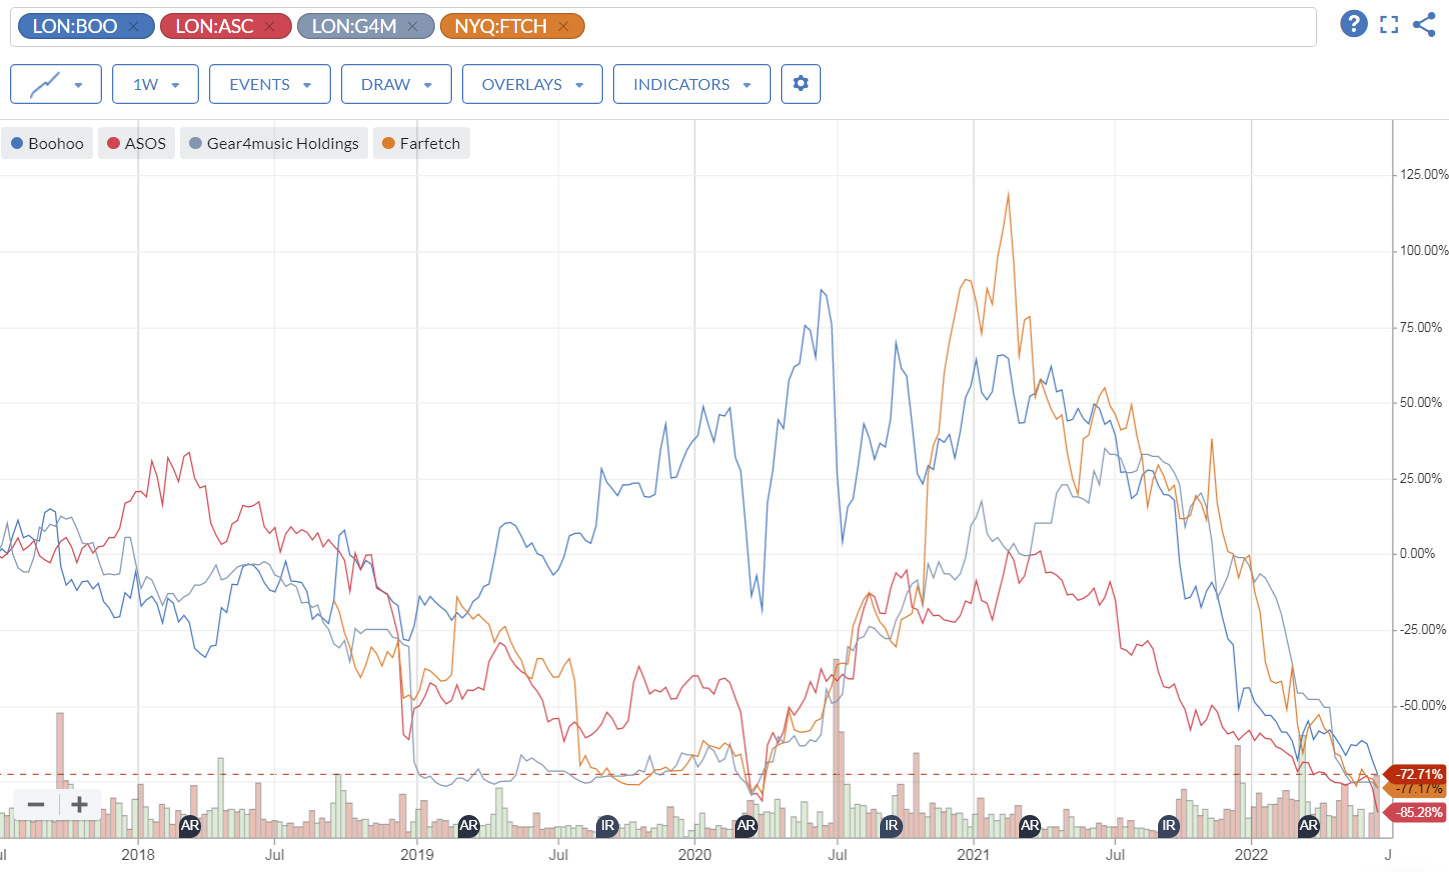
BOO's fall from grace has happened for a variety of reasons -
- the entire sector (online fashion) facing headwinds - mainly supply chain-related cost inflation, and increased competition (esp. China’s Shein), plus now a more general consumer downturn)
- A consequent de-rating, and a collapse in investor sentiment, as sexy growth shares were reassessed as struggling to find further growth, and profit squeezed hard.
- The pandemic pulled forward a lot of demand, which created a boom in 2020 (and re-rating up of the shares), but created very tough comparatives, which companies in the sector are now struggling to match, let alone beat. Have they gone ex-growth, or are we about to see a more normal, structural level of growth return, now that the pandemic effect is disappearing from the prior year comps (from round about now actually, as the last lockdown finished c.May 2021)?
- Widely publicised (putting it mildly) ESG issues for the whole sector seemed to be focused by the press entirely on Boohoo, forcing it to make expensive changes. This had no impact on demand though, with sales booming at the height of the press outrage. Although this issue will have no doubt put off ESG-focused funds from buying or holding BOO shares.
I dispute that we had group-think on BOO. We made perfectly rational decisions to buy a reasonably-priced growth stock, based on the facts at the time. The facts have since changed - an unbroken track record of strong profit growth went sharply into reverse. In hindsight, I think management were too slow to ‘fess up to the issues, which does undermine my confidence in their outlook comments somewhat - a discount needs to be applied to their bullishness! Also there’s no denying that I was slow to wake up to the extent of the problems - I wrongly thought that they wouldn’t suffer too much from supply chain issues. So definitely lessons to be learned there.
I take on board the point about the relentless share price decline too. With mid to larger caps, there are bound to be hedge funds analysing data that we can’t see, and opening short positions. So I’m wondering if it might be better to follow the chart more closely for online retailers?
Fundamentally, and looking long-term, is the business broken? Definitely not, in my opinion.
To save me re-typing everything, he’s what I wrote in the comments section below earlier this morning in reply to a reader request for my current view, sorry for some duplication of the above -
Hi Shrubby,
Boohoo (LON:BOO) has always been a long-term position for me. Obviously the fundamentals have deteriorated badly in the last year, but that's due to clearly identified problems - higher costs of inbound freight, which is impacting everyone in the sector, but should reduce in time. Also, BOO in particular relied on cheap air freight, for distributing all its product worldwide out of the UK. As air freight is now expensive, it's been a big hit to them, and delivery times in the US in particular are recognised to be unacceptably slow at 7-10 days, which is no good for fast fashion, people want something to wear for the weekend. That's why in the UK BOO is still trading alright.
They're fixing things, but it takes time. A new US distribution centre in Pennsylvania is opening soon, but they're saying mid-2023 to be fully up to speed, expect upside on the timings, they indicated in recent webinar that the timing guidance is deliberately cautious, as a big distribution centre takes time to build up. That should be transformative for the US side of the business, as it will allow next day delivery across most of the US - making BOO far more competitive than the key rival, Shein.
Interestingly, in a webinar, the CFO said that there would be no cost savings from using a US distribution centre, as higher import duties would offset reduced freight charges. However, the big benefits are handling returns more efficiently, and crucially restoring competitiveness with rapid delivery times - very much what customers want, it’s called fast fashion for a reason!
Other improvements being made include automating the 4 UK distribution centres, which is expected to reduce labour costs by £25m p.a., and will be another competitive advantage over smaller rivals.
The most recent update was in line, not a profit warning.
Investors are I think spooked by sales going into decline, but Q1 was expected to be soft (previous guidance mentioned this), since the comparative is very strong (the last lockdown, when physical stores competition were closed). The pandemic effect has now washed through, and comps are now softer, so we should see growth resume.
Remember that the 2-3 year growth on pre-pandemic, is huge. It's just that the growth was front-loaded into 2020, so the performance since then has looked lacklustre because 2020 was so strong. That's all through the system now, and hopefully we should see a return of more normal, structural growth. If so, then this could re-rate the share upwards very significantly, from such a low level.
The downside scenario is that there's more competition now, and Shein in particular, might be eating Boohoo's lunch. Only time will tell. Mgt sound confident, but they've been over-confident in the past.
Other positives include an increase in wholesaling, which is a nicer, lower risk, less hassle sales route (the buyer has to cope with customer returns, etc).
Customer returns have always been the bane of life for eCommerce fashion businesses, and that needs a tighter grip.
Note that the new brands absorb cash when they’re acquired, and heavy marketing spend is required. However, they then begin to contribute to profit after a while. Note that this caused marketing spend rose from 9.1% to 11.1% of revenues last year. This is expected to fall back again “in the medium term”, which provides a good tailwind for profitability.
I would suggest people watch the detailed webinars from BOO management, on BRR Media. These show a business & management that are on the front foot, and growing the business for the long-term. Whereas the stock market seems to view the group as a disaster area, which it’s not. As Mahmud Kamani, the joint founder says, "We're dealing with it" - i.e. they know what all the problems are, and they're being sorted out, but it takes time.
My opinion - well probably best to ignore me, as I've been a perma-bull on this share, whilst the share price has collapsed.
However, my stance has always been (as stated previously) on the long-term fundamentals of the business, and I think this remains very positive. At 50-60p range currently, I think this could be a historic buying opportunity. Sentiment could change very rapidly, once it returns to revenue growth, and the costs of lower in & outbound freight come through. Hence why I think it's possibly a future multibagger. But that obviously depends on future performance.
In the meantime, I hope mgt don't take it private, but that must be under discussion with the market cap now so low.
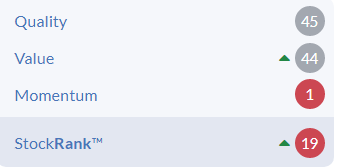
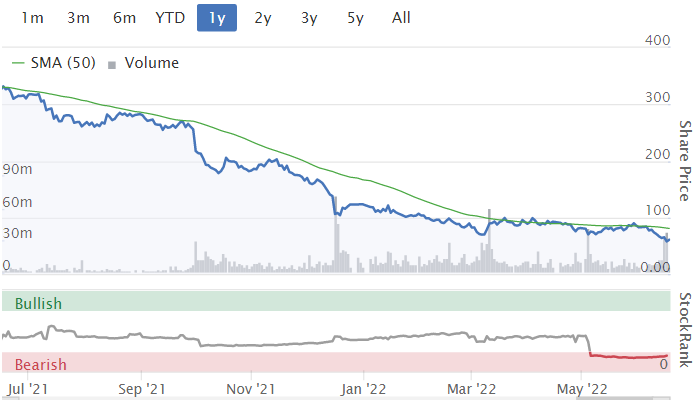
Stockopedia drenches me with a bucket of its unemotional iced water, the StockRank being a dismal 19.
.
.
Halfords (LON:HFD)
145p (down heavily yesterday)
Market cap £318m
Halfords Group plc (“Halfords” or the “Group”), the UK’s leading provider of Motoring and Cycling products and services, today announces its Preliminary results for the 52 weeks to 1 April 2022
HFD has had another barn-storming year -
Underlying Profit Before Tax of £89.8m, +£32.9m (+57.8%) vs. FY20 and -£9.7m (-9.7%) vs FY21.
(note: includes business rates relief of £11m (FY22), £39.1m (FY21) and nil (FY20)).
It’s good to see the benefit of business rates relief spelt out prominently.
Underlying basic EPS is 35.5p - giving a PER of just 4.1, the lowest I can remember seeing for this share. Which is clearly telling us that the market doesn’t currently believe HFD can repeat such high earnings in future years.
Given the share price plunged yesterday, I’m going to focus on the outlook comments and balance sheet mainly.
Outlook - this doesn’t sound too bad to me, given that we should already know that profits are likely to fall in a tougher consumer environment -
FY23 Outlook
Over the last three years, we have built a larger and stronger services business, focused more heavily on motoring. As a result, the Group has a much higher ‘needs-based’ revenue stream, improving our resilience in the current macro-economic climate. However, this transformation journey is not complete and therefore we are not immune to the external challenges, with reduced demand, particularly for more discretionary, higher ticket items, and significant cost inflation impacting our financial performance.
Forecasting FY23 with any degree of certainty this early in the year is particularly challenging. Based on what we see today, we expect FY23 underlying PBT to be within the range of £65m to £75m, but we acknowledge the uncertainty that this year is likely to bring.
Whilst the macro-environment presents a challenging short-term outlook for many businesses, it reaffirms our longer-term strategy. This year, we will continue to invest to improve our customer proposition, particularly in a year where overall value will be critical, whilst simultaneously remaining agile in our operations and carefully managing our cost base. We believe we are well-positioned, given our market leadership position in both motoring and cycling, and our strong balance sheet, to emerge from this challenging trading environment in a relatively stronger position.
I’m really puzzled why the share price fell 28% yesterday on this news, which looks perfectly reasonable to me, in more difficult current macro circumstances.
As usual, I can’t find any broker notes for HFD, so will work out the figures myself.
FY 3/2023 guidance is £65-75m u/l PBT. I’m going to take the low figure of £65m given macro uncertainty. Less 25% Corp Tax, becomes Profit After Tax (PAT) of £49m. Divide that by 218.9m shares in issue = 22.3p forecast EPS. That’s down 37% on FY 3/2022, which sounds sensible in the current gloomier climate.
If my numbers are right, then this gives a valuation of 145p share price, divided by forecast EPS of 22.3p = PER of 6.5, for the current year, which looks cheap.
Hence it looks as if the current share price is already pricing in another profit warning, and further reduced profit in FY 3/2023, which gives me some comfort. Especially if the downturn in consumer spending doesn’t turn out to be as bad as we currently fear.
Dividends - 3p interim already paid, with a further 6p coming, so 9p for the year, a yield of a very attractive 6.2%.
The intention is to increase divis, but that can quickly go out of the window in a downturn, so I wouldn’t hang my hat on the intention.
Personally, I would have preferred HFD to axe the final divi, to maximise cash, in case there’s a recession. Better to do that, than give the shareholders cash, only to ask for it back when the share price is lower, in a recession.
Balance sheet - planned capex for this year FY 3/2023 of £45-50m seems very high. Plus a further potential £15m for integrating a recent acquisition, which again seems very high. I’m wondering if mgt might regret that capex spending, if the economy nosedives?
NAV is £551m, but I need to adjust out intangible assets of £442.4m. This takes NTAV to £108.6m, which is mainly physical fixed assets (PPE) of £101.7m.
I usually also adjust out the IFRS 16 lease entries, which show a net deficit here of £41m.
That takes my adjusted NTAV figure to £142.7m - which seems adequate to me, given the substantial size of the business.
Cash is £46.3m, and there’s negligible bank debt of £0.2m, so net cash of £46.1m - pretty healthy. In a consumer downturn, I don’t want to see any bank debt on the balance sheets of retailers, preferably, so HFD looks OK.
My opinion - as we know, HFD had a big boost from cycling during the pandemic. That said, the motoring services part of the business is growing through acquisitions.
I reckon a lot of HFD customers' spending is actually discretionary spending, not needs based, to contradict the company’s commentary. So it could suffer a bigger downturn in demand than expected, possibly?
For that reason, we may not have seen the low yet.
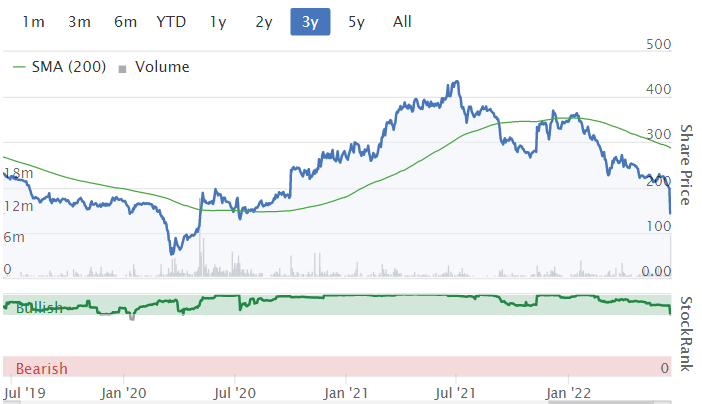
That said, a share price which is now down 67% from its 52-week high does mean that a lot of downside risk is already priced in.
The other broader issue is, why are we valuing companies on this year’s earnings alone? It’s likely to be a bad year, but in the future, earnings should rise again. Hence getting shares now on a low multiple, of low earnings, could turn out to be a fantastic long-term buying opportunity, as both those elements increase. Also shares are probably the best long-term hedge against inflation, although it hits profits in the shorter term, as we're seeing.
On balance, I think this share looks quite attractive now, for maybe a small opening position, or to just go on the watch list for things to buy once the macro side of things is looking clearer, if you’re more risk averse.
.
.
ASOS (LON:ASC)
868p (up 11% today at 12:31)
Market cap £867m
Again, it’s astonishing to see this previous £5bn+ market cap giant now back almost into small cap territory.
As mentioned before, Asos has only ever scraped out a tiny profit margin, although that seemed to be improving more recently. For many years, investors valued it very highly due to the rapid sales growth, which inevitably slows after a while. The high valuation has gone out of the window for now anyway. Will it recover? That’s difficult to say, but if you view the long-term chart below, it’s twice recovered from big plunges, plus of course the astonishing initial bull run, which made it one of, or maybe the biggest multibagger ever on the UK market.
It’s still about 100x the price that I sold my 500k Asos shares, deciding they were overvalued… at 9 pence each, a long time ago! Little did I know that my £45k sale would be the worst financial decision of my life, with those same shares worth over £30m a few years later. Oh well! I just laugh about it, as it’s pointless crying over spilt milk - we can’t change anything in the past, so might as well get some mileage out of it in a blog.

.
Asos dropped about 23% on yesterday’s update, but has recovered about half of that fall so far today (at 13:36), which looks encouraging. Quite a few retailers are in today’s top % risers actually, rebounding from being yesterday’s top % fallers list. We don’t know yet if this is just a short-term rebound, or something more permanent?
I see there’s some decent buying today from Asos NEDs and the Chair. Total Dirs buying is 93.4k shares, that’s about £780k invested, a decent vote of support, more than just a PR stunt I’d suggest.
A major US shareholder has also today announced an increase from 7.16% to 8.71%.
It’s certainly helpful to see big Director buying, as I know lots of investor friends are looking for this, as a signal to give them the confidence to dive in too, given haywire market conditions.
Trading Update for Q2
This update is for the company’s Q3, so this is Mar, Apr, May 2022, for its Aug 2022 year end.
Higher returns rate (also mentioned by BOO)
Revised guidance is now barely above breakeven, given anticipated revenues of c.£4bn -
Guidance for the year updated to reflect uncertain consumer purchasing behaviour and the potential continuation of higher returns with revenue growth expected to be 4% to 7% and adjusted PBT now expected to be in the range of £20m to £60m
My opinion - it’s difficult to know what to make of this.
The whole sector is suffering from supply chain problems, and increased cost of in & outbound freight. That should all get sorted out in due course, so this year’s headwind should become a future tailwind. Hence I wouldn’t write off this sector.
However, another headwind is that customer acquisition costs are so much higher now, as Google, Facebook, etc, grab the profits for themselves. Maybe in a downturn, online marketing costs could become cheaper again?
There are so many moving parts, it’s really difficult to even guess what the future holds.
With BOO & Asos now at similar market caps, the choice is whether you want the bigger (double the revenues) company Asos, or the historically much more profitable one, Boohoo. Or neither of course, which seems to be the most popular choice right now!
What keeps me interested in the eCommerce space, is that we are right at the point where pandemic distortions drop out, and growth rates will be comparable to the prior year, for the first time since early 2020. This could go two ways -
Bullish - structural growth continues, with online continuing to take market share from physical stores.
Bearish - eCommerce has gone ex-growth completely.
On balance, the bullish case seems more likely to me. So many people have got used to shopping online, that it seems more of a permanent, structural change, not a flash in the pan. We’ll know quite soon, but with the added distortion of a general consumer downturn.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

132 comments
Boohoo (LON:BOO) (no position)
I've read the comments and Paul's write-up at different points over the last few days so apologies if someone said this already, but I don't think Boohoo (LON:BOO) management will take the company private.
Their future capex commitments look huge and whilst cash generation is decent, I don't think it's anywhere near enough for their plans.
Even if they sold their expensive London HQ, I think they'll need more cash and will want easy access to the markets.
ASOS (LON:ASC) have spent hundreds of millions of £'s over the last 5-6 years getting warehouses set up around the globe, and still continue to spend as they continue to automate and optimise. The plan is for £200m capex in this financial year alone and they already offer next day delivery in all of the US and 85% of the rest of the world (my notes, November 2021)
Someone made an excellent point about many localised US retailers increasing their next day delivery/BOPIS (buy online, pick-up in-store) offerings as well.
I read a lot of updates from US retailers, many of whom I had never heard of 3 years ago, and can confirm that I've read as much. I imagine next day delivery is something that will very quickly be expected rather than hoped for.
Boohoo (LON:BOO) have a lot of catching up to do and they're going to need lots of cash to do it.
A
What a fantastic community this is. Thanks all for sharing your experiences and opinions in these difficult times.
James Brumby (Langton Capital) tweeted:
Per #BBC's survey;
84% of consumers are planning to save money long term by spending less on #clothes for themselves
If you look at ASOS $ASC and Boohoo $BOO share prices - both are at staggering lows since lockdown heights, troubling consumer behaviour ahead...
#retail #stocks
Supposed 'lockdown winners' giving back their gains:
#Asos/#Boohoo - consumers are swapping fast fashion for durability, wearing #clothes until they wear out
#Car dealers - these are banking profits atm, but demand will drop off an edge as big ticket purchases are delayed
Just seen an email in my inbox telling me that the short interest on Boohoo (LON:BOO) moved from 6.93% today to 7.93%. Looks like the shorters are still after them and feel that there is more to come in the drop.
what has happened is very odd.To control inflation interest rates are going up.The oil prices have increased adding to the misery.The supply of oil is not an issue, the oversupply can easily be arranged thus bringing the inflation down.The housing market must be stable otherwise the whole property market can crash thus adding to the misery.The crypto has also come down.QE is finished or is it changing its form.They call it QT Quantitative tightening.How does it work?Individual share holders are selling and leaving it in the bank.The money in the bank can devalue, so what does he do he buys a property to hedge against inflation.If he buys at the wrong price he can enter into negative equity.
The whole equilibrium is disrupted due to the pandemic and the Ukraine war.Has the central banks made the situation worst with QE.Which companies will survive this recession.Large organisation (the expenditure is bigger) or small organisation that can also go bust.
How will QT reduce inflation ,not with a vacuum or a dust pan.If we can solve this puzzle then we have cracked it.
Think it was Johnny Nash who said there are more questions than answers…
There's no shortage of oil there is thought a shortage of refiners a fund manager was telling we theres a huge refinery in Norway shut down as they can't cope with the quality of saudi oil by all counts russian oil is purer they are trying to refit it to enable them to work on the saudi oil but it will take time to complete the work to get up and running again.
It is all about Sulphur, but we do not talk such things.
Thanks for you thoughts on Boohoo. (Lon:BOO). You mentioned that the share may not stay on the market for long considering the costs to the company. If the share was to be bought into private hands do you have any thoughts as to what an acceptable price would likely to be?
Something surprising has happened at Tern (LON:TERN) recently. Look at all the new large individual investments that have appeared in the top shareholders list (Institutions, on Stockopedia).
What's the explanation?
Pretty sure it's to do with the takeover of Pires Investments (LON:PIRI)
BOO HOO (BOO) Could you give more detail what are the lots of things behind the scenes?
Hi johns54,
BOO HOO (BOO) Could you give more detail what are the lots of things behind the scenes?
I just meant the things explained in the article, i.e. things they're doing to improve the business, plus I've added some more below from my notes on the webinar a few weeks ago - e.g. -
I appreciate that management do tend to be positive all the time, so the above should be seen as them stressing the positives, and what they're doing to improve the business. But I think it does give a flavour of a management team & business on the front foot. They're focused on growth, and less on short term profitability, which doesn't help investor sentiment in the short-term. And as they say, the cost pressures are all due to external, temporary disruption. However, they're also realistic, in forecasting continued disruption & high freight prices for the rest of FY 2/2023.
I strongly recommend investors look at the very detailed results webinars that BOO does. If you go to BRRMedia website, then search for Boohoo, a page of them comes up. I recommend listening to the last 2, Q1 update, and Prelim results. My notes above are from the prelim results webinar on 4 May 2022. I'm about to listen to the Q1 update now, so will post up notes on it hopefully next week (I'm away this weekend, visiting family).
My overall view now (for what it's worth!) could be clouded by optimism of course, but I'm trying to be rational about this, and ignore the share price performance. I think there's strong evidence in the list above that performance of the business should start improving now it has lapped tough comps, and mgt are clearly doing so many things to improve the business, that I'm inclined to believe them. What with an extreme drop in share price, right now I see more upside than downside, hence why I'm bullish.
Regards, Paul.
Hi Paul, re inflation; "The Bank of England are now saying inflation is likely to peak at 11%. If energy costs fall back again (which they often do after big spikes), then inflation could gradually reduce." I wouldn't mind if it went up and then straight back down again like Cptn Kirk last year. Could not the real deal be a re-run of the time I got a mortgage in 1968 at 3 and 7/8%? It's interest rate kept on rising, not being fixed, worse still, it was an endowment mortgage since there was a mortgage famine on and anything else harder to get. A number of years later there was President Nasser being awkward and our government issuing petrol ration books just in case while super tankers were being built to round the Cape of Good Hope to dodge Nasser's taxes. So went the interest rate, on up and up and for years and years. It was excessive amounts of overtime that kept my household solvent and eventually to pay the mortgage off. Let's hope this kind of thing stays in the past.
Silver
Paul,
Your comment re selling your ASOS (LON:ASC) shares and missing out on a £30m windfall reminded me of this story last year of a student matching all Euromillions numbers last year but not winning the £182m jackpot as she didn't have enough money in her bank account to buy the £2.50 ticket :-)
https://www.theargus.co.uk/new...
Have a good weekend all.
Hi danjamesbaker,
Maybe she and I should try to make some money going on a speaking tour? I could be the warm up, with my lost opportunity of £30m on Asos, and she can be the main act, about her winning lottery ticket for £182m which was rejected as her bank bounced the purchase price of £2.50.
Mind you, would me having £30m or her having £182m have actually improved our lives? Probably not. Many lottery winners go completely off the rails, and often lose the lot, then commit suicide. I think it's totally immoral giving such a ridiculous amount of money to ordinary people, who then won't know how to handle it.
Lottery winners also often lose family & friend relationships, then sit around, lonely, in a mansion wondering what happens next, and having to constantly make stressful decisions over what to do with the money, how to invest it, how to avoid being ripped off, etc.? Very bad. I'd give most of it away, to charities & friends/families. Indeed during my investing career, I've already given away about £1m to friends/family/charity. After all, what's the point of hoarding money you don't need, and seeing people you love going without things they need? As one of my investing friends says, "Who wants to be the richest corpse in the cemetery?!"
They should split lottery wins down into much smaller amounts, say £1-5m each, which will make a difference to so many more people, but without ruining peoples' lives. Or, make the prize a monthly payment for life, to allow a lavish lifestyle, but not introduce the risk of them blowing up. I cannot fathom why anyone would actually want £182m? I don't.
Anyway, my approach is, if something does go disastrously wrong, I can't undo it, so just find a way of moving on, and thinking about all the positive things instead. That got me through my personal disaster in 2008, which took about 8 years to recover from. There are whiffs of deja vu at the moment, with a disastrous portfolio year to date, which I am struggling to cope with, as I'm sure many of us are. Every day, multiple times, I get this wave of - what an idiot I've been, if only I'd done this, etc.... But those thoughts have to be banished, as there's nothing I can do to undo the mistakes. It's just a question of learning from the mistakes (again!) and structuring things better next time.
Above all though, I've got everything I need around me - a nice place to live, a job, lovely friends & family, and some savings, and above all reasonably good health. I can rebuild my savings, have done it successfully 4 times already in bull markets. The trick I still haven't learned is when to move into cash, and getting through bear markets.
All food for thought, but it's important to keep the thought process positive - what can I learn from my mistakes. Rather than, if only I hadn't done this or that, which is completely pointless, and self-destructive.
(by the way, this is at least in part, a memo to self!)
Best wishes, Paul.
Great summing up Paul I often think money management is the most important and hardest part of investing its a bit like a football manager with a new team sorting out the defence before anything else.
I always try and ask myself what am I going to do if i'm wrong as we can always find hundreds of ways to hang onto a losing trade once hard earned is committed to it.
Like most I love reading your trips down memory lane with your adventures as a young scamp flipping books on the market a stand out, if you ever do write a book of your investing adventures personally I think it would be a far greater read just basing it on your life's investment journey the ups, the downs and back on the ups than a standard how to analyse stocks type book.
There was a great John Arthurs article on Friday saying if you bought after the Lehman bust you would have been down another 40% sharpish but up 400%+ now even allowing for the current worst time in the last decade.
Regards Andy
Life is about love everything else is merely temporary.
I also bought asos at 7p and sold at 10p happy with the 50%. Think I then rebought at 9p and sold second lot breakeven. Would have been worth £2m at the peak £70/share!!Still got the contract note somewhere
Hello Paul. Thank you so much for your in depth analyses across 2 days for the likes of ASOS (LON:ASC) and Boohoo (LON:BOO) which certainly leave me in a quandary, particularly on whether to buy back into Boohoo (LON:BOO) at some stage.
I have just a couple of things to add. The largest live now pay (not to much) later Klama I think it is called (the Swedish giant) is showing the strain in terms of retail sales passing its way, needing to cut staff and also likely to need to raise some big bucks; and the other is how to assess the effect of the Chinese competitor Shein, here in the UK, across the Pond and in Europe; what damage is it doing; what unfair advantages does it have and how important are they.
I am also concerned about whether Boohoo (LON:BOO) is off the hook, both in the States with the court case still not completely finalized there if I read it correctly?; and in time once more with ESG issues in the UK if the media decide to get their teeth into the company again.
I would be grateful for any thoughts you or any other contributors may have.
thanks for the write-ups Paul. Have a good weekend.
Andrew
[deleted]
Friday afternoon RNSs are not usually good news but a recommended, all cash takeover for EMIS (LON:EMIS) has just been announced at 1925p ~46% premium. I hold, so it is a nice way to end a tough week.
Cheers
Simon
EMIS (LON:EMIS)
What a pleasant surprise on a hot Friday afternoon. From the announcement it looks likely to go ahead. Do you think there is any chance of another bidder? With the current state of the market I think we have plenty of time to research a suitable replacement in the healthcare sector.
EMIS (LON:EMIS)
What a pleasant surprise on a hot Friday afternoon. From the announcement it looks likely to go ahead. Do you think there is any chance of another bidder? With the current state of the market I think we have plenty of time to research a suitable replacement in the healthcare sector.
Possibly. My main concern would probably be the competition authorities getting involved due to over concentration of NHS services with a single provider (United Health). I guess we’ll see in due course as I’m not familiar with the number of services UH already provide. But like you say a sweetener to an otherwise awful week.
All the best, Si
RE: EMIS (LON:EMIS)
Given the value of the pound it's open season on UK stocks.
But given the level of the bid and the state of the markets it's not one to complain about.
timarr
Haha great news, slightly tinged by me halving my position at the end of last week.
Well done guys, I banked profits about six weeks ago....
Eyes went out on stalks when saw it as still on my watch list..ha ha ha
Realising gains at this time might be equivalent to selling the family silver, eh what?
Silver
Also for myself, plus a second bidder entering the ring for Go-Ahead (LON:GOG)
Silver
Brookeda, Buying back shares is a good idea only if the underlying business is intrinsically cheap,buying back to increase their remuneration is certainly not.Going back to markets where cheap money has lifted all boats due to a number of reasons one being goverments bailing markets out with quantitative easing is no longer viable due repayments of debt rising significantly,secondly they are now sellers of bonds to improve their balance sheets, so for me that is a game changer,so personally i think we all need to tread a lot more careful.
Hi coniston,
Fair points, to which I would add these points:
Now that Govts have discovered QE (money printing) do we really think they will put this tool back in the box & never use it again? I don't. Nor does Fed Chairman Powell. As I've mentioned before, in a testimony to congress earlier this year, he was asked what the Fed's response would be to the next proper recession? He instantly replied, "Asset purchases" - which means printing money to buy up primarily Govt debt. Which brings interest rates right down again, and enables Govts to run big deficits, funded by money-printing.
So how long will it be, before the Fed cracks, and starts reversing its current tightening policy? I've never believed that QE would be unwound, as that's a pretty much guaranteed way to push the economy into a recession. That's electoral suicide for politicians.
It'll be fascinating to see how all this works out.
It still seems odd to me, that to deal with inflation caused by external supply problems, central banks are now inducing a recession. Sure that stifles demand, and scrubs off asset bubbles, but the markets/inflation are already doing that job. So will the central banks actually need to tighten much more?
There's continuing inflation (esp food) in the pipeline, but are oil & other commodities likely to continue rising in price as demand falls? I'm looking through commodity prices now, and many have fallen back a lot from the peaks. So surely the cure for inflation is already starting? If oil comes down a lot, and supply chains normalise, then we could see inflation easing at some point in 2023, at a guess?
You could argue that a softer labour market is also needed, to reduce wage inflation pressures. That's a nasty process though, with weaker companies going bust, freeing up labour, and reducing the bargaining power of staff.
Although I also understand the argument that such elevated inflation means central banks have no option than to raise rates, to stifle demand. It's a very blunt tool.
My hope is that as economies slow due to reduced consumer demand, as households focus on essentials, which are costing so much more (esp petrol/diesel, household utilities, and food), then that should do the job for the Fed, in reducing demand for other things, thus reducing prices as companies are forced to discount.
There's also the issue of excess inventories, as many companies have built up inventories to be sure of meeting demand, at a time of supply disruption. That's already led to some US big retailers saying they're over-stocked, and are now cutting prices.
It all looks horrendous for company profit margins, so profit warnings galore in the short term anyway seem likely, especially for companies with modest pricing power, and no particular product differentiation. But that's why share prices have fallen so much - the market is anticipating profit warnings. Maybe not enough though, I reckon profits could be really clobbered at some weaker companies, or even push them into losses & insolvency? So I'll be re-doubling my efforts on balance sheet warnings, and scrutinising debt more closely than ever.
I'm also looking for signs that stocks bounce after plunging on bad news, and there is already some sign of that starting in small caps. E.g. Motorpoint (LON:MOTR) (I hold) plunged on a profit warning & big reduction in forecasts, but the price recovered most of the losses within 3 days this week, checking out the intra day chart it was;
MOTR: night before profit warning, 222p (Tue pm)
Day of profit warning (wed) spiked down to low of 178p in the first hour of trading, then bounced to c.206p in second hour of trading.
Oscillated between 200-215p ever since.
Closed the week at 209p (down only 6% on pre-profit warning).
I think that's rather encouraging. It's telling me that the market seems to have largely factored in reduced earnings, at least for this company anyway. It could also encourage the many people holding cash to start putting some of that money to work, we'll have to see.
We also saw with retailers last week, that both Boohoo (LON:BOO) (I hold) and ASOS (LON:ASC) plunged on trading updates (ASC was a profit warning, but BOO wasn't, it was in line with expectations, but the market slammed it down in price anyway!), but then recovered half the falls the next day. Again, that could be a sign that we might be nearing a short term low on really bombed out smaller caps, perhaps?
I've got some fresh money in the pipeline, probably coming in some time in early 2023, and could accelerate the pace to deploy it earlier (later in 2022), but that feels too soon. I'm actually quite happy to sit and wait, because this feels more like 2000-2, when a period of exuberance & inflated valuations & bubbles ended with a prolonged bear market. Valuations were absolutely battered & investor sentiment was utterly crushed. Then of course from late 2002 onwards, the market absolutely exploded upwards, 2003 was probably my best year ever in % terms.
So I'm torn on how things stand now. Many small caps look really cheap, and I'm fairly sure selectively they could be 2-3 times current prices in say 2-3 years. However, with so many storm clouds gathering at the macro level, profits look very vulnerable indeed for many sectors - absorbing large costs (esp wages) at a time when demand is probably going to shrink, could devastate profit margins for some companies without pricing power.
All fascinating to discuss, especially at weekends when we're not distracted by RNSs and the markets! I certainly don't have the answers, because I don't have a time travelling spaceship to visit the future! But I love bouncing ideas around & hearing what other investors think too. All views are valid, because we're all guessing :-)
Regards, Paul.
P.S. Another thing to consider, is that when markets fall this much, fund managers start to see client redemptions. So open-ended funds come under pressure to sell holdings, even if they don't want to. I remember this happening in 2001-2 in particular. I was buying deep value shares at the time (things priced at less than half their own net cash, amazingly). These were nearly always dot.com junk that floated in the boom, with tons of cash that they were burning through with hopeless business models. I bought up shares in them, and launched shareholder action groups online, to pressure the companies in to distributing the cash to shareholders. All 4 of my shareholder action groups worked, and delivered 100%+ gains. It's how I got started as a professional investor. Anyway, my point is, why were fund managers selling these shares at below half the companies' own net cash? It didn't make sense to me, and I just assumed they were stupid. I recall my late friend Tony Brewer, a city veteran, telling me over lunch at the time that the sellers weren't stupid. They were just funds that were having to raise cash any way they could, to meet client redemptions (withdrawals).
It seems to me that unless something changes for the better soon, then we're likely to see a repeat of this, which could hit some small caps very hard, as the market liquidity disappears in a prolonged bear market. That leads to backed up potential sellers, who can't sell at all. I faced that in 2008 - being forced to unwind large spread bets, and often there were not any buyers at all! Or they wanted a deep discount (c.10%) to take a decent slug of shares in a micro cap (c.£100k+). Hence it's very unwise to be stuck in a tiny micro cap, if you think you might need to sell it. Chances are, if markets get worse, you won't be able to sell much, if any.
Working on the weekend Paul? Giving us even better value for our subscription!
So many varied opinions appearing at the moment. As you say "we are all guessing".
IMO there is a significant rebalancing of public expectations underway and it is going to be uncomfortable.
I'm trying not to let macro headlines influence my opinions of individual companies. We are already starting to see some winners and losers in the same sectors so we can't assess them all with the same macro brush.
Some comments on the macro situation.....
All prosperity derives from cheap reliable abundant supplies of energy. A situation that prevailed in the UK until climate change was invented by the anti capitalists and others who want to control every aspect of our daily lives. Against that background, I set out below a note I wrote in January of this year setting out a broad overview of UK energy policy. It follows that as long as western governments pursue the folly of trying to control the weather in 100 years time, we will have expensive energy driving up inflation, whilst we all find that the prosperity we enjoyed in our earlier lives continues to ebb away.
Energy Policy
The Johnson government has made it a major part of their energy policy to fight climate change. The other 2 major political parties have similar aspirations. The policy requires the reduction of greenhouse gas emissions (emissions) principally CO2. To this end, wind and solar electricity generation are encouraged at the expense of traditional generation from coal and gas, and to a lesser extent nuclear.
Solar and wind are substantially less efficient than coal and gas, so inevitably the cost of electricity must rise. Additionally, gas generators have to be kept on standby to cover intermittent failures of wind and solar. This leads to further inefficiencies, and again increases cost. The grid itself is rendered less efficient through the distribution of power from multiple intermittent producers, leading to further cost.
Bottom line, if government policy is to fight climate change, the cost of electricity will increase. The financial burden is regressive. Low and middle income families are hit substantially harder than those who are better off. In fact, government policy acts effectively to transfer wealth from the poor to the rich. This operates not only on a national basis, but also on a global basis. The fight against climate change means that millions of people are denied the cheap abundant energy that fossil fuels offer and which would liberate them from extreme poverty.
At the same time the government is encouraging consumers to switch from traditional internal combustion engined cars to electric cars, leading to an ever increasing demand for electricity. This demand will continue to increase as consumers are forced to move from gas, as the principal heating fuel, to electricity.
The UK government has made it clear that there has to be a period of transition to its net zero targets. The transition fuel of choice is natural gas. Unsurprisingly, most of the other governments of developed countries have also chosen gas as their transition fuel. Demand for gas is therefore on the rise globally.
The major oil and gas companies have seen the writing on the wall for some time, and have been shifting investment away from fossil fuels to renewables. Without investment, the discovery of new fossil fuel resources, and specifically gas, reduces.
The price of commodities in a free market depends on 2 elements - supply and demand. We see that concerted policies of developed nations is driving up demand, whilst lack of investment is drying up supply. The recent rise in the price of natural gas, particularly in the European market, is a direct result of these policies. Russia’s use of gas as a political weapon has undoubtedly added to the supply side pressures, but is not the cause of the problem.
The problem is less serious in the USA for the very good reason that they have a thriving indigenous gas industry based on fracking, a practice that is banned in the UK, notwithstanding the massive resources that we possess. Another plank of the government’s energy policy that serves to drive up the price of gas.
A windfall tax on oil and gas companies will reduce the amount of capital for investment in exploration and create further disincentive for oil and gas companies to invest in the future. Pressure on the supply side will continue to increase, as will prices.
As mentioned earlier the object of the policy is to reduce emissions. The government will no doubt claim success in this area. However, a proper analysis, which takes account of the emissions embedded in the imports of food and goods, as well as those from shipping and aviation, shows that any claimed savings are illusory.
12/1/2022
"The fight against climate change means that millions of people are denied the cheap abundant energy that fossil fuels offer and which would liberate them from extreme poverty."
But it isn't cheap that's the whole point. It costs the earth. Literally. Our past recklessness with the environment now threatens our very existence. It may already be too late. Climate change wasn't 'invented' by anyone, it's here and has been for quite sometime. The nature of extranality means that we don't necessarily see it on a daily incremental basis but everytime someone jumps in their diesel car they contribute to it obliviously and the loser is everyone but particularly the very same people in extreme poverty you refer to who are not contributing to it but will not be able to grow their crops and our descendants. No one is trying to 'control' the weather now or in the future, we simply have to stop burning fossil fuels and reduce our carbon emissions to survive, and the best way of doing that is through taxation and tax breaks on renewables. We are not 'fighting' against climate change, as a human race we are adapting (which we are very good at hence the dominant species) to climate changes that we have inadvertently brought upon ourselves. There is so much else wrong with your analysis I am surprised you are highlighting it by reposting it!
There are many debating points in your comment SmallCappy; this is not the forum for that although I think you let Putin off far too lightly re gas and oil prices right now. You'll also have noted Europe's heat map over the last week, climate change is real.
I don't think anyone invented climate change it is real but everything else you say i agree with.
Sadly I think we are past the point of no return and in truth everything needs turning off tomorrow but if we did that society would collapse in a week look how bad it got when we could not get toilet rolls let alone being told thats it electricity is never coming on again.
Personally I think the best we can hope for is to delay the inevitable hopefully I'm wrong but I agree with you the idea that we are going to be able to move over seamlessly in the short term is pure fantasy.
More historically, food. Bounteous supplies of food frees up labour for use in creating wealth. An envious position to be viewed from the UK today
regards Boohoo and Asos it may prove to be the case that online distribution of clothing is not very profitable, especially if you allow free returns.
it might be OK if you are working on local distribution with a good local brand names or names but the notion of shipping worldwide seems frankly crazy to me as especially in the USA the consumer has a myriad of choice In the malls and by same or next day delivery by local suppliers. What is the differentiator that means Boohoo are likely to be successful in the USA?
I don't hold these companies and don't see the appeal.
Great to see such a lively discussion today.
Good observation by Paul on mortgages. I know loads of people including myself who've just gone for long fixed rate mortgages. Looking at the rates on offer it was clear that banks were basing their rates on interest rates going up but then coming down again (this might still be the case) but I like having the security of knowing what the rate is going to be and by historic standards it is very low.
Of interest to me today is the divergence in SP performance between Begbies Traynor (LON:BEG) and K3 Capital (LON:K3C) (I hold)
On some metrics K3C appears the better investment. Clearly the market believes that Begbies Traynor (LON:BEG) will benefit from company distress but K3 Capital (LON:K3C) will not.
As I type I notice that Begbies Traynor (LON:BEG) has taken another leg up today touching its recent highs. However K3 Capital (LON:K3C) is still selling off after a recent rally.
I noted that last time Begbies Traynor (LON:BEG) rose sharply (18th May) then K3 Capital (LON:K3C) followed suit the next day (19th May). I wonder if the profit taking on K3 Capital (LON:K3C) is overdone? It is enough for me to buy a few more.
Hello Revs 8. Not so long ago, K3 Capital (LON:K3C) was one of my most profitable companies, and then it has drifted and drifted to become one of my least profitable. The rationale is that it is a diversified business with M&A and taxation etc as well as benefiting from business failures and restructuring. Diversification in this case seems to be working against it. They have said quite recently that they are gong to make their 2022 targets and yet the slide continues, including today whereas many others have recovered following the slide last Monday and even more yesterday. Some months agi, the CEO said he was taking on another top guy to help run the business. That could be taken two way I thought at the time. Negatively, it needs more hands to get the business going at its best; or positively, to build the business even faster. Given the SP performance since that announcement, I'm not so sure the positive was the relevant one. Thoughts?
I think we need some positive news from K3 Capital (LON:K3C) to change the momentum.
They previously confirmed no known reason for the share price slide so presumably it is all down to consolidation in this weak market.
If the rising support line holds then I will too.
Halfords does look very tempting but there is a real shit storm going on in the bicycle side of the industry so I would be very surprised if they didn’t take a hit over the next 24 months .
Big orders were placed by most suppliers 12-18 months ago and are only just landing and into a very soft market . The scenario of billy big balls purchasing decisions a year ago at the peak of the boom is going to mean very high stocks arriving into a really soft market .
E-scooters maybe interesting but it’s a bit of a minefield and several bicycle side distributors have discontinued their e-scooter range .
Does look very cheap .
I think the really smart way to look at a business now is - “would you buy this business” if you could afford it outright .
For example
- I would buy vertu because I’d sell the real estate and end up with 100 million quid .
- I would buy Bloomsbury because it’s got the Harry Potter franchise
I would for sure buy northbridge .
Would I buy Halfords absolutely not , lots of stores and overhead and heating bills and staff pay rises and a softening market - I couldn’t do it .
I mentioned how was I thinking of buying some cheap Halfords shares to my wife last night after yesterday's precipitous fall. She thought it was a terrible idea. Bikes sales to people who don't use bikes spiked during covid but now these ones are in the back of the garage somewhere. The real cyclists don't shop at Halfords. OK,I know this is not what is driving the business model these days but, just saying, it is a point.
Can I take a more negative stance on Boohoo (LON:BOO) ? During 2021 it became increasingly clear there was something up with its international business. Q1 FY22 had RoW down -15% and Europe down -14% although at that time the UK and US growth was very good. However, the US growth quickly went into reverse falling to +7% in the second quarter and -14% in the third quarter. In the most recent update for Q1 FY23 US is now on -28% albeit against a strong comparative quarter. Europe is down -9% but that's against softer comparatives.
There are no signs that this decline is slowing sufficiently except perhaps in RoW which is good but is a much smaller part of the business.
Other factors that are very negative in my view:
Boohoo (LON:BOO) has gone ex-growth and we are being asked in the current market to pay 26x current year earnings for it during an inflationary environment which may become a recession. I think it's just too expensive.
Great post ! I’ve looked at this stock in the past and more recently and would be very wary. I’m not a fan of the massive inventory on top of the recent note on returns plus the potential for recession and further consumer pull back. The cash burn over the last 6 months are likely related to the increase in inventory, but it doesn’t read well…
My red flag which I didn't act on quickly enough so still took a pretty big hit was seeing they were spending £70m on a London office. Don't know if that went ahead.
> would be interested to know how their delivery times compare to Boohoo (LON:BOO) (in other words will Boohoo (LON:BOO) 's distribution centre actually make that much difference?).
Shein USA website shows that standard delivery will take 2 weeks, plus another 2 to 3 days for the warehouse to process the order. Other sources say 2 to 3 weeks. Currently this is similar to Boohoo. With the USA warehouse Boohoo will have next day delivery to roughly 50% of the USA, and within 2 to 3 days for 90% of the USA. Pre pandemic delivery times for Boohoo were 3 to 4 days.
Excellent SCVR today, thanks Paul.
There are some very pertinent comments today from people who have "averaged down" and gone on to regret it. Averaging down has been disastrous for so many investors in the past.
But stocks don't know if you own them or not, so the same logic applies to any new, tempting investments that you are eyeing up and thinking about buying for the first time. Look at the stock and think "if I owned that stock already, would I now be averaging down? If so, is that a good idea?"
Central bank support has meant that for the last decade it's always been a good idea to buy the dip. But sadly, we don't live in a "buy the dip" world any more, so this has the potential to become what I would call a true bear market.
Paul says: "I can’t see Boohoo (LON:BOO) (I hold) remaining listed, if the share price stays this low." and this surely applies to many shares. Ironically, it will be the fundamentally stronger ones that are more likely to be taken off your hands. If it's not disgruntled founders taking them private, it will be takeovers on the cheap. You might own a great business with great long term prospects and you may receive a 20% premium to the price on the day before the bid, but that price could still be significantly below where we stand today.
Each to their own, but make any buy/sell decisions with an understanding of both sides of the debate.
If you average down, you can't regret if the first few purchases are under water (for a period of time). That's the definition of averaging down. You're not market timing and buying it all at the bottom price.
Hi
If anyone interested in $NVDA, super computing, Genomics, leading edge AI and Biotech, and the general quality of the UK to attract the worlds talents. This 5min vid (approx) might interest you.
If my link fails to work, go to YouTube and search for this vid
Regards
Howard
If mortgage rates are now well behind inflation then surely the likes of Lloyds Banking (LON:LLOY) must be terrible investments. Most of their assets are made up of fixed rate mortgages - if inflation stays high for a couple of years then they're looking at a 20% hit in real terms when the mortgage gets repaid.
re. Lloyds Banking (LON:LLOY) etc, My understanding is that generally they match their fixed rate, fixed term mortgages against fixed rate, fixed term government debt or similar, and hence they shouldn't get into trouble from this... assuming they have competent risk management of course, not always a given with the banking sector, but normally it's their investment bank arm or commercial lending that screws up IMO.
Hi Bouden54, the common view is that increasing interest rates benefit banks as the Net Interest Margin (NIM) between deposits and loans is wider at higher rates. More here. Not saying it means it has to happen, but I believe that is the accepted wisdom...so worth considering (obviously credit risk increases in a recession in the other direction).
Yes the conventional view is rising rates is good for banks, because of net interest margins. However, if inflation is rising way more than rates than I'm not sure this would be the case. Surely the bank's net assets (ie mainly mortgage loans) would take a big hit in real terms, that would more than offset a higher NIM. Obviously lots of moving parts to consider, but my sense is to avoid bansk in a high inflation environment (unless rates rise more than inflation).
But.... If inflation is high, money devalues, then long term there will be more deposits... Which they can loan out... And thus "assets" increases?
I've heard that argument but a lot of financial funds investing in banks have done badly over the last few months it seems the possibility of a recession and borrowers defaulting is viewed more negatively than the idea that rising rates are good news for financials.
Sorry I have got verbal diarrhoea this morning. Thank you for the write up on Boohoo (LON:BOO) but on:
“I never imagined BOO would come back (roughly) into our market cap range for small caps again. Again, profuse apologies for getting this one wrong (so far anyway). Collectively we must have lost many millions on it, which is awful - it upsets me to think about it, as we're all here to try to help each other make money, not lose it.”
Please STOP apologising or feeling awful. It is NOT your fault. Anybody who was in Boohoo because “Paul says its gooden” shouldn’t be investing or reading this column.
I have you to thank back 2015 for putting me on to Boohoo (LON:BOO) and when my CAGR on the share price was 44% I was grateful for that but I was the “genius” who invested on the back of my own thoughts (I am very bullish on online selling of anything) and research (limited at the time but I feel I know Boohoo (LON:BOO) very well now).
You gave your opinion, and who says (if it stays a public company) in 10 years it won’t prove to be the right one.
As somebody cleverer than me (I think Ian Cassel of MC2) said “you can borrow someone’s (stock) ideas but you cannot borrow their conviction.
Regards
Michael
Here's a completely unsolicited summary of my views/performance I guess.
Down around 11% YTD, about 1% up over the last 12 months excluding the money I have in funds Stocko can't track.
I've been cushioned massively by Begbies Traynor (LON:BEG) which I've held in various quantities for a few years. At the moment it's nearly a third of my portfolio excluding cash (which perhaps highlights just how rotten the rest of it's doing!). The only other holding that hasn't had a stinker is CMC Markets (LON:CMCX) because I bought most of my shares at pretty much rock bottom. I'll continue to hold CMC but I have trimmed my position slightly - it'll probably be one of the first shares I top up when the time looks right. Like many on here I've bailed out of £BOO. Got out at around 85p which was fortunate timing.
My shares account is about 25% cash at the moment, which has gradually been increasing since summer of last year. I can't see me putting any of it to use anytime soon.
My main worry at the moment is the weakness of the quid. Mainly because, like many on here I'm sure, I have a decent chunk of my portfolio in global trackers (for those interested I invest in £IWFV and £IWFQ rather than 'pure' index trackers). For those of us that have global trackers that don't hedge currency, we've managed to avoid some of the losses of the tumble in the US because the pound has plummeted vs. the dollar. Nice for now, but of course this means that when the £ does begin to recover our losses will extend (or, we won't benefit as much from a US rebound). Generally a bad time to be a UK investor with global exposure.
One thing I've been watching is company buy-backs. Quite a few of my holdings and watchlists constituents are buying back right now which I see as encouraging. I was also thinking watching for these is maybe a way to spot the recovery winners. Interested in opinions here? Am I just deluding myself?
I have quite a few companies doing pretty big buybacks and agree in the long term as long as the business is sound this has to be a positive sign of future EPS growth above and beyond the companies performance. Too many companies buy back at the peak and so this has to be a good thing
Yes, fixed rate mortgages seem stupid cheap. However, if i re mortgage where do i put the money i raise?
Stock market, no.
Crypto, haha
Property, maybe?
Gold, i already have some.
Hi Epitychia,
Just to clarify a small point, I wasn't suggesting that people borrow against their homes to invest elsewhere - which sounds risky.
I was just suggesting it might be worth looking at refinancing an existing mortgage (ie. same amount already owed) at a historically cheap real interest rate.
In the past I've also remortgaged a couple of times to repay much higher interest other borrowings, e.g. loans, credit cards, etc. Although the only drawback with that, is they tend to creep up again over a number of years, resulting in the same level of unsecured debt, but a bigger mortgage! So discipline is required (not my strong point)!
Regards, Paul.
An interesting comment by Martin Lewis of TV fame when asked by a Times radio presenter about inflation. Caveating anything he said was as a non-economist, he thought the Bank interest rises was really the only thing the Bank of England could do, as that was their principal power and focus, but that really, aren't the immediate inflationary pressures Supply side?, about which the BOE could do nothing, so sucking money out the economy by encouraging loan retrenchment etc wasn't really helpful at a time when people might need them.
I thought it was an interesting comment overall.
As I mentioned below, besides choking demand, higher interest rates also shore-up the pound which helps ease supply-side pressures for UK companies.
Tip: For anyone with a remortgage coming up, you can lock in rates up to 6 months in advance of the end date of your 2yr, 5yr fixed.
An example will be my situation. I took out a 5yr fixed back in 2017, at 1.29%.
In January this year, I suspected that rates would have to rise, given inflation. So I applied for a remortgage, found a lender that was willing to have 6 month validity on an offer (most do, but not all). Locked in a rate of 1.27% on a new 5-year fixed.
My remortgage completion is happening in the next two weeks. I just checked the best rates you could get, right now, if you apply, and it is at 2.6% for my amount and LTV.
And likely to go higher over the coming weeks as the 5-yr Gilt is trading at 2.12% now, and the best 5 year fixed rates typically trade 0.6-0.8% above that.
Overall over 5 years, I am saving c.6.5% of my mortgage amount, which is no small change IMO. Its paying for pretty much all the holidays I am planning to go on!
Fantastic additional info, thanks Boon :-)
Excellent commentary. And sincere. I agree with everything you have said. Things are bad and it is time to be philosophical and do some grinning and bearing. These are the times that try our financial souls! Periods of extreme volatility are the price we pay for longer term outperformance. It's also worth bearing in mind, as you have intimated, that some of the current negative factors are, we might say, 'artificial'....man-made....and could be reversed in an instant. A single bullet going in the right direction would, for example, go a long way to making a big difference right now. And when it does, or something like it, markets are capable of bouncing back faster than you would ever believe. It can be very difficult scrambling back in at such times. We have to be in it to win it. Don't jump off the roller-coaster in mid roller-coast! Keep the faith!
Where's James Bond when you need him!
Thanks Paul. I always love your macro musings. They bring clarity to the situation, as did today’s newsletter from The Rational Walk: https://rationalwalk.com/throw.... I particularly think that this is important:
“….you should have an independent estimate of the intrinsic value of what you own. You should anchor to that value, not market quotes that are changing by the nano-second.”
I think it current markets it is important to remember Graham/Buffett: “Price is what you pay [or sell at], value is what you get[or hold at].” I am trying to focus on that and not make the mistake I made in 2020.
[edit] If one wants to think positively, we are in a perfect storm of events: hangover from 10 years of easy money, Covid, supply chain issues, chip shortages, China zero Covid lockdown policy, Putin walking into Ukraine, inflation and interest rate increases. A possible but, not likely maybe, scenario is markets get use to non easy money (as it should have been made to years ago), chip production gets back to normal (predicted anyway for 2023 and demand destruction might bring that forward), China gets with the program that current variants of Covid are not that awful (particularly in the young/fit), Putin is toppled (as he should be) by a western friendly putsch (I understand that one attempt has been made already) and inflation is brought under control. If several or all of these came together at the same time, then a snap back in markets is very easy to envisage. Rose tinted spectacles maybe but still I put it out there. Besides history tells you that being a perma-bear and a long term stock market investor are not a good mix.
On mortgages from experience I can concur on the joys of fixed rate mortgage. I have one in France fixed at 1.38% fixed for the term (2031) and in the UK, while not fixed, an offset mortgage where I keep cash and gives me my risk free rate of return on money. Anybody with a mortgage and the right criteria and liquid assets would do well to look into them.
Regards
Michael
Thanks Paul, a s you've touched on wage inflation which i believe is going to be the changing of the guard where for many years it's been kept low at the expense of labour. Capitalism has thrived under those conditions ,now i think governments will be forced to recognise equality & accept wage inflation where company profits suffer. Secondly imo markets are still adjusting to the unkown( interest rates),which have to be discounted back to assets,personally the ftse100 yield of 3.5/3.8 doesn't compensate you enough,hence why i ithink markets have further to fall .
Good morning all,
Thank you Paul for another good article. Buffett had said that his portfolio was down by 50%+ on 3 occasions so I am not too bothered with my 20% fall.
I trimmed my stocks and I now hold positions on companies I am happy with. My only worry is that I would like to have some extra cash to reduce my average prices, (maybe the remortgage you mentioned can be a double good thing ;) ) otherwise its all good.
Angelos
As MrContrarian points out below a bit of a French farce at M&C Saatchi (LON:SAA)
They issued an RNS suggesting that shareholders vote against the resolution they are personally irrevocably wed to (as a result of agreeing the deal) with Next Fifteen.
This is due to it being as cash and shares offer and £NFC shares having dropped materially in value.
Vin Murria is probably laughing her socks off, as her concerns about the Next Fifteen offer was the share value element (though her offer had a similar structure) and the Directors probably have to hope that she votes against the deal now, after they effectively removed her from the Board due to lack of independence as an offeror.
This may be just a technical positioning by the Directors, to avoid the appearance they have asked the shareholders to accept a lower offer, hopefully to avoid being sued later on by shareholders arguing they have undervalued the sale of the Company. Or it may be they are hoping by shareholders voting against the recommended offer, they can renegotiate the share element, even if they personally have to vote for the recommendation resolution.
How embarrassing for the Board!!
It proves how cash and shares offers are at the mercy of the markets.
I don’t think there is a realistic chance of Next Fifteen Communications (LON:NFC) raising its offer for £SAA. Next Fifteen has already declared its offer “ final”, which under Takeover Panel rules means that they cannot raise the offer, except in certain specified circumstances, eg an offer by a 4th party.
I think the M&C Saatchi (LON:SAA) statement should be read at face value - the board is legally committed to vote in favour but no longer thinks the NFC offer is high enough. Maybe it is a signal to any other potential bidders that the door is not closed.
Paul, many thanks for a great commentary in these torrid times.
Perhaps a good news story was Eneraqua Technologies (LON:ETP) which you wrote about on Tuesday, here. We've just published a results overview by the CEO & CFO video and podcast. They are hosting a webinar with Q&A session on Monday 20 June at 11am. Register here.
Quick summary of the results but Paul gives a much more detailed overview on link above.
I hope you can join us.
Thanks Tamzin! It's very rare for me to be interested in new floats, as they're usually either awful or over-priced, and often both!
However, Eneraqua Technologies (LON:ETP) strikes me as well worth doing more research on it, due to stellar results, strong order book, and seemingly having a competitive advantage in a fast growing sector (eco heat pumps).
Also, I liked that the float raised a relatively small amount for selling shareholders, and management retain very large positions - so an owner managed business.
Downside risk seems that it's only recently started producing big profits.
I'll check out the video, and have already put it on my watchlist to possibly buy when funds allow.
Regards, Paul.
Thanks for your thoughts Paul - very interesting commentary.
I start my input by saying I am not an economist.
BUT IMHO the banks putting up interest rates is completely the wrong thing to be doing and will itself add more inflation as companies pay more to borrow and to invest in capital items.
All of the current inflation is supply side and probably 80 - 90% because of oil / gas / energy pricing. Interest rates increasing will not change this and will not impact this. There is no sign of the economy overheating. None of the inflation is due to demand (though there are some supply issues ongoing because of ripples from Covid / China lockdowns / government sanctions upon various countries/trade issues). Personal spending is flat / slightly increasing in the last measure.
The only area where we seem to be in a boom is employment. This means more people do have a salary and hopefully more disposable income. This is a good thing and also helps the government in terms of the tax take they get.
The trouble with the dialogue we are seeing from government and media (and city people) is that they are assuming a recession and, thus, causing a recession. My friends working in capital items have seen a slow down - only due to fears (from the government / media dialogue) and from companies impacted from oil/gas/energy costs. This of course then rattles through other sectors like services.
IMHO they should lower interest rates and feed the economy - its too late on inflation. They can only further improve this by stopping the Russian war and war crimes, and opening up trade between nations (not having a BREXIT / NI trade war)
Sorry for my rant. I just think there is a lot of "me to" thinking based upon previous inflationary periods and not enough actual thinking and analysis.
I am not an economist
I agree, certainly that I don't understand the link between bank rates and inflation this time. This is nearly all supply-side inflation, with some wage inflation already started because of competition for employees. The second is a good thing, isn't it? But higher interest rates now leads to indebted people calling ever harder for more to cover eroding disposable income. Not their fault, but doesn't solve any macro thing.
The only way out seems to me to be supply-side. For instance, lower energy prices and more flats/houses available for sale and rent. The UK is almost uniquely badly situated to solve this, which is why I have most of my investments working overseas, albeit through UK PLCs. For instance, I can't see me selling VinaCapital Vietnam Opportunity Fund (LON:VOF), Somero Enterprises (LON:SOM), Wentworth Resources (LON:WEN), Diversified Energy (LON:DEC), Atalaya Mining (LON:ATYM) any time in the foreseeable. I'm nervous of my SCS (LON:SCS) holding, even with its balance sheet, just because it's UK retail.
I can't see how higher interest rates help. My concern is how the UK might now experience a new brain drain. If I were younger I would be considering it.
It is true that increasing interest rates is usually intended to throttle demand in an overheated economy but that is not to say it can't help on supply side as well. Putting up rates improves the currency value. If you are buying your raw materials from overseas and the pound sinks, your costs go up meaning your prices need to go up meaning inflation goes up. The Fed being more aggressive with the rate rises than BoE is case in point, look how pound has tanked against the dollar. Good news, though, if your US is your main market for selling into.
Nick (and also raggedtp), you say you're not an economist. I have practiced the dark arts in the past and I would broadly agree with your statement: "All of the current inflation is supply side and probably 80 - 90% because of oil / gas / energy pricing." But when you say that: "Interest rates increasing will not change this and will not impact this. There is no sign of the economy overheating", I believe that you are wrong and I think it's an important point for our expectations of what lies ahead.
As I and many others would see it, the big picture is that the economy is no longer capable of the same level of output as it was pre-pandemic and pre-war (*). The economy is overheating, it's just that it's nothing to do with increased demand. Imagine a plane that has lost 2 of its engines and the pilot is demanding that it maintain altitude. So we have 2 choices: let inflation (overheating) run riot or shrink demand to match reduced supply. For many reasons, shrinking demand, if necessary via recession, is the right answer. High inflation, is simply not a long term solution. The problems just get worse.
There is no short term prospect of a resolution to our supply problems (energy, food, labour) so we must expect a lower starting point for the level of output we are capable of, hence lower GDP, lower profits etc. But also, we might have to accept a lower growth rate going forward, because without improvements in supply, any growth will soon be bumping up against constraints.
(*) That's the simple version. The slightly more complicated version says that actually GDP does go on increasing due to population increase and improvements in productivity. These are long term forces that don't change much, but mean that the path for GDP is always slanting upwards. So what we should say is that the economy can not resume the same path, or trajectory that it had 2009-2019.
On economy overheating - I think all the cheap money and QE over the last 14 years is finally coming home to roost.
While individually certain markets can be justified there are so many assets that are arguably bubbles (or were only a few months ago) because of internationally co-ordinated cheap money - housing, bonds, crypto, tech stocks, tech VC funds, private equity valuations, NFTs, art market etc etc. I believe these bubbles are strong evidence that we have had excessively loose monetary policy
Also when looking at the domestic UK economy, we see sharply rising house prices, vacancies > unemployed, services inflation rising too (not just goods). Weak sterling. Raising interest rates seems to me to be entirely rational. Otherwise, we risk a Turkey style outcome.
I would agree that QE has pushed up asset prices and been one of the main reasons for some bubbles - but this has very little impact on the real economy.
QE just swaps one government debt instrument (higher interest bearing bonds) for another (lower interest bearing cash). It is confined to asset portfolios and very little of it leaks in to the real economy because the transmission channels are weak. Large scale QE has been happening for 20 years and across that whole time there has been more danger of deflation than inflation. Now suddenly we have high consumer inflation. How come? Switzerland, where they have been printing money on a large scale too has 2.9% inflation. How come?
There are good reasons that explain both the long term record and Switzerland now, they have nothing to do with QE. Occam's razor applies.
Do you not think the last two years have been different though in 08/09 the banks held on to the money and we had asset price inflation in the stock market, in 2020 the b of e rustled up £440 billion for the UK goverment to give to the general public to live on.
I'm sure there were many people who did not need the money and spent it on new cars etc 1p on income tax would raise roughly 6 billion so this was like putting basic rate tax up to 99p in the pound.
The US and Europe did from memory 5 trillion combined again new money getting spent granted Chinese lock downs haven't helped but I'm struggling to see how all those trillions handed out to the population didn't at least in part impact on where we are today.
My understanding is that if M2 goes up which it has hugely inflation will follow.
Interesting Volte Face this morning at M&C Saatchi (LON:SAA)
https://www.investegate.co.uk/...
Morning Paul and fellow Stockopedia members.
Thanks for your commentary and honesty.
A couple of thoughts:
Is there blood on the streets? - Yes.
Is there capitulation? - Yes, probably but could easily be more
Is this the bottom? - Further falls definitely possible.
I am fully invested in microcaps where I see long term potential and sector tailwinds. No consumer discretionary, no retail, no drug development, no oil, gas, mining exploration, no binary outcomes. Nearly all B2B.
I have heard some commentators say that the first signs the market was falling, could be seen in Bitcoin which has fallen from over 60,000 to under 21,000 so approx 60% fall (massive) and FWIW I detest BTC. But this capitulation could be seen as the 'canary in the coal mine'. Interestingly, these commentators also suggest that the market will only bottom out when BTC stops falling. This may be something worth watching.
Good luck to all in these challenging times for investors.
Michael
“that the market will only bottom out when BTC stops falling”, assuming it will. I tend to agree with Buffett that the lot is worth less that $25. Buffett on gold here (2011 AGM):
https://open.spotify.com/episo...
is excellent and you could easily replace the word gold with the word crypto.
Except I have a large proportion of my portfolio in gold miners (CAD) and am down less than 10% for the year. Rangebound they say? Thanks very much I reply.
IncredibleMosesLeroy - well done!
Whilst it always sounds like you are blowing your own trumpet when things have gone relatively well it is also quite therapeutic and good for cementing your own ideas. So here goes. My portfolio is down 2.8% on the year so far. The good news is L&G Commodity Fund , a Gold ETF, shorts on 10 year gilts and Treasuries. Still hold gilts sold Treasuries for 27% gain. 10 to 20% cash. I am trying to use cash to take small turns on good news from companies fully aware that can turn nasty. On the less good, 6% holding is Simec Atlantic, belief the new energy regime will need to include wave technology, but bal sheet awful and survives through grants. Sorry Paul as ever should have kept my discipline. Too high in retail, hold Quiz, Sosander, Rev Bars and Unbound, would struggle to get out so will have to maintain nearly 15% exposure and see what comes out far end. Some of my balance sheet plays have weakened recently Record, Spectra, Sylvania. Broadly flat on index linked Gilt but hard to qualify as Hargreaves Lansdowne quote the clean price which isn't helpful at all. Question is where from here and I am really struggling with that. I suspect it will be different this time and there won't be an immediate bounce back. My reasoning being that all recent bounce backs have been a result of massive central bank help. That won't be there this time and higher interest rates/inflation are resetting the investment world. I also think the basis of our societies is energy. This has to be rebooted as we look for alternatives, perhaps the suppliers of this offer hope, just not the underfunded ones!! Defense is clearly going to be more in demand as is IT Security. Maybe the cash generation of BOTB will be a sensible place to be as people search for amusement. I think the big answer for this morning is I have no idea, even after this, where we are going, so perhaps cash is king, but should it be Sterling.........oh dear!!
Shows the importance of a diversified portfolio. My energy holdings such as BP, Shell and Glencore (and to a lesser extent insolvency firms such as Begbies Traynor (LON:BEG) and Manolete Partners (LON:MANO)) have offset some of the steep losses elsewhere, and prevented this year from being a complete disaster (down around 8% YTD).
I think you also need to keep a portion in companies whose earnings are uncorrelated to the economy - on that basis see very good value in Burford Capital (LON:BUR) - its has had a miserable few years but am hopeful some big case wins will shortly start to come through, which could finally trigger a proper re-rating.
I hold Manolete Partners (LON:MANO) and £bur for similar reasons. I worry though that Burford's business may suffer a little as cases are long term and inflation will eat at their values. I appreciate that awards usually include an element of interest but interest rates are lagging inflation at present.
Hi
i am deeply underwater on Boohoo which has been very popular with Stockopedia readers. Given there is a danger of being taken private and many of us are holders. What is your opinion on its value today ?
It strikes me that people still need clothes
I don't know what to do: sell , sit on my hands, double down ?
Thanks
I was also deeply underwater on a large Boohoo position, which I cut a few months ago, taking a significant hit. I averaged-down, which in retrospect, was a very foolish thing to have done. I should have exited quickly when it was blindingly obvious that I was wrong.
Like most of the people here, I try and understand the fundamentals of a company, but I was blindsided by the reality, which was that the share was in a long-term downtrend. Lessons learned: never ignore what the market is telling you. Don't ever average-down a losing position. Keep a position size small until it proves to be a winner.
If I was still holding Boohoo or anything similar, I'd now wait and see what happens rather than adding any more capital. Some books that I found useful in understanding the pros/cons of this sought of decision:
- Trade Like a Stock Market Wizard - Mark Minervinini. There's also an excellent podcast where he summarises the main points.
- The Art of Execution by Lee Freeman-Shor.
Good luck!
Good advice BattleofBrit. Naked trader books sum up your thoughts very well and well worth a read.
Hi Shrubby,
Boohoo (LON:BOO) has always been a long-term position for me. Obviously the fundamentals have deteriorated badly in the last year, but that's due to clearly identified problems - higher costs of inbound freight, which is impacting everyone in the sector, but should reduce in time. Also, BOO in particular relied on cheap air freight, for distributing all its product worldwide out of the UK. As air freight is now expensive, it's been a big hit to them, and delivery times in the US in particular are recognised to be unacceptably slow at 7-10 days, which is no good for fast fashion, people want something to wear for the weekend. That's why in the UK BOO is still trading alright.
They're fixing things, but it takes time. A new US distribution centre in Pennsylvania is opening soon, but they're saying mid-2023 to be fully up to speed, expect upside on the timings, they indicated in recent webinar that the timing guidance is deliberately cautious, as a big distribution centre takes time to build up. That should be transformative for the US side of the business, as it will allow next day delivery across most of the US - making BOO far more competitive than the key rival, Shein.
Other improvements being made include automating the 4 UK distribution centres, which is expected to reduce labour costs by £25m p.a., and will be another competitive advantage over smaller rivals.
The most recent update was in line, not a profit warning.
Investors are I think spooked by sales going into decline, but Q1 was expected to be soft, since the comparative is very strong (the last lockdown, when physical stores competition were closed). The pandemic effect has now washed through, and comps are now softer, so we should see growth resume.
Remember that the 2-3 year growth on pre-pandemic, is huge. It's just that the growth was front-loaded into 2020, so the performance since then has looked lacklustre because 2020 was so strong. That's all through the system now, and hopefully we should see a return of more normal, structural growth. If so, then this could re-rate the share upwards very significantly, from such a low level.
The downside scenario is that there's more competition now, and Shein in particular, might be eating Boohoo's lunch. Only time will tell. Mgt sound confident, but they've been over-confident in the past.
Other positives include an increase in wholesaling, which is a nicer, lower risk, less hassle sales route (the buyer has to cope with customer returns, etc).
Customer returns have always been the bane of life for eCommerce fashion businesses, and that needs a tighter grip.
I would suggest people watch the last webinar from BOO management. As Mahmud Kamani, the joint founder says, "We're dealing with it" - i.e. they know what all the problems are, and they're being sorted out, which takes time.
My view - well probably best to ignore it, as I've been a perma-bull on this share, whilst the price has collapsed! However, my stance is on the long-term fundamentals of the business, and I think this remains very positive. At 50-60p range currently, I think this is a historic buying opportunity. Sentiment could change very rapidly, once it returns to revenue growth, and the costs of lower in & outbound freight come through. Hence why I think it's a future multibagger. But that obviously depends on future performance.
In the meantime, I hope mgt don't take it private, but that must be under discussion with the market cap now so low.
Regards, Paul.
Thanks Paul.
Do you have any thoughts, having previously been at the coal face of fashion, what you would do about the returns “issue”?
On taking it private I also hope not. That effectively happened with £RRE (sold to a larger oil company) removing the possibility of me participating in the upside. Imagine where the Rockrose price would be now!!
On Boohoo (LON:BOO) this is what happened the last time the price fell 50% (the market got it completely wrong that time and there is no reason why the havent this time. Having run my own business for 30 years, I know that when the shit hits the proverbial you don’t just sit there and go “oh well”, you find solutions and actually, assuming you survive, come out the other stronger.
Boohoo price 2014 to 2017:
Regards
Michael
What I do if I'm struggling to sell a losing position is sell half or a third. After you have sold some it becomes a heck of a lot easier to sell the rest. I sold out of Boo at 272, down 20% which is late for me, and I really kicked myself over. I normally assume I've made an error if I'm down by10% and close it straight away. I notice that I sold about 20% at first but was fully out in the next 24 hours (nothing really changed pricewise, just my mindset about the stock). The only way to be able to invest is capital preservation. If you can hold losses to <10% then the 2 or 3 big winners a year will sort you out.
Also, when I sold it it was below all the moving averages which were all going down (10d, 21d, 50d, 200d). That situation has now lasted 11 months. If you are holding all your position in that situation then most of the time you will come off badly. In that situation I'd say "stuff the thesis, I'm out". If the stock is that good, when the whole market recovers the stock will start a new uptrend which you can buy into. It may be higher than before, but you have taken the risk out of it. Leave the first 20% and the last 20% to the other guys.
After this awful market there will be a new bull market. You need your capital for that.
I agree with you 100%.
The most valuable investment lesson that I ever learned was to quickly exit losing positions. If you don't do that, it's highly likely that you'll eventually lose a large amount of your capital. It seems like a simple thing to do, but I think it's the most difficult thing to achieve. I expect that 90% of people cannot do it - which explains why most people lose money when investing/trading.
What most people do not realise is that a 33% drawdown requires a 50% rise just to break even. While a 50% drawdown requires a 100% rise. This is why it is so critical to exit losing positions before the drawdown rises much beyond 20%.
well written Paul, objective and insightful.
I will add that I watched an very good video on youtube (normally not to be trusted at all !!) from a professor at the Stern University New York, Aswath Damodaran. It is about inflation (specifically in the US) and the effect on equity prices. 'In Search of a Steady State : Inflation, Interest Rates and Value' for those that have a idle 1/2 hour !
Aswath Damodoran is always to be trusted IMO! :-)
I enjoy your analysis Paul and I enjoy your musings more. I salute your honesty and commiserate with you right now. Our politics differ though and I moved to 60% cash in 2016 which was much too early. Although advising anyone who asked to stay out of the markets I couldn't resist dabbling which in general has been a disaster, however I have a long watch list thanks to Stockopedia and expect to soon put a lot more of that cash to use. FT readers will have read Katie Martin's article today with the heading We are not at Capitulation Yet. I agree with her, painful as it is right now. The new acronym has changed from TINA and FOMO to FOHO, fear of holding on. Good luck friends.
JASVFS. Have you been 60% cash since 2016?
Regards Michael
Paul or subscribers - any views on Halfords (LON:HFD) after the crash? It is another on a PE of 5 or so, dividend yield now nearly 7%, and seemingly well covered. Recent results seemed strong on most fronts, but with forward guidance being conservative (no surprise there). I have been watching this business for over 1 year and I am not sure there will be a better opportunitiy to buy into this stock at these levels. Famous last words!
Hi BritishExpat70,
I'm planning on looking at retailers later this morning - in particular,
ASOS (LON:ASC)
Boohoo (LON:BOO)
Halfords (LON:HFD)
Which all fell sharply on trading updates yesterday. Leave it with me, something should be up by noon.
Regards, Paul.
Thanks Paul.
I'm with you on this BritishExpat70, Just waiting for Paul's comments while noting his advice DYOR. It's the amount of debt that's held me back previously but they look good value to me right now.
Good morning Paul. As you say, it is usually queiet on a Friday. Hopefully much 'quieter' than yesterday.
Given the sharp falls in Angle (LON:AGL) and its SP over the period since the FDA approval announcement, the market is clearly in the jam today rather than jam tomorrow territory, and with a vengeance. I believe that is the most significant factor in the SP movements, and will be looking to add to my hoding if there is much further weakness in the coming days.
You made some very realistic and sensible comments on the 6th June, so much so that I decided to follow them up. For the benefit of other readers here and now, these were your very fair specific comments:
Amazing to think that Angle has been listed for 18 years, and is just closing in on share price breakeven from the original float (with no divis along the way)! Although it looks to have started out as a technology incubator, and then changed direction subsequently to focus on Parsortix. Looking through the historic RNSs, I see Parsortix was granted a US patent in 2011. By the time AGL actually sells anything meaningful, there won't be much time left on that patent.
I followed these up with the company and this is the comprehensive response, including a short but significant comment on patent protection specifically.
Core patents covering the Parsortix microfluidic platform extend out to 2034. We continue to build out our IP with new patents as new discoveries are made.
Fortunately, there was more on the strength of the moat which is always of interest to us all.
In addition to patents, we have extensive know how, which is kept secret, and copyright in the form of software controlling systems and protocols. Beyond that, further protecting our position is the wide range of third party peer-reviewed publications (now over sixty) providing a body of evidence and credibility.
We thus have many years of competitive advantage surrounding the core technology and we are continually building this out further. In addition, FDA would require any competitor looking to exploit our new Class II Device designation via a 510k submission to repeat the data package that was required for Parsortix which would take many years of effort and substantial cost.
There are elements of the model system that we developed for FDA clearance, which were highly technically challenging and have not been, and will not be, published so substantial innovation will be required by any other company seeking a similar FDA clearance.
The other comments you made on 6th (see below) are still as relevant, and the dangers are there. We will see!!
This is the trouble with innovative medical companies on AIM - it always takes an eternity for them to commercialise things, with repeated fundraisings, and if they do succeed then a bigger player bids for them, taking away the upside. Hopefully for you, Angle might be an exception to the usually dismal performance of innovative medical shares?
I will now return to the Discussion Board area and may never be seen here on Angle (LON:AGL) again - well not for a while.
spot on thinking
Lovely macro summary Paul. Thank you.
In many years subscribing to Stocko I don't think I have commented before, but just had to say "brilliant article, thanks Paul"
How kind, thanks Friday31 :-)
Re Paul's honest commentary. He mentions excellent mortgage deals. As a silver surfer with a paid-up mortgage, I would be in 'Mire' Street if it were not for Equity Release. Just saying.
There's quite an interesting article in The Times today from business CEOs saying how they are seeing consumer behaviour change. Lloyds' CEO says about 80% of consumers only have easily accessible savings of less than £500 which is a pretty stark statistic and thinks 20% of consumers will have to make material adjustments to their spending. Tesco says they are seeing softening of non-food.
Another pummelling yesterday! Trying to keep a sense of humor in these dark days of frequent 2-3% down days. I now have a large portion of my portflio that consists of beaten down small caps on a PE of 5-8, many now with over 5% yields! Congratulations to anyone who had the discipline to move into cash at the start of the year, when the wheels began to fall off. To have all of that dry powder to pick up great businesses cheaply in this market would have been a dream come true.
Somero Enterprises (LON:SOM) hammered despite a positive update, Volex (LON:VLX) seems to continually bounce off a bottom at around 220p, Reach (LON:RCH) now appears extraordinarily cheap with a dividend yield of 7% and a PE of 3!, Lords Trading (LON:LORD) now down to a PE of 10 despite their very credible growth story amd National World (LON:NWOR) will soon be valued at less than its cash. I could go on with plenty more examples but it would be too depressing. I keep wondering if I should sell, decide that they are already beaten down massively so I stay the course, and then wake up the next day with 3% less of them.
I am extremely tempted to buy Hostmore (LON:MORE) at this price of 33p. It didn't collapse further in yesterday's big sell-off, so may finally have found a bottom, 80% down from list price. However, this would simply repeat my modus operandi of adding PE=4 stocks to my portfolio on a 3 year view. Maybe I am getting sucked into value traps thinking I am getting bargains.
Good luck to everyone as you navigate through the pain, and find the multi-baggers for the next leg up, maybe in 2023.
I wouldn’t be too worried about the current volatility provided you are invested in great healthy companies , just keep reviewing them and trust your numbers .
I trimmed a lot of my portfolio to cash (35%) in January but stayed invested in the ones that looked to be great companies in great sectors , with cash , making goodl profits and most whilst down are not being obliterated .
I owned a business for 30 years and went through two big recessions at no point did the fall of the stock market make me look to sell my business .
I now view it that I own 10-15 businesses and the stock market movements does not affect the business . The difference is of course
- the ease by which I can now sell (too easy )
- the fact I cannot influence the company hence I have to believe in the management , this is a massive thing , absolutely ditch everything where you don’t believe the management are there for you .
Hostmore is cheap and a bargain buy but I just don’t like the management and where they have come from.
Ditch every single company where the management issue free options or even worse re-issue their previous options that they now know they wont get - this is a shocker and tells you everything about them.
I was lucky enough to put the bulk of this 35% into sone oil stocks plus just caught Bank of Georgia and Georgia capital at the bottom of their curve and this has meant I’ve not been totally battered (still 10% down overall )
I’m holding some of yours -
Somero looks ok though it could be at the mercy of a US dip but I don’t see it . Plus it is swimming in cash , pays a great dividend , and has good IP and products . So it’s a hold for me .
Reach / NWOR - I had big holdings in both but sold my Reach as I just think NWOR is younger /cleaner and with a driven management . Shoukd be more nimble . National world I keep adding and it keeps dropping but the. “Cash in the bank doesn’t lie” no matter what Mr Market thinks .
Volex I sold out of as it didn’t make it to my short list and to be honest the volatility was doing my head in .
Don’t forget also the 2 year rule for AIM shares generally gets you IHT cover , with the exception of National Workl and Bank of Georgia all my holdings are AIM IHT qualifying so it is not advisable to jump in / out of these if IHT exemption is important to you (it is for me )
Bizarrely and interestingly my biggest holding is a real value trap Holders technology but I actually invested knowing it was a valuer trap and would force me to hold for many years,. Possibly a foolish experiment and bizarre way to force me to stop being a trader and start being an owner again.
This is a company I am now holding 9% of , I probably can never sell the shares .which could be a real stupid / dumb move on my part .
But I looked. t them very closely and the company is run for the absolute benefit of its shareholders , stacked with cash and assets and zero interest in taking in debt . Which just reminded me of how I did it with my business .
I met the chairman / founder at the AGM and said to him
“I am investing in this company not trading shares, the reason is you are like a Northern pig farmer - that’s what I like about you "
He looked confused (he’s Austrian ) , his CEO looked annoyed and his advisor was about to ask me to leave .
“No that’s a good thing “ and I added in broad Yorkshire before attempting to clarify
“I don’t owe no bugger nowt , all these pigs are mine and paid d for now bugger off "
followed by
"Its a compliment, good to be a Northern pig farmer - I like you "
My point is great company , great sector , been going 30 years , going to be here in 30 years . I own part of it and it’s stock market price is irrelevant to me as I have made the decision after my research I wanted to stick my cash here for a long haul
Love it.
Hi planetx,
Insightful, and very amusing too - what could be better?!
Best wishes, Paul.
Excellent comment. Thank you.
PlanetX, thanks for your thoughts and write up. As an aside, got my 11 year old Nanolight out yesterday, quick wash and lube and still rides like a dream.
Good to hear, that was a nice bike super comfy ride . Glad you like it and glad its going strong,
I own Somero Enterprises (LON:SOM) Volex (LON:VLX) and Reach (LON:RCH) as well and do not intend to sell. I am 50% off from my ATH and something like 25% YTD, but to reprise my other comment have companies like these (I also hold Ergomed (LON:ERGO) Bioventix (LON:BVXP) Boohoo (LON:BOO) MPAC (LON:MPAC) Tremor International (LON:TRMR) Games Workshop (LON:GAW) ) lost 50% of their (intrinsic) value? I think not. They are debt free (except MPAC (LON:MPAC) pension deficit and MPAC is one of my few holdings that are not underwater) and I believe sound businesses.
Also while in principle “Congratulations to anyone who had the discipline to move into cash at the start of the year, when the wheels began to fall off. To have all of that dry powder to pick up great businesses cheaply in this market would have been a dream come true.” But would they have the courage/foresight to move back into the market without thinking “it’s going to fall more or “this is another dead cat bounce/bear market rally before continuing downwards.”
I sold at the bottom in March 2020 and managed to come out flat on the year but if I had remained full invested I would have been up 30%+.
Regards
Michael
[edit] it has a hell of garden though http://t3.gstatic.com/licensed...
Trentham Estate has been there for years and is now a modernised venue which attracts families. My son took his kids there and they loved it. I saw some proper bands there in the late 70s early 80s when it was one of the countries finest rock venues :)
Given the current carnage I decided to do a deep review of my key holdings to make sure I haven't been one the wacky baccy .
Started today with Avingtrans which is one of my top holdings .
Its quite a complicated business comprised of a small mix of companies but all in really strong sectors.
This is interesting reading in the 6 month report and struck me that given the windfall tax on energy producers there is about to be an almighty surge in expenditure (as it is I believe 90% deductible against the windfall tax ?) .
So every FD is going to be giving the green light to the projects requiring cap ex as he literally "gets his money back" .
"Hydrocarbons
As oil demand has picked up following the pandemic easing, so the oil price
has followed and the Brent crude price is now trading in the range of $90 to
$95 per barrel, with informed forecasts suggesting a price of $100 a barrel is
possible next year. As a result, new capital expenditure in this sector has
recently begun to recover but our forecasts continue to exhibit prudence, with
some limited restructuring activity in EPM being completed in the half, mainly
due to the relocation of Energy Steel. Aftermarket orders continue to
increase."
All the associated strains of Avingtrans are in real good areas such as
- Stainless metal craft - nuclear waste storage (lots of contract wins past year plus a huge 700m due to be awarded in 2023 ). Big tick on that one.
- Booth industries - industry leading blast doors - big tick
- Magnetica - Mini MRI scanners, new area sucked out 5.1m cash invested, not sure on this but huge market if successful
All solid enough but the hydrocarbons comment is what caught my eye, might be worth watching out for contract wins in those area and then looking down the supply chain to see who are going to be the beneficiaries of the huge Cap ex investment about to be unleashed by the windfall tax companies who will be "forced" to get cracking with all these new projects because if they dont they just give that money to the chancellor .
Avingtrans I am happy enough to hold and it is bearing up pretty well , it is not super cheap but looks to be a beneficiary of whats happening in the world .
- has 22m cash (even after spending 5.2 on magnetic)
- cash inflow last year 4m
- 135m market cap
Thanks Paul for your commentary. It's a really difficult time to be an investor, that's for sure. For what it's worth I don't think markets have yet capitulated. We need to see a big drop. Most of us are UK investors, me included. However, its certainly worth looking at things like Tesla which was a market leader. It's only down 50% from its absurd high. Probably needs to be 80-90% down. Crypto is the other "asset class" which could well implode sometime soon as "currencies" go down. Until all the bubbles have fully deflated we probably have more to go.
Very interesting point you make on 5 year mortgages. Interest rates are nowhere near where they should be. Central bankers: combination of money printing on an epic scale and then being reactive rather than proactive shows that they are all woefully behind the curve.