Small Cap Value Report (Fri 17 May 2024) - PFD, FRP, FA., XLM, COST

Good morning, just Paul today!
I'll leave it there for the day and the week. Have a lovely weekend, and don't miss my next thrilling podcast instalment this Sat or Sun :-)
Last call for Mello Chiswick, which is next week! The schedule of excellent speakers has gone live now. It's great for meeting & socialising with other investors too, and you get to meet management at Warpaint London (LON:W7L) - I think they deserve a beer or two from happy shareholders!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
List of Companies Reporting
Slim pickings today, but I won't relax as sometimes the RNS plays tricks on us, and a load more announcements come through later! In any case, we've got mountains of backlog stuff to keep me busy, so there will be a full report up by 13:00 UK time.
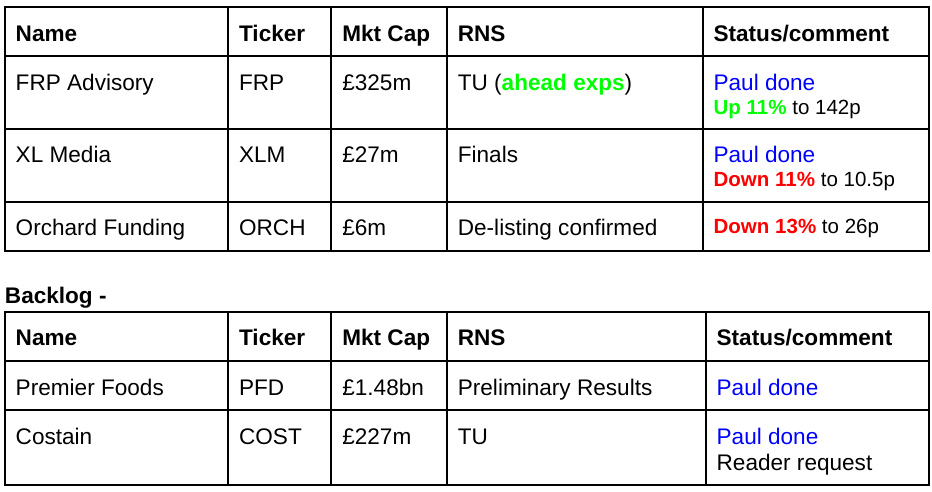
Other mid-morning movers (with news)
Fireangel Safety Technology (LON:FA.) - up 35% to 5.75p (£11m) - Conditional approval of takeover - Paul - PINK (RED on fundamentals)
The takeover bid has been on hold for a while, awaiting UK national security clearance. Today this has been granted, subject to several conditions. The bidder says “ISE is considering the Approval Conditions in order to determine whether it considers them to be reasonably acceptable to it (as is specifically required in order for the NSIA Condition to be satisfied).” FA seems to have issued an identically-worded RNS itself.
Paul's view - As usual, due to the huge number of rule 8.3 and 8.5 announcements, it’s difficult to find the original takeover bid RNS. This seems to be it here from Oct 2023, where the price is a very generous 7.4p cash - I say generous, because FA’s performance has been utterly dire, and I would have valued its equity at zero personally. Given that it’s already been a long and tortuous process, the potential for this bid to fall through is probably significant (without inside information, we don’t know how much risk). So the upside is getting paid 7.4p in the bid happening. The downside risk if the bid falls through? It could easily be a zero I think, and the bidder could just buy the assets out of administration. With such unfavourable risk:reward, I’d say 5.0p bid price in the open market today looks an attractive lower risk option.
Summaries of Main Sections
Premier Foods (LON:PFD) - 170p (£1.48bn) - Preliminary Results FY 3/2024 - Paul - AMBER/GREEN
Decent results yesterday, beating expectations. I remain moderately positive on this foods manufacturer, despite a strong rise in share price it still looks reasonably priced. Especially as the pension deficit has now gone.
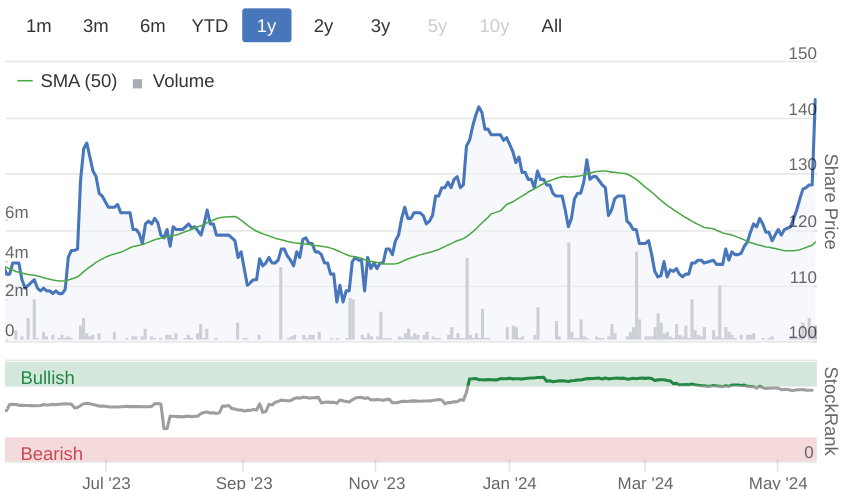
Frp Advisory (LON:FRP) - Up 12% to 143p (£364m) - Full Year Trading Update [FY 4/2024] - Paul - GREEN
Announces a good beat against market expectations for FY 4/2024. The outlook also sounds healthy, and all parts of this insolvency/advisory business seem to be doing well. Balance sheet is nice, with net cash. It has to be GREEN. BEG also worth a look, given the favourable backdrop for this sector.
XLMedia (LON:XLM) - down 11% to 10.5p (£27m) - Final Results - Paul - AMBER
FY 12/2023 results are only of passing interest, since a large disposal was done post year end (see SCVR 21/3/2024). I dislike this sector (digital marketing for gambling companies) because profits can evaporate so easily when the advertising algorithms change, outside XLM's control. At least the balance sheet worries have now been sorted, so I can just be neutral overall at AMBER.
Costain (LON:COST) - 81p (£227m) - AGM Trading Update - Paul - GREEN
An in line update yesterday. It's better than I thought, so thanks to the reader who persuaded me to circle back to it today! Very good cash position, and improving margins mean this looks to be headed for useful increases in EPS. Still looks cheap, providing nothing goes wrong, even after strong recent gains.
Paul’s Section:
Premier Foods (LON:PFD)
170p (£1.48bn) - Preliminary Results FY 3/2024 - Paul - AMBER/GREEN
It’s been another busy week here, where we couldn’t cover every company reporting. So as you know, we have to prioritise, and we follow what you’re most looking at (using the “most viewed” widget on the home page), then we focus mostly on ahead of expectations updates, and companies where we think there’s potential upside in the share price, and large % daily movers. PFD slipped through the net yesterday, and befuddled by the 1-hour time difference here in Gozo, I got up too early today, so let’s make use of the time!
PFD is a large food manufacturer, with well-known brands, such as Mr Kipling. I did a quick review on 6/3/2024 and concluded positively at AMBER/GREEN, based on a reasonable valuation, good performance, rising forecasts, decent profit margins for the sector, and best of all - the ending of pension scheme deficit payments in 3/2025, which opens to the door to more generous divis.
Results 3/2024 -
“Full year ahead of expectations and return to volume growth in Q4”
Revenue up 15% to £1,123m
Adj PBT up the same, +15% to £158m
Adj EPS up 6.4% to 13.7p (PER 12.4x)
Net debt down £39m to £236m incl leases, and £223m excl leases, with “lowest ever” gearing of 1.2x EBITDA
Pension deficit cash payments suspended from 1/4/2024.
“On track” for FY 3/2025 expectations.
That all looks pretty good to me. I like the very good 14.1% PBT margin, demonstrating its brands have good pricing power.
Pensions - important to note that these are still giant schemes. Total assets now £3.57n, and liabilities £2.96bn. Both numbers can move around a lot, but this is still a large accounting surplus of £602m. In the past I’ve always focused on the actuarial deficits of pension schemes, because that’s what determines the cashflows. Although as pointed out by I think it was davidjhill here recently in an excellent reader comment, higher interest rates have changed everything, so that the actuarial and accounting deficits in pensions schemes are tending to converge. That’s such a good point, and it means that deficit recovery payments are sometimes reducing or even stopping. Therefore shares which traditionally had pension scheme problems are now becoming investing opportunities in some cases, as the cash payments into the schemes stop. Might this be good news for other companies, e.g. Reach (LON:RCH) , Renold (LON:RNO) , and Norcros (LON:NXR) spring to mind. Note that Wincanton saw an end to its pension contributions, and shortly afterwards received a takeover bid approach. So this is certainly a very interesting area to investigate for possible bargains, although pension scheme accounting is certainly not simple. Also unexpected events could cause deficits to potentially resurface, eg if Govts find they cannot cope with higher interest rates, and fall back on QE and free money again. We’ve got to consider all potential risks, and huge pension schemes still worry me, even if they are in an accounting surplus.
Dividend - only a final is paid, no interim. 1.728p is far from generous, at a yield of only 1.0%, so with pension payments stopped, there must be scope to increase this?
Balance sheet - is large & complicated. NAV is £1,327m. To make sense of it, I will eliminate several lines: £992m intangible assets, £810m pension asset, £(209)m pension liabilities, and £(153)m deferred tax. Getting rid of those strips it back to what I see as the core balance sheet, at NTAV of £(113)m - not great, but also not a deal-breaker for a business that is strongly profitable & cash generative. So it gets a cautious thumbs up from me, although I’d like to see borrowings continue to reduce. Lease liabilities are very small, so I suspect it must own a fair bit of freehold property. Note 11 to the 2023 Annual Report shows £55m in land & buildings, which seems to be at depreciated cost, rather than valuation - so a good question to ask management is to reveal the market value of that property?
Cashflow statement - looks healthy. It’s a genuine cash generator, and note it spends some of that on capex (not huge at £25m) and is making a series of small acquisitions (self-funded without equity raises). The cash generation would enable the dividends to quadruple - so dividend paying capacity here is much larger than the 1% existing yield.
Paul’s opinion - I’ve got to move on now, but this all looks good to me. Despite a very strong share price recovery, PFD still looks reasonable value to me. I like it. AMBER/GREEN is maybe a bit too stingy, but this type of business probably wouldn’t command a premium PER, so taken with the debt of c.20% of the market cap, maybe the current valuation is in the right ballpark? So I’ll stick with a moderately positive view, AMBER/GREEN.
Note that Asian Nissin Foods owns 24%. Bid potential? It looks too small, but could be part of a larger group maybe - worth investigating.
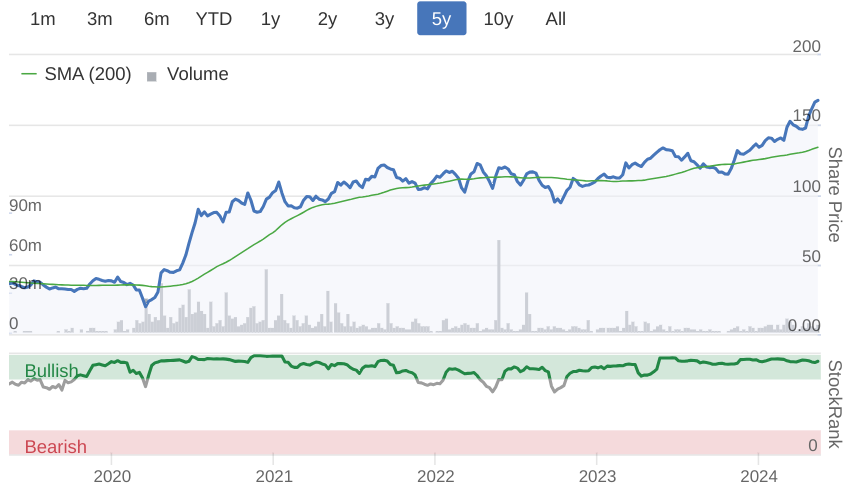
Stockopedia likes it too, with a StockRank of 97 -
Frp Advisory (LON:FRP)
Up 12% to 143p (£364m) - Full Year Trading Update [FY 4/2024] - Paul - GREEN
FRP Advisory Group plc, a leading national specialist business advisory firm, announces a trading update for its full year ended 30 April 2024 ("FY 2024").
Double digit revenue and profit growth ahead of expectations; confident for the year ahead
Excellent trading performance ahead of expectations
FY 4/2024 revenue expected to be £128m, up a striking 23%
Pity they use EBITDA as a profit benchmark - but I can forgive that, as it’s a substantial beat of £5m, 16% above market forecast -
adjusted underlying EBITDA* of £37 million, up 37% on the prior year (FY 2023: £27 million), both exceeding current market consensus**.
** Current consensus FY 2024 market expectations for revenue and adjusted EBITDA of £123 million and £32 million respectively.
Outlook is positive -
Activity levels across all our locations and pillars are encouraging. As a result, we start our new financial year with confidence of making further positive progress."
General market comments are quite interesting - just confirming what we already knew -
- Tough year for many companies due to “increases in interest rates, inflationary pressure, higher costs of living and general market confidence.”
- Company administrations rose by 22%.
- Sectors - construction & retail highlighted as suffering the most.
- Difficult raising finance, as banks tighten lending criteria.
- More positive signs are appearing, but cost base and financing will remain difficult for some.
Back to FRP -
FRP’s restructuring (ie insolvency) division has grown market share from 14% to 16%.
Other divisions also busy.
Acquisitions - 2 done in the year, 1 post year-end, and more in the pipeline.
Cash collection improved in H2.
Net cash £29.7m at 30/4/2024 (up from £22.9m a year earlier) - looks healthy to me.
(I've checked the last balance sheet at 31/10/2023, and it’s good, with NTAV of £53m - no issues here)
Headcount increased 19%
Forecasts - Cavendish (many thanks) issues revised numbers this morning. FY 4/2024 is now 10.0p, (PER of 12.8x at yesterday’s closing price), and it’s only pencilled in 10.3p for FY 4/2025, which I suggest looks too modest, given the upbeat tone and increased number of administrations and restructurings.
Paul’s opinion - looks nice, I would expect a 10-20% share price rise (I've not looked yet!), although these insolvency firms don’t tend to attract particularly high valuations. Begbies Traynor (LON:BEG) is the other one, which might be worth taking a look at too.
FRP is a good business I think, and it seems to manage the conflict between partners and outside shareholders well.
You get a c.4% dividend yield, which is OK. Even though the economy looks set to gradually improve, insolvency firms tend to have rich pickings for several years into a recovering economy, as often it’s the working capital strain of a recovery that finishes off financially precarious businesses. Plus of course higher interest rates is likely to have an ongoing impact, as banks can’t just roll over problem loans if interest payments are not being met, as was previously possible in the 0% interest rate era.
For these reasons, I think we have to be GREEN on both FRP and BEG.
XLMedia (LON:XLM)
Down 11% to 10.5p (£27m) - Final Results - Paul - AMBER
XLMedia (AIM: XLM), a sports and gaming digital media company, announces audited results for the year ended 31 December 2023 ("FY 2023").
Underlying trading was around breakeven, which turns into a massive statutory loss due to a $44m impairment charge.
The 2023 numbers are academic now, since a large disposal deal was done post year-end, which I reported on here on 21/3/2024. This sorted out the previously weak balance sheet, and XLM said it would look at distributing some surplus cash to shareholders.
Certainly the 31/12/2023 balance sheet was uninvestable, due to obviously stretched creditors, eg for deferred consideration, taxes, etc.
Outlook doesn't excite much (as it only mentions unreliable EBITDA which often doesn't turn into real profits or cashflows), and there’s a considerable wait for any (unknown size) shareholder return from the recent disposal -
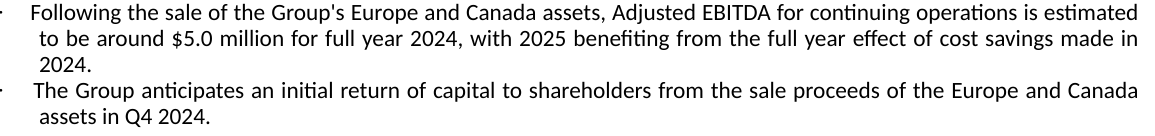
Although to be fair, Cavendish helps us out with forecasts today, saying adj PBT should be $2.3m in FY 12/2024. So maybe the shares are priced about right currently?
Paul’s view - the substantial disposal shows there was some value in its gambling marketing websites. Although I think most of the proceeds is likely to be consumed with costs, and sorting out stretched creditors. What does that leave? A not very exciting, and very small business that’s having to cut costs, based in Tel Aviv. There must be simpler ways to make money, than trying to work out what’s likely to happen in future with XLM. Given the major improvement in balance sheet, my previous warnings are no longer needed, so I’m happy to remain at AMBER. This sector usually disappoints, as lucrative online marketing strategies often seem to have a short life cycle before they’re crushed by rule changes at Google, etc. That’s what has happened before both at XLM, and many similar type of companies, so I tend to avoid all of them, even though they usually look cheap on a PER basis (usually because the market has figured out that earnings are probably not sustainable).
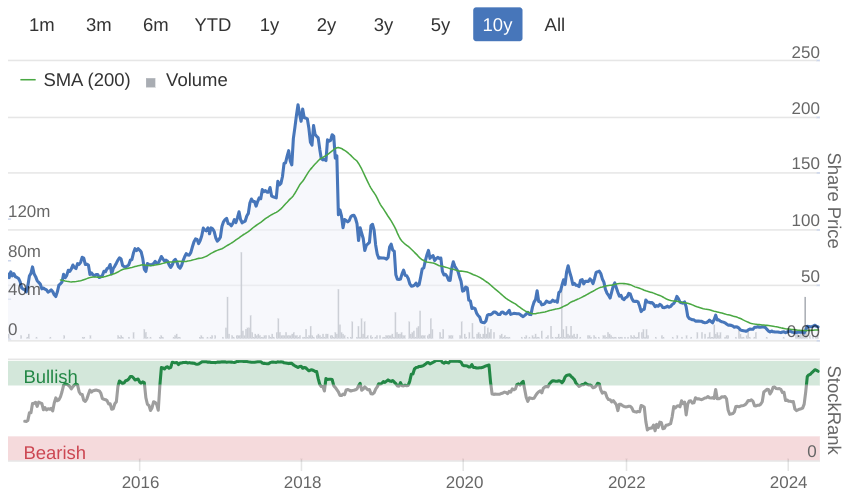
The 10-year chart puts everything into perspective -
Costain (LON:COST)
81p (£227m) - AGM Trading Update - Paul - GREEN
Editors are supposed to make sense of this garbage -
“Costain helps to improve people's lives by creating connected, sustainable infrastructure that enables people and the planet to thrive. We shape, create and deliver pioneering solutions that transform the performance of the infrastructure ecosystem across the UK's transport, energy, water, and defence markets.
We are organised around our customers anticipating and solving their challenges and helping to improve performance. By bringing together our unique mix of construction, consulting and digital experts we engineer and deliver sustainable, efficient and practical solutions.”
If they’d included AI, platform, and diversity/inclusion, then we would have had a full house of current buzzwords!
Why couldn’t they just say: we build roads, water/sewers infrastructure, repair railways, and whatnot?
Looking back, we’ve been positive about Costain, mainly on valuation grounds, despite neither me or Graham really wanting to invest in the sector (low margin contractors) because they so often go wrong -
23/8/2023 - H1 results, Graham saw striking value at 51p/share, so was green.
10/1/2024 - In line TU for FY 12/2023, I also saw value at amber/green, and flagged the pension scheme as something to be aware of.
Trading in FY 12/2024 so far is in line with expectations -
Costain confirms that trading for the period is in line with Board expectations and the Group continues to have a high-quality forward work position that aligns with its strategic plans for both the Transportation and Natural Resources divisions.
Cash position - interesting disclosures here, and it’s great to see average cash becoming a (much needed) more widely reported measure. Clearly this is good news here -
“The average weekly net cash position from 1 January to 30 April 2024 was £168.8m (of which £60.4m was held in joint ventures). The average weekly net cash position for the same period last year was £122.9m (of which £57.2m was held in joint ventures).”
Splitting hairs a bit, but I wonder what they precisely mean by “average weekly cash”? It would be worth asking management if there’s a webinar. That could be the net cash figure on Friday nights, averaged over the period. Or it could be the average net cash figure throughout that week, which would really be an average daily cash balance. Does it matter? Well it might do. It depends on when supplier payment runs are done. For a made-up example, If customers pay COST on Mondays, and suppliers are paid on Fridays, then taking the Monday night cash figures and averaging them would show a much better picture than taking the Friday night net cash figures and averaging those.
Also, I presume the cash within JVs would not be available to COST to distribute to shareholders, so that leaves about £108m of the company’s own cash. Very good for a £227m market cap. We’ve debated before to what extent this cash is COST’s and potentially distributable? I think we should remember that it raised a lot of cash c.2020-21, when the share count more than doubled. I remember that, and the specific reason given at the time was to reassure customers, who demanded balance sheet strength from contractors. Although that was also during the pandemic, when such concerns would have been probably heightened, and maybe not quite so relevant now?
Another point to consider is that COST should be earning a healthy finance income from its cash pile, so it’s not being wasted sitting around doing nothing. If you adjust out the cash for valuation on an EV basis, then obviously EBITDA would lose the finance income from the cash pile.
Outlook - this margin improvement sounds very good, which combined with finance income on its cash balances, could point to nice earnings growth in 2025 -
The Group is in line to deliver its margin targets of an adjusted operating margin run-rate of 3.5% during the course of 2024 and 4.5% during the course of 2025. While the Board is mindful of the macro-economic backdrop, it remains confident in the Group's strategy and medium to long-term prospects.
Broker forecasts - looking at a Liberum note from March 2024, it has 12.3p for FY 12/2024, and 13.8p for FY 12/2025. It also says COST has stopped doing fixed price contracts (so presumably higher inflation no longer a threat), and has scope to do 20p EPS at its target earnings - which would possibly support a share price of say 140-200p in due course - nice upside from today's 81p if the upside case plays out as planned.
Paul’s opinion - it’s clearly too cheap, providing nothing goes wrong. I’m happy to leave the cash as it is, rather than adjusting for it in valuation terms. That gives you a cushion, and the tiny divis are a good indicator that the cash isn’t really free to be distributed. That said, the net current assets at 31/12/2023 was positive £92m, so actually the cash probably is at least partially surplus. Hmmm, this is looking more interesting.
It’s definitely GREEN anyway, I do like this, and my reservations about cash, divis and pension deficit are actually fairly minor compared with the striking value on offer. If the pension payments stop, as we were discussing earlier with PFD, then that could be another upside catalyst.
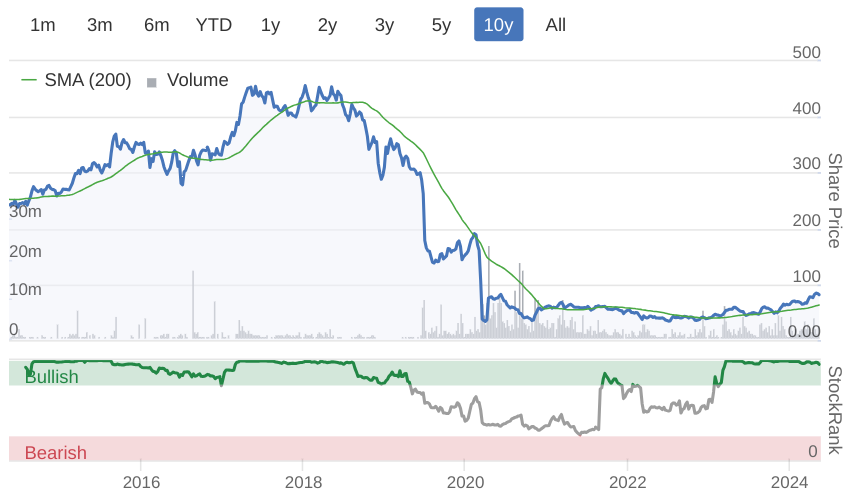
Very poor long-term, and the share count has more than doubled, but it strikes me that the problems seem to have been resolved - great StockRank now too -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

48 comments
Keywords Studios (LON:KWS) I had a full switchback with this one - from doubling initially to then losing about two thirds to then selling a rip back at my original purchase price to buying back pretty much at the recent bottom. Hopefully Monday’s reaction gives me an opportunity to start taking some profits at last.
Well that's a nice start to the week! Keywords Studios (LON:KWS) I was close to selling last week and locking in 30% profit. Glad I dithered now.
https://keywords-offer.com/doc...
Keywords Studios (LON:KWS) congrats to anybody who persisted with KWS, I was early in the process of shuffling back in for my 3rd or 4th attempt so not sure whether it will make up for previous pain yet!
The shorters might be in full reverse ferret on Monday?
May 19 (Reuters) - European private equity group EQT EQTAB.ST is in advanced discussions to buy Dublin-based video game services company Keywords Studios KWS.L for 2.2 billion pounds ($2.79 billion), the companies said in a statement
That is good news, Keywords Studios (LON:KWS) l have held, for just over a year, still under water. This may let me out at a small profit.
Nice premium, unlike some other bids. It is already up 25% this month, even before this bid.
This is the 4th bid within about a month, in my folio, must be a record. Tyman (LON:TYMN), Anglo American (LON:AAL) and IQGeo (LON:IQG) are the others.
Great podcast as always Paul, thanks! Sound track for a half marathon last weekend and a trip in Baku this week!
appreciate the comments the last few months (years!) on Future too. Sat waiting for an entry for 2 years - managed a good load 3 weeks ago for a lovely short term return.
Bank of America holdings RNS for easyJet (LON:EZJ) yesterday, from 10% to 3% of the company, that's down from 12% so I guess it looks like they are selling the lot. Will certainly explain the weakness in share price lately.
Funnily enough they increased their target price to 750p in April, 50% upside... Very odd
Recent weakness seems to be a sector thing - Jet2 and Ryanair also down quite bit since start of April. Don't follow this area closely so not aware of what's driving this, but am keen to take a closer look at Jet2 (LON:JET2) when time permits as seems to be a quality company and very cheap.
Jet2 (LON:JET2)
Must admit i have finally taken the plunge here this week and come on board - i cant really think of anything to put me off here. Obviously with all these companies they do tend to look cheap when things are going well and it doesnt alwasy take much to ruin a year or period even if its stuff that may happen regularly eg excessive strikes by baggage staff or air traffic control blah. In the past i have held easyjet - i feel though that Jet2 seem to have done the better job ref growth in the last few years - whether this will be maintained or not going forward i know not. It seems like most of these airline companies are running reasonably sensibly at present in that they dont seem to be over competing on price. My only slight regret here is not picking up shares last year when they were 25% cheaper - think estimates have been upgraded since then though ref profits so n some respects although price has increased pe multiple still seems good value. Lets hope my turning up hasnt jinxed the party and lets hope this isnt top of the cycle either!
On 12 March 2024 Paul looked at Synthomer (LON:SYNT) and concluded
"A big % riser today, but I'm far from convinced as to the attractions of this potential turnaround. Debt has halved, but is still massive, so no divis for now. Outlook seems quite lacklustre. Maybe brokers have increased forecasts, but that hasn't filtered down to pond life like us yet!"
It was up 30% on that day to 186p, and the price is now 333p. I'm thinking there's more upside, possibly up to 600p according to long term chart signals. What do others think? I'm not very well versed in working out fair value for the share.
I'm going to dip my toe in with a small purchase...
Hi turbo,
Indeed, it's been an amazing share price rebound at Synthomer (LON:SYNT)
To be fair there was nothing factually incorrect in my previous analysis at all, which you quoted. If there was, perhaps you could point it out?
Broker forecasts remain dismal, so they're obviously all missing the point too -
Buyers must be working on different assumptions, that a recovery will be much stronger than brokers are forecasting perhaps?
As mentioned in my podcasts, at the start of a new bull market, it can sometimes be the most highly geared shares which may multibag, because perceived upside suddenly all flows to equity, and debt is seen as less risky. I see SYNT recently refinanced a bond. Hence why I was suggesting last week that it might be time to take some more calculated risks, but on the fundamentals (facts figures & forecasts) we have available to us at this point in time, SYNT looks unattractive.
Looking at SYNT's update on 9/5/2024, it showed some signs of progress, but overall strikes me as a fairly lacklustre update.
Anyway, good luck with your momentum trade, it could work out, who knows? The market clearly sees something positive here, that is not reflected in the fundamentals as yet anyway.
I apologise for being unable to predict future share prices in every case, we just analyse the fundamentals only on any particular day, with the information available.
On average our stuff has beaten the market considerably in both 2023 and 2024, so we're not complete muppets!
Paul.
"To be fair, there was nothing factually incorrect in my previous analysis that you quoted. If there was, could you please point it out?"
Hello Paul,
I apologise if it seemed like I was criticising your analysis. That was not my intention at all. I quoted you to ensure others are aware of the bear case, not to come across as pumping the stock. I should have made that clearer—my mistake!
Honestly, I haven't found anything factually incorrect in your analyses (my fundamental analysis skills are still a work in progress).
Like so many others, I truly appreciate the extensive work you do in analysing companies based on their fundamentals. Your significant contributions to this board are incredibly valuable.
Hope you have a fantastic weekend!
XLMedia (LON: XLM) Ref "I dislike this sector (digital marketing for gambling companies) because profits can evaporate so easily when the advertising algorithms change, outside XLM's control."
It's a noteworthy flag, one that I had not considered. Perhaps blinded by my loathing of online gambling because of the insidious destruction behind the scenes, but not behind the family door, so to speak.
For the reader’s enlightenment, especially if you like online betting, be wary: A friend of mine once worked at Bet365, where his department developed a cunning algorithm to lure customers into gambling on alternative instruments. The strategy involved removing options that customers were notably skilled at, ensuring these choices were conspicuously absent from the table of contents on their subsequent visits. The playing field is anything but level.
One would think the house hedge would suffice, but no—greed drives the company to pick customers' pockets on behalf of stakeholders and investors while padding the Board of Directors' bonuses. It's a stark reminder that in the gambling world, the house doesn’t just win—it actively rigs the game to ensure it does.
The Bet365Stadium of Stoke City FC hosts lots of charitable events to enhance their reputation. A bit like Myra Hindley sponsoring childcare or Putin sponsoring care for orphans or single mothers as an example of dual standards. See Denise Coates, half owner. Makes me sick how this sort of reverse distribution of wealth apparently adds to GNP. LIke drug pushing and prostitution apparently do. There's a replica castle on the west shore of Lake Windermere built by a Liverpool Gin baron in days gone by.
Hochschild Mining (LON:HOC) CEO, Eduardo Landin, has just put his hand in his pocket and bought nearly 1/4 million quid worth of shares. The fact he has done this after a big recent run up is really promising indeed!
Price of silver may also have just broken out of a long term resistance. If so then SP could hit 180p or higher.
A lot of metals are up strongly today, especially Copper and Nickel. No idea why.
Replying to M48's comments in yesterday's SCVR on Marlowe (LON:MRL) (I hold). I personally think it is another opportunity hiding in plain sight.
Below are knowns,
- Disposal of GRC business (excluding OH) for £430M. Current market cap is £507M.
- Out of £430M, £25M will be used for divestment and other fees. £185M debt to be cleared. £220M available of which £70M will be used as working capital and £150M will be returned to shareholders.
- Post divestment Marlowe will have TIC (Market leading - UK's Top 4) and OH business. TIC & OH generated EBITDA of £39M and £16M. HQ cost pre-divestment was £6M (this should go down after disposal). Total EBITDA of post divestment business £49M.
- With the cash proceeds £220M and £49M EBITDA, i get EV/EBITDA of 5.5
- TIC is a solid business with very low churn rate and average customer service cycle of 11 years. 80% revenue is recurring revenue. 13% margin and expected to increase to 17%-20%.
Below are my personal speculative points,
- TIC was mentioned in Sky news for £650M sale in June 2023. This dint go through. Probably it was a punchy valuation of 20x EBITDA and may be some element of debt involved. But now the situation is very favourable for buyer. Marlowe sold the GRC business for 16x EBITDA. Even if we do the low ball offer of 12x EBITDA for TIC & OH we get £600M and adding the cash of £220M gives £880M market cap (around 50% upside)
- If TIC/OH doesn’t get sold, the £150M return to shareholders should give a good boost for the share price (10% to 25% maybe?)
- 3 top players in TIC in UK trades at 12x - 14x EBITDA (all with higher gearing ratio than Marlowe). Intertek (UK based), SGS S.A (Swiss), Bureau Veritas (French).
- Management : Alex Dacre has been really impressive. 5% shareholder and has his earn-out linked to Marlowe share price (Took 50% less pay than market standards). Lord Ashcroft is known for his money making skills over last few decades. Charles Skinner and Alex Dacre both will leave Marlowe.
- Investec has been added as a joint broker to Cavendish from this May 14th. If there is no M&A activities in the background i dont see the need to add a M&A specialist Investec as a joint broker for a much smaller company.
Good luck all. Have a great weekend.
Good analysis, and glad I wasn’t the only one whose ears were pricked! You have basically written what I’ve been thinking/hypothesising.
Had anyone on the board had the nous to recommend fixing the interest rate on their debt pile before the cycle turned, Marlowe (LON:MRL) would be close to the top of the share price performers on LSE over the last 10 years and still going strong. As it stands, it looks to me as if it will probably soon have completely disemboweled itself.
Just as a reminder about tickets for the two day Mello show next week where you can meet all your Stockopedia favourites....Ed Croft is on stage and the two BASH sessions with Damian, Mark, Leon and many more...
If you have never been to one of our two day conferences before then clearly you are missing a great opportunity to engage with management teams and also network with hundreds of likeminded investors so we are offering virgin tickets at just £30 for either of the days so that you can see what it is all about.....a big discount from £99.00 and if you do not agree having spent the day with us I will give you an annual pass to our virtual shows on top. I just want investors engaging with all these quality smaller companies. This offer is only if you have never attended before so please be fair to all those who pay much more.... Simply enter the code NEW2MELLO24
As a thank you to the Mello community for supporting us through the pandemic and since our first conference in Derby in 2014, we are offering a loyalty discount for those who have attended three or more in-person Mello events.
LOYALTY DISCOUNT....Have you attended three or more in-person Mello events? If so, you are entitled to our loyalty two-day ticket at just £67.60
Use Code LoveM2024 https://www.tickettailor.com/events/melloeventslimited/1201351
Terms and Conditions Apply. Please note that loyalty tickets are non-refundable and ticket holders may be subject to proof of eligibility. The loyalty rate is limited to 100 tickets only.
We hope you can join us and stay tuned for our 10th Anniversary in the Autumn!
On a slow Friday, at the end of a busy week, I will use BT (LON:BT.A) guidance to illustrate why FCF matters in recovery. It goes without saying but not necessarily the case that valuations are normally low. This suggests the market doesn't like the current corporate strategy. When valuations are low ... you kind of expect FCF valuations to be low...if they reflect other metrics. Obviously low cash conversion just doesn't work.
BT (LON:BT.A) guided to £1.5bn 2025 £2bn 2027 and £3bn 2030. Nice ....but just add these numbers up..... 2 years at £1.5bn 3 years at £2bn plus £3bn. This totals £12bn which is basically, pre yesterdays share price move, the entire market cap of the company. Now in 2030 I can imagine higher tax and new next gen projects might limit further progress but you will still have a business which "hopefully" can sustain this level. This business obviously has a value significantly higher than today.....even using a 10% FCF yield gives an implied mkt cap multiple times higher. FCF is basically the pillar of strength which all good corporate decisions can flow from.
Obviously the opposing view will be that good old "specific items" will consume this cashflow in a series of one offs, and a slow attrition of the best revenue to the competition will continue to pressure results. In theory the dominant player should yield best returns, unless the regulator steps in. In the UK I guess we have to ask whether we are more satisfied with better service or cheaper prices. I venture with things like AI placing extra demand on service ... quality is the over riding driver now.... but I am biased as we know.
For completeness Ive just listened to the webcast and think Allison did v well. Clear focus on Openreach and FCF.... Global business is on the block, and generates no cash....although there is £2.5bn of revenue £0.5bn EBITDA.... if this goes in a wider consolidation move then all good as far as I'm concerned. Should have done it 10 years ago.
IG Design recovery plan not priced in, says Liberum
Gift wrap and Christmas cracker designer and manufacturer IG Design (LON:IGR) is entering the next stage of its recovery, says Liberum.
Analyst Wayne Brown retained his ‘buy’ recommendation and target price of 345p on the stock, which this week has risen 7.3%, or 6p, at 176p. (Lazy maths calc here!)
‘As the group enters its next stage of recovery, we see the return of growth accompanied by continued margin expansion,’ he said.
‘The plan leverages the group’s key strengths while minimising the inefficiencies inherited from the old strategy.’
The recovery plan is two years in and the next three years ‘should see the business leverage its market-leading scale and share’, with return on capital employed growing as profit builds. Shareholders could also be in for a surprise as cash is already ahead of expectations and the surplus may be returned, said Brown.
‘Even though the shares have performed well recently, we still see 100% upside as the shares are not discounting any future value creation beyond full-year 2024 in the current equity value,’ he said.
IG Design (LON:IGR) Thanks for the interesting post eParo. IGR is, ofcourse on Paul's ideas for 2024 and was liked by Graham in his reviews (these guys know what they're doing)
As a light-hearted aside this reminded me that IGR was one of the stocks suggested to planetx when he asked back at the end of March. As a snapshop I think the top three performers since those suggestions were made are IG Design (LON:IGR) up 70%ish, Premier Miton (LON:PMI) up 44%ish, Poolbeg Pharma (LON:POLB) up 32%ish. Means nothing much but it’s a slow day!
I did ask about the drift at IG Design (LON:IGR) here -
https://www.stockopedia.com/co...
Added soon after and up around 70% in less than a month. So hat tips to Paul & Graham. Well done chaps.
I've got lucky and done well recently from IG Design (LON:IGR). I was alerted to it because it was on Paul's list for 2024 and I bought at the low this year. It seemed to drift down because there had been no news from the company for a while so market was worried but I've also got a poster on one of the bulletin boards to thank as well. They called the company a couple of months ago and company said 'we're comfortable with analyst sales & profit targets for this year' and I took that as my cue to dive in, thinking a profit warning unlikely. My point is that sometimes a company not updating market for a long time can be a great buying opportunity if you're able to pick up a sign from company that all's well.
.
Orchard Funding (LON:ORCH) a bit of a disgraceful announcement. No interest in doing the right thing for minority shareholders until they have to. I have a very small holding unfortunately. The board has consistently tried to talk the share price down, even though trading performance has been OK despite a number of headwinds and a fraud.
Hi Paul, Thanks for another excellent week of updates from both you and Graham. If you have time today, I would be interested if you have a take on the AGM update from Costain (LON:COST) from yesterday which referenced the significant average weekly cash figure of £168.8m vs Market Cap of £229m.
This puts the shares on a cash adjusted forward P/E of c1.8 for FY24 and then c1.7 for FY25. Obviously a lot depends on how truly available that cash is and what use it is put to, and the sector is one that does not attract a high rating due to cyclicality and periodic contract mess-ups, but that just looks too low a rating to ignore in my view.
Thanks 1James1n1,
That sounds interesting, I think you've made me curious enough to want to take a look at Costain (LON:COST)
The cash isn't really their own cash though, as it mostly comes from customers paying up-front. Hence if that were to change, the cash could rapidly disappear. So I think adjusting out the cash for valuation purposes is stretching things a bit!
Still, quoting average weekly cash is a much more reliable number than a one-day snapshot at year end.
I've made a note on my pad, and hope to look at this a bit later this morning.
Thanks for flagging it!
Regards, Paul.
Just an update on the above. On closer inspection, I'm much happier with Costain (LON:COST) and actually a good slug of their cash actually IS their own money! Main section is now up, in main article. So thank you for giving me a nudge to take a fresh look COST looks very good value I think. Although we previously liked it here before too, with GREENs and AMBER/GREEN. I'm back to fully fledged GREEN today :-)
Thanks for looking Paul and the write-up. and its always good to see if someone else picks up a contrary point when reviewing what seems to be a good company and seemingly lowly valued.
Interesting to note that Costain (LON:COST) perform extremely well on supplier payments practices, which flies in the face of what you would expect in this sector - 19 days average payment per the latest bi-annual report:
Payment practice report for COSTAIN LIMITED (check-payment-practices.service.gov.uk)
See you next week for Mello and look forward to a beer in the bar at some point!
Avation (LON:AVAP) very interesting announcement. They made $10m or 10% of their entire market cap selling two ATRs that they haven’t actually taken delivery of!!
They have some 30+ options over new ATRs so there is a lot of hidden value on the balance sheet - looks like those options make up the market cap on their own!
Can’t believe these aren’t moving significantly higher - market doesn’t seem to have appreciated this yet.
David
Thanks for that , put a chunk of my g cap cash released into aviation .
Looks an interesting situation triggered by plane shortages
Reckon Simon Thompson will be harping on about this next week
Anyway 5% in first day holding a share is a good start
Blame game portfolio gets a boost , Used to own aviation so I know it quite well .
yes - Avation (LON:AVAP) ended up with a nice lift planetx
I don't really understand why this hasn't moved significantly. It had a NAV of what around 275p? and I reckon given the profit they can make on undelivered ATRs this has to be higher than that now. So to be at a 60% discount to NAV in a market where air travel is clearly growing and fuel efficient planes are the rage the relationship Avation (LON:AVAP) with ATR to be able to negotiate these 10 year options has to be worth much much more than the market is crediting.
I guess some might point at the debt but in reality that has fallen by some $100m over the last year or so and all but about $300m of it is asset backed finance linked directly to the lease of the plane (no interest rate risk)
The refinancing of the bonds last time was done in some market distress so I expect when they come to refinance (if they don't just pay it down) they will get a better deal. But they have been buying that debt on the open market at 88c in the $ so making a 12% return on their own bonds :-) Wouldn't surprise me to see more of that.
so a fully leased fleet, profitable, paying down debt at (I think the CEO told me) $70m p/a with options on 30 planes that must be worth north of $150m given resale values and strong asset value in existing fleet vs debt and the valuation just looks odd to me.
Panther Securities (LON:PNS) - Andrew Perloff's Chairman's ramblings today always worth reading. He's a legend!
Agreed, such a great read. With such political turmoil in the UK on the near horizon Panther Securities (LON:PNS) could do much better than doubling its SP over the last 3 years.
He's a legend!
Really? Having read his comments, he seems like a twat to me.
His personal political views certainly have no place in an annual report.
Many thanks for the excellent write up on Premier Foods (LON:PFD) I would actually argue that this type of business can command a reasonably high PER - branded food companies will often attract mid to high teens multiple as they usually have good pricing power and sticky consumers.
Fair comment, thanks Bouden54! Maybe Premier Foods (LON:PFD) bull run could continue?
Georgia Capital
Announces share buyback programme of circa 100 million (100 plus 20 usd)
That’s circa 20% of the valuation
Looks a very smart move and shows an agile and aggressive management seizing an opportunity that Mr Market has given them in his 30% off sale .
Rapidly becoming an anomaly in the market which units Bank of Georgia holding now covering all but 50k of the market cap .
Wish I had some bigger balls of steel to sit this one out and even bigger ones to buy more at these levels .
Sad thing is I don’t think I do .
But I’d say management just pulled a blinder and seized a big opportunity with both hands .
Hi planetx
Georgia Capital (LON:CGEO) management strike me as good asset managers and have a history of share buy backs when volatility drives discount to NAV to extreme levels.
Should help with liquidity. I mean buying their own shares gives them an instant 150% return
I stocked up big time last night on Georgia Capital (LON:CGEO) took advantage of the drop in Bank of Georgia (LON:BGEO) to open a small position and pull some divis.
Viz- you might want to look at TBC Bank (LON:TBCG) as well-I bought into it yesterday. Yields 2.0 points more than BGEO.
David
Georgia Capital
You’re a stronger man than me I did crack a bit and sell 20% of my shares in the past week in Bank of Georgia / Georgia capital as I was actually quite overweight in these two Georgian shares .
Was sitting on pretty big gains as I bought most right on the lows after Russian invasion so maybe it’s better to be comfortable and I still have a 10% exposure in my portfolio to these two companies so that’s probably high enough in the current situation .
Bank of Georgia (LON:BGEO) clearly understand that share buy backs are best done when the shares are at a discount, locking in value as well as providing support for the share price. Something Vistry (LON:VTY) (i hold) seem to have ignored, choosing to buy shared on the recovery surge, rather than in the recent dip.
My morning smallcap tweet: Yielding to reality
Orchard Funding (LON:ORCH) Nightcap (LON:NGHT) EQTEC (LON:EQT) Fireangel Safety Technology (LON:FA.) Frp Advisory (LON:FRP) IQ-AI (LON:IQAI) Ethernity Networks (LON:ENET) Pipehawk (LON:PIP), First Property (LON:FPO)
◄Orchard Funding (ORCH)► confirms proposal to delist due to costs, liquidity etc. Will stop divs for the current FY. May use the saved cash to make a tender offer. [SP=30.4 Cap=6m]
◄Nightcap (NGHT)► some holders are no longer deemed to be in the Willingham-Toxvaerds concert party. Maybe they couldn't hack a requiem mass. [SP=4.06 Cap=10m]
◄EQTEC (EQT)► no funds have been received from Verde so the subscription is terminated. Consequently the d4e will not be executed. Negotiations with YA-RF to finalise a longer-term financing solution with no conversion rights. [SP=1.4 Cap=3m]
◄FireAngel Safety Technology (FA.)► Gov't approves takeover subject to conditions including corp gov and requirements relating to the design of networked products. Offeror is considering the Approval Conditions. [SP=3.5 Cap=13m]
◄FRP Advisory (FRP)► guides FY-Apr rev £128m up 23% and adj EBITDA £37m up 37%, ahead of mkt exp of £123m and £32m. [SP=128 Cap=322m]
◄IQ-AI (IQAI)► successful deployment of its imaging software at Insel Gruppe, Switzerland. [SP=1.27 Cap=3m]
◄Ethernity Networks (ENET)► structured investment deed to raise £800k for 40m shares and warrants with a discount exercise price formula. Sounds likes a death spiral. [SP=0.75 Cap=3m]
◄PipeHawk (PIP)► wins £750k 10 month contract. [SP=7 Cap=3m]
In line: FPO
Frp Advisory (LON:FRP) (I hold)
mjfgs I can guess you're an excited holder of Frp Advisory (LON:FRP) but you really do not need to copy and paste a screenshot of the results into the comments thread :)
If everyone did that for every single RNS announcement every day, we'd have a cluttered comments thread!
Sure Boon - kettle, pot, black.... you have cluttered the bulletin board with your policing. I pasted it because it was a rare beat.