Small Cap Value Report (Fri 17 Nov 2023) - FRP, REC, GHT, GEN, TRCS, REVB, AOM, CBOX, G4M

Good morning from Paul!
All done for today! Have a lovely weekend.
More rail strikes have been announced, days and companies are listed by Sky here. Dare I say it, but if that's the full extent of the strikes, it doesn't look too bad. The hospitality sector in particular could really benefit from having an uninterrupted festive season, so let's hope a solution can be found to this very long-running problem.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries
Frp Advisory (LON:FRP) - 122p (pre market) £306m - H1 Trading Update - Paul - AMBER/GREEN
This insolvency (and related services) group is trading well. Now likely to beat forecast for FY 4/2024. Valuation looks more reasonable than in the past, and with a favourable macro outlook for insolvency practitioners, and a 4% yield, I can see that gloomy investors might find this share attractive!
Record (LON:REC) - down 11% to 63p (£125m) - Interim Results - Paul - GREEN
H1 profit drops 16%, but full year (trimmed) expectations are reiterated. Excellent divis here, strong balance sheet, and lovely cash generation. Taking into account the much cheaper share price of late, I think this looks appealing value, for a good quality business.
Gresham Technologies (LON:GHT) - down 14% to 118p (£99m) - Trading Update - Paul - GREEN
An in line update from this specialist software company. The last 4 years have seen it establish very good profit growth. Today's sharp fall seems unjustified, and I crunch the numbers below, concluding that this share looks quite attractive.
Quick comments -
Genuit (LON:GEN) - 315p (£783m) - Trading Update - Paul - AMBER/GREEN
This positive update caught my eye on Weds this week. It’s a building products group, formerly called Polypipe. Despite challenging macro, it’s upbeat, saying FY 12/2023 should produce operating profit marginally above market expectations. That’s despite volumes being 11% down on an LFL basis. It says cost/efficiency gains and new product launches have mitigated lower volumes sold. Net debt sounds under control, reducing to 1.1x EBITDA by Dec 2023 year end.
Paul’s opinion - just on a quick look, I think this is pretty impressive, given tough market conditions. Efficiency gains now should help power profits up when demand recovers. Check out the chart to see a nice base forming, at only a fraction of the 2021 highs. There have been more shares issued though, share count has risen from 202m pre-pandemic, to 249m now. Overall, I quite like it, decent divis too of 3.9%, and a reasonable PER of 12.3
Looks worthy of closer inspection.
Tracsis (LON:TRCS) - 802p (£241m) - Final Results - Paul - AMBER
The market likes these results, as Tracsis’s share price has risen from c.700p to 800p this week.
Adj EPS is up an impressive 19% to 38.5p (PER 20.8x)
Tiny dividends. Earn-outs for acquisitions now paid off. In line exps outlook for FY 7/2024 (c.40p), with an H2 weighting expected. Balance sheet OK, with c.£10m NTAV, including £15.3m cash (no interest-bearing debt). Cashflow OK, but not particularly impressive considering the £241m market cap.
Paul’s view - valuation looks up with events, so TRCS shares wouldn’t interest me at this level. It all depends on what the future holds, so if you think earnings might grow more strongly than broker forecasts, it could be worth paying up. That’s where more detailed research is necessary, I’m only doing brief reviews here remember, I’m not trying to predict the future! Nice company, and v good track record, but I can’t go above AMBER at this high valuation.
Revolution Beauty (LON:REVB) - 27p (£84m) - Interim Results - Paul - RED
A very chequered history, for this online & wholesale makeup company, which I won’t repeat, it’s all in our archive.
Does it stack up now the dust has settled, and new management installed? Boohoo seems to be in driving seat here, with 27% of the shares. Although previous management seem to still have big positions too. No sign of Mike Ashley though, very strange!
Much improved H1 numbers, REVB traded around breakeven, as opposed to big losses in the prior year comparative period.
Revenue up 20% to £90.4m in H1.
Gross margin (just as important) also up strongly from 41.4% to 49.4%.
Excessive inventories (which we spotted here long before the proverbial hit the fan!) have been reduced considerably, from £97.5m (ludicrous) to £58.6m (still way too high). That’s “gross”, but the bal sht shows £42.3m inventories. Note 10 is confusing.
Net bank debt still a big problem, at £23.5m, so it’s highly dependent on the £32m RCF.
Guidance on EBITDA margin is raised, but I can’t find any broker forecasts, and since £6.4m EBITDA in H1 turned into nothing at the PBT level in H1, then EBITDA forecasts aren’t really much use.
FCA is investigating market abuse regulations - possibility of a fine, I wonder?
Balance sheet is weak, with NTAV negative £(15)m. Dependent on bank debt. Looks like it might need a placing to repair the bal sht.
Going concern - some distinctly worrying stuff in here, concluding with a “material uncertainty” warning.
Paul’s opinion - it looks as if the business has been stabilised, but there are still problems and risks to work through. My hunch is that they’ll probably succeed in turning it around, and the margins on makeup are good, so it should be possible to turn this into a decently profitable company. At some point though, I think fresh equity will probably be needed. I don’t see sufficiently good risk:reward at £84m to want to get involved, so it’s not for me. I have to flag high risks, irrespective of what the eventual outcome might be (could be good or bad, I don’t know). High risk means I have to view this RED for now.
Activeops (LON:AOM) - 85p (£61m) - Interim Results - Paul - AMBER/RED
What on earth does this mean? -
ActiveOps plc (AIM: AOM), a leading provider of Decision Intelligence for service operations, is pleased to announce its unaudited results for the six months ended 30 September 2023.
It seems to be a SaaS company.
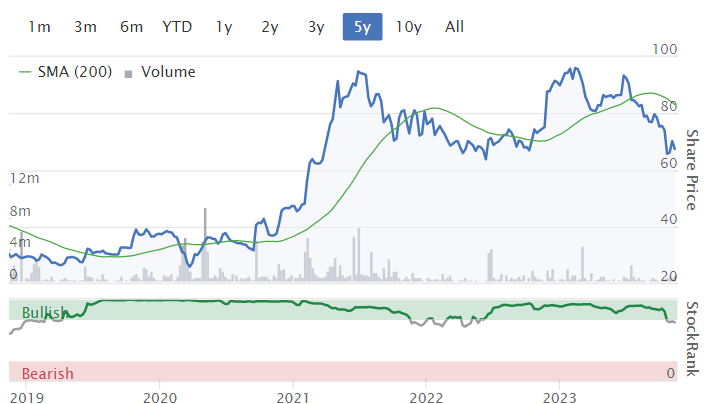
A 2021 float which we’ve looked at a couple of times, concluding that it was floated at an excessive valuation. It dropped by about ⅔ in 2021-2 and has since stabilised, going roughly sideways for the last 18 months.
H1 revenue £13.1m (up 7%), but only trading around breakeven, PBT £0.1m.
Outlook - acceleration in ARR expected in H2, and trading in line with expectations for FY 3/2024 (StockReport shows only £0.4m net profit).
Balance sheet - small, only £2m NTAV, but being a software company it gets paid up-front, so is sitting on a healthy £9.9m cash pile.
Paul’s opinion - a small software company, only growing revenue 7%, trading at breakeven, but valued at £61m. Why?! It needs to significantly accelerate growth, and profitability, to get even close to justifying this valuation. It might be a good idea if the company can actually explain what its software does! Both the RNS and a video on its website have left me none the wiser.
Cake Box Holdings (LON:CBOX) - 149p (£59m) - Interim Results - Paul - GREEN
Cake Box Holdings plc, the specialist retailer of fresh cream cakes, today announces its half-year results for the six months ended 30 September 2023.
I quite like this business, it’s a successful, expanding, franchiser of cake stores.
H1 revenue up 7% to £18.0m (low, because it excludes the stores revenues), £2.4m PBT (up 18%), EPS up 20% to 4.45p, and interim divi up 11% to 2.9p. That all looks good.
It looks like there’s an H2 seasonality to profits.
Outlook - on track to perform in line with market expectations.
Balance sheet is fine, and includes about £6m net cash.
Paul’s view - shares look good value, on 13.7x forecast EPS of 10.9p for FY 3/2024.
Various problems in the past did cause trust issues for me. However, solid interim numbers showing profit growth, in line outlook, nice balance sheet, cracking forecast dividend yield of c.6%, combine to make this share look attractive. Plus continued roll-out potential from more new sites, which can be done quickly, as they’re set up and run by franchisees. Looking good, I have to be GREEN on this!
Gear4music (HOLDINGS) (LON:G4M) - 120p (£25m) - Interim Results - Paul - AMBER
Gear4music (Holdings) plc, ("Gear4music" or "the Group") (LSE: G4M), the largest UK based online retailer of musical instruments and music equipment, today announces its unaudited financial results for the six months ended 30 September 2023 ("the Period").
A loss of £(1.9)m in the seasonally quieter H1, worse than £(1.0)m in H1 LY.
Outlook is in line for FY 3/2024, driven by higher gross margin and cost-cutting, offsetting lower volumes. Strategy is to prioritise profit, not revenue growth, which makes sense to me.
Balance sheet is a bit too dependent on the £24m bank loan for my liking, although overall asset backing is OK, and inventories are high before Xmas.
Paul’s view - it’s difficult to get excited about this company, now the exciting growth has disappeared. I don't see any evidence that previous acquisitions have added value. That said, a £25m market cap leaves scope for a re-rating in the next bull market. FY 3/2025 should benefit from the hefty central cost reductions (IT team scaled back). I can see merit in both bull, and bear cases, so I’ll sit on the fence. AMBER it is for now. I wonder if mgt might tire of the listing, and take it private?
Paul’s Section:
Frp Advisory (LON:FRP)
122p (pre market) £306m - H1 Trading Update - Paul - AMBER/GREEN
FRP Advisory Group plc, a leading national specialist business advisory firm, announces a trading update for the half year ended 31 October 2023 ("H1 2024").
They’re being coy about what the company actually does! It’s mostly an insolvency practitioner, the other listed one being Begbies Traynor (LON:BEG) . FRP also does corporate finance work, such as M&A, and arranging debt finance for clients.
Trading looks good, but it’s a pity they follow (below) the fashion for reporting EBITDA, when most investors I know would much prefer to be told Profit Before Tax and EPS as more credible performance numbers -
The Group's performance was strong during the first half, with continued growth in revenues and profits as well as further investment in the team.
The Group expects to report revenue for H1 2024 of £58.7m, up 19% on the prior year (H1 2023: £49.4m), and underlying adjusted EBITDA* of £15.5m, up 34% on the prior year (H1 2023: £11.6m).
Valuation - there’s a helpful note out today from Cavendish, saying that H1 has achieved 54% of its FY 4/2024 forecast EBITDA, and there’s usually an H2 bias to trading (since decisions on administration, etc are often made early in the calendar year, which is FRP’s H2).
Therefore it strikes me that forecasts are likely to be at least 10% light of what's achievable.
Current forecast for FY 4/2024 is:
£111.8m revenues, £28.6m adj EBITDA, £25.4m adj PBT, and adj EPS 7.6p.
I’m going to guess that 8.5p is probably more realistic, given tough macro (which helps FRP), and a strong H1. Hence at 122p/share I get to a likely PER of 14.4x which looks about right to me.
Dividends are quite generous, with the StockReport showing a 4.0% forecast yield, with probable upside on that too.
Outlook - sounds good - and as mentioned above, it looks set up to beat existing forecast -
Trading since 1 May 2023 has been positive and if current activity levels continue, the Board remains confident of at least achieving full year expectations.***
***The Company believes consensus market expectations for FY 2024 to be revenue of £112.2m and adjusted EBITDA of £28.8m.
Divisional outlook - some interesting snippets in here, for more general read-across - watch out for debt-laden companies, being the key message for us -
Restructuring -
During the 2023 calendar year, the restructuring market has seen an increase in activity levels, including administrations approaching pre-pandemic levels. Companies with significant borrowings who have rolled off lower interest rate arrangements are now subject to much higher debt service costs, with interest rates now considerably higher than the 2009-2021 period. Businesses are also exposed to much higher levels of cost inflation.
Certain sectors such as construction, property, casual dining and food service, retail, administrative and support services are finding current trading conditions particularly challenging.
Corporate finance -
Moving into H2 2024, the pipeline of new opportunities remains solid and we are continuing to see good levels of activity across the national Corporate Finance practice. We are seeing signs of an increase in debt refinancing and restructuring related M&A activity.
Net cash has fallen, due to work-in-progress sucking in cash as revenue grows. That’s normal in this sector - fees are often run up for a while, and then settled from asset sales (which can take quite a long time). It still looks to have plenty of liquidity though -
The Group's balance sheet remains strong with an unaudited net cash balance as at 31 October 2023 of £11.7m** (H1 2023: £21.0m). In addition, the Group has an undrawn revolving credit facility of £10m.
Headcount has risen from 536 (Oct 2022) to 622 (Oct 2023), with the increase mainly coming from an acquisition.
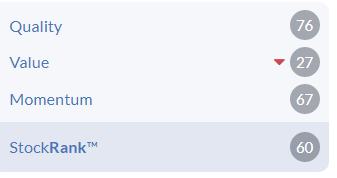
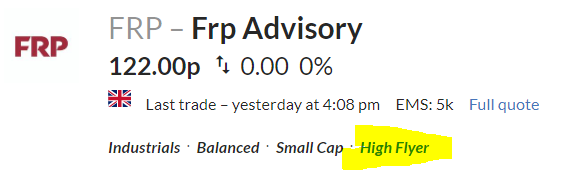
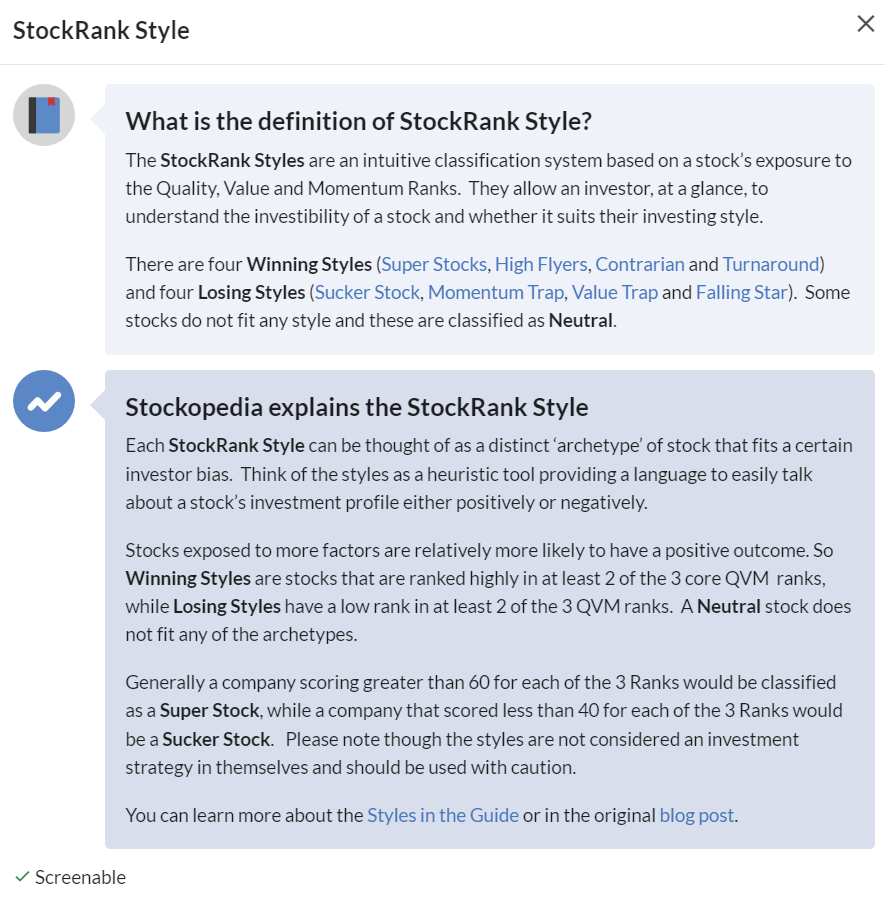
Paul’s opinion - looking back, we’ve tended to view FRP as amber. There’s nothing wrong with it, the accounts are fine, it's a good quality business I think, but there’s not really a lot to make it stand out when we have so many other more interesting, and often better value shares to own. This is also reflected in an upper middle StockRank, although it's classified as a "High Flyer" in the styles section under the company name on the StockReport.
Given the improving outlook for insolvency work, and the likelihood of beating forecasts, plus a more reasonable valuation than in the past, and a 4%+ dividend yield, I’m warming to this share. It’s likely to be reporting positive newsflow, with an ahead of expectations update looking highly likely in the spring.
For those reasons, I’ll nudge my view into more positive territory at AMBER/GREEN.
Some investors like to hold shares in FRP and BEG to help sleep at night, given these companies are counter-cyclical, benefiting from a worsening economy.
.
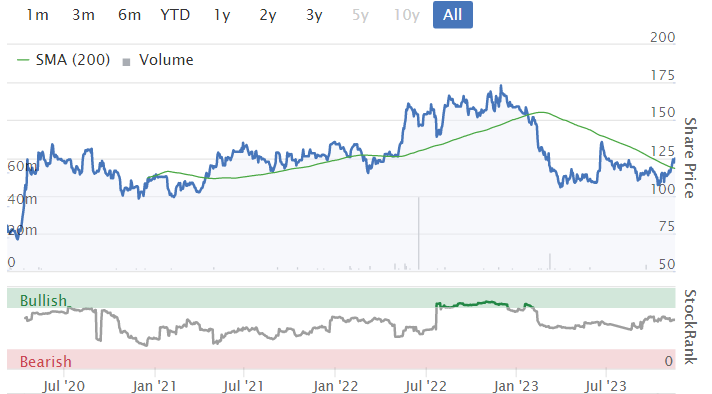
FRP floated just as covid was breaking out in March 2020. So considering the timing, it's been a fairly safe port in the storms of the last 3 years, with some divis on top too -
Record (LON:REC)
Down 11% to 63p (£125m) - Interim Results - Paul - GREEN
Record plc ("Record" or "the Company"), the specialist currency and asset manager, today announces its unaudited results for the six months ended 30 September 2023 ("H1-24").
Checking back through our previous reviews,
30/6/2023 - AMBER/GREEN - 93.5p - I reviewed FY 3/2023 results, which were strong (PBT up 34%). The founder retired. Rising costs mentioned. OK Bal Sht. Nice yield of nearly 5%. So overall I was moderately positive.
18/7/2023 - GREEN - 83p - Graham this time, taking a more positive view than me, based on the strong long-term track record. Although the Q1 update was disappointing.
On to today, we have a change of CEO announced as being planned for March 2024 year end, so this looks orderly. Outgoing is Leslie Hill, after 31 years at Record (4 years as CEO), and internal CEO Jan Witte is now group CEO-elect.
This tickled me -
Leslie Hill, Chief Executive Officer, commented, "I have loved almost every day at Record…
As a large shareholder, I will remain a supportive and interested ally in our wonderful company, which I believe has a very bright future ahead.
Interim Results -
Revenue down 3% to £21.5m in H1
Lower operating profit margin of 29% (LY H1: 34%)
PBT down 16% to £6.3m - still a lot of profit in a half year, for a company valued at £125m.
Interim divi up 5% to 2.15p (historically it split interim:final divis evenly, and pays special divis on top)
Webinar on IMC at 15:30 today, which I’ll listen in to, if I’ve not put down roots at The Mary Shelley (my local ‘spoons)
Balance sheet - looks fine to me, simple with no funnies. £14.8m cash and no interest-bearing debt. £27m NTAV, healthy working capital position. No issues here.
Cashflow statement - simple and good. This is a strongly cash generative business, that pays out most of that cashflow in dividends. Very nice.
Outlook - sounds mixed, but is in line with expectations overall -
"Our client proposition remains strong as does our pipeline of tangible opportunities across our broad product suite. Our growth in financial terms is not linear and delays in new product launches alongside stubbornly high inflation have led to a decrease in our operating margin for the period.
However, looking ahead, we anticipate further fund launches and growth across our range of products which we expect to increase our profitability over the medium term.
"The Group remains well positioned financially, with increased cash generation and a strong balance sheet to support its future growth plans.
The Board remains confident in the delivery of market expectations for the current financial year. I believe the business remains capable of delivering on the targets set out in February, albeit achieving them may take longer than originally anticipated."
Broker consensus forecasts - peaked at about 6.1p, and have been edged down to about 5.1p now for FY 3/2024.
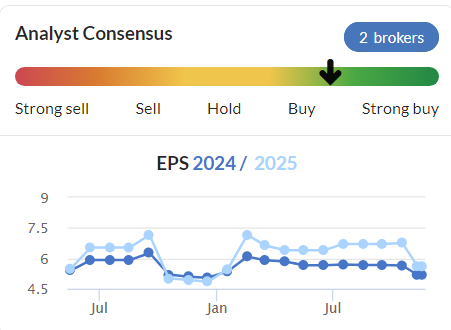
Valuation - at 63p today, the PER is 12.4x FY 3/2024 forecast. That seems very good value to me.
Existing forecasts show almost all earnings being paid out in divis, which fits the historic pattern, with typical divi cover of ranging from 1.1x to 1.4x. Therefore, shareholders are looking at a dividend yield (adjusted for today’s share price fall) of about 7.7% - which the company can afford, as it doesn’t need the cash for anything else (no capex to speak of).
This looks cheap to me, I like it!
Paul’s opinion - not great results, with profit down 16%, but the share price has fallen a lot, more than compensating, in my view.
It doesn’t sound as if the business has gone seriously wrong, and outlook comments reassure that profits should return to growth.
Solid balance sheet, excellent cashflows, and very generous dividends, make this share appeal to me more, now it’s cheaper, and priced like a mature, value share.
I can’t avoid giving it a thumbs up at this price, because the value on offer outweighs a slightly disappointing set of numbers. GREEN.
Could be a good entry point perhaps?
Gresham Technologies (LON:GHT)
Down 14% to 118p (£99m) - Trading Update - Paul - GREEN
A nice clear description here -
Gresham Technologies plc (LSE: "GHT", "Gresham", "Group", "Company"), the leading software and services company that specialises in providing solutions for data integrity and control, banking integration, payments and cash management, is pleased to provide an update on trading and the discontinuation of its legacy IT contracting services business.
FY 12/2023 is on track - with 98% revenue visibility (at end Oct) for the full year -
The Company expects FY23 Group revenues and earnings to be in-line with market expectations.
Singers has helped us with an update note today, leaving estimates unchanged for FY 12/2023: revenue £50.2m (up 3% on 2022), adj PBT £7.4m (up 10%), EPS 7.7p (up 3%)
Note that GHT has established an excellent profit growth track record, after many previous years of rather erratic & lacklustre profitability -
£Adj PBT
FY 12/2020: £1.8m
FY 12/2021: £4.0m
FY 12/2022: £6.7m
FY 12/2023: £7.4m forecast, but confirmed in line today.
[source: Singers note, with thanks]
That’s impressive stuff, and very much the sort of progression I look for when selecting ideas to research further. The valuation seems quite modest for a software company that’s grown earnings nicely, with a PER of 15.3x
Outlook -
The Company continues to have a solid pipeline of opportunities from both new and existing customers and expects to close additional Clareti subscription business before the end of the year which will contribute to the Group's Annualised Recurring Revenue ("ARR") and FY24 planned revenues…
Except for the reduction to revenues directly attributable to the discontinuation of the IT contracting line of business, the Company is making no other material changes to its guidance for FY24 revenues…
Since the move to a Clareti subscription model in 2019, and the acquisition of Electra in 2021, the Company benefits from a strong base of recurring revenues. Clareti recurring revenues now account for 75% of FY24 planned Group revenues on a like for like basis excluding the discontinued contracting services business. Whilst the macro-environment is expected to remain challenging, the above factors support management's confidence in the Clareti business and prospects for on-going growth.
So far, so good. Why’s the share price tanking then? (down 14% as I type this)
Exit from legacy, low margin business providing IT contractors to a major customer - this is explained in detail, with this financial effect -
The Company expects to recognise £8.5m in revenue from these agreements in FY23 with fixed margins of 13% and will discontinue the business from January 2024.
I can see why GHT wants to improve its margins by ditching this element of its work, but surely this is giving away £1.1m of profit? Unless there are other overheads associated with it? It’s not clear from the RNS what the bottom line impact would be, or if the 13% margin mentioned above is just the gross margin?
I think we need more detail on the rationale for this move. For me, profit is profit, and I don’t really care if it’s high margin, low margin, or a combination of both.
Paul’s opinion - this share is looking interesting, in my opinion.
Singers has lowered FY 12/2024 forecast to 7.0p. What rating should we put it on? Software companies with good profits, and mostly recurring revenues, can easily pull a PER of 20x I think. Often they’re premium bid targets too. So to my mind, 140p-ish seems a fair valuation. Currently priced at 118p, I think this share is looking quite good.
I’ve checked the last balance sheet & cashflow statement, and am not impressed. Negative NTAV and high spending on intangibles means there’s little scope for divis. I think it needs to focus on building up the cash pile, although customers paying up-front means it can trade fine with a weak balance sheet. These are not deal-breaking concerns though, so I’m happy to continue with my previous GREEN view back in Jan 2023.
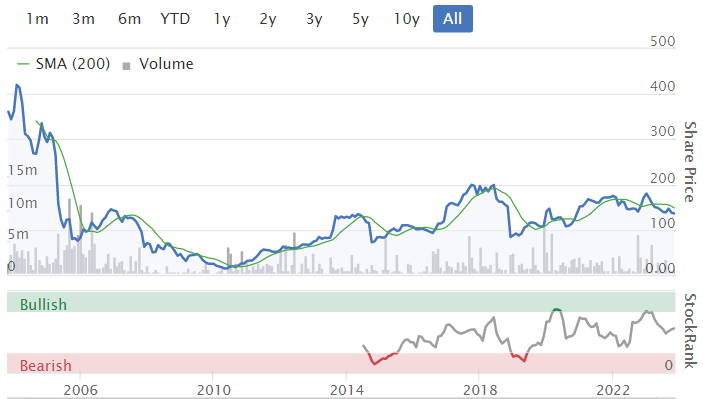
A rather slow burner in 20 years as a listed company -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

77 comments
Interesting that SCS and W7L both done very well, and were holdings for Scion Asset Man. (Michael Burrys firm) a couple of years ago. I remember they were his only UK holdings in 2021 (I think) but sold since.
Redde Northgate (LON:REDD)
The Telegraph mention that Redde Northgate (LON:REDD) approached Halfords proposing a nil premium merger.
Doesn't seem to have bitten, thus far. An interesting development nonetheless.
Redde Northgate (LON:REDD)
I make halford p/e 10 compared to 7 for Redde - bizarrely the halfords board have the cheek to think they would getting the runt of the deal here - when their p/e is 40% higher than that of Redde that is somewhatc laughable. Halfords makes just over half the profit it did 10 years ago on double the turnover (pretty sure they have done som acquisitions along the way too) - so i think they have a cheek thinking they deserve a premium on top of the 40% premium they have been offered - ok pe metric is not everythig but both are reasonably mature buisnesses so pe seems like half decent startiong point comparing valuations - i would guess Redde also has better ntav per share than halfords.
The Halfords board is thought to have concluded that any such deal on the terms laid out would have undervalued the company.
Been waiting a while for someone to call out Kirk as a waste of space. Surely the FT can do better than this….
A waste of Space ? Surely not
Anyone know why Triple Point Social Housing REIT (LON:SOHO) is up over 7% today?
Even at 62p it is at a large discount to the 109P IFRS net asset value per share. There's an uncovered dividend yield over 7% going to 9% next year if you believe the forecasts. Presumably the brake on share price performance is gearing levels.
Not sure I understand its business - does it lease its estate and then sublet within the vulnerable end-user sector? Happy to hold for now, both for the yield and chance of a takeover. A similar company was taken private ealier in the year. (Can't recall the name?)
Maybe that's why it is at a discount to NAV? Complicated business and structure?
A 30-40% discount to NAV isn't that unusual anlngst REITs. Plenty of others at the same discount range. So Triple Point Social Housing REIT (LON:SOHO) doesnt look that out of whack to other REITs in terms of valuation.
Civitas Social Housing was taken over by CK Asset Management. I think I got a 30% uplift and was a bit ticked off, because they got it at still at a c. 20% discount to NAV, if I remember right. Put it into Triple Point Social Housing REIT (LON:SOHO) , so who knows? Some of these ITs are just crazy cheap, and large private investment houses with market understanding are likely to snap up some of these, just like they are taking out UK small and mid-caps at the moment.
Given the mess at Home Reit (LON:HOME), wife holds, you definitely need to DYR
Alternatively take a look at PRS Reit (LON:PRSR) who have a simpler portfolio. I hold.
Extract from latest accounts
-- Net asset value up 30% year-on-year to GBP639m or 116.4p per share at 30 June 2022 (2021: GBP490m or 99.0p per share)
-- Assets continued to perform strongly, with rent collection at 99% for FY 2022 (2021: 98%) and occupancy at 98% at 30 June 2022 (2021: 98%)
- like-for-like blended rental growth over the year was 5.1% on stabilised sites (where all units have been completed and either all or nearly all have been let). Re-lets to new tenants achieved c.10% rental growth
- average tenant rental affordability ratio now at 25% in 2022 (2021: 29%), notwithstanding 5.1% rental growth, indicating a stronger tenant base
- operating costs reduced to 18.2% from 19.5%, reflecting the benefits of scale and close management
-- Portfolio expanded with the addition of 802 homes in the year, taking the total number of completed homes to 4,786 at 30 June 2022
-- Gearing on portfolio (measured as net debt vs. investment value) low at 31%, with 62.5% of the existing GBP400m of investment debt fixed rate at an average of 2.9%
Yes discount not unusual in the REIT space. With respect to Triple Point Social Housing REIT (LON:SOHO) I think the market is not keen on the regulatory risk in this area, while some of the housing associations (who are responsible for paying the rent) have got into trouble leaving the dividend uncovered. Overall too complex and too many unknown risks for me so would much prefer something like Tritax EuroBox (LON:EBOX) which is probably on a similar discount and yield but far more straightforward!
Activeops (LON:AOM) H124 results presentation given to analysts video & podcast.
Quality business. There seems to be a seller. Historically, they've been counter-cyclical (2008 massive growth for them in spite of being a supplier to the banks). They increase productivity hence are in demand when efficiencies need to be made.
Despite a good outlook from Frp Advisory (LON:FRP) today, looks like the SP reaction is muted. Along with Begbies Traynor (LON:BEG) share price. Suggesting that the market as a whole already had a bright outlook as consensus for insolvencies.
(I hold BEG in the Boon Fund).
On strikes... Revolution Bars (LON:RBG) has had a strong bounce from recent lows, probably due to the more positive outlook on train strikes. RMT union set to vote for the new pay deal (although this vote only concludes end of Nov? So still a possibility). But ASLEF strikes now announced, but limited days (but probably during a key week).
Nevertheless, these strikes have been announced after corporate Christmas bookings would have already been done, so I'd suspect the majority of bookings would still go ahead... but maybe with less heads, extra spends, etc...
I have a sneaky suspicion that Revolution Bars (LON:RBG) will have a very good Christmas and there will be some big upgrades that follow. I think companies and colleagues are organising lots of get togethers/events so assuming rail strikes aren’t too disruptive I think people will spend on going out. I suspect that is partly due to a release valve effect firstly after so many disrupted xmases in a row and secondly after belt tightening across the latter part of last year and this. With real incomes rising and energy costs falling I reckon people will still spend a bit and corporates are keen to show staff they are valued. Jan and Feb may be a very different story spend wise tho.
Interestingly as I was thinking this I watched the Marks and Spencer (LON:MKS) update and the CEO was alluding to the same Christmas effect with going out party wear selling nicely. They too are very cautious on the new year impact.
really like what Marks and Spencer (LON:MKS) are doing. Don’t own any but waiting for a small pullback to open a position. Bit late to the party but can see them doubling still in next 3 years.
Re Marks and Spencer (LON:MKS) I was really impressed with Stuart Machin on that Webcast recently, did you see when one of the female analysts asked a question and told him she likes their new branch in Victoria, his reply was something like ' well i hope you do your Christmas shop there and if you do I would appreciate a feedback email' , to me that didn't seem staged just a gut reaction and showed the board's ambition in getting it right.
Apols
Paul, thanks for the quick comment on Genuit (LON:GEN). I'm glad you think it looks worthy of closer inspection.
I was havering over whether to pull the plug on it in September, having taken control of my portfolio from my stockbroker, after going through the Ratio Cookbook (link to video, couldn't find the more recent pdf). I was following your philosophy of ignoring buy price (~527p in March 2021) and just judging it on its current credentials, which is difficult when you're down a large percentage.
Value wasn't great, with PEG of 19 where the cookbook prefers <1, and EPS Growth Q on Q was -48 not >+5, but a decent price momentum and ok quality metrics (and low liquidity risk) meant the QVM ranks were ok at Q87, V56 and M72 giving an overall StockRank of 86. In the end, I kept it, more through inertia than strong conviction (ownership bias, anyone? - but also not wanting to be an overtrading new investor.)
It looks like the ranks haven't changed a lot in the last couple of months, but the share price has stopped its long downward trend :)
Watching with interest...
It is a quiet day....so pls forgive me for kicking off a small diversion from small caps.
So following on from our Bank of Georgia (LON:BGEO) discussion earlier in the week, I'd be very interested in views on Alibaba Holding (NYQ:BABA) from those with the stomach for higher levels of geopolitical risk?
Similarly - I need to prune the Apple (NSQ:AAPL) tree as position now too large given what I perceive to be the risk/reward, and talking about China exposure (19% of Apple t/o is from China) I've been doing some nosing around the crater that is Estee Lauder Companies (NYQ:EL) where the China risk is possibly more "priced-in" and I'm aware there are some holders in this forum (plus I greatly enjoy poring over Terry Smith's rejects).
The discrepancy between the two stocks on a price/sales basis is quite startling (and yes, I'm deliberately being overly simplistic). The Travel Retail component probably means Estee Lauder Companies (NYQ:EL) had greater China exposure and greater cyclicality than many holders realised. Whereas with Apple (NSQ:AAPL) the market doesn't seem to view a new iphone as a luxury purchase....?
Interesting announcement by SCS (LON:SCS) yesterday. Could there be an emergence of another bidder causing the delay? Any views?
It was also announced on 24 October 2023 that it was expected that a scheme document, containing further information about the Acquisition and notices of a court meeting and general meeting ("Meetings"), together with the associated forms of proxy ("Scheme Document"), would be posted to ScS shareholders as soon as practicable and in any event within 28 days of 24 October 2023.
Due to a lack of availability of the court, it has not been possible to schedule a court hearing meeting in sufficient time in order to post the Scheme Document to ScS shareholders within 28 days of 24 October 2023.
Accordingly, the directors of ScS have therefore sought an extension to the deadline for posting the Scheme Document from the Panel. The Panel has granted such an extension to 17:00 on 29 November 2023.
One of effects of so many UK shares (small companies and large) and also a wide range of Investment Trusts falling to extreme bargain levels has been to provide some extraordinarily big dividend yields. That income has proved a blessing during this bear market and the opportunity to cash in with them is still there, though most are now off the ultra extreme recent lows.
Here are some potential and mostly big dividend paying shares and Investment Trusts worth checking out. I hold most of them, and there’s a very high likelihood (if the UK market ever recovers!) of some big capital gain on top.
Aviva (LON:AV.) 413p and 8% dividend. Reassuring update today and confirmation of previous news that they intend to increase the big dividend too.
Amedeo Air Four Plus (LON:AA4) I’ve held AA4 from 33p and now 43p. Even after that share price gain, dividend increases mean even now the dividend is 15%! It’s on a 60% discount but that’s because of the key risk which is uncertainty about the end value of their planes.
BlackRock World Mining Trust (LON:BRWM)556p. 7% dividend but in good years it’s higher. If there’s a Mining boom ahead because of green demand and potential demand far outstripping supply, then BRWM looks a very good way to play it.
Petrotal (LON:PTAL) 48p. Recent update confirms 14% dividend!
Diversified Energy (LON:DEC) 72p. I bought it back recently at 66p. Complex business model and risky, but 15% dividend which has been paid (and with several increases too) for years now. That 15% yield is AFTER deduction of15% witholding tax.
Note the news yesterday. They are going to list their shares in New York from 11th December. (Don’t know why they didn’t list there in the first place as it’s a US Company). That listing means there’s going to be a 20/1 share consolidation as apparently US investors prefer a higher nominal share price.
Henderson Far East Income (LON:HFEL) 209p and 11% dividend. At long last some signs of recovery and rising NAV. It has way underperformed others in the sector but is one of the aic dividend heroes that increase the dividend for multiple years.
Legal & General (LON:LGEN) 226p. 8% dividend. As with AVIVA they promise dividend increase.
M&G (LON:MNG) 203p. 10% dividend.
Oryx International Growth Fund (LON:OIG)1080p. No dividend but excellent performance record and at so wide 36% discount to NAV. There are a lot to choose from in the UK smaller companies sector:-
https://www.theaic.co.uk/aic/f...
Phoenix group (LON:PHNX) 11% dividend. Just looks so oversold unless the Market knows something I don’t. Buy opportunities on the dips.
Serica Energy (LON:SQZ) 208p and 11% dividend if held. I’m not convinced about SQZ nor Harbour Energy (LON:HBR) 225p and 9% dividend that I also hold. Will decide on their next updates. Share prices badly hit by windfall taxes and Labour’s North Sea policy but that looks priced in.
VPC Specialty Lending Investments (LON:VSL)72p and 11% dividend. Being wound up. It will take time but potential for useful profit if realisations are anywhere near reported NAV. At 22% discount. And useful 11% dividend while we wait.
Foresight Solar Fund (LON:FSFL) 98p (recent low 84p) 20% discount to NAV and 7.5% dividend which they are confident will remain 1.5 times covered at least until 2025.
Good Energy (LON:GOOD) 282p. Recent low 160p. No dividend but Investec forecast very fast growth, I.e end 24 18.3p, end 25 33.2p and end 26 69p. Ig GOOD ends up doing a fraction as well as Yu (LON:YU.) and Telecom Plus (LON:TEP) it will go a lot higher.
AND we’re spoilt for choice with bombed out Commercial Property REITS!!
See this link for all the UK Commercial Property Trusts. So many at big discounts and paying big quarterly dividends too.
https://www.theaic.co.uk/aic/f
I hold the following REITS:-
Alternative Income REIT (LON:AIRE) 66p. Recent low 55p. 22% discount. They’ve recently increased the dividend and yield is now 9.3%.
Aew UK Reit (LON:AEWU) 99p. Recent low 94p. Discount is only 5%. That reflects it being the most successful of this group. Dividend is 8%. I bought AEWU at 62p in 2020 covid crash and the dividend yield since then at 13% a year at that buy price shows the VERY useful additional gains big dividends bring. Just ask Lord John Lee!
Schroder Real Estate Investment Trust (LON:SREI) 43p. Recent low 40p. 35% discount…despite buying back heavily to try and reduce it. 7.7% dividend.
Supermarket Income REIT (LON:SUPR) 82p. Recent low 71p. Dividend 7.4%. Supermarkets are secure tenants!
I also hold Tritax EuroBox (LON:EBOX) in the Commercial Property Europe sector. Looks far too cheap on 40% discount and 8.5% dividend. Has bounced from recent crazy 44p to 51p.
Finally this is a great site for ACCURATE and up to date information on dividends:-
https://www.dividenddata.co.uk...
Just click on each of the headings starting with this one for ex dividend dates. Also put epic for any share in box to get the full dividend information for that share.
Thanks for this, Ken. I'm very aligned with your thinking. I take what Ed and others say about growth shares, but it really helps me sleep at night to know we can live of the 'natural' income from our portfolios. What we need is a forum capability on Stockopedia, where we can all post ideas and tag the companies so they can be found by general search. That way we don't need a thread leader.
Anyway, I hold about half your list and would add renewables/infrastructure at this point. They've recovered a touch, but GCP Infrastructure Investments (LON:GCP, Gore Street Energy Storage Fund (LON:GSF) and Triple Point Energy Transition (LON:TENT) will all still give you nearly 10%, and when interest rates do subside in the back half of next year, that bond-like income but surely become attractive again on shares that are at 30-40% discounts to fresh NAVs which had taken rising rates into account.
I also hold Triple Point Social Housing REIT (LON:SOHO) , @ >50% discount and apparently stable >9%.
You might be interested in The Oak Bloke (are any of you him?!). He is analysing some of these too. At random, try https://theoakbloke.substack.c... or https://theoakbloke.substack.c... Hats off to him.
I'm with you on a lot of these. See a lot of value is some of the bombed out REITs (need to be selective though) and the life insurers. Diversified Energy (LON:DEC) looks tremendous value and I have held in the past but everytime I have another look I'm put off by the complexity and the high level of debt. They have a lot of hedging in place which is difficult to get your head around and screws up the earnings numbers. Will probably stay on the sidelines for now.
Ken, absolutely right. In fact i think you've had sight of my ISA portfolio!!! :D
I've been involved in investment since 1984 and i have never seen so many high, growing and safe yields.
It is utterly bizarre!
And to add to that great list:
Imperial Brands (LON:IMB) yield 8.5% but huge capital discipline and buying back shares at a rate of knots. One day there will only be one share left and we'll have to trade it between ourselves!!
Osb (LON:OSB) yield of 8.2%, growing and with excess capital nearly equal to the market cap
Secure Trust Bank (LON:STB) : see OSB!!
Liontrust Asset Management : 12% yield, covered on current forecasts and a p/e of 7, if we are somewhere near the bottom in UK small/mid caps (who knows), then what a geared play on the market this is!
All these held in m y ISA, which helps keep Mrs ChrisW in shoes!
C
It is a bizarre state of affairs this is true. The reality is that these valuations have been brought about by the massive liquidity drought.
If you just generate 15% p/ a a portfolio will do very nicely indeed and now we have a bunch of sustainable 10-15% dividend paying businesses available to investors. They barely have to grow at all and you’ll still do 15%+ total return.
Companies like Osb (LON:OSB) badly misunderstood. It will throw off buckets of cash for years to come even if it never prints another mortgage. I reckon they will pay 10% divi next year and buy back more shares so this fully fits into my 15%+ total return category. Petrotal (LON:PTAL) will probably pay 17% in divi’s alone whilst retaining 30% of its market cap in net cash. Personally I won’t be selling any of that below 100p. They have decades of production left too so unless oil really drops through the floor in the next 5 years the price is nuts.
I love Legal & General (LON:LGEN) too at over 8% and they should benefit from improving conditions.
Lots to choose from……
Thanks for the follow up replies to my post this morning and for further information on other equally bombed out shares too.
Re Diversified Energy (LON:DEC), as Bouden54 posted it’s SO difficult to understand so buying means trusting that it won’t suddenly unravel with a severe profits warning. But I’ve been in and out for several years and collected more in dividends than the money staked, and it hasn’t unravelled….yet! But definitely not for the nervous. otoh that imminent US listing just could put a rocket under the share price!
I hadn’t looked at Osb (LON:OSB). Should have done! It’s well off the lows. Chris W also mentioned Secure Trust Bank (LON:STB) which I bought recently and included in the thread below and Liontrust Asset Management (LON:LIO) which I also hold.
Finally just to point out that imo there are problems with posting on Stockopedia ,except on this excellent Small Cap bb with accompanying superb analysis from Paul and Graham. If we do a decent post here it gets noticed, but elsewhere in my limited experience of posting on Stockopedia, it doesn’t.
I started the thread below and ticks have inched up to 30 compared to 85 just now for my post today, and posts on the thread below similar to mine here here today got just a handful of ticks and far less follow up. In no time the thread gets lost too. This has happened with excellent recent Investment Trust threads too including some superb comment from Charles Mitchell (no relative). And the same often. applies with brilliant articles from Stockopedia staff too. Far fewer viewings than here and far less follow up too.
It’s no problem posting only on the small cap thread EXCEPT that it means off topic non small cap posts take over from the replies to the so thorough analysis of small cap shares covered so brilliantly by Paul. Just look at his incredible output today.
I don’t know whether there’s a solution to this and perhaps few others see there’s any problem, but it seems worth mentioning.
The thread below btw included a post I did on another site at the depths of the Truss/Kwarteng chaos. It’s only worth a quick scan now but the key point was that it IS possible to do well even in a nasty bear market. The shares and Trusts in that post from a year ago were up 24% ahead of the recent big rally. And the second part of that initial post was similar to my post today.
https://www.stockopedia.com/co..
Actually Good Energy (LON:GOOD) do pay a small dividend (I hold)
There is a real battle at £1.10 for Card. It has consistently failed to break this level now, trying 3 times in the last 3 years with a real battle around £1 prior to this. The story looks good and yet the price seems unable to progress. Well it is at £1.10 for the 4th time let's see how it gets on this time. And lets keep an eye for any announcements telling us who is a seller.
Of course it is Teleios!! The battering of the last three years has taken its toll. Sorry guys!
No sooner said than done…..it appears it has broken up to 113p so if it holds here that bodes well. Not obvious what Teleios plan is - they could just be waiting for a slightly better price and push it down again but we will see.
I was a bit of a latecomer to the turnaround but managed to pick up a chunk at 92p. Was expecting a trading update this week so hopefully things are still going as expected.
Card Factory (LON:CARD) has fallen back now, below 112p.
Looks like a cup and handle maybe forming?
I think lots of us are holding this waiting for the break out! It wont break out properly until they update us again though. I agree that we should hear from them very soon, exciting times for this stock. I know there are a few nerves after TheWorks warned but I just see this as weakness in TheWorks... a perennial warner. Finger crossed.
Any thoughts on GHT Paul?
Paul - I just want to say thank you for putting in the time and effort to produce the SCVR spreadsheet. I've found the summary of past reviews super helpful! :)
Retail sales slump to 'lockdown' levels as shoppers delay Christmas spending - Retail Gazette
Although the above from the Retail Gazette is not positive for retail, one paragraph would suggest that Warpaint London (LON:W7L) might still be trading positively
“Meanwhile, cosmetics and toiletries had another strong month, due to the ‘Lipstick Effect’- where the high cost of living meant people spent more on smaller indulgences.
Ive read a lot about the lipstick effect of people buying cheap cosmetics in a high inflationary environment
But does anyone know what happens after we exit the high inflation? If people revert to preferred brands then Warpaint will likely start to underperform in a year or two.
Any research out there?
Hi Jeff,
My understanding of the 'lipstick effect' is that it is not a trading down 'brand' thing it is people buying lower price luxury items to cheer themselves up during times that they cannot afford higher priced luxuries, clothing, meals out, holidays etc . The lipstick effect is supposed to be just as powerful for top end cosmetics as the budget labels.
As for Warpaint London (LON:W7L) specifically, I think that they are winning shelf space in a lot of new and existing customers in UK, Europe and the US so they have many tailwinds ATM.
Having watched Ed's Multibagger webcast this week it did occur to me that Warpaint London (LON:W7L) could fit the criteria, however I am not sure that the board especially Sam and Eoin are young enough ( I hope they dont read this :-) ) to see it through and may not want to delegate to someone who would ??
I’m sure I listened to a Warpaint London (LON:W7L) interview not so long ago where Sam said they absolutely were delegating. My concern in terms of its ‘multibaggability’ would more be whether the significant shareholders choose to sell out ‘earlier’ and take the opportunity out of retail hands on the listed markets.
I had a chat with Sam at a recent Mello investment conference. He is a very good guy. He sees it as his baby and has no interest in retiring or reducing his holding at this point. Well that is what he told me! (I think you have believe in this life despite Elon Musks poor honesty). But more to the point the key to W7 is that they are selling the same cosmetics (nearly all made in China) as the leading 6 or 7 companies. The difference is the others spend a fortune in advertising and brand creation. W7 doesn't and that enables them to sell a much cheaper product of the same quality. Fantastic.
Yes, good point Helvellyn, this trend is well known from the last recession, remember the surge in family camping holidays in the UK as consumers cut their cloth to fit? The 'Lipstick Effect' might apply in many circumstances, a supermarket evening meal for 2 replacing dinner out was another good example from last time around and I remember someone I knew with a nails business saying that rather than losing trade to ladies not getting nails done for a holiday they were no longer taking, customers were determined to treat themselves in compensation. This effect works really well when the perceived saving is significant and there is a low resistance threshold to treating oneself.
I am a shopkeeper by trade and caution the pre-Christmas retail crisis though, it comes along most years and there are always reasons for retailers to be gloomy. Personally I saw September this year as resilient, October tough but November thus far much better than last year. Weather is always a factor. My own feeling, and this is a poll of one, is that if anything Christmas spending is a bit earlier this year, the shock of energy prices with a cold snap as well, and inflation generally, last year piled a lot of trade into December which is typically where consumers become less resistant to the pressures of Christmas giving. I also think Christmas can legitimately be later every year. Consumers wait for Black Friday deals and know that for online shopping they can be sure of delivery even if they leave it late. I think there are retailers who will do very well and it's certainly going to be competitive. If consumers are feeling the pinch it might also encourage them to shop carefully which might hopefully also mean locally, it's too easy to splash the cash online.
But being a shopkeeper at heart I have to end more cautiously: six weeks is a long time in retail!
US retailers are outperforming their 'oversold' lows currently.Target the other day and the Gap up 30% in one day at the highs today.So Warpaint's US sales (i don't hold so not sure the %s between UK, US and rest of world) could be even better than expected too.
I am a little discombobulated this morning. I am looking at the Record results and thinking they are ok. Not exciting but ok and with a divi payer (increased divi) like Record ok is good enough for me. However share price down over 10% which can only be explained by the departure of Leslie Hill, who is very popularbut has been saying for some time that the old management team are on the way out and they have been preparing to move up the talent they have in house. Well they have just done what they said they would do and apparently somebody thinks that is a reason to sell the shares. Does anyone still think the share price always reflects the news inherent in the share?
I have similar feelings about Tatton Asset Management (LON:TAM) which I hold. Down 5.7% today with just 38 share trades! The results this week were good and yet on my trading platform it remains down with, as usual, a large buy/sell spread.
With small caps you just have to overlook these anomalies and wait for the underlying value to come through, with a modest dividend for comfort.
And with just 2 more share trades Tatton Asset Management (LON:TAM) erases all its early losses!
British retail sales volumes (see below) appear to be taking a bit of tumble as the combined impact from higher interest rates, 'greedflation' & the cost of living crisis take their toll on consumers' spending habits.
Indeed ultimately this probably means that as manufacturers' economies of scale reduce (re lower volumes & overhead absorption), profit margins will continue to come under pressure.
Equally though good news for productivity improvement firms (eg software, robotics, etc)
It would be good if Record (LON:REC) interims could be covered today. Making steady progress (but down a bit on performance fees) and announcement of Leslie Hill passing over the CEO role to deputy. Recruiting from inside is often better - indicates strength in depth and a strong team!
For any dividend investors out there, does anyone use the Gordon Growth Model to value a share. John Kingham mentions it, alongside the more complex Dividend Discount Model, and so I looked into it further. It needs a constant long term dividend growth assumption, but I'm finding it quite a sensible 'simple' valuation tool. I am running it at a discount rate of 10% (my target return for good value) and 7% (UK fair value). It certainly flags when you might be over paying for quality, and equally where there is compelling value on offer. Only really useful for companies with a steady long-term dividend record such as Record (LON:REC) so not suited to all companies!).
Any thoughts - does anyone use this?
I teach both models. Unfortunately they are very sensitive to the discount i.e. interest rate used. The valuations produced will then vary widely and not be useful. So a reference point but not really that useful.
Cerillion (LON:CER) release results on Monday with a webinar on Friday 24.11.23, 11am. It's been on of those multi-baggers - following on from Ed's webinar. Stocko describe as a 'high flyer'. Register for the webinar here.
Cerillion (LON:CER) After Ed's excellent webinar on Wednesday, CER does currently show all the signs highlighted for future multibagging! I bought a few yesterday.
It could do but bear in mind its already 10 bagged, I was one of the silly sods who sold all mine at 1.70 (albeit profitably)
Good morning Paul, thank you to you and Graham, that was one hell of a SCVR yesterday, and matched with much activity in the subscriber comments it took forever to read last evening, but well worth my time. As I was catching up late on I noted your new J D Wetherspoon (LON:JDW) mystery shop and photos! As you're now a convert perhaps one quieter Friday you could start the report over a Spoons breakfast?
Spoons do the best breakfast imo. Add unlimited tea or coffee as an extra. Might just pop down to my local later!
Agreed - many thanks for covering so many, and still maintaining the high quality of insight/analysis.
I would happily buy Paul a beer if I was anywhere near Bournemouth spoons later :-)
I visited my local Spoons on Sunday lunchtime for first time in a couple of years. Clean and tidy and doing a good trade. Excellent pint of Ruddles cost just £1.77. What’s not to like?
I feel a new initiative coming on. Paul does the scvr from his local spoons on occasional Fridays and writes his table number in the comments. Subscribers use the spoons app to send pints instead of thumbs up for the day. I suspect by the afternoon this will become known as blackout Friday.
That's genius Phil MC, enough pints and by closing time he'll have put in an order for a quarter million J D Wetherspoon (LON:JDW) shares...
That's a brilliant idea!! :-)
small cap pint report, no?
SCPR
More like Stella Corrupts Value Report methinks.
Great idea instead of tips like they do on YouTube, Kofi and Patreon.I remember when the new Spoons app first came in.Was down in Brighton for a mate's birthday and sent pink sparkling wine to 2 mates who had managed to get up early for one of their brekkies from the hotel.Great app for being actually ordering inside of the shop too.
Included in Marston's Marston's (LON:MARS) announcement on a new CEO was a trading update "Current trading remains in line with management expectations. As previously highlighted, the Group will announce its preliminary results on Tuesday 5 December 2023."
Ominous words today from @FRP_Advisory
Albeit perhaps not too surprising really given the elevated cost of raising fresh capital for many small/microcaps.
"During the 2023 calendar year, the restructuring market has seen an increase in activity levels, including administrations approaching pre-pandemic levels. Companies with significant borrowings who have rolled off lower interest rate arrangements are now subject to much higher debt service costs, with interest rates now considerably higher than the 2009-2021 period. Businesses are also exposed to much higher levels of cost inflation. Certain sectors such as construction, property, casual dining and food service, retail, administrative and support services are finding current trading conditions particularly challenging."
UK companies 'sitting ducks' for takeovers by global giants, fund manager warns:
Undervalued small-to-mid sized UK companies rather than FTSE 100 heavyweights are likely to be more realistic takeover targets. We’ve already seen a lot of private equity interest in companies like Network International Holdings, Hyve Group, and Dechra Pharmaceuticals.
'ASOS (LON:ASC) is another potential takeover target, shedding over 90 per cent of its market cap over five years and more than 27 per cent over the last twelve months.'
https://www.thisismoney.co.uk/...
Here's hoping a few more of my ducks go "QUACK" then!! Only had SCS so far.....
Morning Paul, yes, you got through a lot yesterday (thanks). Would be interested in your views on React (LON:REAT) (I hold) Seem to be doing everything right and put out a nice update yesterday but SP not moving much, They have a who's who of major shareholders who own a majority of the shares which may contribute to this,
Hi PeterT,
I skim-read the update from React (LON:REAT) (specialist, acquisitive cleaning group) yesterday, and thought it looked pretty good. A strong rise in profits, and quite upbeat commentary. Its big problem is that to make more acquisitions, it needs to issue more equity. But the equity is usually too cheap to make acquisitions worth doing, as they don't add value on an EPS basis if they're having to finance them through cheap placings. Hence chicken & egg. The alternative of taking on debt, is now more costly & risky, and probably would be difficult to obtain.
So when there are so many other good quality companies on cheap valuations, I don't think a £17m cleaning company would be on my list of priorities to invest in, I'm afraid.
Having said all that, the chart is showing progress in the last 6 months, with it rising from about 1.0p to 1.6p now. They need to do a 100:1 share consolidation too, as having over 1bn shares in issue and a share price less than 2p makes it look a bit mickey mouse.
At this level of market cap, you've also got liquidity difficulties going in or out, and a wide spread too (although we can usually deal inside the spread).
Regards, Paul.
Many thanks Paul. To be fair, I've had a positive run with React (LON:REAT) but had come to a point of should I stay or should go. You have clarified the situation beautifully for me.
No truer words have been said.
"As for lessons learned, I wish I’d moved to a self-managed pension a long time ago. Readers with a modicum of investment nous should do the same. The fees are cheaper & the platform easier to navigate." Stuart Kirk FT columnist
https://www.ft.com/content/d6b...
Sorry Paul - its behind a paywall. Would have liked to have read that.
Copy and paste the title into a search engine and you should be able to read the article: ;-)
A year of ups and downs . . . and ups
Kevin, click on the link and copy and paste the headline you see to the "Incognito" window in Chrome. There are similar facilities in other browsers but I don't know the terminology they use to describe them.
Thanks all - worked a treat.
I have been following mr kirk too.
For those who do not read the ft, he advocates using a mix of tracker funds that cover the uk, us and rotw For equities and fixed interest.
I may be oversimplifying.
He does NOT believe in stock picking having spent 20 odd years being an investment manager that ran a thematic fund.
He doesn't believe in stock picking....but he does think he can time jumping in & out of asset classes within a time horizon of several months.
As for his pension gains being tax free, he is technically incorrect. Pensions are mostly tax-deferred, not tax-free (unless you time your death conveniently for your beneficiaries).
I'm afraid I've found the articles the FT wrote about him far more entertaining than the ones he writes himself.
kirk is...awful, investment wise
i'll add that his pension advice - the FT already have moira o'neill covering all this sort of stuff, and in much greater depth, column after column; she has it covered. kirk coming to this sudden realisation X years late and presenting it as a revelation to his readers is just lol
anyway, leaving aside the jumping in and out every month (or every week or w/e) for his columns: he brags about having ran a fund as manager for 20 years, yet he's only running half a mil in a portfolio at 50-60 yrs old? politely speaking: where did his money go?! either that or his fund didn't gather much in assets (and therefore fees)
as for the actual portfolio: overweighted to UK indices (the FTSE 100 which isn't even UK derived, mostly...), passively tracking Japan except the japanese stock market gains have come from alpha i.e stock-picking in the past decade or so, not passively tracking the nikkei
passively tracking a european index (IIRC) which is just headshakingly bad...again, you need to either analyse the businesses yourself, find an active/mutual fund that will, or write it off and accept their large/mega caps as your only 'exposure' within a world index
put simply: passive tracking works for the US indices (read: S&P 500, you can possibly argue S&P 400, also), the world indices (mostly US), and developed market indices (mostly US again, some japan, biggest in germany/france/italy/UK etc), largely due to the liquidity & inflows and the thusly derived price discovery. it doesn't work for emerging markets, it doesn't work for small caps, and it definitely doesn't work with jumping in and out, as the bogle ethos is to stay the course and DON'T tinker
then we come to bonds: jfc, this is the worse bit yet. steaming into long dated gilts when they were getting wrecked by inflation and rising rates? buying inflation linked bonds AFTER inflation had already hit? the strangest bit is: he even had some allocation to short-term US treasuries (correct), but made it a tiny %, i.e no where near enough and didn't connect the dots that short-duration treasuries rolled over were the correct way to go...
in short: a really really terrible version of a DIY 60/40 multi-asset fund. i feel bad for the readers that take his columns as gospel, or even worse, copy him
ofc, perhaps it's all a character that kirk is playing and he's secretly generating michael burry/joel greenblatt/early buffett type returns i.e 20%+ ABOVE the indexes year in, year out in his private portfolio, but somehow i doubt it!
anyway i'll stop here since I've ranted enough, but i think you get the idea!
"But the biggest reason I just want to sit on my potty with a lollipop" .....He sounds like a total idiot. I gave up at this point.
Here we go not behind the paywall. Don't tell anyone.
https://archive.ph/20nWF