Small Cap Value Report (Fri 18 Oct 2024) - WTB. Others all short comments: FUTR, BOO, SHI, EVOK, KOO, SALT, MTC.

Good morning from Paul!
All done for today, and the week! Have a smashing weekend :-)
Macro/Markets News
Sorry I forgot to write this on Friday, only just remembered on Saturday.
These are a few points I jotted down this week.
Continued uncertainty & speculation about what tax increases are coming. The latest thing is leaks, and hints to the press, and Govt ministers “refusing to rule out xyz” - eg
The Guardian says Govt is planning a £3bn tax raid on the gambling sector. It’s difficult to argue against this, given the huge damage they do to many peoples’ lives. Apparently some other countries have much higher gambling taxes. This strikes me as a high likelihood for a tax-hungry Govt to target, and probably get little pushback, hence why I am avoiding this sector at the moment. Gaming Realms (LON:GMR) does look a potential bargain though, having sold off in sympathy this week.
Starmer said in an interview that claims Capital Gains Tax would rise to 39% are “wide of the mark” - suggesting there might be some increase in CGT, but not the worst case scenario? We’ll find out on 30 October, but I’m trying to work out what’s most likely. I think an increase in Employers NICs is looking highly likely - which is why I’m steering clear of any big exposure to hospitality or retail sectors right now.
Some increase in Inheritance Tax or closing of loopholes/exemptions seems likely. Let’s hope AIM isn’t clobbered with losing its IHT tax breaks.
Scuttlebutt from conversations I had this week with several estate agents in Bournemouth, who said both buyers and sellers are hesitant, with many people waiting to see what’s in the Budget before committing either way.
Inflation - good news from ONS with a sharp decrease in CPI down to 1.7% in Sept, due to a high prior year comparative dropping out. Good readers comments on this in Weds SCVR. High likelihood of further interest rate cuts in the UK. ECB cut interest rates again this week, to 3.25, now much higher than the UK’s unnecessarily high 5.0%.
ONS data on wage growth showed it slowing to 4.9% or 3.8% including bonuses. This is now well above inflation, so working households are now enjoying rising real incomes, which should translate into more healthy consumer spending - hence possibly better demand for retail & hospitality sectors in future?
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Companies Reporting
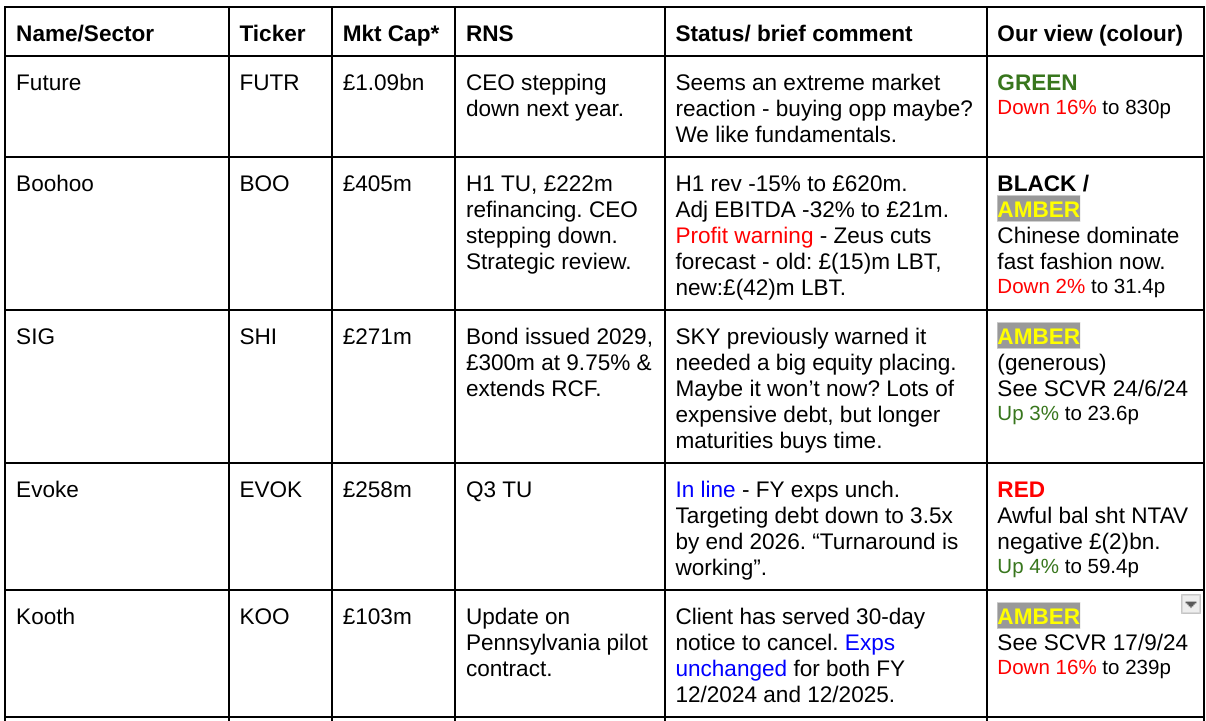
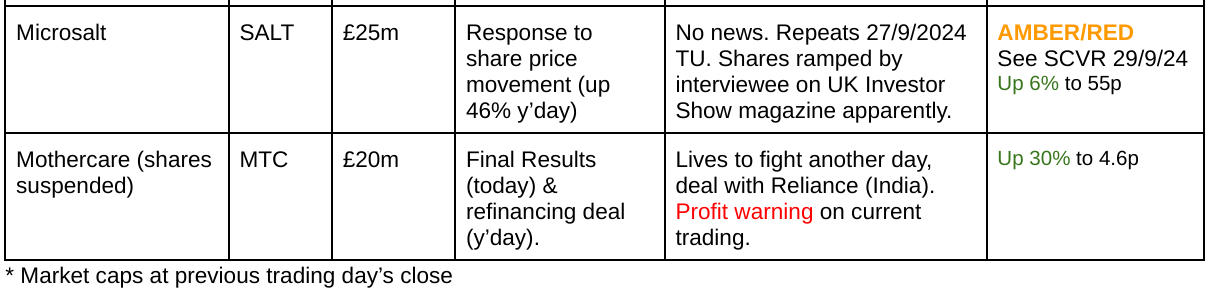
Summaries
Whitbread (LON:WTB) - 3,274p (£5.9bn) - Interim Results (Weds) - Paul - GREEN
Reported interims on Weds that were a bit below expectations, but an OK outlook and news of a fresh £100m buyback (plus very generous £2bn shareholder returns planned over next 5 years) pleased the market. Going through its numbers below reminds me what an excellent business WTB is - very much a strong GARP share. I like this a lot.
Paul’s Section:
Whitbread (LON:WTB)
3,274p (£5.9bn) - Interim Results (Weds) - Paul - GREEN
One of my favourite larger caps, this is the Premier Inn chain.
What I like -
Good market position in affordable hotel rooms, and limited branded competition, high brand recognition makes Premier Inns the go to hotel chain for many customers, and standardised service (eg. comfy beds & good breakfast).
Lots of independent competition disappeared in the pandemic.
Fantastic balance sheet with loads of freeholds and hardly any net debt (excl leases).
Strong profit margins (eg adj PBT margin is almost 25%!)
Self-funded expansion, including Germany, which should develop from being a drag on profits to becoming profitable (achieving breakeven this year).
Reasonable PER 14.4x
Good shareholder returns, with rising divis & buybacks.
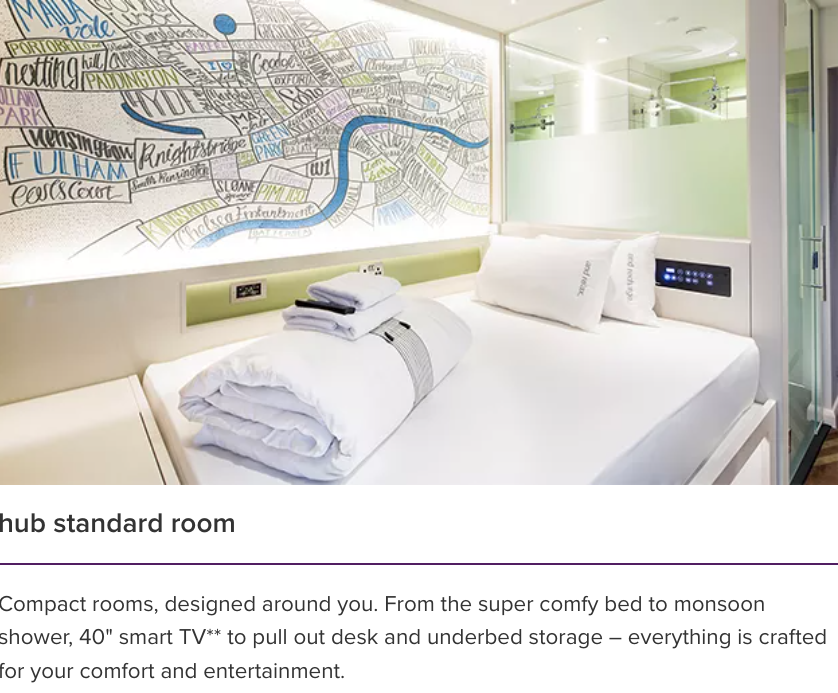
Proactive management, developing the estate & rolling out the “hub” concept (cheaper, half-sized rooms in city centres)
Downside risks? -
Wages increases have dragged on profit lately.
Increase in employers NICs could hurt the sector in the forthcoming Budget.
For disclosure purposes as required, I am not currently holding this share, having banked my profits a week or two ago, as I’m nervous about the effect of the Budget, and wanted the money to top up something else (Intercede (LON:IGP) - I hold - after recent spike down to 152p).
I mystery shopped the Premier Inn in Guernsey in the summer, and found it satisfactory. The main downside was shambolic check-in, with lots of unhappy customers, a long wait, and frazzled staff, as both the self check-in computerised terminals had packed up. Hopefully an isolated incident, but let me know if you’ve had similar problems, as it could indicate wider problems with their IT perhaps?
I’m hoping to mystery shop one of the London “pod” rooms at some point. Great idea, but the main issues might be claustrophobia and possible noise pollution, if the tiny rooms don’t have adequate sound deadening. Do share any experiences you’ve had, if you’ve tried their pod hotels.
I was rather wrong-footed by the positive market reaction to interim results earlier this week.
Key points in H1 results (26 wks to 29/8/2024)
It’s the shareholder returns that really stand out -
“Increased interim dividend and further £100m share buy-back
Five-Year Plan: at least £300m more profit and over £2bn available for shareholder returns”
£2bn shareholder returns in five years is a third of the current market cap. This demonstrates just what a cash generative business this is.
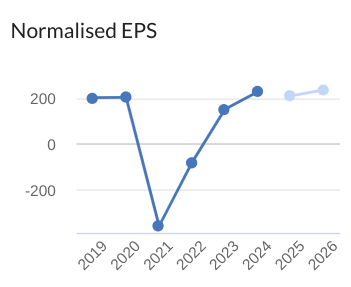
Remember too that we’re in a flat economy at present, with most sectors feeling quite down, so we could have cyclical, operationally geared profit increases to come. Plus remember WTB has absorbed large increases in wages costs over the two year higher inflation period we’ve just gone through. So I think to deliver this track record in tough macro is highly impressive - fully recovered earning to pre-covid levels, despite all the cost increases -
There’s been a useful reduction in the share count too, now down to c.179m (it was over 200m, a couple of years ago).
Trading wasn’t plain sailing in H1 though, eg -
“H1 FY25 results reflect a slightly softer UK demand environment, investment in our Accelerating Growth Plan ('AGP') and lower interest receivable, partially offset by positive momentum in Germany”
I’m happy to go with the adjusted numbers below - note how profit was down, but that’s softened to -6% at the EPS level due to the lower share count from buybacks -
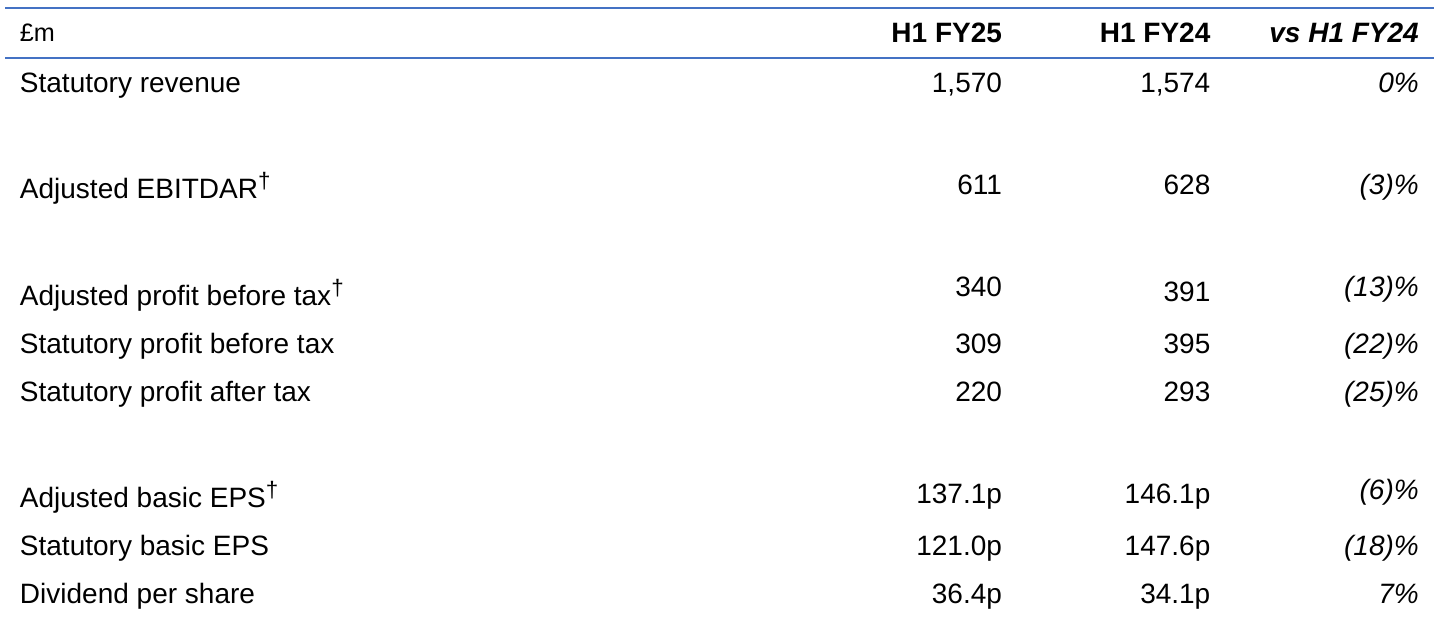
On the day (Weds) of H1 results, Singers said that the H1 operating profit of £340m was a £10m miss against forecast. Despite that, shares rose 4% on the day. I suspect the big shareholder returns and outlook comments outweighed a modest profit miss, but who knows, people buy & sell for all sorts of reasons.
The other problem is that because we’re plebs, we’re not allowed to see any broker research, so who knows what privileged information has been distributed by the big brokers to their clients?
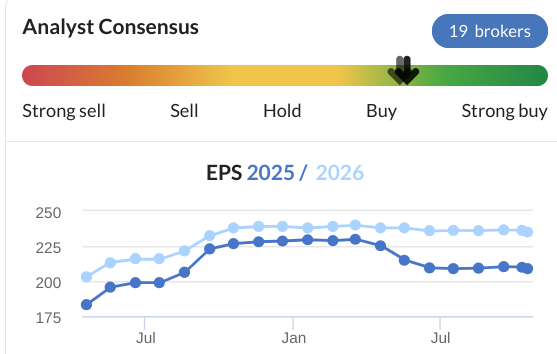
There was a bit of a soft patch in the spring, and higher costs caused brokers to trim forecasts (obviously guided by the company itself), which created a nice buying opportunity in the shares when they overshot down to as low as 2,768 in Aug 2024, which we discussed here at the time -
I don’t think that was anything to worry about, and wasn’t a big problem.
The food & drink offer has been somewhat challenged, but management seems to have taken sensible action to weed out the under-performing sites, selling or converting some of them into additional hotel rooms.
Cashflow - I love businesses that can fund their own expansion, as well as paying generous shareholder returns - when you find businesses like this, at reasonable valuations, then you’re probably going to do well with the shares over the long-term I think -
“The Group remains highly cash generative and adjusted operating cashflow† was £411m reflecting the movement in adjusted operating profit† and working capital (H1 FY24: £483m). This cashflow funded our expansion in both the UK and Germany, as well as £278m of dividends and share buy-backs completed in the period”
Outlook - strange wording here, a bit ambiguous -
“No changes to our previous FY25 guidance other than: with increased cost efficiencies of £60m in FY25 (previously £40m-£50m), we now expect UK net inflation to be between 2% and 3%”
Is that in line overall? I’m not sure. Broker consensus seems to have dropped a tiny bit this week, from 210p EPS to 209p EPS. It’s already done 137p adj EPS in H1, but remember that in undisrupted years, profits tend to be heavily H1 weighted.
Longer term, the 5 year plan sounds ambitious -
“We are executing well and remain on course to deliver a step change in our profits, margins and returns as reflected in our Five-Year Plan”
“Five-Year Plan
Reflecting our increased confidence in the delivery of our plans over the period to FY30, we expect to:
· increase adjusted PBT versus FY25 by at least £300m, and
· generate more than £2bn for dividends, share buy-backs and, if suitable opportunities arise, additional high-returning investments”
"In the UK, we have a clear pathway to further extend our market-leading position and capitalise on the favourable UK supply backdrop. We are determined to build on our significant outperformance since the pandemic and whilst the market has been slightly softer than last year, we remain on course to grow our UK returns substantially over the medium-term
In Germany, we are really encouraged by our progress to date. Our trading performance and the progressive maturity of our estate mean we are set to reach breakeven on a run-rate basis later this year. Our longer-term plans to become the country's number one hotel brand are also on track, as we move towards replicating our success in the UK market, delivering double digit returns on our current open portfolio by FY30.
Net debt is only modest, and 62% of the drawn down debt is offset by cash - this business could gear up substantially more if needed (which might attract a private equity predator maybe?) -
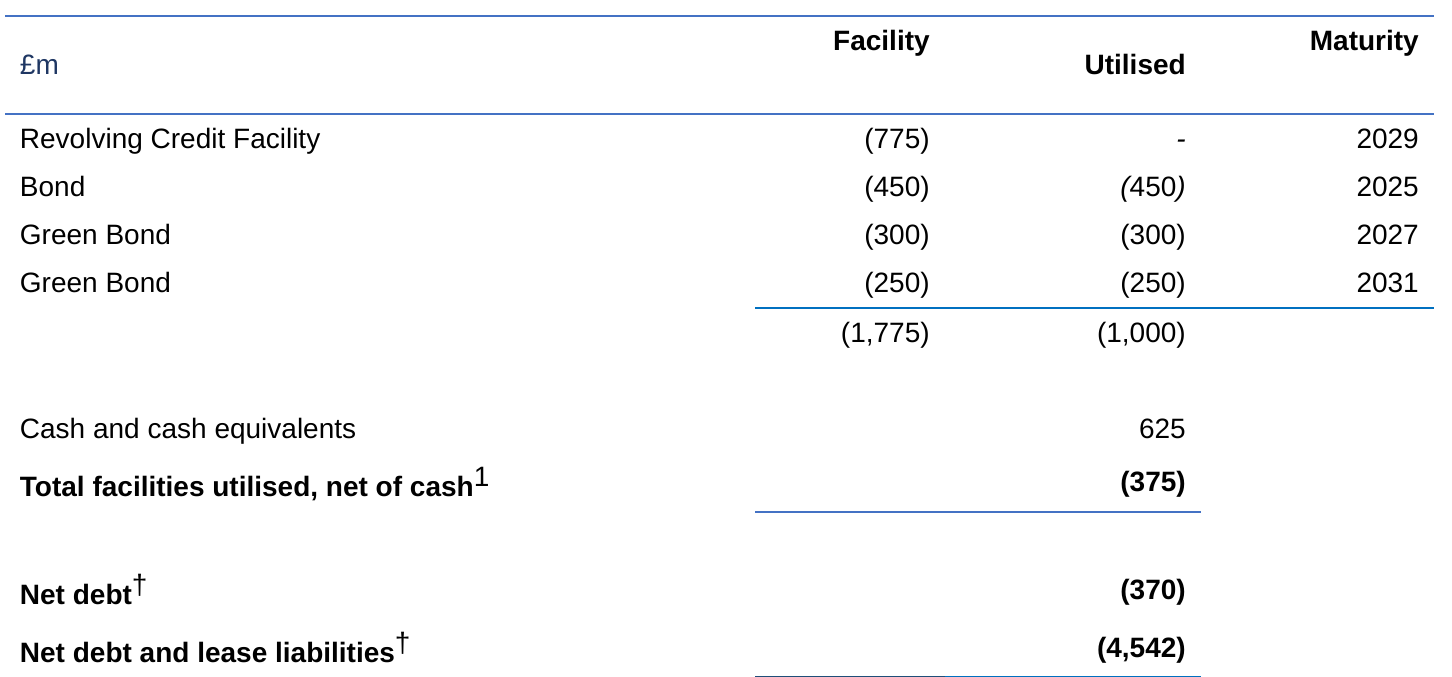
Balance sheet is excellent. NAV £3.48bn, and that includes only £181m intangible assets, so NTAV is c.£3.3bn - very healthy indeed. Net borrowings are only £375m, which is dwarfed by mountains of freehold property - just over half its properties are freehold.
Pension schemes are almost fully funded now, see the section in the H1 results RNS.
Paul’s opinion - this is such a good business! I am reminded of that every time I go through the figures.
Pity I sold my own shares just before the results, but I’ll be buying them back on the next significant dip, as I think there’s a strong bull case for share - self-funded expansion, very little net borrowings for the size of business & its cashflows. Generous shareholder returns. Market leading UK position, and the possibility of Germany replicating that success over time as it grows.
It’s got to be GREEN again.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

91 comments
My husband has plagiarised Phil Hanson’s spreadsheet and updated it to include stock rank. He only started in August this year but it will be kept upto date. Should anyone want to view it the link is here……
https://docs.google.com/spread...
Thanks Barbara. Tell Hubby, Thanks.
Thanks Barbara, your spreadsheet looks interesting. So is it trying to measure performance both of my/Graham's colour-coding, and the StockRanks combined?
There seem to be some prices manually overwritten, which means those are not updating to give the latest prices. I tend not to overwrite any of the live current share prices for this reason, or only if the company has delisted, to give the last price when it delisted. Whereas you've overwritten some live prices for shares that are still trading normally, so it's giving incorrect results on those overwritten prices. It's fine to overwrite the original price on the day of the report, if that fails to update, but the current live prices need to be a live formula, not overwritten, because otherwise you'll need to keep manually updating the live prices.
Great to see someone modifying and tweaking Phil's spreadsheet for your own use, and sharing it with us, we hoped that would happen! :-)
Regards, Paul.
The ones that have been manually overwritten (coloured in blue) all have a comment on them explaining the reason. If you have reported on the same company more than once then the current price is locked at the price it was when you gave a new rating. Graham added that in after listening to your podcast where you always state your ranking is on the data of the day and your views change when you revisit so thought it was right to lock the price when this happens. If you sort the data on company name then view the blues it will all make sense.
Love the spreadsheet. Thank you. I to have plagiarised but added a FTSE250 column (index at time of review) so I can track the broader movement over the same timeline and compare with each individual share.
Reading today's report at the end of the day, so sorry commenting on Whitbread (LON:WTB), which I don't hold (but use) quite late. Regarding Premier Inn Pod rooms, I have stayed at several over recent years in (at least) London and Edinburgh when on work trips and they worked very well - comfortable, clean, quiet and well laid out. That said I only needed them to sleep in, arrived late and got up early and so did not need to spend any time in them during the day. If I was staying for pleasure or spending any time working in them, I would find them claustrophobic but often there may be communal areas to sit in with a drink. I don't remember any specific check in issues, but I'm sure if the IT system was down there would definitely be a big problem. What probably matters most is that there are humans on hand to go back to manual systems if needed. Not too long ago the IT system at immigration when entering the US went down, and fortunately we went back to people, paper and pens, which was definitely very much better than spending the night sleeping in the airport.
I stayed at the hub by Premier Inn on Farringdon Rd (London) a few months back. It ok, served its purpose but was pretty pricey.
This was a single night stay before a meeting the following morning, so just needed somewhere to eat and sleep. Similar to Alkmund, arrived in the evening and the pod room was fine for a single night stay. Bed very comfortable but I do think the touch console by the bed that controls the lights and temperature felt flimsy and I can see this wearing out.
No noise issues at all, in fact the corridor on the way to the room was deathly quiet. The room and hotel were clean but I did find the bathroom lacking, the shower had little water pressure and there is no room to work - I did try to do a bit of work on my laptop in the morning, which was uncomfortable, to be honest.
I would not want to spend any time in the room beyond sleeping.
A few staff on hand who seemed to do everything from checking to working the bar and preparing the food.
On this point, given the time I arrived and the long day I’d had, I decided to eat at the hotel the evening I’d arrived. Very limited menu and pre-prepared microwave food in the evening. Breakfast was much better with both cooked and continental breakfast served.
Staff pleasant enough, but couldn’t pour a pint despite two of them trying - London prices (double what I pay back home) for what turned out to be little more than a half! Would have caused a riot with the Camra card holding brigade in my local. I hasten to add this was in the evening and not with breakfast!
I find them very good value, stayed at one near Heathrow, only £42, room was excellent, had be refurbished recently. No noise from outside. Food was quite good. No issues checking in or out.
One in Liverpool was only £38, did not stay as not in the right area for me.
Paul
We’ve used Premier Inn as our first choice UK Hotel chain for years now. Premier have been a Which Best buy for years and rated very well for cleanliness and the comfort of their beds as well as value. Our experience of their check in and out has also been good. Reviews on most of their hotels are good too.
Re Whitbread (LON:WTB) buybacks. Perhaps worth pointing out that Whitbread sold Costa for £3.9 billion in 2018 and decided to return most of that cash to shareholders via a big buyback. Those buybacks started around £40 and the share price has never since reached that £40! Was it really a “reward to shareholders?”
Also Future (LON:FUTR) have just completed their £43 million buybacks. The average price paid was £9.72p. Today the share price fell to £7.94. There are so many examples like these which is why I don’t like buybacks and think their benefits are way overplayed. The theory is convincing though!
Thanks Ken. Perhaps the cash could be utilised as a special dividend rather than buyback as a more tangible benefit to shareholders. Also , unless the shares are cancelled is there a risk they sit in treasurey possibly awaiting awards to directors.
Whitbread (LON:WTB)
Re Whitbread (LON:WTB) buybacks. Perhaps worth pointing out that Whitbread sold Costa for £3.9 billion in 2018 and decided to return most of that cash to shareholders via a big buyback. Those buybacks started around £40 and the share price has never since reached that £40! Was it really a “reward to shareholders?”
This keeps getting repeated (not sure if its always the same poster or not ) - but are you really saying a one in a hundered year event like covid should have been seen or planned for? - clearly the reasons the buybacks look poor value NOW is 100% due to the later effects of covid on the buisness after that buyback was done. They will have been far from alone in being caught out by covid and this is a really poor example to try and argue/show buyback are always bad - they aint and thats pretty simple and in this cirsumstance their timing ref buybacks was very unlucky - its that simple.
It’s not that simple rmillaree. Whitbread sold Costa in 2018 and the buybacks were completed before covid.
There are so many examples where there was no obvious “reward to shareholders” from buybacks and where after them for many years the share price did not again reach the buyback prices. E.g Abrdn (LON:ABDN) who started buying back at £5 around 6 years ago and where the share price has fallen ever since, despite further big buybacks every year. The share price is now around £1.70 and way below the £5 buyback starting price.
Future (LON:FUTR) have just completed their buyback programme and at an average £9.72 price. That’s not a reward to shareholders now the share is under £8. And it would have been better buying back when the shares were much lower around £6 at the time of an upbeat trading update then.
Buybacks can work well. E,g Next (LON:NXT) is a classic example where they have been very effective. Next will only buyback when confident the share is at a bargain price. But for every NEXT there are far far too many Companies that just buyback at sometimes highly rated share prices and don’t only buyback when the share looks good value at around £6 this April instead of AFTER the share price had risen substantially.
The big Mining Companies like Rio Tinto (LON:RIO) spent multiple £billions buying back their shares prior to the big Mining Sector bear market that ended in 2015 which saw their share prices crash, rendering those buybacks ineffective. So now they don’t buyback and reward shareholders via dividends and big specials in the good years. They paid dividends of 20% that way in 2022.
But you don't know what the shareprice would have been if they had not done any buybacks? Future (LON:FUTR) could have much lower.
US large caps do large sharebacks and their shares go up and up. Some shares are not going to be saved by buybacks such as Abrdn (LON:ABDN).
It’s not that simple rmillaree. Whitbread sold Costa in 2018 and the buybacks were completed before covid.
sorry ref early buybacks bit was that simple at Whibread - the buybacks turned out to be wasted money only because covid came along later and that severely impacted the business - its that simple. this is a well run business (as they are kinda proving now) and buybacks would probably have been good value without covid.
they couldnt have seen covid so buyback were particualrly poorly timed - obviously we know now that was bad plan but thats ONLY with the benefit of hindsight because covid came along.
Its always about the future success of the business that matters ref buybacks - if busines does well then buybacks genrally work. You can pick any number of companies where things went bad later and its obvious that things wont work out well ref buybacks.
There are so many examples where there was no obvious “reward to shareholders” from buybacks
If one doesnt believe in future success of the company you own surely you would simply sell up ? so sometimes buybacks can be a good time to exit the investment if you believe that future prospects arent great and that them betting on themesleves doing well is hubris.
Ramsdens Holdings (LON:RFX)
Gold price approaching £2100 an ounce, yet the shares continue to remain cheap with cash on the balance sheet, despite a positive trading update of 10th October. If the gold price remains at this level or moves higher as some think, it seems to be me that another upgrade will be forthcoming.
My view and I hold the shares, but am looking to add
"Ramsdens Holdings PLC, the diversified financial services provider and retailer, is pleased to provide the following trading update for the financial year ended 30 September 2024 (FY24).
As highlighted in the trading update published on 6 August, FY24 has been another year of record performance and the Group expects to report profit before tax of at least £11m (FY23: £10.1m). The positive trading momentum sets the Group up well for continued growth in FY25.
Ramsdens intends to announce its FY24 results on 14 January 2025.
Peter Kenyon, CEO of Ramsdens commented:
"We're pleased with the record profit performance in FY24. All key income streams are growing and we have optimism for further progress in FY25."
"This performance once again demonstrates the strength of our diversified business model which underpins our long-term growth strategy."
would it not make sense for Card Factory (LON:CARD) to initiate buybacks at this level rather than pay out an interim dividend?
Just what we need for a friday aftenoon - another divis or buybacks mass debate
im dont mind starting ot though so
Heck pe is dirt cheep - so buybacks make sense if they think earnings are sustainable - thats alwasy the million dollar question though are future prospects as good as we are being lead to believe? - as things stand 2026 numbers look very tidy.
I hold Fonix (LON:FNX) but I don’t like today’s announcement and I am tightening my stops.
There’s a couple of things that worry me about the statement :-
Firstly
If the profile of customers in the Republic of Ireland was similar to the UK, then I would expect the revenue derived from the two countries to be a similar split to their populations. But that’s not the case – the populations split 93% UK, 7% Ireland, and the revenue splits 86% UK, 14% Ireland.
That tells me Fonix has built an Irish business (in 2 years) which is disproportionately large compared to that of the UK (which took 18 years to build). As Fonix admits, the Irish business is almost entirely gambling related compared to the broader UK customer base.
And that in turn causes me to ask - were there any incumbent suppliers in Ireland 3 years ago which have been displaced by Fonix, or is this an entirely new sector that has sprung up using Fonix itself as a catalyst?
And – why is the 'broadcaster prize draw' element of the UK business disproportionately small? Is that because the Irish business is out of control and in need of regulation? Or that non-gambling customers in Ireland aren’t interested in using Fonix, and if so why would that be?
BTW these are rhetorical questions designed to illustrate my thinking on today’s announcement – I don’t necessarily expect anyone to answer them
Secondly
I think it’s a bit disingenuous of Fonix to suggest that the act might not apply to them;
‘It is … not clear whether the legislation covers ……, our Irish broadcaster customers….. [who]….. are continuing to seek legal advice over the potential impact.... of the Bill’
I’m no lawyer but I would have thought there will surely be some impact? After all, it’s called ‘The Gambling Regulation Bill’ so I think it's a reasonable assumption that a new unregulated form of gambling that has sprung up in the last two years might be an area the regulator would want to be looking at.
Having got that off my chest I reiterate I definitely see a ‘storm in a teacup’ scenario as a possible outcome from here – let’s hope so.
I found the article below on the internet today which suggests to me that if what Fonix assures us is true – namely that they are good guys and their track record in the UK proves that - then all that will need to happen is for Fonix and their customers to obtain licences and then crack on with business as usual – let’s hope so:-
https://www.algoodbody.com/insights-publications/finally-a-new-era-for-gambling-regulation-in-ireland#:~:text=On%2016%20October%202024%2C%20the,as%20it%20accelerated%20towards%20enactment.
AFAIK, they don't have any gaming customers in Ireland. What they do have are the media companies and what they're talking about are the prize draw competitions (like when you text "WIN" to ITV on a daytime TV programme competition). In the UK these are outside the Gambling Act provided there is no cost to enter beyond the normal communication cost (a stamp or SMS), or if they do have a cost, they have to also provide a no cost entry route (as above) as well.
They expect that similar rules will apply in Ireland, but since it's not mentioned in the new Bill, they have to flag it as a risk. However it would be very surprising if these kind of prize draws were outlawed, particularly as they are a way for the state broadcaster to engage with its audience and fight against the streamers.
Fonix Ive learned from bitter experience to act upon bad news. If in doubt, get out. Sadly, I like FNX but I chopped it today
I don't hold Fonix (LON:FNX) , but if I did I wouldn't be selling on today's news. What Brothersinarms says looks sensible to me. These are not really 'gaming revenues' and are unlikely to be treated as such. Quite right for the company to flag the small chance that the Irish broadcasters will get caught by the legislation but it doesn't appear likely.
Overall, this looks like a small issue (in terms of revenues affected), which in any event is outside the company's control and doesn't alter the investment case.
Maybe not selling, but why would anyone be buying? It's been a really odd couple of weeks at FNX.
Good results hit 240p, relentless seller pushes shares down to 208p low, bounced back to 226p and the exploded earlier this week up to 262p. Then today we get this news and it touches 225p again. All I will say is jt appears the seller cleared at a very convenient time, or more likely they knew the date of the Irish legislation vote?
Fonix (LON:FNX) have said this was coming in their last 2 results/trading statements so it’s hardly a surprise.
Hi, do you think Paul's short comments are just the ones in the Companies Reporting table, or has something happened to the Summaries section? (I feel a little daft for asking :) ). Thanks
The summaries seem to have vanished.
We only do summaries of the main sections. There's only one main section today, on WTB. Hope that clarifies. Nothing has vanished!
Hi Paul, re your comment on the Whitbread (LON:WTB) share count decreasing, that was when they had a tender offer after selling Costa Coffee. The share count did actually rise after they had a rights issue during the lockdowns. (I hold).
Whitbread (LON:WTB)
Hi Paul, re your comment on the Whitbread (LON:WTB) share count decreasing, that was when they had a tender offer after selling Costa Coffee. The share count did actually rise after they had a rights issue during the lockdowns. (I hold).
Paul is 100% correct here JCPr - you are getting confused between the earlier stuff and the more recent buybacks. Just to clarify Paul is talking about buybacks that are real and have been going on last couple of years. The recent half yearly results have confired that in the last 24 months the share count has reduced from 200 million to closer to 180 million - so its exactly as Paul has described (the pre covid buyback and during covid issue of shares obviously happened but aint really relevant to the here and now)
Nice to see a few of my portfolio holdings with the wind at their backs for a change.
Notably ME International (LON:MEGP) Sigmaroc (LON:SRC) and Jet2 (LON:JET2)
It seems that ME International (LON:MEGP) has at last caught the eye of some fund managers, Iain Pyle of Shires Income to name one (see Citywire) and this may be one reason for it current performance.
Jet2 (LON:JET2) and Sigmaroc (LON:SRC) are both AIM listed. My take is that the former is trading well and remains cheap. The current share price has been stable, despite founder, Phillip Meeson selling 5 million shares recently, however he still retains 15% of the company. It benefits from an excellent management team and first class customer service.
As for Sigmaroc (LON:SRC) it should be a beneficiary from the fall in interest rates that will hopefully feed through to house building, but as a mainly European orientated company I assume that yesterday's cut in EU rates will have added to positivity. Cash flow should improve significantly as the lime assets acquired from CRH become fully integrated and as with Jet2 (LON:JET2) I am a fan of the entrepreneurial management team.
Sigmaroc (LON:SRC) has been flying under the radar for a good while. Initially a much hyped SPAC it diligently concentrated on buying up companies in the limestone sector until geopolitical uncertainty around some of its Eastern quarries triggered a sharp rerating.
Mid last year outlook fundamentally changed when management serendipitously developed a £1b reverse merger opportunity of considerable complexity which now looks like it has been delivered. It's the only listed business at that scale in the European sector, the other two large incumbents privately held it seems? Shareholder presentations really worthwhile to dip in, in particular if one is innocent of limestone and the many industries that it is crucial to, to really appreciate how diversified SRC markets actually are.
SRC's recipe for success is to drive efficiency gains through its acquisitions, on the progress of which it diligently reports. Also a commendable drive towards greening this very traditional sector. Focus now set on deleveraging and potential dividends being muted. New CFO just come in, eagerly awaiting Q3 trading update (Oct).
The momentum master Robbie Burns topped up yesterday so his followers might be giving it a push , Robbie also mentioned in his blog yesterday he had been waiting for a seller to clear before topping up, he now thinks the seller is out of the way.
Sometimes better to wait a week or two after NT has bought something
Next (LON:NXT) On a fairly quiet Friday, I have just caught up with listening to the 1st Half Presentation by Lord Wolfson. Why did I leave it so long? He is such an impressive CEO and for me, who spent half his career in retail businesses making the mistakes that he has avoided, it is so instructive. The sales numbers are excellent and he gives a clear forecast for the current year's profit and eps. In my working days, there were problems with giving profit forecasts. I would like to see every company to do this, but not sure what has changed.
I love his answer to the investor question, "how big do you think overseas can be?":
"We have no idea at all ....... and we would be depriving you of the most important part of your job if we guessed on your behalf."
I recommend every investor watches this presentation:
https://www.nextplc.co.uk/inve...
Full disclosure, I recently sold a third of my Next (LON:NXT) holding (but it is still my third largest holding after Halma (LON:HLMA) and Diploma (LON:DPLM)). I am taking some profits because this new government looks like it is making the mistakes of the last government even worse, increasing Employer's NI really is the worst tax. Why we tax someone for giving someone else a job, irrespective of profitability, is completely beyond me? So reducing exposure to companies where most of their business is in the UK seems sensible to me, while we see how it plays out.
Is something going on at Dowlais (LON:DWL) - shares up 10% on no news
Courtesy of BaronInvestment on Twitter, "Dowlais shares rising as BNP Paribas Exane raises its rating to outperform from neutral, seeing a potential sale of the Powder Metallurgy business unlocking value.
Analyst William Jones says with the share price at all-time lows, there are now more reasons to be positive with “significant potential to unlock value” if the Powder Metallurgy business gets sold"
Boohoo (LON:BOO) I'm trying to see some positives in today's update regarding the strategic review of their 3 segments to maximise value for shareholders/stakeholders. Given that Frasers owns nearly 30% off Boohoo are we looking at some sort of tie up or sale of brands to Frasers going forward. That would be the most straightforward way to realise some of that value, assuming Frasers is reasonable with their valuation of the brands within. Or maybe i'm just being optimistic given that it's Friday. Reality is that Frasers usually wait until administration to swoop in.
Frasers recently put in a couple of bids for Mulberry (LON:MUL) as a large shareholder but the major shareholder won't budge so far though.His revised bid was 150 p a share.So perhaps there's some hope for Boohoo (LON:BOO) there.Apparently Ashley didn't like seeing his equity in Debenhams going to 0 naturally, although i'm not saying Boohoo (LON:BOO) will.But he's not just a total bargain bin guy.
The latest Red Flag alert from Begbies Traynor (LON:BEG) gives a useful summary of the sectors getting better and those getting worse. Highlights below.
632,756 UK businesses are in 'significant' financial distress, up 5.1% on the prior quarter (Q2 2024: 601,950) and 32.3% higher than Q3 2023 (478,176)
· 'Significant' financial distress increased in 21 of the 22 sectors covered by Red Flag Alert in Q3 2024 versus Q2 2024
· In Q3 2024 'significant' financial distress rose particularly rapidly in Utilities (+19.3%), Food & Drug Retailers (+10.4%), Financial Services (+9.94%) and Bars & Restaurants (+8.7%)
· The number of businesses in 'critical' financial distress fell quarter on quarter by 23.2% to 31,201 in Q3 2024 (Q2 2024: 40,613), 17.3% lower than Q3 2023 (37,772)
· This trend was seen in the Hotels & Accommodation (-33.5%), Construction (-28.5%) and Real Estate & Property Services sectors (-26.5%), in particular, with all experiencing a reduction in 'critical' financial distress versus Q2 2024.
· The sectors experiencing the highest numbers of companies in 'critical' financial distress were Support Services (4,860), Construction (4,324) and Real Estate & Property Services (4,099).
Gore Street Energy Storage Fund (LON:GSF)( I own) nice announcement today of significant capacity deal on the large US asset going on line. I am far from an expert here but stock trades at a massive discount, shares 57p compare to NAV 105. The installed capacity is set to grow significantly this year ... at March 24 371MW... current expectation is for it to reach 750MW this year. The Big Rock asset adds 200MW alone so this is meaningful. They have a small amount of debt and expect to receive a payment of $60-$80m this year as tax incentives for investing in the US assets supporting growth investment commitments. I know it has travelled in bad company but this looks seriously mis-priced unless I am missing something. Please advise of negatives.....
N.B In the recent NAV update in September they sort of hint that this tax receipt could also be used to buyback stock...which down here must make a lot of sense.
Definitely a sector that I have my eye on, as the logic for future growth is there. I think the main negatives in this sector are to do with the high energy costs in past years massively boosting profits which have now collapsed and the infrastructure to support the installation of new assets is very week and this hinders growth. However, it is great that this fund is investing in USA also and maybe labours "GB Energy" plan will help initiate growth in infrastructure in the UK and boost investment options for these funds. I just think it won't happen quickly but these shares really are rock bottom and if they can survive short term issues hopefully the rebound is there.
I have some concerns about how Gore Street Energy Storage Fund (LON:GSF) presents its numbers (operational EBITDA and fund level EBITDA - and it worries me why a company would pay large dividends for 5 years out of capital raised from investors, rather than covered by actual free cash flow. I also question the whole battery energy storage system (BESS) listed sector, which seems to have presented itself as solid dividend paying infrastructure investment, when its cash flows have been so volatile (as battery revenues have been so volatile) in recent years - particularly in the UK.
Having said that, I too view today's statement as positive as it should contribute to the coverage of the dividend and create more stability going forward.
My main concern going forward is the continuing decline in BESS pricing for new batteries. This is partly due to weak lithium pricing but I also understand that economies of scale are also bringing in greater efficiencies in production. Hence operators with existing BESS capacity (e.g. Harmony Energy Income Trust (LON:HEIT) , Gresham House Energy Storage Fund (LON:GRID) and Gore Street Energy Storage Fund (LON:GSF) ) might find that their historic price of their installed base is not competitive. New lower cost entrants might push down the equilibrium revenues BESS will earn.
I have owned at various times GSF and GRID - but I have no position now.
Following up on Paul's post about potential small cap bargains; https://www.stockopedia.com/co...
Tristel (LON:TSTL) report their full year results on Monday. Back on 22nd July they said;
"Tristel plc (AIM: TSTL), the manufacturer of infection prevention products, announces a trading update for the year ended 30 June 2024, having delivered a strong trading performance ahead of market expectations and the Company's own performance targets."
Shares hit 490p on that news, yet today trade at 375p. It looks like an obvious price dislocation to me, but we'll know soon enough!
Looking at this stock Tristel (LON:TSTL) last night so this update is interesting but why the price drop in July? Is it just too expensive?
Good spot AimingHigher. I last held Tristel (LON:TSTL) 4 years ago when the PE was 38, the price was 490p. I have just re-brought on a more reasonable PE of 24 @ 379p.
Tristel has been hit by the AIM sell off ahead of the budget. It is though ahead of expectations for revenue and PBT, so we know it has had a good year. In addition it has an F Score of 8/9, but if you interrogate the Stocko F Score criteria for the point it fails on, it very nearly passes, so it is effectively one of the few companies with a maximum F Score for improving fundamentals.
I look forward to more news on Monday.
Thanks, having a look at the StockReport for Tristel (LON:TSTL) it still looks quite expensive, even after the big recent drop. Nice company though, but fwd PER of 23.7x looks fully priced to me.
Graham was more positive on the last update, ahead exps on 22/7/2024, so he was AMBER/GREEN at 479p, although did mention he wouldn't personally pay 28x for it (the valuation at the time).
Also, strangely, the broker consensus chart doesn't seem to have budged, despite an ahead exps update on 22/7/24.
Regards, Paul.
The large director sales are a negative, if they are doing really well why are they selling?
Iofina (LON:IOF)
Good Q3 update from IOF this morning. Production, demand, pricing and financing all looking solid.
This business has improved significantly over the last couple of years. It's a small position for me as it is effectively a single product company, but it may be worth a comment if Graham or Paul have the time.
I added a few this morning. The immediate outlook is encouraging and it's an interesting little business.
I'm also tracking Iofina (LON:IOF) as a potential play.
However, how do you get comfortable with the fact that brine supply is dominated by a few suppliers, and that the company kinda has no security/control over the supply?
Ideally, this needs to be bought out by one of the oil/shale majors who also own the brine, and therefore use Iofina as a nice profit-maker on the side to lower their net cost of oil/gas production.
I was in Iofina (LON:IOF) , attracted by good ROC and expanding production. However, I sold at a loss when one of the brine suppliers pushed through an increase in price mid way through production. As boon suggests, any increase in profits might just taken by the brine supplier.
UK Retail sales
MoM 0.3% forecast -0.3%
YoY 3.9% forecast 3.2%
A quiet day, so Ill just make a few boring points; an antidote to noise perhaps... In Bond land, MOVE is high at 122 - not crazy but it does imply a volatility we aren't really experiencing. Despite all the noise, ECB cut yesterday, which weakened the Euro but bonds hardly reacted. In the US bond yields have risen this month by 30bp...pretty much across the curve. There is a very small steepening, but you could argue flat. None of this is really worthy of comment other than the market is braced for volatility that isn't happening which may explain all the shouting.
Gold, Silver, Uranium, Platinum remain strong. Making, or almost making new highs. Copper pulled back after the China pop. Today it's bouncing, the trend is uncertain. If Fidelity China Special Situations (LON:FCSS) is an indication, UK investors have given up on the China trade rather quickly and taken profits. The discount is back at 14% yet overnight China and HK have rallied nearly 4%. Two podcasts worth a listen are Toptraders Unplugged with Louis Gave ( bit of permanent bull on Asia) and Odd Lots with Richard Koo and Zichen Wang. Richard was the balance sheet recession man and Japan expert, his negativity is softening. But more fiscal needs to follow. Thesis intact Id say.
I spent yesterday reading the BAE Systems (LON:BA.) report and accounts. Remind myself they are no longer on any Airbus programmes! and found it interesting to read of all the diverse areas of defence that are growing currently. Obviously Chemring (LON:CHG) yesterday confirmed similar. Conflict resolution may gift us an investment opportunity in defence so worth a look... I own neither. Rheinmetall AG (ETR:RHM) shows ratings are similar in EU and stock also drifting after strong run following Ukraine.
At home the ALL share and FTSE 100 are pressing on and I feel the smaller indices will follow once we know the detail wrapped in the budget. I can't believe less building activity will be the outcome but who knows. It's a shame with the timing since we probably lost two good months in September and October as corporates wait for the news.
The Nuclear theme improves daily. The Sprott Physical Uranium Trust is nearing NAV now and therefore could start to raise and invest in spot. The spot price hasn't moved much yet. Yellow Cake (LON:YCA) (I own) NAV is c650 .. so the gap is narrowing. I wouldn't be surprised if they raise some money if momentum continues. Geiger Counter (LON:GCL) in contrast looks cheap .... NAV 65... price 51... 22% discount, and the larger holdings Uranium Energy (ASQ:UEC) Cameco (NYQ:CCJ) Nexgen Energy (NYQ:NXE) all heading towards new highs. Amazon joined the party this week with an announcement of $500m investment in SMRs... so all the big guns are lined up with the sector.
That's all, Bonds quiet and equities up....whats not to like.
Not sure about platinum remaining strong. Guess it depends on when it was purchased. I have held Wisdomtree Metal Securities (LON:PHPT) for nearly 10 years and I'm still waiting for it to get back to cost!
On Uranium I did have a small holding in Cameco (TSE:CCO) but sold out mid 2022 as not going anywhere and concerned about potential for volatility. I guess recent surge from CA$50 to CA$78 in 6 weeks demonstrates that volatility but is as you say down to the interest of Microsoft (NSQ:MSFT) and Amazon.com (NSQ:AMZN) looking to use nuclear facilities for their AI data centres. Agree on the strength of gold - certainly benefiting holdings in Wisdomtree Metal Securities (LON:PHGP) though the large gold miners ETF VanEck Gold Miners UCITS ETF USD A (LON:GDGB) seems to be a bit of a laggard given the continuing rise in the price of gold.
Apologies I am not privy to your entry levels. Neither is anyone else. Platinum is trading above its 200 day level, 50 day and 20 day. All of these averages point up. It has lagged Gold since its fuel catalyst characteristic have outweighed its precious metal qualities. Never-the-less it "looks" to be joining the Gold and Silver party. It hasn't pulled back with Copper, Iron Ore or Steel. It's about to clear some important levels and so in the game of trying to guess what happens next, I venture the price may well go higher. Whilst reclaiming all time highs look a stretch, a ten year high does not.... so on balance, I think that qualifies as being strong.
Looking at the 5 year platinum chart, it has not exactly knocked it out the park and other PMGs have fared worse; much as I'd love it to be otherwise and see my Sylvania Platinum (LON:SLP) holding recover. In their last presentation, they highlighted that they are one of the few producers in the sector who are currently profitable due to having lower costs and the offset of chrome, where prices moves are negatively correlated to PMG.
QQ for Paul Hill
Morning Paul - Do you think there is a much better chance of the Equals (LON:EQLS) sale going through now the team have their incentive shares, or would they have got those anyway?
Hi NewInvestor1972
Either way (re exercise of options), I believe a 135p/share offer is coming for Equals - as otherwise the Consortium would have backed out a long time along.
That said the key is going to be whether the institutions accept it.
ATB
Great point,
I know if I was on the list I would be very slow getting the consortium the spreadsheet they wanted if i was waiting for ordinary shares from my incentive plan :)
The longer the saga at Equals (LON:EQLS) goes on the less likely anyone is to accept it if the business continues growing at 30%
I am not minded to accept at 135p personally.
As it's a relatively quiet Friday - Can I ask has anyone done the maths on Centamin £CEY. Simple Q - Is it worth holding on for the takeover to go through - or sell now and move on. As it's not a cash deal there is also the Q whether to hold the Ashanti shares or sell them. At least with Britvic it's a cash deal and I reckon its barely worth holding on - might as well sell now ? Any thoughts please.
Hi bohenie, on Centamin (LON:CEY), having digested Ed and Megan's excellent webcast this week I implemented the "sell half on takeover bid" rule of thumb this morning. I was previously planning to hold at 100% and see where it went.
Note that the current price (~165p) is higher than the takeover bid price (equivalent to 163p, combination of shares and cash). I don't have the skills time or knowledge to work out the implications of that, so 'sell half' seems simplest thing to do.
Hi bohemie, weeks ago I'd promised myself I would sell all four holdings of Centamin (LON:CEY) when/if the price reached 165 pence (I note another commenter sold at 155 pence a week or so ago) so yesterday I did, sold the lot. Reviewing the situation today I'm now thinking the votes may go against AngloGold Ashanti's offer in the Court Meeting and the General Meeting on the 28th of October resulting in a renewed Offer. I also found that four insider Institutions recently bought more shares which helps to confirm my latest thoughts. The most telling argument is surely the future price of physical gold.
Thanks silverMoon - thats quite revealing and it's all there to see in the list of major shareholders. (I had not thought to look before) I did think at the time the offer was not exactly generous. Either these institutions are going to vote against - or they are looking to buy into Ashanti through the back door - which does not seem to make sense!
Announced that the Future (LON:FUTR) CEO to leave after less than 2 years in role, presumably came over from the US to take the role on - either homesick or things haven't worked out as they expected / Board not happy with strategy / plans - thoughts?
Is it possible that the change of government / non-dom rules etc. have any part to play in the decision? Who knows, but it's a possibility.
Good questions. I note he's staying for 12 months so hardly a rushed exit. Maybe an over reaction by the market and a buying opp.
looks like a big overreaction to me - likely preyed upon by Marshall Wace - noted they recently took out a short. That can often amplify a reaction to news like that.
With UK headline CPI inflation now below 2%, the markets are expecting the Bank of England to reduce interest rates to around 3.5% in 12 months' time.
Not only boosting GDP (see below) but also allowing the Labour government to spend & borrow more as a % of GDP.
Guardian article today on the potential tax increase on vapes, would expect Supreme (LON:SUP) to take a hit this morning. Would see this as a less controversial tax grab compared to the others moated.
https://www.theguardian.com/society/2024/oct/18/rachel-reeves-considers-raising-tax-on-vapes-in-autumn-budget
Buying opertunity on negative sentiment or another sign it's PE ratings should be that of a big tabocco company,
Another classic case of nominative determinism in that article;
"Matt Fagg, NHS England’s director for prevention and long-term conditions, said the statistics were “incredibly concerning. It means they are at risk of becoming hooked on one of the world’s most addictive substances, and that is before we consider the longer-term impacts which are still unclear.”
Since when has taxation ever been punitive enough to stop people's habits? I can remember people talking about no one ever driving anywhere if the price of fuel went above £1 a litre. At £15 a pack of fags, this still does nothing to dissuade smokers, if anything the cheaper price of vapes is moving people onto them. I cannot see a situation where taxation of cigarettes are on par with vapes, it simply does not make sense especially for the NHS.
Most excise duties, for reasons of economic theory, are on items with inelastic demand curves - so the tax does not alter behaviour. Taxes on products with highly elastic demand curves would (in theory) raise little money - as demand for the product would collapse.
One example of a “tax” working in this way (and surpringly effectively) was the minimum charge on a plastic bag - although not technically a tax.
Altria (NYQ:MO) 's still one of the largest multibaggers i think.Like Viz said, 'sin shares' are often successful for a reason and management will work out a way of making decent money from them somehow imo.
My morning smallcap tweet: Gross exaggeration?
MicroSalt (LON:SALT) Boohoo (LON:BOO) Intuitive Investments (LON:IIG) OptiBiotix Health (LON:OPTI) Cloudcoco (LON:CLCO) Fonix (LON:FNX) Iofina (LON:IOF) Mothercare (LON:MTC), Evoke (LON:EVOK)
◄MicroSalt (SALT)► notes the huge SP rise yesterday - there is no trading or operational update. Co "notes comments made in a recent UK Investor Magazine podcast, during which the interviewee [Tekcapital’s Clifford Gross] indicated a hope for "blockbuster B2B and retail distribution agreements in the coming months." MicroSalt wishes to emphasise these remarks were purely the opinion of the interviewee." [SP=54 Cap=26m]
◄booHoo (BOO)► H1-Aug rev down 15% and adj EBITDA £21m (£31m). Expects higher sales and adj EBITDA in H2. New £222m debt facility at SONIA + 4%. "Board strongly believes there is potential to unlock shareholder value and is exploring options to deliver on this." Bigging up Debenhams marketplace potential. CEO to leave. [SP=32.26 Cap=409m]
◄Intuitive Investments (IIG)► £6.2m placing at 133p, a 1.5% premium, for investment in Hui10 to accelerate the rollout of Hui10's products and services in China. [SP=130 Cap=263m]
◄OptiBiotix Health (OPTI)► some spat involving AQSE listed ProBiotix Health which OPTI has a holding. [SP=13.75 Cap=13m]
◄CloudCoCo (CLCO)► contitional agreement to sell CloudCoCo Connect for £250k ncluding the sale of net liabilities in excess of £1.7m. [SP=0.32 Cap=3m]
◄Fonix (FNX)► re Irish act creating a Gambling Regulatory Authority: FNX's "Irish broadcaster customers, which represented the vast majority of the Company's revenue outside the UK in FY24, are continuing to seek legal advice over the potential impact, if any, of the Bill on their business." [SP=245 Cap=242m]
◄Iofina (IOF)► guides H2 production in line. Sales are strong, driven by sustained demand and increasing iodine prices. [SP=17.5 Cap=34m]
◄Mothercare (MTC)► FY-March adj EBITDA £6.9m (£6.7m), ahead of analysts' expectations. But March was 7 months ago. Current H1 Franchise Partners retail sales £121.2m (£137.3m). Blames continuing challenges in Middle Eastern markets. [SP=3.4 Cap=20m]
In line: EVOK
“notes comments made in a recent UK Investor Magazine podcast, during which the interviewee [Tekcapital’s Clifford Gross]….”
Interesting MicroSalt have issued this today. They came straight out of Tekcapital’s portfolio who still hold two thirds of the shares. - a case of speculatively talking up their own book?
Methinks Mr Gross’ comments should be taken with a pinch of salt.
Fonix (LON:FNX) possible change of regulations in Ireland. Not good, markets don't like uncertainty!
Yep thought about whether to cash in today but have decided to ride it out. Really does seem uncertain at the moment and the business model still is exciting. Might indeed be a good entry point given this has traditionally been trading at high multiples
For me it's short first, ask questions later. Regrettably
Shoot not short!
Although 'short' works too!
Fonix (LON:FNX) possible change of regulations in Ireland. Not good, markets don't like uncertainty
Ireland is less than 15% of the company’s turnover, which, in the event that the product succeeds in being rolled out across other European countries will fall to below 5%. And there’s not even any clarity on whether regulation changes would affect the company at all.
Cavendish has issued an update this morning saying it's not changing forecasts, and doesn't expect any impact from Irish bill.
Also note that FNX is mainly UK business, its Irish operation is relatively small.
Storm in a teacup maybe?
Thanks for that Paul. Possibly, am I being too cautious?!
I think you are right to be cautious for a company trading on a PER of 23x and forecasting EPS growth of 0.93% this year and 3% the year after. Add in regulatory uncertainty (is it a massive stretch to speculate the new Irish bill could impact the wider UK market too?) and I'd say it looks very top heavy.
A good business, but is it worth 23x earnings? Not in my opinion.
Think those EPS targets are set too low and you'll get upgrades, 10-15% annual growth over 5 years might well be doable which goes some way to justifying the premium multiple. If you think growth actually will be sub-5% then it's overvalued.
Yes I’d say a 20* PER is exactly what you’d expect for a business with a strong moat, zero customer churn and very very sticky revenues.
Fonix (LON:FNX) possible change of regulations in Ireland. Not good, markets don't like uncertainty!
Could well be a storm in a teacup in this instance but maybe provides some uncertainty re: the ease of international expansion?
Fonix (LON:FNX) I think management have been quite candid about international expansion, basically they are very selective in choosing new countries to enter as the key factor is owning relationships with the mobile network operators. From what they've said I inferred that what they do can't just be rolled out into any country they choose, and there are other businesses doing similar things elsewhere around the world.
From memory, they are active in DACH, for example, but my understanding is it's tiny in terms of revenue because they operate via a partner who has the MNO relationships (presume Vodafone is a big deal in that region) so their share of the takings is lower. I think they also mentioned that they provide similar access for a few overseas peers...they have access to something like 95% of UK mobiles via their relationships with the mobile networks.
I assume the reason Ireland and recently Portugal are mentioned as important is because they own the MNO relationships directly hence the economics are similar to what they can achieve in the UK.
I might be mistaken here, open to being corrected if anyone has a better understanding?
Boohoo (LON:BOO)
John Lyttle stepping down. Tears anyone?
Already shed those after losing my shirt on them!
BBC News - Inheritance tax increases expected in Budget
https://www.bbc.com/news/articles/c8el3z910r9o
I think we’ve all come to recognise that all things are being considered but that the Telegraph in particular wants to sensationalise with alarmist copy