Small Cap Value Report (Fri 19 April 2024) - 888, FNX, SAGA. Movers: EMG, ZTF, NCYT, ENET

Good morning from just Paul today, with it being Friday.
Not much news today, so it'll be a catch-up day. I've got a list as long as my arm of companies to review (SAGA first), so no more requests please, there's masses to do, so I should have a big report done by lunchtime. It's overcast & windy here in Gozo, so there's nothing else for me to do!
Overnight news suggests that Israel may have launched a retaliatory missile strike against Iran, which is unsettling the futures. This is not the right place for discussing geopolitical issues, but it's likely to have some impact on markets, as the situation seemingly escalates. Two powerful nations directly firing missiles into each other's territory (rather than via proxies) is certainly an escalation. Let's try to stick to the impact on markets & economics here, rather than going down the rabbit hole of the politics of it all, which is definitely best left to all the vocal, self-appointed experts on social media!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
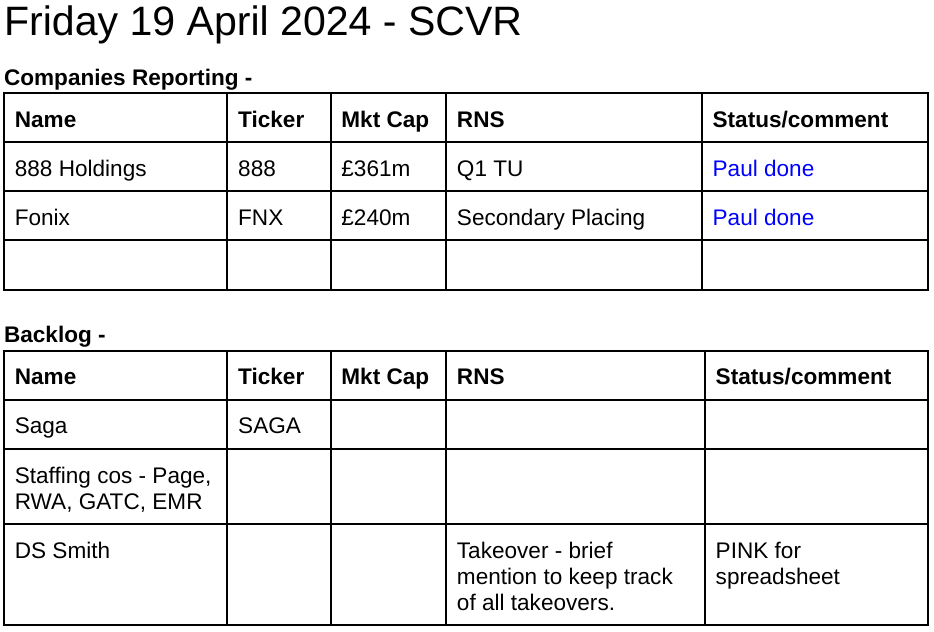
Other mid-morning movers (with news)
Man (LON:EMG) - down 5% to 255p (£3.06bn) - Q1 Trading Update - Paul - AMBER/GREEN
It's been many years since I last looked at this fund manager, which is known for its clever, systematic strategies. Shares crashed in the years after the 2008 crisis, and have only partially recovered since. Both Graham and I think the fund manager's space is a good bargain hunting ground at present. The StockReport shows attractive valuation metrics for many, including MAN - fwd PER of 8.3x and 5.5% yield, with decent asset backing too.
Q1 update today gives the key AuM (assets under management) stats, which show growth of 4.9% to $175.7bn - entirely driven by impressive investment gains in some funds. Client flows showed small net outflows.
Paul’s view - I don’t know why the share price has fallen 5% on this news, the market must have been expecting something better, or people just wanted to bank profits, who knows? Anyway, on the quickest of skims, I think this looks worth a closer look.
Zotefoams (LON:ZTF) - up 3% to 380p (£186m) - Partnership Agreement - Paul - GREEN
The market gives a cautiously positive reaction to this news -
Zotefoams, a world leader in cellular materials, is pleased to announce that it has entered into an exclusivity agreement with design and technology company, Design Blue Limited ('DBL') in relation to a newly launched foam material, developed in partnership with DBL, for high-performance impact protection solutions for the defence and law enforcement sectors…
I’ve looked up Design Blue at Companies House (co no. 03792408) it looks pretty good - FY 12/2022 revenues of £24, PBT £5m, with a nice strong balance sheet. So I’m guessing this deal with ZTF isn’t likely to be huge, in terms of revenues/profit for ZTF, but who knows?
Novacyt SA (LON:NCYT) - up 5% to 67.4p (£47m) - Pre-Trial Review - Paul - no view.
This was a covid wonder stock, that crashed & burned. It’s ended up with lots of cash, but a big legal case against the UK Dept Health, with trial imminent. It says today that the case against it is weak, and expects it to be thrown out (but they would say that). So it’s a special situation for punters who like gambling on court cases! Good luck.
Ethernity Networks (LON:ENET) - up 6% to 0.93p (£3.5m) - FY 12/2023 - Paul - no view.
Disastrous 2017 float, based in Israel, multi year losses & heavy cash burn. So it looks a disaster by all usual measures. However, 2023 results offer a glimmer of hope - revenues growing (up 26%), and a strong improvement in performance for H2 - EBITDA loss reduced 74% from H1, to $(0.8)m. Also has $2.0m cash left. Very much in the last chance saloon I would say, but the rapidly reducing losses, and maybe enough cash to get through 2024, mean there’s a possibility it might survive. Material uncertainty in going concern is an obvious worry. Paul’s view - this is not an investment, it’s a punt. I just wanted to get a quick comment into our archive for future reference, if any significant news were to come out. De-listing risk probably high. So yes it’s high risk, for sure.
Summaries of main sections
888 Holdings (LON:888) - up 2% to 81.3p (£366m) - Q1 Trading Update - Paul - AMBER/RED
Q1 update is reassuring, and FY 12/2024 expectations unchanged. I recap on the scale of the debt problem here, which is mind-boggling. This is a high risk: high reward special situation. It's likely to be a big mover in the next two years, but I don't know in which direction. Downside risk is too great for me to want to get involved.
Fonix Mobile (LON:FNX) - down 3% to 232p (£232m) - Director Selling - Paul - GREEN
Secondary placing by Directors. I run through the reasons why this has not spooked me. Hence I remain positive on this impressive share.
Saga (LON:SAGA) - 111p (£158m) - FY 1/2024 Results - Paul - AMBER/GREEN
Cruise & travel are doing very well, but insurance is still a problem area. Overall underlying profit improved, but is now expected to be flat for this year FY 1/2025. Debt needs restructuring, but I'm not worried about solvency or liquidity. To me the glass looks potentially half full here, but I'm not totally convinced, it depends how future trading goes.
Paul’s Section:
888 Holdings (LON:888)
- up 2% to 81.3p (£366m) - Q1 Trading Update - Paul - AMBER/RED
888 (LSE: 888), one of the world's leading betting and gaming companies with internationally renowned brands including William Hill, 888 and Mr Green, today announces a trading update for the three months ended 31 March 2024 ("Q1-24" or the "Period"). Further detail on the financial results by division is included as an appendix to this announcement.
Graham normally reports on this highly indebted gambling group.
Checking his previous notes for background -
28/9/2023 - Profit warning - Graham is amber, Paul is red, in a rare disagreement
5/12/2023 - Sunday Times rumour that 888 turned down a takeover offer from Playtech of 156p in July 2023.
17/1/2024 - Mild profit warning, low end of forecast range. Graham is amber/red at 74p.
26/3/2024 - FY 12/2023 Results. Main issue is huge debt, but has time to refinance. Graham: AMBER/RED.
Clearly it’s best to see this as a special situation, with higher risk:reward.
Today’s news - its Q1 update is reassuring, but not price sensitive particularly. At least it’s broken the chain of previous profit warnings, so forecasts seem more reasonable now, having come down a lot (more than halved over time from original hopes) -
Q1 2024 revenues slightly ahead of guidance; no change to full year expectations
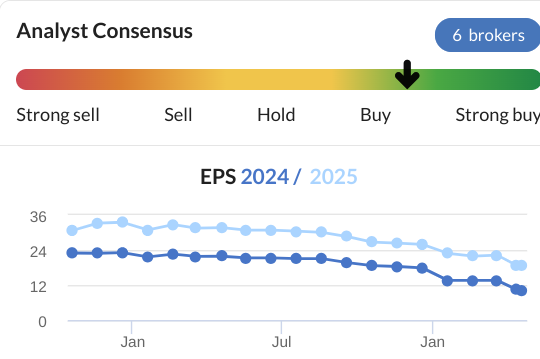
Revenue appears to be on a gently improving trend -
Revenue up 2% relative to Q4 2023, reflecting a continuation of positive sequential quarter-on-quarter trends. The Group continues to expect revenues to return to year-on-year growth from Q2 2024 onwards, with full year 2024 revenue growth expected to be consistent with the mid-term target of 5-9% annual growth.
Strategy is reiterated -
On 26 March 2024 the Group announced its new strategy, Value Creation Plan (VCP) and clear medium-term financial targets, namely to grow revenue by 5-9% per year, improve adjusted EBITDA margin by approximately 100bps per year and focus on deleveraging to reach net leverage of 3.5x or below by the end of 2026. Strategic focus on embedding new ways of working across the business…
Reset of operating model well progressed, with £30m 2024 operating cost savings being reinvested into more profitable marketing to drive growth, in-line with the VCP.
Action taken to improve EBITDA from 2025 looks good - but was previously announced, so nothing new -
Conclusion of strategic review of US B2C business announced on 28 March 2024, with the sale of selected assets and closure of remaining operations expected during 2024 subject to regulatory approvals. This is expected to deliver an ongoing EBITDA improvement of £25 million per year from 2025.
Outlook -
"I am pleased to report that Q1 2024 revenue was slightly ahead of our guidance, with strong player volumes converting into improved revenue run rates. Having lapped various regulatory and compliance changes during the quarter, and with increased marketing investment supported by an exciting product pipeline, we remain confident in a return to growth from Q2 2024.
Paul’s opinion - this update generally seems mildly positive. At least they’re doing something to dig themselves out of trouble. We don’t know whether it will work or not at this stage.
I’ve had a quick look back at the FY 12/2023 results, and the scale of the debt problem really is mind-boggling. NTAV was negative c.£(2)bn. Remember the market cap is only £366m, so equity is a small stub really, it’s debt that is of paramount importance (and of course debt ranks ahead of equity in law), with net debt of £1.7bn at Dec 2023. This was 5.6x EBITDA, unchanged from end 2022. The problem is that higher interest rates mean this debt is now expensive, with finance costs of £195m consuming all the operating profit (and that’s using the more flattering adjusted numbers). Note that the c.£40m finance income is nearly all forex gains, which are one-off, so I've ignored that.
Therefore this means there is practically zero chance of 888 being able to repay any meaningful amount of its debts from cashflow. So some alternative solution needs to be found in the next couple of years, as debt maturities are 2026-28. Covenants would need careful scrutiny.
Takeover approaches may not work, because the huge debt has change of control clauses, making it immediately repayable. So a would-be acquirer would first have to negotiate with the debt providers, before even considering what they might offer for the equity - why would they be generous? A bidder might just wait a couple of years for the debt providers to get more jumpy, and do a deal that wipes out equity perhaps? Other scenarios might be a debt for equity swap, which again would be incentivised to drive a hard bargain to the detriment of existing equity. Debt is so large that I regard it already as quasi-equity. These numbers remind me a bit of Cineworld, whose equity eventually collapsed under the weight of massive debts.
All in all, it’s a can of worms, and the only hope is that trading improves significantly, and allows management more flexibility to do a placing and/or debt for equity swap with a higher future share price.
The upside scenario would be if trading really takes off, then the benefit would all flow to equity and give a potential multibagger. I’ll keep an eye on it, but for the moment it’s not at all clear which direction this is headed. It’s going to be a big mover in the next couple of years, but I don’t know in which direction unfortunately! As risk is high, I’ll stick with AMBER/RED.
EDIT: I checked one of the bonds, and the 2028 9.4% bond is trading in Germany at 98, almost par. That seems to suggest the bond market isn't worrying about getting their money back - the price has been on an improving trend in the last year too.
Fonix Mobile (LON:FNX)
Down 3% to 232p (£232m) - Director Selling - Paul - GREEN
A managed sale of Director shares has been done through a “secondary placing” - remember for anyone not aware, this has no effect on the company itself, secondary placings are when large lumps of existing shares are bought & sold off-market, matching buyers & sellers.
…the Selling Shareholders have successfully sold a total of 6,666,667 Placing Shares at a price of 225 pence per Placing Share due to significant overdemand. The Placing Shares in aggregate represent approximately 6.7 per cent. of the Company's issued share capital.
It’s a fairly modest price discount, so price is not a worry.
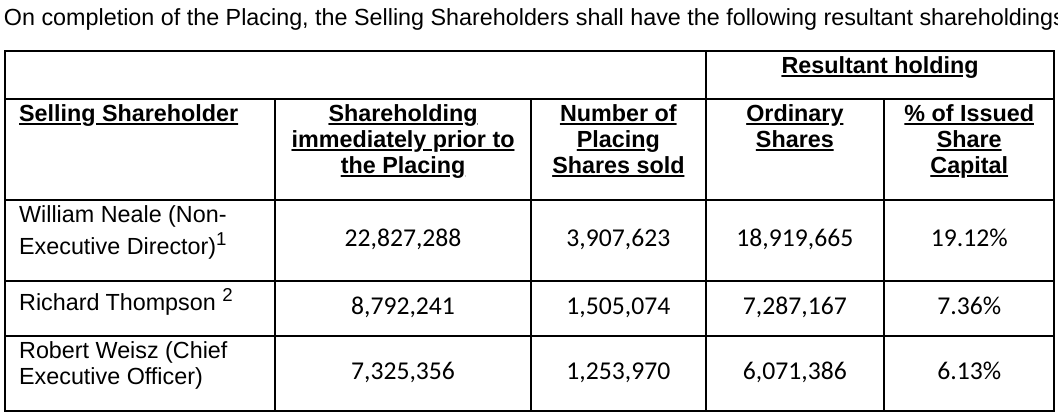
Selling shareholders are mostly Directors, which to me is always a negative (Directors selling hefty amounts). However, I’m reassured that they still have very significant holdings, so it’s probably not a cause for alarm, or major concern -
Lock-in? I prefer it when this type of announcement comes with a commitment not to sell any more shares within say 6 or 12 months, but nothing is said here.
Paul’s opinion - hefty Director selling is never welcome, and can often be the canary in the mine, that it’s time for small investors to sell too. However, each case is different. In this case, I think the numbers look fine: the table above goes from 38.9m shares before, to 32.3m after. At 225p/share, their remaining holdings total £73m - a huge amount of money remaining invested in FNX, and 32.6% of the company.
To me, that’s absolutely fine. I’m told the Directors are serial entrepreneurs, who invest in many startups, etc, so it seems entirely reasonable that they might want to lighten the load a bit in FNX, to use funds for other investments.
Overall then I don’t feel knocked off course by this news, and happily remain at GREEN. I think Fonix is an excellent company (loads of detail in our archive here). Message to brokers - find more companies like this to list on AIM, and the market will blossom over time.
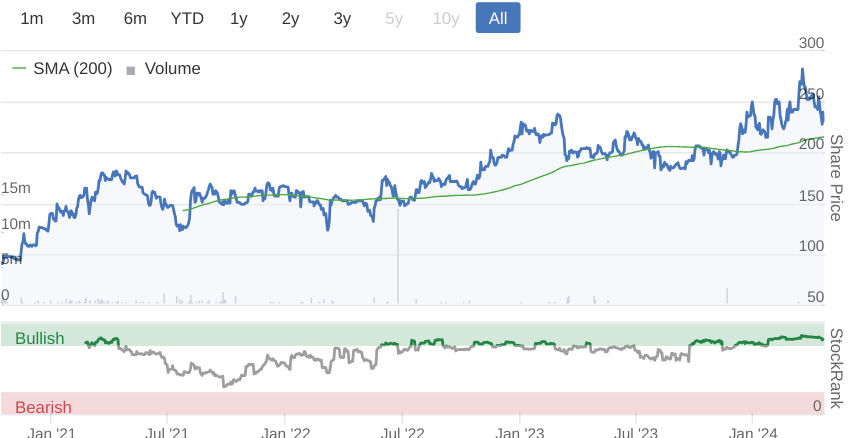
Note that Fonix is also a reliable cash cow, and dividend payer, so the total shareholders return is better than the chart suggests. FNX shares have gone in the opposite direction to most small caps over this period since the 2021 market high - so relative out-performance is much better -
Saga (LON:SAGA)
111p (£158m) - FY 1/2024 Results - Paul - AMBER/GREEN
Saga plc (Saga or the Group), the UK's specialist in products and services for people over 50, announces its preliminary results for the year ended 31 January 2024. These results are reported under International Reporting Standard (IFRS) 17 'Insurance Contracts' and any prior year comparisons have been restated accordingly.
SAGA’s main operations are insurance, and travel (particularly two owned cruise ships). The concept is that it’s a long-standing (and trusted?) brand for services directed at the over 50’s. Historically this was highly profitable & cash generation, but a period of private equity ownership (using it as a cash cow) seems to have done a lot of damage. Or maybe the whole concept of a brand for older people is now outdated, since an increasingly internet-savvy older generation can just shop around for whatever they want, from any company? Who can say, I’m just pondering. Personally, I think this brand is still of considerable value, just maybe not as much as before.
I can’t use the highlighter on my abroad chromebook, but the obvious points below are the large size of adjustments in both years - but if you accept the adjustments, then profit is moving in the right direction. Also note the huge (but reduced somewhat) net debt -
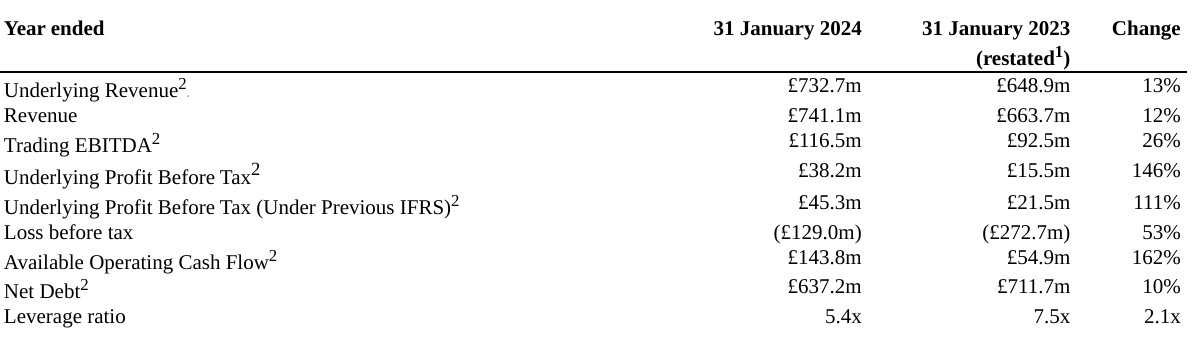
Debt - the key point, which many people just seem to ignore, is that most of the debt is financing the owned cruise ships. So the leverage ratio doesn’t make sense to me. I would strip out the cruise loans, which is asset financing, and then view the remaining net debt as structural, and it’s not actually particularly excessive. Sure it would be better if it came down, and profits need to rise further. Anyway we’ve covered this so many times before, I don’t want to get bogged down in analysing the same things again - different investors view it differently. The key point is that I don’t see insolvency risk here, because the founding family have propped it up with loan facilities which give plenty of headroom for the bond repayment.
A £75m reduction in net debt in FY 1/2024 is actually quite good. There probably won’t be any divis for a while, until these historic things have been sorted out.
If performance improves in future, then the leveraged upside to equity (from a market cap of only £158m) could be substantial, as one of our top regulars, davidjhill has explained in the reader comments earlier this week. Both bull and bear cases make sense to me, depending on how future trading goes.
Also management are looking at ways to make it a more capital-light business model, which it has been speculated might involve a sale & leaseback on the cruise ships. That would wipe out the bulk of the debt in one fell swoop, and could be a nice catalyst for a re-rating of the shares, if it’s done, and on sensible terms?
There’s also been repeated talk about disposing of the insurance underwriting division.
Cruise & travel - impressive words here -
"Ocean Cruise had an outstanding year and, as a result, we far exceeded our initial earnings targets, while River Cruise and Travel both returned to profit for the first time since the pandemic. Looking ahead, forward bookings are strong, with all three of these businesses significantly ahead of the same point in the prior year.
Insurance - not sure about this, it seems to be a problem area -
"While our Insurance business continued to be hindered by challenging conditions, with inflationary headwinds impacting policy volumes and margins, particularly for our three-year fixed-price policies, we are taking the necessary actions to reposition the business. We are investing in price to improve our competitive position and stabilise our policy volumes and early signs indicate that this is delivering the expected benefits.
Outlook - rather uninspiring -
The net result of these is that we expect the Group to generate an Underlying Profit Before Tax10 that is broadly consistent with that of 2023/24, reflecting growth across Cruise and Travel, offset by a transitional year in Insurance, before a planned return to growth thereafter.
Paul’s opinion - debt & liquidity bother me less than most other investors, I think.
Cruise & travel seem to be performing well, but the insurance businesses look to be the problem. So I think the upside case on SAGA shares mainly comes from them being able to sort out the insurance side, and return it to previously decent profits. If that can be done, then the shares would have big upside I think.
Alternative upside could come from a deal to clear the debt on the cruise ships, and that’s surely looking more likely now that we know they’re operating profitably & ahead of expectations?
I appreciate some readers will think I’m wrong, but I see more upside here than downside, so I’m going with AMBER/GREEN. I don’t have any position, or emotional attachment to this share, in fact I’m rather fed up with it after years of disappointments when I forlornly waited for a promised turnaround that didn’t happen (or rather, has only partially, and very slowly happened). So I’m definitely not looking through rose-tinted glasses, as with all shares, we’re trying to look at things dispassionately with fresh eyes.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

74 comments
This week's podcast has gone up early tonight, as I'll be busy tomorrow relocating from Gozo to Valletta.
Web version is here: https://shows.acast.com/630c95...
Two powerful nations directly firing missiles into each other's territory (rather than via proxies) is certainly an escalation.
Thank you for your insights. Right or wrong this is huge and of serious concern.
Almost want to shut up shop and let things develop - but there is no fun in that.
Sorry Kids Grandad is a nut job - let the games begin.
Bad news still over the pond naturally and not just for financial markets internationally.
On a side note Argentex (LON:AGFX) still being sold down on Rockwood reducing slightly i suppose.I'm guessing they haven't suddenly totally changed their minds about the company.I'm hoping they just need a bit of cash liquidity elsewhere!
New TR1 from Harwood over at Funding Circle (LON:FCH) this afternoon. Well worth checking out the special situation over there; £25m buyback, cash = market cap, selling US business, UK business profitable, new Fintech subsidiary Flexipay experiencing explosive growth. You can certainly see why Mills wants to take a stake.
Well, the market has closed so for those with a pool to dive into - enjoy!
Hey that's where I'm staying at the moment in Gozo! How did you manage to get a picture of my pool?! LOL :-D (it's too cold to use unfortunately)
Is Spire Healthcare (LON:SPI) abut to live up to it's name and break out of the range it has traded for the last 3 years?
Profit growing but margins and ROCE are work in progress.
Recent sale of hospital to NHS for £10m won't make much progress on YE debt of £1,207m.
Might be worth a trade from current 246p to target of around 350p
Not one I hold
SPI
This was Ed. Croft choice last year and Robbie Burns regularly trade in at around 200 and gets out around 240. It has been such a predictable performance. The macroeconomics with a huge waiting list is in their favour. It is also my candidate for being taken over, my hope!
Spire Healthcare (LON:SPI) Lamentable failure to take advantage of the poor state of the NHS.
Couldn't disagree with you more there doctor. My wife has just received an incredible level of care and attention for a gall bladder op at no notice. In fact, so busy are the Norwich and Cambridge Spire Hospitals that I have put Spire Healthcare (LON:SPI) on my watchlist!
That's great, very pleased for you on a personal level. But at the organisational level, I expected Spire Healthcare (LON:SPI) to take full advantage of the difficulties the NHS is facing, and it hasn't, in my view, shown the imagination to develop and expand in the way I would have expected.
I'm thinking of using Spire Healthcare (LON:SPI), the NHS takes so long, l had to wait 9 months for an appointment at a hospital, l could have died before then. After the appointment which did not find anything will to have some tests, no idea how long that will take.
If it is cancer then best to pick it early.
I know some people use Spire Healthcare (LON:SPI) and have good reports and they are very particular.
Having paid into the NHS for many years, pity it is not available when you needed it.
I do have a small recent holding in Spire Healthcare (LON:SPI) .
Re Novacyt Paul, I have a view, they were shafted by the Health Department. Yes you might have guessed --I can pick em! I liked what they did and how they did it during the Pandemic, I still like what they do. We only have 1250 shares but are down almost £6,000. Will I be outside the courtroom with a placard? No, but having followed what happened, and what was happening at the time with suppliers and contracts, I am on their side. It's not the forum for it but if anyone is better informed on this than I am, I would love to read their view.
I broadly concur. I haven’t looked into this for a while, but (foolishly as it turns out) held whilst the legal action unwinds. My reading at the time was that there was little to indicate that Novacyt SA (LON:NCYT)’s product was faulty and that the DHSC were using it as politically expendable scapegoat, following a government dictat to reduce spending on Covid related equipment.
That said, we are now so long after the fact, I can’t see even a comprehensive victory in the courts as having more than a minor impact on the companies fortunes.
Re Saga (LON:SAGA) I’d urge anyone even mildly interested to watch the analyst meeting recording on their IR website…..the nub of the matter is that moving to a capital light business model when you’ve already got the cruise ship assets charged to the existing funders is not going to be straightforward…unless Saga give up significant commercial upside..
Will give it a watch, I brought in earlier this year and am nursing a 15% price reduction so am considering selling. My logic earlier this year on a basic level was that older people drawing down on their pensions with less debts to pay (not all) have been doing well out of a higher interest rates and are now getting more pension income to spend on things like cruises. The issue saga has with a lot of debt themselves is the same high interest rates will impact them too until & unless they can pay down debt or sell + leaseback the boats.
Saga (LON:SAGA)
Paul
The key point is that I don’t see insolvency risk here, because the founding family have propped it up with loan facilities which give plenty of headroom for the bond repayment.
imho the issue here is that they have confirmed that Sir Roger wants his money back in 24 months and they have confirmed they dont have the money to pay either him or the £250 mill bond that matures in July 2026.
I dont see it necessarily as an insolvency issue (more a potential dilution issue) but surely they are telling us they need to raise large amount of funds quickly from somewhere - imho thats exactly the opposite of the family propping up the business - they are saying we saying we want our money back and you need to find it from elsewhere to pay us and the clock is ticking !! - as has been done to death they may have asneaky cunning plan but if they do they are keping that plus point close to their chests whilst slapping us in the face saying they cant pay the bills in 2026 !!
The Directors have considered the resilience of the Group, taking account of its current position, the principal risks facing the business in severe but plausible scenarios and the effect of any mitigating actions. Under all scenarios modelled, the Directors have identified a need for additional mitigating action beyond the scope of normal trading to manage the solvency of the Group at key pressure points over the five-year period. These points include the maturity of the £85.0m loan facility with Roger De Haan in April 2026, and the maturity of the Group's £250.0m unsecured bond in July 2026.
Hi rmillaree,
I take your points, but you seem to miss one key thing - that over the next 2 years, SAGA should generate considerable cash (as it did in FY 1/2024, reducing net debt by £74m). Therefore by the time the 2026 bonds fall due, it should have accumulated much (maybe even most) of the cash required. If there is a shortfall, then it really shouldn't be difficult to finance that with some new, smaller borrowings.
The price of the 2026 5.5% SAGA bond has been recovering nicely of late, which I think davidjhill pointed out, doesn't seem to be pricing in much default risk -
When you ring-fence the asset-backed ship loans, the rest of SAGA's debt really doesn't look insurmountable to me, it might even be a bit of a storm in a teacup. I'd be worried if profits & cashflow took another dive at SAGA, but on the current trajectory I think it's probably going to be OK.
I'll watch the webinar with mgt, it sounds from others here as if people were less than impressed. Mind you at least Euan Sutherland is no longer in charge, which has to be a plus, with his reverse midas touch track record!
Regards, Paul.
I noticed the other day that Eaun Sutherland from 1st May will become A G Barr (LON:BAG) CEO.
I know this is a company Graham likes. Should be an interesting ride.
Morning Paul..hope the move to Valletta goes smoothly
From the results at Saga (LON:SAGA) the cashflow this year was flattered by a number of significant non recurring items & clean cashflow reduced in the period. The issue I see as key is their looking to raise cash from the cruise ships but those were funded on fixed rates a while back when interest rates were far lower….to raise capital they need to repay or renegotiate these funding arrangements in a much higher interest rate environment…to become capital light they are looking to sell & leaseback so they may release capital but at the cost of higher operating lease costs….passing ownership to a third party must also offer some attractive terms for the third party…& their upside must come from somewhere. In summary I think as the bond prices are indicating they’ll find a way to repay the 2026 bonds but the cost to equity holders will be significantly higher than perhaps shareholders are expecting.
it’s been a fascinating case to observe from quayside..I was especially struck by how they managed to buy the risibly named Big Window biz & sell it in the same year & treat as exceptional the acquisition costs, trading loss & disposal costs…truly remarkable capital allocation from Euan Sutherland
Saga (LON:SAGA)
Ref missing something I was simply quoting their comments that they won’t have the cash flow to pay these items in 2026 - seems odd when they are specifically warning they can’t settle we should ignore the warning and presume they will have the cash ?
Ref the bonds imho these are not particularly relevant - for shareholders to be royally shafted the bonds do not need to default - the whole point is that the bonds will get repaid - but that might be at the expense of shareholders if they need large rights issue or have to sell ships and that means they earn less profit.
But you are assuming two things that I think are low probability rmillaree
1) There is no bond market to refinance the bonds - my take is that given their free cash flow and track record of paying coupons on time and redemption of the 24 bond that this is unlikely.
2) Roger insists on getting his money back in 26 rather than say a year later. I’d say that is also unlikely given the support he has given in the past and the coupon he takes from the debt facility. Ie it is on commercial terms +
So whilst the company has to cover its a**e by saying that expected FCF over the next two years does not cover debt maturities I think you are reading this as they don’t have options or aren’t planning for it - ie its a distressed scenario, but that isn’t what that that statement is saying. The bond market tells you that.
Saga (LON:SAGA)
1) There is no bond market to refinance the bonds - my take is that given their free cash flow and track record of paying coupons on time and redemption of the 24 bond that this is unlikely.
I would agree that refancing is possible - just that their comments saying they had no plan dont help - so to me thats a red flag - i fully concede that bond rewal of some type is possible - it wasnt my choice for them to flag up solvency issues here and their lack of plan to sort these items - that was their choice to flag up the problem !!- i am simply comenting on their factual statements -
So whilst the company has to cover its a**e by saying that expected FCF over the next two years does not cover debt maturities I think you are reading this as they don’t have options or aren’t planning for it - ie its a distressed scenario, but that isn’t what that that statement is saying.
imho its anything other than normal if one thinks bonds will be refinanced to start mentioning solvency and saying that we need to do something actively ref these issues as based on curent projections the numbers dont stack up.
The bond market tells you that.
What i saying is there is potential here for shareholders to be screwed via rights issue or some pivot in business type that reduces profits materially if they need to raise "cash" - nothing more or less than that. Its pretty damn obvious to me the bondholders will be repaid - thats my point though - if shareholders need to be screwed over via discounted rights issue to do that thats is a realistic possibilty or probability.
I would agree there is huge middle ground here for them to sort business out sort financing out my comments are simply being conservative - seems illogical to ignore the very explicit warnings here though and say everything is a ok with their specific wearnings.
grumpy5Joined 2012426 posts8:28 am
I wish I had the skill of discerning body language on a podcast! ;-)
grumpy5 may I suggest you watch the Investor Meet Podcast on Saga (LON:SAGA) from yesterday and you may see what I mean.
I watched the Saga (LON:SAGA) results presentation and while not everyone can be blessed with good communication/public speaking skills I thought both the CEO and CFO were poor at best, I got the feeling they had had a disagreement just before they aired. When I compare that with the Ashtead Technology Holdings (LON:AT.) results presentation this morning with CFO Allan Pirie and CFO Ingrid Stewart who were both excellent, with clear presentation, a real ability to share their vision of the company's future and ability to not only answer questions but to expand those answers to give investors further colour on each situation, I know why I am invested in Ashtead Technologies and not in Saga.
I think the joke here was that the phase used was "podcast" which is audio only.
Good write up on Card Factory (LON:CARD) in Shares Magazine. I think Card deserves to be called "the Greggs of Gifting" :)
A single digit PE (price-to-earnings) ratio, double-digit earnings yield - the inverse of the PE ─ and a plump free cash flow yield suggest Mr. Market underappreciates the earnings power, growth potential and cash generation of Card
Factory (CARD).
The value-focused greeting card-to-party supplies retailer’s revenue has returned to above pre-pandemic levels and the business has positive momentum under chief executive Darcy Willson Rymer’s new growth strategy. Wakefield headquartered Card Factory’s value-focused product offer continues to serve it well during a cost-of-living crisis and heap pressure on arch-rival Clintons, which is heading for a
restructuring with potentially a fifth of its stores to close.
As the consumer backdrop brightens, Shares expects the group’s expanded gift offer could feel the benefit ─ at present it only has a 1.7% share of a UK gifting market worth £13.4 billion.
While the UK greetings card market in which Card Factory has the leading value and volume share is considered low-to-no growth, the birthday cards-to-balloons purveyor is cannily developing partnerships to sell through other retailers, which
currently include Aldi and Matalan in the UK and The Reject Shop in Australia.
The acquisition of SA Greetings in South Africa and a franchise deal with Liwa in the Middle East mean there is an interesting overseas growth angle too.
Back in January, Card Factory delivered yet another upgrade to its earnings guidance following strong Christmas sales across stores and online; Liberum Capital cautions that ‘when (not if) Card Factory get its online business moving, one should maybe be concerned for the likes of Moonpig Group (MOON) and Funky Pigeon’.
Results for the year to January 2024 are slated for 30 April, with the consensus pointing to a 21.5% rise in pre-tax profits to £61.4 million following a
series of upgrades. With Card Factory’s balance sheet in a much healthier position, dividends ─ which were put on pause due to Covid ─ could even be restarted
during the year to January 2025.
Just sweeping the investor chat sites on Card Factory (LON:CARD) - there is chat of a potential bid. Personally think its a load of cobblers but 5x volume spike is worth noting. Telieos probably taking the opportunity to dump another load of shares which is fine by me. Long and strong.
Thanks for sharing your perspective on Fonix Mobile (LON:FNX) Paul. A couple of additional points worth noting. They have conducted a secondary placing previously (about 12-18 months ago iirc) at a lower price. Also, just shy of a million shares in this placing were purchased by the company and immediately cancelled. Like you, I’m relaxed about it all and placed the news in my “meh” tray although given how much pressure institutions are under to raise funds for redemptions at the moment, perhaps a seamless secondary placing at such a small discount should be seen as more positive than that.
Cheers
Simon
Edit - The previous secondary placing was 23rd June 2022 for exactly the same number of shares as today and was priced at 150p.
Alpha Financial Markets Consulting (LON:AFM) - noticed that the last 3 days - some heavy buying from ii's, bucked the market trend over this week.
DS Smith (LON:SMDS) - it seems that Mondi has walked away from the bidding table so causing a 12% drop in SMDS's share price.
But why are DS Smith (LON:SMDS) down to 351p when the offer from International Paper is equivalent to 425p? Is that a massive arbitrage opportunity or did I miss something?
DS Smith (LON:SMDS) I hold
I make the see through price 360p as things stand
($34.86 x .1285 = $4.48 / $1.2431
I think it’s a real pity there is no cash element as broadly the UK mkt needs cash to recycle into new names. Another large transaction Barrett and Redrow is also all paper
Equals , Bank of Georgia
Seems to be breaking up through 130p level
Following the good results I think the market has decided with or without a bid this should be higher probably around the 150p level in pretty short order .
Even if no bid I’d say this is now got a pretty good bull case so be interesting to see if it holds 130, falls back or surges through .
Bank of Georgia has slipped back and I’m increasing however as Georgia capital is my third biggest holding certainly puts me somewhat overweight in Georgia .
Can’t see much wrong with bank of Georgia so unless I’m missing something looks a good share for the SIPP.
Any bank of Georgia holders got any worries to the downside or is this pullback just a drag back on general market weakness ??
hi planetx
Any bank of Georgia holders got any worries to the downside or is this pullback just a drag back on general market weakness ??
I'm not a Bank of Georgia (LON:BGEO) holder but the weakness may be to do with the current protests regarding the proposed new pro-Russian legislation which, if it gets through, will spear Georgia's plans to join the EU.
This is the subject of today's lead article in The Times.
Snazzy
Snazzy
Thanks for that interesting .
I’m not convinced joining the EU would do Georgia much good myself but bit above my pay grade and I’m no economist .
Sold my Carrs today which was not a core holding (nice 25% gain in 6 months )and rotated that into bank of Georgia which I’ve been wanting to move to a bigger holding for a long time but haven’t had sipp funds .
Still only a 1/2 holding but with Georgia capital being my biggest holding probably wise to stop there .
Planetx & Snazzy
This “Foreign Agent” legislation is not pro Russian per se, though it is taken from some Russian legislation that has subsequently been abused by powers to crush dissent. The concern is that the same abuse of the power could occur and is thus anti democratic. That goes against EU principles around democracy and would threaten EU membership.
Note: The President actually has veto and she has already said she will veto it so this is really a play by the incumbent government ahead of elections imo.
Nothing particularly new and don’t see that it is likely to have any implication on Bank of Georgia (LON:BGEO) for a considerable period of time even if it did get through in some form or other.
The other geo political concern is that Russia may breakthrough in Ukraine and decide to attack Georgia too in its exuberance.
But given a PER of below 5 and based on its own funds position you could argue this is more than priced in based on its growth trajectory and regional diversification. I do and I hold.
I've just sold out of Jupiter Fund Management (LON:JUP) on the news that Alliance Trust have dropped them. I don't know what the financial damage is, but the reputational damage seems likely to reverberate through AUM for a while, which may deter anyone thinking of a takeover.
I would expect that will be just one of many redemptions Jupiter Fund Management (LON:JUP) will see related to the departure of what is regarded as their star fund manager. As this news shows, anyone thinking of redeeming won't wait until the actual departure.
Thanks for the spot! I missed that this morning https://www.thetimes.co.uk/art...
I suppose we might also see new business via Alex Savvides so let's see.
There is a Q1 update on Tuesday too.
I hold Jupiter Fund Management (LON:JUP) . If it can recover then there is multibagger potential here and I like some of the things the new management is doing (narrowing product range, reducing fees). Even if management don't fix all the problems it should rise on equity markets alone so I think the downside risk is limited at this point.
i'm sticking with it too with the assumption that it is still very much valued as value and a longer term perspective too.Perhaps will attract a bid somwhere..?Perhaps optimisitic thinking, but will revisit (barring a total disaster in a year or 2 and when rates start really getting cut in reality ..!).Maybe because i don't do well short term trading and predictions at all.
Gresham House Energy Storage Fund (LON:GRID) in case any holders missed it they put out a sneaky update yesterday afternoon announcing dividend suspension and cessation of buybacks to enable completion of the current construction programme -driven by the poor performance this year. This has been caused by the grid not buying enough power from the battery storage network.
Webinar this morning at 1100.
A very poor show giving investors so little notice!
I had email dialog with both Manager and Chair, they both think things are going well!! I sold, my biggest loss this year.
On some measures of course they are going well snowdrop. They own more capacity than anyone else (approx double) but the problem is the market isn’t working and National Grid are switching on gas power instead of using the batteries. Ridiculous really.
I would say from the 1100am webinar today they are definitely spooked and apologetic that they have had to scramble to the bilge pumps, with more info to come at the year end in 10 days time. Ben Guest was also very confident about the longer term future -during questions when not following the script the enthusiasm shines through not that that optimism is compensation for a heavily discounted share price and no dividend until 2025.
Gresham House Energy Storage Fund (LON:GRID) l would have more confidence, if Ben Guest bought some shares, l can't see he has any. If he is so confident why not invest?
BGuest has roundly slagged off NG, no 1 potential customer, in public. Enthusiam over common sense?
Haha! Good point!
Very quiet and little news here this morning so just a reminder that the Mello2024 conference is just five weeks away and that you will have the rare opportunity to meet the management teams of 40 companies and listen to some amazing keynote speakers plus network with lots of your Stockopedia fellow subscribers.
Here is the post that provides all the info...
Stockopedia | Mello2024 conference...22nd and 23rd May | By carmensfella
I just wanted to plug ‘Pigs get Slaughtered’ by AD Vaughan, I’ve just finished it and really enjoyed it, a fast paced financial thriller with romance, murder, insider trading and the protagonist a professional trader! Highly recommended and written by one of our own, and of course part of the proceeds given over to charity ! When’s the sequel?
https://www.amazon.co.uk/Pigs-...
Ox,
Thanks so much for the 'plug.' It means a lot to get positive feedback and feel that what I've written is appreciated. As I said before, it really felt like I was writing the book for this audience. The fact that you and others on Stockopedia have enjoyed it is great news. At the end of the day, it doesn't matter how good the book is if nobody reads it. Getting people motivated to read it is most certainly the challenge. Thanks again for taking the trouble to help the cause. All the best.
Looking forward to the next one.
Zotefoams (LON:ZTF)
A quick google of the Design Blue/D3O company brings up an interesting list of the brands that they manufacture for. Looks like a good win for Zotefoams to me.
Brands using D3O® technology | D3O
Interesting, thanks for highlighting this Hellvellyn! The defence section features 3M helmets which reminded me of the ex 3M body armour business that Avon Protection (LON:AVON) are closing down having bought them 3-4 years before the current management team joined and started the big turnaround.
Avon own the Team Wendy helmet brand which has a leading market position so this may not be too much of an issue for them…who knows? There is a veritable minefield of IP in this space and it takes years to get new systems tested and approved.
Design Blue certainly work with an impressive list of brands so this should be good for Zotefoams (LON:ZTF) and provide some diversification from the exclusive Nike arrangements, though they might not be too impressed seeing Adidas on the list!
Ah many names from the motorcycling world impact protection
Could I second the comment made by KevinS1 this morning on the exchange of comments yesterday by davidjhill and rmillaree onSaga (LON:SAGA) .Brilliant exchange of views and opinion. I hold.
I listened to the Podcast on Investor Meet and I found the body language of the FD really disconcerting.He gave the impression he really did not want to be there.
A long term hold for me but not happy with the performance of the new Management yesterday.
I wish I had the skill of discerning body language on a podcast! ;-)
Saga (LON:SAGA) The davidjhill/rmillarlee exchange is very helpful indeed. I tuned into the Investor Meets too, what is striking is that the CEO is Ex-Debenhams and Co-op bank!? The FD is ex-Investor relations.
What we need is a veteran, battle hardened team with a track record in turning businesses around. An FD who has dealt with a syndicate of mean spirited bankers in a previous post.
Look at Gulf Marine Services (LON:GMS) as a current example of bringing in an heavy weight management team to turn things around.
Hi portugull, I also second that.
There was a brilliant exchange between davidjhill & rmillaree on Saga (LON:SAGA)
I had always identified these two posters as being very knowledgeable, but what struck me yesterday was that they both had differing views but the debate was undertaken in a superb way without resorting to attacking each other and having the greatest respect for each others viewpoints.
This is why I pay my subscription - not for the ill-tempered, childish rants that sometimes get in the way of a grown up investment board. Thanks both of you - class acts.
It is great to see two very intelligent posters having an investment debate with different views and at the same time respecting each other.
Obviously these two members are completely in control of their emotions, and as investors we must all make being in control of our emotions our default position.
The very best investors like Peter Lynch, Warren Buffet & Charlie Munger, Jim Slater were in control of their emotions, or they would of never the been great investors that they became.
First post today !
Interesting exclusivity agreement announced by Zotefoams (LON:ZTF) this morning, although no clear information on potential market opportunity and timing as such.
Also, note that the Stockopedia quality metric has dropped 32 points since Pauls Mar23 'green' on the company. Appreciate any views on the cause of this and should anyone have any better understanding of the potential opportunity via the ex agreement with Design Blue. Many thanks..
Thx TPV ... I wondered why they popped this morning. I was just about to start delving.
Morning TPV - smashing first post, welcome to the comments at Stockopedia! :-)
thanks Paul, been finding the research and work you and Graham post really useful in some of my picks for a while now.
On a PC you can use the "print" button to open a historic stock report (say just before the drop). If you open another browser tab with the latest stock report, you can then toggle between them to see what's changed. In this case it seems the F-score took a dive as well as EPS growth and cashflow. It would be nice if Stockopedia automated this somehow, I often want to know why there was a big changes in one of the QVM metrics.
Zotefoams (LON:ZTF) The 2023 figures were published, the profits were lower than 2022, this affects the F score and various other Quality measures.
Debt has also increased.
It is annoying I can't reply to the original post, without going all the back to it, I can reply to all the replies, though, seems a bit odd.
Thanks Richard/Rusty, very helpful
As a Brit living in Sweden and a keen follower of the SCVR (thanks Paul and Graham!) thought this summary from the FT of the Swedish ecosystem and comparison with UK/EU markets was an interesting short read in terms of the discussion re. bringing small and mid-caps to market in the UK.
https://www.ft.com/content/edc...
Possibly my first post as well, I can't remember.
Interesting article. I'm also a Brit who's been living in Sweden for more than 30 years, and invest mostly in the Swedish stock market these days due to most of my income and assets being in SEK (and a morbid fear of the Swedish tax authority digging too deeply into my UK investments).
The are a lot of large world class companies based in Sweden such as Astra Zeneca (dual-listed of course), Atlas Copco, Saab and Volvo (trucks, not cars), but we've lost quite a few to takeovers recently such as Swedish Match.
Yes there's been a lot of IPO activity in the last few years, many of them medtech or cleantech firms that listed in the post-pandemic frenzy and that are now well underwater (like in the UK). Like everywhere, you can make a quick buck at IPO but you really need to sort the wheat out from the chaff.
My main concern is that, in reality, most Swedish shares are smallfry by world standards and it's important therefore to diversify by choosing companies with international operations to spread the risk. The weakness of the currency is also an issue at the moment.
ReggieThe Dog
ReggieThe Dog - Completely agree. Without the equivalent support of a board such as this to support small/mid-cap discussions I've concentrated on Swedish large caps operating internationally, Investment Companies and ETF's.
What we need is an equivalent Pål and Gustav over here to provide similar insights! Trevlig helg!
Good article and a lot of good points in the comments. Running from memory
Swedish govt does not issue gilts over 10y and ins cos need long term SEK equivalents = equities.
much friendlier investor tax regime
Culture of widespread retail ownership 40% of private money in equities. Taught in schools.
Lots listed but also a lot of dross.
Even I noticed that the charts do contain 'chart crimes' sad as I think the ft invented the term.
Many from UK blaming gordon brown for decline of UK stockmarket. My bad memory says the rot (in terms of clever tax raising wheezes) began before him in 88-92. Fairer posters said successive govts have made things gradually worse over a very long timescale.
As I understand it the pension funds pay more tax on dividends from equities than they do on those from gilts, following Gordon Brown's tax changes. I am sure there are other factors too, but now that pension funds own so little of the UK equity market reversing these tax changes would be a winner for the equity at very little cost to the government ( true ..it might make government borrowing a bit more expensive).
The above was pointed out in an article in The Times, I think by DAvid Wighton. It does seem a bit of a no brainer, and a something sensible the Tories could do before departing.
If you IPO in UK its very hard to get liquidity below certain levels of market valuation. IPO fees are not exactly small either.
But on the UK tax side over the last 20 or so years there is no consistency of tax treatment, so, what looks like a tax incentive going in is likely to be successively whittled away.
Take Entrepreneurs Relief (A CGT incentive). There were some basic qualifying criteria at the start, with no taxable ceiling but with a 10% on chargeable gains minimum. This was to encourage longer term shareholders holders. Then the taxable threshold went down to £10m, and now its £1m.
I know some owner managers who have witnessed this erosion over this timespan, and having effectively risked capital many times over, employed hundreds of people, & paid innumerable taxes (Employers NI, Corporation Tax etc) are coming to the end of their business lives, and they have effectively been undermined by such changes.
Now there is talk of levelling CGT and Income Tax rates (by a future incoming Govt) , so frankly what is the point? I am sure entrepreneurial risk takers will still be around, but if they have got any sense who could blame them for eyeing up other markets where they may be more greatly valued, and where one would hope there is some consistency of treatment, in a good way.
Hi apozniak
A really interesting read, many thanks for posting it.
Regards
Howard
I never managed to get to the SCVR yesterday due to being too busy, but caught up this morning.
There was a brilliant exchange between davidjhill & rmillaree on Saga (LON:SAGA)
I had always identified these two posters as being very knowledgeable, but what struck me yesterday was that they both had differing views but the debate was undertaken in a superb way without resorting to attacking each other and having the greatest respect for each others viewpoints.
This is why I pay my subscription - not for the ill-tempered, childish rants that sometimes get in the way of a grown up investment board. Thanks both of you - class acts.