Small Cap Value Report (Fri 19 Aug 2022) - JOUL, HSW, VLX

Good morning! It's just Paul here, with it being Friday. I have to finish by 11am today, due to being required to take Mum to Newbury for her 85th birthday lunch. My brother particularly likes this restaurant, but it's a 75 minute drive away, so the food had better be very good! Update: sorry I have to leave it there for today, but got 3 companies done anyway. Have a lovely weekend! I'll have a look at your comments this evening, so do flag up anything interesting that I could come back to next week. Today's report is now finished.
I should give a special mention to "our Graham" (80's reference!) who has diligently worked Mon-Thu this week in really difficult circumstances, with terrible internet in a holiday cottage, a crying baby, and a family wedding. Yet he's managed to cope with that, and produce sterling output here, so thanks Graham!
Weekly summary podcast - click here (Sat 20 August).
Agenda
Paul's Section:
Hostelworld (LON:HSW) - my notes are below from the webinar yesterday on IMC. There was a lot of information & commentary via a slide deck, but I only jotted down a few points that seemed most important. I'd be more interested in this share, if it were not for the expensive, risky debt. There's a capital markets day in November, so maybe that will be a precursor to a placing, to clear the debt problem? Management come across as knowing what they're doing, so I'm less bearish about this share, although still dislike the balance sheet structure.
Joules (LON:JOUL) (I hold) - another profit warning, as trading has continued to deteriorate over the last few weeks. I estimate this could lead to an H1 loss of about £7m. Bank remains supportive, and discussions with Next continue about a strategic investment. I think my patience with Joules has run out, and am considering whether or not to sell up. There's likely to be a nasty fall at the open today I'm afraid, so the damage is already done unfortunately.
Volex (LON:VLX) - the share price has been strong in recent months, bouncing almost 50% from the lows. Today's reassuring, even upbeat update seems to underpin that share price (partial) recovery, so I reckon it's looking safer now we know it wasn't just a bear market rally. Forward PER is modest, at 13.3. I think the risk of a profit warning seems quite low, due to favourable tailwinds in all Volex's main product sectors (e.g. EVs). It's got pricing power. More acquisitions are in the pipeline, and maybe it might be able to snap up some bargains in more difficult macro conditions? Thumbs up from me.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section (no Graham today, as it’s Friday):
Hostelworld (LON:HSW)
My notes from InvestorMeetCompany webinar yesterday
I reviewed this online booking portal for hostels here on 10 August, when it reported rather poor interim results. My impression was negative, mainly due to the expensive debt structure (with a US based investment company, and payroll taxes deferred to the Irish Govt). Also, the market cap seems to already factor in recovery in travel, so what's the attraction of paying up-front for a recovery that's only partially happened? Particularly when many other travel sector shares are looking much cheaper right now.
On 10 August, a member here jvb68438 posted an interesting more bullish view of HSW in the reader comments here (note that you can get a link to any specific reader comment by clicking on the icon that looks like a pair of spectacles, which also then allows you to post that comment on Twitter, etc) .
So I decided to watch yesterday afternoon's webinar from HSW, to get a more bullish view of the company, to weigh up against my more bearish view. We try to keep an open mind here at the SCVR. I didn't take detailed notes, but jotted down what seemed to me the key points from this H1 results webinar -
There were 3 presenters, the CEO (ex-Expedia) who is softly spoken, but seems to know his stuff, and seems strikingly positive about the outlook for this business (but I suppose that's part of his job!). Also the CFO Caroline Sherry sounded on top of the numbers. The third person on the webinar (operations guy, I think) didn't talk until near the end, but I missed his name. Hostelworld is based in Dublin.
Some revenue is deferred, only being recognised once the cancellation period has passed. Since the business was effectively re-started from almost nothing in lockdowns, H1 this year required this balance sheet provision to be re-built. That's a one-off, and it suppresses the reported figures, but won't happen again (we hope).
Very highly geared to travel sector recovery.
Expect to be EBITDA positive in H2.
Expect to be very highly cash generative in future (as to be fair, it was pre-pandemic, and paid big divis, but lacked growth, so was more of a value share pre-pandemic)
Young customers, who typically don't have mortgages or children, full employment, so not as impacted by cost of living crisis as other age groups.
Operating costs (excl. marketing) are lower than pre-pandemic, due to cost-cutting in pandemic - leaner business now.
Forex hit in H1 due to strong dollar.
Social platforms - this bit was really interesting. CEO explained how its app has been developed to encourage travellers staying in hostels via HSW to socialise - a key aspect of hostels, where 60% of travellers are solo, and want to mingle with their own younger age group. So features on the app allow chat, and organising group activities, conversation starters by being linked to people staying in the same hostel, leaving feedback, etc. Other companies can also advertise via this social platform, targeting people for drinks/meal promotions, live gigs, etc. It looks well thought-out, and I'd be interested to find out what the competition is doing in this social area. Could be good for repeat business, as it's clearly an added value service. Although I wonder how many people in a hostel would have necessarily booked through HSW, it may not be that many?
Capital Markets Day planned for November - I wonder if this means a fundraising is on the cards, to clear down the substantial debt owed to the US lender, which is 9%+ base rate cost, and the Irish Govt payroll tax arrears (CFO says they are currently negotiating a payment plan to repay in instalments, and there's no interest cost at present). So to plan for some dilution, I think would be sensible.
Cohorts graph (of customers) was interesting, showing long lifetime value, and repeat business of each cohort. Obviously dwindles a lot over the years, but is still quite a significant base.
Customer payback period on marketing costs is 30-90 days.
Current trading shows that customer behaviour is mathematically very predictable, with gradual return to near pre-pandemic levels, for the various cohorts (year groups) of previous customers, very much as expected. This enables very predictable budgeting.
Marketing costs - 60% of revenues this year (i.e. incredibly high!), reducing to 50-55% (still very high!) in 2023.
My opinion - my reservations about high valuation, and weak balance sheet with expensive debt remain. However, I think the business seems fundamentally pretty good, and it sounds like considerable improvements have been made during the pandemic. Can it get back to being a profitable, cash generative business? Yes, I think so, and we were given a lot of evidence to back up the idea that previous customers are returning as expected. Although the big challenge for online businesses right now, is getting value for money from online marketing, which is now very expensive. Spending 60% of revenues on marketing, suggests to me that this is a key, and problematic, issue. In the past HSW struggled to generate revenue or profit growth, it was starting to struggle pre-pandemic remember. So I'd need a lot of convincing that it's a growth company.
Joules (LON:JOUL) (I hold)
44p (before market open) - update: 30p (down 32% at 09:02)
Market cap £49m - update: £33m at 09:02
Trading & Business Update (another profit warning)
Joules, the premium British lifestyle group, provides a trading and business update in respect of the period since the end of its financial year to 31 May 2022.
Profit warning -
As a result of the recent softness in trading and the current weak consumer sentiment set out above, the Board expects a significant loss in the first half, followed by an improved performance in the second half as the benefits of business simplification begin to be realised. In light of this, the Board currently expects the Group to deliver a full year loss before tax, and before adjusting items, significantly below current market expectations.
Key points -
Trading has “softened materially” in the last 5 weeks.
Hot weather has impacted core categories (e.g. coats, knitwear, wellies).
Cost of living crisis.
Retail sales down 8% in financial YTD (June, July, August to date)
Wholesaling for Joules brand doing well - up 10% vs LY
Garden Trading “significantly impacted” (no figures provided) by slowdown in home & garden market.
Retail margins (presumably they mean gross margin?) down c.6% points down on LY - due to discounting required to shift stock.
Expecting a “partial recovery” in margin, as full price Autumn/Winter ranges come in.
“Good progress” to simplify business & improve profitability.
Liquidity/covenants - is under pressure -
Net debt £21.1m (end July)
Headroom £11.4m (end July) + £5m additional headroom (until Nov 2022) since agreed with bank.
Managing cash carefully, expects sufficient liquidity, including repayment of £5m extra by Nov 2022 - so no immediate crisis by the sound of it.
Covenant waiver needed - in “positive discussions” with the bank on this, and medium term funding needs.
There are options here though, with bank debt. Remember that JOUL owns its Head Office freehold, in the books at £18m cost (but maybe not worth that much now?), and it also owns a wholesale receivables book (which could be used for a non-recourse lending facility from the bank) of typically £9-12m. Hence the bank does have security over most of the debt. That’s probably why they’re not panicking (yet).
Discussions with Next (LON:NXT) over strategic investment continue - announced previously on 7 August. “...no certainty that these discussions will lead to any agreement”.
Diary date - for FY 5/2022 will be in late Oct 2022. That’s very late. Last year's results were out in early August 2021. I imagine going concern disclosures are likely to be an issue.
Forecasts - nothing has come through on my email yet, so I’ve worked out my own figures, as follows.
H1 LY was £127.9m revenues, and a £2.6m PBT.
Of that, £99.8m revenues for the retail division, at 54.6% gross margin = £54.5m gross margin.
Reducing revenues by 8%, and margin by 6% (as guided today), lowers gross margin to £44.6m - that’s a £9.9m shortfall.
If we ignore costs & the wholesale division, assuming it will all net off (which is probably being too optimistic), then H1 PBT his year would become a loss of at least £(7.3)m.
The actual loss in H1 could be worse, as there will be considerable increases in costs compared with H1 LY, due to wage rises, and the resumption of business rates. Set against that, the company has been cost-cutting more recently, so that could mitigate things.
There’s also much higher energy costs to contend with.
UPDATE at 09:20 - many thanks to Liberum for an update note that has just come through via Research Tree. It has reduced forecast for FY 5/2023 from £3.4m PBT, to a loss of £(7.0)m, so a drop of £10.4m. That's almost identical to my estimate of a shortfall in profit of £9.9m in H1. This implies that Liberum probably haven't made any changes to the H2 element of its forecast.
Liberum does point out a potential positive, that Joules's supply chain fell apart in Autumn/Winter last year, resulting in very poor customer service (remember all the negative reviews on TrustPilot that we discussed here last year - on reflection that was the canary in the mine, as some of you said at the time, to be fair), and gaps in the product ranges as stock was stuck on the high seas. This year should be better in this respect, as supply chains have eased.
End of update.
My opinion - my patience has run out here, and I’ve decided to probably sell up, but am still thinking about it.
On the plus side, the bank is being supportive, and I very much doubt it is likely to pull the plug, but it is likely to insist on an equity fundraise. If that comes from Next, great - a strategic investment of the mooted £15m for 25% (as reported by Sky News, what would be do without them!), and the expertise of Next to sort out Joules’s lousy supply chain & logistics management, plus an implied financial guarantee from the sector behemoth, would straighten out the problems and remove risk, I imagine. So expect significant dilution either way, hopefully not ruinous, but we don't know, that depends on lots of things.
Joules is a lovely brand, but it clearly can’t sell the product at full price, which tells me it does not have pricing power - a key deficiency in an inflationary world. Customers now know they can just wait for the discounts to roll in, as products they like probably won’t sell out at full price. That’s a tough thing to eradicate once it’s established, and it devalues the brand. It’s better to start off with somewhat lower prices, and not hold constant sales discounts, and secure better prices from suppliers, which might mean Joules needs to drop some of the nice product detailing (which costs more in production). Whether Tom Joules, still a 22% shareholder, will allow that, is another matter. Maybe it’s time for him to go?
There’s turnaround potential here, so it’s not a complete basket case, but unfortunately I got it wrong by not realising how badly trading was deteriorating.
Expect another plunge in share price today, I’m afraid, which is likely to wipe out a good chunk of the recent recovery.
Bulls need to hope that the Next deal gets signed soon, and that the new CEO can take bold and prompt action to sort out the issues within the business.
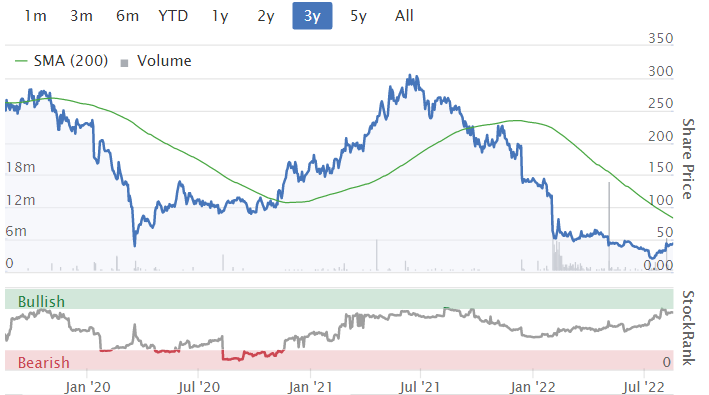
This 3-year chart is before today's likely 30-50% fall in share price (my guess at 07:57) -
.
Volex (LON:VLX) (I hold)
304p (down 3% at 09:48)
Market cap £482m
AGM Statement (trading update)
Barely a day goes by without a profit warning right now. Often it’s companies where you think, well that was all pretty obvious, why didn’t they manage down broker forecasts earlier? Instead of acting surprised that costs have gone up, and customers are drawing in their horns?!
The trouble is, we’re also getting bombshell announcements from plenty of good companies that we thought were high quality, reflected in high PERs, who suddenly surprise us with profit warnings where the CFO seems to have also not budgeted for increased costs, e.g. Treatt (LON:TET) springs to mind.
It seems almost a lottery right now, apart from the people who always seem to be wise after the event!
With Volex, I couldn’t see many risks, although as mentioned before, I did wonder whether it might have be buoyed up by customers building inventories to prevent supply chain problems? We saw how with both Luceco (LON:LUCE) and Supreme (LON:SUP) a sudden & unexpected de-stocking by customers, whacked their profits (and share prices). Could the same happen to Volex?
Turkey (the country) risk (80% inflation rate now, apparently) was dismissed by VLX management on a previous webinar, saying that currency devaluation was going at a similar pace as local cost escalation (which is what happens when hyper-inflation gets embedded, in a self-fuelling cycle), thus offsetting local inflation, and keeping Volex’s Turkish factory competitive.
I see Turkey is advertising on UK TV, for holidaymakers, and it does look tempting, I’ve never been but apparently Turkey is meant to be a beautiful country. So that’s going on the list of places I’d like to visit once my portfolio recovers.
The price of copper has been a red herring, as explained by management several times, they have contractual terms which allow re-pricing (with a time lag) to pass on higher input costs.
Anyway, moving on, we get a Q1 update from Volex today -
Volex plc (AIM: VLX), the global manufacturer supplying power products and integrated manufacturing services, today issues a trading update for the three months ended 30 June 2022 ahead of the Company's Annual General Meeting, being held today at 4:00pm BST.
This sounds reassuring -
Strong start to FY2023 and continued progress across the business
Q1 performance is strong, in line with mgt exps, and the new 5-year growth plan.
Revenue - organic growth of +4.9%
Positive customer demand.
Managing “challenging” supply chain.
Higher inventories (as mentioned in June’s update) continuing to ensure timely deliveries to customers - I think this is fine, and a good thing to do when supply chains are under pressure, making Volex a reliable supplier, and maybe able to gain market share in future as a result?
Acquisitions - are being integrated well, and there’s a strong pipeline of further deals.
Product categories - Electric Vehicles continues growing. Consumer electricals also growing, and increased market share. Medical - robust demand, and revenues up despite availability problems for components. Industrial - core demand remains strong. Growth in future from replacement cycle of high speed next generation cables (data centres, etc). All sounds good, with no sting in the tail from anything.
Outlook - sounds good to me -
Overall, whilst still early in the year, the encouraging trends in the first quarter mean the Board expects to deliver full year underlying operating profit in line with current market expectations1.
1 Latest company compiled view of market expectations shows an underlying operating profit consensus of $62.8 million with a range of $62.3 million to $64.0 million.
It’s so helpful when companies provide a footnote, thank you, and why can’t everyone do this? It’s because apparently some brokers don’t let their clients do it! Telling them (which is obviously untrue) that they’re not allowed to say what market expectations are. Suggestion - change brokers, if they stand in the way of clear communications with investors.
No such issues here, with Singers being one of the best brokers for getting information across to us.
My opinion - I’m long-term bullish on Volex, because Nat Rothschild seems to have done a cracking job of restructuring & transforming this group both organically, and through acquisitions. It’s got a good spread of businesses in different niches.
So far, so good, today’s update sounds very good to me, given the macro picture. As noted before, Volex has some positive industry tailwinds in its EV, medical, and data centre markets. So I’m hopeful the underlying growth there could offset tougher macro conditions. Plus of course, rising selling prices generates revenue growth even if volumes remain static or fall slightly.
We have forecasts confirmed today, which means this valuation data should be something we can rely on - in particular a forward PER of 13.3 looks attractive to me, for what seems a resilient, and growing business.
Thumbs up from me.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

33 comments
Hi Paul
I know you are very busy but I ll appreciate your thoughts on my concerns (two days ago) on Boohoo’s Chairman tactics and the money invested for no reason on Revolution Beauty.
Hi yiannos1
On Boohoo (LON:BOO) (I hold smallest holding). Is the rumour about Kamani buying to the IPO of Revolution Beauty (LON:REVB) anymore than Daily Mail tittle tattle. I can find nothing online to confirm and there is no notifiable holding.
Regards
Michael
I don’t know thus the reason I am asking Paul ( maybe he knows something since he is a Boohoo supporter ).
But, the money Boohoo invested in Revolution Beauty last week makes me wonder. Makes no sense to me to invest in a company with so many issues ( accounting issues , future placing issues etc ). Is it meaningful you? Wouldn’t you wait to get it from the administrators?
Is this not it: https://www.stockopedia.com/sh...
Oh dear, uber hoop day for Cineworld (LON:CINE) today isnt it!
Paul
Thank you for the review of Volex (LON:VLX) (I hold). Confirmation bias in play (perhaps) but agree with all you say.
As for:
It’s so helpful when companies provide a footnote, thank you, and why can’t everyone do this”
I think this should be obligatory under listing rules. And if they can’t and if they don’t know then they should be obliged to say “they have no idea”.
Regards
Michael
Hi Paul,
Thank you for taking the time to listen to the Hostelworld (LON:HSW) ICM presentation and your follow up comments which are all very fair and reasonable. Its now time for the show me stock to show you !
Made Tech (LON:MTEC)
For GARP lovers this must be the most important (and positive) update of the day. Made Tech has exceeded slightly reduced revenue and its more significantly curtailed profit expectations this morning. This could signal a turnaround in investor appetite for the name, which is a competitor to Kainos (LON:KNOS) in the provision of digital transformation (DX) services to government. This is a very hot area of the DX market with a long runway for growth. Competitor Netcompany, based in Denmark, recently announced 30% growth in their UK government division.
For an idea of what Made Tech delivers for government and public services, I recently had to update my photo card driving license. Not surprisingly, I chose to do so online and was able to point the DVLA to my passport records from which they picked up my latest photo ID and delivered a new license to me within 24 hours. Impressive.
The Sharewatch small companies publication gives an excellent background to the company, as does the research by Singer published on ResearchTree. I won’t go into detail here because I imagine most of you have access to one of those two resources. For my own part l spent many years delivering DX services in the public sector when active as an entrepreneur. It was very rewarding.
I am somewhat bemused at the price the market places on this name and at the swift reversal of today’s early 20% spike. The former might be explained by the disappointing trading update from February and a persisting concern that today’s swallow does not make a summer. On the other hand, the issues that resulted in the share price collapse of February, namely problems in achieving hiring targets and therefore meeting contract objectives and margin pressures owing to wage hikes, both appear to be somewhat resolved in today’s update, while the swelling order book bodes well for the achievement of the next six months’ targets. The mid morning pullback might just be would-be sellers finally enjoying an up day on which to sell holdings without depressing the price.
Made Tech is valued on half the rating of competitor Netcompany and less than a quarter of the multiple enjoyed by Kainos based on FY24 expectations. The name has more aggressive targets, being a relatively new, faster-growing player in the market and a recent (busted) IPO, but the risk is significantly mitigated by the fact that it is already cheaper than both today based on current year forecasts.
I’m not going to make bold predictions for the future trajectory of Made Tech’s share price, although it looks strong value to me today - Singer calls it "a deep value growth stock" in today's research update. But my not insignificant holding, to which I have added again this morning, reflects decades of experiencing an ever increasing demand for IT resources married to an ever diminishing competitiveness on the part of government in delivering its own IT projects without trusted partners. On which point, Made Tech’s satisfaction levels are very strong, as Singer confirms in this morning’s note.
I encourage GARP investors to research in depth.
Thanks BnB.
Made Tech (LON:MTEC) is a new one for me and looks interesting except: what are the £2.4m share based payments and why have they been excluded from the £2.6m EBITDA number? At first glance, with not much research, this seems at first blush to be a huge red flag. What am I missing?
cheers
Francis
Made Tech (LON:MTEC) is a new one for me and looks interesting except: what are the £2.4m share based payments and why have they been excluded from the £2.6m EBITDA number?
I think you'll have to wait for the audited results and annual report for that one. But it is hardly unusual for IT growth companies to exclude SBC from EBITDA, much as GAAP would have it as a real cost.
GAAP has it right, IMHO.
The share-based payments were £0.71m in H1 (which equated to a total of 6,847,812 new share options), which compares with £2.4m of payments for the full year. They did not reveal how many share options had been issued at the full year, but as the share price has collapsed ( back on Nov 30, 2021 used for H1 accounting the share price was £1.10 compared to £0.35 on May 31, 2022), surely the option pricing would be adjusted downward accordingly. Back of the envelope estimates would suggest that could equate to between 40 and 50 million new share options in the H2 period compared to a total share count of 148m (according to Stockopedia data). Surely I’m missing something or have made a mistake, for such generosity makes no sense! Can someone put me right please?
Fascinating to see that Joules (LON:JOUL) has had a rising Stockrank since January and it now stands near an all time high. How does this happen? It provides a cautionary tale if one puts too much reliance on the Stockrank.
Unless of course it is actually pointing to a hugely positive factor that does not seem visible anywhere else!
Hi Aislabie,
It looks to me as if the StockRank for Joules (LON:JOUL) is being heavily boosted by overly optimistic broker consensus forecasts, which is giving it (on paper) medium-high quality & value scores. Clearly as the new forecasts flow through into the data after today's profit warning, the StockRank is going to plummet, rightly so.
StockRanks are very, very useful as a sense-check I find. However, particularly with smaller caps with limited (if any) broker forecasts available, we have to manually double-check whether broker forecasts look reasonable or not. In normal macro conditions, that wouldn't be an issue, but right now, many broker forecasts are going to be wildly wrong. Hence much more care is needed than usual.
It provides a cautionary tale if one puts too much reliance on the Stockrank.
Yes I agree. For me, StockRanks are one of the tools (and a very important one) in my toolbox. But there's no substitute for manually verifying the reasonableness of everything. The smaller the company, the more important that is too. If I know something is going wrong at a company (e.g. a profit warning), then I would ignore the StockRank. That said, they usually pick up on changes in the fundamentals quite quickly, and start moving down.
With a StockRank of 70 at the moment, I imagine JOUL will see the Value, and Momentum scores plunge from tomorrow onwards, to reflect the marked deterioration in fundamentals.
Regards, Paul.
For me, StockRanks are one of the tools (and a very important one) in my toolbox. But there's no substitute for manually verifying the reasonableness of everything.
Always worth remembering that Stockranks are statistical. Around 2 in 3 of stocks with an SR over 90 go on to outperform, but there are no guarantees. Buy a portfolio blind and the history suggests you'll do very well. Buy an individual stock without doing your research and you're still going to do better than a coin toss, but you can't blame the ranks if you buy a dog, especially if you only buy a small number of stocks.
Of course, many high ranking stocks that look like dogs do go on to outperform, but that's the point really.
Factor analysis is all based on what has worked historically and there can't be a guarantee that it will continue to do so in all situations and for all time. So far it's done pretty well if you allow for the lag between new data being published and the ranks being updated - but that's an area that could be improved on, if only to add a warning to Stock Reports to say that there is new data to be processed and the ranks may be out of date.
As a starting point, however, they're damn useful.
timarr
Kahneman suggests using computer algorithms but to always check for "broken legs". In Joules case the broken leg is a profit warning. Paul, I don't think the value rank will change significantly until the next results but the recently strengthening momentum will fade.
History for Q,V,M and SR below. I don't understand why Stockopedia can't provide this information.
Edited so all chartlets have the same scale.
Great charts and breakdown of ranks, Dwit199. These are exactly the type charts that Stockopedia should provide. With the data available, surely it wouldn’t be difficult to implement.
With the data available, surely it wouldn’t be difficult to implement.
It must be harder than it looks as this feature has been requested many times.
Another broken leg with Joules is the Risk Rating. This is "Highly Speculative". The volatility(1yr) is 107%, which is extremely high. In my opinion anything with a volatility(1yr) greater than 60-70% needs very careful consideration as it is reflecting huge uncertainty about valuation. Shares in the highly speculative category tend to perform poorly.
Fascinating to see that Joules (LON:JOUL) has had a rising Stockrank since January and it now stands near an all time high
I can't seem to locate the stock rank trends over time. Where do I access this trend information?
Stockopedia ranking is shown in the chart, under the share price chart, on the Stockreport.
Volex (LON:VLX) a reassuring AGM statement. Steady as she goes.. You have to hand it to Nat Rothschild, no doubt ably assisted by his management team. He has taken Volex (LON:VLX), a venerable and forgotten UK manufacturer of commoditised electricals back into the limelight. A fabulous turnaround
Difficult times ahead for the global economy, but over time an investment in Volex (LON:VLX) should prove rewarding. I remain a happy holder of the shares.
Morning Paul. Happy birthday to your mum on her 85th. I too have a birthday (61 years old) today, so I will raise a glass to for her at lunchtime.
Enjoy the time together and keep up the excellent commentary- small caps are due a resurgence soon.
Mark
Wynnstay
Just a follow up to yesterdays posts and my harping on about discounted fund raise not open to PI .
Quite impressed that Finance Director Paul Roberts replied himself notably at 6.05pm that was a good sign indeed , I always liked getting (only just) out of hours replies from business owners / directors as shies they have a bit of “founder mentality”
I did reply further suggesting that the discount was unnecessarily high and asked if in future they could bear my points in mind and try to include existing PI .
Anyway the end result (which I had come to before this reply was that my head ruled my heart and my initial plan to increase to a full holding on weakness stays in place , I bought a good chunk yesterday around 595 region .
- two weeks ago I I was happy to buy and was looking to increase
- since then despite the 1% “dilution” the price has dropped 4% AND the investment case seems to have improved as Wynnstay look to be really looking to make sone positive improvements especially with the Humphrey feeds acquisition .
So in football parlance
1-0. Solid asset backed company with good management and very long track record
2-0. Sector. Strong and Wynnstay seem adaptable as their supply chain very broad
3-0 Recent addition of Humphrey feeds looks to be a key acquisition which gives a growth element
4-0. oK dividend history
4-1. Dilution own goal
5-1 Good management response engaging with a PI
6-1 Now got 10 million extra firepower to deploy
That’s s 5 goal advantage so it qualifies for the “5 clear goal screen “ and is on the buy list .
“Thank you for your email, and I am genuinely very sorry to hear about your dissatisfaction and recognise your frustration.
The decision as to how to raise new funds for the Company is always considered carefully and taken in consultation with our advisers, and with the best interests of all our shareholders in mind. Unfortunately for smaller quoted companies like us, raising moderate sums of this quantum, we have to be conscious of the cost-effectiveness and timescales of the process.
In this case, we used existing authorities granted by shareholders in March to proceed with the equity raise, and believe that the proceeds, once deployed should greatly enhance the business’s ongoing growth prospects, and benefit returns to all our shareholders.
I can assure you that the Board values the support of all shareholders, whether or not they are institutional fund managers or private investors, and that we continue to work hard to deliver the best results we can for our members.
I do hope you can continue to support us, and despite your frustrations, I would look forward to meeting you at our AGM.”
Thank you
Will let you know if my old fashioned letter gets a reply, suspect it will!
Tommy
Best wishes to your mum on her 85th Paul, and Graham thanks for your hard work in challenging circumstances this week. I certainly know what that is like. I have noted the profit warning on Joules (LON:JOUL) which is not unexpected to be honest given the current market and macro backdrop. Glad I bailed out of this with a loss 4 weeks ago, following your previous comments Paul. A more significant loss has been avoided but commiserations to those who remain in this stock. I am sure the SP will Improve but not in the short term. ATB, Bris.
Joules (LON:JOUL) Wellies? Blaming summer for not being winter. Who writes this stuff and who checks it?
I can see from now Joules Christmas update saying that due to the current winter conditions trading has been worse than expected and the loss has accelerated. Never touched , never will , never understood where was the value here.
Weirdly £Joules (LON:JOUL) is up in early trading. Market expecting Next to have even more leverage in the talks perhaps?
And now down 33% - oh well
Joules (LON:JOUL) opened at 27p, bounced to 30.7 (down 13.3) then fell back. That's not up.
It was up on my Stocko folio at 8.25a.m. - obviously the delay is longer than I thought.
Volex (LON:VLX) AGM statement
"Outlook
Management continues to focus on diversification, vertical integration and realising cross-selling opportunities across the business in order to deliver sustainable revenue growth.
Overall, whilst still early in the year, the encouraging trends in the first quarter mean the Board expects to deliver full year underlying operating profit in line with current market expectations1.
1 Latest company compiled view of market expectations shows an underlying operating profit consensus of $62.8 million with a range of $62.3 million to $64.0 million."