Small Cap Value Report (Fri 19 Jan 2024) - BAKK, KIE, CURY, FOUR, BIG

Good morning from Paul!
I've done 3 backlog sections for you to get off to a flying start today.
Today's report is now finished. Have a lovely weekend! Podcast tomorrow morning.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
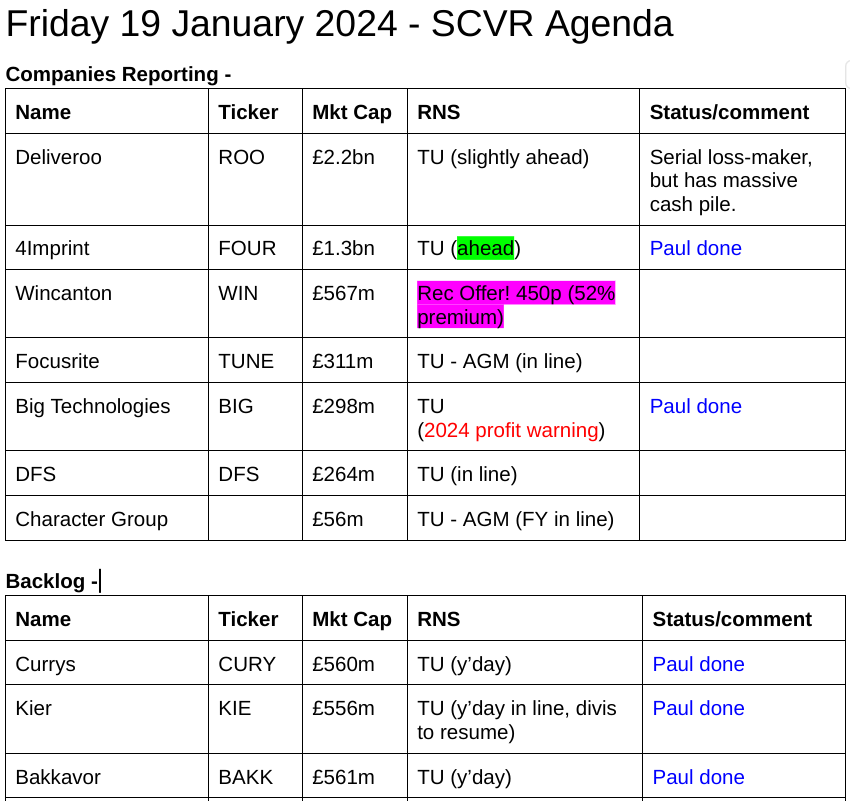
Summaries
Bakkavor (LON:BAKK) - up 6% to 97p (£561m) - Trading Update [upper end range] - Paul - AMBER/RED
Slightly ahead update for FY 12/2023. Outlook sounds OK. I also run through the negatives below, mainly a weak, heavily indebted balance sheet. Divis look too generous given that it should be focusing more on debt reduction. I can't get excited about this low margin, indebted business.
Kier (LON:KIE) - up 11% y’day to 125p (£556m) - Trading Update [in line] - Paul - AMBER/GREEN
An in line update from this big contracting business. Low margins, and balance sheet isn't the best. However, performance is OK, and divis are about to resume. Still quite good value, but given shares have doubled in the last year, I'm moderating my view from green, to amber/green.
Currys (LON:CURY) - up 9% to 49.4p y’day (£560m) - Trading Update [ahead] - Paul - AMBER/RED
I was expecting bad news, given recent PW from Marks Electrical (LON:MRK, but CURY has performed OK, and raises guidance a little. Greek disposal pending should eliminate bank debt, but remember it relies on huge trade credit from suppliers. I can see potential upside if consumer spending recovers, but for me the weak balance sheet and very cash hungry pension deficit put me off.
4imprint (LON:FOUR) - 4635p (pre-market) £1.31bn - Trading Update [slightly ahead] - Paul - GREEN
Positive update today, with 2 brokers raising FY 12/2023 forecast earnings by 7-8%. Valuation still looks reasonable for a company with a superb long-term track record that 50-bagged over 15 years. Looks good to me!
Big Technologies (LON:BIG) - down 21% to 101.5p (£294m) - Trading Update - Paul - BLACK (profit warning flag), AMBER/GREEN on fundamentals.
2023 trading is fine, in line. However it reveals imminent loss of a large contract in Colombia will hit 2024 numbers, along with increased costs to ramp up sales efforts in the US. Zeus reduces 2024 forecast by about a quarter. Shares plunged first thing, but have bounced somewhat now. I think it actually looks quite interesting now, with the valuation now only a fraction of the inflated 2021 IPO price. The large cash pile is curiously not mentioned today.
Bakkavor (LON:BAKK)
Up 6% to 97p (£561m) - Trading Update [upper end range] - Paul - AMBER/RED
I did a quick review of this ready meals manufacturer a few days ago here on 15/1/2024, coming away unimpressed with the heavy debt burden (high finance costs), low margins, but intrigued by a 20% stake changing hands (potential bid target maybe?)
It provided a year end update yesterday -
Bakkavor Group plc ("Bakkavor" or the "Group"), the leading international provider of fresh prepared food ("FPF"), today updates on trading for the 52 weeks to 30 December 2023 ("FY23"), ahead of the publication of its full year results on 5 March 2024.
This sounds positive -
2023 profits, net debt and leverage ahead of market expectations with encouraging outlook for 2024…
The Group anticipates FY23 Group adjusted operating profit to be at least in line with the upper end of the range of market expectations2
Is that in line, or ahead? It’s a bit of both really!
The range is very tight -
2. Based on company compiled consensus ("Consensus") which includes; Citi, Goodbody, HSBC, Investec, Kepler, Numis and Peel Hunt. Adjusted operating profit Consensus for 2023 of £90.2m, with a range of £89.7m to £91.1m.
Operating profit is not a good measure for a highly indebted company like this, as finance charges consume a good chunk of operating profit.
Net debt has come down more than expected, to a still substantial £230m.
BAKK overpays divis, and should cut them back in my view, and instead focus on deleveraging. So I don’t see the high dividend yield as being necessarily safe in a downturn.
The forecast yield is 7.6%
Outlook - a bit mixed, but overall sounds positive I think -

The smaller US and China businesses have been poor performers, but seem to have scope to improve, which should help the overall group results.
Paul’s opinion - margins are low, and it’s just not a very interesting business, supplying supermarkets, so under constant pricing pressure. As I mentioned a few days ago, after hefty finance charges, the PBT margin is only about 3%. Growth seems limited.
Not madly exciting then, but shares have had a bit of a rebound recently - although we’re seeing lots of situations where dormant sellers use price rebounds and increased liquidity to resume their selling.
What’s the upside case? Pre-pandemic, EPS was over double the current levels, and there’s been no dilution since then. So if BAKK can regain previously higher margins, then the shares could recover perhaps? Although note that higher interest rates now mean the debt costs a good bit more, so earnings could be permanently lower for that reason perhaps?
It’s not been a successful 6 years since floating, although divis have softened the losses somewhat, with c.26p paid out in total since floating.
I’m struggling to find a compelling reason to get involved here, when there are so many other more interesting (and good value) companies to look at.
Kier (LON:KIE)
Up 11% y’day to 125p (£556m) - Trading Update [in line] - Paul - AMBER/GREEN
Kier Group plc ("Kier" or the "Group"), a leading infrastructure services, construction and property group issues a trading update for the six months ended 31 December 2023 ("the period" or "first half"). The Group will publish its results for the six months ended 31 December 2023 ("half year results") on 7 March 2024.
Trading - this sounds reassuring -
Consistent with the update in November 2023, the first half of the current financial year continued to trade above the prior period and was in line with the Board's expectations. This was driven by strong volume growth, particularly in Construction. Similar to last year, the Group's performance is expected to be second-half weighted.
Order book is huge, and gives good visibility -
The order book as at 31 December 2023 was c.£10.7bn, a c.6% increase on the year-end position (30 June 2023: £10.1bn) and the prior year comparative (31 December 2022: £10.1bn). The Group has secured revenue of 92% for FY24, providing a high degree of visibility. Long-term framework positions are excluded from the order book and represent an additional opportunity. Bidding discipline and risk management embedded across the business continue to drive the high quality and profitable order book.
Cash/debt - I like the reporting of average month end, but average daily would be better -
Kier's focus on operational delivery and cash management alongside the cash generation from the strong volume growth has successfully resulted in the Group continuing to deleverage materially with average month-end net debt of c.£(140)m (HY23: £(243)m) showing a significant improvement of c.£100m.
Kier is expected to report a modest net cash position at 31 December 2023 (HY23: £(131)m).
Balance sheet - I’ve checked the June 2023 one. It’s large and complicated, but NTAV is negative at £(132)m - not good, but not terrible either, given that public sector projects tend to be good payers, helping working capital.
Dividends - balance sheet weakness limits the divis it can pay, and nothing has been paid to shareholders since 2019. Although the good news is that it expected to recommence divis, starting with the H1 results (to Dec 2023) which should be out in March 2024.
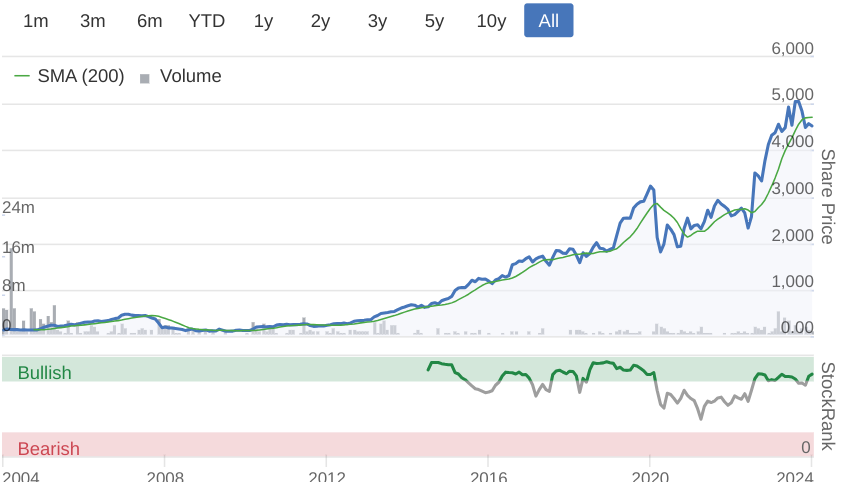
Paul’s opinion - I only looked at KIE once in 2023, giving it a GREEN view on 16/11/2023, mainly due to cheapness, trading well, good outlook & order book, and a 5% forecast yield.
That remains the case now, with a forward PER of 5.9x, and forecast 4.5% yield.
The main downside here is the risks associated with all these large contracts, and a wafer thin profit margin - leaving very little profit to absorb any contract losses (that sooner or later always surface in this sector).
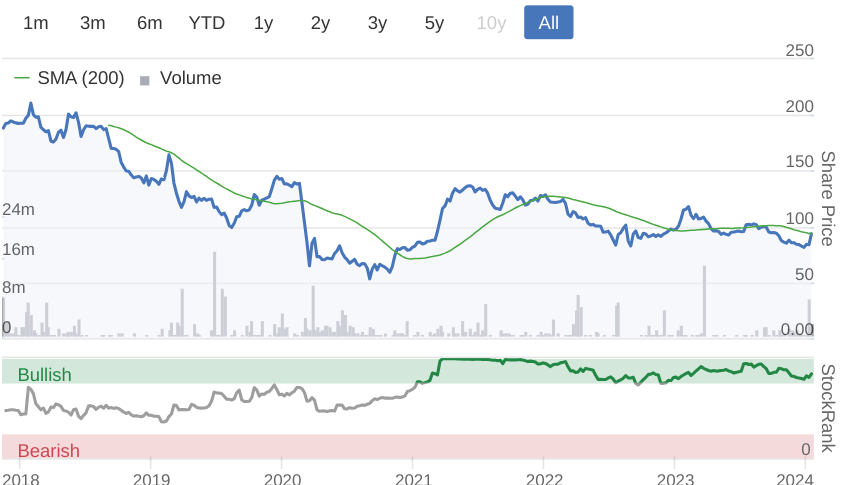
That said, KIE shares are clearly in a nice uptrend, having doubled in the last year, and it seems to be trading well, and still looks quite cheap. At some point people will probably want to bank profits though, that’s very much the feel of UK small caps at the moment.
It’s had a good run, so think I’ll shift down a bit to AMBER/GREEN.
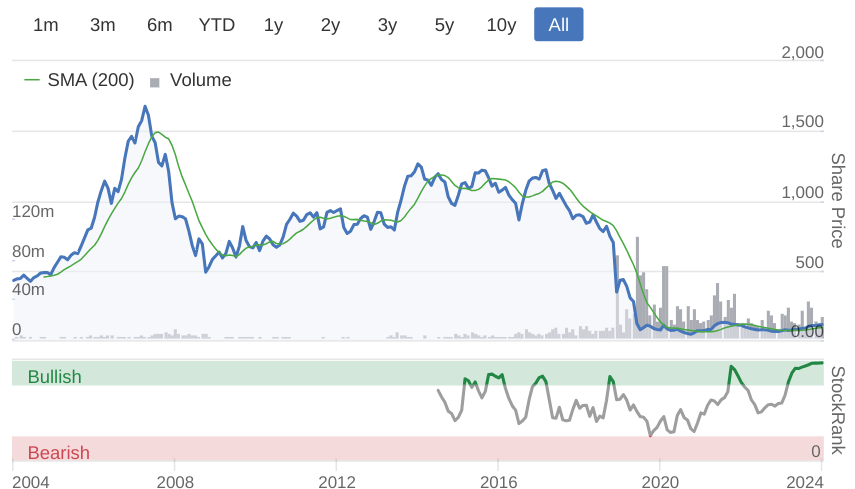
It's also worth pointing out the long-term track record -
Currys (LON:CURY)
Up 9% to 49.4p y’day (£560m) - Trading Update [ahead] - Paul - AMBER/RED
The giant UK/Nordics electrical retailer pulled a positive surprise out of the hat, with a slightly ahead of expectations update, with upwardly revised guidance -
Group adjusted profit before tax is expected to be £105-115m, ahead of consensus expectations2
2. Consensus forecasts FY 2023/24 adjusted PBT of £104m. Company compiled consensus for FY 2023/24
Although the surplus is little more than a rounding error on c.£9bn revenues expected for FY 4/2024.
Also note they have not removed the Greek subsidiary (pending disposal) from this £105-115m guidance, which is wrong I think, it should be eliminated as a discontinued activity. That’s £18m of profit to come off the £105-115m guidance above.
Greece disposal is expected to complete soon, and should then result in CURY having a net cash position - a useful improvement, but lower profit in future obviously. The disposal price of £156m after costs looks favourable to me, and reduces balance sheet risk considerably. Although the whole business is financed by enormous credit provided by its suppliers, which has always concerned me.
Year-to-date LFL revenues were weak though, negative (3)% in the UK, and (5)% in the Nordics.
I heard an interview with the CEO on Ian King’s Sky podcast, who said that Red Sea shipping had introduced delays of 1-2 weeks on some products, but that “customers won’t notice”, and little to no financial impact is expected. They’re used to dealing with supply chain chaos, given the events of the last 4 years. Being the biggest retailer in the sector, they’re “first in the queue” when product supply is restricted. He sounded pretty relaxed about things.
Paul’s opinion - I’m tempted to move up again from amber/red to amber, but still have concerns, namely -
Weak balance sheet - NTAV is about negative £(700)m
Cash-hungry pension deficit
Dependence on trade credit to finance the whole business
Very low margin, only just over 1% at PBT level
Another big increase in living wage pending from April 2024, increasing costs.
Aggressive online competition, eg AO World (LON:AO.). & Marks Electrical (LON:MRK) so margins are always going to be low.
Little to no pricing power, as it’s selling third party brands mainly.
On the upside, it’s survived the last few years surprisingly well, remaining (just about) profitable despite all the disruption and headwinds. Very large revenues of c.£9bn means there could be considerable upside if consumers do relax spending, which I expect given the large increases in real wages, benefits & state pension in the pipeline.
As mentioned before, the whole sector of electrical retail doesn’t interest me at all, and I wouldn’t buy any of them.
CURY doing reasonably OK, does raise questions over MRK, which recently warned on profits, halving its forecast, blaming price conscious customers and lower margins. That seems more a home-grown problem, as CURY has clearly avoided those pitfalls, further undermining the investment case for MRK.
With CURY, I’ll stick with AMBER/RED, given the considerable bear points noted above, but I’ll be happy to be proven wrong if the consumer does increasingly get their purses out in 2024. Many electrical purchases are forced purchases when existing equipment breaks.
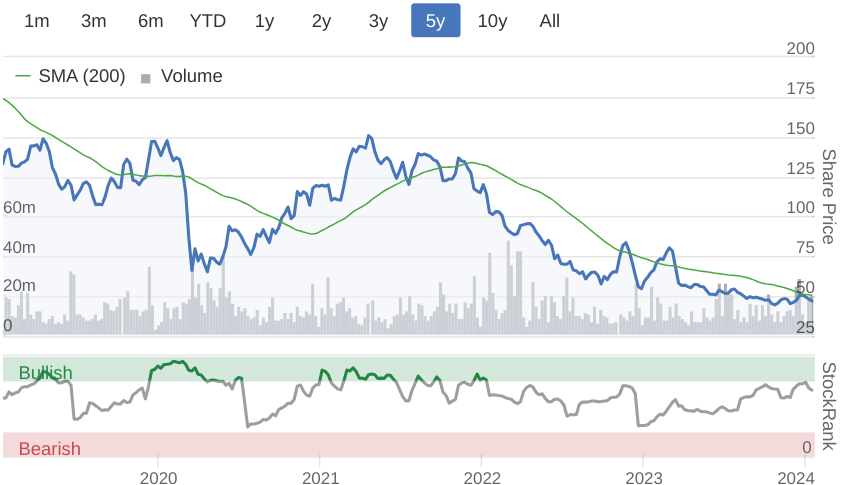
Note that CURY share count has actually gone down (from buybacks) over the last 5 years, so theoretically shares could regain previous levels, if revenues and profits were to return to pre-pandemic levels. So there is an upside case here, if you’re bullish on consumer spending.
4imprint (LON:FOUR)
4635p (pre-market) £1.31bn - Trading Update [slightly ahead] - Paul - GREEN
This share has been a stunning success in the last 15 years, roughly 50-bagging from low to high. It sells marketing/promotional goods, mainly in the USA.
I’ve long admired the company, but never imagined the shares would be such a rip-roaring success, and they often looked too pricey on the way up - there’s a lesson there!
4imprint Group plc (the "Group"), the leading international direct marketer of promotional products, will announce its final results for the year ended 30 December 2023 on Wednesday, 13 March 2024. Ahead of this, the Group today provides a trading update.
The update today is self-explanatory, so here it is in full -
Excellent progress has been made by the Group during the course of 2023, giving rise to a strong financial performance for the year.
Unaudited Group revenue for 2023 is anticipated to be $1.33bn, an increase of $186m or 16% compared to $1.14bn in 2022. Unaudited profit before tax in 2023 is expected to be not less than $140m (2022: $104m), slightly above the upper end of the current range of analysts' forecasts.
Unaudited cash and bank deposits at the 2023 year-end were $105m, (2022: $87m), leaving the Group very well funded entering the 2024 financial year.
The Group has made significant operational progress in 2023, reflecting a clear strategy and a highly resilient business model. The Board remains confident in the Group's prospects.
That’s a big increase in adj PBT, up 35% vs 2022.
Note the US dollar reporting.
Liberum & Cavendish both update us today via Research Tree.
Cavendish ups FY 12/2023 EPS by 8% from 346c to 372c, which is 293p, so the PER is now 15.8x, which seems good value to me, given the growth and the amazing track record.
Given that the share price is likely to rise today, the PER would go up a bit I expect, and might end the day nearer 17x at a guess (writing this pre market open). That still seems a reasonable price for an outstanding business.
Given the size of the US economy, I imagine c.$1.3bn revenues probably leaves plenty of scope for further growth.
Paul’s opinion - this looks good. GREEN from me.
Big Technologies (LON:BIG)
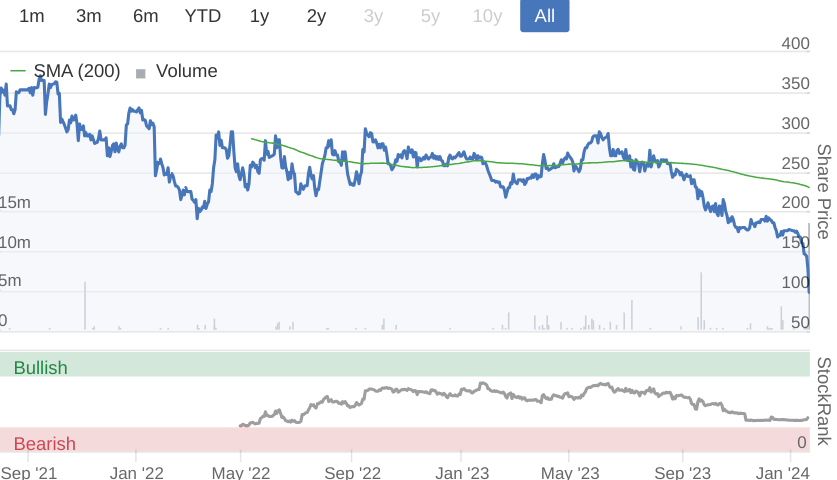
Down 21% to 101.5p (£294m) - Trading Update - Paul - BLACK (profit warning flag), AMBER/GREEN on fundamentals.
Big Technologies plc, the UK-based remote people monitoring technology company, issues the following trading update ahead of the announcement scheduled for 26 March 2024 of its full year results for the year ended 31 December 2023.
This share went into freefall in the first few minutes of trading, bottoming c.75p, since bouncing a good amount up to 101.5p at the time of writing, although that could be out-of-date by the time I’ve finished this section! A nice trade there early for the brave.
I’ve only looked at BIG once, here on 20/9/2023, where I detailed:
Bull points - very high margins, cash generative, owner/manager with a big stake still, recurring revenues, surplus cash pile.
Bear points - 2021 float, mgt greed re share options, and valuation too high.
2023 trading - is fine, in line with expectations -
The Group has continued to perform in line with the board's expectations with revenue for the year ended 31 December 2023 expected to be approximately £55 million (2022: £50.2 million) and adjusted EBITDA to be approximately £33 million (2022: £30.5 million). These results are in line with current market expectations1.
1: The Company has compiled forecasts from four analysts with current market forecasts for 2023 revenue to be in the range of £54.0 to £54.5m, with a consensus of £54.3m, and for adjusted EBITDA to be in the range of £32.7m to £32.8m, with a consensus of £32.7m.
A black mark for only revealing adj EBITDA. Zeus comes to our rescue with an update note, to translate adj EBITDA into real profit.
Zeus has FY 12/2023 as adj EBITDA £33.0m, and adj EBIT (operating profit) of £28.9m. It doesn’t show adj PBT, which I presume will be higher than EBIT due to interest received on the big cash pile. Adj dil EPS is 8.9p, so a PER of only 11.4x - looks cheap.
2024 guidance - it’s cheap on a 2023 earnings multiple because we have a profit warning for 2024. Adj EBIT forecast has been lowered by 25% to £23.9m, which is a 17% drop on 2023 actual.
What’s gone wrong? A large contract in Colombia has been “subject to short term renewals since September 2021”, but is now expected to end in H1 of 2024.
This has been partly mitigated with several other new contract wins.
“Investment” in expanding its sales efforts in the USA will cost more in 2024 and reduce short term profits, for a (hopefully) acceleration of growth in the medium term.
It says 2024 revenues should “at least” match 2022, which was £50.2m.
What about profit though? It doesn’t provide profit guidance for 2024, saying it will update when more is known re Colombia in March 2024, so we’re in limbo until then.
Zeus has pencilled in 7.3p for FY 12/2024. That would be a PER of about 13.9x, which strikes me as probably a fair price.
Outlook - it’s not all doom & gloom -
The Group continues to see opportunities to expand market share and scale-up the business and is in the process of releasing its first innovative substance detection technology to priority customers. We have enjoyed contract renewals across the business and won a number of new customers in recent months which will start to contribute revenues during 2024 and 2025. A return to growth is expected for 2025 and beyond.
Cash - is a key bull point for this share, as it has a lovely balance sheet. At June 2023, it had £99m NTAV, of which £76m was cash, almost all of which I regard as surplus cash. That’s just over a quarter of the £294m market cap (at 101p/share).
I imagine cash has probably gone up in the last 6 months, which makes it all the more perplexing as to why today’s update doesn’t mention cash at all. Talk about an own goal!
Paul’s opinion - I think this share looks quite interesting at the new, reduced valuation. Especially when you take into account the big cash pile too.
What today’s profit warning reminds us, is that many smaller companies are highly dependent on one or a few big customers and contracts. If Colombia was only being renewed on a short term basis since 2021, then that really should have been disclosed to the market previously, I wonder if it’s in the IPO documentation as a risk factor?
As I always say, outsiders don’t really know what’s going on inside any company, and there can be hidden risks like this at almost any company.
Given the cash pile, and the various other positive things about BIG, combined with a now much more sensible valuation, I’m going to lean slightly positively towards it for a potential medium term recovery, so I’ll go AMBER/GREEN on fundamentals.
Although for the purposes of my spreadsheet, it’s BLACK, to flag the profit warning today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

96 comments
Alumasc (LON:ALU) .... Following BnB's excellent New Year's Eve Post re rotating into cyclical, I have been waiting a buying opportunity... finally took the chance today as we approach the 50 day and 200 day m.a. Hopefully they will act as support levels as valuation is looking very enticing.
Bango (LON:BGO)
I have no idea how or why but some very useful aditional information is available via this link. Note one should not presume anything posted heerf is the truthn for obvious reasons.
I feel that if any further information was to be communicated here in this regard then it should have been made available to all at the same time rather than being provided to one individual.
It does add much more meat to the bone but probabaly asnwers very little - imho this person does not seem up to the job of comunicating market related senmsative info . Seems crazy to agree massive downgrades but then say i still think we will hit old targets - particularly if they have changed accounting standards i would have said that alone would make that imposible.
https://martinflitton1.wixsite...
(Bango (LON:BGO) I thought Malhotra sounded disingenuous. I didn't like the implausibility of his glib optimism. As they say on Dragon's Den: "So, for that reason, I'm out". (I held)
Bango (LON:BGO)
the problem here is its always been a story stock - last year and this year (year just started) were meant to be the proof of the pudding and they have mostly pulled the plug before the year has started. Even if forecasts are good for next year i doubt the market is going to give them any advance credit.
Hey ho i think main bods here have huge stake and increase in sharecount had been modest - so if they are genuine ref reasons ref this downgrade hopefully it will work out ok for holders pariculalry if they are now mor conservative etc . I just hate when any company doesnt tell it like it is from the outset though - seems much more prevelant that for companies not making profits/not having positive cashflow - that are selling a story seem to over egg the situation much more than companies that have real cashflow.
This does create a conundrum - i quite like companies morphing into profits as thats when they can get on a real roll - the roll at present here seems kinda non existant at present.
For companies like that i would have had much confidence if they promised low and beat on each update - when sales are groing quickly unles you need chunky fundraising - seems to me like acounting should always be conservative rather than the opposite.
Whether it is disingenuous or not i dont have any opinion - (Traitors spolier alert) i would say its as sketchy as Paul on the Traitors was and we all ..............
Completely agree with your reasoning on Bango. And I would also point out that shares have fallen on the PW but haven’t yet dropped in step with the evisceration of payment stocks globally. Perhaps that won’t happen but it’s the reason I sold last year. Looked too likely to pull back before any operational issues reared their head.
Here are this week's volume leaders. See Superdry (LON:SDRY) started the year well again!
Have a good weekend all.
Today's volume leader's
I was looking at Northamber (LON:NAR) the other day from your list as the cash and freehold are well above its market cap. No debt.
Trading at about 47-48p with a NAV close to £1. (No holding yet!).
Northamber - a blast from the past. I seem to recall that this company had a large family shareholder who was apparently content with the status quo.
The difficulty is working out how the NAV could be realised. Has something changed?
The family control it and do not seem that bothered about other shareholders. Great assets but ... I did hold for a couple of years but sold out of frustration 18moths ago at a small loss. They are currently upgrading IT systems- I have an account with them as a customer.
I don’t really know anything about Northamber (LON:NAR) other than the NAV is well above market cap and that the major shareholder and founder has sadly passed away about 3 years ago.
Can you give us some information please at what exactly they do and if there is any room for improvement(profit/margins).
Thanks
They are an IT distributor- specialising in AudioVideo hardware and Software Solutions .They are an OK company to buy from, but as an investment it did not work for me. I am not sure were they can grow to be honest. I sold out 18 months ago and rather lost interest.
I cant really add anything to what Charles Mitchell has said. Its been going a very long time and was talked about in the dot.com boom in various tip sheets.
Family members own over 60% and by the look of it, little has changed after what would seem the passing of the founder.
I thought it might de-list at some stage - but its obviously still around.
De listing must be an option.
In terms of Kier (KIE) it is worth, imo, looking even more long term than the period covered by the Stocko chart you illustrated Paul. Kier was effectively a revived version of French Kier after a management buyout. French Kier almost went bang in 74, not long after the merger of the original W&C French and JL Kier, for various reasons, some known by the investing public, some not. The shares went down to 7 pence / share and the Kier CEO took over as group CEO from the W&C French CEO. The current CEO of Kier reminds me a great deal of that Kier man, John Mott. French Kier then consistently and continually increased turnover and profit for the next eleven years and were taken over at, IIRC, £2.68 / share in 86.
After a further few years they had a difficult year or two after a revival of their major project division, with a few major projects giving them grief, and the management, knowing that there were huge valid claims to be settled on those projects, bought the company out from the owning conglomerate, cheaply I would assume, and Kier (KIE) came into being after a flotation. The Stocko chart then shows an excellent short term rise as, I suspect, the claims settlements boosted profits, then the company ended up run by accountants posing as CEOs after the final Civils generated CEO (John Dodds) retired. Lots of very poor acquisitions and obfuscation of consequences followed for a few years until eventually the brown stuff hit the fan, and the new CEO Andrew Davies was recruited, with a mass exodus of the old board. His initial assessment of the state of Kier and the actions needed struck me as spot on, and that, combined with the somewhat ruthless implementation of those actions really reminded me of John Mott's tenure. Unfortunately his revitalisation of Kier was badly delayed by Covid etc., but now seems to be going reasonably well, although I'm sure he will not be able to quite match the stellar recovery of John Mott's time. As a fairly recent shareholder, I'm hopeful about the company.
I notice that there has been discussion about Card Factory (LON:CARD) here this morning. By coincidence I popped into my local branch today to do some mystery shopping and was amazed at how busy it was (@ 11:50 a queue of 5, plus another 5 in what is a small, compact store). The poor shop assistant was rushed off her feet, but was cheery and helpful to all customers.
BnB referred to the product as tat, but looking at was for sale I would say instead say that their products are ephermeral, (how well built do you need a birthday card to be?) but I was pleasantly surprised at the quality of (their own) designs, and so I ended up buying 8 cards for £9.33.
I hold.
Card Factory (LON:CARD) - Found a terrific and thorough review of the company from last year - well worth a watch (note starts in Spanish before kicking into English - ole!)
?feature=sharedNow that guy has done his research.
It’s an excellent dive into he company.
Since no-one has mentioned it, I thought I'd mention that Palm Oil produce M P Evans (LON:MPE) issued an update today.
http://newsfile.refinitiv.com/...
Share are up 2.2% to 746p, so the market seems happy enough with this update.
"Crop and production grew steadily in 2023 thanks to a continuing focus on operational excellence in the Group's estate and milling activities, combined with a further increase in the Group's own milling capacity. The Group has invested for future growth, resulting in a 20% increase in its planted hectarage during the year.
The Group received an average mill-gate price for its CPO of US$729 per tonne in 2023, approximately 15% lower than the US$854 in the previous year. In 2022, pricing had been unusually high, particularly in the first half of the year, moderating in the second half and since then to levels still considered strong by historic standards. The Group continues to receive mill-gate prices in excess of US$700 per tonne."
MPE do seem to be committed to expanding their business, both in terms of acreage and mill construction. It uses them to mill both its own crops and other farmers. It seems to treat its employees well.
I remember hearing that the group commissions its own research in the expected NPV in its shares, so the fact that it has being doing buybacks might suggest that its shares are not overvalued.
So CPO (the Palm Olive price) is down, which is something to think about. You can see the price of palm oil here:
https://tradingeconomics.com/c...
Commodities in general have been a strange old game. Before 2021 prices were below 3500. Then things went absolutely crazy, reaching 7000. Since then prices have been relatively stable, in the range 3500 - 4000, or thereabouts.
Where next? Well, it depends whether you think prices will revert to their old range of 2000-3000, or if we've reached a "permanent" new shift. Time will tell, although I'm inclined to think the latter. If you believe inflation isn't dead, then some exposure to commodities isn't such a bad idea.
Analysts etimate and eps of 107c for 2024, which is about 85p. This puts it on a forward PE of 8.8 based on a share price of 746p. Pretty reasonable in terms of value.
I totally botched the purchase of this share, so you'll probably want to take my views with a pinch of salt. I bought back in May 2022, when the oil price was high. Bad move, obviously, and I'm down around 23% on this. I bought based on the StockRank and was investing mechanically. In retrospect I should have realised that that a commodity company is highly dependent on the commodity price. D'oh.
One day the seller in XP Factory (LON:XPF) will run out of shares and I will have a massive party.
It just can't keep it up, not even for a day.
They could all buy the party gear at Card Factory (LON:CARD)
DAZZA64 that is great info on Watches of Switzerland (LON:WOSG) .
Thanks for sharing.
Eagle Eye Solutions (LON:EYE) - big volume spike right now. Trades (down as a sell) worth 6million (1milion shares). Price is 535p, opened the day at 565p.
That is the sell price, to buy 569.4p Eagle Eye Solutions (LON:EYE).
Eagle Eye Solutions (LON:EYE) I meant that the 6mil trade went through as a sell at 535p. You are correct, buy price hasn't moved at 569p. There was a volume spike a few days back too which I bought on. Definitely something going on here. (I hold)
Lots going on in REIT land at the moment! Following davidjhill’s comment about Newriver Reit (LON:NRR) yesterday , today abrdn Property Income Trust (LON:API) is being merged with Custodian Property Income Reit (LON:CREI) at 61p a share and it’s up 15% today to 55p -so some arbitrage space left there. I’ve been building a reit sub portfolio at enormous discounts to NAV and often 8-10% yields to lock in high income for years to come, now it seems the value is beginning to be unlocked by corporate activity. I had only just finished building my position in LXi REIT (LON:LXI) when that agreed a merger! In some ways annoying after doing all the work :) but hopefully these will become stronger and more resilient providing even more certainty over future income streams.
abrdn Property Income Trust (LON:API) just ploughing through the RNS and the delight is in the detail! It seems the divs will increase by 7% and they are already yielding 8.3%
“That based on the Closing Price per CREI Share, the exchange ratio represents a premium of approximately 29.4% to API's Closing Price, 23.0% to API's 1-month volume-weighted average price and 26.5% to API's 3-month volume-weighted average price as at the Latest Practicable Date;
API Shareholders are expected to experience an annualised uplift in dividends of 7.3% (based on the Exchange Ratio and CREI's target dividend of 5.5 pence per share) with the dividend being fully covered;”
The manager, Custodian Capital is a wholly-owned subsidiary of Mattioli Woods plc ("Mattioli Woods") Mattioli Woods (LON:MTW)
abrdn Property Income Trust (LON:API) and Custodian Property Income Reit (LON:CREI) - yes, a good merger but only a small % have backed so far. Scale, balance and cost savings make this a no brainer. Custodian have a better record than abrdn so it makes perfect sense really. I hold a few shares in both, but they are stronger together. I haven't been selling REITs, but I haven't been buying either. I'm more in favour of alternatives at this point in the cycle. Value and Indexed Property Income Trust (LON:VIP) looks a bit of a bargain though and so I might be tempted to add some more, although I already have a full size position. I also hold Mattioli Woods (LON:MTW) and it will be a big win for them if it goes through!
The delight may be in the detail for holders of abrdn Property Income Trust (LON:API) but as a holder of Custodian Property Income Reit (LON:CREI) it does not look so great. The stock is down 15% today so clearly the deal is not well appreciated.
One thing about Watches of Switzerland (LON:WOSG) this morning which puts me off a little is that the manufacturers (Rolex) seem to be able to turn the screws on the retailers quite easily. I think that's worth factoring into anyone's view.
Watches of Switzerland (LON:WOSG) I were tempted to buy WOSG this morning, but after reading this article explaining Rolex seem to control what type of watches they supply them and presently that's steel lower value watches, I haven't. https://www.watchpro.com/rolex...
‘In light of the recent challenging trading conditions and based on a more cautious view of the outlook for the remainder of the fiscal year, management is now providing revised full year guidance for FY24, which assumes no recovery in consumer demand and reflects discussions with key brands.’
If I was thinking of trying to catch a falling knife in Watches of Switzerland (LON:WOSG) I’d be very concerned about that last semi-sentence, what discussions with key brands, it can’t be good if they’re downgrading.
I wonder if Rolex are thinking of a "two-channel" approach where they sell their cheaper watches to companies like WOSG and keep the more expensive ones under a more exclusive lockdown. If this is a new strategy by Rolex then I'm inclined to think that no amount of discussion is going to change their mind.
I might be being too down on WOSG as it really annoys me to see companies bomb just a few years after floating. I don't like it not paying a dividend, either. It's an attitude I picked up from listening to John Lee. In my own mind I've relegated WOSG to my "too difficult" pile, and leave it for folks with more insight than me to make their own views.
I think you are much better off owing Richemont than WOSG today. The former bounced 10% on a good TU yesterday, owns the IP and is cheap relative to history. This looks like a good entry into the mother lode. Others are commenting on the luxury slowdown and associated China weakness as if the market hasn’t known this for six months. As I said before. Buy these centuries-old brands on major weakness. I bought Hermes and Ferrari in Oct 22, LVMH and Richemont in Jan 19 and Burberry last week. If Burberry is a dud - and I do not rate it as highly as the others - it’ll be the first. The rest have all nearly doubled and, thanks to the recent slump, look reasonable value next to history - though not as lowly rated as Card Facory (sorry, couldn’t resist)
COMPAGNIE FINANCIERE RICHEMONT SA (SWX:CFR)
Burberry (LON:BRBY)
Hi BnB
I bought into Richemont last year after you mentioned them and I went away to investigate - thank you for the suggestion.
I'm not sure about valuation relative to history as I personally prefer looking at the valuation today and what I would pay for it if I had the money.
They've had a growing FCF for years, and I estimate that they'll make €4b for FY24 (which ends March 2024), a similar amount to FY23.
The current Market Cap is €66b, with net cash announced yesterday of €7b.
For a company with such remarkable brands - Cartier being the crown jewel - this looks cheap, even in the face of a subdued Asian market. Surely at least a x20 multiple makes more sense, which means the share price should be much higher?
---
I also bought some Burberry (LON:BRBY) last week on similar valuation grounds and the quality of the brand.
I think their cash generation - which should be c.£400m - the strong dividend history, a decent dividend yield and their net cash position (c£700m) make now a compelling entry point for a company valued at £4.4b.
Fingers crossed for both.
Hi Abtan
Looks like we’re both seeing the same good value in both names. These companies have been around for a century or more for good reason. And the more venerable they become - the greater the moat, all else being equal. Meanwhile don’t underestimate the long term capital appreciation and shareholder returns fostered by the principles of Swiss family ownership - even if Johan Rupert is really S African! The company’s discount to luxury peers is unjustified. My bank has a price target of €140. But soon after the luxury sector starts to recover, that target will be nearer €180. Good luck to you (and me) with them.
Watches of Switzerland (LON:WOSG)
Cheers Dazza
i am slightly gobsmacked here that any owners potential investors here wouldnt have known the score here.
Rolex dont act like any normal retailer - they massively restrict supply so that there is always without fail limited supply available at the best of times , retailers need to scramble to get what they can from Rolex - all retailers need to suck it up and take what they are given in that regard.
As if that was not enough of an elephant in the room is that Rolex have in the last 6 months bought the worlds largest watch retailer !!! - if limited supply aint bad enough waht about ten prospect of direct competition.
https://www.time4diamonds.com/...
So whilst there may be no specific reasons for believing WOS cant thrive all investors need to understand the elephants in then room here imho.
at present from me its pretty uninvestible at anything other bargain basement prices here as a punt - if the price keeps declining and the pe gets to about 5 or 6 that could be tempting territory - i would want to see some stabilisation in earnings though too - as i would be worried if Rolex dierct stuff still acounts for material % of their profits things could get worse again if their relationship with rolex worsens - i would almost want to know they are making their profits without any direct stock from rolex as who knows when supply could dry up.
I have previously mentioned any of the above as i thought everyone knew the score and the risks here of how the buisnes model works.
Watches of Switzerland (LON:WOSG)
'i would almost want to know they are making their profits without any direct stock from rolex'
I think this is the key point now. What does the business look like if you were to strip out the 'new' Rolex sales. What kind of eps would one expect without the new Rolex sales? Not sure if they break this down in the annual numbers (i.e. % of turnover that's new Rolex watches).
If these numbers stack up without Rolex then I would be happy to buy WOSG at the right price. At the moment I have no idea what those numbers might look like - and therefore what a fair price might be.
I still think the used market is a huge growth market for luxury watches. Although there is price volatility and security concerns, people will always want nice watches for either fashion reasons, aspiration reasons, or just for the appreciation of a fine horological piece. The world is going to get wealthier over time with the demographics long term favouring a company like WOSG. Imo it would be a solid investment if they were very profitable without selling new Rolex's - I just don't know if they would be or not? Or how material to the bottom line this would be?
100% agreed here - note we might miss out on a bargain if we cant get the clarification - so it could still be good value -its just to me too much uncertainty i dont need , slight shame as i agree about the market for fine horological pieces being a nice marekt segment to have some exposure too at presesnt - shame one cant cut to the chase and invest in Rolex .
If only Bitcoin did watches.
Watches of Switzerland (LON:WOSG) I also have a slight fear about the growth of smart-watches vs luxury watches with more & more health info now being incorporated.
I have a very nice Omega watch that I bought 20 years ago and today costs a not insignificant amount - was way cheaper when I bought it and could never see me paying that much just to tell the time, but appreciate everyone has their own limits.
However, I never wear it as I have a smart watch now that does so much more; golf, fitness, heart-rate monitoring, health snapshot, tracking, sky-diving (if that's your thing), maps, music, payment device etc. etc.
I can't see me going back to just a simple old time-piece.
Whilst others will, and the luxury watch market will never die off completely I just feel that as these smart watches get cleverer and cleverer and young people (I am def not one of these) start to rely on them so much the total market could drop off.
Maybe time to research Garmin (NYQ:GRMN) or the like.
Watches of Switzerland (LON:WOSG)
I also have a slight fear about the growth of smart-watches vs luxury watches with more & more health info now being incorporated.
is the point not that people are doing exactly what you have done - they are buying these watches to not wear generally - in which case if they wear somethig smart related on day to day basis that doesnt mean they dont want a Rolex to give to their grandkids or pay for a nice holiday when they retire and in the meantime they may only wear it a few time a year at most if ever.
Exactly. I have a smartwatch and a dress watch for “best” - not a particularly sought after or expensive one, but it is a rare brand, a Swiss movement and I like it.
not sure whats in the water today everyone in agreement for a change :)
shame one cant cut to the chase and invest in Rolex .
But you can in Richemont with a host of brands more exclusive than Rolex - and they put out a good print yesterday, bucking the luxury slump. Shares are very cheap relative to history as the sector is weighing on valuations. Family owned so a good yield of 3%.
Adriatic Metals (LON:ADT1) I have twice pointed out to Stockopedia that the market cap of this small miner is not over one billion. It still has not been corrected. How can we trust the statistics?
Having pointed this in multiple occasions as well the answer I got is that the provider is not updating them. Basically blaming someone else.
But I am not paying the provider. I am paying Stockopedia.
Not to be trusted along with the estimates and the cash/debt figures especially.
yiannos1 has a very good point. We, the subscribers, are paying Stocko for a service. But if that service is supplying us with faulty data how can we trust any of the Stocko data. Other users have commented previously, and not irregularly, on the inaccuracy of some of Stocko's data and I think it's time that they, Stocko, put their house in order rather than blaming their provider(s).
I agree far too many errors. I'm only picking up the more glaring ones. Seems Stocko rely totally on their provider. If there is an error, then have to go back to the provider, to correct it. Look at that fiasco with the dates on the results for 4 stocks, that took about 6 months to sort out, that effects those stocks and others, one of which was 4imprint (LON:FOUR). If you look at this print: https://s3.eu-west-1.amazonaws... which is November 2023, you will see the. analysist forecasts for 1.1.22 were still estimates, even though the 31.12.22 results had been published in April 23.
My experience has been that every few months I find an odd or incorrect figure. I notify Stocko and within a few hours have had a friendly and helpful response , with an explanation (once or twice it was not an error), and what they are doing to resolve the issue quickly.
The issue is often to do with data flows from their providers, and they have usually been able to get the issue quickly resolved.
But if that service is supplying us with faulty data how can we trust any of the Stocko data.
I have always presumed that the stockopedia date is "indictive" i have never presumed its wholly accurate. Would be nice if it was but its clear to me its not practicable when pulling volume through from external sources that everythig is going to be correct or can be corrected.
I suspect the majority of subscribers accept the realities here that with the volume going on not every error will be corrected.
Yes there will be some errors, agreed. The amount of errors seems to getting worse. I don't use SharePad, they seem to do more with the data, doing adjustments and they seem more accurate, maybe they have staff checking and working on the data?
If Stocko cannot fix the data immediately it would be good of they computer some sort of sticky warning note saying data shown is under query
I looked at Works co uk (LON:WRKS) yesterday and eps forecasts for 2024 still showing as 9.3p.
Singers forecast in May '23 was 3.3p, moved to 1.2p in November '23
Makes the rest of the data , screening and stock rank etc on the company pretty worthless.
How can we trust the statistics? Adriatic Metals (LON:ADT1)
That is a good point. The problem with this company seems to revolve around the number of shares in issue.
According to the company rns on 5/1/24 there are 294,855,069 shares in issue. Stockopedia says 570,611,206. The london stock exchange says 555,754,000 on its "tear sheet" but calculated from the stated mkt cap on the main company page must be using a number around 292.7 million. Sharepad says 292.7 million, which is consistent with the (wrong) london stock exchange page.
What a mess! This should be easy to resolve if all sources were updated to include the latest company announcement in a timely fashion.
Big Technologies (LON:BIG)
Zeus 2024 EPS cut 23%
2025 EPS cut 20%
Big Technologies (LON:BIG)
I’ve been watching this slide too. I like the basic proposition and the superb margins but today’s TU urges caution.
Big Technologies (LON:BIG) Looked at it for the first time last night. This has set forecasts back 2 years I'd say.
Love the cash generation, but really need to find out when these larger contracts end, as this could potentially be a rolling problem every couple of years?
Big Technologies (LON:BIG) Down 45% now. Almost half the market cap in cash. Tempted to dip a toe in here.
Big Technologies (LON:BIG) I'm also very tempted and have been watching this for a few days now.
What makes me hesitant is they prided themselves on having never lost a customer (that's just happened) and they didn't win the big MoJ contract earlier this year despite their confidence they would (Serco won it), so from claiming to have the best product on the market how actually good is it?
Having said that the mountain of cash on the balance sheet and the huge EBIT margins pull me towards taking a punt.
Greed/Fear/Greed/Fear....another cup of tea
Big Technologies (LON:BIG) Been a good rebound trade, up 35% from the lows at 8:30. Now down 20% on the day which is probably more like the downgrades this morning suggested might happen.
Couple of million quid buys, maybe director buying. You'd expect them to have piled in this morning.
Big Technologies (LON:BIG) - large block sales of 530k on Monday and 390k yesterday seem as clear case of insider dealing as it's possible to get
Morning Wolf of Small Street.
Thanks for flagging, Big Technologies (LON:BIG) didn't come up on my initial sweep of the RNS. I'll take a look at it, as it seems to be a PW. We've only reviewed it once before, on 20/9/2023, I remember it because I copied its website which said it does tracking devices for the elderly, but then readers corrected me saying it was more involved in security tags for criminals. I thought it looked an interesting, cash generative, owner/managed company, but thought the valuation seemed a bit toppy at 216p, but I see it was down to 128p by yesterday, and sounds like it's likely to take a further tumble today?
Just read the update, and it's lost a big contract so 2024 PW.
Best wishes, Paul.
Was it Solid State (LON:SOLI) that lost the contract, some years ago, for tagging criminals? This is the problem with large contracts.
Yes, Solid State (LON:SOLI) went up like a rocket on the MoJ contract (they were a part supplier I seem to remember) and then went down like a lead balloon as the contract stalled due to the other party and eventually got canned. The FD got ousted as a result. I met the CEO and CFO at a meeting with my broker and was very impressed with the CEO. His Father set up the business and he has no intention of ruining legacy. I held until it hit 1400p and then sold as found the rating a bit rich at the time. It has grown into the rating though. Superbly well run in my opinion. If it ever has a dip that’s not profit warning related I would buy again.
You can't say we weren't warned about Big Technologies (LON:BIG) . Here is Paul Scott's comment from 20 Sep 23:
Share options charge is an outrageous £5.5m in H1 alone! Maybe if management could keep their hands out of the till, the valuation might look a bit more attractive?
Hi Paul, sorry off topic but I missed your gozo penthouse video the other day and then it was removed…can you point me in the direction I can see it please?
Search for paulypilot on YouTube.
Thanks!
Why was it removed - I didn't find it offensive and its nice to see where Paul is doing his work from?
search paul scott on you tube
Big Technologies (LON:BIG) - heavy selling yesterday afternoon from somebody in the know before today's announcement makes this uninvestable now for me
"Any idea why stockopedia says they are a company in financial distress?"
That was a complete post here (my bold) on Wednesday that led me to panic - I might lose the 11 months left on my renewed subscription if Stocko goes under.
Perhaps "they" referred to another company though? I was reading in one of the 3 ways that are not threaded.
Hence I am posting at the begining of the day to support Helvellyn's cry yesterday about being driven "nuts because so many contributors do not cross reference which company they are talking about with the @ tag and a lot of the comments then become meaningless".
The instructions in the header every day ask us to "include the company name/ticker, otherwise people won't necessarily know what company you are referring to".
Can we please give that a go today?
4imprint (LON:FOUR)
Spooked the market with references to a mild slowdown in demand in the previous TU and shares fell 15%. Today, no references to potential recession and an “ahead of expectations” update. The market has discounted a soft landing more broadly but FOUR shares have yet to recover. I see value at today’s undisturbed price. Indeed I saw value 3 months back and bought then. This is a very high quality operator that I regret selling in the past.
I got spooked out of my shares in FOUR in March 2020, when they tanked. Although I had done well in the shares, what I should have done is held on, when the price subsequently rose from 1270p to where it is now (around 4635p).
Although it's never easy to say when a company has reached the end of its runway, the lesson I learned is that in a quality growth company it pays to play the long game. We shouldn't be overly concerned about the macro and whether they'll be recessions or soft landings. FOUR has a great track record with high ROE and growth. The market falling out of bed is a buying opportunity.
Totally agree on 4imprint (LON:FOUR). I did the same thing. Originally buying at 1800 and then selling g at a loss.....we live and learn (I hold them now again)
Card Factory (LON:CARD) JD Sports Fashion (LON:JD.)
I could be wrong, but holders of the former who are bamboozled by its persistent low valuation might want to look at the valuation of the latter post- PW, whose CEO and Chairman have each bought this week. I know which shop I’d rather own shares in and it’s not the one selling tat for 99p, it’s the one that sells it for £99! And indeed I do now, an outsized position.
Very different businesses selling staples around celebrations that we have a cultural history of doing versus fast fashion in trainers.
there’s a case for both but “selling tat” is a very glib statement BnB and could be equally applied to the expensive tat of JD?
Selling tat” is a very glib statement BnB and could be equally applied to the expensive tat of JD?
And I did! Surprised you missed that. On the broader point, I learned early in my business career that there is far more profit in selling higher priced goods and services. Card Factory (LON:CARD) looks to me like a trade, JD Sports Fashion (LON:JD.) an investment, albeit with a cyclical component which might be offering a great price today. The CEO and Chairman think so even if their purchases are not huge. I could be wrong, as I mentioned before.
Not a fan of Card Factory (LON:CARD) as I cannot see where the growth is coming from , but Buffett did pay around $25B for a tin of baked beans and a a small bottle of Ketchup-it is the operating margins that matter. Otherwise we will all own only Boeing Co (NYQ:BA) shares!
To be fair BnB Card Factory (LON:CARD) have 13-14% ebit margin on the 99p tat. JD Sports Fashion (LON:JD.) 8-10%
That is a fair point and I may have touched a nerve when it was my intention to shed some light on the bafflement of Card Factory (LON:CARD) holders at the persistent low valuation. Few would consider it a better quality business than JD Sports Fashion (LON:JD.)
Well Stocko disagrees with you there. JD Sports Fashion (LON:JD.) has Q rank of 90, Card Factory (LON:CARD) has 99.
JD Sports Fashion (LON:JD.) shares have fallen far more than Card Factory (LON:CARD), I hold both.
But sales of expensive items are going down, better to buy stocks that are selling cheap tat? Look at all the luxury stocks getting hit, Rather buy 10 cards for £1 than spend £100 on trainers.
Look at all the luxury stocks getting hit
Like Richemont? Check their TU from yesterday and compare to WOSG. I agree that they’re a cyclical issue for luxury right now however. But that’s when you buy the stock!!
Surely the problem for luxury stocks at the moment is China's economic slump. China in recent years has been the most important market for many luxury brands.
Card v JD
I’m with Card , They control their own production and distribution, nice business model
JD - there’s an upcoming swing in the market against high price fashion, it’s moving to 2nd use and vintage and this will gather pace not decrease .
They are massively exposed to Nike and other big brands and will lose margin as sales reduce .
Just don’t see much in JD except as a reseller of other peoples high end brands that are all under pressure .
They are watches of Switzerland of fashion and look pretty exposed .
Card looks pretty steady away and nice simple business model .
Card Factory (LON:CARD) Two analysts on buy, two on hold with different price targets/valuations. It would be so useful to understand the different perspectives from retail industry experts....
I think there is an important social trend that is benefitting JD Sports Fashion (LON:JD.) That is the increasing number of women and girls taking part in sport.
I found myself watching the second half of the Arsenal v Chelsea WSL match, I thought the crowd looked fairly large and I was amazed to hear it announced as a record WSL crowd of 59,000.
Add in the fact that England Women won the Euros and reached the World Cup Final, I think there is not only added interest but an increasing number of customers for JD Sports.
Granddaughter recently signed as semi-professional for a minor club - she's 19 so hopefully this will be the first step in a career. The buzz around women's football is amazing and so far we haven't had too much trouble from the you-know-what problem which is too political to mention here, so I think you are right and there is scope for sports fashion to benefit. Some of the "Lionesses" have contracts with fashion houses.
But that’s when you buy the stock!!
Although I don’t own Watches of Switzerland (LON:WOSG) I agree in principle with your comment. This is exactly when you buy stocks having bought Meta Platforms (NSQ:META) at $107 when no one wanted to know anything about it.
That is what someone said about Burberry (LON:BRBY) a few months ago, not sure if that was you, that did not work very well. Richement has fallen back, same as many luxury brands, such as LVMH Moet Hennessy Louis Vuitton SE (EPA:MC). Is the fall over or just beginning? There are many problems in China, unemployment and property.
My morning smallcap tweet: How the hypey have fallen
Versarien (LON:VRS) Wincanton (LON:WIN) Capital (LON:CAPD) Character (LON:CCT) N4 Pharma (LON:N4P) DFS Furniture (LON:DFS), Focusrite (LON:TUNE)
◄Versarien (VRS)► yet another placing: £400k at 0.08p, 47% discount, to keep the lights on. Are there any believers left in this POS? [SP=0.18 Cap=1m]
◄Wincanton (WIN)► 450p rec offer, a 52% premium. [SP=297.5 Cap=371m]. I hold.
◄Capital (CAPD)► guides FY-Dec rev $318.4m, up 9.7%, missing $320-340m guided. Outlook - strong demand across each of its business divisions. [SP=91 Cap=176m]
◄Character (CCT)► first 4 mths of FY rev flat but profitability improved. Guides FY-Aug profitability in line. [SP=273.6 Cap=53m]
◄N4 Pharma (N4P)► its a novel delivery system for cancer treatments, gene therapy and vaccines, Nuvec, gets a patent in India. [SP=0.97 Cap=3m]
◄DFS (DFS)► cuts FY-June rev guidance by c.4% but keeps U/L pretax at £30m-£35m with good operational performance, progress on gross margins and lowering its cost base. [SP=110.8 Cap=259m]. I'm short.
In line: TUNE
Wincanton (LON:WIN) acquisition shows market very cheap. Ive held for nearly 20 years and dividend stream been welcome as is the premium offered this morning. Another British stalwart leaves the market.
Yep - another one bites the dust……. Guess that’s Wincanton (LON:WIN) off my watchlist then.
the pool of investable companies gets smaller alas and very little coming onto the market let alone anything quality.
capital markets are not working efficiently in the UK - we really need government to start paying attention before it’s too late.
What? We’ve had Deliveroo (LON:ROO) , Cab Payments Holdings (LON:CABP) and Dr Martens (LON:DOCS) , to name but a few…
We gonna be left with Chill Brands (LON:CHLL) Versarien (LON:VRS) to choose from !