Small Cap Value Report (Fri 19 July 2024) - PMP, KIE, CRL Brief: HL., BPT, CAL, SCE

Good morning from Paul!
Phew, that's me done! Have a lovely weekend, and enjoy the weather - at last it's arrived!
As the RNS is broken, due to a global IT problem apparently, I'll look at some backlog stuff instead. Mine & Stockopedia's IT seems to be working. EDIT at 10:39 - we're off! RNSs just started coming through.
Subscriber vote! Click here to vote (voting now closed, thanks for your interest) for which backlog item you would like me to write about today. I've done the 3 items that got the most votes!
Voting update - no need to call Jon Snow, I have the data in hand (the dog request made me chuckle!) -
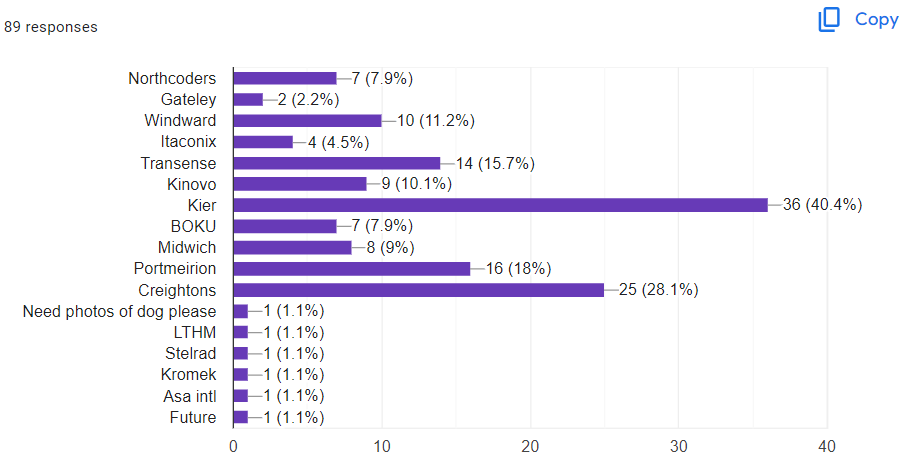
On the back of your votes, I've done sections on Kier (LON:KIE) , Creightons (LON:CRL) , and Portmeirion (LON:PMP)
This is great, I think we'll do polls more regularly, so we can focus on what subscribers most want.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
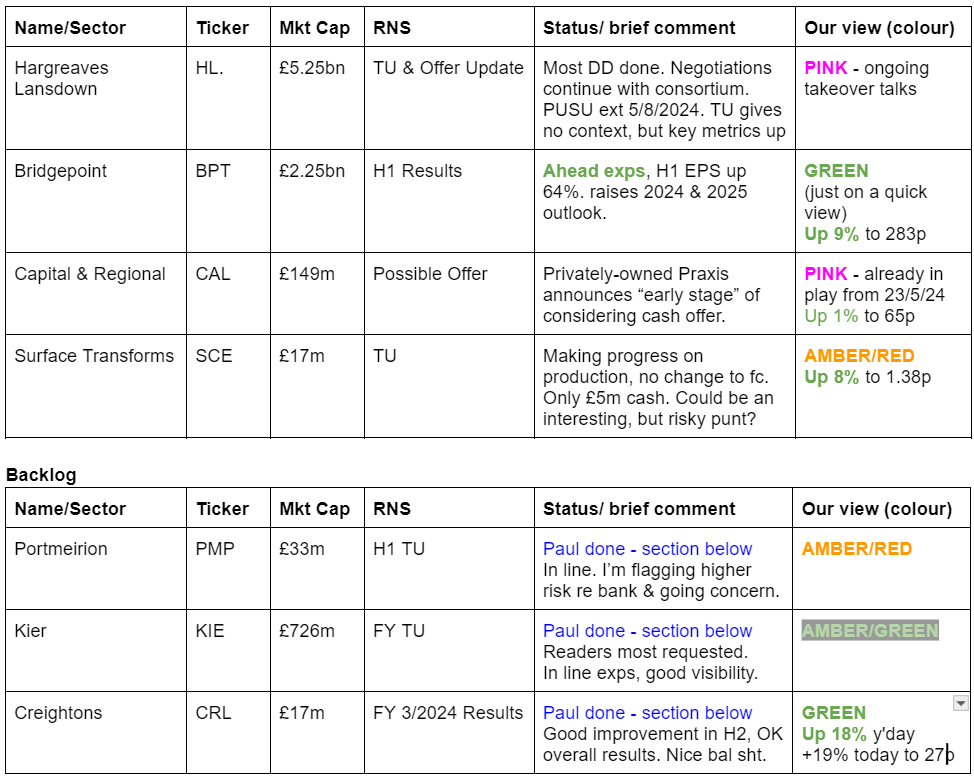
Summaries
Portmeirion (LON:PMP) - up 12% y’day to 235p (£33m) - H1 Trading Update - Paul - AMBER/RED
In line update for H1 (the much weaker half), despite a 60% plunge in sales in the important S. Korean market, blamed on destocking. Other markets are OK though. Cost cutting done, as planned. Nothing said on most important issue, the bank renewal due in Sept 2024. I flag the last "material uncertainty" going concern statement. I'd rather wait for confirmation of bank facilities renewing, and the upturn in H2 trading actually happening. Until then, it's high risk in my view, but that's why the shares are low.
Kier (LON:KIE) - up 3% to 161p y’day (£729m) - FY 6/2024 Trading Update - Paul - AMBER/GREEN
Top of my poll of reader requests. An interesting situation - it's traded in line, and has good visibility thanks to a giant order book of public infrastructure projects. Shares have already re-rated significantly from a PER of 3.1x to 7.3x, and could possibly have further to go? I've shifted up a notch from amber to AMBER/GREEN.
Creightons (LON:CRL) - up 19% today, plus 18% y’day, now 27p (£18m) - FY 3/2024 Results - Paul - GREEN
I'm moving on up, as Heather Small would sing, from amber to GREEN. Good progression upwards in profit from H1 to H2, although achieved from cost-cutting. Very decent balance sheet has been de-geared from good cashflows. New management seem more commercial. I see the decks as cleared now for management to have a good stab at getting a recovery underway here, with potential to return to higher historical profit levels. So risk:reward seems quite good to me.
Paul’s Section:
Portmeirion (LON:PMP)
Up 12% y’day to 235p (£33m) - H1 Trading Update - Paul - AMBER/RED
Portmeirion Group PLC, the owner, designer, manufacturer and omni-channel retailer of leading homeware brands in global markets, provides an update on its trading for the six months to 30 June 2024.
This (mostly) ceramics maker used to be a wonder stock, let’s pretend we’re back in late 2018, and see its 12-bagging performance from the 2009 lows to 2018 high -
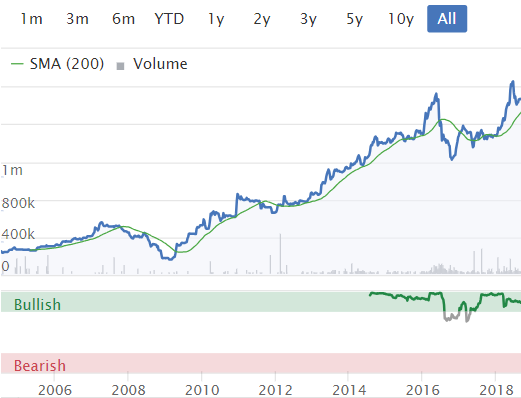
Unfortunately, since then, performance has disappointed, and series of acquisitions do not seem to have added value, but did weaken the finances. Plus of course the pandemic, energy and supply chain problems more recently. So it’s had a tough time for sure. Although as mentioned before, I can’t shake off the feeling that something structural is going wrong - ie that demand just isn’t as high as it used to be for PMP’s core products, and diversification hasn’t worked.
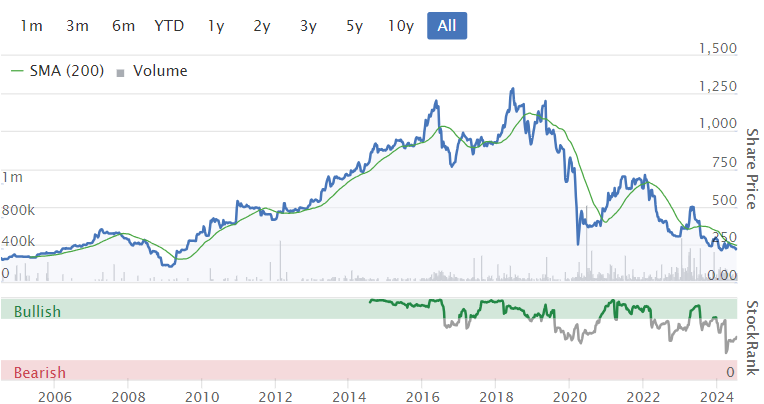
Note the share count has gone up from c.11m to c.14m in the last 6 years too. I wonder if it will need another equity fundraise, if the bank don't play ball - more on that below.
Reviewing our previous comments here in the last year, to remind me of the background (which anyone can do quickly using my summary spreadsheet here, then doing CTRL-F for the PMP ticker) -
20/7/2023 - AMBER - 285p - Profit warning hidden in seemingly mild update. Broker slashed profit forecast by 68%! Blamed on US de-stocking.
2/2/2024 - AMBER - 217p - In line 12/2023 TU. Paul - shares could go either way, not clear.
28/3/2024 - AMBER/RED - 244p - FY 12/2023 results. Still profitable, but down on LY. Main issue = “material uncertainty” going concern, re bank facilities.
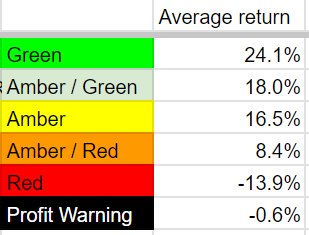
Remember that if we go AMBER/RED or RED, it’s a high risk warning. It’s not a prediction of what will happen next for any particular company. Some of these companies recover, a few even multi-bag, but on average these categories go on to under-perform our more positive colour-coded shares. Here's the latest data re our colour-coding. Take out outliers MCB and HOTC, and the rest of amber/red is about zero -
In practice, very few listed companies go bust, or have bank facilities withdrawn. Although plenty are forced into highly dilutive, discounted placings, which I’ve been hit with in the past, hence why I avoid any company that obviously needs to raise fresh equity (especially in a bear market). Everyone has their own risk tolerance, so armed with the facts, we can make up our own minds for each individual share.
Right, back to PMP, this is the latest news - which sounds reassuring -
“H1 2024 Trading update
Improved demand across US/UK, tough macroeconomic backdrop remains in South Korea
Remain on track to meet Full Year market expectations”
Remember PMP has a big seasonality towards H2, as that includes bumper Xmas sales.
Last year FY 12/2023 it made £3.0m adj PBT (down 63% on 2022), but adjustments were large (mostly non-cash impairments), leading to a £(8.5)m statutory LBT.
Singers leaves forecasts unchanged, anticipating a 50% rise in adj PBT to £4.5m (24.5p adj EPS) for FY 12/2024. I’m not sure how realistic that is, given that PMP has just said H1 revenues are down 17% (all caused by a plunge in S. Korean sales. Other major markets are OK, the US and UK). Although it says this sharp drop in S. Korea was expected, and was previously flagged in March - which I’ve just confirmed (although it wasn’t quantified, and this 17% drop in total H1 revenues is a lot more than I imagined).
Sales elsewhere were up 5%, so this implies sales in S. Korea must have absolutely collapsed, to take the overall group revenue to -17%. Ah yes, here we are, it says H1 S. Korea sales were down an enormous -60% - that’s a big worry. De-stocking means the products are not in demand, so there’s clearly a problem here, and I’m worried it might not just resolve itself in H2. Although this bit reassures it might only be temporary -
“In South Korea, following a significant stock refill in 2022 and first half 2023, the more recent consumer slowdown has resulted in distributors and retailers needing to reduce high stock levels. This has impacted short term orders for this market however we are confident that our Portmeirion brand remains ever popular with the end consumer as evidenced by healthy, growing online channel sales in the market.”
Hence H1 results are likely to look grim when they’re published (revenues down 17% on a previous H1 only at breakeven last year).
Wax Lyrical, its home fragrances business, is doing well, with UK sales up 25% from new product lines achieving good orders.
Outlook - remember H2, and Xmas orders, are crucial to overall performance. Some comfort here -
“We expect FY24 profit to be up on the prior year with improved operating margins and we remain on track to meet FY market expectations.
We expect sales in the second half in our South Korean market to be back to broadly in line with the prior year and we have healthy order books for Christmas across the US and UK…
…We are also encouraged by our advance US orders for Christmas which remain significantly ahead of last year.”
Cost-cutting done, and a mention of shipping costs/disruption doesn’t sound alarming -
“The actions we have taken to reduce our overhead cost base by 10% leaves us better placed to navigate any continuing macro pressures as trading conditions around our key markets across the world continue to be unpredictable. We also continue to manage the increasing disruption to global container freight shipping together with rising rates.”
What’s missing? Nothing is said about by far the most important issue at PMP - its cash/debt position, and banking relationship.
This is what caused the “material uncertainty” in the last going concern statement. Going through that again, it said a £3m loan repayment is due to Lloyds on 31/1/2025. A decision on extending the bank facilities was said to be expected in Sept 2024. The downside scenario in the FY 12/2023 going concern note forecast 10% downturn in revenues. H1 is actually down more than that, at -17%, admittedly the seasonally quieter half, but even so it’s a worry. It says if they promptly took additional cost savings action, then “sales could reduce by 18% before we breached facility limits or any covenants”. -17% actual in H1 is dangerously close to that figure, so it’s now vital that sales do recover in H2, or PMP would be in a pickle. “we do not consider the likelihood of an 18% sales reduction to be plausible. “ - yet it’s (almost) happened in H1. I suppose they are talking about the full year though. An H2 recovery in sales is clearly vital.
At the mercy of Lloyds (who I don’t trust to be supportive, having had bad experiences with them personally), PMP said this in the going concern note (26/3/2024) -
“The Directors recognise that the current bank facilities, which include both a committed revolving credit facility of £10 million available until September 2025 and an uncommitted facility element of £12.5 million available until September 2024, are all required under both a base case and downside scenario in order to provide the Group with sufficient liquidity to continue trading. Under an unlikely but plausible scenario by September 2024 Lloyds could decline their option to extend the committed revolving credit facility beyond September 2025 and therefore decide not to renew the uncommitted facilities at the same date. Under this scenario alternative third party funding would need to be secured in order for the Group to meet liabilities as they fall due and therefore continue as a going concern.”
The Group has a positive and long-standing relationship with our lenders however, if the Group could not secure alternative funding by this date, then the Directors acknowledge that this represents a material uncertainty which may cast significant doubt on the Group's ability to continue as a going concern.
The Board considers the likelihood of lenders removing facilities at this date and not being able to secure an alternative source of funding to be low, and therefore the Directors have a reasonable expectation that the Group has adequate resources to meet its liabilities over a period of at least twelve months from the date of signing the financial statements. Accordingly, they continue to adopt the going concern basis in preparing the annual report and accounts.
Paul’s opinion - I don’t like this bank risk hanging over PMP shares. So for me, risk:reward isn’t attractive at the moment. I’d rather pay a bit more for this share, once it has confirmed renewal of the bank facilities, and that trading in H2 is improving as expected.
Before that happens, it’s higher risk, so it has to be AMBER/RED again.
You can make up your own mind if the risk is worth taking, that’s entirely up to you. IF the bank renews, and trading shows signs of improvement in H2, then I wouldn’t be surprised to see PMP shares bounce strongly.
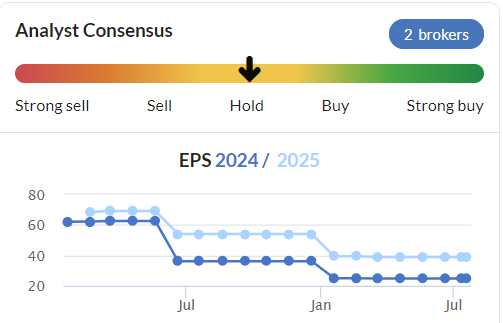
However, see below how much forecasts have already come down. Also PMP management have a tendency to gloss over bad news, and hence I don’t trust their optimism. The downside case here is another profit warning in the autumn, which I suspect could happen, saying they won’t recoup the necessary sales, and the bank could then tighten their grip with maybe smaller facilities, and a side agreement that PMP will raise more equity in a (probably discounted) placing. I don’t want to take that risk, so I’ll watch from the sidelines for now. Good luck to holders, I hope the upside case pans out for you, which it could well do, who knows?!
Kier (LON:KIE)
Up 3% to 161p y’day (£729m) - FY 6/2024 Trading Update - Paul - AMBER/GREEN
Kier Group plc ("Kier" or "the Group"), a leading infrastructure services, construction and property group issues a trading update for the year ended 30 June 2024, ahead of publishing Full Year 2024 ("FY24") results on 12 September 2024.
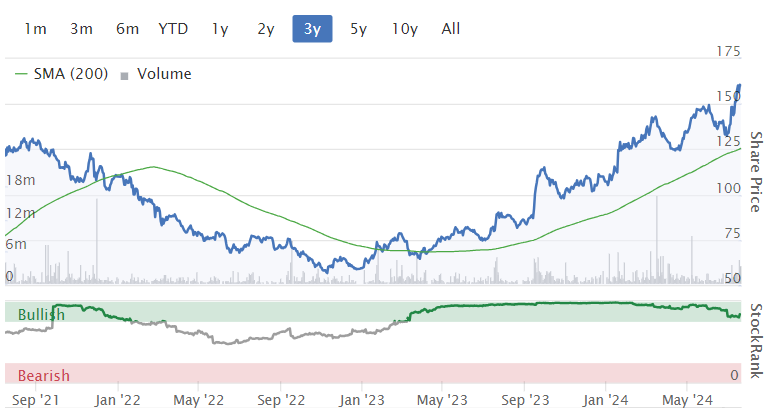
Kier shares bottomed out in late 2022 at c.60p, and have since been in a lovely uptrend rising c.168% to 161p as of now. A terrific outcome for shareholders, well done to people who spotted the value. We were a bit slow on the uptake here at the SCVR I’m afraid, but I caught up in Nov 2023. Here’s a recap -
16/11/2023 - GREEN - 104p - AGM TU - appealingly cheap, 5% yield, trading well, decent outlook, worth a closer look if you invest in low margin contractors.
19/01/2024 - AMBER/GREEN - 125p - In line TU - Low margins, weak balance sheet. Performance is OK, divis about to resume. Still quite good value, but given shares have doubled in the last year, I'm moderating my view.
07/03/2024 - AMBER - 139p - H1 results as expected, FY 6/2024 outlook in line (note that forecasts have been slightly reduced in the last 9 months). Balance sheet is large, complicated, and weak. Shares have had a great run, but look up with events to me now.
Those are all fair points I think, but the market disagrees, and has taken KIE shares up a further leg to 161p today.
Must admit, with the forward PER still only at 7.6x, I probably made a mistake becoming more cautious this year as the price rose.
This sector seems to be becoming more fashionable with investors, and ultra low PERs are now attracting buyers. We saw something similar with Galliford Try Holdings (LON:GFRD) recently, which has moved up sharply, now having a forward PER of 12.8x. It also has ambitious growth plans.
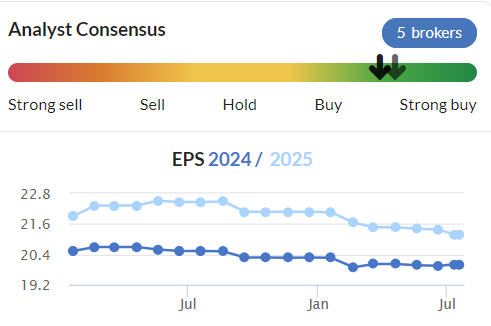
KIE is mainly a re-rating story (onto a higher PER), as the earnings forecasts have actually gone slightly down during the same period that shares rose by 168% -
We can look back in time, using the “PRINT” button on any StockReport (which brings up a menu of loads of historical StockReports), and sure enough, KIE shares were on an insanely low PER of 3.1x in Jan 2023 - a bargain hiding in plain sight!
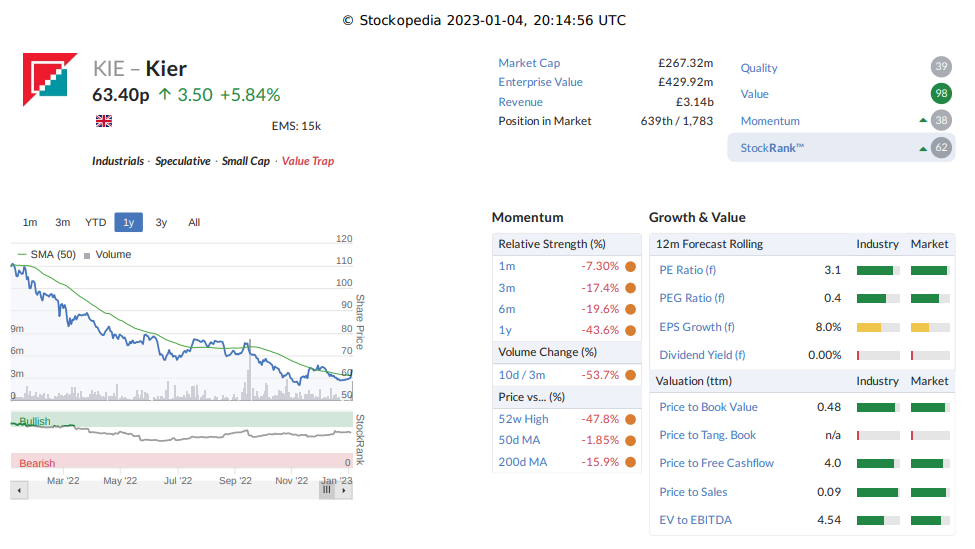
(Archived StockReport from 4/1/2023)
Although it’s also valid that KIE had big debt and pension liabilities back then, a poor track record, and dilution from quadrupling the share count during the pandemic. So perhaps investor caution made sense at the time. A strong recovery since, with forecast earnings recovery turning into actual recovery, has fuelled the big rise in share price.
So can the shares re-rate any further is the key question? And when/if will earnings start to improve? It needs either an earnings increase, or a further re-rating onto a higher PER, to keep the bull run going. Ideally, both would be great!
Kier has 2 main divisions of roughly equal size (revenues/profit) -
Infrastructure Services - H1 revs £944m, up 16% (boosted by HS2), operating margin rose from 4.1% to 4.7%.
Construction - H1 revs £915m, up 29%, operating margin fell sharply, from 4.6% to 3.6%.
These are the type of contracting projects Kier does -
Infrastructure - seems all-encompassing design/engineering/delivery/maintenance of roads, rail, ports, air, water, energy, nuclear, telecoms, etc.
Construction has national coverage delivering schools, hospitals, defence, custodial facilities and amenities centres for local authorities, councils and the private sector.
I’m assuming these will all be competitive tender & framework type arrangements, so it’s difficult to see there being much upside on margins in future. Although investors seem to like the story of margin upside in this sector. We also have to consider margin downside risk, when things (quite often) go wrong on major infrastructure projects. The UK seems remarkably bad at delivering infrastructure at anything like on time, and on budget. A key point is how the contracts are set up, and I don’t see how investors can judge that, seeing as we don’t get to see contract details. You just have to quiz management, and hope they know what they’re doing, in this sector.
Upside potential obviously comes from there being a large need for increased infrastructure spending in the UK, like many other countries, and a new Govt that seems amenable to pulling in more private sector funding to accelerate necessary improvements. So I think it’s safe to assume there should be a gigantic pie to share out between the big contracting groups, something that some investors have clearly (and cleverly) already cottoned on to.
Enough rambling, let’s get back to the point.
FY 6/2024 Trading Update - from yesterday.
Kier Group plc ("Kier" or "the Group"), a leading infrastructure services, construction and property group issues a trading update for the year ended 30 June 2024, ahead of publishing Full Year 2024 ("FY24") results on 12 September 2024.
Overall -
“The Group's full year FY24 results are anticipated to be above the prior year and in line with market expectations, reflecting a strong operational performance.”
Good visibility for FY 6/2025.
Year end spike in the cash position to £165m, average net debt of £(115)m is a more relevant measure, and has halved - very good.
“The year-end cash position was partly driven by a seasonal inflow of working capital, particularly in the Construction division.”
Dividends resuming, as expected.
Refinancing completed to 2029.
“In February 2024, the Group completed a refinancing of its principal debt facilities. This included the issuance of 5 Year £250m Senior Notes, maturing February 2029 and an extension of its Revolving Credit Facility, with a committed facility of £150m to March 2027.
With £400m of facilities, the Group has secured significant funding to support its medium-term value creation plan.”
“Strategic supplier” to the public sector - this looks important, with Google telling me -
“The UK government's 39 'Strategic Suppliers' are a group of companies who provide such vital services to the public sector that the Cabinet Office takes a more hands-on approach to managing the government's relationship with them.”
Outlook -
“Our core businesses are well-placed to benefit from investment in UK infrastructure, particularly in water, affordable homes and public housing maintenance. “
“During the year, Kier won new, high quality and profitable work in our markets reflecting the bidding discipline and risk management embedded in the business. The Group had a strong end to the year…”
The medium term growth targets show only modest growth on what it’s already achieving - this is much more modest growth than GFRD recently set out, and not at all exciting -
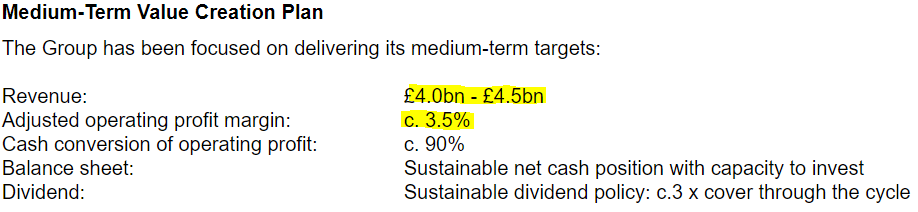
Paul’s opinion - I’m impressed. Could this share re-rate higher? Yes, I think that’s entirely possible.
I made a mistake dropping from amber/green to amber last time, so am happy to recognise that, and shift back up to a more positive view - AMBER/GREEN.
Although the shares have had such a good run, you could argue that the main % upside has probably already happened. However, I wouldn’t be surprised to see the PER rise to maybe 10x over time, and as the balance sheet improves, so upside to maybe 200-250p in due course? Not bad, if it happens, and of course assuming nothing goes wrong.
A very nice recovery in the last c.18 months -
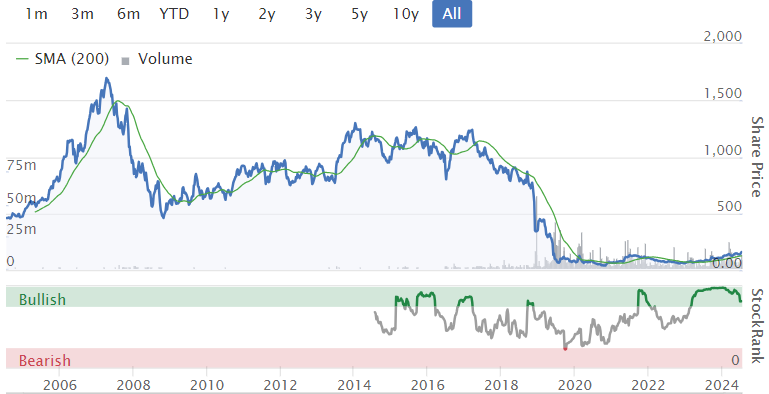
However, a dismal story of shareholder value destruction over the long-term, with big dilution since - so you need to be very sure previous problems won't be repeated -
Creightons (LON:CRL)
Up 19% today, plus 18% y’day, now 27p (£18m) - FY 3/2024 Results - Paul - GREEN
Creightons Plc (the "Group" or "Creightons") brand owners and manufacturers of personal care, beauty, and fragrance products, is pleased to announce its preliminary results for the year ended 31 March 2024.
I’ve been sitting on the fence here, with only a couple of SCVR updates in the last year -
04/12/2023 - AMBER - 22.5p - H1 Results - modest profit, sound bal sht, CEO sacked last week. No strong view either way.
08/7/2024 - AMBER - 19p - AMBER - goodwill impairment looks storm in a teacup. H2 trading improved vs H1. Sound finances, nothing to worry about.
A reminder that amber is not negative, it’s me effectively giving the shares a clean bill of health, nothing for me to warn you about. It’s where we don’t have a particularly strong view either way. Things are nuanced of course, so it’s worth reading our summaries too, not just the colour. That’s for people who find our colour-coding useful, not everyone does, which is fine!
Key numbers for FY 3/2024 -
Revenue down 9% to £53.2m
Turnaround underway, to improve margins & reduce costs.
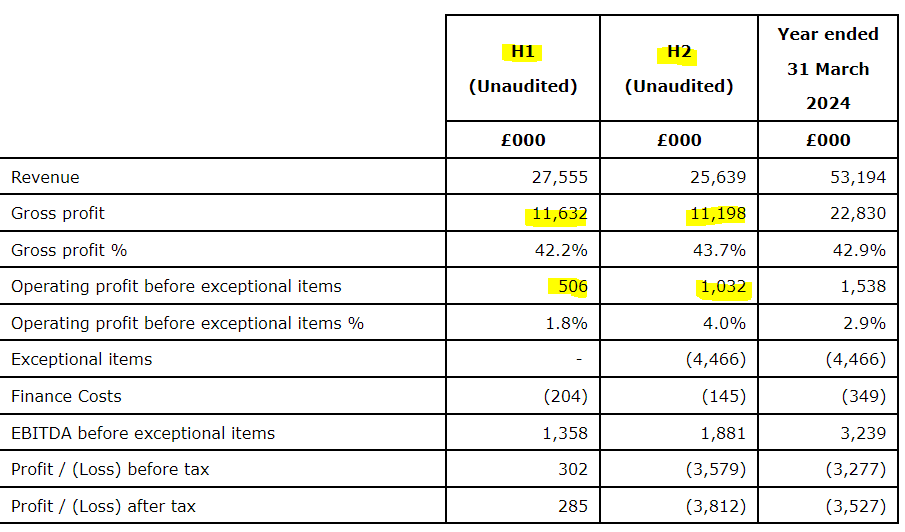
This useful table below splits out H1 & H2 performance. As you can see, gross profit fell £434k, so that should have led to £506k H1 operating profit almost disappearing in H2. Yet operating profit (pre exceptionals) actually doubled to £1,032k. This must have been achieved by stripping out a substantial c.£1m of costs in H2. Whilst that’s good, you can’t keep cutting costs, so it will need to drive both revenue & gross margin higher in future, to sustain further profit increases.
“Key cost reductions in administration and distribution also provided significant gains in operating performance overall.”
Balance sheet - is good, which I’ve flagged before. NAV is £22.1m, less intangibles (reduced after recent impairment) of £7.9m, and I’ll also take off deferred tax of £1.8m, giving my adj NTAV of £16.0m - that’s more than enough for the size of company, it’s well-capitalised. So dilution risk should be small, unless they decide to do a sizeable acquisition. Given mistakes made by previous management, let’s hope new management are either better at deals, or don’t do any at all for now.
I’ve previously been slightly concerned that too much capital was tied up in inventories & receivables. Both have come down usefully, by a larger % than the reduction in revenue, so that’s a positive thing, if they can maintain the new lower levels.
Cashflow statement - looks very good. Note that both this year and last year almost doubled cash generation from £3m to £6m due to favourable working capital movements, which may not continue, so don’t get carried away with £6m cash generation, it’s not likely to repeat. Capex is modest at £0.6m this year.
What happened to the cash generated? Mostly it’s paid down debt - reflected in a big improvement in net cash.
The headlines say it had £2.2m (vs LY negative £1.2m) but that doesn’t look right to me. The balance sheet shows £3.1m gross cash, and “borrowings” (excl. leases) of £620k + £2,315k. So I make that just £0.2m net cash. If anyone goes on the webinar due 11am, 24 July 2024, perhaps you could query this point? It’s not a deal-breaker, but I’m curious why CRL discloses net cash in what seems to be gross cash less leases, but ignores “borrowings”. It just looks wrong anyway, hence me querying it.
Paul’s opinion - I heard that Richard Crow’s followers have been piling in this week, hence the big surge in price.
It seems to me that they could be onto a winner. Although that depends on whether new management can drive good revenue & margin growth. The commentary seems to show a sharper commercial focus, whereas old management were addicted to doing deals as one investor friend put it. Which clearly they were no good at, as evidenced by the Emma Hardie debacle. That’s the past though, which is no longer relevant, as we’re buying the future, not the past when we buy a share, hence why I called the goodwill write-off a storm in a teacup recently.
With a nice sold balance sheet, net debt cleared, a better commercial strategy, and a good improvement from H1 to H2, I’m happy to move up two notches to GREEN.
CRL has a track record of making nice profits in the past, and hopefully can get back to previous £3-5m annual profit, which would justify a usefully higher share price, for sure. Can it do that though? No idea, we’ll just have to wait and see! I think an £18m market cap gives you pretty decent risk:reward.
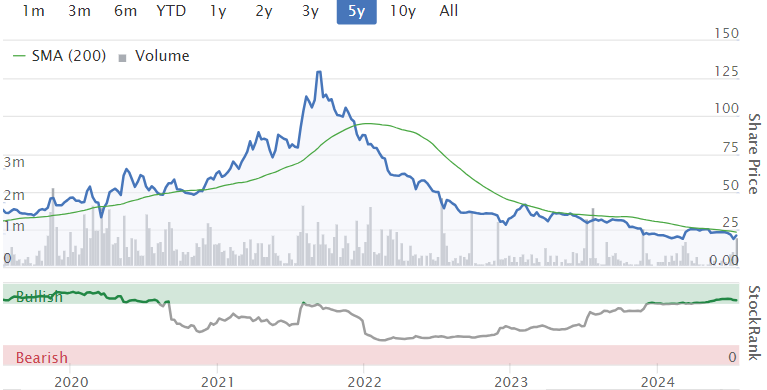
The market got over-excited in 2021, but with not much dilution over this period, there's no reason why CRL shares couldn't recover some of this fall, if performance improves -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

109 comments
Joe Biden finally withdraws from election race.
Podcast. Excellent,
Larf....I haven't larfed so much since Aunt Mabel.........
Thank you!
And for the poll on Friday. Great innovation. I didn't catch it in time to contribute, but look forward to doing so in future,
Portmeirion (LON:PMP) - ugh! Squeaky butt time! This one has gone badly against me. Should they ever fix the margins then it needs little sales growth to multibag. Nice opportunity. All the same I'd like it cheaper in view of the risk please! Disappointed to see it go up firmly on the update.
cheers
Mark
The comment at the end of the PS's podcast 20 Jul made me smile. It neatly summarised my week.
Thank you.
LOL yes I was in full rant mode, but thankfully the recording switched off just at the crucial moment!! ;-)
Would be possible to do a write up of Metals Exploration (LON:MTL) ? Solid results released yesterday, was expecting a healthy jump in the share price. It would be interesting to hear people’s thoughts.
Metals Exploration (LON:MTL)
The life time of the mine limits any upside here.
All the best
I agree somewhat. However they are debt free, with gold prices at record levels they are a money making machine. Runro may have 3-4 years left but Darren Bowden the CEO is very confident he can make MTL much bigger than it currently is. The abra tenement will hopefully be up and running when the current mine closes. It’s a huge area with good results from testing. The PE is incredibly low right now too, I think there are a lot of things to be excited about here.
Have a great weekend,
Mike
Hi Michael Harris,
Sorry we don't cover the natural resources sector in the SCVRs. That's because I've found it requires specialist knowledge, and there are too many unknowns in assessing performance. So rather than cover it badly, we don't cover the sector at all.
Sorry about that.
Regards, Paul.
Hi
As it is (frisky) Friday. This might interest some who invest in US tech orientated shares. One NOT for the faint hearted I suspect though.
Serve Robotics (NAQ:SERV) is up +113.58% as I type. This note gives the catalysts NVIDIA (NSQ:NVDA) and an earlier link to Uber Technologies (NYQ:UBER).
This was an earlier news feed.
** Shares of Serve Robotics SERV.O surge ~80% premarket to $4.74 after Nvidia NVDA.O disclosed investment in the co
** NVDA said in SEC filing late Thurs it bought 62,500 shares of automatic sidewalk delivery firm for $4/sh in Jul 2023
** In Apr, NVDA invested in co again, converting a promissory note into ~1.1 mln shares at $2.42 a piece
** NVDA owns ~3.7 mln SERV shares for ~10% stake
** SERV made its public debut in Mar under the OTCQB Venture Market, and then uplisted to Nasdaq Capital Market in Apr upon pricing of $40 mln public offering at $4
** Ride-hailing firm Uber Technologies UBER.N has ~14% stake in SERV, per LSEG data, and is also a strategic partner
For my sins just bought a toe in the water position :(. I know it will end in tears !!!!!
Regards
Howard
I wonder if they're similar to the Milton Keynes' (Milton Keynes is a perhaps to some surprisingly tech forward town) Starship Technologies sidewalk delivery robots that are already operating? They look pretty cool.Have to stay at a Whitbread (LON:WTB) Premier Inn someday and try and get a room order! https://www.mkfm.com/news/loca...
'After two years in action, Milton Keynes had the 'world's largest autonomous robot fleet'.
Global X Robotics and AI UCITS ETF USD Acc (LON:BOTZ)
Hi all - happy Friday. Quick question for Paul / Graham. would it be possible to add the Stock Rank of a stock in your "Companies Reporting" summary table at the top?
to be fair, you can get that to the right hand side of the page, here >>>
not sure we need commentators to manually add that in, but not for me to say either :)
Hi Dulpesh - thanks for the suggestion, about adding the StockRank into our "Companies Reporting" list. Let me have a think about that. Width of the table is the constraining factor, which I constantly have to tweak to prevent the text becoming too small.
But a new column for StockRank would be very narrow, so I might try it out and see if it works!
Thanks for the idea :-)
Although at tic_tac_toe kindly points out, there's a panel to the right of each report, where you can reference the StockReports, called "Securities mentioned", so actually that info is already right next to the SCVRs. Although I can also see the merit in having it in our table too, so let me have a think & I might trial it and do a reader poll to see if people want it or not.
Have a lovely weekend.
Regards, Paul.
Live on Vox Markets at 9.30am Monday (22nd July), I will be interviewing legendary UK fund manager Christopher Mills of Harwood Capital Management Ltd
It's sure to be another masterclass in all things investing - including lots of fascinating stock ideas such as: #NIOX #EKF #ANCR #PINE #AVG #TRB #TRI #SPI #ELM #CARR #PAY #HSP & many more.
Alongside of course, trying to answer any questions that you might have.
So please feel free join us here on Youtube. Everyone is welcome. A must watch conversation for all serious investors.
Great interview Paul. Christopher Mills and his team are the class act in UK small cap investing.
Massive volume traded so far in Smiths News (LON:SNWS) - over 11.5m
Super Stock (SR=99), yielding 8.79%, p/e 5.8 and psr of 0.14.
I wonder who is buying?
... and who is selling Smiths News (LON:SNWS) . The SP is still within yesterday's spread. It looks like a rearrangement between accounts rather than a lot of significant independent trading.
Accelerating takeovers and political stability could boost UK smaller companies...
https://www.trustintelligence....
Thanks for circling back to Kier (LON:KIE) Paul - another I hold. Looks like you're warming to the sector!
Most Employee Benefit Trusts have a use inasmuch as they allow management to buy in shares to cover option awards, and this if done well forestalls dilution, in that companies don't have to issue new shares to satisfy options exercises.
Technically shares held in the Trust are treated as shares still being in issue, and there should be no difference in the number of shares before and after a buy in to the Trust. Usually shares held in the Trust do not receive dividends unlike other shareholders, though this may depend on the Trust deeds terms. This provides a very modest benefit to other shareholders if dividends are part of the normal cycle of the Company.
Technically usually the Trust owes the money to the Company used to buy in the shares. This could be generated by the exercise price to some extent, if the hedging of the price of the share bought in is sensible.
Of course issuing excessive options, or options with a low bar to performance, or arguably at nil cost will cost both the Company and its shareholders both in terms of remuneration and its cash resources ( if a Trust is used to buy in shares) so a balance needs to be struck on all fronts.
Good news, Microsoft (NSQ:MSFT) Solitaire stills works.
I would be interested to know which online broker services are working. Mine (Barclays Stockbrokers) is still not available at the moment.
I can access iWeb, AJ Bell, T212, and HL accounts.
Good news CBBC is back on air ! Well it is a warm summers Friday and lets face it scant news to discuss
Interactive Investor and Iweb were not working this morning but I was able to trade on both about 11am
Looks like some RNS is now trickling through
This MSFT outage seems to be more minor here in the UK, and set to hit harder in the USA?
I've been reading news reports that the big American airlines are asking the FAA for a global (by that they mean USA airports) halt of all flights. That's pretty drastic, as today probably is one of their busiest travel days summer, Friday before weekend, etc.
Also - it was reported in either Times/Telegraph that today is the busiest airport day in the UK for the year, given school holidays... oh dear...
Looks like the glitch has been fixed and the RNS's have landed.
Stelrad (LON:SRAD) , one of the building product suppliers mentioned here for possible beneficiary of pick-up in housing market.
I noticed yesterday, it has made good progress since the election - possibly on the basis ofthe government announcing that homeowners won't be forced to rip out their boilers any time soon.
Wonder if the rns's will suddenly appear at some stage today, it'd be great to catch out the mms for once. On the buck side if they don't appear today then cue a lot of rumour mongering over the weekend
they just have!
I'm not a tekkie, but wondering if today's outage, for the LSE may be an opportunity for Beeks Financial Cloud (LON:BKS) - one of their products, managed cloud could I believe could have run a lot of RNS's at a minimum.
While I see myself as a long term holder, I also assume that the theses on which I buy cannot realistically look more than a couple of years forward. Crowdstrike Holdings (NSQ:CRWD) , on a forward p/e of 77 has no room at all to make mistakes so it could require quite a while to recover this level of confidence. Re-rating , both up and down, is one of the biggest movers of stock prices and this is going to weigh on CRWD.
Okra recovered from its dual, and very embarrassing, cyber incidents within a couple of months
I should be encouraged by this but Okta (NSQ:OKTA) is on a fwd p/e of 37 and Fortinet and Palo Alto Networks are below 50 so you can see where I am going with this!
SentinelOne (NYQ:S) a much smaller competitor in their area of cybersec is up pre market 10% ish., no surprise there.The other very few big publicly listed name cyber names, seem to be up smaller percenatge wise.Okta (NSQ:OKTA) had an embarrassing issue earlier this year/late last year where part of their systems got breached and recovered market cap wise.Invesco QQQ Trust Series 1 (NMQ:QQQ) has been a bit wobbly lately and vix has been moving up yesterday again, around 16.60 currently.So i'm imagining the stock could take a bit of a bath for a while, until next earnings at least.That's the problem, single point of failure, i guess with very few big players dominating such an important service/market.
FYI - bug with this morning's MSFT disruption...
While it looks like RNS are appearing when you go to individual company's News sections....
They are not showing up under the "News" widget on the Homepage, for portfolios.
So if you use that widget to see if a company in your portfolio has released an RNS, note that it is not showing up RNS that have been released today so far.
Despite what the Stocko banner says "no disruption".
(And for those that use Research Tree to see RNS of their portfolios, their service is also not showing up any of the RNS for me either, in the Dashboard view)
Gateley (Holdings) (LON:GTLY) 'S Stock Report says the next dividend will be paid on the 1st of October and going ex-divi on the 10th of October. Anything to do with the MS outage?
Doubt it but I think the correct dates are 10th and 25th Oct.
Is the fact that “major worldwide outages “ like the one today, can be caused so easily by the actions of, or even just a big mistake by one Company, a big warning sign for the whole World?
Is there a risk that something way bigger could cause absolute chaos with nearly everything down long term? Solutions and back ups then would be useless. It’s an issue that never gets addressed but should it be?
The movie Leave The World Behind was the first thought that came to mind this morning
watched it a couple of days ago as it happens, wasn't impressed with what is a good narrative for a film
Is the fact that “major worldwide outages “ like the one today, can be caused so easily by the actions of, or even just a big mistake by one Company, a big warning sign for the whole World?
Hi ken
Centralised cloud based systems like Azure are a single point of failure, even if you're using multiple regional nodes. Any company that requires continuous operation needs to run multi-cloud - e.g. Azure and AWS.
There have been occasional outages among all of the big cloud providers so this isn't a Black Swan. Managements running business critical processes in the cloud - usually for cost saving reasons - can't use the excuse that this was unforeseeable.
Obviously they will anyway, and claim force majeure, but it's not true, they just weren't willing to bear the extra costs of ensuring their systems are resilient.
timarr
Hi timarr
I didn’t explain it well and can’t because of near zero understanding of things like the cloud and how all this incredible modern technology that has taken over our lives, works.
My “what if” was simply if the whole lot came crashing down thanks to some unforseen and unprecedented disastrous event to mean everything is lost everywhere worldwide.
Is that impossible?
My “what if” was simply if the whole lot came crashing down thanks to some unforseen and unprecedented disastrous event to mean everything is lost everywhere worldwide ... Is that impossible?
No, not impossible, but very difficult. Famously the internet was designed to withstand nuclear war, but there are some core backbone systems that if targeted could cause widespread disruption.
More likely, though, is an issue with centralised or widely deployed services. For example, in my world of payments, many banks outsource to processors and those processors increasingly outsource to the big cloud providers who in turn call upon specialised third-party providers such as Crowdstrike. This level of indirection means that it's increasingly difficult to figure out whether the system is truly resilient, because it's possble that somewhere, somehow, everyone is relying on the same piece of software.
But if I wanted to bring the world to a stop I'd target payment systems - hit the major schemes simultaneously and the world would be in chaos within hours. And it's not impossible - Visa went dark for several hours a few years ago due to a misconfiguration of their systems.
Just keep some cash under the bed, just in case ...
timarr
Good to see you posting your pearls again Tim, hopefully post 2pm most of us will be feet up in the garden, with a couple of cold one's deckchair and a good read like Ezilifeme.
Thanks again timarr.
Don’t know what would happen if there was something like an unprecedented solar storm bringing down all the technology we now rely on for everything . Best not to think about it as the complete losing of our investment portfolios would be just one tiny result of a total outage of everything. We are so reliant on all this technology and a complete wipe out doesn’t seem to have been given much consideration.
I was thinking of that total outage possibility rather than the likes of cyber attacks from rogue states or individuals.
In my view you and Graham efforts make stockpedia work and your weekend podcast is essential listening. I for one appreciate your output thank you
I may, and often am, be being totally thick here, but it seems to me some of the Alliance news releases are based on absent RNS's. For example I noticed Hargreaves Lansdown (LON:HL.) was showing an Alliance News release titled Hargreaves Lansdown reaches record assets under administration and it does indeed refer to a report issued this morning about it's 4th quarter. I see now there is an ALNC item about Bridgepoint (LON:BPT) and suspect I will find something similar. This cannot be right can it?
Yep same for Bridgepoint (LON:BPT)
Hargreaves Lansdown (LON:HL.) Here is the missing RNS: https://www.hl.co.uk/investor-...
Hargreaves Lansdown (LON:HL.) Thank you Laurie, I had just found it! So it was in the public domain, though how many people visit the websites of the companies they have shares in on a daily basis. I get that the info was due to be rns'd today so you might go looking for it but still think inherently this is wrong. About to visit Bridgepoint's website now. Bridgepoint (LON:BPT)
It seems like Tapi (former management of Carpetright) are close to buying out parts of Carpetright in a pre-pack. As reported by The Times (paywall).
I remember asking if Headlam (LON:HEAD) or Likewise (LON:LIKE) will be impacted, as suppliers? But got some feedback from other Stocko users that they didn't supply the likes of Carpetright.
However, I think now if Tapi acquires Carpetright and solidifies their market share in the UK, it might make life more difficult for smaller carpet + floor covering retailers, especially independents, that maybe the two above supply?
So no immediate impact... but strategically a medium or long term impact to their customer bases?
Morning Paul, did you ever get chance to look back at Distribution Finance Capital
Morning alex,
Sorry I've been too busy to revisit Dist Finance Capital, but thanks for the reminder, will note it down again on my backlog list. Done - with an asterisk, to increase the chance it might actually get done!!
Regards, Paul.
thanks Paul
Having only bought Renold (LON:RNO) shares on Wednesday I, rather expensively, sold them today.
After what I now realise was the complete BS re the share options from the FD and CEO in the investor call on Wednesday, they have very clearly failed two of my share filters:
- Do I trust management?
- Is management remuneration excessive?
This has cost me in the short-term, and it wouldn't surprise me if the shares bounce strongly from current levels. However, I will now sleep better.
Bully for you shanklin, when thy eye offend thee, cast it out.
I am thankful to Paul for pointing this out. From past experience, if there is bad/dishonest/misleading behaviour, then there is likely to be more, and its best to get out. Like Shanklin100, I also sold (88 pc of my holding, retaining a small stake so I can go and complain to Renold), fortunately I did take a profit, but as the share price is +15pc down this week, I didn't bank as much profit as I wanted to.
I am another who is grateful to Paul for the careful detective work on Renold (LON:RNO). I have held Renold (LON:RNO) a little while now so there were profits to take. I halved what had become a large position for me as a compromise on my feelings about the general opaqueness, and used this as an opportunity to diversify my portfolio by increasing my positions in teapots, Churchill China (LON:CHH) ; and wallpaper Sanderson Design (LON:SDG).
I know this is a broken record, but great work on Renold (LON:RNO) yesterday (amongst all the other bits of great work on everything else). From the looks of it, lots of people have read it and decided that maybe Renold (LON:RNO) isn't worthy of their money. Down 8% as at 0840!
Dave
Hi Cowlid,
Seem a rather extreme market reaction re RNO. I should reinforce that I still like RNO shares, and am positive on it. The excessive mgt reward schemes are annoying, but not a deal-breaker for me, and a say 10% correction in price compensates for this issue I think.
We shouldn't forget that RNO mgt have done a great job in taking a serial underperforming basket case, and transforming it into an excellent business now on the front foot, making good profits & cashflow, doing decent acquisitions, etc. So it's a success overall.
"Employee benefit trusts" definitely need closer scrutiny at all companies which have them, from now on. It just looks a too-easy way to reward mgt without it significantly showing up as a cost in earnings numbers, yet it's real cash going out of the company and into mgt pockets.
This is another example of where the cashflow statement reveals the truth, so is arguably a lot more important than the P&L, yet many of us barely look at cashflow statements. I do a lot more now, as they're proving so useful in situations like this.
Regards, Paul.
Just published
“Microsoft (NASDAQ:MSFT) has resolved a major outage that hit its cloud platform in the Central U.S. region and Microsoft 365 services worldwide. The Azure outage led to several low-cost airlines delaying and canceling flights.
The outage began around 6 pm ET on Thursday, impacting Azure services including failures with service management operations and connectivity. While most services covered, a small subset is still experiencing residual impact.
"A backend cluster management workflow deployed a configuration change causing backend access to be blocked between a subset of Azure Storage clusters and compute resources in the region," Microsoft (MSFT) said in a status update. "This resulted in the compute resources automatically restarting when connectivity was lost to virtual disks."
The company also noted that users around the world couldn't access Microsoft 365 apps and services, and resolved the issue overnight.”
Sounds like a complete ‘backend cluster Ffffudge’. Who writes this stuff!?
Just as a quick reminder. Assuming we're still all waiting for the daily RNS' to be released, then I'm interviewing Roland Head live here this morning at 9.30am.
Where he's kindly taking questions from the audience.
Morning Paul,
Firstly just to add my appreciation of your and Graham's extensive output, both quality and quantity. not forgetting Roland. Very well done. As I have previously said the SCVR is worth the Stockopedia subscription fee on its own.
Secondly as a previous holder of Portmeirion (LON:PMP) I was wondering if you might expand your thoughts on the potential turnaround? I know he company reasonably well but one of my main bugbears has been the paltry number of shares held by the management team, especially Mile Raybould, the CEO.
All the best
The market should not have opened today. Should have been delayed until all participants have the same information available and all issues sorted.
All the best
Fair point yiannos.
As a $MSFT holder (in my coffee can fund), I'm feeling embarassed this morning. Someone's career has come to an abrupt end!
As a $MSFT holder (in my coffee can fund), I'm feelling embarassed this morning. Someone's career has come to an abrupt end
Firstly, it’s only speculation that Microsoft is to blame for the outage. However, should that prove to be true, I’d argue that it makes a strong case for loading up on Microsoft shares. Firstly on the grounds that this incident underlines just how central is the company to the entire fabric of the global economy. And secondly to recognise just how rare such incidences have been - a credit to their technology.
The news now seems to point to a Crowdstrike Holdings (NSQ:CRWD) issue. I hold and I am not looking forward to the US market open!
The news now seems to point to a Crowdstrike Holdings (NSQ:CRWD) issue. I hold and I am not looking forward to the US market open!
Seen down double digits, but these things tend to blow over. I’m a holder too so it could be the curse of BnB and therefore more long-lasting. Nevertheless, are you just in for this month, or for the long term?
Potential buying opportunity
I held Crowdstrike Holdings (NSQ:CRWD) until about 6months ago when I sold out of a lot of my US shares too early. Looks like it could take a hefty fall today, 20-25% would not be surprising. However, it is likely to be a nice opportunity to buy back in more than anything. BnB is right, these things will blow over eventually and the price will move back up.
There must be huge and currently unquantifiable contract liability. I am not so sure, Crowdstrike Holdings (NSQ:CRWD) will bounce back so quickly.
Crowdstrike Holdings (NSQ:CRWD)
How do you know that?
Gails Bakery is also down, shows how serious this is!
HL and AJ just started working it seems
It will be interesting to know if any brokers are still down ?
Chapel Down (LON:CDGP) An unusual source of reliable financial news, but The Sun carried this story about a possible buyer for Chapel Down Group
https://www.thesun.co.uk/money...
After publication a Treasury Wine Estates spokesperson: “We can confirm that Treasury Wine Estates is not participating in the sale of Chapel Down wines”.
Barclays Smart Investor platform is down ?
Imagine if a company you worked for had an awesome announcement out today, you could just load up first legally
Sky News live broadcast off line blaming Technical issues IT Disruption is spreading
Now Breaking with the always slightly slower BBC
The outage has been blamed on an update to the CrowdStrike security software, causing an issue with Windows software. Microsoft, the US tech giant, was not immediately available for comment. The IT issues have also affected businesses in countries such as Australia.
Going to be honest, I think Renold (LON:RNO) might have taken one for the team in some of the criticisms of its share option accounting.
Ever since IFRS2 was introduced 20 years or so ago, companies with employee benefit trusts will have been accounting for market share purchases through reserves and not the income statement. Ever since IFRS2 the income statement has been hit instead with an actuarial (i.e. complicated statistical) type calculation of the estimated cost of the schemes for the company - the cash cost would never reconcile with this.
So if there’s criticism on Renold (LON:RNO, it should focus on the quantum. Here again, just because the employee benefit trust has bought shares in the market doesn’t mean they will all end up with the directors. Some might go to staff more generally, some might never get awarded and just sit in the trust. You really need to look at the directors remuneration report to see what they have each been granted, and what is likely to then actually vest, when it eventually comes out in the annual report.
It’s complicated but it’s more to do with IFRS2 than Renold (LON:RNO) specifically I think.
That said, there are other things going on at Renold (LON:RNO) that concern me more. I think they are opaque about the benefits to revenue and profits their more recent acquisitions have brought. It should be easier to see the organic growth. And whilst other companies have been finding ways to get the pension payments under control in a higher interest rate environment, Renold (LON:RNO) stands out a bit by having not done so. Having watched the capital markets day session a while ago (which is a worthwhile use of 2 hours for anyone interested in the company), I’m not sure I really rate the CFO.
Really good reflections on Renold (LON:RNO) thank you M48. Do you have a link please for the capital markets day presentation?
My 2p worth: looking at the company's progress overall, I was struck by what a turnaround its been - credit to Paul for drawing attention to this.
The way asset backing has been restored (well, created from zero) is genuinely impressive.
For next year, I do not see how this can be right:
The company has shown it can restore margins - it achieved higher operating profit on lower sales in 2024 against 2025. That's an improving trend, so should be stronger still in the current FY. Yet the forecast says that we will have marginally higher sales in FY25 with lower profits. Seems to me that leaves room for upgrades during the year. Also, FY2024 sales were affected by currency headwinds and destocking. Those fluctuations may just as easily go the other way next year, they are noise rather than signal.
Ultimately though, trust in management is essential and the opacity of share-based rewards has definitely shaken that trust. Hence I'd appreciate the time to review that capital markets day. Thanks!
It’s here if you scroll down the investor homepage I think
https://investors.renold.com/
Thanks M48, good points. As with other companies, RNO will be following the accounting rules, so I wasn't suggesting there's any skulduggery. Just that the potential dilution shown in the notes to the accounts seems excessive, and the accounting treatment (which as you say is not chosen by them) does tend to hide what's going on, being buried in notes to the accounts.
Bottom line, it's over £9m in cash gone from Renold's bank account, to buy RNO shares, earmarked for eventual gifting to Directors (and hopefully some other staff too). So we need to be aware, and make an adjustment to the company valuation, I think lopping off about 10% from what I would otherwise have valued RNO shares at looks reasonable.
It's still an excellent company, and reasonably priced share though, so I don't want people to think I'm ringing alarm bells, or to panic sell, etc, I was just flagging an interesting situation.
Regards, Paul.
TBH, I am as concerned about the disingenuous way Renold (LON:RNO) addressed the share options on Wednesday's zoom meeting, as costing investors nothing (as they'd already bought the shares) and implying there won't be any more of them (really?), as I am about its existence.
In terms of not receiving the information we need as investors, I was also struck by the way we were hit by 20 odd slides of largely meaningless data (in big picture terms), but provided with no detail on:
- the YoY performance of the existing business in terms of sales and profitability (a positive story at least in terms of margin)
- the impact of acquisitions
Most (all other?) companies provide this information as a matter of course so we as investors can get some feel for what's going on. So why not here?
I am pretty sure management are doing a decent job of turning round the company, albeit in a difficult market, and phrases like "inflection point" sound very positive about the future.
So why treat shareholders so badly in terms of basic information? And if we are not getting this information, what information might be hidden in the future?
On a separate tack, does anybody understand how the UK pension deficit is definitively elimated by 2031?
It's potentially going to be an interesting start to the UK markets today.
Companies have already released their 'price sensitive' updates into the UK's RNS system, but the outlet pipe to investors is clearly blocked.
As such - assuming the problem isn't resolved by 8am - then would anyone trading on this 'non-public' information be deemed as breaking the standard insider dealing rules?
Are you saying LSE should delay opening today until RNS issue resolved?
Agreed - someone has blocked the RNS outlet pipe
*LSEG INVESTIGATING TECHNICAL ISSUE REGARDING RNS ANNOUNCEMENTS
Microsoft Azure (i.e. their cloud ) is down for some reason.
https://downdetector.co.uksta...*y0z6ln*_ga*MTAyNTA4NzUwMC4xNzIxMzczMDQz*_ga_0PZM58H213*MTcyMTM3MzA0My4xLjEuMTcyMTM3MzA5OC4wLjAuMA..
Morning all. Paul and Graham, can I just add my voice to the clamour of appreciation for your efforts this week? Not just for the breadth and depth of the commentary, but for your willingness to pursue particular questions, such as the management remuneration at Renold, right to the well-disguised truth. Enjoy a well-earned weekend break.
Echo that. Will be interesting to know how rife this is. Have the RNO board been asked for comment?
That's very kind, thank you! We do appreciate feedback, very much.
I think the brief comments in the list of companies reporting is a good innovation, as we can get the main points up for lots of companies in the first hour, then focus on the most interesting stories after that, and we're closely following the "most viewed" list on the Stocko home page, so we write about (mostly) what you're collectively looking at. Constant improvement, hopefully, that's the aim :-)
Now I just need to keep nagging Ed to give me a third writer, and have Graham for more hours! It's dependent on subscriptions rising though, due to budgetary constraints.
Still very much a labour of love for me - I write these reports mainly because I enjoy it, and the discussions here, although getting paid is also quite useful ;-)
Still no news at 07:22, very unusual. I might start work on a backlog item. There will be a full report up by 1pm regardless.
Best wishes, Paul.
Might be connected ? US Airlines have had IT Issues and now Australia (suggested a possible link to a Microsoft 365 upgrade) https://www.bbc.co.uk/news/art...
An official Microsoft 365 service update posted to X earlier in the day said " we're investigating an issue impacting users ability to access various Microsoft 365 apps and services".
Paul. I converted from monthly to annual sub yesterday on the back of your #RNO work. I bought in 2021 (at 26p) after you highlighted them (at 14.5p) on a stock slam. I exited yesterday at 56p after your latest comments. Thank you.
Slow RNS day. Take a well deserved day off Paul
Looks like the RNS machine is broken
Yes it's very quiet. Too quiet! Something's gone wrong. I've made a list of backlog items to cover, so there's plenty for me to do here, then 5 tinnies left over in the fridge, ice cold, as my reward for later :-)
Looks like the RNS machine is broken
Refinitiv terminal is down and so is my banks research feed. The gremlins are in control.