Small Cap Value Report (Fri 2 Dec 2022) - PMI

Good morning from Paul! There's hardly any news today, and I'm suffering a bit from having my covid/flu jabs yesterday (nothing serious, just a bit groggy), so apologies for this report being a bit sparse.
Agenda -
Paul's Section:
Premier Miton (LON:PMI) - full year results for this fund management company. Very simple accounts, and this share looks attractively cheap on a PER basis, with very generous divis too. Balance sheet is adequate, but not a huge amount of asset backing. Thumbs up from me.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Premier Miton (LON:PMI)
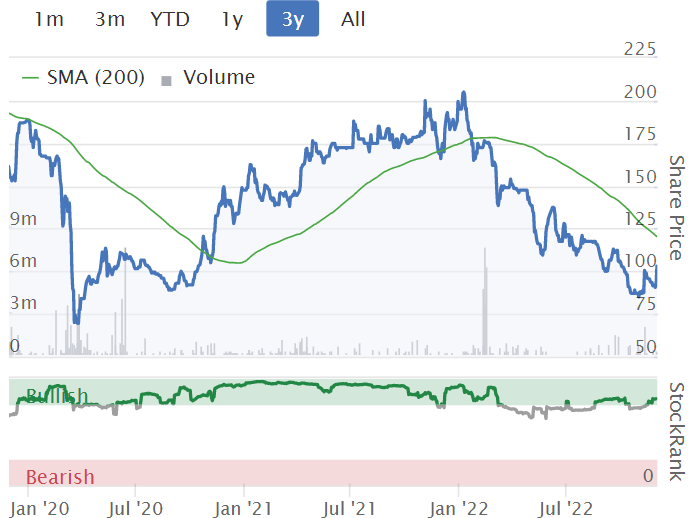
106p (up 16% at 09:03)
Market cap £154m
Premier Miton Group plc ('Premier Miton', 'Company' or 'Group'), the AIM quoted fund management group, today announces its final results for the year ended 30 September 2022.
Graham normally covers this sector, and has been flagging up lots of cheap brokers & fund manager shares of late. Obviously they’re cyclical, and earnings drop when markets drop. As we’ve discussed here before, it makes sense to buy these cyclical shares when sentiment is on the floor, then sit back and enjoy (hopefully) a share price recovery, and a decent flow of divis.
Some key numbers from PMI today for FY 9/2022 -
Assets under management (AuM) fell from £13.9bn a year ago, to £10.6bn at 30 Sept 2022 - of which £1,076m was client outflows, with the rest being market falls.
Better news is that in the most recent 2 months AuM has started rising again, reaching £11.3bn at 25 Nov 2022, with net inflows returning.
Adj PBT held up quite well considering what an awful market it’s been, falling from £28.6m in FY 9/2021, to £24.3m in FY 9/2022.
Adj EPS is 13.8p (LY: 16.5p)
Adjustments - these need to be carefully considered - particularly share based payments of £4.5m this year and last year. I’d say that’s staff remuneration, and it’s significant at 18.5% of adj PBT. So investors might want to add back that cost, which reduces adj EPS to 11.25p - I’d use that number to value the shares, giving us a PER of 9.4 - which still looks cheap.
Dividends - very generous, at 10p for the full year, giving a lovely yield of 9.4%, although future divis can't be guaranteed.
Balance sheet - looks OK, although once the intangible assets are removed, NTAV is £34m, so not a huge amount of asset backing for a £154m market cap. It would be worth looking at other shares in the sector, to compare this.
My opinion - this looks excellent value, so it gets a thumbs up from me.
The StockRank is good, at 80.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

47 comments
Micro-transactions in shares
Many thanks to all of you who took the trouble to respond to my query. There are clearly several explanations, and I feel much enlightened by your explanations.
Good w/e to all.
Richard
Paul - Thanks for doing the Premier Miton (LON:PMI) analysis when you are not feeling good.
I bought Jupiter Fund Management (LON:JUP) after reading Graham's analysis and that has worked out well so I think Premier Miton (LON:PMI) may also be a buy for my income portfolio. I never considered it until now because a lot of their funds strike me as being mediocre, but if customers are still coming through their door they must be doing something right.
for those interested in Directors' purchases, CEO of Real Estate Investors (LON:RLE) just purchased £1M's worth (and FD bought £280,000) : https://www.stockopedia.com/sh...
Those guys have a tight focus on Midlands real estate, so I see that as a very bullish signal.
Looking just now it is 30.9p to add so having got at 28p they have done well, or had someone who was wanting out!
Tommy
Ps. I hold Real Estate Investors (LON:RLE)
Thanks for your note, not looked at this share before but following your note looked at this over the weekend and today I now hold.
Friday wiffle
So after a loss of confidence and a pretty much total capitulation following the Truss/Kwarteng after party to which I was not invited or maybe the invitation will turn up sometime next year? I admittedly sell on a defined drop from purchase or peak which I have done since spring/summer 2020 (lesson learnt of holding losses and watching them go down further and further and further and thinking that Mx Market was going to realise they were wrong and come back one day or maybe not when I looked back).
I have slowly been starting to build once more - is that time for the Bear to Roar once more? - my ISA and my Mum's ISA (Pension but in ISA not SIPP), will start on my sister's ISA next week.
Some are obvious repurchases at a higher price of what was sold, and others starting to create a more diverse portfolio, or at least having a greater number of holdings at a lower percentage for now. So whilst more purchase costs (fee+ stamp) overall keeping smaller holdings for now, remaining ~50% cash, but with the mind that actually price drops for a fundamentally good company, such as Legal & General (LON:LGEN) or Redde Northgate (LON:REDD) is a top up opportunity rather than a sell protect capital stance. This is trying to get back to a longer term view after several torrid years in terms of family, work and investing.
Would this be a "buy the dip" or just me trying to reduce the nervousness and sell trigger on volatile days?
So first question, being with IWeb (cheap but usually does what it says on the tin) some of the holdings are now unavailable, as apparently they are now unsuitable for a retail investor, such as Twentyfour Select Monthly Income Fund (LON:SMIF) or NB Global Monthly Income Fund (LON:NBMI) so predominantly monthly income or higher yield products, but there are others too as I find them I add them to the list. I am thinking to move some of the money to a different provider but want to work out who actually lets you purchase this stuff as don't want to go through the transfer hassle to find that I have the same problem again... Any thoughts on the likes of Hargreaves Lansdown (LON:HL.) or AJ Bell (LON:AJB) or others? Can you find out what providers let you buy before you open an account and fund it or does anyone hold things like these with another account?
Second question, does anyone else have any monthly income products they hold or have held or have looked at? Not looking for tips just stuff that I can put on a list to research whilst my wife is at book club tomorrow night and see if any of them can be got through IWeb.
Wiffle over
Tommy
Ps. I hold Legal & General (LON:LGEN) & Redde Northgate (LON:REDD)
I attempted to buy both of the products your mention in my HL account. You can buy them both, but the following message comes up before you can purchase - 'To buy this complex investment, you need to complete the General Complex Investments questionnaire. This is so we can be sure that you understand the risks involved'.
Thanks John
Good Day Tommy,
I hold NBMI and SMIF with Jarvis x-o, It was no problem purchasing a substantial amount of them in an ISA and/or SIPP, low charge and reasonable spread, although that was a few years ago.
Thank you
I had bought a long while back too, but sold along with everything else. So hence having to go through the you let me hold this for years, I used to be able to buy but cannot now what is going on??? Do you not communicate withdrawal of things to existing holders? Etcetera etcetera. But having looked wider more things are not available to buy, ok some of them I can kind of understand but at the same time it is thinking maybe time to split the funds and use someone better.
Cheers
Tommy
I was looking at bond trusts a few weeks ago and found NB Global in particular held a lot of B & CCC rated which is junk category I believe and TwentyFour held a lot of BB & B still in the speculative rating. Maybe this is why they have restricted the purchases of these trusts. Henderson Diversified Income & Invesco Bond Income Plus looked to hold higher quality bonds. Caveat I know very little about bonds just a general opinion on reading each of the trust documents.
Thank you Danto
Similar, I am not in anyway an expert at Bonds, or even very knowledgeable, but slowly learning more. I know that some of the holdings have higher risk bonds so BB and lower rating, and hence part of the research is understanding the discount to par offered, the typical default history, the number and spread of holdings and all that and then most importantly keeping to a small position (~1%) with a manual capital loss protection in place (up to the last couple of months this was down 20% from purchase or peak).
Though no doubt if I dig deeper there will be overlap between the different funds purchased all seeking the same yield, a bit like anything FTSE Income will typically hold British American Tobacco (LON:BATS) for example.
I hold Invesco Bond Income Plus (LON:BIPS), well mum does already.
I have some other Henderson Funds such as Henderson Far East Income (LON:HFEL) and Henderson High Income Trust (LON:HHI) I will have a look at Henderson Diversified Income Trust (LON:HDIV) tomorrow evening. I need to remember to also look at the bottom right for the similar things too.
Cheers
Tommy
I hold Invesco Bond Income Plus (LON:BIPS) Henderson Far East Income (LON:HFEL) & Henderson High Income Trust (LON:HHI)
I hold Twentyfour Select Monthly Income Fund (LON:SMIF) and similar in an Interactive Investor ISA with no problems.
Hi Tommy
This article explains General Complex Investments quite well and when you have to compete the form.
https://medallionguarantee.co....
I was recently asked to complete one because I held a couple of ETFs and Oakley Capital Investments (LON:OCI) which is a private equity investment trust.
Thank you
TommyH and others who’ve posted on Investment Trusts today:-
1. They are not complicated or dangerous investments (except for obscure sectors). They are similar to but usually FAR superior to the much more popular Open Ended Funds/Unit Trusts. Since they have portfolios just like ours, they are less dangerous than any single share as if a share they hold goes badly wrong the loss is mitigated by all their other holdings,
2. The need to sign that risk form is a technicality. It’s very quick and easy to do. Use your common sense and give the answers that means your application will be successful. E,g yes to being experienced or whatever with Investment Trusts.
3. They are usually very easy to buy and sell and are traded in exactly the same way as shares.
4. Investment Trusts are a great way of investing all round the World and for high dividend sectors like UK Commercial Property.
5. I haven’t the time to post regularly or in detail here.
www.michaelwalters.com
has a lot on Investment Trusts including an Investment Trust portfolio that has been running for several years and includes a wide range of Investment Trusts. That portfolio doubled before the market falls this year but is still up 75%.
Michael Walters’ site is run by ex Deputy Daily Mail City Editor. He favours very high risk shares as do a lot of his subscribers but there’s also a thriving thread on Investment Trusts. Though it’s a subscription site (£70 a year) Mike usually allows potential subscribers to try it for a ŵeek or so.
6. By FAR the best site for Investment Trusts is the aic site run by the Association of Investment Trusts.
Here’s a link that gets you in to the Country Specialist sector:-
https://www.theaic.co.uk/aic/f...
I’ve chosen it as it includes the 3 Vietnam Trusts which I’ve held for much of the last 10 years as it’s a young and fast developing Country and is now attracting ever more big US and other Companies switching from China.
Just click on each Trust for a wealth of information including performance, Announcements (e,g brilliant monthly fact sheets etc etc.
DO check out the discounts to NAV. This is just one of the big plus points for Investment Trusts. Unlike Open Ended Funds they can be bought for less than they are worth and sometimes way less!
e.g Phoenix Spree Deutschland (LON:PSDL) which I bought recently is on an extraordinary near 50% discount to Net Asset Value. Phoenix Spree Deutschland (LON:PSDL) invest in Property in Berlin. Temporary problems and that explains the huge discount to NAV but longer term very positive (check out Announcements). Phoenix Spree Deutschland (LON:PSDL) used to trade at a premium to NAV.
And then do the same for every other sector and Trust that you want to follow up.
e.g The UK Equity Income Sector here includes Trusts that have been in existence since the 1800s! And a few have increased their dividends for more than 50 years in a row. e.g £CTY
https://www.theaic.co.uk/aic/f...
Finally you asked for monthly dividend payers. Here are 3 of them (again easy to check out on aic)
Twenty Four Select Monthly. TwentyFour Income Fund (LON:TFIF) 8.5% dividend
NB Global Monthly Income. NB Global Monthly Income Fund (LON:NBMI) 7.3% dividend
EDISTON Property £EPIC 7.8% dividend
Adding a bit more to my previous post.
Though the Stockopedia stock pages for each share are so useful for shares they are not imo for Investment Trusts as they don’t and can’t cover things like discounts to NAV and whether the current discount is narrower or wider than usual. (As always happens in bear markets a lot of Trusts are on wider than average discounts at present, providing great buy opportunities as there’s the double plus of an increasing share price in time being given an added boost by a narrowing of that over large discount).
Also the Investment Trust stock pages do not cover must know things like the Top 10 holdings for each Trust. Or say for Commercial Property Trusts any detail on their Property Portfolios (e.g retail and if so with big names like Aldi or Next or retailers in trouble). Or mostly retail parks (good) or mostly High Street (not so good) or Offices or Warehouses etc etc. Nor do the stock pages cover must knows like rental collection figures.
Hence the suggestion to use the aic site which covers all that and much more on top.
I subscribe to Stockopedia and Sharepad, with key reason for continuing with Stockopedia being the brilliant small share value reports and subsequent comments.
But only investing in UK smaller Companies is far too narrow imo bearing in mind how so many Markets often perform much better than ours. e,g US and Vietnam for starters. And what about Emerging Markets?
Paul Scott is a fantastic commentator and analyst and it’s worth subscribing just for that and to take advantage of his extraordinarily detailed understanding of balance sheets. But Paul freely admits he is not clued up on Investment Trusts or sectors like Commodities. I think he and others are missing out and would vastly improve their own investment performance by branching out more via Investment Trusts,
e.g Quality Commodity Investment Trusts like Blackrock World Mining Trust (LON:BRWM) CQS Natural Resources Growth and Income (LON:CYN) and Blackrock Energy and Resources Income Trust (LON:BERI) have superb performance records and pay big dividends too. And Black Rock World Mining Top 10 holdings include large stakes in the major miners like RIO and Glencore etc. I’ve held all 3 for years.
Just to add to this, holding Investment Trusts (CEICs) as opposed to Investment Funds/Mutuals (open ended) can work out far far cheaper if holding with Hargreaves Lansdown:
If held in a SIPP or ISA, HL charge 0.45% pa.
This is capped at £200pa or £45pa respectively for investment trusts or shares.
There is no such fee cap for holding funds (which are surprise surprise, heavily promoted by HL!!!) - the fee is 0.45% on the first £250k of your holding then 0.25%.
So, if I held £250k in investment trusts and/or shares in my SIPP it would only cost me £200pa, and in my ISA only £45 so £245pa to hold £500k.
If I held £250k of mutual funds in both my SIPP and ISA it would therefore cost me £2250pa.
If my maths is correct (which it might not be!), that difference of £2005pa (2250-245) compounded over 15 years at, say 7% with the yearly 'fee saving' of £2005pa added each year, makes a difference of nearly £60k - not insignificant!
HL do very very well from people holding funds rather than investment trusts.
Also beware the 'Costs' tab on the individual fact sheets for each share or fund on the HL website - the assumptions made are often incorrect and do not reflect HL's fee structure as detailed above. Investment trusts are usually shown as being more expensive to hold than they actually are - obviously this benefits HL and their push for people to hold mutual funds.
mjfgs
Exactly. You’ve shown a key reason why the likes of Hargreaves Lansdown rarely if ever promote an Investment Trust. Yet Hargreaves happily promoted that disastrous Woodford Open Ended Fund until the very day it was suspended for good. Woodford incentivised them well.
Investment Trusts are better than Open Ended Funds for many reasons, including better performance overall.
A key negative with Open Ended Funds is in bear markets. Unlike Investment Trusts they have to sell or part sell their holdings to pay out investors who want out once they’ve run out if cash held to cover that. Investment Trusts never have to sell any of their investments however large the selling gets. Instead the Trust goes to a big discount …which provides buy opportunities for clued up investors. Unit Trusts/Open Ended funds always trade at NAV. I.e if the Unit Trust NAV is £1 investors buy at £1. If an Investment Trust NAV is £1 but is (like Phoenix Spree Deutschland (LON:PSDL) now) at a 50% discount then investors can buy at just 50p!
A very good example of this is with Property Open ended funds. Whenever there is heavy selling they cannot suddenly sell properties to pay out leaving investors. So they have no alternative but to ban all selling by locking their investors in and they are unable to sell for several months sometimes! But Property Investment Trusts just go to very wide discounts to NAV when there is heavy selling. That’s just happened and hence there are some extraordinarily large discounts in the UK Commercial Investment Trust available right now. See here for more and see that 5 of them are on discounts above 40%!
Look at those big dividend yields too!
https://www.theaic.co.uk/aic/f...
As it is a quiet day, can I raise a subject which may be tangential to small caps but which has been perplexing me?
When I look at at share transactions in a company (esp small caps) I see a surprising number of vey small transactions (betwen 1 and 5 shares, often 1). In times gone by someone might buy such small amounts to entitle them to attend the AGM so that they could berate the chairman, complain about non-executive fees, the costs of the audit, or to make political points, but I see too many small transactions these days for that to be a plausible reason.
Could it be market makers trying to establish a price for shares (or, perish the thought, a false price)?
I would be grateful if someone could enlighten me.
Richard
They could be automatic bids, ie you put in a price to buy shares at say 59p, the mid price is 62p, this order may get partly filled with small amounts. Happened to me when I did an order at low price. 1 share is generally no use to me.
Would not be very happy paying £4.95 for a trade getting 5 when I asked for 1000! but that has happened to me once, and I thought it was my fat fingers :-D maybe not.. I'm not sure these are the trades Richard is referring to in an upward trend as it tends to be the most someone has paid....inversely then yes perhaps, but there tends to be two or three in succession which makes me think not.
I pay £3, sometimes I got around 50% of my order at a really good price, ie the selling price but then I got some 1 share trades so I stopped it on UK stocks, pity you can't put in a minimum order. On US stocks I only pay 0.5%, so it is fine if I pick up 1 share, usually their prices are much higher than uk stocks.
Some brokers have a fill or kill trade option. Either it completely gets filled, or the trade doesn't get executed. You set a limit price.
Yes HL have that. HL only fill whole orders, IG fill orders at your price which maybe only 1 share.
I'm with DEGIRO. If I place a tight limit order on a GTC basis it will sometimes fill in dribs and drabs over several days and individual share purchases are not uncommon as part of the transaction process. DEGIRO charges a single transaction fee (currently a flat £2.58 for stocks listed on the LSE) irrespective of how many parts the trade actually breaks down into.
Could it be market makers trying to establish a price for shares (or, perish the thought, a false price)?
Indeed it appears to be someone trying to hold up or depress a price, and the quantity of the previous few share transactions should be checked as they can give a momentary false prospective on the trend...although if long term investing it's a little less critical....put every penny helps of course.
Good luck!
I do hate to spoil good conspiracy theories, but the more likely answer is that some small shareholders may have set up DRIPs on these stocks....i.e. asked their platform/broker to reinvest their dividends?
I do hate to spoil good conspiracy theories, but the more likely answer is that some small shareholders may have set up DRIPs on these stocks....i.e. asked their platform/broker to reinvest their dividends?
That happens, but I don't believe this is what Richard is referring to, if you watch the trades on level 2 you will see its timed to support or depress a share price within the range, and happens when shares are close to peaking or dropping, often with multiple single share trades, paying the very highest or very lowest price within a range,
It doesn't bother me either way, and when you are hunting a share which is on a pull back these transactions actually help, but if you are trying to chase a rising share these small trades can be a curve ball because they are pushing the range and can be a red herring, for what you should be paying. Wait and the price will reset, unless some numpty keeps ramping it.
It's just what I have seen and my own opinion...I have never dug to find out more, and have seen it so often it's just the norm, although the timing of these trades makes me think it is more than just a coincidence...
Very small trades will just hit the extremes of the bid/offer spread - market makers don't really want odds & sods in illiquid small caps so their automated quote algorithms will just just price as wide as possible, rather than seeking to quote closer to mid to persuade the client to execute. There often isn't a human involved.
That's not to say you don't get some funnies when there are options in the background...
We used to get shareholders selling their shares xd. Then they would receivea share or 2 shares and just off load them. I am not saying this is the whole reason but it wasn't uncommon.
Could it be that some platforms do not charge for trades so buying very small numbers is not prohibitive. I think, but may be wrong, Trading 212 does not charge for trading where as HL charges £11.95 per trade.
On some of the small caps I watch these low volume trades come from the numerous trading platforms out there that charge zero dealing fees, the rub is that they will typically transact at the full bid / offer
some of those small trades will actually be spreadbet buys or sells
Premier Miton (LON:PMI)
very good results in the circumstance - annoyed with myself for not buying more on the bell (I hold)
25% of market cap in net cash.
In a very poor year for assets still managed 13.8p adj eps
After market falls and outflows damaged AUM by £3.3bn it has subsequently risen £700m between y/e and end Nov - so now appears to be reversing declines
almost all funds in 1st and 2nd quartile for performance should help with both retention and inflows as markets normalise.
Divi is circa 10%
Asset managers usually trade around 13 - 15 * on historic standards whereas Premier Miton (LON:PMI) trading on 8* even after todays rise.
In terms of fund performance, it depends what time period you're looking at - several of their key funds have been really poor recently and bottom quartile over 1y (retail fund investors tend to be quite short term so this probably won't help in terms of attracting new inflows).
You have to look at 3-5 years. Basing an investment decision on a 1 year performance is like comparing apples to oranges. Investment horizons are completely different.
In my experience retail investors may well be very short term in the stocks they own but less so in funds, which is what I think we are seeing in the reversal from outflow to inflow in the last 2 or 3 months.
The 3-5 year figures don't look anything special either to be honest, with one or two exceptions. In the headlines they mention that 87% of funds are 1st or 2nd quartile, but this relates to the track record since launch or fund manager tenure - there is probably some survivorship bias in here as poorly performing FMs are more likely to have been axed or the funds simply closed.
Overall not particularly impressed with their performance or their fund range (why do they need about 10 UK equity funds?) although I guess this is reflected in the bargain price so not saying this is a bad investment.
SCS (LON:SCS) (I hold) CFO to step down. 12m notice period and will remain to facilitate handover. No reason given. As Mr. Contrarian would say, 'He is not thanked' - but maybe that comes later. SP unch.
I owned SCS (LON:SCS) some years ago pre current CEO. I liked the CFO as I thought he had a very strong operational and value creation understanding of the business and was quite hands on in an almost COO like way as well as CFO...more so from a equity investors perspective than the old CEO (who was a great retailer sort but didn't seem to have regard for the equity vehicle his biz was contained in). It was evident to me that he wanted to be CEO's replacement and that was why he joined (as well as being back home).
It wasn't the main reason I sold but it was a contributing factor (main reason was capital allocation errors being made). It suggested something odd IMO re the exec mgt.
Morning Paul/Graham, perhaps you might review yesterday's acquisition of Location One by Facilities by ADF (LON:ADF), time permitting.
Hmm is it me or does PayPoint (LON:PAY) now have fewer backers for Appreciate (LON:APP) takeover? On 7 Nov they had irrevocable undertakings and letters of intent from 23.2% of shareholders. Today says 19.21%. Presumably some selling out before today? On plus side PayPoint (LON:PAY) might need to up their offer. (I hold Appreciate (LON:APP))
Some interesting moves on the Appreciate (LON:APP) shareholder list post the takeover offer from PayPoint (LON:PAY) nb I am long both
Interesting on Appreciate (LON:APP)
Looking at the shareholder register, it looks like the maximum is 2 out of the top 5 shareholders supporting it so far. Not great for Paypoint. Top 7 shareholders hold 62% so they have some collective power in their hands.
On the other hand, Paypoint pulling their offer will see this crash to 30-35p is my guess. So there's some risk, holding out for an offer which I don't think likely to go above 50p.
(I hold in the Boon Fund)
Samson Rock who have taken a 14.75% interest in Appreciate (LON:APP) post takeover offer are gradually increasing their short in PayPoint (LON:PAY) nb I am long both