Small Cap Value Report (Fri 2 Feb 2018) - Share tips, NTBR, MAI, FCRM, MOS, PURP, KWS

Good morning!
Thanks for your suggestions - they are a key element in my decision-making.
Today on the radar we have:
- Northern Bear (LON:NTBR) - trading update.
- Maintel Holdings (LON:MAI) - trading update.
- Fulcrum Utility Services (LON:FCRM) - acquisition.
- Mobile Streams (LON:MOS) - trading update.
- Purplebricks (LON:PURP) - trading update.
- Keywords Studios (LON:KWS) - trading statement (from yesterday).
Cheers!
Share tips - I thought I'd add a few comments on my thought process when shares in my portfolio are tipped in the mainstream press, as happened this morning.
Two of my shares, Record (LON:REC) and PCF (LON:PCF), were tipped for the first time by the Investors Chronicle, as "Bargain Shares" for 2018.
For the avoidance of any doubt, this was bad news as far as I was concerned. I didn't want their share prices to go up, because I had absolutely no plans to sell them and in fact I had been hoping to buy more shares in PCF (LON:PCF) very soon.
One attitude to take is that it doesn't matter, because anyone who buys shares on a magazine tip probably doesn't know very much about the company, and will be a seller in due course. Some investors even sell into these tips, because they are so confident that the share price will retreat over the coming weeks and months, enabling them to buy back in at a profit.
For me, though, having researched a company, I don't want to take the risk that the share price doesn't come back down, with the result that I never get to buy as many shares as I originally planned.
So I went ahead and bought my last slice of PCF (LON:PCF), getting the full quantity of shares that I was originally going for.
I had to pay a bit more than I intended, but it would be much worse if the price continued rising, and I never got them.
My particular concern with PCF is that there are only about 50 million shares in the free float (depending on how you count it), i.e. the free float has a market value of less than £15 million. That's not much value for a small number of investors to scramble for simultaneously.
The full list of shares tipped was as follows: MPAC (LON:MPAC), Crystal Amber Fund (LON:CRS), Shore Capital (LON:SGR), Conygar Investment Co (LON:CIC), PCF (LON:PCF), Titon Holdings (LON:TON), Parkmead (LON:PMG), Sylvania Platinum (LON:SLP), U and I (LON:UAI) and Record (LON:REC).
Northern Bear (LON:NTBR)
- Share price: 81p (+24%)
- No. of shares: 18.5 million
- Market cap: £15 million
This is a tiny company even by our standards, but it's one we've commented on twice over the past year.
Based in Newcastle, It provides specialist building services, predominantly to the public sector - local authorities, housing associations, NHS trusts, etc.
These services include roofing, solar panels, fire protection, health & safety, etc.
Today, it reports that the good times continue, with a positive trading update for quarter ending in December 2017. Turnover and "adjusted profit before income tax from continuing operations" are ahead of management expectations.
The outlook remains strong, "subject to there being no exceptional adverse weather conditions over the remainder of the winter period".
As noted previously, this stock is a favourite of the StockRanks:

Examining the share price performance, there has been surprisingly little progress over the past six months (today has gone a long way toward rectifying that, naturally):

Recent share price weakness maybe have been related to the Carillion (LON:CLLN) fallout. Today, we also get reassurance that there has been no "material direct impact" from this, and the company doesn't know if there will be a material indirect impact.
If I was to try to guess, I would have thought that contractors will at least in the medium-term be marginally less willing to bid too cheaply for public contracts, having witnessed the disaster suffered by Carillion and its suppliers. Perhaps contractors will have a little bit more pricing power, going forward?
Northern Bear's interim results, published in November, showed PBT from continuing operations of £1.3 million, flat against the prior year (incidentally, the company remarked at the time that it was being "careful" in terms of contract selection).
There are no broker forecasts available to me, but today's update strongly suggests that the full-year result this year which will prove better than FY 2017, i.e. that PBT from continuing operations will excelled £2.4 million.
Conclusion - the shares are obviously in "bargain" territory, although this is what you'd probably expect for a small building services contractor.

Management appear to be highly competent and executing well, and investing here is probably a bet on the management more than any other factor. That's the factor which I'd be most curious in, if I was investigating this further.
Edit - A holder of Northern Bear has posted their thoughts in Comment #20, in the comment thread below. As they appear to be very familiar with the management style and the company's divisions, I'd recommend taking a look at this comment for more insight.
Maintel Holdings (LON:MAI)
- Share price: 775p (+11%)
- No. of shares: 14 million
- Market cap: £110 million
This is not a company I've covered before. Checking the archives, I see that Paul has occasionally written on it.
It provides "managed services", i.e. it manages communications/IT systems for businesses:
Our core business is about enabling people to work together more effectively.
Checking the archives, I see that there was a profit warning in December. Paul is not a fan of the sector, reckoning that smaller telecoms & cloud companies such as this do not have a sustainable earnings stream, as technology changes and as prices for their services deflate over time.
This update on its face is fine. After downgrading expectations on 6 December, today it says that trading for the full-year ending 31 December is in line with those expectations. I should hope so!
Adjusted EBITDA for 2017 will be c. £12.5 million, at the bottom of the £12.5 million - £13 million range which had been presented.
This is the important bit:
The Board remains confident in delivering substantial growth in revenue and EBITDA in the full year to 31 December 2018.
Adjusted EBITDA was £12.6 million in 2016, and then £12.5 million in 2017, as announced today. Brokers are targeting adjusted EBITDA of £16.9 million in 2018.
I think my concern is that the organic growth rates, excluding the effect of acquisitions, might not be very big. In 2016, the organic growth rate was just 1%. There was another acquisition in 2017, though on a smaller scale (£5 million deal size).
Unfortunately, I don't feel qualified to judge the prospects here at this point. It's certainly cheap, but what is its sustainable competitive advantage? I don't know yet.
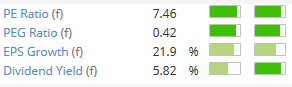
Fulcrum Utility Services (LON:FCRM)
- Share price: 61p (+3%)
- No. of shares: 175 million
- Market cap: £107 million
Acquisition of The Dunamis Group Limited
This a multi-utility/duel fuel installation company.
Profitability has taken off over the last couple of years, leading to a "multi-bag" outcome for shareholders:

Today's announcement is material relative to the market cap: a £22 million acquisition, partly funded by a £10 million placing at 60p. £11 million of new shares will also be issued to the vendors.
The target company designs, constructs, installs and maintains electrical connections.
In the previous two financial years, it generated EBITDA of £4.1 million (2016) and £2.6 million (2017). 2017 revenues were only about half of 2016 revenues, which explains the drop-off in profitability.
Revenues might have recovered in the current financial, thanks to a single customer:
In the current financial year, Dunamis' focus on battery storage facilities has given rise to a key customer (across a number of separate projects) representing approximately 40 per cent of Dunamis' annualised revenues.
If this was a completely new customer (admittedly, this is somewhat unlikely), then it would have needed to boost revenues by c. 65%, in order to reach 40% of the total amount.
Further detail is missing, but there are grounds for optimism that the EBITDA figure for 2018 might be more like the 2016 figure, rather than the 2017 amount.
The rationale is sensible:
The Directors believe that the acquisition of Dunamis represents a compelling strategic opportunity for Fulcrum, allowing the Company to extend and expand its services to create one of the UK's leading multi-utility services groups. The Acquisition will significantly strengthen Fulcrum's position in the approximately £500 million UK electrical connections market, and substantially expand and extend the Company's electrical utility services offering. The electrical connections market is of strategic importance to the Company as it seeks to provide the most trusted end-to-end multi-utility service in the industry and continues to drive growth in multi-utility contract wins.
There is a lot more said about planned cross-selling activities and Dunamis' expertise in battery storage units at renewable energy sites. All in all, it sounds like the two companies are a good fit.
Trading update - over the last few months, trading is in line with expectations.
My opinion - I have a positive impression both of Fulcrum and of this deal, which is surprising since I rarely invest in utilities and generally stay away from them.
But Fulcrum has been producing superb performance levels and I haven't spotted any red flags surrounding it just yet:
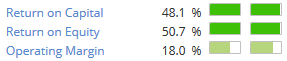
Mobile Streams (LON:MOS)
- Share price: 1.9p (-35%)
- No. of shares: 92 million
- Market cap: sub-£2 million (EXTREMELY SMALL)
I always agree to writing about this without checking its latest market cap - oh dear!
As I said last month, I think this company's business model is to buy up cheap copies of popular gaming apps, and other cheap software titles, and distribute them to individuals who can't afford smartphones in Argentina and India.
Sales in Argentina collapsed last year as its customers moved on to smartphones, so the company has been rolling out in India.
Today's update is for the six months ending 31 December.
- Trading in Argentina was stable (misspelled in the announcement)
- 180,000 active paying customers in India.
The company continues referring to its "addressable audience" in India of 750 million possible users.
That is obviously a pie-in-the-sky kind of number, especially when you consider that the number of active paying customers has fallen from 230,000 reported at the previous final results, to 180,000 reported today.
Has the user base been deliberately reduced due to unprofitable customer acquisitions - was this the "customer churn optimisation"?
"Our primary focus during the period was to reduce losses with our key accounts in India through a process of marketing and customer churn optimisation..."
The company also talks about "certain challenges" with several of its telecom operator partners - it needs them to be able to bill customers conveniently, so that sounds serious.
It also refers to "increased regulation for value added services". Increased regulation was what wiped out Zamano (LON:ZMNO), so that's another potentially serious issue.
The EBITDA loss for the six-month period was about £700k, leaving net cash in December of £1.4 million. Revenues for the period are £1.9 million, just over half the amount recorded in the equivalent period in the prior year.
Marketing spend has been reduced by a whopping 80%, so as to conserve cash.
My opinion - having collapsed its marketing spend, the company is now in survival mode, trying to conserve cash to avoid going bust unnecessarily quickly. It very likely needs to be refinanced, so anyone who doesn't like being diluted should be avoiding these shares in the open market.
The business model of catering to people using low-tech phones is also rather limiting - sooner or later, won't the same thing happen in India as just happened in Argentina?
Purplebricks (LON:PURP)
- Share price: 426p (-6%)
- No. of shares: 273 million
- Market cap: £1,163 million
Statement Re Share Price Movement & Trading Update
This online estate agent is well above our market cap limit, but I feel the need to comment on this highly unusual announcement.
The Purplebricks (LON:PURP) share price fell about 7.5% yesterday, on the back of a critical research note published by Jefferies.
According to the FT (external link), the research note claimed that only half of Purplebricks' customers in November 2016 had sold their home within 10 months. It also claimed that revenue may be overstated, unless Purplebricks has no contractual obligations to its customers after listing their homes on major property portals.
Purplebricks responds today as follows:
Jefferies estimated Purplebricks' completion rate is based on a single month's data and does not include properties that have completed but have yet to be uploaded to the Land Registry, which can take several months.
That could be worth some additional percentage points to the conversion rate, indeed. But Jefferies have been doing the analysis now, in early 2018, so that all of the November 2016 properties would be uploaded already.
Equally the research does not take into account properties which have exchanged, have reached sold subject to contract (SSTC), or are on marketing breaks.
Isn't ten months still quite a long time for a house to reached sale agreed (STC) status? And don't marketing breaks imply that the original marketing effort was a failure?
Purplebricks reiterates its most recently published sales conversion rate from instruction to sale agreed of 78 per cent, which it believes more accurately reflects its sales performance, although this figure itself does not include those properties in the sales pipeline at the end of the period which will in due course sell.
I think the share price is down today because this "refutation" doesn't really "refute". Instead, it strikes me that Purplebricks is merely quibbling with the Jefferies analysis.
The revenue recognition problem arises from the following two facts:
1. From 2013-2016, Purplebricks revenue was recognised as follows:
Fees earned on instructions of residential property are accounted for at the point of publication of the advert to property portals. Where property particulars have not yet been published to property portals, the fees are recognised as deferred income and presented within liabilities.
2. Customers are entitled to take "marketing breaks", referred to above. When they come back, they are supposedly entitled to continue receiving Purplebricks services to sell their home.
This means that Purplebricks hasn't done all of the work it will necessarily have to do for its customers by the time it puts their advert on the property portals. And as accounting principles testify, that would imply that they shouldn't recognise all of the cash received as revenue at that date.
Today's announcement doesn't clarify on this question, but merely states that Purplebricks stands behind its accounting policies and its results.
Trading update - There is also a trading update, stating that trading is in line with expectations for the year ending April 2018.
My opinion - I've remarked before that this company appears overly sensitive to negative customer reviews. It is also clearly sensitive to negative reviews by equity analysts, which is a bit more understandable given the claims that were made yesterday.
However, the 7.5% share price decline is frankly irrelevant when you look at the bigger picture:

What really matters is the risk of reputational damage from the suggestion that only 50% of properties from a particular month had sold within 10 months, and that revenues might be overstated.
As stated in my previous commentaries, I continue to suspect that the Purplebricks service is nothing to shout about. I also believe that the shares are overvalued, and have checked whether it is possible to short them today.
Keywords Studios (LON:KWS)
- Share price: 1628p (+0.5%)
- No. of shares: 62 million
- Market cap: £1,004 million
This is an acquisitive group providing services to the video game industry, e.g. art creation and translation/dubbing ("localisation").
The share price has just about doubled compared to when I covered it last May - congratulations are in order.
As a consequence, it is now above our typical market cap limit.
I do maintain a positive impression of it: it has executed its growth strategy very well (so far), and it has excellent exposure to the long-term secular growth of the gaming industry. At the same time, as a service provider, it doesn't face the same level of risk or volatility as do those companies which actually publish the games.
Yesterday's update was ahead of expectations:
The Board is pleased to announce that it expects revenues to be not less than €150m (FY16: €96.6m) and adjusted PBT* of at least €22.5m (FY16: €14.9m), both of which are comfortably ahead of consensus market expectations.
It's a truly international business, with 42 studios in 20 countries. The last time I studied the company, I noted that only 3% of revenues were denominated in GBP - the majority is in USD and EUR. Operational headquarters are in Dublin.
The outlook statement by the CEO is appropriately bullish.
Despite the positivity, it's probably reasonable to start having concerns about the valuation at these levels.
Against an EUR €1,140 million market cap, analysts are forecasting adjusted PBT of €39.5 million in 2019, pre-acquisitions. They reckon that like-for-like revenue growth is in the mid-teens.
The StockRanks are fairly clear:
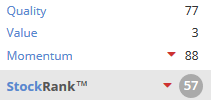
My opinion - As confirmed by analyst forecasts, the current valuation doesn't make sense unless you expect Keywords to make more and more acquisitions, and for these deals to be at least as successful as the previous deals.
It has performed brilliantly so far, but the risk of a mishap must surely be increasing, with the share price not leaving much margin for error.
I'm all done, thanks very much for your requests and have a fantastic weekend!
All the best
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

33 comments
Thanks Graham, that’s a really interesting report. Particularly liked the intro about how to respond to mainstream press tips and Purplebricks and Mobile Streams. I don’t have any holdings in them but there’s definitely things to think about there as a read-across.
Regards
Andrew
Thanks Andrew! Glad you enjoyed it. G
Thank you for the updates Graham.
Purplebricks (LON:PURP) seem to be yet another business with an aggressive revenue recognition policy; the problem with having an aggressive revenue recognition policy is that the share price quickly goes into reverse when the truth comes out - Just ask £CLLN
I've personally used PB for three transactions over the previous four years - but not in the last 24 months. My feeling was that the service was OK, but not maybe as hands on as a typical estate agent. But then, some traditional estate agents are useless.
I was delighted at the reduced fees for the all important access to Rightmove, and was happy to handle negotiations myself.
My wife undertook a transaction and got great support from the PB agent.
My concern about the company was the pressure put on their staff, and I felt that they were overworked - but I'd guess that PB may not have a monopoly on that.
The wider macro view seems to be volatile at the moment - US bond yields rising, the FTSE100 down for a few sessions in a row, and Bitcoin tumbling.
Graham - do you have a view or opinion on the wider macro environment? And anything you're doing different over the last week in terms of your portfolio, compared to previously?
Hi, I do have some macro views - published them on my personal newsletter this morning.
I'm currently about 25% in cash and would love a huge correction to come as quickly as possible, to enable me to buy more shares.
G
Fantastic post Luthrin....very value added if I may say so.
Re Northern Bear (LON:NTBR)
Northern Bear's share price opened at 84.5p on 30/11/17 when the interim results were released, and despite a seemingly positive RNS, it closed at 79p that day (and has been falling ever since). What seemed to initially spook investors was that higher turnover had come at the expense of a decline in gross margin from 22.2% to 18.4%. Since then we've had the Carillion fallout, and there were concerns regarding Northern Bear's possible exposure. On the bulletin boards you'll find shareholders expressing frustration over the past couple of weeks that the company hadn't issued a statement despite requests for clarification over possible Carillion contracts/debts. This overhang of doubt understandably resulted in a further decline in the share price. Today's RNS has finally allayed those fears.
At its core, Northern Bear (LON:NTBR) is a specialist roofing contractor with some additional subsidiaries in the group which provide more general building and ancillary services. All of the subsidiaries have the same accounting year end, so you can go to Companies House, download the relevant accounts, and construct a spreadsheet which will give far more granular detail on the split of turnover, profits and staffing levels than can be found in the Annual Report. Certainly in my case this gave me far more insight into the business.
The three roofing subsidiaries (Jennnings, Wensley and Springs) have in aggregate shown a steady rise in turnover and profit for the past 7 years (the farthest I went back), save for 2016 when the severe winter impacted operations. This division provides roughly 70% of operating profit and has very stable margins. Meanwhile the building services division has recently shown much higher turnover, and while the gross profit margin in this division has certainly fallen, the operating margin is fairly stable (perhaps management should emphasise this more).
The company is highly cash generative - it has produced £11.4m in free cashflow over the last 6 reported years, not far short of its market cap at the close last night (although I'm expecting FCF to be lower this year due to the H Peel acquisition and a reversal of some favourable working capital movements in 2017).
It's a highly illiquid stock with a wide spread, there are no broker forecasts, the company doesn't pay an interim divi due to the possible impact of winter weather, and whilst management are commendably down-to-earth with their business approach, investor communications could arguably be improved. This lack of news flow means that the share price is susceptible to declines for no apparent reason. In short therefore, it's really one for the patient long-term value investor.
I currently hold.
Thanks for the suggestions, I'll try to get around to covering all of them.
Have held FCRM for several years. Target has one customer responsible for nearly half of revenues and one co-founder leaving but staying in the same line of trade with non compete clause. Hmmm.
Please ignore! Si
Northern Bear (LON:NTBR) I'm currently a holder - I think some of the sell off was due to general macro unease and the possibility that Carrilion could have been an issue.
Obviously both those things have been addressed and now hopefully we should see some upward growth in the SP.
Re: Fulcrum Utility Services (LON:FCRM) I too took a small position
'The Acquisition is expected to be significantly accretive to underlying earnings per share in the first full year following Completion'
Expected a greater mark up at open so well happy..........
Just thought I would paste a portion of the trading update from Mobile Streams (LON:MOS) (which, some of you I think are still, alas, holding) - it looks dire reading, as usual:
During the first half of the financial year, the Indian mobile industry saw a number of changes which impacted the Company. Reliance Jio's continued growth throughout the year, based largely on their free voice, low cost data packages, has proven to be very challenging to other telecom operators negatively impacting their own revenues. This has led to consolidation in the market (Airtel takeover of Telenor and Tata and the Vodafone-Idea merger), and increased regulation for value added services. Conversely, consuming mobile content has never been easier for customers with enhanced networks, cheap smartphones and data making the opportunity in India, particularly for games content, a huge one.
As a consequences of these challenges, the Company has sought to refocus and reduce its marketing spend to approximately 20% of the levels in June 2017 with a view to protecting EBITDA and cash. This has resulted in reduced revenues with the result that the Directors expect unaudited revenues for the six months ended 31 December 2017 to be approximately £1.85m (31 December 2016: £3.6m) with cash and cash equivalents at 31 December 2017 being £1.4m (£2.8m as at 31 December 2016). Trading conditions in the Company's core markets of India and Argentina are unlikely to change materially in the second half of the current financial year meaning that the Company expects that second half revenues will be slightly below those recorded in the first half of the year. The EBITDA loss for the 6 months ended 31 December 2017 is expected to be in the region of £700,000. The Company expects that the EBITDA loss for the second half of the year will be lower than that experienced in the first half of the financial year.
Hi Graham
Another vote for Mobile Streams (LON:MOS)
Thanks Andy
re: Mobile Streams (LON:MOS).
Hi Andy, done. Cheers for the request. Probably the smallest market cap we've seen here since the last time we covered it!
Interested on thoughts on Northern Bear (LON:NTBR) too please - not saying much but what can we imply. Graham you have been positive before on this company. Cheers.
I'm also interested in Northern Bear (LON:NTBR) and Fulcrum Utility Services (LON:FCRM) following the announcements; personally I think Northern Bear (LON:NTBR) is very good value, with a PER of under 10.
Paul gave a positive overall view of Fulcrum Utility Services (LON:FCRM) in early December when the interims came out. Since then I've kept a close eye on the price and it's dropped over 10% since then... so on this announcement I have taken the "plunge" and bought a dribble of a shareholding.
Anyone got an idea why Titon Holdings (LON:TON) is up 20% on no announcement? It's been covered here before...
Titon Holdings (LON:TON) was tipped by Simon Thompson in the IC, last night. As was Record (LON:REC) hence bounces from both
HI Graham
If you feel like it, Mobile Streams (LON:MOS) brought out an update after the open this morning. And if you have any additional thoughts on Spectra Systems (LON:SPSY) which Paul commented on yesterday, that would be great.
And if anyone missed it, I posted my notes from the very interesting Growth and Innovation Forum earlier this week here. https://www.stockopedia.com/content/report-on-the-growth-and-innovation-forum-30th-january-2018-307038/
have a great weekend
Francis
If you have time it would be nice if you could cover yesterday's trading statement from Keywords Studios (LON:KWS) ? Everything seems pretty tickety-boo with this games development aggregator at the moment!
Morning Graham - Second request for Fulcrum Utility Services (LON:FCRM) please
It looks like a substantial acquisition. I make it that revenues and EBITDA of the acquisition would add roughly 50%. P/S approx. 1 , EV/ EBITDA approx 6. . Placing was done at only 1% discount. Can't find anything negative? Of course no idea about the profitability of the acquired co.
All IMO
Re Fulcrum Utility Services (LON:FCRM), the company they are acquiring (The Dunamis Group Limited) was incorporated in Sep-15. Their last published accounts were for the y/e 30th April 2017.
The acquiree's Balance Sheet showed NAV of £14.2m. However, this is mainly intangible asset value as Dunamis itself grew via two large acquisitions (Matrix Networks & Maintech Power services). So the tangible asset value is close to zero.
Dunamis had Sales of £10m, gross profit of £3m but an operating loss of £0.8m. However the key reason for the loss was a £2m amortisation charge related to the mentioned acquisitions.
Unable from the accounts to estimate what economic moat (if any) Dunamis maintains.
https://s3-eu-west-1.amazonaws...
Re. Fulcrum Utility Services (LON:FCRM) Thanks for this additional info , Marx.
From today's RNS,
" For the 6 months ended 31 October 2017, Dunamis achieved unaudited revenues of £10.2 million and EBITDA of £1.8 million"
So it looks like their sales at least are well ahead of previous year's. FCRM's revenues forecast is £41m. Acquisition is bringing in around 50% additional revenues?
re: Fulcrum Utility Services (LON:FCRM)
Hi ramridge, I've taken a look at that now and written it up. Interesting deal and company, especially since utilities are usually so boring!
Hi Graham - Re. Fulcrum Utility Services (LON:FCRM) I completely agree with your assessment. I hate using the overused word but this acquisition could be transformational.
Acquisition announced this morning by Fulcrum Utility Services (LON:FCRM) looks interesting so your views on that would be interesting. The market seems to like it with shares up over 4% this morning.
Well Graham, if you're bored your views on Maintel Holdings (LON:MAI) would be much appreciated.
Those in the know liked it yesterday before the update and it seems the general market now likes it.
I note Paul wasn't overly keen a couple of months or so ago, considering it may be in Amazons cross-hairs.
Thanks in advance and wish you a great weekend.
Hi matylda, thanks for the suggestion re: Maintel Holdings (LON:MAI)
I don't know enough about it yet, as I haven't covered it before, so apologies if my treatment of it today is sub-par. Need to familiarise myself with it more! Have a good weekend you too.
Hi Graham,
Much appreciated, me too, on my ever expanded "look into more at some stage" list, perhaps some fellow members have more insight.
Slainte!
My morning smallcap tweet: Just the one.
Northern Bear (LON:NTBR)
Northern Bear (NTBR) Q3 trading strong. Rev and adj pretax (cont) are currently ahead of management expectations and prior year. I hold.
Morning
Northern Bear (LON:NTBR) too for me. Can't understand the SP decline.from july 2017
Thanks
Morning Graham.
Micro cap builder Northern Bear (LON:NTBR) out with a bullish (almost effusive) trading statement this morning.
https://www.investegate.co.uk/northern-bear-plc--ntbr-/rns/trading-update/201802020700037094D/
Share price and stock ranks have tailed off a lot since last Autumn. Maybe worth a look if you have a mo’.
Gus