Small Cap Value Report (Fri 2 July 2021) - CMOStores, POLR, GYM, FCAP, CBOX

Good morning, it's Paul & Jack here with the last SCVR for this week.
Timing - I'm going to type up my notes on the Cake Box Holdings (LON:CBOX) webinar today, which was good. Should be finished by c.1:30 pm.. Today's report is now finished (14:06)
Disclaimer -
A friendly reminder that we don’t recommend any stocks. We aim to cover notable trading updates & results of the day and offer our opinions on them as possible candidates for further research if they pique your interest. We tend to stick to companies that have news out on the day, and market caps up to about £700m. We avoid the smallest, blue sky type companies, and a few specialist sectors (e.g. resources, pharma/biotech).
A central assumption is that readers then DYOR (do your own research) and discuss in the comments below. The comments, incidentally, sometimes add just as much value as the articles. We welcome all rational views, whether bull or bear!
It's helpful if you include the company name or ticker within reader comments, otherwise some readers may not be aware of what company you are commenting on.
Agenda -
Paul's Section:
CMOStores - It's a quiet news day, so I take an initial look at a forthcoming (next week) new float. This is an online only building materials company, with a drop-shipping model. I like the concept, but generally avoid new floats.
Gym (LON:GYM) - a £31m equity placing, to accelerate new site rollouts and (I suspect!) calm the bank down. Good business model, and this seems a great time to be opening new sites, due to favourable property market opportunities. My main issue is the market cap - it looks far too expensive to me.
Cake Box Holdings (LON:CBOX) - my notes from today's interim results webinar. Very positive - management are exactly what I look for - hands on entrepreneurs, with tons of skin in the game.
Jack's Section:
Polar Capital Holdings (LON:POLR) - results from yesterday for this active fund manager. A record year for inflows, with scope for organic and acquisitive growth, plus a dividend yield of close to 5%. Tech continues to dominate assets under management and inflows remain sensitive to market conditions.
Finncap (LON:FCAP) - a year to remember for this growing broker and financial advisory business. FY22 pipeline also appears to be strong, but these businesses are cyclical and earnings can be volatile.
Paul’s Section:
CMOStores.com Ltd
This looks potentially interesting.
The link above is the initial RNS on 25 June, giving some bare bones information about the company, which caught my eye. It is trying to disrupt the traditional builders merchant market, by selling online only. Goods are mostly dispatched by the manufacturers, on a drop-shipping basis, a capital-light model for CMO.
It has 7 websites:
The Group currently operates seven specialist websites,
Roofingsuperstore.co.uk
Drainagesuperstore.co.uk
Insulationsuperstore.co.uk
Doorsuperstore.co.uk
Tileandfloorsuperstore.co.uk
cmotrade.co.uk and
Totaltiles.co.uk.
There must be websites operated by traditional builders merchants, so I don’t think CMO is doing anything unique, but it does claim to be the largest online-only supplier of building materials.
It’s been going since 2008.
Current trading - strong like-for-like growth of >30%. Total growth (including acquisitions) of >70%. Both figures are the 5 months to 31 May 2021. Impressive! But for online businesses, growth is largely driven by how much they spend on marketing.
Placing and proposed admission to trading on AIM
This announcement came out today. The company’s investor website is not working at the time of writing, but there should be an admission document up there shortly.
Placing details:
- Liberum is the broker
- 34,090,909 shares have been placed at 132p, raising £45m
- Market cap will be c.£95m on admission (total of 71,969,697 shares in issue)
- Raising £27.3m for the company, and £17.7m for selling shareholders
- Looks like a private equity part disposal, with Key Capital Partners retaining 26.8%, founders 10.4%, and senior management 6.4% on admission. So I expect a lot of the cash raised will be used to pay down private equity debt, so in effect nearly all the money raised in the float is going to selling shareholders
- Diary date - shares are expected to commence trading on 8 July 2021 (next week)
My opinion - I quite like the sound of this, and will check out the Admission Document when it is published.
With new floats, I like to search the Companies House website for the historic numbers, and nearly always find that the historic profitability is nothing like as positive as presented in admission documents! These things do get buffed up for sale to the stock market.
CMOStores group accounts (company number 10710953) only go up to 31 Dec 2019, which shows revenue of £45.0m, and an operating loss of £(464)k. The tell-tale signs of private equity ownership are there (tons of debt, and high finance charges). The loss before tax was £(2.2)m for 2019.
Net asset value was horribly negative, at £(13.5)m, mainly due to £17.8m of long-term debt. Therefore the new money raised in the float is almost certainly mainly to pay off this private equity debt - in effect therefore the float is almost all money going to selling shareholders.
As I would expect for a float, the historical losses have transmogrified into EBITDA profits for 2020! So it could have been a beneficiary of the lockdowns last year. It’s also a reminder that private companies tend to not like making profits (as they don’t like paying too much corporation tax), whereas public companies tend to maximise profits to please investors. Which does beg the questions how real, and sustainable, are the reported profits at the time of flotation? Also, profit warnings in the first year or two post-floating, are quite common, as the aggressive forecasts to maximise the float price unravel. Hence why personally I rarely buy new floats. Better to monitor them for a couple of years, and see what track record emerges.
CMO has a proven record of revenue growth, profit growth and cash generation. The Group generated pro forma revenue of £67 million and pro forma adjusted EBITDA of £4.4 million in the year ended 31 December 2020 (including Total Tiles, which was acquired on 31 December 2020) and has demonstrated consistent growth before and during the COVID-19 pandemic through a combination of organic growth and acquisitions.
.
Gym (LON:GYM)
279p (down 2%, at 09:10)
No. shares: 166.2m before placing + 11.35m placing shares = 177.56m post placing
Market cap: £495m (post placing)
This announcement was issued just after the market close, last night. A reader GBValue flagged it up in the comments below, so thought I’d take a look, because there’s a lot of interesting information about expansion & strategy in the announcement.
The Gym Group plc (the "Company" or "The Gym Group"), the nationwide operator of 187 low cost 24/7, no contract gyms, announces its intention to conduct a placing of new ordinary shares of 0.01p each ("Ordinary Shares") in the capital of the Company to raise gross proceeds of approximately £31 million (the "Placing").
- Funds to be used for accelerating roll-out of new sites - targeting 40 new sites in 18 months
- Attractive property deals available currently
- Potential to double number of sites ultimately
- Revised terms on £100m bank facilities linked to this placing - which does raise the question whether the bank might have pushed the company to raise more equity? Particularly as it was about to breach a covenant by the sounds of it below -
The revised agreement provides permission for a total of £10m of third-party finance leases, increased capex spend limits and waives the June 2021 covenant test due to the extended lockdown in early 2021.
Targeting 30% Return on Investment (NB. this ignores the first 2 years of trading! So it’s a buffed up figure really) - good business model, but remember there’s a fair bit of ongoing replacement capex, once heavily-used equipment & fittings wear out.
Current trading -
- Membership numbers continuing to rise, reaching 734k by 28 June 2021 (vs 794k pre-pandemic Dec 2019) - doesn’t seem to be like-for-like though, due to new site openings this might be flattered.
- All members now paying again, since freeze on fees ended in April 2021 re-opening
- Summer is seasonally quiet for new memberships
- Stronger membership growth expected in the autumn & new year trading peak (all those new years resolutions. Been there, done that, have many lapsed gym memberships under my belt!)
- Pricing remains firm. Note that GYM is at the value end of the market (no swimming pools, hence cheaper)
- Net debt £62.6m at 28 June 2021. £7.2m in stretched creditors, hence underlying net debt is £69.8m. This has almost maxed out the £70m normal bank facility, but there is a £30m extension to £100m available until June 2022.
- Cashflow positive in May 2021 (before expansionary capex) - first full month of reopening.
Result of Placing - an update at 7am this morning.
Numis & Peel Hunt have successfully placed the new shares, details:
- 11,350,000 placing shares - an increase in share count of 6.8% - fairly modest dilution, so not a problem to my mind
- Price - 275p per new share, a modest discount of 3.5%. Although note that the share price dropped almost 10% in the week before the placing was announced - could be a coincidence, but when hundreds of people are taken inside, the information can leak out. This is why shares really should be suspended a week before a placing is done, and before anyone is taken inside. Otherwise it’s a false market. Apparently that’s what they do in Australia, and we should adopt the same system here.
My opinion - given that the company was effectively maxed out on the regular part of its borrowing facility (£70m), then I reckon this looks a hybrid fundraising - ie. partly for more rapid expansion, and partly to keep the bank happy. There’s nothing wrong with that, because it’s been well-executed - only 6.8% dilution, and a modest price discount.
There’s no open offer, but they’re not really needed with a c.£500m market cap company, and a smallish fundraising with minimal discount. Small shareholders can buy in the market, at close enough to the placing price, if they want to top up.
Accelerating the roll out of new sites makes complete sense to me, given favourable market conditions in the property market.
Overall, I quite like the business model of GYM, but it’s not doing anything unique - there are plenty of other low cost gyms. Also, I question the valuation, which strikes me as much too high. The story tends to be that gyms generate lots of EBITDA. But that ignores the heavy maintenance capex, which gets a lot heavier over time, as sites age & everything wears out.
There’s also the issue that plenty of people have found other ways to exercise during the pandemic (e.g. pelatons, or running around the park, cycling craze continuing), so it will be interesting to see how long the pent-up demand of returning to the gym settles down longer term?
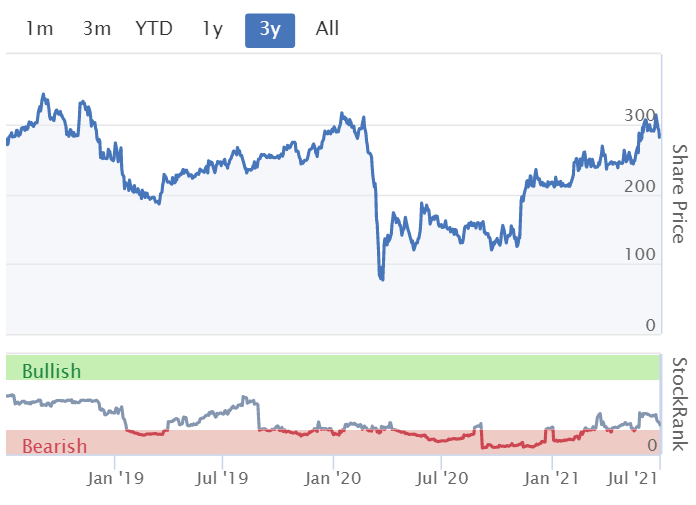
As you can see below, on the 3-year chart, it's already fully recovered to pre-pandemic levels, when it was richly rated. Is there scope for even further multiple expansion of the PER? Remember that new sites take time to build up into decent profits. I think the easy money has already been made on this share in the last 14 months. Further gains might be harder to come by, possibly?
.
.
Cake Box Holdings (LON:CBOX)
325p (down 2%, at 13:42) - mkt cap £130m
Webinar today
This results presentation webinar was held from 11am, arranged by Equity Development. It was excellent, so I jotted down some key points. The slide deck & the recording of the webinar will follow in due course.
I reviewed the interim results earlier this week here. So I won’t duplicate that here.
Here are my notes from today’s webinar (NB. not comprehensive, just key points that jumped out at me).
Lots of applications for franchisees, but only 3% make it through the selection process - after quality, not quantity
Franchisees earn on average a positive EBITDA of £89k p.a., making it an attractive income, and growing
CBOX manufactures cake sponges at its in-house bakery, high margin of 70%
Actually seeing input cost price deflation, due to rapidly rising volumes
Music to my ears - the company buys freehold property “Rather than paying extortionate rents” - NB this relates to central functions, not the shops which are leased by franchisees, not the company.
Inventories rose in H1 due to buying packaging from the Far East. Increased stockpiles to avoid any possible supply interruption.
Support fund of £1.5m to help franchisees start up, but no longer needed because Nat West have recently started lending for the fitout costs, to franchisees
Home delivery - great progress from selling via UberEats & JustEat at start of pandemic, so set up their own website sales a few months later. All delivery is current run rate of £6m p.a. Gone down slightly since shops re-opening, but many people still ordering online & collecting in store.
CBOX was born in the 2008 recession, and proven highly resilient in pandemic.
New distribution centres in Midlands & North have greatly reduced road miles for deliveries to franchisees.
Pandemic has triggered high quality people applying to be franchisees - career changes, redundancy money, etc. “Never waste a good crisis!” quipped the CEO.
Kiosks - similar in revenue & profits to stores. Smaller, but higher footfall. Typically operated by a franchisee, who operates nearby shop, and delivers twice per day to the kiosk.
A major supermarket approached CBOX to do the kiosks, so was able to strike an attractie deal. Identity currently confidential, to be publicly revealed soon (but easy enough to find out, as they’re already operating LOL!)
(I think the kiosks could be very good business, and highly attractive to franchisees, potentially doubling their profit)
My question - how much profit is booked from sale of each new franchise? Answer - it averages £40k per site.
Store numbers - what’s the limit? “We always think about Greggs” - so what’s that, maybe 2k+ potential sites in the UK? Hence there could be a lot more growth to come, over the long-term.
International expansion? Not for the moment, but it’s possible, watch this space (Paul: and would suit the franchise model)
Cyber-security attack - possible fine from the ICO estimated at £14-250k. Fully provided for. Systems now secure.
Current trading strong - June 2021 LFLs in double digits
Capacity of bakeries? They only run 1 shift, so could double up if needed.
Vegan cake is in development, should be ready soon.
Red velvet product doing particularly well.
Lucky to have no direct competition nationally, although some similar companies at local level.
Average weekly sales per shop (franchises remember) has gone up from £6.3k to £6.9k.
Brexit - not much impact, as don’t buy much product from EU. Also all customers are UK-based so no impact on sales.
Recording of the webinar will be available soon.
My opinion - very positive. I’m really kicking myself for not having bought this share before, as it ticks so many of my boxes.
It’s subjective of course, but I watch as many company webinars as I can, because there’s nothing like hearing management talk about their business, to get a feel for what they are like.
In this case, the CEO and CFO made a very positive impression. I’m not looking for slick presenters, or polished pronunciation & charm. I just want to see hard-working, hands-on entrepreneurs, who know their business inside out, and can rattle off facts & figures. Also I like honest, open answers to questions, not pauses, and deflection.
CBOX passed my tests with flying colours, and I think this management seem very backable.
Even better, the CEO & CFO own 42% of the business, which is plenty of skin in the game.
Overall then, I have a positive view of this business, and regret not having bought in the past when it was good value. Unfortunately, the price is now too high for me. I’ll put it on my watchlist, as the sort of thing I would buy on a general market panic sell-off, which we get from time to time.
Well done to shareholders here, I think you’re on to a winner. Very much a coffee can, tuck away and forget stock, in my view.
.
Jack’s section
Polar Capital Holdings (LON:POLR)
Share price: 860p (+0.35%)
Shares in issue: 100,113,855
Market cap: £861m
(I hold)
Polar Capital is a specialist fund manager with a particularly strong reputation for its Tech fund, which is by far its largest. Compared to other managers, it is overweight in this sector. Nearly half (49%) of its assets under management (AUM) are in its Technology strategy, up from 43% in the previous year.
It’s been a great performer over the past few months - one of the more obvious opportunities in hindsight. This is because back in January or so the group was paying out a 5.31% forecast yield despite its strong reputation, improving momentum, cash generation, and very strong profitability figures over time.
Even today, after months of steady rerating, that yield stands at an attractive 4.76%.

I've a position not because I made that connection but because somebody else pitched it for the Stockopedia Investment Club - and I’m glad they did! Here’s the more in-depth stock pitch from January. The company’s getting a little big for the SCVR but it’s a slow news day, so it looks like we have time to circle back to yesterday’s update.
The outlook is positive with our diversified range of fund strategies, enhanced digital marketing footprint and broader distribution reach.
Highlights:
- Assets under management (AUM) +71% to £20.9bn; average AUM +18% to £16.7bn,
- Net inflows of £2.1bn and £1.7bn in acquisitions; net inflows for Q4 of £517m,
- Pre-tax profit +49% to £75.9m,
- Basic EPS +54.5% to 67.2p; adjusted diluted EPS +53% to 62.2p,
- Total dividend for the year +21% to 40p.
The results value Polar shares at 13.8x adjusted diluted FY21 earnings and are ahead of the consensus forecasts on Stockopedia. A 40p dividend makes for a yield of 4.7%.
That seems good value, given that this year has seen ‘the highest single year of growth [in AUM]’, up some 71% to £20.9bn. Trends continue to be positive - from 31 March through to 25 June, AUM increased to £22.7bn.
A total of 11 of the group’s UCITS sub funds saw positive net inflows over the reporting period, with the largest inflows recorded by Global Technology (£1.7bn), Biotechnology (£379m), Emerging Market Stars (£243m), Global Insurance (£187m) and UK Value Opportunities (£181m).
Net outflows continued from the North American Fund, however, totalling £545m over the reporting period. The rate slowed in Q3 2020 and turned positive in Q1 2021.
While core operating profit increased by 24%, strong fund performance and performance fees drove profit before tax up by 49%. No doubt Polar holds more than its fair share of ‘Covid winners’ in its overweight Tech strategy. There’s a chance this might go through a period of underperformance at some point.
The acquisitions noted above include the International Value and World Value equity team from the Los Angeles based asset manager First Pacific Advisors on 16 October 2020 and Dalton Capital on 26 February 2021 (European equities). A joint venture, Phaeacian Partners LLC has been established and a new thematic team is joining in September 2021.
Polar is focused on growth and diversification, by both channel and geography, and it sees ‘significant opportunities outside of our home market of the UK’, particularly in Continental Europe in key markets, such as Switzerland, Germany, France and Spain.
Conclusion
Despite the challenges of the pandemic and lockdowns, Polar Capital has had a very successful year. It will always be sensitive to the health of the market though, and things could have turned out quite differently.
The early stages of the COVID-19 pandemic had a significant impact on stock markets, resulting in the European funds industry's worst ever outflows in March 2020 (-£197bn). There’s been a remarkable recovery since then of course but the point remains that Polar would not be exempt from a major downturn. It does have a strong balance sheet to mitigate this, with net cash in excess of £100m.
So there’s a big exposure to Tech here, and a sensitivity to market conditions, plus the ongoing industry headwinds of margin pressure. Most players attempt to offset this with M&A and increasing scale. Polar says it has plenty of the market to aim for in this regard.
The group is diversifying into new teams and across new markets, which should in time alleviate some of the dependence on Tech as well. This can be seen in the past year’s trading, with Polar noting that ‘the vaccine induced rotation into value and cyclical stocks further benefited our value style strategies’.
The group enjoys a strong reputation, having been recently ranked 2nd for Brand Preference, 2nd for Product Quality and 4th for Account Management. Maintaining this reputation could be a key differentiator in terms of attracting inflows. To this point, Polar places great stock in its liberated culture of autonomous investment teams which allow specialists to thrive. Employee turnover is low.
Reputational risk is still a consideration for investors, should Polar’s standing deteriorate. Performance is measured in quarters in the fund management world after all.
That aside, the group expects to pay an annual dividend within a range of 55% to 85% of adjusted total earnings, so shareholders can expect to be well compensated for holding the stock. Even after a strong run, Polar qualifies for three Guru Screens and has a StockRank of 92. It’s getting flagged for good reason in my view.
Finncap (LON:FCAP)
Share price: 38p (-3.8%)
Shares in issue: 176,585,014
Market cap: £67.1m
It’s been a bumper year in the capital markets - think of all the placings and IPO fees. Things go from feast to famine here and we’re firmly in ‘feast’ mode. Assuming societies continue to reopen, would that lead to renewed momentum in corporate activity?
It’s possible that the next year or two will continue to be strong, but I wouldn’t depend on it as a long term sustainable dynamic. It’s always been cyclical.
FinnCap has its own growth strategy in place however, which means its growth is not purely predicated on the state of the markets. Although they certainly help a great deal.
Since IPO in December 2018 the group has busily been evolving into more of a financial advisory business. Before that it was just small and mid cap equities. With more diversified operations, the business model could be improving.
Highlights:
- Total income up 84% to £47.6m,
- finnCap Capital Markets revenue up 84% to £34.5m; finnCap Cavendish revenue up 66% to £12.1m,
- Adjusted PBT up from £1.6m to £9.6m; PBT up from £1.2m to £8.4m,
- Adjusted EPS up from 0.8p to 4.80p; basic EPS up from 0.49p to 4.41p,
- Total dividends 1.5p,
- Cash of £20.4m at 31 May, down to £17.2m at 29 June 2021.
The figures are ahead of Progressive Equity’s forecast of 4.4p adjusted diluted EPS and put the shares on a multiple of 8.3x. Clearly that’s low and signals a degree of skepticism that current levels of activity can be maintained.
It has been a bumper year. Total deal and advisory fees of £33.4m (FY20: £16.0m), with 76 transactions completed and £723m of equity raised via 36 public market placings and 4 IPOs. £124m of debt raised across nine completed mandates. 16 public and private M&A transactions advised on, with an aggregate value of c.£600m.
In light of this strong market, FinnCap has invested in its human capital across sales, corporate broking, and ECM. It’s targeting new sources of capital across Family Offices and Private Growth Capital, and has set up finnCap Analytics, which is focused on servicing larger hedge funds and institutional investors.
FY22 has started well with revenue ahead of last year. The deal pipeline remains strong, ‘subject to equity market conditions’, with a number of IPOs and equity fund raisings already scheduled and the expected completion of a number of private M&A transactions.
FY22 outlook: revenue to be in the £40-£50m range; staff costs (excluding share-based payments) c.58-62% and non-staff costs c£10m.
Conclusion
Funny to think of brokers providing research for other brokers. The company is well placed to take market share from… well, us.
Still, business is business and Progressive Equity (which also does a good job for PIs) is happy to give credit where it’s due regarding FinnCap’s ambitions. It does forecast a reduction in revenue and profits for FY22. Whether that reflects one-off activity levels in FY21 or is another example of prudent forecasting that can be upgraded is a point to consider.
No doubt the company’s in a sweet spot right now but, while there may well be longer term sustainable growth potential here, there’s also a risk that the share price currently reflects an unsustainable environment. The markets are forward looking, so perhaps sellers are foregoing some potential upside to ensure they can take profits while the going is good.
That said, the group says its deal pipeline remains strong so it looks like the supportive conditions are set to roll on in FY22. Anecdotally, it’s hard to escape FinnCap’s presence these days in terms of research notes and house stocks, so it does have the feel of a company making moves and taking share.
I’m slightly wary of brokers as a business model - when the times are good they can look excellent, but if you look at the share price chart of Cenkos Securities (LON:CNKS) or Numis (LON:NUM) over a period of years, you’ll see the shares can be a punishing ride when conditions turn.
I do have a favourable impression of FinnCap as a company that provides for retail investors though, and the markets it operates in are ripe for disruption, so hopefully the momentum continues.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

57 comments
Thanks for your thoughts on Cakebox. They concur with mine and I did buy in. I did think the management were quite active. I think it is steady company.
Amazing input on Cake Box Holdings (LON:CBOX), I bought it at £205,25 (I Hold), Is part of my SIPP portfolio which I consider my Coffee can approach (after reading 100baggers and 100 to 1 on stock market), its something I will not have access for the next 30yrs.
I bought it after watching a webinar about 6 months ago, I loved the management and the numbers.
Thanks a lot for your thoughts on GYM, very much appreciated! Have a great weekend...
Hi all,
Thanks for sharing notes from Cake Box Holdings (LON:CBOX) webinar Paul.
Impressive company and management. However, like you, missed the boat on this one, for now. Refuse to chase it up at 25 x forward earnings!!
Love the write up on CMOStores.com Ltd.
Sounds like a barge pole job to me.
Regards
Michael
Hi Michael,
Love the write up on CMOStores.com Ltd.
Sounds like a barge pole job to me.
Why do you say that? I quite like the concept of drop-shipping building products using the internet. The promotional RNSs were quite persuasive, so I think this might be a popular stock. Maybe that didn't come across in the main report, but I always try to look for potential negatives, so all bases are covered!
Regards, Paul.
As a customer of CMO, I think this sort of model will take huge market share from the lightside trade of the Builder's merchants. Many trades are becoming much more business savvy, and the CMO model gives a much wider choice of products at a lower end cost. Many of the equivalent high value products are to order anyway through the larger BMs.
I was about to post that the only disadvantage to the small builder is the lack of monthly credit terms, but have just checked and see that they do trade accounts too.
My guys will be fitting the 3 rooflights that arrived from Roofingsuperstore this morning, next week!
Thanks FuzzyHaha,
There's nothing as good as genuine customer feedback, so I'm really interested to hear your thoughts on CMO.
Quick question though - surely existing builders merchants also have online offerings for people who want to buy via the internet? So why would you go to CMO's websites instead?
Regards, Paul.
Hi Paul, they're slow on the uptake. I think the traditional BM's like to price according to the customer. I've had 15 years as a small scale developer in Andover doing new builds and office conversions to flats. I tart myself around the large BMs for bricks blocks etc, because Hermes can't deliver them,. Different BMS seem to have different rebates each month from different suppliers, so pricing is fluid. but there's a whole range of lightside merchants. We have a number in Andover who can supply stuff that can only be delivered on a van. They're pricing seems to be bespoke to the customer, but online still seems to be cheaper. I guess this is down the CMO dropship model. Capital light etc etc. Of course CMO-like merchants will lack personal touch, but maybe in time that's something they'll develop with relationship managers for customers worth keeping
Hi Fuzzy, I’m in Andover too - beer sometime? You’re right about the local BMs prices vary so much and it’s really down to who serves you as to what price you get. I’ve a friend of friend who’s the manager at one of the big merchants in town. If he’s on duty then my prices are 20% less than normal. Whatever I need to buy I do research on the internet and show them the price that I can get there so they can hit the deal button. No objection to paying 5-10% more in order to shop local and keep jobs in the town.
Hi Paul
On CMOStores the bits of your write up that made me write what I did were:
"Looks like a private equity part disposal, with Key Capital Partners retaining 26.8%, founders 10.4%, and senior management 6.4% on admission. So I expect a lot of the cash raised will be used to pay down private equity debt, so in effect nearly all the money raised in the float is going to selling shareholders"
"As I would expect for a float, the historical losses have transmogrified into EBITDA profits for 2020!"
Additionally on a sample of one I bought my house in 2017 and had it refurbished in the summers of 2018 and 2019 by a builder/electrician/plumber friend of mine who waxed lyrical about Screwfix and he would ring Monday and it was ready for pickup or delivery Tuesday. See https://www.screwfix.com/ and I feel that Screwfix have huge brand recognition amongst the trade and general public whereas I have never heard of any of the specialist web sites mentioned.
The other high profile supplier Wickes offers delivery or Click and Collect.
So I am struggling to see the edge/moat/USP that CMOStores have but that could just be me.
And I am just wary of private equity/owners selling and even more so having got caught by BOTB shortly after a large owner sale.
But I accept only the above, not through any deep analysis of the business model or the company.
Regards
Michael
Here are my SCVR heat maps for today (prices as at ~9:40am).
I share these heatmaps with the intention of giving a visual indication of what is going on in the SCVR world: who’s reporting (and it's impact on the share price); and what’s moving more than 'normal'. There are no associated recommendations, implied or otherwise, just information. How, or indeed if, you choose to use that information is up to you. Please feel free to ignore them if you don't find them useful.
Please read my heat map thread for a great deal of explanation of how the heat maps are formed and how I use them to guide me with my research, and for a full key to the contents.
I very much welcome feedback so if you do have any feedback, not already covered in the heat map thread, it would be very helpful if you could post your comment in the heat map thread rather than the SCVR thread. The more specific and constructive the feed back is, the more that likely it is that I will be able to act upon it. Thank you all for the feedback so far.
Small / Micro Caps reporting today:
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
Microsaic Systems (LON:MSYS) heads Mr Contrarion's listing today. Looking through its newsflow this year, it seems to be making progress after much disappointment. Large issue of new shares early in the year at 0.1p. Profit taking on today's big jump. Products seem very relevant. There's substantial institutional holding. New Chairman and NED. Does anyone know whether its products are really novel?
On the topic of IPOs/new issues, the placement of Open Orphan (LON:ORPH) ‘s shares in Poolbeg Pharma announced a couple of weeks ago is being brought to market.
https://www.stockopedia.com/sh...
This includes a retail tranche being offered via PrimaryBid which has a copy of the Pathfinder Prospectus and a video of an interview with the CEO.
Gus.
Good morning again, Paul or Jack. Would you please comment on Finncap (LON:FCAP) results yesterday, or perhaps you feel/felt that the company was not worthy of comment. Your commentary is always so insightful and valued. Another reader has made a brief comment today, but you give a lot, lot more and it is so helpful.
Finncap (LON:FCAP) are one of the companies which offer free research which we long term SCVR contributors find valuable, and you often comment on. Could you spare a little time, or perhaps give reasons why you think it isnt worthwhile on this occasion. Thank you, as always.
Re Finncap (LON:FCAP) - its shares are extremely illiquid, so personally I didn't want to spend any time on it (because even if readers like it, it's so difficult to trade in).
However, given reader interest here, I think Jack might be looking at it today.
P.
Re Finncap (LON:FCAP), thank you Paul - and / or Jack!
Since it appears to be a quiet news day I thought I would make a comment about the disclaimer above which mentions DYOR. I am fairly certain a lot of us are influenced by the stock report and make a buy or sell as a consequence because we don't really know where to start when it comes DYOR.
This clearly is not the fault of Paul and Jack because of the 100s of companies that are reported on - despite a remarkable job covering these companies some important details can be missed.
I have noticed that Phil Oakley wrote a very good book on investing which made reference to share pad and how it could be used to make stock picks.
I was wondering if Stockopedia would be interested in producing such a book. I think there are a lot of pros to producing a book like Oakley's - it could bring more subscribers, give context and an idea on how to DYOR on the stock reports etc.
.
Morning letap73,
Have you checked out the "learn" section in Stockopedia? There's some really great info in there with a load of great books and guides. Highly recommended.
https://www.stockopedia.com/le...
Cheers,
When I joined in December, I thought Stocko did a great job of guiding research. The Today page takes you straight to the video 'How to Read a Stock Report' and links to the Help guides, which took me to Learn with its reading and video sections. I found watching Ed's webinars on YouTube most helpful and was what got me to the point where I could make that first buy.
Bidstack (LON:BIDS) announced a share placing after market close yesterday at 2p/sh (33% discount to closing price of 3p)
Based off £10m raise they are now forecasting cash of £7m by end of 2021 and £2.5m by end of 2022.
No position - far too speculative but they seem to be fully funded now for a couple of years
Re. The Bidstack (LON:BIDS) placement, Wimbledonsprinter picked this up at the tail end of yesterday’s SCVR. Thought I’d copy over my comment from last night as an observation on how a lot of AIM company brokers seem to be going about raising add on capital for their clients at the moment.
Gus.
——————
“Re. Bidstack (LON:BIDS), it’s ”another kick in the b***s” for the PI as Pink Floyd once nearly sang.
On the principle that even if it doesn’t repeat it at least usually rhymes, history suggests the shares will open down 30% or so tomorrow, slightly above the 2p offer price giving those not in the placing the chance to buy in the market and avoid the heavy dilution. If you still buy into the story top up as the placees sell down to their preferred holding position. If not cut your losses and sell. This seems to be the modern/cheap way of achieving an underwritten rights issue nowadays. No position.”
I really like Bidstack (LON:BIDS) model. I think they could potentially be phenomenally successful and whilst I've held previously have remained on the sidelines up until now as I felt they needed to do another raise.
I'd say they have been somewhat naive since being on the market. Investors got very carried away with the opportunity a couple of years back and the price got up to around 30p at one point. Why they didn't raise £15-20m there with a market cap in the range of £150m at the time I will never know. They could probably have got a big raise away with minimal dilution, fully/over funded the business and removed a lot of stress/management time from subsequent raises. They did eventually raise cash but clearly not enough and at much lower prices and only when they had no choice. Then they allowed the same to happen again, this time with the share price dribbling down consistently from 5.5p as investors worked out their lack of runway before they got it away at 2p today! Given they listed at 6p it's a pretty sorry tale and whilst I actually think they may well now go on to exceed that listing price from here a lot of this pain could have been avoided. Perhaps an experienced city hand on the board rather than media types might have helped avoid this. I'm sure they genuinely believed they could commercialise the business with the money they had but just goes to show how over optimistic directors can be about the timing of revenues and cashflow breakeven. Sosandar (LON:SOS) have been a bit guilty of the same thing in the past and I think they have a great business too, but these funding mistakes are fundamental and end up costing existing shareholders badly.
Anyway that said I will now look to pick some up as I reckon they are finally well enough funded and once revenues reach inflection point the change in cashflow generation should be pretty dramatic.
I'd tend to agree, I think the management and shareholder communication from Bidstack have been abysmal. They even have comments disabled when they post on twitter, presumably because they'd be bombarded by disgruntled shareholders - and rightfully so.
I have tiny holding, as the concept makes perfect sense, but as always execution is a completely different story. There has been no evidence thus far that the concept translates to a viable business.
There are some huge red flags, but if they can get their act together and get some traction, they could do very well.
So breakout if you dont mind me asking will you to be topping up on Bids at ~2p? i cant see a single sign they are improving things or an a viable path to profitability personally
CMO Stores. A quick way to value an IPO is price to turnover or market cap divided by turnover so 95m/45m (using Paul's figures above) gives a P/T of 2.1 which isn't too bad.
PIWORLD interview with Stuart Widdowson, Odyssean IT. Here, Stuart discusses investing with a private equity perspective. He looks to double client's money over 5 years. The trust is a JV with Harwood Capital, owned by Christopher Mills. Companies mentioned include Flowtech Fluidpower (LON:FLO) Sdl (LON:SDL) Elementis (LON:ELM) Xaar (LON:XAR) Clinigen (LON:CLIN) Chemring (LON:CHG) Vectura (LON:VEC) He is incredibly knowledgeable and very engaging. Highly recommended. Video & podcast.
If you're interested in Private Equity investments, over the next two weeks we have two events with Listed Private Equity, the organisation representing PE funds. During the two webinars, six funds will outline how they invest. The first is next Tuesday 6th July, 2pm when we are joined by CapMan, Gimv and Nb Private Equity Partners (LON:NBPE) The second is Monday 12th July, 2pm when we are joined by BMO Global Asset Management, CVC Credit Partners and Oakley Capital Investments (LON:OCI) Register here.
Other results webinars over the next week:
Panoply Holdings (LON:TPX) full-year results presented by management followed by Q&A. Register here.
Creightons (LON:CRL) full-year results presented by management follwed by Q&A. Register here.
Paul if you have time take a look at #AAA please - significant announcement and although the share is suspended one can gain some exposure by buying #ASLR - I first bought this at 3p and have bought over 40 times and now the market cap is £500 mill it deserves a look
I have been following AAA from the sidelines, but concluded that it was a Ramp. Very little real detail can be found out about it's purported investments, and there's a connection (ultimately) to the infamous Robert Bonnier (formerly of Scoot). Who knows, maybe there are some great businesses in the portfolios of the likes of All Active Asset Capital (LON:AAA) and the somewhat related (by certain large shareholders) Asimilar (LON:ASLR) but from what I can ascertain, there's a slightly strange rampy like smell about them both. Maybe Mr Bonnier is going to make a spectacular comeback. More background if interested.
When I tweeted a while back that I was unsure if All Active Asset Capital (LON:AAA) had an actual business there, I very swiftly received a response, allegedly from an Irish Stockbroker, saying: "From the snippets that we have been told a new ecosystem is beginning. Think of it as a socially responsible Facebook. Look at where they started and where they are now. Some early investors get the concept other old school investors don't". This was after the same person told me "Just shows Mark you don't know what you are talking about. You will be eating those words when you see what AAQUA brings to the table. We are buying the stock again today so crack on and keep them coming".
I thought the comment in bold somewhat summed it up for me. But this is mild compared to the abuse that some people receive on Twitter whilst commenting on stocks, so I got away lightly!
Also - as the brilliant Mr Contrarian says in his daily summary (above) - you don't have to delist here to gain a listing elsewhere. Maybe the reason it's delisting here is because of the disclosure requirements of a prospectus will show that All Active Asset Capital (LON:AAA) is a game of smoke and mirrors?
Can anyone here post some meaningful and accurate financial information about AAQUA and Sentiance, the two proposed acquisitions? I will metaphorically stand in the stocks and be willingly be pelted with rotten food, as penitence for this post!
I hope you are able to sell up and profit handsomely in due course Cleve (and any other holders out there), I have my doubts. I DMOR on this and the red flags were enough to make me run a mile. But well done to early holders of these - IF you can sell up.
ok lots there but I think mr Von Rosen of lotto land involved and nick Candy of Candy and Candy- I think the reason to float in the USA is because they value tech companies more highly and in the uk Tom Winnifrith keeps attacking and they are probably not in a position to reveal everything as lots of moving parts. They have raised 135 million from memory at 80 p a share - Sentiance is an AI company there are very few AI plays around and AQUUA allows you to control who holds your data hence the responsible face book line.
If you look at the larger share holders they do not seem to be selling and those that ramp usually start to get out and I do not get that feeling here - also AQUAA have been taking staff from the other big tech companies so with the fundraising they do not need any more money and whilst personally I would prefer it not to delist as it means it gets thrown out of my ISA which will be painful (not sure if it will get thrown out of my SIPP, I hope so as that will prevent future overfunding taxation) but if it lists in the USA then I guess there is no need for uk listing.
I can understand you being sceptical and I am all for that, always good to hear all views and I do think in the coming weeks that more information will be forthcoming which hopefully will answer more of your questions
Morning Cleeve,
I had a quick look, but All Active Asset Capital (LON:AAA) looks quite complicated, it's a special situation, that would take me hours to dig into, which we don't have time for here. We tend to focus on companies that are trading, and reasonably straightforward to understand, because otherwise we wouldn't get through 5-7 companies every day!
Sorry about that.
Regards, Paul.
thanks Paul understand your reasons
Hi Andy Sav
Best of the Best could do with some good news. It has been dropping like a stone!
Regarding IPO's , "The Lifecycle Trade" is supposed to be an excellent US based book which analysed the lifecycle of a number of recent IPO's. Just thought I'd mention it in case it's of interest.
Thanks Paul, for the review of CMO Stores.com Ltd.
I am grateful that you are starting to review the new floats coming to the market. I have looked at a few myself, but often find that they drop in value once the listings are live. Therefore, I am reluctant to get involved in the first instance and prefer to see what happens when they start trading on the open market.
I think the problem with new floats recently, is that there have been too many, and lots of them are priced far too high. Plus it's pretty obvious that some of the floats are lockdown winners (eg Virgin Wines Uk (LON:VINO) and Parsley Box (LON:MEAL) ) whose owners have decided to use the strong trading during lockdown as a platform to achieve a bumper payday by selling the business at an aggressive valuation, whilst glossing over the one-off boost to profits from lockdown, pretending that it's the start of stunning long-term growth.
Also, it's amazing how businesses that make little to no profit historically, are transformed into exciting growth companies generating stellar adjusted EBITDA in the Admission Documents! Hence I think a healthy dose of scepticism is necessary.
Ultimately, if the people who know the business best, are sellers, and they get to choose the timing & price, then risk:reward is probably skewed against us taking the other side of the trade.
That said, plenty of IPOs do go on to be very successful, I just think additional caution is needed.
Regards, Paul.
EDIT: Sorry, I put in the wrong ticker originally, I meant Virgin Wines, not Naked Wines. Have now corrected it.
Re Naked Wines (LON:WINE) if it was so overpriced at IPO why has it 3 bagged since, looks like the owners sold too early. Some IPOs are overpriced and do fall back within the first year, I recall Boohoo (LON:BOO) shares halving.
Morning herbie47,
My error, apologies I put in the wrong ticker. I meant Virgin Wines recent float, not Naked Wines. I've edited the comment above to correct that.
Incidentally, I think Naked Wines could be an accident waiting to happen. Clearly in a speculative phase, with people lapping up the story about non-existent profits actually being huge underlying profits once the marketing spend is ignored. Parsley Box (LON:MEAL) does the same thing. I don't buy it. But each to their own!
So just because a share price rises 3-fold (particularly when it happens fast) doesn't mean a thing about the fundamental of the company long-term. Things like that happen in bull markets, but are often speculative bubbles, with reality coming home to roost some time later.
You're right about Boohoo (LON:BOO) . It floated at about 50p, went to a premium, then disappointed in a profits warning. However, that presented a stunning buying opportunity, as I reported here at the time. The problem wasn't poor performance, it was just that expectations had been set too high at the IPO.
As you imply, there have been some excellent floats. The point I was trying to make, is that risk:reward isn't great with floats overall, because they're buffed up for sale, and the prices are often too high. So it's a bit like finding a needle in a haystack, so many go wrong that I'm wary, until they've established a track record over say 2 years.
Regards, Paul.
re: cmo stores
I've had some experience with their roofing company in the past and found that they were cheaper than the usual merchants for several velux balcony windows I was seeking. So I simply returned to our usual merchant and he matched the price. Roofing superstore couldn't go any lower. Yes this experience is limited but I question their competitive advantage if they couldn't bring their price down beyond that of a typical merchant. It is something I'll certainly keep an eye on.
Nice to see Best Of The Best (LON:BOTB) appear on the Jim Slater ZULU Principle Screen
Yes but that is based on 143p eps for fy 22 which has not been changed following the rns about slowing sales. The view of the market has clearly been that 143p is not going to happen given the sp fall - once we get a clearer picture of actual performance it may well therefore not be a Slater stock (I hold)
Best Of The Best (LON:BOTB) Probably not much consolation to his son! (Or me I hold 6.1% of portfolio and small top up yesterday)
Good morning! I’d be keen to hear your thoughts on the GYM placing. Have a great day!
OK, I'll take a look at GYM next.
P.
Also interested in this as a holder. On the face of it the reason (rapid expansion into currently bargain space) sounds solid but have seen some comments around this being a bit of a smokescreen.
Share price hasn’t reacted too badly this morning so far and placing was at a discount of only 3.5%.
An acquisition by Team17 (LON:TM17) announced this morning looks good. Expected to be immediately earnings accretive and all of their apps on the App Store look highly rated.
£TM17 - earnings accretive acquisition.
But isn't it the case that any acquisition of a company making profits funded by cash/debt, but not equity, is by definition going to increase earnings per share.
Hi shipoffrogs.
Re. Team17 (LON:TM17) ‘s comment about their acquisition being earnings enhancing, I read this as saying that the RoC of the acquisition target company is lower than their own cost of capital (being the weighted blend of TM17 ‘s average cost of debt and average cost of equity). Although funded out of cash/debt rather than the issue of new equity, their overall cost of capital is still the relevant benchmark IMO. Either way, Mr. Market seems quite happy with the deal at the moment.
Gus.
Not too much small cap news with this morning’s RNS. Now well above the SCVR market cap limit, nice bolt on acquisition announced for video games developer Team17 (LON:TM17) which is acquiring Story Toys, an “edutainment” developer/distributor (their phrase not mine) for up to US$49m. Deal is being funded out of existing resources.
https://www.investegate.co.uk/....
Extends Team17 (LON:TM17) ‘s product range and by adding a younger target audience (under 8’s!) provides a natural feeder into the rest of Team17’s portfolio as well as being expected to be immediately earnings accretive (albeit limited financials given). Always a risk with this kind of acquisition that the IP/goodwill walks away but at face value seems a good fit. Impressive company, especially the CEO, with very high “Q” scores although share price probably overheated last year and it’s currently ranked as a Falling Star. I hold.
Gus.
My morning smallcap tweet:
Microsaic Systems (LON:MSYS) Diurnal (LON:DNL) All Active Asset Capital (LON:AAA) Distribution Finance Capital Holdings (LON:DFCH) E-Therapeutics (LON:ETX) GYG (LON:GYG)
Microsaic (MSYS) development and demonstration of the first, real-time monitoring Process Analytical Technology solution for the on-line production of biotherapeutic drugs such as vaccines and anti-cancer treatments. "We are not aware of any other technology that can simultaneously analyse small and large molecules as part of on-line production.." [SP=0.22 Cap=13m]
Diurnal (DNL) receives UK Marketing Authorisation for Efmody as treatment for the rare condition congenital adrenal hyperplasia. [SP=63.67 Cap=107m]
All Active Asset Capital (AAA) £150m placing at 80p, a 50% premium to pre-suspension price, "to pay the subscription money due following the exercise of the remaining balance of €119m of the AAQUA Option and to provide growth and working capital". Proposes leaving AIM and listing on an international exchange in due course. Co doesn't need to cancel AIM list to list on another exchange. [SP=53 Cap=5m]
Distribution Finance Capital (DFCH) Q2 new loan origination over £295m (£115m) but loan book flat at £166m. Blames "increasing commodity prices and a knock-on impact on their supply chains. Manufacturer production levels are exceptionally high, however the achievement of projected delivery dates have been materially impacted." Expects growth to normalise through H2. [SP=59 Cap=109m]
e-therapeutics (ETX) milestone payment from Galapagos. No £££. [SP=22.1 Cap=114m]
GYG (GYG) 3 week extension to PUSU offer deadline. [SP=85.1 Cap=40m]
Good morning. Yesterday was quite a busy day, but I wonder if there is time today to have a look at Finncap (LON:FCAP) prelims from yesterday. The results will have largely been predicted from an earlier statement in past weeks, but in the detail I thought that ahead of the opening yesterday, they looked good. Would there be time today to have a look at them and comment on why the market didn't seem to like them? Thank you.
Scs (LON:SCS) Ditto!
Norfolk, as I thought you discussed here with another subscriber yesterday, there hasn't been any news from Scs (LON:SCS) (I hold).
The last trading update from SCS was on 16 June, which I reported on here.
Regards, Paul.
Yes my mistake I missed the SCVR from 16th June, although I am an avid reader!
Hi ridavies
re Finncap (LON:FCAP), I don't follow what you saw in the detail of the results that you thought looked good. It has been known for some time that last year was a blast, and it is encouraging that they are hoping for same again income this year. The market must have felt that same again wasn't quite good enough - stockbroker earnings are notoriously volatile, and they tend not to be highly rated. Personally I hold because I think they are a well-run outfit, but I am starting to feel that they are high enough for the moment.
SundayTrader, Thank you for that response.