Small Cap Value Report (Fri 2 June 2023) - DPH, PAY, GTLY

Good morning from Paul! A leisurely start this morning, as it's Friday.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Paul’s Section:
Dechra Pharmaceuticals (LON:DPH)
Up 8% to 3644p (£4.1bn) - Recommended cash takeover bid - Paul - AMBER
Shareholders in mid-cap Dechra Pharmaceuticals (LON:DPH) will barely need to dust down their Coronation bunting, to celebrate this morning, with a cash offer priced at 3,875p. That values Dechra at £4.46bn. As you can see from the chart below, it already had a bid premium in the price, hence why the 8% uplift today is modest. The bidder is Scandinavian private equity group, EQT.
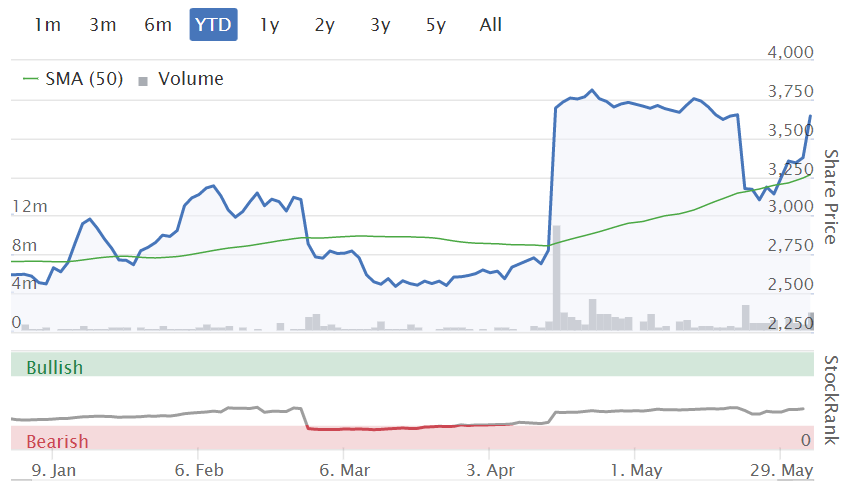
Dechra also puts out a profit warning today, so shareholders got lucky that the takeover bid has happened, as otherwise this probably would have been a nasty down day -
The Dechra Board expects that full year underlying operating profit for the year ending 30 June 2023 will be materially below £186 million, the guidance provided within Dechra's interim results announced on 27 February 2023 ("FY23 Profit Forecast").
Paul’s opinion - none, as it’s not a company or sector I follow. However, the shareholder value created here look fantastic, so well done to anyone who has owned this share over the long-term -
PayPoint (LON:PAY)
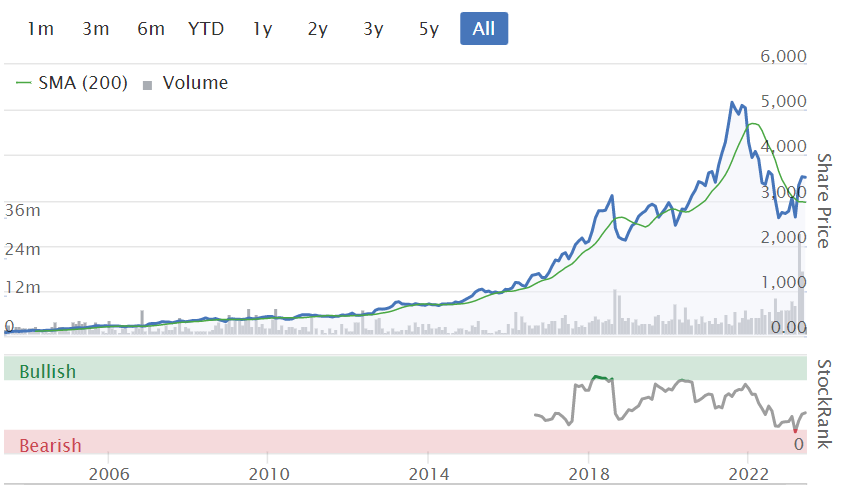
Up 6% to 401p (£290p) - Trading Update - Paul - GREEN
This share came up in the “BASH” discussion session at Mello which I participated in, so I did some very quick research on my phone a few minutes beforehand. The result of my shallow research was positive, that PAY looked great value, but the obvious concern is whether its core activity of utility prepayment cards has longevity or not? Mind you, investors have been worrying about that for many years, and like newspapers too, it keeps spewing out profit/cashflow despite being possibly in long-term decline. Plus it’s making acquisitions too, including an opportunistic bid for gift card business Appreciate.
Positive Trading Update and Confirmation of Preliminary Results Date
Here’s the whole of today’s update -
PayPoint today reconfirms the guidance issued in the post-close trading update on 20 April 2023 that Group net revenue for the financial year ended 31 March 2023, excluding Appreciate Group, is expected to be around £125m (FY22: £115.1m) with accelerated revenue growth across all three business divisions. The Group anticipates that profit before tax for the financial year ended 31 March 2023 will be at the top end of the range of market expectations, excluding exceptional items and Appreciate Group impacts since completion of the acquisition, driven by the strong momentum across the business.
The Group has materially enhanced its platform and capabilities in the past year: our integrated payments platform has expanded with the addition of Open Banking and prepaid solutions to our solutions across card, Direct Debit and cash; our retailer and SME proposition is now stronger than ever, with multiple opportunities for partners to earn revenue; and our e-commerce offering has gone from strength to strength, delivering record volumes and an unparalleled in-store experience for consumers. This enhanced platform will unlock future opportunities and deliver sustainable and profitable growth for shareholders, underpinned by our business-wide partnership philosophy and intensity of execution.
The integration of Appreciate Group (now known as Love2shop) continues to progress well, opening up further revenue opportunities, expanding our capabilities further in the gifting, rewards and prepaid savings markets and enabling the creation of enterprise level solutions into new markets, combining our extensive payments and commerce solutions across the Group. These opportunities have accelerated since completion.
Trading has been positive early in the first quarter of FY24, and we look forward to updating the market further at our preliminary results for the year ended 31 March 2023 on 6 July 2023.
Sounds pretty good to me.
A note from April 2023, kindly published by Liberum, via Research Tree, estimates 58p EPS, and 41p divis for FY 3/2023, rising slightly for FY 3/2024.
At 401p per share, that’s giving a remarkable yield of just over 10%, and a PER of only 6.9x
Paul’s opinion - value investors would be negligent not to do more research on this share, when the value measures are this cheap! I can only give it a thumbs up, so green opinion from me, due to the fantastic value on offer here.
Gateley (Holdings) (LON:GTLY)
Down 2% to 163p (£206m) - FY 4/2023 Trading Update - Paul - GREEN
Gateley (AIM: GTLY), the legal and professional services group, is pleased to announce a trading update for the year ended 30 April 2023 ("FY23"), ahead of the publication of its audited results in late July 2023.
I’m not keen on this headline, as it’s ambiguous -
Growth in-line with market expectations
Thankfully, the next paragraph clears up any ambiguity -
The board is pleased with the Group's performance for FY23, a year of further revenue growth demonstrating the resilience of the Group's diversified business model. Revenue for FY23 is expected to be not less than £161m, a c.17% increase on the prior year (FY22: £137.2m) with underlying adjusted profit before tax expected to be in line with market expectations.
The Group had net cash (pre IFRS 16 liabilities) of £4.3m at the period end.
Many thanks to Liberum, for an update note today, forecasting £24.2m PBT, up nicely from £21.6m last year. In EPS terms, it’s 15.3p for FY 4/2023, with just over half paid out in divis of 8.8p.
Valuation is therefore a PER of 10.7x, and yield of 5.4% - good value I’d say.
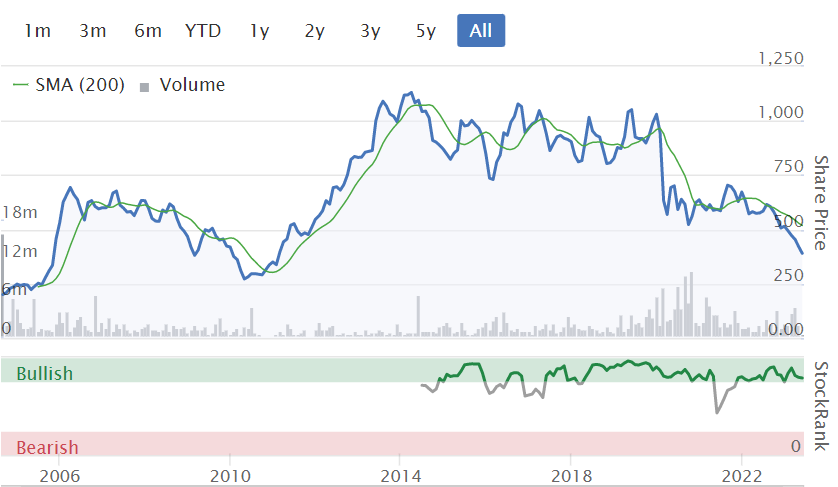
Look at the performance graphs, which are strikingly good for a share that’s only rated at 10.7x
The market seems to be giving GTLY little credit for a decent track record of growth -
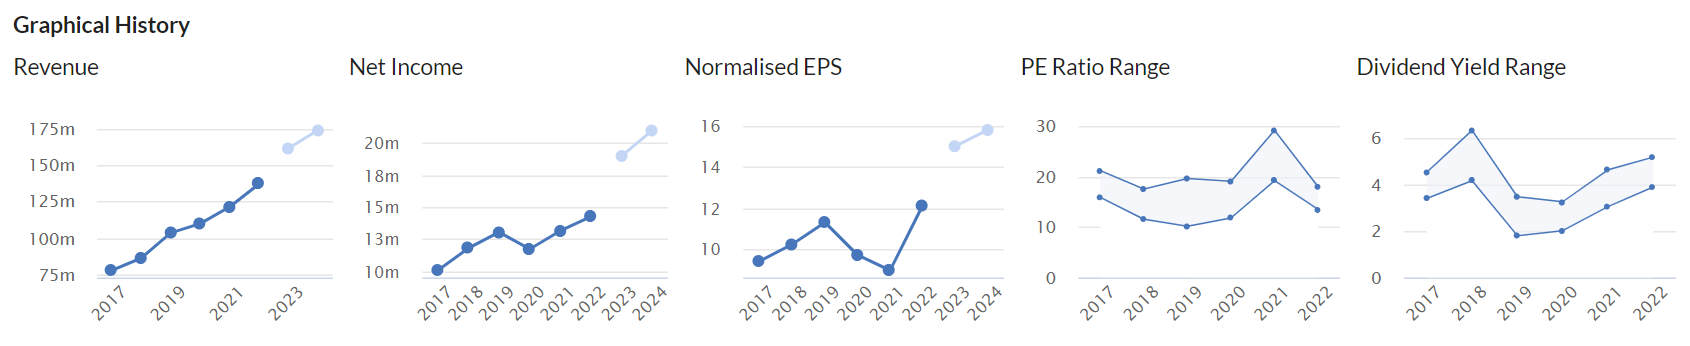
Paul’s opinion - I’m not a fan of legal services business, or indeed any people businesses where there’s a natural conflict of interest between fee earners, and outside shareholders.
However, the sector has some striking bargains in it, where this might be a good time to pick up some cheap shares, and GTLY seems to fit the bill.
I also recently looked at Knights group (LON:KGH) which looks astonishingly cheap, on a forward PER of just 4.3
Given the cheap valuation, and in line trading update today, I haven’t really got any choice than to view GTLY shares positively, so it’s green from me, thumbs up (the same thing).
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

35 comments
Didn’t Buffet strike gold with Blue Chip Stamps? I see Paypoint / Appreciate being a similar model. How long do you have to wait to write back unspent deposits to P&L? Interested in other peoples thoughts.
Hi Paul - did you do an interview with the CEO of XP Factory (LON:XPF) ? (and if you did, was it for Stockopedia or a private chat?)
It’s a big holding of mine - so trying to read everything I can.
(aplologies if you saw this comment already, I posted quite late yesterday so might not have been seen)
I could be wrong but i think if you go to the stock report of the stock you are interested in nd click discussions, this shows all mentions of the stock, hope this helps, looks like it was discussed in May by Paul
Reading an interesting note on UK fund outflows in the last 2 years.
Can understand why UK shares are so weak, with such sustained selling pressure. Eventually outflows will turn into proper inflows, who knows when? Could be next week or next year or even longer.
It will happen tho, and there'll be big money to be made as cash starts to flow back into the UK market. Key from my perspective is to have enough cash to be able to take advantage when it happens so im obsessive about stop losses to just stay in the game. Everyone has their own method tho.
"In the past two years, investors have pulled £19.7bn out of open-ended UK equity funds – the equivalent of the entire market capitalisation of Tesco – with negative net sales in all but two of the past 24 months, and outflows of over £12bn in the last 12 months alone. "
Retail Sales to April. Id imagine May was negative. Seeing more money move into fixed income this year. Certainly did a good job of panicking right at the bottom last Sept/Oct
This is a reminder that one can do all the analysis in the world but that effort will always be trumped by money flows. Politicians have noticed that the stocks and share ISA is not doing its job of directing equity towards British companies, being a significant subset of the London market. Should those rules change then we should see significant indigenous flows back to the home market.
Part of the blame for this lies with the way London listed companies return cash. The focus on dividends makes technicals look awful and gives a completely misleading perspective on the returns the market has generated. Companies should direct much more of their returns at buy backs. This keeps share prices heading up and makes the market overall look much more attractive. This is at least part of the reason why New York markets have forged ahead.
It is in one sense good to see that equity income funds are the ones selling off. These are like a value trap guided missile and their recent dominance of the fund industry has in part shaped the London market. That said they were a function of ZIRP and it could just be that funds are going backed to fixed income, which is where they would have been under normal conditions.
andyfwwtench
Not sure about this bit from your post:-
“The focus on dividends makes technicals look awful and gives a completely misleading perspective on the returns the market has generated. Companies should direct much more of their returns at buy backs. This keeps share prices heading up and makes the market overall look much more attractive. This is at least part of the reason why New York markets have forged ahead.”
The FTSE 100 isn’t much higher now than it was at the end of the last Century, but if adding dividends reinvested it has nearly doubled. And many shares paying decent dividends have soared, so much so that in time investors get their original stakes back every year just from their now 100%+ dividend yield every year.
There’s a place for buybacks and many Companies combine the two. But it’s a fallacy that “buybacks keep share prices heading up.” There’s a very long list of Companies where the shares are now much lower than all their buyback prices. Also if you were right all we investors would need to do to ensure investment success would be to buy shares in Companies buying back their shares.
I wonder if it the normal tail chasing by most investors. The U.K. market did badly last year compared to global funds so sell those funds. Eventually it becomes so cheap that a bounce back occurs. This is one reason markets follow such a volatile roller coaster.
My morning smallcap tweet: A fork in the road or a knife in the back?
PayPoint (LON:PAY) Revolution Beauty (LON:REVB) Anpario (LON:ANP) Pelatro (LON:PTRO) Proton Motor Power Systems (LON:PPS), Gateley (Holdings) (LON:GTLY)
◄PayPoint (PAY)► guides FY-Mar at the top end of market expectations, excluding exceptionals and Appreciate Group impacts since acquisition. [SP=377.5 Cap=274m]
◄Revolution Beauty (REVB)► H1-Aug (!) postax loss £13.4m which apparently is a 54% growth from a bigger loss. Guides FY-Feb low single digit rev growth. This Q1 rev in line. Guides FY24 high single digit rev growth, and adj EBITDA (at const FX) high single digit £m. Still suspended. [SP=8.25 Cap=26m]
◄Anpario (ANP)► £9m tender offer at 225p, a 16% premium. [SP=194 Cap=47m]
◄Pelatro (PTRO)► wins $650k PA. No duration stated. [SP=6 Cap=3m]
◄Proton Motor Power Systems (PPS)► order for a containerised fuel cell power plant with a power output of up to 240 kW. Delivery in 2024. [SP=9.87 Cap=153m]
In line: GTLY
Yesterday Trinity Exploration and Production (LON:TRIN) released its full year results. Just a minnow in the oil sector. Good results, being doing a buyback and going to commence dividends. Worth further investigation imo. Cenkos released an update and are increasing valuation to 227p which is nearly a3 bagger from current price. ST from investor chronicles was pushing it 6 months ago when the price was about 120p I think. Technically it’s in a downtrend still but possible the bottom is in now. Not far off the 50 EMA, which if it breaks above that it could be back to 120p quite quickly. As I said, worth further investigation.
See Anpario (LON:ANP) announced earlier a Tender Offer @220p so not much of a premium to recent trading levels.
Presume it makes sense for the company to deploy funds in this way but how attractive is it for (smaller) shareholders who've seen such a savage recent SP decline? Possibly of interest to institutions sitting on chunky positions where they might welcome a quick, clean exit?
I hold and wont be selling at these levels.
Iqe (LON:IQE) Can anybody make sense of the director shareholding announcement ("Dr Drew Nelson, Non-Executive Director, has delivered a further 699,647 ordinary shares of 1 pence each in the Company ("Ordinary Shares") to Equities First Holdings ("EFH"), having received a margin call") ? I don't like the sound of a margin call. Wouldn't this mean there are more shares coming on the market and forcing the price lower? I may have got hold of the wrong end of the stick though! I'd just added this to my folio as I liked the big (£2.5m) director support in the fund raise.
Funnymoney: from their website it seems that EFH lend money by taking a transfer of shares as security, at some agreed ratio of the size of the Loan To the Value of the security (LTV). I assume that if the value of the shares falls below thee agreed minimum LTV, they request more shares to be transferred to them to maintain the minimum LTV, and this is the 'margin call'.
Others here may be more familiar than I am with this form of loan.
Thanks for that. I should have noticed the words "Equity First" and run a mile!
I never feel that these contracts are a good sign. The contract permits Directors who want to sell out their shares to half disguise this by "borrowing " against the shares. The amount borrowed is some way below the share value allowing EFH leeway to sell out the shares and cover the borrowing. The Director then has got cash out of his shares while they continue to fall (encouraged by the selling that EFH has to make if the Director does not repay his loan). Furthermore it does not immediately show any reduction in the Director's shareholding, as, initially the shares are simply pledged against the "loan".
There is, as apparently in this case, a provision for the Director to provide EFH with more stock (if they have or can get any) to ensure that the value of falling stocks still cover the borrowing and to prevent EFH being required to sell. It is not so usual to see Directors meeting their margin calls as in this case.
Aislabie (your para 1) : Exactly !
EFH was behind the lending to Quindell and IQE directors back in the day, both of whom did exactly that.
HI Nanotrader - the short answer from me is not much, adding to a few things but I have remained nervous but fully invested. The latest bear instalment is that we should be worried about Treasury issuance sucking liquidity out of the market following debt ceiling conclusion. To me, since debt ceiling would appear to have already sucked liquidity out of the market, this doesn't make sense. I remain of the view that inflation "should" tick down for the next two months...if it doesn't yields will rise...and then later in the year may even rise again. This means rate cuts less likely.... and the big slowdown recession just takes time. It takes longer this time because the mortgage market has had less abuse - interest only type lending. Anyway for me .... higher inflation is a problem for Treasury issuance not a recession. AND given the euphoria around Nvidia there would appear to be plenty of money sloshing around at the moment. So with the debt ceiling out out of the way...feels like things "should" loosen up.... we see.... initial signs are good...and defensive "tech" positioning extreme. In a week or so we will have a clearer idea of how the mkt wants to swing.
All the best...
Paul I would be very interested in your thoughts on Avacta. It has over the years been a real jam tomorrow stock based on its Affimer technology bought out of Leeds University. These are being developed all be it at the normal drug development pace, all be it their technology does seem to have some significant benefits to the way we currently treat cancer to name but one benefit. This is their Therapeutic business. They have also split out their Diagnostics business which was generated really from Covid where they failed to capitalise on what they claim is a clear advantage of Affimers over Antibodies, namely you can emgineer Affimers much more quickly as well as they are about a tenth of the size. So they have recently bought two Diagnostics businesses on the Continent with the latest this week. a Belgian business Coris BioConcept for £7m cash and a £3m share if targets are met. Given the whole business had £41m in cash prior to the deal with no real income yet and considerable costs to cover I am left believing perhaps they feel the Diagnostics side will provide cash for the Therapeutics side. Given the dilution over the years and higher interest rates I suspect this would make sense. Added I do believe Diagnostics is a way forward given the challenges faced in the Health world. I still struggle to see a GP if I need one (fortunately I am in good health) but when I do they seem to Google a response (a good sign for where AI may well hit deep!) Anyway as its a light day I thought I would share something that has been taking my time of late. Their report and accounts have been published on their website today. All the best.
Ed Croft’s brother likes it, Ed recently said. I’ve been watching and trying to see if of interest.
Went to my surgery this morning, fed up with paying to listen to a Partner's spiel and then joining a virtual queue. Was prescribed by a GP 3 weeks ago and went to discuss progress now. Receptionist's window was closed from 8 am to I don't know when, but returning at 9.30 managed to get an appointment for a date two weeks on. Feeling better already now I've had this whinge:-). Google is fast but won't hand you onto a Consultant. Sorry about that.
Silver
Not sure i can continue living in this country if it is impossible to see a GP.
PayPoint (LON:PAY) not an overly easy business to understand, but after doing my research; reading the previous interims, checking debt levels and available finance, digesting the recent updates and reviewing the investment metrics the shares just appeared too cheap.
I looked at the commentary by Graham on the SCVR and read various reviews, especially by Mark Simpson. I also took note of the recent acquisition of Appreciate and the fact that it had been part funded in PayPoint (LON:PAY) shares. Mark made the point there may be pressure on the share price due to Appreciate holders selling their small holdings into the market. There is also the issue of liquidity or absence of it in unloved UK small caps.
I came to the view that PayPoint (LON:PAY) is financially sound and trading well, and as far as I can tell the share count has not increased for sometime, although it must have issued equity to part fund the Appreciate acquisition. The dividend yield was approaching 9% when I started buying and covered 1.5ish times; it was trading on a 7ish PE, yet no one was interested.
I started buying at around 420p and have since added, most recently at 387p. I admit to being surprised when the share price closed at 377p yesterday. I began questioning what I had I missed? This morning confirmation of current trading is a relieve and in part a vindication of my research, also it doesn't include any contribution from the Appreciate acquisition.
PayPoint (LON:PAY) may not be everyone's 'cup of tea' but at these levels it is absolute buy in my opinion.
Thoughts and comments welcome. Views Paul?
while all quiet I mention some contrast in US market.
the the Lululemon up 13% and Dollar General down 20%.
so much for the value shopping !
Admittedly it is the China effect elevating the luxury.
Luxury and the big tech are surviving everything you throw at the them.
big techs are up 61% this year!
Luxury brands have been hit recently. Slowdown in the US and now China this week. Look LVMH Moet Hennessy Louis Vuitton SE (EPA:MC) and Burberry (LON:BRBY)
If I had enough cash I would buy more Burberry (LON:BRBY) now.
Bought some already.
Its a transitory state
Morning all, just thought I'll get people's opinions on what they are doing in terms of portfolio management. I've notice my holdings grinding down slowly on no news. Sometimes it pays to take the stop loss e.g. iEnergizer (LON:IBPO^E23), M&C Saatchi (LON:SAA) as bad news soon hits, but other times likeVolex (LON:VLX) , Yu (LON:YU.) Redde Northgate (LON:REDD) the news was good and they shot up again. My current dilemma is Card Factory (LON:CARD)
Some of my holdings have been bounding down two steps at a time of late, I'd be delighted if they only ground down slowly!
I was saying here yesterday that at times of stress on my holdings I like to sanity check each and remind myself why I was holding. The lurch down on no news on Wednesday, following three weeks of declining share price for Card Factory (LON:CARD) [I hold] and so is a case in hand. I think with Card Factory one is invested in future performance from self help measures, expansion opportunities, debt reduction, a stable share count and the potential in due course for dividend.
It has had a very good run since last summer but I still personally think offers growth are a reasonable price type value. There are bear points though, in particular in concerned whether the business can truly become multichannel, and about the ongoing decline of the high street which must affect footfall. Nonetheless it passes my tests and nothing has fundamentally changed in recent weeks except the share price, and Stockopedia noting some fall off in momentum.
Re Card Factory (LON:CARD) - FWIW, On a 2 year basis I also think it offer decent value because it is NOT relying on becoming a truly multi-channe. By 2027 online is still a small % of the business
Nevertheless,it is dominant in store-led sales that are forecast to remain +/-80% of the market with a good size moat (vertical integration and its brand) in part by filling in the few remaining gaps in coverage and upgrading stores at a time when doing so favours the leasee.
I also like its focus on expanding and being a leader in near adjacent markets like balloons and small gifts (although it over-cooks by trying to inflate the addressable mart to £14Bn; really on the numbers it presents it is 3-4Bn and I'm happy with that).
It is steadily sorting out the consequences of its previous financial miscalculation by using cashflow to pay down debt, and will be able to resume dividends at a modest but progressive level from next year which will help the share price. However, it remains a bit vulnerable.
My final wonder is that now the shine has come off Moonpig/online, whether a consolidation of CARD + (insert major online brand!) would make sense at some point, allowing CARD to junk its online offer entirely. If not, then based on its physical store brand , a weak 3rd place in online looks sustainable if not very profitable.
Net, I'd all this suggests the current price is about right and no obvious buy more/sell decision is indicated now. (I hold)
Regarding £CARD. Occassionally visit Merry Hill shopping centre and noticed opened third outlet there, all look quite busy compared to competitors, seems a popular choice and hopefully turnover can be turned into profits. Hold PayPoint (LON:PAY) as well and considering adding on results.
Hi Nanotrader09,
I think it's a difficult market for sure, and sometimes doing the "right" thing can not work out and vice versa.
I've had a tough year as I like to buy with a bit of momentum but I also use stop losses. So it's meant some buying high and selling low as momentum has been short lived at times. I think the market has probably suited traders and conviction holders and punished those in the middle.
Going forward I see it as 3 options. Be more patient with buys and wait for strong pullbacks (to give a bit more margin of safety); widen stops and be more of a pure fundamental investor; or keep stops smaller and be more nimble to be out if it goes wrong.
I haven't decided the best plan yet, probably the first option combined with the third. But as ever it is easier said than done.
Morning Paul. Will you be posting a review of the ME International (LON:MEGP) update from yesterday, as I think you hinted at doing this? Thanks
Ignore!
Yes, I'll have a look at ME International (LON:MEGP) today, sorry for the delay from yesterday. A nice response to results from the market, up about 10% yesterday, and it's one of my favourite value/GARP shares, which is now the top performer on my "runners up" list of upper medium level conviction value/GARP share picks for 2023.
Hi Paul, what are your thoughts on the Polarean Imaging (LON:POLX) warrant extension? Seems poor to me when he has had 10 years to cash them in already.