Small Cap Value Report (Fri 2 Oct 2020) - SAGA, CNKS, WIN

Good morning, it's Paul here with Friday's SCVR.
Portmeirion interview - here is the link to my audio interview today with Mike Raybould, CEO of Portmeirion (LON:PMP) (I hold), which I hope you find interesting.
Timings - should be mostly done by 1pm.
Agenda - as usual, Friday is quiet for announcements. These are the companies (below) that I'm going to be writing about today. If a company doesn't interest you, then please skip to the next section. I cover about 500 companies in total, which should provide enough variety for everyone. Comments on which companies I cover are distinctly unwelcome (because they just cause negativity), and I don't take any notice of them anyway! If you don't find my reports interesting, then maybe don't read/comment on them?
Saga (LON:SAGA) - results of open offer (refinancing)
Cenkos Securities (LON:CNKS) - Interim results
Wincanton (LON:WIN) - trading update
.
US President - covid
I've just heard the news that President Trump, and the First Lady, have tested positive for covid. That's knocked the futures overnight, as it throws a spanner of uncertainty into the US election. The comment that he will be continuing with his duties as normal, is pie in the sky. As a 74 year old, overweight man, he's at high risk. This virus can knock the stuffing out of you, for quite some time, as I experienced in March/April. It will be interesting to see how things pan out - will someone deputise for him? Whatever people think of his politics (no comments on that either please!), basic humanity means I wish him & his wife a full recovery.
.
Wincanton (LON:WIN)
220p (up 5%) - mkt cap £277m
· Trading remains resilient underpinned by strong eFulfilment performance
· Agreement reached on 2020 triennial valuation of pension scheme
For background, it's worth recapping on my notes on the trading update here from 20 July.
Wincanton plc, the largest British third-party logistics company, today issues the following trading update ahead of its half year results for the six months ended 30 September 2020.
- H1 was "resilient"
- eCommerce is growth area
- "Encouraging" new business wins (examples given, of big name client wins/renewals)
- Guidance unchanged from 9 Sept update (materially ahead of [greatly reduced] forecasts)
- Results for H1 will be issued on 5 Nov
- Very surprising to see a net cash position, but we're not told how much of this is due to temporary deferrals of creditors;
net cash position of approximately £60m at 30 September 2020 (net debt at 30 September 2019: £14.8m).
Pension scheme 2020 triennial valuation
This is a material issue for WIN, because the pension scheme sucks so much cash out of the business, in deficit recovery payments.
For anyone not aware, pension scheme accounting is bizarre, in that the calculations which go into the accounts are different from the usually harsher calculations used for the actuarial basis which determines the cash payments companies have to make. Therefore the actuarial figures are more important, in my opinion, since they drive actual cash outflows from the company. Hence why we need to look carefully at these 3-yearly actuarial calculations.
Main points;
- the recovery plan will run to 31 March 2027 (unchanged)
- £18.2m p.a. from April 2021 through to March 2024, increasing annually from April 2021 in line with the Retail Prices Index
- £21.3m p.a. from April 2024 to March 2027, increasing annually from April 2024 in line with the Retail Prices Index
Clearly these are huge amounts (total £118.5m), for a £227m market cap company, but these have been reduced by £6m p.a., compared with the existing, 2017, plan. So that's good news. Perhaps surprising, given that ultra low interest rates are extending liabilities. It says that longevity assumptions and strong asset values have helped in this regard.
The above payments will be deductible for corporation tax
The actuarial deficit near market lows at 31 Mar 2020 was £154m, which reduced substantially to £105m at 30 June 2020. Very sensibly, the trustees agreed with the company to de-risk the pension scheme, in order to lock in the lower deficit figure. That's really good news I think, as it now largely ring-fences the pension deficit as a known problem, which should now be largely fixed in size, and not capable of ballooning out of control again.
My opinion - this is good news. The pension deficit now looks much more manageable, although still a huge drain on cashflows for the next 6 years. That's why the PER is low with this company. The shares are cheap because so much of the cashflow is having to fund the pension deficit, hence limits the amount that can be paid out to shareholders in divis.
The business itself is doing OK, although note that the ahead of expectations stuff is because expectations were lowered so much, not because the business is performing brilliantly. I'd say performance has been solid, in the circumstances this year.
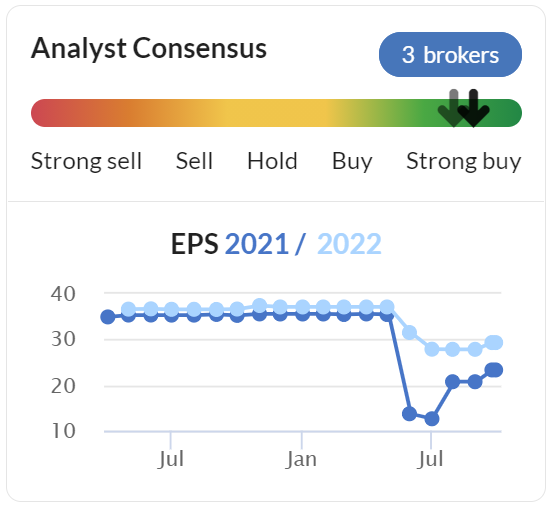
As you can see, broker expectations are still quite low, but rising, as the situation improves after lockdown.
I still have concerns over its weak balance sheet, but today's positive update re the pension scheme makes me a lot more comfortable about the overall risk. It seems a decent business, although logistics is not a sector that interests me for investment.
.
.
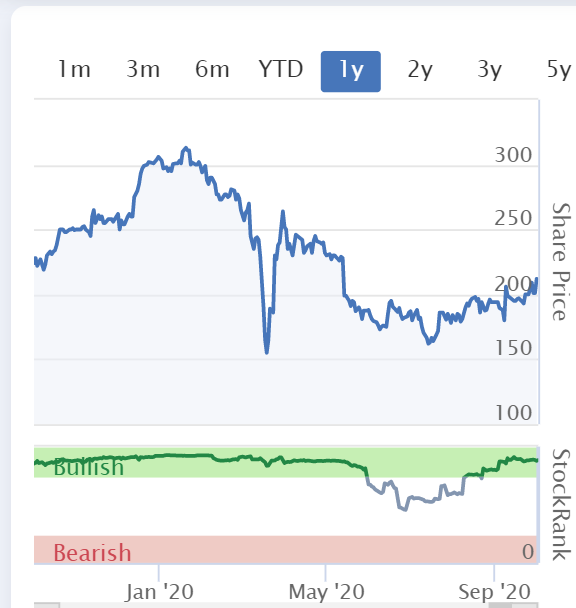
It's possible there might be a trade here, for a gradual re-rating, as risk recedes?
.
.
Saga (LON:SAGA)
Share price: 12.55p
No, shares: 2,093.9m total after fundraising (including 971.9m new shares)
Market cap: £262.8m
(I hold)
I've updated the market cap above, for the newly issued shares. It's a rather complicated fundraising, with various clawbacks, but the whole thing was underwritten, so once a few technicalities are completed, the deal is as good as done.
I think this is a potentially very interesting situation, which I've done quite a lot of research on. Saga is a tremendous brand, which has been neglected over a 15-year period of mismanagement under private equity, and then public markets. As is so often the case when private equity get their teeth into good companies, they ruin the company by loading it up with far too much debt, and running it for maximum short term cashflow. Thereby often causing a longer term decline of the business, and its brand values.
The good news with Saga, is that it's still a strongly profitable, and cash generative business - primarily the insurance division, which is trading OK (see recent interims).
The problem division is travel, with its package holidays on hold at the moment, which isn't a disaster because most costs are flexible. The more troublesome part of travel is that, with very unlucky timing, Saga commissioned & bought (with debt financing) 2 brand new all-balcony, modern cruise ships. They are mid-sized with capacity for about 1,000 passengers each. With covid/lockdown these shiny new ships, which are budgeted to make £40m p.a. EBITDA each, have been idle, and the cash drain from the travel division is a (manageable) £6-8m per month - covered by profits from the insurance division. Hence there should not be any solvency issue with Saga, now that it has used the current fundraising to clear most of the bank debt (leaving behind ring-fenced debt for the cruise ships, and a £250m bond, which the company says it should be able to repay from internal cashflows by the time it falls due in a few years' time).
Cruises are scheduled to resume in Nov 2020, but I'd guess that's looking unlikely now. Although note that the company has reassuring plans for covid measures on the ships, including social distancing, and interestingly fresh air (no recycling) aircon. Plus every cabin has a balcony. Saga customers are itching to go cruising again - the company said several times on a recent webinar that "demand is not a problem", they're already fully booked for the new ship, if it is allowed to sail. Once these ships are operating again, then Saga should be a prodigious cash generator again (we're talking over £200m p.a. positive cashflows likely). I think that could trigger a serious re-rating of this share, but obviously we have no guarantees on the timing of this.
Operational turnaround is already underway, under newish management, with a very sensible strategy. Before pre-judging this, I do urge readers to view the recent interim results webinar, which sets out in great detail everything you need to know. Hmmm, I can't seem to find the video webinar, but here are the 74 presentation slides from it, giving the key info. You cannot make an informed judgement on this share without having examined this in detail, in my view.
EDIT: I just found the link for the webinar, here. End of edit.
What interests me most, is that the equity fundraising has been underwritten by Sir Roger de Haan, a former CEO and son of the founder of Saga. He is returning, and has bought 26.4% of the company in this fundraising. He personally underwrote £100m of the £150m total fundraising. A key element of this, is that he injected £60.5m at a share price of 27p - more than double the current share price of 12.5p. If the founder's family think it's worth at least 27p, then I sit up and take notice. He paid 12p for the balance of his shares, as did everyone else, including those of us who took up the open offer (43.6% take up).
The company also mentioned in passing recently that it had turned away a tentative 33p takeover offer. Again that excites me, given that I can buy at 12p, for obvious reasons.
My opinion - there's no guarantee that the turnaround will work, although even if business continues at the current level, then the shares are still a pretty decent bet. Once travel resumes, then the company would clearly be worth a lot more than the current market cap, and the short term losses of £6-8m per month are manageable.
The debt position looks under control, although I haven't managed to find detailed information on the ship loans, because that pre-dates the latest Annual Report. I think one of the capital repayments has been deferred. I don't see debt providers being difficult about this, after all why would they be difficult? Do they want to repossess 2 empty cruise ships that can't currently be operated? Of course not, so it stands to reason that the provider(s) of the ship loans are likely to be flexible if needed.
We discussed Saga at the recent Mello Virtual evening, with me being the most bullish. Everyone else on the panel commenting that they'd like to wait and see how the turnaround goes. That's fine, but of course once the ships are cruising again, and cashflow is rolling in, then the share price could be at least double the current level, by my estimation.
There's an element of risk of course, but overall I'm very keen on this one, and have grown it to one of my larger personal portfolio holdings. With Sir Roger de Haan now back, and Non-Exec Chairman, I think we could see Saga really blossom again, as it goes back to its brand heritage values, but with a focus on digital for both marketing, and running the business. Hence a nice mix of old style customer service & differentiated products, combined with modern ways of exploiting its huge database of over-50s - amazingly 20% of its customers are (on paper) millionaires. I think once covid is under control, some time in 2021 hopefully, then there's likely to be massive pent-up demand for cruises, holidays, etc, from this the most wealthy demographic. On the basis that we've all experienced this forced shutdown of our lives, and once we're free again, people are likely to let rip I think, and enjoy the moment. This is why I've been looking for a safe way to get the upside on a resumption of cruising/holidays by the over-50s, and underpinned by its insurance division, I reckon Saga is the ideal spot. I wouldn't want to invest in airlines or pure play cruise lines, as they're under such severe financial pressure in the meantime, and share prices have not adequately discounted the risks, in my view. Whereas Saga is less risky, but the shares seem to have excessively discounted the downside risk.
As always DYOR, you may disagree, I realise this is a controversial share, because everyone has a fixed, negative view about it.
I should add that my investing timescale on this one is 2-3 years. So I'm not expecting instant results, and divis are not going to be paid for a while, until debt has been substantially reduced from cashflows.
.
Cenkos Securities (LON:CNKS)
47p (up 4%) - mkt cap £26.5m
I don't normally cover financial sector companies, but tend to cover CNKS because I see it more as a special (value) situation. Subscriber antehelion posted a good synopsis of the key points in the comments below. The attraction of Cenkos shares, is that at this level you get the business in for free, given that the net cash pile roughly equals the market cap.
Historically, Cenkos has at times been highly profitable, with some bumper fees from floats, but a lot of the historic upside came from its relationship with Neil Woodford, who cornerstoned some big floats. It paid out much of those bumper fees in dividends for shareholders. The big question is whether those glory days might return? Looking unlikely at the moment.
Cenkos Securities plc (the "Company" or "Cenkos" or the "Firm") today announces its results for the six months ended 30 June 2020. Cenkos is an independent, specialist institutional securities group, focused on small and mid-cap companies and investment funds. The Group's principal activity is institutional stockbroking.
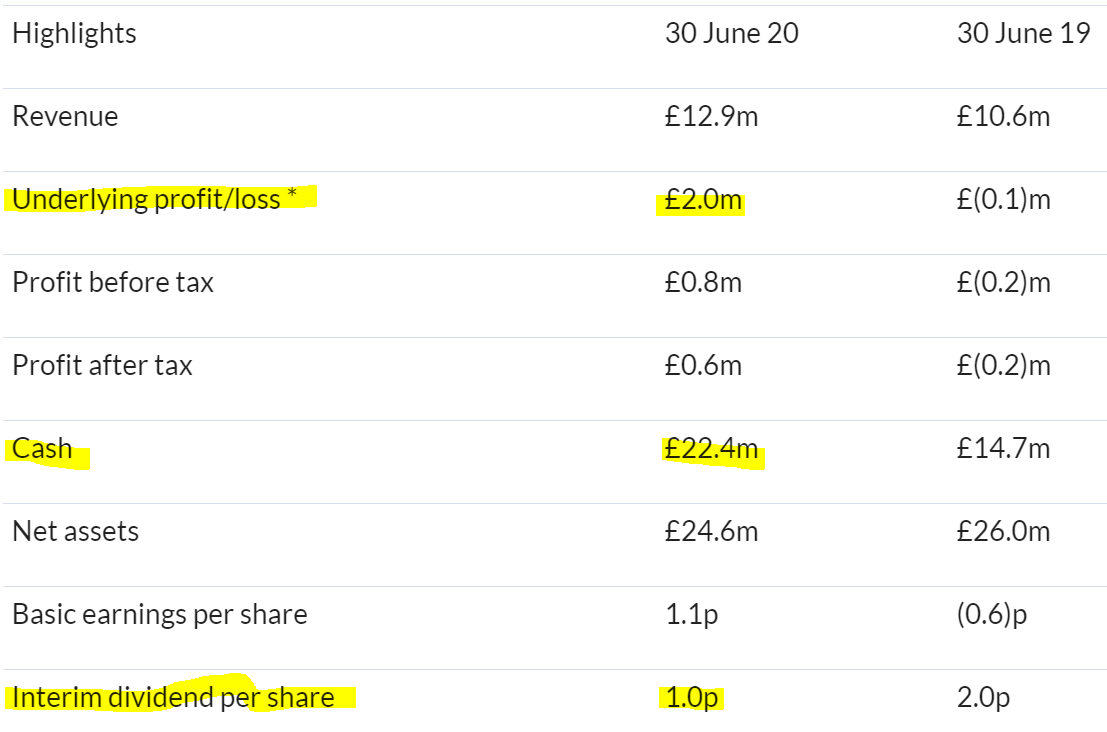
Given the tumultuous covid/lockdown events in H1, these numbers look half decent to me. Although there have been so many fundraisings done by listed companies, and the fees always strike me as outrageously high, then perhaps we could have expected more profit this time?
.
.
A divi of 1p is not bad in the circumstances, that's a 2.1% yield just for the interim divi, in difficult times. If things improve, then the yield could rise in future. A massive 177.3p has been paid out in divis since floating in 2006.
A reader questions how reasonable the adjustments are, so let's have a look at the asterisk;
* Underlying profit is profit before restructuring costs and charges related to the Cenkos Short-Term Incentive Plan and tax. A reconciliation between Underlying profit before tax and Profit before tax is shown in the table below.
The STIP was launched in April 2020 as a one-off plan to retain and incentivise key members of staff. The plan was funded using shares already held by the EBT, which will vest in equal tranches on the first and second anniversaries of its launch. The charge of £0.5 million (H1 2019: £nil) represents the portion of the fair value of the scheme allocated to this period.
It's another form of remuneration, so it's tricky how we should view this. Maybe they adjust it out, because it's paid in shares, not cash?
Outlook comments sound OK;
Although our current pipeline is encouraging and we continue to win new clients, we recognise that the prevalence of both the virus and measures taken to contain it, pose a continuing risk to the health of the economy and the financial markets. The restructuring programme started in 2019, has resulted in a significantly lower cost base going forward which, combined with the strength of Cenkos balance sheet and a rejuvenated strategic focus, means the Company is well placed to face the challenges ahead. The second half of the current financial year has begun with energy and purpose at Cenkos, despite the ongoing macro challenges presented by the ongoing coronavirus."
.
Balance sheet - is excellent, with £24.5m NTAV, most of which is cash. With a market cap of only £26.5m, we are almost getting the business for free, which is attractive.
Overall - it remains a good special situation, almost fully asset backed. Therefore any bumper future years are free upside. I see this as an interesting tuck away & forget share. I held some for a couple of years, and remember suddenly finding thousands of pounds in unexcepted funds in my cash account, and it was a big divi Cenkos had just paid out!
The reason this share is so cheap, is probably because there are too many small brokers, chasing not enough work. I do think the market has overdone the gloom though, valuing the business at little more than its own cash.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

61 comments
Evening
Just read Paul's write up on saga which is interesting. Can someone explain why when I look at the share price on Google it's saying 134.5p not 12.55 p that Paul says it currently is. The graph shows no major uptrend either?
1 new for 10 old shares consolidation just recently
Ok. Thanks.
Re Portmeirion (LON:PMP) - Many Thanks to Paul for his interview with the CEO Mike Raybould (see top of this days SCVR.
Raybould came across as very open, honest and trustworthy (if not the greatest public speaker) - for instance in being prepared to push back and explain why Mgt have low stakes currently (new young team) and accepting a measure of overstock). Paul also winkled out i) potential good news in respect of freehold values on property in the UK ii) an intention to use B2B as a way of disposing of seconds iii) a clear understanding of and willingness to invest in solving production bottlenecks, admitting some under-investment in the past and iv) a clear statement of preference for driving organic growth over acquisitions. CEO also recognised need to get out to PI events spread the word and encourage liquidity outside the same old holders. All good to my ears.
Most importantly, the CEO spoke about building online sales and specific investment steps/plans taken to improve this. He quoted figures shared elsewhere of 6% online in company websites in 2019 rising to 15% this half (with retail closure) at 10% better margin. Balance of online through 3rd party (Amazon, John Lewis) at similar margins to retail was also interesting to hear.
I had written to the company to complain about the poor state of its current website and emails with some specific examples and had that acknowledged. The CEO said much the same thing but spoke to me convincingly about investments and new people hired to change this.
Net, I already held some but will slowly buy more in the coming days
Saga (LON:SAGA) ( I hold) I think the 1:15 share consolidation is a good move as it makes it easier for institutional fund managers to own as they tend to shy away from penny shares.
The stocko PER metrics on Cenkos Securities (LON:CNKS) look all wrong, it is reading as PER of 300! More than Microsoft!
a second thanks. terrific reporting. frightening, isn't it?
Went to London on Wednesday with my wife; hosted a mainly zoom business event although with some delegates attending. Postponed twice because of government restrictions. My first trip to London in. about 9 months. A real eye opener. Victoria station almost empty; usually if you want a taxi you join the longish queue. This time no one waiting and a long line of taxis. Hotel near the centre of London....usually very busy. No bar or restaurant open. Never saw another guest. A reception manager standing well behind so much glass we struggled to hear him. Looked in the pubs; those that were open were almost empty. The roads were so quiet in the evening that as a Londoner born and bred it was almost scary.
The conference venue; delighted to see us. Custom built centre that usually is full most days. This should be peak season for them. We were their first customers in nearly a month. Manager commented that they had often seen Ministers and even PM's presenting there on "vision" and "the way forward". Now they felt forgotten about. Enough funds for a while but end of the furlough scheme will mean most staff gone.
Took a picture of the street at about 8pm. A man walking his dog. At times, no cars, no noise, no people. Fitzrovia, near Oxford Street, London. Yes it was a Wednesday but London is always buzzing.
On the same day, the Office for National Statistics (ONS) disclosed that the UK household savings ratio surged. People seem to sense that bad times are coming. People are paying off debt at a record date; I guess they know that high levels of unemployment is on the way.
Looking at my holdings today. Where will the shocks come from? Will the Ftse100 fall below 5000 again? Shell and BP are apparently at 25 year lows. Lots to think about!
Thanks for posting, really interesting on the ground insights.
head to London suburbs where I live and quite busy with bars and restaurants quite full and perhaps a bit more through the week too (anecdotal observation rather than data). Central London is full normally of white collar and professional workers and tourists (from abroad and elsewhere U.K.) so not surprising it’s quiet
Spent weekend in London. It was fantastic and highly recommended. The lack of crowds made for a wonderful experience. Tower of London was busy but pleasant. Nearby Coffee shops reasonably busy but again, easy to get a table and watch the world go by. Cafe's around Kensington were very busy and we had a lovely brunch. Temp checks on way in, reasonably spaced tables (sufficient for social distancing but not too far that atmosphere was lost). £70 for 4 suggests plenty of money still to be made even with a few less tables. Walking the Mall to Buckingham Palace was serene. What a beautiful place. Walking up to the gates and peering through with no hustle and bustle is an experience to behold. Hyde Park - wow! Albert Hall, we just walked up the stairs and got photos really easily. Trafalgar square was off course rammed with nutters but was fun to observe from afar. As we walked from site to site, there was lots of evidence of shut shops, bars and cafes which clearly not great for the economy. We stayed in Acton and the traffic was chaotic the further away from central London you got. Tube again got busier the further from London you got although didn't enjoy the mask wearing experience. (Generally 99% were wearing masks on Tube). I also used the NHS app for the entire weekend. Most places had a QR code and it was really easy to use and helps keep things moving. Do I care if someone knows I was in Starbucks, no I don't. Do I like masks, No I don't but will wear one if requested to do so. People just need to roll with it and crack on. Overall, I think this is a once in a lifetime opportunity to explore the wonders of London and really take in it's majesty as a city of the world. This time next year it will be rammed again with tourists.
Wondering if you have any views on £CRS ? Big rise last 2 days following announcement. Personally, massively overweight.
£ CRS worked out how to get the ticker in now!
A delayed RNS related to Omega Diagnostics (LON:ODX) has been released this morning. Omega Diagnostics are the manufacturer of the UK-RTC Abc 19 finger prick test which takes 20 mins to provide a result.
The RNS reports that the evaluation of the test by Ulster University have produced excellent results when compared to the 'pseudo gold standard" of existing tests.
You can read the RNS here ...
I've included a link to a Youtube video from Abingdon Health desciribing how to use the UK-RTC Abc 19 finger prick test
This product is part of the jigsaw that Johnson was describing recently when he said in Parliament during PMQ's ...
"the world we want to move to as fast as possible is a world where everyone can take enabling tests at the beginning of the day, an anti-gen test, to identify whether or not we have the virus or not, like a pregnancy test within 15 minutes or so, so that we know whether we're able to live our lives as normally as possible. That's the vision that the Health Secretary and others have been sketching out over the last few days. That's where we inted to get to"
Imagine how many tests that might be ... per day ... for months to come
In July, Omega Diagnostics (LON:ODX) reported that they were scheduled to have initial production capacity of 100,000 Abc 19 test per week in place for September
What I should point out is that at present that test is marked "for professional use" implying that it is administered by a health professional but looking at the video I see no reason why it can't be rolled out to members of the public.
Saga:
£410 million debt.
£500 million ship debt when next ship has been delivered.
£140 million fundraise.
£7 million pa cash burn for travel businesses.
Approx 2 billion shares = £250 million equity.
These figures right Paul?
Thanks
Here's slide 19 from the slide deck which I provided a link for in the main report, for Saga (LON:SAGA)
This shows you the pro forma debt facilities position post capital-raise, which looks fine to me. Note the points on the right, including that the RCF will be undrawn. Hence plenty of liquidity. It's not a financial distress situation at all.
Vertu Motors (LON:VTU) Notice Richard Teatum, owner of Stoneacre a rival company, increased his stake to 4% in Vertu Motors a few days ago. Hasn't made his intentions clear yet, so perhaps worth watching, I know a few people here are invested in this share.
Disappointing take up for the Saga rights. Does anyone know their net debt figure now the raise has been done. I know there is the debt for the second boat to come once that has been completed.
Paul how is the boat debt ring-fenced?
Thanks in advance.
1spatial (LON:SPA) H1 20 presentation given to analysts given on Wednesday, by Claire Milverton, CEO & Andy Fabian, Interim CFO.
Video & podcast.
1spatial (LON:SPA) develop and sell IT software for Location Master Data Management, primarily to Government, Utilities & Transport Sectors. They operate with a relatively new management team.
Just to summarise, this week piworld have produced results videos/podcasts for:
Find them all here.
Forthcoming piworld webinars in October:
Sumo (LON:SUMO) H1 20 results webinar with management including Q&A, Thursday 8th October, 1pm. Register here.
piworld interview with David Thornton: Growth Company Update. Thursday 15th October, 1pm.
David will give an update on some of his picks from his July interview. Further, he will give his overview of, what he considers, are some of the most exciting growth companies he’s interviewed, during the recent barrage of results. Through this, we’ll learn more of his investing thinking & strategy, and his views on current markets. He may offer another special subscription offer, to his Growth Company Investor newsletter. Register to attend here.
Has there been any independent verification of the positive COVID test for Trump? His twitter hasn't been a reliable source of accurate news.
If he were to recover quickly and announce that a cure for COVID would be available across the US in mid November, there might be a big rise in stock prices and in his re-election chances.
It seems far-fetched to imagine this could be a stunt but ...
His doctor released a statement confirming it.
https://edition.cnn.com/2020/1...
Yes, it's aCNN link. Other news providers are available :-)
Not sure that I 'd consider Trump's doctor independent verification!
.... but we know who is the master of ‘Fake News’! Boris Johnson got the sympathy vote earlier in the year which he has now completely dissipated so perhaps Trump trying the same trick in time for the election. On a more serious/sensible note John Authers (Bloomberg) excellent daily analysis email newsletter considers the implications for markets, the dollar and stocks.
I didnt think this was twitter and maybe thought that people would wish the President of the USA well. But for the record YouGov just put out the info that Bojo catching Coronavirus did not prompt a surge of support for the government.
Interesting to see that take up for the Saga (LON:SAGA) 12p Open Offer was 43.6% even though (as I did) it was cheaper to buy at around 11p in the market a few days ahead of the closing date.
So Roger De Haan got a lot of the 54.4% not taken up and now owns 26.4% of Saga shares. The business was very successful in his hands years ago,
I’m really looking forward to Paul’s update as SAGA now looked really interesting! They turned down an indicative bid at 32p (and didn’t tell shareholders about it at the time) and Roger De Haan bought that big stake at 27p and a big premium to the share price then, and a much bigger one still now the share has fallen to 12.6p.
Could a bidder return? Could Roger De Haan try and take SAGA private?
Currently it seems their insurance business is keeping Saga afloat, along now with the new money raised. Signs of covid weakening or a vaccine closer and they have a successful travel business that would come back to life, and also that now much improved cruise business with those 2 new state of the art cruise ships. They are the first all balcony small cruise ships apparently.
They are scheduling cruises from April and already bookings seem to be going well and the inaugural cruise on their second new ship is heavily booked already.
With so much potential, along with share price so bombed out, I would much rather see SAGA stage a full recovery with the share a potential multi bagger, than it go to a low ball bid, or go Private soon.
Pointless (imo) 15/1 share consolidation post the completion of the Open Offer comes in to effect on Monday.
Hope Paul’s update doesn’t show much of this to be nonsense, but fwiw until he or other contributors here cover negatives I’ve missed, I think SAGA looks exceptionally tempting at the current 12.6p price.
Sorry Paul but I reckon there will be a lot us of who recall the way SAGA took their vulnerable long term customers for a ride and so whatever the news, will steer clear...... I'm also not convinced that the existing model of financial and running cruises is right for the present...
That's a fair point, and it's an example of the brand damage done under the years of mismanagement. That's exactly the kind of stuff that new management at Saga is trying to repair. It's all about surprising & delighting customers again, not leaving them with a sour taste, as you suggest.
So the turnaround could take several years I think.
Paul I had a look at the really very difficult to read last accounts. Insurance company accounts are hard but when its mixed in with other activities its even worse. My view is they can't trade out of this without divesting the boats - its fine to have a travel agency but there is no need to run ships and they do not have the resources to do so.
Though agreeing that the SAGA turnaround could take some time, aren't there also possible big shorter time share price triggers too?
e.g Roger de Haan now has over 26%. What are his intentions now? Could be to lead the SAGA recovery. Or could be looking to take SAGA Private?
What about the potential recent bidder at 33? They could well get SAGA for less now but still way above current bombed out 11p price.
SAGA had an exceptionally successful business before they went Public. Now THE man who along with his DAD started SAGA from nothing in Folkestone is back at the centre of things. I remember when Barratt lost their way and the founder Barratt returned to sort it out and the share soared.
If there is no bid or attempt to take SAGA private, then it is likely that the share will bump along around current 11p price or lower perhaps for a good while. BUT even a whiff of better covid news and travel returning to normal (e.g if vaccine promise and near) and SAGA share price should soon start to price that in and long before the recovery is obvious.
SAGA have done so much wrong for a good while. They even managed to mess up the Open Offer just completed, and had to reduce the price from 15p to 12p. Surely they should have got it away at that 15p?
Why only raise £150 million? OK raising more would have meant even worse dilution but it would also have meant debt further reduced.
Was it only £150 million to enable Roger De Haan to get to 26% holding without eating too much in to his £1 billion wealth to do so?
And why was he prepared to pay 27p and that big premium to then share price?
Could all this suggest very interesting turn of events perhaps quite soon?
Obviously SAGA floated at far too high a price. AND worse still (and reflected in some reader comments here today) many of their loyal customers were sucked in to investing in SAGA and it has been a bitter experience for them. 90% loss for them. Ouch!
And now any who hoped to get a bit back via the Open Offer when the share was as high as 20p ahead of it, have just been kicked in the teeth yet again. For all that their cruises are very popular and the quality of their offering and service is superb.
SAGA Magazine is popular and very good with some excellent columnists. Ahead of flotation the plus case for customers and readers to buy the shares then, who had often not invested in any share before, was plugged strongly in their Magazine. But in recent times, including the Open Offer events, the share has never had a mention.
How effective is current CE Euan Sutherland? Not sure that his pointing out in his SAGA column that when he looked over their latest new cruise ship it was the first time ever he had been on a cruise ship!
What about the share price today?
After rising to 13p it then fell all the way back to multi year low 11p. There were a lot of sales, quite possibly some of their now even more disillusioned small shareholders who took part in the Open Offer.
Could they be selling at or very near THE long term low?
SAGA has a potentially very successful cruise, travel. and insurance business. The share is bombed out like so many shares in the hospitality sector. Some of the survivors will likely multi bag once covid is over and travel and business return to more normal.
And could SAGA be one of those very big winners? Yes imo... unless there is a low ball bid.
I commiserate with bohemie, I bought shares in Saga (LON:SAGA) for my better half as a birthday present at the share price of. 190 pence, just prior to the grand slide beginning August 2017. Nevertheless I did put some more to it in the Open Offer if only to cut losses.
To add to Ken's comment about the, in his opinion, pointless 15/1 share consolidation I am left wondering what will happen to my wife's left-over 5 old shares or the one-third of a new share come next Monday. Can anyone enlighten me only these bits must add up.
Ususally in these cases the company aggregates the fractions and sells them in the market, giving the total as a donation to charity.
re Saga (LON:SAGA) share consolidation -
Charity - you must be joking - extract from RNS q.v. :
"Where the Consolidation results in any Shareholder being entitled to a fraction of a Consolidated Share, that fraction will not be allotted to such Shareholder and arrangements will be put in place for any such fractional entitlements arising from the Consolidation to be aggregated and sold in the market on behalf of the relevant Shareholders. Amounts of less than £5.00 will not be paid to such Shareholders and will instead be retained for the benefit of the Company. Having regard to the current share price of the Company, it is anticipated that no proceeds of fractional entitlements will be distributed. As a result of the Consolidation, Shareholders with fewer than 15 Ordinary Shares following completion of the Capital Raising will no longer hold Ordinary Shares in the Company".
Not being critical but why did you hold on? Is it an example of the psychology of investing where we hate to admit a bad decision and hang on regardless hoping for a turn around?
Yes, that is what it was and also I didn't want o tell the wife.
£SAGA. I think consolidation is sensible. Some companies do it it to increase liquidity, reduce the spread and appeal to wider share ownership. In Sagas case its just good house keeping and makes the shares look slightly more respectable. RBS did it a few years back 22p to £2.20. Lloyds probably would have been advised to do it, but never thought their share would be languishing in the 20p's a whole decade later. The important bit is obviously the business. I think there was a note out yesterday that the November cruises are rescheduled for early 2021 not surprisingly. The sale of the motorcycle business in august for 26 million should cover that just about!
Re £Saga I am a recently new share holder and have continued buying today. I haven't reached my full % portfolio size yet, so whilst ' not wanting to catch a falling knife' I am hoping( again not a great investment strategy) that this is ' being greedy while others are fearful'. I listened to the recent presentation again and although a little wooden in places, it is a good team. I thought the best bit was the questions at the end and the management team answered them well and confidently. Bonne chance
Does anyone know whether fees are contingent for Cenkos Securities (LON:CNKS) ? I note $98m placing in September carried out by them.
I second all the positive comments on Paul's splendid work, but I would also like to congratulate Jack, who has come in and added another, excellent dimension to the SCVR reports.
Many thanks David, at the end of the day we're all human, we're all more or less on the same side, and a few kind words can make a big difference to anyone!
Really appreciate all of Paul's hard work and valuable insight into the financial mechanics of companies but I also agree it was great to see some coverage of Mining & Biotech in the SCVR recently too.
positive interim update from Cenkos Securities (LON:CNKS) today - would you be interested in taking a look perhaps Paul?
revenue up 21% on prior year to £12.9m
profit £2m vs -£0.1m
2.22% yield on the interim dividend (still paying) - historically this has been much higher when the economy isn't dulled.
current cash of £22.4m vs market cap of £25.51m - the profitable company comes virtually for free.
Yes I'll take a look at Cenkos Securities (LON:CNKS) results today. Thanks for the synopsis - useful :-)
Hi Paul thanks for the sterling work you put in it is much appreciated - would it be possible for you to circle back on Cloudcall (LON:CALL) Cloudcall they were on your list last week I think but dropped of on a busy day.
Share price has been ticking up and results moving in the right direction - I hold and I think you do as well
Thanks
Rob
Hi Paul
If you had any time to comment on last week’s Cloudcall (LON:CALL) results then I would also welcome your thoughts, however brief. I too realise that you ran out of time last Wednesday.
To echo others, I enjoy reading your reports whatever stocks you cover.
Jon
Thanks for the prompt on Cloudcall (LON:CALL) (I hold), I'd forgotten about that one, so have added it to the list for later today.
I’m a bit dubious about the CNKS presentation of their P&L.
I wonder what your view is of Incentive Plans and P&L’s? There could surely have been a better explanation of incentive and rationalisation costs, to understand what is and isn’t recurring?
So where do we believe the recurring profit level sits?
Keep up the good and honest posts.....
Perhaps someone could enlighten me as to the nature of Cenkos Securities (LON:CNKS) trading revenue stream?
Do they purchase shares in their clients at the point of transaction and subsequently trade these on a discretionary basis?
A small part of revenue but presumably one that drops straight through to the bottom line and so could introduce volatility to the relatively small profit figure (and some potential upside should markets recover).
I think trading consists of a market making function and they also take part in some of the placings - especially the well supported, nicely discounted ones!
I looked at this share a while ago - the BoD/founders seem to take most of the profits, via opaque Long/Short term IPs, bonuses, and finally (as they hold lots of equity) via dividends.
2020 has been remarkably kind to brokers as institutions have been ready to back rescue fund raisings, generating nice fees but it still looks a lumpy business with poor visibility and lots of competition.
thanks Paul, a helpful write-up and analysis, cheers!
My morning smallcap tweet:
BigDish (LON:DISH) Van Elle Holdings (LON:VANL) Scancell Holdings (LON:SCLP) Abbey (LON:ABBY) Wincanton (LON:WIN) OptiBiotix Health (LON:OPTI) Holders Technology (LON:HDT) Regional REIT (LON:RGL) Cenkos Securities (LON:CNKS), EKF Diagnostics Holdings (LON:EKF)
BigDish (DISH) BigDish-to-GO App completes beta tests and has payment function added. [SP=1.53 Cap=6m]
Van Elle (VANL) refinances debt. Has net cash of £5.8m [SP=35 Cap=37m]
Scancell (SCLP) wins contract to manufacture plasmids for Phase I clinical trial of Scancell's COVID-19 vaccine in 2021. [SP=16.58 Cap=104m]
Abbey (ABBY) to match or perhaps better last year's H1 rev and profit. [SP=1550 Cap=NA]
Wincanton (WIN) stll guiding FY materially ahead of market expectations. [SP=212 Cap=264m]
OptiBiotix Health (OPTI) partner Seed Health gets FDA approval for Phase II trial of DS-01, a broad spectrum multi-species, multi-strain probiotic which contains OptiBiotix's Lactobacillus plantarum. [SP=54.99 Cap=48m]
Holders Technology (HDT) forms a JV with Sentistic to provide data visualisation and valuable insights based on data from buildings. Will "provide customers with an easy way to manage their lighting, energy and occupancy requirements". [SP=40 Cap=2m]
Regional REIT (RGL) sells industrial, warehouse and office park for £32.7m, 4% above NAV. [SP=65.5 Cap=283m]
Cenkos Securities (CNKS) H1(June) rev up 22%, pretax £0.8m (-£0.2m). Div 1p (2p). Outlook:"Although our current pipeline is encouraging and we continue to win new clients, we recognise that the prevalence of both the virus and measures taken to contain it, pose a continuing risk to the health of the economy and the financial markets." [SP=49.9 Cap=28m]
In line: EKF Diagnostics Holdings (LON:EKF)
As always, superb work from Mr C - thank you.
Although headlined “In line” the trading update from Ekf Diagnostics Holdings (LON:EKF) is in fact full of indications that things are going rather well.
Ricardo
Ricardo
I hold Ekf Diagnostics Holdings (LON:EKF) but I must say I am tempted to disagree. My finger has been hovering over the sell button but so far I have decided to hold off.
The current broker forecasts only include the confirmed orders upto the end of September for PrimestoreMTM, therefore I have been working on the assumption that there will be in all likelihood a further increase in guidance for 2020. We are told today that October will be a record month for sales and profits but there is no increase in the guidance, from which I can only infer that they have minimal confirmed orders, as of now, for Primestore for November and beyond. I find this slightly strange as the 14 July trading update stated that Longhorn had as of that date placed orders for the next 11 weeks (upto end-September).
But I have decided not to sell because:
1) the promised further trading update in early November, indicates that the company will have something significant to say then and therefore there should be a strong chance of a further upgrade, if Primestore sales continue.
2) Despite the excitement over Primestore, the main long term value in the group remains the core (diabetes/ haematology diagnostics) business - and momentum here seems to be improving in October.
Dear WS,
I think they are being careful not to overpromise (with the inevitable risk that they may then under-deliver), and also, this allows them to manage the news flow/expectations over the next few months.
Your 2 points seem to me to be good reasons for retaining your shares. There is also their new venture (Trellus) which on past form (eg Renalytix Ai (LON:RENX) ) may prove rewarding.
Good luck, whatever you do!
Ricardo
I think Paul is feeling a bit grumpy about the 'you know who' growls. If it's any consolation to him, I'm feeling just as grumpy for not following his incisive advice.
It's worth reviewing CNKS, I think.
For owners of PCA, see who's just popped up on the share register. And he's no idiot.
I'm feeling doubly grumpy about TCAP, a big holding for me. I'm now going to have to hold on for a long while for them to recover, I suspect.
Why not state who has popped up on PCA and why it might be interesting ?
Peter Gyllenhammar, I had to google him, but he sounds like he knows what he is doing, involved in Indigovision (LON:IND) but probably after Pauls time.
Morning all,
I was surprised at the negative comments on yesterday’s report. There is so much content out there to read if you’re not interested in the SCVR.
I personally find these reports absolutely brilliant and it’s my favourite daily read. Keep up the good work Paul, your efforts are appreciated.
Cheers
In my view- overly negative comments are for other boards and there are plenty out there if anyone feels they need to rant. The exchange of opinions and views on this board which are conducted in a professional manner are one of the many reasons I subscribe. There are some very smart and interesting commentators with good additions. Before anyone sends a moaning comments think before you hit the send button perhaps?