Small Cap Value Report (Fri 20 Jan 2023) - LUCE, HOTC, FIF, DOCS, BUMP, HEAD, PAY, WRKS, G4M, STB

Good morning from Paul, and unusually for a Friday, Graham offered to join me today, to look at some backlog items of interest.
I did a few backlog items last night, whilst watching The Apprentice, so we're off to another flying start! And hopefully nobody here is going to get fired!!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda
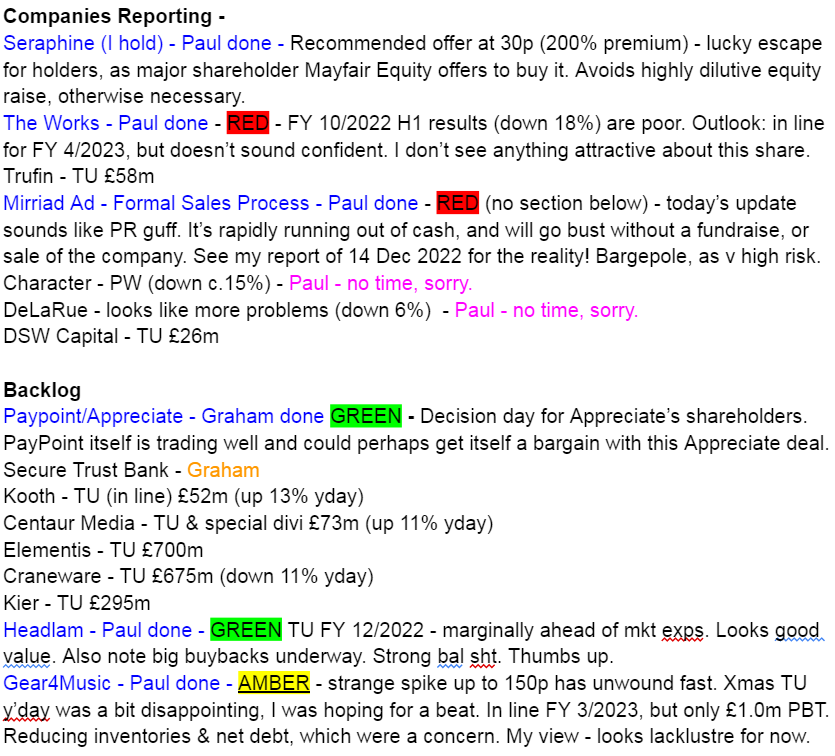
I've got to finish early today, so not sure we'll get through that much of today's list, but here it is anyway -
Paul's Section
Luceco (LON:LUCE) - rose 20% yesterday to 128p - FY 12/2022 TU - guidance: operating profit (adj) at upper end of £20-22m previous range, on £206m revenues. Good, but does that justify a 20% rise in share price? Slow Q4 (as expected), revenues down 22% on Q4 2021, due to accelerated customer de-stocking. Demand from housebuilders slowed 10%. Gross margin improved in H2 to 37.5% (H1: 34%) after raising selling prices. “Exceptionally strong free cashflow” from reducing inventories & good collection of receivables. This has slashed net bank debt from £54m (June 2022) to £24m (Dec 2022) - that’s really good news, as I was worried about high debt, when reporting on its Oct 2022 profit warning here.
Liberum forecast 10.0p EPS for 2022, and only 8.3p for 2023. So price probably about right for now. If it keeps rising, then 150p might be a nice point to top-slice possibly? Or if you think it’s likely to beat forecasts, then it would be one to hold. It mentions cost inflation factors (freight cost, forex) now “moved in our favour” - which could drive margins up once hedging arrangements have expired. Interesting.
My opinion - this looks quite good, but I’d be careful not to anchor to the pandemic share price, which was an artificial high from a boom in DIY. Profits have since dropped a lot.
Overall, I don’t have a strong view either way, but the overall tone of today’s update seems encouraging - it’s over the worst by the looks of it, so maybe the share price should re-rate upwards?
CFO is stepping down after 5 years. Looks civilised, as a NED becomes new CFO (unusual, but why not?!). Handover in March 2023.
Hotel Chocolat (LON:HOTC) - rose 12% yesterday (taking mkt cap to £286m) on an in line H1 update (6m to Dec 2022), year end is June 2023. The tone of the update makes it sound as if they’ve knocked the ball out of the park, but it’s only trading in line with expectations - footnote says £213m revenues and £8m underlying PBT for FY 6/2023 - very modest profits for a company valued at close to £300m. Presumably bulls think it’s going to beat these numbers?
Net cash of £31m at 18 Jan 2023 is healthy.
Inventories down 17% vs LY, good as excessive inventories were an issue.
My opinion - the valuation seems to hinge on hopes that it can achieve aggressive profit growth, with Liberum assuming FY 6/2023 profit of £8.3m grows to £20.5m next year, and £32.7m in FY 6/2025. That doesn’t look realistic or prudent to me, given subdued consumer sentiment, and rising costs (although HOTC reckons it can cut costs), but we’ll see. The market’s running with the bull story, with a nice looking chart. Quite often when a share seems inexplicably expensive, it’s because the buyers know something good is going on. Although they were wrong in the past with HOTC, as it was over-valued for years, and then crashed when the international expansion all went wrong.
Finsbury Food (LON:FIF) - Finsbury Food - TS £118m - says its on track to meet market expectations for FY 6/2023. Decent revenue growth in H1, and I’ve been really impressed with how this business has managed to successfully navigate higher inflation, passing on extra costs - the sign of an efficient, well-run business, I reckon.
I don’t understand why the market is so stingy with its valuation of FIF, with a PER of only about 8. This seems a bargain to me, but it’s always been cheap, nothing ever seems to change, investors just don’t seem interested in it. Still, I’d rather have it that way around, and get a nice surprise (e.g. a takeover bid), than overpaying for something that’s always too expensive!
Dr Martens (LON:DOCS) - nasty profit warning, down 31% to 145p (a new all-time low). Softer demand and logistics problems, with its US warehouse in LA going badly wrong by the sounds of it.
Revised guidance: we now estimate FY23 EBITDA will be between £250m and £260m
Some knock-on problems into FY 3/2024.
My opinion - I can’t take it any further, as there’s no broker research available. But that 250-260m EBITDA figure is still impressive. H1 showed £89m EBITDA, which became £58m PBT. The market cap has just come down from £2bn to £1.4bn in a day, so this might be worth looking into.
The last balance sheet only had NTAV of £82m, but debt doesn’t look excessive, given the large EBITDA number supporting it. Overall, this might be getting interesting, now the excessive IPO valuation has dissolved.
Seraphine (LON:BUMP) (I hold) - this is actually my largest personal portfolio position, so when news came through last night (as always, from Sky News) that Mayfair Capital had agreed to buy it back for a 200% premium, at 30p, I had to pinch myself, and also woke up this morning wondering if it had been one of my frequent share-specific dreams?
The good news (depending on when you bought the shares) is confirmed in an RNS today -
Recommended Cash Offer - from Mayfair Capital (holds 43%, and originally floated BUMP at a bonkers valuation as it turned out).
The offer is 30p cash, a 206% premium, but just 10% of the IPO price of 295p in July 2021. It was one of many opportunistic floats, where private equity sold a business that was doing well in the pandemic, to gullible fund managers, who thought the growth was structural. To be fair though, the ecommerce sector was then hit with a big rise in digital marketing costs, and supply chain/forex chaos, combined with a consumer downturn, and re-opening of physical stores. So a lot has gone wrong since the IPO, including a series of profit warnings, and a net debt position that was looking distinctly uneasy, and a balance sheet that obviously contained stretched creditors & inadequate capital.
Anyway, I don’t care about the history, as I’m a Johnny-come-lately, buying at an average of 21p, after big Director buying and a bombed out valuation. It didn’t work very well though, with the price then more than halving after yet another profit warning, and I was getting really worried about this share, as indicated in these reports and comments, where I flagged it as very high risk (and I didn't really want readers to follow me in, in case it went wrong).
Today’s announcement makes some interesting points of wider read-across, that we need to avoid any small cap which needs to raise fresh capital, as the stock market isn’t interested, and demands deep discounts right now -
Seeking this capital on-market would likely be highly dilutive, and the restoration of value would take time.
"The Seraphine Board, therefore, believes that this transaction would remove the substantial costs associated with being listed and afford management the time and space to give their full attention to a return to profitable growth. The Seraphine Board also welcomes the further capital which has been committed by Mayfair, to accelerate growth and reinforce the Company's balance sheet, as well as Mayfair's stated support of the management team and employees.
"The Seraphine Independent Directors believe the offer from Mayfair, which follows a period of intensive negotiation and which represents a premium of approximately 200 per cent. to the current share price is a fair and reasonable offer that we recommend to our shareholders."
My opinion - clearly I didn’t follow my own rules here, and taking a large position in a company that obviously needed more equity, was a stupid mistake. That’s the trouble isn’t it? When you’ve got an excitable personality like mine, the decisions I make are sometimes irrational, and undisciplined. I find it impossible to follow a logical, sensible strategy, particularly after heavy losses, when my judgement is impaired even further, as it has been in the last year. As mentioned before, I enjoy doing the company analysis, but am pretty hopeless at managing my own money.
So this outcome, of a generous bid for a financially distressed company, is a lucky escape, and no skill or congratulations should be celebrated by me (although obviously I'm over the moon at a very good outcome).
Still, I live to fight another day, and should shortly have a nice cash pile to deploy on my bulging watch list, at last some good news, even if it was created more by luck than judgement.
Headlam (LON:HEAD) - 330p (mkt cap £267m) - trading update yesterday for FY 12/2022. UK’s largest floorcoverings distributor. I’ve got a call booked for today with former CEO, Tony Brewer, who now runs growing competitor Likewise (LON:LIKE)
HEAD seems to be performing as expected -
Revenue and underlying profit before tax for the Period are both expected to be marginally ahead of market expectations¹.
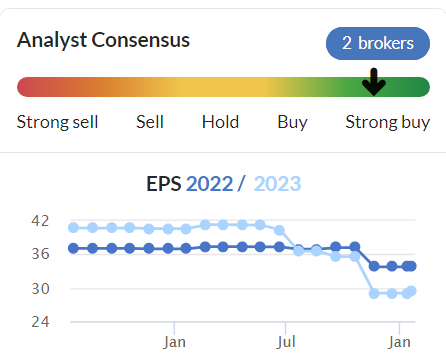
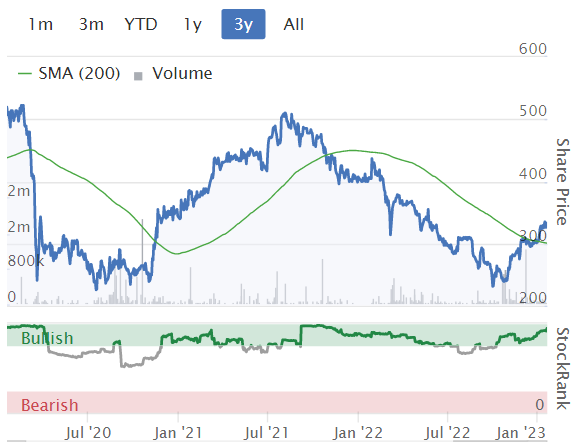
The footnote gives a link to its website, as usual here is the more specific link you need. This shows consensus 2022 forecast of £660m revenues, and £37.0m underlying PBT. That looks consistent with Stockopedia’s PAT of £30.5m, and EPS of c.34p. I make that a PER of 9.7 - a modest valuation I think, especially as HEAD has a particularly good balance sheet (loads of freeholds), and is a proven cash generative business (paying lovely divis), even in tough macro times. No outlook comments, but given tough macro, I'd assume it's likely to tread water, at best, in 2023. Forecasts for 2023 have already come down a fair bit, which gives us some margin of safety hopefully, lessening the likelihood of a profit warning -
It also has some good self-help and growth initiatives underway, including expansion of trade counters, passing through price rises (hence revenue solid, even if volumes fall), and chasing larger customers (it’s previously said there are gaps in its market, which it needs to target). Also efficiency measures being done - it’s previously said the patchwork quilt of depots, and overlapping logistics, is being rationalised, which saves money & improves service.
Share buybacks are sizeable - accelerated since Nov 2022, this £15m programme should be complete by end March 2023. That’s almost 6% of the market cap, so will nicely enhance future EPS & DPS.
High StockRank of 94.
I remain positive about this share, thumbs up. It’s still really good value I think, and now we also have the reassurance that it’s trading in line. Although rapidly growing LIKE is snapping at its heels, and already has c.6% market share, vs HEAD's 30%.
There was an IMC presentation yesterday, so I’ll watch the recording over the weekend.
Thumbs up from me.
.
Works co uk (LON:WRKS) - very quick comment on today’s interims & current trading update. Stores did well over Xmas (against soft comps re omicron). Online weak, down 14%. More price markdowns this year in Jan sale. H1 figures look poor to me, a loss of £(10.7)m, much worse than last year’s £(1.0)m loss, although H1 is seasonally weaker half year.
As mentioned here before, WRKS last year benefited from a big subsidy from Govt re business rates, that’s now ceased, a £3.9m additional cost. Net cash of £7.0m, down a lot, but should improve in H2 (seasonally stronger). Says it’s not changing outlook for FY 4/2023, which Stockoepedia shows as a PAT of £1.4m. But comments sound cautionary, so risk of an H2 profit warning possibly?
Balance sheet is OK-ish, if you take out the IFRS 16 lease entries.
My opinion - remains cautious - this looks a marginal business, operating just above breakeven. So it’s vulnerable to any further downturn. That said, it could see margins improve as freight & supply chains ease? Mgt will have to work hard to keep it going. I’d stick with CARD and SHOE, they look tons better than WRKS.
Graham’s Section:
PayPoint (LON:PAY)
Share price: 530p (+5% yesterday)
Market cap: £365m
Good morning! There’s quite a lot of newsflow around this one currently, and it was mentioned in the comments section yesterday, so I thought I’d drop in today and help to keep everybody updated on it.
Let’s start with the trading update for Paypoint’s Q3 (October to December, since year-end is in March). The company remains confident of delivering expectations for the year.
Key points:
Total net revenue +9.8% year-on-year to £32.5m
“Shopping” division net revenue +4.8% to £15.4m
There’s a lot of detail provided for this “Shopping” division. The main point is that their flagship product for UK stores - the PayPoint One terminal - continues to sell strongly and trade well. Within the Shopping Division, UK retail services net revenue increased 9.2%.
The other major part of the Shopping division is Card Payments, through which Paypoint provides card payment machines under a couple of different brand names. It also enables the purchase by customers of loyalty cards, gift cards, etc. (this includes gift cards from Appreciate). Net revenue here was flat.
Other divisions:
E-commerce (Collect+) division net revenue +50.9% to £2.3m
Payments & Banking division net revenue +10.6% to £14.7m
Strategic Update
PayPoint has neatly presented its progress on its four strategic priorities - one priority for each of the three divisions, and one for the group as a whole.
I haven’t got much to add here except that I think PayPoint has already achieved its first strategic priority - to be embedded “at the heart of SME and convenience retail business”.
It also has an ambitious goal to be “the definitive technology-based e-commerce delivery platform for first and last mile customer journeys”. I’m not sure if that is realistic - surely the competition in that niche must be formidable? But it does have partnerships with Amazon and FedEx, and Royal Mail strike action is another boost for it, so who knows?
Balance sheet - net debt of £35m as of December 2022.
Estimates - according to Stocko, full-year estimates are for revenues of £121m and net income of £37.1m, which puts the shares on a cheap valuation (ValueRank 94).
Appreciate takeover
Appreciate (LON:APP) also issued an announcement yesterday, noting the FCA’s approval of Paypoint’s proposal to acquire them.
Each Appreciate share is set to be bought for 33p plus 0.019 new PayPoint shares. This is worth about 43p-44p, depending on which value you use for PayPoint shares.
News here is imminent:
The Scheme remains conditional on the approval of Scheme Shareholders at the Court Meeting and Appreciate Group Shareholders at the General Meeting, such meetings to be held on 20 January 2023…
In a takeover situation, 75% of votes cast at the shareholder meeting need to be in favour of the deal. As noted originally by Boon and then Michael C, there are some hedge fund shenanigans with a group called Samson Rock building an 18% position in Appreciate and also shorting PayPoint. Could they perhaps be intent on forcing PayPoint to pay more?
(Note that if or when the deal goes ahead, the PayPoint shares they receive could be extremely useful when it comes to closing their short!)
My view
It’s a complicated story. My view is as follows (I don’t currently have a position in either share, but I have in the past owned both of them, personally or on behalf of others):
PayPoint is a good-quality business with a history of excellent cash generation and ROE, and I like its future prospects. It is part of the shopping infrastructure that convenience retailers need, and its products have remained modern and relevant. I also think the shares offer decent value at current levels.
That having been said, the Appreciate takeover doesn’t make great sense to me from the point of view of synergies. Yes, PayPoint sells Appreciate gift cards (alongside Amazon gift cards and video game vouchers). Yes, many PayPoint customers are also Appreciate customers. But is that enough to justify the combination of the two businesses, strategically?
The easiest rationale for the takeover, in my view, is that it’s an opportunistic one. The Appreciate share price got too cheap, by a wide margin. PayPoint, as a large, financially strong business that has a working relationship with Appreciate, was able to identify this and act on it.
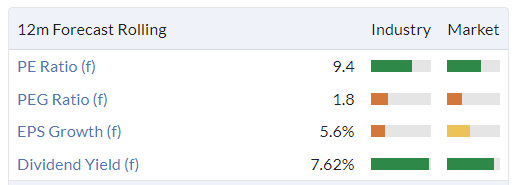
At its current share price, which is near the takeover price, Appreciate gets the follow value metrics from Stocko computers:

It seems like quite a good deal for PayPoint, doesn’t it?
Secure Trust Bank (LON:STB)
Share price: 735p
Market cap: £136m
Thank you to GreyInvestor for mentioning this in the comments yesterday!
This specialist lender issued an “in-line” trading update yesterday, but the shares are superficially very cheap, so let’s take a closer look!
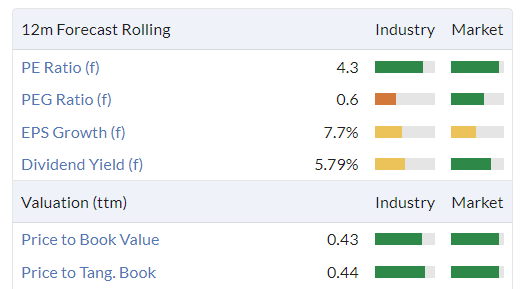
Highlights from the Q4 update:
“Significant” increase in adjusted PBT.
Core loan book up 19% year-on-year. Consumer finance was up strongly, but real estate finance was up only marginally (due to the interest rate rises).
New business lending down 5.4% year-on-year.
Customer deposits up 19.6% year-on-year.
It’s reasonable to wonder about the fall in new business lending. The explanation is that “given the current macroeconomic environment, the Group took a proactive approach to tighten credit criteria”.
CEO comment:
We will continue to manage our risk exposures appropriately during this period of uncertainty and remain confident in delivering our growth ambitions and medium-term targets.
Estimates: on Tuesday, the commissioned researcher Edison adjusted (i.e. lowered) its forecasts for STB, “to better reflect the deteriorating economic outlook in the UK”.
They revised their view of loan growth lower, reduced their operating income forecast for 2023 by 5% to £185m, and reduced the corresponding underlying PBT estimate by 18% to £41.6m.
My view
You don’t need me to tell you that’s a very significant reduction in the PBT estimate - but maybe it’s already priced in at this market cap? What are the risks?
The trading update says little about impairments, but Edison’s note says that “if economic conditions remain challenging, future impairment charges may be materially above forecasts”.
The £1.1 billion real estate book is said to have an LTV below 60%, so perhaps we can conclude that the £350m commercial finance book and £1.4 billion consumer finance book contain most of the risk?
Balance sheet equity as of June 2022 was just over £300m, supporting assets of £3.1 billion. That’s a high degree of leverage, and helps me to understand why the shares are priced so cheaply.
I would need to do more work on this to come up with more definitive conclusions but for now I wouldn’t automatically assume that it’s a bargain. Shareholders could be exposed to significant risk here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

69 comments
Congratulations to Stockopedia contributors on the standard of discussion. It is top drawer. I especially liked today's commentary on Spirent Communications (LON:SPT).
Glad to hear Seraphine (LON:BUMP) has worked out, Paul.
Also it makes for much enjoyable and educational reading, to learn about the actual ups, downs and mis-steps of investors. (Quite a lot of financial journalism aimed at investors only ever mentiones the upsides).
Seraphine (LON:BUMP) is yet another situation that makes me ask: why on earth does anyone, EVER buy shares offloaded by private equity and hedge funds?!!
Couldn't agree more - just look at Hostmore (LON:MORE) and Unbound (LON:UBG) !!
More broadly - why does anyone buy IPO shares? They have been a terrible investment (generalising of course) over the last few years.
The reason why? Private funding has been much easier to access, through PEs and VCs. So there is no incentive for a well run, quality company with genuine growth prospects to raise money via a (laborious) IPO process.
However, could this tide be shifting? I can see that PE and VCs will be tightening their deployment from now on. Therefore, companies will find it harder to raise funding privately, and maybe now see it easier to do it via public markets.
Not a small cap but could be if falls further! Spirent Communications (LON:SPT) trading update this morning has had very damaging impact on share price, down c18% as I write. This has been a long term hold (since July 2018) for me and has been a strong performer more than doubling in price with reasonable dividends along the way. Though this morning’s update doesn’t explicitly offer up a profit warning the market has certainly taken it as one. I have too many of my ‘speculative pot’ shares sitting at massive losses to original buy prices so I ca n’t let one of my few winners go the same way so reluctantly sold my remaining holding in Spirent Communications (LON:SPT) this morning. No doubt on my past record it will bounce back and not continue down like the shares I decide to hang on to when they have a bit of a meltdown.!! A very frustrating game which I am rapidly losing confidence in!
RE: Spirent Communications (LON:SPT)
Yeah - I mean, it wasn't a profit warning, but in fretful times markets tend to shoot first and examine the bodies afterwards. But when a second half weighting from a respected company in a growth area causes this kind of collapse you know capitulation can't be far away.
In the end, as a holder, you have to take one of two positions on these things - you either bail with the market (why fight it, right?) or trust in your analysis and hold through whatever the weather. I'm in the latter category, and I'd need to see either the long-term outlook change or evidence of utter management incompetence before I would sell my holding.
Speaking of utter management incompetence, the Dr Martens (LON:DOCS) update yesterday was a shocker. The valuation now looks stupidly low, but how much credibility is left? Although this is another IPO gone wrong it looks in a different class to many of the others, which were floated at stupid prices. This one was floated to get the owners away from the management, it seems.
Congrats to all Seraphine (LON:BUMP) holders, btw. We need all the help we can get these days ...
timarr
when a share like SPT drops 18% in today's market you have three options: sell, hold or buy more. I did the last!
RE: Spirent Communications (LON:SPT)
I'm in the same camp. I simply don't see enough in the (sort of) PW to justify that level of a fall. It's not as though the name is expensive at half the price of Calnex Solutions (LON:CLX). Both are picks and shovels plays on 5g adoption which is a multi year runway. I wish I'd been smart enough to sell at open and buy back just before the close however. Instead I just dripped a little more in at luchtime.
RE: Spirent Communications (LON:SPT)
I just reckon there's very little chance of a permanent loss of capital on a multi-year basis. Obviously there could be a slowdown next year, but by the time that happens the market will have probably gone from depressed to manic and be ignoring all warnings because they're looking ahead to sunny uplands.
Or perhaps 5g will be proven to Bill Gates' way of injecting us all with nanotechnological widgets that inject us with viruses that make us all think that the planet is warming (to be fair, he has form with this with DOS).
Or something. I have no idea what the markets will do in the short term.
I also bought a few more today.
timarr
Timarr
That made me laugh !
But seriously you hit the nail on the head, the market looks forward and Spirent Communications (LON:SPT) said today that although they have not seen any customers cancel orders some have pushed them back , so the market took this as a potential PW.
I didnt hold before today but I bought a few this afternoon.
H
Hi Paul
Well done on BUMP. I was thinking that the SP seemed to be rising over the last week, and maybe somebody knew something ... Anyway, good on you and I hope that 2023 continues to be filled with upsides!
Love the notes everyday, and I especially enjoy the weekly podcasts / streams of consciousness on individual companies and the macro situation. Looking forward to tomorrow's already.
BTW what software do you use to store your copious commentaries on each share?
Thank you,
Andy
Hi Andy (Haggis58),
BTW what software do you use to store your copious commentaries on each share?
Stockopedia! These are my notes, here in the SCVRs. It's literally where I keep all my information on individual stocks, posting it here! :-) I don't keep any other records, other than an A4 notepad with one page per day, where I jot down the occasional idea, things for the podcasts, to do lists, notes from telecons with companies, etc.
Regards, Paul.
While waiting for today's meeting (does anyone know when it is?) to decide the immediate but not necessarily final outcome of the PayPoint (LON:PAY) offer for Appreciate (LON:APP) I have been mulling over the possible consequences. It seems to me that Samson Rock (a Cayman LLP) are taking a big risk here. As I mentioned yesterday I was a holder of Paypoint when the takeover bid was announced and it triggered a substantial fall in the share price. I'm guessing the market didn't see the value in Appreciate that Paypoint (and Graham, and some people here) did, and still do. Or maybe there are algos programmed to sell whenever a company launches a takeover bid? Whatever the reason, if the bid fails there is probably a binary outcome. If Paypoint increase their offer Samson Rock win because they will make a profit on their Appreciate investment and, probably, on their Paypoint short. But Paypoint might not increase their offer. They might walk away. I think this is unlikely because directors of companies which launch takeovers hate to "lose" or "fail" and emotions can override sound business judgements. But if Paypoint does walk away I foresee Appreciate shares falling and Paypoint shares rising unless, perversely, the market now decides the takeover was a good idea and Paypoint is worth less because the bid failed. In this case Samson Rock lose on both sides of their strategy. At the moment my instinct tells me that if the bid fails I should buy both Paypoint and Appreciate. Comments and reasons why my instinct is wrong are invited.
I personally suspect that might just be over complicating it re Appreciate (LON:APP) and £PAY. Samson Rock, which calls itself an "investment management firm dedicated to equity event driven investing" have likely just picked up on the arbitrage opportunity. There have been quite a few opportunities to pick up Appreciate (LON:APP) at or below 40p since the offer was announced. That's a circa 10% return if you include the dividend which went ex-rights yesterday for a three month holding period (if you annualise that it becomes even more impressive).
I don't disagree. It's easy to over-analyse these things!
You didn't mention the fatal flaw in my post which is that perhaps Samson Rock will vote FOR the takeover to get the arbitrage and then presumably close their short on Paypoint - looking at today's price I think the short may have been covered already. On the chart the blue line marks the day when the takeover was announced.
And my response was to sell Appreciate (LON:APP) after the offer was made, and buy PayPoint (LON:PAY) with the proceeds when it fell, average 520p. Its latest TU is very encouraging, and I think it has a growth path, as it seems to be managing a lot of different business strands rather well now. With a div of nearly 7%, I'm fairly sure the SP will be usefully higher in 2 years (my normal horizon for target prices), especially as it got APP for a song in my view.
RNS out:
"the requisite majority of Appreciate Group Shareholders voted to pass the Resolution at the General Meeting to approve the implementation of the Scheme, including the adoption of the amended Appreciate Group Articles,
and accordingly the Scheme was approved."
Gear4music Holdings (LON:G4M)
"Paul - done". I think that may be a "No section below".
On April 21st there was a rather mealy-mouthed profit warning and I got out at 250p for a very nasty loss. However, at today's 105/110 I'm glad I did!
My attitude to PWs changed a lot thanks to Ed's webinar a few years ago. Prior to that I would probably have hung on in hope.
So, for newer subscribers who haven't seen it here is your weekend viewing:
Aeorema Communications (LON:AEO) released a Major Contract RNS yesterday afternoon. they also confirmed strong trading and the prospect of further contract wins to be announced.
there was a share price spike shortly afterwards but has now unwound. And the chart looks very strong given their growth record.
It all sounds very positive but there are no forecasts in the market. In H2 last year they made 0.6m PBT so it is reasonable to double that and add some growth as per the Trading Update in the RNS? I dont know... but taking those assumptions that would give EPS of >10p. I think they have small net CASH too (pre Creditor adjustments). You mentioned before that you knew 4 of the >3% shareholders as shrewd investors. I hold.
Dr Martens (LON:DOCS): nasty second profit warning, previous was November. Never seen the investment case here. They are faking it on a reputation built up in the 70s/80s but these are not the same thing at all. Nasty, cheaply made Chinese boots with the durability of Poundland flipflops. It would be interesting to know what the US issues are. Returns?
With all due respect please tell me what 'fast fashion' brands are durable. My Nike trainers fall apart after less than 12 months. And yet Nike has been a wonderful investment. They make shoes in China for X and manage to sell them to [gullible / susceptible / brain washed - choose your acronym] wealthy Western consumers for 4x + . That is the magic. I couldn't agree more that DOCS was floated by the PE crowd at an insane multiple. There remains a serious headwind from the share overhang resulting from their residual shareholding. It comes with all the associated risk of a single brand positioned in fast fashion and not luxury. Hermes, even Burberry, it is not. And we know what has happened to the likes of Superdry, Ted Baker, etc, in this space. BUT. Following the recent collapse it is beginning to look (very) interesting if you believe they can get on top of their recent operational issues and the top line demand remains intact. Gross margin is excellent. Leverage modest. Taking the reduced EBITDA forecast of £250m and today's EV, and applying a crude FCF (EBITDA-Capex) ratio, yields 15%. That really isn't bad IF they can steady the ship. A high quality stock (Diageo, etc) it definitely isn't. But then again the latter trades at 5%. Hence as a contrarian Special Situation it is beginning to look interesting.
The whole point was that Doc Martens were not fast fashion . The other issue is another company who bought the equipment that Dr Martens used to use in this country is now selling boots. And being recommended word of mouth on social media which is the best recommendation.
Once. But I don't believe the kids / young adults who make up the majority of its current consumer base see it that way. It's a lifestyle statement / accessory. These are the same kids who profess to be green but love their disposal coffee / travel, and will go to a music festival with a cheap tent, which they then discard. Sorry. The world has changed. A Mercedes today, build quality wise, has nothing to do with a Mercedes from the 60s / 70s / 80s. Nevertheless the brand sails on. Times change...
Yes I don't wear them myself but they seem to be in fashion at the moment. I've seen people wearing them quite a lot recently; even in the office that style of high boot seems acceptable now. In years gone by they catered for a niche/ alternative crowd and perhaps another crowd who prized them for their durability. I'd probably put a pair on myself but am generally too tight for that sort of carry on.
In terms of investment my fear is that the recent revenue spike is a fad driven perhaps by a splurge in marketing etc. Its hard to gauge the sustainability of revenues when they've increased so dramatically. Are we we mid fad or have previous owners or PE rinsed it and are we approaching a decline. I'd need to understand this better.
There is a price at which I'd buy both the boots and the shares but I might just wait for a sale Dr Martens (LON:DOCS)
Well done on the STB analysis, very helpful
Sorry, one more comment on Secure Trust Bank (LON:STB) . This is a straight lift from Edison:
We do not envisage any losses at STB that could eat into its book value and capital base
Edison's latest forecast is for earnings above the current average forecast, although below theirs. Their share price forecast is way above the current share price.
The proviso is that Edison are paid by Secure Trust Bank (LON:STB) .
I am still looking through the Cannacord Genuity research note, but it does look undervalued. I may wait until next results are out before purchasing-due March 30th.
Secure Trust Bank (LON:STB) Canacord say the current share price is pricing in a very significant rise in bad loans, which they think is very unlikely given their fairly prudent lending approach over last couple of years, with an increased focus on prime lending on the consumer finance side. I personally think it looks significantly undervalued and have been buying.
I watched the PIworld video presentation by the CEO of Secure Trust Bank (LON:STB. He stressed prudent lending practices and other reassuring factors, I did the usual research, and I bought. The sp remained very weak and I convinced myself the market knows better than me and there must be something wrong with the company so I sold just before the recent 25% increase. Sometimes one feels one just can't win!
Hi All - has anyone's views changed on Audioboom (LON:BOOM) following this mornings announcement on renewals and new partnerships?
Works co uk (LON:WRKS) I annotated the Stocko chart for this the previous time Paul mentioned it with his words "A poor business". I have belatedly started to annotate charts (I didn't know you could) and it has been really useful so that you are reminded of the salient points/reasons you did/didn't buy etc. Anyway, as usual, thanks Paul.
I use the annotate a lot with charts. Buy/sell targets, reminder of dates. I regularly check charts and great to have info on them. Click the "draw" box above the chart and have a play, right click to delete.
ticker for Likewise (Headlam competitor): Likewise (LON:LIKE) - not LIKE (TYO:2462).
I was wondering why it was listed in Japan for a while...
Thanks moolahcoast, I've fixed that error now.
So pleased for you Paul that you got out of jail in BUMP . Enjoy a celebratory
Thanks Bert, it's Dry January, so I celebrated BUMP with a coffee and a slice of strawberry gateau in Bournemouth this afternoon! :-) Next job this weekend is the Tax Return, clock's ticking on that, end January I think.
" I enjoy doing the company analysis, but am pretty hopeless at managing my own money."
I often wonder why someone as talented as you doesn't sort this out. Investment objectives, a strategy, a plan, rules you refine and improve over the years like never invest when your excited.
Seems like you have cracked the difficult part of investing and you cant be bothered with the dull mundane task of building and managing portfolio.
I think everyone who followes your articles wants to succeed.
You seemed resigned your a bright guy sort it out.
Jag to Daimler to Porsche, next was Trabant?
As Paul says, "....clearly I didn’t follow my own rules here". Its not always as easy as it looks otherwise we would all be millionaires. Just yesterday, I was pondering about breaking one of my rules, I didnt in the end, but I did break another, and that's with me trading for over a decade now. One thing I won't do though is pass judgement on my fellow investor/traders.
Just flagging for interest this article in Retail Gazette who are keeping a running tally of retailers' Christmas trading updates: https://www.retailgazette.co.u...
I thought it was interesting even though I am not sure what themes to take away from it!
"BUMP, HEAD" - really Paul? You taking after MrContrarian these days???
Probably more like SORE HEAD after your win today.....
Have a good weekend, and as ever, your efforts on these posts and the brilliant podcast are very much appreciated.
Dave
Hi Guys, serial poster here - twice this week ! HUGE thanks for these daily snippets, its becoming my go to section every day.
Any comment on SPT after todays news of ahead of forecast revenue & adjusted profits yet massively down ?
Spirent Communications (LON:SPT) has fallen because the market ALWAYS takes the outlook more seriously than the reported performance. And 2023 is cloudy as customers are delaying purchasing decisions owing to macro uncertainty. They even used the dreaded words “performance will be weighted towards the second half of the year”.
I personally think the sell-off is rather overdone because the long-term drivers for this business from the adoption of 5G are very powerful and any delayed orders will be coming in in due course. But it doesn’t help that Ericsson also reported a slowdown this morning.
Hello again Colin!
Spirent Communications (LON:SPT) is above our usual mkt cap limit of (flexible) £700-1000m, and it's not a business or sector I can really add value to by commenting, also we're really short of time today, so sorry.
But feel free to discuss it amongst yourselves here!
Regards, Paul.
Re Spirent Communications (LON:SPT): It looks like Calnex Solutions (LON:CLX) may have fallen back in sympathy too?
There's been director sales in Calnex Solutions (LON:CLX) this week, which might be behind their fall. For now I'm retaining my holding in that company.
Calnex Solutions (LON:CLX) was looking a bit high, I did sell half of mine this week. There are a few others looking toppy after a good run over the last 3 months. Shoe Zone (LON:SHOE) also.
I know it is not a small cap, but Graham has previously reported on Close Brothers (LON:CBG) which is down about 12% this morning.
I have no idea when it comes to banks, but I recall him saying this is preferred of all the main banks.. Grateful if (Graham) you have a moment to add any brief musings..
close brothers is an interesting bank. It is a merchant bank with loans mainly for vehicle purchase, if I remember correctly, an asset management and a market maker business (Winterflood). Caledonia investment trust which is conservatively run, used to hold 21% of its assets in this shares.
It has performed badly since the financial crisis. Today drop mainly relates to some£90 provision for ? underperforming loans.
it pays good dividend , around 7%.
It is on my watchlist until the half year result is out in March.
I view Close Brothers more as a specialist lender than a mainstream bank - I'd also put Secure Trust Bank (LON:STB) and Osb (LON:OSB) in this bucket. By focusing on more niche areas (such as vehicle finance or real estate development loans) they tend to have much higher net interest margins than the likes of NatWest /Lloyds. Close have always been a pretty solid performer (and have actually performed strongly since financial criss which they navigated well so have to disagree on that point). However it's teneded to trade on a big premium to other lenders which I don't think is completely justified (eg Secure Trust is on a 60% discount to book value, whereas Close was trading at a premium, at least until today).
Close Brothers also finances insurance premiums which can range from just a few hundered to ... not sure of upper limit but can certainly do a good 300k or more. Mostly insurance broker commercial insurance business . Loans are secured against the insurance policie(s) with rights of recourse against the client and (depending if the broker covers a %%either the broker also). Most policies refundable to an extent. A lot of admin but highly computerised. Not sure what proportion of the total Close book this represents but from the outside looking in Id assume its petty profitable (is one of only 2 major players in this particular niche market).
I’m a very happy holder of Seraphine (LON:BUMP) having bought a part stake at 9.6p after reading your Blog comment a few weeks ago reproduced below. There’s so much quality information just in that one tiny part of the service you provide for us.
It’s not just the speed that you somehow manage to do it all, but also because of the time on top it takes to analyse updates etc before you can write anything! I can’t fathom how you can comment on so many Companies in such depth and in a so easy to read way that also reflects your warm and generous personality day after day.
Your contributions alone make it worth the subscription to Stockopedia.
Here’s that section from your blog, where you somehow manage to provide us with a written version on top of doing and recording it! Incredible.
“Seraphine (LON:BUMP) (I hold) - I spoke to management but it was an off the record call, so I can’t really say much. But they reiterated what last RNS said - have too much product, so winding it down gradually. The beauty is, 70%+ of product is “continuity” product - i.e. not fashion product, but stuff that sells over continuous years. I think BUMP is a fundamentally good business. But, it is risky, no denying that. Will it be the next Joules? It’s possible, but I suspect not. Is there de-listing risk? Yes, definitely. It’s spending a lot on the listing, and if I were in the Board Room, I’d ask what are we getting from this expenditure on the stock market listing? The share price has collapsed over 90% since it floated, but that’s their fault, because they’ve under-performed. Anyway, BUMP is up against some big macro headwinds that are not its fault - mainly that the cost of marketing has shot up (but now starting to ease). Also inventories built up, but now being shifted gradually. They’re not trashing the brand by over-discounting, which is what killed Joules by going into permanent discount. I think it should be OK. Only has £3.5m of net debt. I know Seraphine is now a risky investment, but £5m market cap is a joke. Trouble is, it has one major shareholder, Mayfair Private Equity, with 43%, who are said to be very supportive. Also Christopher Mills has bought 8%. He doesn’t have enough to swing the decision making, but he has a nasty habit of de-listing companies without paying a proper premium. Although I have to say, his latest de-listing SourceBio looks a very fair price (the tender offer). He thinks the private market will value it more highly. I hope Mills doesn’t do the same thing at Seraphine (de-list it). I did ask management about this, but obviously they can’t reveal anything that might be price sensitive, so I didn’t get anywhere on that point. Even if Seraphine does de-list, I think it’s so cheap, that it probably wouldn’t drop any more. Ludicrously cheap already, and only 15% free float, £750k in total. One buyer could buy the whole lot! I’m prepared to take a risk on Seraphine, I’m aware of what risk:reward is - if it works, a 5-6 bagger, if it goes wrong, potentially a zero. So as long as you know what risk:reward is, you can make a judgement.
Run out of time, byeeeee!”
I also bought in late in December at what might even have luckily been the all time low of 7.9p a share. The writeup you post above was what encouraged me in as a speculative punt, it seemed to have more upside than downside. Paul - congratulations as I'm certain your profits from the day will far exceed mine, however, I am very content with this little earner (Seraphine was 2% of my portfolio) and will be having a few celebratory drinks this evening. Certainly owe you a pint if we ever cross paths!
BenHazz
The above also prompted me to have a speculative punt 10 days ago. Made back some of what I have lost on Hostmore
Paul I was in Exeter yesterday and I made a point of looking at the New Revolution BarRevolution Bars (LON:RBG) which opened in Queen St last summer.It had just 3 customers at one table.It was 1pm.
I know it opens from 12 noon to 2am and Exeter has a huge student population. You might like to look at the Trip Advisor Reviews because although 70 out of 111 are excellent 31 are terrible or poor. One review stands out! Huge apology from the Manager.
Well done on BUMP Paul, very well deserved.
Had some punt money in myself at 8.6p, with Mills in at 10p+ thought it worth a small go.
Ive never been a big fan of buy and hold, the last year has shown me I like it even less now. As BUMP and others show....when the going gets tough the weak bugger off!
Paul - Thanks for all the hard work - and the enormous amount of shares covered recently. How do you keep it up? I'm exhausted just reading it! Your warnings are a really useful balance to the research suggestions. And I'm finding the short summaries way more usefull than I expected and the podcast (I'm not a great user of podcasts) very educational and entertaining!
I do think you are selling yourself short on your investing skills. We can't all be emotional robots - nor can we all suddenly become emotionally suited to investing in a small cap bear market overnight. I'm not.
It doesn't take many more wins than losses to be a successful investor - but that's not going to happen in a bear market and I expect that most of us feel that we've been revealed as poor investors over the last year, I certainly do. But that will pass - you've been reminding us its the decisions we make now when we are hurting most that will determine our future success.
Most reviews of great investors conclude that a deal of luck at the right time is needed in addition to being a great investor. That's been unlikely for the last few years at the top of a bull market and then the recent chaos. And I'll finish with this thought - in my view its your private investor experience warts and all and your experience as an FD that makes your commentary so unique - and encourages us all!
Apologies if I've overdone it. Just saying it as I see it,
cheers
Mark
Seraphine / Bump and Finsbury
Think you are being harsh on yourself it was never a basket case just required a good FD to get the stock turn down and stock levels normalised .
It ended up being a 3 million pound company with 40 million turnover and cash tied up in stock.
My biggest concern was operations which seemed to be creaking but fixable .
Anyway well done.
Market seems a bit frothy at the moment a lot of money sat on the sidelines I think starting to get redeployed .
Rockwood / Christopher mills on yet another winner, those guys are on fire at the moment and they are also into Finsbury food .
Finsbury seem to a real takeover target with Dbsy building heavily and they are advis with LDG who are sat on a pile of cash . I very briefly invested in LDG as sone smart investors are in there especially Richard Griffiths .
All about too smoke and mirrors on LDG so I sold out but they have definitely focussed on Finsbury buying 7% through LDG and 10% through Dbay .
The smarter money might be Finsbury as firstly it’s a great company at good valuation and it has a seemingly interested party with plenty of cash building a stake .
My issue with Finsbury i that I’ve been told to stay off the cakes and pastries .
I see the CEO of Unbound (LON:UBG) bought 400,000 shares yesterday.
18k in cash terms.
Maybe its to encourage confidence, but still its a positive that at least he believes its not a basket case.
Morning Jef Warwick,
re Unbound (LON:UBG) Director buys -
Maybe its to encourage confidence, but still its a positive that at least he believes its not a basket case.
The amounts involved are small relative to the Directors wealth, and I don't think we can assume they believe anything.
I've seen small Director buys at financially distressed companies before, that were probably done to bolster confidence and help attempts to get a placing done.
Given its very wobbly financial position, with excessive debt & now loss-making, I'd be very careful to avoid UBG regardless of what the Directors are doing. Why take the risk, when the numbers are this bad?
Regards, Paul.
My morning smallcap tweet: BUMP jump, Zamboni boosts word supply
Seraphine (LON:BUMP) DSW Capital (LON:DSW) Character (LON:CCT) Octopus Renewables Infrastructure Trust (LON:ORIT) Allergy Therapeutics (LON:AGY) Devro (LON:DVO) De La Rue (LON:DLAR) Circle Property (LON:CRC) Mirriad Advertising (LON:MIRI) Supply@Me Capital (LON:SYME), Trufin (LON:TRU)
◄Seraphine (BUMP)► confirms rec 30p offer, a 206% premium. [SP=9.76 Cap=5m]
◄DSW Capital (DSW)► warns FY-Mar rev £2.8-3.1m (£3m), EBITDA £1.4-1.7m (£2.2m). Several deal completions paused after the Truss Budget and co seeing continued deal slippage and caution in the market. [SP=NA Cap=NA]
◄Character (CCT)► warns FY rev and adj pretax marginally below market expectations. Rev in last 4 months down 42%. [SP=NA Cap=NA]
◄Octopus Renewables Infrastructure Trust (ORIT)► hikes FY-Dec 2023 target dividend to 5.79p, up 10.5%. [SP=95.27 Cap=538m]
◄Allergy Therapeutics (AGY)► guides H1-Dec rev down 18%, "primarily due to the previously announced voluntary short-term pause in production in the UK, together with the previous strategic streamlining of some older products". Co increasingly confident that its funding discussions (as mooted) will be successful. [SP=6 Cap=42m]
◄Devro (DVO)► guides FY-Dec rev up 15% and op profit ahead of the Board's expectations. Cites "strong operating margins, reflecting the benefits of management's pricing actions, operating efficiency and foreign exchange tailwinds." [SP=308 Cap=516m]
◄De La Rue (DLAR)► suspends banknote printing at Kenya JV "owing to current global market demand, and no expectation of new banknote orders from the Central Bank of Kenya for at least the next year". It "further serves to adjust the capacity to current market demand, while retaining the capability to scale up operations when market demand recovers". Does not affect FY guidance. India investigation into the conduct of former Indian Finance Secretary, in which the historical activities of De La Rue in India prior to 2016 have been implicated. Co says no merit to the allegations that relate to De La Rue. Co has not served India since 2016. [SP=78.8 Cap=154m]. I hold.
◄Circle Property (CRC)► plans to return 103p/sh (initially) as it sells assets. [SP=215.1 Cap=63m]
◄Mirriad Advertising (MIRI)► hoists For Sale flag " following the Company's progress and improved position in the US market and the development of its platform capabilities including programmatic readiness, the Company is significantly undervalued". Part of Strategic Review that may include fundraise, strategic partner or de-listing. Co has cash to Q3 2023, as stated [SP=4.1 Cap=11m]
◄Supply @ME Capital (SYME)► long biz update. New Italian legislation when passed "is expected to provide greater opportunities for Italian banks to adopt the Platform". TradeFlow AuM up 25% over year to Dec. Zamboni claims everything's great. [SP=0.06 Cap=31m]
In line: TRU
Congrats on BUMP Paul - See you Monday then :)
Worrying news on consumer spending in December. It’s not going to get better in the near future. From investing.com
Retail sales volumes fell by 1% in December from November, the Office for National Statistics said.
A Reuters poll of economists had pointed to a 0.5% monthly rise in sales in the key Christmas month.
Compared with December 2021, sales were down by 5.8%, the biggest fall for that month in records going back to 1997.
In terms of value, spending was down by a month-on-month 1.2%
A survey published earlier on Friday showed a first drop in three months in consumer confidence in January which fell back close to its lowest level since at least 1974.
Any retail company reporting in line figures in this environment is doing well.
Well done Paul with the takeover of Seraphine. As investors we have to take all the bumps (haha!) that come our way, so very important to enjoy the good moments too - the highs and lows of investing!
Also very impressed with mountain of updates you are churning out at the moment!
Congratulations Paul on the Seraphine (LON:BUMP) exit…good to see
Half year results out of City of London Investment (LON:CLIG) today. I hold. Funds under management pretty much unchanged. Unaudited profit £11.9m v £15.6m, which puzzles me. The sums work out fine, but I'm not sure why the profit is down. However if you work out an annualised EPS, it seems to me that it is projected to be higher than forecast, which is what I've expected. Best case maybe 43p for a full year, worst case maybe 35p as forecast.
The divi is unchanged and management have stressed that it will continue to be supported due to cash reserves.
Valuation feels about right or maybe a little high to me. I continue to hold. This is never going to be a growth stock, just a high yielder. If anyone else can cast more light on the profit decline, I will be interested....
A stock which depends upon emerging market stock markets; not without risk but they are on reasonable valuations.
It's probably also worth noting City of London Investment (LON:CLIG) is very affected by currency movements with dollar. Hence its revenue and profits have held up very well vs other fund managers this year because the dollar strength has made up for any reduction in FuM.
I really like City of London Investment (LON:CLIG) - massive divi underwritten by a decent cash pile and very conservatively run.
Yet the $ is down around 17% against the £ from September, 2022. It is now 1.24$ to £, was 1.05 at the low.