Small Cap Value Report (Fri 20 May 2022) - EYE, SAA, WRKS, WIN

Good morning! Friday, and it's Paul & Jack here to round off the week. Looking at the futures, it looks like today will be a bounce-back day, which is always nice for a Friday - less worrying over the weekend. Today's report is now finished, have a lovely weekend!
In case you missed it, lots of people were asking me to review Shoe Zone (LON:SHOE) results, so I did in yesterday's report here. It looks potentially very good, although I'm a bit wary of the household spending squeeze, which is impacting lower income households the most (due to energy & food being a higher % of their outgoings).
Agenda -
Eagle Eye Solutions (LON:EYE) - a strong trading update, with FY 6/2022 profit (well, EBITDA anyway!) guidance raised 10%. It's wildly expensive on a PER basis, so not for value investors. However, it seems clear that there's something special with EYE's product, given it is building recurring revenues with major retailers around the world. So it appeals to my more adventurous investing side.
M&C Saatchi (LON:SAA) - a surprise twist to the story here, where Vin Murria has been trying to force through a hostile takeover bid - not something you expect from one of SAA's own Directors! Today we're told that a better deal has been agreed with £NFC which looks a good outcome for SAA shareholders. There could be an 11% profit on arbitraging this deal, if I've got my figures right, at 220p per SAA share in the open market.
Works co uk (LON:WRKS) - a superficially positive trading update, but it's not as convincing once you dig into the detail. Tiny market cap, so could be worth a punt, but of the smaller retailers, I think SHOE wipes the floor with this (I hold neither).
Wincanton (LON:WIN) - a thumbs up from me, despite my dislike of its weak balance sheet. This logistics business is performing well, and open book contracts mean that it can pass on most increased costs to customers, reducing risk of a profit warning. Good order book. Low PER mainly due to large pension deficit recovery cash outflows, but that could be a receding issue now, possibly? I think this is a good share to own long-term, and with not much short-term risk apparent either.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Eagle Eye Solutions (LON:EYE)
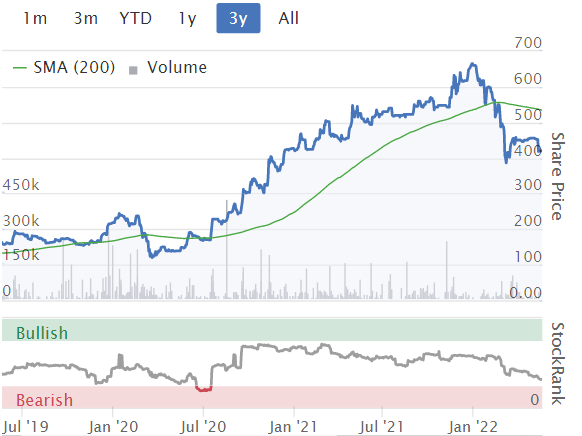
420p (yesterday’s close)
Market cap £110m
Eagle Eye (LSE: "EYE"), a leading SaaS technology company that creates digital connections enabling personalised, real-time marketing…
PR headline -
Strong momentum continues with go live of national US grocer, lifting expectations for the year
Good news, it’s trading ahead of expectations -
… is pleased to announce a continued positive trading performance since the release of Interim Results in March 2022. A notable development in the period is the go live of the national US grocer, announced in January 2022, secured alongside our partner, Neptune Retail Solutions.
As a result, the Board now anticipates revenues and adjusted EBITDA for the year ending 30 June 2022 ("FY22") will be ahead of current market expectations* by approximately 7% and 10% respectively.
* Market consensus for FY22 is Group revenue of £28.1m and adjusted EBITDA of £5.2m.
Thanks for the footnote on market expectations, that saves investors so much time. It needs to be become standard practice for all company announcements. Why on earth wouldn’t all companies include something that so obviously helps investors digest an update? (the only reason I can think of, is because they’re badly advised!). No complaints here though with EYE.
So it’s now saying that adj EBITDA will be c. £5.7m.
As I always point out, EBITDA is meaningless in some sectors, especially software, where they capitalise so much of the payroll (development spend) onto the balance sheet. That’s allowed under accounting standards, but it means that EBITDA is absolutely not a proxy for cash generation!
For example, a previous broker note showed that £5.2m EBITDA turned into only £1.6m adj PBT, a huge difference, hence this is a key point. That was 4.8p adj EPS.
If we uplift the profit figures by the 10% indicated today, we get to 5.3p EPS for FY 6/2022, giving a PER of 79 times. That ‘s a lot, especially in a market where tech valuations have crashed (look at NASDAQ, and it’s even worse when you strip out the mega caps).
EDIT: Update at 09:27 - a new note from Shore Capital has just come through, many thanks, revising up adj EPS to 5.7p for FY 6/2022, and the share price has moved up 10% (as at 09:27) to 458p. Combining those, the PER is now 80, so negligible change from my draft calculations above. End of edit.
Should we be valuing EYE on a PER basis? Maybe not, because it’s a credible growth story, and is gradually building a highly impressive client list, with recurring revenues. Therefore the value in EYE shares is probably more about those client relationships, and how valuable it could be to an acquirer, and long-term growth.
There again, that all sounds like boom talk, and maybe we need to un-learn the bad habits in justifying excessive valuations on tech shares in the last few years?
Anyway, whether you find the valuation attractive or not, is up to you. I’m struggling with the valuation, despite it having dropped by a third from the peak. Although an out-perform update today clearly helps.
I suppose downside risk is that some better technology comes along, and EYE becomes old hat, and withers away. Tech moves so quickly these days, it's dangerous to assume today's winners will necessarily still be going strong in say 5 years' time.
What else?
Significant new clients wins
Deepening with existing clients (so EYE clearly has an attractive product)
Outlook - positive -
Tim Mason, Chief Executive of Eagle Eye, said: "We are delighted to have taken one of the largest grocery retailers in the US live on the AIR platform so quickly, providing us with another fantastic demonstration of the relevance of our combined offering with Neptune in this substantial market. Our ability to deliver personalised, 1:1 marketing at scale is resonating with retailers around the world, as they seek to accelerate their digital marketing strategies.
"This successful go live and growing momentum in the business, combined with the underlying strength of our SaaS metrics and record new business pipeline, all combine to underpin the Board's confidence in our outperformance in the current year and prospects for sustained growth."
My opinion - it doesn’t work for me on the numbers alone, from a value investing perspective. Plus growth investors have taken a long-overdue battering recently, as often ludicrous valuations reset hugely downwards.
That said, I do think there’s clear evidence of something special with EYE - winning & retaining lots of major retailing clients, internationally, building recurring revenues, etc. It’s more about the strategic value of EYE, and what a bidder might pay for it - which could be substantial I reckon. So you probably can justify the high market cap on that basis.
Meanwhile, now it’s making money (at last), it shouldn’t need another fundraising, so dilution shouldn’t be a worry.
Overall, I think this share looks interesting, for more adventurous investors.
.
.
M&C Saatchi (LON:SAA)
214p (up 30% at 08:15)
Market cap £262m
SAA shareholders collectively get a £60m windfall today, as the share price shoots up on news of a recommended takeover bid from Next Fifteen Communications (LON:NFC) (market cap £1.2bn).
This has been a fascinating situation to follow. Renowned tech investor, Vin Murria, nicknamed “Britain’s tech queen”, joined the Board of SAA, and obviously liked the company so much that she bought up shares in it personally, and via a cash shell company £ADVT , then tried to buy SAA in a hostile takeover approach, which never made any sense at all to me - it was just an attempt to seize control of SAA, in my view.
Why would investors in SAA, a successful company, want to swap their SAA shares for shares in a cash shell, thereby handing control to Ms Murria? It was a daft idea, in my view, and really not the kind of thing I would expect a Director of any company to attempt. Shareholders want Directors that are loyal to the company, not some kind of trojan horse.
SAA rebuffed her approaches, and it now turns out they’ve been working behind the scenes on a better deal, from NFC.
Recommended acquisition - of SAA by NFC.
This is a recommended deal, i.e. agreed by SAA’s independent Directors.
Terms - it’s 40p in cash (not very much), and mostly in new NFC shares.
The trouble with paper deals, is that the takeover price changes in real time, as the NFC share price moves. The formula to work out the current value of SAA shares, if the bid goes ahead, would be:
40p + (0.1637 * NFC share price)
At the moment that would be:
40p + (0.1637 * 1258p) = 246p per SAA share.
You can currently buy SAA shares in the market for 222p, so that looks an anomaly to me, or I’ve got my formula wrong! There could be an 11% profit there for traders, arbitraging this deal, if it goes ahead. Downside risk is that Vin Murria blocks the deal, but why would she, as she’s the biggest SAA shareholder, and would probably be delighted to bank her profits, which would more than cover all the costs of her abortive bid. I’m guessing there, obviously.
Another risk is that NFC would be issuing a lot of new shares, to people who don't necessarily want to hold them. So there could be an overhang, leading to NFC shares drifting down over time, possibly?
My opinion - as you can tell, I didn’t like the Vin Murria deal, it looked opportunistic, and illogical to me. There was little logic to the deal for outside shareholders.
That seems to have forced SAA to find a white knight to take it over. Pity really, as SAA was a good company, and some shareholders might have preferred it to remain independent.
However, NFC is offering a substantial premium, and at a time when shares in PR/marketing companies would probably wilt, given the macro picture.
Hence the NFC deal looks sensible to me, and if I were a SAA shareholder, I’d accept it.
EDIT: I see AdvancedAdvT (LON:ADVT) has issued a statement, just saying that it is considering its position. Maybe they'll try to push NFC to pay more, or adjust the deal to include more cash than paper?
So far, the stock market seems to like the deal, with NFC share price now slightly up on the day, at 1284p (up 1.4%) although that's only on tiny reported volume of shares traded - but as always, there could be larger trades not yet printed, as big trades are allowed delayed reporting, or could be "working" in the background - i.e. being bought/sold piecemeal, before being reported once the trade is complete). SAA share price is now 225p to buy (at 08:55) which is offering a >10% profit, if the NFC deal goes ahead, and providing NFC shares don't drop - could be an interesting trade, for arbitrage specialists, as mentioned above)?
.
Works co uk (LON:WRKS)
57p (up 13% at 10:09)
Market cap £35m
TheWorks.co.uk plc, the multi-channel value retailer of arts, crafts, toys, books and stationery, announces a trading update for the 52 weeks ended 1 May 2022 (the "Period" or "FY22").
I’ll call that FY 4/2022, as it only includes 1 day of May.
WRKS shares have come up on the top % risers list, so I’ll prioritise reviewing this.
Here are my notes -
This only sounds in line with expectations - good, but why would that trigger a 13% share price rise? -
Improved proposition helping to offset external headwinds; FY22 EBITDA forecast of £15.0m is reiterated.
Note that only about half of EBITDA turns into profit before tax. In EPS terms, current consensus is 9.2p, a PER of 6.2 - seems cheap, but I’m not convinced that level of profitability is sustainable, due to the benefit of -
Business rates relief - a red flag here, which I raised when digging into the interim results here. It seems that business rates relief has been a massive boost to profit. That’s phased out now, so the question is whether sales can rise enough to recoup this big headwind?
Striking improvement in net cash to £16.3m, from almost nothing a year ago. The interims show net cash of £17.8m at 31 Oct 2021, which doesn’t tie in with today’s announcement, which says that net cash was £10.0m at the interim stage - strange. How come? Where did all this cash appear from in H1? Luckily I investigated cash here, when reporting on interim results. It’s vital reading to put today’s update in perspective - namely that the huge increase in net cash in H1 was largely down to favourable working capital movements - i.e. a big increase in trade payables of £10m, for an increase in inventories of only £2m. That said, net cash has only slipped back a bit in H2, which is seasonally much stronger, so it looks OK.
Put more simply, the big increase in net cash looks to be one-off in nature, not likely to repeat to anything like that extent in future, if at all.
Performance is highly seasonal, with most profits coming in H2.
Divis reinstated - OK this would be seen positively by investors, with a policy to increase divis further in future - probably behind today's investor buying interest.
Sales - the best comparison is with pre-pandemic, and it’s good - up 10.4% on a like-for-like (i.e. same stores) basis. Although that includes online, with no split given of online/stores.
Product developments, including drawing new attention to books (“BookTok” phenomenon - no idea, we’ll need to google that!)
Branded toys & games doing well (e.g. Peppa Pig - any read-across to £CCT I wonder?)
Cyber-security incident end March (RNS’d on 5 April 2022, so not news).
Store portfolio is 525, with only minor changes in the year.
Results delayed, to Sept 2022, compared with July last year. The reason given is improvements to IT, following the cybersecurity incident. Accounts shouldn’t take 6 months to prepare, so this reinforces to me that financial controls at WRKS seem weak. Although I suppose moving from July to Sept jumps the summer holidays too.
Current consumer spending - as expected is under pressure, and it’s interesting that investors have looked past this today, so perhaps markets have now factored in the macro slowdown? -
Consumer spending is widely reported to have slowed in recent months and we believe this has had an impact on our sales…
Outlook - good to hear that the company says it is budgeting prudently -
There continues to be uncertainty relating to the external environment and how this might affect levels of consumer spending in the months ahead. This has been taken into account in setting the Group's internal plans for FY23.
The Board remains confident in the future prospects of the business because of the underlying appeal and relevance of The Works' proposition, the opportunity to grow sales profitably through the implementation of its strategy, and the Group's strong financial position.
My opinion - WRKS looks good superficially, but I always find with WRKS that when I dig deeper, things are not as good as they first looked.
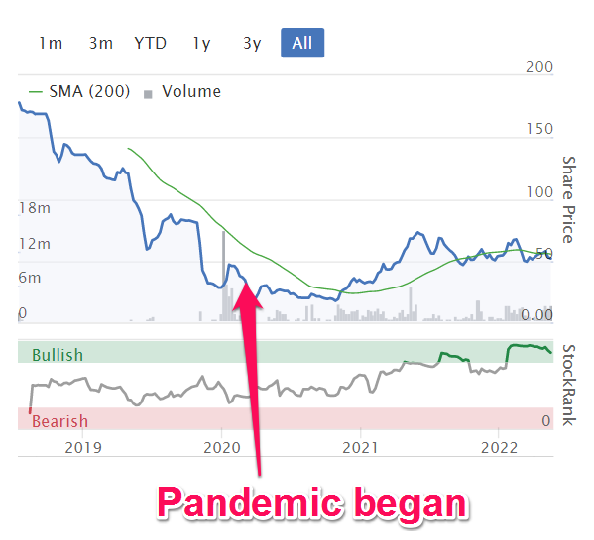
Bottom line for me, is that this was a float in 2018, which went disastrously wrong before the pandemic. Sure, improvements to the business have been made during the pandemic. However, I think the current bumper profits have been helped by substantial business rates relief, despite there being little impact on trading from the pandemic during this latest period, probably providing a net boost to profits.
Therefore, combined with a consumer slowdown, I reckon there’s a considerable risk of profits tumbling in the new financial year, as business rates revert to normal (which seem to be about £14m p.a., so it’s a huge cost).
That said, reinstatement of divis suggest management are confident, so who knows?
Personally I think it probably looks priced about right for now, given the macro uncertainties, and it’s fundamentally not a very good business. So not really a turnaround situation with big upside, which would interest me more.
Time will tell how it trades once everything is normalised, in particular re business rates. I reckon future profits probably aren't likely to be much more than breakeven, but as always I could be wrong, because nobody can predict the future.
If you have to buy a small cap retailer, then SHOE from yesterday’s report looks vastly better than WRKS in my opinion.
Share price since listing -
.
Wincanton (LON:WIN)
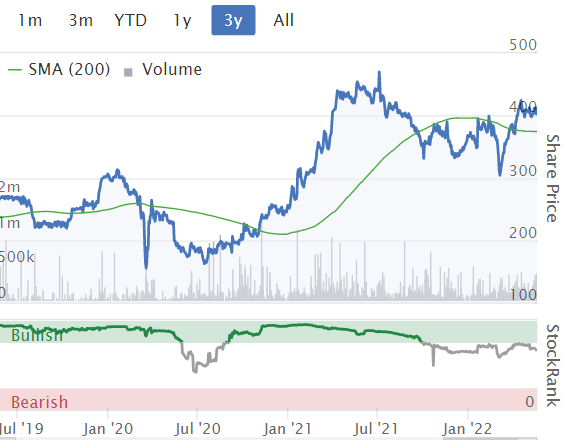
412p (up 2% at 12:24)
Market cap £511m
We’ve been reporting positively on Wincanton for a while now, with impressive trading updates. We didn’t cover it at the time, but a trading update on 5 April 2022 gave guidance for FY 3/2022 of adj PBT c.£56.5m.
Today’s actual is a c.3% beat, with adj PBT actual being £58.1m (up an impressive 23% vs LY), on revenues of £1.42bn (up 16%), so an improved PBT margin of 4.1% (LY: 3.9%).
That profit beat is all the more impressive, given that forecast EPS has been steadily rising, as you can see below, with actual adj EPS coming out at 40.8p, a PER of 10.1.
Statutory profit is 94% of adjusted profit, so not a huge difference.

.
Dividend totals 12.0p (Interim: 4p, Final: 8p) is the same as forecast. The yield is only 2.9%, due to so much cash being needed to fund the pension deficit overpayments, and the weak balance sheet.
Inflation protection - a key factor right now, that we have to think about for every investment. By using mainly open book contracts, WIN passes on cost increases to its clients. Hence this should be a robust business model in a higher inflationary world, as seems likely for the foreseeable future -
… Inflationary headwinds mitigated by management actions on costs and contract mix; less than 30% of Group revenue from closed book contracts
For investors, this means a much lower risk of a profit warning, so is of considerable importance, and makes WIN shares attractive.
Outlook - vague, but reassuring -
Outlook
· Wincanton is well positioned to maintain its positive performance across its chosen markets, driven by ongoing investment in the business and continued progress against our strategy
· While the Group remains mindful about the macro-economic headwinds and the potential impact on consumer sentiment, there is good momentum in the new business pipeline and we are confident in the future growth opportunities across all four of our sectors and in our continued ability to deliver our strategy successfully
Pension scheme(s) - still a huge issue. The commentary says £19.2m was paid in cash, into the pension scheme in FY 3/2022. Remember that is not expensed through the P&L! This is why the PER of 10.1 looks so low, for a successful business - it’s because so much of the profit/cashflow by-passes equity holders, and has to be paid into the pension scheme.
The interesting thing is that higher bond yields recently seem to be generally reducing pension deficits, sometimes by a lot (each is different in its rules, actuarial assumptions, etc).
We’re told that £20.7m is to be paid into the pension scheme for deficit recovery payments in the new financial year FY 3/2023.

This table above is useful, in showing how the higher discount rate (linked to bonds) has reduced liabilities. Although recent asset price falls looks to have reduced assets, but by a smaller amount. Giving a pension scheme surplus of £114.5m.
For people not familiar with the total mess that is pension scheme accounting, there are 2 sets of rules. Accounting rules, for the accounts. And actuarial rules (stricter) which determine the more important cash payments to rectify any deficit. So clearly the actuarial rules are far more important, as they determine real world cashflows from the company to the pension scheme.
The company does comment on the all-important actuarial deficit, saying this today -
The estimated actuarial deficit on a technical provision basis has reduced to £37m at 31 March 2022, compared to £67m at 31 March 2021. At 31 March 2022, the Scheme's investments were split between 19% in return-seeking assets and 81% in defensive assets. The inflation and interest rate risks facing the Scheme are hedged to mitigate the quantum of any future movements in the actuarial valuation.
I’m guessing here, but that seems to suggest that only 2 years’ more cash payments of c.£19m would eliminate the pension scheme actuarial deficit, and hence presumably not require any more cash payments - which would be fantastic for equity holders, as it could possibly trigger a re-rating of maybe 50-100% on the shares? Although the trouble is, as you can see above, is that the pension deficit is the difference between 2 very large numbers, which are both subject to volatility. So although things seem to be moving in the right direction, that could change again - e.g. if bond rates reduce again due to a recession & more QE, alongside assets continuing to collapse in value. Hence I would say the pension situation has improved, but remains a significant risk.
Balance sheet - is still poor, but has improved a lot, mainly due to the pension scheme “asset” having risen from £50.8m to £117.0m. The only problem is that it’s not really an asset, because the company is actually paying large deficit recovery cash payments into it.
Ignoring this £117m pension asset, and the £110.7m intangibles/goodwill, results in NTAV being negative at £(147.2)m - I’ve also written off the £16.9m deferred tax creditor, as that is probably linked to the pension scheme.
There’s little interest-bearing debt though, only £25m, and that was more than covered by cash of £28.7m on the balance sheet date, so a small net cash position.
How can this be, when NTAV is so bad? It’s because customers fund the business, by paying cash up-front. Hence why trade payables is so enormous, at £323.6m, as it contains the offsetting credit entries relating to customer cash debits.
In conclusion then, WIN is in a lovely position where it seems to have a permanently favourable negative working capital position - very much like furniture retailers.
Although I'd like to see the daily cashflows, and the average daily net cash/debt, which can sometimes be very different to a year end snapshot on one day.
The bank is clearly happy too, having extended facilities to £175m, not maturing until March 2026. WIN has plenty of headroom against its bank covenants, so no issues there. It also has some additional bank facilities of £57.5m for various purposes if needed.
My opinion - I do like this share, because the company is performing really well, and seems to attract & retain big retail customers, so it clearly must be very well organised, hence very good at distributing stuff. The weak balance sheet isn’t a deal-breaker, providing customers remain happy to pay up-front.
What intrigues me, is that if the pension deficit payments (which currently are greater cash outflows than divis to shareholders, so it’s a big issue) do reduce, or even stop, which appears to be a possibility, then that could trigger a re-rating of the shares - since it would enable divis to be doubled, to a 6% yield, and/or fuel more acquisitions.
WIN shares also have considerable inflation protection, due to its open book contracts, which is a big plus right now in current macro conditions - i.e. profits should be protected, despite higher costs, as they can be passed on within most existing contract terms.
Clipper sold for a PER way higher than 10 (Wincanton’s) suggesting there could be big upside on WIN shares long-term, and providing the pension scheme behaves itself.
Therefore, this share gets a thumbs up from me. As a reader pointed out yesterday, we should really compile a list & update it every day for shares which get the coveted thumbs up from the SCVR! We only give that to companies which are performing well, and which are reasonably priced. Not to the more speculative turnarounds that often crop up, but tend to be higher risk.
.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

70 comments
wonder what Richard Crow thinks of the Works co uk (LON:WRKS) trading update Paul, as he was certainly very bullish in the podcast you did with him , released on the 22nd July !! He has such a good track record, that I am inclined to think this maybe a good buying opportunity. Like Saga (LON:SAGA) I think it’s a case of just being patient with bombed out shares !!
ignore as posted on wrong thread !
Paul thanks for your write up on Eagle Eye Solutions (LON:EYE) - although I normally am put off by sky high P/Es, I do hold Eagle Eye (and have been buying over the last few weeks).
It is also worth pointing out one negative today, in that founder and CTO Steve Rothwell exercised low-cost options and sold the resulting >£1m of stock today at 455p. While any director sale is a negative - it should be pointed out that Rothwell has been an intermittent seller of shares in the past, when other directors have been buyers. Also despite being the founder of the company, Rothwell is not the public face of the company, with CEO Tim Mason and CFO Lucy Sharman-Monday facing investors. The key director shareholders are long-standing NEDs, William Currie (13%) and Sir Terry Leahy (9%), who was Tim Mason's old boss at Tesco.
K3 Capital (LON:K3C) today (I hold) just about sums the whole pantomime up..lol :-)
Or did i miss an RNS?
Recent strength might be a read across from Begbies Traynor (LON:BEG) in my opinion.
No RNS
But I would guess one of the reasons for recent weakness and very recent strength is a seller clearing .
In another place the rise of K3 Capital (LON:K3C)has been attributed to this:
https://www.linkedin.com/feed/...
I am not currently a shareholder, waiting for a suitable entry point, if one ever comes! As a long time Saga (LON:SAGA) watcher and regular user - for our needs in the upper age range, their what I might call 'sedimentary' holiday offerings - flight & hotel; flight and tour; sometimes flight, hotels and boat (eg Adriatic) - are superb value and ver7 satisfactory quality.
We have looked at their cruises on the new liners, and some months ago tried to get a good stateroom on their Christmas 22 cruise to the Canaries. No deal; full up,
Interestingly we were offered a range of staterooms yesterday after being told we were on the end of a long waiting list at the time we enquired. Symptomatic of a significant level of cancellations in the economic circumstances? Who knows?
In the meantime, even if there were rook on the liner, we reconsidered the prospect of spending a significant time at sea in December, much of it in the Bay of Biscay, and decided to fly to Madeira instead - another sedentary holiday, with Saga of course. Looking forward to it, though taking thermals, especially after last holiday in Lanzarote in Feb 2019 when they would have been most welcome!
Thanks ridavies!
Incidentally, I follow the RNSs from Carnival (LON:CCL) and they recently sold out their new ship in record time. There's little doubt that affluent pensioners have huge pent-up demand for cruises, and the means to pay for it.
For that reason, I'm taking a very positive 2-year view of SAGA. Cruise should do well this year, but tour less so - that seems to be needing more time to rebuild.
Some headwinds in the insurance division, but again that's all known about.
I think it's just a question of being patient, with lots of bombed out shares.
Generally speaking, aAs long as the balance sheet is OK, then I'm trying to ignore the share price altogether. I'm not an owner of this year's earnings. as a shareholder in many companies, I own all future earnings. This makes a downturn (likely in many cases) this year a blip, rather than a permanent loss of shareholder value.
Regards, Paul.
A quick look at various Saga (LON:SAGA) cruises this summer shows good booking rates already, albeit nothing sold out of 90%+, and I do see they are still running discounts and promos on some summer cruises, which they won't if demand was exceptionally strong.
Will be very interesting to see, in about half a year, the profitability from their cruise operations. As no figures available from pre-covid to extrapolate from. However, even then we won't get the full potential. Increased fuel costs, staff wages, food costs... margins will be depressed. On the other hand, I'm hoping they're selling more cruises at sticker price rather than discounting.
Insurance will keep throwing off cash. And with QT happening, hopefully less money going into the sector and driving down premiums as has been the case.
(I hold in the Boon Fund)
Shoe Zone (LON:SHOE) (I Hold) More Good News for holders!
Shoe Zone announces that Terry Boot, Finance Director of the Company, has
today purchased 25,000 ordinary shares of 1 pence each in the Company
("Ordinary Shares") at a price of 151.5 pence per Ordinary Share, (the
"Purchase"). Following the Purchase, Mr Boot's shareholding stands at 32,626
Ordinary Shares in Shoe Zone, which represents 0.07% of Shoe Zone's current
issued share capital.
At least he will be instep with other shareholders now. I have seen a presentation by this chap, he's a decent soul, and he cobbled together some very useful figures. As you know plenty of FD's talk a real Croc a lot of the time. Mind you this guy wasn't afraid to stick the boot into the opposition. Although if you've ever been into one of their stores they're pretty sole less places.
Ok enough, but it is Friday afternoon and the markets are up today - have a great weekend!
Hey "Norfolk", just the ticket, a Friday afternoon giggle!
I think you out-punned even Austin Powers there, outstanding effort! :-)
Best wishes, Paul.
Why is Character (LON:CCT) mentioned in 'Securities mentioned' on the RHS of the page? I cannot see any reference to it anywhere else?
Why is Character (LON:CCT) mentioned in 'Securities mentioned' on the RHS of the page? I cannot see any reference to it anywhere else?
The ticker didn't activate in the text: "Branded toys & games doing well (e.g. Peppa Pig - any read-across to Character (LON:CCT) I wonder?)"
Edit: that was in Works co uk (LON:WRKS)
Thanks for your write up yesterday on Shoe Zone (LON:SHOE) Paul. RNS just released today to show the FD (the very aptly named Terry Boot!) has just purchased 25k shares in the company. Another very positive sign for the company.
The CFO at Spectra Systems (LON:SPSY) has resigned w.e.f. June 3 to pursue other business opportunities. he is thanked.
Thanks for the analysis of Works co uk (LON:WRKS) (I don't hold). The shop in Tunbridge Wells has one or two people in it whenever I pass though that seems too few to cover the overheads. They were receiving a pallet of new stock yesterday. Card Factory (LON:CARD) seems pretty empty too (I don't hold). [In the recent Mello, 'Cockney Rebel' suggested these cheap shops were potentially interesting in view of inflation, so I have been looking at them].
In contrast, Poundland and Wilko always seem busy. (are either of these listed?).
Could you look at Anglo-Eastern Plantations (LON:AEP), Indonesian Palm Oil producer, Trading update at 11am today for 3 months to 31st March 22. £320 market cap, with £202m Cash. Confirms that the export ban has now been lifted.
Palm oil is a fascinating micro sector. Each constituent has its peculiarities. Dekel Agri-Vision (LON:DKL) is really a play on the cashew project and the entrepreneurship of the management (and that fighting in C/W Africa doesn't get to Ivory Coast) Anglo-Eastern Plantations (LON:AEP) is majority owned by one of Malaysia's richest ladies. She's in her 80s and doesn't seem interested in doing anything with it, hence there is no reason to expect a short term revaluation or a special divi. She could have another 20 years in her! R E A Holdings (LON:RE.) is a play on current high prices enabling it to pay off debt and get out of the financial doo-doo caused by ill-executed diversification and M P Evans (LON:MPE) is the quality pick of the bunch and without the weirdisms but is much more highly valued.
Overlay this with events in Ukraine which have reduced supply of substitute veg oils, politics in Indonesia and environmental concerns and it is fun to watch!
I own all of the above except for M P Evans (LON:MPE) I especially like the 9.25% prefs which have substantial arrears but are now in catch up mode £RE.B and hope like heck that Dekel can pull off a big win with cashews as it is my largest holding and the cashew opportunity is big, they just have to get the full processing plant finally commissioned... I don't rate their palm oil business especially highly (as their balance is to processing rather than owning sources of production), the others grow more of their own palms.
Hi DAZZA64,
SRe Anglo-Eastern Plantations (LON:AEP) - sorry, we tend not to cover overseas companies that list in the UK. The reason being, to quote Mark Slater, "There's usually something wrong with them!" Note usually, so I'm not saying anything specific about AEP.
Looking at its StockReport, I see AEP has been listed in the UK for a long time, which is a key positive (frauds don't tend to last more than 5 years or so). But it seems to report huge profits, a low PER, but only tiny divis - not good.
Where's all the profit/cashflow going? It seems to be spent on capex, which actually does make sense for a plantation owner, where it would take a few years for crops to be produced. It would be good to somehow verify with a local that the company does indeed own what it claims to own. For overseas investments, I think a private detective is more useful than other things!
I think given the long track record as a listed company, being on the main list, then AEP looks an exception to my usual rule of avoiding like the plague overseas small caps listed in London - so many of them turned out to be frauds, indeed I think ALL the Chinese AIM floats turned out to be frauds, a few years ago.
AEP has a long, and pretty good track record though, so I wouldn't want to dissuade you about this particular company, based on a very quick look at the StockReport. Key issues would be whether management are trustworthy, and maybe ESG concerns about palm oil (not something I know anything about, but we hear a lot about it).
By all means post more detail on it, if you think it's good :-)
Regards, Paul.
Thanks for this Paul, I think Richard Goodwin has summed up AEP well about the main issue of one individual owning 51% and the miserable dividend. I do hold AEP and given the general outlook for palm oil and the barriers for entry into all cooking oils, AEP are likely to hold there current full market cap in cash within the next 15 months unless the Indonesian government throw a spanner in the works. In terms of ESG then AEP are not ripping up forests to grow palm oil (although this will have happened many decades ago) and palm oil production is very efficient in terms of land used, when compared to alternative cooking oils.
Re Anglo-Eastern Plantations (LON:AEP) - sorry, we tend not to cover overseas companies that list in the UK. The reason being, to quote Mark Slater, "There's usually something wrong with them!" Note usually, so I'm not saying anything specific about AEP.
Looking at its StockReport, I see AEP has been listed in the UK for a long time, which is a key positive (frauds don't tend to last more than 5 years or so).
Anglo-Eastern Plantations (LON:AEP) has been listed since 1985 so if it's a scam it's a slow burner :-)
The history is interesting: https://www.angloeastern.co.uk... Anyway, the elderly Madam Lim Siew Kim has a controlling interest but no apparent involvement in running the business which goes its own sweet way. And the moment the business is very sweet indeed because crude palm oil prices have rocketed due to the Ukraine conflict restricting the supply of sunflower oil.
AEP had $218 million on the balance sheet at the end of the last financial year. Despite the various issues, including the temporary ban on exports by the Indonesian government which has just been lifted and an increase in taxes, it's hard to see them making less than the $137 million they made last year.
For reference crude palm oil prices were averaging around $850 per ton last year, this year they look like being around $1,300 (they've been a lot higher). So at the current rate cash will soon exceed the market cap - or the market cap will be a lot higher.
It won't last, it never does, but in the meantime it looks like a decent place to keep some money as a proxy for agricultural commodities.
timarr
SRT Marine Systems (LON:SRT) presented to a PIWORLD audience on Wednesday here is the video & podcast. No questions were left unanswered by CEO Simon Tucker. Investors have had to be very patient here, now, there may be signs their patience will be rewarded. finnCap forecasts, (5 April 22) an increase in revenue by 5x by FY23 when they will move into a healthy profit.
M&C Saatchi (LON:SAA), thanks for the write up Paul.
also interesting is now AdvancedAdvT (LON:ADVT) shares themselves. If the bid goes through, even without a higher Next Fifteen Communications (LON:NFC) offer, the NAV of AdvancedAdvT (LON:ADVT) increases to 112p. this will be c.80p CASH, but the remaining c. 40m held in NFC shares could be very quickly turned into CASH given the size and liquidity of £NFC.
disc, I hold AdvancedAdvT (LON:ADVT), my strategy is low risk value investing so buying at discount to CASH seems attractive to me, and VM will probably now be free to use that CASH profitably after recent tech share price falls.
Hi 305020,
Interesting, thanks! re. AdvancedAdvT (LON:ADVT)
Although I reckon Vin Murria is likely to have run up substantial fees, which would need to come off the ADVT cash figure. Couple of million quid maybe, at a guess?
It's been a fascinating situation to follow, I can't remember anything like this happening before in small caps anyway.
As you say, with tech valuations having crashed, ADVT is in a much better position now to find some bargains to acquire.
Regards, Paul.
Good morning guys. I think this is a great place to chew the cud over stocks and I thank you all for your intelligent input. I have one suggestion. If you make a comment about a stock it would always be useful to include whether you hold it already, are in the market to buy it or are a seller. Some comments, very few, but some one suspects are individuals just trying to ramp a stock. I have been in the industry a long time and one thing that annoys me is rampers!! Its is just dishonest. NOT SAYING ANYONE HAS.
Very pleasing update from Braemar Shipping Services (LON:BMS) . Management must be confident if they are able to provide an upgraded underlying profit before tax for the year ending February 2023. Market consensus is for £10m, but the company have said that due to increased scale and current favourable market conditions it will now be not less that £12m. Quite an improvement. Also a increased dividend of 5p is to be paid at forthcoming prelims, originally the intention had been to pay a dividend of 4p.
Currently held in my wife's ISA which she naively lets me manage.
Morning jonno,
That's a smashing synopsis, I've just checked it all against the RNS from Braemar Shipping Services (LON:BMS) and it's accurate - as I would expect from you! Sometimes people who hold a share like to cherry-pick the positives, so I always check the facts before giving a thumbs up :-)
I don't feel confident about reporting on BMS, so usually leave it to Jack or Roland, because the sector is a mystery to me.
I suppose one has to ask the question that, given profiteering by major shipping companies, enabled by supply chain crises, why isn't BMS making much more than it is?
E.g. look at the Stocko graphs for major shipping group Hapag-Lloyd (HLAG) below! (European subscription on Stocko needed to access the StockReport)
Thank you Paul. I am flattered.
All the best
Held Braemar Shipping Services (LON:BMS) for a long time, a long-lived dog, am continuing to be pessimistic.
The selloff of Yellow Cake (LON:YCA) may have reached a turning (inflection) point. NAV announced at £3.96 today supported by a strong $
Uranium prices are significantly off their highs but IMO that may be short term unless energy prices come down.
Chart is set up for a possible break out.
I added this to my watchlist this week as a pullback entry. Correct order of moving averages, 50DMA, 100, 200, price trending up, Stoch & RSI trending up. Just crossed the 100MA and 26 today. Has been supported by the 200MA since Jan 2021. hopefully it can hold above the 100ma today.
Yellow Cake (LON:YCA) an uptrend looks promising but I’ll await further confirmation from the ichimoku cloud before diving in. CCI is currently negative. Added to the watchlist. (I don’t hold)
I added a few weeks ago. RNS today:
20 May 2022
Yellow Cake plc ("Yellow Cake" or the "Company")
DELIVERY OF URANIUM
Yellow Cake, a specialist company operating in the uranium sector holding physical uranium for the long term, is pleased to announce that it has taken delivery of 2,022,846 lb of U(3) O(8) from Kazatomprom at the Cameco storage facility in Canada, following the exercise of the Company's Buyback Option.
Market likes it so far.
Angle (LON:AGL)
Not the news I was hoping for but new research to be funded by Prostate Cancer UK specifically using Parsortix.
The study will investigate the use of the Parsortix(®) system to
isolate circulating tumour cells (CTCs) as a predictor of future disease
recurrence. Assessment of whether prostate cancer is likely to progress, if
this can be done reliably, may have a major bearing on whether radical
prostatectomy surgery is the most appropriate treatment choice.
I wish they were coming to Mello, so we could grill them.
Morning, grumpy 5. Which comment and company are you referring to? It always helps! Is thi s Jim McLad and Angle (LON:AGL) or something/someone else? If it is Angle (LON:AGL) and Jim, then I would say that they have already appeared before Mello - see the Mello back catalogue if you are an annual passholder as am I. I would guess, and I think Jim McLad would aagree, that what the senior Angle (LON:AGL) management would nt be able to say very much more than tthey did then; and there have been references to other research studies, corporate actions etc in the meantime - see the Angle (LON:AGL) news history here on Stocko. Unfortunately, we need to wait patiently and trust that the FDA are acting as quickly and as fairly as they can to allow the rest of the world, including the USA medical system, to take advantage what many consider to be the proven superior process which Angle (LON:AGL) provides.
Hello Jim. As usual, I share your frustration. If I remember correctly, Angle (LON:AGL) did do some work with a major London hospital some years ago on prostate. Cant remember which hospital but I believe the result was regarded as positive. Do you have further, more precise, memories?
In the meantime, I think it is another valuable additional and very important, funded research element for Angle (LON:AGL) in the UK - a significant market of high standing in terms of research reputation.
No further details on the size of the scheme, and the length of time before research results are likely to be forthcoming. However, Angle (LON:AGL) senior management have said that their objective is to get approval for the current application, breast cancer, first and then it will be quicker and easier to get approval for subsequent applications. Good to start on that process now, especially if it is funded by someone else.
Ridavies, grumpy5 et al.
Sorry, just noticed I omitted the link to the RCS which gives details of the study and answers a few points.
https://www.stockopedia.com/share-prices/angle-LON:AGL/news/rcs-angle-plc-prostate-cancer-uk-funds-new-study-using-parsortix-urn:newsml:reuters.com:20220520:nRST1779Ma
The CEO has been as open as he can be. If you look at the recording of the prelims of 28 April on the Angle (LON:AGL) website he mapped out the way forward and was questioned by analysts. Doubt you’d get any more at Mello.
From memory the previous UK based work on Prostate cancer was with Barts Cancer Institute (Queen Mary University of London). who are involved in the new trial. As it will be following patients in 'real time' the trial could last a few years though could be shortened if very positive results results are shown early.
Now wrestling with what appears to be a Stocko fault – my portfolios were entirely GREEN this morning. I think they’ll have it fixed soon.
Re Angle (LON:AGL), thanks as ever Jim. From the detailed reference which I have picked up from another source, I found this to be a particularly telling comment from the guy leading the research at Barts (which I remember now was where I believe the original work was done some years ago, Right treatment for individuals, best results for patients, less cost to he NHS, so looking forward to the results - and to the FDA, please give the green light so that more institutions throughout the world can apply this appropriate, life-changing, process to cancer treatment - whether it be breast cancer (which the FDA is now considering specifically) prostate, and other types of cancer where Angle (LON:AGL) and Parsor nd Professor of Molecular Oncology
at Barts Cancer Institute, Queen Mary University of London, commented:
"If our hypothesis is correct, we hope that this blood test will become the
future standard of care for these patients. Patients with localised prostate
cancer will be treated more efficiently and in a more personalised way, rather
than surgically removing the prostate and just waiting to see what happens.
Doctors will have more information about whether the cancer has really spread
or not, based on this test meaning patients won't be over or under-treated."
and Dr Hayley Luxton, Research Impact Manager at Prostate Cancer UK, commented:
"We are delighted to support this trial which has the potential to inform
treatment decisions and improve outcomes for men living with prostate cancer.
Prostate cancer is the most common cancer in men, killing 11,500 people each
year in the UK. Being able to identify aggressive cancer beforehand will help
to ensure that men are receiving the right treatment at the right time."
ONS monthly retail report out shows retail sales up 1.4%, largely driven by an increase in alcohol and tobacco spend in supermarkets. Also an increase of 8.4% in sales at off-licences and tobacconists. Overall retail sales nearly 5% lower than last year.
Unsurprisingly it sounds like people are reacting to cost of living increases by staying home rather than eating and drinking out.
timarr
You’ve got to feel sorry for anyone trying to run a restaurant. Out of the Covid frying pan, into the cost of living fire! Brutal.
I guess it depends on the restaurant and the relative wealth of the local community. The Cote in Tunbridge Wells seems busy much of the time.
I’ve always said that if your going to cater, cater to the rich. Less competition and higher margins.
a good example to this would be the restaurant L’Enclume in Cartmel. Always in the top 3 restaurants in the country and you need to book at least 6 months in advance. It holds approximately 40 seats a night with an average cost per customer between £350 and £400. That is roughly £5m sales a year.
It sounds like central London hasn't gotten the message. Every restaurant I've been to last week and this week has been packed, with almost every table occupied.
It sounds like central London hasn't gotten the message. Every restaurant I've been to last week and this week has been packed, with almost every table occupied.
I'm splitting my time between Surrey and West Cornwall at the moment.
In Surrey the restaurants are packed, the bars are spilling out onto the street, the footfall through shopping areas is significant and all of the supermarkets are busy (although as noted previously, Lidl seems to be enjoying a boom).
In West Cornwall it's dead. The pubs are empty, the restaurants are empty, there's very little footfall in the shopping areas. Lidl is reasonably busy, but not overly so, the other supermarkets are less busy. It was unbelievably quiet at Easter. My friends and relatives down there are restricting their spend on everything, including petrol. No one is going out, it's all pizzas and cheap wine at home.
We need to be careful not to draw too many conclusions about the general state of affairs, especially if we live in affluent areas. As the ONS data shows, cost increases are biting.
timarr
I experienced similar in the Lake District for the May Bank Holiday.
My take is that people dont want to Staycation anymore , they want to go abroad .
Morning timarr,
Are you sure that you're looking at retail sales, and not retail volumes? I don't have time to check myself right now, but I can't see how overall retail sales would be down 5% on last year. That's almost certainly retail volumes. At higher prices, then lower volumes would translate into higher sales. Maybe you could clarify, as I've not looked at the data yet.
Thanks, Paul.
Hi Paul
You're right, I think, I was skimming. If I was correct, given inflation is running at nearly 10%, that would be depression era stuff. This is from the Guardian just now:
Shoppers actually spent 4.5% more in April than a year ago, but ended up with 4.9% less stuff.
On a monthly basis, retail sales values (the amount spend) jumped by 1.9%, but volumes (the quantity shoppers bought) were 1.4% higher.
And over the last quarter, people spent 10% more than a year ago, to get 1% more items.
That widening gap between retail sales values and volumes reflects rising prices in the shops, with inflation now at a 40-year high of 9%.
If people are spending more on less then presumably it's the non-discretionary stuff that's suffering.
timarr
timarr - Brilliant, thanks for clarifying, very helpful quotes too :-)
Bombed out retail shares could turn out to be very good long-term investments in a higher inflationary environment. Sure, they'll take a short term hit to profits, but over time they rebuild margins, and of course rents are fixed, so drop considerably as a % of higher revenues. Hence the better retailers could turn out to be nice investments, with built-in long-term inflation protection.
I think the mid to large cap retailers are looking very interesting right now, if you can look through short term issues. So £NXT , £DNLM B&M European Value Retail SA (LON:BME) and others intrigue me.
On smaller retailers, I'm expecting lots of takeover bids, they're just so cheap now, that private equity is bound to be checking out the numbers.
Regards, Paul.
P.S. Also, remember it's the retail sales (not voumes) that goes into retailers results. So that number is going up, not down, on lower volumes (so less distribution cost). It may not be as bad as investors currently think, medium to longer term anyway. who knows? It's all guesswork!
Of course, one has to find strong retailers where volumes don't decline as much, so that net-net with Price Per Item going up and Items Sold going down, the gross sales revenue growth is still positive.
Supermarkets are the obvious candidate. People will consume a bit less calories, but there's a limit how much less. So we should see increasing gross sales revenue growth over time. However, profit margins are likely to be very squeezed for a while, given the highly competitive nature of the UK grocery industry.
Supermarkets are the obvious candidate. People will consume a bit less calories, but there's a limit how much less. So we should see increasing gross sales revenue growth over time.
Maybe. But as Target and Walmart showed this week, they can't pass on cost inflation if consumers can't or won't pay up. I know it's purely anecdotal but here in leafy Surrey it's very clear that the local Lidl is getting a lot more trade. Against that we can see from the ONS numbers today that people are substituting eating and drinking out by buying from the supermarkets - which presumably is very bad news for all of those mid-market restaurants and bars.
Generally I think this is an error that markets are only just correcting - the idea that all cost increases can be passed on. They can't when people are struggling to heat their homes and put petrol in their cars. Ultimately corporate earnings have to fall, although that will be unevenly spread.
Of course, it's very easy to get wrapped up in the short-term when everything seems gloomy - but it is genuinely difficult to work out what lies ahead because we're in uncharted territory. Quite clearly there will be corporate failures, and preserving capital to fight another day is important. I certainly don't have the skill or knowledge to navigate retail investments in this environment.
timarr
Hence my caveat that it depends on the competitive environment :)
I know several European markets where there are just two or three dominant supermarkets. Those would be the ones to invest in. However, UK, USA, and Germany.... probably not!
Paul, sales in nominal £ would go up, yes, but profits are a different issue. Just taking those ONS figures, assume that all costs and revenues are going up 10%, but volumes are down 5%. Gross profits up, but net profits likely down, possibly turning to losses depending on operating leverage and efficiency savings (sacking people who are then less able to do their own spending). And that's assuming that they can maintain margins while the market is shrinking in real terms - a tough challenge.
Meanwhile, the market's initial reaction to today's figures has been that they don't demonstrate enough demand destruction (even with this component of GDP falling by 5%), implying that we need to raise rates to shrink GDP even further to match demand with our reduced level of potential output. I always admire your optimism Paul, but I suspect you might need to draw on more of it in the year ahead!
Hi cmpeckham
I always admire your optimism Paul, but I suspect you might need to draw on more of it in the year ahead!
That's not at all consistent with what I'm saying! Just to clarify, I'm not at all optimistic about the short term, you'd have to be mad to be optimistic about earnings given all the macro headwinds right now!
There's no doubt that short term profits are likely to be hit, we all know that.
I was referring to the medium & longer term, where decent retailers tend to do well, because the shares have in-built long-term inflation protection, if they can raise prices, which everyone has to, otherwise they would go out of business.
The other question is how much of this is already priced into share prices? Take the eCommerce sector, where prices for many, even large, eCommerce companies are down 80% or even more. True, they may have been over-priced to begin with, but there does come a point where all the negatives are in the price, and we could see some powerful rebounds possibly.
As an aside, I wonder if charting could be more useful right now, to help see changes in investor sentiment? Trouble is, the rebounds are generally not sticking, so the risk of buying breakouts, is that you could be buying a spike that other people then sell into.
All fascinating stuff, which is why I find markets so stimulating, even in the bear markets. You just never know what's going to happen next!
Regards, Paul.
As an aside, I wonder if charting could be more useful right now, to help see changes in investor sentiment? Trouble is, the rebounds are generally not sticking, so the risk of buying breakouts, is that you could be buying a spike that other people then sell into.
I read an interesting article on investing.com that stated that buying the dip still works but you must be prepared to take profits on short term rises. Charting sentiment (plus getting tips on SCVR) is working reasonably well for me recently. Although it does feel like trying to run up the down escalator!
Either you are trading over days/weeks or taking a very long view. IMO the mistake is to get caught between the 2.
Also known as scalping :-)
OK, but your comment about lower sales volumes can't have been about the medium or long term - that would be an unprecedented economic disaster!
As you say, "there does come a point where all the negatives are in the price", but the biggest negative usually becomes risk aversion - and that typically doesn't change until central banks target expansion rather than contraction. There's a good reason for that too - when they are all moving interest rates in the same direction, it creates a powerful force:
I don't think we're at the end of the current tightening cycle yet. Indeed, the Fed seem likely to raise rates several time yet. That will then pull other CBs along with them. As per the chart above, that would suggest a weak global economy over the next year. Things can change quickly but I don't think we're at the turning point yet.
Thanks Chris, interesting points, makes a lot of sense.
Interestingly ' Ms Bovill said: "Clothing sales had a strong month especially online, with some retailers suggesting consumers were purchasing clothes for summer holidays and weddings." from here https://www.bbc.co.uk/news/bus...
Yes it was retail volumes down 4.9%. Unfortunately, shoppers had to spend 4.5% more in total for that decreased amount of goods.
Morning big P... Could i please ask...How does one 'check the futures'... I would like to see what you see please. Is it a ticker I use?
They are shown on Reuters…
https://www.reuters.com/market...
Just scroll down to futures section
Try https://uk.investing.com/indic...
try dailyfx. Has futures, commodities and currencies under the rates drop down
Bloomberg app shows the Futures pricing for indexes (FTSE, S&P500, Nasdaq, etc). Think it will show for even Free users.
M&C Saatchi M&C Saatchi (LON:SAA) the saga continues as Next Fifteen Next Fifteen Communications (LON:NFC) enters the race.
That sounds interesting.
What's the relevance of a scheme of arrangement? It sounds like they're aggressively reacting but I don't really know.