Small Cap Value Report (Fri 20 Oct 2017) - REC, ESG, BOOT

Good morning!
Graham here.
It's been suggested that we insert a standard disclaimer/information notice for new readers, so here goes:
Please note that these reports are just our opinions, and do not constitute investment advice.
We are particularly open to suggestions to cover stocks with market cap of less than £500 million. We cover a range of industries but tend not to cover oil, mining or other natural resources, REITs, investment vehicles, and the like.
Best wishes,
Graham
Record (LON:REC)
- Share price: 45p (-5%)
- No. of shares: 199.1 million
- Market cap: £90 million
This is a currency asset manager which I last covered in April.
AUME (assets under management equivalent) started the year at $56.6 billion, and are now at $61.2 billion, after another quarterly increase.
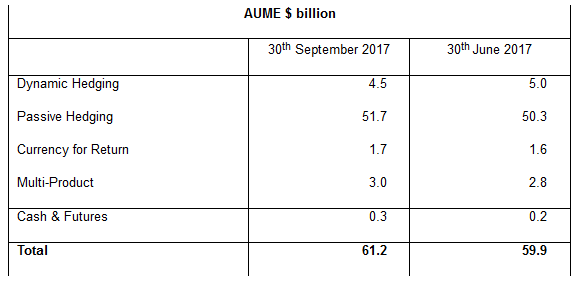
As you can see, the vast majority of the AUM is in hedging products. This is either a cheap passive hedge or in a momentum-oriented "dynamic" hedge which tries to maximise the client's exposure to currencies which are strengthening.
Despite the increased size of the business, the flows were disappointing. There was a net withdrawal by clients of $1 billion, offset by market/exchange rate gains of $2.2 billion.
This is noteworthy:
For UK-based clients, Dynamic Hedging achieved cost-effective protection of currency gains from sterling's depreciation in the six months following the EU referendum. However, persistent weakness in sterling meant negative returns and cash flows were unavoidable. As a result Record's remaining UK-based Dynamic Hedging clients converted their mandates to Passive Hedging or terminated during the period.
If I understand that correctly, it sounds like Sterling holders eventually capitulated in terms of trying to use the more sophisticated Dynamic Hedging product, and instead simply sold out the rest of their Sterling holdings - either with Record's Passive Hedging, or with somebody else.
Taking a glance at the chart against the Euro, August was a particularly difficult month for Sterling, and Sterling sellers finally capitulated around then:
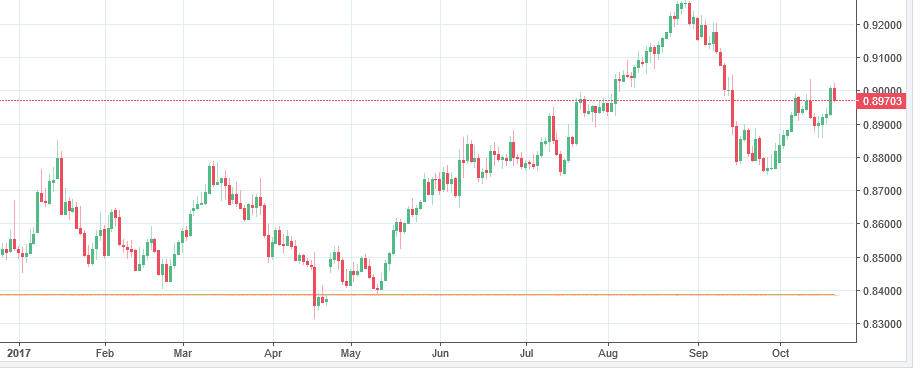
It's a bit disappointing that Record's Dynamic Hedging didn't prove its worth to clients over this period. But I suppose we are talking about a timeframe when there was no benefit to be gained by waiting to hedge, so there wasn't much of an opportunity to be clever and try to time things.
Summing up the weak performance, for both UK and US clients, no performance fees were earned.
So it's a really mixed bag of an announcement. AUM reaches its highest ever level but performance was poor, clients withdrew funds, and there is an additional threat posed by increased regulation.
Outlook is summarised as follows, not giving too much away:
"The theme of volatility in currency markets linked to political and economic uncertainty continues, and the consequent uncertainty provides opportunities for engagement with both existing and potential clients. We remain confident of making further progress in the second half of the financial year."
My opinion
I still think this share is worth a look.
It's undeniably niche, providing a specialist service which banks are lazy about.
It is extremely well-capitalised, as it needs to be.
It treats shareholders well, paying out dividends as it can reasonably afford to (and the yield is currently about 6%).
The main negative is that it has fewer than 60 clients, and predicting mandate wins and losses is difficult.
And conditions have been difficult for it to generate good performance lately.
Overall, though, I might buy a few shares in this.
Eservglobal (LON:ESG)
- Share price: 11.625p (+12%)
- No. of shares: 640 million
- Market cap: £74 million
This mobile transactions company announces details of a £24 million fundraising from an institutional offer, a firm placing and a retail offer, all at 9p per share.
It has a cross-border payments joint venture with Mastercard and BICS, called HomeSend, in which it has a 35% share. This joint venture needs additional capital, and Eservglobal (LON:ESG) is raising this money today partly on its behalf:
The net proceeds from the Fundraising will be used in part to fund an expected capital raise by the HomeSend JV to fund its short-term cash requirements and provide further capital for future cash calls, therefore enabling the Company to maintain its 35 per cent. ownership in the HomeSend JV.
And there are internal purposes too:
The proceeds will also be used to further support the rationalisation exercise within the core business, pay down all the Company's debt to strengthen the balance sheet and for general working capital purposes.
Checking the H1 report, I see that overall group revenues in the first-half were just €4.1 million, down on the previous year. The company talked about earning €15-19 million over the 14 months to December 2017, an awkward choice of period. "Timing challenges" in relation to two contracts were blamed for the fall-off in revenue.
The company describes its achievements as follows:
eServGlobal has been a source of innovative solutions for mobile and financial service providers for over 30 years.
Despite this, the core business doesn't seem to have achieved lasting success, judging by its declining sales and losses. EBITDA breakeven is the target for this part of the business in Q4.
HomeSend is the exciting part, where Eservglobal (LON:ESG) has been able to participate along with Mastercard because of the role played by its technology.
In June, it said it was "on the point of significant sales expansion within HomeSend".
The addressable market is considered to be huge, covering a vast array of international remittances by individuals. It looks like HomeSend wants to go head to head with Western Union.
For now, this is still early-stage. It sounds a lot more promising than the typical early-stage opportunity which comes in front of me, so perhaps it's worth a look.
But for me personally, I don't have any interest in investing here.
Fintech strikes me as an investment bubble which has been inflated by the very strong bull market of recent years. I don't want to buy into anything which is associated with that sector, where I might be investing alongside some of that really speculative money.
So for that reason, and perhaps unfairly, I'm not motivated to research this particular stock in any further detail. I'd rather spend time analysing stocks in sectors where there is no bubble and no speculative money, because I think my probability of getting a decent result is automatically improved by that decision.
Henry Boot (LON:BOOT)
- Share price: 330p (+7%)
- No. of shares:
- Market cap:
This is an old name in property development, based in Sheffield.
Results are set to be materially ahead:
...trading has continued to be very strong across all our business segments, in particular, within property development and land promotion. Therefore, given the accelerated completion of transactions in September and October 2017, and the successful delivery of major development schemes through the second half of the year, we anticipate that the Group's performance for the year ending 31 December 2017 will be materially ahead of the Board's existing expectations.
"Almost every deal" the company was hoping to complete, has indeed completed.
And a whole range of deals completed faster than anticipated.
We normally see the opposite problem, that customers are slow and that sales get delayed (see the "timing challenges" for the previous stock).
Since companies who suffer delays often expect some kind of catch-up in the subsequent period, I guess the opposite might be true in this case - there will be fewer deals available to complete in 2018, since they have already completed in 2017.
But the company explicitly tells us that this is not the case:
We continue to backfill the opportunity pipeline and work on deals for 2018, thereby replacing the deals that have been executed earlier than expected, and there remains a possibility that some of these may conclude before the current financial year end. With this in mind, together with the wider UK economic backdrop, the Group's expectations for 2018 remain unchanged.
Wow! An unanticipated increase in deal speed, combined with the maintenance of the work pipeline. Doesn't get much better than that.
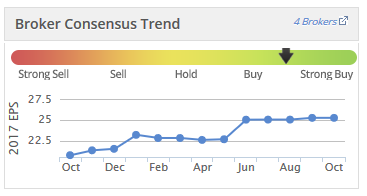
The NAV was 184p at June and so we can look forward to this getting a healthy uplift, perhaps in the region of 194p-196p by year-end? And that's after the payment of dividends (the yield is c. 2.6%).
The earnings momentum is illustrated by Stockopedia as follows:
As I said last time I covered this, my main question is around the valuation. I think this is trading at around a 65%-70% premium to NAV.
While it's fairly clear that the company has executed its plans extremely well, that premium seems more than generous, especially given how the property markets work.
As I've said before - property companies often look the cheapest when they are most expensive, and the most expensive when they are cheapest (relative to earnings and investor sentiment).
When I've bought property developers and REITs in the past, I've done so on the basis of the NAV discount, when it looked bigger than average, and methodically sold them when the discount disappeared or the premium was bigger than appeared to be justified.
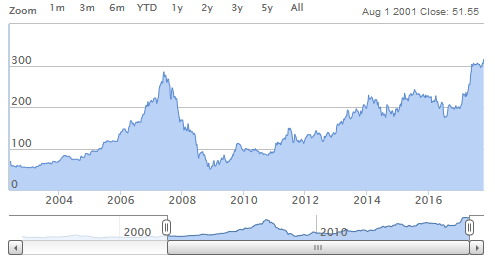
For example, Henry Boot (LON:BOOT) had a NAV of 129p - 138p from 2009 to 2012, when the share price was in a range of 60p - 130p.
As you can see, the discount/premium to NAV is a lot more volatile than the NAV itself!
I'll keep this on the watchlist, but won't be buying it at these levels.
That's all for now. Of the three companies mentioned, I don't have any positions, although I like Record (LON:REC) the best at current valuations!
Thank you for the comments and suggestions.
Best wishes
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

51 comments
What impact will Mifid II (EU Financial Regulation) have on Stockopedia?
IQE (LON:IQE) was left on watch list and I bought back in teens and when in thirties made a decision to sell out (I think I got 41p for last tranche). Clearly "foolish" and could have held to 150p. Why are there some many shorters today?
With regard to people short of IQE (LON:IQE) - perhaps they understand the semiconductor industry better than those that are long? I believe some people even believe the technology industry is non-cyclical such is the length of the bull run since the boom caused by smart mobile devices started 10 years ago, and that the only way is up. This is wrong, the semiconductor industry has a long history of being cyclical, it's just that it's been so long since any kind of downturn that most people have forgotten.
I get a pretty good indication of how the semiconductor industry is going in my day job (although not specifically the compound semiconductors that IQE (LON:IQE) produce) and there is certainly no sign of it letting up yet, but at the same time I'm highly sceptical of some of the claims being made about future applications for IQE products.
Yes, it's easy to see the kind of technologies that will happen in future but the timing of when they will gain mass acceptance has proven extremely difficult in the past and as an investor the timing of revenue from these technologies is extremely important. It is certainly not the sure thing that I have read from comments I have read on here. Everyone saw smartphones coming but it was several years, and much later than anyone predicted, before they reached the kind of volumes that justified the money thrown at developing the technologies. I believe the same will prove to be true about the future technologies gaining lots of attention now e.g. driverless cars.
I've worked in the technology industry all my working life and if there's only one thing I've learnt, it's that it does hype and bullshit very well, and as an investor you really have to cut through that and concentrate on realities.
All the best, Si
what is your go rank seadoc?
nick,
I have no idea. I think the last time I played with better players was Cambridge in early 70s. On a 9x9 with Igowin I have to give the 'puter a couple of stones. What is your rank and what do you give Igowin?
seadoc
I learnt in early 70's at uni. Now I play on kgs web site (the best and most used). Handicap is 3 kyu Are you a doctor?.
Nick
Nick,
Yes, surgeon, but well retired.
Seadoc
Any chance of a comment re POS? Recent announcement seems to be a game changer.
Good day Graham, Paul
A general point:
An interesting comment was made the other day that companies that were releasing results that were even "in line" with market expectations were seeing their share price being marked down. It seems that the market is becoming harder to please with results and that unless results are ahead of market expectations then a mark down can not be ruled out. This seems to particularly be the case with the higher growth companies, companies which have seen their share price motor ahead over the last year or so.
So many companies now seem to be over valued that I believe we have to be extra careful when stock picking. We have been in a bull market for so long that many will not have experienced a market correction nevermind a bear market and are unaccustomed to what goes up inevitably will come down (to some degree) over time.
In two instances recently I have seen a high percentage of my profit wiped out by what may be regarded as over optimism (on my behalf) based on the latest trading update. Obviously the market was unimpressed and was looking for more. Likely the share price was already factoring in the news. There can be a belief that despite the share price movement South all is well and at any moment the trend will reverse. Many may be tempted to "average down" and pump more funds into a share. We need to keep our feet on the ground and be realistic and not get carried away with the hype and hope over any company, being careful of confirmation bias where we are looking for others to confirm what we believe or want to believe.
When good news fails to raise the share price and the slightest hint of disappointment hits it, is it not perhaps the first sign that the market is topping out?. One difference at the present time is that we have been in a very prolonged period of historically low interest rates. This may be one reason why the market is holding up. Indeed, even if interest rates were to double, the amount of interest on any modest sum invested in an interest bearing account is still small and would possibly be seen only as a defensive move to move capital.
There may still be some positive movement in the markets to come but I believe it may be limited. Time to pause perhaps before pushing that buy button.
Just my thoughts, open to different opinions.
Regards
CM
Thanks Graham
I do hold Record REC and will continue. It is in both my Winter and Summer NAP portfolios.
I am inclined to agree with the sceptical comments on Octagonal (LON:OCT), although to be honest it's not one that I've studied before.
We typically have a lower limit of £10 million for market capitalisation and while Octagonal (LON:OCT) has a market cap of £20 million, its major shareholder owns over 50% of it. So the free float is still less than £10 million. Besides the small size of the free float making it impractical for too many of us to invest in it, there are also the well-documented risks of buying into small companies which have a large dominant shareholder.
I wonder if Record (LON:REC) may be losing business to Alpha FX (LON:AFX) - they said they floated specifically to raise regulatory capital be able to grow their business.
Yes John, I also wondered whether Alpha FX could be taking business from Record as well as taking business from banks. Graham mentions that the main negative with Record is that it has less than 60 clients and I note from the Alpha FX web site that it has 341 clients so it certainly looks the preferred holding from this viewpoint.
Dear Graham and Paul
I own loads of stuff and would like you to tell me whether it is any good or not. Most of all I would like you to do it now, and do it for free.
Is that OK? (He said, disappearing in a massive cloud of sarcasm).
Re. Octagonal (LON:OCT) agree with rhomboid. I bought some last year but soon sold out after looking deeper into the company's operations and management. Tom Winnifrith had a run-in / spat with John Gunn the CEO. The x-holdings and x-investments between various subsidiaries together with John Gunn holding majority shares made me very nervous. To me, protecting your capital is the number one priority. On that basis I will continue to stay away from OCT. Shame because underneath it all, there may well be a decent and profitable business.
It is regulated by the FCA, but as we know, that is as much comfort as a fig leaf in the rain. The FCA is like the cavalry arriving the day after the massacre has already taken place.
Well said, Ramridge (and Rhomboid1).
(I have no position in Octagonal (LON:OCT).)
Regards,
Ed
Morning Graham
I have a number of holds that I would be interested in your Opinion some of already been mentioned
IQE
Boohoo
such high recommendations large buys price still below £2
PTSG
was doing ok now going backwards
Destiny Pharma
my big mistake any comment ? on that one
Thanks
As some have pointed out here, if a company hasn't reported news Graham+Paul wont comment on it. While I can't speak for them, I believe they are probably too busy dealing with current news to answer untimely requests.
To see how they felt about the latest news released by your companies, go to the top right of the page, type the relevant tickers into the search box and read through the archives. They really are a wonderful resource and go back years in some cases.
I'd also advise you get comfortable making your own decisions. I use the opinions of Graham and Paul to inform, not form, my views on companies. I've often disagreed with them! Sometimes to my benefit, sometimes not. No one gets it right every time and building your own investment approach is the best way to have long-term success.
Best,
Portsmouth Pirate.
EDIT: I just realised the search box doesn't appear on this page, but this one:
https://www.stockopedia.com/co...
I hope that helps.
Thanks Portsmouth pirate.
But I was not asking for advise just stating a few names to see his opinion, Have been trading for 30 years very successfully, can't see what all fuss was about, others asked his opinion, he invited people to ask so I did too.
I always make my own decisions.
The above stocks were of particular interest among many others.
Got into IQE at 30P and Boohoo at 40p
Thanks for your kind attention
Hi lolarose,
We usually stick to names where news has been released on that same day, except when it's a slow news day or other exceptional circumstances. As daveinthelakes suggested, we might put this in our standard disclaimer.
Kind regards
Graham
Hi Graham
Henry Boot (BOOT) has issued a very positive 2017 trading statement. Any thoughts. Sorry posted on wrong Newsletter meant for 20th
Hi, I've covered Henry Boot (LON:BOOT). Good suggestion!
Thanks,
Graham
My morning smallcap tweet:
IQE (LON:IQE), Thalassa Holdings (LON:THAL), Elektron Technology (LON:EKT), Eservglobal (LON:ESG), DX (Group) (LON:DX.)
IQE (IQE) Big tax screw up on US subsidiary. Has paid the estimated £4.2m + £0.4m interest for the years ending 2013, 2014, 2015 and 2016. It is believed that no similar tax liability arises in 2017. IQE "will be pursuing full recompense as a matter of priority with the previous advisors." Surely the tax would have been payable if they'd had correct advice, so only the interest can be claimed? Though maybe they'd have structured the subsidiary differently and reduced tax.
Trading: Q3 strong with "ongoing strong VCSEL ramp in support of a highly significant mass market consumer application". So they hint at the iPhone demand for the first time, so they could have some good news to offset the tax ballsup. Despite the tax payment, guides net debt in-line. I hold.
Thalassa Holdings (THAL) resumes buy-back.
Elektron Technology (EKT) sells subsidiary, Sheen Instruments for £1.2m. "The disposal will be dilutive of earnings initially but the Board expects to improve the performance of the remaining businesses." So it's dilutive full stop.
eServGlobal (ESG) £24m fundraise at 9p, a 10% discount. Includes £3.4m offered to retail holders. "Will be used in part to fund an expected capital raise by the HomeSend JV to fund its short-term cash requirements and provide further capital for future cash calls."
DX Group (DX.) FY nil profit. Exceptional (non-recurring) items of £80.7m, mainly goodwill. Also property dilapidation provisions - why is that a 'one off'? £24m funding from convertibles. New board. Trading: "As might be expected, trading in the new financial year has been affected by the challenges in the business." But " Firm foundations are in place for the Group's turnaround". Super.
Graham,
With regard to the disclaimer you may wish to add words to the effect that priority will be given where there has been a results release or other major RNS announcement today/yesterday and that for any others a reasoned basis for consideration must be provided.
Dave
Hi Graham, a look at CNKS would be appreciated!
Thanks
Has Cenkos Securities (LON:CNKS) put out any news today?
(For anyone interested there was news yesterday of a proposed and refused merger of Property Franchise (LON:TPFG) and Belvoir Lettings (LON:BLV) . Is this a marker of consolidation coming in amongst the estate agents? Perhaps this is a sign of hard times to come on the property sector.)
They announced appointment of a new NED and there was a disclosure about an exempt principal trader without recognised intermediary. I've not idea what the latter is about but I'm trying to understand why it's slipped about 8pc this week
It went ex-div on the 12th (4.5p) 7% and the spread is 2%, so an 8% fall is pretty good really! Congrats, you've picked a winner!
Hadn't spotted the Property Franchise (LON:TPFG) and Belvoir Lettings (LON:BLV) exchange. The combination certainly makes a lot of sense. The list of principal objections put forward by TPFG suggests that they aren't averse to a deal but don't like the deal as currently structured. Specifically, they want 1) a premium 2) more shares/less cash with less resulting leverage and 3) more management/board representation. These look solvable if BLV is willing to compromise.
If BLV is successful could be good news for Mortgage Advice Bureau (MAB1). Belvoir bought Brook, a MAB affiliate, a couple of months ago to develop their financial services income as an offset to potential loss of tenant fees. Assuming TPFG isn't already a MAB affiliate, you would be talking about a combined group with nearly 700 outlets but less than 32 advisers (as of a couple of months ago).
Totally agree, old chap. There are possible synergies here, but Property Franchise (LON:TPFG) are rightly seeing themselves as being short changed. I think the egos may prevent any merger happening though. It will be interesting to see if this is the beginning of a trend.
Also second shout for Octagonal (LON:OCT). 17.5% increase in revenue leading to a 40% increase in bottom line. Also, net margins have risen from 40% to 47.5%. If this increase in revenue is sustainable, and on a PE of only 16 it looks like a lovely opportunity with risk/reward skewed to the upside. Nice Minervini isetup on the charts too. My main question would be, what is their moat, and is this increase in revenue/profitability sustainable?
Octagonal (LON:OCT) doesn't meet Minervini's Trend Template. For a start, the 150 MA is below the 200 MA.
I'm guessing that's the least of the problems with Octagonal (LON:OCT), Ricky.
Hi Graham,
Octagonal has put out a good looking trading update today, any chance of a review?
Rgds
I'd second Record. Looks to have dropped this am. I read FUM is up. Can't recall anymore. Think this has been reviewed in SCVR. Before.
Octagonal (LON:OCT) please? Ian
Re Octagonal (LON:OCT) it’s connection to David Lenigas makes it uninvesteable for me , John Gunn who holds over 50% and is Chair and CEO has other interests that are all interlinked, same auditor Welbeck Associates , common directors etc NED approves boat load of options to other directors, a few days later he gets options as well,Looks cheap though, hope it does well for you
Hi Rhomboid
Could you explain why connection to DL is a red flag? I personally avoid resources, oils and the like now but am interested in the why in this case? His quoted vehicle has done well recently though Stockopedia classifies Doriemus (OFEX:DOR) as Momentum Trap and gives it a rank of 11.
I certainly have better places to put my money!!
I’m not alleging any misbehaviour & would love to explain more but don’t wish to be venturing into legally problematic areas
A few points in this article might help clarify
http://www.thisismoney.co.uk/money/markets/article-3042471/CITY-FOCUS-David-Lenigas-money-mouth-is.html
Or the Shareprophets archives might help
Thank you rhomboid1. Understood.
An interesting announcement from IQE (LON:IQE) this morning, although maybe not enough to necessarily warrant Graham's coverage, Settlement of prior year taxes
It seems to be in three parts:
* A subsidiary we purchased has screwed up its USA taxes, so we have to cough up a load of dollars
* But it was not our fault, it was our tax advisers, so we might seek compensation from them
* But because of the strong VCSEL ramp up, we will still meet expectations
Given the bull market is so unforgiving about slip-ups I expected a larger drop in the share price, but I'm in this for the long haul so not worried.
Disclosure: long
Lion Tamer,
IQE (LON:IQE) Probably at £900m (for now) a bit big for Graham but I saw that RNS. If you are on a p/e of 50 then £4.2m is a couple of hundred million so may bring valuation down to the right range soon. I also looked up on the FCA website:
https://www.fca.org.uk/static/documents/short-positions-daily-update.xls
and now (well probably a couple of days ago) shorts at 6.81%
.
And I guess the fed will just accept such an error and would not make a punitive fine?
I am learning a bit about spread betting and my first bet was to go short at 10p a point which I think is £10 every penny the sp moves.
Regards,
Seadoc
EDIT. I know Paul was long IQE (LON:IQE) , he might have a comment on that basis.
Seadoc,
Just to point out that IQE (LON:IQE) may be on a trailing PE of 50, but the forecast PE is 36 and it is easy to envisage profits (although perhaps not cashflow due to investment in capacity) doubling again the following year giving a PE of 18. It is being valued on future forecasts, hopes and dreams which makes it highly risky as both a long and a short.
Also, the £4.2m accrued over several years and has been stated not to affect the current year so implicitly not future years. Although I'm sure you weren't being entirely serious, that means the hit on valuation would logically be £4.2m plus some amount for possible similar screw-ups / general incompetence, not £4.2m x PE.
However I suspect today's price movements will be more about reports of poor iPhone 8 sales and speculation about whether that foretells higher or lower iPhone X sales.
Hi,
Yes I hold IQE (LON:IQE) - it's my largest long position.
The announcement today re underpaid US tax is irritating, but not material - only £4.2m. This seems to have been paid, yet net debt is in line with expectations - which suggests to me that cashflow would have been running ahead of expectations, if this tax issue had not arisen. It seems to be a cock-up by their tax advisers, and sounds like IQE might sue them for damages, to recoup the losses.
More importantly, there's a reassuring trading update;
The VCSEL ramp up in production is believed to be related to the iPhone X, 3D sensors.
However, what the market doesn't seem to have fully appreciated yet, is that IQE has multiple, major new product lines in development & for launch in 2018-2020. Therefore, we should see a dramatic increase in revenues & profits over the next 2 years. This is not yet factored into broker forecasts, which look far too low.
Indeed, Peel Hunt reckon that EPS could rise from c.3p currently to 12-15p over the next 2-3 years. If that happens, then clearly the share price would probably multibag again, from the current level.
IQE claims to be the world leader in semiconductor wafers, with 80% of global outsourced production. These products are getting more & more complex, so there's a tremendous opportunity in the years ahead for IQE.
I suspect it would also be a takeover target.
So IQE might look expensive on the historic numbers, but it could end up looking cheap once the new products really start to flow through. It's gearing up for much larger output, with increased capex. Hence free cashflow looks poor right now. I'm looking beyond that, which is where the excitement lies.
So whilst an irritant, the tax issues announced today are really just background noise, and irrelevant to the big picture.
Regards, Paul.
Hi Seadoc.
(Pedantic) point on the putative impact on the IQE (LON:IQE) valuation of the £4.2m fine. Given it's hopefully a one off, one time hit for this year only presumably the notional impact shouldn't be multiplied by the p/e but rather be taken as a simple deduction from the market cap? If it were expected to recur every year - say being hit for an annual royalty payment to a third party - you could make a case for a p/e multiplier effect you describe.
Gus.
Hi Seadoc
IQE (LON:IQE)
Thanks for your reply. I rate your opinion here so take notice of what you say.
I think IQE (LON:IQE) is an interesting bit of sport in the (rapidly growing) fun section of my otherwise boring & predictable portfolio of mainly safe dividend payers. However I've just calculated my stake and its only about 0.6% of my portfolio, so I'm long, but not as strongly long as say, Paul. I believe it may be a share that comes good in the mid to long term. I expect to have fun following it's progress.
The shorts positions listed in the link you provided are a warning and a manifestation of the fact some are bearish on this. I'm currently taking the view that those bears can (or at least believe they can) predict the short term future, but as I can't I'll play the longer term game. I suspect the longer term future is okay for IQE, for the reasons given in the replies by leoleo73, Paul and Gus1065, so will not repeat their comments here.
All the best in the markets!
Lion Tamer,
Thank you for kind comment. I do agree with most posters (but who that Paul chap?) that the long term future of IQE (LON:IQE) is rosy. I think I have already said that I bought in teens and sold (too soon) in thirties. I will come back to that later. But as catstycam points out the market as a whole is looking more than a bit toppy. I have moved about 1/3 of my money into really boring things like REITs and property bonds maturing 2020. Most of that money came from cyclicals. Each month (well actually every 4 weeks) I go through the portfolios share by share and sell anything that I would not have on a watch list. The last couple of culls have been difficult, I had reservations about both Tristel (LON:TSTL) and Treatt (LON:TET) held but might have been better off selling. It was some comments by Paul that had me look at Spread-ex. I spent a bit of time looking at indices and FTSE100 shares. It is clear that machines do better than humans so caveat emptor.
As an aside I followed alphago move by move and the new "zero" version is worth a google. In summary the old version was given thousands of human games to study and beat humans, eventually the world champion. The new version needs an order of magnitude less grunt in terms of processing and was simply given the rules and allowed to play with itself (!). Within 40 days it was put against old version and won all 100 games. I also used to play a lot of chess and was interested to see that on youtube are many classic games that are played move by move and the comments are often what the "engine" would do and how that would have saved a grandmaster from defeat. It seems there is also a huge problem with cheating at the highest professional level and even an iPhone has enough computing power to beat a professional chess player. To come back to investing, almost all trades are now made by machines and I have no reason not to believe that the AI used is as good or better. So it is clear to me that day-trading is a mugs' qame, indeed investment on anything less than 6 month horizon is probably going to fail. On that basis, and out of curiosity, I have five hundred pounds in a spread bet account. It took much longer to crack Go than chess so I looked for smaller, much talked about shares with the longest expiry dates (June) and ended up shorting IQE (LON:IQE) and Purplebricks (LON:PURP) and one is doing better than the other!
To return to IQE (LON:IQE) my problem is not with the technology, simply with the BoD. When the Singapore plant was financed with a cash call, from memory 2005, there was a fantastic future reported in a weekend FT along lines of the production line running 24/7 and increased sales would go straight to bottom line. The share went up 4-5 fold but there was then a profit warning due to "de-stocking" I got out with 100% residual profit but share then fell to pennies (?3p). IQE (LON:IQE) was left on watch list and I bought back in teens and when in thirties made a decision to sell out (I think I got 41p for last tranche). Clearly "foolish" and could have held to 150p. Why are there some many shorters today? My guess is that there are professionals who had the same experience. They may also see the BoD granting themselves huge options and working the share price. The debacle of "forgotten tax" may be the tip of iceberg. And gus is right, the loss could be put against market cap and my indirect application via a high p/e was probably disingenuous. However the ROCE grew from single figures to peak in yr to 2015 but looks like it headed back to single figures. If you compare eps with cash flow per share there is a huge hole, part was that the published "adjusted" figures were what they would have got had they not taken an option to sell at a loss to the chip manufacturer in lieu of the cash they did not have. OK the perceived view was that IQE were better at running the plant which is why the RFD plant was "given" away.
Finally I did some traded options in 90's and it became clear to me that the only way to make money is to have a target and stick to it. So where will sp of IQE (LON:IQE) go? I think it could drop to 60p but will close my position at 80p. On the up-side I will close my position if the 200x is still climbing and both the 20x and 50x cross it. I can, and will, add more margin but looking at charts today, on that plan my loss would be up to £1000.
Sorry probably over-thinking this and totally wasted effort on my part given that I have less than 0.1% of funds invested in the shorts. But so is playing chess, go and doing the daily Sudoku and I do all three of those.
Regards and atb to you too,
Seadoc
Hi Seadoc
Thanks for the thoughtful in insightful reply. I agree with your monthly review (mine is more like every six to eight weeks). My process starts with an export of portfolio data into a spreadsheet, and ends with a review of news and any scuttlebutt. Whilst the process has saved me from some upsets in the past, it also took me out of Greggs (LON:GRG) in August 2014, something I remind myself each time I consider a sale. As a result I tend to have a higher bar than many before selling, and trade very much less often than I suspect most do. Most of the time it works for me, eventually.
Unlike you, I'd not consider spread bets, least not until I change my mind. I'd certainly not entertain the thought of day trading. I was at an investor show some years ago and the topic of autonomous trading machines was discussed briefly in one of the sessions, at about the time when they were first becoming mainstream. I learned that as you say, the machines have the upper hand (can you say "hand" when discussing a machine?)
As an aside, did you see this?
Anyway with the gradually rising level of AI proficiency the machines are becoming harder for private investors to beat. Therefore my strategy is formed starting with the premise that I'm playing the "loser's game". This may seem at odds with my holding in IQE (LON:IQE), but part of my disciplined approach for my main holdings is to be allowed to play with some more exciting holdings on the fringe of my portfolio. Of course, I still want to win on these more speculative holdings, the point is I can afford to be a lot more reckless, scratch that itch, and still sleep at night. Sounds similar to your reasons for your spread betting account.
Thanks for the insights about the IQE (LON:IQE) BoD and for the history lesson. I've noted this on the scuttlebutt jotter I'll use for my next regular review, it might inform a different decision about if I continue to hold or not.
All the best
Edit: changed the link to the "loser's game" to a more fitting source.
Also the statement that my strategy is formed on the basis I'm playing the "loser's game" should be be taken to imply I only invest in trackers, as this is very far from the case.
Good morning Graham
Would you be able to look at Record (REC).
Hi marcus, I've covered it.
Regards,
Graham
A large placing and open offer announced at Eservglobal (LON:ESG). Is the ship finally starting to turn around, or is it a sinking ship? I was once invested here and gave up on it as the share price only ever seemed to go down! It seems like it has never been commented on here despite being in the SCVR universe...
Hi grb, good point that it's never been covered here! I've taken a brief look.
Best,
Graham
( Eservglobal (LON:ESG) )