Small Cap Value Report (Fri 20 Oct 2023) - G4M, BOWL, SED, IQG, PROC

Good morning from Paul!
Today's report is now finished. Thanks for all your interesting comments this week, and I'll record this week's podcast tomorrow morning. Have a relaxing weekend, we need it!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Quiet today, so I'm catching up on backlog items -
Summaries
Gear4music (HOLDINGS) (LON:G4M) - down 7% to 125p (£26m) - H1 Trading Update - Paul - AMBER
Confirms trading in line with FY 3/2024 expectations (a modest £1.2m PBT). But cost cutting in H1 should boost H2 and next year's profit maybe? I like the strategy, but question whether low margin eCommerce companies that have largely gone ex-growth will ever command premium valuations again? There might be some upside here maybe?
Hollywood Bowl (LON:BOWL) - up 3% to 241p y’day (£413m) - Trading Update FY 9/2023 - Paul - GREEN
Is it ahead of expectations or in line? Fudged wording has left me unsure. PER of 12x, >5% dividend yield, and self-funding growth, with pots of cash in the bank - a very attractive investment proposition I'd say. So another thumbs up from me.
Saietta (LON:SED) - down 29% to 27p (£28m) - FY 3/2023 Results & Resumption of trading - Paul - RED
Just awful. Shares have come back from suspension, due to late FY 3/2023 accounts. Material uncertainty red flag in going concern statement. Probably out of cash, or close to it by now. Could easily be a zero. I've deployed my bargepole, and borrowed another one from a friend, just to be sure!
IQGeo (LON:IQG) - 255p (£157m) - Call with management - Paul - AMBER
See my notes below from a call with management yesterday. They wanted to talk me through my balance sheet concerns, which I'm pleased to say seem OK. This looks a very interesting rapid growth company. I would be green, were it not for the rather high valuation. Well worth people taking a look at IQG, if you are prepared to pay up for exceptional growth. Now profitable and cash generative too.
PROCOOK (LON:PROC) - down 13% to 18.7p (£21m) - Q2 Trading Update - Paul - RED
Shops and eCommerce seller of kitchen goods. Q2 saw a continuing fall in sales, although slightly better than Q1. Looks on track to make another loss this year, I reckon. Tiny free float - delisting risk? Why get involved, when there's no sign of a trading recovery yet?
Paul's Section:
Gear4music (HOLDINGS) (LON:G4M)
Down 7% to 125p (£26m) - H1 Trading Update - Paul - AMBER
Gear4music (Holdings) plc ("Gear4music" or "the Group"), the largest UK based online retailer of musical instruments and music equipment, today announces a trading update for the six months to 30 September 2023.
H1 (quieter half) revenues down 6% - not a problem, as the stated strategy is now to focus on profitability, not sales growth.
“Challenging market”
Net debt £18.1m, down £3.7m on a year ago, but up £3.6m from the 31 March 2023 year end figure of £14.5m. It says this is due to normal seasonal inventory build-up for peak trading over Xmas.
Cost savings - some serious inroads into overheads have been made, £4.0m annualised savings already implemented, mostly in software team salaries - which did previously strike me as a rather excessive level of spend.
Outlook -
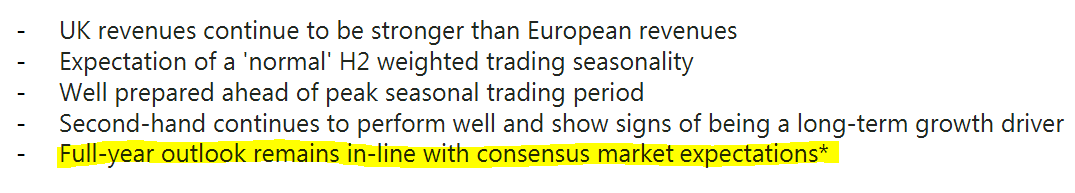
* Gear4music believes that current consensus market expectations for the year ending 31 March 2024 are revenue of £161.7 million, EBITDA of £9.8 million and profit before tax of £1.2 million.
That’s good to see they’ve included the consensus PBT figure of £1.2m, I think that’s new. In the past it was the highly misleading EBITDA figure only that was quoted. Look at the gulf between them: £9.8m EBITDA and only £1.2m PBT!
Paul’s opinion - I like the strategy of focusing on lean costs, and profits, ahead of revenue growth.
How to value it? Modest PBT of £1.2m this year (FY 3/2024) could be improved on next year (FY 3/2025) possibly, as a full year of cost reductions should help, and possibly something of a consumer recovery maybe, as real incomes have turned positive again? Singers seems to be thinking along the same lines, and has a jump from £1.1m adj PBT this year, rising to £2.7m for next year. In EPS terms, that’s 3.6p to 9.2p. What PER? In a future bull market, maybe 20x, so that’s 184p, a handy 47% upside - not really enough to get me excited, when I’m surrounded with opportunities for shares that could easily double or triple in the next bull market.
Therefore, I think I’ll stick with AMBER - no strong view either way. £26m plus the debt, means an EV of c.£40m (using year end debt, rather than the seasonal peak at interim period end), which is probably enough for a very low margin business that’s gone ex-growth arguably.
It’s difficult to imagine that racy valuations for eCommerce businesses are likely to come back any time soon, if at all. I caught both of the big surges in G4M over the years, so this has been a very lucky, and lucrative share for me. It's difficult to see how a similar surge would happen again.
Hollywood Bowl (LON:BOWL)
Up 3% to 241p y’day (£413m) - Trading Update FY 9/2023 - Paul - GREEN
Hollywood Bowl Group plc, ("Hollywood Bowl" or the "Group"), the UK and Canada's largest ten-pin bowling operator, announces a trading update for the financial year ended 30 September 2023 (FY23).
Excellent financial and operational performance in the UK and Canada following continued strong customer demand.
Revenue £215m (up 11%, or up 16% underlying: one-off VAT benefit for LY adjusted out)
90% of revenue is UK, 10% Canada.
LFL revenue growth (excluding new sites opened) was +4.1% in the UK - OK, but below inflation. Canada a much more impressive +15.1% (constant currency).
Odd wording here - I don’t like companies messing around with the wording of comparisons to market expectations. They’re either ahead, or not, this muddies the water -
The Group expects to report EBITDA growth (pre-IFRS 16), ahead of market expectations
There are not any broker notes, so I’m in the dark as to whether this is an earnings beat, or not?
Lots going on, with new sites, and refurbs, all self-funded from cashflow.
Net cash of £52.4m, plus undrawn £25m RCF.
Final divi of at least 7p. Stockopedia shows a forecast yield of 5.3%, very nice. Especially as the likelihood seems to be that future divis could continue increasing, as the business expands. Self-funding growth, and paying a 5.3% yield, impresses me a lot.
Paul’s opinion - I’m always GREEN on BOWL, because it’s a cracking business, reasonably priced, and always seems to trade well, regardless of macro factors.
Assuming no change in forecasts, then Stockopedia has it on a forward PER of only 12.0x - that seems smashing value, for a high margin, self-funded growth company, with plenty of net cash, that is paying a >5% dividend yield.
Why is it such good value? The only reason I can come up with is the risk of possibly customers losing interest in bowling, and over time increased competition. There doesn’t seem any sign of that happening though. Or it could just be due to general malaise in small caps - more sellers than buyers, for reasons unconnected with the fundamentals of the business maybe?
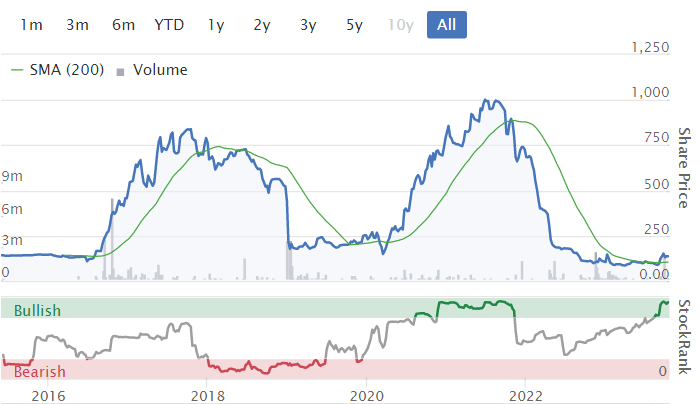
Considering how much progress in size, and profits, that BOWL has delivered in the last 6 years, despite the pandemic, energy and cost of living crises, nothing much has happened to the share price. This is really surprising I think.
Hence it has to be another GREEN view from me on BOWL shares. Are we missing something here? If any readers take a more bearish view, do post a comment.
Saietta (LON:SED)
Down 29% to 27p (£28m) - FY 3/2023 Results & Resumption of trading - Paul - RED
Lifting of suspension of its shares was done at 12:30 yesterday, after publication of overdue FY 3/2023 results.
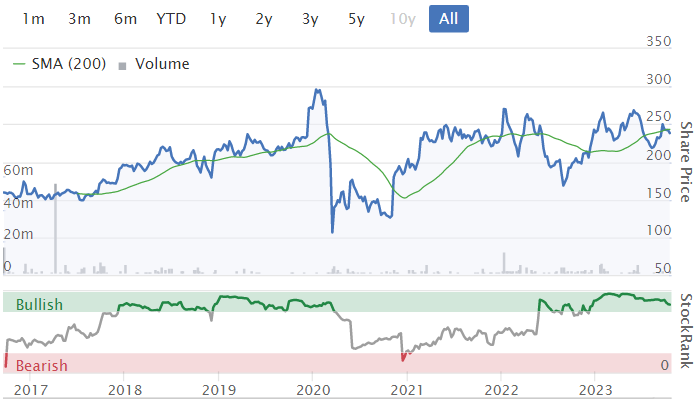
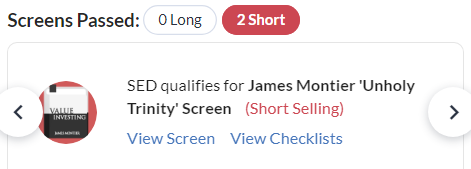
I can remember that we previously thought this share was a steaming pile of rubbish, based on the appalling facts & figures. Checking my notes confirms that recollection. We flagged high risk and heavy cash burn, marking it RED on 6/12/2022, 12/4/2023, and 25/9/2023, warning readers away from it in the strongest possible terms. Meanwhile, unscrupulous paid PR promoters were pumping this stock to the gullible. Same old story at the bottom end of AIM, I’m afraid.
FY 3/2023 Results - already 7 months out of date almost.
Saietta Group plc (AIM: SED), the multi-national business which designs, engineers and manufactures complete electric drivetrain (eDrive) solutions for electric vehicles, announces its full year results for the 12 months ended 31 March 2023 and provides an operational and financial update.
RED FLAG! Material uncertainty in going concern statement -
Furthermore, the forecasts also include payments from Saietta VNA, the Group's joint venture in India, for equipment for fully automated production of AFT motors. The Group has spent £3m on such equipment and this amount is to be reimbursed by Saietta VNA. In the absence of such reimbursement there may also be a need to raise additional funding
Whilst the Directors expect that additional funding can be raised this is not guaranteed and when continuing with an accelerated expansion this presents a material uncertainty which may cast significant doubt over the Group's and the Company's ability to continue as a going concern
FY 3/2023 figures -
Revenue £2.1m (up 52%)
Operating loss of £(19.4)m - this is not a typo. The previous year was a loss of £(10.9)m.
There’s an additional £7.9m loss from discontinued operations on top.
I can scarcely believe these figures, they’re so bad.
Balance sheet - cash has reduced from £18.4m to £7.2m between March 2022 and March 2023. On that trajectory, there’s probably nothing left by now.
Paul’s opinion - this is a disaster. I see the CFO announced his resignation on 6 Oct 2023, effective once the late accounts were filed.
As things stand, the company looks likely to go bust imminently, or be forced into a highly dilutive fundraise. Or, a miracle might happen, who knows?
I’ll happily look at it again with fresh eyes, once it has refinanced, but at the moment it’s a double bargepole.
It’s possible that SED’s technology might be world-beating, but as we’ve seen with many companies like this, commercialising it is quite another thing, and always takes far longer, and costs far more than originally planned. People who invest in these IPOs nearly always get taken for a ride, over the cliff, like boarding a highly efficient, but doomed electric rickshaw perhaps? Maybe it’s the investing equivalent of Thelma and Louise, but with less engine noise and wheelspin? It rarely pays to be an optimist, with cash burning minnows on AIM. Why get involved, when it’s almost certainly dangling by a thread in terms of cash?
The only Stockopedia screens that SED qualifies for, are James Montier style shorting ones - although something this small isn't really practical to short. Also I would never personally short anything tiny, because the risk involved is potentially ruinous. A friend once shorted something at 1p, certain it would go bust, and it spiked up to 31p. Imagine that - a £10k position suddenly became a £300k loss, when something completely unforeseen happened.
Another friend lost about £1m shorting some Chinese fraud. Everyone knew it was a fraud, but when the shares were suspended (worthless), the Chinese promoters had cornered the market, and his broker was forced to buy back the short at a ludicrous price demanded by the Chinese. So I would strongly urge everyone here to not even think about shorting small caps, it's way too risky and could ruin your life. It only needs one to go spectacularly wrong.
IQGeo (LON:IQG)
255p (£157m) - Call with management - Paul - AMBER
I reviewed the interim results from this interesting software company here on 26 Sept 2023. I was very impressed with the big organic growth of 83% in H1, turning 2023 into a breakthrough year where years of losses have now moved into profit. So definitely a company I want to research in more detail.
It offers specialist cloud-based geo-spatial software mainly for telecoms and utility companies, globally. Customers use the software to plan, record, and manage their large networks of physical assets (eg. fibre networks, other cables and pipes, etc). The rapid growth clearly demonstrates that the product is resonating with clients, hence why I’m keen to learn more about the company.
I also flagged a couple of negative points - valuation of the shares strikes me as too high, although that’s subjective, and rapid growth companies are rarely cheap!
Also I had a concern about the very high level of receivables on the balance sheet at June 2023, presenting a risk that customers might not pay maybe?
An adviser reached out, and offered me a call with management, to resolve my queries, and also so I could learn more about the company, ask questions, see a presentation slide deck, etc. So I had a most interesting online meeting with management yesterday, and thought I’d update readers here on my balance sheet query in particular.
High receivables - the CFO said a number of factors had boosted year-end receivables, including a £1.8m invoice paid a few days after the period end. Plus another £1.2m where a customer had got into an accounting muddle, since resolved.
All bar £21k of the 30 June receivables have now been paid by customers, which is the key point - obviously I’m basing this on trust.
Another point, which I hope isn’t commercially sensitive, is that deals done with some customers allow them more time to pay on an agreed basis. You can see that from the 2022 annual report anyway, which shows that overdue invoices are nearly all 0-90 days overdue, so not seriously overdue.
Also the rapid growth means receivables look high compared with revenues, because the most recently billed things will be much larger than revenues billed 6 months earlier.
It’s not ideal having extended receivables, but the explanations from the CFO seemed credible, and there doesn’t seem to be a broader problem.
So I’m happy to say I think this looks OK, but I’ll keep an eye on future balance sheets, as we do need to see receivables reducing as a percentage of revenues.
Product/market - this was very interesting. It seems that IQG is in a sweet spot, where its software is providing what utilities want, in the right way. Whereas competition is said to be mainly older established, non-cloud based. IQG reckons it’s 2 years ahead of the competition, with better software, in the cloud.
Land & expand strategy, so a lot of growth is coming from customers who trial part of IQG’s offering, then buy more modules, and more users. It eliminates “swivel-desking” (what a great phrase!) where users have to use several different software systems to do different parts of their work.
IQG’s software is mission-critical, and customers are very sticky - typically each contract win sets up a 20-year+ relationship with the client, with recurring revenues, upgrades, etc.
Very good markets, “riding the wave” of big telecoms spending on fibre networks.
Market size is massive, and global. IQG targets larger customers first, and management seem ambitious about securing a decent market share over time - and I keep coming back to that stunning 83% organic growth in H1 revenues. Obviously large % gains inevitably moderate over time.
Just won a competitive technical tender, where the customer was prepared to pay substantially more for IQG’s system, because it was better than the competition.
Drivers for demand are waves of capex being undertaken by utilities, and replacing outdated systems.
Flexible cost base, making use of some consultants for implementations, etc.
Very low customer churn.
65% of revenues are N.America - I wonder if it could be a takeover target maybe (although this wasn’t mentioned on the call).
Typical contracts are 3 years initial, then rolling annually.
See customer testimonials on website.
Investor meeting at Cavendish’s office on 29 Nov 2023.
Capitalising c.65% of development spending.
Moving to cashflow positive this year, so cash pile looks adequate I think - low dilution risk, unless they do more acquisitions, and high market cap means a little dilution wouldn’t worry me.
Addressable market c.£2.5bn ARR - plenty to go for.
Key advantages are - fast moving nimble business, global presence & huge markets, low staff turnover, acquisitions have gone really well, cashflow positive & profitable now, very rapid organic growth shows the product is in demand (in a sweet spot).
Paul’s opinion - I was previously AMBER/RED, due to my balance sheet concerns. Those are now resolved satisfactorily, and having learned more about the company, I’m much more positive about its potential. So leaning towards a positive view, but the high valuation means I think I’ll go up to AMBER for the time being.
Overall then, IQG looks a really good, rapid growth company, but a little too expensive for me at this stage. I could see this company being a long-term winner though. A bit like Cerillion (LON:CER) (different niche, but in a similar area), which is another growth company I really rate highly, it could be worth just paying up for these two shares. Long-term, investors who paid up for quality a few years ago, have been very well rewarded.
Here's a short video presentation from management, re recent interims - gives a flavour for the top team, who I think seem strong -
PROCOOK (LON:PROC)
Down 13% to 18.7p (£21m) - Q2 Trading Update - Paul - RED
ProCook Group plc ("ProCook" or "the Group"), the UK's leading direct-to-consumer specialist kitchenware brand, today reports on Q2 trading results for the 16 weeks ended 15 October 2023.
The current financial year is FY 3/2024.
There’s a slightly improving trend re % sales decline from Q1 to Q2, but for H1 as a whole, sales of £26.3m is down 3.8% on LY, and down 4.4% on a LFL basis. At a time of considerably increased costs (eg wages and energy especially), this can’t be good for profitability. It doesn’t provide any clear guidance on profitability, just saying -
However, the Board remains cautious with regards to the FY24 outlook given the highly challenging market conditions which persist, and the current trading volatility and sales trends over recent weeks, with customers seeking more value and taking more time to research before committing to purchase.
Trading in September and into early October has been markedly softer…
Net debt is £3.2m - slightly up on £2.8m six months earlier. Available liquidity of £12.8m sounds good, but I wouldn’t be surprised to see bank facilities reduced at some stage.
Paul’s opinion - I’d be very surprised if it gets anywhere near the £3.5m net profit figure shown on the StockReport. Another loss strikes me as more likely, but we’ll see. FY 3/2023 saw a small underlying loss of £(0.2)m - not a disaster, but I can’t see any signs of recovery yet. The last balance sheet at March 2023 looks adequate, with about £9m NTAV.
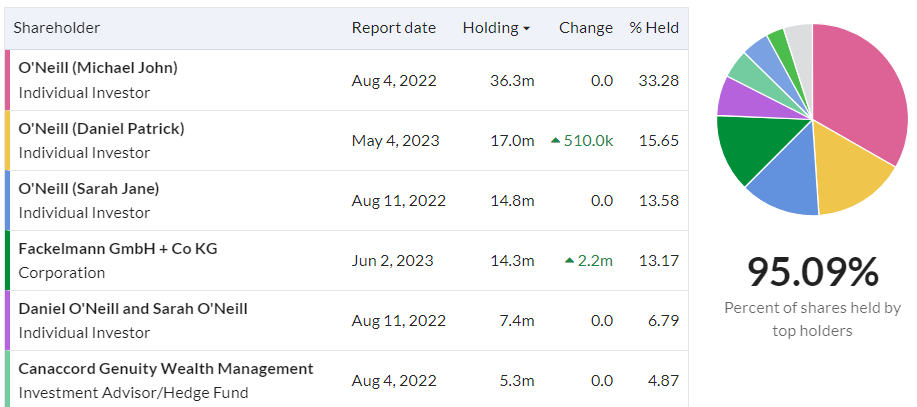
The O’Neill family completely dominate the shareholder register, and there’s hardly any free float. Hence I would say delisting risk here looks very high - I cannot see why they would want to continue with a stock market listing that hasn’t worked (due to poor performance after the 2021 boom turned to bust).
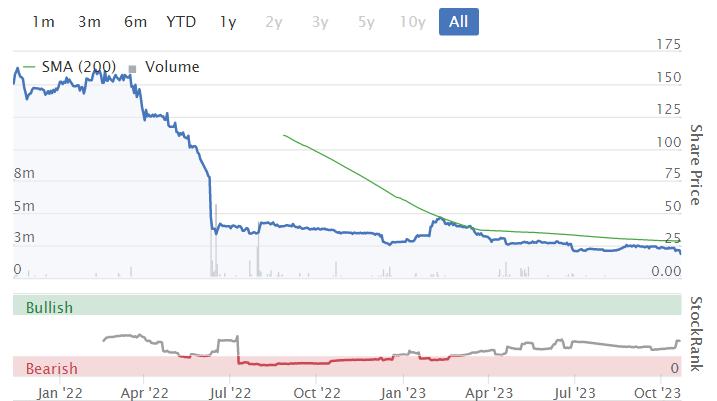
We’ve been RED in our previous reviews, on 14/12/2022, 19/4/2023, and 28/6/2023. I think we’d need to see firm evidence of a trading recovery to consider moderating that to amber. Given the continued soft trading, and the delisting risk, I’ve got to stick with RED for the time being. Why get involved?
.
Another vintage 2021 float -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

54 comments
I welcome this development and look forward to your podcasts. I started back in the Stock market in feb 21 thinking now is a good time with the markets being on the floor so to speak , I thought I couldnt go wrong , Well i got so many things wrong its a wonder i survived. at the moment I am around 7% in the black so any info re market trends is welcome.
Thanks for your always entertaining podcast this weekend, Paul. Can I just add that my wife, who has only a passing interest in equity analysis, is now a confirmed fan. She finds you very soothing and charming!
Anyone with any thoughts on the recent dip in ME International (LON:MEGP) share price?
It's done well for me but now getting close to selling and taking the remaining profit. That would be a shame, as I had high hopes for closer to 190p. The main concern for me up to about a week ago has been the owner's large % holding; other than that I've been very happy.
Goes ex-div on 2nd Nov.
No news suggests ME International (LON:MEGP) might just be suffering in the broader market place sell off. Shoe Zone (LON:SHOE) and Ramsdens Holdings (LON:RFX) are examples of similar shares with unexplained sell offs just prior to positive updates. ME have an update likely the first half of November.
It might also be worth reading, if you haven't already, Ed Crofts article yesterday on limiting losses where he mentions it being too easy to sell into a gain. I understand also from the comments that his next article in the coming week will be on the topic of when to sell.
My reflection is that having sold Ramsdens Holdings (LON:RFX) when it fell suddenly and hit my stop is that it's done me no good. The market is very volatile and even very good companies are getting tested.
[I hold ME International (LON:MEGP) and Shoe Zone (LON:SHOE). ]
Thanks
I think the price has just come back to support and also filled a price gap on the chart, that’s where I had an order that got filled yesterday. You also had Montefiore increase their position recently so I’m cautiously optimistic here. I also recall Paul Scott’s recent chat with a fund manager, a key trait of successful investments is finding businesses that are scaleable, this company ticks this box for sure. I also just re read Grahams last write up, lots of reasons to stay invested.
Thanks. Both you and Tein have given me things to think about. Will backcheck your suggestions. (I like to buy and hold)
Treatt (LON:TET) . Yes, a bit odd as he's only 52 and spent all his career at Treatt. He's done a very good job. I'm no longer a holder but it was a multi-bagger for me.
This weeks Top of the Pops & Top of the Flops (excluding the junk end of the market)
DAX gave a good sell trigger when the moving averages crossed, looks Scheisse
S&P might trigger the same signal next week. Will also likely trigger MACD sell signal soon. If you're a short term trader unlikely to want to hold longs over the weekend.
Gold is on a tear unsurprisingly in the last fortnight.
Personally Im short DAX, long Gold and S&P (tho close to being stopped out there) No idea whats going to happen but more fun next week im sure. Im off to get drunk :)
According to Stocko, ME International is listed on the main market. Anyway, fund manangers faced with a net outflow have to sell whether there is news or not, good or bad. Better for them to sell on good news as they get a better price, which may explain prices falling back after a rise following good news, or even a fall on exceeding expectations.
Richard
ME International (LON:MEGP) the latest quality AIM share to drop sharply on no news. Gap filled to 140p, perhaps?
ME International (LON:MEGP)
the latest quality AIM share to drop sharply on no news. Gap filled to 140p, perhaps?
Wish I could understand what this actually means? I've looked at the chart and haven't got a scooby.
Presume it's some kind of mysterious and obscure tea leaf reading?
ME International (LON:MEGP) is a FTSE 250 company
He was quoting JoeDoe2378.
Yes, my bad, forgot it was promoted recently. Surprised to see close below 140p. Horrible market. Unless someone knows something we don't....
Can I just plead with posters who are commenting on a previous comment to put a reference to the stock they are talking about. 'Ref VOD' would be enough. It saves us having to scroll back all of the time. Thanks in anticipation.
Anybody adding a supplementary comment should use the "@" symbol so it is immaterial whether you are reading comments as a thread or not. Ideally there would be a "General" symbol or similar for all comments like this.
Cafcash, change your settings to Replies Threaded and you won't have this issue.
Many of us want to easily find new comments. Reading Unthreaded means that new comments are contained in a red outlined box at the top or bottom of the page. Reading Threaded means that new comments are easily missed. Please put the ticker on your comments.
From Paul, in the introduction: Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Treatt (LON:TET) I do not hold
Not a trading update but I would suggest possibly significant with announcement of the resignation of CEO:
"Daemmon's retirement comes after 32 years with Treatt, the last 11 years as CEO. He has agreed with the Board that he will step down from his role on 31 December 2023"
https://www.research-tree.com/...
This seems a very short notice period, considering he has been with the company 32 years. Has he fallen on his sword? Share price decline has been horrendous from over £13 in January 2022 to just £4.30 today. (That’s even worse than some of my holdings :-)).
I believe still a large holding for Lord Lee and popular with PI’s.
Any thoughts welcome.
Regards
Michael
Or has the Treatt (LON:TET) CEO simply retired due to old age?
Possibly but if you have been with Treatt (LON:TET) for so long I would have thought they would have a succession plan in place. After all he didn’t suddenly get old.
Regards
Michael
Treatt (LON:TET) looks like the classic case of how the market took a good company, and enough of a "story" was created to inflate the SP to unrealistic highs.
Its a decently profitable, solid moat company in its sector. Albeit with some challenges at the moment. But how it ever got to 50x PE, which was already on top of racy growth forecasts by brokers...
Although only 26% of their business now it will be interesting to see how this plays out with Halfords (LON:HFD) , are they going to have a lot of over priced bicycle inventory to push through or will it be offset by the ability to buy at bargain prices?
Instem (LON:INS) - is there a relatively straightforward 10% on offer here? RNS today suggests that management has visibility of nearly the required 75% for this deal to go through. Court meeting on 2nd November so not long to wait. Stock offered at 752 for a takeout price of 833. Looks quite good risk / reward as the chance of t being voted down now look quite low
Mammyoko, Thanks for a great spot. A very high chance of a 10% yield and hopefully! only need to hold for a couple of weeks. I have bought a few.
mammyoko,
I saw this too, and bought a few, probably should have flagged it like yourself, good of you to share.
Still a small risk that it gets voted down but given the scale of other risks around that one seems comparatively minor!
Well spotted but Mr Market doesn't seem to be as positive as you. SP fell back on the 12th and hasn't risen that much today. Why is money being left on the table?
General apathy to the Stock Market I would guess. I bet a lot of people have stopped looking.
ONS September Retail Sales Report:
BOE to hold rates at the next meeting?
Paul I would welcome your comments on Manolete Partners (LON:MANO) trading update from earlier in the week (Wednesday), as it has actually been a riser for me this week. It was last covered by the SCVR by Roland on 21st April 2023 when he graded it Amber.
I think their prospects have improved since the impact of the government protections against insolvency during the Covid period have been removed. I took a small position after seeing them present at Mello, partly because I liked the fact that they were working on a pilot scheme with Barclays to pursue fraudulent Bounce Back Loans. This pilot has been successful and is now being extended.
Hi shopping365!
I enjoyed your thoughts on Sosandar (LON:SOS) - great to get a woman's perspective on womenswear!
As regards Manolete Partners (LON:MANO) - thanks for flagging it. I've just read the recent trading update, and it's got some interesting-sounding bits in it, for sure. So I can see why you think it looks interesting. I don't tend to write reviews of litigation-financing businesses, as they're complicated, and have lots of moving parts. So often it can be a case of building up a valuation stage by stage, by assessing each individual large case, and making broad brush assumptions about how smaller cases would get resolved. I like the sound of it funding Bounceback Loan recoveries - it was an open secret at the time that many unscrupulous people used Bounceback loans for illicit purposes - apparently sales of Ferraris and Lamborghinis went through the roof when this Govt scheme started!
Overall, the update sounds like they're building business up again after a hiatus, so there could be a medium-term opportunity here possibly?
This is what they say about trading -
Subject to auditor review of the interim accounts, the Directors believe that the Company will report profitability for H1 FY24 at marginally less than was reported for H2 FY23. This is primarily due to the reduction in average case sizes and after the investment in new staff and business development, as the Company builds capacity to meet the current, and anticipated, significantly higher business activity levels. Traditionally the second half of the trading year is the stronger for the business.
The StockReport is showing a fwd PER of 11.7x, and a reasonable price to tangible book ratio of 1.78x, so quite good value metrics there.
Manolete has a history of being decently profitable, albeit quite erratic amounts, pre-pandemic, which gives comfort that this is a proper business.
I'd see this as a specialist sector, so not sure I can add any value by commenting further on it.
Best wishes, Paul.
Destiny Pharma plc (LON:DEST) XF-73 is the Phase 3-ready drug developed by DEST and next up for partnering: recent positive study results and an XF Pipeline Update on Tuesday showcased its strengths and huge potential. As you can see in a new research note from Dr Andy Smith today - free acces to read here:
https://www.equitydevelopment....
Saietta (LON:SED) "Meanwhile, unscrupulous paid PR promoters were pumping this stock to the gullible." Who do we think that is? Anyone? Anyone? Bueller? Beuller?
Vox and directors talk. I held on that now tiny looking spike in the chart last March.
Buy on a good announcement, wait for vox and director talk rampy interview. Sell into the buying stampede.
Not exactly classic investing but it all counts.
More Terry Thomas than Terry Smith eh ? :o)
Absolutely shower indeed
Saietta (LON:SED)
Could it perhaps be.........https://www.stockopedia.com/co... (at 39.35 minutes)
Can Mr Hill of Vox explain this ?
Wiggle / Chain Reaction on the brink .
Bit of industry commentary and read across for anyone interested and I think this is a Mike Ashley grab .
Cycle industry online big boys wiggle / chain reaction are going into administration .
Not only is online / e-commerce generally under massive pressure at the moment .
Add to this cycle industry is also distinctly out of fashion and in a post covid bust phase .
I once visited a small Irish bike shop run by a young kid called Chris out of the from room of a tiny shop in Northern Ireland . His mum Janice made me a cup of tea, probably around 2005 . That was chain reaction and Chris surfed theinternet wave and built a great business .
Wiggke got sold to VC ,
they bought CRC ,
they pumped it up and dumped into onto a SPAC,
they loaded it with debt and fees.
The market turned
The lead investor / banker pulled the finance
Goes into admin
bizarrely mick Ashley just bought 45 bricks n mortar stores in Germany from signa sport for 350 million in Germany and then they pull the funding on wiggle putting it into administration .
So wonder if this is Mike Ashley pulling the strings to get wiggle / crc for 10-20 million .
He then owns evans , PBK , Universal cycles , muddy fox .
He’s got big balls has Mike and if this is indeed the play he has taken a massive grip of the bicycle market .
Bizarrely I was once approached by sports direct to buy Planet X and had a couple meeting with them then end result was not pretty when they basically asked me to “guve” then the company and they would grow ur and allow me to keep a % .
My response began
“I know it is closed to Christmas but am surprised that Mike Ashley still believes in free gifts ……
And it ended in OFF .
Just rambling .
Keep rambling planetx, very interesting summary! I've bought from Wiggle and thought them very competitive but VC's kill many companies and walk away smiling.
I hear on the grapevine there are 25k unsold mountain bikes sat in a warehouse in Switzerland.... the industry got a little carried away esp with e bike ordering that went on during Covid.... believed their hype... good deals on US marks already and going into 2024 prices set to fall. So it's worth holding off although bike prices in the UK much more competitive.
Does anyone really understand what Mike is up to? You normally find out at the end of the game that the player buying everything was stealing the odd £500 in monopoly ...... no view, no position. A Friday comment
Another Friday comment;
My wife and I met Mike Ashley back in 1996 whilst on holiday, his business then was still called Sport Soccer, just before it became Sports Direct, apart from him trying to sell me loads of socks as I had a wholesale business and he had just bought the Donnay brand, we got on very well and spent a lot of time together. In my opinion he was without doubt the best retail brain in the UK at that time, but this was really pre e commerce and whilst he told me lots of little retailing wrinkles that I thought were so clever, later I never really thought that he fully understood how to get the best out of etailing, obviously I cant comment on his son-in -law/new CEO but I have always put 2 and 2 together and thought these purchases of dedicated etailers was to improve his knowledge because he just didn't 'get it.
Frasers vs Next: How big are their growing retail empires? - Retail Gazette
This may be of interest from this mornings Retail Gazette
I don't 'really' know but the way I have thought about it in the past, is he clearly knows retail and the high street and is doing very well whilst others are floundering. In the end I think he will be the Amazon.com (NSQ:AMZN) of the high street. Wherever we shop he will be involved and more likely things like free delivery, free returns will be a thing of the past for those new acquisitions and maybe even where he has big stakes and influences.
At Sports Direct even click and collect has a charge (unless over £100 spend) and it is a 3-7 day wait. I must say that the shops have massively improved over the last 15-20 years, they used to look like a dump with stock just piled everywhere or at least the shops near me did but now the shops are lot more organised and a better experience.
PS even Amazon.com (NSQ:AMZN) is trying their best to stop free delivery even to lockers in my recent experience giving me no option but to have it delivered to home for a fee. I just didn't bother to proceed as I thought it was very underhanded as it would not even let me select another locker. (Guessing they want the prime subscription)
He's a contrarian investor buying business when few will. He's bought and will buy some strong brands that have hit the rocks due to being poorly run (which Big Mike will fix) or the populace have cooled on
Good Morning Planetx,
What has gone wrong in the Cycle Trade ?
I am assuming it was Covid led, loads of overnight demand because cycling was one of the few 'activities' people could legally take part in, the unravelling of this was no stock for retailers to buy, retailers then placing huge orders with China/their wholesalers , then a subsequent massive drop in demand when people were allowed to do 'other' activities, the chinese orders turning up, no sales, lots of second hand bikes on Ebay etc making things worse, then a cost of living crisis tempering demand as things normalised.
TIA
Always enjoyed the service from Wiggle tbf, from a customers perspective thought it was a decent business (never looked under the hood though). Certainly seeing the COVID bounce in cycling massively dropping off in my network - friends and colleagues that were putting in the miles every other day are now staring at their bikes gathering dust.
Like Mike Ashley I'm hopeful of picking up some cheap bargains from friends who have put their bikes in to administration.....
Can never have too many bikes and always worth having spares of everything.
I do hope they (Wiggle) survive. They have been a great offering, but I guess its the PE & debt that will have killed them off. A warning for all.
Good morning Paul an excellent rant on Saietta (LON:SED) to start the day…I especially liked this quote;
’Meanwhile, unscrupulous paid PR promoters were pumping this stock to the gullible’
Wholeheartedly agree
Vox ? Paul Hill ?
2024 Q2 trading update from Record (LON:REC) today (I hold). Performance fees of £1m is twice that of 2023 Q2 but by my reckoning the previously announced drop in Q1 means that half year fees are £1.5m compared to 2023 HY of £2.8m. CEO Leslie Hill also flags up that diversification into asset management and digital assets is progressing slower than envisaged. Half year results to be announced 17 November, along with more detail on their strategic process.