Small Cap Value Report (Fri 20 Sept 2024) - Brief: STCM, PRES. Small cap bargains?

Good morning from Paul!
Podcast mystery share this weekend (21/9/2024) is: Warpaint London (LON:W7L)
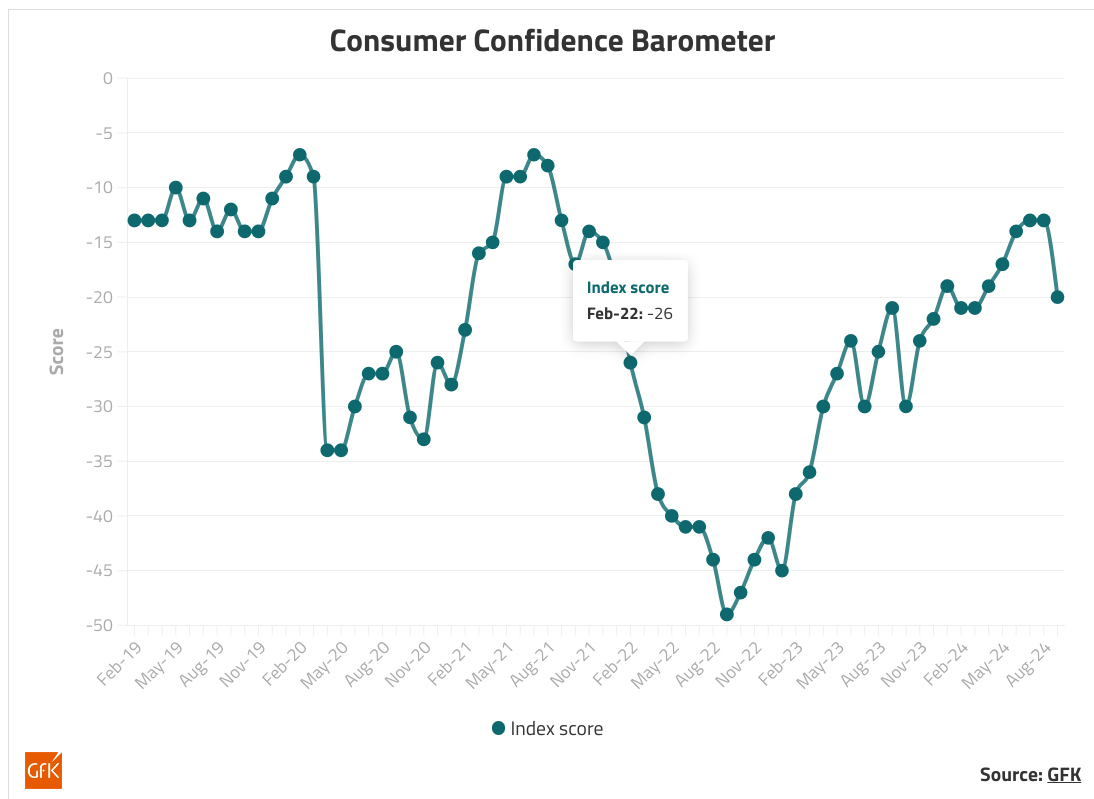
Consumer confidence drops sharply
Data out today (I can't find the source on GfK's website, so have used a free article from Retail Week, many thanks to them).
This shows below a sharp fall in the widely followed consumer confidence survey from GfK, dropping from -13 in August, to -20 in September, undoing the steady improvements which had been occurring earlier in 2024. I'm livid about this, as it's obviously been caused by the inept messaging from the new Govt, about a supposed black hole, taking the fuel allowance away from pensioners, and how a dreadful budget is on the way. They clearly have no understanding of the economy needing confidence in order to grow, for both businesses and consumers. So a pretty dreadful start I'm afraid, with basic, schoolboy errors. Let's hope they realise they're saying all the wrong things, and remedy the situation with a more positive approach in future.
Possible small cap bargains?
New video looking at screening for potential bargains: click here
Also now published on Youtube, to help anyone who struggled with the bandwidth on the original link (buy a new computer, cheapskates LOL!)
?si=sFNoSygICdRT36SKAnnoyingly, I got up early today to record a video looking for bargains in small caps. Dutifully done, but it didn't record any sound, so I had to do it again (edit: done, link above) now with the sound on. Please see below some of the share ideas which came up for further research on my manual and screening approach to find recent fallers which may or may not be bargains. My thinking being that we could be seeing some irrational, fear & tax-driven selling in UK small caps, whilst US markets rise to new all-time highs, which should be good for UK shares in due course, once the end Oct budget is out of the way.
Here are some ideas for you to properly research yourself in more depth -
Mortgage Advice Bureau (Holdings) (LON:MAB1) - note reader comment flagging potential regulatory issues - thanks for that.
Frontier Developments (LON:FDEV)
Sanderson Design (LON:SDG)
Tristel (LON:TSTL)
Tribal (LON:TRB)
Vertu Motors (LON:VTU)
Beeks Financial Cloud (LON:BKS) (I hold)
Volex (LON:VLX) (I hold)
Brickability (LON:BRCK)
Spectra Systems (LON:SPSY) (I hold)
Hunting (LON:HTG) (I hold)
Osb (LON:OSB) (I hold)
Warpaint London (LON:W7L)
Hollywood Bowl (LON:BOWL) (I hold)
J D Wetherspoon (LON:JDW) (I hold)
Zotefoams (LON:ZTF) (I hold)
Gulf Marine Services (LON:GMS) (I hold)
Gaming Realms (LON:GMR)
A late one I forgot earlier: Eurocell (LON:ECEL) (I hold)
More details on each share idea above are in the "Discuss" tab of each company, all have been discussed at length here in the SCVRs previously.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (Sept 2024)
Companies Reporting
Hardly any news today, here's my quick commentary on what there is (I won't be expanding on these, as they don't interest me) -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

123 comments
Hey great to see you back here Yiannos
DD
Hi Paul. I am a new listener to your podcast and enjoying it very much. Newbie question... I have not discovered how to locate your mystery share of Tuesday last week as the spreadsheet on Stocko only shows up to 13/09. Is this where one should be looking?
Hit the 'Discuss' icon on left margin of Stocko home screen, and you'll see Small Cap Value Report under 'UK BLOGS', where all the SCVR's are available for viewing.
Thanks Ortho
Thanks DitW! Glad you like my podcast :-)
Podcast mystery share is Warpaint London (LON:W7L) this weekend, 21/9/2024.
I'm just updating the spreadsheet now.
Regards, Paul.
Thanks Paul
Booo. You'll never make it as a mystery writer. "Chapter 2 - The butler did it, with an ice-pick, in the larder".
y
Hi Paul,
Just watched the video. Always interesting to see how other people use Stockopedia.
On Osb (LON:OSB)… I would just warn against valuing banks using P/E and P/TB. Most banks are on low PE’s and large discounts to P/TB, just look at Barclays (LON:BARC) and Standard Chartered (LON:STAN) for instance.
I looked at OSB following a recent SCVR and two things put me off:
1. The loan book is not funded by deposits and so is dependent on external funding. And we all know what happened to Northern Rock! I recently moved some money into a savings account for a few months and one of their brands (Kent Reliance) was offering the highest rates and has been for some time - a sign they are keen to address this issue.
2. I am wary of private landlords being targeted in the upcoming budget. This seems low hanging fruit to me for this particular government. This could have a knock on effect to the buy-to-let market on which OSB is dependent.
All the best, Si
Hello Si!
Point taken re banks being valued on low PERs and often large discounts to NTAV. Although I suspect that might be because their accounts (eg Barclays) are incomprehensible, and there could be all manner of nightmares & risk hidden in the huge numbers for things like derivatives. Also it shocks me how little capital they have overall to support huge lending, although we're told that apparently they're much safer now post 2008 regulatory changes. Hence why I avoid holding bank shares,
What appeals to me about OSB is that it has hardly any of that complexity. Its balance sheet is really simple - it collects in deposits from savers (I couldn't determine what proportion are on demand, and what are term deposits), then it lends to BTL landlords. Those debits & credits make up the main bulk of its balance sheet, with only some relatively small other items. It's that simplicity & transparency which I like about it.
So I don't understand your point 1, because the loan book IS funded mostly by deposits.
BTL landlords - apparently there's still plenty of demand from more professional BTL investors, who buy properties through limited companies now. Whereas sellers are, as you say, often people with just 1 or 2 BTL properties in their personal name, who are being hit by wave after wave of tax and regulatory attacks (under the previous Govt), and more likely as you suggest.
My main issue with OSB is that its margins seem to be under pressure, from increased competition presumably, with a couple of profit warnings citing reduced lending margin, and continuously falling broker forecasts. Overall though, I think that's been overly priced-in to the shares, which are now looking very attractive for divis, sound (and simple!) balance sheet, hence why I like it.
Talking my own book, for disclosure I am long.
Regards, Paul.
Thanks for taking the time to add your view Paul.
Point taken re banks being valued on low PERs and often large discounts to NTAV. Although I suspect that might be because their accounts (eg Barclays) are incomprehensible, and there could be all manner of nightmares & risk hidden in the huge numbers for things like derivatives. Also it shocks me how little capital they have overall to support huge lending, although we're told that apparently they're much safer now post 2008 regulatory changes. Hence why I avoid holding bank shares,
What appeals to me about OSB is that it has hardly any of that complexity. Its balance sheet is really simple - it collects in deposits from savers (I couldn't determine what proportion are on demand, and what are term deposits), then it lends to BTL landlords. Those debits & credits make up the main bulk of its balance sheet, with only some relatively small other items. It's that simplicity & transparency which I like about it.
But it's still a bank. I think we both agree that the banking business model is lousy and requires huge amounts of leverage just to keep the lights on. At least the leverage of OSB is lower (around 12x) than the large banks which have 18-20x assets to equity. The latter means if 10% of the loan book turns sour the equity is wiped out. The good news for these banks is that they are too big to fail, because they would take the UK economy down with them, so the government is lender of last resort for them. Alas, as we found out with Northern Rock, small banks and buildings societies will not be afforded this safety net beyond retail savers being protected up to the FSCS limit. Whilst I appreciate that the OSB balance sheet is easier to understand, it is also clear it is less diverse and almost subject to a single point of failure i.e. the UK buy to let market.
So I don't understand your point 1, because the loan book IS funded mostly by deposits.
I don't understand why you don't understand? It is a fact that deposits do not cover loans and that some external funding is needed. I couldn't find another UK bank where this situation exists but I didn't search exhaustively; all the larger banks have loans which are 60-70% of deposits. To make matters worse, the gap in funding is at least partly made up by securitising mortgages - does that ring any bells? Even if they are not alarm bells currently! This all adds to risk and hence a discount to the valuation of other banks should be applied and IMHO OSB is not as cheap as it looks on those grounds. It's also a fact that two of its brands (Kent Reliance and Charter Bank) are always at the top of the savings rate tables when I look. I'm not trying to be alarmist, but this reminds me a lot of the situation with Icelandic banks in 2007.
Of course, the share price may bounce from here and everyone will make money and be happy, I hope. But all I'm saying is that the risk/reward is not as good as it looks from a cursory glance at the StockReport.
All the best, Si
There are hardly any defaults/bad debts with buy to let lending though.
That's why OSB is attractive, as a simple savings & loan business, making a margin on low risk, vanilla secured lending to people who are not going to default.
Sounds like we're not going to agree here, not sure why though.
Run on deposits - why would that happen? £85k are insured.
Sorry, Paul. I don’t like banks because 2008 is still seared into my memory.
My main point is that OSB is maybe not as cheap as it looks and that P/E and P/TB is not the way to value a bank. I agree it’s simple to understand compared to other banks, and I’m not saying it’s going to go bust, just that some of the warning signs and risks you’d look for are there i.e. deposits do not cover loans, they are needing to offer market leading rates (well in excess of gilt rates of the same duration) to get those deposits. These are facts. I wasn’t even trying to be bearish!
Run on deposits - why would that happen? £85k are insured.
You should read some Richard Thaler books if you need to ask that question. The FSCS limit is a fig leaf IMHO. What percentage of deposits exceed the FSCS limit? We don’t know, but anyone with savings above the limit will withdraw their money and others will follow, that’s all that’s needed to start a run. Even Mervyn King has stated that’s what you should do. Even those protected by the FSCS will take months to get their money back. The good news is that OSB don’t have branches so there won’t be pictures of queues on the BBC News! :-)
The 2008 Banking crisis showed that the DIrectors of the big Banks didn’t understand Banks. e.g the hapless Fred Goodwin of RBS and the Directors of Northern Rock and the other Banks that either went bust or had to be rescued. And if they don’t understand their business model and the risks in it, what chance have most of us got?
Osb (LON:OSB)
Very good points Si.
And I will add (having analysed the banking sector for many years) that this has all the signs of potentially ending up in tears.
1. They have written an impairment credit out of almost £5B stage 2 and stage 3 loans!
2. Their coverage ratio of stage 3 loans is 7.95% whereas for HSBC is above 20%!
3. Their stage 3 loans amount is just bonkers!
4. When they decide to take the proper impairments they will record massive losses.
All the best
I think it was Mervyn King who said it makes no sense to start a run on a bank, but once one has started you should most definitely join in :-) Liquidity my dear boy, liquidity!
Except Simoan, that the Government backstop protection on customer deposits means that retail depositors are generally no long skittish.
If you look at SVB the cause of that was no backstop - lots of large balance skittish investors and a very low liquidity ratio,
Osb (LON:OSB) liquidity ratio exceeds 200% (100% is mandatory requirement in Europe). That means the event horizon is significantly longer.
Except Simoan, that the Government backstop protection on customer deposits means that retail depositors are generally no long skittish.
I think we all know that what people say they'll do, and what they actually do given the chance of their money being locked up for a period are two completely different things. I've read enough behavioural economics books to understand that what you wish for is unlikely to occur and a bank run is likely in the worst case scenario, particularly once word goes viral on social media. Or do you think assurances from the government will stop it given the low esteem in which politicians are held these days? :-)
No-one has to invest in a bank. It's all about risk and reward and all I'm pointing out is that the risk is higher than for other banks for a number of reasons, and so perhaps the valuation of OSB is not as cheap as it first appears.
Hi Yiannos,
Of course what people are missing with Osb (LON:OSB) though is that they only lend against collateral. In this case property, and the LTV is just 66%. There is a huge coverage there - even if we apply a 10% haircut for quick sales when did property asset prices last fall 24%?
The other banks all lend both unsecured and secured so impairment ratios are different.
Exactly David!
OSB loans money to buy-to-let landlords. They don't default. And if they do, it's secured on the property. That's the bull case on the shares in a nutshell.
P.
Is anyone else feeling suspicious about last week's events at Advanced Medical Solutions (LON:AMS)? A vague report on Sky Business News about a possible bid from private equity literally on the day before interim results. Then after ok (but not earth shattering figures) a couple of very large trades go through at 252p before the price suddenly drops 10% in two days to 225p. Call me a cynic, but I am not believing those conveniently placed bid rumours.
B.P. Marsh & Partners (LON:BPM) BPM.L - Positive net debt, FCF growing year on year for 3 years. Smooth chart 45 degrees angle upwards for last 5 years. 95 stock rating, super stock , 7 screens passed, buying back shares , revenues increased 58% to £51.1M. Net income increased 78% to £42.5M. A cash cow under the radar... results oct 15th.. going to put 30 to 40 bags of sand in this one - rocket ship.
Agreed. Seems to be ready for abigmove upward. Imho.
Paul,
Thanks for taking the time to record and upload your vid for "screening for small cap bargains", unfortunately I cannot get it to play and i noticed another potential viewer couldnt either. Is there another channel that you could try?
TIA
Try on mobile my old pc so slow it's the two screen moving that slows it down
davidallen77,
Looks like that has worked. Appreciated, thanks.
Live at 9.30am on Monday's Vox Markets Exchange (23rd Sept), I will be interviewing accomplished UK smallcap fund manager William Tamworth of Artemis.
It's sure to be another insightful conversation - including lots of compelling stock ideas such as #BKS, #ALPH, #APH, #GBG, #GLE, #MOON, #W7L, #SRP, #FUTR, #NCC, #MONY & #HAT. Alongside a smattering of edgier plays like #AOTI & #NFG.
If you'd like to ask any questions, then please feel free join us here on Youtube. Everyone is welcome.
Your Video was brilliant Paul really helpful and will save me a lot of time when researching shares thank you
Great video on screening for potential bargains Paul, thank you! I smiled at your phrasing of Tristel (LON:TSTL) being on 'mid-season sale'. A throwback to your Pilot days perhaps.
Bit of a bombshell (see below link) dropped last night in the construction industry, after the UK's 6th largest contractor, ISG (£2bn+ sales) filed for bankruptcy.
In turn impacting its public (prisons, HMRC) & private (Google, data centres) customers, 3,000 employees and 100s of suppliers – albeit the difficulties have been flagged for sometime.
Nonetheless this is the biggest blow-up since Carillion in Jan'18 (£6bn+ debts) and once again raises fundamental questions about the contractor business model.
The sector is still super competitive - generating wafer thin margins that provide little wiggle room in the event things go wrong.
https://www.constructionnews.co.uk/financial/administrations/isg-uk-subsidiaries-apply-for-administration-19-09-2024/
Work in the industry, rumours this was coming for a couple months.
Beck interiors is another contractor who has recently gone into administration, only a 10th of the size of ISG revenue but was still a well established contractor
Lots of architecture practices also making redundancies in London, seems like people just aren't looking to start new projects,
Bit of a bombshell (see below link) dropped last night in the construction industry, after the UK's 6th largest contractor, ISG (£2bn+ sales) filed for bankruptcy.
Of course, ISG was listed until 2016 when it was taken private. I remember it well because the balance sheet looked a lot like Carillion’s at the time and the share price followed Carillion south and stayed there. I imagine the balance sheet has always been ropey even in private ownership so not too much of a surprise that a period of higher interest rates has caused its demise.
I have no idea why people invest in these low margin, lumpy government contract type companies. The less your investments depend on the actions of the UK government the better is my general rule.
Enjoying all the ideas today, looks like there's plenty to look at and DYOR. Thanks to all who are suggesting.
I thought I would add to the fun. A few days ago I noticed one of those fintwit challenges, except it was over at Bluesky, where there is a small but growing number of smallcappers and other (some former) fintwitters.
The challenge was "what’s the smallest (market cap) profitable firm on London markets you know of? Ignore any pre-revenue pharma or explorers, actual makes profit after tax, no dodgy adjustments etc. Even better if they pay dividends".
I thought for a bit and then realised I might have good selection in my p/f. So I stopped watching Hit & Run on Netflix (highly recommended!) and responded...
Profitable / Growing / Divi paying / share buyback / net cash
Mkt Cap £8.4m. EV £5.6m - that's nano for you.
Stockrank 92. TechnologyAdventurous / Micro Cap / Neutral
HY results due "on or around 26 Sept" - next week!
Latest (AGM TA) "buoyant / ahead / comfortable with expectations. Margins "healthy".
Iliquid. :(
Share count - same for years. :)
Ladies and Gentlemen - Touchstar (LON:TST).
DYOR! Have a good weekend!
Mark
@Fonix should also be on your list Paul, they reported gross profit & earnings ahead of expectations in a TU dated 22/07 and shares traded at 260p, they've since fallen back 10% ahead of reporting next Tuesday.
They also announced an exciting partnership with JustGiving a couple of days ago; https://www.fonix.com/blog/fon...
Shares are flat YTD, which seems anomalous in light of their trading
will the massive drop in EV sales not effect volex VLX
Volex (LON:VLX) has already reported weakness in EV sales over the last year or so. However, EV makes up about 15% of revenues, and other areas are growing strongly to more than offset this. Not too concerned at this stage but something to keep an eye on.
Your comment got me thinking about the global demand for EVs, here is what chatgpt had to say:
Global electric vehicle (EV) sales in 2024 are expected to continue their strong growth trajectory, with projections indicating that over 17 million EVs will be sold by the end of the year. This marks a more than 20% increase compared to 2023.
Emerging markets are also seeing rapid growth in EV sales. For instance, countries like India, Vietnam, and Brazil are experiencing significant increases, with some markets seeing growth rates of 50% or higher.
This global surge is supported by improving infrastructure, including a 40% increase in public charging stations in 2023, especially in fast-charging capabilities, which are crucial to support EV expansion
The massive drop in EV sales seems to be mainly concentrated in the UK, largely thanks to an extraordinary mis-information campaign led largely by the Daily Telegraph. Our local electric car dealer, who we bought our Renault Zoe from, says it's had a big effect on his sales - though we prices now really depressed, it would be a great time to buy a 2nd hand EV.
Worldwide, however, the trend is strongly upwards, with nearly 1 in 5 cars sold in 2023 being electric, 60% of these being in China, which is pushing strongly on these (also leading world in installing chargers etc).
Norway have reached tipping point already with BEVs, consistently 90% market share of new vehicles. They had the same campaign of the grid can't cope, batteries don't last long, EVs are just as bad for the environment etc
I think this FUD is just delaying the inevitable not having a long lasting effect, we will follow suit. At the end of the day EVs just make more sense. But don't say that to Cockney Rebel :)
Tesla (NSQ:TSLA) is my largest holding btw
Yes, CR has a real bee in his bonnet about EVs! Seems such an odd thing to get cross about.
Norway has a much higher GDP per capita than Uk and ironically due to being a petrostate, so majority can afford high innitial costs, also electricity to run EVs is very cheap with generation from hydro. Perfect combination that accounts for 90% share in market. Sorry for politics.
Are China still building hundreds of coal powered generating stations to power the EVs?
Volex (LON:VLX)
Reference EVs. The following is the AGM statement from Volex of 1st August
Continued trading momentum
The Group's trading performance in the first quarter of FY2025 has remained in line with management's expectations with the positive momentum outlined at the Group's FY2024 results continuing into the new financial year.
As anticipated, the Group has delivered an encouraging start to the new financial year with year-on-year constant currency organic revenue growth of 9.0% driven by particularly strong performances in the EV and Data Centre sectors. Murat Ticaret is trading well year to date in its first full year of ownership, supplementing strong year-on-year organic growth in the Off-Highway market.
Investing for growth
The Group has continued to make targeted capital and operational investments to enhance capacity and capability in key locations. This includes the completion of the site expansions in Mexico, India and Indonesia, with further expansion in Türkiye due to complete in the coming months. This additional capacity allows the Group to support a range of customers who are reconfiguring their supply chains to localise production and mitigate risk.
Outlook
The Group's encouraging performance in the first quarter, combined with the ongoing investment plans, improving market backdrop in key sectors and continued integration of Murat Ticaret, gives the Board confidence in Volex's ability to make further progress against its strategy during the year and deliver on its expectations.
China stopped approving new coal power stations last year, at the same investing $546 million in renewable energy sources, including wind and solar, far more than any other country. This year, I think the number is even higher. Most of the existing approved coal stations won't get built - there are issues with over-capacity and competition from, yes, the renewable electricity sources.
So, short answer to your question, "No".
Electric car sales are falling in Europe too. I don’t think the Daily Telegraph can be blamed for those falls! Only 92,627 electric cars were registered in the EU in August. That’s down 44% compared with August last year. The drop was a “spectacular” 69% in Germany.
https://www.reuters.com/busine...
Well, whoever is driving the anti-EV articles in the DT may well be funding similar editorial stances in Germany and beyond - but I'm afraid I'm not familiar with EU equivalents of the DT!
I do know that the DT scare-mongering attacks on EVs are simply not based on fact, which is a bit depressing. Buy an EV or don't buy an EV, but at least do it based on the evidence.
I know Musk is marmite and I sound like a conspiracy theorist but Reuters have produced pretty much a daily article about why Tesla won't survive and EVs are not the answer. They are as good as sponsored by big oil.
I'm not saying what they print is always false, but it always follows their narrative that EVs are either bad, or won't survive anyway.
I think there will be a paradigm change in the next 5 years anyway, ICE's are on their way out for the mainstream.
I think the issue is not whether EVs will continue to sell, but more whether Tesla will survive regardless of the EV market. A lot of hopes (or dreams?) of Tesla followers seem pinned on the upcoming robotaxi unveil. Obviously this hasn't been revealed, but I saw a Waymo yesterday, with all its appendages of LiDar etc, got me thinking how can Tesla do the same with just regular cameras, with little or no depth perception? I'm no expert on this, but logic tells me it can't. And besides, how many people want to travel in a driverless taxi?
Besides all this, Tesla faces a number of uphill battles: if the Democrats win in November, potentially a significant source of Tesla revenue could be at risk if tax credits are reviewed, and carbon credits (which Tesla made $1.8bn from last year) also.
And then you have numerous investigations into Tesla itself - NTSB & self driving claims, potential securities fraud and so on.
I'm trying to look objectively at Tesla, maybe that's what Reuters is trying also.
Indeed, only time will tell on Tesla (NSQ:TSLA) Cisk.
Couple of points though. Back to base principles If humans can drive on pure vision then so can AI, but 8 cameras are better than two, faster, more responsive. AI will be much safer than humans, it already is.
Lidar is too expensive and impractical, mobile eye have just discounted it, a full year after Tesla did
Elon and his companies will always attract a lot of hate and volatility, certainly not for everyone, maybe one for the dreamers
as Charlie Munger said
"Tesla has made some real contributions to civilization. Elon Musk has done some good things that others couldn’t do. But I would never buy it, and I would never sell it short.”
Roll on 10/10
I reckon the massive drop in EV sales will probably hit Vertu Motors (LON:VTU) more, thus the reason I dumped my holding yesterday for a small loss.
Chairmen selling
Chairmen blaming EV sales and the Govt obsession with penalising the car industry for cars not everyone wants or can afford.
20% drop from recent high.
Haven't seen Paul's video yet but I see it made his list, I will watch the price with interest if it goes sub 55p
Dalata Hotel (LON:DAL) (I hold) Helikon Investments Limited have increased their holding to just under 8.2%. Helikon say they are medium to long term investors who discuss with management to ensure that the value are aligned with this time horizon. I like DAL, they are expanding the number of hotels they have in a controlled fashion. with a mix of fully owned and leased hotels.
I also own Dalata Hotel (LON:DAL) and was actually talking to an industry expert earlier in the week who was very complimentary on them.
Another thing we were discussing was the pushback a lot of cities are starting to do on Airbnb (NSQ:ABNB) which could positively impact Hotels longer term. Some are looking to expend their Aparthotel offerings to meet this demand.
Spot on Paul,elementary errors from the new government determined to take cheap shots at the previous government,they need to learn quickly having left this two month vacuum to the budget and realise people are going to put off big decisions like buying a house and reign in spending until 30th October.What a shame they lack common sense
Quite a good summary by Dr Mohamed A. El-Erian (on the R4 Today prog this AM) about the economic situation but Labour comms was dreadful for months before they gained power and has got worse since
Its like a football manager criticising another team, then becoming their manager and faring even worse, whilst still criticising the previous manager and paying more for strikers who've have never scored a goal, and don't turn up for training.
It doesn't work as a credible strategy, just sounds like poor excuses and poor management.
Hope I've tortured that analogy enough! :-)
Good analogy.
Sounds like when Brian Clough went to Leeds from Derby.
Didn't end well, he lasted 44 days.
Lessons there for the PM and his Chancellor
New Brian Clough docu started today on iPlayer.
Spoken like a very long suffering football fan …..:))
When I read this it reminds of my team. Still it can only get better
Paul
Thanks for your list of ideas for research.
Your first once is Mortgage Advice Bureau (Holdings) (LON:MAB1), which I agree is an interesting set up.
It issued an H1 TU on 25.7 saying trading was in line with a modest pick up in activity expected in H2. The shares closed at 900p that day.
Subsequent housing and mortgage data and updates from e.g. TPFG (which owns some MAB1 franchisees following its BLV acquisition) and (on Wednesday) LSL suggest the modest pick MAB1 expect will indeed come through with more growth in FY25.
But at 580p MAB1 is down 36% from its most recent TU, with interims due on Tuesday 24.9.
There may be some CGT selling. But the main fall has been since the FCA published draft TOR for pure protection products on 28.8. At para 3.2 FCA says it will look at loaded commissions and whether they distort adviser incentives or affect fair value. MAB1 uses loaded commissions.
I would never underestimate the FCA and the power of its broad brush consumer duty (as CBG and SUS holders will attest), but since MAB1 charges a flat fee (typically 0.3% of sum borrowed), its incentive IMO is to recommend the best deal (not the one with the highest commission) and £750 fee on £250k advance seems IMO fair value to take details, review all the options, help with the mortgage application process and take the risk that the transaction never occurs. Peers like QLT have not fallen in line.
Thanks Alistair
I had appreciated the CGT impact but had not known about the FCA involvement. Like a lot of things with headline impacts baby and bathwater spring to mind, not for the first time.
Briefly reading the TOR from FCA it's about pure protection products sold through intermediaries like Mortgage Advice Bureau (Holdings) (LON:MAB1) .
Do you have any data on what this is worth to Mortgage Advice Bureau (Holdings) (LON:MAB1) on a yearly basis?
The FCA's proposed terms of reference (relevant to Mortgage Advice Bureau (Holdings) (LON:MAB1) and others) is at fca.org.uk/publication/market-studies/ms24-1-1.pdf with a summary of the concerns at para. 3.2.
The MAB1 AR23 says on p. 7 that 39% of revenue was from insurance commissions, some of which is presumably MAB1's share of the loaded commissions charged by franchisees.
Mortgage Advice Bureau (Holdings) (LON:MAB1) This explains their historic response
https://www.ftadviser.com/prot...
I make no comment as to whether loaded premiums are justified by the additional costs of training
Just a word for Volution (LON:FAN, which I seem to highlight every time there’s an update. Today sees a healthily earnings-accretive acquisition that greatly strengthens the company’s position in Australia and sees shares enthusiastically bid. From time to time I think about trimming my now sizeable position. Keep your fingers off that button BnB! At least for the time being.
Card Factory (LON:CARD) raised to buy at UBS this morning. I know a lot of us hold,
Card Factory (LON:CARD) Thanks Feta, i was wondering why the big jump today. Hopefully we'll have a debt free company when they report on Tues 24 Sep and a Special Divi announcement for Nov 24. Wishful thinking, but not beyond the realms of possibility.
Hi Feta, I guess that accounts for the spike in the share price? Results next Tuesday, hopefully UBS's faith is justified.
Funny how often institutions are behind the curve and it takes over a 30% rise in the share price for them to decide its time to buy, when the shares were available at less than 100p some 3 months ago and could have been picked up for around 115p just after Telios exited.
Ho-hum.
As you say there are several on Stockopedia who hold the shares, myself included. Hopefully Tuesday brings positive results and a reasonable dividend.
Surely it's obvious that they let their clients & contacts load up first, then publish the buy recommendation?
That's would be a criminal offence!
Thanks Feta, broker upgrades are not normally things I notice
Thanks Feta for posting this, helps explain today's advance. In addition, I just noticed on Cockney Rebel X, that he says the UBS price target is 180p, 30pc higher than SP of 138.6p as I type this.
Paul, as it looks like a quiet day for news, I would welcome your comments on Kooth (LON:KOO) results that were out on Tuesday. They have now turned profitable and AAR is up by 181% to £60m. I have held this share for some time as it helps to address an enormous ongoing need and I am aware of a number of children/young adults struggling in this area. There was a presentation on the investor meet company website on Tuesday.
Hi shopping365,
I just had a quick look, and the H1 figures from Kooth (LON:KOO) look interesting thanks for flagging! As you say, it is now profitable (genuine profit too, in my view). Almost all based on one contract though, so that's the risk isn't it. Capitalising a lot of costs, but it's still genuinely cash generative despite that.
It does look interesting actually, now promise has turned into hard numbers. I can't find any broker research.
My initial view? AMBER/GREEN I'd say - you could be onto something with this one.
Regards, Paul.
Hi PAUL , ARE YOU NOT IN POS ANYMORE ?
Quite the opposite mate, he went over 3% of the company yesterday
ok thanks !
Hi Paul,
Many thanks for sharing your list! I noticed that the Gulf Marine Services (LON:GMS) is no longer HOLD for you, but on the 4th September it was I think. Any specific reasons why you decided to sell it you could share with us? It has been on my watchlist for some time.
Many thanks
Hi TGP20,
Just checked and sorry yes I do have a very small "placeholder" position in Gulf Marine Services (LON:GMS) - where I left a few on my account as a reminder to buy more when funds permit. So technically yes I do own some, but not very many. I'll edit the article above, as strictly it is an existing holding. I'd like to buy more, but no spare cash.
Regards, Paul.
Thanks for the bargain list Paul.
One I would add is Billington Holdings (LON:BILN) which reported earlier in the week. I am talking my own book but I do think it looks like an interesting company at the moment as:
The only reasons I can think of for lack of share price action this week is either the market was pricing in a beat (but at a p/e of 8.8 I can't see that's the case) or some people were thrown off by H1 results being slightly down on last year - last year's H1 was a very strong comparator and if it's performing this well at the bottom of the cycle then imagine where it will get to when the construction market improves.
I actually messaged Plexus Holdings (LON:POS) yesterday morning asking when shareholders would get an update on commercial activities- since it has been over 6 months - no reply of course
SDG - sanderson design group
Not good right now and CEO lisa montague is looking mightily exposed .
Seems a good tailwind leader with her happy clappy right on bullshit initiatives , which incidentally most self respecting companies take forgranted
She is very clearly a snowflake leader not a commercial CEO ready to lead and make tough decisions .
Such a pity SDG is a hidden gem but its run for the benefit of directors and employees not shareholders .
Will probably always breakeven and has the luxury of willism morris archive but Im finding it more and more of a total fugazzi sham of a company .
The red line is crossed with the renumeration committee laughable , offensive , ridiculous , pathetic, weak handling (outlined below) of bonuses awarded to very well paid executives despite missing targets by a country mile due to “headwinds”.
If there had been tailwinds would they have revised targets upwards ?
Heads we win
Tails we win .
This is one of my favourite shares and a deep value play that will rise with tailwinds but it is now moved to the garbage bin category of a company i cant abide due .
“For the 2021 award, the Remuneration Committee assessed performance against the underpin conditions up
to 31 January 2024. Despite a robust performance over the period, particularly the relative Total Shareholder
Return as shown in the adjacent column, the underpin performance criteria were not met in full. Whilst the
sustainability underpin was met with continued reduction in carbon emissions, retention of Planet Mark
certification and no environmental, social or governance issues occurring to potentially incur reputational
damage, the free cash flow and profit underpins fell short of their criteria. Despite there being free cash
generation of £6.9m over three years, the outcome fell short of the underpin target, and adjusted underlying
profit before tax at £12.2m in FY2024 fell short of the underpin of £21.2m. Both financial underpins were set
before the significant economic headwinds which impacted the last two years of the measurement period.
The Committee reflected on the outcomes, taking into account the stretching nature of the underpins and
the significant progress which the Company has achieved over the last three years, including the strong
performance in Total Shareholder Return, and determined that a scale-back of 34% of maximum would be
appropriate, resulting in final award size of 66% of maximum for the Executive Directors.
You read that properly? Directors missed their targets by a mile, still get a 66% award lol. Same for 2020 RSP awards.”
Haha. The snappy assessment had me laughing. Thanks.
Wow! Back to 2020 by the looks of things, would sell now if I held Sanderson Design (LON:SDG) . Must go and have a closer look at Dr Martens (LON:DOCS) now which unfortunately I do hold.
I completely agree about Sanderson Design (LON:SDG) , planetx. It is scandalous behaviour to set management incentives at a certain level and then still pay most of them for achieving way less. Institutional investors have a job to do here in voting such shenanigans down but they rarely make a stand. Mind you, if you want to see a more extreme example of this abuse take a look at Playtech (LON:PTEC) . They achieve a decent price for selling Snaitech and award themselves a 100m euro bonus pot! Of course, they would have volunteered for a large pay cut if the acquisition had failed!!!
Don't hold back planetx. We bought a few more Sanderson Design two days ago, living in hope again! I noticed it was on Maynard Paton's recent screen in the search for his next long term winner, along with Castings and Wynnstay. In depth analysis of Castings followed, recognising the quality but didn't make his buy list.
I wonder if the regulatory related guff that goes into preparing statutory accounts nowadays becomes a major source of distraction for SME Directors, and particularly for the type of Directors that Planetx identifies. Personally I leaf past pages and pages of stuff to get to the nub of what is of interest to me. Ironically most of it is a waste of resources.
This is very good news for investment trusts on the LSE. https://citywire.com/investmen...
"The investment company sector is celebrating a regulatory breakthrough after the Labour government announced it would scrap flawed cost-disclosure rules that have helped blight the sector for over two years."
Why was this not done with last lot about time
Too busy partying!
My morning smallcap tweet: BS gushers plugged & abandoned
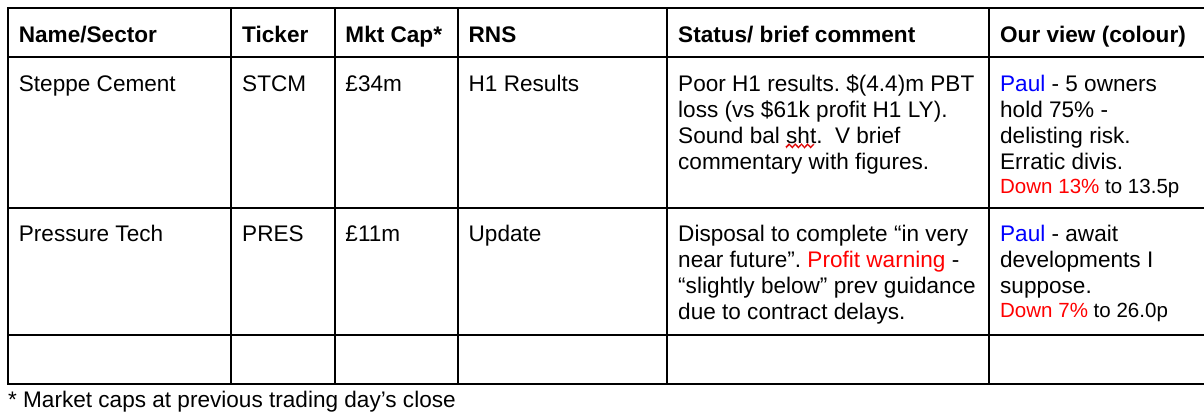
Pressure Technologies (LON:PRES) Concurrent Technologies (LON:CNC) Biome Technologies (LON:BIOM) Catenai (LON:CTAI) Eco Buildings (LON:ECOB), Iofina (LON:IOF)
◄Pressure Technologies (PRES)► the delayed dale of Precision Machined Components Division to complete in the very near future. Warns FY24 slightly below previous guidance (of EBITDA £1m+) due to later than anticipated defence order placement and project delays in Chesterfield Special Cylinders. [SP=28 Cap=11m]
◄Concurrent Technologies (CNC)► will now be branded as Concurrent. COE trills "This rebrand is not just about our evolved name and a new logo; it's about redefining our purpose and what we stand for. Our new brand and broader marketing efforts reflect our modern and ambitious culture, and act as a testament to our innovation, reliability, and exceptional service. It emphasises the expertise and dedication of Concurrent's incredible team, and our commitment to making our people the centrepiece of our story."
As Alan Sugar would say "Do you think I was born yesterday? What a load of old bollocks." [SP=117 Cap=100m]
◄Biome Technologies (BIOM)► H1-June. Further delay to a coffee pod certification likely to introduce some delay in the customer's sales campaigns and slow down revenue uptake in 2024 Q4. [SP=6.23 Cap=3m]
◄Catenai (CTAI)► H1-June rev £125k and £13k loss. Co "may need to raise further capital in the future through equity or alternative financing agreements." [SP=0.18 Cap=1m]
◄Eco Buildings (ECOB)► wins several orders. Expects to receive over €1m of rev from now to end Dec. [SP=10.05 Cap=8m]
In line: IOF
Superb comments on Concurrent! I concur 100%. What a load of absolute twaddle bollocks!
At Last!! Mr C is saying it how it really is.
Straight out of the late night shopping channel lexicon. Embarrassing!
Re Concurrent, 16 major design wins over the last 18 months is the opposite of old bollocks & would have Sugar salivating at the prospect of the revenue & profitability growth which will arrive from FY26 onwards. They've also doubled revenue over the last 2 years...
Just looking at major share holders at Plexus Holdings (LON:POS) . I can’t see Paul on the register at 3%. There are a few at below 3% in the top 10 holders. Am I missing something?
Plexus Holdings (LON:POS) are they insiders so have to declare? Paul only just went over 3% so Stocko hasn't updated yet
You can access yesterday’s RNS disclosing PS’s holding via Stockopedia >>>> https://newsfile.refinitiv.com...
Thank you New Investor. I note the last update on Plexus Holdings (LON:POS) share holding on Stockopedia was 2023. So maybe Stockopedia is a little slow in its updates.
As a share holder I am also slightly concerned with the lack of news flow from Plexus. I would have hoped for some contract win announcements by now. Maybe that will all come in the November RNS.
Hi Dairy Farmer,
I'm not surprised you're concerned with the lack of newsflow at Plexus Holdings (LON:POS) [I hold]. Me too. It's been a full 6 months since they updated the market on how it's trading. I've made it clear to old and new management that I think this is poor - public companies should be much more engaged, and give their small shareholders and the market much more regular updates, even if it's only to say they're trading in line.
New mgt are settling in, and we should be getting an update in the not-too-distant future, but I can't find any dates on their investor relations website.
My view is unchanged, that it has a big commercial opportunity, secured the biggest ever contract in 2023, and that industry factors re methane leaks are playing to their core strength. However, success or failure will depend on a small number of large contracts being achieved, which is completely unknowable at this stage. So definitely speculative. But outsized reward if more deals are secured. The tech is long-term proven, and the IP is valuable, as evidenced by the Schlumberger deal at end 2023. I'm also hoping that the previously announced customer-funded product development could lead to firm orders, which is the logical next step. Cash should be OK for the time being, but we need updated figures asap.
Definitely not for widows or orphans, but I like a riskier punt every now and then. Why not? It's my money, so I can do what I like with it.
Regards, Paul.
It has a bit of a Paul Scott boost today!
Plexus Holdings (LON:POS)
Worth noting Plexus Holdings (LON:POS) is only up 4% on the week, even though it's up 18% so far today.. Swings and roundabouts
Hey Paul, maybe you should buy some more and get up to about 20%, then take a seat on the board and get those rns’s pumped out.
I remember when an old mate of David Stredder who was an active share board commenter went onto the board of a company. I think his commentary name was Alice in Wonderland. If my memory is correct, the company got into serious problems, and it was not a good outcome for him.
Humility in all things!
Probably very wise.
Hi Trident,
Yes I remember that, it was actually a terrible thing. The poor chap who tried to help other investors by joining the board of some dodgy company, was misled by the Dirs, and the company then went bust or similar, and he had a breakdown over it I think. Such a shame, as it wasn't his fault, but he felt he had let everyone down, and just disappeared. Hopefully he got over it, but never should have felt those feelings of shame and guilt in the first place, as it wasn't his fault. The rest of our community should have supported him better, but I wasn't really involved in it, so didn't know what was going on until much later.
P.
Is the Stocko forecast for Plexus correct - it's on a current year PE of 2.99? Thanks
Dairy Farmer...you are not the only one who is a tad concerned by lack of newsflow, as although my holding is not as large as Paul Scott;s, is my largest holding. However, I am still content and not considering selling as the sp drop has largely been as a result of people getting bored and moving on. As I write, I note the sp has now climbed 18%, so GLA and once we double, we can all meet up at Paul's fav Wetherspoons in Bournemeouth!
Far better to meet at Spoons in Poole. On the Quay and you can have a nice beer or three on the terrace overlooking the bay :)
Looking at the Sunseekers we can’t afford!
Is lack of news flow because something afoot.
Schlumberger NV (NYQ:SLB), our own Ashtead Technology Holdings (LON:AT.) or Equinor ASA (NYQ:EQNR) plus STO and OSL, Reach Subsea ASA (OSL:REACH) also STO into Remote Operator Vehicles (Deep Sea Divers worth their salt). Or whomever did the Nord Stream Pipeline - but suspect they are not listed.
For Schlumberger NV (NYQ:SLB) it will be less than their staff coffee machine bill.
I'd also spotted that same on Plexus Holdings (LON:POS) and was wondering how often the Stocko algorithms update this data.
TBH some of the smaller holders really shouldn't be on there - if they are then my small holding should also be reportable, which clearly its not. Anyone know why such small holders/holdings are reportable. There are 4 people with holdings of less than 25k shares and 0.002% of the company - these holdings are worth less than £3k each.
Mkt cap is £10.7m so a 3% reportable holding should be some £300k+
Good luck to Paul - I hope it goes well. My holding is purely fun money.
Plexus Holdings (LON:POS)
Major shareholders include some below 3% - where are you seeing this? All I can get on Stocko is:
At least the company itself is bang up to date:
https://www.plexusplc.com/shar...
Hi share,
If you use the Stocko link it looks like this;
#wzl director selling £500k of options immediately; not great confidence tbh and reason why it sold off so much
Assuming your talking about Warpaint London (LON:W7L) ? If so, does anything else highlight more that potentially a lot of these director selling is to do with fear of CGT?
Unless they see something far down the road, as they are selling into another positive set of results
For memory the last time they sold down was immediately before more positive news flow and they also at that time gave a 12 month lock-in commitment
Warpaint London (LON:W7L)
Subject to PAYE not CGT. People exercising options are immediatly liable to PAYE.
Recent sales by executive directors have been to pay the PAYE tax on vesting share awards. Two by the founders in May (at 450p) would have incurred CGT, as would the latest (smaller) one by a Non-exec.
Director selling is a bad sign if after the directors have sold the share price plummets. In the case of Warpaint London (LON:W7L) two directors sold at 485p immediately after exercising their options. The share price subsequently went over 600p, so this was not a warning sign.
Well Paul. You've only gone and done it i.e. broken through the 3% on Plexus Holdings (LON:POS) . Most viewed share on Stocko today! Really hoping this works out big for you.
Thanks Peter T, there's no disputing that Plexus Holdings (LON:POS) is highly speculative, and riskier than most things we talk about here. So I don't want people to blindly follow me on this, in case it goes wrong. We've had a news blackout for 6 months, which I've complained about to the new Board. They've said they're happy to engage with me & other shareholders once the closed period has ended, with publication of FY 6/2024 Annual Report due in the not too distant future. Hopefully earlier than end Nov last year.
Definitely not for widows or orphans, and I confirm I obviously don't have any inside information. I've got all my info from the RNS, and broker notes.
Regards, Paul.