Small Cap Value Report (Fri 21 Jul 2023) - DPP, THRU, DWF

Good morning from Paul. Sorry, overslept this morning, I must be on Central European time: 8am is 7am.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Paul’s Section:
DP Poland (LON:DPP)
Unch at 7.7p (£55m) - H1 Trading Update - Paul - RED
DP Poland, the operator of pizza stores and restaurants across Poland and Croatia, announces a trading update for first half of 2023.
This company has the Dominos Pizza franchise for Poland (114 stores) and Croatia - the latter being a startup with only 4 stores. I'm not keen on companies that have to pay a third party to use their brand.
DPP has been listed since 2010, and has never made a profit. It’s been propped up with numerous equity fundraisings, and now has over 712m shares in issue. It’s always looked an absolute dead duck to me, but with a £55m market cap clearly there are plenty of optimists out there who think it might eventually succeed. So as always, I’ll approach it with an open mind, and look at the facts, figures, and forecasts.
Poland is the main operation. Today’s update only talks about revenues, not profitability.
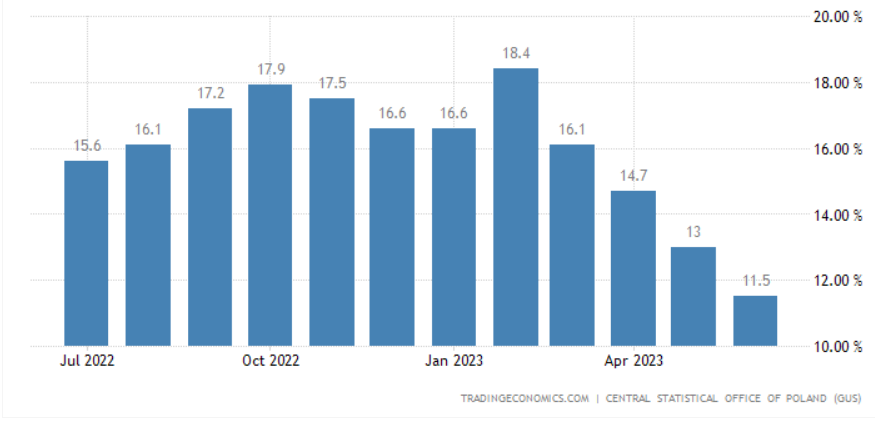
Like-for-like (i.e. excluding site openings & closures) looks very good, at +18%, being volume +11.3%, and the rest must be price increases. Trading Economics (an excellent site for macro information) says inflation is currently 11.5% in Poland, having recently come down from a figure closer to DPP’s LFL, so maybe +18% isn’t so great after all? Everything needs to be seen in the context of higher inflation, and of course its costs (especially wages) will be rising fast too.
Outlook - always sounds optimistic, which I suppose management have to be, offering jam tomorrow instead of an insufficient number of pizzas today! -
High inflation in energy and food have eventually started to abate in May, and whilst labour rates are still under inflationary pressures we are constantly focusing on further optimization projects. We expect performance to continue improving and remain optimistic about the outlook for the Group."..
Inflationary costs have begun to diminish in food and energy, however, labour inflationary pressures have remained.
Cash - has dropped from £4.1m at Dec 2022, to £2.5m at end June 2023 - starting to look tight for cash again, when’s the next placing going to be then?
My opinion - nothing is said about profit/losses, so it’s not really a trading update as such.
Singers helpfully updates us, with no change to forecasts, showing £(1.1)m adj PBT loss this year FY 12/2023, which is a big improvement on the past, when annual losses were more usually £3-4m pa.
So I conclude that DPP looks as if it’s finally making some progress. Since it has a hefty depreciation charge for store fit-outs, it should now theoretically be cash generative.
I have to say, this is the closest DPP has looked to being a viable business, in the 13 years I’ve followed it.
Is it worth £55m though? Absolutely not, the market cap is crazy given the poor track record. If you have to invest in a fast food outlet, I would say Tortilla Mexican Grill (LON:MEX) (I hold) looks far better, and is a lower market cap too.
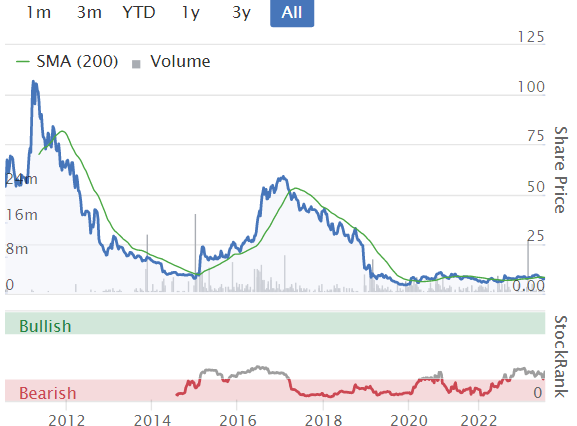
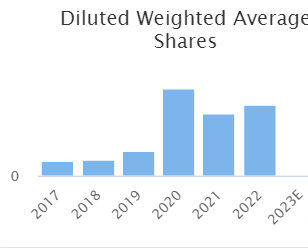
Note that the share count has risen from 142m to 712m since 2017 -
Thruvision (LON:THRU)
Down 7% to 28.5p (£42m) - FY 3/2023 Results - Paul - AMBER
Thruvision Group plc (AIM:THRU, "Thruvision" or the "Group"), the leading provider of walk-through security technology, today publishes its results for the financial year ended 31 March 2023.
This loss-making company has been on my watchlist, because the products look very interesting (similar to airport body scanners), and it has an impressive-sounding contract with US border forces. So the story is that performance could greatly improve if orders take off, and you can’t really get a better reference customer than the US border authorities.
Key numbers -
Revenue £12.4m, up an impressive 49%
Two thirds of revenue came from that big customer, US border, so horrible concentration there, making it high risk:reward.
Almost at breakeven EBITDA, a £(0.2)m loss.
Adj PBT is a loss of £(0.8)m, improved considerably from £(2.3)m last year.
Cash looks tight, £2.8m at Mar 2023, and £2.4m on 20 July 2023 (yesterday), so I imagine another placing is likely. It gives itself a clean going concern statement.
Outlook - very vague, with no specific information here - I think investors expect more than this waffle -
Having proved the value of our solutions beyond doubt, the focus of the business is now moving towards scaling as rapidly as our markets and resources will allow. We believe that our target markets are significant and should impose no foreseeable limits on our growth. Our growing sales team will focus equally on acquiring new customers, particularly in the US, and on increasing the Thruvision presence with existing customers. Meanwhile, our technology investment will ensure that we build an even greater lead over our competition.
The past year, combined with current activity levels, have reinforced our confidence that Thruvision will continue to grow well and become the solution of choice for walk-through security.
Balance sheet - NTAV is £8.7m, and includes £2.8m cash (with no borrowings). Both inventories & receivables look too high, so I’d want to see those turn into cash, which would then leave it in a satisfactory position. It might be able to escape without doing another placing, if working capital could be more tightly managed.
Paul’s opinion - quite high risk I think, due to the dependence on a single major customer. Also looks borderline in terms of cash, so there might be further dilution.
However, I remain intrigued by the product, so the next step would be to investigate its market, and what competitors are offering - is Thruvision’s technology unique and patented (good)? Or is it using generic technology (bad)?
Overall, I think this one is worth you doing some more detailed research, ideally talking to customers who have shopped around and chosen this product.
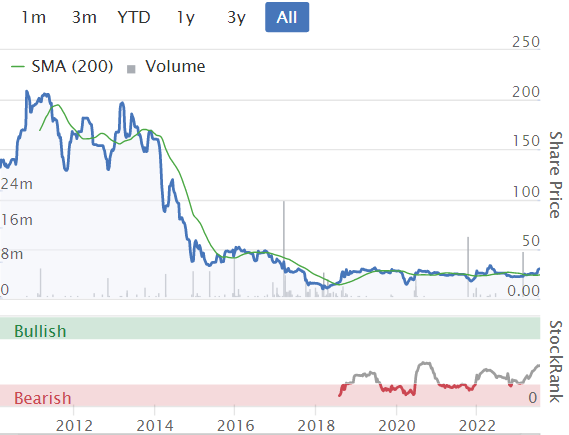
Optimists have not fared well here in the past -
DWF (LON:DWF)
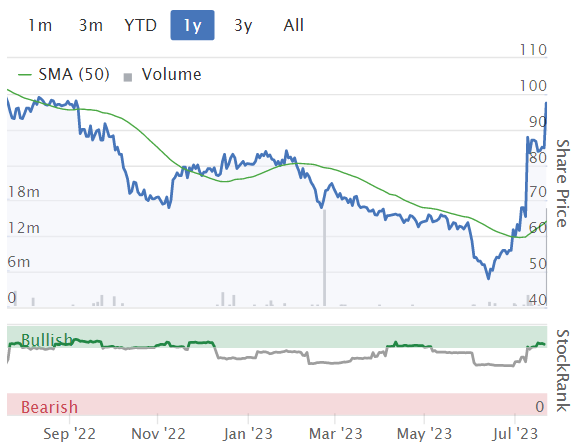
Up 15% to 97.4p (£334m) - Recommended Cash Takeover - Paul
As we reported here on 11 July, DWF announced that it was in talks with Inflexion (mid-market private equity firm) about a possible takeover, at 97p+3p dividend. At the time, the market share price only rose to 88p, so some shareholders were clearly happy to sell in the market for certainty, rather than take the deal risk - which I think makes a lot of sense, given how many deals have fallen through of late. Or maybe take a hybrid approach, selling half in the market, and holding on for the full payout for the other half?
Anyway, the good news for people who held on, is that the deal is going ahead. 100p takeover price is over double the recent low, so well done to anyway who took the risk and bought at or near the low.
Paul’s opinion - this whole sector (legal services) looks quite interesting, as valuations are really bombed out, there must be some other bargains in the sector. Also some banana skins though maybe?
This deal once again shows that the public market for small caps is undervaluing many companies compared with the private market. This is very encouraging, and makes me increasingly convinced that small caps is now the best area to be invested in, with tremendously bullish potential, once the balance of buyers and sellers turns favourable, which is only a matter of time I think. Valuations are too cheap now, so risk:reward now looks the best it has done in years, in my view.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

62 comments
My weekend podcasts are now up.
Mystery shares this week, just FYI (my best ideas that I hold back for Stockopedia readers) are -
Brickability (LON:BRCK) - very good webinar induced me to go up to GREEN (Monday)
Concurrent Technologies (LON:CNC) - very impressive update (see Monday's SCVR)
Cohort (LON:CHRT) - really impressed me, see Weds SCVR.
I hope you're enjoying the rain, it's good for the garden LOL! :-)
Also my SCVR summary spreadsheet is now fully up-to-date, for people who find it useful (if you don't then ignore).
Like many of you, I have always been hugely impressed by Chris Mills and enjoyed his Mello interview very much.
He sang the praises of React (LON:REAT) saying his fund had been buying shares.
Subsequently the share price rose and at 4.30 today the following RNS appeared saying his Oryx fund had reduced its holding:
newsfile.refinitiv.com/getnewsfile/v1/story?guid=urn:newsml:reuters.com:20230721:nRSU8539Ga&default-theme=true
Sounds like pump and dump.
I agree with that Rusty2 that's why I don't take too much notice of salesmen in suits, however plausible they come across, as they always have their own agenda, and it's never in my interest the best thing always is DYOR.
Just to be clear I have held React (LON:REAT) from when they acquired Fidelis as I know the company and potential as I am involved in the industry (not the company)
Re React (LON:REAT) and Chris Mills…
Market abuse is being implied (or least dishonourable behaviour). This is really silly perspective. I don’t hold a torch for Mills. I generally avoid listening to the great and the good (…all you Simon Thompson tip chasers annoy the f out of me!). If any fund manager talks up a holding publicly I’d assume it’s probable it’s a mature holding for them and perhaps one they are exiting (so fluffing their liquidity). Druckenmiller is the champ of this imo.
I listened to Mello on Monday as I hold React. The sequence of events were React had been on before Mills (good presentation, particularly as the wet behind the ears CEO seems to have found his voice more assuredly than ever…I think showing matured into role). David Stredder asked Mills re React as it had been on the show. Mills said that they held a non notifiable position for a while but then started buying in more meaningfully after Laddersfree related raise…and particularly as the share price went to lows. He was clear he liked the biz.
It definitely wasn’t any fevered oversell front run of a dump…overall it’s pretty close to a ‘neutral’ comment in the circumstances. What if he had said I can’t talk about React? What sort of crazy stuff would be inferred from that?
Mills has got a very large portfolio of many illiquid things to run. He’s made a nice positive return on his React investment to date. On Thursday it seems he sold down from just over 10% to just less than 9% holding in company.
From his perspective nice portfolio management as shares that spike higher normally don’t carry on like that. Simple gravity. Obvs I hope React does carry on its recent spike as as a minnow I’m more sit and hold and don’t have his liquidity creation requirements. If the spike up continues it won’t be a surprise if Mills sells a bit more…and if it falls back he may buy back. Classic big portfolio fund manager behaviour.
Is there a smoking gun here? I’d suggest it’s the tendency of many PIs to chase tips…and a vehicle like Mello that broadcasts about micro cap stocks is going to sometimes create liquidity effects. If you chase micro caps post tip or Mello etc you put yourself at risk. I love live event Mello. I’m not a fan of the Monday night event as I think it creates too much funnelled interest in tiny stocks …and I don’t like that even for things I hold as imo it can create an unhealthy liquidity and volatility binge/bulge that can lead to hangover (sometimes long lasting). There are many reasons why React became lowly valued and one of them is likely a hangover from excess promotion
Just to put the physics debate re infrared to bed (from Wikipedia):
Infrared (sometimes called infrared light and IR) is electromagnetic radiation (EMR) with wavelengths longer than those of visible light and shorter than radio waves. It is therefore invisible to the human eye. IR is generally understood to encompass wavelengths from around 1 millimeter (300 GHz) to the nominal red edge of the visible spectrum, around 700 nanometers (430 THz). IR is commonly divided between longer wavelength thermal infrared that is emitted from terrestrial sources and shorter wavelength near-infrared that is part of the solar spectrum. Longer IR wavelengths (30 μm-100 μm) are sometimes included as part of the terahertz radiation range. Almost all black-body radiation from objects near room temperature is at infrared wavelengths. As a form of electromagnetic radiation, IR propagates energy and momentum, exerts radiation pressure, and has properties corresponding to both those of a wave and of a particle, the photon.
Infra red the top debate - Quiet RNS day, markets not overly volatile. No disrespect to any contributor but Pedantry to the fore. Have a good week end all
company with zero to almost non existent revenue like ceres power, ITM and the Cryptos are getting investments when money is really tight! are we missing something?
JPMorgan had a note out saying hydrogen is pivotal for global energy transition and tipped ITM Power (LON:ITM) , Plug Power (NAQ:PLUG) and Bloom Energy (NYQ:BE) . I suspect other hydrogen plays also rose on the back of this. For transparency I own ITM Power (LON:ITM) .
Random Dialogue on Pensions Assets from someone who is a Yorkshire Farmer's Son, though chose to exit Stage Left into Construction... if that doesn't give enough of an investment caveat I am not sure what else would be required?
From my distant past I do have the honour of being part of two DB pension schemes (thanks dad for making me sign up), if they still exist when I reach retirement age I will get ~£900 per year total from them.
I got the annual update letter though this morning from one of the schemes. This is a closed scheme (waiting for everyone to die off) which is invested within Fixed Interest Corporate Bonds, GILTS and Liability Driven Investments (LDI) and Secured Finance.
Value at 31 Dec 2021 ~£1.2bn
Value at 31 Dec 2022 ~£0.8bn
The majority of that reduction is "net return on investments" so I read that as we bought this for £1 and it is currently worth 67p if we sold it today.
So whilst I do not know what this means for other companies with DB schemes and the whole actuarial valuation on a triannual basis.
I would note that whilst simplistically the raise in returns on various products is great for pensioners, what does that actually mean when the Pension Fund bought the products when the value was higher and the return was lower?
Yes you get your £1 back on maturity assuming no bankruptcy or default, but surely the rate of investment return is still based on the fact you bought for £1 not for 67p?
So if I had bought British American Tobacco (LON:BATS) at £35 the yield would be on 6.86% for 2023, not the 8.98% should I buy today at £27, or 9.60% if I had bought at £25 as a simple example.
So for these closed funds, the increase in yields is not actually a benefit as they are fully invested already?
There may be benefit is for currently open funds which are still getting deposits so buying more? Or those lifestyle funds where they automatically switch from shares to fixed income from 20 years out. But then would it not depend on the quotient of pensioners versus deferred versus active members and all the averaging?
Or should I go and shear me cows?
Cheers
Tommy
ps. I hold British American Tobacco (LON:BATS) in my Mum's ISA (aka Pension)
pps. I appreciate that this is an incredibly complex field, maybe I should have been an Actuary?
Tommy H, first of all congratulations on your £800m pension pot ;)
More seriously, an answer from a half or failed actuary ie take it with a pinch of salt as I'm no current expert (I got half way through exams and switched to the more relevant CFA Chartered Financial Analysts as I was working more on asset than liability side and second half of actuarial exams weren't 'academic' but doing things like learning how an insurance co operated and it was excruciatingly tedious for someone who is a poor student anyway)
The scheme sounds as if its 'liability matched' which means that the members neither benefit or lose from the movement in asset values...the same stream of income is going to get kicked out to fund their retirement. At the margin higher income to asset price is likely beneficial to scheme and will make the ongoing funding easier (there is never perfect matching) although that is a complex conclusion as it depends on where income levels settle in future.
For non 100% matched schemes the rise in yields eases funding and means that pension deficits have fallen. This relies on a combination of non matching assets (eg primarily equities but inc property and alternatives) not falling too far (that can be further than bond price falls but not so far that future growth can't catch up) and also having future growth potential that exceeds govt/corp bond yields
I got half way through exams and switched to the more relevant CFA
Out of the fire and into the frying pan!
Haha. It was a hot bath by comparison! Exams never enjoyable...but CFA is nowhere near as archaic and painful as later stage actuarial stuff...and if you are bad student like me then that makes the CFA much easier to cope with.
Thank you Mojomogoz
I did the Engineering Council Exams instead! They seem a lot lot better than even the CFA, three years of formal training signed off. Submit your reports and CPD. Interview, written exam (essay at that time). Done.
Tommy
Quite a lot going here Tommy.... I can say this, the difference between a DB Scheme and a DC is that you entitled to an annual pension in a DB ...and the scheme value in a DC. So you get your £900/yr. As interest rates have risen the value of that £900 has fallen. So the scheme assets can fall and your pension stays the same. You have to measure the assets ( investments ) Vs the liabilities ( pension commitments). IF you were planning on exiting theDB scheme now is probably not a great a time. For a DC scheme it's the other way round... so you have a pool of assets and they are worth X. They will buy you an annual pension - an annuity. Annuity rates benefit massively from rising interest rates...so a pension of X gets you a much better annuity now. OR an annuity of say £900 a year will cost you a lot less ....
The whole idea of liability matching ...is that the scheme assets and liabilities move as closely together as possible and are interest rate and inflation neutral.
Thank you RDHowarth
Most of my Pension is DC which I am very conversant with, I have my little pot to drink from and that is it.
It is the DB matching that was beyond me, will go back into the overall funding versus liability section of the letter this evening!
Tommy
Trying to be as concise as possible...
Closed DB funds won't hold many equities. They will be mostly invested in gilts & linkers, perhaps some corporate bonds, with a derivative overlay to modify their sensitivity to changes in expected interest rates and inflation.
The coupons from those bonds will be matched to the forecast pension payments, taking into account whatever annual inflation uplift pensioners have been promised.
The value of long-dated index-linked bonds can be hugely volatile, but the "real" (i.e. taking into account inflation) income they generate will be very stable - the "defined benefit" promised to pensioners.
So the "transfer value" of a DB pot may well have almost halved in value over the past 12 months, but the promised pension it aims to provide, after inflation, should still be the same.
The change in the values of those long gilts/linkers over the 12 month period Dec 21 to Dec 22 is what you will be seeing when the value went from 1.2 to 0.8.
So do the change in market yields over that period matter?
If the closed fund was 100% funded and perfectly hedged then no (assuming everyone still has the same forecast lifespans....called "longevity")
If the closed fund was less than 100% funded, or if the hedging was not 100% then it may move further into deficit or be in surplus. If in deficit then the sponsor of the scheme may have to top it up - it won't be pensioners bearing the cost unless the sponsor goes bust (and even then the pension lifeboat takes some of the pain).
Dear Monto Carlo
Thank you, I am not looking to transfer it is more understanding the dynamics of DB pensions and what the investment side is.
Whilst the company I worked for does not exist any more, it was sold out of what is now Taylor Wimpey (LON:TW.) into Carrillion back in the 1990's and the pension is part of Anglo American (LON:AAL) I do not know how or why just very grateful!
This is more about my understanding for investment to the dynamics and impacts of pensions on existing companies, so where this may or may not go on shortfall schemes over the coming years, as I hear a lot of yields going up is good investing in companies with shortfalls (buy less to get the income you need) so their deficit payments should be reducing at the next assessment point, but as you say there is a lot on the volatility of the underlying assets so it is never easy when taking a simple year end snap shot.
Tommy
In general you are on the right track, higher yields should mean reducing deficits.
But...in truth it is more complex than that. It is actually real yields that matter most on the liability side (the combination of interest rates and inflation). On the asset side there are also quirks - the shift from RPI to CPI for linkers, how credit spreads have moved relative to gilt/swap rates etc. Schemes may hedge less of their inflation risk than their interest rate risk so you get a range of outcomes after major shifts in markets. Schemes also vary in where they cap the inflation uplift (in fact within the same DB scheme you may find multiple tranches, as they got less generous over the years). Some schemes also shifted from final salary to career average etc etc so it is impossible to generalise. This is one reason why IFAs charge so much for DB pension transfers - there is a huge amount of analytical work to be done, not to mention the liability if the client later sues for poor advice.
There are several ways of measuring the funding status/deficit of a DB scheme - the actuarial and accounting approaches can be very different.
The Pension Regulator website is a good place to read more.
I remember this when it was a subsidiary of a lifestyle company called Digital Barriers founded by a man called Tom Black. Sold off and floated a few years ago. Black was a city favourite who made money selling a company whose name I can't remember years ago and who everybody seems to think can repeat that achievement. Meanwhile he chairs this company. Not a fan.
The product seems to work. Depending on infra-red of a certain wave-length which will show on a monitor to an operator, a colder area of a person's outer clothing if some article is hidden under the clothing.
I doubt whether they hold any patents, seems like the technology of cameras for checking the insulation of a house. That won't stop it making money but not necessarily for new investors.
Thermal imaging works on heat, IR is the part of red spectrum of light. I use IR camera fir photos, no use for checking heat leakage from my house. But yes I don't think the technology is anything special, you can buy thermal imaging cameras, quite cheaply.
Thruvision (LON:THRU)
Sorry to disagree Rusty2 "Thermal imaging works on heat, IR is the part of red spectrum of light." but that's wrong. IR is a large part of the electromagnetic radiation spectrum between microwave and visible radiation. It's the effect you feel on your skin from a radiator in your house among other things. But we are agreed nothing that can't be done by somebody else.
I'm talking about infrared cameras, they record infrared light not heat, some materials reflect it more than others, nothing to do with heat. Thermal radiation is different, that is heat not IR light. If I photograph hot water it will look the same as cold water. IR is the wavelengths above red visible light between 780 nm and 1 mm. So you think my images are based on heat?
You are talking, I think, about a camera with a built in infra red illuminator. All digital camera sensors react to near infra-red which is, on my wildlife camera filtered out during daylight, and allowed to react to the illumination at night. I was talking of infra red far from the visible spectrum. Your statement "IR is part of the red spectrum of light" is completly wrong, infra means below and in this context means a lower frequency or longer wavelength than red light and towards microwave frequency.
No, I'm talking about a camera with an IR filter which blocks out light below 820nm, you can get other filters, you can also use IR film in film cameras. They work by recording IR light.
IR illuminator, no, my camera does not emit anything, it records light in the IR spectrum. It is invisible to humans but can be recorded on sensors and film.
Most cameras has filters that remove IR, on the sensors, as it can cause problems with normal visible light images.
It is the same as your camera but just has a different filter on the sensor.
Infra red = Black heat.
a quick check found they hold a few patents, thou last one granted a good 10 yrs ago
A mention here earlier by tiswas of lists of highest % movers. Just had a look and was stunned to find Cineworld (LON:CINE) on the risers list. Just what part of ".....there will not be any recovery for holders of Cineworld's existing equity interests" do people not understand?
Last RNS saying that was 29/6:
I see that following 2 Vox Market videos, posted here by Paul Hill featuring Gervais Williams, Premier Miton continues to increase holding in I3 Energy (LON:I3E) . Yield is now 14.4%
JP Morgan are also buying more.
Roger did you see the Divi and capex cut announced last month for I3 Energy (LON:I3E) ? I believe this will bring the Divi rate down to around 8%. Still decent.
DP Poland (LON:DPP) is rather interesting now Paul, however, I would not go near it until I see how much money they spent to increase those LFL sales and what the margins look like as I believe a lot of new sales go through portals who will be taking their share.
I was in Poland recently and was struck by how nice it is. The people I was visiting were all around their mid-twenties to early thirties and were very happy there with no intention of leaving as their lives were pretty good where they were.
Poland is very different from the early 2000's when I first was sent there with work, and have been back regularly since. Amazing place and well worth visiting!
There are several good things going on in the country, young educated workforce and increasing opportunities without having to emigrate (temporarily or permanently), there are several challenging dynamics including wider unemployment levels, temporary immigration and their Eastern Border.
With regards to take out food, the demand for take out and delivery is increasing as the wealth demographic increases and the western work/life balance impacts, but is there a demand for a subsidiary of an international pizza chain over a local owned and operated pizza shop which does not have a logo but avoids the overheads? I do not see the investment moat or thesis.
I do not hold DP Poland (LON:DPP)
But one could say the same thing about Domino's Pizza (LON:DOM) with their UK stores - they couldn't have been the only pizza stores when they started in the UK, yet this "foreign brand" with "franchise overheads" is now quite dominant. Market cap £1bn+
Same with Yum China Holdings (NYQ:YUMC) - KFC, Pizza Hut, and Taco Bell weren't the only fast food outlets in their categories in China when they started, plenty of local shops and chains. Yet, now market cap $24bn+.
How would you explain these two successes then?
Fonix Mobile (LON:FNX)
Apologies but someone recently mentioned Fonix with regard to the Eurovision SC and voting being only via a dedicated App etc etc and being worried that this would affect Fonix ongoing business, but I cant find the comment to reply to.
Fonix's offering enables their customers to take payment from mobile phones from a variety of platforms including Apps.
Integrating mobile operator payments (fonix.com)
Fonix Mobile (LON:FNX) had a trading update yesterday. To find comments I find the easiest way is to go to yesterday's SCVR and put FNX in a control-f
(Another reason to include the company name/ticker as requested daily in the header but ignored by some).
I agree there are too many posts, without any ticker or mention of the which stock they are posting about.
It is easier now, you just need to put @ plus the ticker as in Fonix Mobile (LON:FNX) , even works on foreign listed stocks.
What is the rise in Hargreaves Services shares caused by
Hargreaves Services (LON:HSP) was reviewed positively by Christopher Mills of North Atlantic Smaller companies Trust (and Harwood Capital) at Mello Monday this week. The recording, available to non-attendees, was released yesterday so I suspect some people may have bought on that basis today. Cheers
That probably explains the rise in HSP, Sutters, I thought that there might be news about to surface of repatriation of profits and loans from the German associate, or even news of its potential disposal, which I believe is probably a company priority. More likely to be the Mello event effect.
Cohort plc (LON:CHRT) after record results on Wed, we have a detailed note out today on their prospects and valuation. For anyone not glued to cricket or or golf, and keen to hear very experienced insight into the global defence outlook (not just Cohort), watching the CEO and FD's webinar at 11am is recommended.
New note accessible here: https://www.equitydevelopment....
Webinar registration here: https://www.equitydevelopment....
Some excellent news from Filtronic (LON:FTC) and personally, having dumped my Portmeirion (LON:PMP) shares on Tuesday, I bought into Filtronic (LON:FTC) which I have tracked for sometime and wasn't planning on opening a position. Finally, luck has come my way, dodging the profit warning and getting a significant order this morning - I should buy a lottery ticket.
Anway, the announcement today would seem to suggest that this is the start of on ongoing order book, which I presume that will get other operators to sit up and take notice - getting into space will hopefully provide a lift off for the company!
There's been some discussion about the UK law firm Knights group (LON:KGH) . Has anybody taken a look at a similar firm called Anexo (LON:ANX) which looks similarly interesting?
Anexo (LON:ANX) I wouldn't say it's similar to Knights - Anexo is a credit hire company. Looked at it a few years ago as was very cheap, but came to the conclusion the business model was based on exploiting a legal loophole to charge very high credit hire rates on sub prime customers. There could easily be a clampdown on this so decided it wasn't for me, although I've not looked at it for a while so possible the business model may have evolved.
I guess I meant 'similar' in the sense that they're both lawyers... Good point about the regulatory risk.
As previously mentioned by Bouden54, I wouldn't class Anexo (LON:ANX) as lawyers - more like an equivalent of an ambulance chaser. As stated they are exploiting a ridiculous loophole which at some point will surely be amended. They charge out hire vehicles at up to £400 - £500 / day - and through a loophole they then recover the costs from the liable insurance company. They can only do this for what they describe as 'incumbent customers'. - ie those non fault motorists that can't afford a hire vehicle and have no alternative but to use this arrangement.
So they have built a business around this loophole, it is very strange that it has not been amended but imo there is no longevity to this business model. Also management imo are of a similar quality to the business - pretty poor. There new income stream is through making claims against landlords for housing disrepair etc. In the last interview I saw with management it sounded like this was being run almost like an intimidation racket - they send out all kinds of threatening correspondence and have no intention of fighting the cases - they seem to take the easy settlements as they come. Personally I am not going to stand up for dodgy landlords who deserve to be targeted. But the overall feel of the business to me is one of a very low grade.
The biggest problem with Anexo is that imo they make very little money. They are good at making it look as though they are very profitable with some great metrics - but none of them actually make any sense when properly analysed. For instance if you look at the revenue and net profit growth over the years - it looks like a great business. However they make no free cashflow - negative free cashflow pre share. Therefore each year they spend the profits on ensuring the revenue for the next year, and are hiding these costs from the top and bottom line. Just look at what they claim to make and then look at the debt and the free cashflow! One could argue that you could look at a metric like net fixed assets as a potential substitute for free cash flow - ie. Secure Trust Bank (STB) for instance could argue that the profits have been diverted into fixed assets. Anexo can't claim this, so where has all the profit gone over recent years? The receivables are always extremely high - and I have no idea of the reliability of this income. The book value is largely based on a falling vehicle fleet. So a growing business with a falling fleet - sounds odd! Also who knows the true value of this fleet - I certainly wouldn't take their valuation as gospel - considering the murky transparency of the numbers elsewhere - this would be a further worry.
This is all my opinion and could be wrong. Just my reading of the numbers and when I researched the company some months ago. If I am misinterpreting the way the numbers work then I would be happy to be corrected and to learn the reasons why.
cheers
Matt
Ambulance chasers are typically lawyers... and the founders are lawyers and the class-action emission suites against VW, Mercedes etc are legal cases, so I would definitely put them into the 'legal' sector...
But yes, I did wonder about the negative free cashflow. Your analysis + that from the previous responder has moved this into my too hard basket. Clearly the founders have done very nicely out of selling their own shares!
Paul, wouldn't you have been an hour ahead if you're on CET?
Anyhoo, not much on the RNS front this mornin...
Morning Planetx,
You mentioned the other day Trifast plc and , as I always do , when someone mentions a company not familiar to me , I have studied their accounts and history in detail last night and it is clear that they will hit their previous +10% operating margin in the next 2-3 years.
The future free cash flows indicate clearly that this is undervalued.
IMHO the share price can easily double from current levels and I have started adding this to my portfolio.
Thanks for the feedback .
I agree, its a business I am very comfortable with and I can only imagine how tough it was for companies like these during covid and then energy prices and freight prices through the roof.
With normalised freight, energy and correct stock management and a new management team there seems limited downside and good upside.
Seems to be clearing the 80p barrier which I have been buying around.
I plan to increase further not sure if to sit back and wait for 80p target buy price or bite the bullet at 82p.
My reduction in Somero was to rotate into trifast / filtronic which despite the comeback of Somero I still think is a good call as both Trifast / filtronic have better upside . (unless somero gets taken out at a bid premium ) .
Feeling a bit happier today with Filtronic having a good contract announcement though ideally I would be a bit higher on holding.
PS - Cracked and just bit the bullet going up to a half position (82.66/82.7), no point worrying about 2p
Have you looked at the valuation gap between Trifast and US market leader Fastenal? Close half the gap and you’ve a potential multi-bagger!
Trifast (LON:TRI) had a quick, debt looks high?
So many times planetx I have waited for pennies and missed opportunities. Trifast has a 5% spread which is more the issue I would have thought. I agree with your selection although my main issue is whether they can get profit margins back. That is not to say they won't be profitable it is more of a case of whether 10% margins are achievable in the new world. I have a small holding.
Stocko only has a spread of 145bps on Trifast (LON:TRI) , but looking at the trades, it does look much wider than that.
Yiannos1
Whenever someone predicts the future I like to test their confidence by asking what odds they would accept for a bet they will be shown to be wrong . you sound over 90% confident . Would you offer 10/1?
I don’t predict the future. I buy shares after careful examination of their accounts , the available research , and my own forward cash flow analysis. If the market price is below 30% of my understanding of where the price should have been , then I invest.
Other things being equal; I will make money on this one.
Hope that helps.
I'm in this one Trifast (LON:TRI) and have previously commented.
Like Babcock International (LON:BAB) , it is one of those shares where I've been too early into the turnaround story. I've bought more on weakness but I don't really expect a quick return.
Some points to bear in mind:
There are good points, but they have been expressed elsewhere so I won't repeat.
A lot of hard work is going on behind the scenes. It reminds me a little of Spectris (LON:SXS), one of my long-term holdings, back in the 1990s before it acquired the instrumentation businesses (then known as Fairey Group, with a complex past linked to the Fairey Swordfish). That one has required patience (I can clearly remember the management's frustration through periods where the share price refused to reflect their efforts) , and I suspect this will too.
My morning smallcap tweet: Rapid RNS reduction
Filtronic (LON:FTC) Renalytix (LON:RENX) DP Poland (LON:DPP) Samuel Heath and Sons (LON:HSM)
◄Filtronic (FTC)► €3.7 million payload development project from the European Space Agency. Included in FY24 F/C. Final hardware deliverable by Mar 2025. [SP=15.31 Cap=33m]
◄Renalytix (RENX)► distribution agreement makes kidneyintelX.dkd available in Middle East. [SP=122.23 Cap=155m]
◄DP Poland (DPP)► guides H1 LFL up 18%. Order counts up 11%. "We expect performance to continue improving and remain optimistic about the outlook." [SP=7.7 Cap=55m]
◄Samuel Heath (HSM)► FY-Mar rev up 5% but pretax £0.93m (£1.47m). "iven the uncertainties at the half year, the overall result was better than we feared might be the case, also taking into account that the previous year saw exceptional outperformance at the profit level due to what we highlighted at the time to be unsustainably low cost levels....Order book held up reasonably well during the year, but sales were held back by production difficulties caused by machinery breakdowns and labour shortages." Current trading -some weakness. [SP=462.5 Cap=12m]
A sad reflection on the current market is that the first thing I do every day is have a look at the ADVFN list of largest percentage fallers to see how many of my stocks are showing!
I love reading the comments made by, and debate among, fellow subscribers.
However, in recent days the tone and intercourse has on occasion had echoes of ADVFN with borderline shaming and insulting comments.
Sure most agree debate and disagreement on analysis of facts and personal investment opinions is healthy - the market is the aggregation of all such views - but please keep things respectful.
Nobody has a monopoly over investment insight/knowledge and nobody is right all the time otherwise nobody would subscribe as they'd be sitting on a beach somewhere.
Yes I agree completely with what you say. I have seen a marked increase in posts that wouldn't seem out of place on ADVFN or LSE recently ie more personal and negative and dare I say rude comments. Please keep the posts professional and keep up the standard of what is in my view the best small caps discussion forum around by a country mile.
Completely agree with you.