Small Cap Value Report (Fri 21 Oct 2022) - TRI, WIX, ZTF

Good morning, it's just Paul here today, as it's Friday.
CEO interview with David Stirling of Zotefoams (LON:ZTF) -
Audio version is now live here.
Here is the written summary .
We've positively covered this specialist foam manufacturer in the SCVRs seven times this year, with increasing enthusiasm for how the company is successfully passing on inflationary price rises, thus demonstrating its product is in demand. This follows years of heavy capex to revamp its factories in the UK, USA, and Poland. I reviewed the last good update from ZTF here on 13 Oct 2022 , and I'm also impressed with the balance sheet, plus the shares remain good value. So I invited the CEO to talk to me.
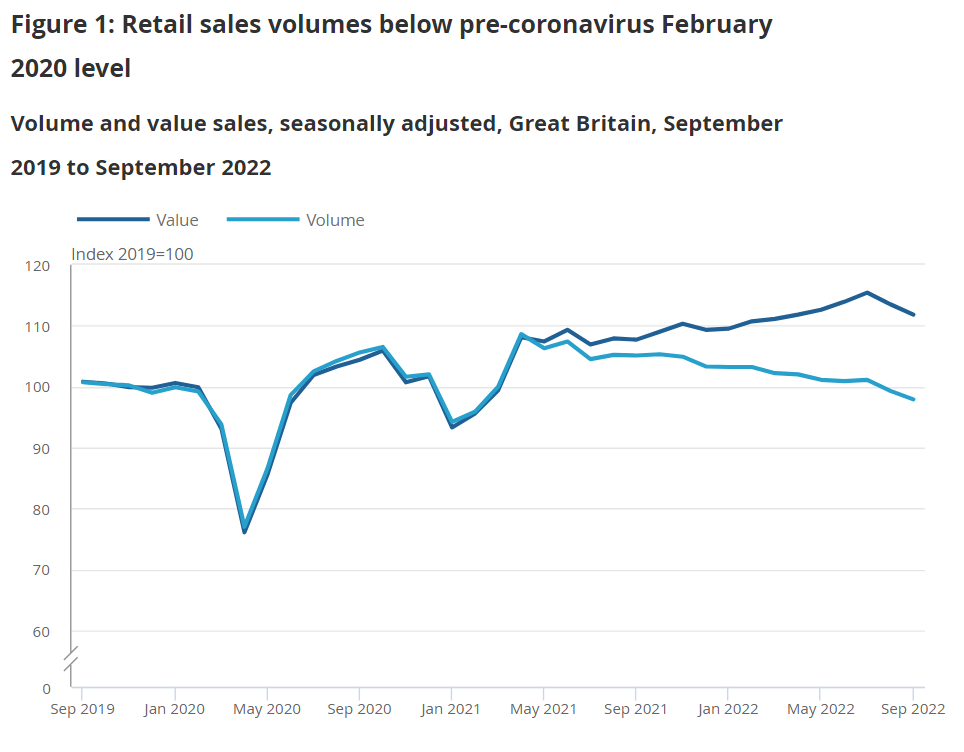
Retail sales data for September 2022 is published today by the ONS. As usual, the press are reporting it wrongly, which they always do, saying that retail sales are down. That is wrong! Volumes of goods sold are down, but the value is actually up. I like this chart below, which explains it better than any words. See how higher inflation has opened up this gap between value, and volume of retail sales. Of course, it's value, not volume, that matters to us as investors, because the value line is what becomes company revenues.
Agenda
XP Factory (LON:XPF) [I hold] - I mystery shopped its 2 new Bournemouth sites yesterday afternoon, and am impressed. As it was a rambling & photo-filled review, it took up too much space for here, so it's in a separate post here, for anyone interested.
Trifast (LON:TRI) [no section below] £89m mkt cap at 65p - this fastenings company dropped 9% yesterday on an H1 (6m to 9/2022) trading update. It’s dropping FY 3/2023 adj PBT guidance from £16.3m to £14.7m, due to increased costs, and delays in negotiating customer price rises. H2 weighting, so interim results may not look great. The balance sheet was already very heavy with inventories & receivables, and inventories are said to have risen even more in H1. I think the strong balance sheet can cope with this though. This share is starting to look cheap. So it could be worth you taking a closer look. [no section below]
Wickes (LON:WIX) - a solid Q3 update, with no change to profit guidance of £72-82m for FY 12/2022. This looks a good business, and I also like its strong, ungeared balance sheet. Forecasts have come down a fair bit already, and may come down more. Also there are worries about operating costs & higher energy costs when its fix ends in Mar 2023. But overall, taking a longer term view, I think this looks good value. So a thumbs up from me.
Wickes (LON:WIX)
125p (pre market open)
Market cap £323m
Wickes Group plc ("Wickes"), the market-leading home improvement retailer…
Stable trading in the third quarter; profit guidance unchanged
This looks a solid update for Q3 of FY 12/2022
Key points -
Quarterly like-for-like (LFL) revenues -
Q1: (4.0)%
Q2: 5.4%
Q3: 2.6%
It would be interesting to know the split between price rises, and volumes, but that’s not provided. Remember that, even if sales volumes go down, higher unit prices mean that this can be absorbed by some businesses.
Most importantly, profit guidance is unchanged - specified at £72-82m adj PBT for FY 12/2022. Note below that broker forecasts have already been lowered in recent months, which is good, this is how it’s meant to be done - bring down the guidance when times are hard, then meet the lowered guidance. Rather than forecasts being a straight line sideways, then a profit warning is issued. Watch out for this on this chart below, for every company you look at, it's a key point at the moment.
I’m also currently looking for companies where 2023 forecasts are below 2022. That makes sense given current uncertainty, and as you can see below, this has been done for WIX forecasts (from 7 brokers, but none publish them on Research Tree for us, annoyingly) -

The question is whether forecast downgrades have been done enough already, or whether further downgrades are required? We don't know yet.
Other points -
Impact of extreme heat in July & Aug, but sales improved in Sept.
Inflation - cost of timber reduced, which has helped moderate selling price rises - very encouraging, and follows on from what I was saying yesterday that there’s increasing evidence inflation might be peaking, and set to reduce in 2023, possibly quite rapidly, which is bullish for shares in due course.
Outlook - the obligatory comment about uncertainty over consumer confidence, but otherwise sounds quite upbeat.
Operating cost inflation is mentioned, in particular energy costs which are estimated to rise by £7.5m in March 2023, based on current energy price cap.
My opinion - this has impressed me. It may only be in line, and forecasts have been trimmed a fair bit, but the valuation is now looking really tempting.
Of course, the question is whether forecasts need to come down some more, e.g. if earnings halve from here, then the PER of 5.9 would double to 11.8 - which is fine in a bad year, then long-term holders would probably see the share price rise, as earnings recover.
Look at the dividend yield too, a thumping 7.8%, although that could be at risk if consumer (and trade) demand really plummets (no sign of it doing so as yet though).

The last balance sheet was very good, ungeared, and strong once you delete the spurious IFRS 16 entries, so there’s no solvency or dilution risk, in my opinion.
At some point, things get so cheap that I think it’s worth buying for the long-term, and just ignoring the short term price. It’s not a binary decision either - I like the strategy of buying in thirds, ie. starting with a ⅓ position size, waiting to see what happens, and then increasing (or decreasing) depending on how things pan out.
At the current valuation, and with its strong ungeared balance sheet, I’m giving WIX a thumbs up, and have added it to my watch list as a possible buy.
The best retailers should weather this storm without too much trouble, and I think this is one of the quality outfits that’s worth considering.
The chart looks as if it's trying to form a base maybe?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

27 comments
Sosandar (LON:SOS) pI World podcast popped in earlier. Really strong sounding story. Took a modest amount last week after following it for ages until it bounced off recent lows. I have a feeling NEXT are more likely to jump in there after the recent Reversal from Joules. Strong October sales they say and seems to be a crowd pleaser for their target audience.
Yes indeed. I listened to the excellent PI World webinar with Sosandar (LON:SOS)
I had put down SOS (a long-standing favourite of mine) on my list of companies to approach to do an audio interview with me. But there seems no point, as Tamzin completely nailed it in her webinar. I don't feel there's anything I can add. Thanks Tamzin!
After Alpha FX (LON:AFX) raising forecast due to higher interest received on cash, I wonder if others will shortly do the same ? James Halstead (LON:JHD), James Latham (LON:LTHM), Headlam (LON:HEAD), Victrex (LON:VCT), Nichols (LON:NICL), Robert Walters (LON:RWA), RWS Holdings (LON:RWS), Castings (LON:CGS), Softcat (LON:SCT), Bloomsbury Publishing (LON:BMY) all highly cash generative with net cash...plus all the house builders...(I hold all above so fingers crossed)...
Hope you are right truegent, especially all the housebuilders. I hold Barratt Developments (LON:BDEV) £PSN £TW Redrow (LON:RDW £VTY Galliford Try Holdings (LON:GFRD) Mears (LON:MER) the dividends are so cute compared to the others mentioned.
Well, Appreciate (LON:APP) is my play on this. They have £140m ring fenced customer cash and £20m own cash. Now going to earn much more interest.
Market cap is only £50m-ish!
(i hold in the Boon Fund)
The chart looks as if it's trying to form a base maybe?
I realise this isn't the best place to discuss chart patterns but the most successful base traders, O'Neal, Ryan, Weinstein and later Minervini all only looked for bases forming on a chart with a rising (or bare minimum flat) 200DMA*. Wickes has a sharply falling 200DMA.
* Weinstein used to use 30 week MA as described in his book but has since changed to the 200DMA.
There are a few forming a base some of better quality than wickes - some have bullish divergences, one of the most reliable signals out there. You still need another price action signal to form to confirm.
DYOR
Hi Paul, on a different subject altogether, have we lost Roland (Head) from the Stockopedia community? I always looked forward to his SIF reviews and analysis. Regards, Chris
Hi Chris - I think he backed off the frequency of SIF to do some other stuff, but he published an update this week which was nice to see/read.
He also has his own weekly/monthly email on his dividend PF which is an excellent read/analysis.
Thanks, Kevin - I somehow missed the SIF update on 18th but, I will review now! Cheers
Wickes (LON:WIX) Pleased to see Paul's comment, 'The chart looks as if it's trying to form a base maybe?' Not maybe, definitely. Obviously not an infallible signal but ignore at peril if a share is on the buy list.
I know we don't report buys and sells here so all I will say is: I hold (and I didn't hold yesterday) :-)
Good luck with it but that’s just bottom fishing imo, no evidence at all it will go higher from the current chart outlook, may get a small oversold bounce but the trend is firmly down.
Great content Paul! General comment / question from shares noted here over the last few weeks and the general environment we have now (higher interest rates etc).
I've been shortlisting mid-cap companies, with cash balances sufficient enough to make a reasonable addition to bottom lines (CMC Markets, IG Group, Polar Capital) - I appreciate they have other risks (Gov regulation, relatively recent acquisitions), but I expect over the next 6-18months we should see the 'interest' on this cash coming through on the bottom line / straight through to net company earnings I expect, at 5-6% (Maybe a bit high on what they can actually get) - on ow company valuations this looks to make a significant mark up on net returns.. + added security of the lack of debt worries..
Interested to hear thoughts / something obvious I am missing here !
(Edit - just read Timarr's comment below - looks similar and answers the question I think!)
Wickes (LON:WIX) looks like an interesting opportunity to me too. As an anecdote, a builder friend of mine is very complimentary about the Wickes trade service. Apparently if you order online they have the products ready to load onto your van when you arrive - he tells me it a brilliant service.
Paul, thanks for your fantastic mystery shopping write up on XP Factory (LON:XPF) - it's definitely not one for me but it was a great and insightful read. I really had no idea that these concept bars existed but they do have the look of something a bit faddy perhaps and entering into a tight consumer squeeze, I'd worry about the appetite for something like this.
Having said that, I was recently listening to a favourite podcast of mine about past cultural phenomenon (Decoder Ring) and it covered the origins of an unlikely American success of the 80's and early 90's called Chuck E. Cheese which was a bizarre family entertainment and pizza restaurant chain founded by the co-founder of Atari. The concept featured ball pits, crawl tubes, animatronic shows, arcade games, amusement rides, and stage shows whilst serving pizza and fast food. It's mascot was a giant rat and it became a runaway success so you can never really tell what might work!
I've been dribbling money into Wickes (LON:WIX) since the profit warning and will carry on doing so for some time barring something unforeseen. It's impossible to pick the bottom on these things, but it's a well run company, with a motivated management at a very reasonable price. Which is not to say it can't get more reasonable of course, particularly as they'll be exposed to the full force of energy price rises from next Spring.
However, if the housing market stalls due to interest rate rises owners will shift to improving their existing homes, so demand for Wickes' services isn't going to just stop. Whether they can increase prices to compensate for inflation remains to be seen.
More generally there are an increasing number of decent looking companies whose share prices have tanked following profit warnings. Arguably where we're seeing warnings due to unavoidable but temporary wider economic factors, rather than company specific issues these falls offer long term value. Off the top of my head Treatt (LON:TET), Gooch & Housego (LON:GHH) and (yesterday) GB (LON:GBG) might fall into this category.
I also think some of the warehousing REITs and alternative energy trusts are interesting at current levels. Prices have pulled back significantly in line with rising gilt yields, but as the deputy governor of the Bank of England has indicated, interest rates aren't likely to rise as far as is currently being predicted.
I'd also note that not all companies are negatively impacted by interest rate rises. Alpha FX (LON:AFX) today reported windfall profits on the safeguarded cash funds they hold. That's likely to be a theme emerging in the next few months - companies like Jarvis Securities (LON:JIM) and IG group (LON:IGG) hold significant cash on account and as those accounts roll off fixed interest terms the they'll start to see the benefit to the bottom line.
Investing in a bear market is always fun, as long as you can ignore the pool of your own blood you have to walk through to do it ...
timarr
Morning timarr. Always interesting to read your extended comments, thank you. Re Wickes (LON:WIX) and your comments
'However, if the housing market stalls due to interest rate rises owners
will shift to improving their existing homes, so demand for Wickes'
services isn't going to just stop. Whether they can increase prices to
compensate for inflation remains to be seen.'
I see where you are coming from, but I'm not always sure that this applies. People - whoever they are -may not have the money at all, so hold back on purchases in a slump.......and potential/frustrated first time buyers aren't going to improve the places they are renting, are they?
I still like the company for the reasons Paul Scott has given in his review, and other comments about their offerings I have heard too. I'm just waiting for that 'bottom' point!
RE: Wickes (LON:WIX)
I still like the company for the reasons Paul Scott has given in his review, and other comments about their offerings I have heard too. I'm just waiting for that 'bottom' point!
When it gets there let me know, and I'll load up :-)
An alterative view of Wickes from earlier this year (this was pre profit warning, mind): https://yetanothervalueblog.su...
timarr
agreed. its not just that the housing market will slow, but that real-term disposable incomes will also fall
'as long as you can ignore the pool of your own blood you have to walk through to do it'
Love it
Investing in a bear market is always fun, as long as you can ignore the pool of your own blood you have to walk through to do it ...
So true! Not sure if anyone else has a trading log kept in a spreadsheet like I do, but I like to analyse trades (particularly bad ones) to see what can be learnt, if anything, for the future. As you can imagine, year to date all the sells look like they were made by an investing genius and the buys were left to a drunk! The only good news is that, on a capital only basis, I'm only 2% worse off overall than if I'd just sat on my hands since 1st Jan. That's not enough of a loss to dissuade me from continuing to put cash to work. So I continue to dribble money into my best ideas at increasingly lower prices.
BTW I wish something could be done about IFRS16 bloating the net debt of companies with leases. When I looked at the Wickes (LON:WIX) StockReport I just instantly turned my nose up at the huge amount of "debt". But then, as Paul correctly points out, there is nothing wrong with the balance sheet on a non IFRS16 basis. I used to use a Net Debt to EBITDA rule in my screens but IFRS16 has rendered it useless.
All the best, Si
Boohoo (LON:BOO) JPMorgan took a 5% stake a few days ago and look like they have now sold it. Apart from getting cold feet, can anyone shed any light on why they would do this? Many thanks in advance.
If you look back at previous RNSs, JP Morgan seem to be doing the hokey cokey with BOO shares, so it's probably some sort of derivative or hedging thing. I just ignore those announcements.
Boohoo (LON:BOO) have noticeable broken their long downtrend using IG charts (2hr tick). i have no idea re trading etc but do take note of significant chart patterns.
disc i hold small short term trade position
I reckon their team saw our own Graham's recent YT analysis and had a change of heart on BOO
For anyone interested in Fonix Mobile (LON:FNX) you might easily miss the laconic trading update buried amongst the "Notice of AGM, Dividend Timetable and Investor Presentation": The Company continues to trade in line with management expectations.