Small Cap Value Report (Fri 22 July 2022) - UBG, SGI

Good morning, it's just Paul here today (as Graham does 4 days, and Friday's are usually quiet enough for me to manage on my own). There's hardly any company news today, so I'll work on some backlog items instead, hence a full report should be up by 1pm.
Podcasts
Tomorrow I'll be publishing the 4th episode of my SCVR summary podcast, on my personal podcast website here. It's a Stockopedia thing really, I just publish it myself so as not to create any admin for the busy team at HQ. The audio can be downloaded on wifi very easily (click the 3 dots, and select download) for listening on the move. I'll look into how to get it onto a proper podcast platform at some stage, but want to keep it as simple & quick to do as possible for now, to get into a manageable routine.
New podcast (today) - I've just interviewed renowned investor Richard Crow, who talks us through his favourite share ideas, his stock selection process, and his surprisingly upbeat current market overview.
Doing podcasts is good fun, and feedback from listeners has been positive. With the SCVRs, the information is already fresh in my mind, so it makes sense to recycle it into a podcast at the weekend. Also, I do enjoy making podcasts, and am much more relaxed about it now, having done quite a few. It's not life or death, so if something goes wrong, it doesn't really matter!
Agenda -
Unbound (LON:UBG) - a shocking announcement last night, of a large discounted placing, and a huge hole in the forecasts, despite previous (now clearly false) in line trading updates. I feel very let down about this one, and let rip about it below, in detail. Apologies to readers, we've been led up the garden path it seems, although I don't think current events could have been foreseen (wildly wrong forecasts from the company/broker).
Stanley Gibbons (LON:SGI) - announces it is delisting, at the request of the 58% controlling shareholder. An exit price of 1.5p is offered, which looks fair. In a bear market, delisting risk increases considerably for micro caps, as liquidity dries up. So that's something to think about, for holders of the tiniest companies' shares.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Stanley Gibbons (LON:SGI)
1.45p (before market opens)
Market cap £6.2m
After a long stint (over 20 years) on AIM, and producing a dismal performance for shareholders, SGI is proposing to bow out. It is controlled by 58% shareholder Phoenix Asset Mgt, which has understandably concluded that there’s no point in maintaining the cost & hassle of a stock market listing.
The reasons provided below are worth pondering, for read-across to other tiny, illiquid shares, and clearly make sense. Point 3 is an interesting one, that being listed and the disclosures given, educates the competition, so is actually a drawback commercially -
.

.
There’s a sting in the tail too - a threat to withdraw financial support, if shareholders don’t agree to Phoenix’s demands.
On the upside, Phoenix says it will buy shares in the market, at 1.5p (slightly above the current price) for anyone that wants to sell. That’s rather decent of them I think, as otherwise the share price might have halved, which is usual when delistings are announced.
My opinion - it’s difficult to argue with this. There’s no point in maintaining a listing for a micro cap with a controlling shareholder, and years of dismal financial performance.
The 1.5p exit looks completely fair to me, so nobody can really complain about this.
Investors need to think hard about delisting risk for micro caps generally. In bear markets, liquidity dries up, and plenty of the smallest companies leave the market. This can often be accompanied with a crash in share price. So if you can’t see any reason why one of your shares is listed, and it’s almost completely illiquid, then be careful. Especially if there’s a controlling shareholder who can force through a delisting.
.
Unbound (LON:UBG) (I hold)
13.5p (down 39% at 08:06)
Market cap £5m (before placing)
Clearly this has been an unmitigated disaster, so my apologies for leading you down the same garden path that I’ve been led down. It’s now become obvious that we were sold a pup.
Management had previously denied that they needed to raise funding, and that only a small amount c.£1m might be raised, purely for expansion - they told me this directly, on a recent call, and sounded very relaxed about funding/liquidity (3 weeks ago). Which naturally makes me question management's integrity.
Last night a placing/subscription for £3.3m was announced, for 22.0m new shares, being a considerable 58% increase in share count from the existing 37.9m. (the RNS says it’s a 52% increase, so maybe they’ve included share options to reduce that % figure?)
Pricing - is 15p, a discount of 32% to the market price, which had already been in freefall for a while.
Singers have done the fundraise, and I think should be congratulated for getting it away at all, they must have called in some favours.
A city source tells me that the original fundraising proposal was a £5m placing + £1m open offer at 25p. That then reduced to 15-20p range, and ended up as £3.3m (under-subscribed) at 15p, due to lack of investor appetite. So if they say it was over-subscribed, that’s not true.
There is a £1m open offer, also at 15p, but with the share price currently (08:20) at 12-13p bid-offer, then the take up is likely to be little to nothing.
The 25p nominal value of the shares will have to be reduced, to allow a fundraising, but that should be a formality at a general meeting, using the standard mechanism of dividing existing shares into new, lower nominal value (1p in this case), and worthless deferred shares (24p theoretical value, but actually worthless).
Directors have put up £268k of the fundraise, 8.1% of the total, so some skin in the game there at least.
I don’t believe the reasons given by management for the fundraise - claimed to be for expansion. Since they previously said that would only need a small fundraise c.£1m, for expansion, then clearly trying to raise £6m originally, means there’s a deeper problem.
Current trading - only gives revenue & gross margin, not profits. But they are up on last year -
The Directors are pleased with the progress that Hotter Shoes has made in the current financial year to date. Revenues in the four months to 31 May 2022 were £16.9 million, up 12.5 per cent. on the prior year period (£15.0 million), with gross margin also improving to 68.7 per cent. (2021: 66.7 per cent.). This improvement in revenue partly reflects softer comparatives in the prior period…
Overall, Hotter Shoes continues to trade in line with the Board's expectations for the current year ending 5 February 2023.
Net debt - I’ve previously mentioned here that I was a bit worried about net debt, which looked too high. This certainly looks too high now -
Overall Group net debt was £9.7 million at 30 June 2022, comprising £10.1 million of net debt within Hotter and £0.4 million of cash held by the Company.
Forecasts were completely wrong - this bit is absolutely appalling. Market expectations come from the company, via brokers. So it seems, almost unbelievably, that the CFO forgot to budget for £2m of costs! He should be fired by close of play tonight, for total incompetence (and that’s being charitable) -
Furthermore, the Directors note that current consensus market expectations do not reflect any income or expenses associated with the Group's growth plans for the wider Unbound platform or other Group costs such as for the head office. The Directors estimate that these other Group costs will be approximately £2 million in FY23.
Although I'm not sure I believe this explanation, it could just be an excuse for under-performance and cost over-runs? A city source has told me this morning that brokers covering UBG insist their forecasts did include head office costs originally. It would be strange if they didn't.
Existing forecasts - I’ve downloaded the last 3 notes from Edison (commissioned, so the figures would have come from Unbound’s CFO) - and the forecast for FY 1/2023 was consistently £2.0m adj PBT, and 3.8p EPS.
Unbound had issued several trading updates this year, saying trading was in line with that. That's why I continued to hold the shares, because it looked increasingly cheap.
But we’re now told, almost as an aside, that they forgot to include £2m of costs. So actual performance is now likely to be just breakeven.
Once this came to light, the shares should have been immediately suspended. Instead, they kept quiet, and did a covert fundraising. These fundraisings take several weeks, so there has been a totally false market in UBG shares probably at least for July to date, maybe longer.
Highly material, price sensitive information was not disclosed to the market, when it clearly should have been, weeks ago. So rules have almost certainly been broken here.
The trouble is, the £3.3m fundraise, which will probably be under £3m after costs, probably won’t be enough to pacify a bank that is likely having kittens about being owed nearly £10m by a business that it thought was nicely profitable, but now turns out to be operating around breakeven.
My opinion - the new share count is likely to be about 60m (assuming little to no take up of the open offer), so currently at 12.5p, the new market cap would be about £7.5m.
Is that a bargain? Yesterday, I would have said yes, because the company had confirmed repeatedly that it was on track to make a profit of £2m this year.
Today we now know that the forecasts were wildly out, and the latest picture (if even this can be believed) would be about breakeven.
Almost £10m of debt, and a fundraise (net) likely to be c.£3m, would still leave net debt at about £7m. We’re not told what the bank’s position or attitude is, but I strongly believe this fundraising (attempting to raise £6m originally) was probably driven by the bank getting cold feet over the forecasts being completely wrong.
I think it’s important to focus here on what has specifically gone wrong, and learn the lessons from it. No doubt people will say that they never believed the business model, etc, which is fine, but that’s missing the point. What has specifically gone wrong here is this -
- Unbound was floated with too much debt, and this was glossed over in the demerger process.
- An incompetent CFO forgot to include £2m of costs in the budget, supposedly, and so should be replaced immediately with someone who can count!
- The market has been misled about forecast profitability. Surely this can’t have been deliberate, as it would have been discovered sooner or later? It just sounds like a gigantic and obvious mistake by the CFO. How on earth can you overlook £2m of head office costs when budgeting? It’s just unimaginable, speaking as a former CFO myself. You should have every detailed line of expenditure in your budgeting spreadsheet.
On the positive side, Hotter Shoes is a nice enough little business, which seems to have coped well in the pandemic, and more recently with supply chain & inflation. For me it was always a minor consideration, with Hostmore (LON:MORE) being the most interesting, and valuable part of Electra.
The jury’s out re the broader strategy to drop-ship complementary products, which seems low risk, and worth a try.
But for me, none of that matters now. The basis that I invested (or continued to hold after the demerger) was that this was a profitable business, with possible upside from a cheap, and low risk strategy to broaden the product range.
That’s no longer the case. We now have a business operating at breakeven (or worse, who knows what other skeletons there might be in the closet?), with too much debt, that has tried to raise £6m, but will probably end up with about £3m. With £7m remaining bank debt, which looks risky.
Risk:reward has completely changed, for the worse, a lot.
I don’t trust management and think they should be sacked by shareholders.
In particular, in good faith, I did a Q&A with management & posted my notes here on 1 July 2022. That was only 3 weeks ago. I don’t believe that management could have been blissfully unaware of their forecasts being wildly wrong, with a massive hole in them, just 3 weeks ago. So I feel used, and manipulated, to prop up the share price unwittingly, and given clearly false information about funding/profitability, which I then relayed to you here in good faith, since I wrongly believed it to be true.
Although to be fair, the other information, about the drop shipping model, was correct, and the reader comments the previous day were incorrect, about it requiring substantial working capital.
So I think we should be careful not to conflate those issues here.
What has gone wrong, has nothing to do with the business model. It’s a catastrophic failure of forecasting & funding, by totally incompetent management. They’ve got to go, and I don’t think there will be a chance to raise any more equity under this management, if at all. Therefore it's a possibility this share could end up at zero, if anything else goes wrong.
Sadly, the only conclusion I can come to, is Unbound is now uninvestable.
I’ve therefore decided to ditch my shares, and just take the loss, and learn from it.
Lessons to learn - the dust hasn’t settled yet, but I can already think of several things that I can learn from this -
- Opaque accounts - the problem with Unbound, is that it was the vestiges of Electra Private Equity, and it wasn’t clear what the clean figures just for Hotter Shoes would look like.
- Balance sheet - I didn’t focus enough on the financial position of Unbound as a standalone company. It’s now clear that it was left with too much debt, an error made by Electra, not the management of Unbound, who had to take what debt they were given, but maybe should have fought harder to have Hotter’s debt reduced by the cash pile at Electra before floating.
- Management - a lot of us thought that the fancy buzzwords used by the CEO in presentations sounded lightweight, but is that enough of a reason to avoid a share? Probably not. I don’t think anyone could have guessed that the CFO would be useless at budgeting, and make a £2m mistake in the forecasts. That’s just one of those things you can’t predict, unfortunately.
- New listing risk - we nearly always avoid new listings here at the SCVR, because they are so often over-priced and/or rubbish. Unbound was a bit different, because the price has always been set by the market (previously as Electra shares), and it looked like the businesses were undervalued, based on the information we had at the time. Although a consumer downturn & bear market in discretionary spend type companies has inevitably smashed the share prices of Hostmore (LON:MORE) and Unbound (LON:UBG) since they listed, which would have happened anyway. But clearly with UBG there’s been a lot more wrong under the surface too, which has only come to light today.
Profuse apologies from me on this one, I clearly got it horribly wrong, and was misled.
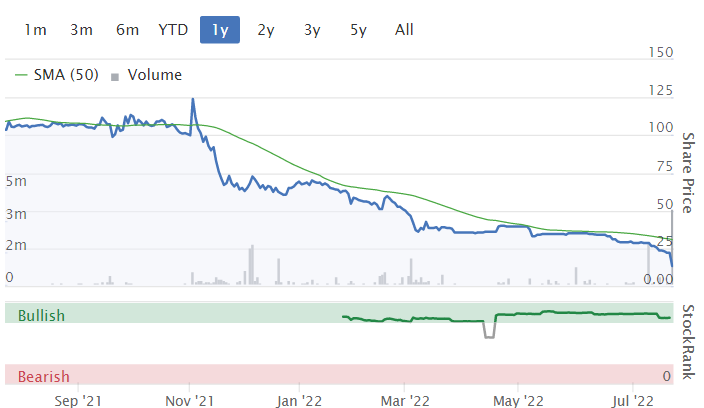
It fooled the StockRank system too, surprisingly -
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

116 comments
Some general comments on the state of the market today. I think it is possible to provide some answers. As far as general sentiment is concerned then I have no idea. However, looking at the performance of individual companies can give us a clue as to whether price moves are rational, related to known predictive factors or whether they seem to be more or less random.
I have developed a simple technique to shed some light on the latter question. I take about 750 shares, sort them by a factor such as Stockrank and then look at the total return over the next 6 weeks. The chart below compares the 6 weeks up to 13 May with the subsequent 6 weeks up to 16 July. The left side represents the average total return of the 250 top ranked shares relative to the average return of all shares. Each point to the right represents the value of this window slid down the data by one point at a time until the extreme right of the chart represents the average relative return of the lowest ranked 250 shares. It is quite clear that during the early 6 weeks the Stockranks did a poor job of separating the good performers from the bad. The most recent 6 weeks shows Stockranks performing excellently. To me, this suggests a move to more rational share price movements although it doesn't tell us much about general market sentiment.
Whilst I can't predict a market rise or fall from here, I am much more confident that a factor based approach to a portfolio will outperform the average by a substantial margin in the immediate future, although I will of course be in a better position to judge the accuracy of that prediction in 6 weeks time!
Totting up at the end of the week; the last month has been pretty grim but now I am back where I was, in spite of Morses Club (LON:MCL) which I still hold.
Hi Paul
Don’t you think it would have been a good idea that there was an announcement by Hostmore today regarding the events of the day?
An announcement that Hostmore will and does not need to make a placing and that all the figures given to Edison are correct would have calmed the market and kept yesterday’s stock market price.
Instead they chose to be silent and lose 11% of their market cap.
Hi Yiannos
I was thinking the same but what can they say? " We are not like the other company that lies to brokers, we are honest and the figures are correct?" Did anyone really blame them for something or is it just speculation that there is a link between them? I have spent hours today trying to find an actual link ( or anyone trustworthy who knows something) but I did not find anything. I will definitely not sell because of a speculation ( I might be wrong), the question is: is it becoming even more of a bargain or not? Any thoughts on this would be welcomed
Angelos
I believe it was the right thing to do as the two companies were the last two left from Electra and both covered by Edison. Also , Hostmore’s recent announcements have been contradicting as well.
Whether it is a bargain or not it is easy to answer. If all figures and earnings estimates are correct for the next three years , then this will at least 4x from here.
Are they though?
Thanks
Great Podcast, thanks Paul and keep them coming.
Re Unbound (LON:UBG)
Reasons for optimism
1. Exceptionally low Sentiment.
The share price closed at 22p last night. Subsequently there was a 58% increase in the share count at 15p. So the theoretical post issuance price is 19.4p
((100*22)+(58*15))/158 = 19.4
This is some 55% above the current 12-13p spread
2. The Institutional shareholders will likely insist on managerial changes, which will be taken positively.
3. The underlying business appears sound & is now reaching the inflection point from loss to profit
4. There was once mention that Unbound (LON:UBG) could be the benefactor of a £10m insurance claim (can anyone substantiate this ?)
Reasons for pessimism
1. The stock is uninvestible until management is changed
2. Apparent pressure from bank to reduce debt at a faster rate than the £3.3m raised overnight
3. No great institutional ownership to date, which limits pressure for change.
4. General macro headwinds as we head into a recession.
Hello Epsilon. Interesting comments. However, even tough I am a user and recent buyer of Hotter products along with my wife, your following point has little or no substance I am afraid.
3. The underlying business appears sound & is now reaching the inflection point from loss to profit
I have highlighted it because I think it is without foundation, but what do I know? It may bounce, as has Joules (LON:JOUL) in recent days on news, not that the business is gong to be better, but that the lenders will not imminently pull the plug.
I fear I have had a few of those in the last couple of years, and generally the optimism doesnt last. At least £HOST which unfortunately seems to have suffered today because probably there has been an unfair cross read from Unbound (LON:UBG) has a decent franchise, just suffering from having an over priced product in the current market conditions. I saw the Mello presentation from management at a Mello evening event some months ago and I thought they were quite good; I haven't heard the Unbound (LON:UBG) management speak but I have read the claptrap about what their hopes and aspirations were, and now they are in a sorry state to say the least.
ECO Animal Health (LON:EAH) (I hold)
I have opened a small position in ECO Animal Health (LON:EAH) who supply drugs to prevent unpleasant animal diseases. They are particularly influenced by the price of pork in China and the SP has been slaughtered recently (excuse the pun).
The Stockopedia metrics look good. The Quality and value metrics are high.
The broker forecasts have been downgraded (halved) so may be realistic.
Aside from a good QV score my theory is that China is reopening and all food prices are going to rise so the value of pork will too.
The company has also protected its R&D spend and is actively trialling a treatment for a chicken mite that could be big news if successful.
There are 3 buy or strong buy broker recommendations.
For the chartists, the share price may have made a small but significant move this week.
Not for everyone but for those looking for quality at a beaten up price then ECO Animal Health (LON:EAH) May be interesting.
I was interested to read today's comments. But no-one has mentioned the obvious: Use stops. Especially in a down market.
Any stop put in at any point would have taken you out of Unbound with small łosses. Get rid of losers. Sigh, swear, admit it was a dud, sell. If you wanted to you could wait and buy back lower later on. Cut the loss instead of averaging down. There seems a lot of confirmation bias around too and emotional energy used up. Don't go wasting your precious time, as the Spice Girls stated.
Taking a loss is the hardest thing, It confirms you made a mistake. I've met 1000s of traders over the years and relentlessly hanging onto losers with confo bias is the biggest reason for losses and inability to make money. When shares continually go down over months there's always a reason, Mr Market knows and take that cue to exit. Stops will take the emotion out of trading.
I ain't gonna lie, gotta go, the Mrs wants to force me to watch a recording of Love Island. Someone help me. But it is what it is.
Robbie, especially about Unbound (LON:UBG), you could have said so many truer words. They would have helped me with my Unbound (LON:UBG) holding some time ago.....and I would not have been tempted back in at any price.
Reading here about views of this whole dreadful saga ( no offence meant to Saga (LON:SAGA) ), no mention has been made about the dreadful what might almost be regarded as 'theft' of £12m by apparently one of the country's finest brokers - yes, you guessed it, Numis (LON:NUM) - for handling - mismanaging....I'm struggling for the right words and I cant find sufficiently critical ones - the 'translation' of £ELTA into first £HOST and then even worse Unbound (LON:UBG) efficiently and economically.
That £12m is best put into context by comparing it to the current ombined Market Cap of around £50m for the two, although market factors will have played a significant part in their decline in value, given that most parts of the market have been hit in recent months.
The failure of Electra Private Equity and Numis (LON:NUM) to cPE investors into a couple of decent businesses has been discussed, especially by Paul and others here on a number of occasions. The choice of Numis (LON:NUM) was probably the wrong one by Electra Private Equity in the first place. I haven't seen any offer by Numis (LON:NUM) to replay some of that £12m on a goodwill basis, despite the fact that it is difficult to understand how they could justify that. Have Unbound (LON:UBG) ( formerly Electra Private Equity until 23rd Jan 2022, even after the spin off of £HOST ) indicated they will be making a claim against Numis (LON:NUM) I wonder?
A very good reminder and one I really should use more.
Luckily I did that with Hostmore (LON:MORE) but it was too slow/late, but I have saved myself a lot of pain.
I couldn't believe initially that they could keep on dropping - their offering was good, their management team seemed talented from the videos I had seen and they had a great business plan. I'd have saved many thousands simply by having a simple stop-loss.
I feel many of us get too attached to the story and hang on too long - and as you say we can always buy back in.
Utilising strong SL rules along with the Stock Ranks (see todays recent article by Ed C) I am sure I could become a better investor and generate better returns.
PS. I was tempted to go back into Hostmore (LON:MORE) again recently, but the stench from Unbound (LON:UBG) is enough to put me off - they maybe a completely different bag, but I'll sleep easier by avoiding them and if I lose out so be it.......plenty more fish in the sea. They are too closely related to that POS Electra/UBG I cannot risk a similar experience.
The problem with losing money on a dud is the temptation to "get revenge" and go back to it to win back the initial losses. I reckon the best thing is to remove the share from your screens, ignore anyone's positive comments on it and pretend it doesn't exist at least for three months. You've become emotionally involved. And then there's all the wasted time you spend watching it, thinking about it. The moment you get angry and blame the management or others or whatever for your losses you've got emotional. That's bad news for an investor/trader. Got to be cold hearted and clinical with shares and learn to move on.
For anyone who uses stop losses - let me know when your stop losses trigger, and I’ll be there to pick up the pieces. Selling into in illiquid down market in any kind of size just makes your broker rich. Stop losses are no substitute for proper research.
I might just buy shares in your broker too.
If you'd picked up the pieces on stops in small ones recently, you'd be broke !
Such bad advice. Supposedly you don't really need to know the companies you buy even when they are small caps that have variable liquidity and in volatile instruments you should sell on first sniff of down -> and that is a road to success?…
There’s some insight missing …
Nobody makes money that way beyond some temporary hot streak…but maybe if you have a following and promote your own picks and make a liquidity push behind it and then sell before you notify the followers?
I don’t follow your work so maybe I’m being unfair. But I believe my comment is very fair relative to what has been said here and damaging to PIs.
Most people make good money by knowing something and doing their work…and often buying weakness in stuff they know. Timing can be finessed and doubt, humility and intellectual honesty helping ‘stop loss’ errors which are commonplace for us mortals
PS my profession is assessing and managing professional investment managers. The number of simple formulaic non fundamental trade rules I’ve seen blow up is countless. I’m not anti stop loss but in isolation it always leads to destructive whiplash particularly if very tight…the only time it works is with CTAs (commodity trading advisors which really mean trend following in super liquid macro instruments, usually index and commodity futures) and even then it’s very sensitive to how short a trading horizon time frame is used and size of assets managed.
I have bought and listened to two of Robbies audiobooks. I am not an experienced investor, having been investing for just over one year. Having also listened / read a number of other investment books, it appears to me that there is no 'right' answer. In any of the various investing 'paradigms' any number of examples can be found that suit the thesis.
I would only say that the advice that I have found the most useful from his books is to force yourself to admit when you are wrong. For an inexperienced investor like myself, the temptation to think that the initial perception of a company (particularly through webinars / presentations) is correct, and the emotional ties to that company are formed. I think much of the financial industry is based upon these 'narratives' (and I use Ben Hunt's term here), Unbound might be taken as a case in point.
I dont think that stop losses are as easy to set in practice as in theory. If the market turns down for a couple of days and the share in question loses 10%, and the spread is another 10%, this means that stop losses should be 20% down before you even talk about whether the company is doing well or not.
All I can say is that what I have taken away from Robbie's books has more than paid for their cost, and from Benjamin Graham that I am an unintelligent speculator !
Thanks Robbie, I have to say I've read your books many times over and they always bring a sense of grounding and common sense back to my investment practices. The above advice is golden and has saved me absolutely thousands (at a time when I had very limited means to replace my investing pot).
My stops aren't as tight as yours, and they are not automated (I often a buyer on those illiquid volatile days when the story hasn't changed) - however once it reaches a certain level - and it's clear I've got it wrong - it has to go. It's the very real difference between losing 5-25% Vs 65-80% on an investment for me, and as I've said it's saved me thousands. Thank you!
The lack of time to look at holdings, plus AJBell cost and sign in system (since remedied), and no auto stop loss leaves me currently holding Boohoo (LON:BOO) THG (LON:THG) and Ferrexpo (LON:FXPO) in the "coffee can". Oh forgot £MCL - now look at them a lot more and drops below the 50dma then at least reduce exposure or just get out and set an alert in stocko.
As said above we will never have the information available to Mr Market so the trend is your friend.
Have a plan set a target price and stop lost before hitting the buy button or better still listen when yourself moves out of small caps
£LGRS
Out of coincidence more than anything I have shopped three Loungers sites over the past two weeks - Didsbury (Expo Lounge) was too busy to get a table on Saturday lunchtime, Lichfield (Faro Lounge) was very busy considering it was midweek and Shrewsbury (Floro Lounge) we had to wait about 5mins for a table to free up today on Friday lunchtime. Interestingly a very varied customer base of various ages in all sites. Food quality I felt was above average for the price being charged and staff were attentive and helpful. Visiting the sites first hand it really doesn't seem like Loungers are feeling the impact of the market downturn despite suffering a significant drop in sp.
I don't own shares myself but after the recent writeup on the SCVR by Paul and positive words on the podcast with the other Paul (Big fan of the new podcast Paul as I can listen whilst driving to work!) I am going to look to add a small holding in the coming weeks.
Have a good weekend all
I see some comments about how the market could be turning upwards. Maybe, every bear market has some rallies, but to me the evidence says this has a lot further to run.
Data released today suggests the Eurozone is now contracting, while yesterday the ECB raised rates twice as much as had been briefed. Other central banks (CBs) are accelerating rate rises too. This is all highly unusual. Normally, at this stage of the cycle, CBs start cutting rates to keep a counter-cyclical stance. This chart shows interest rate changes across the biggest developed economies (US, UK, Eurozone and Japan) against a good survey indicator of growth:
Also, the aggregate policy stance across these banks, is forecast to be further tightening until the end of the year. The last time CBs tightened policy despite a downturn starting, was in the 1980-82 period. That resulted in deep recessions that took a long time to crawl out of. As can be seen in the chart above, it can take at least a year for things to turn around once rate cuts have started.
That 1980-82 period was the last time that CBs focused on fighting inflation as the number 1 priority. Will similar deep recessions happen this time? Maybe, I don't know. But what I would say is that markets don't form a bottom until the end is in sight. Recessionary bear markets commonly end about 3 months before the end of the recession. There are some good signs that inflation is moderating and supply chains freeing up, but there are no signs of the growth trend turning upwards. History suggests that will be needed for markets to really turn around.
£UBG Totally agree with your comments and feeling of being duped by totally incompetent directors. The CFO should resign as clearly lacks competence and conscience. I too have ditched my holding and put it down to experience as I just can't back any management who clearly do not understand so many aspects of business and clarity. It is unbelievable that a company aiming so clearly at the over 55yr demographic sector has alienated so many of that demographic who have invested in Unbound. Talk about a shoe business putting it's foot in it. Uninvestable.Caveat Emptor.
Would be a good idea to erase all data on Unbound from Stockopaedia as, in view of yesterday's disgraceful revelations, it is proven to be unreliable. Not a Stocko fault, that of useless BoD.
Paul
Regarding your guilty feelings on Unbound don’t beat yourself up we are all grown men on here .
One point I think you should follow up on , even if to fire a shot across the bows of any other management that directly mislead Stockopedia (via its analysts)
You say a
”So I feel used, and manipulated, to prop up the share price unwittingly, and given clearly false information about funding/profitability, which I then relayed to you here in good faith, sinc”
Taking this a step further then as Stockopedia is a credible operation you guys should’ be taking some legal advice as to damage to reputation etc , if you have been directly lied to and then fed that information into your readers then yes Stockopedia has been manipulated and there is a liability for damage to reputation .
Not my specialist field but I had plenty of times when I decided to not just accept things and even if to make a bit of a statement it was the right thing to do so I would suggest Stockopedia takes some advice .
This is a time when it shouldn’t be accepted as the old classic DYOR , if Stockopedia / you were misled and you passed that on to your thousands of readers then you should not allow that and must follow through .
Totally agree, I pay stockapedia membership to use their advice and metrics to make investment decisions. Is this now not the case?? Be interesting to see if this hits wider social media...
On an aside, taking a leaf out of Ed's book I created a My Naps 2022 virtual portfolio 11 days ago. It is doing better than any of my real ones even with Unbound (LON:UBG) going down the pan but as anyone will imagine I stepped in and smartly swapped that for another prospect.
To add to this, my Progress Report Graph has , at last, leveled off.
Wishing All a very Happy Rest of Year- Silver.
Are you crazy?! The last thing I'm going to do is start some legal action - the costs are absolutely ruinous, and it takes over your life. So no thanks!
I've defended myself (and won) in Court once before, and it was a horrible experience.
P.
Paul
Firstly I specifically said “Stockopedia”. Not you personally .
I also said “take advice” as to the position of Stockopedia and the potential issue .
You have misinterpreted or over reacted to what I said .
I think at an absolute minimum Stockopedia has to establish its position / standing , Once this is established then you guys can talk from a position of understanding .
If it ends up with “there is nothing we can do to protect our reputation and our clients interests and everything we say is at the mercy of us being told untruths and DYOR “. Then no problem .
If I was the owner of Stockopedia I would to own the situation and protect my reputation at all costs , And Stockopedia should desperately want to look after its readers and subscribers over and above all else .
So to quote my wife “it’s not all about you” and this is about Stockopedia standing up for itself and it’s subscribers .
If there is nothing to be done (and there probably isn’t ) then fair enough but you guys need to establish your backstop position .
Dave
Everyone loses in legal action.
Best action is for PI’s to spread the word both from an investor and consumer point of view.
Taking legal advice is very very different from taking legal action !!!
Just establish the position is
Then at a minimum put in processes and steps to prevent this re-occurring .
And Stockopedia has to look after us it’s subscribers and it’s reputation .
£UBG. a/Can Edison be sued ? and b/ When did Singers first know that the figures were wrong ? c/ Somebody certainly knew, the stock was offered to buggery all the way down !
Can anyone help me here ? I am an engineer by profession, not an accountant. Searching on Stockopedia and on the UBG balance sheet, I cannot find the £10m of debt that Paul is talking about. Have I got the wrong ticker.. ?!
Hi cheeky_minnows,
I was referring to the latest net debt figure, as provided in an announcement yesterday from Unbound (LON:UBG) here: https://www.stockopedia.com/sh...
Regards, Paul.
Hi, thanks for your reply Paul. I will read it through. I don't have any holding with Unbound, and therefore this is just for my understanding (DMOE - doing my own education !).
Unbound (LON:UBG) . If you are talking about the Stockreport that is because it's not there. It shows Enterprise value of -£16m !
Having looked through their annual report I see now that any of the figures up to Jan 2022 have nothing to do with selling shoes.. (despite lots of pictures of legs & comfy shoes - probably chosen to be good at running.. off with the cash). It is all the accounts for transfer from Electra, and I cant be bothered to look through the deliberate obfuscation to be sure, but I guess that the EPS on selling shoes is -15.3p rather than 111.4p
Hi Paul
We were all taken in by £UBG so no need to apologise.
Your analysis so accurately sums up why I invested and what I felt yesterday when reading the fundraising announcement. There is some consolation in knowing that I didn’t make a rookie error. Even seasoned investors were taken in.
I agree that (with hindsight) the market for these shares appears to have been false for many weeks. I wonder if it warrants regulatory attention?
I’ve also sold out and moved on.
I agree, Revs, Paul should stop beating himself up about shares that go sour. We all do our own research and TBH I'm gobsmacked that UBG & MORE were such losers and disgusted at the way we were all shafted by the City boys who took their huge fees and commissions, chewed us up and spat us out.
I too sold out this morning. Stuff them.
Paul, really good Podcast Paul. I am really pleased you decided to do it. Thankyou. I note you said "Hostmores EBITDA numbers are nonsense", perhaps portentious given todays information from Unb.
Hostmore (LON:MORE)
Hi Camtab - Apologies if i missed it, but where did Paul say that about Hostmore? As far as i can see he's still bullish on the company medium / long term?
Hostmore will probably take the same path as the Unbound group. If you go through their recent updates and the broker forecasts , you will find many striking contradictions as well.
The problem with both companies , is not their business or their brands , but the incompetence of their management. When , and if , both are changed , with a better management then we will see different stock market prices.
Yes Paul is quite bullish about it. But he makes the comment on EBITDA at 2 mins 45 seconds.
Unbound (LON:UBG) I think the lesson is be wary of ex-private equity holdings - for obvious reasons PE outfits are very skilled at pumping up a company's prospects and selling for maximum profit. Be extremely wary of a company where the private equity owner (Electra) was unable to shift - Hotter along with TGI were the 2 positions they were clearly struggling to offload and that should have told you everything.
Skilled?
I'd say skilled, yes, they did a good job of promoting the prospects of ELTA as a diverse and unique proposition. Turned out to be a can of s***
I am talking generally about the PE industry - clearly very skilled at selling companies for maximum profits. Electra themselves made very handsome returns for shareholders as they sold off their portfolio - inevitably there were a couple of stragglers which they couldn't get rid of, but still a good return overall.
and I wholeheartedly agree with you.
Rudyard Kipling "If" - "don’t deal in lies,"
Re Unbound (LON:UBG) and £MORE and any link - clearly not a positive development since both cos came form the same stable, were primed for independent life and have stumbled since issue. Although very annoying I suspect the failure of the process has contributed to the announcement. Had the demerger been more successful I could imagine in another world today was a cheeky 10% placing to kick start growth and taken very differently. Never the less the company was listed in the knowledge that their plans would require additional finance which is a bit naive and the shares are where they are. I guess however the company would argue they hadn’t made the plans yet and so these things were far from certain - and until the company listed - no plan to launch the platform existed.
For £MORE apart from the heritage link the read would appear somewhat limited. £MORE have downgraded numbers for weaker trading than initial scenario analysis but have confirmed their expansion plans are self financing. Director share buying after the statement supports the idea they aren’t currently sat on more bad news ie a fund raise. As someone has pointed out they are separate companies with different management and apart from the share register nothing much in common. The pressure remains to start delivering against forecast and build a rating. I note Harwood capital has also appeared on the register and no doubt C Mills is on the phone to management making sure they are not about to pull any similar stunt. On balance it’s understandable to fear something but I do not believe there will be a link. It’s also worth noting that Unbound (LON:UBG) was the significantly smaller part of the deal and most likely received a lot less attention than £MORE.
A long history of demergers have often seen one side do very much better than the other which is why they receive so much attention. It’s nearly a year since plans were originally made and I believe you should view these complaints as separate entities now. Good luck all with any positions you retain.
re Unbound (LON:UBG) - Ian Watson, CEO purchased a chunk of shares in the open market in March 2022...
He paid £57000 for the purchase of 150,000 shares.
Not bad , to spend a small portion of your salary in order to keep your job for the next years or so , and perhaps say to us that he invested in the company as well!
Unbound (LON:UBG) Why does the Stockopedia report show an enterprise value of -£16 million when the market cap is £8.5m and there is £10m of debt ?
I questioned a couple of times if we could trust the Stockopedia metrics. The EV and forecast lead me to invest. Not all Stockopedia’s fault as they rely on external data.
The problem with the data for Unbound (LON:UBG) is that this is the same share that was previously Electra Private Equity. So some of the backward looking data will be referencing Electra's numbers. So it's not a data error, it's that the company has totally changed from an investment trust, into a standalone trading company. This is a standard problem whenever an existing listing changes its activities - e.g. when something reverses into a cash shell.
Yes. I found it difficult to know where to draw the line between the two. We live and learn….
Volex (LON:VLX) has made a stunning recovery in the last 20 trading days. Was on a bonkers valuation imo based on company updates. Tesla results were better than expected so a good read across.
Wonder if someone is building up a position here w.r.t corporate activity?
Break above 309p crosses the 200d MA.
Nat Rothschild holds 25% of Volex (LON:VLX), so I don't think there will be any corporate activity without his say so. Acquisitions are part of the corporate modus operandi so perhaps some activity behind the scenes. The AGM is on 19th August and available to watch on the investor meets company platform.
Hats off to Volex (LON:VLX) and several other UK small caps for taking the time and opportunity to engage with retail investors and also to the investor meets company platform, an excellent resource.
Unbound (LON:UBG) As usual many people must have been aware of the need to raise money, the shares have been offered only for months, sometimes there was not even a bid for 2000 shares with usually a 50 or a 100,000 on offer.
Frp Advisory (LON:FRP) down around 7% on their back of this morning's results. Been fairly strong recently, so perhaps market expecting a bit more? It is a fair bit more expensive than Begbies Traynor (LON:BEG) (I hold) but never understood why it deserved a premium. Will keep an eye on it and may look to buy some if it goes a bit lower.
Unbound (LON:UBG) Are brokers regulated and held to account for the forecasts they publish? Or are they just a branch of PR, posing as finance professionals?
Should we maintain a list of brokers and other advisors who have badly let down PIs, so that we can avoid any company that uses them in future? A public list might even create some incentive to brokers to do a professional job.
It seems strange to me to blame a broker for forecasts, as most broker analysts would work with the Company to ensure they are roughly 'on track', unless a broker has gone completely off on their own wild guessing game?
You are 1000% correct.
The company ( in this case , Unbound ) has simply mislead both the brokers and the market and as I follow Edison’s reports and how they operate I strongly believe that they will stop covering this stock.
Does anyone know why Stockopedia doesn't put the broker names next to the ratings ? They are listed sometimes, but it is very rare. It leads me to ask myself - why wouldn't the brokers want to publish their names with their analysis..
I have had a quick look at &UBG (I have been steering clear of the retail sector having seen what happened with Boohoo), and one thing that is striking is the operating margin. On my stock screens I look primarily for high margins and no (or low) debt, but one thing I have found I have had to do (counter-intuitively) is to exclude any company with an operating margin >30-40% as I dont find I can treat them as serious. Unbound have an average operating margin of 90.8% (is this credible ?)
Morning yiannos1,
The company ( in this case , Unbound ) has simply mislead both the brokers and the market...
Spot on. The broker reports did include head office costs, I've confirmed that through a reliable city third party this morning.
Regards, Paul.
FREng,
The problem at Unbound (LON:UBG) is entirely the company's fault, not the brokers. Brokers are fed the numbers by the company, and guided by them. Especially when it's commissioned research. As John MacArthur formerly at Tracsis (LON:TRCS) once said to us, at an investor evening, "The broker forecasts are the company's forecasts".
As I've just put in the main article above, a city friend rang me this morning after speaking to analysts that published the forecasts, to insist that the broker research definitely did include head office costs. So I think UBG are not telling the truth in last night's announcement.
Regards, Paul.
Personally I think ResearchTree should sue the Company (unb) for damage to their business, because it certainly brings into question the research papers they rely on.
Unbound (LON:UBG) Maybe Stockopedia should too ?
Paul
If the broker research included the HO costs at the correct level, it appears that the brokers were given a fair amount of detail to support the forecasts that Unbound (LON:UBG) gave them. Yet substantial costs were apparently omitted in preparing those forecasts. Doesn't that imply that the broker failed to use the detail that the company gave them to carry out a reasonable sanity check on the forecasts and ask relevant questions? I recognise that brokers are not auditors but surely they have some duty of care towards investors.
They should take some resposibility for the research they publish. Otherwise they would be just allowing the company to use their name to add credibility to whatever the directors wanted the market to believe.
I'd like Unbound (LON:UBG) to publish in full the information they gave their broke, so that everyone can see who is responsible for the market being misled.
Regards, FREng
Ref - market changing a bit ?
Market sentiment seems to have changed quite a bit in the past 10 days .?
Few weeks ago everything was getting bombed out and grinding down even the good companies that look super solid and relatively recession resistant .
Even good results / ahead of expectations caused no change.
Now I’m noticing that good results / announcements are having strong effects on share bounces, not sure whether these rises are gong to stick or disappear in the next period of doom / down days .
Definitely I think the panic selling has abated and some cash is finding it’s way back in so the oversold can bounce sharply back .
Just a feeling, I have 3-4 shares that have bounced so will be watching to see if they hold or fall back (Bloomsbury , Equals , Somero )
Anyway just thought it interesting maybe someone cleverer than me can look at RSI movements and see if this feeling has anything technical to support it .
- ref: the market has changed a bit -
I've been waiting for others to say something - as I've also noticed subjectively that some microcap shares I hold are showing uncharacteristic strength - not so much strong gains - but more a failure for the bid to continue falling and in some cases even a progressive rise over the last week. It deosnt seem like the usual bear rally, much less volatile. Time will tell.
cheers
Many UK shares tend to just follow US markets so its worth keeping an eye across the pond. S&P almost back to long term trend and MACD about to turn. The huge excess has been at least partly erased and a buy signal looks likely next week.
Sentiment indicators have been appalling for a while now, some worse than 2008, so youd expect most people who were thinking of selling to have already done so. Who knows if this is 'the' bottom and the continuation of a long term bull market, no one knows, but its at least positive short term.
I wouldnt really call the S&P in a bear market. Still well above pre covid highs and above long term trend. A proper bear market would take us below 3000 in my opinion, so another 25%+ down.
Personally Ive went 90% invested in the last month and will take some profits if the rally continues, tho I do have stop losses set as theres the potential for a huge selloff.
Shorter term is bullish. Higher lows since June selloff. Market reversed after an initial selloff on the day of record US inflation and ignored talk of a potential 1% interest rate hike. Im bullish so long as recent lows arent breached.
I am open minded as to market sentiment but will not be getting aggressive either way. The impending winter energy crisis in Europe does make me extremely nervous. Of course we were well set for this rally as we have discussed but on balance would be chipping away at some stocks on the sell side. Esp if they have held up well but a recession 2023 wasn’t part of my original thinking. The Fed had the taps off and EU too - so risk capital and speculation will continue to retreat until we get a pivot. I don’t plan to try and front run the Fed.
For UK small caps it's always worth looking at fund flows, as they're an indicator of private investor sentiment. In June net outflows from equity funds were about £2.6 billion, which doesn't suggest a lot of positivity.
As Ruffer said this week - there's a time for getting rich, and a time for staying rich and, right now, we're in the latter.
timarr
Morning timarr!
Good point re fund flows.
I was chatting to a city friend the other day, and he said some funds are getting quite a lot of client redemptions, which has led some fund managers to leave open-ended sell orders with him.
Therefore, we should keep an eye on the trades for particular shares. If there are loads of retail buys going through, but the share price remains depressed, it's probably because there's an institutional sell order being worked in the background, which don't get printed until much later, or when the order is completed.
It's an unfortunate fact that flows of money in & out of funds tends to reflect recent performance. People put money in when they're riding high, and take it out after a big sell-off, i.e. usually the opposite of what they should be doing.
AIM IHT portfolios should do better re redemptions, because people lose the IHT benefit if they sell up, which is a 40% hit potentially.
Regards, Paul.
There is also a truism that says the private investor always sells at the bottom and buys at the top. Perhaps a portent.........let's hope so.
Agreed. I'm seeing some illiquid small caps I track, lurch downwards day by day. Probably instis having to sell to meet redemptions.
Of course there's the risk the declines is actually a fundraising situation like Unbound (LON:UBG) and people in the know are getting out before the ship sinks.
But if the company is sound in terms of balance sheet and limited risk to trading, then it gives a very good buying opportunity.
Hi Paul,
With reference to your last paragraph, it used to be the case that the 40% IHT benefit was not necessarily lost when qualifying AIM shares (held for 2 years) are sold, providing you re-invested the proceeds in other qualifying shares within 3 years. When re-investment occurs, the IHT benefit was revived without having to wait 2 years. Has HMRC changed this rule?
Regards,
John
Hi peterthegreat,
Ah yes, sorry, I think you're right.
That point was mentioned in this week's webinar from my friends at Fundamental Asset Management, who specialise in IHT portfolio management, and they're very good actually.
The rules are quite complicated, so I shouldn't have made a sweeping statement about IHT, apologies!
Regards, Paul.
I find the following index interesting although I do not base any investment decisions on it. https://edition.cnn.com/market...
Agreed. In the last 6 months, bad news or good news for that matter resulted in markets getting pummelled but seems much of the misery is priced in and markets looking ahead rather than mired in doom and gloom. Longer term technicals are looking like they might be bottoming out too so with plenty of automated/black box trading out there a bit of a downside buffer is appearing. Good luck All
I'd noticed, according to Stocko, my portfolios were turning around and overtaking the market relative to FT-A this past week or so. When I check momentum I can see some 'SCVR favourites' (as discussed, not necessarily recommendations) have positive relative strength over this past week (data rounded and not checked, don't rely!) e.g. JOUL +19, BOO +14, VLX +14, CNIC +14, SOM +14, COG + 13, SUP +13, CRST +9, LGRS +8, HWDN +7, BMY +6, SDI +6, STEM +6, FORT +6, WIL +4, WIN +4, VTU +4, LUCE +4, CER +3, RWA +3, SLP +3. Maybe a turning point?
Hi Dave/Planetx,
I have also noticed that the markets have recently started to turn positive. As gringo has stated, the UK market tends to follow the US market.
I remember reading an article which stated that a good time to buy back into the stock market is 7 months after it has fallen from its highs and under gone a correction. If you look at the US market it hit a high around mid November 2021, fast forward 7 months and that takes us to around mid June 2022 which is more or less when the markets bottomed out and slowly started to rise. Could this the answer to your observation??
The article stated that 7 months was a good time to wait because by then, most of the bad news is out in the open and priced into the market; and hence the stock market can start to look towards the future. However, I notice that the market is still in a longer term downwards trend and making making lower lows. Furthermore, I believe the market could see some volatility during the winter months if Russia restricts gas supplies.
Has anybody else heard about the 7 month timeframe and what are their views on it??
David.
hi Paul - I know the rns is a week or so old by now but if you’re working on a backlog it would be great if you could look at Equals. Thank you
Unbound
I had been harping on about these clowns for several posts and the writing was not so much on the wall but certainly hidden in a back room full of the cash the management had already made in the float .
The key here is of course to take the pain and learn the lessons .
- be wary of private equity backgrounds they are as a rule in it for themselves they are not founders who love their businesss and respect shareholders ( Warren Buffet invests in businesss with a founder who loves the business not the money )
- replace EBITDA with bullshit earnings (another Buffet)
- question the clearly ludicrous, 4.5 million customers was being quoted by Hotter but it was clearly just meaningless Hot air
-run a mile from management that issues zero cost options (even at a high strike price) and accept it as what it is , theft from shareholders pockets , this is a big sign management fancy themselves more than they fancy the shareholders
- a key lesson is don’t think a company can create a new platform /market , this is super hard . The recent claim of “creating an online platform to sell third party brands” is a bit silly if you actually think about it long and hard
The biggest wake up call here I am afraid to raise is the crossover into the Hostmore . Given the comments and wake up call on Private equity and in particular this set of clowns do we really not need to smell the TGI roasted coffee and accept the management may well but cut from that same cloth?
Unbound (LON:UBG) My wife said the Hotter brand was losiing core customers, their market had changed. Their offering had not.
Hi
I am sorry to hear about Unbound (LON:UBG) which I was considering buying at one point. There were a few things I didn't like ( the number of customers was one thing) but I am not sure we can relate it to Hostmore (LON:MORE) (I hold). They have different management and they are basically completely different companies since they broke out of Electra. If anyone knows different I would like to hear your views.
Exactly this “since they broke out of Electra” which wasn’t that long ago and just think of them as in an extreme case )in order to mentally crystalse our thoughts) let’s say “cash devouring private equity zombie vampires who offloaded their dross at inflated valuations onto a raging bull market “
The management were involved in the float and they “got it away” .
I think contrast the happenings here to Supreme which I think I cocked up on by selling out of last week .
Supreme has a founder who clearly loves his business and is going to die fighting for it, he has also gone back in (admittedly with the millions he made from the float) and is putting his own cash on the line, at market prices to show the market he is leading from the top . Bravo for him.
Still headwinds for Supreme but there you have a guy who has his neck on the line and you get the impression is going to turn himself out to make a success of his business and not with options or incentives . He will live by it and die by it .
I’m not getting much of that from a lot of feeling with Hostmore and the birth and creation of Hostmore onto the stock market is one of the zombie vampires .
planetx - Your post could have been written by me. I bought Supreme (LON:SUP), saw a nice little gain, and being very frightened at the moment I took it as a bird in the hand and sold. This was clearly a mistake. I agree with you and at the presentation which I reported on here I thought the CFO was equally determined to make the business work. My only caveat is that I wonder if this is another company that might delist at some stage. The CEO might decide he would be happier on a personal basis if he didn't have all the hassle of a listing, and in view of the share price history I am doubtful the listing is a path to raising more capital if they need it.
I am not in Unbound (LON:UBG) but I am in Hostmore (LON:MORE) so any crossover issues and words of wisdom for Hostmore (LON:MORE) from the Unbound (LON:UBG) news would be very much appreciated.
Just for clarification to all here with what you are suggesting :
How much cash did the management of Electra make from the float?
Give us a number please.
Thanks
Unbound - I am sure the authorities overseeing AIM are furious at the incompetence of the Management team. But more importantly who is going to support them now? I won't deal with these idiots and my shares will be unceremoniously dumped today. I don't care about the loss I am just annoyed I ever got involved with private equity. Sounds like an emotional response but it really isn't, outside of me being annoyed at myself for ignoring my own investment rules, which include don't deal with new issues and don't deal with private equity both of which are encapsulated in this tin pot company. A market cap of £8m as I write and they have just alienated the private investor. Genius. Who the hell is going to invest in them now? I cannot believe how little these people understand the market they have just entered and I honestly cannot see the share price making any sort of comeback from this debacle even if the market turns.
Hi Camtab
I no longer hold £UBG . Just got rid of the shares.
I posted my disgust last night. Don’t want to be annoyed by them anymore.
I can’t see the shares getting back to 15p now that we know what is really going on.
I will also be warning any friends away from the brand Hotter and any related Unbound (LON:UBG) sites.
You can’t behave like this and not expect repercussions.
Paul, your last paragraph rings so true, this is something that has been a big concern for myself. As a relative newbie and too old for comfort I find myself invested in some very shaky positions at a time like this.
Pleased with the results at £YCA. Shares trade at a big discount. Company Comments:
"The confidence we have in our longer term outlook remains very strong and this is driven by the same supply demand fundamentals that have supported the performance to date. We expect to see a sustained increase in uranium demand and price increases in years to come as the global demand for clean energy highlights the need for nuclear energy. We have seen very positive policy developments in the US, the EU and in China as nuclear is increasingly recognised as a core way to urgently address climate change. Yet despite a clear growing demand picture and recent prise rises, supply remains severely constrained, and looks set to get even tighter as utility companies around the world start to address their future uncovered fuel requirements. Yellow Cake is very well placed to capitalise on these market characteristics."
Yellow Cake (LON:YCA), These seem way ahead of the forecasts, yet the share price is down.
Yellow Cake (LON:YCA) is merely a vehicle for holding physical Uranium. Not sure how forecasts come into it as it doesn't generate a profit in the traditional sense. Should be valued with reference to NAV and currently on a nice discount.
Cameco CCO on Toronto stock exchange may be a long bet. Geiger Counter (LON:GCL) holds a stake. Have mines which can open up when economic to do so. Yellow Cake (LON:YCA) reliant on supply from Kazakhstan which is a risk and must be costing them to store it I think at Cameco’s facilities. Plus it takes a long time to build these things so demand a slow burner. Shame some bright kid can’t figure out a way to recycle radioactive waste stored at Sellafield - maybe too busy designing wind farm blades.
Re Unbound (LON:UBG) this section from the fundraising RNS is notable
“Furthermore, the Directors note that current consensus market expectations do not reflect any income or expenses associated with the Group's growth plans for the wider Unbound platform or other Group costs such as for the head office. The Directors estimate that these other Group costs will be approximately £2 million in FY23.”
We’re being asked to believe that directors have just noticed that there’s a £2m error in the f’casts..
Morning rhomboid1,
I know, the Unbound (LON:UBG) announcement is one of the worst I've ever seen.
It's (at best) total incompetence - I think CFO (and probably CEO too) have to go.
Regards, Paul.
Totally agree. How could this shambles have possible have passed through a NOMAD change and nobody pick up on missed overheads. The 'in line' t/u less than a month ago was incorrect and your conversation with management gave no indication of concern.
Going to take my 80% loss and sell up today.
It might double or something in the future but it might also go to nothing. Learn the lesson and move on
yes done the same myself. So annoying
Morning Paul ,
1.Probably is an understatement. They should have gone ( both of them ) at the beginning of May when a property was sold that was generating 20% p.a. income. Why should anyone sell a valuable asset that generates this kind of income? The company needed urgently cash and have not informed the market accordingly.
2.They have both mislead the market CEO and CFO ) in the recent trading update announcement by not informing the public about important financial information.
3.This is yet another company that did not provide any meaningful numbers in their last trading update.
Morning yiannos1,
Yes, good points, I agree.
Regards, Paul.
It is more than just the board.
There will be an accounts team that gathered and checked the numbers
There will be a qualified accountant who passed the numbers on to the board
Either the whole process was broken (incompetence at best thought the chain),
or for some reason the message was not transmitted from the business to its owners.
In which case one hopes a qualified accountant should have whistleblown internally or to the FRC. Maybe someone did, but the wheels grind very slowly and as such are of no value to shareholders.
My point here is that I think we tend to over-focus on the board. The quality of the organisation's processes/ institutional memory/ culture is in many ways more important.
Now, how you measure that... I do not know.
Re Unbound (LON:UBG), the Edison report that I referred to has the following disclaimer: "This report has been commissioned by Unbound Group and prepared and issued by Edison, in consideration of a fee payable by Unbound Group. Edison Investment Research standard fees are £60,000 pa for the production and broad dissemination of a detailed note (Outlook) following by regular (typically quarterly) update notes. Fees are paid upfront in cash without recourse."
My understanding is that given the relationship, the numbers would at least have been seen by management before issuance. There were also the movements in the Edison cashflow which I couldn't understand.
£ubg changed Nomad about 3 weeks ago - pretty big coincidence that this announcement came out shortly after. Maybe the omission was spotted pretty quickly and the fund raise has been cobbled together in the ensuing period?
Wow Arix Bioscience (LON:ARIX) puts out unaudited NAV. Share price = 105p. Cash = 101p out of 176p of NAV! Not much market value in their portfolio of investments. Watch out for a Simon T article in next week's Inv Chron!
Wolfspirit. Thanks for highlighting Arix Bioscience (LON:ARIX) - I have looked at it in the past (may be two years ago) - as it was then trading at a large discount to NAV (probably larger than now). I did not decide to invest then as the company had very high running costs (which they said they were planning to reduce) and it never paid out money to shareholders in capital returns or dividends. Have things changed in recent years? I must admit trading just above cash looks interesting.
I see an rns from COG this morning with joint share purchases from both the CEO and CFO yesterday after their trading update. Nice to see them putting their money where their mouth is.....
CEO & CFO of Cambridge Cognition Holdings (LON:COG) (I hold) bought £26k shares each - announced this morning.
Encouraging. I liked the trading update yesterday, and hope to write up a short section on it today. It seems to fit into the category of shares that have fallen hard on a de-rating due to overall market conditions, and not because anything has actually gone wrong at the company itself. It looks a relatively safe haven to me, not being linked to overall economic conditions.
Cambridge Cognition (LON: COG)
Morning Paul
Agreed.
These are the first director buys since the raise in early 2020 definitely a very positive sign. after yesterday's TU.
There are also large achievable options at around 150p - I am not sure if targets for these have already been hit or just missed as they depend on the SP remaining above a certain level for a period of 3 months.
Michael
Hi Paul,
Some very positive numbers but with H1 revenue up 31% why was profit after tax down massively to only £0.02m (from £0.1m)?, appreciate it was “in line with expectations” but that’s an eps of only 0.064p (if I have correct Zero’s!), analyst consensus is 1.79p for the year (based on the numbers here), so how is bottom line profit going to be 27 times greater in H2?. Sorry if I’m missing something obvious and I’m just being stupid :).
Ps love your podcasts