Small Cap Value Report (Fri 22 Mar 2024) - IGP, TRAK, DARK, SYM, BILN, REC, SAG, ECEL

Good morning from Paul!
Today's report is now finished. Have a lovely weekend!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
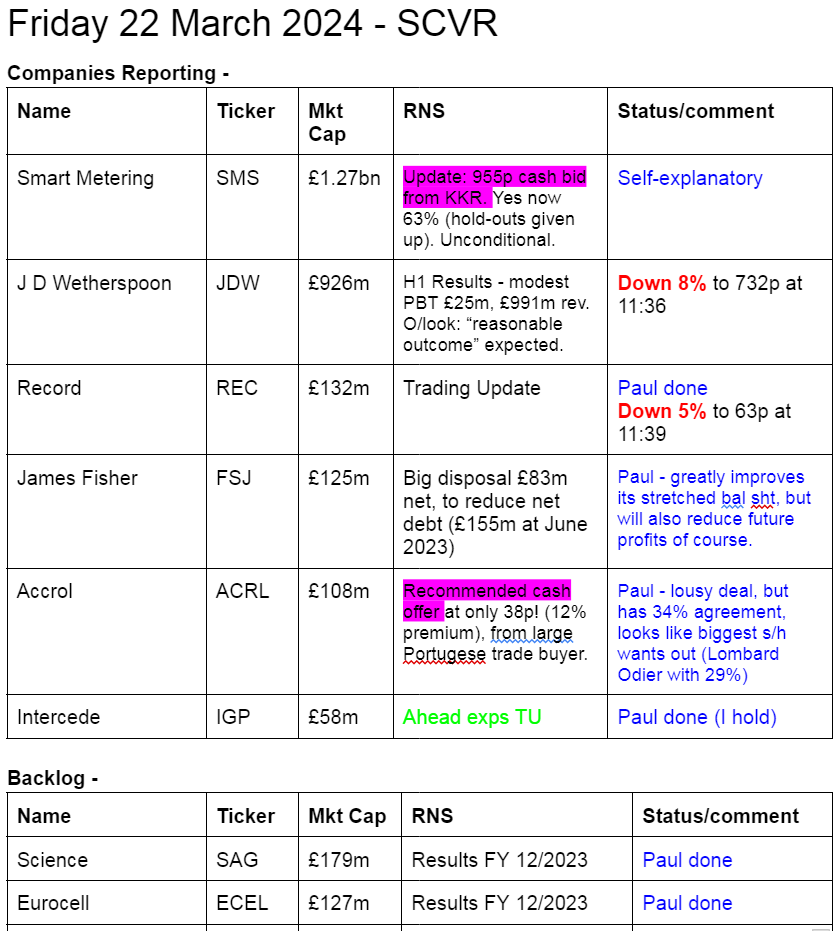
Other mid-morning movers (with news) -
Trakm8 Holdings (LON:TRAK) - down 36% to 9p (£4.5m) - Profit warning - BLACK - a large contract negotiation that underpinned FY 3/2024 forecasts is now not going to happen in time. Feb & Mar also slower than expected in its insurance-related telematics. New guidance: revs £16.4m and adj loss before tax of £(1.4)m. That’s miles away from last forecast (24/11/2023) from Allenby of £1.8m adj PBT. Cash looks tight at £0.4m, and they forgot to tell us today that they’ve got substantial debt: £5.3m term loan with HSBC, and £1.6m convertible loan (expires 9/2024, 12% interest, 17.1p conversion). I recall TRAK has sailed close to the solvency edge in the past, and it looks pretty much bust now without a placing and/or debt for equity swap - the lenders are probably having kittens and looking for a bail out from equity holders - equity could be worthless, who would want to put in fresh cash to pay off the bank?! Also warns on FY 3/2025 profits. Management have been around a long time, and repeatedly disappointed, so why would anyone believe any new assurances? It’s a RED from me.
Darktrace (LON:DARK) - down 9% to 418p (£2.94bn) - Secondary Placing - remember these are when existing shareholders exit, so no financial effect on the company itself. Full exit of shareholder KKR Dark Aggregator LP - has sold into the recent share price spike (peaked at c.490p on 14/3/2024), 19.4m shares (2.8% of the company) at 425p. Yesterday’s close was 461p. I looked at it briefly here on 7/3/2024 - impressive H1 results with large rise in profits & raised future guidance. Doing some googling, I see DARK was attacked by short-sellers last autumn, who will have suffered heavy losses in the recent spike, if they’re still short? Dangerous game shorting, especially if leverage is involved. Or maybe they had previously closed out, having been unsuccessful in trying to trigger a share price crash last autumn? Also it looks as if DARK was previously attacked by shorters in 2022, detailed on Wikipedia here.
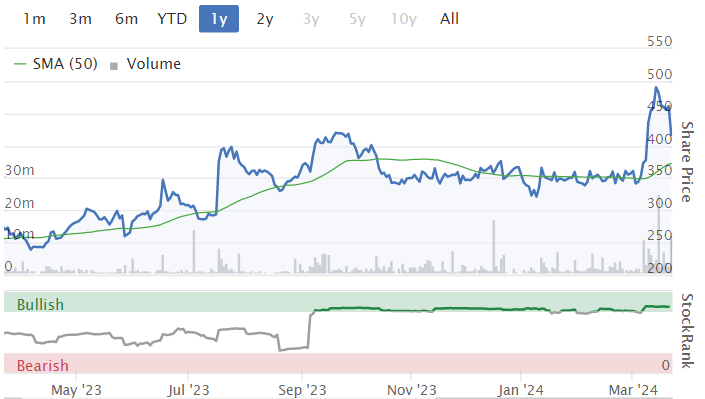
Symphony Environmental Technologies (LON:SYM) - up 31% to 2.75p (£5m) - Fundraise - very small, but I thought this deal looks noteworthy. A serial disappointer, recyclable plastics company. As you can see from the chart below, it’s been around donkey’s years, and every now and then mug punters (including me a couple of times!) chase up the shares on positive-sounding news that fails to turn into profits. Today it announces a small equity fundraise of £1.4m that’s priced at 3.5p, a 67% premium. The money has mainly come from its 2 largest independent shareholders, and the CEO. So they obviously want the share price up, and are backing that with fresh money of their own - I like that. In a long & detailed announcement, it says that the shares are undervalued, and that prospects for 2024 are looking better than they have for a while (my summary, to reduce the wordcount!). Another £0.5m is also being offered on Primary Bid. there was some kerfuffle over an EU judgement recently. Balance sheet is fairly weak, and note it has modest debt, and convertible loans from shareholders. So it’s quite encouraging to see them putting in fresh equity this time - which gives credibility to the positive outlook comments below, I think.
I’m tempted to have a fun money punt again, but that has been a mistake in the past. Can mgt assurances be believed though? -
The opportunities for Symphony are significant, and whilst taking considerably longer to convert than originally anticipated, a combination of more positive conversations, trials and other factors give the Board confidence that these can and will be converted in the short to medium term. In the meantime, with the lower cost structure and consistent high gross margins (40 per cent.), the 2024 outlook shows a much more positive commercial position for the Group compared to recent years.
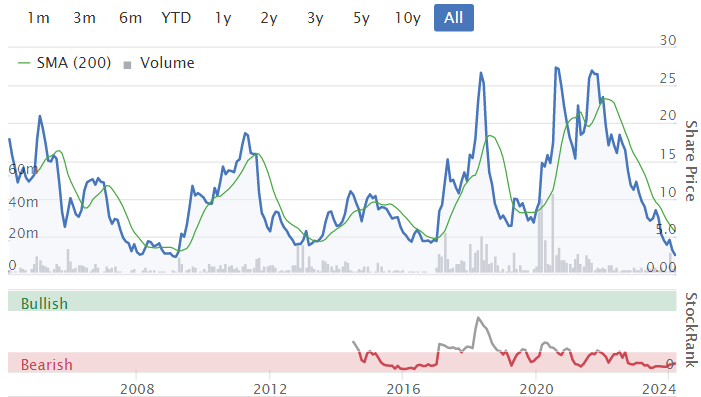
Billington Holdings (LON:BILN) - up 13% to 450p (£58m) - £90m contract awards - Paul - AMBER/GREEN
Structural steel company. We like the numbers for BILN, and were amber/green on 14/11/2023 (ahead exps TU). Good bal sht, decent divi yield. Worries about cyclicality in a downturn seem unfounded given news of 6 new contracts today, a record order book, all “further underpinning” market expectations for 2024 and “into 2025”.
Paul’s opinion - I like BILN, and today’s news bolsters the bull case - although how much is already in the price, given it’s already more than doubled since autumn 2023?
Summaries of main sections
Intercede (LON:IGP) (Paul holds) - up 13% to 112.5p (£66m) - New Orders & Trading Update - Paul - GREEN
Another contract win means Cavendish ups FY 3/2024 forecasts (by 4%) for the seventh time since first introduced! I run through the detail below. This remains one of my top 20 share ideas for 2024, and I see scope for further progress.
Record (LON:REC) - down 5% to 63p (£126m) - Trading & Business Update - Paul - GREEN
Shares dipped a little today on news of an IT project being abandoned, but the numbers involved seem small to me. More importantly, it's reached a new all-time high in AuM. I continue to like this share, with a modest valuation, and 8% yield whilst you wait for a re-rating. Maybe I've missed something negative?
Science (LON:SAG) - 394p (£179m) - Audited Results FY 12/2023 - Paul - GREEN
My view remains positive on this group. PER valuation looks reasonable. Balance sheet is OK. Management hint at possible deals of some kind?
Paul's Section:
Intercede (LON:IGP) (Paul holds)
Up 13% to 112.5p (£66m) - New Orders & Trading Update - Paul - GREEN
Intercede, the leading cybersecurity software company specialising in digital identities, today announces a new contract win, further strong trading and uplift on market expectations for the current financial year ending 31 March 2024 ("FY24")*.
* The current market forecast for the year ending 31 March 2024 is revenue of £19.2 million and adjusted EBITDA of £5.6 million.
Key point - IGP prudently doesn’t capitalise R&D spending, so EBITDA actually is a meaningful number here. I’ve told them they should be quoting PBT instead (because it’s a more credible number, and is only slightly below EBITDA for this company), but the analysts prefer EBITDA I believe. Well, at least I tried to help!
Cavendish (many thanks to them) raise FY 3/2024 forecasts c.4% -
Revenue goes from £19.2m to £20.0m
Adj EBITDA from £5.6m to £5.8m
Adj PBT from £5.3m to £5.5m
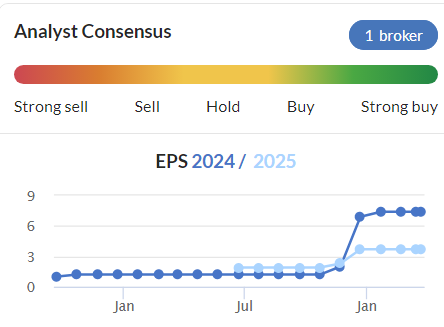
Adj EPS from 7.4p to 7.7p
Remember that FY 3/2024 benefits from a one-off mega contract. So FY 3/2025 forecasts are more meaningful for valuation purposes. This is £16.1m revenues, £3.0m adj PBT, and adj EPS of 3.7p. Giving a FY 3/2025 PER of 30.4x - but PER is a blunt tool at fast-growing tech companies. They’re often valued on a (quite high) multiple of EBITDA, or even the bonkers multiple of sales ratio, which ignores profitability completely. There's big operational gearing here due to high gross margin on licence sales, and largely fixed cost base, so each new contract drops through nicely to profit.
Cavendish’s note hints at further upgrades for FY 3/2025 being possibly (likely?), and says it has upgraded FY 3/2024 no less than seven times since forecasts were first introduced. So we now have a very credible pattern of under-promising and over-delivering, which is what we very much like to see here at the SCVR.
Clients are very sticky at IGP, and it has high levels of recurring and repeating revenues. There is single client risk though, as it has some very large contracts that renew every year.
Paul’s opinion - a long-term favourite of mine, it’s great to see Intercede on a roll now.
I’ve invited the CEO to do an interview on my podcast channel, maybe after the next results are out? It’s one of my top 20 share ideas for 2024, so these upgrades are helping my performance stats! Although Graham remains stubbornly 1% ahead of me, not that we’re competitive ;-)
In my experience, once companies start winning a flurry of decent contracts, it usually continues, although I can’t back that up with any firm data. Especially when they’re won through channel partners, who gain confidence in solutions that work and then might put Intercede forward as their preferred choice on future deals. Remember that IGP software is for managing secure user credentials, so it’s a cog in a bigger machine of IT systems.
Overall I’m happy to remain at GREEN, and I don’t see £66m market cap as being anywhere near stretched given the growth, and the potential, and the stunning client list that includes multiple US Federal Govt departments, major aerospace companies, banks, etc.
For full disclosure, I’m a shareholder personally, and intend sitting tight/adding more on dips if funds are available.
5-year chart below shows how quickly shares like this can rise when a flurry of good newsflow happens, blink and you miss it. I see this as probably a sustainable rise, because it's backed by big contract wins and forecast upgrades -
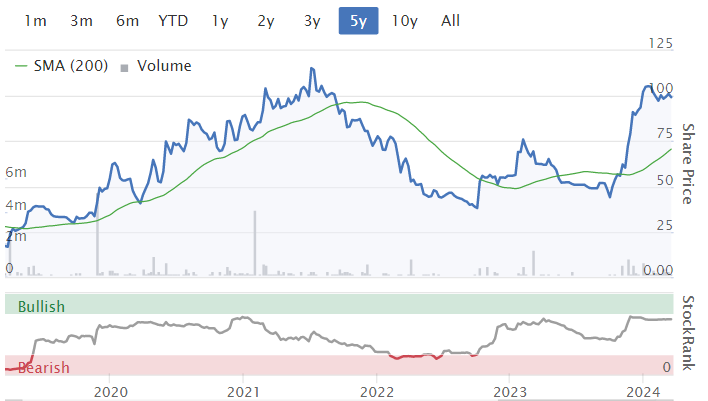
Look at the scale of the large one-off contract win on FY 3/2024 forecasts below. Although remember each big contract typically comes with a multi-year tail of support & upgrade revenues -
Record (LON:REC)
Down 5% to 63p (£126m) - Trading & Business Update - Paul - GREEN
Record plc ("Record", the "Company" or the "Group"), the specialist currency and asset manager, announces a trading and business update for the year ending 31 March 2024 ("FY-24").
Assets under management equivalent has hit a new all-time high of $101.3bn at 29/2/2024.
FY 3/2024 revenues expected to be £45m, in line with market expectations.
Abandoning a 2-year IT project via external consultants, to focus on internal IT instead.
Costs don’t seem significant at £0.5m restructuring, and £1.9m write-off intangibles.
Paul’s view - assuming this update is giving us the full picture, it doesn’t sound like anything to worry about, abandoning a smallish IT project, these things happen.
I remain of the view REC looks an attractive niche business, and EPS has gone up a lot in recent years. The dividend yield is seriously good, at c.8% after today’s drop in share price. Is it sustainable? I think it should be, as this is a capital-light business that pays out most of its earnings as divis each year. Maybe I’ve missed something, as the share price seems to be in a downtrend? Providing nothing goes wrong, patient investors could enjoy a re-rating of this share at some stage, and get paid an 8% dividend yield whilst you wait. Management changes in progress.
Science (LON:SAG)
394p (£179m) - Audited Results FY 12/2023 - Paul - GREEN
Figures were published yesterday. I’m coming back to these as we like SAG here at the SCVR, viewing it as GREEN on both 24/7/2023 (H1 Results), and 22/11/2023 - in line TU.
Figures for FY 12/2023 look good -
Revenue up 31% to £113.3m
Adj operating profit up 16% to £20.5m
PBT is close to operating profit, given that net finance costs are only £526k
Adj EPS up 13% to 33.3p (PER 11.8x)
Diluted statutory EPS is much lower, at 12.0p, so make sure you’re happy with the adjustments, as they’re big, and include a rather generous £2.0m share based payment charge.
Balance sheet is sound I think, with £33m NTAV. Includes £31m of cash, partially offset with £13m of bank borrowings. Note freehold properties are valued at cost of £20.6m, with a open market valuation of a rather bizarrely wide range between £16.9m to £31.6m! Surely commercial property can be valued more accurately than that?
The core consultancy businesses, which generate most of the profit. Then it also has an audio chips business, Frontier, and a submarine related business.
Frontier had a bad year in 2023 (previously mentioned in the H1 results) with a “small operating loss”, but new product development was all expensed through the P&L. It says Frontier should perform better in 2024, helped by improving market conditions and cost cutting.
Acquisition of TP Group sounds like it’s going to plan.
Divis & buybacks continuing.
The Exec Chair has this (below) to say in conclusion. It’s not clear to me what he’s hinting at here? Inviting takeover approaches, taking it private, inability to issue new equity for acquisitions at an attractive price vs cost of acquisitions? Who knows -
For over a decade, Science Group has demonstrated a consistent operating track record, enhanced by a successful M&A programme, delivering a substantial return for shareholders. While the Group has the ambition and capability to accelerate the strategy, the relative valuation of the company against both UK and international comparators may prove a material constraint. The Board will therefore consider all options to address this disparity and deliver value to shareholders.
Paul’s opinion - remains positive. SAG seems to have absorbed the sharp fall in profits at Frontier through its other businesses performing well, and an acquisition.
Maybe the lowish rating on the shares is because SAG seems a strange hotch-potch of different businesses?
It’s effectively owner-managed, with the Exec Chair owning 20.7%, and 5 institutions owning c.50% of the group. So he would only need to make 5 phone calls to get any kind of deal done.
I’m wondering if a takeover bid might come along for SAG? Maybe that’s what the Chairman is hinting at above? Anyway, the shares look pretty good to me, so I’ll happily stick at GREEN.
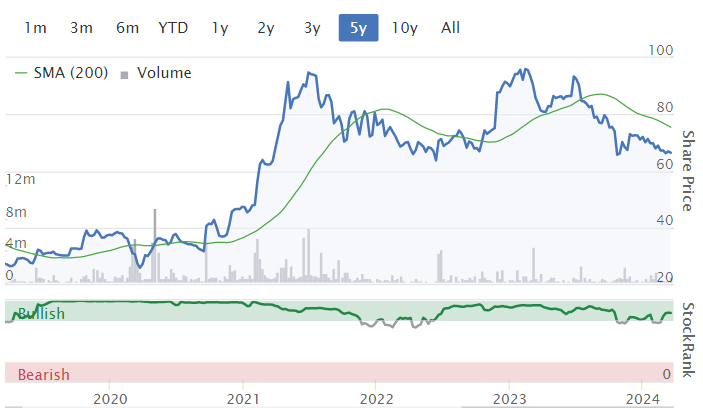
Holding on to most of the 2021 gains is a good performance relative to many other small cap shares. High StockRank too -
Eurocell (LON:ECEL)
116p (£127m) - Preliminary Results FY 12/2023 - Paul - GREEN
Eurocell plc, the market leading, vertically integrated UK manufacturer, distributor and recycler of innovative window, door and roofline PVC products, today announces its preliminary results for the year ended 31 December 2023.
This was on my top 20 list for 2024, hoping for a cyclical recovery to start, and underpinned by a strong balance sheet. The idea being that it would then just be a case of waiting for a recovery to start. It hasn’t worked so far, but it’s early days.
Here’s a nice summary from the company -
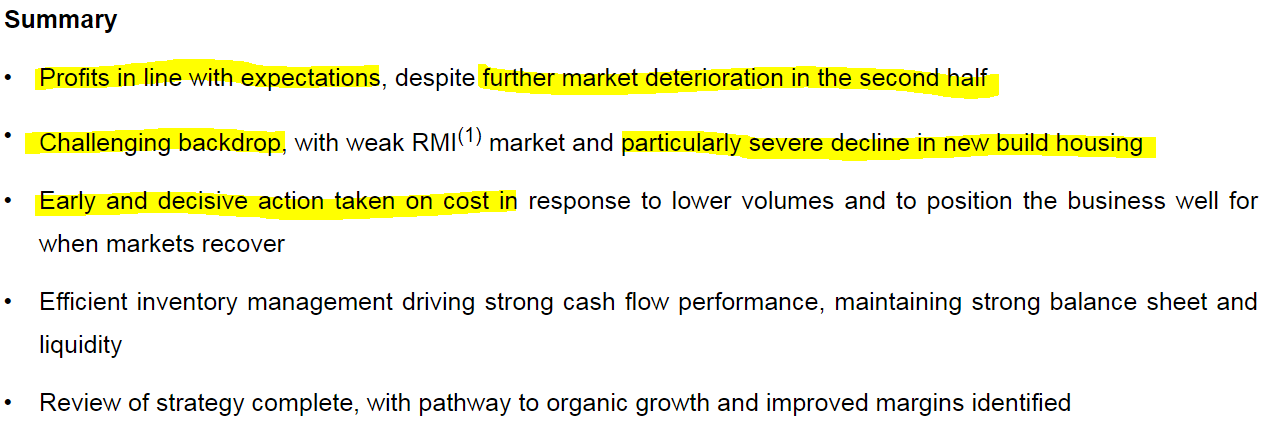
Revenue down 4% to £365m
Adj PBT down 55% to £15.2m
Adj basic EPS down 49% to 11.0p
They nearly caught me out, by switching from % to absolute amount in the change column. So I had to work out my own percentages above (apart from revenue). Sneaky.
Net cash of £0.4m (LY: net debt of £(14.4)m)
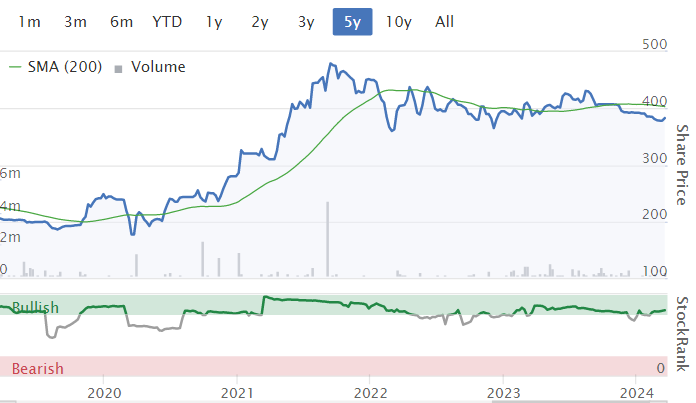
Not a good year then in 2023, but we already knew that, and it’s why the share price is still bombed out, and forecasts have fallen a lot -
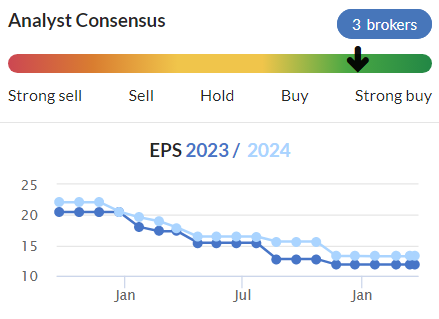
Margin pressure is a concern -
Increased competition for limited demand leading to pressure on margins in the branch network
Divis almost halved compared with 2022. Share buyback of £5m is half completed so far.
Outlook - are they seeing any green shoots yet? Not really, no -
Whilst the near-term outlook for our markets remains challenging, these actions leave us well placed to benefit from a market recovery when it comes.
Our review of strategy is now complete and I am very pleased with the outcome. Looking ahead, we have identified a clear pathway to building a £500m revenue business, generating a 10% operating margin over a five-year period…
Let’s not run before we can walk!
Balance sheet looks very nice, with NTAV of £98m, supporting most of the £127m market cap. No bank debt to worry about, although I imagine it would use a bit of bank debt from time to time in normal daily operations.
Cashflow - is very impressive, even when you adjust for the lease finance charges distorting the numbers.
Paul’s opinion - I’m very comfortable with ECEL, as a securely financed business that has remained profitable even in tough market conditions. Recovery? It should happen at some point, hopefully.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

77 comments
Friday night 5.10pm RNS from Beeks disclosing option conversion and sale of shares by CEO and CFO. Disappointing timing by the broker, clearly underhand, and in my view there is a smallish accompanying taint to Beeks Financial Cloud (LON:BKS) which is unfortunate as I hold them in high regard (I hold).
I had a similar reaction but on reflection I'm not so concerned and it could offer a buying opportunity on Monday depending on the market reaction. I prefer the after market announcement on a Friday to give people a chance to reflect over the weekend rather than announce during market hours where PIs have an unfair disadvantage. Although large in monetary terms, its only 10% of the CEO's total holding and reading between the lines I wonder if this is the reason he needs the cash for a certain settlement without spelling it out: 'This shareholding now excludes 740,000 Ordinary Shares that continues to be held by Mr. McArthur's former spouse'. The CFO transaction is a much bigger share of his total options / shareholding but perhaps he has his own personal reasons and was just taking advantage of the liquidity event offered by the CEO sale to institutional investors. All conjecture of course but one viable explanation.
Yes. There's been no previous RNS about change in the CEO's beneficial holding so it seems the divorce is recent. The last mention was 2019 when she was described as his wife.
Also, as Michael Tee points out on twitter, their renumeration is designed to be through shares/options so they've got to sell some time. In 2023, the CEO was paid 64k and the CFO 126k. Compare that with Tclarke (LON:CTO) which is half their size.
Perhaps there is more to be concerned with in their down-sizing of their auditors.
However, the CEO selling £3.6m of shares does jar slightly - remember some big sales by director/founders in Telecom Plus (LON:TEP) which proved to be the top by a considerable margin, even though they retained a considerable holding, as here.
Edit: Equally as someone famous said, there are many reasons to sell, but only one to buy - so who knows.
J D Wetherspoon (LON:JDW) didn't recover as much as I expected.... down 6% at close. Maybe next week : )
Well done Paul (&Graham) another incredible week of output.
I would like to start off a new 'Quote of the week' post - Friday afternoon frolics, call it what you will....
Paul's Weekend podcast. Having reviewed a company and decided it was rubbish he later returned from the Mary Shelley Witherspoons, in downtown Bournemouth for;
'A Carling infused purchase'
I literally fell off my chair at this one - please keep 'em coming. Have a great weekend all!
Fall of the JDs JD Sports Fashion (LON:JD.) and J D Wetherspoon (LON:JDW) are down by a similar amount today (7%). No further comment from me apart from the fact I'm going to have my favourite tipple tonight (Jack Daniel's). Have a great weekend everyone!
Northern Bear (LON:NTBR)
they have updated an investor presentation on their website for anyone interested , note sure it conatins any really useful info.
Does the fact they have gone to the trouble up uploading this info make me confident they are on track to meet expectations ? i would say mildly yes to that (albeit if broker current forecasts are not included here then ...)
expected earnings growth (eps next year) next year per current stocky forecasts 31%
pe based on 58p and 14.5 eps next year = 4 kinda cheap for that growth !!
we are within 2 weeks of next year being this year as they have 31/3 year end
https://northernbearplc.com/in...
Paul my read of Record is that it is going through a period of change. Leslie and Neil are riding off into the sunset and leaving a new untested management team. In addition their business was low margin and they have diversified and pushed into new areas. I have held this stock for quite a few years largely because of the yield, strength of balance sheet and focussed management team. I have reduced, and I mention this only because you say you may be missing something and this is my guess, having worked in the industry you need 3 factors as a basis for selling your business. An established organisation, tick. An established management team, to be seen and an attractive offering, which I think still has to be proved. So for me it the basics are weaker than they were. I believe they will probably pull it off which is why I still hold some but my level of conviction reflects the added risk. I hope that helps. Whether you can take one persons view and multiply it out I don't know but I too have been wondering why it has been so soft of late.
Paul- Record (LON:REC) is as you say great value at the moment. I have no concerns over the management change going on and Leslie Hill as I recall said she would be holding her stake post retirement. I Hold.
Record (LON:REC) update a tad disappointing but still getting some asset growth. Leslie Hill did a very good job, but possibly had a few too many initiatives on the go, so not a total surprise that at least one won't come to fruition. Still a good prospect for medium term growth. Happy to hold long term and not expensive at today's valuation.
Symphony Environmental Technologies (LON:SYM) A trip down memory lane prompted by Paul's mention of another placing. I took part in their IPO on Ofex at 75p round about the year 2000 and succeeded in turning a decent profit. They had some success with making Tesco carrier bags degrade so I don't know what's held them back. I remember packing away some Christmas decorations and the next year when I picked up the carrier bag from the box they were stored in there was a festive snowfall effect from a disintegrating Tesco bag. I thought I shouldn't have sold out, this seems to work. So what took them so long to make profits, their homeopathic approach to constant dilution must have run out of mugs by now.
Frp Advisory (LON:FRP) FRP looking better today.
A seller has been at it for the past few weeks, bringing down SP. It’s having a strong year, but the SP is in no way reflecting this. Had a strong H1, reported they will "at least meet expectations".
Near its trough, IMO. Decent divie yield. Today, a surge in buying. Perhaps the seller has finished?
Top U.S. asset manager Vanguard doesn’t believe the Fed will cut interest rates this year:
https://www.google.com/amp/s/w...
I have started reducing my US exposure recently after a tremendous performance over the last year+
How on earth can Trakm8 be classed as a 'Super Stock'?
Trakm8 Holdings (LON:TRAK) All the Stockranks are above 50, I think that is the criteria. Figures take a few days to update.
Zotefoams (LON:ZTF) little very perky! Hefty volumes yesterday. Today, registering a 9% rise.
The recent presentation was interesting- and there is considerable potential if the rezorce carton packaging goes ahead. I hold
Zotefoams (LON:ZTF) jumping up today, 9%, after a lot of big trades went through yesterday and the day before, looks like a large seller might have cleared out.
Spread's getting tighter 378-382
Zotefoams (LON:ZTF) possibly due to Nike results?
But Nike (NYQ:NKE) results are not very good?
Nike is rationalising its running shoe offering but focussing on its high performance running shoes which use Zotefoams (LON:ZTF) foam cushioning. So its a good thing for Zotefoams (LON:ZTF) and is aligned with the strong start to FY24 they reported.
It is a bit confusing, as they are reducing forecasts, for the first HY, that is probably why the shares were down 9%. 14 brokers have reduced their profit forecasts. "NKE's direct-to-consumer strategy not driving growth as
expected, say executives, amid losing ground in the running
category"
The switch could benefit Zotefoams (LON:ZTF).
James Fisher And Sons (LON:FSJ) Non-core disposal (£83m) will halve the debt. The oil and gas bus t/o is ~£107m out of total sales of approx £490m, and RMSPumps was just part of that. Richard Staveley (Rockwood/Harwood) thought this could 3-5 bag from 260p. Worth listening to the interview again via the discussions for #FSJ. This looks like the start of that ascent, but WDIK?
It was 22% of sales in 2023 but 11mm Operating Profit is 45% of the total 24.7mm. It does look slightly like a forced sale so they can refinance the RCF.
James Fisher And Sons (LON:FSJ) Agreed, could be a forced sale, but to get to £57m debt from £140m at a stroke does change things somewhat (it was £172m in September 22). It's back to the same amount of debt as in 2012 when sales were lower and the share price was 500p (with the same number of shares in issue). RMSpump is only part of the £107m sales for Energy; Scan Tech AS, Scan Tech Offshore and Fisher Offshore are also part of that number. There is still annualised revenue of somewhat >£380m from good businesses in currently weak markets. The share price recently shows the market is not optimistic about this stock, but given three years there is enough quality left to move towards higher EBITDA multiples. We will see!
How did you calculate these numbers out of interest? Thanks!
Billington Holdings (LON:BILN) Up 12% on largest ever contract win !
Billington Holdings plc (AIM: BILN), one of the UK's leading structural steel
and construction safety solutions specialists, is pleased to announce that the
Group has recently been awarded six new contracts with a combined value of
circa £90 million.
Billington has secured the largest single contract in its trading history to
achieve its largest order book to date, materially ahead of the previous
record in Q1 2023. The contract wins span a variety of sectors including power
generation, manufacturing and retail logistics, and will be delivered
nationally over the next 24 months.
Yes, good news from Billington Holdings (LON:BILN) (I hold). To put it into context, Stocko's annual t/o figures are for years ending December:
TTM £101 mn
2023E £125 mn
2024E £115 mn
So the £90 mn of new contracts will have a substantial impact on the next two years. Of course BILN still has to deliver the contracts successfully and profitably....
RE Billington Holdings (LON:BILN) I an intrigued by the largest shareholder. I cant find out very much about them or what they stand for. Can anyone shed more light on the main holder? I am rather suspicious about large cagey holders, especially after my losses on the IEnergizer fiasco.
The largest shareholder in Billington Holdings (LON:BILN) , Gutenga, is an entity controlled by the founder of Billington - Alexander Ospelt.
My notes show the last sale was in June 2023 at 390p. And there has been some other large chunky sales in 2019-2020, in the 300p to 410p range?
So wondering if we will get further sales into the market, now that the SP is north of 400p+.
Thanks Boon for your explanation on ownership of Billington Holdings (LON:BILN)
Billington Holdings (LON:BILN) If I remember correctly some time ago the board and Gutenga decided that the large shareholding was creating liquidity problems given the company size, and that Gutenga would therefore gradually sell down a proportion of their shareholding as and when feasible, with a view to improving liquidity.
Sigmaroc (LON:SRC) Good to see new non-exec director buy in with 110,062 shares.
Presumably next week we will get more details on the exercise 2nd Target (UK) purchase of CRH's limestone operations, as the option deadline is 28 March and they issued notice to exercise on 3 March.
I hold.
Ocean Wilsons Holdings (LON:OCN) decent preliminary results published this morning and the share price remains approx half of Edison's recently est NAV. At this level of discount, the investment portfolio is in for free. The review of its majority, Brazilian maritime services stake, still ongoing.
ACRL mgmt blaming the market for accepting the offer. Is this fair? Seems low to me.
On January 7th 2020 when Accrol group (LON:ACRL) was 33.70p I noted here that I saw no long term value in a company that “turned large rolls into small rolls”. While I grant that this was a bit flippant (and I got smacked for it!), since then the company:
- has never made a profit, while not quite doubling its sales
- has almost doubled its debt, while increasing its issued shares by 50%
- remains at about 39% of its IPO price and only one Director has increased his shareholding
I am pleased to find there is anyone who wants to take this on and hope that they can do better than the current lot
Generally we need more people like Sir Tim " I named my company after a teacher who said I would never amount to anything" McMad Martin.
My morning smallcap tweet: Paltry premium pinches paper products producer
James Fisher And Sons (LON:FSJ) Riverfort Global Opportunities (LON:RGO) Accrol group (LON:ACRL) Trakm8 Holdings (LON:TRAK) Light Science Technologies Holdings (LON:LST) Record (LON:REC) Billington Holdings (LON:BILN) Intercede (LON:IGP) Robinson (LON:RBN), Skinbiotherapeutics (LON:SBTX)
◄James Fisher (FSJ)► sells RMSpumptools [sic] for £83m (EV £90m). Price is 7.4 x EBITDA. [SP=248 Cap=125m]
◄RiverFort Global Opportunities (RGO)► sells debt and equity linked portfolio for £2.2m. RTO of S-Ventures, a health and wellness co. To loan £1m to S-Ventures. Shares suspended. [SP=0.21 Cap=2m]
◄Accrol (ACRL)► rec offer of 38p, a paper-thin 12% premium. [SP=34 Cap=108m]. I hold.
◄Trakm8 (TRAK)► is cack mate as it warns FY-Mar rev only £16.4m and adj pretax loss £1.4m. Blames large contract slipping into FY25 and a weak Feb-Mar, primarily due to ongoing shortages of insurance capacity. FY25 boosted by said expected contract but also hit by the lower levels of insurance connections. [SP=14.9 Cap=7m]
◄Light Science Technologies (LST)► wins £188k one year gov't grant. [SP=2.9 Cap=10m]
◄Record (REC)► guides FY-Mar rev £45m, in line with market expectations. Abandons R-Platform project and will focus resources on building out its internal IT development expertise. £1.9m write-off and £0.5m one-off reorganisation and professional costs. [SP=66 Cap=131m]
◄Billington (BILN)► wins six contracts worth c.£90m, further underpinning market expectations. [SP=400 Cap=51m]
◄Intercede (IGP)► guides FY-Mar ahead of market expectations. Wins order for a new licence test environment "for an existing US Federal Agency". Better than those orders from non-existing entities we've seen from some companies. [SP=99.5 Cap=58m]
◄Robinson (RBN)► FY-Dec rev down 2% and pretax -£0.7m (+£2.3m). Final div kept at 3p. Guides FY23 rev and adj op profit up. [SP=95.25 Cap=16m]
In line: SBTX
"trakm8 is cack mate" really made me chuckle
Intercede (LON:IGP) new contract win and further upgrade to March ‘24 expectations. However no numbers mentioned. Intercede has certainly been on a roll with the new product announcement from yesterday and todays new contract win boosting March ‘25 contracted revenue backlog.
Hi clanger,
Cavendish has raised forecast profit by c.4% for Intercede (LON:IGP) [I hold]. I've just published a main section on it above. I see your post was much earlier, so it may not have been out by then.
Regards, Paul.
thanks Paul for the write up on Intercede (LON:IGP) it seems that a few companies are reporting ahead of schedule which is promising for this year such as Synectics (LON:SNX) IQGeo (LON:IQG) . Perhaps we are about to breakout of the malaise.
Intercede (LON:IGP) It seems that a few companies are reporting ahead of schedule which is promising for this year such as Synectics (LON:SNX) IQGeo (LON:IQG) . Perhaps we are about to breakout of the malaise.
Or perhaps, as I’ve consistently maintained throughout my professional and subsequent investing career, technology is where you need to be.
You put the crux better than me. Innovation and marketing together are the key.
hi BnB
Or perhaps, as I’ve consistently maintained throughout my professional
and subsequent investing career, technology is where you need to be
I wouldn't disagree. However for those (like me) who don't have a technology background and are of the later in life generation (like me) it's very hard to feel comfortable enough that you understand the products / prospects / marketplace. Too many great stories that are no more than blue sky / rose tinted stories.
I'd be interested to know how you identify suitable investments. Perhaps you could share some of your stronger convictions?
Snazzy
However for those (like me) who don't have a technology background and are of the later in life generation (like me) it's very hard to feel comfortable enough that you understand the products / prospects / marketplace.
This is clearly a risk with smaller, niche names, but you don’t need a tech background to see how Microsoft has infiltrated every aspect of the professional world while providing the operating system and security framework for every personal computer. Or to witness the astonishing success of the iPhone and its ever growing ecosystem. Or to understand that Alphabet/Google owns your online search activity and the associated advertising revenues. And, above all, to recognise that everything has a semiconductor chip inside. After that, marvel at the extraordinary cash generation for which only a basic financial background is required. Buy big Tech, a cybersecurity ETF and a semiconductor ETF and you’re sorted.
You won’t get the niche wins from obscure M&A or surging semiconductor capital equipment makers or the smug satisfaction of reading the tech landscape. But you’ll likely perform equally well investment-wise!
2 of my core tech holdings are semiconductors etf (25% annualised returns last 10yrs ) & Nasdaq etf (18% annualised returns last 10yrs). Sometimes it pays to just keep it simple imo. Cheap exposure to US tech. Tech & semiconductors are building the future as returns show imo.
Hi Joe,
Those annualised 10 year returns are impressive; makes me wonder why I bother trying to pick individual stocks! Do you mind if I ask which etf's you use?
I use the ishares etf's. iShares Semiconductor ETF (NMQ:SOXX) & iShares NASDAQ 100 UCITS ETF USD (Acc) (LON:CNDX) although others are available.
Thanks, Joe.
Would you still advocate investing in technology when the era of 0% interest rates is over? Inflation is back and history suggests only 'real' assets perform.
Would you still advocate investing in technology when the era of 0% interest rates is over? Inflation is back and history suggests only 'real' assets perform.
Semiconductors aren’t real? Software doesn’t promote productivity? Big Tech’s cashflows are illusory? Think how much the world has changed since the creation of the Internet. It will change more in the next 10 years than it has in the last 20. Can you afford not to invest in technology?
Hi BnB (and others)
With regard to the discussion on investing in US tech, and the question posed, is it real? Yes, in my opinion and extensive research it is very real indeed.
Below is a graph showing the YTD performance of a selection of US tech stocks who provide products to different layers of the full technology stack (from chip designers right up to software creators to exploit the power of the chips).
NVIDIA (NSQ:NVDA) design the semiconductors and infrastructure and software which supports the data centers and computing power used by many of the companies in the world. Microsoft (NSQ:MSFT) supports the operating systems most of us use (excluding Apple users) and are now leaders in rolling out AI co-pilots which with infiltrate everywhere. Taiwan Semiconductor Manufacturing Co (NYQ:TSM) make most of the worlds semiconductors (for designers such as NVIDIA (NSQ:NVDA) & Advanced Micro Devices (NSQ:AMD) ) Advanced Micro Devices (NSQ:AMD) compete with NVIDIA (NSQ:NVDA) but offer a different design thus providing an alternative. Palantir Technologies (NYQ:PLTR) supply a whole software stack which knits together data security, integration of multiple data sources, real time digital twins of organisations, use cases to support many industries and latterly integration of AI to exploit users data.
In short, I believe these are all very real assets and are fueling a new era of productivity across the globe. As well as creating new technologies for the world to dig deeply into some of the most challenging problems facing mankind.
I selected these few to illustrate just some of the layers in this tech. sector.
I agree with BnB that you do not need to be particularly conversant with this world in order to invest in it and therefore taking steps into it through a selection of ETFs is a sensible approach.
Regards
Howard
PS I hold all the stocks listed.
We'll have to respectfully disagree on what constitutes 'real'- I don't think it is YTD share price performance of a corp (NVIDIA) now sitting on a PE of 78.
I meant in the traditional sense of 'hard' or physical assets: gold, property, land, commodities etc.
I don't share confidence in the NASDAQ, it is absurdly concentrated in a handful of names. I would caution everyone before they run off and buy a NASDAQ ETF, you do not have the breadth of exposure you think you do:
Hi IncredibleMosesLeroy
With regard to your point ....
'I meant in the traditional sense of 'hard' or physical assets: gold, property, land, commodities etc.'
I am not so confident your examples hold 'real' value. For example property values of CRE (Commercial Real estate) in the US are being decimated to the extent it is increasingly likely some US Regional Banks will indeed collapse as they have large exposures to these 'real' assets.
Google Gemini highlights a couple of examples ....
Absolutely, here are some recent examples of significant drops in US commercial real estate valuations:
Unless China does some extraordinary stimulus I cannot foresee any significant rise in commodities in the near future. If anything we might be heading for a globally synchronized deflation.
In today's climate I am more comfortable betting on chips, tech infrastructure and software than your list of 'real' assets.
I am less convinced about the investing thesis of 'real' assets than I have been in the past.
Regards
Howard
No, I don't think software improves productivity on it's own:
If it did the annual growth in productivity would be substantially above the red line, not below it since 2009-2010. My thesis is that we are witnessing the final stages of a bubble supported by 15 years of 0% interest rates at the exact moment that globalisation has gone into slow reverse.
I will have shorts on the Nasdaq and S&P by June. Best of luck!
Deleted - repeat post
Most commentators would consider established businesses with strong cashflows to be real assets which reward in inflationary times. We saw this in the margin expansion enjoyed by large caps and niche winners with pricing power during the inflation surge of ‘22. And I’m afraid that showing us a chart of the UK’s lack of productivity to illustrate that US software companies’ products don’t promote business efficiency is simply bizarre.
However, your proposed short might briefly work after a very strong run up for the Nasdaq. I think your timing might be quite good. But not for the reasons you suggest. Interest rates are more likely to fall than rise this year and next. Tech stocks are vulnerable to a fall when or if the growth rates actually being enjoyed today turn out to be less sustainable than currently anticipated. That may or may not happen. And I challenge you to leave your short on for half a decade as your thesis demands.
Some big tech are naturally hugely profitable, even without stripping out R&D expenses, and have large cash piles and moats.Of the currently still unprofitable ones growing sales, which were rewarded heavily during virtually zero rate environment, i'm sure some will become winners of the future.I wouldn't like to guess which ones...... but i am invested in some currently loss making cybersecurity tech names as part of what i see as a continuing secular trend.Look at all the outages recently of big businesses like Greggs (LON:GRG), J Sainsbury (LON:SBRY), Mcdonald's (NYQ:MCD) etc.. now that was probably a common 3rd party software provider's fault for many of the affected names, but we'll never know for sure which is a good thing, as that could naturally become a cybersec issue if we did.But could equally have been a cybersecurity issue from the start.. especially with the current geopolitical trend and increasing digitalisation of society.
J D Wetherspoon (LON:JDW) results out. Tim Martin comments (seriously??):
The company continues to be concerned about the possibility of further lockdowns and about the efficacy of the government enquiry into the pandemic, which will not be concluded for several years.
J D Wetherspoon (LON:JDW)
Although he is probably a bit of a nutcase I think Mr Tim is highlighting the fact that the excessive lockdowns we had in this country probably did far more damage than good on pretty much all levels - there seems zero appetite at the top to accept this and to the contrary the powers that be seem to be going out of their way to not accept these facts. Dont get me wrong here the first set of extreme lockdowns were obviously necessary/ made sense based on where we were but really we need to take lessons here otherwise we will be similarly stupid if the same happens again ref going ott - in that regard sir Tim’s rant makes complete sense to me - I understand others will tell him just to get on with running his business and shut up - in that regard mr tim has been fairly consistent over the years !
The problem in fact, which is bourne out by every study across countries who took different approaches, was that we failed to lockdown early enough BOTH times, resulting in the need for lockdowns that were excessively long and restrictive. Boris himself was largely responsible with his dithering and ‘let the bodies pile up’ attitude. Sorry no more politics!!
The problem in fact, which is bourne out by every study across countries who took different approaches, was that we failed to lockdown early enough BOTH times,
i would certainly agree ref first lock down that we spectatulorly failed to act when it wass pretty obvious what was coming our way based on what was going on in italy. ref later lockdowns the evidence is far weaker as the virus clealry became less deadly over time. two wrongs dont make a right though imho clearly as covid was killing far less % of victims than "worst foercasts" the forecasts were obviously making us over react. Anyway my piece is said here apologies for straying slightly ot.
The new variants were actually more deadly until the effects of mass vaccination kicked in.
We also didn't close or control our borders early enough
That would have slowed the spread down as well.
May have been excessive, but you obviously never had a relative that died....
i feel for anyone who lost a relative does that mean we shouldnt discuss the matter if it might impact future company affairs ? presumably not , not sure it adds to the conversation getting personal and trying to guilt trip people for simply responding to points made by others and having an opinion.
Getting to the technical part of the info posted is there anything factually wrong with the conclusions of the experts highlighted by Tim?
"The conclusion of Professor Balloux, broadly echoed by Professor Dingwall, based on an analysis by the World Health Organisation of the pandemic, is that Sweden (which did not lock down), had a Covid-19 fatality rate "of about half the UK's" and that "the worst performer, by some margin, is Peru, despite enforcing the harshest, longest lockdown."
"Professor Balloux concludes that "the strength of mitigation measures does not seem to be a particularly strong indicator of excess deaths
note part of Tim's point here is that the government enquiry will not conclude for several years - the best thing we can do to minimise later deaths is to have proper scientsits doing proper scientific work with clear conclusions free of political influence quickly - that would serve much more purpose than the powers that be doing very little over long period of time as that probably suits them to poas teh buck to a time when they wont be around.
Better to keep politics off this board. Look at the mess on ADVN which did not clamp down on this.
Too much clamping down on things already on this board.
I agree with the general point ... but I don't think Stocko would benefit from a zero tolerance approach. I think there has been more than enough censorship here of late.
I think the medics were advocating 'herd immunity' rather than lockdowns in the first instance, Boris was guilty of following the medical advice
I dont think that's true. Medical advice was to lock down as hard and as quickly as possible.
J D Wetherspoon (LON:JDW) - thats just the opening comments - there's a great deal more positive info there in the following pages - and Yes its what you expect from Tim.
Well at least he is no longer banging on about the EU.
One part of the J D Wetherspoon (LON:JDW) results caught my eye... The roll out of the franchise model. This could create a bigger business with a decent profit margin. The fact that they have rapidly created 3 units on this basis and are considering more sounds promising.
Quite surprised by the markets negative reaction to the results. Especially on an "up" day. 7.5% down as I type. I wonder where they'll end the day? My guess is higher than they are now - but we'll see.
J D Wetherspoon (LON:JDW)
i think share price reactions with pub results is always likely to be very random - i think there are often so many moving parts its hard to work out what the important issues are. I suspect debt being up never helps- they are were they are in that regard though and there is no doubt that reverting to freehold should pay good rewards to shareholers long tem as long AS long as they dont need to go cap in hand to the market again to do that. Tim is probably the kind of guy who would probably want to buy back the extra shares issued to get back to pre covid position when funds allow -at present with their elevated debt options may be somewhat limited in that regard. All in its as its always been a nice simple company making real money - only questions are whether to trim back when price is up with events and whether to add more when price is "reasonable"