Small Cap Value Report (Fri 23 Aug 2024) - ADF, MCG

Good morning from Paul!
Very quiet for news today, so I spent most of the morning having a proper dig through the placings/acquisition for ADF, which is quite interesting. Sorry it took so long, but that's up now. Also some important new information (good and bad) from Mobico (LON:MCG) (I hold).
That's it for today, and the week. I hope you enjoy the long weekend :-)
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 26/8/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
Summaries
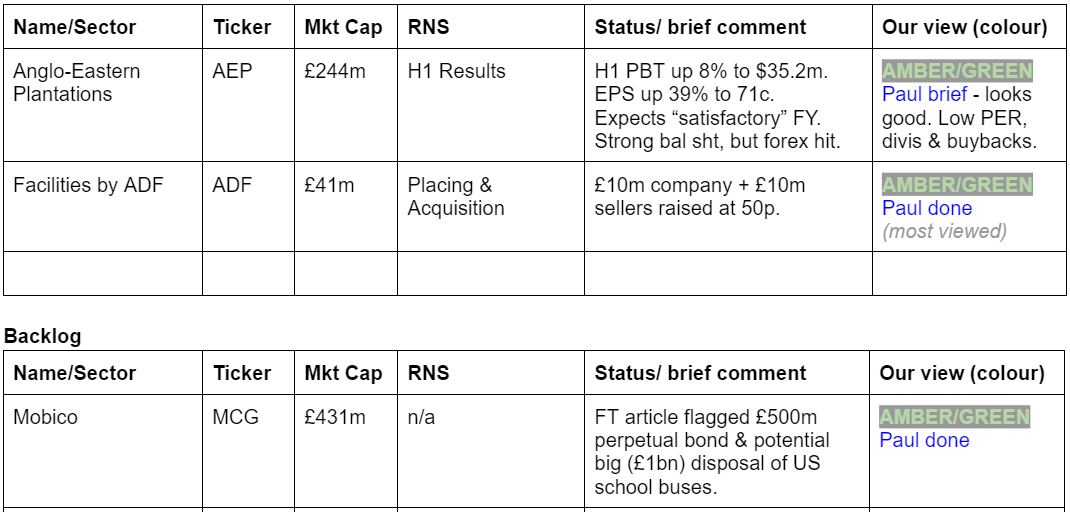
Facilities by ADF (LON:ADF) - Unch at 51p (£41m - pre dilution) - Acquisition & Placings - Paul - AMBER/GREEN
I very much like this acquisition, it seems a great fit, reasonably priced, and funded prudently through a 50p equity raise, and self-funding earn-outs by the looks of it. A soft H1 in 2024 means there's a risk of another profit warning later this year, but despite that the 2025 upside looks good, so I'm upping my view from amber to AMBER/GREEN. It's possible I'm being too cautious here, this one was nearly green.
Mobico (LON:MCG) (Paul holds) - 71p (£431m) - Disposal & FT article re perpetual bond - Paul - AMBER/GREEN
A recent FT article flags that the US school bus division disposal underway could produce a blockbuster disposal up to £1bn. Bank of America thinks £400m is more realistic. So a wide range of outcomes here, but in either case it would greatly reduce, or even eliminate disclosed net debt. However the FT also flags that MCG has £500m of off balance sheet debt, in a perpetual bond, which is designed to be disclosed as equity. I try to explain it below.
Paul’s Section:
Mobico (LON:MCG) (Paul holds)
71p (£431m) - Disposal & FT article re perpetual bond - Paul - AMBER/GREEN
I covered international bus/coach group in some detail here on 21/8/2024.
Some more information has come to light, which I need to flag to you.
Firstly the good news. An important article in the FT flags that the US school bus division could be worth up to a staggering £1bn, and works through its rationale for that huge valuation, based on previous deals in the sector, where MCG is the no.2 player, and a good turnaround is underway. This seems to be based on a note from Jeffries, which of course we don’t have access to.
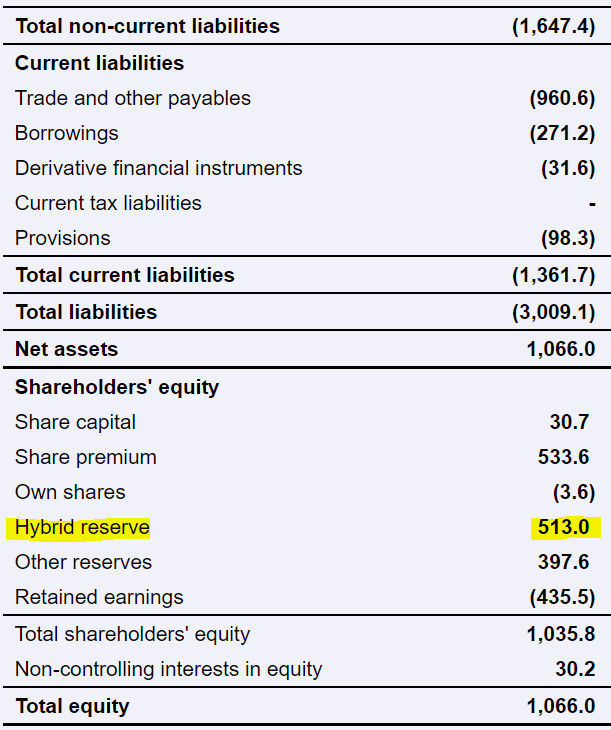
Now the bad news. The same FT article flags that MCG has a £500m perpetual bond in issue, which is a form of off-balance sheet debt. I was not aware of this previously, so am very grateful to the FT for flagging this important point. For the first time ever, I read a bond prospectus from start to finish, understanding most, but not all of it! This perpetual bond was issued in Nov 2020, bringing in £500m of cash, however it’s structured so that there are no repayments required, it’s perpetual. Plus the interest payments are optional, and called dividends. Hence apparently under accounting rules, this has been creatively structured so that it’s classified as equity, not debt, hence does not appear as a liability on the balance sheet. Instead the credit entry is shown in the separate reserves section of the balance sheet as equity (alongside share capital & share premium accounts) - a section that hardly anyone looks at.
I have never come across this type of perpetual bond financing before, so thought it was such an interesting situation, that I would flag it to you.
Here it is lurking in reserves, not within assets/liabilities in the main section of the balance sheet, because technically this £513m never has to be repaid, so it’s treated as a form of equity -
I didn’t spot this when doing my review on Weds. However, I did spot an item on the cashflow statement which perplexed me, namely a cash outflow in both 2023 and 2022 of £21.3m -
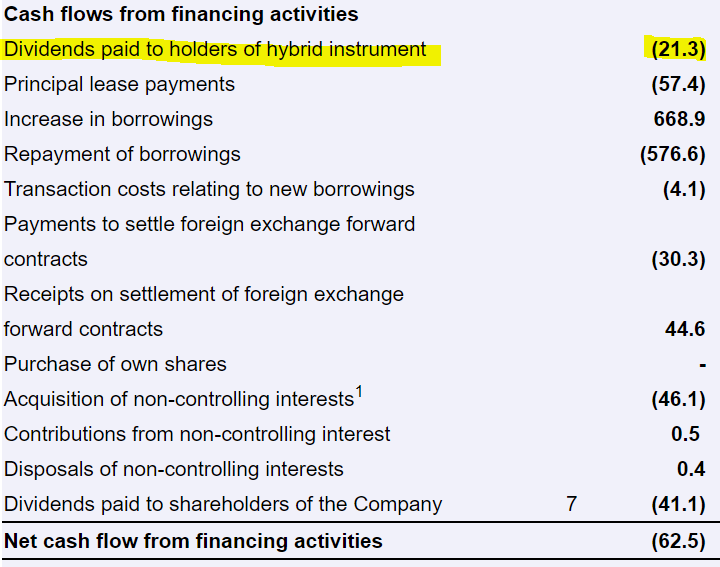
Therefore there are 2 ways of looking at this hybrid bond -
It’s disguised, undisclosed debt, which is what the FT is saying (and I’m leaning towards seeing it that way too), or
Not debt, as it never has to be repaid, but is instead an annual £21.3m cash outflow. I think MCG adjusts for this in its EPS calculations.
There are some circumstances which trigger repayment of the perpetual bond, eg insolvency or takeover I think, but let’s skip over that. In normal circumstances, all MCG has to do is pay the £21.3m pa divis, and the debt just sits there forever - just like equity receiving normal dividends, but never getting repaid. The perpetual bonds are traded on bond markets, so that’s how holders can cash out if they want, and currently trade at about 92, below par (hardly surprising give that base rates rose greatly after this bond was issued in the zero interest rate period).
Another complication here is that the interest rate payable (currently 4.25% pa coupon, despite the prospectus saying its a 5.25% coupon, and was issued at par). So there’s a query here on what is the actual interest rate? Moreover, another query is how the interest rate reset mechanism works? Maybe our resident bond specialists could clarify this? It did talk of a margin (over what? Base rates maybe, or the risk-free Govt bond rate?) and a consultant who is authorised to calculate and reset the bond's coupon interest rate every 5 years. Hence a key question is whether the attractively low coupon of 4.25% (costing £21.3m pa, making this a cheap form of financing for MCG) might see a sharp increase in the cash outflows when the rate is next reset upwards?
Call dates & terms. MCG has the option, but not any obligation, to repay (“call”) these perpetual loans once every five years. I’m thinking that if the annual finance cost remains at a low 4.25%, then it would make sense for MCG to not call (repay) this hybrid bond, but instead focus debt reduction on its other bonds & private placement, which are substantial.
Paul’s opinion - sorry I missed this very important point last time. Discovering £500m of (arguably) undisclosed debt at a £431m market cap company is a bombshell. There again, it’s more accurate to say that details were disclosed, it’s just that I didn’t spot it until flagged by the FT. So I wonder how many other investors here are aware of and understand the perpetual bond, and how many don’t? The big shareholders who have been in for a while will definitely be fully aware, but some PIs, like me, may not be aware of the perpetual bond, if we hadn’t gone all the way back through the RNS to almost 4 years ago when it was announced. Just shows doesn’t it, cutting corners on research can be dangerous. As I say though, I’ve never come across this issue before, in my 25+ years investing, I thought off balance sheet financing was a thing of the past, but clearly not.
Overall then, there could be unexpected, and maybe very large upside from a successful disposal of the US school buses division. If the disposal is anywhere near £1bn the FT quotes, then I think that would seriously put a rocket under this share, as that would wipe out all its disclosed net debt (but not the £500m hybrid bond of course, which never has to be repaid anyway, it’s just a cash drain for the interest costs, called divis).
However, the Times quotes a note from Bank of America, saying it expects the school bus disposal to raise a much smaller (but still very handy) £400m.
It’s more complicated than I previously realised, but I still like the turnaround potential, and the core Spanish business is trading really well. If a bumper price can be achieved for the US school buses, then that could be transformational. However, discovering £500m of off balance sheet debt has unnerved me. Hence I’m trimming back from green to AMBER/GREEN.
Facilities by ADF (LON:ADF)
Unch at 51p (£41m - pre dilution) - Acquisition & Placings - Paul - AMBER/GREEN
Quite a decent business this one, it hires out mobile facilities (e.g. production offices, makeup studios, etc) to the outside broadcasting industry, so films/TV. Obviously it was clobbered by the impact of the Hollywood strikes in 2023, and recovery has been somewhat hesitant since - reminding me of Zoo Digital (LON:ZOO) which has said similar things about the sector.
Graham gave it a GREEN on 29/2/2024 despite a profit warning, as he prioritised eventual recovery.
I was a little more hesitant on 29/4/2024 (reviewing the FY 12/2023 numbers and future outlook) at AMBER, because it seemed to me that the hesitant recovery at that point made 2024 forecasts look unrealistically high. So I’m expecting a proper recovery in 2025, not 2024, implying another profit warning could be in the pipeline, if I’m correct.
Last night ADF announced this -
Proposed Acquisition, Primary & Secondary Placing
Acquisition of Autotrak Portable Roadways Ltd. - “one of the market-leading suppliers of portable roadway” - conditionally agreed to buy it for up to £21.3m. Initial consideration is £10m cash, plus 5.92m new ADF shares (worth £2.96m at 50p each, with a 2-year lock-in for half these shares).
Earn outs of up to £4.2m (£1.4m pa) in cash, if 2023-2027 performance is at least equal to 2024 forecast performance. An additional possible earnout of up to £4.0m payable in cash in 2028, based on profit growth. I like the way this deal has been structured, as the earn-outs look like they should be self-funding.
We’re told that in FY 12/2023 Autotrak generated £8.3m revenues, and £4.3m u/l adj EBITDA.
I’ve looked up its accounts at Companies House (co. no. 02999669 - created Dec 1994, so it’s been around for a long time, a good sign), but unfortunately they’re abbreviated accounts with only a balance sheet. NAV rose by £1.87m from Dec 2022 to Dec 2023 (ending at £6.6m, which includes £3.0m of tangible assets and £3.7m of cash). From that I Can deduce that it must have made £1.87m profit after tax and dividends in 2023, a very nice outcome. Renting out portable roadways is clearly a lucrative business, generating a very high return on capital - the NBV of its portable roadways is only £1.2m. It bought a freehold property for £946k in 2023). So based on the limited information available, this looks a good acquisition I’d say.
ADF says it has a good existing relationship with Autotrak, so they know what they’re buying - something I always look for when companies do acquisitions. It’s an obvious & logical fit with ADF, so I think this deal makes a lot of sense with cross-selling, co-ordinating contracts, etc.
“The Acquisition will be significantly earnings per share accretive following integration into the Group.”
I wonder why the vendors want to sell? That absurd phrase is included, to howls of derision from many people reading the RNS I'm sure -
"Sale of not less than 20,000,000 Sale Shares at the Issue Price on behalf of the Selling Shareholders in order to meet strong institutional demand."
Utter rubbish! They're selling because they want the money, and there just happens to be institutional demand which has allowed them to sell. I thought this misleading and inaccurate phrase had been consigned to the dustbin of financial history, but it sounds as if Cavendish didn't get that memo!
Strategy - I’m much happier with this approach below, than the previous strategy of trying to expand into Europe, which was a really bad idea in my view -
“The Acquisition is the next step in the delivery of the Group's vision for ADF as a one-stop shop for film and HETV production, operating across multiple businesses and run by talented local management and accelerates ADF's diversification of product offering and customer base, including across complementary industries.”
Placing - the first one is to raise money for ADF, to fund this acquisition. It’s raising £10.0m at 50p (6% discount is reasonable), so 20m new shares. Costs are an outrageous £0.9m. Surely of all the reforms needed to UK markets, ending this gravy train needs to be a priority? We need a quick, cheap, electronic way for existing listed companies to raise fresh equity, giving proper -re-emption rights to all existing holders. The current placing system is woefully outdated, expensive, and unfair. Leaving shares trading for weeks, whilst discounted fundraisings are secretly in progress is absurd, and an open invitation for insider dealing - rarely detected or punished.
This placing is cornerstoned by two institutions, putting in the bulk, of £7.6m. It’s great to see institutional appetite for small placings returning, let’s hope this is the start of the UK market resuming the key function of providing capital to decent growth companies. I’m very encouraged by this.
Retail Offer - at £0.5m is barely worth mentioning, but better than nothing I suppose.
Selling Shareholders - not good. Why do they want to sell, when there is apparently good upside on ADF shares? A secondary placing is happening to allow existing holders to dump 20m shares. Who are they? Details here -
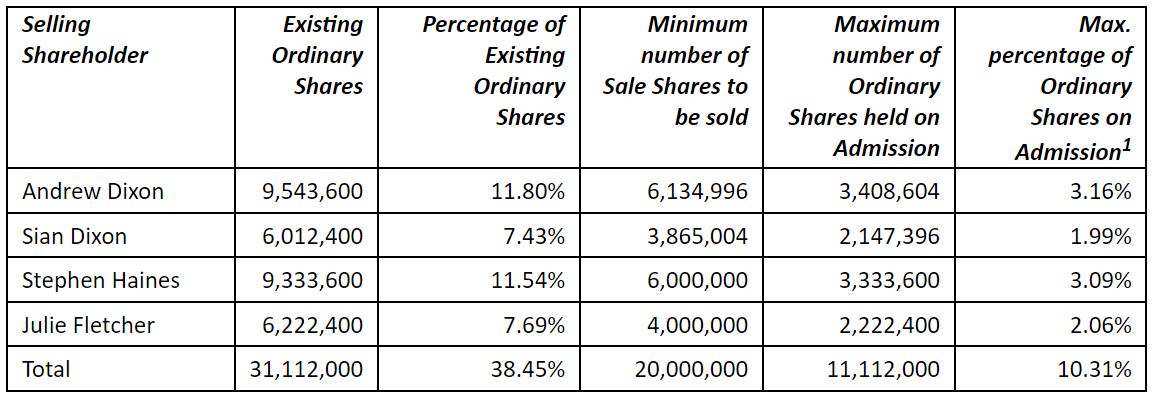
It’s bound to raise questions when holders of 38% want to dump most of their shares.
Current trading - sounds encouraging, but I don’t see any reference to performance vs market expectations -
“Following the end of the strikes in November 2023, and the continued growth in demand for ADF's services as evidenced by the current order book, the Company expects the financial performance in the six months ended 30 June 2024 ("H1-FY24") to be significantly ahead of the H2-FY23. [Paul: I should hope so, as H2-2023 was very weak, a £(2.1)m LBT]
Although the impact of the strikes on the film and HETV industry has carried on into the first few months of 2024, with producers having to reorganise the schedules of all relevant parties, ADF expects the situation will continue to normalise as the first half of the year progresses before returning to a full second half, more in line with pre-strike levels. Underlying market drivers still provide high confidence that the demand for ADF's services will continue to expand over the medium to long term. “
So I think that’s code for a weak H1, and an H2-weighting for 2024.
There’s H1 guidance here -
“the Company currently expects to report unaudited H1-FY24 revenues of approximately £15.2 million and H1-FY24 adjusted EBITDA of approximately £2.5 million.”
Last year FY 12/2023 adj EBITDA was £7.3m but adj PBT was only £0.9m. Hence the gap is about £3.2m per half year. So I can translate the H1 2024 guidance of adj EBITDA at £2.5m into an H1 loss before tax of c.£(0.7)m. Therefore expect weak H1 results when they are announced in mid to late Sept. Although the market may well look through the soft H1, if it sees evidence of the expected industry recovery in H2, who knows. Plus of course there should be some benefit from the Autotrak contribution towards the end of 2024.
Broker update - Cavendish helps us with revised forecasts, now expecting 5.8p adj EPS (which I think is likely to be missed), and a very nice jump to 8.8p in FY 12/2025 based on a full industry recovery, and a full year contribution from Autotrak. Maybe those figures are a bit too optimistic, but if it gets anywhere near the 2025 forecast, then the current share price of 52p would probably have moved up nicely, to maybe something like 75p? Cavendish has a target share price of 93p, which looks entirely possible if the forecasts are achieved.
More acquisitions - are in the pipeline, with surprisingly good details provided today. A disciplined approach of paying 46x maintainable EBITDA, and using a mix of cash & shares, with self-funding earn-outs, strikes me as spot-on.
Paul’s opinion - with 21m new shares being issued, the share count goes up from 80.9m to c.101.9m, a 26% increase. That looks fine, given that the acquisition is strongly profitable. I like the structure of the deal, with earn-outs probably being self-funding, and motivating the sellers who will remain in situ running Autotrak. I wonder why they decided to sell? It could possibly be something to do with potential tax changes maybe, who knows?
My main reservation here is that I think ADF has glossed over its weak H1-2024 trading. Hence hitting full year targets looks difficult, and I suspect it might be heading for another profit warning in late 2024. That could be a banana skin in the short term, although if markets are bullish they might well look through it, if the 2025 outlook points towards a full recovery after the lingering impact of Hollywood strikes. We don’t really know if the big spending by streaming companies was a one-off, or is likely to recover?
I’ve liked ADF since it floated, as a reasonably priced, decent business. Its achilles heel is gaps in utilisation. We’ve seen before that it’s nicely profitable when large, long contracts are won, but struggles a bit when projects are shorter, with down-time in between contracts. Hence it’s always going to be vulnerable to lumpiness and the occasional profit warning, in my view.
Finances are sound, with NTAV c.£19m at Dec 2023. Raising equity to fund this good quality acquisition looks prudent.
This is a situation where apparently Brexit might have been both a hindrance (ruling out European markets for its UK fleet), but also a benefit since this also closes off the UK market to European competition. Buying complementary UK businesses is a much better strategy than trying to compete in unfamiliar European markets, in my view.
Overall, I’d have gone green if it hadn’t been for the challenging H2-weighted forecast for 2024, so hoping to dodge a profit warning, I’m more comfortable at AMBER/GREEN for now (up from amber last time).
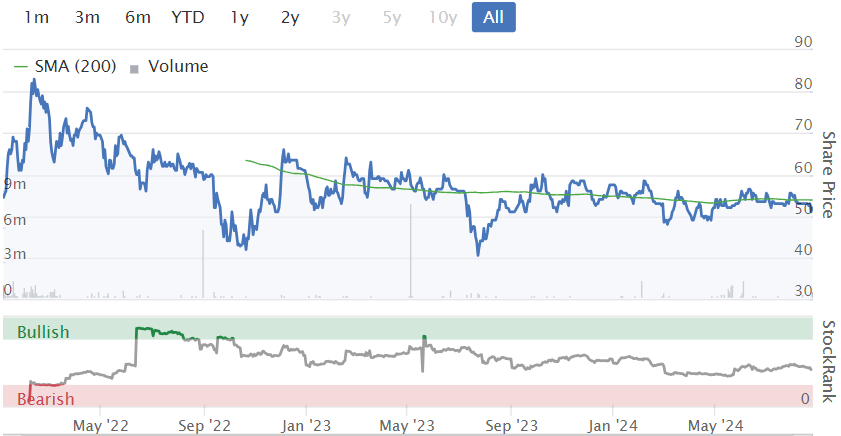
Share price has held up well since listing, if you allow for the fact that 2022-23 was a horrible bear market for UK small caps, and that ADF also had major industry disruption from the Hollywood strikes in 2023. Considering all of that, I think this performance is more than acceptable -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

55 comments
Paul, many thanks for your in-depth analysis on Mobico (LON:MCG). Very much appreciated.
My pleasure triktrak! I'm annoyed with myself for not properly understanding the perpetual bond when previously looking at Mobico (LON:MCG), so big thanks to the FT for flagging it.
Best wishes, Paul.
Ocean Wilsons Holdings (LON:OCN) RNS just released re possible sale of Wilsons Holdings in which they hold 57%. Share price moving nicely north.
Nice spot. This could be the catalyst for a re-rating as part of their strategic review? Managed to pick up a few in any case.
Am I right in thinking Ocean Wilsons Holdings (LON:OCN) stake in Wilsons is currently worth c£550m? Based on 7.26b BRL. So £100m more than the m/c with the investments in for free?
I guess they have tax to pay on any sale?
Good morning all, I haven’t had the chance to read through Pauls thoughts on ADF yet but some might find it useful that I work in the film industry particularly outside locations and have noted having a lot more contact of late with ADF facilities which may indicate their winning more contracts as the industry begins to recover from its set backs. I have also heard from those on films sets that ADF have purchased a company called Location One which specialises in plant hire to the film industry such as generators, portable toilets etc.
I have not checked any of this out for myself, so don’t shoot me if it’s rubbish but its an observation whilst at work and talk around the coffee machine!!
Location One was taken over by Facilities by ADF (LON:ADF) 1 December 2022. From their RNS:
Facilities by ADF plc
("Facilities by ADF", "ADF", the "Company" or the "Group")
Acquisition of Location One Limited
Complementary services create an expanded Group offering as investment in the UK Film and TV industry continues to accelerate
Facilities by ADF, the leading provider of premium serviced production facilities to the UK film and high-end television industry ("HETV"), today announces the acquisition of Location One Limited ("Location One") ("the Acquisition"), the UK's largest integrated TV and film location service and equipment hire company. The Facilities by ADF and Location One businesses are well known to each other, with a successful history of working together on a wide variety of productions since Location One's conception.
With respect to the issue of large insiders selling share this is not as bad as it looks. I have been a holder in ADF for some time and we have had three placings where these holders have sold shares. They are mainly the founders who no longer work in the company getting out and they have created an overhang that we have known about for 18 months. Post this deal they hold 13% of the shares ( need to check that is post dilution but I assume it is) and I am told that they are now happy holders as keen to just pick up the income on this holding. 12 months ago they held 50% of the stock so I am personally very glad this stock has gone to the hands of new and existing institutional investors. There has historically been a seller who sits on them at 59p so if they get there we will need to see if he resurfaces or not. I like the space and the management are very sensible people. One day this probably gets taken out by Ashtead or another larger industry player. The only question I have ever had is are they depreciating the rental vehicles correctly as if they are wrong about residual values then one day we get a horrid write down.
As I reported last week, still plenty of Facilities by ADF (LON:ADF) vehicles working in the Richmond area . Just passed another load of them parked near the Stoop rugby ground in Twickenham . Work definitely seems to be picking up, so happy to remain a shareholder
Home Reit (LON:HOME) sneaks out a glimmer of light that long suffering shareholders, of which I'm one, will eventually get a return of (some) capital.
This company certainly proved the old adage that the best way to make a small fortune is start with a large one.
Posting of Circular
Further to its announcement of 16 July 2024 regarding the proposed implementation of a managed wind-down strategy (the "Managed Wind-Down"), the Company today announces that it has published a circular (the "Circular") containing details of the proposed changes to the Company's investment policy and notice of a general meeting to be held on 16 September 2024.
The Board are proposing to amend the Company's investment policy in order to effectively implement the Managed Wind-Down strategy for the Company pursuant to which the assets of the Company would be sold with the objectives of optimising remaining shareholder value and repaying the Company's loan balance (the "Proposal").
The text of the Chairman's letter, which includes the rationale for the Proposal, together with the expected timetable, have been extracted from the Circular without material amendment and are set out in the Appendix below.
The Circular also includes a notice of general meeting of the Company to be held at 8 Bishopsgate, Level 1, London EC2N 4BQ on 16 September 2024 at 10 a.m. (the "General Meeting").
The Circular will also be available on the Company's website (http://www.homereituk.com).
Some news if you follow uranium
Kazatomprom is the world's largest uranium producer generates and a fifth of global uranium supply. It has reduced its 2025 production target by 17% due to delays in projects and shortages of sulphuric acid, which is crucial for uranium extraction. This cut, from 30,500 tonnes to a range of 25,000-26,500 tonnes, is likely to push uranium prices higher, as global demand for nuclear fuel continues to rise, especially after the energy crisis sparked by Russia's invasion of Ukraine.
The supply constraints are a significant concern for utilities, which rely heavily on uranium for nuclear power, and they are willing to pay high prices to secure the fuel. Kazatomprom's difficulties are exacerbated by geopolitical tensions, particularly Russia's growing influence in Kazakhstan, and its own internal challenges, including low inventory levels and recent executive departures.
In addition to these issues, Kazakhstan's sulphuric acid supply is strained due to delays in new plant construction and competition with other industries, adding further pressure on uranium production. Analysts expect Kazatomprom to struggle to meet its production targets, leading to a tight market next year and potential revisions to agreements with the Kazakh government.
Imo Yellow Cake (LON:YCA) is the Uranium play trading below NAV at the moment.
Yellow Cake (LON:YCA) decent discount to NAV need to find some cash for this.
Yellow Cake (LON:YCA) NAK Kazatomprom AO (LON:KAP) production cut news the same week as China announce approval of another 11 reactors.
Even if NAK Kazatomprom AO (LON:KAP) can increase production, it's mainly all spoken for by China & Russia.
Canadian Cameco Cameco (NYQ:CCJ) is the second-largest uranium miner in the world behind National Atomic Company Kazatomprom. It also refines and produces fuel rods for nuclear power plants. 2024 Cameco acquired 49% of Westinghouse who built nuclear reactors and also SMR (Small Modular Rector) and a Microreactors.
Downside is we are down the solar/wind path and no going back so demand will be good but not a renaissance.
Centrus Energy (ASQ:LEU) are developing enchanced uranium pellets on US soil to support new more efficient and modern nuclear plants and the need to develop and secure supplies before the thing fires up.
So one safe and one riskier hold on the industry.
An ETF will pick loads of players which you will never have herd of or have time to research. I like Sprott as more mining centric than trying to cover every sector but Wisom, iShares, HanEtf all have versions.
There are serious issues with connecting DC renewables to our AC power systems at domestic levels. This will work out over time by those selling inverters and believe batteries to balance the loads. In the meantime gas/coal/nuclear will be the good old reliable banger keeping the lights on.
QQ as it's a quiet Friday
Anyone who cares to answer, What share do you think offers best value at the moment? I actually have some cash in my ISa which is very rare and really can't decide where to spend it. I've missed some great opportunities over the summer holidays, the ones i'm interested in look peaky.
Have a read of Mark Simpsons latest set of articles.
NewInvestor1972
Maybe International Personal Finance (LON:IPF) Has risen a lot since May but still has great scores on Stock including V = 95 and overall 100. Good divi. too.
Gulf Marine Services (LON:GMS) looks decent to me below 17p (seller in play) Again decent Stocko scores. Long term hold. Paul quite likes it too I think. (I hold both)
Some good ideas on Mark Simpson's post as cadmunkey says
Are you looking for trade or an investment? Please don't say both!!
If the latter, I agree that Gulf Marine Services (LON:GMS) looks interesting at this level. But you’ll be waiting for any significant gains, should they eventuate.
If the former, head to the Stage 2 thread!
Thank you, I'm looking for an investment rather than a trade, something with long term potential, I don't like the phrase but 'multibagger potential',
NewInvestor - Beeks and Corero are my largest and most confident holdings for sticking in a bottom draw and waiting until the takeover happens. No idea if they will be cheaper at some point but sure that they will be one day multibagger. Plenty of info available on Stocko and elsewhere.
Thanks Roger, I'm always wary of getting in on a spike and sitting on a loss for ages, That's what put me off Beeks Financial Cloud (LON:BKS) , sometimes have to let the bus go and wait for the next one
NewInvestor, for what it's worth I sat on both those companies for ages at a loss - in the case of Corero over 60% down - then topping up substantially sub 3p. Speculative then but now they have got to the point they aren't likely to have to worry about running out of money. And their potential market is massive.
Thanks Roger, and well done for spotting the potential early and sticking with them!
I hope I don't get shot down for being pedantic but over the last several months I have noticed several investors writing about a bottom draw. Actually, the expression is that you put something in your bottom drawer (of your chest of drawers, where traditionally young women would collect linens until the happy day came when they married and could bring those linens into the marital home).
I bet that's been playing on your mind for ages murrb :)
Not pedantic at all, every day is a school day.
One that gets my goat is 'don't loose money'
It depends on how you define value, but there are many. For me the following represent good value, but they are all from my portfolio, so beware the bias.
VP (LON:VP.)
Sigmaroc (LON:SRC)
Michelmersh Brick Holdings (LON:MBH)
Van Elle Holdings (LON:VANL)
Brickability (LON:BRCK)
Volex (LON:VLX)
Avingtrans (LON:AVG)
All bar Volex (LON:VLX) and Avingtrans (LON:AVG) are to a greater or lesser extent picks and shovels plays on an improving outlook for UK construction, housebuilding and infrastructure, which is yet to materialise. Michelmersh Brick Holdings (LON:MBH) and Van Elle Holdings (LON:VANL) have cash on the balance sheet.
Avingtrans (LON:AVG) looks expensive on a conventional PE view, but the share price fails to reflect the value of its engineering business, which is driving profitability with exposure to regulated industries, notably nuclear. The potential of the medical division that currently consumes cash and makes no profit contribution is in the price effectively for free.
Volex (LON:VLX) despite the recent share price rise still looks cheap to me. The management team under Nat Rothschild have executed very well and made a number of astute acquisitions without overpaying. Also as previously posted Nat owns >25% of the equity and has never sold a share. A PE of 15, which seems reasonable would give a share price of about 440p
Safety
Greggs (LON:GRG)
Financials
International Personal Finance (LON:IPF) - on pull back
Frp Advisory (LON:FRP) - #1 player for administrations, likely to benefit from debt restructuring and corporate advisory as rates fall
Mortgage Advice Bureau (Holdings) (LON:MAB1) - interest rate cuts / housing recovery
Polar Capital Holdings (LON:POLR) - good yield as it recovers
Underrated
Fonix (LON:FNX) - quietly growing cash machine
Tristel (LON:TSTL) - easy to use product with moat gaining traction
All pay dividends and positive return YTD
Here's one out of left field, that you will not find in any screen, and certainly will never be covered by Paul and Graham.
Quanterix (NMQ:QTRX) . There is a lot of discussion today about new wonder drug Lecanemab which will be used to help slow the effects of Alzheimer's. Talking to some who works in this field, you need to get in early for the drug to work and that is where Quanterix (NMQ:QTRX) comes in.
They are in collaboration with Eli Lilly and Co (NYQ:LLY) working on early diagnostics of Alzheimer's. My "friend" reckons there could be some interesting news shortly.
It's a very volatile share at the moment, and could go to Zero or Hero. Anyone else who deals in U.S shares have this one come across their radar?
Hi NewInvestor1972,
One of the shares I hold and I like the look of is Synectics (LON:SNX) .
I have 10 different Search Screens which I use to find what I believe to be the best shares to invest in. SYNECTICS appears in 5 of my 10 Search Screens.
Q 88
V 83
M 90
SR 98
The share has gone sideways so far this year so it hasn't yet broken out which is why I believe it still has excellent value. It looks like it is getting ready to breakout and it is up +8.6% so far this month.
David.
David
Coincidently, I contacted Stocko a few days ago with the query:
“I use a copy of a screen created by the Stocko team called Screen of Screens. I assume this is somehow run against the ‘output’ from numerous Guru screens.
Would it be possible to create a version that can be run against selected screens in MY SCREENS ?”
Response was:
“Hey, Not at the moment. This may be something we do in the future though. Your feedback has been noted.”
Hi David,
would you mind sharing your screens? I read through your Bio and can really stand behind your approach of investing!
I am pretty new to Stockopedia, so I hope it is fine that I blatantly ask like that.
Take it as cash, buy some small denomination gold - those snap off things, or buy the wife a nice bracelet or two, and bury it under concrete where can forget about it. Called an inflation hedge. Just don't 'forget about it' lol. Can consider a Rolex but too flashy and won't hold onto it for long methinks in our modern world.
Tribal (LON:TRB) H124 results presentation by management earlier this week video & podcast. Improving ARR, EBITDA & FCF.
Logistics Development (LON:LDG) [investment company] Perhaps not one for here, as I see it has not been covered on SCVR before, but would be interested in any opinions on this one. (I HOLD)
From todays release:
Stake in Finsbury Foods (Owns 27.5%) is £39.5M [assuming it is still valued at the takeover price]
Stake in Alliance Pharma (71,165,281 shares) is £25.9M
Stake in SQLI (9.1%) is £14.8M
Unsecured Loan note issued is another £10m (assuming it is paid back!)
Cash at May £31.9. Cash today 29.5M once I allow for the 2.4M investment post reporting date.
So total value I get of their portfolio is £119.7m. Shares in Issue 258M, so a value per share of 22.6p.
A discount of 50%. Been this way for some time now.
What are the chances of it closing this gap?
Perhaps some will find this interesting and maybe add as one to look into yourself.
Hi ScotchGambit,
Funnily enough, I had a quick read through the accounts for Logistics Development (LON:LDG) this morning, and also thought it seems quite interesting for the reasons you explain, mainly the big discount to the value of its investments.
The investment portfolio seems very highly concentrated though.
Question - does it have any further risk or liabilities from its former activities, Stockopedia is coming up with an Eddie Stobart logo against it, which vaguely rings a bell, and ties in with the name too.
Regards, Paul.
Hello Paul,
Agree with the risk of it being highly concentrated. They recently exited their positions in Trifast and The mission group (both for small profit) which has left them with only 3 positions. The two publicly listed companies they have on their books are both sitting at a loss from what I can gather, perhaps a reason for the current discount. But both seem reasonable companies at a quick glance. (I was happy when you upgraded APH to Amber/Green earlier this year).
I haven't come across any risks or liabilities from the Greeenwhitestar (Eddie Stobart) deal since I've been watching this one. From what I gather they just sold out cleanly to Culina Group for £127.5M and have been investing that money.
Perhaps one further point if anyone is still interested. There was some excitement when Richard Griffith got involved in this one. Name didn't mean much to me (Sorry Richard), but he has been nicknamed the Welsh Wizzard!
One warning is that it doesn't trade much. Lucky to get 5 trades in a day!
An old truck haulage company which used to trundle down the A1/M1, turned into some sort of investment vehicle. Richard Griffiths has some connection.
2022 - market cap of £67m with £29m assets, $80m cash and no debt. SR of 90 at the time so seems to have transitioned, with capital raises.
Facilities by ADF (LON:ADF) interesting contrast between the bullish broker note - acquisition is eps accretive by 10% to 20% - and the market reaction - shares tumble 6%. All easily explained by the dilution and insider sales - not a good look. Shares do look cheap, but the streaming market simply isn’t what it was when budgets were unconstrained. Hmmmm. No need to rush in, I reckon.
This piece in the FT the other day might engender a tail wind for Facilities by ADF (LON:ADF) ?
"Disney to spend $5bn in Europe on making new blockbusters
Regional chief says UK and continental Europe will play a big role in future box office and streaming hits"
Jim
Thor Explorations (LON:THX) very good update today. Revenue up 40% on H1 2023. Noted by Michael Taylor as having good potential.
No apologies, I am going to promote Pauls favourite cause today, namely Zane. I know he will also flag it today.
Why now? Because Tom and Jane Benyon, the founders, are about to start their 14 days of walks along the Severn Way. They will walk 107 miles and it is the biggest single fundraiser. To learn more please visit www.zane.uk.com You will see how important this is to many who are in Dire Straits (great band) in Zimbabwe. If you appreciate what Paul does here, every day, you have a way of showing you appreciation by making a donation to Zane. Large or small, any donation will make a difference. The website has a button to make your donation. Thanks for reading and an even bigger thanks if you donate. Have a good day investing.
Thanks Charles!
To echo your message, Tom & Jane's sponsored walks for ZANE are remarkable, especially as Tom had to have both hips, and I think one knee, replaced several years ago, but keeps doing these long walks every year to raise vitally needed money for the charity he founded.
We only occasionally mention it here, and thank you to the readers who already contribute with regular donations, it's very much appreciated. Also I fully appreciate that many readers do your own things for other charities, hence why I only gently & occasionally plug ZANE here, but it is a wonderful charity. I'll never forget my trip to Zimbabwe in 2019, when I saw for myself ZANE's work by shadowing the trustees as they had numerous meetings & site visits to see the charity's work on the ground. It certainly made me very grateful for what I have here, and also inspired by how lovely the people in Zimbabwe are, despite the country being in extreme poverty & many basic functions having completely collapsed (like the public water system, where taps haven't worked for many years, instead they have to use boreholes if available). ZANE is literally keeping hundreds of very vulnerable people alive, and giving them support and dignity.
Right, back to shares!
Thanks, Paul.
Just had a look at Zane and what they are doing for the good people of Zimbabwe - a country I was lucky enough to visit back in 1995 before everything went t*ts up.
Direct debit now set up to help support them and the great work they do. Happy Friday all.
Thanks Gimmers, and Caper4, and everyone else who helps ZANE. It means a lot to me, and more importantly the people we're helping.
Best wishes, Paul.
Yes I am a long term supporter although I do have a special reason having lived in Rhodesia when young and married there . Zane do remarkable work and deserve to be supported
Facilities by ADF (LON:ADF) it’s certainly all going on at ADF
Their acquisition of Autotrak looks a decent fit (if somewhat ambitious for a company with a £41m market cap to spend up to £21.3m) and the fundraise to pay for it was ‘heavily oversubscribed’
It’s interesting tho that at the same time, a number of their shareholders wanted out, and so sold £10m worth in a Secondary Placing- too risky for them or they didn’t agree with the chunky acquisition or that they simply saw the liquidity to exit?
I’ll watch how the share price responds with interest
Facilities by ADF (LON:ADF) Yes I don't know why they would sell given the positive metrics associated with this deal but looking it at with my 'half full' glasses all of those shares were purchased AND the placing was still over subscribed, that's good going in these illiquid times...
The cavendish note out just now makes for compelling reading, it all happens in FY25..
I'm an ex holder but I've just bought back in on the opening.
Facilities by ADF (LON:ADF) announced a primary and secondary placing and a retail offer after close of business yesterday to fund an acquisition. Placing described as being heavily oversubscribed this morning. (I hold)
I don’t think a placing is ever not “over subscribed” according to companies and brokers.
My morning smallcap tweet: Damning with a faint raise
Dillistone (LON:DSG) Petrofac (LON:PFC) Mycelx Technologies (LON:MYX) accesso Technology (LON:ACSO) Celadon Pharmaceuticals (LON:CEL) Evoke (LON:EVOK)
◄Dillistone (DSG)► £60k placing at 8p. an 11% discount, for working cap in case the Group's markets continue to be challenging for an extended period. Also £300k convertible at 9.85%, funded by 7 directors. H1-June in line with mgmt exp; it warned in June though. [SP=8.51 Cap=2m]
◄Petrofac (PFC)► extends forbearance for non-payment of the interest on its senior secured notes to Sep 20. [SP=15.77 Cap=83m]
◄MyCelx Technologies (MYX)► £700k placing at 51.5p, a nil discount, for various purposes. Trading in line. [SP=51 Cap=12m]
◄accesso Technology (ACSO)► £4m max buyback. [SP=541.12 Cap=226m]
◄Celadon Pharmaceuticals (CEL)► funding saga update. maintains positive dialogue and the investor who has failed to pay £400k of £1m in a placing. Also gets a further £200k of the £1m requested under a loan agreement. The lender claims it is awaiting completion of a property sale. Talks on substantial longer term debt facility. Cash at hand £210k. [SP=23.68 Cap=16m]
◄Evoke (EVOK)► buys 51% of a Romanian gaming biz WInner for €10m. Winner's gross gaming revenue c.€19m in recent half. [SP=69.05 Cap=302m]
Ofgem has announced that the energy price cap will rise to an average annual £1,717 from October from its current £1,568 (+9.5%). The regulator says that the rise is due to the continued higher price of wholesale gas. This will clearly take cash out of consumers’ pockets and reduce disposable income available to spend on non-essentials.
I read this too, and then I googled wholesale gas price.
I'm not sure it's really true. Yes p/therm is closer to 100 than the 50p it was at the start of 21 but it's nowhere near 300p or the peak of 600p that has been the case since then.
Their own website:
https://www.ofgem.gov.uk/energ...
Agree Doug. This is the negative mainstream media feeding off a headline hungry Ofgem regulator. A drop in the ocean in real terms. Whilst it is a Q on Q increase the comparison Y on Y is surely key to our headline Inflation number. Wouldn't expect this to impact any BoE decisions this side of Christmas. Suspect they might make us with until October for the next reduction but direction of travel seems clear.
Let's see where the market goes first week of September when they are all back to work. Unless the Mid East takes another turn for the worse I'm in the optimists camp.