Small Cap Value Report (Fri 23 Dec 2022) - SDRY, MSI

Good morning from Paul! Here's the last SCVR before Christmas. I'll pick up on a couple of items left over from yesterday, then look at the news this morning, which should hopefully be quiet.
New way to put in tickers - instead of using £TICKER, just type the "at" symbol, and then a box pops up, where you enter the company name or ticker. This seems to work better than the old £+TICKER arrangement.
Agenda
I reveal all the companies we've reported on here, in the last 6 months (more detail below)
Superdry (LON:SDRY) - news of a bank refinancing (with a specialist, higher cost lender) is excellent, and has greatly improved risk:reward. I'm not so impressed with the trading update though, and forecast profit for FY 4/2023 has been reduced to not much above breakeven. It's difficult to get excited about this share at the moment, but it could be a good recovery share at a later date, if the market sees more evidence of a consumer recovery - difficult to imagine now, but maybe later in 2023, who knows? (more detail below)
MS International (LON:MSI) [quick comment] - more good news for shareholders, with a big contract win announced today - overseas customer, buying an anti-drone gun. It’s £22.4m, expected to be recognised in calendar 2023, so straddling FY 4/2023 and FY 4/2024 by the sounds of it. Revenues in recent years have been between £50-80m, so this looks a material deal. I don’t know what the profit margin would be on this product. If it works well, there could be follow-on sales (this is the first sale of this new gun). Graham has mentioned MSI positively here twice, in June, and earlier in Dec, and from memory I think this one was a mystery share in one of my recent podcasts. After today’s announcements, I imagine shareholders will be holding tightly, with good reason. Thumbs up from me. (no section below)
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
How many companies have we covered in the SCVRs?
When I started this column, it was an experiment to see if it was possible to review the whole small cap market. The idea came to me in 2012, so I downloaded a spreadsheet of all listed companies from the UK Stock Market website, then sorted it into market caps, and sectors. One by one, I eliminated sectors with lots of companies that I didn’t understand (e.g. natural resources, biotech/pharmas, blue sky), and also anything below £10m mkt cap, and above about £500m (at the time originally, I think, or it might have been £300m at first?). This resulted in about 500 companies remaining, which meant that if I looked at 2 unique companies each working day, I could cover everything in a year. I then began publishing it as a daily blog, and Stockopedia decided they liked it some time later, and they’ve put up with me here ever since!
Anyway, I was twiddling my thumbs a couple of days ago on a quiet news day, so pondered to myself, I wonder how many companies we’ve actually covered this year? Let’s see how the actual number compares with the original universe of c.500 companies.
Also, I wondered if we are focusing too much on my favourite shares and sectors, and not covering enough of a spread of other companies? (as a handful of readers have alleged in the comments).
So instead of guessing, let’s actually measure it, and find out what the facts are!
I must have been very bored, as this spreadsheet I created shows all the companies we have covered since 1 July 2022 to date. It then uses the “CountUnique” function to count unique tickers written about, not the total number (which would be higher, once duplicates are counted).
Drum roll please, the grand total of companies we have reported on here in the last (almost) 6 months, is 384.
6 months took long enough to work out, so I reckon if I’d extended that to the 12 months whole of 2022, then it would be a good bit higher, probably not far off 500. 450 possibly, as an estimate?
Bear in mind also that we ignore anything we think looks uninvestable or seems to be going nowhere, then I think we’re covering a pretty big proportion of the market’s sensible small caps. So if you can’t find anything of interest in our reports, then that surprises me!
Paul’s Section:
Superdry (LON:SDRY)
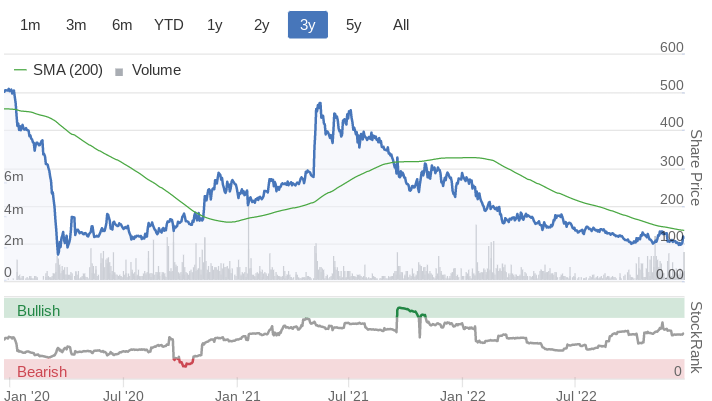
118p (+17% yesterday)
Market cap £97m
Trading update covering the 26-week period (‘H1 23’) to 29 October 2022
Positive start to Autumn/Winter 2022 (“AW22”) season
New financing facility agreed, and auditors appointed
New financing - I think this is by far the most important part of the announcement, because as we’ve reported here before, the situation was looking decidedly dicey - the existing bank facility had not been renewed, and it was clear from the last update that SDRY’s old bank was not interested in renewing it. That made this share very high risk, and uninvestable for me, until new arrangements had been put in place. The 31 January deadline was looming.
Here are the details in full -
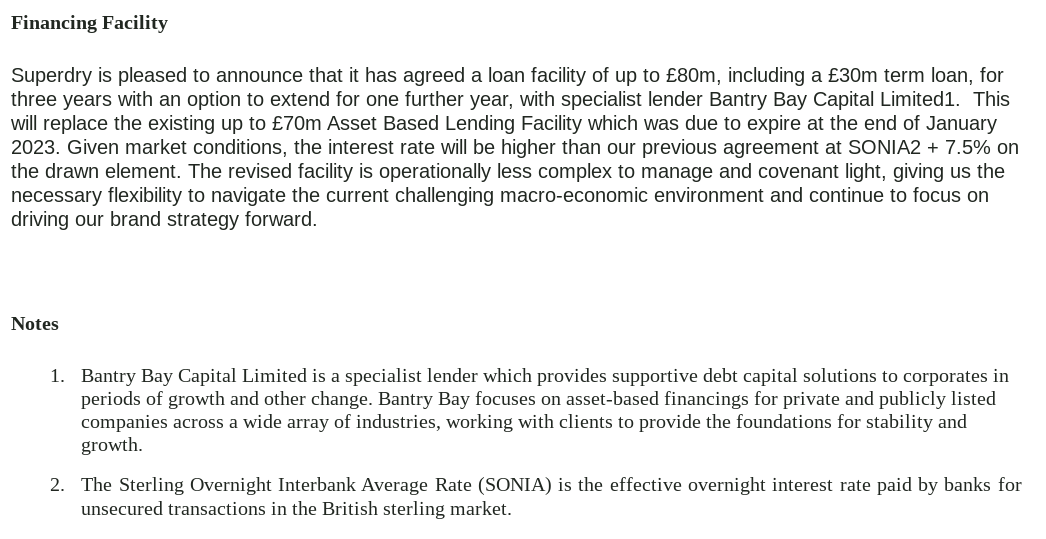
We have to be careful when googling “SONIA”, because instead of taking me to the Bank of England website, I got information about the 80’s scouse pop singer, which wasn’t much help. Here’s the Bank of England website, which records SONIA as 3.43% last night, close to base rate of 3.5%. The historic graph is striking, at how suddenly interest rate policy has changed recently, after years of near-zero rates. No wonder there’s been a lot of market & economic turmoil this year.

SDRY will soon be paying SONIA + 7.5%, so that’s almost 11%, and likely to go higher (with markets forecasting peak interest rates of c.4.5% that would be 12% cost of borrowing to SDRY).
I’ll estimate the annual interest cost, as follows -
Term loan of £30m at 11.5% pa = £3.45m interest pa
£50m additional facility (presumably an RCF or similar), assume half used on average, half of the year = £25m * 6/12 months * 11.5% interest = £1.44m
Total estimated annual interest = £4.89m - so I’d say that’s an unwelcome expense, but it doesn’t look ruinously expensive. Although this is in the context of SDRY probably only making a tiny sliver of profit, if anything.
Net debt is only £13m at 20 December 2022, down £25m from 1 October 2022. That’s excellent, and it does reinforce what I’ve mentioned before here, that SDRY borrowing is genuinely seasonal, to fund peak stock intake, and then reduces or disappears altogether when seasonal cashflows improve. So it’s not a distressed level of debt in my view.
Bantry Bay Capital - that SDRY has had to go with an expensive specialist lender, suggests to me that the main UK banks probably weren’t interested in lending to it, or required onerous terms (e.g. tight covenants) that the company wanted to avoid.
I imagine that Bantry Bay’s phones won’t have stopped ringing from other UK companies eager to refinance problematic bank finance!
Overall though, my view is that the main risk for this share has now been dealt with. Although we don’t know what the arrangement fees are, nor the covenants (it only says covenants are “light”).
In this case, I can see the logic for paying more to a specialist lender, in order to have more secure lending facilities.
Auditors - new ones appointed, RSM, a well-known firm.
Remember that the old auditor resigned, and for several years has flagged in the Annual Report weak financial controls - so that is an ongoing risk. It wouldn’t surprise me if a large provision against inventories might be required at some stage. So this share could still be at risk from a plunge in price on a profit warning due to these poor financial controls.
To me, it also makes me feel management seem cavalier in their approach. It’s really not that difficult to control the finances of a business like this.
Trading update - we’re told this is positive, but I’m not convinced. H1 revenues are only up 3.6%, with decent store performance (up 14%) offset by lacklustre online growth, and poor wholesale revenue. Later deliveries are blamed for some of that wholesale shortfall.
Mild weather in Sept & Oct wouldn’t have helped either, as that suppresses sales of more expensive coats & jackets, but the more recent cold snap will have helped.
“Margin dilution” which presumably just means a lower gross margin, of over 200bps is bad news. For context, on £644m forecast revenues for FY 4/2023, that’s c.£13m lower gross profit, which would largely drop through to the bottom line. It’s not clear if this shortfall is against last year (probable), or forecasts.
Forecasts - many thanks to Liberum for publishing an update. This shows it reducing estimated profit from £16.2m to £10.4m, for FY 4/2023. So only just above breakeven really, on revenues of £643m, that’s only a profit margin of 1.6%
We are in a consumer downturn though, so tough conditions exist. Plus this sector has seen lots of upward cost pressures, and supply chain issues. Could some of those problems partially reverse in 2023 perhaps? Also remember SDRY has a long tail of loss-making shops (evidenced by the IFRS 16 entries on the balance sheet), so over time that should improve, with rents renegotiated downwards on renewal (or exit).
My opinion - given that competitors are in some cases really struggling, and in the case of Joules even collapsing, then SDRY’s performance so far looks OK, I think.
Renewing its essential bank facilities (albeit on more expensive terms) greatly improves risk:reward, so paying 120p now for SDRY shares seems to me far more logical than paying 100p a few days ago - when you were taking a risk of a 100% loss. That 100% loss risk has now gone.
It all boils down to what you think of the brand, and how likely a recovery in performance is?
Overall, I can’t decide, so am probably neutral on this share. At some stage though, the stock market might decide to get more bullish on it, anticipating a consumer recovery.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

39 comments
Happy Boxing day everyone.
Awful year for my portfolio value but it looks like @polx will be having a nice end to the year, it just received FDA approval on its 2nd attempt.
Could be one to watch on Tuesday
Fantastic section written by extremely knowledgeable professionals and is a really fascinating insight into small caps. Thanks to everyone who puts it together and merry Xmas.
Just to second all the good wishes, thanks and best luck to everyone for next year - but above all to those in real need.
Paul, Graham and not forgetting contributions from Roland and Jack, before his departure,
Many thanks for all your hard work and insight during 2022. I may not always agree with the consensus on individual shares but your hard work and analysis are much appreciated and invariably help my decision making process in relation to stock selection.
Best wishes for the festive season.
Jonno
I wish you both a well-earned break and hope you have a lovely Christmas. Thank you for the excellent work you do. Only yesterday I struggled to find out what was going on at Tekmar (LON:TGP) , and I was particularly grateful for your insights.
Hello Paul - Oliver here from Stocko HQ. Given your preamble, I thought I would take a look from my side at the number of companies covered in Small Cap Value Reports throughout the year.
Using tagged stocks as a guide for companies mentioned, I get the coverage to be an incredible 533 unique companies discussed, well in excess of your initial target!
I am sure I speak on behalf of the whole community here when I say thank you to Graham and Paul for your tireless efforts in providing us with your insights and knowledge, helping us all to stay informed about such a vast set of companies as well as the overall investment climate.
Safe investing in 2023!
I must say I am gutted I didn’t reinvest my K3 Capital (LON:K3C) sale into MS International (LON:MSI) , which was on the list. I did reinvest some into Yu (LON:YU.) so I suppose I mustn’t complain too much. Both would have been a very nice end to the year. Good luck to MS International (LON:MSI) holders, just thinking if I would be too late to jump in?
Ha - I missed Yu (LON:YU.) at 360p which I felt was in a strong upgrade cycle so am kicking myself on the inverse to you!! That would have been a nice short term trade but not to be and I don't want to chase it.
With regards MS International (LON:MSI) - until the recent wins around defence I would have been happy at 600p to be honest. However, I think there has been a material change in future prospects with the recent wins that I expect to translate into some large eps upgrades. It is also verging on £100m market cap territory which in itself should bring more interest from institutions.
Before todays announcement it was trading on around 14* PE. Strip out net cash of 150p and it was around 11* earnings. So not particularly rich for a defence company in the right moment.
After todays announcement I suspect we are looking at sub 10* earnings again even after todays rise. Whether you think thats good value I'll leave up to you.
It is an illiquid stock though so persistent interest will likely see it trade much higher but equally if there is no news and there are frothy buyers looking for the next hot story then it could just as easily drift back a bit. I have learnt that with this stock you have to be patient - management say no more than they absolutely have to so don't expect any promotion.
Thanks David, I will keep an eye on it.
MS International (LON:MSI) My newbie thoughts were:
1. dont' chase it wait up - FOMO etc
2. who will swoop to get the IP
3. what is the IP (suddenly found a new type of radar?) and a bit of good stuff on the side
Similar to WANdisco (LON:WAND) - great story and thanks for the SCVR for bringing it onto the radar.
Been burnt since starting this journey in March 2020 (furloughed for 8 weeks). Did not win big in the 'bull market' bought and sold like a lunatic where could have just bought 5 shares and gone to sleep.
Have a large 'coffee can' waiting for the gold blend to arrive. They are not bad just IPO's - market seems to have killed the golden goose methinks.
I think the 'elephants' will consolidate next year, which they can do, so the SCVR may become a better space for multi-baggers - but will need more than good stories and maybe making an actual profit (would be nice).
Best wishes to the Stoko crowd and lets hope the bears hibernate during January so can 'live the dream' in 2023.
Luckily I bought both MSI and YU earlier this month.
Good on you, nice Christmas present.
Thanks, only when I sell. My December purchases are helping offset losses from the previous 11 months. Usually over trade, this year under traded until I became proactive.
Good morning Paul and Graham, just wanted to say have a great Christmas with family and friends. Thank you for everything you do, and the changes you have made along the way to improve or add to the SCVR. Plenty of Malbec and Baileys and I’m sure we will think the next year will be a bed of roses.
MS International (LON:MSI) looks like it has finally hit a step change to its business, particularly in defence. Has taken a long time and management words are few and far between (probably a good thing). The anti drone gun contract is highly material at £22m and it seems they are confident of winning more. The US naval version that is in promising testing for sole source is also potentially very material.
Think I'd estimated 45p eps+ this year but given todays announcement see that considerably higher. If anyone has a good calc on this I'd appreciate it. With net cash of something like 150p this is still far from richly rated. I had not anticipated 650p so quickly but it looks like the business finally has momentum based on a high quality revenue stream. With countries realising that anti drone is imperative, rather than a nice to have, and increasing spending on defence I think I'll be hanging on to my shares.
Just wanted to add my salaams and thanks for another great year (not talking returns!!) here Paul, Graham and Jack. There is much to applaud but most of all the cameraderie which comes from honest cooperation and generous sharing (in my opinion much needed these days). So many contributors have added to my year that it would be unfair to name one in particular. But Happy Christmas or whatever you celebrate or even don't celebrate and have a fantastic 2023!!
There seems little interest in special situation / arbitrage stuff here, but as a quiet day Curtis Banks Curtis Banks (LON:CBP) RNS seems fairly positive: https://www.londonstockexchang...
Seems to suggest it's as good as done, and might hear something by 9 January. Strangely there is still no price, however. I think Harwood is on board and based on previous comments (some videos on Voxmarkets eg
at 7:55) I imagine it's 350+? and this article: Curtis Banks / Nucleus: Scale benefits but tech challenges remain - Citywire mentions higher figures. So if anyone has better insight would be great to hear, and might still be reasonable risk/reward for a quick turn for some gunslingers :)
A Happy Xmas to Paul, Graham and Mr C for all the hard work this year. Much appreciated!
I read scvr daily after work but rarely post. I would like to say thankyou to Paul and Graham for their brilliant coverage. As a non accountant I'm constantly learning from how you both analyse the information. I like the fact that you take some of the story stocks and then show us where the skeletons are hidden in the numbers. Spotting and avoiding the losers is an important part for me. It has been a tough year but the community contributions have been a great read too. Lots of openness and humour and again, for me, lots of learning points. Too many contributors to mention but I'd like to thank mrc for consistency and wit. I'll never look at B&M the same way again after one of Paul's recent comments. I'm happy with the Malbec part, just not sure about the Baileys. Merry Christmas and a hopefully happy 2023 for everyone connected with the scvr. Thanks Phil.
Hi Paul & Graham
Thanks for your continuous good work. I’ve been out of the market for a few months but I still read your commentary.
I’ve just started buying selected companies that have good Stockopedia rankings. SThree (LON:STEM) and Somero Enterprises (LON:SOM) are 2 that I’ve always been a fan of.
I took a little punt on Quiz (LON:QUIZ) which is unusual for me but I feel that the demise of all retailers might be overdone. The Superdry (LON:SDRY) update gave me hope that people are still buying clothing and the demise of Joules (LON:JOUL^L22) will remove some supply etc.
Thanks again and have a good Christmas.
PS the new @ method for tagging stocks works really well and avoids tagging the wrong stock!
Well done Paul & Graham. I remain in awe at the quantity of quality content you are able to produce on a daily basis. Be careful of burn out though and make sure you are taking enough time out to rest, recuperate and recharge.
My best wishes to you both and all the Stockopedia team and subscribers for the festive season. Let’s hope 2023 is an easier year to navigate than the last one.
Cheers
Simon
Morning all, can any one shed light on the eps impact on the MS International (LON:MSI) announcement? Kicking myself for selling 1/3 off my holding last week
Hello Nanotrader09,
MS International (LON:MSI) (I hold)
'can any one shed light on the eps impact'
Yes, I'd use the words - Good, Positive and Significant.
If you want a number. I'll put a finger in the air.Something like £5m+ operating profit and 22p additional eps. Based upon previous figures from the operations of this division. But depends how its split over FY23 (to end April). Normally I'd say very little in this FY - but it looks to be high-priority and therefore likely that long-lead parts have already been placed on order (normal procedure to maintain end dates). So perhaps +5p in FY23 and +17p in FY24. But thats just a guess, if it displaces other work then the additional profit could move later.
For me its less about this contract and more about what this contract means for the future. It's a vast new market for their naval system heritage, much larger, and growing at a huge rate because of the current conflict. Why MSI are in the right place at the right time is probably too much detail for this. Assuming that this contract and system are a success - and the size and speed of the order indicate that's not much in doubt - it's likely a significant increase - doubling would not be a high estimate - in the future revenue of this division.
I know what you mean about deciding to take profit. But its never a bad thing. I've not sold - but it leaves my portfolio severely unbalanced (at least for me) right now,
cheers
Mark
Thanks Mark, really useful
You should be congratulating yourself for keeping 2/3 of your holding
Morning All
Wishing everyone a Merry Xmas, and just to say a massive thank you to Paul and the team at Stocko for the time they spend trying to help us get rich :-)
And to Mr C without whom this page would not be quite the same
Cheers
My morning smallcap tweet: Xmas pudding
Gfinity (LON:GFIN) Symphony Environmental Technologies (LON:SYM) Skinbiotherapeutics (LON:SBTX) Journeo (LON:JNEO) Crystal Amber Fund (LON:CRS) Plexus Holdings (LON:POS) Webis Holding (LON:WEB) Curtis Banks (LON:CBP) MS International (LON:MSI)
◄Gfinity (GFIN)► e-sports co super-slow to produce FY-June figs. Rev down 8%, pretax loss £4.2m (£4.2m). Can't find any trading stmt for the period. What contempt for holders. Co talking to 'strategic partners' to identify the best way to support the business. Could be begging in the street for all we know. [SP=1.03 Cap=14m]
◄Symphony Environmental Technologies (SYM)► guides FY-Dec rev only c.£6.5m (£9.2m) and post-tax loss c.£2.5m (£1.4m). Blames "Middle East destocking issue has still not been resolved mainly due to delays in receiving the requisite government certifications for our partner's new factory in the UAE, which finally became fully operational in December." Expects Q1 profit though. [SP=10.25 Cap=19m]
◄SkinBioTherapeutics (SBTX)► audited FY-June op loss increased £266k from prelims due to writedown of £266k on inventories. [SP=15.88 Cap=25m]
◄Journeo (JNEO)► wins £0.5m order, included in management's expectations of performance for FY23. [SP=127.45 Cap=11m]
◄Crystal Amber Fund (CRS)► attempting to remove 6 directors of Hurricane Energy in which it has a large holding. [SP=96 Cap=80m]
◄Plexus (POS)► AGM stmt brimming with hope, as ever. [SP=1.76 Cap=2m]
◄Webis (WEB)► WatchandWager biz gains access to ll Monarch-operated racetracks in North America. [SP=1.29 Cap=5m]
◄Curtis Banks (CBP)► PUSU offer deadline extended to Jan 9. [SP=295 Cap=197m]
◄MS International (MSI)► first sales of its new land based mobile gun systems, "which are aptly named MSI-DS TERRAHAWK VSHORAD". I suppose so, if you like hyperbolic names and know that VSHORAD = very short-range air-defence. Terrahawks was a Gerry Anderson kids series in the '80s. Order worth £22.4m in 2023. [SP=472 Cap=76m]
Merry Xmas Mr C.
Thanks for a year of timely reports and acid humour .
Phil
Mr Contrarian,
This of all years - you have often made me smile on unrelentingly bad days! Thank you for all your contributions across so many companies.
Re MS International (LON:MSI) I hold - £22.4m contract announcement first order for new weapon system. Bear in mind that this division only turned over £30m in the previous financial year - so its a big order for a new system - to be fulfilled 'as soon as is practicable' - which might imply something about where these systems are headed? A land application is a huge new market for their traditional naval based systems.
This comes hard on the heels of the US navy's announcement of intention to procure sole source the naval version (clue - it's painted grey instead of green ).
I'm rather surprised that you chose to go with just the acronyms rather than the full name of the system
'which are aptly named MSI-DS TERRAHAWK VSHORAD dual feed weapon systems - mobile air defence.'
Which whilst arguably being aptly named is also a military fetish with over description of tools, naming, export categories, for the use of.
The chairman is notoriously economical with his communications - and I doubt that he has suddenly taken to all this jargon, so in this case I think perhaps you missed the subtle dig?
Share price of 600p appears to have arrived somewhat more quickly than I'd anticipated when discussing the recent H1 results. A very bright spot in a very dark year for my portfolio and at this late stage resuces my performance from terrible to bad-but-not-that-bad. Though rather at the expense of - hopefully temporarily - unbalancing my portfolio, which says as much about how badly the rest is doing as it does the success of MSI
cheers
Mark
Great work Paul & Co.
Would be good to get your thoughts on the Superdry (LON:SDRY) trading update yesterday. Re-finance looks expensive.
Good morning eParo,
Yes Superdry (LON:SDRY) is top of my list to report on today. I was on the road yesterday afternoon/evening, so it missed the cut-off for yesterday's report.
Also I'll be looking at a couple more that I ran out of time yesterday -
Journeo (LON:JNEO) and Character (LON:CCT)
Regards, Paul.
Morning all
Happy Christmas everyone and good luck for 2023 investing .
Update on Titon holdings which is the company I am starting to get to grips with .
Have had a few conversations with rue executive chairman now . To summise in no particular order
- circa 8-9 million market cap
- illiquid (negative )
- headwinds a little (negative)
- Korean subsidiary 49% owned used to deliver circa 1 million profit , “nice to have” bit somewhat out of their control . I’m fine with this and the focus should be on the UK business
- had a horrible experience installing am ERP system which hit them hard this year now working ok (I had this so I get it )
- new CEO In May sounds good
- has plenty of cash sounds good
- real estate backed being revalued very good
- regulatory rules mean new doors have to be fitted with their technology as standard (good)
- huge rising tide sector which I had totally not understood .
- some patented IP
- very pleased to have new shareholders and happy to engage
- agreed on options only at market price
The news round here and (even my missus ) is continually moaning about condensation and indoor airflow and dealing with moisture is a big rising tide sector especially for councils etc with social housing. They now have regulatory requirements as well as clear health benefits to fitting and using titon products .
Im liking it a lot but it is illiquid and a micro cap . Looks undervalued and if yiu don’t mind the value trap risk it is an interesting company that actually welcomes investors and seems genuinely pleased that someone actually wants to talk to them .
Re Titon Holdings (LON:TON) the South Korean subsidiary is loss-making according to their Trading Update, so not sure why it is 'nice to have'. I note Harwood are building a stake here. Richard Staveley from Rockwood spoke about Titon a couple of webinars ago.
Korean subsidiary has been historically profitable and does not suck any cash from uk and is asset rich . So if it sends profits across great, if it doesn’t perform then that’s not what I’m counting on and nothing comes across
Management focus on uk .
Re Titon Holdings (LON:TON)
Looking at the liquidity I fail to see how anyone could exit a sizeable stake without sending the price way down. It’s trading in a very similar pattern and proportion to any other building products company. Why not just buy any of the more liquid alternatives including two that benefit from exactly the same regulatory tailwinds:
Genuit (LON:GEN)
Volution (LON:FAN)
I think with Rockwood on board and with it being backed by cash and property it has prospects .
Don’t know too much about volutuon / genuit .
I invest in what I understand and I understand a company with cash making profits with its market cap covered by its real estate is a good buy .
Lack of liquidity doesn’t worry me. I have 25% of my shares in illiquid stocks that’s what I decided was my risk appetite .
I don’t doubt you’ve done your sums and wish you a successful investment. My experience with illiquid names has been that they are much easier to get into than out of - which has shifted my investment universe up the scale. Ideally you can exit on a profitable takeover.
Quite an achievement, but for me the community you create is as valuable and has been a huge support during the tougher times. The openness, honesty and humour create a great environment for discussion. Huge thanks to you and the team.