Small Cap Value Report (Fri 23 Feb 2024) - TRB, YU., CLIG, HRN, SED

Good morning from Paul!
Director interview - I've resumed doing my audio interviews with CEOs. Yesterday afternoon I had an interesting update call with founder/CEO of Beeks Financial Cloud (LON:BKS) Gordon McArthur. Disclosure: I have a small position (<1% of my personal portfolio) and intend buying more at some point when funds are available. Remember the point of difference is that I approach companies I want to interview, and I don't charge any fees, so that it's independent, rather than PR. It went out on my podcast channel yesterday, or the web version is here. I thought it was very interesting, not just his points on Beeks, but also wider market comments. I've got 3 more company interviews in the planning stage! Ideally it would be great to talk to all 20 companies on my list of favourite 2024 shares, which has got off to a good start so far. So any company advisers who could facilitate this, please do get in touch.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Paul's 2023 share ideas, with live prices.
New SCVR summary spreadsheet from July 2023 to date, updated at weekends (very useful quick reference tool, search for ticker using CTRL+F). Hover over cell for pop-up notes.
Frozen SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Morning movers (with news) -
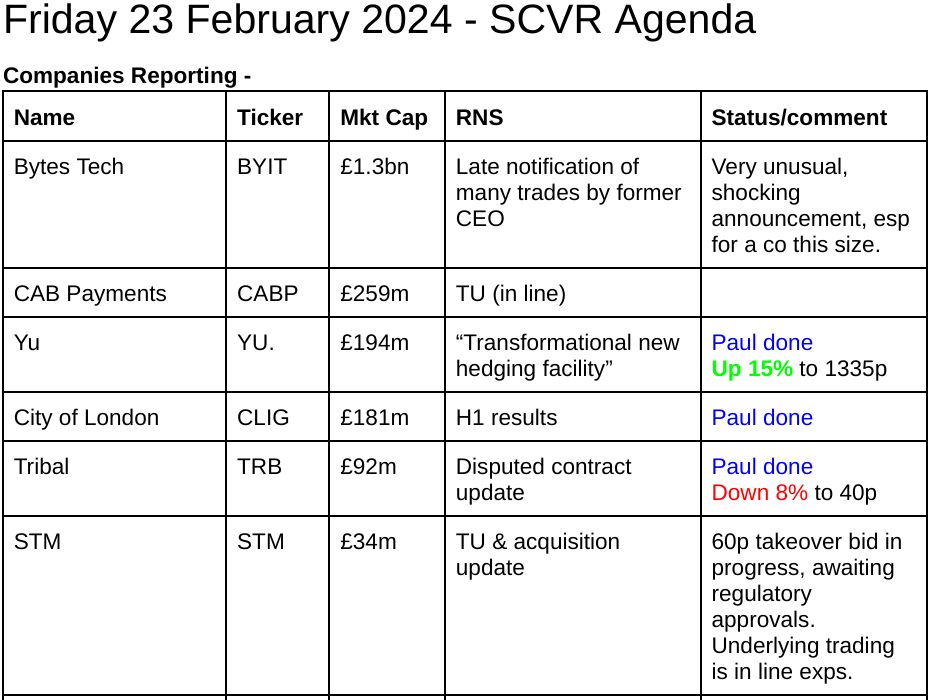
Hornby (LON:HRN) - up 35% to 28.5p at 14:18 (£48m) - Hornby welcomes Fraser (FRAS) as supportive strategic shareholder, FRAS ups its stake to 8.9%. This could get interesting! FRAS owns GAME, which sells Hornby products (model railways, and other heritage brands).
Note that Phoenix owns 72% of HRN, so is in the driving seat. I imagine Phoenix are probably delighted that key retailer/brand owner Frasers is taking an interest in HRN. Maybe this opens up an opportunity for Phoenix to sell down some of its shares in future? Trouble is, after years of attempting a turnaround, HRN is still heavily loss-making and has way too much debt. So on fundamentals it looks hopeless, but it looks as if traders might be having some fun on the Frasers news, in a very illiquid share with little free float. Could it be the next Games Workshop? Probably not, but FRAS involvement could be a catalyst for something more interesting to happen, who knows?
Saietta (LON:SED) - down 43% to 3.25p - almost game over. Puts itself up for sale, and says it has a week to arrange something, or it will have to consider going into administration. Looks like it's all over, almost. Everyone here knows my views on this company, so I won't twist the knife for any holders.
Summaries
Tribal (LON:TRB) - down 5% to 41.5p (£88m) - NTU Contract Update - Paul - AMBER/GREEN
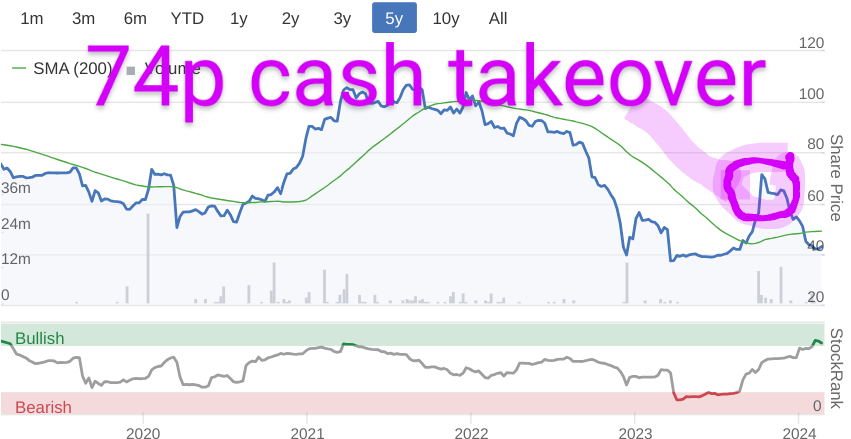
The educational software group announces that its large disputed contract in Singapore is now entering mediation. The total claim against TRB is about £10.6m, so this is a big dispute, and TRB has a weak balance sheet (negative NTAV of £(26)m) so it's not clear how it would fund any substantial settlement cost. Although I wonder if entering mediation means a negotiated compromise might be the outcome? Cheap compared with a 74p cash bid last year, there could be a trade here maybe?
Yu (LON:YU.). - up 15% to 1,335p (£223m) - Transformational New Hedging Facility - Paul - AMBER
A very significant announcement that the market likes, saying that a new supply arrangement with Shell has released a large amount of cash collateral. I run through both the bull & bear views below, and end up sitting on the fence with AMBER. It's your choice how you see this share, there are compelling bull and bear points, and nobody knows how this will play out in future.
City of London Investment (LON:CLIG) - up 4% to 358p (£181m) - H1 Results & Board Changes - Paul - AMBER/GREEN
This niche asset management group has a long history and expertise in closed ended funds investing. It pays a 9.6% yield, which is the main attraction. It could also benefit from discounts to NAV narrowing, which might attract more AuM into its funds maybe? So there's also a possibility of a cyclical recovery in the share price too. Looks pretty good to me.
Paul’s Section:
Tribal (LON:TRB)
Down 5% to 41.5p (£88m) - NTU Contract Update - Paul - AMBER/GREEN
This is the key bit -
Further to the announcement on 2 May 2023, Tribal is now entering into a mediation process with Nanyang Technological University ("NTU").
This is a contractual dispute that has been muddying the waters with TRB shares for some time. NTU has also "updated" (presumably that means increased?) its claim -
NTU has updated its demand for damages allegedly incurred as a result of its purported termination of its contract (as previously announced) ("NTU Demand"). The updated NTU Demand is in the amount of SGD17,511,651 and USD377,724 on account of alleged damages, losses, costs and/or expenses. NTU reserves the right to update the quantification of its demand.
The Company has sought legal advice regarding NTU's Demand which it intends to vigorously dispute.
I initially thought this was only a small dispute, at $377,724. However, on checking the sterling to SGD (Singapore dollar) exchange rate, 1 SGD = 59 pence, so SGD 17,511,651 above translates into a hefty £10.33m. So this is a substantial claim. I had a figure of c.£10m in the back of mind as having previously been mentioned for this dispute.
Paul’s opinion - this dispute seems a significant size, although the market might see a mediation process as preferable to a costly dispute in court. It raises the question of whether a negotiated compromise might be achievable, drawing a line under this disastrous project?
I don’t rate TRB as a standalone business, because it’s had many slip-ups in the past, of which the disputed NTU contract is just one. However, it’s the value to an acquirer that interests me - software companies are often highly valued by acquirers, even if they seem poor businesses, we’ve seen some very surprising takeovers of serial disappointers from the UK market in the past (e.g. Proactis and Tungsten spring to mind). Tech valuations in the US, and in private markets, are very high of course. That's why cheap shares on AIM are receiving takeover approaches, often from the US and/or private equity.
Note that TRB shareholders rejected a 74p cash takeover bid last year. Then there was an ahead of expectations update recently on 2/2/2024. So the current share price of only 43p could have upside on it, as a trade, maybe?
That could get derailed though, if the mediation results in an onerous settlement that TRB might struggle to afford, as its balance sheet is weak - the last interims showed NTAV negative at £(26)m. It’s true that software companies usually don’t need any significant net assets, due to capital-light models and receiving cash up-front from customers. However, anything in negative NTAV territory is taking things too far, in my opinion.
TRB shares could go either way, I don’t know what the outcome will be. However, the price being so far below a recent takeover approach makes me lean towards the positive side, so I’ll stick with AMBER/GREEN as previously on 2/2/2024.
Yu (LON:YU.).
Up 15% to 1,335p (£223m) - Transformational New Hedging Facility - Paul - AMBER
Yü Group PLC (AIM: YU.), the independent supplier of gas, electricity, meter asset owner and installer of smart meters to the UK business sector…
Bulls are back in charge now, with a +15% share price reaction to this news -
…entered into a new structured trading agreement ("Hedging Facility") with Shell Energy Europe Limited ("Shell Energy") with an initial five-year term.
There seems to be a key improvement with this new facility, in releasing substantial collateral cash -
Further, while the Group meets its ongoing obligations in the Hedging Facility, Yü Group will not be required to deposit cash as collateral to support mark to market movements, due to energy price fluctuations, as has been required under the Old Facility. Finally, Yü Group will benefit from Shell's leading and considerable commodity trading access to liquid commodity markets, at market reflective prices.
The Hedging Facility fundamentally transforms Yü Group's working capital profile releasing cash that would previously have to be held on balance sheet to support the Group's robust hedging policy.
£52.25m of cash previously lodged under the Old Facility has now flowed back to Yü Group, with further material cash benefits to be realised over the next month.
That’s highly significant on the face of it, although without seeing all the small print of the old & new contracts, outside shareholders will never fully understand this. We just have to trust that management know what they’re doing, and haven’t taken on any hidden risk.
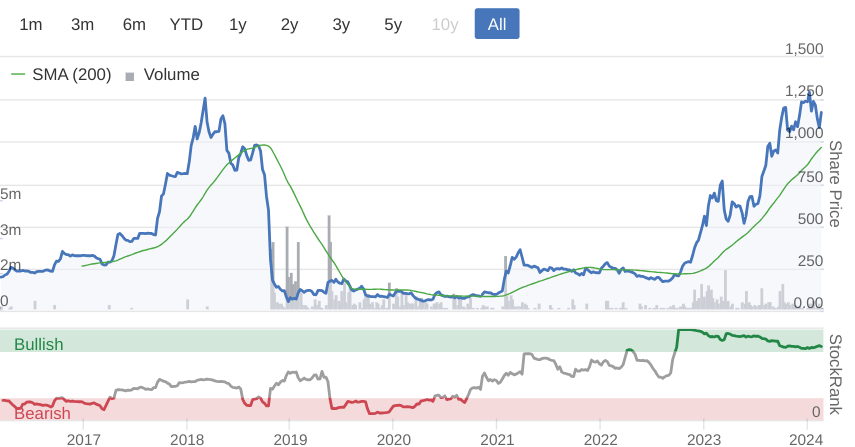
This is a highly risky sector - look at how many utility suppliers have gone bust during this energy crisis. YU also had a serious setback in 2018. However, it’s clearly played the more recent energy crisis extremely well, being a serious multibagger starting in 2021, but really taking off in late 2022 to date -
Releasing all that collateral cash opens up the possibility of faster expansion, more generous divis, maybe buybacks, acquisitions? I can see that it would open up a lot of options for management that have been restricted by the previous supplier/hedging contract -
The new hedging facility unlocks over £50m of cash currently posted as collateral and removes a material working capital constraint to the business lifting exposure to mark to market movements from future energy market fluctuations. This provides us with substantial strategic and financial benefits, enabling increased distributions whilst continuing to invest to deliver our ambitious growth agenda.
Paul’s opinion - I’ll do bull and bear -
Bullish view - this certainly sounds an interesting announcement today, I can see the benefit from releasing all that collateral cash. It also suggests that Shell must be comfortable with YU, to not require collateral.
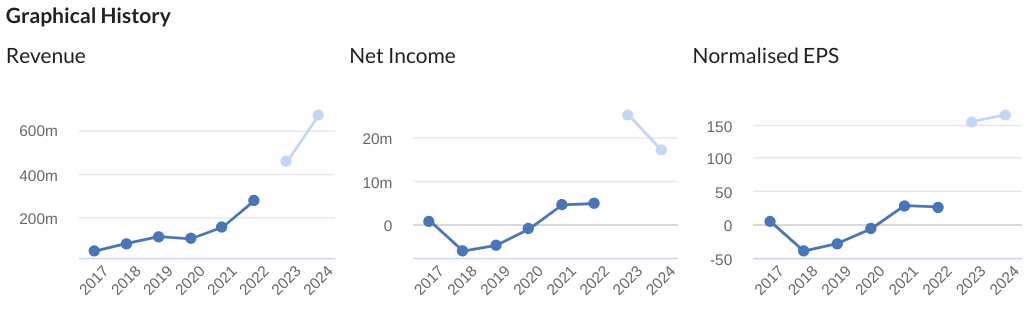
On the upside, YU has produced stellar growth during the energy crisis, with profit soaring -
Broker upgrades have been astonishingly good -
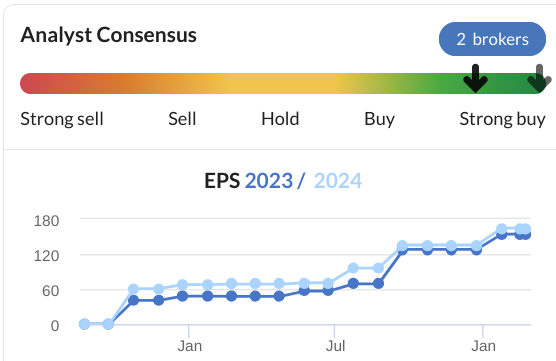
Valuation on a PER basis is still more than reasonable - the StockReport shows a forward PER of only 7.1.
Bearish view - all the profits have come from the energy crisis, it made next-to-nothing beforehand. The number 1 question to ask for all investments, is “are profits sustainable?”. IF they’re not sustainable, then buying a cheap PER share that’s enjoying a temporary bonanza in earnings, could turn out to be an expensive mistake.
YU has previously come unstuck, and with the whole business model resting on management making correct (and sometimes lucky?) decisions on purchasing and selling prices, plus the all-important hedging. If they get that badly wrong, it could be disastrous, and how many management teams always get their hedging right? Hedging is meant to tie selling prices and buying prices together, to give guaranteed profit whatever happens to market prices, but how many companies actually hedge perfectly like that?
My previous concerns with YU’s accounts was a huge bad debt charge. It seemed to be selling electricity to small businesses that couldn’t pay their bills. That’s not good business! I think YU was addressing this issue though, so that might be OK now, it’s just something to check.
Overall - I can see why some investors will be excited about the superb performance YU is currently producing. Equally, I can see why other investors might see this as a flash in the pan, with super-normal profits likely to be competed away as markets normalise.
As I don’t know what the future holds, I’ll just sit on the fence with AMBER, but well done to bulls, it’s certainly been a terrific share so far.
City of London Investment (LON:CLIG)
Up 4% to 358p (£181m) - H1 Results & Board Changes - Paul - AMBER/GREEN
We didn’t look at CLIG during 2023, but Graham wrote a really interesting review recently here on 22/1/2024 reminding us what CLIG does - it’s a specialist asset manager, which invests client money in closed end investment funds. The attraction being that they’re experts in this field, and that attractive (for new investors!) discounts have opened up in closed end funds, providing possible future upside. Although it said some discounts narrowed in Q4 2023.
The main attraction of this share is a stonking dividend yield of almost 10%.
Doing some googling, this very interesting article from Maynard Paton’s blog came up, indicating the 32% major (founder) shareholder wasn't happy with the Board last autumn, although I see a new chairman is now in place.
How do today’s actual H1 figures compare with that guidance? I’d be very surprised if they’re any different, but actually the profit, and the cash figure do seem to be a little below what the H1 TU (issued 22/1/2024) previously stated -
Funds under management (FuM) up from $9.4bn (Jun 2023) to $9.6bn (Dec 2023) - TICK! (actual same as guidance)
Adj PBT $13.9m (flat vs H1 LY) - question mark over this, as the actual figures today say $13.3m underlying PBT, and give a different LY comparative of $13.6m. Sounds like this might be a slight miss against guidance? Looking again at the H1 TU, it did say $13.9m adj PBT was only an approximate estimate, which seems to have been missed by £0.6m.
Cash guided at $28.8m - the actual balance sheet shows cash of $25.9m, and no bank debt. So this also seems below guidance, by almost $3m, which is strange as cash should be the simplest figure to report! Maybe there’s a reasonable explanation, I don’t know. If anyone talks to management these discrepancies are worth querying.
Interim dividend 11p - TICK!
FuM latest figure post year-end is down slightly to $9.5bn at end Jan 2024.
This is the first year in which CLIG has reported in dollars, so make sure you note that when doing comparisons.
Balance sheet - looks robust, although it doesn’t support much of the market cap, so this is an earnings/divi based valuation for CLIG shares, rather than asset-backed.
NAV of $151m is mostly intangible assets of $126m, which look to be (see note 5) almost all goodwill and similar, relating to previous acquisitions. Deleting those, as is customary, gets NTAV of $25m, which is nearly all just the cash pile.
Overall, it’s fine. I see the commentary says the company has “never had debt”, not something I can recall any company saying before, although it’s probably also true of some of the very conservative, family owner/manager companies we like here.
Board changes - very minor, shuffling the NEDs.
Outlook comments - are interesting, more a strategy statement than outlook! This is from the Chairman -
The current very wide discounts in CEFs remind me of my early investing days. I first invested in an EM CEF in 1993, a very strong year for EM. During the year, that fund surged in value and moved to a 10% premium to net asset value at which point I sold it. When Alan Greenspan and the Fed began raising interest rates in early 1994, I was then able to invest in well-managed CEFs at 15-20% discounts at a time when emerging markets were in a severe correction. I called it buying a double-discount. Two years earlier, Barry Olliff founded CLIG to pursue a similar strategy. Little did I know then that savvy George Karpus had begun investing in discounted CEFs in the US starting in 1992. Our Founders Barry and George developed their investment processes and teams to buy low and sell high. Now in our fourth decade, this spirit of buying quality at discounts resonates strongly within the Group.
A talented investment manager we know describes his approach as investing under a cloud. He uses clouds (bad news and uncertainty) as markers for uncovering value below. Indeed, inflation, the ensuing interest tightening cycle and geopolitical headwinds are presenting opportunities. It is notable that emerging and international markets have substantially lagged the US market since the merger. Indeed, the S&P index has delivered a cumulative return of 49% in the 39-month period versus just 2% for EM and 23% for international markets. At the same time, rising interest rates have created opportunities for KIM's fixed income and municipals strategies. Relative valuations are much lower in the markets where the Group has the majority of its assets under management and discounts in our CEF portfolios are at compelling levels. Our teams are energised and we remain constructive on the outlook for performance at CLIG.
The CEO also has a rather quirky style outlook paragraph - I can't decide if this is charming or just annoying! -
In my CLIG outlook from the FY2023 Annual Reports and Accounts, I used the phrase "with a following wind" to reference that the foundations for growth have been laid, and the Group was poised for growth pending an improvement in the overall market sentiment. The wind has not yet shifted, as CEF discounts remain wide across multiple strategies. Despite a headwind versus a tailwind, the Group is positioned to go further together, with thanks and appreciation to our colleagues for navigating the rough seas.
Cashflow statement - is really simple. All the cash generated is spent mostly on paying divis, but also note $3m was spent last year on buying shares for the employee benefit trust, and $1.1m in H1 FY 6/2024.
Paul’s opinion - I like this share, mainly for income seekers, with a 9.6% forecast yield that looks reasonably safe. Even if it came under pressure, I imagine the cash pile and no other need to retain capital, would mean divis reduced rather than cancelled, if earnings were to fall. This is confirmed by the dividend graphic below, which shows reliable divis, even through the pandemic - plus an occasional special divi on top -
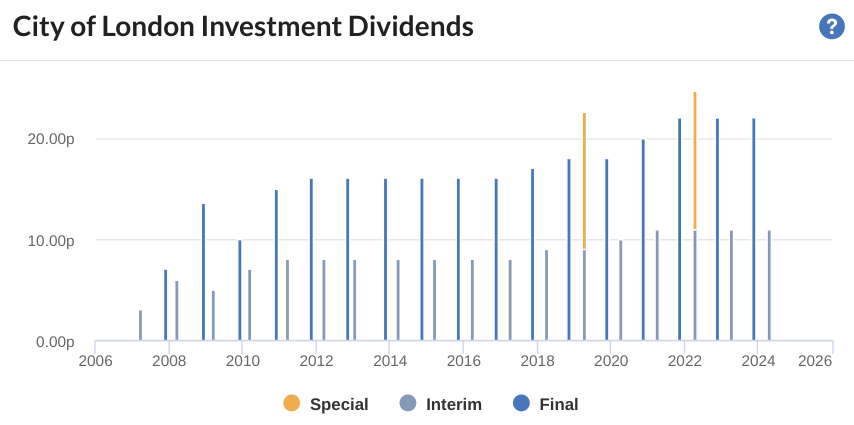
There’s a lot to be said for letting CLIG do all the clever stuff, and just own its shares and collect in a 9.6% yield, as opposed to investing directly into choosing our own closed ended investment trusts - although I know some of the readers are experts in that field too.
On the negative side, Graham did raise some valid issues about the downward trend of its margins, so investors need to reassure themselves that CLIG is not in structural decline. Nothing of that sort is jumping out at me from the graphical history -
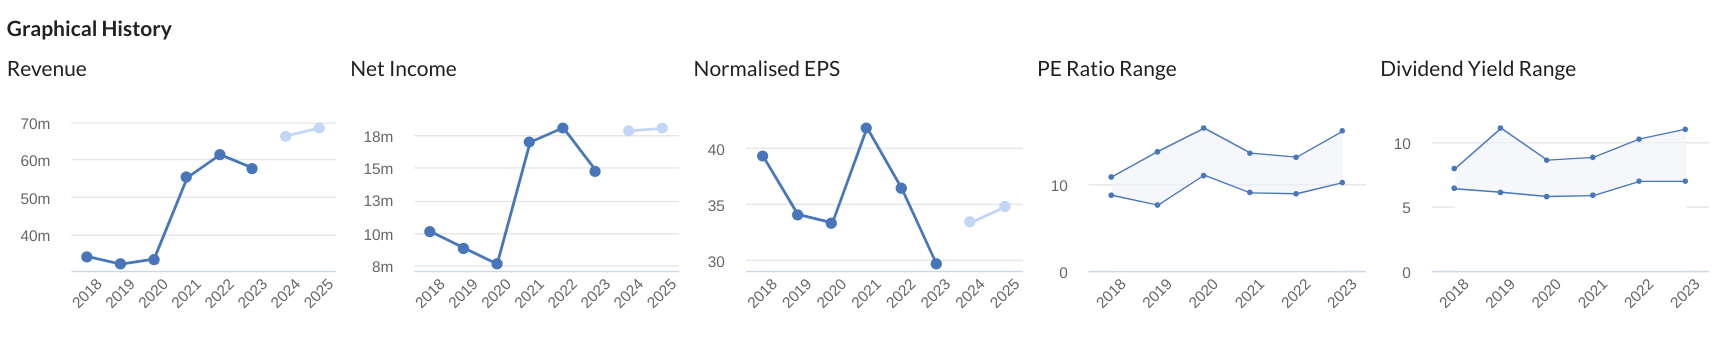
In conclusion, I think AMBER/GREEN feels right to me, ahead of Graham’s amber view recently.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

79 comments
It's very sad what has happened to Saietta (LON:SED) as it looks like really promising technology but they made some wrong turns and the cash burn was astronomical. I see the share price ended down 80% by the end of the day so condolences to any holders. It was interesting to look back on the interviews with well known fund managers over the last couple of months with one saying they were in a great position less than a month ago while the SCVR was repeatedly screaming red given the dire financial position. Maybe in a different market with strong financial backing they could have made it eventually as there did seem to be a demand for their eDrive systems which would have been good for the planet. I hope they find a buyer with deep pockets but it's not looking good.
A continuing rubbish market for UK small caps if my portfolio is anything to go by. But it will change. I suspect that will be when Andrew Bailey takes the metaphorical road to Damascus and hopefully sees the light
If this was other years and I had a week with a share up 24% another up 16% another up 10% a couple up 5-6%. I would have had a Stella week. But week after week, for every share that goes up by a decent amount, the rest of the portfolio wipes it out. It's like a game of wack-a-mole. My portfolio has gone nowhere for two years now. I was down 0.5% this week.
But never mind, I'm in Malta for the weekend and It was sunny and warm today.
Chemring (LON:CHG) a UK small cap in the defence, security and space sector, seems to fly under the radar a bit. I hold along with several other European defence companies, but most are large cap. Chemring fits my GARP approach, is a small cap and is, I think worth a look, providing you don't have any objection to investing in defence. After hosting Ukrainians for 14 months, I no longer have any such reservations and I think Trump's recent comments mean the European end of NATO is going to have to get its act together and fairly fast.
Chemring (LON:CHG) report unchanged guidance for 2024, perhaps not surprisingly given the strong tailwinds in the defence sector. Chemring has a 50% market share in the global countermeasures market. The 2024 order book at £991 million is up nearly 52% on 2023 with nearly 80% forward visibility.
The ROKE division in the sensor and information division shows solid growth with recent sales of electronic warfare systems to Sweden and Japan. ROKE also reports an increase of £10 m to £50m of project zodiac which is a core part of the British Army's Land Intelligence, Surveillance, Target Acquisition, and Reconnaissance ("ISTAR") Programme. The Sensors and information Division now has forward sales visibility of 74%
Their Countermeasures and Energetics Division has also delivered several major new deals providing 99% forward sale visibility for 2024. Chemring's Norwegian subsidiary Chemring Nobel has signed a 5 year contract worth £42 million with Diehl and in the US they have signed off a £9 million contract with NASA for the NASA standard Initiator system. They have also signed off on a AUS$31 million contract with the US Air Force who are acting for taly, Australia, Japan, UK, Poland, Germany and Denmark.
The shares have delivered a return of 134% over 5 years + an annual dividend of 2.3%. The business holds no debt but ROCE is a pedestrian 10% or so. I am hoping margins and ROCE improve in the years ahead as the product mix changes with increasing sales of from the ROKE division.
Chemring (LON:CHG) Agreed, but at 10yr high and directors selling at these levels...what do they know?
Michael Ord was appointed to the Board on 1 June 2018. Since his appointment, he has consistently sold options and never held the shares long term which I agree is a bad look. Sarah Ellard is basically the company secretary and has been at Chemring a long time. She also does not hold onto her options either and sells them pretty quickly. I have no idea who Lewis is ... he/she is not on the Board currently anyway.
What do I take from this?
They have always sold even as the profits moved higher. To be clear, Sales, Net Profits, Cashflow and EPS have all moved higher and consistently so over the past 5 years. Not only that but the company has progressively become cheaper on any measure - PE is down so is Price/Book and Price/Sales. So yes, they are at a 10 year high (but so are many of my defence companies - Rheinmetall AG (ETR:RHM) ; Kongsberg Gruppen ASA (STO:KOGo); BAE Systems (LON:BA.) ), but Chemring is actually at the cheapest point they have been for the past 5 years on the basis of the above metrics.
I think these individuals are deeply conservative as in the opposite of entrepreneurial. This mindset pervades the defence sector which must be one of the tightest regulated sectors out there. They are all heavily security cleared. I think they view their share options as part of their (cash) salary package.
I could be wrong of course, but they have been around a long long time and can trace their roots back to 1905. They have a critical role to play in defence strategies across NATO including the US and also supply NASA. I can imagine the intelligence community from multiple agencies has been all over them.
Having said this, in 2018, it was announced that the SFO had opened an investigation into corruption and money laundering. A SFO spokesperson has stated that the inquiry is focused upon "the conduct of business by Chemring Group and CTSL". However, in 2022, the SFO concluded: "There was insufficient evidence to support a realistic prospect of conviction as required by the Code for Crown Prosecutors".
https://www.sfo.gov.uk/cases/c...
Maybe there is some dirty washing about to be aired, but I doubt it. As I say, I think the share sales are a sign of a lack of entrepreneurial mindset.
Chemring (LON:CHG)
"She also does not hold onto her options either and sells them pretty quickly"
A lot of people who have never been given an option don't realise that as soon as the option is exercised the difference between the value and the exercise price attracts PAYE income tax. For a lot of people the only realistic way of paying this is to sell some. A company I worked for gave everyone a share option in lieu of a pay rise, when it vested there wasn't a choice but to buy and sell in one deal via the company broker. The proceeds were paid net of income tax with the next salary payment.
Georgia Capital (LON:CGEO) Edison latest update https://www.edisongroup.com/re...
Main holding is Bank of Georgia (LON:BGEO) . CGEO trades at a large discount to NAV.
Apologies if previously posted: attached link is a 20 minute interview with Laura Foll of Janus Henderson. It's an additional Money Makers podcast interview from last weekend. Focus is on small caps and the state of the UK small cap market, especially the lack of support from UK wealth managers versus, say their counterparts in Australia. Good interview.
http://tinyurl.com/ya37xtem
Nice little quirk on the widget today - top company is ME, 2nd best is YU!
Pity we didn't get "US" and "THEM" as 3rd & 4th!
I was wondering if anyone was going to spot that! Made me chuckle! :)
YU SED TUI ME ! ;)
DecEnt Big Boy Has Just Four Page...
Ndivia and our own Indivior yesterday had my eyes going cross eyed
to ME. to Yu!
(for anyone who grew up in the 80s)
LOL perfect!
Saietta (LON:SED) looks to be heading for the graveyard in a rather oddly timed RNS (13:40 today)
Looks like Saietta (LON:SED) is heading for the chop. RNS just out - sale process, administration possible.
Hi Mark, Thanks for flagging Saietta (LON:SED) announcement just out.
Key bit says -
"Should the Company not have made material progress with its formal sale process or with any other financing initiatives by the end of next week, the Company may need to commence planning for an administration."
Saietta (LON:SED) someone, somewhere might pick up some excellent Intellectual Property for a song.
Shame they didn’t get very far with their outboard motors as Yamaha have just recently agreed to buy Torquedo for a decent number. They seem to have put most of the work into light vehicles of one form or another, two and three wheelers for Asia.
Bytes Technology (LON:BYIT)
Wolf of Small St. and AstonGirl have both commented on this but there is also the question of closed period trading. Looking at October 23 there were these trades in today's RNS:
Interim results were announced on 26/10/23
"Under Article 19(11) of the UK Market Abuse Regulation (UK MAR), the period of 30 calendar days before the announcement of an interim financial report or a year-end report that an issuer is obliged to make public according to the rules of the trading venue where the issuer's shares are admitted to trading or the law of the United Kingdom, during which a person discharging managerial responsibilities of an issuer is prohibited from conducting any transactions on its own account or for the account of a third party, directly or indirectly,
relating to the shares or debt instruments of the issuer or to derivatives or other financial instruments linked to them".
More Harwood buys of Argentex (LON:AGFX) I see.
Hi davidjhill. May I ask if you a holder of Argentex (LON:AGFX) or prospective buyer? I ask as I greatly value your thoughts/opinions.
I've held them twice before, been in profit both times but then ended up selling for a small loss. As I'm a sucker for punishment, I've bought back in, with a small starter position, hoping that "third times a charm". Rockwood buying gives me some confidence that things might be better this time. I see Paul Hill has also bought in recently (any relation?)
I have a small position in Argentex (LON:AGFX) . I am considering buying a larger one at this price given the Harwood connection. Can’t work out how much of an overhang there is from Harry Adams (ex CEO) though as don’t think there has been a holdings RNS from him. So I am wondering where the selling is coming from and how much more there is to go.
And - no relation to the other Mr. Hill no ! :-)
Perhaps FOMO has got the better of me; I have today taken a position in Argentex (LON:AGFX), having held a couple of times in the past, and have often seen the SP of hover around 0.70 level as a matter of course. Maybe I was spurned on by buying by Harwood Capital who have increased their stake from 4.3675% to 5.0615%, as well as director buys over time, including some chunky ones:
For a balanced view, it's worth referring to Roland's comments (31 Jan 2024):
"Investors may be tempted by a low-ish P/E multiple (market cap is 8 times 2023 operating profit) with the possibility of an earnings recovery over the next few years.
The company is still profitable - as pointed out by the interim CEO - and it had net cash of £19m as of June 2023. If that has continued to move in the right direction, then the enterprise value here could be less than £45m.
Against that, I’d be cautious when considering:
Recent loss of senior management
The possibility or likelihood of share sales by departing managers
An unknown future strategy
Competition in the currency space - did senior management/the Board disagree over strategy as growth momentum was running out of steam in a crowded market?"
Hi Paul.
Like others have mentioned, I just wanted to say that the interview with Gordon from Beeks Financial Cloud (LON:BKS) was great, very informative and the reason why this share is one of my largest holdings. I initially invested at the end of 2021 and averaged down on recent share price weakness. I'm sure the share price will recover further when the regulatory approval is given on the latest Exhange win, hopefully this will be in the not too distant future. Looking forward to the Investor Meet Company Beeks Financial Cloud (LON:BKS) results on the 5th.
Great interview with Beeks Financial Cloud (LON:BKS) enjoyed it. Well done Pablo.
Yu (LON:YU.) has signed a landmark hedging deal with Shell, which represents an endorsement of the model. It reminds us how far Yü has come since the last deal in 2019. It obviates the need to post collateral in the foreseeable future. Net cash and interest estimates are left unchanged, since Yü was receiving interest from Smartest Energy anyway. However, this reduces the need for a cash buffer and we expect Yü could invest significantly in further growth whilst also increasing shareholder payments. At 31 Dec 2023 net cash plus collateral was £4.90 per share. We believe that lower energy prices are manageable. The hedging will no longer be marked to market which also reduces reported earnings volatility. Maintain BUY and TP up from 1,676p to 1,883p; a CY 24 P/E of just 6.8x
Liberum note courtesy of a poster on ADVFN BB
RE:CLIG
A long term holding here as well. A very rare company where the management is aligned to long term shareholder value.
In the news today another giant step for mankind as an unmanned spacecraft driven by AI successfully lands on the moon and transmits pictures home. I've worked with technology since 1965, wrote my first computer programme in 1971 but this blows my mind with its potential and opportunities. Watch for an explosion of news similar to the dotcom era, some good but probably following the 80:20 rule. Be wary.
YES! SO EXCITING! I see Intuitive Machines (NMQ:LUNR) up 45% so far in the pre-market, surprised it is not up much more.
I hold Intuitive Machines (NMQ:LUNR)
Perhaps in the next landing!
Well done finding this stock. Its multi-bagged nicely if bought in at the lows. I've added this to my watchlist if it sets up again, its rallied too much for an entry right now.
The US markets reminds of the AIM stocks back over a decade ago, when there was still plenty of risk but plenty of reward too with multi-baggers in abundance. Now its smells of death.
Got my eyes on Arm Holdings (NSQ:ARM), waiting for correct setup before I take a position.
Intel (NSQ:INTC) is interesting in my opinion as well-I have added to my position today as I feel they have the capacity for much bigger revenues. Arm Holdings (NSQ:ARM) is on my watchlist as well.
Intel (NSQ:INTC) is interesting in my opinion as well-I have added to my position today as I feel they have the capacity for much bigger revenues.
Well done on LUNR but if you can tolerate a negative view, Yiannos, INTC is dead money IMO without a decent divi to keep you engaged. Losing market share for the last decade across AI and Data Centre due to a lack of competitive products vs NVDA esp but also AMD and now losing out to multiple new competition on CPUs across PC/notebook. They've always got a plan to fight back and it hasn't worked in all the time I've been watching. Price is barely up in 20 years.
File under IBM - literally and figuratively!
From John Authers today - At one point, Intel’s market cap was $497.6 billion bigger than Nvidia’s; now it’s $1.78 trillion behind.
Maybe I know things you don’t know
Who knows!
All the best
Hi Paul - Fantastic interview with Beeks Financial Cloud (LON:BKS, thank you very much.
Is Volex (LON:VLX) one of the other interviews you have lined up? If not, i can put you in touch with someone who is in contact with the CFO/CEO and could help set up the interview. Please let me know.
Thanks joshwood. I haven't approached Volex yet, as thought I'd wait for the next trading update. I think people are fretting about the risk of customer destocking, that seems to be affecting quite a few companies - although in the past VLX has seemed to absorb problems in one division with out-performance in others.
Also I find the IMC webinars and results statements very thorough for Volex, so not sure I could add much value with a CEO interview there. So I'll leave that on the backburner for now, but thank you very much for the offer of your contact to help fix up a podcast, I might take you up on that at a later date.
Best wishes, Paul.
No problem Paul.
Annoyingly, Volex (LON:VLX) don't update the market between October (HY results) and Apr (FY results), so we won't get an update from them for another couple of months.
Volex (LON:VLX)
#Annoyingly, Volex (LON:VLX) don't update the market between October (HY results) and Apr (FY results), so we won't get an update from them for another couple of months.
Surely they only dont update if they are on track to meet expectations - if they are no longer on track to meet expectations are they not obliged to tell the market pronto ?
Yes the de-stocking has even impacted Tate & Lyle (LON:TATE) and Safestore Holdings (LON:SAFE) this week. There was a headline about Nestle too I think.
Lower volumes atSmurfit Kappa (LON:SKG) last week (sales down 12%) which I hope won’t read across to Macfarlane (LON:MACF)
Lower volumes atSmurfit Kappa (LON:SKG) last week (sales down 12%) which I hope won’t read across to Macfarlane (LON:MACF)
Thanks for the pointer NeilS - after a quick look at the Smurfit overview it doesn't look too bad - the company reports improving demand into Q4 and high demand for sustainable packaging. Enough for them to hint at an improving outlook for FY24?
Smurfit is an impressive operation but I find it hard to draw comparisons as Smurfit is a global paper maker. I do note that at Smurfit volumes are down 3.5%, sales down 12% and basic eps down 20% - which points towards lack of pricing power?
By comparison Macfarlanes TU (results next Thursday 29th) reported sales down 2% and adj profit ahead of last year. We're not given volumes but I suspect that they have fallen further than Smurfit's and is the opposite trend - indicating some pricing power? Not entirely suprising if thats the case as Macfarlane is primarily a distributor and its growing manufacturing operations are in high margin sectors - defence, medical, industrial - so should be more nimble than the paper mills with which it is normally compared?
Macfarlane did report particularly good performance from its European operations - to the extent that it will need to take a charge for writing back the deferred consideration for Packmann which it had previously considered unlikely enough to write down. Given the huge opportunity in Europe I found that encouraging?
Perhaps Macfarlane will also point to an improving outlook next week? Thanks for the pointer,
cheers
Mark (Macfarlane is my second largest holding)
Hi Mark, well they both sell cardboard boxes but Macfarlane (LON:MACF) is more of a merchant whereas Smurfit Kappa (LON:SKG) is vertically integrated and owns forests, paper mills and colossal converting and box manufacturing and printing capacity especially in shelf ready packing. Whereas DS Smith (LON:SMDS) sits in the middle between the two with a smaller mill footprint and a lot of retail brand exposure.
I believe you are right about some of Macfarlane (LON:MACF) niche markets as they did buy a correx (fluted polypropylene) converter a few years ago however just for example, Smurfit Kappa (LON:SKG) leads in wine boxes and owns the IP for the taps.
Here’s to hopefully good news from Macf next week! I hold too.
Shein targets Boohoo suppliers amid UK expansion
https://www.retailgazette.co.u...
Shein is understood to be in the process of onboarding several Boohoo suppliers as it ramps up its UK expansion plans.............The news comes as Shein rapidly expands its presence in the UK, with the appointment of former Boohoo-owned Pretty Little Thing buying director Gemma Dunne as its first ever chief product officer
Ouch! That’s gonna really hurt!
Chemring (LON:CHG) Trading update "broadly to plan' with severe weather pushing revenue into the second half. Order book at the end of January £991m v £654m. Mkt cap £990m before anyone whinges.
Thankyou, great interview with Gordon Paul. Clearly we have to double down on finding these undervalued gems!! I hope your Mum is recuperating well.
Transense
Long chat yesterday with the chairman and also been discussing with the head of technology .
Have agreed to go meet them in a few weeks in Newcastle if annoying wanted to jump on board and come along they sounded very amenable and surprised by the internet .
It’s quite an interesting set up and I think similar to my perception of a lot of Aim companies.
There seems to be s plethora of technology led AIM companies that have floated and raised money based on technology and opportunity your classic “jam tomorriw” “let’s raise sone money “ companies founder and scientist led but with not much commercial savvy and they fall down converting to sales .
It’s a classic “men in white coats” trying to run s company and build a brand .
Sometimes they succeed but often they lack commerciality and they fail often in my opinion because they can’t think like a customer. The best entrepreneurs always think from the perspective of satisfying the needs of their customer .
Transense certainly historically seems to have fallen in that category but are fortunate in having diene a smart thing is licensing off one part of their company to Mitsubishi for a royalty stream.
This runs to 2030 I believe and is generating 2.6 million last year , it reduces in the last years of the agreement - by my day packet this underpins the company meaning no fund raising required . Plus tax free due to tax losses .
That was a smart deal and we’ll done to chairman .
That leaves two divisions
A tyre monitoring division which they are already selling overseas to several tyre manufactured but bizarrely no uk sales .
This is a good sector with statutory requirements for trucking companies , tyre manufacturers etc to record and measure tyre wear . Also police forces need and are trialling .
Huge market but the “men in white coats” mentality appears to have held them back and looks to me like they have only really started to take this seriously .
There is good scale in this, And it has mass market potential if handled correctly but they are not marketeers and concentrate on selling to manufacturers .
They need a serious effort on sales, marketing . Branding etc . Which they clearly know as they have hired a head of sales and head of marketing, if the head of sales is good and the marketing is good they have a bit of an open goal .
They also need to scale up production .
These look the right moves but seems early days and it’s so blindingly obvious they need someone to go sell it and market it seems strange to have left it this long .
Bit torn on this , from the little I know this Couid be a goldmine if a wheeler dealer entrepeneur got into it and made it mass market with a quirky brand and dropped the price (every car in the country Couid have one in the glove box)
That may well happen in 5 years but as the IP doesn’t look good it will be an Amazon type Jeff bezo that make the money and not Transense despite them have been in first mover position .
Third part is an sawsense which seems very clever and again jam tomortow at the mercy of super long runway in getting big contracts . Looks potentially hugely interesting but can’t see it happening quickly
Managrment very down to earth chairman has bought his own shares with cold hard cash and earns a paltry 60k and is very engaged with things and seems to be the one who nailed the Bridgestone contract which has given them the cash to continue without getting the begging bowl out .
Ryan head of technology owns two of my bikes so he’s ticked a few boxes and he seems to be responsible for the sawsense opportunity and development , as a proven entrepeneur who sold his first business maybe he’s got the stamina and skill to work this one out .
All this is based on the limited knowledge I have
Personally I wouldn’t recommend buying anything now as there is no real significant thing likely to happen but I’d watch out to see if any sawsense contracts start getting RNS .
If sawsense does get commercialised that’s them delivering on the second part of the business .
Anyway if anyone fancies a trip up Newcastle with me let me know , probsbly in about a month as off to Italy for a few weeks road trips on Sunday .
Sorry for typos written on phone and my dyslexia and bad eyesight are a deadly combination .
Actually, I enjoyed the typo's - a bit of a brain teaser! I assumed you had used a dictation app to render your long and very interesting note.
I first heard of Transense Technologies (LON:TRT) in a recent tweet from Rhomboid (thank you!) and spent a few hours looking into it. There are a few small cap companies such as Good Energy (LON:GOOD) and Eenergy (LON:EAAS), who have recently manged to acquire plenty of capital for their endeavours over the next few years and the Bridgestone deal does that for TRT. I agree your observation that is smart, because higher interest rates will constrain many small companies from effectively exploiting their assets over the next few years, with the result that a strong balance sheet will tend to become more highly valued relative to other factors.
If the tech is good (and the Bridgestone deal is a very good indicator of the quality of wat they can do) and if they can sell it, they could do very well. From a market cap of £16M, that could mean very well indeed for shareholders. The board do seem very aligned with the shareholders, refreshing but also an indication of the likelihood of a good outcome.
There are some bullish signs but I don't know for sure they will do well, merely that they could, based on what I have seen so far. If I was a betting man I would say the chances range from genteel failure 20% to 33%, reasonable success over a 5 year period 34% to 60% and multi-bagging 20% to 33%. Well, I must be a betting man because I bought an initial stake.
Regarding your potential visit, I would like to join you, but my ability to do so will depend on the particular day arranged. You can reach me on Twitter at @Monty9_David or email davidbwhitehouse@yahoo.co.uk .
They sound to be quite innovative planetx and of interest. That said and I don't know my facts with regard to their offering here but my Tesla has a tyre monitor in it already. I don't know where it comes from but it constantly tells me the tyre pressure and when the tread depth is no longer legal. So are they trying to reinvent the wheel or is this different? If you have a date and I am free I will nip up to Newcastle with you to try and get a bit more of an understanding of what they do.
PlanetX Thanks for your interesting comment and I wish you good luck with the investment. Transense Technologies (LON:TRT) is just the sort of innovative company that should be at the smaller end of the stock market and hopefully should be able to be financed by investors. The management are open and approachable and you should get a lot out of the meeting
I held the stock for a couple of years and sold out in June 2023, a few months after attending the AGM in Bicester, when I realised I was really a newbie and most of the other shareholders were still waiting for Godot. So, for balance, let me point out a few of the bear points - although I am no longer up to date with the company.
1). The P/E is a meaningless number as the itrack royalty will end completely after FY2030 and will take two serious step downs in 2026 and 2028.
2). The SAW technology has been the long-term promise for this company for a long time but it seems a slow burner - the licence deal with GE was signed in 2016.
3). I would advise listening to the 20 October 2020 ImC call (questions 5 in particular of the Q&A asked by someone called “John” - but also see Qs 6, 7 and 11). On listening to this in 2020, I decided that the company would be really hard nosed about capital allocation decisions - and would not fall into the temptationof frittering away the cash flow from the iTrack business. I felt Nigel Rogers was guiding the market that within the next 12 months or so (by end-2021 say) they would have a good idea if SAW was a worthy investment or not. I guess the reason I then sold out in 2023 was that I was not so confident this remained the corrct assessment.
You seem to see quite a bit of promise in the Translogik (tyre probe business). This was seen as the least important of the three businesses at the time I was looking at the stock more closely Perhaps things have moved on .
Big volume yesterday on Hornby (LON:HRN) Frasers increased holding to 8.9%
The Fat Controller
Positive strategic development. Obviously it can't be a prelude to a takeover given Phoenix stake and I wonder if Phoenix sold some of their shares to them to make this happen, since it is hard to see how they aquired that many otherwise given low liquidity. I have been patiently holding and think it's another case of a turnaround taken longer than planned.
And Hornby (LON:HRN) up over 20% this morning I believe. Patience is a virtue.
Bytes Technology (LON:BYIT) the recently departed CEO appears to have fancied himself as a bit of a wheelie dealer with not less than 118 trades in his own company’s shares. All of which he neglected to tell his employer of. Doubt it’s a coincidence we’re told he resigned this week and left immediately ;)
I am no expert but is this not illegal - insider trading?
Blimey - thats not good! Illegality depends on whether those trades were undertaken in a closed period for the company…… hard to see how 118 transactions could be done outside of those windows in entirety but I guess thats up to the company to investigate and work out. However, I’d say it very likely breaches MAR rules given his position.
For directors to be able to trade requires consent from the board and advisers to ensure they are not taking advantage of inside information at any point. It is obviously completely against the law that he has done this 118 times and somehow it has come to light...maybe a whistleblower. There could be criminal proceedings and if it was in the US the case would de done and dusted in six months and jail for six years....Here it will take seven years to tell him he should have done better with those trades and needs to attend a course with the Naked Trader lol
Larger companies have policies on this, with guidelines about when it's permissible to trade (normally outside close periods, and provided that no inside, market-sensitive information is held) - I had to agree that my broker would report all trades in my company's shares to the Company Secretary, who routinely vetted them.
Not sure if the recently departed Bytes CEO has done insider trading, but he doesn't seem to have benefited much from any insider knowledge if he has. I assume he will plead ignorance which, looking at the number of trades, would seem a reasonable supposition. Pleading insanity might be the other option (but only joking).
Results out of City of London Investment (LON:CLIG) today. Earnings down modestly, but a bit worse when translated back into sterling (I’m not a fan of UK companies using dollars, but I understand why they do).
Dividend flat.
I have a modest holding, and will continue to hold. There is no doubt that emerging markets are cheap, and CLIG will benefit from any upturn. I suspect that China and US interest rates are the cause.
Still a well run firm.
A notable point in the report regarding the growth of passive funds v active. The former are now larger.
Still a lovely dividend at City of London Investment (LON:CLIG) which looks safe for now! Plus we're probably at or near the low point in the cycle so I think this is a pretty good entry point.
Main bear point is the profit margins seem to be coming down so need to keep an eye on that...
Bytes Technology (LON:BYIT) ex CEO merrily trading shares between 2021-23 without bothering to inform the market.
"trades total to 313,741 shares acquired at a volume weighted average price of 479.23 pence per share and 313,741 shares sold at a volume weighted average price of 483.46 pence per share"
He's no future as a trader that's for sure. I'd like to see the book thrown at him for this tho.
I won't be getting my hopes up.
My morning smallcap tweet: The City's event horizon
STM (LON:STM) Tribal (LON:TRB) Verditek (LON:VDTK) Yu (LON:YU.)
◄STM (STM)► guides FY-Dec rev £28m, ahead of mkt exp due to higher interest income. However 'overall performance' in line. [SP=56 Cap=34m]
◄Tribal (TRB)► now entering into a mediation process with Nanyang Technological University. Latter has hikes its demand to $378k. [SP=43.4 Cap=92m]
◄Verditek (VDTK)► extended current cash runway by a week, to 4 Mar as it talks to bondholders. [SP=0.09 Cap=m]
◄Yü (YU.)► a 'transformational' new Hedging Facility with Shell whereby Yu won't have to deposit cash as collateral to support mark to market movements. Releases £52m. [SP=1160 Cap=194m]
Great interview with Beeks Financial Cloud (LON:BKS) Paul, thanks!
Thanks Plinkut, glad you liked it! :-)
I'll try to do more of these interviews, as they do add value I think, but take quite a lot of preparation time that's the trouble.
I've never properly looked at Beeks Financial Cloud (LON:BKS) before but one thing that puts me off immediately is the Stocko data suggests despite growing revenues it has not managed to grow profits and in fact its margins seem to be falling. Is that where it has had to spend a lot on capital investment?
Beeks Financial Cloud (LON:BKS) must have spent about £60m on CAPEX over the last five years; this massive CAPEX investment at the same period managed only to return about £4m in profit.
Beeks Financial Cloud (LON:BKS) must have spent about £60m on CAPEX over the last five years; this massive CAPEX investment at the same period managed only to return about £4m in profit.
Build it and they will come, Yiannos1. I hate comparisons with Amazon but this is one instance where the comparison is valid. Not only because there was a company that constantly reinvested in capex at the expense of profit to build its market dominance, but because that capex was mostly in servers and data centres. And that worked out pretty well. But I guess you never fancied Amazon’s accounts either! Plenty of ways to build a portfolio
I like Beeks because of the combination of a) incredibly sticky, high value services that constitute a powerful moat and b) the highest spending customers on the planet. That coupling spells big potential for profits to me down the line even if it takes a while to find the optimal service offering.
These are the figures I have in front of me on Beeks Financial Cloud (LON:BKS) hopefully the results will come.
All the best
Hi Yiannos - Beeks Financial Cloud (LON:BKS) is an infrastructure play and whilst it is capex hungry early in the roll out it will be a cash machine in future years. Absolutely no different in that regard to AWS or Azure, just at a slightly different stage in trajectory.
But this type of business (with tier 1 exchanges and other financial institutions) trades historically on very high multiples as the business is so sticky, and as canny investors know, the level of spend each institution contributes tends to go up materially over time. This is why Michael Spencer managed to sell the likes of NEX to the CME at close to 40* earnings as an example.
I bought a few years back at around 60p and haven’t sold any because I anticipate it to be much much higher in a few years time. The market doesn’t quite recognise it yet because there is far too much focus on the very short term, at least in the UK. Maybe not the best/most lucrative strategy for me as I could have traded in and out but I’m more of a long term investor - ie I prefer growing businesses that can compound for me.
But forecasts do not include anything from the new Exchange client so I expect them to be materially upgraded once reg approval (c. 6 months) comes through for this deal, plus Beeks Financial Cloud (LON:BKS) is now cashflow generative (ie can self fund the capex investment and still increase net cash).
Anyway thats just my view for whatever its worth - could be wrong of course.
I'd like to open a position in Beeks Financial Cloud (LON:BKS) but I just have a feeling that over the next few months there is a good chance it might start to drift down on a lack of news (with once again traders getting bored) and there might be a better entry point in the 130-140p range.
I'd like to open a position in Beeks Financial Cloud (LON:BKS) but I just have a feeling that over the next few months there is a good chance it might start to drift down on a lack of news (with once again traders getting bored) and there might be a better entry point in the 130-140p range.
So buy a third and, if the next move is up, you’ve made a profit and started the journey. If it drops, the hit is minimal and your strategy is working!
Beeks Financial Cloud (LON:BKS)
For some companies is plainly clear that they need upfront capital investment to be able to reap the rewards later - there isnt anything intrinsically wrong or dodgy about any of this its pretty simple facts and beeks is one of those companies ihmo.
I wont disagree with anyone who says its not for me as the rewards might never turn up in which case you have invested for little to nothing or even lost your money.
however if company does come out then other side here where they reap the rewards without having to spend material extra then all that extra spend is thrown back as cash on top of profits.
In summary the lack of cashflow now should be no surprise and has innocent explanation albeit there is always possibilty the jam may not arrive for one reason or another.
I dont hold here but i think the upward trend in sales is clear the jam is "on order" (update 06/02/2024) and the furture narrative is crystal clear
Per the company 06/02/2024
Our growing contract momentum demonstrates the considerable appetite we see across the financial markets, and we now anticipate FY25 will be significantly ahead of our previous expectations."
this statement does not seem to be coming from company with faint hopes of the jam tomorrow (Bango plc they recently casncelled their jam?) - i dont think they would be upgrading 2025 numbers unless they were uber confident. Those numbers are for £6 mill profits 2025 - that is clearly transformational compared to what they have spent in the last 5 years. That being the case why would anyone look back at the last 5 years without equally looking ahead to see if things are better - they clearly are.
Fair play to company for putting progressive note on the website - this confirms in 2025 we can expect over £2.5 mill of free cashflow - ref capex it will still be chunky at £9 mill - but thats down from peak of £12 mill capex in 2022. So for 2025 we are still getting under 50% of profits turning to positive cashflow - but the trend is clearly improving and one should expectb that to grow again in 2026. It will be intersting to see what 2026 numbers are pencilled in when those are first made available - i would like to think cashflow should be improving again unless they have plans to ramp up sales yet again. Note 2026 may seem far off but as this company has 30/6 year end we are nearly within 4 months of that being "next year forecasts" - so 2026 numbers should turn up within 6 months if they arent out there somewhere now.
Not listened to the Beeks Financial Cloud (LON:BKS) interview yet but after giving me a decent update on the UK stock market vs rest of world "CoPilot" gave me this summary in response to "Beeks Financial Cloud News"
Certainly! Here’s some recent news related to Beeks Financial Cloud Group plc:
Beeks Financial Cloud plc is a leading managed cloud computing, connectivity, and analytics provider for capital markets and financial services. Their vision is to Build, Connect, and Analyze by delivering low-latency compute, connectivity, and analytics on-demand. With ISO 27001 certification, Beeks supports global customers exclusively within global capital markets and leading financial centers5
Quite impressive I thought (the response) but the figures seem decent too.