Small Cap Value Report (Fri 23 June 2023) - HOTC, IGP, HFD, BOOM, G4M

Good morning from Paul!
I'm hoping for a quiet news day today, so I can catch up on some of the backlog things on my list.
Today's report is now finished. Have a lovely weekend!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Agenda
This is my plan for today, below. I'll start with the 2 profit warnings, then I really want to finish off MSI, which I looked at in detail last night, as it looks an interesting company (a podcast mystery share in late 2022), and has a bulging order book. Something interesting seems to be going on there, and we're already GREEN on it anyway, so a recap would be useful for results that were issued yesterday. [EDIT: sorry, I'll finish MSI over the weekend, there wasn't enough time today]
Hotel Chocolat (LON:HOTC)
Down 13% to 121p (£166m) - Trading Statement (another profit warning) - Paul - RED
Hotel Chocolat Group plc, a direct-to-consumer premium chocolate brand, today updates on recent trading.
Background - the current financial year is FY 6/2023. Checking my previous notes here -
6 Dec 2022 - I mystery shopped Islington store, and found product disappointing & expensive. AMBER.
20 Jan 2023 - 209p - H1 (Dec 2022) in line. Guidance £8m PBT FY 6/2023. I’m sceptical about valuation. Brokers forecast large increase in profits in future years - realistic? AMBER.
27 April 2023 - 158p - Profit warning, now says only breakeven for FY 6/2023. Remains over-priced at 158p. I move to RED.
Today’s update -
Cost cutting has been slower than expected
Sales in line with market expectations (footnote: £201.8m)
Profits lower - “underlying marginal loss” for FY 6/2023, below £0.3m current guidance. Doesn’t sound too bad, but what’s a “marginal loss”? £1m, £2m, £3m?
Cash generation healthy & has £19m cash (down from £28m at Dec 2022) with no interest-bearing debt - the balance sheet is solid at HOTC, so providing it doesn’t start generating massive losses, then I think solvency (and dilution) are very low risk at the moment.
Outlook - this is the bad bit, as they can’t pass this off as a timing issue -
For FY24, the Group expects sales and underlying PBT to be lower than current market expectations due to ongoing weakness in consumer sentiment and continuing inflationary pressures.
Guidance for FY 6/2025 is reiterated, but in my view wasn’t credible to begin with, and now looks like pie-in-the-sky -
For FY25, the Board clarifies its guidance for the target of 20% pre-IFRS EBITDA to be achieved towards the end of the year, with the full benefits being achieved through FY26.
Broker update - many thanks to Liberum’s analyst Wayne Brown for his detailed update this morning, this is really helpful, and I'm aware that a lot of work goes into these broker notes with detailed forecasts. He’s answered my question above, by pencilling in adj PBT loss of £(1.5)m for FY 6/2023, down from a previous forecast of positive £0.8m. That’s a mild disappointment, but not a disaster, as I see it.
The real damage is a massive cut in FY 6/2024 forecasts - the unrealistic £20.3m adj PBT now becomes only £6.0m. Given macro, personally I’d be surprised if they even achieve that reduced figure.
The FY 6/2025 forecasts were bonkers previously, at £33.1m profit, which has now been greatly reduced to £14.3m, but still seems optimistic.
Paul’s opinion - I remain highly sceptical. The only positive thing is that shareholders don’t have to worry about financial stability, as it has a nice strong balance sheet with cash, no bank debt, and £20m freehold property. Lease liabilities might become a problem though, if shops become loss-making.
The company has repeatedly over-promised and under-delivered. I think the share price has much further to fall, as the bull case unravels further.
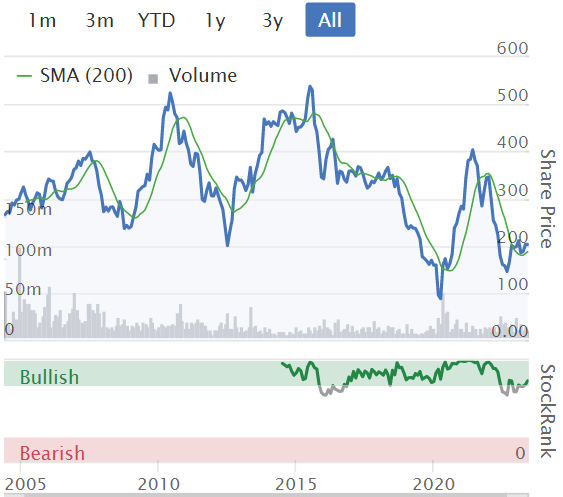
Previously the market valued this as an international growth company, but that's now fallen flat. It seems much too early to be anticipating a recovery, we need to see some evidence of a turnaround first -
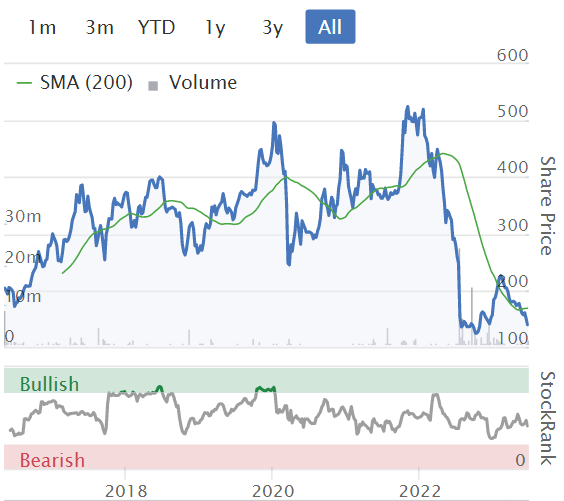
The StockRank isn't good, and I imagine it's likely to worsen, as lower forecasts and a lower share price feed into the momentum and value scores. As for quality - well I don't see this as a quality business at all!
Intercede (LON:IGP)
51p (£30m) - Results FY 3/2023 - Paul - AMBER
Intercede, a cybersecurity software company specialising in digital identities…
Background - we’ve followed this small, specialist IT company for many years here, and spotted a nice turnaround in 2018-19, doing well on the shares which I held personally for about 3 years, as they 3-5 bagged depending on when you bought. It's since given back a lot of those gains though, in the last 2 years.
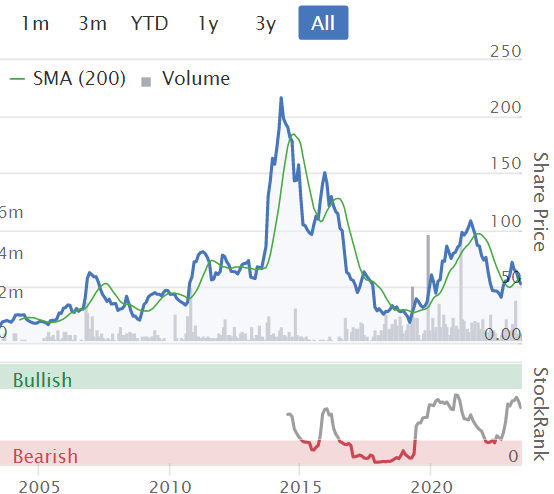
(the excitement in 2014 was big contract wins, which were not repeated)
Old management had a high cash burning strategy, spending on new, speculative projects, but it nearly ran out of cash. So new CEO Klaas van der Leest was brought in 5 years ago to turn it around. He’s done a good job I think, firstly stemming the losses, then moving it into profit, and resolving a convertible loan note debt problem. The finances are now very healthy, with a nice cash pile. It’s also making small bolt-on acquisitions.
So this is a small, profitable, soundly financed, niche software company. The main attraction is its staggeringly impressive client list - very sticky recurring revenues, from US Govt departments, major aerospace companies, etc. Most of its business is in the US, and it seems to be a small part of big IT systems, and is dependent on several long-term, major US contracts, so client concentration is a risk.
FY 3/2023 Results - key points -
Revenue up 22% to £12.1m - small, but very high margin, and good growth (helped by the strong dollar)
Clean accounts, with no adjustments, and all development spend is expensed.
Profit before tax (PBT) only £0.6m (double last year though)
Corporation tax is negative, due to favourable R&D tax credits, so a £685k tax credit, more than doubling the £626k PBT to £1,311k PAT (profit after tax) - although on webinar, CFO said this will reduce to £350-400k in future years.
Diluted EPS is 2.2p (LY: 1.2p), giving a PER of 23x
Dividends - it doesn’t pay any.
Balance sheet - only about £4m NTAV, but that’s fine because working capital works favourably, with customers paying up-front for support, licences, etc. So the £8.3m cash pile has mostly (£7.5m) come from deferred revenue (customers paying up-front), but that rolls continuously, so not a concern.
Outlook -
This has been an encouraging and successful year for the Group. However, to maintain and sustain its current momentum, it needs to continue to invest in its colleagues, IT Infrastructure, product development and sales and marketing.
We embark in to FY24 with good visibility on the pipeline, known and fully resourced internal critical investments and with a clear road map on our acquisition strategy. As mentioned frequently, the focus is on 'growth' and execution of strategic plans to deliver it.
The way I read those outlook comments, is that revenue growth is probably going to be ploughed back into the business, so probably not much prospect of significant profit growth for now (unless it wins a monster new contract). That’s probably the right thing to do, but it does mean shareholder returns could be limited.
Also, staff costs make up most of the overheads, so current wage inflation has forced IGP to give 5-7% pay rises to its (mostly UK) staff, and performance bonuses.
Paul’s opinion - probably priced about right for now.
Bull points:
- Stunning client list of major organisations in the US
- Global specialist in its niche
- Takeover target for a larger IT group possibly?
- Sound finances with £8.3m cash pile (gone up since y/end mgt said in webinar)
- Upside potential if it wins big new contracts, drops through to profit
- Much wider target market now, with new product development, previously just high end
- Capable and trustworthy management that tell it like it is, good shareholder comms (see recent IMC webinar), and have implemented an effective turnaround at a previously problematic company.
Bear points:
- Sluggish revenue growth historically, although +22% this time is better
- Growth likely to be reinvested in higher costs, so limited profit growth?
- Valuation up with events on a PER basis.
- Long-serving staff - great experience, but set in their ways maybe? Are they hungry enough for growth?
Overall - I think there’s a good case for holding this share, so you’re in the right place if/when some major contract wins, or a takeover bid happens, but that's speculation, and may not happen of course! The main downside risk I see, is if one of the really big US Govt clients rips out & replaces their IT without Intercede in it - so client concentration is the main risk I see. Other risks might include catastrophic system failure or security breach.
I’ll keep an eye on it, and hopefully shareholders might be rewarded with an acceleration of growth, and some decent sized contract wins. Good, credible management, are worth backing I think, but I'll stick with AMBER for the time being.
Halfords (LON:HFD)
211p (£472m) - FY 3/2023 Results - Paul - AMBER
I last looked at this motoring/cycling group in Jan 2023 here, when it issued a Q3 profit warning, lowering profit guidance for FY 3/2023 by about 17% to £50-60m range. Shares dropped 20% to 173p, and I took an AMBER view then, based on the facts, figures, and forecasts on the day.
What’s the latest?
FY 3/2023 Results - I haven’t got time to go through this in detail, so will just draw out some main points -
Revenues £1.6bn (up 15% on LY), so a substantial business.
It’s more than just a retailer (61% revenues), with Autocentres (servicing, MoTs, etc) 39% of revenues (£614m)
Underlying PBT £51.5m, towards lower end of range guided in January, and well down on LY, which was boosted by customers’ pandemic lockdown spending.
Adjustments benefit this figure by £8.0m, and in note 4, I think these are rather questionable, especially £6.3m restructuring costs, which I think is fairly normal for this type of business, so personally I would add that back, lowering profit by about 12%.
Underlying basic EPS of 18.8p (LY much higher at 35.5p) - PER of 11.2x
Outlook - there’s a big section, so let me summarise the main points -
Current trading - “good”, positive LFL sales growth, despite poor early spring weather.
Expecting modest profit growth in FY 3/2024 - comfortable with £53.3m u/l PBT from brokers (barely any change from £51.5m FY 3/2023 actual) - so it could easily move over or under, given the large numbers & uncertainty.
Net cost headwinds expected at £30m - wages, FX, energy, “partially offset” by lower freight costs on imports.
Aiming to offset this cost headwind with lower cost purchasing of products, and efficiency gains, a third already delivered.
H1 expected to be below LY (which benefited from a forex gain), but H2 above LY.
Expects to end FY 3/2024 with “small net cash position” (excl. leases)
Further out, it says -
Looking beyond FY24, we expect strong profit growth in FY25 as we take a significant step towards our mid-term expectation of £90-110m underlying PBT, as outlined at our Capital Markets Day in April 2023.
I think it’s too early to forecast that far ahead, so I’d take this with a pinch of salt for now, until macro becomes clearer.
Balance sheet - NAV is £563m, but deducting £482m intangible assets gives us £81m NTAV - OK, but not a lot given the size of the business. Note that NTAV has fallen in the year, from £109m last time.
Given the not particularly strong balance sheet, I question Halford’s strategy of both paying fairly generous divis, and continuing to make acquisitions. The danger here is that it erodes its NTAV, building up goodwill, but weakening the overall financial position.
I think this also makes the divis not particularly safe. In the event of a big consumer downturn, HFD would have little choice than to cancel its divis. Just something to bear in mind.
Net debt was eliminated in the year, from £46.1m at 1/4/2022, to net cash of £1.8m at 31/3/2023. Although given the large size of the business, I wouldn’t get too excited about year end snapshots, as the daily figures are likely to yo-yo all over the place during the year, when large payment runs to suppliers, payroll, VAT, etc are paid. Whereas daily cash inflows will be fairly level and predictable, being retail cash coming in from the card processing merchant divisions of their bank. What we need, for all companies, is the average daily net cash/debt figure. I’ve done a search using CTRL+F for the word “average”, but it doesn’t throw up anything relevant. However, note 5 shows only £1.4m finance charge on bank borrowings, which suggests it's probably not using the RCF excessively, and intermittently, which is what it's there for!
Cashflow statement - looks amazing, but the £154.8m operating cashflow is a nonsense number, because it excludes rents! These are lower down, in financing activities, and are £8.8m + £80.5m, so that lowers genuine cashflow to a more realistic £65.5m, which is not particularly good for a company valued at £472m.
Also look closely at the “investing activities” section, with £32.6m spent on acquisitions - fine, it’s buying up and rebranding car servicing businesses. Note £25.4m “purchase of intangible assets” - I don’t like the look of that, it sounds like capitalised development spend on IT, which I think should be expensed, not capitalised. Although the P&L does include a £17.9m amortisation charge. Net these off, and it looks as if profit is boosted by £7.5m through this policy. Physical capex is £29m.
Two unusual items are £22.7m “Receipt relating to supplier financing”, and an offsetting £23.5m “Payments relating to supplier financing”. I don’t recall seeing that before, so am curious what it is, a good question to ask management to explain this, although it’s not material overall.
Dividends - total divis up 11% to 10p, yielding a nice 4.7%, but as noted above, I don’t see the dividend paying capacity as being particularly good.
Paul’s opinion - the really detailed outlook/guidance section suggests to me that this seems a well managed business, where management and finance people are really in control of everything, and unlikely to be caught out by unexpected things within the business. External factors are obviously unknown.
The year reported faced big challenges, so to come out still profitable, isn’t bad.
On closer inspection, profit, balance sheet, and cashflow are OK, but nothing special.
Outlook sounds strong, but is only forecasting a tiny increase in profit for FY 3/2024, and the numbers are so large, with a really small PBT margin of only about 3%, that it wouldn’t take much to move that number a lot. There could be upside, or downside, who knows, as there are so many moving parts right now.
This share looks priced about right to me. Given macro uncertainty, personally I wouldn’t be interested in buying any at this stage.
But if you think Halfords can out-perform, and deliver better than expected numbers in future, then it could appeal.
Not a growth share, long-term, but nice divis are the main reason to hold. Could it re-rate once the economy improves? Each 1% on the margin would be an extra £16m profit.
Audioboom (LON:BOOM)
Down 26% to 210p (£34m) - Trading Update - Paul - RED
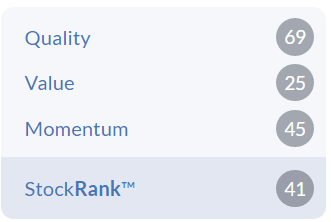
This is an interesting company. It produces & distributes podcasts, mainly in the USA I believe. Shares have boomed & busted twice now, as you can see from the long-term chart below. I recall reporting very negatively on it for a few years, when the fundamentals were terrible.
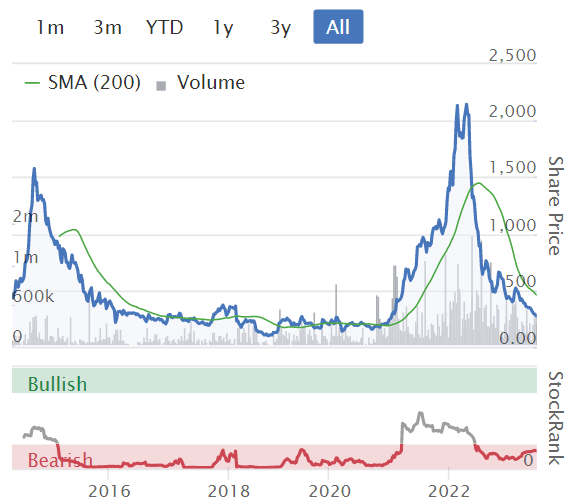
However, more recently new management did manage a decent turnaround, with very impressive revenue growth, and the market got excited about it being a tech company in the latest pandemic tech boom, causing the shares to 10-bag up to a peak of c.2000p. It’s not really a tech company though, it’s more an advertising company, using podcasts to generate ad revenues.
Ad revenues are now under pressure, hence the share price falling all the way back down again.
Checking my notes from earlier this year -
23/1/2023 - concealed profit warning in an upbeat-sounding update. I thought it was maybe fairly priced at 405p based on the facts/figures/forecasts at the time, so AMBER.
24/3/2023 - 435p - OK figures reported, but management nicked all the profits in share options charges. This greed tipped me into a RED view, calling it uninvestable.
Latest news - the share price has halved to 210p since the above comments. This market is not taking any prisoners!
Key points today -
Advertising markets have remained challenging for longer than expected.
Revenue & adj EBITDA for FY 12/2023 “lower than previously anticipated”.
Claims good KPIs, and growth, but excludes a (presumably large) podcast that it lost!
New records set for downloads & ad impressions - So what? If profit is lower than expected?! Must mean ad rates are lower?
Liquidity sounds OK, and apparently no cash burn (a bugbear in the past, when it was much smaller) -
Group cash at 31 May 2023 of US$5.2 million (31 March 2023: US$5.1 million) with a further US$1.8 million available via an undrawn overdraft. The Company has collected in excess of US$30m to date in 2023
Paul’s opinion - we need to know what the revised forecasts are. Unfortunately, Finncap issues a brief update today, saying it is putting its forecasts under review (ie. withdrawing them). So we’re now completely in the dark.
Therefore I don’t have any choice than to reiterate my view as RED. The main problems are -
- We now don’t know how it’s trading.
- Also it’s not a very good business, even in the good times, only making a very low gross margin - podcasting is competitive, and the most popular podcast creators shop around for the best deal from the various platforms. Not an issue that has as yet cropped up for me!
- Finally, management greed with share options that seem completely out of kilter with profitability, finishes off the bull case for me. Although hote one Director has been a repeat, smallish buyer in the open market for a while.
The bull case might include -
- £34m mkt cap is cheap now relative to the previous spikes, so traders might get involved and take it higher once they see a favourable chart pattern in the future perhaps?
- Takeover potential?
- Shares could recover once ad markets rebound.
- Solvency doesn’t appear to be an issue, but that depends on the numbers, which we can’t see at the moment, due to lack of broker forecasts.
Gear4music (HOLDINGS) (LON:G4M)
98p (£20m) - Final Results - Paul - AMBER
Gear4music (Holdings) plc, ("Gear4music" or "the Group") (LSE: G4M), the largest UK based online retailer of musical instruments and music equipment, today announces its financial results for the year ended 31 March 2023.
Graham last covered G4M here on 6 April 2023. I remember it well, as I was enjoying the sun on holiday in Gozo, and I decided to buy a few at 79p, but have since sold them, to bank a modest profit, and recycle the money into something else - just in case anyone wanted to know if I still hold this. Also, we always disclose our personal positions, since that might introduce unconscious bias. So we're not just announcing our trades for the sake of it, which is pointless (and can be irritating to readers - unless you're Warren Buffett, nobody cares whether you've bought or sold!).
Although 6 April was a profit warning, what did impress me was a substantial reduction in net debt, from worrisome, to probably OK. For me, that offsets the downside of profitability which fell from the pandemic boom peak, to only expecting around breakeven for FY 3/2023.
Actual FY 3/2023 Results - key numbers -
Revenue £152m - exactly as guided.
EBITDA is meaningless, but it’s £7.4m, within the £7.3m to £7.7m range guided.
Net debt reduced from £24.2m in Mar 2022, to £14.5m at Mar 2023 - as guided, and this is the most important and positive point I think, in greatly reducing risk to investors of dilution or worse.
HSBC has renewed £30m facility for another 3 years. Great, but memo to management - please don’t use it! It’s risky in a downturn.
Outlook - this seems to be suggesting that H1 won’t be very good -
Market conditions have continued to be challenging since our last update in April, and we are taking the appropriate and necessary actions to ensure our business is correctly configured, resourced and positioned strategically for long term success. To ensure the Group can return to profitability during FY24 H2, we will focus on product margins, efficiency and overhead cost reduction ahead of revenue growth, whilst we continue to develop new growth initiatives for the longer term."
Balance sheet -
Looks adequate, but not strong, because bank debt is needed to part-fund the large inventories. NAV is £37.2m, but includes £22m intangible assets, which I always write off, giving NTAV of £15.2m.
Whilst net bank debt is £14.5m, this includes a gross bank loan of £19.0m (variable rate, linked to SONIA), which still feels too much to me, for a company trading at breakeven. Although the bank is obviously happy, as it’s extended it for 3 more years, and has seen it reduce substantially from £28m a year earlier - proving that G4M can indeed reduce inventories (still quite high at £34.4m, but down from £45.5m a year earlier) to generate cash. This might have hurt margins a little too, discounting to sell slow moving lines?
It’s got freehold property remember, so that is a strong positive of £7.7m book value (£550k downward revaluation, see note 8).
Cashflow statement -
Cash generation is high, due to big reduction in inventories, reversing last year’s increase, so this is excellent to see.
Very heavy capitalised development spend on IT, of £5.3m. Amortisation charge was £3.0m, so if we remove these items, it means the company is loss-making.
Cash generation was used to repay £9m of bank borrowings.
It doesn’t pay divis.
Overall then, not a cash generative business really, at this stage. Once it’s bigger, that would be the hope.
Paul’s opinion - it’s got through a really tough year, and looks a lot more secure now, with bank debt substantially reduced. I’d say this looks a fairly low quality business, with no pricing power at all really, as we’ve discovered with a lot of eCommerce companies, once the market euphoria from rapid growth has subsided.
What does the future hold? I think G4M looks set to slug it out with competitors, growing market share, and seeing also-rans fall by the wayside. People can just buy items from Amazon, etc, but musicians tell me that they prefer to buy from G4M because of fast delivery, and no-quibble customer service if anything goes wrong. Whereas buying from Thomann (the main European competitor) can result in 2-week, or uncertain delays, a benefit to G4M from Brexit!
Bottom line is price. Is £20m a fair valuation? I think it’s cheap, so I may well crop up as a small shareholder again at some point in future, on a buy the dips basis, if funds are available. There again, there are so many companies that look attractive buys at current valuations - how to choose?
Lower freight costs, stronger sterling, and supply chains normalising should all be helpful. Whereas staff wages rising is probably the main headwind.
More for value investors, than quality investors, I’d say.
Management are good I think, tenacious & committed, with Andrew Wass holding 23% still, and sitting on a big cash pile (c.£24m!) from well-timed previous sales! Well good for him, it shows he’s shrewd, and he didn't deceive anyone, he just tells it like it is I've found, on my occasional calls/meetings with management.
This is a really lucky share for me. I caught both the big bull runs, with large positions, happily sold near the top - more luck than judgement. So I will be eternally grateful to management here.
Will G4M shares make it a hat-trick, or is it destined to remain Bactrian? Only time will tell.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

91 comments
Just FYI, the "mystery share" in this weekend's podcast is: Volex (LON:VLX)
Paul, do you have a list of the past "mystery shares"?
Paul, do you have a list of the past "mystery shares"?
Unfortunately not. I should have kept a list, then we could have measured the performance over time (they're not short term trades remember)
Hi Paul - did you watch the investor meet for Volex (LON:VLX) ? If so what are your thoughts? Personally it has made me more bullish on the company. Management came off fantastically and the acquisition seems another brilliant piece of business which could transform the company to new heights
Hi joshwood976,
Yes I did follow the Volex (LON:VLX) webinar today, whilst typing up my section on Halfords - an impressive piece of multi-tasking, even if I say so myself ;-)
Nat Rothschild sounded super-bullish, far more so than in previous webinars, which are sometimes quite flat. I noted down that he was using too many superlatives, everything seemed to be "incredibly", "exciting", etc. It was a bit too much I thought. But I'd rather have that, than them sounding cautious!
Overall though, it sounds like the business is doing great, and the acquisition looks very shrewd, and the culmination of a 3-year process to get to know the (retiring) owners. Turkey sounds a great place to be building up facilities to supply European customers who now don't want to be dependent on extended & wobbly supply chains from the Far East.
Best line was his answer to a question on whether the shares are undervalued,
"I've just invested £15m, because I think it's cheap. Enough said!"
Actually, I think I've talked myself into selling some BOTB, and buying some VLX with the money.
Regards, Paul.
Paul
I do hope they do not have any more earthquakes as I do not know where the latest acquisition is located.
Company is my largest holding.
Robert Peston thinks rates will average 5.5% for 3 years. Using the patented Peston logic hes extrapolated how things are today 3 years into the future, with no change in behaviour.
I asked my cat what she thought. Looked at my funny then licked her arse. My cat still has more sense than Peston.
rates are now only returning to more normal levels, after 15 years of almost Zero rates!
i get the feeling that becuase BoE waited far too long to start increasing them, they may stay higher and for longer than people think
Angling Direct (LON:ANG) announced a trading update and board changes in an RNS yesterday. The CEO is becoming the Non-executive Chairman and the CFO is becoming the new CEO. Interestingly the spiel about the new CFO (Sam Copeman) includes the following:
As announced on 16 May 2023, Sam is an experienced CFO and most recently led the trade sale of Esportif, the global sports consultancy with a presence in the UK, France, South Africa, Japan, Australia and New Zealand, to Wasserman, the global sports, music, and entertainment agency. Prior to this, Sam held senior finance roles across a variety of industries within private equity and privately owned businesses and has a track record of creating shareholder value through the development and execution of ambitious strategic plans, delivering growth and leading successful shareholder exits.
To my mind, based on the statement, it looks as if they are looking to sell the business otherwise why highlight this background in the statement.
Trading is in-line with the board's expectations, but no numbers are given.
Have a good weekend all,
Ben
Hi Ben. I almost had a punt here for a trade when it was heading towards cash level.
Forecasts in May were for 0.9m and 1.2m for 2024/25 so its not really forecast to go anywhere fast. (2022 was 4m)
Free cash flow was negative every year from 2015 up to the pandemic. 0.9m + 0.4m forecast. Id have thought it would be better to sell the business and use the proceeds +£15m net cash to buy something more exciting. Theres surely some good opportunities out there now if you're a cash buyer
What do you think?
SRT Marine Systems (LON:SRT) placing looks a reasonable price to dip a toe in. I personally wouldnt pay much more than 50p.
Forward PER of 13? seems OK risk/reward now, tho free cash flow still negative. Looks like the unsigned order was just used to drum up interest for the placing, its a small placing but quite a discount at almost 14%. Unsigned contract RNS and no share movement quite often = placing in the works.
CEO buying £50k so better than nothing, but thats about all. New shares hit the market next Friday so may dip below 50p sometime next week, tho its a small placing so maybe not.
Ive taken a half position just below 51p, at this price all the froth has been blown off and its back at the 50d moving av. Theres probably enough sizzle to attract new buyers looking at the story/growth forecasts and things look lined up well. Can they walk the walk tho?
"Can they walk the walk tho?"
It's to be hoped SRT Marine Systems (LON:SRT) can walk on water...
Hi
As it seems like a bit of a slower news day and lower levels of contributors comments, then prompted by a couple of posts mentioning NVIDIA (NSQ:NVDA) I thought I would make this post.
If you are not interested in US, tech., AI, cloud, MML's, trends and so on, then definitely skip this post.
If however, these things do interest you, then these two recent vids might be worth your time.
First, this interview yesterday covering Amazon.com (NSQ:AMZN) AWS, cloud, AI caplilities and various MML's is a good overview of what is occuring across this space and its implications for organisations and AWS more specifically (thus Amazon.com (NSQ:AMZN) as an investment).
Second, this similar interview with NVIDIA (NSQ:NVDA) vice president of enterprise computing Manuvir Das. This also covers topics touched on in the AWS interview but dips deeper into the AI stack, compute power and energy usage, heterogeneity versus homogeneity of AL/MML solutions, and much more.
Both offer an articulate overview of what might be useful to investors who are investing in this space, or assessing how AI/MML technologies might be expanding out into all sectors of industry. Ranging from say LVMH Moet Hennessy Louis Vuitton SE (EPA:MC) partnering with EPIC Games to enhance customer experiences in retailing, to Adobe (NSQ:ADBE) making big strides in visualisations and all things media.
In my opinion as an investor I must develop a reasonable comprehension of these movements if I am to keep current with how organisations are evolving their operations.
Disclosure: I hold Amazon.com (NSQ:AMZN) , NVIDIA (NSQ:NVDA) , LVMH Moet Hennessy Louis Vuitton SE (EPA:MC) and several AI/MML/Cloud themed holdings.
Regards
Howard
FWIW, I have a mate that used to work at a US hedge fund. He worked in IT, not as a fund manager, but he seems pretty cluey, more than me at any rate. He reckons that the Fed bailing out regional banks introduced a massive spurt of liquidity into the market. He said that was likely responsible for the S&P being up 19% YTD, and not due to AI. He's also expecting a recession and the S&P to fall this year.
Anyone interested in liquidity should listen to this, it's a real eye opener. Not something much discussed. I'd highly recommend it.
Michael Howell: "QE Is Coming Back, Big Time" https://open.spotify.com/episo...
He also thinks the BoE have just made one of the biggest policy errors of recent times.
https://www.youtube.com/watch?...
Youtube video may be better as there are slides shown.
Hi WoSS
Useful vid thanks.
Regards
Howard
Hi Mark
Thanks for the comments.
Yes I expect US stocks to fall. In fact reducing my US position sizes as I type. I will re-buy in near future I expect so looking for cost dollar averaging over the med/long term with these AI/Tech holdings.
Regards
Howard
Also the fact the the US Treasury ran down the TGA (Treasury General Account) also meant more liquidity in the system. The question now is since the debt ceiling has been raised they will need to replenish the TGA which should drain liquidity from the system.
My timing on Hotel Chocolat (LON:HOTC) was lucky yesterday :)
well done.
can see this one getting hammered further, as its an expensive product, that can easily be cut from people's discretionary spending.
The shares are very illiquid. I tried to short with IG at 350-400p but they obviously couldn't borrow the stock. That means that the share price can be disconnected from its value because holders will prop it up. So yes it could pop up, but that would be irrational.
I wish you well but I will be buying all the way down to 70p if that happens :)
Why? Really interested which part you think creates value at this level.
See my comment below. Trading on a nice price to sales ratio for a long term growth stock in my view.
See my comment below. Trading on a nice price to sales ratio for a long term growth stock in my view.
Why do you think Hotel Chocolat (LON:HOTC) is a long-term growth stock? Surely that story has fallen apart, with the disastrous overseas, failed expansion? Sure it's doubled revenues in the last 6 years, but profitability has collapsed to nothing for FY 6/2023 (post pandemic, note), and forecasts for FY 6/2024 have just been heavily slashed, so the recovery story is looking threadbare at the moment too.
Price to sales can be a dangerous measure, as revenues are vanity, especially when you're not making any profit, as is HOTC's current position.
So I would say this is not a long-term growth story, it's more a hope for a turnaround story.
It's your money, so your choice. But I hope you don't mind me questioning your averaging down strategy on a share where the newsflow keeps getting worse? I think it got off very lightly with a -17% drop on the latest profit warning, given that forecasts were drastically cut for the current year FY 6/2024.
There are much better bargains in the market right now than this, which isn't a bargain at all in my view. But your choice, sounds like you may be emotionally/irrationally attached to it, if you don't mind me saying! (been there, done that!)
Regards, Paul.
Morning Paul
100% with you on this one.
Will run out of money in Q2 2024 and even at 60-75p seems way overvalued.
Thanks yiannos1!
I'm bearish on HOTC's performance, and its high valuation, like you.
However, I've just checked the last interim accounts again, and I see very little risk of it going bust. There's plenty of cash, plus £20m in freehold property. It's a sound balance sheet. So trading would have to go catastrophically bad before solvency would be an issue.
Q2 of 2024 is very specific, why do you say it "will" run out of money then? Any why "will", rather than "might"? How can you be so sure?
Thanks, Paul.
They are burning about £4m-£5m (£19m cash now) per quarter and with , definitely , worsening conditions , they will have no money left by Q2 2024.
I haven’t said anything about insolvency (yet) ; they can still use their credit facilities.
There is no turnaround story here.
Hi yiannos1, thanks for your reply. I don't think HOTC is actually "burning" cash - i.e. operational cash losses on an ongoing basis.
Looking at its most recent interim results cashflow statement, It raised £40m equity in 2021, to spend on expansion - big capex for new sites, and big loans to its failed JV in Japan.
It's already stopped any more cash burn from Japan, that's been restructured. Also, new store openings can easily be switched off if necessary, to conserve cash.
Even operating at just breakeven, the heavy depreciation charge can be added back, thus potentially making it cash generative, if expansion capex is stopped.
So overall, mgt can very easily conserve cash if they want/need to.
I think it's very important to distinguish between operational cash burn (e.g. jam tomorrow, zero turnover type companies), and discretionary capex such as HOTC has done in the past (not very successfully!). Capex can be switched off easily, without harming the prospects of the business. So it's not really "cash burn" at all. It's investment. If the investments turn bad, then it's cash burn though!
I just spotted a weird item in HOTC's H1 cashflow statement - a £6.4m cash outflow in the investing activities section, labelled "Financial Guarantee Contracts". Any ideas what that might be? It seems large/unusual. Ah I've just found the answer in note 3. This was a cost related to the failed Japanese JV. Ouch!
Interesting discussion anyway, always good to bounce views around, and I think we agree that HOTC is a highly unattractive share, even after big falls. Still overpriced.
Regards, Paul.
Morning Paul ,
You are looking at past performance and I am always looking at the 3 year future earnings ; this has been our main difference in almost all of our heated discussions (and my calculations clearly indicate a cash burn of at least £4m per quarter).
They will have to use their credit facilities before the end of 2024 and will 100% at some point in the future be worthless.
We do agree though that it is one for the foolish ones.
Have a nice day.
Short option! Spread too wide though...
Hello. Would you consider covering Babcock International (LON:BAB) ? It's an "interesting" company in interesting times. A mixture of defence contractor and service provider, juggling cost overruns on Frigates with a return to dividend paying yesterday, hence the 15+% jump. It's a key, but overlooked, part of the UK infrastructure scene and your expert eye on its complex accounts would be revealing please.
Instead of raising interest rates mortgagees should be forced to make increased mortgage capital repayments. That would reduce disposable income and help to curb inflation. Mortgagees can complain about short term pain but will be better off in the long term as they will have reduced their debt and hence future mortgage interest payments. Win/win for everyone.....
A lot of people would not be able to afford it.
Agreed but they can't afford the higher interest payments either. At least this way they would get their money back so it's fairer - they would lose it completely with higher interest payments. It's a fairer approach to an inevitable painful experience. Also it would bypass the issue of fixed rates that delay the effect
Next will be the suggestion of increased taxes instead of interest rate rises. Same effect. Sucks money out.... Win/win?
My feeling is that interest rates below 4% have little effect on inflation. Between 4% and 5% put a brake on inflation and over 5% causes a recession and kills inflation. I think the BoE should have moved to 4% quickly last year in increments of 0.75%. Then we would be on the braking / soft landing path, but now we are in the crash landing / recession path.
Surely Bailey should be sacked? He also messed up at the FCA in his previous job.
It doesn’t work like that. The bond market guides them to any rise or fall of interest rates. And the 2 Year , 5 Year , 10 Year and 30 Year market clearly indicates there is a recession coming , whether you like it or not and whether Bailey is totally useless ( I think he is not the best economist for the BOE ).
However, this recession will be with us and on a magnitude not seen for many years , after the US 2024 elections.
After all Kier , Angela and Rachel are going to govern this country soon.
I can’t wait!
is not part of the problem that inflation has been mainly supply driven (COVID lockdowns, UKraine etc), not demand driven?
So raising rates may not do too much, other than push us into recession.
The wages argument from BoE i find is bull, as that is lagging, people only start asking for increases when prices have already gone up, just to try and keep up
Morning all, quite the hoo ha over a 50bp rise in interest rates.
I had a quick look at moneysupermarkets this morning and 4.75% mortgage deals still seem to be available. Looking at my bond positions in corporate, govt and IL they were little moved but small positive on the news. I think this is important... actually bonds react well to strong policy moves. This underpins long term funding in credit. It seems to me we might have a few months to wait until October when maybe we get some much better inflation data. So maybe that's why a surprise additional 25bp move was taken.
The UK Stockmarket rating is probably being held back by higher inflation and weak sterling. Sterling has started to strengthen ... this will reduce $ earnings...but maybe the PE rises...we see....stronger £ will help out on inflation too.
Ive just listened to Fwd Guidance interview with Mike Howell.... some interesting charts re liquidity rising... which has driven much stronger S&P 500 ... it's a worth a listen, he's been positive this year and not many have.
I think the inflation story is getting pretty long in the tooth....but it isn't going away... tbh I think the UK will fall into the pack... and re this weeks rise...it seems like a shrug to me, positive for savers and v little impact on mortgage lending as far as I can see. So net net... we soldier on....
Does anyone have a strong view re Bluefield Solar Income Fund (LON:BSIF)? ...the shares have been week and NAV fell a little but the divi was up. It now looks to be trading at a decent discount to NAV which I think is quite unusual ...so am thinking a reasonable source of income. Any views out there welcome.
Interesting about liquidity in the US markets as Michael Green seems to be saying the opposite, Ed Croft posted this yesterday about NVIDIA (NSQ:NVDA) - https://theunhedgedcapitalist....
"Passive investing is making markets increasingly inelastic because coming in this morning Vanguard had to buy NVIDIA, alongside the shorts, alongside the dealers who are hedging these short call positions that they’ve entered into. Those who decided to overwrite, for example, are now scrambling to reestablish their position. So all of these things are happening in an environment of extreme inelasticity for individual stocks. Individual stocks have become increasingly inelastic which is an economic term saying how much does price move for a change in supply and demand. And it turns out that on very small moves in supply and demand we’re seeing unconscionable moves in pricing."
Yep ...so individual name liquidity is falling due to the passive influence in markets but overall financial liquidity is improving as bond volatility falls ( Move Index 200 to 100) which frees up collateral ...that finds its way back into financial markets ... hence strength this year not weakness - as widely expected. My view but it's just a guess is that this collateral demand for long bonds has contributed to yield curve inversion.... and next move might be to start to normalise. We see.
It is not just NVIDIA (NSQ:NVDA) though, it applies to many US large caps and some technology stocks. Mention AI and prices shoot up even more.
Some large caps are up 2-3x this year, I don't know how long this will last, I have been taking some profits.
The UK market is almost the opposite.
I (well Mum in her pension) holds NextEnergy Solar Fund (LON:NESF) and Foresight Solar Fund (LON:FSFL) , I had previously Bluefield Solar Income Fund (LON:BSIF) but preferred these two a while back when I was doing my research so sold the Bluefield Solar Income Fund (LON:BSIF) .
Looking at the email I got yesterday from Shell saying my home energy is changing, the gas price has dropped massively and the electric price has only a minor drop, so whilst the prices are dropping I think that they are going to do ok longer term as I am looking at a income play.
I guess there is a bit about longer term energy demand, does anyone actually do anything to reduce their use in reality? Is the cost of living of more hits going to affect people and make them turn down their heating, turn off the lights when not in the room? When does the empty offices not being heated/cooled/used kick in? Total in today on my floor = me.
Sorry not very analytical, will need to see if I kept my notes from the time or whether that was an old note pad that has been recycled in clearing up the spare room.
Tommy
Here is the energy changes now I have time to find it
Your electricity rates are changing from 31.924p to 29.287p per kWh. So a reduction of 8.3%.
Your gas rates are changing from 10.234p per kWh to 7.430p per kWh. So a reduction of 27.4%.
So hence whilst this is only my sample of me, this kind of says that electricity prices are holding up, I cannot remember the strike price that was negotiated for Hinckley C but feel it was a lot higher than this and obviously a while before it comes online, so meanwhile the sun is out, let solar run.
Audioboom (LON:BOOM) I guess I must be old and set in my ways. I just look at the Stockopedia Financial Summary and see that it doesn't pay a divvie and make consistent losses despite being public since 2003. Average share count has compounded at 14% aver the last 5 years. I think some folk have been touting this share, which has me shaking my head. It's got a momentum score of 1, which strikes me as a massive red flag.
Hello Mark,
I agree with you, looks awful.
Very interesting on £HOTC. Thanks for the analyis Paul. Shareholder here and I will be topping up today on the weakness, although obviously wish the execution was better.
I think the product is an interesting one, their chocolates can sometimes seem a bit weird, and can be like marmite, but do tend to build brand loyalty in customers. The overall brand is very attractive and I think the customer service and overall proposition is decent. It's a company that over the long term has continually tried to grow and build its manufacturing capacity.
I like their ethical angle too and focus on better quality chocolate (i.e. more cacao less sugar) which I think is something that helps drive customer loyalty.
I know the chocolate industry, and hold stakes in various small, truly premium chocolate companies. As a business Hotel Chocolat (LON:HOTC) HOTC has little value at 120p. The only value is if Thirlwell takes it private but who would fund it given its track record? Pros: yes it has a brand, and £200m of sales is impressive but Cons: it makes no money on those sales; its products are undifferentiated; its price is mid+ and chocolate gets cut fast in a recession; it's in the wrong markets (japan) instead of China and the US. The industry knows that you cannot make serious money from chocolate unless you're in the US. Small family French brands like Pralus excepted. Their production strategy is wrong (too many SKUs); the product itself is not value for money; they cannot generate gross margin; they overstock; they have trouble monetising their (attractive) digital base; they have a poor execution track record. Now, please tell me exactly why you are positive as I'm keen to learn?
I think the brand is good and getting better. They have good customer service (see trustpilot reviews). Over time they have expanded revenue, even if it's not profitable yet. I see the whole package around the brand being unique in the space (the ethics and the hotel mainly - but also the way they try to create this kind of holistic customer experience, includfing the VIP club). The brand is ultimately key, and I think they're managing it well.
They have invested a lot in capacity and manufacturing space - giving them runway to expand into.
I am also personally a fan of their product, and find myself turning to it fairly often as a gift rather than flowers for people through the online store.
The velvetiser / hot chocolate thing is interesting. I am a little skeptical that this will generate a good return on investment for a while, but the product itself seems to have good reviews and looks great. I am generally bullish on (dark) drinking chocolate (and dark chocolate in general) becoming more of a thing given a bunch of recent scientific research showing the health benefits of cocoa. I suspect the 85% and 100% offerings will provide their best long term bet. I am happy that they have innovated signficiantly here with the hot choc - both via the velvetiser and the sachets - and doubled down on that with manufacturing capacity and marketing. It reflects the actions of a company that is serious about growth. Time will tell whether their bets pay off.
I am pleased that they seem to be discontinuing unsuccessful products such as their crap coffee machine.
You make a good point about the US and China. I imagine they are going through Japan because they have existing relationships and capacity to do this. Sometimes a business is best placed to play the cards it has infront of it.
Interesting insight on their SKUs being too numerous, how do you know this? If not too differentiated then this is something that can be rationalised. At least having more SKUs gives them flexibility to experiment with different product lines more readily - possibly a good thing for pre-profit phase.
I agree with Mulberry. Hotel Chocolat (LON:HOTC) chocolate is really nothing special, especially when you consider their prices! Yes, their products are nicely wrapped, but once it's in your mouth, this doesn't count for anything.
At the more prestigious end of the mainstream chocolate brands I prefer Lindt and Green & Black's to Hotel Chocolat.
If I was going to invest in a chocolate brand, my money would go with Chocoladefabriken Lindt & Spruengli AG (SWX:LISP) over Hotel Chocolat (LON:HOTC) every time.
Moser Roth chocolate in Aldi is delicious and way better quality than Hotel Chocolat. It’s cheap too. And while there have a look at their excellent wine offering and again at bargain prices.
To say a little about how the chocolate industry works, "Moser Roth" is a fake "brand" exclusive to Aldi AFAIK. It may be a trademark and not actually a brand. It's probably industrial chocolate from one of the big contract manufacturers who supply the majority of chocolate for the known brands. I doubt if Aldi make their own given the volume, but I might be wrong. The major contract manufacturers are Barry Callebaut AG (SWX:BARN) Cargill and Fuji Oil Holdings Fuji Oil Co (TYO:5017) are the big 3 here.
You’re right Mulberry and I realised that. Also it could well be that Aldi Moser Roth and Lidl JP Gross are the same supplier as the taste is so similar. Also some Aldi products including some of their biscuit ranges are from the same suppliers as Marks and a Spencer, and are simply much cheaper in Aldi. There’s no attempt by either Marks or Aldi to hide that snd the packaging is the same and the biscuits identical. And, supermarkets rarely make the products they sell, just as they don’t run the lorry fleets that transport their products!
What matters with chocolate is the taste and the now very poor figures from Hotel Chocolat suggest that a lot of people who’ve bought their over priced chocolate didn’t like it! I don’t care who makes it, as long as it’s good quality and good value. And with Aldi and Lidl it’s often both.
e.g try Lidl Batts salad cream at 79p and taste it blind against the major brand at £3+. I much prefer Batts. Ditto their BATTS tomato ketchup also at 79p which we prefer to Heinz at over £4. A lot of investors, and commentators still dismiss Aldi and Lidl as discounters selling poor quality. The reality is the quality is often excellent, including their streamlined wine ranges. Aldi, helpfully give the Decanter mark out of100 where a Decanter have tested them. Plenty at 90 and sometimes more, and exceptional value. Until covid I regularly bought our wine at the vineyards in France, and wine is a hobby,so though taste is a personal thing, I know Aldi and the special parcel Lidl ranges are often high quality. The everyday Lidl wines are not as good. Those are better in Aldi.
e.g we blind tasted their a£5.99 Freemans Bay Specially Selected Sauvignon Blanc against the very expensive Flagship Cloudy Bay at £18 when the latter was on a 25% off offer. We preferred the Freemans Bay.
5.1x sales vs 0.9x sales for £LISP vs Hotel Chocolat (LON:HOTC) !
Got to admit I do like Lindt. But I would argue these and the other brands are just supermarket chocolates, rather than something that is all about an "experience". This is what Apple did with computers... it's the whole "welcome to my ecosystem" thing. Make the brand holistic. Sell only in your own shops. Make it like a members club.
My chocolate “experience” with hotel chocolat was to throw it away because it was so unpleasant. It’s the only time I’ve found chocolate so horrible and the only time I’ve found chocolate inedible. I realise others might like it, but imo it’s not good quality and it’s way over priced.
And “just supermarket chocolates” ignores some chocolate sold in supermarkets being very high quality , delicious and good value. If you’ve never bought Aldi brand Moser Roth or Lidl J D Gross give them a try and taste them blind against hotel chocolat. And much higher price Lindt is very good too.
Also Godiva chocolate sold on Cunard cruise ships is very good, but it’s very expensive.
Also I would be very interested to hear more about your other chocolate investments if any are public domain shares :)
They are both private companies. One sells to Fortnum and Mason (a number of UK and continental manufacturers do, under white label). The other is in speciality stores with a strong ethical story. Answering your "too many SKUs" question - walk into a Hotel Chocolat (LON:HOTC) store - just look here https://www.hotelchocolat.com/... They're all over the place..no consistency on flavours, what they're actually experts in - by having so many lines, they're missing big flavour trends. I would bet that the usual rule applies, 70-80% of their sales come from a small number of products and they could bin the rest and simplify production, stock and distribution. Hot chocolate is always "the next big thing" in the industry. If you really want to test HOTC, email them and ask them who actually makes the chocolate they use...
to save us emailing HOTC and the suspense in their reply, grateful if you could disclose their chocolate manufacturer for all readers, if you are obliging? I had thought they make their own.
Only Hotel Chocolat (LON:HOTC) knows exactly who makes their chocolate - it would be fun if a number of people from here emailed them to ask. Their reply will tell you everything you need to know. If they refuse, you'll know they're embarrassed. If they state that they make a significant % of their own chocolate (and I mean, from the bean) I'll be very impressed and they'll have got themselves some kudos, and if they confirm that they buy in a lot of their couverture, then you'll know that they are a "re-melter" and add chopped nuts and fruits and re-package industrial chocolate. I am genuinely curious.
Morning all,
Does anyone have any updated broker forecasts as yet for Volex (LON:VLX)?
Regarding MS International (LON:MSI), was stopped out yesterday morning, only to typically see the sp rebound! I'm now in that FOMO/don't want to jump straight back in mindset. What to do!
Volex (LON:VLX) Peel Hunt have upgraded their PT to 400p from 300p. I haven't got access to the note though unfortunately
Capital (LON:CAPD
Capital (LSE: CAPD), a leading mining services company, announces that Jamie
Boyton, Chairman of the Company, and Brian Rudd, a founder and Executive
Director of Capital Limited (the "Sellers"), have indicated their intention to
sell up to a combined 5,000,000 common shares in the Company (the "Placing
Shares") (the "Placing") at a placing price of 98.5 pence per Placing Share
(the "Placing Price"). The Placing Shares represent approximately 2.6% of the
Company's issued share capital.
As a holder this makes me a little bit nervous. Jamie Boyton will still have a 10% stake in the company and he is the founder but with so many new contracts, rising forecasts and MSLABS pulling up trees why would you want to sell such a large amount of stock?
Anyone out there got any thoughts or further info on this?
He's held the shares for a long time so entitled to take some money out for personal reasons. Be reassured that the placing price is reasonable so presumably a keen buyer in wings and good to get it done quickly and openly.
Hi Colin
Thanks for the reply. I can agree with that but my problem is that 2 directors are selling in this case, not just one....
It could simply be that an institution wants to buy and has said they'll only do so if a large amount of stock is available. We won't know unless they tell us. Something similar happened with Manolete Partners (LON:MANO) a while ago.
Fair enough, thanks Richard, I hadn't considered that.
Of course I would feel happier if they were buying 5 million instead - it doesn't specify how much each of them is selling but they still have a fair amount left. Pain with CAPD is that every contract win results in upfront Capex - either debt or placing but it looks a well run company
Gear4music (HOLDINGS) (LON:G4M) Any chance of a very brief comment on this please Paul (unless I've missed it this week)?
Sure, I'll try to fit in Gear4music (HOLDINGS) (LON:G4M) today too.
Looking forward to Paul's macro podcast on the latest interest rate rise! The media seems to think it's a good thing
SRT Marine Systems (LON:SRT) fund raise - will be very interesting to see how well it is received / subscribed. Bigger discount than I'd like to have seen.
SRT Marine are raising money this morning at 50p. For a company offering the opportunity they purport to offer it seems a large discount (13.79% according to Primary Bid).
You just gotta laff:
"Governor Andrew Bailey has said the central bank has "very big lessons to learn" about how to operate during periods of big shocks".
A very costly (to others, he's on £600k+ pa w /golden pension, AIUI) work experience exercise... ;-<
'It hurts too much to laugh...and I'm too old to cry'
Pretty simple really; don't massively increase the money supply at a time when productivity is falling off a cliff.
Broadly speaking, a nation's living standards should be proportional to it's productivity - as a nation, we should have collectively accepted hard times during covid, instead of (some) looking to the government and central bank to artificially support.
If good living standards and wealth could be achieved through printing money, Zimbabwe would be a utopia.
Support should have been limited and targeted, not giving handouts (furlough etc) to those in a position to support themselves.
An alternative view is that the furlough scheme meant that mass redundancies were avoided. If it hadn't been introduced potentially millions would have been made redundant, and they in turn would claim unemployment benefit so the government (tax payer) would be pick up the tab either way.
Most of all, Kouremenous, Lock Down would have been better avoided, when the figure of the deaths caused by hospitals shipping out Covid-infected pensioners to care homes is taken away from the total then things would look a lot better. Personally I have had 4 immunisations against Covid, caught Covid between jabs 3 and 4, and at 78 am no Spring Chicken but a survivor. No Lock Down, no redundancies see?
But there wasn't a vaccine available during the lockdown - or it wouldn't have been needed. Certainly things could have been handled better - a quicker reaction by govt would probably have meant a shorter, possibly lighter, lockdown was needed, and not paying people to eat out and spread covid would certainly have helped!
This is a similar argument that is rolled out for Y2K.
All that effort and money was spent and then there were no problems! What a waste…
Would appreciate your thoughts Paul on Intercede if that is still on your list to catch up on. Thanks
OK, I'll do a brief comments on Intercede now :-) Give me half an hour and it should be up!
Intercede (LON:IGP) - Paul - request for your thoughts seconded.
My own notes:
The company gives diluted eps of 1.2p based on a profit of £1311k which is after R&D staff costs of £3053k. If all of that had been capitalised (this company does not) eps would be 7.3!!! (mind you if that was the practice over the years there would be an amortisation charge but that could be overlooked in the adjusted figure loved by brokers).
finnC goes for adj. eps 3/24 to 3/26 of 1.2, 1.9, 2.7 confirming my general impression of dull year then boom boom. My question on IMC (52m 5s in) confirmed my suspicion that this year will be H2 weighted (year reported on was 50:50) so see the SP going nowhere for the time being and possibly sinking on interim results providing a buying opportunity.
Revolution Beauty (LON:REVB) It will be interesting to watch the duel between the current directors and BooHoo play out. Trading update today for March to May 2023 sounds promising. Sales, gross margin, ebitda and cash all reported up.
Less than 15% of Revolution Beauty shares owned by small private investors.
I would think Boohoo have done their homework to make sure they had the backing they needed before starting down this road..
Maybe the lesson here is to never buy a share where more than 85% of the shares are owned by institutional and large investors.
Paul could you look at Halfords (LON:HFD)? breaking out great statement on wednesday
Hi davidallen77,
Yes Halfords (LON:HFD) looked quite good, and I see the shares responded well over 2 days after results, and I did start looking at it the other night, but was too tired to finish it off. So I'll prioritise a quick section on this today, it's gone on the list!
Regards, Paul.
My morning smallcap tweet: Bonfire of the inanities
Audioboom (LON:BOOM) Revolution Beauty (LON:REVB) Hotel Chocolat (LON:HOTC) SRT Marine Systems (LON:SRT) Guild Esports (LON:GILD) Carclo (LON:CAR) Capital (LON:CAPD) Non-Standard Finance (LON:NSF), Filtronic (LON:FTC)
◄Audioboom (BOOM)► guides FY revenue and adj EBITDA lower than expected. Blames continued weakness in ad mkt. Co expects to return to meaningful growth in Q3. [SP=284.5 Cap=47m]
◄Revolution Beauty (REVB)► Q3 rev up 60%. EBITDA at constant currency £3.5m (£7.4m loss). Tells boohoo where to stick its lipstick, again. [SP=8.25 Cap=26m]
◄Hotel Chocolat (HOTC)► warns FY23 small pretax loss despite rev in line. Cost cuts slower than expected. Also guides FY24 rev and underlying pretax miss "due to ongoing weakness in consumer sentiment and continuing inflationary pressures". [SP=139 Cap=191m]
◄SRT Marine Systems (SRT)► to the surprise on no-one. a £4m placing at 50p, a 14% discount, for working capital and extra jam. [SP=58 Cap=105m]. I hold.
◄Guild Esports (GILD)► one-year partnership deal with Secretlab which will provide the Sky Guild Gaming Centre with its top-of-the-range gaming chairs. What's a gaming chair? It's an office chair with a list of bollox features like 'magnetic memory foam' and 'class 4 hydraulics' and '4D armrests'. That's right, the armrests are hyperspace objects! [SP=0.69 Cap=4m]
◄Carclo (CAR)► amends interest cover and net leverage covenants to June 2025. [SP=13.65 Cap=10m]
◄Capital (CAPD)► execs to sell 2.6% of co at 98.5p (4% discount) via a placing. [SP=102.18 Cap=198m]
◄Non-Standard Finance (NSF)► d4f and delisting. Nothing for shareholders. [SP=0.2 Cap=1m]
In line: FTC
MrContrarian: "Tells boohoo where to stick its lipstick, again" - priceless!
Morning Paul, can you not get Ant and Dec to help with the backlog?