Small Cap Value Report (Fri 23 Sept 2022) - W7L, REVB, ITS, WRKS, Mini Budget, MADE

Good morning, it's just Paul here today, with it being a Friday (usually slow for news, so I can catch up with backlog items of interest here). Today's report is now finished.
Mini Budget
Tax cuts are expected. I'll be following the announcement c.09:30 and am planning on updating this section asap afterwards with the key points. Here it is -
Mini Budget - Kwasi Kwarteng speech to House of Commons today
Here are my notes, hopefully I caught the main points correctly.
Energy costs - reiterated household & business support measures already announced.
Erratic wholesale prices - Govt will give 100% guarantees to emergency bank loans for suppliers.
Overall measures on energy will reduce peak inflation by 5%. Plus cheaper costs for index-linked debt.
Bank of England - is taking action to control inflation, “independence is sacrosanct”.
Growth - is too low. Tax burden too high. Need to break this cycle.
Aiming for 2.5% p.a. trend growth in GDP, via tax cuts & supply side reforms.
Prudent public finances (!) UK national debt is 2nd lowest as % GDP in the G7. Plan to reduce as % of GDP in medium & long term.
Costings will be published today. Energy plan costs are particularly uncertain, will cost £60bn in 6 months from Oct 2022, and then come down. Price of inaction would be far greater.
Infrastructure - too many barriers to enterprise, e.g. planning system, childcare, immigration. Planning is too slow & fragmented on major projects. Need to unpick complex laws. List of priority projects to be published today.
Houses - more new houses needed. Reforms, including release of surplus Govt land.
Unemployment - lowest for c.50 years. Need to get more people off benefits & into work.
Strikes - other countries have minimum service levels, we’ll introduce the same. Pay offers must be put to union members in future.
Pension funds - reforms to boost investment in infrastructure.
Cap on bankers’ bonuses - will be repealed. Hasn’t worked - either repelled high earners to overseas, or raised base salaries vs bonuses.
Financial sector - more regulatory reforms to come in autumn.
Levelling up - new investment zones will be introduced, with big tax incentives - e.g. no business rates, 10 year tax relief on investment, no NIC on first £50k per employee. Mentioned possible locations including Teeside, South West, and Norfolk (??).
Corporation tax - rise from 19% to 25% will be cancelled (Paul: this is highly significant for company earnings, across the board. As expected though, as with most of this announcement). 19% will be lowest in the G20, attracting business to the UK. Bank surcharge will remain at 8%. This will plough £19bn back into the economy, for jobs, investment, and dividends.
Investment allowance of £1m p.a. was set to reduce to £200k. Cancelling that, will remain at £1m permanently.
EIS/VCT/SEIS limits will be raised. Want a nation of entrepreneurs.
Office of tax simplification - abolishing it, to instead embed simplification into Treasury, HMRC, etc. Sunset EU regulations.
IR35 to be simplified, too complex & costly. 2017 & 2021 reforms will be repealed.
Tourism - VAT-free shopping, digital scheme to be introduced.
Booze - planned increase in duties will all be scrapped. More support for small brewers.
Personal tax - social care levy will be scrapped, and no cuts to NHS spending.
National insurance & dividend tax increases also scrapped. Worth £330 per person on average for 28m people.
Stamp Duty - being reduced at the bottom end. Zero up to £250k. Zero to £420k for first time buyers.
Income tax top rate of 45% will be scrapped. It’s too high vs internationally.Top rate will now be 40%, as it was previously for over 20 years, including whole of New Labour Govt (apart from their last month!)
Basic rate income tax will reduce from 20% to 19%, 1 year sooner, in April 2023.
Focus is now on growth, and being globally competitive, not on income redistribution.
My view - this is a very big package of economic stimulus. It's likely to cause a big increase in Govt borrowing, at least in the short term, but if that averts a prolonged recession, then it might be the right thing to do, only time will tell.
Agenda -
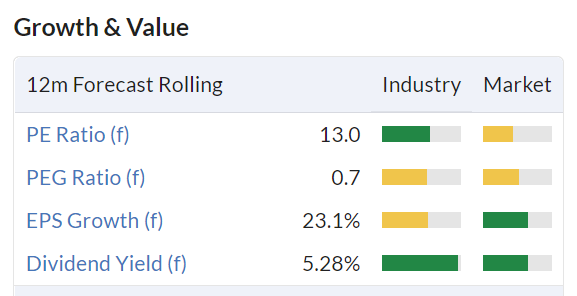
Warpaint London (LON:W7L) - The short version is that I'm very impressed with this makeup company's progress. I wrote up a positive review of it earlier in Sept, after FY 12/2022 profit guidance was raised. This positive impression was reinforced by the interim results/commentary. It looks a very good value/GARP share now, in my opinion. So it's high on my personal watch/future buys list. I'm hoping to speak to management at some point too. More detail below.
Revolution Beauty (LON:REVB) - another update from this company whose shares remain suspended, due to accounting problems that emerged during the audit, causing a failure to meet the 6-month deadline for accounts publication. Today's update says an independent investigation has begun, as problems seem to have deepened - little clarity on what these problems actually are, but it sounds a can of worms. Banks remain supportive, and net debt looks manageable. Timeline is "several months" for this investigation. It doesn't look bust, but we have no idea of how extensive the accounting problems are, so who knows what will happen? More detail below.
In Style group (LON:ITS) 26.5p (£14m mkt cap) [no section below] - today’s RNS is really an operational update, although it’s called a trading update (but doesn’t say anything about trading). It’s trying to sound upbeat, but the reality is that brokers have been reducing forecasts, and a heavy loss is now expected for FY 3/2023. Cash is down to £4.3m, and it’s all about cutting costs and survival. Hence I don’t see any value in the equity as things stand. (no section below).
Works co uk (LON:WRKS) - a big rise of 35% this morning, but my initial quick reaction is to be a bit careful over these strong numbers for FY 4/2022, because they're not likely to be repeated - forecasts have been cut heavily for FY 4/2023 after the profit warning in August. (more detail below)
Made.Com (LON:MADE) - looks almost game over now. It can't do a placing, so is trying all other options (sale, debt, merger, etc). I think it's too far gone, with losses now so bad, that there's no value in the existing equity, so administration and shares to 0p looks likely quite soon. Bad luck to any holders. 4p is better than 0p though, so I think it's still worth dumping any remaining shares. (more detail below)
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section:
Revolution Beauty (LON:REVB)
Shares suspended at 19p (£59m market cap)
It's a makeup special today! Shares in REVB are still suspended, since it was unable to publish FY 2/2022 accounts by the 6-month deadline, once problems emerged with its audit. Today's update says that -
BDO LLP ("BDO"), the Company's auditor, has written to the Board and identified a number of serious concerns that have arisen during the course of its work on the FY22 audit regarding, amongst others, the Group's ability to provide sufficient and accurate audit evidence in respect of a number of key audit areas and the validity of certain commercial arrangements entered into by the Company. BDO has indicated that, at the present time, it is not able to sign an audit report in respect of the FY22 accounts....
Well that's as clear as mud! An independent forensic investigation has begun, at BDO's recommendation, and is expected to take "several months" to conclude.
Is it going bust? Doesn't look like it, at the moment. Net debt is £16.1m, well within a £40m facility, providing "sufficient liquidity". Technically in breach of bank facility (due to late accounts), but banks remain supportive so far.
Current trading - a variety of excuses (macro, Ukraine, consumer sentiment, costs, etc) resulting in a profit warning today for FY 2/2023 - materially below market expectations. It seems strange that competitor W7L is trading well, with those macro factors not impacting it at all. So it's obvious that REVB's problems are home-grown.
My opinion - shareholders have to hope that the problems get resolved, and shares resume trading, but that won't be for several months, if at all. The risk to shareholders is getting wiped out, if someone offers to pay off the bank, by buying it out of administration. I speculate that Mike Ashley & Boohoo, and possibly others might be circling? Note that Boohoo bought a stake in the market shortly before the shares were suspended (which was a known factor, so nobody was caught out by the suspension, it was pre-announced). It'll be interesting to see how this turns out. When accounting problems emerge, it usually seems to end up being a lot worse than originally thought.
Warpaint London (LON:W7L)
126p
Market cap £97m
Warpaint London plc (AIM: W7L), the specialist supplier of colour cosmetics and owner of the W7 and Technic brands is pleased to announce its unaudited interim results for the six months ended 30 June 2022.
Record first half sales and significantly improved gross margin
I’ve been very impressed with the progress of W7L, in particular this year, where it has delivered a series of profit upgrades. Impressive, given the tougher consumer environment.
Here are my notes from the last positive update on 8 Sept 2022, when profit guidance was raised by 8%, and I also flagged the 6% dividend yield, strong balance sheet, and entrepreneurial management with big stakes. Plus a reasonable PER. So W7L is a favourite value/GARP share of mine (no current holding personally).
Here are my notes from the recent interim results -
H1 revenues £25.2m
Revenues are £10.4m UK (up 17%), and £14.8m International (up 55% - key point)
Gross margin increased from 34.5% to 39.0% - very impressive, as shows pricing power improving, despite input cost & freight headwinds. Confident about future margins.
Divis - interim divi is 2.6p (H1 LY 2.5p). Full year forecast yield is good, at 5.5%
Seasonality is an H2 weighting to revenues, profits (and divis)
Growth seems to be helped by new accounts (Boots, CVS mentioned), and strong online.
Further big new retailer accounts commencing Oct ‘22 (H-E-B) and Jan ‘23 (CVS stores).
W7L products are value-orientated brands, ideal for current conditions.
Sees opportunities for further growth.
£480k legal dispute, but mostly provided for last year - what’s this about?
Most product is made in China - a risk?
Balance sheet - looks excellent. NAV £39m, less £8.5m intangibles, so NTAV is fine, at £30.5m. Inventories are high, but commentary explains why, to ensure continuity of supply & to instantly meet large orders - sounds fine to me, and commentary reassures on stock provisioning (so shouldn’t end up like REVB!). Net cash £2.9m.
Cashflow - slightly negative, as cash sucked into increased working capital. That’s fine, as long as it reverses at some point in future.
My opinion - this all looks very good. Something positive is happening here, with W7L’s products obviously going down well with consumers and hence retailers. I like that new accounts are being won, and that international expansion is particularly impressive.
Entrepreneurial management with big stakes (founded the company 20 years ago).
It’s priced like a value share (see below), but is actually a growth company. Providing growth continues, then that looks very attractive to me.
Works co uk (LON:WRKS)
39p (up 35% at 08:27)
Quick View - I saw that Works co uk (LON:WRKS) was up 35% in early trades, so am planning on looking at that one next. Having a very quick look, I think maybe people are getting carried away with the good figures for FY 4/2022. These numbers are not sustainable. In particular, it benefited hugely from business rates relief.
There was a profit warning for FY 4/2023, which I covered here on 8 Aug 2022, and caused the share price to plunge. Look at what has happened to broker forecasts since -
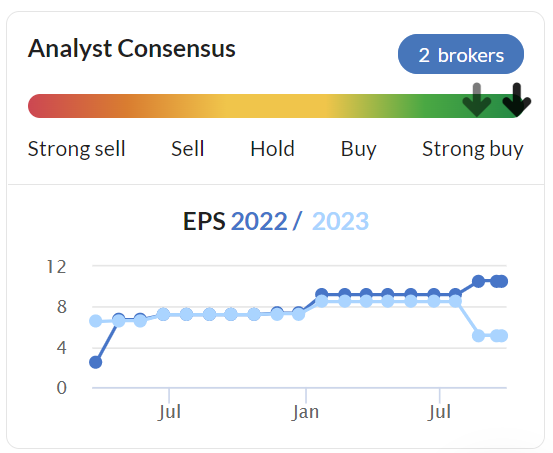
That's clearly demonstrating that the 2022 figures are not going to be repeated, which the company reiterates in today's outlook comments.
For that reason, I would urge caution over this morning's euphoric reaction to these numbers - possibly more of a selling opportunity, than a buying opportunity? Who knows, I can't predict short-term market sentiment, anything can happen.
Balance sheet - is OK actually. NAV £21.6m, less £2.7m intangibles = NTAV of £18.9m. But bear in mind the IFRS 16 lease entries add up to a deficit of £17m, so if we eliminate those entries, NTAV would rise to about £36m, which is fairly secure actually. So I'm not worried about solvency. Although a deficit on the IFRS 16 numbers is clearly indicating that there are some loss-making shops that need to be disposed of, and will be a drag on performance.
With a consumer downturn, and increased costs (e.g. wages, utilities), plus business rates kicking back in, I very much doubt whether WRKS will make significant profits in future.
Bulls might point to its value product offering, which could prove of more enduring appeal in a consumer downturn possibly?
I'll have a closer look later today, but those are just my initial thoughts. As always, we're happy to hear your views, whether you agree or disagree!
EDIT: Not much more add, having had a closer look. Although I think the current trading comments sound reasonably reassuring -
When we updated on Q1 trading on 8 August 2022 we noted that store sales had been resilient and online sales more challenging, although significantly higher than pre-COVID levels. The more positive pattern of trading that had developed by the end of Q1 has continued for the subsequent 7 weeks ended Sunday 18 September 2022, with our refreshed outdoor play range performing well, a very good 'Back to School' season and a gradual improvement in our online performance. This resulted in store LFL sales up 7.9% and online sales down by 10.1% (but 40% higher than pre-COVID levels), resulting in a total LFL sales increase of 5.7% during the seven week period. For the year to date (20 weeks ended 18 September 2022) the store LFL is up 4.0%, online sales down by 21.7%, the overall LFL up by 0.8% and total sales were up by 2.3%.
We are encouraged by the strength of recent trading which reinforces our confidence in the resilience of the business and that the ongoing improvements we are making to our proposition are resonating well with customers. Despite the positive recent trading, we remain cautious with regard to how consumer spending might be affected during the remainder of this financial year, by factors such as higher inflation, and therefore the Board's expectations regarding the FY23 result are unchanged (6).
(6) | For reference, the Company compiled estimate of the market's expectation for the FY23 Adjusted EBITDA result is approximately £9.0m. |
It's not clear if that adj EBITDA is pre, or post IFRS 16 (which makes a big difference). Assuming it's pre-IFRS, then it's a fall from £16.6m actual for FY 4/2022, to £9.0m in the current year to FY 4/2022. That looks to be equivalent to an adj PBT dropping from £9.0m, to just £2.6m this year. Hence I remain of the view that profit for FY 4/2022 looks a one-off, and is not likely to be anywhere near repeated this year. Although as a value retailer, maybe it could surprise on the upside, who knows? I think in this bombed out market, there are probably better, and safer options elsewhere.
Made.Com (LON:MADE)
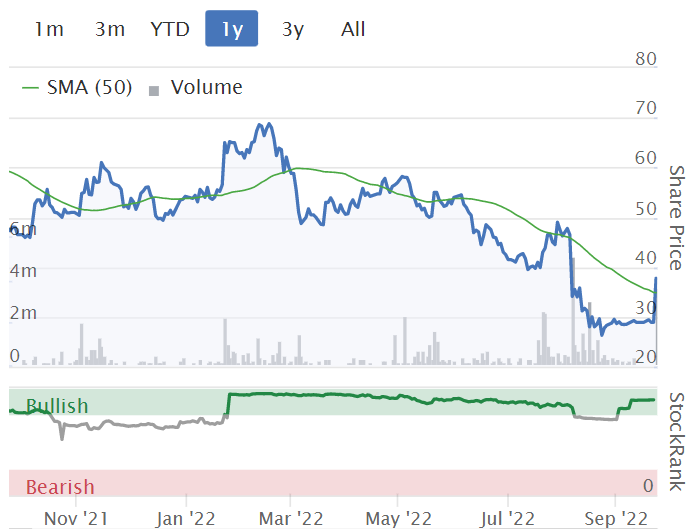
4.4p (down 22% at 12:08)
Market cap £18m
Strategic Review and Formal Sale Process
There’s really not any point in regurgitating all the detail in today’s update.
Trading has deteriorated further, and guidance (which is already for a huge loss) is withdrawn, so it’s even worse than guided previously.
Reasons given for poor performance are -
- Falling consumer demand
- Discounting needed to shift stock, thus lower margins
- Negative operational gearing effect from fixed costs
- Built up inventories to ensure supply, just as demand was falling
- Higher cost of acquisition of new customers
- Supply chain difficulties
- Freight costs astronomical (£8.2m in 2020, to £45.3m in 2021)
- Not benefiting from fall in freight costs now (sounds like they locked in high prices)
- Higher carrier costs in the UK
A lot of those are sector-wide problems, but some self-inflicted injuries too I reckon.
Further cost-cutting is needed.
Key point - an equity fundraising not possible, we're told today.
Seeking a sale or merger, or debt raising.
My opinion - I think it couldn’t be clearer that it’s almost game over for existing equity. If a fundraising isn’t possible, that suggests existing institutions have refused to pump in more cash. Therefore they’re resigned to being wiped out. Private investors can still sell in the market, which is the only logical thing to do now.
The chances of someone launching a takeover bid look low, to nil. Why would anyone take on a hugely loss-making business, with all the liabilities, when it could probably be bought from the administrator quickly & cheaply in a pre-pack? Buying all the inventories for pence in the pound instead.
It hasn’t worked, and we can pick over the history and learn lessons from it some other time, but for now, I would urge readers not to take the risk of having a flutter on the shares because they’re so cheap at 4p. They’re almost certainly worth 0p, so they’re not cheap at all.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

98 comments
looking fwd to the weekly Podcast summary Paul if you are still doing it. Thanks
Of course, my podcasts are every weekend, without fail!
I'm just about to record this week's summary now. So it will be up in about two hours, on the podcast platforms and my own website.
Regards, Paul.
The markets gave their verdict on the largest budget giveaway since 1972. Gilts rose, and the pound and stock market tanked. If 1972 is any indication, the UK is going to have high inflation for longer, interest rates will have to rise higher, and this likely leads to a longer recession.
Worth noting that literally every sector in every country tanked yesterday, there was a global selloff.
In 1974 the S&P had its second-worst start to the year. Currently, it's having its 5th worst start to the year.
Enterprises generally try their best to manage their way around the various hurdles all Govts put in their way, and as a conservative myself (note the small c), the tax system and Govt strategy seemed to be fighting against itself and hurting businesses (particularly small business). Higher minimum wages, higher NI, higher dividend taxes etc, coupled with regulatory, and tax compliance laws few seem to be able to manage, except the very large and well resourced businesses.
On the ground many businesses have to fight their way through a pile of trickle down compliance from large institutional bodies, or big businesses. It is rewarding lawyers, and hampering initiatives.
I can fully understand why many thought the supposed advantages of Brexit were barely apparent. Everything seemed to be like the EU, except with even more paperwork.
So, on a purely theoretical basis I can fully understand why this mini budget has come about. The fact that it didn't come about before was largely because although a Conservative BJ was incontinent financially, and just wanted enough cash to splosh around as a political palliative whenever needed. This and the general political orthodoxy of its bad to be seen to be rewarding the 'rich' just made more sense to build a war chest for BJ, steal the political ground from non Conservatives (by being just like them) and tipping the hat to fiscal discipline.
Its big and bold, but whether it has come too late in the electoral and financial cycle is hard to say (though plenty will).
We're not interested in politics here, this forum is for economics, company earnings, etc.
this is fair Paul, though I found the post stimulating and from an implicit economical sense, relevant to the PI world;
we have a new pair of policymakers at the top, who are now potentially undoing a lot of economic decisions made over the recent past.
it's perhaps hopeful that the changes might deflect a protracted recession, and allow our small caps to grow again.
whilst I similarly to you don't want to get involved in the angles around 'do I like these politics and politicians any more or less then the last set', what they say and do will impact on our investments, so as long as the discussion remains centered on the facts and economic implications, I think there's a grey area we can allow ourselves to dip into occasionally perhaps
It's very hard to seperate the economics from the politics sometimes though given govts set the economic culture and boundaries via fiscal policy. :) Thanks for trying to keep us walking the right path
I know that Begbies Traynor (LON:BEG) has been discussed favorably on the SCVR recently, but I think it's worth pointing out how strong the chart is looking at the moment.
It's having a prolonged consolidation within a tight range just below 150p... very constructive and supported by the macro picture where insolvencies are expected to continue for some time yet.
I fancy it for a move up above 180p, possibly to re-test the historical high of 200p. It really is one of very few companies that interests me in the current environment. For full transparency I already hold shares in my ISA, but I'll be looking to add on a definitive break above 150p, which I feel is coming (its made a couple of false breaks already, but has consolidated and not fallen away).
Held up well again today while everything else was selling off heavily - good sign of strength. The only real negative for me is the spread which is large enough to be uncomfortable when buying.
I know we don't do charts a lot on here, and I have hesitated before posting such a worrying pair, but one can't ignore the situation.
The first chart goes back to the very early 1980s and was published today. https://tradingeconomics.com/u...
I can't find the original source for the second chart but the numbers are correct.
UK bond yields are moving up in line with what's happening in the USA - its aggressive interest rate rises are causing chaos in forex markets, and causing bond yields to rise everywhere. So marking the charts up with UK political events seems largely spurious to me.
Nicely flashing contrarian signal...
If I scroll through the SCVR archives, in H2 last year the average views per SCVR report was around 9-12k.
In the past few months, its around 5-7k. Granted, not comparable, as old SCVR reports continue to rack up views over time, so they will get more. But you have to imagine the majority of views are within a day or two (for example, today's report already as almost 5k views 5pm).
Looks like a section of the Retail investor population (those that subscribe to SCVR) have somewhat thrown in the towel!
Re £more, thanks for the update Paul. I would add that although the finances look wretched there is a small ray of sun shine — the register. Now I can’t promise everyone the dilution won’t be brutal but let’s face it - £10m -£15m sorts the situation out …. U get proforma recovered ebitda back at 30-40m and 10x post funding return so yes I think it gets done. And doesn’t fail - plus unlikely the shareholders want to sell it. The only issue is Numis doing it as a placing to top shareholders and we don’t see the offer. Having said that we can afford to wait and see - grumble if we can’t buy the cheap shares but still should have a decent recovery play from the TERP. So yes trading is awful , yes it can go bust and op gearing is brutal in lease financed businesses.
Always remember if u r sat on large losses 80-90%, then this weeks falls we’re not that expensive. All is not lost however and I think some of those on the register incl management will make sure this thing doesn’t fail. I have some very small exposure now but won’t sell because it doesn’t matter anymore but suspect we get another crack at this one but time will tell ….
Good luck all as always
For anybody feeling miserable about seeing another red day, thinking they got their stock picks wrong and tearing up their strategy to start again - on days like this its not you, its the market.
ETF's are a good gauge as they tell you if certain industries are doing well... this image says it all, and there is nothing you can do. Let your stops get hit, or ride it out. Nobody makes money on the long side when the market is behaving like this - This selloff is across the board, nowhere is a safe haven.
Stay calm, limit losses where possible, trust in your process and you'll see improvements when the market picks up.
Seems to be blood on the streets, much of this being driven by America sell off IMO, which I am afraid needs to happen.
I think we will be taking a leg down, with small/mid cap previous lows coming under serious pressure. So heading back into cash via stops being breeched and on the look out for bargins.
America continues to head down post opening, so I feel these falls could head into next week, so no rush to buy as yet, perhaps...difficult to know but keeping calm.
Hope you are all managing...good luck to you all, sorry if you are taking big losses.
I hope this does not spoil your weekends, its only money, and I notice my Mums coffin (a council tenant) was the same size as the Queens. You can't take it with you or buy back time and good memories.
Good Luck!
Paul
Just some random thoughts. The market is not really punishing the UK for the budget as all the markets across Europe are weak, in fact some are worse than ours.
Property stocks are often priced off yields, if gilts are hammered then not only are they less appealing relative but refinancing and new financing also become harder.
In 35yrs this is without doubt the hardest trading/investing conditions I have seen and I would say I have seen quite a lot!
I am convinced that there are some huge opportunities that will emerge but have no idea when the carnage ends. As an aside it is now possible to get close to 5% fixed on cash at some of the private banks, that is an extremely high hurdle rate for risk assets. Risk has been mispriced in my view for many years with all the QE suppressing normal market mechanisms. Strong balance sheets or extremely strong cash flows which both Paul and Graeme often talk about our critical imo.
I'd also just like to say a big thank you to Paul and Graeme for their unstinting and excellent work. It's been very easy to become demotivated in this environment. I am trying to re engage more this afternoon so have Galliford Try Holdings (LON:GFRD) on IMC and a meeting with Sigmaroc (LON:SRC) after-both of which I think are compelling opportunities!
Hi MH1
Would be very interested to hear any thoughts you might pick up if you do get meetings with Sigmaroc (LON:SRC) (I have invested in/out of this over past few years and really like the company), and/or Galliford Try Holdings (LON:GFRD) (also held this in the past).
I have also been watching Marshalls (LON:MSLH) (held it for a short time in the past).
I am not holding any of these at the moment.
Regards
Howard
Totally agree. Risk and the time cost of money have been ignored for a long time. As someone who's only ever been in the markets for "risk on" periods, this is coming as a shock to me! I've just transferred a big chunk of cash into my ISA (bonus month) but it will be staying as cash for the foreseeable, even though I'm straining at the leash to buy more Warpaint London (LON:W7L) .
Govt continue to peddle the myth that the top rate of income tax is 45%. For those of us fortunate to earn between £100k and £125k, the rate is 60% on the earnings between those two figures.
Hi Chris
I just lost what I wrote so will try again.
You have to remember that we live on the headlines only now, never read the detail.
There are several traps within the tax system as stands that punishes those who cross the boundary, whether it is stamp duty, capital gains, income tax, child benefit, pension allowances, below the line most do not know they exist, in "no person's land" you are in serious pain of penal rates as you describe, and above it, well that is for your accountant, wealth manager etcetera to worry about and earn their fees.
This has been a subject of correspondence with my local MP (Rishi) to why we do not simplify tax code, remove the ambiguity, loopholes and just create a simple tax system and stop pretending we are bashing the rich, when we are really squeezing those on the boundary points. I would also add more and more reliant on those chose not to use public services and go private, wait 3+ years or go private and get your new hip next month for example?
We live in a country with many benefits, and I am glad that I am a part of this country, I accept there is a price that I have to pay to live here (taxes amongst one) but there are many things that can be done to improve the country and tax regime, and whilst I do not want to appear to bash the Civil Service and elected representatives, I also would never want their jobs, I need to work out how to help them!
Answers on a postcard, feels a bit like lobbying the FCA again!
Tommy
Totally agree with your comments.
The continually missed opportunity is to simplify the tax framework AND make the an UK attractive and competitive place to do business or headquarter:
Corbynanomics has become reality for the rich! £
No Corbynomics was a reality for the less well off during the great giveaway when Sunak and Johnson gave away out children’s unearned future so people could sit at home and watch Netflix.
We ended up with the greatest tax burden since WW2, capital flight and a mild brain drain.
Let's do the politics on Twitter, not on here please! Ta.
Sure. Let's hope the others get the message as well :)
Are you actually on twitter Paul ? I just tried to search for you but no joy !
Does anyone clever understand why some REITs are plummeting post the "mini" Budget e.g. Tritax Big Box REIT (LON:BBOX) and Tritax EuroBox (LON:EBOX) - is it because asset prices generally are falling off the back of the Government's announcement?
Hi Patrick
It is not just the industrial, Impact Healthcare REIT (LON:IHR) is down a lot in the last couple of days (one of my larger holdings obviously), and I see Warehouse Reit (LON:WHR) (thankfully sold) and others are in the downwards trajectory too, I sold Warehouse Reit (LON:WHR) as felt it had overshot and too much reliance on Amazon, without the intercompany dealings of directors.
Simple answer is no reason other than there seems to be a lot of sellers today, but then it will be worth a look at what the volume actually is, are there a lot of sellers or just no buyers and the MM's are driving a hard bargain to try and find someone to spend their cash?
This is kind of why I have been moving back into the market again, I know that I cannot judge the bottom, but I can make my own decisions on when to buy, when to buy more, and when to say it is time to exit the dancefloor (and try and find a way to manage my pride). But I am starting to build for the next future, then again maybe that will be cash again in a few weeks if everything heads to Rio...
Good luck
Tommy
Rising gilt yields probably main factor - gilts getting absolutely hammered.
Well a "red" week again, but overall calm.
Which considering I am "At Risk" of redundancy but no decisions have been made but your last day will be Monday!
But I am a lucky one, years of being sensible (and yes, I do tell my parents regularly thank you) means we are as reasonably secure as you can be in the modern world, mortgage paid off, pension ok, girls university/house/life funds started, and a substantial rainy-day fund if I cash in the ISA >2 years we will get through this and life will have another interesting twist.
I just had a quick look at various portfolios, there are some crazy things going on Volex (LON:VLX) down 7% and Argentex (LON:AGFX) up 5% obviously there is a whole more complex things going on here than my 5 minutes on an old iPhone can cope with.
I have been starting to buy again, going from 90% cash to 60%, but then my main pension remains 80% cash (a lot of FOMO on every bounce).
Whilst this was meant to be erudite it is a waffle.
There is no right answer, we will come through whatever life throws at us, it will be stressful, hard, emotional, but having hopefully cash to invest, and I hope not too many are leverage on credit the wrong way today, good luck, find a reason to smile, and take some time away from the screen today!
Tommy
ps. I hold Volex (LON:VLX) (getting close to check list sell point) and Argentex (LON:AGFX) (actually still in profit bizarrely!)
Good to hear that as the taxpayer is burdened with supporting the energy crisis, the government have not implemented a windfall tax and have cut the tax rate on the highest earners in this country! Couldn't make it up.
The Tories will get pummeled in the next election.
What good is a windfall tax? We're currently being bent over a barrel because we Europe outsourced its energy security to a rogue state. We need to encourage investment in energy security, taxing companies just reduces the amount of money they have to invest in and disincentivizes them to do so.
No one was calling for them to be given taxpayer money when the oil price went negative during last year's contango. Can't have it both ways - ie if you're not successful the market will punish you, but if you are successful the treasury will punish you.
Industry received a lot of support during the pandemic. Energy retailers are being supported now. A winfall tax on the "cash machine" profits resulting from Putin's war on Ukraine is fair and IMO wouldn't deter investment.
See my comments below. Note that oil/gas companies currently pay 65% in tax.
MJP - spot on. Business cannot plan and won't invest if there's a threat to returns caused by something outside of their control.
The British taxpayer is having to subsidize decades of rubbish energy policies through the price caps - regardless of the party in power. It's those policies that are now resulting in what we see today.
There was a time when North Sea oil & gas meant we were supply independent, and unlike Norway (who kept the benefits of their share), it was squandered away (on who knows what!) over decades.
It's easy to believe press headlines - but often the reality of the way the world and business works is very different to how newspapers and news channels make it out to be. They know this, it's their job to sell copy / drive impressions.
Provided high earners pay their tax in the UK its a good move as we want to attract and retain big earners, they pay a lot of tax ! I find it weird how some folk seem to think it's a bad thing to do well. I started with SFA now I'm ok, I decided I needed to make more money so I changed what I did, worked hard and prospered. Giving handouts simply encourages easy street and it just don't work.
Windfall taxes just discourage investment we need investment, I rather suspect a conversation has gone on behind closed doors, invest or we will tax you.
Regarding: "the government have not implemented a windfall tax" - that is untrue.
UK oil/gas companies used to pay 40% tax. That was increased to 65% by Rishi Sunak. The government has said that they will not introduce a new windfall tax, but there is no plan whatsoever to repeal the existing one...
Energy is a highly cyclical sector. These companies need to occasionally make large profits to offset the inevitable string of bad years when oil/gas prices are low.
Note that Shell/BP shares are owned by a large number of retired people in the UK and the share price is below what it was 5-years ago, while the dividend has dropped. Where is the bonanza that everybody seems to think is falling on the shareholders of energy companies?
Very well said. Shame a lot of people just don’t seem to get this.
I've not worked in the North Sea but suspect a quite frightening and costly place to try and make a living. Cut your nose ....
Pound ££ now flirting with 1.10 to the US Dollar.
What are some potential takeover candidates for US companies?
Craneware must be one. Good recent results & real traction in US healthcare sector. Getting cheaper at this £:$ rate.
£spi
Good to see IR35 defanged a little - even better if it was scrapped. It is essentially compensation for the Govt not raising taxes evenly across taxpayer groups and its effect is to reduce employment and/or self employment to no real good purpose. One of Brown's worst innovations IMHO.
Disappointed not to see any news on the 2% income tax bizarrely levied as NI
Nor anything on the removal of personal allowances at 50p in the pound over £100,000 that, (ignoring Employers' costs) results in a marginal rate of 60% on income from £100,000 to £125,700. If 45% is too high on an income of £1,000,000 how on earth do you describe 60% on £100,000?!
I would have preferred to see the above two abberations scrapped before the 45% rate was reduced, but I don't know the cost, perhaps it was not possible. Apart from that, it looks like a brave start in the right direction, fingers crossed the economy is strong enough to support it.
The budget seems to have been received unenthusiastically by the market.
I find it extraordinary that they could just reverse the focus on the Deficit that was central to government economic policy for a decade. It's as if Corbyn was right and there is a magic money tree.
Not the bond markets... the prices are plummeting, the yields are skyrocketing.
I'm looking at some of the 6-month or 2-year gilt yields, and they are starting to look attractive, compared to just keeping cash in my ISA and SIPP.
What's the best way to invest in them? ETF or Fund, or direct purchase? I've never done the latter before.
I am no expert - yields rising does that not mean market is not confident of UK?
Happy to be educated.
Disappointed not to see any news on the 2% income tax bizarrely levied as NI
The problem here is that pensioners don't pay NI so it would be a big vote loser to try and merge NI with income tax. Never going to happen. A self inflicted government problem almost on a par with the Northern Ireland Protocol.
2% yield on bonds when the actual price has plummeted recently isn't good - they could have a lot further to fall yet. Def not low risk. You should be able to get 2% in cash pretty soon (and probably can now in ISAs).
But how to get a good return on cash in one's Stocks & Shares ISA? Most providers don't offer anywhere near the interest rate of Cash ISAs.
Ishares have range of government bond ETFs such as £IGLT I would personally invest in US treasuries for govt bond exposure and avoid gilts like the plague.
Ah but you are just buying $ which doesn’t seem the smartest long term move given where we are….
Not just dollar (although that's probably good right now) , you are also buying US interest rate duration which could look very attractive if global economy starts to slow and Fed start cutting again (perhaps next year?) - 10y treasury yields around 3.5% so plenty of scope for these to fall back and deliver capital returns.
But if u hedge out the currency it’s not such a smart trade - $ will be a sell before long otherwise everything g collapses - which may come but not before a fight. Bank of England have messed up - 100bp yesterday was needed yet they thought they could do 50. Intra meeting rise coming…….
I am happy to have USD exposure so don't hedge, but there are currency hedged treasury ETFs if this is a concern. However, I'm mainly interested in getting exposure to US yields where I think there is value now - would expect treasury yields to start falling back once it becomes apparent that inflation has peaked and growth slowing (since the Fed would then need to start cutting rates).
The problem is with ETFs, is that they continuously "roll" or buy/sell different maturities right?
All I want to do is buy a Gilt that is being issued now (or soon), and hold it to maturity, for the guaranteed yield that is stated on issue. Surely that should be easy to do? Or is it not?
Gilts can be purchased from the UK Debt Management Office. Their website is DMO.GOV.UK . You do have to apply and be accepted into the DMO’s Approved Group of Investors in order to purchase but this in reality is a check for money laundering.
Just checked on HL and they can be purchased there without all the form filling. Google “uk gilts hargreaves lansdown” and it will take you directly to the relevant page.
I think HL (and others) only operate in the secondary market? I may be wrong there.
For what it's worth, gilts can also be bought and held in ISAs or SIPPs. HL, ii and AJB certainly support this.
Hard to know where UK interest rates will go at the moment - it's difficult to believe that the bond markets won't be testing the government's resolve in the next few days, and harder to believe that yesterday's (non-)budget won't induce the BoE to do something vaguely forceful for a change. It wouldn't be surprising to see a further interest rate rise in very short order.
There'll clearly be an opportunity to buy gilts at a better price than now, but I don't think we're there yet. Whether they'd be good value at such a price is hard to say - inflation tends to be difficult to tame, especially because governments like spending to win elections. Buying 4% fixed interest in a 4%+ inflation environment is a losing game for investors (although a winning one for the government and the BoE as debt is inflated away).
On the other hand £ELLA is still yielding 6.5% and is as safe as houses. I'm really surprised it's held up so well, but that's probably because the shares are tightly held and the management highly regarded for their fiscal responsibility. There is a lesson there, perhaps.
timarr
interesting that you mentioned ELLA. I’m our churches treasurer and we use them for building insurance. They really have a captive market, they charge over £1500 a year for buildings insurance but how many insurance companies would take on an 800 year old building! I did ask them to look at investing the PCC funds but their fees were a joke and their performance was awful.
I will be honest this budget favours myself considerably but this mini-budget is surely storing up trouble for next generation.
These are Corbynesque levels of deficit which we we informed in last GE bordered on communism.
There wasn't a focus on the deficit for the last decade though. We've just gone through the biggest giveaway probably ever - people were paid £2k a month to sit at home!
Agree. After the BoE abdication of responsibility (again) yesterday and the mad hatters budget this morning I have put all my spare money into £GBUS
Have to say largely mitigating the effect of IR35 may seem a small thing, but it was a disastrous piece of legislation. Hard to apply in real life, and businesses couldn't even be sure if they tried to apply it, that they were on anything like firm ground.
Osirium Technologies (LON:OSI)
Cyber security company. M/Cap £2m.
SP down another 15% today following similar fall yesterday on Interim results announcement. SP now 4.25p.
Have had a brief look at this. Listed in 2016 at 160p but looks a basket case with repeated fund raising / heavy dilution and remains loss making. Another fund raising expected in H2. Last round of fund raising was at 6p raising £1m. Can't see their being much appetite from investors when the begging bowl comes out again.
Looks a classic jam tomorrow share. Has anyone researched this one? Have any views?
Never heard of them so went to my favorite site for views on techie stuff; only one page found by the search on it, from four years ago:
https://www.theregister.com/20...
The project contemplated seems to be on allowing IoT devices to only connect when secure and the gist of the Osirium connection seems to be password management; not to judge too much on whether this is one of their core strengths but as one of the comments to the article says "Stop using passwords" (certificates would be better).
I haven't logged onto their website yet as it wants to feed me cookies (strange for a security orientated company). Don't think I'll try harder.
Warpaint London (LON:W7L) Very large range / presence on Amazon with free postage for Amazon Prime subscribers and thousands of 4* or 5* reviews (I don't hold)...This business reminds me a little of Quiz (LON:QUIZ) (I hold) in some respects when reading others' comments...
Brave Bison (LON:BBSN) (MC£23m) released impressive H1 results yesterday and Paul,if you have time today, I think they are worth a look.
This stock has long been a basket case and Oliver Green is the 7th CEO since its IPO in 2013. But this time it could be different!!!! The Greens bought a 27% stake in Brave Bison in 2019/2020 and Oliver Green (in his early 30s) installed himself as Exec Chair in June 2020. He runs the company together with his younger brother Theo.
BBSN disasterous history has meant the company has built up masses of tax losses, but the Green brothers have brought in the old fashioned virtue of focusing on cash. Net cash stands around £4-5m and Cenkos are forecasting £2m of FCF in each of 2022 and 2023 and see the shares trading around 10x P/E this year and next year. The outlook statement released yesterday said the board was confident of meeting or beating the 2022 expectations
BBSN is a “new media” company with two lines of buiness - “Media Network”, producing content (and selling advertising) on social media channels and “Digital Marketing” (fee based service) advice for brands. 2022 H1 saw revenues double - but this is mostly inorganic following the transformative Greenlight acquisition in 2021. But still EPS tripled as cost control was strong.
BBSN has embraced working from home and is now recruiting people globally (Egypt and Bulgaria etc) and argue this increases the talent pool to hire from and reduces cost. They have a inherited (from the Greenlight acquisition) lease on a building in Kings Cross which expires in 2023 and further property rationalisation could reduce cost further. (I was in the office a few months ago and there were many empty desks).
To buy the stock you have to believe that digital marketing is at least somewhat isolated from the forthcoming downturn (which surely will hit traditional advertising). The chart over the last 3 years does not look like most micro caps - recently hitting a multi-year high.
The main potential downsides to me are 1) the lack of track record of the management; 2) the low organic growth of the media network business (which has much higher operating leverage than digital marketing and 3) the economic outlook.
Finally, despite the healthy cash position and good cash generation, I don’t expect dividends - cash is likely to be used for acquisitions.
Hi Wimbledonsprinter,
I did start to look at Brave Bison (LON:BBSN) last night, after a reader comment saying how amazing the results were. But the growth seemed to have come from acquisitions, and profit didn't look particularly great for the market cap.
I'll aim to do a bit more digging, and come back to you once I understand it better. I last looked at it in 2017, so it's a start again from scratch job, which take longer.
Regards, Paul.
Brave Bison (LON:BBSN) did an InvestormeetCompany presentation yesterday and they are due to be on the Mello Results Round Up on Thursday 29 September. I must admit I don't think they present as well as they could - the two brothers seem almost fall over themselves to give themselves equal time. Yesterday's ImC video was (in my opinion) the most relaxed and natural that I have seen them in a presentation (no doubt helped by the fact they were presenting positive results).
Good morning Mr Paul Scott. I watched the online presentation from the board team at £WZL and found their presentation very impressive. So I am looking for holes as well as accolades before increasing my holdings. You have picked up some risks so I wont comment on those.
Certainly, given the market conditions and their price positioning, then assuming the products aren't half bad, then it is ideal - if anything can be at this time.....and that is a point. Their target market will always want to look their best, but will they have ANY money to spend, even on 'necessities' like cosmetics. My guess and - hope - is they will!
It seems to me that much of the international expansion, especially in the US is for TRIAL amounts and EVENT (ie Christmas) situations in large groups but a VERY SMALL number of stores proportionally to the whole group, so it will very much depend on how the products sell through at these events, and whether there is continuing sales on a week by week basis, and whether they can do 'a Tesco' over there (Tesco is their big win in the UK, and is the big story to tell others, especially in the US).
I'm surprised that they are not in Superdrug in the UK which must be a big target. On the other hand they have a toe in Boots, though surprised that there isn't a bit of confusion with Boots No 7 brand!
Just a few other comments on the Q & A session, answering my own and other questions.
Why is cash lower? Because we have made sure investment in stock is high. Liverpool docks problems? None for us. Ditto Felixstowe. No empty shelves for us.
Very significant drop in cost of shipping - 1/3 of what they were paying at the peak per container, if my memory serves me correctly.
Why no women on the Board? Last NED appointment, went for the best quality - guy ex Revlon chosen.....but most of the staff are female, including the senior management. I have to say that the men on the board seem to be doing ok but always good to have the other point of view IMHO.
I asked why were they paying such a good dividend, when as a growth business they could be reinvesting in the business through staff expansion, M&A etc. Response was they had made one small purchase, but frankly they didn't see the need to, and they had the money so distribute it in divis. Simple really!
Good pricing points - especially interested in 'King of Dupes' slide where their 3 products were priced at very competitive levels (!!!) compared with their comparable competitor. They can be in the market with a product within 6 months.
They have rationalized over time the number of SKUs (products) they have, focusing on their heroes as they call them. This has saved them money, and made them money. Win, win. (Assumes of course they can tell the difference ahead of the introduction of products).
Thanks ridavies, that's really helpful! I can't see Warpaint London (LON:W7L) on InvestorMeetCompany. Is there a recording elsewhere for the W7L webinar, as I'd like to see it.
Thanks, Paul.
Not that I know of Paul, but I have asked, Will report back.
Warpaint London (LON:W7L)
Paul, you said "Most product is made in China - a risk?" Well I know that my Chinese daughter-in-law and her friends won't touch Chinese cosmetics. Whenever they visit she takes suitcases full of UK brands home. There have been cases of undesirable ingredients in locally manufactured cosmetics. Obviously, not knocking the company but it's a risk and I hope they do checks for harmful additives.
Timings today, courtesy of The Guardian:
The agenda
• 9am BST: eurozone flash PMIs for September
• 9.30am BST: UK flash PMIs for September
• 9.30am BST: the chancellor, Kwasi Kwarteng, presents mini-budget
• 11am BST: CBI distributive trends survey of UK retailers
This and a lot more can be found on https://tradingeconomics.com/c... remember to correct the time (UK is UTC +1). For instance it shows Germany is contracting according to the PMI numbers. (DE services 45.4).
Warpaint London's cosmetics are located just after the women's magazines, and right where you queue for the tills, in my local mini Tesco. Superb in-store product positioning.
Made.Com (LON:MADE) oh dear, oh dear. How have the lowly fallen. Despite one well known pundit's recommendation when the SP was around 200p on the basis that his children's generation like it and buy its products, it has not been able to withstand the battery of negatives thrown its way in the last year. Lesson 1 - don't listen to pundit on flimsy evidence. Lesson 2; its always tough for new boys to break into a well established high item price consumer market. Other lessons?: I'm sure there are plenty.
Another 33% drop! I cannot wait for Richard Leonard's next interview. Something tells me he won't be on for a while...
Hasn't Made.Com (LON:MADE) been trading for the better part of a decade already? Definitely not a failure to "break into". I'd be interested to see a post mortem of what went wrong at Made.
Goes to show. Decent brand, decent product does not automatically make a good company to invest in.
Leonard's enthusiasm for Synthomer and Devro have not exactly shot the lights out either. Fortunately I own non of them. I do however own one of his other holdings - National World which is by far my largest loss.
Richard Leonard was interviewed by PIWisdom in July 2021 & spoke regarding eleven stocks:
The subsequent performance has not been impressive - average stock performance of -53% lagging the FTSE Mid250 by -31%.
It's a truism that not every Fund Manager can finish in the Top Quartile , but this level of underperformance must be nearer the Fourth Quartile.
https://www.piworld.co.uk/educ...
Could also add to lesson 1: never listen to any pundit. They talk up their own books!
But to be fair to RL you could have made plenty of money on some of these as long as you sold out once they started to drop - 20% off of their highs, or a 20% SL on your own purchase price (or other) or dropping below the 200 DMA may have saved you a lot of the pain.
I haven't followed this advice on the majority of my holdings, but with hindsight I think I maybe a bit more disciplined in the future.
I like these types of interview - they throw up a lot of interesting ideas, but you should only invest once you have DYOR and are fully comfortable. Following any investment manager (without exception) is likely to lead to some errors/issues.
I've often wondered if I would be better off in a number of different IT's rather than choosing my own PF, but take a look at any fund/IT at the moment and they are nearly all doing poorly. I'd much rather back my own choices/judgement and with a broad enough PF holding for the long-term (with some clear SL's) I'll take my chances.
This is a horrible market currently, but one day it will turn and we can all breathe a sigh of relief.
Morning !
What fantastic results from Works co uk (LON:WRKS) ! I always tend to skim over their results because they were loss making and had a terrible balance sheet, but today, they have beat forecasts, made loads of cash and now have a big cash pile. Very unexpected ! The only thing is the outlook, they do tell us next years profits will be roughly half of this years...
Thanks truegent,
I saw that Works co uk (LON:WRKS) was up 35% in early trades, so am planning on looking at that one next. Having a very quick look, I think maybe people are getting carried away with the good figures for FY 4/2022. These numbers are not sustainable. In particular, it benefited hugely from business rates relief.
There was a profit warning for FY 4/2023, which I covered here on 8 Aug 2022, and caused the share price to plunge. Look at what has happened to broker forecasts since -
That's clearly demonstrating that the 2022 figures are not going to be repeated.
For that reason, I would urge caution over this morning's euphoric reaction to these numbers.
Balance sheet - is OK actually. NAV £21.6m, less £2.7m intangibles = NTAV of £18.9m. But bear in mind the IFRS 16 lease entries add up to a deficit of £17m, so if we eliminate those entries, NTAV would rise to about £36m, which is fairly secure actually. So I'm not worried about solvency.
With a consumer downturn, and increased costs (e.g. wages), plus business rates kicking back in, I very much doubt whether WRKS will make significant profits in future.
Bulls might point to its value product offering, which could prove of more enduring appeal, in a consumer downturn.
I'll have a closer look later today, but those are my initial thoughts.
Regards, Paul.
Paul, I recall that Cockney trader was very bullish on £Wrks when you interviewed him in July but you were not buying it then. Will be interesting to see your more detailed consideration of the current situation.
Thanks for all this Paul, its what I thought too and if anything I would be looking to short if there is any substantial rise in the sp...
Impressive to hear Simon Tucker expounding on the potential of SRT Marine Systems (LON:SRT) (I hold) at their recent AGM. Selling transponders and MDA (Marine Domain Awareness) systems - air traffic control for the seas. Claiming to be a leader in the field, and having taken some time to get to this position, the pipeline looks impressive. Find out for yourself by watching the video on this page: AGM September 2022. Is it about to come good big time?
I looked into SRT Marine Systems (LON:SRT) after a recent video was uploaded on piworld. I looked at a presentation in 2017, also by Simon Tucker. Interesting to watch near the end when he is talking about orders 'already in the pipeline' - I didn't find the revenues that matched these claims. I wondered whether this wasn't a jam tomorrow business, but a go and pick the fruit and buy the sugar yourself type.. Maybe I'm completely wrong and this is going to the moon !
www.youtube.com/watch?v=Cm1q0H...
Yes, I agree cheeky_minnows, SRT Marine Systems (LON:SRT) has been on the cusp of huge new orders, and a gigantic pipeline, for many years. Something always seems to go wrong. Remember it's been listed, and doing the same thing, for 17 years!
Although I see the current year forecast is for a giant leap in revenues, and decent profitability. I'll believe that when I see it.
The most recent TU from SRT said H1 is expected to be "materially better" than H1 last year. Which is a good thing, because H1 LY (6m to 9/2021) showed only £4.7m revenue, and a £(3.1)m loss.
Investors have been extraordinarily patient, and ever-optimistic with SRT over the last 17 years. Or maybe it's such a long time, that several generations of investors have passed through, and there's a fresh batch of believers to take their place every now and then?!
Mind you, we do occasionally see a stale, long-standing story stock come good - e.g. £SCE . I have to say though, the successes are very rare, and even those are usually not that great in share price terms, due to huge dilution along the way from repeated placings.
Regards, Paul.
Yes Paul, those who invested all those years ago have paid for what has been developed and have suffered during that time. But the best time to invest, as with Surface Transforms (LON:SCE), is when the technology and all that investment is about to come good. What's amazing is that SRT Marine Systems (LON:SRT) have more orders than the can fulfil on the transceiver side, have a truly revolutionary product about to launch and have these big system orders without ever having to advertise or even have a sales force. Do watch the video and make your own mind up.
I'm one of those patient SRT shareholders. To say they've been "doing the same thing for 17 years" is misleading because it's not entirely true. SRTR were once a radio business which saw potential in AIS and in 2006 transitioned into making the "boxes" that ships needed to have to be able to see and be seen by other vessels. They made high quality units and pinned hopes on the growing number of mandates various countries created requiring vessels to have AIS transponders. There was little enforcement of these mandates so sales were not as good as expected.
SRT changed direction to become a Systems business offering various Marine Domain Awareness products. At the heart of this was a piece of software they bought in late 2013 for approx £950k called GeoVis.This was spin out from the university of Wales and it had the ability to input data from multiple sources, AIS Radar etc and display it in real time. Significant development since then has enabled SRT to offer maritime authorities the ability to monitor all sea borne activity in their waters and beyond.
Some early sales eg. Bahrain in 2015, provided proof of concept and acted as a reference for other potential customers . By March 2017 the Chairman proclaimed that the transition to a systems provider had been completed although it still made and sold the small AIS transceivers which had once been its sole business. Moving on to the current date, several important contracts have been signed. The Philippines £32m fisheries project (BFAR) is nearing completion. An un- named but by now well known Middle East customer signed a £40 contract in January. The key thing is that these contracts which unfortunately take years to understand what the customer needs and show that SRT can deliver the solution are just the beginning of a long term relationship.
Initially following a contract signing the infrastructure (control rooms, masts, power and connectivity) and necessary laws have to be put in place, then equipment can begin to be supplied. The people who will use the systems have to be trained, boats have to be fitted with transceivers. It's not a short process and revenue is earned on completion of milestones.
The long term relationship is based on two things. Firstly SRT gains the trust of the customer by being prepared to listen, to understand what they need, to help them realise what they need, not what SRT wants to sell them and to be endlessly patient despite endless bureaucracy, idiosyncratic behaviour and delays.
Secondly, once the customer realises that they have bought the right solution and that they own something that allows them to control their waters which is not at the discretion of a foreign government, they will not go back or seek a different solution. RT not only sells them the system, subsequent updates, and all the equipment but also the data gathered by satellites which have coverage beyond the reach of coastal stations.
This is why SRT are optimistic about the future. Covid caused a 2 year hiatus as most customers or potential customers were too busy dealing with the pandemic to put resources and money into maritime systems. Things are moving again now and having talked to people directly involved in dealing face to face with those customers, existing and new, I am also optimistic that SRT will fulfil its promise.
Re SRT Marine Systems (LON:SRT)
"doing the same thing for 17 years" is misleading because it's not entirely true.
But you then went on to explain that it's the same activity - electronics for ships/boats to report their locations!
Let's compromise here. I'll be happy to amend my comment (too late now, but if I could) to "doing broadly the same thing for 17 years". How about that, I think that's undeniably true.
Regards, Paul.
I cannot decide about SRT. There is a need for what they offer which is a very good start. AIS is a leading product. The market is big. This is a good platform for the investment case. But the story has been the same for quite a while and revenues really haven't gone any where. £10m 2013 £8.1m 2022. Profits have declined to losses over the same period. In the 2017 youtube video they talk of strong growth, they do now "significant new contracts are expected to drive considerable growth" in the systems division. What does "validated sales opportunities" even mean? They have identified potential sales so what? I really want to see an opportunity in these miserable markets and my gut says there is something here, but it all seems lots of impressive opportunities (validated or not) and little delivery (I agree with cheeky there is no connection between Tucker's pipeline and delivery). The only thing is surely they know they have to deliver something or they are going to run out of time and promises.
SRT Marine Systems (LON:SRT) to answer the question, what is the "validated sales pipeline" or VSP, it's not a list of possible new opportunities. It is a list of opportunities that have been extensively discussed with a customer who not only has the need but also has the budget. or the political will to make the budget available. SRT get lots of enquiries from customers that clearly have no money nor the government backing to proceed. These are politely batted away with helpful advice on what they need to enable meaningful discussion. So the VSP is a vetted list of active work to develop a project to the point where a contract can be signed. It may take a long time to come to fruition but it is not a fantasy.