Small Cap Value Report (Fri 24 Feb 2023) - KCT, CINE, ZOO, MTEC

Good morning! It's just Paul here today, with it being Friday.
I'm fizzling out into the weekend now, so will leave it there for today.
My SCVR summary podcast will be back tomorrow, after a break last weekend when I didn't have any inspiration, which happens occasionally.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Made Tech (LON:MTEC)
33.5p - market cap £50m
I originally posted this as a reply to a reader query below, but am copying it here.
I did have a look at Made Tech (LON:MTEC) last night, and found it difficult to form a conclusion. H1 figures are poor as you know, but it reckons it can deliver a much better H2 performance. So there's a quite a lot of guesswork, and having to trust what management says, which is probably why the share price is volatile, and attracting traders as you say.
So there's not much value I can add by guessing as to whether it will achieve the FY outcome, or whether there's a risk of another profit warning. Big H2 weightings quite often do result in another profit warning.
What I can do to help is review the balance sheet. This looks fine. With £8.7m net cash, and NTAV of £11.9m, this strikes me as a solid balance sheet, with little to no risk of dilution or insolvency.
Share based expense looks excessive, at £1.5m in H1, and £2.4m last full year. That's taking the proverbial, given the share price performance.
Market cap of nearly £50m seems a lot for a company that has just reported negligible profit. What you're paying for is the hope that it will achieve a much greater profit in H2.
We had a good discussion about these IT consultancies a little while ago, with most readers agreeing that they're not necessarily a licence to print money, and that they quite often get into trouble with projects going over budget, inadequate staff expertise, etc.
Tpximpact Holdings (LON:TPX) was a good example of where things have gone horribly wrong, and with bank debt, its situation looks precarious. At least investors in MTEC can rely on a much stronger balance sheet with net cash, so it's a much safer bet on a recovery than TPX.
Zoo Digital (LON:ZOO)
200p (£179m)
The positive newsflow here is gathering pace. ZOO announced another deal with a Hollywood studio earlier this week. Checking our archive here, I was sceptical on 23 Mar 2022, but turned positive on 25 Apr 2022 in response to strong trading updates. Graham was also previously sceptical, but reported here positively on ZOO on 8 July, 21 Sept, and 8 Nov 2022. The company is definitely on a roll, and broker forecasts have risen a lot. Although shares appear expensive, the excitement here looks justified because it’s got a wonderful combination of very strong organic growth, combined with increasing margins from the operational gearing. That can be an explosive mixture for profitability. Well done to holders, it looks like you’re on to a winner here!
Cineworld (LON:CINE)
Down 33% to 2.65p
As discussed in the reader comments below, this overly-indebted cinemas chain has made it clearer than ever today that its restructuring is almost certainly going to end with the shares being worthless. This has been obvious for a long time now, hence I cannot understand why its shares are still being traded. Surely they should have been suspended pending clarification of the financial position, which is what usually happens when a company becomes worthless?
Anyway, we’ve warned readers away from this share for a long time, and this brief comment is just to reinforce that view - anyone dabbling with this share is almost certainly facing a 100% loss, so for goodness sake, please don’t be tempted to buy or hold any CINE shares. The equity is worthless because the value of the business probably falls short of its massive debt pile, which the company has confirmed again today. Once that stage is reached, then creditors control the situation, and just wipe out equity holders.
Kin and Carta (LON:KCT)
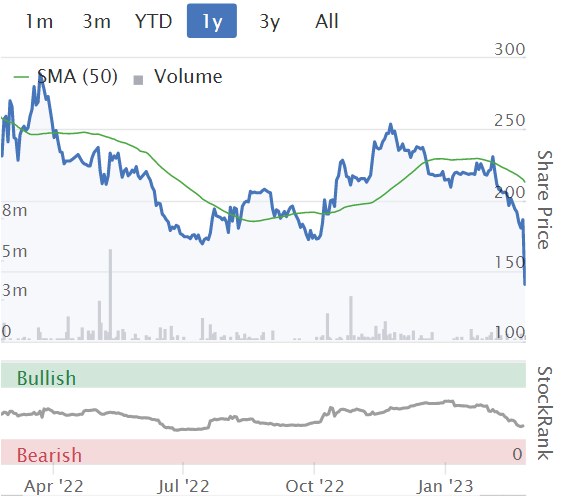
148p (down 20% at 08:18)
Market cap £265m
Kin and Carta plc ("Kin + Carta" or the "Company"), the global digital transformation ("DX") consultancy, provides a trading update covering the six-month period ended 31 January 2023 ("H1"), ahead of the announcement of its half year financial results expected 15 March 2023.
If you think that’s a poor description of what the company does, then the “About Kin + Carta” section lower down the announcement is unadulterated gobbledegook.
Having read it all, I still have no idea what this company actually does, and am left feeling biffsquiggled! From memory, I thought KCT used to post out marketing material for banks, etc.? Although it might have disposed of that operation?
Anyway, today it’s issued a profit warning -
Following the impact of macro headwinds in late H1, the Company is reducing expectations for the year to reflect more cautionary client spending and elongated sales cycles seen across the industry…
As a consequence we expect adjusted operating profit for FY23 to be below market expectations.
We expect a return to a more normal level of growth with improved profitability in FY24 supported by the current levels of demand, increased nearshore delivery and improved cost structure.
Net debt is modest at £11.9m (under 0.5x EBITDA) - although that’s higher than the £0.5m reported at July 2022.
Previous accounts have shown enormous adjustments, which turn adjusted profits into statutory losses, so I’ve never been a fan of this company’s accounts. Too many acquisitions, and adjustments.
KCT claims to have a strong balance sheet, which is usually an amber flag. Sure enough, the NAV of £124m at July 2022 was mainly £97m intangible assets, and a £39m pension surplus. There’s not really anything in tangible net assets once these 2 items are deleted.
Pension "surplus" - note that the last accounts explain that even though the pension scheme is in surplus, KCT is making £2.5m pa “voluntary contributions” into the pension scheme(s), plus £0.4m pa costs, until April 2025. That’s a peculiar pension scheme surplus, which is costing £2.9m pa to fund! Which is why I usually delete supposed pension surpluses from the balance sheet. The only exceptions being where a company has specifically stated that it expects to receive cash back from its pension scheme, something that is rare.
Profit guidance - There’s a fair bit of detail in today’s statement, but we have to go round the houses to work out the profit guidance. I'm totally confused by it. An 8% operating profit margin in H1 doesn't sound too bad, and seems to result in adj operating profit of £7.9m, slightly up on H1 LY of £7.7m. Why couldn't they just state what the revised number is for profit guidance, compared with the previous guidance provided?
There doesn’t seem to be any broker coverage available on Research Tree either, nothing since March 2020, so we’re in the dark for now, until revised broker consensus figures filter through next week hopefully.
Outlook - sounds more positive for H2 -
Demand remains strong heading into H2, with a strong sales pipeline of £166 million, up 45% year-on-year and record order backlog of £124 million, up 17% on prior year.
My opinion - this share has never interested me. Looking further back, it used to pay big dividends, but they were slashed after the 2008 financial crisis. The reduced divis were slashed again when the pandemic hit in 2020, and are forecast at almost nothing now. Although modest net debt, having de-geared in 2021/22, means it possibly could start paying worthwhile divis again, once trading has improved, maybe?
The accounts are really opaque, dripping with adjustments, with acquisitions and disposals muddying the water. It can’t clearly explain what it actually does, and today’s update doesn’t provide clear enough profit guidance. What investors needs is something telling us that the company expects to make £x profit this year, replacing previous guidance of £w profit. Or put that information out via brokers, ensuring that it accessible to all through Research Tree or commissioned research providers.
In this case, I’m in the dark, with inadequate information, so have no idea how to value this share.
All we have to go on, is the share price, which has dropped about 20% in early trades.
Given all the above, I have to give this one a thumbs down, mainly due to uncertainty, and the opaque accounts, rather than anything more worrying. I don’t think there’s any concern about solvency, given that net debt is low.
I’d welcome any reader comments, particularly if you’ve done more detailed research on KCT.
Paul's SCVR Summary spreadsheet - sorry for the delay, but the summary sheet is now up-to-date. It's a hopefully useful tool, to enable subscribers to see at a glance a month's worth of SCVRs in one go. Hover over any cell to see a pop-up box with Paul/Graham's opinions on the shares, from a value investing perspective. Obviously we're not trying to predict what share prices will do, nobody knows that, we're just commenting on the fundamentals/valuation. Hopefully it might help you avoid some bad situations, and highlight some good ones too, but the detailed research is down to you - we're only doing brief reviews of companies remember.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

50 comments
Paul you seem to have conveniently forgotten your reporting on Zoo in your weekly podcast
Can’t think why
Made Tech (LON:MTEC) H123 results presentation from the webinar given by CEO & CFO with results video & podcast.
Rev £20.6m +76%
GP% 33%
aEBITDA £0.5m
Cash £9m
Sales bookings +23%; contracted backlog +53%
3 contract wins £27m since period end incl DVLA
Outlook: in line with expectations with very strong visibility, healthy demand environment and a very strong pipeline of opportunities.
Markets are a bit scary at the mo. Not sure whether they are coming or going. E.g. Zotefoams (LON:ZTF) - high quality but has shed some of its gains from its high. Yu (LON:YU.) was at 620 but got bought up. Bloomsbury Publishing (LON:BMY) without the release of a early spring TU - peeps getting a little nervous, Braemar (LON:BMS) could have been bought at 275p and the list goes on. Not sure if we are amidst a major step down (thus, do not want to get caught in transition (as I have many times before)) or will the sp's recover? IMO, given the news out on Friday in the US, it's a major step change for risk assets, which guides the market at least for the next few weeks until the Fed's March meeting (oh, almost forgot, we've got US non-farm payroll coming up - if they are hotter than expected - get your tin hats out).
I noticed the FTSE250 and AIM peaked around 3 weeks ago, since then both have been in decline. There has been some big moves on no news. The FTSE has has held up until last week. Not sure which it will go, markets often do the opposite from what I expect.
Kin and Carta (LON:KCT) TU sentiment analysis from ChatGPT AI:
The sentiment of this trading update from Kin + Carta plc is mixed. The company reported a 15% net revenue growth in H1 FY23 compared to the previous year, but like-for-like organic net revenue was down by 6% with a decline in both the Americas and Europe. The company also lowered its expectations for the year due to cautionary client spending and elongated sales cycles. However, the company is optimistic about future growth, citing new contract wins and a strong sales pipeline. The CEO emphasized the company's focus on enterprise clients with higher margin nearshore delivery and a record backlog demonstrating ongoing demand for their services. Overall, the sentiment is cautious but optimistic for future growth.
Sounds something like Simply Wall Street will publish.
Sounds something like Simply Wall Street will publish.
Indeed. Can we leave the interpretation of TUs to Paul, Graham and those PIs happy to put heads above the parapet? Quoting ChatGPT summaries simply regurgitates management’s doublespeak! It clutters up the forum.
Well...it remains novel and interesting so far. I look forward to another instalment of ChatCGP where I will rush off to buy if it's a thumbs up!
ME International (LON:MEGP) - does anyone know what's going on? - FY results due either Mon or Tues. Down significantly today.
Earnings release for ME International (LON:MEGP) shows in Stockopedia as being on 20th March, in line with the last years timing, (I hold).
ME International (LON:MEGP) From 14th November trading update: "The Group will publish its results for the financial year ended 31 October 2022 towards the end of February 2023."
MEGP seems to have a solid Stockopedia rating. Perhaps there has been some profit taking after a long upturn and before a possible fall after results published in line with expectations. I may buy after results.
Does anyone have any thoughts on the update from Avation (LON:AVAP) ? Seems to be ahead of market expectations.
Yes - I expect NAV to be circa 300p against market cap of 125p. Risk on NAV is to the upside as 2nd hand planes values are increasing, particularly for newer planes of which Avation (LON:AVAP) fleet is and also for energy efficient fleets. tick again.
Remember the vast majority of debt is backed by the plane. Ie it is a mortgage. The risk is then passed to the lessor (airline) - the airline makes payments to Avation (LON:AVAP) which is sufficient to pay down the capital and interest. At the end of the lease Avation (LON:AVAP) holds the plane unencumbered. There is no interest rate risk as both are fixed, so the predominant risk Avation (LON:AVAP) faces is credit risk to the airlines or to NAV in 2nd hand values falling. Every year as the airlines make payments to the company the debt falls and is added back to NAV so should be accretive.
The main caveat to this is the bonds as they obviously need to be redeemed in 2026 but they too are asset backed by planes. There's a reason why only a tiny % of bondholders chose to tender their bonds at 85c in the $ and that is because they fully expect them to perform until maturity.
There is also quite significant hidden value in the balance sheet I believe which by my estimation should also add quite a bit to NAV but I'm discounting that to zero for now.
Historically aircraft lease companies trade around NAV. Now I understand why that may not be the case given the pandemic is still fresh in investors eyes but over time that will unwind. in my view. I think it will take a few quarters of sustained progress but Im fine to wait.
Currently they have 3 planes unleased - 2 of these should be gone very soon and 1 unutilised aircraft is about the norm so I have no real concerns there.
Appreciate your thoughts, thanks
Avation (LON:AVAP)
There's some good commentary here on the latest update for any interested:
https://www.lemonfool.co.uk/vi...
Anyone else having problems with the site today? It is very slow and Im getting lots warning messages.
As a holder of a small amount of Kin and Carta Kin and Carta (LON:KCT) this is a day to leave me with the dunce cap. But having taken a pasting I have hesitated before selling and would offer up some thoughts.
Are the results bad? Well there are companies out there that would not be embarrassed to have an 11% sales gain on the comparable H1, even if this is somehow seen as cheating because it includes acquisitions. It is part of their stated intention to grow with acquisitions, so it seems OK if this intention is carried out successfully
Are the accounts intended to be obfuscatory? From my view they are not surprisingly complex for a company with three sales and three acquisitions in the year, covering several geographic locations.
Why fund a pension with an excess? They have said that the £2.5mm will cover up to April 2025 and is aimed at achieving “low dependency” on KCT. The fund is moving from a mixed equity/ bond make up to a primarily Government Bond basis and this will ensure as far as possible there is no further call.
Is the balance sheet asset light? Yes, if you are looking for hard saleable assets. But who expects this in a people based consultancy. In my opinion it would be a criminal misallocation of capital to, say, buy their office buildings when everything in their business requires people investment and growth in working capital(ie Receivables)
Are large adjustments from GAAP reasonable? For an understanding of the business, they seem fair and not especially unusual to me. Out of £29mm, £20mm comes from two items: the amortization of intangible assets on acquisition (a conservative thing to do) and the IFRS3 requirement that where purchase consideration is in the form of deferred remuneration it must be expensed.
It is a valuable rule that your first loss is your smallest so I may at least cut back my holding, but I think it is likely that todays drop will be seen to be overdone
I suspect you are right on Kin and Carta (LON:KCT). The accounts aren't really obfuscatory - the reality is that the official p&l would actually be misleading as a large chunk of deferred consideration needs to be treated as remuneration expense (even though it isn't).
You can argue about depreciation of purchased businesses but to a new investor you don't care about that as it doesn't impact cashflow going forward (which is what you are buying).
So the adjusted number is probably a reasonable reflection of the actual business. An 8-12% growth is still pretty good and there are plenty of tailwinds - just look at the order book and pipeline growth.
at £230m market cap they are now probably on a rating of sub 10* which is way lower than peers so I think the fall has been overdone. A mild profit warning was expected and the shares had dropped from 230 to 185p on anticipation so really they have dropped 50% on a reduction to anticipated growth rate of say 10%. Feels like an overshoot in a poor market. Only £4m worth of shares have changed hands and the market cap has lost £100m !!!
From my lens the business is worth around 200p so I'm not a seller - I expect them to be fine over a 2 year horizon but could be wrong of course if things materially deteriorate but given revenue visibility and cost cuts I'm not expecting that as a base case. The only thing that worries me a bit is that this comes from the new CEO so the question is whether any of this is down to her leadership. Only time will tell on that but to be fair to her she was in the seat running the US business prior to taking on the CEO role so I will give her the benefit of the doubt for now.
Kin and Carta (LON:KCT)
Very helpful comments on the treatment of deferred consideration, thanks. I think what the market is concerned about, however, is the steep reverse in organic growth. I hold a number of DX names, here and abroad, and nearly spat my morning cuppa out when I read the following:
For the current financial year ending 31 July 2023, the Company now expects net revenue growth of 8-12%, with organic net revenue at constant currency showing a low single digit percentage decline from the prior year
coming on top of:
Like-for-like (organic, constant currency) net revenue (in H1) was down 6% in total with a 1% decline in Americas and a 16% decline in Europe
Netcompany a Danish DX consultancy, which competes head to head with KCT in Europe and the UK, grew organic revenues 19% over the same period, though encumbered by its greater scale at GBP1.5bn mkt cap. A further 10% growth is expected this year. At the other end of the scale, local counterpart Made Tech (LON:MTEC) fell 20% (and recovered half the fall a day later) after forecasting organic growth of nearly 50%.
All of which begs the question: what has gone wrong at KCT that revenues are collapsing? One clue is the mention that the UK is the laggard and perhaps that is a cyclical factor which will reverse in due course.
Taking a step back and studying the charts, it’s clear that most DX names are trading at or below 50% of their post-pandemic highs. That list includes EPAM, Globant, Endava, Netcompany and now KCT. Perhaps the bad profit (or rather revenue!) warning, and it is a bad one, was the opportunity for the market to cut the previously rather resilient SP down to a commensurate size?
Longer term, I think the tailwinds for DX are such that KCT will be fine, and this could represent a rather profitable entry point. But the picture is cloudy today and I do not see any points of positive differentiation in a business that relies so heavily on M&A for growth. The lower rating seems justified to me in much the same way that the market is sceptical of MTEC’s potential to deliver GAAP profits. If concerns are addressed, both will prove winners for investors at today’s level.
Good global context so thanks for that. The thing I would say is that Kin and Carta (LON:KCT) is now at almost a third of post pandemic highs so seems like the falls are somewhat excessive. I'd expect this type of business to trade around 14 to 15* normalised earnings so more like 200p which would still be 40% off the high.
Going back to last trading update revenue expectations were still for strong growth so I agree the decline is concerning. I think that the mini budget had the effect of pressing pause on capital projects on a lot of businesses in the UK though as they felt it prudent to wait a few months and see what transpired. I would expect that with the situation stabilising many of those projects will now go ahead so one would expect Kin and Carta (LON:KCT) to make up some ground.
I struggle a bit with the ack of organic growth. These businesses shouldn't be overly reliant on acquisitions so I hope there is some focus on the sales / bus development process there.
Nonetheless looking forward 12 months I'd expect to see revenues of £230-250m and op margins of circa 13-14%. So at the upper end of my expectations circa £35m of operating profit. Lets say £25m after tax at 14* earnings is £350m market cap or about 200p. If their stated medium term 15% growth at mid to high teen margins is achieved then 300p looks achievable so I'm currently thinking at these levels upside looks attractive over a 12-24 month view. There should be no shortage of available business in the DX space for several years to grow into so really it is about the competence of the new CEO (or old US head). So far I'd say her report card is a C minus but there is an argument that the UK situation wasn't a problem of her making. She needs to prove herself now though - has the marginal benefit of the doubt but no more mis-steps should be tolerated.
I think that the mini budget had the effect of pressing pause on capital projects on a lot of businesses in the UK though as they felt it prudent to wait a few months and see what transpired
I tend to agree. It may be that the stronger proportion of (possibly more resilient) UK government work enjoyed by competitors accounts for the contrasting trajectories in revenue growth. The company is not forecasting a quick reversal in fortune, however - only a slow grind back to growth in H2.
Kin and Carta (LON:KCT) - obvious that some peeps were selling with advanced knowledge of the TU. Have been watching the sp action in detail. It hit 230p and from there it crumbled to c173p with heaps of selling, where an II made a big buy of £200k+ which sent the sp back to 180s just prior to the TU. There I was thinking that I got myself a nice entry prior to a TU at 183p. Lesson learnt: TU for growth companies in this environment can be very volatile. Very blessed that I made it back with a trade on CentralNic (LON:CNIC)
obvious that some peeps were selling with advanced knowledge of the TU
Maybe they just saw the disappointing reports from competitors in the previous week. The signs were there.
However, Elixirr International (LON:ELIX) did not dive in the last few weeks like KCT prior to the KCT's TU. Perhaps, one may argue, ELIX's shareholders are less insightful or something else is at work...
This morning’s TU from Elixirr International (LON:ELIX) is quite reassuring so you may see a bounce. It certainly underlines the weakness in Kin and Carta (LON:KCT)
Hi Paul,
Are you going to do a write up on Made Tech (LON:MTEC) which was on the agenda yesterday? tia
Are you going to do a write up on Made Tech(LON:MTEC) which was on the agenda yesterday? tia
I would echo this request, please. TU was in line and performance has stabilised. CFO confident on profits for the year ending in 3 months. I asked the CEO about medium term growth this lunchtime. He said FY24 forecasts, which I felt were unimpressive, had been set very conservatively but with an eye to an election next year which tends to depress government IT spending temporarily. Share price has been bouncing around as traders adjust (sell the news). Would appreciate your thoughts on the accounting adjustments. Thank you
Hi,
I did have a look at Made Tech (LON:MTEC) last night, and found it difficult to form a conclusion. H1 figures are poor as you know, but it reckons it can deliver a much better H2 performance. So there's a quite a lot of guesswork, and having to trust what management says, which is probably why the share price is volatile, and attracting traders as you say.
So there's not much value I can add by guessing as to whether it will achieve the FY outcome, or whether there's a risk of another profit warning. Big H2 weightings quite often do result in another profit warning.
What I can do to help is review the balance sheet. This looks fine. With £8.7m net cash, and NTAV of £11.9m, this strikes me as a solid balance sheet, with little to no risk of dilution or insolvency.
Share based expense looks excessive, at £1.5m in H1, and £2.4m last full year. That's taking the proverbial, given the share price performance.
Market cap of nearly £50m seems a lot for a company that has just reported negligible profit. What you're paying for is the hope that it will achieve a much greater profit in H2.
We had a good discussion about these IT consultancies a little while ago, with most readers agreeing that they're not necessarily a licence to print money, and that they quite often get into trouble with projects going over budget, inadequate staff expertise, etc.
Tpximpact Holdings (LON:TPX) was a good example of where things have gone horribly wrong, and with bank debt, its situation looks precarious. At least investors in MTEC can rely on a much stronger balance sheet with net cash, so it's a much safer bet on a recovery than TPX.
Hope that helps.
Regards, Paul.
P.S. I've copied the above into the main article.
Thanks Paul. Much appreciated.
Nanoco plc market cap is now exactly equal to the expected litigation cash receipts from Samsung (i.e. 23p) and I have started adding my usual 5% to my portfolio.
Anyone know why Elixirr International (ELIX). I can't see any news.
Volume is up today, so could be some large sales, similar situation to iEnergizer (LON:IBPO) as mentioned below.
Elixirr International (LON:ELIX) is down because of Kin and Carta (LON:KCT) + softening in employment in consultancy biz
At the Mello meeting in November, Graham picked up Jupiter as one of five contrarian share. I followed him and pleased to see it went up 12% today.
His other picks were TTG, MEGP, IGR and one which I do not remember.
I think Graham's 5th was Disney
Hi Lucky dip,
Yes indeed, Graham wrote some excellent articles about fund manager shares last autumn, and I remember agreeing with him that the whole sector looked very good value. Earnings obviously soft in 2022 due to the bear market, but earnings should recover in time, and hence share prices recover. A very simple investment idea!
I see Jupiter has halved its divi, but that looks to be as expected, and still gives a very pleasing 5.0% yield.
Fund outflows seem to have stopped now, and markets have bounced, so it seems reasonable to expect profits at fund managers to improve.
I don't know much about it, but I do like this sector, given the cyclicality probably having bottomed out. Although that's already been reflected in strong share price rises from the autumn lows.
Regards, Paul.
Paul. The dividend is not 5% - that's historical based on the held interim. The dividend is toast! The final is just 0.5p down from 9.2p. I don't, for the life of me, see how this has gone up today. Income investors will be dumping in their droves.
Not really Lord Gnome - the dividend policy has moved to 50% of pre performance earnings
That means given the improving fund flows picture I think we should expect circa 6 - 7p dividends next year which is around 4.5 to 5% yield as a base case. However, as the asset mgmt cycle turns that could go up considerably.
Shares are up because they massively outperformed expectations on earnings and the funds flow picture has stabilised and reversed with a base case of 5% yield and likely to move up over the cycle.
Paul, Kin and Carta has been on a major transformation of its own into a digital transformation (DX) consultancy*. An attractive market with, in my own professional experience, an almost endless runway for growth, although running hotter this decade. Businesses have not stopped evolving through technology since before the invention of the steam engine.
There has been a general trend in the DX marketplace for cautious outlook statements recently, owing to lengthening sales cycles and general caution around the macro. Consequently I was expecting a profit warning, but not one that reads so badly compared to the likes of competitors EPAM, Globant and Endava over the last fortnight. Combine the weakness of the results and the obfuscation of the accounts, not to mention the persistent GAAP losses, and this would be well down my list of DX names to invest in.
*a software house/consultancy that helps corporations and govt entities remodel their processes from analog to digital
'Tragic Roundabout' Mr C - Exceptional! Head. Nail on the.
I can't stop spluttering my coffee all over my keyboard. Lovely start to a Friday, thank you so much!
cheers
Mark
The share price of iEnergiser iEnergizer (LON:IBPO) has fallen around 20% in the last few days. Yesterday (Thursday) it was down nearly 10%. No RNS, no news. 4 x the normal daily volume. Smacks of insider knowledge?
It is an unusual company where shareholding is dominated by the founder and CEO with over 80% of the shares, and has some big names with other but significant ‘names’ with smaller shareholdings. Only 3% of shares are held outside the top shareholders. The lack of information may be related to the fact that only 2 shareholders – the CEO and two majors AXA and Premier have more than 3%.
The CEO put the company up for sale in 2022. There was not an immediate response, and the CEO then after some time withdrew it after the company had a good rate of all round growth at the last report in Nov 2022.
Over a longer period the SP has risen 5 x in the last 5 years. In the last year it is down 33% from the year’s high.
I wonder if any other readers, maybe investors in the company, have any further information or opinions.
Morning,
I posted yesterday on the seemingly strange share price decline recently. Share price is nearly 50% off high of last year now.
If the owner was looking to sell or delist, why didn't he choose to sell the company last year, when 550-600p would have been achievable?
I have emailed the company, will see if any response.
Mark minervini says, no matter what the fundamentals or results, if these aren't backed up by the share price, get out!
Thanks for that JohnDoe2378. I must have missed your posting yesterday. I look forward to any response you get.
Re the sale, Im not sure that anyone came forward with offers to buy iEenergizer (iEnergizer (LON:IBPO)), or am I mistaken?
This one has been on my watch list for a while. The other week it was the only share showing up on one of the Stockopedia guru screens ( although it has now fallen off ). It has some amazingly good metrics but the ownership structure puts me off. I am not sure whether it was clear if any offers were made last year. It was reported in September
"The IT service management company launched a formal sales process back in June. Earlier that month, it said it was in talks to be bought out by BPEA Advisors Private Ltd.
"The company subsequently engaged with a limited number of parties but given stronger trading during the process...the board felt that it was in the best interests of the company to withdraw and terminate the FSP at this time, and confirms that it is no longer in active discussions with any interested parties," iEnergizer said.
At that point they were reporting a quarterly increase in sales of 30%
Roland had a look at it last year and said that he would add it to his SIF folio if the price dropped below 350, as it met all other folio rules.https://www.stockopedia.com/co...
iEnergizer (LON:IBPO) , the problem is the free float must be very small, so any selling will affect the share price. I know Robbie Burns held this stock, maybe he has dumped his holding which triggered some stop losses. Or the CEO?
I do hold some, tempting to top up. Shares are now up today, 358p to buy.
Similar thing is happening with Quarto (LON:QRT) but in reverse, there is a large shareholder there also, apart from delisting rumours I can't find anything.
Miniverni trades in US mid to large caps, he uses very tight stop losses.
Only thing is that minervini looks at large caps where that is probably true. Small caps can move a fair amount on someone trading a single share
Any chartists out there? Looks like now sitting on a long term uptrend. 4th touch going back to 2018.
My morning smallcap tweet: Tragic Roundabout
Cineworld (LON:CINE) Kin and Carta (LON:KCT) Circle Property (LON:CRC) Avation (LON:AVAP), Webis Holding (LON:WEB)
◄Cineworld (CINE)► has non-binding proposals to buy some or all of its business. None of these is an all-cash bid for the entire business. Shareholders unlikely to get even a bag of popcorn to munch through the end of this disaster. [SP=4 Cap=55m]. I'm short.
◄Kin and Carta (KCT)► warns FY-July adjusted operating profit below market expectations. Blames more cautionary client spending and elongated sales cycles. H1 rev up 15%. LFL-constant currency rev down 6%. [SP=NA Cap=NA]
◄Circle Property (CRC)► sells its largest remaining asset for c.£12.3m. Net proceeds will be returned to holders, as announced. Will seek to de-list. [SP=NA Cap=NA]
◄Avation (AVAP)► guides FY-June significantly ahead of market expectations due to "a combination of factors such as lower than anticipated aircraft transition costs, lower administration and legal costs, improvements in finance income, recognition of gain on an investment in a listed airline". [SP=115.92 Cap=82m]
In line: WEB
MrC - as always, thanks so much for posting these superb early summaries, very much appreciated.
I'll get stuck into Kin and Carta (LON:KCT) now.
I don't understand how Cineworld (LON:CINE) shares have been allowed to continue trading, since the company has been saying for months that there's unlikely to be any value in the shares once it restructures the enormous debt mountain.
As you mention, CINE is even more specific today, including -
... based on the proposals received to date, it is not expected that any sale transaction will provide any recovery for the holders of the Company's equity interests...
the Company does not believe that there will be sufficient creditor support for a Plan that contemplates any recovery for equity interests, and it is therefore not expected at this time that any Plan will provide any recovery for holders of Cineworld's existing equity interests.
Surely they will have to suspend/cancel the stock market listing now, since the company has explained even more clearly than before, that they're worthless?
After that, I'll look at some older items from earlier this week.
Regards, Paul.