Small Cap Value Report (Fri 24 June 2022) - DVRG, TWD, RPS

Good morning, it's Paul here on my own today. Fridays are usually quiet, so Graham's here Mon-Thu, just so you know what to expect. Today's report is now finished.
Agenda - hopefully not too many bombshells today, as I'm hoping to catch up on a couple of things from earlier this week.
Deepverge (LON:DVRG) - readers were yesterday discussing apparently encouraging FY 12/2021 results. I had a dig under the bonnet last night, and discovered a Citroen 2CV with worn big ends, needing an overhaul, not a Rolls-Royce! I would steer well clear of this. In particular the £10m placing monies have gone in less than a year, and it's now using desperate-looking short term loans.
Trackwise Designs (LON:TWD) - readers asked me to look at a trading update today (revenues down, but profits in line with expectations). I was expecting to conclude it's another jam tomorrow share, but from an initial review have come away intrigued. This looks worthy of further research, and do please post a comment if you know the company well. Speculative, but looks potentially very interesting I think.
RPS (LON:RPS) - a positive update, and broker raises FY 12/2022 forecasts, for this international consulting group. Valuation maybe about right? I wouldn't be inclined to chase this one, given the macro situation. Although RPS does seem to operate in sectors that could be resilient. Gross debt is a bit higher than I would like, and there's negligible NTAV backing.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Deepverge (LON:DVRG)
10.5p
Market cap £23m
Final Results
This was mentioned in yesterday’s SCVR comments section, by Chris1011, and chrisgb, asking me to check it out.
The headlines look good - revenues up 107% to £9.3m, and almost reached EBITDA breakeven, after years of heavier losses.
It raised £10m at 30p per share in June 2021, so the shares at 10.5p could be a bargain.
However on closer inspection, I’m not at all happy with the numbers, and think people should be cautious, and research this share very carefully before plunging in.
Where’s the cash gone?
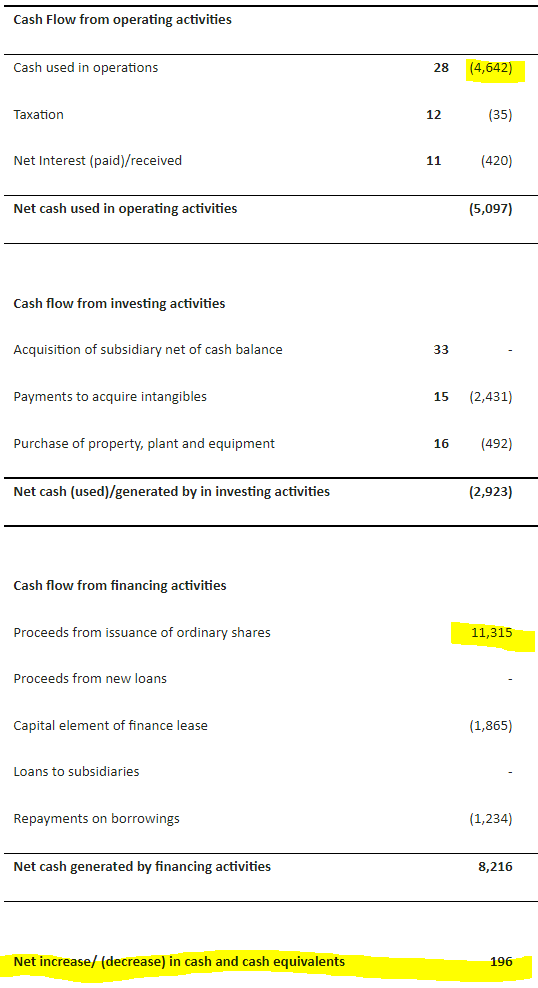
It raised £10m in June 2021, but by Dec 2021 year end, there was only £1.85m left. Where’s it gone? Take a look at the cashflow statement, which shows that DVRG burned £4.6m in operations, and capitalised £2.4m of costs into intangible assets. A further £3.1m cash outflow relates to leases & repayment of borrowings, plus a few other bits & bobs, and that’s the whole £10m fundraise money gone.
Here's the cashflow statement - as you can see, it raised £11.3m in fresh equity during the year, and burned through the whole lot, leaving just a £196k increase in cash for the year as a whole -
.
Excessive receivables
Note 28 shows that there’s a hefty £3.2m depreciation and (mainly) amortisation charge. Hence EBITDA is meaningless. The company isn’t anywhere near breakeven, as EBITDA suggested, it’s still heavily loss-making in both P&L and cashflow terms.
Note 28 also shows that receivables grew by £5.07m to end the year at a huge £6.8m (relative to annual revenues of £9.0m). Put simply, what that means is that most of the revenue booked for FY 12/2021 has not actually been paid for by the customers. It’s instead sitting in receivables, unpaid.
The auditors have signed off the accounts though, so presumably would have checked that the receivables have actually been paid? Maybe, I don’t know.
This suggests that large sales must have been booked in H2, and not paid for by the year end. That could just be a timing issue, or possibly something worse - e.g. large lumpy sales booked just before the year end.
Assuming that receivables turned into cash in 2022, then the company’s cash position should have improved from £1.85m at end 2021.
The commentary in the strategic report confirms that the company may require additional funding.
New loan facility
Was set up in March 2022, suggesting that the company hasn’t got enough cash. It’s surprisingly large, at up to £25m, and is a 3-year mezzanine loan from Riverfort Global Opportunities PCC Limited, and YA II PN, Ltd - never heard of them, but it might be worth googling them.
The terms of this large loan facility are provided in note 35 - Post balance sheet events.
DVRG drew down £4.0m initially in March 2022 - why did it need to do this, since the large receivables should have been paid by then?
The terms of this facility look expensive, and maybe a sign of desperation?
The loans are convertible, and have hefty quantities of warrants attached, priced at 20.0p for the initial drawdown. What this does is cap the upside for DVRG shareholders, since if the share price recovers to 20p+, then the lender will be motivated to convert, exercise warrants, and thereby limit the upside beyond 20p through selling into the market.
Alarmingly, the initial £4.0m drawdown has to be repaid quickly, in just a few months -
The initial drawdown is to be repaid by the payment of £500,000 on the 16th day of each month for five months commencing from 16th October 2022, with the balance of £1,500,000 being repaid on 16th March 2023.
My opinion - this looks a can of worms to me. The company clearly is using fairly desperate & expensive short-term funding, when it shouldn’t need to, if the receivables had turned into cash. This makes me suspect that the figures could turn nasty in future, with a big write-off of receivables maybe?
What I would expect to see next, is a PR splurge, to ramp up the share price to 20p+, so that fresh equity can be raised, and lenders persuaded to convert loans, and exercise warrants. What are the chances of that succeeding in this bear market? Very low, I suspect.
Overall, I’m staying well away from this share, it looks awful. In a nasty bear market like we currently have, investors might not be willing to keep putting in fresh cash for jam tomorrow shares, hence they're best avoided I reckon. It wouldn't surprise me if DVRG goes to zero by next year - even if it doesn't, why take the risk?
I appreciate this will be uncomfortable reading for holders, but I've got to tell it how I see it.
.
Trackwise Designs (LON:TWD)
53p (down 12% at 08:19)
Market cap £20m
We’ve only looked at this share twice since it listed in 2018, and came away underwhelmed both times, due to high valuation & jam tomorrow numbers/commentary in the past.
Wolfspirit has asked me to look at today’s trading update, and Quilleron has added some useful background information in the comments section below, thanks for that.
Trading Update
Trackwise Designs (AIM: TWD), a leading provider of specialist products using printed circuit technology, provides an update on current trading for the year ended 31 December 2022 ("FY22").
Reduced demand from electric vehicle maker(s) in the UK.
Revenues below previous expectations (no figures provided)
More positively, adj operating profit, and PBT are in line with market expectations (that’s unusual, but it says due to contractual terms, presumably for minimum order quantities?)
Order book is now £4.6m (for delivery in FY 12/2022), so together with revenues of £3.3m YTD (end May 2022), that implies FY 12/2022 revenues of at least £7.9m (assuming no slippage into 2023, and there could be new orders maybe?) - roughly flat vs £8.0m for FY 12/2021. Finncap is forecasting £22.1m revenues for FY 12/2022 though, which looks way too high, given what the company has just said.
Cash received of £3.2m re an asset funding loan, but no actual cash balance or net debt figure is provided, an annoying omission.
New factory at Stonehouse (freehold) sounds almost ready, which will significantly increase production capacity, initially prioritising electric vehicle parts.
Looking through previous RNSs for Trackwise, it announced net debt of £4.16m at end Dec 2021. However since then it raised fresh equity at 80p per share, raising about £5.5m (I’ve estimated expenses and deducted them from the reported £5.86m before expenses).
My opinion - you’re probably expecting me to say Trackwise is a jam tomorrow, over-priced speculative thing, as it has looked in the past.
But actually, this share is starting to look quite interesting, for more risk tolerant investors, due to -
- Market cap has now fallen to a much more reasonable £20m
- Production is already happening, with a potentially big contract, and £8m revenues in 2021 is not bad.
- New factory to increase production capacity, almost ready to start.
- Modest losses of £569k (PAT) in H1 2021, and FY 12/2021 looks to be in a similar ballpark, per trading update of 28 Jan 2022.
- The cash burn is mainly capex for the new factory, not so much trading losses, so that’s fine for a small growth company.
- Interesting pipeline for its innovative IHT product, of 95 customers.
On an initial review, I think this share is worth a closer look. The key point for readers to research, is what the products do, how appealing they are to customers (the big order from an EV maker suggests they’ve got something good here), and what the competitive landscape is. Also, is the product patented, which is probably key? If so, how long for?
It doesn’t seem to have published FY 12/2021 results yet, which is terribly late, so they’re due out imminently. They were similarly late last year I note.
Finncap’s forecasts look too aggressive, but it says these will be amended when the FY 12/2021 results are published (probably next week I’m guessing, or the shares would need to be suspended I think?). So I'll keep my eyes peeled for the 2021 results, and review them next week.
I’m intrigued by this company. Am not really looking for jam tomorrow shares right now, but this is on the cusp of scaling up production, so the jam could actually be served up (on toast?!) imminently.
I’ve just found some interesting info on the company’s website, including patent info, here.
If this IHT product (large, flexible printed circuit boards) takes off, and assuming the IP is watertight, then this could get very interesting. I’m tempted to have a little punt here.
.
RPS (LON:RPS)
114p (up 4% at 10:42)
Market cap £317m
RPS is a diversified global professional services firm of circa 5,000 consultants, designers, planners, engineers, and technical specialists.
As an established technology enabled consultancy, RPS provides specialist services to government and private sector clients.
RPS, a leading multi-sector global professional services firm, is today issuing a pre-close trading update ahead of its H1-2022 results on Tuesday 9th August 2022.
PR headline -
Better than expected trading and positive outlook
Figures given today are for the management accounts to May 2022 (5 months of FY 12/2022).
Overall - “Strong trading”, “encouraging”, and “ahead of the Board’s expectations”
Revenue up 12% on LY (constant currency)
Profit margin - “c.100bps of margin improvement” - it depends what this means, gross margin, operating margin, net margin? Looking back at H1 last year, it refers to 5.6% adj operating margin in the highlights section. So it looks to me as if the company is saying that’s risen to c.6.6% this year in H1, which would give a useful profit uplift of about £2.6m by my calculations vs H1 LY.
Growing order books & increasing headcount.
North America is the only area not growing, due to slow private equity activity, and delays to Govt infrastructure projects (starting to improve now). Note that N.America seems only a small part of the group.
Outlook & valuation - sounds good, but note that it hasn’t said anything about full year market expectations, so I assume that stays the same, but is perhaps de-risked by strong H1 trading?
Actually no, Liberum has helpfully issued an update today, and has raised profit estimate by 7%, to 7.3p adj EPS (fully diluted for share options).
That gives a PER of 15.6 - not exactly a bargain, in these uncertain times.
Positive Outlook
The Group's contracted order book at 27 May 2022 was up 8% on December 2021 and 12% on May 2021 and continues to be supported by the very positive market trends in urbanisation, natural resources, and sustainability.
Following the strong performance in the Period and the growing contracted order book we expect this momentum to continue in the second half…
"There remains clear demand for our expertise in our areas of focus - including renewables, project management, transport infrastructure and sustainability - and we are well positioned to continue to benefit from the positive market trends in urbanisation, natural resources and sustainability well into the future."
Balance sheet - nothing is said about this today, but I’m checking everything, given the potential for a recession, and higher interest rates, which usually triggers banks drawing in their exposure.
The last balance sheet for RPS was as at 31 Dec 2021, and it’s adequate, but not great.
Writing off £340.8m intangible assets, takes NTAV down to only £7.8m.
The current ratio (working capital) is adequate at 1.19 - remember there are no inventories at a company like this (consulting business), so it can run a lean balance sheet much more easily than companies which sell physical goods.
Note there was also £53.6m in borrowings in non-current liabilities, although largely offset by cash of £40.1m on the year end date - probably a favourable snapshot.
Hence net debt of £13.5m would likely be considerably more at various times of the year & month, due to normal cashflow swings for a business of this size.
I wish companies had to report average daily cash/debt, which is crucial & much more meaningful information, that not many companies actually report because it’s not required. It should be, so there’s a suggestion for an improvement to accounting disclosure requirements.
Overall then, it’s not the best balance sheet, but not a concern either, providing business holds up in any possible imminent recession. If business were to dry up, then the bank facilities might become an issue, possibly? Although in that scenario, receivables would usually unwind, thus reducing bank debt. So it’s probably OK.
My opinion - if we’re entering an economic slowdown, as seems likely now, then I’m not sure I’d particularly want to own shares in a consulting group. That said, the company emphasises it covers lots of geographies, and sectors which sound like they would be resilient in a downturn, and the outlook comments seem strong.
It’s great to see a company reporting upbeat trading, but the question is, will that last? Hence personally I wouldn’t want to chase this one, at its current valuation.
Sector expert Simon Hedger @vodkaquickstep on Twitter, has pointed out the takeover potential here, and he’s got it right about that in the past with other companies, so that's something to consider.
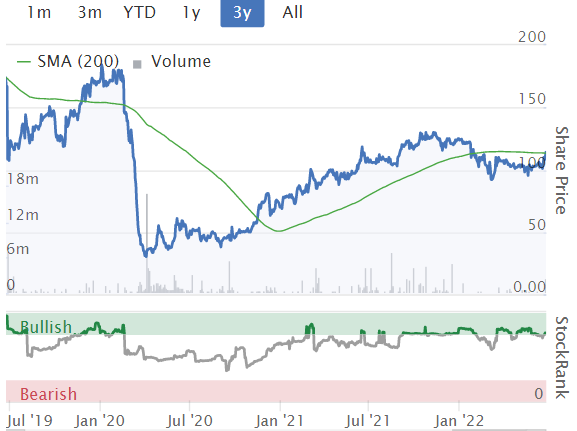
The 3-year chart below has been a lot more resilient than most small caps recently. Also note the strong StockRank, hovering just below the green upper quintile.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

42 comments
Liontrust Asset Management (LON:LIO) up over 6%
Chunky dividend in the offing soon
Thanks Paul for your thoughts on Trackwise Designs (LON:TWD)
This has been on my watchlist for a couple of years but the sp had always looked too high but now it is a quarter of the price last November. Today's drop on a warning regarding revenue but not profit at first seems to give me a good chance to take a toehold but two things hold me back:
1) Results to 12/21 - previously late - 23/6/20 with notice on 12/6 and 22/6/21 with notice on 9/6 - but this morning's RNS, an opportunity to give notice says nothing. I don't want to buy shares today if they will be suspended next Friday.
2) Yes, it says "adjusted operating profit, and adjusted profit before tax, in line with market expectations" but does not quantify these. The problem here is that it is quite a spread: Edison gives eps 1.6p whereas finnCap goes for three times that at 5p, hence the 3.3p average shown by Stocko. This may be pedantic but they do not use the word 'consensus' there, so is anything between 1.6 and 5 in line?
For those wanting to do more research there are presentations on IMC and the best for a general introduction is the one not on results but on the need to increase capacity (27/11/20) https://www.investormeetcompan...
Trackwise Designs (LON:TWD) did a plaing and token OO in Jan at 80p, a disgusting 45% discount. The rev f/c at the time (and until yesterday) turned out to be fantasy at £21.5m. Now the SP is 50p
Holders should not be surprised to be shafted again.
I previously held, including through the heavily discounted raise. This was frustrating as I'd bought in after the previous fund raise believing that was sufficient to get to profitability....
Anyway, there are 2 divisions:
The Integrated Harness (IHT) division - this is where the growth potential is. It has one key EV customer, Arrival, with whom they have a take or pay contract. Arrival, a UK company, listed in the US via a SPAC, is making progress bringing their buses and vans to market and has customers signed up. The journey to live production has had many delays but is now due to start later in the year.
An acquisition last year helped to scale the small and slightly profitable Integrated Circuit Board (ICB) division. This seems to be a bit of cash cow (on a very limited scale).
My concern is that whilst they describe multiple exciting use cases with lots of customer interest for IHT, very little progress, in terms of agreements being signed/pilots etc, has been made in the last 18 months. This is despite past pilot studies with large car OEMs. In addition, the factory and fit out is months behind schedule, so much so, that the costs escalated. This drove the equity raise.
In summary, I agree completely with MrContrarian's wise council.
There are many companies mentioned here that have large pension deficits. Presumably those that have a link to RPI are going to take a hit or are about to.
Saga (LON:SAGA) ( I hold)
I saw this comment from Investec yesterday.
UK motor insurers – Inflationary pressures to drive industry turn? - Industry pricing has lagged claims inflation ytd, but ONS data suggests price momentum is improving. Separately, consultants EY forecast an 18 point worsening in industry combined ratio in 2022, arguing a 25% increase in rate is needed to return the industry towards profitability.
Clearly this may account for some SAGA weakness but also suggests an inflection point on the insurance side. At least they have insurance!
As for cruises they should clearly generate a lot more than last year. Will it be as much as initial forecasts, I think unlikely. On heavily reduced 2023 numbers its not even on 5x pe now. The airlines are seeing strikes and staff shortages so if people want to go away, the relative attractions of cruises have probably increased.
It clearly has headwinds but the Roger de Haan last paid circa 292p for 1m shares. Personally, I think the possibility of Saga being taken private is quite real.
I have always considered Deepverge (LON:DVRG) in the most basic schoolboy terms to be Deepshit. Hope nobody is offended.
Hope you all enjoy the sun this weekend.
Michael
Begs question why we are interested in duds in this time. Are there no serious good companies that have been beaten up and now very good value. Not random subscribers having bought some story and trying to get insight into their naivety.
I'm underwater with lots of SCVR hopefuls Volex (LON:VLX) for instance and jury is well and truly out - sorry don't have 5 years retire by investing - well not with Volex anyways.
Stock does lots of screening tools so lets pick some winners and not random RNS losers.
Lamprell (LON:LAM) That's a horrible profit warning. It's not often a share price falls by 70% in a morning.
Great photo Paul, keep up the good work.
Eneraqua Technologies (LON:ETP) FY22 results roadshow presentation video & podcast. These were their maiden set of results post IPO in November 2021. Revenues up by 148% to £36.2m, EBITDA +319% to £5.55m. Cash £3m. FY23 revenue order book covered at 95%. Obviously tremendous ESG credentials. They provide energy consultancy on end-of-life gas, oil or electric heating and hot water systems to replace with the most efficient communal heating whether gas or ground/ air source heat pump solutions. On the water side they provide efficiency upgrades for utilities and commercial clients. Their offering is underpinned by their own patent-protected Control Flow HL2024 which accurately controls water flow in water and heating systems.
Separately we have a few webinars coming up register for any/all here, chronologically:
IG Design (LON:IGR) full year 2022 results with the new management team, Stewart Gilliland, Executive Chairman, Lance Burn, Interim COO and Paul Bal, CFO this Tuesday 28 July, 11am.
A Private Equity funds feast over two days, titled Exploring Listed Private Capital Pt 1 & Pt2:
Tuesday 5th July 2pm, NB Private Equity Partners, BMO Global Asset Management and Gimv will each present for 15 minutes.
Thursday 7th July, 2pm: Oakley Capital Investments (LON:OCI), CVC Credit Partners and CapMan
Sosandar (LON:SOS) full year 2022 results with Ali Hall & Julie Lavington, Co-CEOs & Steve Dilks, CFO Tuesday 12th July, 12.30pm.
We hope you can join us, register for any/all here.
Talking of CVs Lamprell have come up as a Fiat 500. My least favourite car (its a long story involving a ski trip, a man pretending he couldn't speak English and Hobson's choice). Whilst we always say things are never different this for me is a genuine surprise. By good fortune I don't hold at the moment.
Paul - any thoughts on Saga
Reviewing my portfolio and it’s the one that worries me as it’s not my normal type of holding .
Excuse the pun but it looks a big ship to get moving .
Must admit I bottled it and sold 25% of my holding yesterday and that is reserved for top up of my 5 star golden rated shares ( crest chic / avingtrans)
Bottom line is I’m much more confident in other holdings so probably going to switch .
There you go , just talked myself into what to do , how cathartic to write it all down .
Is saga just going to be a saga ? Feels that way .
Hi planetx,
I don't normally comment just on share price movements, especially at the moment when things are going all over the place, including some ridiculous moves (such as Volex [I hold]) which should have gone up on good results & excellent outlook, but instead has been dropping.
We're not in a rational market right now. People are trying to factor in inflation/recession risks, but I'm also seeing capitulation-type selling, where it makes no sense at all, and is not linked to trading updates in any rational way.
Maybe people think (wrongly) that Saga (LON:SAGA) (I hold) would be vulnerable to higher interest rates, but its borrowings are actually at fixed rates, without the usual bank covenants on trading.
Also higher oil price - not an issue, as they hedge their fuel at the time of starting to sell cruises.
Higher wages & costs - yes, but it's put up prices to cover this.
Rich pensioners are not likely to cancel cruises because of higher utilities & food prices, in my opinion.
So, as far as we know, SAGA's performance should be OK - although note that the broker forecasts have been coming down a lot - which might be why some people are selling, who knows? Although the upside from lower forecasts is that hopefully it meets expectations, rather than issuing a profit warning.
Long-term it should be fine. Short-term, it's anybody's guess, same with most shares right now. I think we're getting some fantastic buying opportunities at the moment, for people with the patience to ride out current volatility, and the potential for a recession that could hit earnings in 2022 and 2023.
Owning shares is all about owning all future earnings & cashflows though. So the odd bad year due to negative macro factors is inevitable, and gives us the best long-term buying opps.
Regards, Paul.
Paul
Thanks for taking the time to reply , much appreciated .
I’m super confident on my core 5- 6 holdings and saga is in my non core group so think I will let it run , even if the ship sinks further not really going to affect my overall position so I will cruise along with it for now .
Dave
I wonder if the broker forecasts have been coming down not because of the cruise and travel side of the business, but the insurance side?
There's a recent Bloomberg article that said that insurance premiums in Q1 2022 has been the lowest ever in 6 years.
Also that as used car prices go up, spare parts cost more, labour costs more, longer wait times for repairs (so courtesy cars paid for longer), that car insurers are facing unprecedented cost increases.
Along with that, Aviva warned that bogus insurance claims could be increasing, due to cost of living squeezes.
I am re-evaluating my Saga (LON:SAGA) holdings at the moment, albeit it still seems very cheap, on a long term horizon. But it could always get cheaper based on short term headwinds.
(I hold in the Boon Fund)
£Saga is a highly risky play no doubts about that , for "debt laden companies" like this there is zero downside protection - and solvency worries of any kind can quickly lead to shareprice collapse. If there is any chance Saga will need to raise more funds and shareprice is depressed then existing shareholders who bought higher up will likely do very badly on their initial investment (they may get lucky if they top up at lowpoints). So great upside potential for saga but anyone who is holding should know there is a % chance they lose their shirt here - i do hold a bit of saga. Obviously higher interest rates generally for comapneis like saga is really bad news. Note i am not saying saga has any solvency concerns at all but facts of the matter is that debt will need refinancing at some stage even if that is not anytime soon. There lack of being able to provide any curent year forecasts (other than being above breakeven) really doesnt help their case infact if they expect to be making £50 mill profit not telling us what their expectations are so they can be tracked in year is unnaceptable. Hopefully they eek out enough in both segments to pay down some debt and hopefully progress towards a more benign environment next year - with high interest rates - high fuel costs - less spending money for lots of peeps and a struggling insurance side of the business they are unfortunately facing a few headwinds at present.
Hi rmillaree,
As you know, I place huge emphasis on balance sheets & avoiding excessive debt. Hence I wouldn't have touched SAGA (I hold) if there was any chance of solvency or finance problems.
The debt is medium-dated, and it also replaced all the bank debt with another bond issuance fairly recently, which is now looking very smart indeed. There's also a cash pile which is (from memory) not far off the size of the remaining, part-repaid earlier bond.
I think if you look into the detail of the borrowings (expiry, terms, etc) you'll better understand that solvency risk is extremely low, because SAGA doesn't have to worry about bank covenants, or imminent repayment of anything.
I agree with your general point about debt, but you're ringing an alarm bell on the wrong company, which is not at risk. SAGA has deliberately set up all the debt safely, so that it won't have to call on shareholders again. It looked over-cautious at the time, but is now looking a master-stroke.
Leave it to me, to flag up the companies with problem debt, as I'm all over that issue, more so than ever! :-)
Regards, Paul.
Saga (LON:SAGA)
I think we will have to agree to disagree here - to be clear here i do not see any imminent concerns about the business being able to survive - but i do stand by my comments that from my viewpoint there is no shareprice floor here is the company may need to back to the market cap in hand at some stage - you cant argue that the position is not continually worsening too ref prospects (details below) . Its not the worry of insolvency just the worry that at some stage they might have to raise some cash if curent trends continue to worsen.
I do hold this share at present (losing position) so the fact there is risk does not mean i think the worse case will actually happen. You just have to look at the revolution bars situation where by the time they raised finance the shareprice was shot to pieces - so my fear would be similar.
2023 eps was expected to be 68p in january and is now expected to be only 25p !
2024 eps was expected to be 86p in january and is now expected to be only 44p
Lower profits will directly flow through to less ability to service their debt - so its clear the "safety net" that did exist back in january simply isnt as big now as it was and i like a decent safety net where there is big debt - the numbers have clearly changed for the worse and therefore risk is up imho. There are covenants in place too so not sure what they need to book to be fine in that regard - they have reasonably shiny new ships here and there should be plenty of cashflow coming in to pay off those ships so hopefully you are right that this is a complete non issue with peeps on ships the debt should be manageable- i personally do see an element of risk here that company could raise more funds "if" things take a further turn for the worse and if that were to happen my specific worry is teh price would tank in advance of that news.
Hi rmillaree,
Re Saga (LON:SAGA) (I hold)
You're right that lower earnings estimates will mean lower (but still positive) cashflow, so slower debt reduction. Fair point, and we agree on this.
Due to the bond refinancing, the liquidity position is very strong - at the last update, on 27 Jan 2022, SAGA said (my bolding) -
Strong financial position following actions taken over the last 12 months:
o At 31 December, Available Cash of £151m and £100m undrawn revolving credit facility.
o Available Cash at 31 January 2022 expected to be broadly in line with the half year.
[note that this implies a rise in available cash to £175.3m, which is what the interim results said as at 31 July 2021]
So SAGA is sitting on a big cash pile, which is surely way above what it would require, even in the gloomiest scenario.
As regards the bonds, the first one is repayable in May 2024, so that's 2 years for it to raise the money. But actually, it already has the money to repay it in full!
The original £250m debt was £100m part-repaid (see RNS dated 22 June 2021) in a tender offer, so there's now £150m outstanding, to be repaid (or refinanced in May 2024). The remaining £150m bond costs 3.375% p.a. fixed rate interest, so annual cost of £5.1m. My notes, from when I went through all the detail, say "no covenants" on this bond. I think our resident bond expert said there were some technical covenants, but there's nothing related to the group's actual trading, which is what matters.
Ship loans - the lender proved very accommodating during covid, deferring repayments, but restricting payments of divis until up-to-date (perfectly reasonable, and SAGA doesn't want to pay divis for now anyway).
I've dug out my old notes, only got notes on the first 2015 ship loan, but it's also fixed rate, of 4.31%
My apologies, I'd forgotten that there actually are covenants on the ship loans.
The main one is Trading EBITDA: Debt service costs has to be above 1.2 (as at 31 July 2020, it was 3.8). I think this is interest, and capital repayments?
I'm not sure if debt service costs is just the interest, or the capital repayments too? I think it's probably the total repayments, which would be about £43m p.a. from my rough calculations. So the covenant of 1.2 times that means EBITDA needs to be above about £52m p.a.
H1 results seem to show "Trading EBITDA" of £29.3m. But that period includes mostly the second lockdown, when cruise & your were both heavily loss-making. Hence that should be a low point fro EBITDA, but would still (annualised) be enough to meet the ship loan EBITDA covenant.
The two ship loans total £516m as more recently reported at 31 July 2021. At 4.3% interest, the annual interest charge would be about £22.2m.
The interest cover covenant on the ship loans (not the bonds) says that Trading EBITDA must be above 2x, which means over about £45m, so a bit below the above level of about £52m for the other covenant (these are all just rough figures, as I don't have bang up-to-date facts/figures).
Put all that together, and it seems to me that the ship loan covenants are set at a level where PBT would need to be negative, which you can see from this table in the last interims results (doubling the figures to annualise them), in order to possibly trigger a covenant breach -
.
Would it matter if the ship loan covenants were breached? It would hurt sentiment for sure, but the lender would almost certainly give a covenant waiver again, as it did twice in both 2020 and 2021.
Remember that the ships are now in use, generating cashflow. Latest broker consensus is for net (of tax) profit of £35.7m, adding back corp tax of 25% and that's £47.6m PBT. Add back depreciation & interest charges (of about £60m p.a.) and EBITDA comes out at over £100m for the current year.
Hence it would take a profit miss of about £50m this year, against lowered forecasts, to risk breaching the ship loan covenants. That seems unlikely.
Put all that together, and I think it's very unlikely that SAGA would need to return to shareholders for more cash. The only scenario where that might happen, would be if covid became a major problem again, requiring a long shut down of cruise, and no Govt support.
Anyway, thanks for cajoling me into looking again at the numbers, it was a useful exercise. I'd forgotten about the cruise loan covenants, but don't see that as a problem, having stress tested it above, unless covid returns.
On balance then, an equity fundraise at SAGA looks highly unlikely, which is my main point. In a recession, I think there are many other companies, dependent on bank financing (which of course SAGA isn't), which would need to tap shareholders.
McBride (LON:MCB) springs to mind, which I think could be in serious trouble now with its heavy bank debt, and collapsed share price.
There are plenty of companies which loaded up with cheap debt in the zero interest rate period, which may come to regret it now things are tightening. SAGA shouldn't be one of them though, as its borrowings are fixed rate, and the bonds don't have trading covenants. (ship loans do, as it now turns out! Sorry again for missing that earlier, but they're set at a level which is highly unlikely to be breached).
Regards, Paul.
£Saga
oustanding post Paul thanks for taking the time to highlight the salient points - i would agree there appears to be no imminent dangers here particualrly . - at least if saga can get its mojo back or tickover enough for debt issues to ease then hopefully tthese concerns will subside - despite holding company are still in my bad books for coppiong out ref providing an estimated range of earnings this yearb - however sketchy imho they are of such size that we should have been given something to work with - not sure if them saying nowt while winking at the brokers is enough to ensure that brokers have "downgaaded sufficiently" that does leave a bad taste in my mouth as i would be 100% certain they had a target range in mind when they told us they couldnt/woruldnt tell us.
Looking briefly at the "debt" as that is the elephant in the room
Looking at the annual report it appears the ship loans are being paid in "equal installments" between now and 2031/2032 (with covid catchup) - so presuming thats 10% lower debt each year i am happy with that - sometimes with "fixed cash repayments covering capital and interest" the loan doesnt come down much to begin with so nice to see that 10% of that debt will be gone each year (presuming my presumptions in that regard are correct) - basically long hp at decent rates and interest should presumably come down 10% each year other things being equal so thats al fine and dandy.
Ref the the bonds - that is kinda the noose around the neck of the company - £400 mill is quite a wad - albeit as you say they have the cash wad - i think a bit like SCS they really ideally need to keep that cash wad handy just to stop everyone hyperventalating over the debt. I would be much happier if this was lower - we are where we are though and it should certainly be serviceable. Note in total though with ship loans and bonds they do have £572 mill to pay betwen 2-5 years - hopefully bond rollovers wont be a problem and hopefully insurance will churn out enough "clean profits" that they can eat into that debt. At present i would be happy having nil dividends with debt being paid down even if they are in a position to resume divis.
Hi rmillaree,
Re Saga (LON:SAGA) (I hold)
Thanks for the reply. I think we've done a good job between us, thrashing this out! Useful exercise, so thanks again.
Regards, Paul.
rmillaree " I stand by my comments that from my viewpoint there is no shareprice floor here..." I think at times like this it is best to remember that all companies have a share price floor! The worry is it might be zero
Zalando
A big profit warning after hours last night. They're currently down about 15%. They had still been trading on a much higher valuation than Boohoo and Asos. The usual story of slower growth. A quick look at the numbers suggests -15% is quite kind! Its hard to gauge at what point its "all in the price".
All the consumer discretionary names are in a very difficult place currently. When a JD Sports or Next trade at circa 11x PE, it's very difficult to make headway at the smaller end.
With Consumer Discretionary shares right now feel if buy you have to take a 5 year view and and try to judge what the upside could be in 5 years i.e what share price would Boohoo have to be in 5 years to justify buying today ?
In the midst of all the dire news, it was great to see "ahead of the Board's expectations" update from RPS (LON:RPS) this morning (I hold). 12% growth in Fee Revenue, strong demand, growing order books and margin improvement. Expecting the momentum to continue into the second half.
Hat tip to Graham (awesome to have you back on SCVR), as I first learnt about RPS (LON:RPS) from an in depth article by Simon Hedger on Graham's former Cube Investments website (now Monopoly Investor substack).
I don't recall all of the details but the gist of it was making the case for a likely takeover at some point due in part to the history of the CEO, John Douglas who was at the helm of Coffey when it was taken over by US based TetraTech in 2015.
Interestingly, TetraTech (who also acquired WYG in 2019) have made no secret of their desire to add UK water consulting capability to their portfolio.
Whilst it's never a great idea to hold shares purely on the basis of potential bid interest, this is one I'm happy to keep tucked away especially given the rarity, in today's market, of an upbeat trading statement.
My thanks to peterg for your post yesterday on the “green blob”
I now fully understand what Paul said yesterday in response to my post on £SNWS. I will use the Green blob to write to the Stockopedia team this morning in the hope that they will update the financial data and in particular the Z score which is very misleading.
Hi portugull,
Apologies for any confusion I caused!
Hopefully you can report back when Stocko HQ reply to you, which is usually very quick. I suspect they'll say Z-scores are worked out on annual results.
Regards, Paul.
"Riverfort Global Opportunities PCC Limited, and YA II PN, Ltd - never heard of them, but it might be worth googling them."
Even better they have their final results out today. Riverfort Global Opportunities (LON:RGO)
YA are under the same umbrella. Death spiral providers to all manner of shitty AIM companies. Not the worst death spiral provider, but they will put unrelenting downwards pressure on share prices. They won't necessarily smash it to pieces like the worst death spiral providers.
I'm long Riverfort Global Opportunities (LON:RGO) as they are about the only people who make money from the detritus at the bottom end of AIM.
How interesting, thanks BlueFrew.
I've not an expert in it, but have come across death spiral financiers before. Their modus operandi often seems to involve complicated arrangements which involve quietly forward selling shares in the market, then banking a profit on the short position through new issues of shares at much lower prices once the company has its back against the wall.
I can't work out how Riverfort is doing it in the case of DVRG, since the conversion price and warrants all seem to be at a 40% premium, which means they wouldn't want to convert loans, or buy the warrants either, now the share price is 10p.
It's confusing, but in itself death spiral type funding is a massive red flag.
As you say, it means the equity is likely to have constant downward pressure on it.
Unless something earth-shatteringly good happens with the company (which is possible), as things stand I would strenuously avoid DVRG. Risk:reward looks really bad.
Regards, Paul.
Hi Paul, the information is buried very effectively within the £DVRG financing RNS (17th March), but the important bit is this:
"The Company may elect not to repay the Advances that fall due (see below) and, in such circumstance, the Lenders will have the option to convert the Advance's principle and interest and any relevant outstanding fees into the Company's Ordinary Shares at a price equal to the lower of (a) 80 per cent. of the average of the two lowest VWAPs in respect of Ordinary Shares during the 10 business days immediately preceding the date of the Conversion Notice and (b) Fixed Premium Placing Price up until the Maturity Date."
The 40% premium and the warrants are clearly just spoofs, so they can pick them out as highlights at the head of the release. The actual details get buried way down in the weeds.
Hi BlueFrew,
Brilliant, thank you (and well done!) for your further research on the death spiral at Deepverge (LON:DVRG)
Regards, Paul.
"... in such circumstance, the Lenders will have the option to convert the Advance's principle and interest ..."
Hmmm, that could be an even bigger problem then, because even if they convert the principle, the principal will still be outstanding. Say that one of the Lender's principles is to never invest in a company that doesn't know the difference between "principle" and "principal". According to Deepverge, the Lender can convert this principle in to a holding of ordinary shares. Niiice! This would be a good deal for the Lender as it comes at zero financial cost and leaves Deepverge still obliged to repay the principal. On the other hand, this isn't really such a good deal for Deepverge shareholders, poor sods.
Forgive me for not taking this entirely seriously, but it sounds like Deepverge is verging on the deeply ridiculous.
I hope you cover Trackwise Designs (LON:TWD). Market has spoken on the revenue warning, but would like your eyes over the business please!
Difficult to comment I suspect with such a thin RNS from Trackwise Designs (LON:TWD) but a small revenue miss is being punished by the market. Essentially a company in a unique position of being able to print any-length flat flexible wiring cables that are lighter and easier to install than traditional cabling bundles - the future of cabling in EVs and aircraft. Once they've got their enlarged capacity completed at Stonehouse they'll be able to turn the presses at ever increasing speed.
So despite being 50% down I've bought a few more this morning as their IHT sales pipeline with 95 customers and opportunities has grown and the operational gearing will be significant once these (and they take a long time to come to fruition) come rolling in.
As ever, think of the future rather than the past but DYOR.
@paul , thanks for covering!
The tech sounds interesting - but it would come down to electrical performance issues.
The PCB length seemed to be the main feature, but I also liked the medical use. Being able to get micro circuits and antenna in one production cuts out joins. The promise of the tech is high. However it is a design level change, not a replacement - that embeds them with OEMs but increases the sales cycle. I am hoping this current market amplifies the negativity in the short term. I'll wait for the results next week - a 20% increase in profit gets smashed these days - so "on target" with a rev drop is surely worth another 20-30% drop in SP?!?
Paul - thanks for the slap in the face over Deepverge (LON:DVRG) . I have stayed away because of the divergent business areas. Now I have more concrete reasons to not be tempted by interesting tech.
Shareprophets think it's awful too.
Thanks from me too. I shall watch with interest - from the side lines - how this pans out.
Re iEnergizer (LON:IBPO) yesterday, a question to Bryaz and to Paul Scott today on something I don't understand. This may or may not be relevant to consideration of the company and its current position re value and plan to sell the business.
Brryaz commented yesterday:
the high increase in debt for IBPO was £100 mill which was then paid out
as a special divi 50p per share if memory serves i currently hold
I was on the point of asking Paul for an opinion on why the debt had gone through the roof and presumably as a consequence the book value/book value per share had gone through the floor. Following on from this, what does this do to the attraction /valuation of the company. I am at a loss because of my inexperience.
Been a relatively quiet week for me on the markets this week with the continuing slow grind down offset by some reasonable updates and announcements from some of my companies. I feel very bullish long term but not enough to add more funds to the market yet. The gas /oil issues of the winter scares me to put more in at the moment. I continue to not trade anything but continue to mainly hold BTB companies outside of the manufacturing space that are growing (for now.) Here's to a nice end of the week hopefully and a good weekend.