Small Cap Value Report (Fri 24 Nov 2023) - TM17, IKA, FIH, MTC, MACF, MBH

Good morning, just Paul here today.
I've got a lunch in Oxford today, so will have to rush out this report early. I'm meeting Tom Benyon, founder of charity ZANE, to hear an update on the situation in Zimbabwe, which I believe is particularly grim at the moment with another outbreak of cholera, and continuing hyper-inflation. Many thanks to those of you who support ZANE with monthly donations, it's literally keeping vulnerable people alive. It also helps me put my own problems into perspective, when I hear about Zimbabwe.
Right, gotta dash! Today's report is now finished. Sorry this has been such a rushed job, but I covered everything on the list!
Tune in for tomorrow's next thrilling instalment of my weekly podcast!!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries
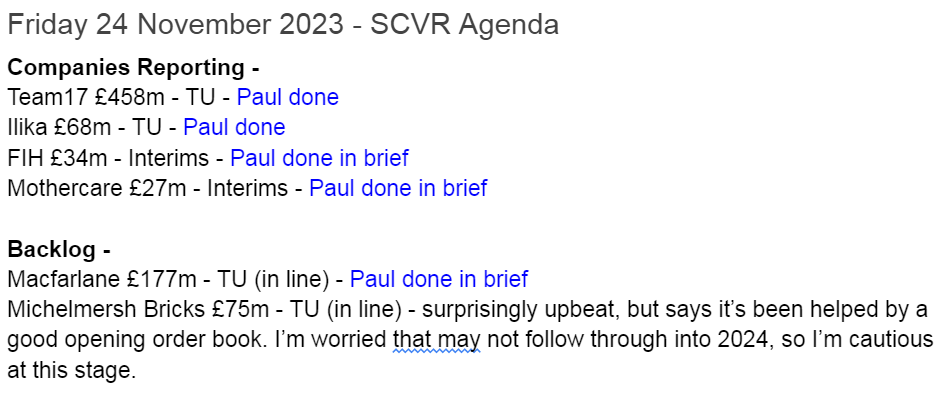
Team17 (LON:TM17) - 314p (pre-market) £458m - Trading Update (profit warning) - Paul - AMBER/RED on fundamentals, BLACK (profit warning) for spreadsheet
This looks like a profit warning due to various factors. I'm not keen on the computer games sector generally. Complicated accounts, and a lack of broker notes ended up making this quite difficult to untangle.
Ilika (LON:IKA) - Unch 43p (£68m) - Trading Update - Paul - AMBER/RED
Jam tomorrow batteries developer. Makes lots of encouraging-sounding noises, but it still hasn't commercialised anything. Could it be on the cusp though? I'm sceptical, but there's a chance it might surprise, just a complete punt at this stage.
FIH (LON:FIH) - unch 270p (£34m) - Interim Results - Paul - AMBER
Revenue up 17% to £26.7m in H1. Underlying PBT £0.6m (unchanged). There’s a heavy seasonal bias to H2 profits. Net debt of £3.6m (excl leases). C.£40m NTAV.
Paul’s view - a very peculiar group of companies. Not sure why it exists, or is listed anyway? Nicely asset backed though, and paying a 2.8% dividend. One for special situations investors maybe? [no section below].
Mothercare (LON:MTC) - down 4% to 4.5p (£25m) - Interim Results - Paul - RED
Better than I was expecting. H1 PBT £1.8m adjusted, or £2.0m statutory.
Balance sheet - big issues are bank debt, and pension deficit. So this is a special situation which hinges on them being able to refinance/reduce those liabilities. Hence high risk of dilution through a placing, if it’s possible to do one.
Paul’s opinion - a high risk special situation. Could go either way. I’ve been RED in the past, due to the high risk. I’m toying with easing that a little to amber/red, as there’s a possibility this might survive, and maybe even recover. Although on balance, I’ll wait until it’s refinanced before moving. So let’s stick with RED to reflect the high risk. [no section below]
Macfarlane (LON:MACF) - issued an in line update yesterday for FY 12/2023, despite weaker volumes and pricing. Mitigated through new business wins, management of pricing & costs, and 3 acquisitions (all performing well).
Sorry I don’t have time to review it in more detail, but see the archive for plenty of coverage. We like this share, good value/GARP business with conservative accounting. Shares never seem to go anywhere, but zoom out to the long-term and it’s been a 7-bagger in the last 11 years, and pays divis on top. I think this is an excellent choice for long-term investors.
Michelmersh Brick Holdings (LON:MBH) - see very brief comment in agenda above.
Paul’s Section:
Team17 (LON:TM17)
314p (pre-market) £458m - Trading Update (profit warning) - Paul - AMBER/RED on fundamentals, BLACK (profit warning) for spreadsheet
Graham normally covers this computer games developer, sounding mildly positive (but viewing it as AMBER) in updates on 29 March, and 6 June this year.
Today it says re FY 12/2023 -
Revenues expected to be “modestly ahead of current market expectations”.
However, sales mix has been less favourable, with lower margins.
“Too slow to address some project overspends”.
Cost-cutting will benefit next year.
Impairments to be made against some games in FY 12/2023.
New guidance for FY 12/2023 -
Consequently, the Group now expects to deliver full year adjusted EBITDA of at least £28.5m, which includes non-cash title impairments of up to £11.5m.
Annoyingly, it doesn’t provide the previous guidance, so I have to waste my time now trying to find out what change this is.
Adj EBITDA was £16.5m in H1, and the interim commentary suggested an H2 weighting was anticipated. So the new guidance today implies a fall to c.£12m adj EBITDA in H2, which looks like a miss of possibly upwards of £5m?
However, will they be adjusting out the non-cash impairment charge of £11.5m mentioned above?
EBITDA is usually a particularly useless and misleading measure in this sector, because the up-front development costs of new games are capitalised onto the balance sheet. Although doing a little digging, TM17 seems to state its EBITDA on a more conservative basis, and leaves in the amortisation charge of development spend, so it's actually OK in this case.
TM17 capitalised £18.3m of dev spend in H1.
On checking the 2022 accounts, I think it must state EBITDA after amortisation of development spend (yes, it does). Note 8 to 2022 accounts shows development spend of £26.0m, but an amortisation charge of only £9.3m, so profits are being boosted considerably versus cashflow, by this mismatch.
This is complicated, and I don’t have full information, due to lack of broker notes.
Stockopedia is showing a broker consensus of £35.9m net (after tax) profit for FY 12/2023.
I’ve manually recalculated it, and I’m coming out with a PAT of c.£28m, assuming 25% tax, and assuming that the £11.5m impairment charge is adjusted out.
So it looks like a c.23% profit miss, would be my best guess, using incomplete information.
At EPS level, that would mean the consensus of 25.8p currently dropping to around 19.9p. What PER to put that on? 10-15 perhaps, which means 199p-299p per share. I haven't looked yet at the live share price, but suspect it will drop into that range today.
We’ll have to wait until next week to see how the Stockopedia broker consensus figures change, so treat my estimates here as provisional, and based on incomplete information.
Cash - it seems to have plenty of headroom, with a £45.2m cash pile at 30 June 2023.
Overall its last balance sheet wasn’t great, with only £16m NTAV.
FY 12/2024 outlook -
The Group has an exciting schedule of high-quality new releases planned across the Group in 2024, while back catalogue investments will continue to support revenue growth. Management will provide greater clarity on FY24 at the full year results, but currently expects to see an improved underlying trading performance compared to FY23.
Paul’s opinion - I don’t have enough information to form a definite view, but this is definitely a profit warning, which I’ve estimated at about a 23% miss against broker consensus.
So expect shares to fall.
I’m not that happy with the business model, and this is a horrible sector with dangerous business models of up-front heavy development spend, then a short and unpredictable sales window to earn that money back. Although back catalogue sales do help.
Also we’ve seen from other profit warnings in the sector, that online distribution platforms have become less generous with their payments.
There have been takeovers though.
Overall, I’m avoiding everything in this sector, and with a profit warning today, I’ll go with AMBER/RED.
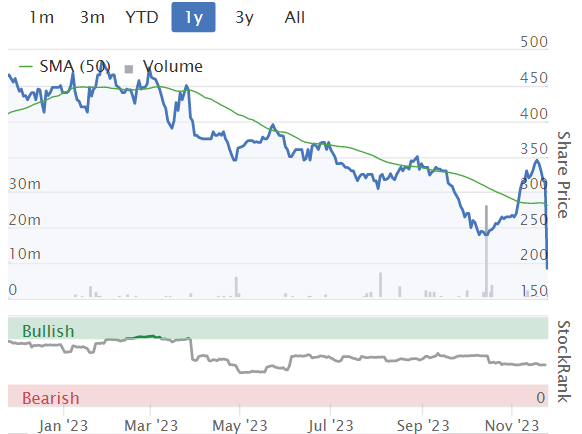
Update at 09:20 -a brutal share price reaction, down 42% to 183p at 09:21 - bad luck to any holders here.
Ilika (LON:IKA)
Unch 43p (£68m) - Trading Update - Paul - AMBER/RED
I’ve followed this innovative battery development company for many years. It floated in 2010, and has been promising great things ever since, racking up losses every year, and repeatedly raising fresh equity to burn.
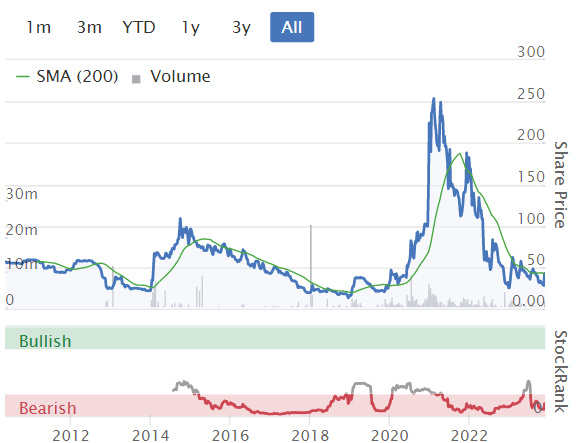
The jagged share price below shows the impact of numerous upbeat-sounding updates, and short-lived booms in share price when a speculative frenzy takes hold from time to time, before fizzling out again every time.
The 2021 boom & bust was particularly pronounced, I wonder if that’s where some of the bounceback loans ended up?! Either IKA, or Bitcoin maybe?!
Today Ilika says -
Ilika (AIM: IKA), a pioneer in solid-state battery technology, provides an update on trading and notice of results for the six months ended 31 October 2023 (the "Period").
Shipment of batteries to customers have started (at long last).
“Key milestone” with licensing agreement (Aug 2023) - Cirtec Medical (USA), sounds like it’s limbering up to start production.
Goliath Programme - positive noises, but it doesn’t seem to have started production yet.
Prototypes going to car manufacturers next year for evaluation.
H1 revenue £1.3m higher due to grant receipts, not expected to repeat in H2.
H1 EBITDA loss of £(1.9)m
Cash looks OK for now, with £13.2m (although down by £5.4m in a year) - the company has a long history of continuous cash burn.
Paul’s opinion - it’s more of the same. Jam tomorrow, promising sounding progress, but nothing of commercial value yet.
I’ll go with AMBER/RED, due to the extremely slow development of these batteries. Unless you’re a sector expert in innovative batteries, then this share is just a complete punt.
Ilika sounds close to achieving commercialisation, but that’s always been the case in the many years I’ve followed this share.
£13m cash in the bank means another placing is not likely until 2025 or 2026, thankfully.
For people who like a speculative punt, this one could be quite fun! Personally I wouldn’t risk money on this unless I was relaxed about seeing it wither away. Although look what happened in 2021 - in a bull market, and supported by rampy-sounding announcements, this type of share can provide some excitement. The trick is obviously to bank the profits before the party ends. One day, who knows, it might commercially succeed, and the fact that credible third parties are backing it, means I think there’s some possibility of a favourable outcome here, eventually. So despite my dismissive tone above, there could be something interesting here maybe?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

88 comments
Sigmaroc (LON:SRC)
I have a reasonable holding.
So I could better understand the mechanics of the fund raise and proposed acquisition of the limestone quarries from CRH (LON:CRH) I spent last night reading the 50 page brokers note from Liberum to help decide decision whether to add to my holding'
The following points are I think on the positive side of the risk/reward see-saw.
The potential negatives and more obvious pitfalls are:
Conclusion
There is an awful lot of detail including numbers in the Liberum Note, too much to summarise, I am afraid
Whether or not the acquisition goes ahead will be decided at the General Meeting on 11th December. I would be surprised it it doesn't get the green light from shareholders. It is a significant opportunity but comes with execution risk, amplified by the size of the acquisition.
Quarries are large long life assets, admittedly subject the vagaries of the economy, but if managed properly can be very rewarding. I have therefore decided to keep faith with the management team and have taken advantage of the price weakness to add to my holding below the offer price of 47.5p.
I'm out of date on RM (LON:RM.) not as I'd given up on the botched RM Resources integration process (I lost interest before then!) but as I think there is high risk of disappointment in the higher profit / 'sexier' areas of RM Technology and Assessment (previously called 'Education' and 'Results" I think). What do I mean?...
My following and analyse of the company over many years thinking it was a turnaround play (I invested and exited before the woes became visible for a small profit...not worth the legwork) lead me to think that there is product problem at the biz...in that they are light on genuine repeat and scalable product that can be expanded profitably over many users. Instead they do a lot of bespoke IT work for their customers when selling and providing product (they badge that when reporting as if its a standard product but imo its a lot more client by client) with that grunt work done through the Indian bit of company. That made sense 10+ years ago as Indian IT/software labour was much cheaper and could be tasked with grunt work unprofitable in a western setting (...or likely to lose you your valuable technical and support staff through disillusionment). BUT Indian tech and support labour is more expensive and generally moved up the price-quality curve. This creates a big organisational problem for RM as they have sunk cost and knowhow relative to what I think is a rather fractured and messy product set.
So what do they do? Move that to a lower cost destination? That's probably not feasible either in terms of alternate location or moving a great deal of rather heuristic knowhow with the current client base. Simplify and generalise their product offering? That would likely create clients friction and loses.
There's a risk IMO that there is not much salvageable at RM as an ongoing business.
Several years ago I thought the CEO of RM to be a bit underestimated and destined for bigger things over time. That was an error of judgement and now I see he was probably a shortsighted tinkerer...
I'm out of date so someone may put me right...
Thank you to everyone who provided their insights today.
Best Black Friday offering I've seen.
Trifast
Pretty chunky director buy by the new independant executive chair serena Lang
137000 at 73.8p just over 101k
Not sure if anyone sold that’s a big chunk to get hold of.
Anyway very good to see a balls on the table commitment from a director as opposed to the nonsense of free charge or discounted share options that are in many cases nothing more than blue collar shareholder theft .
Bravo Serena .
We just need Venus now to start buying!
Executive directors are committed to buy to 250% of their salary over the next 5 years-that’s a lot of buying.
Thanks for the MBH comment, I like the company but the industry/market is up against it at the moment (chart below from UK Government) and i find it hard to think that Michelmersh Brick Holdings (LON:MBH) will be able to counter that.
Brick deliveries have persistently tracked downwards through 2023 and I can't imagine a quick recovery; so i agree with Paul's assessment that their order book going into 2023 has probably protected them, but 2024 may be difficult as the order book drawsdown.
Jubilee Metals (LON:JLP)
Bullish reversal signal on the weekly charts has formed. Berenberg bank brokers has a price target of 21p. Currently 5.14p.
Article on defensive ETFs
Off-Topic on a Friday, but I just want to share this (free) link to David Stevenson in FT https://on.ft.com/3sMpFnd ; I sent it to my mate so I want to post it here where I get so much in the way of good analysis.
P.S. Thanks Paul for the comment on ZANE
PP.S. I am not buying defensive ETFs myself now as I'm hoping we might have seen the worst, for now at least
Team17 (LON:TM17)
The Group has an exciting schedule of high-quality new releases planned across the Group in 2024, while back catalogue investments will continue to support revenue growth. Management will provide greater clarity on FY24 at the full year results, but currently expects to see an improved underlying trading performance compared to FY23.
Hmmmm looks like they are pimping it up next year woprds wise - i never like that. Proof of the pudding will be the exciting high quality release they make - lets see if their assertions here turn out to be factually correct.
I had previously liked this company but never taken the plunge (i have no sector exposue and this previously looked the best bet) - with their current woes i dont see any rush to buy in and i am slightly skeptical the bounceback will be quick - is thereb perhaps oversupply in thuis market? and can they compete with lower cost competitors?
On tyhe flip side perhaps these are temporary woes - if that is the case i might be mising out on soemthing near the bottom. Certainly at present i will continue to watch only.
Does anyone have a clue if their release line up next year is known and does it look decent ?
A shame that the recent acquisitions have put so much drag on operating costs. Often the case, but I think they will work out over the long run. Businesses so often under estimate the short term costs of integration and buy more than they should. Still, I think they will learn and push down the operational costs to get margins back to what they were. For traders, this looks like a nightmare. For me, I always try to think of 10 years and I still like this business. I think, I am happy to own this and accumulate more. So I am. Not my only business, so this year went from being great, to being good, in terms of my market capitalisation. It still amazes me just how fickle shareholders can be, but they may be proven right. I will see how it pans out over the next ten years. I think I am writing this to help me process just how much the market punishes businesses that hiccup and yet as people and anyone who has been in any business, knows this is part of the territory. I see opportunity, others are running for the hills.
I can't seem to resist buying renewable energy sector investment trusts and infrastructure trusts this year like Greencoat UK Wind (LON:UKW) Renewables Infrastructure (LON:TRIG) NextEnergy Solar Fund (LON:NESF) Bluefield Solar Income Fund (LON:BSIF) BBGI Global Infrastructure SA (LON:BBGI) HICL Infrastructure (LON:HICL) JLEN Environmental Assets (LON:JLEN) etc. etc. They just seem very attractive at c7-9% indexed dividend yields along with 20%+ discounts - the double impact means they could quite easily generate a 10% annual return (my target) over the medium term if interest rates fall from here.
I audited a number of energy companies for years when valuations were very high, but now value is on offer big time in public markets. Anyone else finding them an attractive proposition? Just finding it a better bet than taking on a zero yield high risk proposition at this point in the cycle with a recession looming. A bit boring, I know!
disappointed you haven't bought Gore Street Energy Storage Fund (LON:GSF) ( I just bought) - hopefully nothing wrong with that one.
I'm dissappointed I bought just over a year ago at around 118p looking for a 6% yield :-( However, it has recovered 25p from the low point and yields 9.6%. Looks like a much more convincing buy now!
https://www.bloomberg.com/merr...
I have been doing the same although listening to Meryn Talks money podcast last week ( Nov 17th) with Barry Norris was a bit of an eye opener! Worth a listen as a counter arguement.
I agree - I’m overweight renewables & REIT’s at present - also bond IT’s as I think they show good prospects of growth with very limited downside provided interest rates have peaked. However many mid & small caps are also very cheap, but with more risk. However, if this is a bear market bounce then I like the security of the income from REIT’s & renewables. At the end of October I loaded up on NextEnergy Solar Fund (LON:NESF) , Renewables Infrastructure (LON:TRIG) , Supermarket Income REIT (LON:SUPR) , & Twentyfour Select Monthly Income Fund (LON:SMIF) the first decent moves I have made this year, which will hopefully help me clawback from -12% YTD, due largely to being overweight in commodities & bond proxies earlier this year.
I have indeed found the energy sector tempting recently both old and new age. Very much not an expert in the sector, however I did recently buy some of tiddler Good Energy (LON:GOOD) that held its Mcap in cash and have an interesting, albeit young, business in the renewables space. Is that one you have come across?
They just seem very attractive at c7-9% indexed dividend yields along with 20%+ discounts - the double impact means they could quite easily generate a 10% annual return (my target) over the medium term if interest rates fall from here.
Pretty much agree with this view but sadly I held quite a few renewable energy and infrastructure trusts for their good dividend yields (even better now) before interest rates rocketed! I still hold so consequently capital losses are significant given the widening of discounts and falling share prices largely due to the lack of investor interest with risk free gilts now a viable alternative (NB: I note that the AJ Bell platform has recently enabled on line gilt purchases - previously you had to telephone to buy). In various family vehicles I hold Greencoat UK Wind (LON:UKW, Renewables Infrastructure (LON:TRIG), Bluefield Solar Income Fund (LON:BSIF), HICL Infrastructure (LON:HICL), Gore Street Energy Storage Fund (LON:GSF and Supermarket Income REIT (LON:SUPR). The sector is not without risks as I unfortunately also hold the problem childs (!) of Asian Energy Impact Trust (LON:AEIP) and Digital 9 Infrastructure (LON:DGI9) one of which is suspended and the other is at a 50%+ discount! Given all this I would very much like to see a recovery if/when interest rates begin to fall. Fingers crossed!
I also hold all of these we are lucky to get dividends tax free in ISA.
Re Wind Power, have a listen to last week's Merryn Talks Money podcast with Barry Norris. Very interesting in how Wind Power has quite a number of drawbacks and perhaps isn't such a great investment
Soros Fund Management was short the danish wind producer Orsted.. one of the 'better performers' last year.They've closed and gone long for whatever that's worth.They were short Vestas too i think, not Siemens Energy though, which almost got into real funding trouble.
I think the UK government has finally upped their prices/guarantees too now after the previous wind auction debacle with no takers.The US still is a problem i read with Orsted dumping a couple of wind projects they were going to do over there for three billion in losses, due to inflation related cost issues, price guarantees again no doubt.Best to stick to good old oil and gas still perhaps.
An update from my sector - Education
I know there are many of us on here who have vast experience within a range of different sectors but I don't think there are too many from within Education (I hope I'm wrong!). As Friday is typically quiet day, I thought I would share my views on the Education sector, where I have worked for the past 15 years, the last 5 in a senior management role with budgeting responsibility.
Put briefly, money has dried up, bigtime. The 6.5% raise to teacher wages was only part funded by the government, with half needing to be made up by the schools themselves. After raises the previous year we are now in a situation were schools are having to make significant cuts to any non-essentials. When it comes to schools, regardless of what anyone might say, only one resource is truly essential and that is teachers.
Companies like Pearson (LON:PSON) I believe will struggle this year. Normally we splash the cash on remarks of exam papers, which rakes in profit for Pearson, not this year, we can't afford it. Resources for revision and exam preparation, we used to provide for all students, now only those most at need. Students will still need to sit exams of course and papers need to be marked, but the will be less money from schools available to line the pockets. University and college books I imagine a lot of students will be more likely to look for second hand.
RM (LON:RM.) has already started its decline but this is only going to get worse, cut backs on physical resources like books and paper have already started, and as a school we have already shaved 10's of thousands off what we spent last year to free up funds. A lot of their assessment products are non-essential and schools will cut them, they do not have the same moat as a company like Pearson (LON:PSON) where at least some their main products are necessity for schools.
Teacher shortages are the worst in my living memory and it is a problem that is amplified in less affluent areas. I work in the West Midlands and even the best schools have huge staffing issues. The impact of this is simple, we have to pay more to get decent teachers, sign on bonuses, golden handcuffs (10k bonus for 3years for some Maths teachers), unwarranted additional responsibilities to up the annual salary. Again, this then reduces the funding available for other things. Companies like Hays (LON:HAS) can essentially name their price for some staff and this could be seen as a big bonus for the education recruiters. The issue is unfortunately, that whilst they might be making more profit than ever on each teacher they place in a school, they have less people on their books than ever before. Behaviour is schools continues to decline and this is the number one reason why staff are leaving the profession, those that join recruiting companies to have a go as a cover teacher (the pay is very good for the qualifications needed) typically don't last very long as they can't deal with the classroom environment. This means that the recruiters just don't have that many people on the books. We are often asking for staff and they just don't have anyone to fill the vacancies.
I personally would steer well clear of any start-up or small company that aims to profit from carving out a new niche within education. Schools are not willing to take a risk on anything new or unproven. I would have my doubts even about larger companies like Kooth (LON:KOO) as it is such an easy thing to pull funding on (I recognise they have a large US market and don't just operate within Education) but I personally wouldn't take the risk as I can't see the growth being maintained as contracts will not get renewed.
Overall I am heavily bearish on anything where profits rely on schools putting their hand in their pocket. Recruiters would be the exception, if only they had the staff to fill the vacancies!
Depressingly this is borne out by School Cuts relaunch puts unions and DfE on collision-course (schoolsweek.co.uk). My son's Uni experience has been less than startling too, with inconsistent quality of lectures and generally being regarded as a cash cow. It doesn't bode well for the future if we're not educating our kids....
My daughter and son have the same opinion that the quality of the education vs the cost is out of kilter. My son has had to move college because the teacher guiding the class was making less sense than the material he was reading on his own. Standards in this country have fallen a long way
Not much use to your son but the Open University have great materials for those who prefer or don't mind studying at home, whilst potentially working too.I'm coming to the end of an undergraduate degree with them and even i've done well.
Great materials and tutors who are responsive and not just interested and bogged down with research do make all the difference to the academic side of things.It's still marginally cheaper than some other unis now too i believe.Although, that was a real shame when they had to put up their fees as many liked to study for enjoyment.I always like to extol the virtues of great organisations.
As Paul often counsels, this site is about investing NOT politics. However, on a Friday, I do think a macro-political view is required. For UK centric companies, the polls strongly suggest a change in Govt and whilst funds for any party may be limited post election - unless you believe in the sunny uplands that Hunt now claims to spy! - in general, political parties spend on areas of concern to their supporters.
Short term that means of continued Conservative financial support for the elderly/retired - hence the continuation pension triple lock and non-means tested benefits for the elderly (20% of whom are reported to live in households with >£1mn in assets according to the think tanks!)
Labour are likely to be voted in by a much younger demographic, much more concerned with new housing, schools and the environment. Regardless of your politics, medium term that is much more promising for these sectors and the stockmarket is said to anticipate reality by 6 months.
So whilst I think you are rightly bearish on 'schools' stocks now, at some point they will become 'blood on the street' bargains if they can survive and have some sort of moat.
I think housing supply companies are at that point now - surely new house builds cannot decline by another 20% next year. Starmer has promised to 'bulldoze' opposition to building. I listened to Norcros (LON:NXR) webinar today for instance and they were the most bullish I have heard them. Marshalls (LON:MSLH), Ibstock (LON:IBST) and smaller players like (Alumasc (LON:ALU)) look good too.
Another interesting stock-picking year beckons.
I know this may be tangential but Bloomsbury Publishing (LON:BMY) have a growing sector of their business in digital resources (BDR) sold to schools colleges etc (majority in USA I believe). This may spread more to UK but with money so tight as you describe it may be a way to add resources without the teachers cost.
Any views on this
One thing that the Covid pandemic evidenced is that students cannot learn effectively without a good classroom teacher in front of them. Even high quality remote lessons were shown to have little benefit for most students, especially those with low prior attainment levels. Therefore digital resources in primary and secondary school will have low impact unless utilised alongside a classroom practitioner, I have seen this with a range of programmes such as those designed to improve reading or phonics. Therefore, I don't think there is too much scope at the 4-16 age range. However, in colleges and universities I do think there will be more of a demand, as students are typically by that age more adept at self study and will be able to benefit without the cost of teachers (I hold Bloomsbury Publishing (LON:BMY) )
On a side note - We are currently looking at moving to become a paperless school. The initial cost of this is quite high, an Ipad for every student. But medium term the money saved on paper and printing adds up fast and for a lot of schools this will be a more viable financial option than it was 5years ago when a few schools started to do it... more money for Apple (NSQ:AAPL) then!!
Interesting that the choice is iPads. Two of my kids' schools have gone for Chromebooks - cheaper and more versatile than an iPad. Some good buy now pay later type deals from provider, and means that all the kids have the same kit....
Dave
Also an option we are exploring Dave. Unfortunately most kids these days are highly apple literate so it requires the least training and has reduced barriers to entry and engagement for the kids.
There's plenty of research that indicates people learn better with a pen and paper in their hands.
Having spent over 20 years teaching adult professionals, I found that that digital learning, even with self-directed postgraduates, isn't money well-spent. Online education is therefore a sector I would never invest in. There are plenty of other ways to lose money at the moment!
From what I have experienced locally here in Switzerland, iPads are the preferred choice as they are easier to properly lock down - Chromebooks are weak security-wise and kids are rather good at circumventing any restrictions the schools might put in place. Here they usually supply the school iPads in a protective case with attached keyboard - seems to work very well.
Interesting to relate the general environment to specific stocks - the government argument is that money will come with growth, but that will take time, and in the meantime local authorities and the public sector in general are being forced to make cuts. Worth thinking about how that will impact individual companies elsewhere.
I work in education as a full time physics teacher but have also taught maths. I used to work in telcos prior to this. I can certainly backup the shortage of maths and physics teachers in my area. More worrying is that we are losing staff to early retirement, largely because they have had enough. We are also seeing a shortage of ects in these subjects. The main issues for me are workload/increased expectations (normally i wouldnt be able to read the scvr until around 8pm due to work but our school is closed today that said i have been working a few hours and will do more on the weekend), pay, behaviour (to a lesser extent) and, since the pandemic, I feel that the inflexible nature of the job means that work from home/more flexible jobs are probably more appealing to those who might have considered a teaching career. Some schools used to manage costs by forcing those on m6/ups out into capability but the lack of replacement cheaper trainees coming into the machine has reduced this. I think you are right in terms of the digital spend going forward and companies like Pearson, I can't see schools in my area shelling out given the budget constraints.
Cerillion (LON:CER) FY23 results webinar today at 11am Register here..
It's up over 10x since it IPOd 2016 & it's growth continues with Rev up 24% & dEPS +24%.
Unsurprisingly it has many quality metrics in Ed's Spotting Multibaggers presentation given last week.
Here's the Tracsis (LON:TRCS) FY23 results presentation with Q&A given last week video & podcast.
re ZANE
I am a trustee and treasurer of a small charity so know how charity finances work. I always look at the accounts of a charity before making a donation and in many cases i don't like what I see. Investors know what a PE ratio is. With a charity just work out the expense ratio is i.e. how much of that quid will go in expenses. You will soon get the hang of it. It can be addictive even.
Financially ZANE is about the best I have seen. The trustees work for nothing and expenses are clearly essential for the work of the charity.
I am a Director of a small South African based charity and I echo your comments whatmore1951. Having been married in Rhodesia and with friends still living in what is now Zimbabwe, I appreciate the excellent work ZANE is doing .
Is there a site that produces essential data for charities, as Stocko and Sharepad do for shares? If there isn't such a site I'd say it would be a worthwhile project for a small team to create. It would have to be chairty in its own right, not monetised.
My least favourite charity was set up 57 years ago, has the most ridiculous expense ratio I'm aware of (it describes itself as a campaigning organisation so it spends most of its money on salaries), and has been an utter, abject failure over its entire existence because the issue on which it "campaigns" has got worse, not better.
The Charity Commission's website is actually pretty decent (generic example below, not fair to stick Zane up here without commentary) - you can chart various types of income & expenditure from the past 5 years worth of accounts for any registered charity.
Of course greater granularity in expendure would be helpful, but that would require subjective interpretation. You can separate out what is spent on fund-raising, and what is spent on governance.
Hi Whatmore 1951, interesting to see that you are a trustee of Zane. My sister travelled to London a couple of weeks ago to take my daughter to a Zane event - only to discover it was cancelled! She hopes it didn't make too much of a dent in your fund raising plans?!
He is not a trustee of Zane but another small charity
Oops. My bad. Maybe Paul might know after his meeting with Tom Benyon
Team17 (LON:TM17) was one of my best mutibaggers from 2019 after robbie burns mentioned it at one of his seminars and i looked into it. shame how the tables have turned.
Disaster one for me, think I bought it at the peak and sold today for a 60% loss. We live and learn I guess.
But did you jump too soon today Brookeda? I have added some Team17 (LON:TM17) , I may be wrong by thinking I cannot lose on the addition. The main damage is done and I share your disapointment in TM17 having bought in at £8.34 and receiving no dividends along the way. Games Workshop (LON:GAW) which I no longer hold is in a completely different ballpark.
Just wanted to add a message of appreciation for your work with ZANE, Paul. Zimbabwe is a long way away and events there don't impinge much on our lives, especially with everything else that's going on in the world. The long-term, dedicated and compassionate work done by ZANE is clearly a lifeline for its beneficiaries and some of that work has been made possible thanks to you championing the charity with the community here. Thanks for all that you do.
PS A short update after you've met Tom Benyon would be great, if you have time.
PS A short update after you've met Tom Benyon would be great, if you have time.
Yes definitely, will do! :-) Thanks for your kind words too.
W7L
It is refreshing to see options granted to directors etc at current share price (W7L 325p) rather than give away options at nil cost which in my opinion should not be allowed.
Happy holder of W7L
On a quiet day for small company news it’s perhaps worth putting this post here as well as on a thread about making money even in bear markets. I’m a big fan of quality shares paying big dividends, and there have never been so many to choose from as there are right now!
Usually dividend yields above around 6% tend to be a warning sign that the dividend is unsustainable and likely to be cut or even cancelled. But right now there are shares and Investment Trusts paying covered dividends much higher than 6% that not only look sustainable but sometimes are even getting increased.
Here are 12 shares I hold that look worth checking out. Most of these are big dividend payers. Perhaps readers disagreeing with my enthusiasm and confidence about these shares will post why and put me right! Or alternatively suggest alternatives that look as good or even better choices.
So here goes.
Oil shares don’t get much coverage here. These UK oil shares all look stunning value.
Ithaca Energy (LON:ITH) 163p. Up10p today in belated positive reaction to their results yesterday. PE 5. Dividend a whopping 17% and they’ve just confirmed another 10p or so dividend to come. Debt falling fast. Share is DOWN 16% over 1 year.Recent low 140p. Gets 96 for value on stock page here.
Serica Energy (LON:SQZ) 213p. Up 6p. Dividend 10% and PE just 2.5. See Greater Buchan news today where Jersey Oil and Gas (LON:JOG) (which I also hold) has agreed to farm out 30% interest in North Sea Buchan Field to Serica. The deal sees Jersey Oil and Gas (LON:JOG) up 20% today but it’s riskier than the other oil shares covered here, despite great enthusiasm from Simon Thompson and Malcy. Excellent recent article on Serica from Roland Head. Share is DOWN 28% 1 year and recent low 193p. Gets 95 for value and 96 overall.
Harbour Energy (LON:HBR) 223p. Up 3p. PE6. Dividend 9.5%. Down 1 year 28% and recent low 220p. So it’s at the year low! Gets 95 for value.
Next to these Fund Managers. As most will know their share prices take a big hit in bear markets thanks to big outflows from their Funds. And then soar in bull markets as big net inflows instead. So many investors buy the peaks and sell the dips instead of doing the obvious and buy the dips and sell the peaks. Fund Manager shares bought at appropriate time are often far better investments than their Funds are!
EDIT. Sorry. Further oil shares in the wrong place!
Gulf Keystone Petroleum (LON:GKP) 129p. Low85p. DOWN 38% 1 year and down from 302p high.PE 2.5. NO dividend. ( Stockopedia figure as too often with dividends is wrong). Gets 94 for value. GKP paid about 40% in just a year in dividends….until BOMBSHELL BAD NEWS of the sudden closure of the IRAQ/Turkey oil pipeline. It’s now been closed for months and each expectation that it will open again hits the dust. GKP is managing to sell enough oil to survive this and if the pipeline reopens the share price could soar AND open the way for very big dividends again too. BUT IRAQ oil is obviously risky and until the pipeline reopens it’s just a punt.
Petrotal (LON:PTAL) 50p. Low 34p. 1 year now up 15%.PE4 and 9.8% dividend. Gets 92 overall.
So. Now to Fund Managers!
Premier Miton (LON:PMI) 61p. Recent low 49p. 1 year DOWN 35%. PE 10 and 9% dividend. Another attraction of this sector is the possible continua of sector consolidation via bids.
Polar Capital Holdings (LON:POLR) 460p. Recent low 396p. 1 year DOWN 6%. Dividend 10%. PE 13. Much more richly valued than the others but that reflects among other things some very successful Fund performance.
Jupiter Fund Management (LON:JUP) 82p.Recent low 74p. DOWN 34% 1 year. 6% dividend if held. PE 9.5. 93 for quality and 92 for value.
Liontrust Asset Management (LON:LIO) 571p. DOWN 18p today but it went ex the next 22p dividend today. Recent low 525p. Dividend 22.2% and PE 8. Share price was (far too?) hammered when Liontrust decided NOT to overpay for GAM. Gets 98 for quality.
Others.
Cavendish Financial (LON:CAV) 7.5p. Cavendish is the recent combination of FinnCap and Cenkos. IF AIM market at long last on the way up the newly formed Cavendish could win a lot of new business.
Good Energy (LON:GOOD) 306p. And DOWN from 370p just a couple of days ago. 1 year up 56% because of recent very fast gains. PE12 but explosive increase in EPS forecast. Gets 99 overall too. Could go way higher but it’s one to buy the so far temporary dips rather than get sucked in at latest top.
Secure Trust Bank (LON:STB) 650p.1 year FLAT. Low 550p.PE3 and dividend 8.2%. Gets 97 for value.
Finally a key attraction of most of these is the exceptionally high dividend yields which reflect how cheap the share is in most cases and NOT a high risk of dividend cuts. And that up to 17% dividend yield is a great gain annualised even with no share price gains at all. BUT the likelihood is that in the next bull market the dividend yields for most of these shares will reduce to more normal levels via big increases in the share prices.
Glad to see someone looking at oil shares I agree they are oversold but fund managers have got to prove they are ESG correct
I notice the two sectors producing those big divis are investment managers and oil and gas. Maybe the yields on offer are a reflection of the long term outlook for each sector ( although O & G will be producing a surely very necessary product for longer than some think)?
My preference for high sustainable yields is the life assurance and financial services sector, although the yields are lower.
High dividend and out of favour shares.
looking beyond two years I think the housebuilders offer outstanding value. less risk than the oil and gas sector.
Energean oil&gas plc seems to be the best value in that sector (especially with their gas reserves).
Sorry, but did you mean Energean (LON:ENOG) yiannos1?
Yes
Energean (LON:ENOG) - their contractor platforms are a good target for Hezbollah rockets (although Israel and Lebanon have agreed where the marine line of demarcation lies so maybe they will leave them alone?). https://carnegieendowment.org/...
....and the full text of the agreement can be found here: https://www.timesofisrael.com/...
I keep looking at them as they have found game changing reserves of gas in the East Med. Their balance sheet looks horrible, but future cash flow should remediate that.
Eduardo Sergio Elsztain, the major shareholder in Argentinian agriculture and real estate company, Cresud SACIF y A (NSQ:CRESY) (I own) is a backer of Energean (LON:ENOG) which gives one some comfort that somebody has done some proper due diligence. Mr Elsztain was a protégé of Mr Soros.
Ironically, I think Energean (LON:ENOG) is probably a better geopolitical risk than Serica Energy (LON:SQZ) (which I own). They certainly have far superior 2P reserves. I continue to watch Energean (LON:ENOG) and ponder whether to buy or not !!
Obviously very dependent on oil prices staying high. But food for thought, a small position is probably a good idea.
Just a note - you are incorrect on Petrotal (LON:PTAL) dividend. It will pay circa 15% yield if you exclude the buy backs, which in their own right add a few % to that number.
David
re Petrotal (LON:PTAL) I hold a miniscule amount but I noticed that Stocko's dividend page appears to be wrong and I have asked stock to check although I havent heard back yet. You are right though yield is about 15%. See their RNS
Great post. My pick of fund managers is Foresight group (LON:FSG)
If you like high yield shares Ken Mitchell, have a look at Diversified Energy (LON:DEC) currently paying steady quarterly divs of 19.66% p.a.
There was a recent Vox commentary from Sid Lall of Canacord here https://www.stockopedia.com/sh...
Never recovers though the EX Dividend price. Lost half of its value and half of its revenues ; dividend yield not sustainable.
You need to be very sure you understand how Diversified Energy (LON:DEC) make money from depleted shale reserves abandoned by other companies. It can be done ..... look how Peter Mann at Rockrose was able to use misunderstood decommissioning liabilities to finance the expansion of his business. Sadly, but understandably, his new vehicle appears to have given up on the North Sea and who can blame them?
Roger Baron
I hold Diversified Energy (LON:DEC) and included it in a previous post on bombed out shares and Investment Trusts. I didn’t include it this time as the focus of my post today was on what (imo) are good quality shares and risky DEC can’t be classed as quality.
DEC business model is fiendishly difficult to understand and I don’t! Bearing in mind the debt and decommissioning costs I can’t fathom how DEC not only pays big quarterly dividends but somehow has increased the dividend several times, including 3 increases in 2022.
Yiannos1 says the dividend is unsustainable. That’s what I thought years ago and so far that’s wrong. I’ve held DEC on and off since 2017 including a lucky buy on a dip after covid to just 55p and have already had most of my stake back in dividends, so if there’s a sudden dire profits warning or worse, with sudden dreaded suspension of the shares “pending clarification of our financial position,” (I.e we’ve gone bust) it’s no problem. And for all I know DEC could go on paying the huge dividend for a lot longer.
I’ve never understood why DEC is on our market and not their Home US market. But!! DEC recently announced that from December 11th the shares will be listed in the US too. In preparation for that and because apparently US investors prefer shares with a high nominal price there is a 20/1 share consolidation soon.
Some are hoping that being on the US market will give the share a big boost. I’m not so sure and so far there’s no sign of the share having a good run ahead of the US listing.
So I see DEC as a risky punt, but maybe some here will disagree with that and put a more convincing case.
I am not talking about ‘years ago’ , as years ago the dividend cover was 4 and now on a 2 year forwarded it’s not even 1 and it’s definitely not sustainable.
Years ago (last 4-5 years) it was not 19-20% as the price was higher.
Incorrect yiannos1. “
Years ago” I bought some Diversified Energy (LON:DEC) at just 55p compared with 72p now. So any who also bought then have seen a capital gain as well as a huge annual dividend. More recently though the share price has fallen significantly and even accounting for the big quarterly dividends investors who bought ahead of the current dip are losing.
As I and others have posted the jury is out on DEC. It’s not a share for a cautious investor.
What’s incorrect?
I am trying to understand where is this going?
I just corrected your statement that the current dividend of 19% is unsustainable (the current!) as it is not covered by future earnings. My statement has nothing to do with the price you bought the shares or if you have got back your investment in dividends. That’s the past- Don’t think anyone is interested about that.
I am just warning potential investors that the current dividend yield cannot be covered by the current/future earnings and cash flows; according to all research available.
Thanks
Doesn't Diversified Energy (LON:DEC) come under the heading "if it looks too good to be true, it probably is?" Especially given that no one seems to understand it....?
Yes I agree - not for widows and orphans. But debt is being repaid, dividends maintained and let's not forget they are also buying back shares. I'm comfortable with both the risk and the dividends.
Team17 (LON:TM17) - ex holding - no great insight for selling, probably just hurting from other losses that were actually underwater so not saleable - better to be lucky than smart!
In the olden days (pre 2021) Tm17 had in my view the best accounting in the sector. One year amortisation & ROCE adjusted for intangible impairments. Think a new CFO was involved which in changing amortisation period to 2 years which is why the amort maybe less than.
In terms of the share price, I can understand mid cap investors being miffed considering what the EPS/CFPS have done in its time as a listed company to be down 18% over 5 years.
That's said, I think Debbie Bestwick leaving was perhaps the signal & clearly errors (or they got carried away) on capital allocation. What's interesting is she put a fair chunk of her own money in the placing near enough the top & I imagine she has pretty good judgement with how the industry is likely to develop.
I can see a world where she takes the company private (and probably negotiate a pretty good deal for herself)
For once I have dodged a bullet, as I sold out of Team17 a while ago. However, I thought today's share price reduction might be overdone (at 188p it is below what Paul suggested the likely range) and some of the issues do seem to be short term. The profit warning is difficult to interpret so I tried to download the last accounts from their website. At first sight this looked a long document but I soon realised I could only see the even numbered pages. Note 11, analysing the intangible assets starts on an odd page. Anyone else have the same problem, or know where I can get the full accounts?
Annoyingly, some companies download their annual reports in double bag spreads. On my laptop, I find that I can only see the even pages, but if I zoom out, the odd pages appear too. But the print is then very small!
double bag should read double page - auto spell oversight
jdn
I'd suggest contact the Investor Relations team at Team17 (LON:TM17)and ask them to send you a hard copy (they usually have a few) or the Financial PR at the address on the latest RNS and ask them to reformat the pdf to single page view and send it through. If they don't know how to do that, or claim technological incompetence, ask them to contact the design agency that created it for them. It's a quick fix.
It is difficult to overemphasise how challenging the past few years have been for our asset class. The Numis Smaller Companies (excluding investment companies) Index has lagged the broad UK market over the past 1, 3, 5 and 10 years. In other words, the "SmallCap Effect", which has been a major tailwind to investors' returns for the past 70 years, has been working in reverse for the past decade. This is a rare event: the last time this happened was in the late 1990s.
More recently, this underperformance has coincided with outflows from the asset class reaching parity with that witnessed after the Global Financial Crisis. According to the Investment Association, cumulative outflows from UK SmallCap Funds amounted to £2.1 billion since January 2022, almost in line with the £2.3 billion experienced in 2007-09. Several open-ended UK SmallCap Funds decided to wind up this year while some industry veterans have retired. In the investment trust space, wider discounts have prompted some consolidation.
Valuations for the asset class have returned to levels last seen during the Global Financial Crisis, which marked the start of the recent Great Bull Market. At 13.9x, the 8-year Shiller P/E for UK SmallCap is rapidly heading towards the all-time lows of August 1992 (10.9x), March 2003 (11.6x), February 2009 (11.8x) - which would suggest 15% to 20% maximum downside from current levels. While the past is of course not guaranteed to repeat, history tells us that when valuations have previously reached current levels, returns over the subsequent 5 years for SmallCap were between 100% and 150%. Investors should perhaps take note.
https://www.londonstockexchang...
No one know where the 'bottom' is until much later. However, my guess is that we are very close to it.
RM (LON:RM.) Significant decision by the Board to close its consortium division, which is the largest by far of the company's three division. It is the largest UK supplier of sundries to UK schools. Not sure what RM (LON:RM.) will do with its assets that includes a large state of the art warehouse. The announcement states that the decision was taken with the agreement of its lenders. RM (LON:RM.) is the largest holding in Rockwood Strategic (LON:RKW) managed by Richard Staveley.
'The Consortium business, the provider of education supplies and resources to schools, has experienced an extended period of underperformance following the negative impact of the rollout of a new ecommerce platform in 2022. Today the Company announces that it has taken the difficult decision to close this business from the end of December. The decision to close Consortium is in line with the future strategic direction for the Company and has been made with the full cooperation and support of its lenders. The decision will also enable RM Resources management to focus on its successful TTS business.
In the accounts for the year ending 30 November 2023, the Board expects to make a material write off of the carrying value of Consortium and its related assets as a non-cash item, and to make an additional provision for exit costs but there is not expected to be any cash impact in this current financial year.'
Basically a failed IT project has forced a closure of the consortium business, crazy stuff. They've spent 10s of millions trying to sort it but have finally given up. It's hard to understand why they couldn't sort it. Maybe this will be a start of a sell off of some of the other businesses as well. It's hard to work out if there is value here, some of this is clearly priced in and when a business does close a struggling part its share price often reacts well.
RM (LON:RM.) are there any listed business which will pick up the slack from the closure of Consortium? Might be worth focusing on those than on RM.
Possibly Computacenter (LON:CCC) ?
Would love to know who the IT Partner is/was or whether it was in-house. As an IT person I find this shocking. Not that all the blame sits with IT - it takes a dedicated partnership with the business to screw up on this scale.
Listened to Richard Staveley on a Vox Markets recently (a Pail Hill session excellent IMO) where he spoke about RM at length. Apparently RM supply 90% of the Primary schools in the UK - their competitors must be rubbing their hands. I hold.
RM
Very hard to work out what’s going on and overall effect .
Interestingly Harwood have been adding recently PlUS they sit on the board and presumably they knew about this .
Not sure where the lines are in terms of inside trading but they are clearly still confident .
I once wasted 300k on a failed IT project so have some sympathy though it was down to getting overly excited after snake oil salesmen promised the world and delivered a totally useless system .
Be very interesting to watch the RNS in next few days If Harwood continue to add to what is already an oversize position (20% of Rockwood) then it is pretty safe to assume they know something we don’t and I will follow that prompt .
All eyes on Mills / Staveley ! If they take the holding higher on this weakness they are playing the joker (for anyone that remembers it’s a knockout)
&ab_channel=TheYesterdayMachine
Consortium is one of 3 businesses in "RM Resources".
Sales 6m to May 23 fell to £6.7m from £16m for the half year to May 22. Horrible.
6.7 / 42.2 = c. 16% of divisional sales.
6.7 / 87.6 = c. 8% of rev from whoe company cont. ops
For full yr to Nov 22 Consortium was 33.6 / 114.4 = c. 29% of divisional sales, or 33.6 / 214.2 = c. 16% of company turnover.
At the interims (released 9th Aug) the commentary stated:
"Following the completion of the IT and distribution centre implementations the division is returning to a stable footing after an extended period of organisational and customer disruption which primarily impacted the Consortium business"
So I think we have to conclude that things have got worse. Customers got fed up with Consortium and went elsewhere. Elsewhere was probably cheaper (Amazon Business?) and more reliable. These customers have not come back, and they didn't move across to TTS either....
What is as clear as mud is the overlap between Consortium and TTS? The websites look very similar, with a very similar product offering. Is most of what what we see on the TTS website really Consortium underneath? My presumption is that they tried to push through the Consortium range through the TTS brand, whereas the value in TTS is the in-house products developed by TTS (the robotics/programming offering). This would mean there is transfer pricing going on between Consortium and TTS....
When Rockwood's Staveley was discussing their investment thesis for investing in RM (LON:RM.) a year or so ago (not the recent interview on VOX) he was very much working from a price/sales methodology in seeking to ascribe a break-up valuation.
The management might be doing what is necessary, but if your price target was derived from a multiple of sales then I'm afraid that target valuation is now 16% lower, and given the dent to credibility, possibly more.
Monty Carlo
Thanks that’s a great summary saved me a load of work !
Still think seeing at what point Rockwood / mills start to add .
Think this has further to fall and if it over shoots for sure they will buy
We shouldn't be surprised at this development though, given this line in the Summary slide at the interims:
"Consortium continues to be a challenge to improving our financial performance, and clouds the value of the rest of the Group"
Perhaps all we should conclude is that they couldn't find a buyer....it was already likely they wanted out.
RM (LON:RM.) From what I could glean from the annual report:
Just spend 10 minutes on each of:
https://www.consortiumeducatio...
and
https://www.tts-group.co.uk/?g...
Then come back and please tell us what you make of it?
Oops...you can't - they seem to have just taken the website down (or there is an internet issue somewhere, but TTS is still running)
My observation was a huge amount of product overlap.
It was an internet issue - website is back.