Small Cap Value Report (Fri 25 Aug 2023) - CMCX, ZED, IPEL, LOOK, TRB

Good morning from just Paul today, with it being Friday!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Good, nearly everything done, sorry I'm too tired to look at Colefax today.

Summaries
CMC Markets (LON:CMCX) - Down 15% to 104p (at 08:39) £290m - Trading Statement - Paul - GREEN
A frustrating update, with limited information, and no broker notes to help me. So I have to dig through the last full year accounts to make some sense of it. The main point is that balance sheet NTAV is now above the market cap, and it’s almost all liquid assets. So this share looks astonishingly cheap for a possible recovery in due course. Providing nothing more serious is going wrong under the surface.
Zenova (LON:ZED) - Unch 5.25p (£6m) - Interim Results - Paul - RED
Loss-making tiddler. I only review it briefly below, to get something into the system here. Main point is, it's financially distressed, and needs to be recapitalised to fund the continuing losses. Near zero revenues. Fire safety products might be interesting, but it needs to get proper funding in place first before I would go near it.
Lookers (LON:LOOK) - Interims - Paul - AMBER
Strong H1 trading, and it looks set to beat forecasts for FY 12/2023 (although doesn't say so). Management have agreed a 130p cash takeover bid. These good results might make shareholders think twice before voting for the deal. Although a bird in the hand, and all that, especially in wobbly macro times.
Impellam (LON:IPEL) - 710p (£318m) - Interim Results - Paul - RED
Maybe I've missed something important, but based on these numbers, this staffing business looks very considerably over-valued. It's in bid talks with a Netherlands-based group, and I fear that if talks fall through, this could crash big time. Risk:reward looks very bad to me.
Tribal (LON:TRB) - 44.5p (£95m) - Interim Results - Paul - AMBER/RED
A poor track record, weak balance sheet, and a large legal dispute over a botched Singapore contract, put me off this educational software group. However, its H1 numbers actually look quite good. Hence I've edged from RED to AMBER/RED. Could be a takeover target maybe?
Paul’s Section:
CMC Markets (LON:CMCX)
Down 15% to 104p (at 08:39) £290m - Trading Statement - Paul - GREEN
CMC Markets Plc ("CMC" or the "Group"), a leading global provider of online retail ("D2C") and institutional ("B2B") platform technology, today issues a trading update for FY 2024.
A strange and vague description above. It’s actually a spread betting/ CFD company, 59% owned by Peter Cruddas, so he’s in control, which can bring risk with it sometimes, as we occasionally see at companies with a dominant single shareholder.
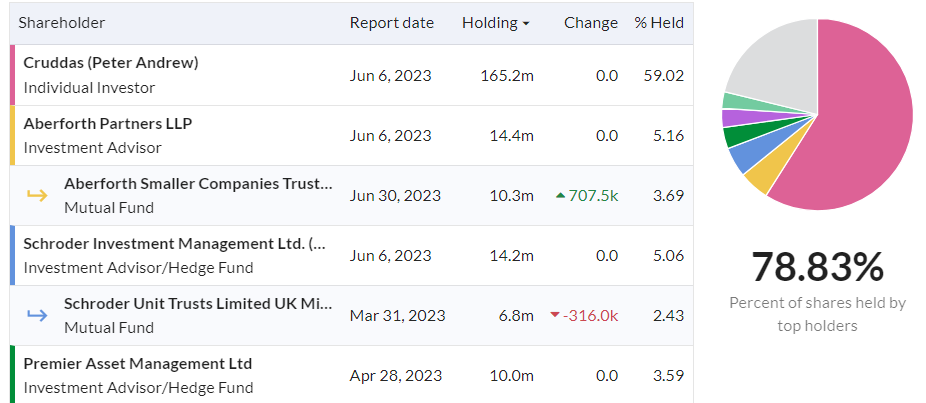
The current financial year is FY 3/2024.
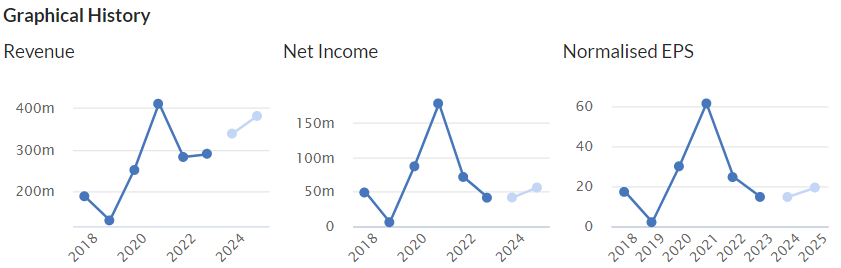
As you can see below, it enjoyed a profitability boom during the pandemic -
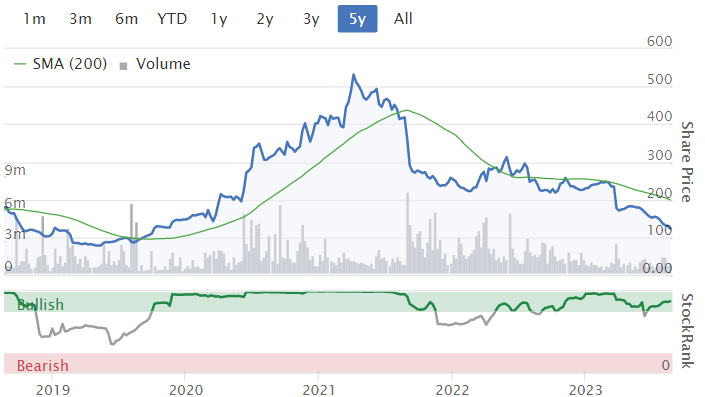
The share price has since lost over ¾ of its peak valuation - here’s the 5-year chart - looking very poorly now - ominous, or an opportunity, I wonder?
To get me up to speed, Graham & Roland’s previous comments on CMC are as follows:
25/1/23 - GREEN - 235p - TU: trading stable, in line exps. High quality, PER 11x.
13/6/23 - GREEN - 160p - In line FY 3/2023 results. Roland - fundamentals strong, good value.
27/7/23 - GREEN - 147p - TU: weak customer activity. Graham: sector looks cheap (holds IGG personally)
The above is a good reminder that we can only review the facts, figures, and forecasts as they are on each day. We’re not able to reliably predict the future! Clearly business has been slowing down at CMCX more recently. However, at some point in the future, it might pick up again, that’s usually what happens in this sector.
This is the latest - sounds like private clients are hiding or on holiday, rather than trading! -
Following the update provided on 27th July 2023, subdued market conditions have continued through August with trading and investing net revenues trending 20% lower year-on-year. August in particular has seen a more challenging environment with markedly lower monetisation of client trading activity due to a higher proportion of lower margin institutional volume.
Revised guidance -
Whilst underlying market activity has the potential to recover, should year-to-date market conditions continue for the remainder of FY24 then it is expected that net operating income will be between £250 and £280 million…
Management expectations for FY 2024 operating costs excluding variable remuneration are unchanged at £240 million. A further update on costs will be announced with interim results.
What a confusing way to report! Why can’t they just guide what the profit (before tax) is going to be? Or give a range of outcomes?
There are no broker notes available.
So I’ll have to refer back to previous published accounts to work out what today’s update means.
Net operating income - this is effectively a gross profit number, but before all the substantial overheads (mainly staff, premises, marketing & IT, I imagine) -
- Guidance today for FY 3/2024: £250-280m
- Actual FY 3/2023: £288m
- Actual FY 3/2022: £282m
Operating expenses - looking back at previous accounts, this looks quite straightforward, they’ve given us the two numbers needed to deduce operating profit. Operating expenses are -
- Guidance today for FY 3/2024: £240m (but it says this excludes variable remuneration - staff bonuses I suppose. £240m is unchanged from guidance given on 13 June 2023)
- Actual FY 3/2023: £234m (very large increase on previous year - why?)
- Actual FY 3/2022: £188m
Operating profit is therefore -
- Guidance today for FY 3/2024: £10-40m (excl. staff bonuses)
- Actual FY 3/2023: £54m
- Actual FY 3/2022: £94m
(staff bonuses were £16-17m in each of the last 2 years)
That’s clearly a worrying downward trend, and also a wide range of outcomes for the current year, from not much above breakeven, to about 26% below last year.
What was previous guidance? I can’t see any profit guidance in the Q1 TU of 27 July 2023. It just said that Q1 performed as expected, and that net operating income was “similar” to last year.
Interest income - this is an important point. I recall before the zero interest rate period, spread betting companies made most of their profit from finance income - pocketing the interest earned on substantial client funds. Now that interest rates have gone up substantially, and rapidly, this should result in a dramatic increase in finance income for companies like CMCX.
Indeed, the TU on 27 July 2023 made this important point -
…however weaker client activity has been offset by stronger interest income, resulting in overall net operating income tracking at a similar run rate to the same period last year.
[NB - from previous update on 27 July 2023]
Today’s update doesn’t say anything about interest income.
Note the net interest income increased from £1m in FY 3/2022, to £14m in FY 3/2023. So it’s reasonable to assume the figure for this year will be substantially higher again. Although it seems that net interest income is already included within net operating income.
Client funds & assets - this sounds reassuring, suggesting that some clients have paused activity, rather than closed accounts and withdrawn their cash & assets -
Core KPIs including client money, assets under administration, and active clients across both the trading and investing businesses remain robust with no material change seen through recent weeks.
EDIT: Client monies are segregated, ie not shown on CMCX's balance sheet. This is from the FY 3/2023 accounts -
Client money
Total segregated client money held by the Group for trading clients was £549.4 million at 31 March 2023 (2022: £546.6 million).
Client money represents the capacity for our clients to trade and offers an underlying indication of the health of our client base.
Client money governance
The Group segregates all money and assets held by it on behalf of clients excluding a small number of large clients which have entered a TTCA with the firm. This is in accordance with or exceeding applicable client money regulations in countries in which it operates...
This gives us an idea of what interest income CMCX could earn on client funds. If it's say 5%, then on £550m funds, that would be c.£28m pa - which is nearly double the finance income earned last year.
Balance sheet - this is the best bit! I’ve reviewed the last reported balance sheet as at 31 March 2023, and it’s excellent.
NAV was £374m, with only £35m intangible assets to write off. So NTAV is £339m. Better still, that’s nearly all liquid assets (including cash of £146m), and near-cash (i.e. receivables that would turn into cash within days probably).
Bear in mind that the market cap after this morning’s drop is only £290m (at 104p/share), which is 14% below NTAV (almost entirely liquid assets). That’s crazy! It’s much too cheap in my view, and being more than fully backed by liquid assets, the valuation doesn’t make any sense at all to me.
Paul’s opinion - it’s taken me almost 2 hours to pick my way through this update, because it’s unclear the way the company reports, and I’m hampered by not having any broker notes available, and also being personally unfamiliar with the company.
Clearly conditions are tough, but that’s the market generally, not anything CMCX is doing wrong, I imagine. Sooner or later markets recover, and activity increases again.
In the meantime, it looks as if CMCX is still profitable, but only just, if it only hits the bottom end of its forecast range provided today. That’s clearly not good, but it’s a volatile business, where trading activity by clients ebbs and flows - this is completely normal, not exceptional.
Reading previous accounts, it looks as if CMCX has been expanding and increasing costs. That could be reversed, if depressed market conditions continue or worsen.
Therefore, I see the deep fall in share price more recently as a potential buying opportunity, for a recovery in due course.
The best bit is that the market cap is now more than fully backed with liquid assets. That’s remarkable.
The main risks are that something might be going badly wrong within the business itself - so not just a cyclical downturn, but competitors eating its lunch. That’s the main thing to check. So the next step would be to review major competitor IG group (LON:IGG) announcements, and if they’re similar to CMCX then that would reassure. I see IGG’s share price is also soft, but hasn’t fallen anywhere near as much as CMCX, which suggests the market seems to think CMCX has some company-specific problems on top of market cyclicality being poor at present.
Overall then, I recognise that CMCX is not trading well at present, but the deep value on the balance sheet is such that I have to give it a positive GREEN view, for a recovery in share price that is now incredibly well underpinned with liquid assets. It almost doesn’t matter what trading is like in the short-term, as long as it doesn’t slip into heavy losses, since investors have more than 100% liquid asset backing of the market cap.
The other potential risk with companies like this, is a catastrophic meltdown of IT, and hedging risk. If the IT allows traders to buy & sell at the wrong prices, they’ll quickly exploit it to the full, and the company could bankrupt itself in days, or even hours. So you have to hope they’ve got the most robust IT systems possible.
Once markets begin recovering, it wouldn't surprise me at all to see CMCX shares maybe even up to 100% higher than they are now. So a very credible candidate for further research I think.
Zenova (LON:ZED)
Unch 5.25p (£6m) - Interim Results - Paul - RED
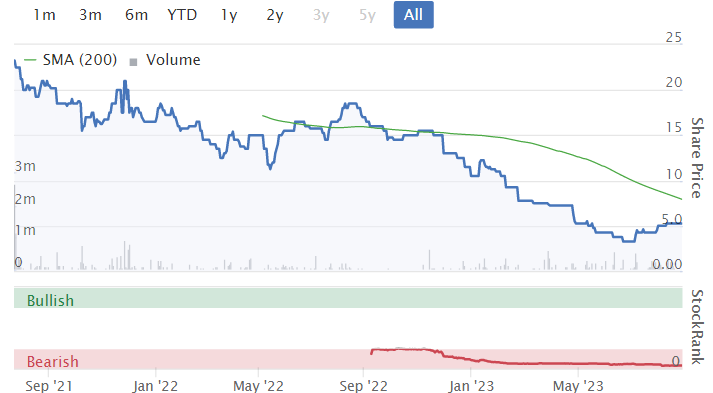
Fool Hardy flagged this tiddler in the reader comments here, so I’ve had a very quick (literally 5 minute!) skim of the numbers. Just to get something in the system, as we’ve not looked at it before.
Negligible revenues of £108k in H1
Loss before tax £709k in H1 (FY Nov 2022 was £2.0m loss)
It’s burned through the £1.7m cash pile in the last year, only having £312k left at 31 May 2023
Placing at 4p raised only £500k in June 2023.
Director loan recently of £350k
Warrants issued, so note this is more dilution if shares recover in price.
Paul’s opinion - the finances look distressed, so it needs to get proper funding in place before I would see this as investable. More dilution looks inevitable, and could be ruinous. Even then, if it does get proper funding, you’ve got a blue sky, loss-making tiddler with negligible revenues.
On the upside, product news, contracts, etc, sound promising, but it needs to get the financial basics in place first before I would want to delve into the product side of things.
Looks to have floated in 2021, which tells me everything I need to know!
Impellam (LON:IPEL)
710p (£318m) - Interim Results - Paul - RED
This one has slipped through the net, we’ve not covered it since 2019. Pity, as there’s been a fabulous share price recovery since 2020, with it hitting new highs recently.
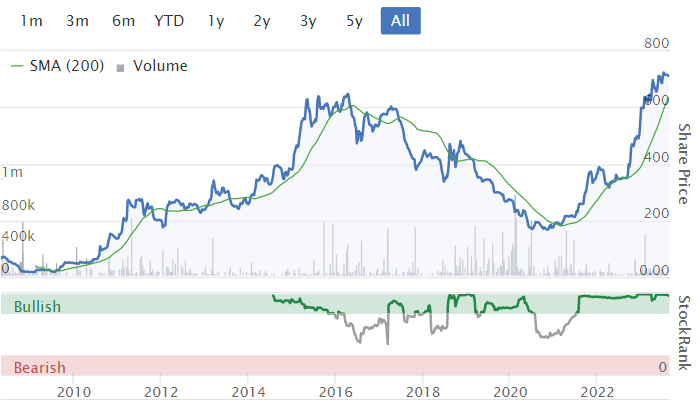
It’s a staffing business controlled by Lord Ashcroft, with his family trust owning 56%. There was controversy over his political connections (a former Tory Party treasurer, and big donor), and Impellam winning large NHS contracts to supply temporary staff (locums). The Guardian hints there might be a connection here, which Lord Ashcroft denied.
The blue band at the top of the StockReport says that Impellam “is involved in a takeover situation”. Rummaging through the RNS list, it keeps issuing extensions to the PUSU (put up or shut up) deadline, with bid talks (not a formal bid as yet) ongoing with HeadFirst Global, a Netherlands based group. Looking at its website, HeadFirst’s numbers only look slightly larger than Impellam’s, so I’m not sure how a bid would work from HeadFirst? Would it be a merger, or involve taking paper instead of cash, or a mix? I don’t know. HeadFirst’s website says it has an investor, IceLake Capital, which is helping it fund European growth, so that could be the answer. The commentary says that Lord Ashcroft wants to sell, and had previously notified this to Impellam.
Interim Results - were issued on 21 August 2023
Impellam (AIM: IPEL) announces its unaudited interim results for the 26 weeks ended 30 June 2023.
Gross profit growth in a challenging market
I have to say, Impellam’s interim numbers look feeble for a business valued at £318m - eg
H1 gross profit up 2% to £97.6m
Operating profit before amortisation £8.3m (down 11%)
Continuing operations adj EPS up 26% to 9.6p (so looks like there’s been a disposal)
Net cash £56m (up from £18m a year earlier)
Disposals - it’s sold a big chunk of the business, Medacs (the controversial healthcare business), and other regional subsidiaries, for £104m in March 2023, funding a £60m special dividend.
Actually there have been 3 special divis paid, of 69.3p, 55.4p, and another 55.4p, between Dec 2022 and Apr 2023.
Balance sheet - has negligible NTAV at 30 June 2023, only about £12m.
Forecasts - there don’t seem to be any, so I can’t value the shares on forecast earnings.
Given that it only reports continuing operations adj EPS of 9.6p in H1, which annualises (assuming no seasonality) to about 19p for a full year, I’d put that on a PER of about 10 maybe, being generous, so I get to 190p share price as looking reasonable. The actual share price is 710p! So I must have missed something here - there must be some hidden value in the group that isn’t obvious from these interim numbers.
Paul’s opinion - based on what I’ve seen so far, this share looks wildly over-priced, given it’s a low margin operator in a tough sector that seems to be embarking on a macro downturn.
Do any readers understand why the market cap is anything like this high? Particularly given that the cash from disposals has already been paid out?
If the potential bid from the Netherlands falls through, then I could imagine this share re-rating downwards by a huge amount. It’s probably only worth about a quarter of the current share price based on my reading of the interim numbers. Although as I say, there might be something important I’ve missed, as I’ve not looked at this share for 4 years.
Hence risk:reward looks extremely poor to me. RED.
Lookers (LON:LOOK)
128p (£489m) - Interim Results - Paul - AMBER
Lookers plc, one of the leading UK integrated automotive retail and service groups, today announces its unaudited interim results for the six months ended 30 June 2023 ("H1" or "the period").
Good trading performance despite macroeconomic headwinds
I’ll keep this brief, as it’s in a bid situation, with a Canadian suitor having already increased the bid from 120p to 130p, but failing to gain much in the way of acceptances, so there’s a chance this might fall through. When that happened once before, the share price plunged, then the higher bid came through.
The 130p cash offer is recommended by LOOK management, and a shareholder vote is imminent, for 5 Sept 2023.
So this is a tricky situation, where each investor has to decide for yourself whether to hold on for the bid, which involves accepting the risk of a say 20%-ish fall in share price if the bid falls through, which seems a distinct possibility. Would the bidder raise the price again? Could another bidder get involved? Is there a risk that the bid premium might take LOOK shares too high relative to its listed peers? Who knows.
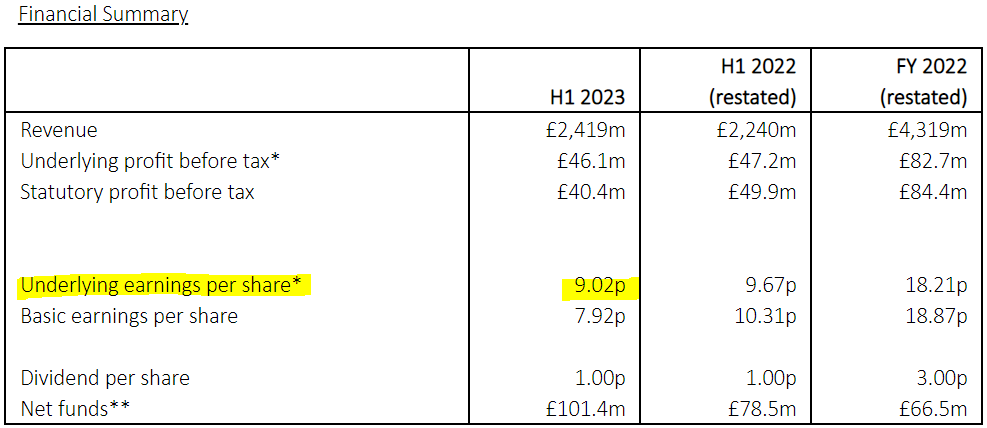
I interpret this table positively. Car dealers had a bumper year in calendar 2022, yet it’s almost matched the EPS in H1 this year too. There wasn’t any seasonality last year, with H1 & H2 being very similar, yet the broker consensus for FY 12/2023 if for EPS to drop to 14.2p. With 9.0p already in the bag for H1, it seems likely that LOOK could be on track to beat 2023 forecasts perhaps.
Note how finance costs are rising steeply, to £18.3m in H1 (£11.6m H1 LY) which is a worry I have for this sector, as they often use large loans to finance inventories, which is an increasing headwind.
Going concern - the “material uncertainty” is a red herring, as it only applies to what might happen after the takeover bid goes through, which is irrelevant to us, as shareholders would no longer be shareholders then! There is a clean going concern statement for the group as it currently exists (i.e. if the takeover bid were to fall through). Solvency and balance sheet look fine to me.
Paul’s opinion - trading remains robust at LOOK, which could have nice read-across for other shares in this sector perhaps?
It seems that LOOK could beat forecasts, given the strong H1 performance, so the fwd PER of 8.8 is possibly less than that in reality. Although how long will fairly robust trading remain, if (as most people seem to now be expecting), higher interest rates push us into a hopefully only mild recession? People tend to buy fewer cars in recessions, but these days many new cars are rented on personal leases, so it’s not really a big ticket purchase, if you’re paying say £300 per month for an essential mode of transport.
The increasing squeeze on mortgages though is bound to hurt households, who might decide to keep an existing car for longer. There again, retired people who are now earning interest on their savings for the first time in 15 years might decide to splash the cash and treat themselves to a new car. It’s so difficult to predict these things, and often what happens seems to be the complete opposite of what many of us expect! That’s certainly one lesson from the last 3-4 years of chaos.
Personally I’ve banked my profits in the car dealers, as they’ve had a good run this year, and I wanted the money for other buys. Although the bid interest in the sector could continue, and they all look cheap still, so that might have been a mistake, who knows?!
I view LOOK as AMBER currently, as it looks a good business, seems to be performing ahead of expectations (for H1), but I wouldn’t want to take the risk of the bid falling through, just for a couple of pence upside.
Tribal (LON:TRB)
44.5p (£95m) - Interim Results - Paul - AMBER/RED
Tribal (AIM: TRB), a leading provider of software and services to the international education market, is pleased to announce its interim results for the six months ended 30 June 2023.
I’m not keen to spend any time on this accident-prone education software business, but it did jump 15% yesterday on publication of these interim numbers, so let’s have a quick look.

The NTU contract was a disaster, and quite significant financially, so I’d want to know what the terms of an agreed settlement are, before even considering an investment in Tribal. Although there could be a relief rally on news of any settlement maybe, removing a big uncertainty.
I tend to ignore all the adjusted figures here, and look at statutory numbers - which are surprisingly good actually - PBT of £5.9m in H1 (up 89% on H1 LY), on revenue of £43.4m.
Balance sheet - this is grim. Writing off the £76m intangible assets, NAV of £49.6m becomes NTAV of £(26.4)m. It’s true that software companies don’t really need a big asset base, but I dislike the working capital section (£24.6m current assets, but £40.5m current liabilities), plus a sharply increase £14m “borrowings” creditor in non-current liabilities.
That might just about be acceptable in normal times, but with a large potential legal liability over the disputed Singapore contract hanging over it, a weak balance sheet is not a happy situation. A very bad legal outcome could for example panic the bank, and require an emergency placing. I’m just flagging potential risk, not trying to predict what will happen.
Going concern - the Directors give themselves a clean bill of health, which auditors do check, so maybe I’m worrying too much about solvency?
Paul’s opinion - on a very quick review, I think this is looking better than I expected.
However, a weak balance sheet, and a large legal dispute over a botched contract, mean it will take more than just one decent update to convince me it’s worth paying £95m for what has historically been a disappointer. But we’ll keep an open mind, and as I always mention, software businesses are often bid targets, even if they look hopeless as standalone businesses. Proactis, and Tungsten were both good examples of that.
Let’s move from RED to AMBER/RED, to reflect a seemingly improved performance, but with continuing reservations.
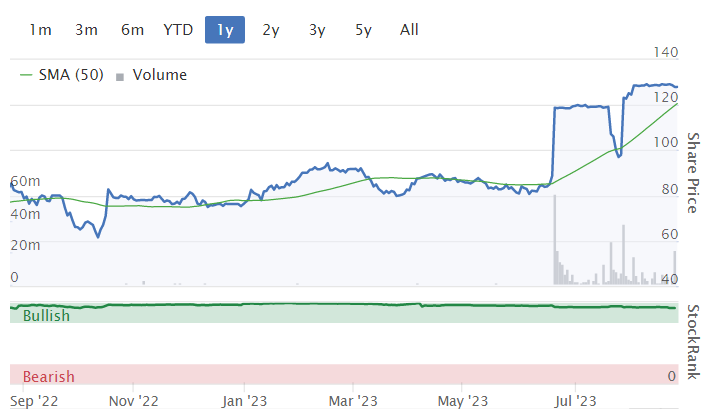
A long-term serial disappointer, but with some strong rallies from the lows along the way - one to think about trading, rather than investing, possibly? Whatever floats your boat! -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

67 comments
Tribal (LON:TRB) I'm quite shocked that Tribal has bounced following the update. It should definitely still remain red in my view.
It is important to note that Tribal consistently has negative free cash flow. Management come up with various excuses for why they don't generate any cash as the net debt continues to climb.
The main reason given is to do with the investments that they are making in their platform as they have moved to a cloud solution. Millions are poured into development costs every year; however, it results in very limited growth. At some point these capitalised costs will have to work their way through the income statement which will be a grim day for profit numbers.
Please see a snapshot from their latest numbers. As you can see, the development costs in the period (H1 2023) were £4.635M. The amortisation charge was £607K (this charge went through the P&L). If these development costs were expensed, instead of capitalised, it would nearly wipe out the entire £4.7m of statutory profit. Please note there are other drains on their cash too.
Tribal are managing to hide this in the accounts by increasing the useful life of their software, which they have now done a few times in their results. Increasing the useful life helps to keep the impact on profits low (for now!) but it will catch up to them and shareholders eventually.
The only way out of this hole is through rapid growth and unfortunately fast growth in their target areas is very very difficult. In addition, they are in a finger pointing game with NTU, in Asia: a region that was meant to be a source of growth!!
Hi ! I hope you're enjoying the long weekend.
My Top 20 watchlist for 2023 is now only up 5% YTD (down from 8-9% recently). But that's way better than AIM All share, which is about 12% down YTD. So I've got a 17% out-performance there on my share picks for this year, pretty good!
My SCVR summary spreadsheet is now up-to-date (I update it each Saturday). You can search using CTRL+F for any company's ticker, which quickly finds our reports. Hover over each company ticker, and a box pops up with a quick summary of our view. And it's all colour-coded. If you've not seen it before, have a look - it's very useful as a quick look up tool. I use it every day myself, to quickly get up to speed on any share we're writing about in the SCVRs.
This week's podcast went up yesterday. These are available on podcasting services such as Apple, Google, Spotify, Audible, etc. (search for "Paul Scott small caps" or similar).
If you're not familiar with podcasts, then the web version is here. They're free, and with no ads!
My podcasts summarise the week's SCVRs, and mention a few other shares which we didn't have time to cover, or were too small, eg Plexus Holdings (LON:POS) [I hold] which I think looks interesting, with a large contract announcement. Cenkos says will move it back into profit this year, FY 6/2024. Up-front milestone payments should mean it has enough cash. High risk, potentially high reward I would say. I'd be interested in your comments, bull (or more likely bear!). The history of Plexus is interesting - profitable before 2015, but the collapse in oil exploration after the oil price crashed in 2014 pushed it into multi-year losses. Despite this, it clung on, but now seems to have turned a corner, with royalties from a licensing deal (recently extended) with Schlumberger expected to kick in next year.
Plexus's well head designs prevent leakage of harmful methane, which is apparently now becoming an environmental priority, so it looks to be in the right place re ESG. I know nothing about oil services, so I'm keen to hear from other investors. I'm aware of Plexus's dire history in recent years, but the important thing to focus on is the RNSs in the last year, showing considerable progress it seems. The £5m contract win (for rental) was recently extended to £8m, and will all be recognised as revenue in FY 6/2024. That means revenues are increasing by about 6x historic level, and losses should be eliminated in FY 6/2024. I'm hoping it's not just a one-off.
There's further dilution possible from the CEO & Chairman who propped up the company with a convertible loan in late 2022, with conversion terms being a 20% discount to the share price when converted - an incentive for mgt to keep the share price low. Cenkos says there is a commitment to also offer outside shareholders an opportunity to put in fresh funds on the same terms.
All in all, a high risk, but potentially interesting special situation I think, where there does seem good evidence of the tide having turned. So the mkt cap of only £6m still looks appealing to me, although I think I was the main buyer last week, so was worried that I was pushing up the share price against myself.
Anyway, if you do speculative nanocaps, and accept the risk, take a look & let me know what you think of Plexus Holdings (LON:POS) . Thanks.
Paul.
Hi Paul, Interested to know how you got on with the request for an interview with Oxford Metrics (Oxford Metrics (LON:OMG) ) (12th June write up notes)? One of my larger holdings, and come back into 'top up territory' price for me, but doing some work on single product risk and I know that was one of your main questions you were looking to test with the team? Maybe I have missed it already, but great to hear how you got on with potentially planning that one in!
Hi TRADERWEEKS,
No, I didn't manage to speak with Oxford Metrics (LON:OMG) . Sorry about that.
Regards, Paul.
Ok, thanks for the feedback!
There have been a few comments on liquidity recently. I know that the main index charts include the volume data, but I use the closing price * volume as an indication of the value. There are probably better ways to do it, and perhaps some of the level2 data will show you this anyway (would include the summation of trades rather than my simplistic averaging). If anyone knows that this is available, then I would be interested. Anyway, for what it's worth, for AIM;
I calculate total market cap (for the whole market & just AIM) and then normalise this against the relevant index (just for a sanity check). The peak in mid August I think is mainly down to EMIS.
For the UK market;
Interestingly the peak in mid June seems to be from the Odey affair as far as I can make out.
Not small cap, but I am finding it difficult to resist topping-up renewable energy infrastructure trusts (wind, solar and battery) at the moment - yield is typically 6.5-8% and they are on a c20% discount. Seems too cheap for an inflation linked and very high quality income stream, if you can ignore short-term pain. Investors are marking them down badly because of gilts yielding 5% for no risk, discount rates having increased and power prices having reduced from last years highs.
I am buying because I can see a good opportunity for a 10% annual return from here - i.e. eventual closing of the discounts and 8% annual return largely embedded in the discount rates being applied.
Own all of these 10 now: Renewables Infrastructure (LON:TRIG) Greencoat UK Wind (LON:UKW) Bluefield Solar Income Fund (LON:BSIF) NextEnergy Solar Fund (LON:NESF) Bluefield Solar Income Fund (LON:BSIF) Pantheon Infrastructure (LON:PINT) Foresight Solar Fund (LON:FSFL) Gresham House Energy Storage Fund (LON:GRID) JLEN Environmental Assets (LON:JLEN) Harmony Energy Income Trust (LON:HEIT) - anyone else thinking the same?
Hi Topvest. I am similarly tempted by the renewable energy Inv Trusts for the reasons you give. In particular, I am interested in those that are making progress in energy storage investments. I am also hoping for some geographic diversity. Looking at those you mention (and any others that I come across) is my homework for the weekend to narrow down to maybe two or three.
Cheers, Mark
Topvest I can see the investment case for these trusts and am particularly interested in NESF but have reservations about the risks from a change in government policy, subsidies or regulation. What are your thoughts?
I personally think there is more likelihood of a positive change in government policy than negative given the net zero targets. Investment in new renewables is tailing off as companies are finding it more difficult to raise finance.
Just take all the listed infrastructure comanies that are all now on a discount and so cannot raise new equity for investments, by way of example. A year ago they were spending like crazy!
I’m tempted too for the reasons you gave but so far have only bought NextEnergy Solar Fund (LON:NESF) . I rarely buy more than 3 Investment Trusts in any one sector for fear that if we are wrong we would have too may eggs in the one basket. But I have broken that rule by holding several Commercial Property Trusts, and as the renewable infrastructure yields are also very good, there’s a case for holding a lot of the sector.
Good luck with yours!
Most of the renewable funds have limited life assets. Take NextEnergy Solar Fund (LON:NESF) as an example. It's solar assets have a current average life of 26.1 years. So although the current dividend is 9.6%, you would loose a large chunk of this to the reduction of NAV for each years that passes, as the value of the assets eventually tend to zero.
The wind farm VCT Ventus recently sold all its assets due to this problem and redistributed the cash to shareholders. The closer you get to the end of life, the greater the reduction in NAV, but even with 26 years remaining, with the 8% discount rate that NESF use, and assuming a 3% uplift each year in income, there is still around a 6.5% theoretical reduction in NAV per year currently.
Good points rpannell. Thanks.
Re: Renewable Energy Funds
there is still around a 6.5% theoretical reduction in NAV per year currently.
I have shared your concern. I still do to some extent. Though some of the funds would concern me more than others.
The thing is, if the theory of the DCF (discounted cash flow) was working then by now we'd expect to see some substantial falls in the NAV per share of these funds as they all went out at IPO and purchased similar lifetime (well not longer anyway) assets on the secondary market?
The current leader of the pack Greencoat UK Wind (LON:UKW) with an MCap of £3.2Bn has been listed for just over 10 years unyet its NAV per share has risen from 100p on listing to 166p in the recent interim results. With 10years being around a third of the average lifetime of its asset base the NAV per share should have fallen significantly over this period - if the theory was working?
It seems that there are other factors than the DCF at work? Or the assumptions built into the DCF may not be a reasonable best estimate of the future? In particular the terminal value of the assets is something that I think may not be well modelled in the DCF?
On that I note that Renewables Infrastructure (LON:TRIG) has just disposed of 3 Irish windfarms 'close to end of life' for £21.4m a premium of 26% above the DCF valuation for the assets at December 2022. It seems that the DCF may not be very accurate even when very close to the end of life? If so, then how accurate will it be with 26years or more still to go?
Another factor is that both Greencoat UK Wind (LON:UKW) and Renewables Infrastructure (LON:TRIG) appear to have played the game very well so far. They've both raised massive equity funds repeatedly while their shareprice was trading at a premium to NAV to invest in new assets. They've also raised significant debt (leverage) maybe 20% of their Gross Asset Value. They've also changed their investment rules to allow them to invest in different classes of assets including assets under construction. Helping them to substantially escape the timeout trap with all their assets going end-of-life at the same time as well as raise the IRR they expect on their projects? They must be a significant distance towards evergreening their funds I should think? Much further to go but it seems that they have demonstrated the ability to do this so far.
None of that means that I know whats going on. Because I can't foresee the future. But neither does a DCF. It may be that the ability of these funds to raise their NAV per share over the last 10 years rather than it fall as the assets move towards end of life is due to exceptional circumstances? But the longer the exception continues - the less exceptional I think it to be?
cheers
Mark (disclosure - I used to hold Greencoat UK Wind (LON:UKW) Renewables Infrastructure (LON:TRIG) JLEN Environmental Assets (LON:JLEN) and so on in my porffolio. I don't any more as I have concentrated and focused my portfolio on around a dozen UK small caps. Aim listed mainly. Just to prevent my life becoming too predictable or too boring. I do still hold these funds in an ISA I manage for someone else.
Looks like we have another Direct listing on the Main Market today.
The company in question is called "RegTech Open Project" and will have the ticker "RTOP". It's a technology business specialised in the automation, management, and optimisation of regulatory compliance operations.
Judging the size of the company, it looks like it will enter the micro/small cap universe. Link to the announcement below if anyone is interested.
https://www.londonstockexchang...
I’d suggest anybody interested in this pays close attention to Mr Zamboni’s other London listed venture…
I was just about to say the same thing Rhom. More red flags here than a Chinese tourist shop
FFS its this joker again
Watches of Switzerland (LON:WOSG) Some info for anyone interested.
"Peel Hunt on Friday said it is "almost impossible to believe" there will be no change in the relationship between Rolex and Watches of Switzerland-rival Bucherer, after the watch maker bought the watch retailer in a surprise decision announced on Thursday.
The broker noted Bucherer currently has 48 sales outlets out of just over 100 worldwide that don't distribute the Rolex brand. "That may change," it said, creating a negative for Watches of Switzerland over the longer term.
Peel Hunt cut its rating on the FTSE 250 stock to 'hold' from 'buy' and its price target to 600 pence from 900p. Watches of Switzerland shares were down 19% to 560.99p on Friday afternoon in London.
In its announcement of the acquisition of Bucherer, Rolex explained that the two companies have a relationship forged by their respective founders going back to 1924. Jorg Bucherer, the 86-year-old grandson of founder Carl Bucherer, has no direct descendants and so had decided to sell the company. Rolex said it stepped in to preserve their partnership.
Bucherer will keep its name and continue to operate independently, Rolex said, adding: "The fruitful collaboration between Rolex and the other official retailers in its sales network will remain unchanged."
Peel Hunt wasn't convinced.
"If our suspicion is right and the shape of global Rolex [product] allocations evolves, it is unlikely to be a positive for WOS," the broker said "Around 50% of its sales are Rolex, so other brands will have to step up, but sentiment will be harmed."
For its part, Watches of Switzerland on Friday said it the acquisition doesn't represent a strategic move into retail by Rolex, and there will be no change in the product allocation or distribution of Rolex watches.
Watches of Switzerland said it had this "confirmed by the highest level of Rolex management" in Geneva.
Jefferies kept its 'buy' rating on Watches of Switzerland shares, but agreed the Rolex move "may add new concerns to the WOSG debate".
The US investment bank pointed out that Watches of Switzerland is holding an investor event in the autumn, and this will provide the company with "the opportunity to assuage potential new fears in the market".
Peel Hunt concluded: "The concerns about Rolex's plans are likely to act as a cloud over the shares for the foreseeable future, and it would be hard for WOSG to be expansive in its long-term planning given the uncertainty."
For a contrarian view to what the brokers have commented on this significant news, I think it's worth reading this article on the ABlogToWatch website which has provided leading and longstanding commentary on all things related to the luxury watch market for over 15 years.
I don't have a position in WoS but it's long been on my Watchlist and will continue to be so until if or when I figure out a suitable entry point.
In the current market there is an awful temptation to average down which many experts nearly always advise against.
I hold 3 Shares which in the past have yielded major profits but are now at their lows for different reasons.
Ferrexpo (LON:FXPO) has yielded some £60k in profits since 2016. Current SP 78p due entirely to the Russian invasion of Ukraine. A very well run Company but now very high risk for obvious reasons.
GB Group (LON:GBG) £15k profits in recent times now 227p against a year high of 658p.
The issue seems to be that the Company overpaid for an acquisition in USA. Very tempted to add at this level.
Fresnillo (LON:FRES) £10k profit from a single trade in Sept 2020 but heavily down on a holding which is 6% of my portfolio. Largest Silver Miner in the world very tempted at 557p against a year high of 997p.
I would welcome any pearls of wisdom from the community to my dilemma.
In the current market there is an awful temptation to average down which many experts nearly always advise against.
Which experts? I keep reading this on this blog and it's utter rubbish. If you're a trader, I can see that it's all about momentum and you would avoid downtrends, but if you're an investor and the investment case still stacks up, why would you not buy something when it is even cheaper? It's two completely different mindsets. You just need to decide whether you're a trader, an investor, or maybe a bit of both. But this idea that you can't make money over the medium to long term by averaging down on good quality companies with sound balance sheets is complete nonsense.
I quite agree, Simoan. Averaging down = Buying the dips
Portugull, as Simoan says you have to decide if you're a buy and hold investor or trader. There's some excellent investors but you dont hear from them often as they're not watching daily price movements.
As a trader the trend is down in all 3 so Id focus on how much im prepared to lose setting a stop loss. If you buy more, dont set a stop and things get worse you've just geared up your losers.
Ferrexpo (LON:FXPO) Nope.
GB (LON:GBG) Nope (tho could be tempted soon)
Hi Portugull,
I hold Ferrexpo too.
Option 1 either Ferrexpo runs out of money before they get access to the black sea and the share price goes to 0.
Or option 2, the Russian invasion ends, Chinese steel manufacturing increases and the share price returns to 300 pence.
If you feel the odds of option 2 are greater than 26% then topping up could be the correct option.
Cheers.
Psychologically averaging down gives me a nice warm feeling, I need the price to recover less ground to turn it into a winner instead of a loser. Instead of being 20% down I can be 10% down and not feel such a loser. I don't have to admit I was wrong with my first buy... it's a win, win!!
My experience as a relative novice/amateur is that it's easy to get overexposed to a falling stock with poor momentum/market sentiment and to accelerate paper losses and pain.
I'm certainly no expert, and of course I have averaged down and made gains, but my general approach now is to try to ignore what I have previously gained, lost or am holding. I try to start from scratch as if I am thinking of buying the share for the first time and to go through my normal process.
What has changed recently to drive down the price? What might change this direction of travel and in what timeframe?
Would I make a first buy at this price with all the current fundamentals/knowledge I can find?
How many shares would I buy if this was a first buy? What would be a sensible position?
Is this more than I already have? Then buy some more!
Mostly I take a trading approach. I bought Ferrexpo (LON:FXPO) as a gamble on the war ending when the price started to settle around 120p and sold as it continued down to 105p. I'll be all over it when the war ends, but in the meantime I don't want to watch my capital drip away.
The war is unlikely to end overnight, and even if it did the price is unlikely to return to 300p immediately. If I miss the first jump I'll be disappointed but I expect I'll be quick enough to make decent gains.
Equally I might hop in again sooner with a tight stop if the price stabilises, with a warm feeling that I can now buy at a lower price than I sold for.
It concerns me that CMC Markets (LON:CMCX) derives much of its revenue from spreadbetting (which is only legal in the UK and Ireland as far as I know) - I assume that there is a distinct possibility that spreadbetting could be banned or further regulated. Or perhaps it will be permitted in other countries......
I don’t hold CMC Markets (LON:CMCX) but I think you’re missing that spread betting and CFD trading tend to be used interchangeably (even tho they obviously aren’t the same and are only similar).
So whilst spread betting is legal in UK and Ireland, CFD trading is legal across Europe and Australia. CMC, IG, Plus500 etc Operate across these jurisdictions offering products tailored to the specific market. That’s why if you go to a UK website you’ll tend to see spreadbetting used as the term but in other countries it will be CFD/Forex trading.
Find it highly unlikely that spreadbetting or CFD trading will get banned. A review was concluded only a few years back by the FCA and changes made to the market.
I do however, think the current interest rate environment has significantly changed the spread/CFD market. When rates were free you could happily hold leveraged exposure for long periods at minimal funding cost (couple of %) which meant people took out longer term positions. At closer to 8% funding costs today that clearly decimates returns. I suspect these companies are seeing the effect of that hence the trading warnings despite moderately volatile markets.
I’m not convinced we see an end to that change in behaviour any time in the near future personally so it does make me wonder what that does to the business model.
Liontrust Asset Management (LON:LIO)
Research firm Peel Hunt has upgraded Liontrust from an ‘Under Review’ rating to a ‘Buy’ in the wake of its failed bid for GAM.
Analysts said that the failed offer “de-risks” the investment case for Liontrust.
The team noted the asset manager’s share price had been “significantly impacted” by fears over the GAM acquisition and believe it should now rally.
Peel Hunt added: “In our view, GAM would have brought significant execution risks but uncertain financial benefits given continuing falls in its assets under management. Strategic issues arise; further M&A is possible with Liontrust as either predator or target.”
“Management has signalled its willingness to undertake large, complex acquisitions in the context of its desire to diversify the business away from its current over-weighting of UK retail investors and equities.”
“There is a risk, in our view, that further M&A could follow. Conversely, the fall in Liontrust’s shares and currently low valuation multiples could render it as a target for others.”
On Liontrust Asset Management (LON:LIO) I haven't heard any update on this...
"Liontrust has also agreed to provide GAM with two equal tranches of short-term secured Financial Support in an aggregate amount of up to £17.8 million under two separate facility agreements. The first tranche was made available under the Tranche 1 Facility Agreement which was entered into prior to execution of the Transaction Agreement and the publication of the Pre-Announcement and the Announcement. The final maturity date under the Tranche 1 Facility Agreement is 31 December 2023."
If its not repaid and GAM get into financial difficulty then maybe they can pick up the pieces at a very low price without much of the overhead cost?
Not sure how it works. Does this cash figure exclude customer cash?
Oh yes, sorry I meant to say, CMC Markets (LON:CMCX) has customer cash segregated, ie not on its balance sheet. I'll add that point to the article now...
I bought back into IG group (LON:IGG) recently after selling a couple of years back to take a profit (those were the days!). It struck me that the price was relatively soft, the Company was cash liquid, and it was buying in shares to cancel, and offering a 9%ish dividend (according to Stockopedia at the time). So whilst admittedly its difficult to predict volatility which tends to favour their trading platform, there was a pretty solid base for getting in at lowish price.
As Paul has also pointed out with CMC, IG's cash resources should also generate higher interest income, giving them a boost of sorts.
Regulation is always the bugbear with these types of shares, but taking these factors overall I decided to take the plunge.
I was about to buy, then looked at director deals - all sells- and that put me off for now.
Most of them were share options, though.
CMC Markets (LON:CMCX) (I hold) will be demoted from the FTSE 250 very shortly, that's the bad news and I believe it's been falling in expectation as well as trading poorly, you would expect that the share would fall further once institutions are forced to sell out after demotion but bizarelly on the limited research I've made shares tend to do the opposite to expectation
Kinovo (LON:KINO) (I hold) Paul, if you're not too busy I'd love your take on the shenanigans going on with what I see as the miserly potential offer from RX3 yesterday and the ensuing rns's this morning. Thanks
Hi threeputt,
Thanks for the point re CMC Markets (LON:CMCX) demotion from FTSE 250, I wasn't aware of that. Could make things volatile, as you say. Presumably people anticipate that and sell in advance if they need to? Could be one factor in creating such an unusual discount to the company's own liquid assets?
I noticed the lowball takeover approach for Kinovo (LON:KINO) yesterday. It's not something I can add any value to, as unfamiliar with the company, and everyone can see the offer looks mean, which is all I would have to say on the matter.
CMC has all the hallmarks of a P&L account which is being depressed by both weak cyclical trading and heavy tech investment spend ahead of cheeky take private. I suspect Cruddas is both disillusioned and embarrassed by the listing given his political activities. Taking a position here is a coin flip given minorities are price takers.
30% down on Watches of Switzerland (LON:WOSG) now, it was on my sell list! Drat, what to do?! Think it's an over reaction but probably best just to exit...
Watches of Switzerland (LON:WOSG)
Response to acquisition of Rolex SA of Bucherer SA - 07:45:03 25 Aug 2023 - WOSG News article | London Stock Exchange
Crikey, SP down over 20% on the back of this.
Watches of Switzerland (LON:WOSG)
Still falling. Does that mean they won't be able to sell Rolex?
The implication of the sp drop is that there is a chance Rolex have had a change of strategy and want to have the whole pie by retailing direct. Personally I doubt this is the case and that they have bought Bucherer SA for the reasons WOSG give in the RNS. If you believe that, this could be a quick trade possibility.
I have traded WOSG before but if i had held long term i would have looked into their agreements with Rolex and others manufacturers to see how tight they were.
RE: Watches of Switzerland (LON:WOSG)
The implication of the sp drop is that there is a chance Rolex have had a change of strategy and want to have the whole pie by retailing direct. Personally I doubt this is the case and that they have bought Bucherer SA for the reasons WOSG give in the RNS if you believe that this could be a quick trade possibility.
From the RNS:
All of the above is reviewed and confirmed by the highest level of Rolex management at Rolex HQ in Geneve and locally in the UK and US.
Unless WOSG are lying it looks like this is an overreaction. But the herd is easily spooked these days.
Of course, if Rolex were to go into direct retail their next obvious move would be to buy Watches of Switzerland (LON:WOSG).
timarr
Apparently ... Rolex contract has 3 months notice on it. A headache holders don't need however tempting the bounce trade is. (Unverified X gossip but worth looking into).
Well D2C is only going one way. We all know that you cannot buy product from a manufacturer and then try to compete with them on price. Hence the end of the Department Store model and the likes of Decathlon, Go Outdoors. Angling Direct John Lewis ( amongst many many others)scrambling to build credible own brand ranges.
Unless WOSG are lying it looks like this is an overreaction. But the herd is easily spooked these days.
However the worry is that Rolex may not be telling the whole truth or may 'change their mind' in the future.
My view is that Rolex didn't have much choice other than buy Bucherer but may review their position in the future.
Personally I doubt this is the case and that they have bought Bucherer SA for the reasons WOSG give in the RNS. If you believe that, this could be a quick trade possibility.
My thought too. Rolex would be cutting off its own nose to cut ties with all those distributors. It would be a multi-year process to replace them all.
At this price, maybe Rolex will buy Watches of Switzerland (LON:WOSG) too!!
Then again, in watches and jewellery, I prefer to own COMPAGNIE FINANCIERE RICHEMONT SA (SWX:CFR) which is looking stupid cheap for the world’s second largest luxury group.
Any idea anyone what is the % of ROLEX in the WOSG (I hold) luxury watches market? I couldnt find this info in their latest annual report, I guess it's not something which is normally disclosed in the financial reports?
No exact numbers but watches were 88% of WOSG rev and Rolex has a 30% share of the world luxury watch market .
No exact numbers but watches were 88% of WOSG rev and Rolex has a 30% share of the world luxury watch market .
I think these numbers underplay the significance of Rolex to WOSG. It’s their main cash cow.
Just found this: This is unlikely to be positive for the UK group, said Peel Hunt, pointing out that over 50% of sales by Watches of Switzerland are Rolex. Link: Watches of Switzerland drops 27% on Rolex deal news | LSE:WOSG (proactiveinvestors.co.uk)
Published in the FT …
‘However, some analysts warned the deal could have a substantial impact on the UK retailer, which generates 55 per cent of its revenues from Rolex products.”
Zenova (LON:ZED) Zenova might be worth a look today. I don’t think it has been covered here before. Growth stage company so quite speculative but I hold. I have bought one of their products the Zenova FX500 which is small home fire extinguisher and will deal with any fire type. They also sale fireproof paints etc.
Thanks for flagging. I've done a short review of it, just to get something in the system here. When you read it, you'll probably wish you hadn't mentioned Zenova (LON:ZED) !!
Zenova (LON:ZED) Imagine being a new company coming to market and you don't bother to use a broker providing forecasts to private investors. Dont raise enough cash at IPO, try winging it, but crash the share price anyway.
Cant get my head round it. I like the products but they must be fighting over the dunce hat at board meetings.
At least they live streamed the pre IPO risk management and risk responsibilities meeting :)
That's exactly how I felt after reviewing the figures from Anexo (LON:ANX) , CentralNic (LON:CNIC) ,and Tremor International (LON:TRMR) recently!!! :-)
You do a very fine job Paul, much appreciated.
Thankfully freeing the rest of us up to get side-tracked watching old episodes of Minder and Bullseye on youtube.
Minder loved it Wolfie back in the day no good when Tel left but him and Arthur were pure gold together and pursued by the hopeless Chisholm.
The episode with Ian MacShane as the villan was brilliant when they get the videos mixed up.
I liked Minder too, but preferred The Professionals with Bodie & Doyle, and the Fords (RS 2000, and Capri 3000S). Amazingly, in the first episode or two, they actually drove an Austin Princess, and BL also supplied other cars. They kept breaking down, so were replaced by Fords apparently. In the opening credits, Cowley is driving a Rolls-Royce Silver Shadow at high speed, amazingly.
Also of course The New Avengers is on my watchlist. The cold war/ mad gadgets plots there are hilarious! Purdey (Joanna Lumley) in a yellow MG Midget, and Steed in a flared wheel arch Jaguar XJC, and of course Gambit in an XJS - superlative!
These days, I relax after work binge-watching Bangers & Cash - the classic car auction show. It's brilliant - all the cars have a story, before and after the auction. On my wishlist, is a Rover P6 V8. It's like an itch I can't get rid of, the urge to own one of those (like Grandad's pride and joy).
I had a gold 3.0 S Capri with black “go faster” stripes, brilliant car. Also (before that) had an old Mark 3 Cortina which was a different experience altogether but a lovely car to drive. Ford had it all in those days (late 70s/80s). My brother and I liked watching Starsky & Hutch for the car action…
For Ford Capri and The Professionals fans, two Capri’s driven by Doyle up for auction this weekend, guide price £200k - £230k (for the two)
https://www.iconicauctioneers....
Amazingly, in the first episode or two, they actually drove an Austin Princess, and BL also supplied other cars. They kept breaking down, so were replaced by Fords
Oh that hurts!
Quite a comprehensive list of the cars here
http://www.mark-1.co.uk/Profes...
Quite fun to watch for the location spotting - particularly the deserted closed down factories and warehouses around North London and Watford. And the range of cars, trucks and vans as extras throughout. Though the dolly sprint has to be the star of the show for me.
cheers
Mark
My morning smallcap tweet: Bum's the word
CMC Markets (LON:CMCX) Shearwater (LON:SWG) Zenova (LON:ZED), DWF (LON:DWF)
◄CMC Markets (CMCX)► warns Aug rev down 20%. If weak market conditions continue guides net operating income £250-280m. [SP=122 Cap=341m]
◄Shearwater (SWG)► finals delayed to 5 Sept due to slow audit. Recent Q1 rev up as a number of the delayed contracts have now been received. Confident in seeing a much improved FY financial performance. [SP=38.52 Cap=9m]
◄Zenova (ZED)► H1-May rev £108k (£75k). Outlook: expects "large orders from new key customers as well as increased uptake from existing customers and distributors. Executing on new and existing contracts should result in stronger top-line performance " [SP=5.5 Cap=6m]
In line: DWF
Wondering if this more +ve update signals a bottom for SWG? The sp decline has been catastrophic, mkt value now under £10m.
"Following the trading update in June and mindful of the delay in FY23 results, the Board also provides an update on Q1 trading for FY24 in which it confirms expected improving traction as a result of more favourable market conditions.
A number of the delayed contracts have now been received and revenues in the first quarter exceed levels for the comparable period last year. The significant investment made in the Software Division is now delivering on a number of promising opportunities and with market conditions in the sector being more favourable, the Board is confident in seeing a much improved financial performance in the current year."
Shearwater (LON:SWG) Its been a clear avoid , but if this rise sticks looks like it could be in play now. I like a gap up on a downtrend, can signal a switch in sentiment.
Its a serial disappointer tho, but at least forecasts were positive free cash flow.
I'd like to see why the auditors are taking their time completing the audit, for some reason I have little trust in Shearwater (LON:SWG) , I'm keen to see the results before potentially investing but of course I could also miss the boat by then
CMC Markets (LON:CMCX) By coincidence, I was doing some research into IG group (LON:IGG) yesterday and had come to the conclusion it was a buy (but not pushed the button). Will be interested to see how impacted they are by the CMC announcement: hard to believe that they will not be seeing something similar. Very little change in IG SP as I write this.