Small Cap Value Report (Fri 25 Oct 2024) - BOO, KOO, INDV, SCT

Good morning, it's Paul here today.
I have to leave it there for today.
There will definitely be at least 1 podcast this weekend! Not sure if I'm going to revisit the gap last weekend, or just draw a line under it, we'll see how things go.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
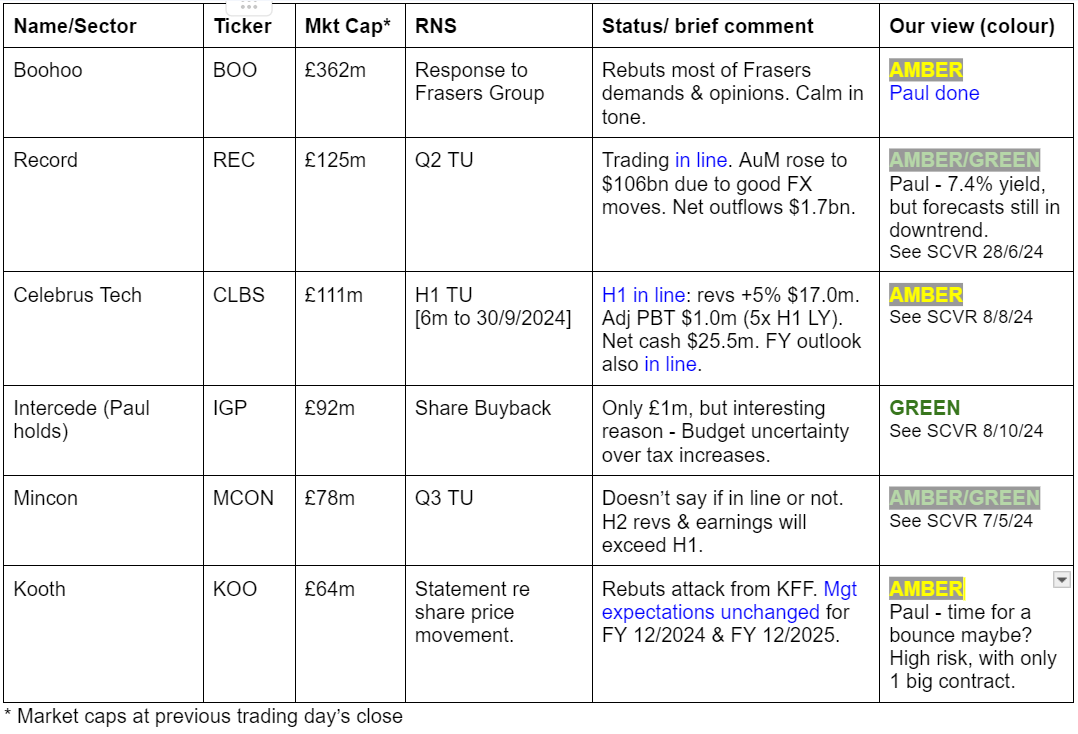
Companies Reporting
Paul’s Section:
Brief Comments
Boohoo (LON:BOO)
28.8p (£365m) - Conflict with Frasers - Paul - AMBER
Yesterday BOO announced that it had received requisition notices for an EGM, called by 27% shareholder Frasers (LON:FRAS) . This audacious move seeks to have Mike Ashley (founder & majority owner of FRAS) brought in as CEO of BOO, along with another FRAS connected party, Mike Lennon. It also seeks the removal of BOO’s CEO, John Lyttle, who had already announced his intention to step down a week earlier.
FRAS was highly critical of BOO in this open letter, dated 23/10/2024, describing its performance as “abysmal”. They’ve got a point, I briefly mentioned BOO last week here on 18/10/2024, with a weak H1 trading update accompanied by a big reduction in forecasts from Zeus. BOO likes to focus on EBITDA, but the real numbers are a forecast adj loss before tax of £(42)m this year. Getting into dangerous territory if things don’t improve. Bank borrowings were however refinanced recently, so that has calmed investor nerves somewhat.
It’s amazing to see how growth powerhouses Asos and Boohoo are now on their knees, due to increased competition especially from Chinese giant Shein, which is just undercutting them on price & promotions for customers who want fast fashion (which has also somewhat gone out of favour).
What happens next? BOO is still inspecting the legal paperwork (presumably hoping to find some flaw in the requisition paperwork). We should hear in the next few days whether BOO is forced to call an EGM or not.
As BOO says today, it cannot just appoint a large shareholder as CEO, because that would break all the rules on corporate governance. The question is whether Mike Ashley can muster enough votes to carry any EGM vote in his favour. It looks a close call, with FRAS on 27%, Schroders on 8.5% (who seem to like Ashley), but the founding Kamani family + employee benefit trust seem to total c.22%. There could be other connected parties with smaller holdings not disclosed, I imagine.
Is it worth getting involved? I’ve decided not to, because I think both Asos and Boohoo are now in real trouble (Asos could even go bust in my opinion). Whereas BOO is likely to survive I think, but sounds like it needs a big sort out to make it leaner.
FRAS prowling around trying to take control is not necessarily going to deliver the best result for BOO shareholders. Ashley is clearly trying to take control by the back door, rather than making an offer for BOO that probably wouldn’t get the necessary shareholder support. I’d say it’s more likely that the founding family might try to buy it back, but why would they be generous on price?
Given that BOO is now loss-making, what is it worth? It’s difficult to say. I don’t think fashion brands are worth that much these days, other than to foreign buyers or licensors.
FRAS strategy really worries me. It seems chaotic and too aggressive, with some fairly major mistakes made in the past, all driven by Mike Ashley with no constraints on his personal dominance due to him owning 73% of FRAS. FRAS seems cheap on a forward PER of 7.2x, but I can’t help shake off the feeling that it could all go horribly wrong in some unforeseen way, because of the way Ashley operates.
Hence my view is that it will be a fascinating situation to watch but only from the sidelines. I’ve no idea how things will pan out, so have to give BOO AMBER again, although maybe I should be more bold at amber/red? It’s finely balanced, but I’m definitely struggling to see a positive case for BOO given that Shein has grabbed its market, and BOO now loses money.
Softcat (LON:SCT)
Rose 12% y’day to 1,719p (£3.37bn) - Results FY 7/2024 - Paul - NO COLOUR
Worth flagging for the very positive market reaction to results out yesterday.
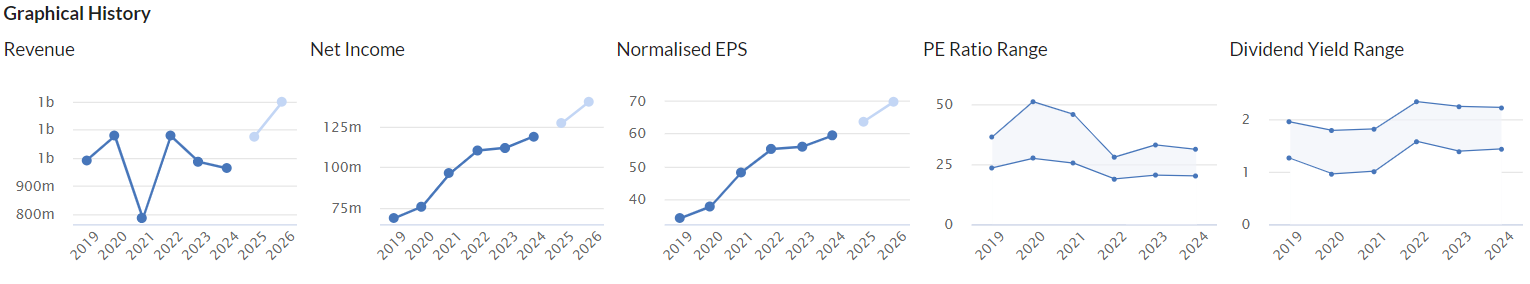
I’m not familiar with this company, so have only had a quick skim of the fundamentals. It’s got a very nice track record but looks pricey on a forward PER of 26x -
Indivior (LON:INDV)
Up 10% y’day to 720p (£886m) - Q3 Results - Paul - NO COLOUR
I’ve looked at this a couple of times this year previously, flagging that it looked potentially interesting on 25/7/2024. There was a profit warning shortly before that, which we touched on here 9/7/2024. Shares seem to still be in a downtrend, albeit with sharp bounces occasionally.
It might be worth readers taking a look, given that shares rose 10% yesterday on results. This is a complicated situation though, with a highly profitable business, but substantial litigation costs, and other issues. The StockReport is now showing a fwd PER of only 5.2x, a rating which tends to be a good indicator of there being something wrong! (or it’s a bargain). Let me know what you think, we’ve had some interesting discussion about Indivior before here.
Kooth (LON:KOO)
Down 9% to 160p (£58m) - Statement re share price movement - Paul - AMBER
I thought this share might bounce today, given that KOO rejected some critical press comments here about its lucrative Californian contract.
KOO says today that its outlook for FY 12/2024 and FY 12/2025 are unchanged. It would have been more helpful for KOO to tell us what those expectations actually are.
Another small pilot contract was recently cancelled, which started off this calamitous fall in share price, worsened by the article linked to above.
I see that on 8/10/2024 Root Capital did a secondary, discounted (12%) placing at 280p, so it is difficult to avoid the impression they might have got wind of potential problems maybe?
Paul’s view - it’s a pity because I was warming to Kooth, after decent interim results showing a strong rise in revenues, and a move into a maiden profit.
The recent share price collapse and talk of contract problems could be giving us a bargain, but I must admit that the single contract risk has scared me off now, and it looks as if the market generally shares that view. Good luck to holders, but this is looking like a coin flip now over whether or not the California contract survives. It could all be a false alarm, if the company is to be believed, or there could be serious problems here. How can we invest without knowing for sure which it is?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

107 comments
If there are massive outflows on AIM due to budget changes and prices drop accordingly my concern is that its simply going to be the "new normal" for the affected shares. We might look at is as a buying opportunity but what will be the catalyst to bring the money and demand back into the shares? Aim has been regarded as cheap for years and that hasn't been exploited by the "big money" to an extent that it has caught up. So if tax advantages are removed as well then why would they swoop in for the "bargains" (apart from perhaps a few outstanding performers).
Could the entire AIM become a value trap?
Just something I was thinking about this morning.
AIM companies always have the option of moving to a main market listing, especially the larger ones. Some would even be able to enter the FTSE 250 which would attract almost guaranteed fund flows.
I would assume that:
The only group of investors, post Budget, that will be barge-poling AIM are the money/funds specifically looking to save on IHT. As AIM shares will no longer be eligible.
Premier Inn Hub update. Although smaller than we are used to, the double bed was perfectly adequate for a really good night’s sleep. Furthermore, the linen is of good quality and the room stayed quiet and at a nice temperature all night long, thanks to the aircon. The shower is excellent.
Only a continental breakfast is on offer. But at a mere £6 with a great range of really fresh and appetising ingredients, it is exceptionally good value.
A final pleasant surprise was to find that some chocolates and two cans of cocktail mix had been secreted into our room while we were out, taking in a show. We established that this is not normally part of the service, so we appear to have received some special treatment. Maybe the manager is a member of Stocko and saw the first part of this review!
As a shareholder, I’m taking the opportunity presented by a visit to my London-based offspring of mystery shopping the Hub by Premier Inn in Covent Garden. I have to say I’m very happy with the experience so far. A nice lounge with free refreshments downstairs and an extremely clean and well-appointed room, if rather on the small side. The price is reasonable for West End London although at the highest end of the Hub concept and its competitors. It’s very quiet in the room and let’s hope we get a good night’s sleep. I think that will depend on the efficiency of the aircon.
That’s a small double bed, by the way. The wide angle lens distorts the proportions. Have a good Saturday night everyone
Amazing, thanks BnB! Quite a few of the reviews online have said the Premier Inn Pods are great for single occupancy, but bed too small for dual occupancy. Your photo reinforces that. There are larger pod rooms available I believe, not sure if they have a larger bed than the small double you showed here?
Will you get a full english in the morning?
Will you get a full english in the morning?
Mrs BnB will ;-)
Do you have to move the chair to get to the loo? Looks well presented, but on the cosy side?
Do you have to move the chair to get to the loo? Looks well presented, but on the cosy side?
No. the picture was taken from beside the bathroom door. The chair is in front of a window. The room is bigger than it looks, albeit certainly cosy. I should have stressed that I had to use a wide angle lens to get it all in. The bathroom is at least as big as you would get in any normal budget hotel. We really liked it and would stay again without hesitation. But we do have a penchant for cute little rooms that remind us of a trip to Tokyo.
Youtube is so full of adverts now, some are over 5 minutes long.
Id forgotten about Starmers bespoke pension deal. Might make it less likely that he reduces tax free cash sums from pensions : https://x.com/guidofawkes/stat...
Hi Paul put your feet up for the weekend we can all survive without the podcast for a couple of weeks, its a shame you aren't better known outside of finance as there would be a great film in your life story, who would play you though ?
Paul, listening to your podcast while walking my Cavapoo is a weekend highlight. While I agree that you fully deserve your downtime please don’t think I won’t be compulsively refreshing my podcast app for signs of life…..If I don’t see any by 3pm I’ll have to revert to The Rest Is Politics or even an Off Menu…
HAha, my conscience has been layering on unbearable levels of guilt this morning, so I've just published last weekend's late podcast.
I'm planning on doing the more recent week tomorrow. Getting there! So Rover gets two walks LOL! :-)
Here's the web link, should filter through on podcast apps over the next hour or so, it's still processing at the time of writing -
https://shows.acast.com/paulsc...
much appreciated thanks!
Maybe a dumb question but I am a technotwit. Is it possible to download your podcasts for offline listening? I haven't yet found out how to do that.
I have an app 'Podcast Addict' on my android phone. I download all my podcasts on that app so I can listen offline.
I listen through Spotify which is pretty user friendly imo.You can through there if you have the mobile app.Haven't heard of acast but i'm not a big podcast or music person.More addicted to youtube.
How to Download Spotify Podcasts to Listen Offline [2024 Guide]
Listen offline - Spotify
Thanks both. I'll look at Podcast addict and Spotify. My phone defaults to Acast at the moment and I just cannot find a way to download.
Thanks both. I'll look at Podcast addict and Spotify. My phone defaults to Acast at the moment and I just cannot find a way to download.
"Maybe a dumb question but I am a technotwit. Is it possible to download your podcasts for offline listening? I haven't yet found out how to do that."
Yes, my podcasts get published on all the main podcast platforms, with most people listening through Apple podcasts. Also it goes onto Spotify, Audible, and lots of others.
If you follow me on those podcast apps, it will give you the option to automatically download new episodes.
So if you search for me on your usual podcast platform, it should be there. If not use the acast web link I provided above.
NB. I do them for fun & there are no charges, and no adverts, so it's not a commercial thing.
Regards, Paul.
Anyone read the Close Brothers (LON:CBG) motor finance case RNS?Ended up down 24%.New all time lows i think.I wondered why Lloyds Banking (LON:LLOY) was down 7% too .Larger move, especially outside of earnings, for a company with Lloyds Banking (LON:LLOY) market cap.
Close Brothers stops underwriting new dealer finance after landmark court ruling..
This is one where I don't think the writing was on the wall. I held Close Brothers (LON:CBG) for a while and not once did I see any suggestion that this problem was looming. Am I right that S&U (LON:SUS) are off the hook? If so they should get a lot of extra business in the auto finance sector.
Yes S&U (LON:SUS) should benefit as they never engaged in the type of commission payments that occurred elsewhere in the sector. At the moment they are exiting the FCA process (like many similar businesses) which has explicitly set out how the new rules work. With the shares currently recovering from their lows I'm optimistic for their recovery.
Live at 9.30am on Monday 28th Oct on VOX Markets Exchange, I will be interviewing accomplished fund manager James Taylor of M&G .
It's sure to be another fascinating discussion - including lots of stock ideas such as #HTG, #XPP, #FAN, #CHG, #ESNT, #VCT, #TRU, #PFD, #OXB, #LRE, #QLT, #ALFA, #HILS & #ACSO.
If you'd like to ask James any questions, then please feel free join us here on Youtube.
Everyone is welcome.
Bioventix (LON:BVXP)
Another drop in the % held by K A-L's Buffettology fund announced today. This will not have helped the recent slide in the sp. Neither does it help that there has not been a single trading statement in the 7 months between the Interims on March 25th and the Prelims coming up on Monday. Bated breath for that. In the meanwhile it has slipped from being my 3rd largest holding having been leapfrogged by Bloomsbury Publishing (LON:BMY)!
Bioventix (LON:BVXP) There is a hybrid presentation for ShareSoc members in November - https://www.sharesoc.org/share...
Hi Paul,
On 22nd October Plexus Holdings (LON:POS) (Final Results day) You wrote -
More later, but I didn't want today's SCVR to be dominated by an obscure micro cap, just because I happen to hold some personally.
I want to make a request that In your forthcoming weekend podcast that please could you not hold back and give us full coverage and your opinion on the Final Results of Plexus Holdings (LON:POS)
I do hold personally and like most of us here are aware that you hold 3%, but I am very genuinely interested in what your current view is on Plexus Holdings (LON:POS)
I always do my own research and I do always take full responsibility for all of my investment decisions.
I feel extremely fortunate to have access to all the fantastic work that you produce for us here and the excellent podcasts, and Tinkerbelle and Dexter are very much looking forward to their weekend walk with you back on board.
Regards Neville
BOO Personally, if I were a shareholder I wouldn't mind having Ashley in control. It's not like BOO has a stellar track record of operational excellence.
In related news, Shein is planning a listing on the LSE next year (https://www.bbc.co.uk/news/art...), said to be worth £50b. That will be interesting.
that would be positive for uk iof shein listed here (possibly positive for boohoo if their tax advantages are eroded) - waht they really need to do is level the playing field though so those "dispatching" orders from te uk are not disadvantaged - so powers that be should really be levying some additional taxes on those that import directly to consumers to compensate for the fact they are not paying the other taxes that uk based entities are . That could be a win win all round if it became tax efficient to actually be based in the uk. I think for those selling directly to consumers abroad a minimum 10% surcharge on top (with vat having been charged for sure too !)would be fair if they choose not to have uk base they dispatch from. Somewhat crazy that post brexit we dont look after own by at least havinga minimum of a level playing field.
Let’s hope the budget reveals this loophole these Chinese firms take advantage of is closed.
Ab Dynamics (LON:ABDP)
Does anyone have a view on ABDP's recent share price weakness please?
Thanks
Not sure, but if you look at all the quality AIM shares have the same price weakness in the last couple month - we guess it's budget, IHT, CGT related uncertainty .
Ab Dynamics (LON:ABDP)
Does anyone have a view on ABDP's recent share price weakness please?
As others have stated, this is most likely down to the same factors, all budget-centred, that appear to have afflicted most UK quality companies that are not absolute coffee can (RELX, LSEG) - and who know how safe even those are? There have been idiosyncratic examples, such as Mears which was affected by news flow (that I missed), but I think you can lay the blame here on Rachel R. However, the fall from the June peak to the August peak is something else - perhaps rising concerns about the health of the car industry. And those have increased of late, so there may be a multiplier effect.
I find this to be a difficult stock to invest in. Its SP is extremely volatile and the high valuation means it is never optically cheap - even down at £10. Although that has proved a good entry in the past. I think there is more risk here than in other quality names that are down 20% since August. One to watch however.
Ab Dynamics (LON:ABDP)
Thanks for the comments. I've been in and out of this already earlier in the year and am looking for another decent entry point. If, however, the end markets are softening it is still pretty highly rated, so I am going to wait and watch for a while.
Luceco (LON:LUCE) - does anyone know why this has fallen off the wrong side of the bed the last few days, particularly after the yesterday's TU. I thought yesterday's TU was rather reassuring, yet peeps appear to be on a sell mode. Does anyone know if the brokers have put out something negative? Any feedback would be appreciated. Thanks.
Luceco (LON:LUCE) - and it's not even on AIM.
I hold Luceco but I think this from the trading update might make people nervous. that there could be a FY miss. Just speculation on my side. I've not seen anything from a broker out there.
"· On a like-for-like basis Q3 2024 revenue was down 3.6%. However, strong fourth quarter order book supports like-for-like revenue growth expectations for the second half."
Luceco (LON:LUCE) My take on it is that its a reaction to the like for like fall in sales in Q3 of 3.6%, which was a bit of a surprise. And whilst the company was very bullish about Q4 , there may be a risk of an underlying miss here, possibly clouded by the contribution from the relatively recent large acquisition.
Another factor was the very large (£3m) share sale by the CEO’s wife just a few days before this trading update.
I don't know the law, but surely it must be ethically wrong for the CEO's wife of Luceco (LON:LUCE) to sell so many shares just before a Trading Update??
A minor bit of scuttlebutt. I tried contacting Luceco (LON:LUCE) for some information prior to possible investing. I was dealt with quite inefficiently and rudely, so decided not to invest. It is interesting how much one can learn about the culture of a company by contacting them.
Re Luceco (LON:LUCE) . It certainly raised a few eyebrows nettle. I’m not familiar nowadays with the rules on close periods for Director dealings but am surprised they don't appear to apply to close relatives.
Re: @LUCE & "I’m not familiar nowadays with the rules on close periods for Director dealings but am surprised they don't appear to apply to close relatives."
Persons Closely Associated with PDMRs {Persons Discharging Managerial Responsibilities]? They surely do apply to close relatives, after all, transactions in declarable shareholdings are required to be reported.
I agree. If the CEO’s wife sold just before the trading statement, she risks allegations of insider trading.
Thank you for the clarifications ed and pj.
Think I might have to dig into this a bit deeper, maybe contact Luceco (LON:LUCE) advisors to get their comments . Will report back in due course.
Just had a look at the definition of close period :
“The closed period is a 30-day period before a company's mandatory public announcement of an interim or year-end financial report”
Given that this was a Q3 trading update and not a mandatory announcement, it looks like maybe there was no closed period in force here. Seems a bit of a grey area to me though !
In all fairness to the Luceco (LON:LUCE) CEO, the trading update wasn't particularly market moving, and presumably the sale was CGT motivated pre-budget ....
Very possibly Cancun.
Although the market has indeed marked Luceco (LON:LUCE) down 10% in just a few days.
Could have done it immediately after the trading update instead of before ? No difference from a tax planning perspective.
You're obviously 100% correct Lochinver, I was just giving him the benefit of the doubt that he didn't feel that he was gaining by selling before, as there wasn't anything particularly material.. although surely any update should involve a closed period...
The 10% down move is presumably a reaction to him selling, but ( as Paul has alluded to I think ) these CGT changes are presumably front loading a host of sellers and hopefully the sellers post budget may be relatively thin ( particularly in non Aim stocks, if BPR is removed )...
Luceco (LON:LUCE)
I had a look at the trades on the Stock Exchange website (it's had a makeover and very easy to use) for the 16th and the 3million sticks out like a sore thumb at 0917 as an off-book trade. My understanding is that means a retail trade. Around that time were several other trades, the largest single one being 245702. It could be that shares were effectively transferred between the family and only reported to the market after the event. Hence possible insider trading would surely not be the case. The reporting announcement could have made that clearer though.
Sams grandad Luceco (LON:LUCE)
This has been discussed previously, in some depth. Thank you for your research and for highlighting this matter again.
The share sale by the spouse was nothing to do with the family share transfers
Although it was possibly designed to look like it was .
There is something clearly wrong with what has happened here which, in my view , warrants further investigation. It cannot be right that the spouse of a plc CEO sells millions of pounds worth of shares only days before a trading update which shows an unexpected and unforecast decline in like for like sales.
It is possible that the closed period for share transactions by directors and their affiliates was not a factor here in that the very recent Q3 trading update was not a mandatory reporting period.
Having said this, as a result, the share price has declined by 10%, my shares have taken a hit and the spouse is £300k better off than she might have been if she had sold after the trading update. Which she could easily have done after the trading update if the primary concern for her sale was tax related.
I intend to take this matter up now with the stock exchange authorities, the company itself and the CEO himself . Something does not appear to be right here.
I intend to take this matter up now with the stock exchange authorities, the company itself and the CEO himself . Something does not appear to be right here.
I’m not sure there’s anything here. It looked to me like a way of crystallising some CGT pre-budget (sales by wife), while retaining ownership in an IHT-friendly way (purchases by children, presumably after a PET)
Further to BnB's post, the price action wasn't consistent with any wrong doing by the CEO's wife .... she sold at 157p on the 16th, the RNS came out on the 17th... I topsliced on the 18th at 162p ... but should have done more... it then drifted down to 149p over the next 5 days, before results on Thursday... the price then oscillated around 148p for a day and a half... it was only 10.30 onwards yesterday that it finally fell to the lows ... it wasn't the Q3 update which caused a sudden sell off ...
Hi Paul,
Welcome back
Kooth (LON:KOO) also have a £20m pa UK business so it's not correct to say they are a single contract company.
As they keep reiterating guidance for FY24 and FY25 one could draw the conclusion the California contract has a 2 year minimum contract length, plus they anticipate two new pilot contracts in CY24 and will launch Solana in the UK Q2-25.
MCAP £57.6m (SP 160p) Cash £15m / EV £42m / ARR £60m makes it attractive to me
There's no buyers in this market and a clear seller in Kooth but I can see this bouncing. Majority owned by PE with Root not selling for 90 days (I doubt they will sell now) but are they now a bid target ? A little uncertainty but trading below the original California contract and £10m fund raise at 260p
Hi Scoobydoit,
I don’t think you can say this is an ARR business of £60m. The California contract is dominant and that has just 2 years to run so could be viewed more as “exceptional” rather than recurring.
What is unclear is how well that contract is performing. Not as in whether it is in compliance with terms but how the buyers perceive the value and benefits. If we knew that it would give more confidence around renewals.
The problem for Kooth (LON:KOO) is that the California contract was supposed to open the door to multiple new large contracts and as yet it hasn’t really done that. So the company has way too much exposure to a single customer. Investors are unlikely to accredit much value to that. I mean think about - if you were going to buy that contract from the company what would you pay for it? Maybe 1.5* ebitda? Now if they renew for another 5 years that becomes a different matter of course but right now we have zero visibility so it’s just a digital option.
So one could take the view that it should be valued on a SoTP basis. If we extrapolate from expected £15m ebitda then £10m of this is attributed to California and £5m to UK but, if the California deal were not renewed my guess is that the £5m UK ebitda is less due to reduction in margins via the reduced scale (ie corporate overheads being a larger %age of a smaller revenue pie)
So for me I see an EV of £42m made up of a large single client contract I might pay £15m for and maybe 5*ebitda for the £5m UK part which comes out around £40m SoTP.
I suspect the report was based on similar maths and then sensationalised (as seems to be the way) to guarantee the fall.
This is the problem with client concentration risk and lack of contract forward visibility. Either you need a long term contract or a more diversified revenue base. It is why consultancy type businesses with a couple of main clients rarely trade above 5-6* profits.
Anyway all that said it feels to me like Kooth (LON:KOO) valuation has dropped into investor disappointment territory from investor optimism and so if one is prepared to risk the California contract renewal there may be some good upside. Downside looks limited to maybe 25% if it doesn’t renew given cash build up, but I have no idea of how damaging a lack of renewal might be on the overall financial position. (Ie exit costs, restructuring etc. would that eat the cash pile? Don’t know). I’m not rushing to this as a bargain but at first glance its interesting enough to re-take a look at.
Just thinking aloud. On my tour of the charts I was surprised that YouGov (LON:YOU) had continued to be so poor. I remembered the last update being kind of ok. I just had a glance over the trading statement and obviously it was slightly ahead but with some cost cutting targets. I then popped back to the stock report and was again v surprised to see a rating of 10x. Ofcourse the system has flipped to 2025 now.... and actually decent earnings growth which looks to be based around 18% revenue growth. some acquisitions cloud the picture and I haven't done enough work to have a firm view of how conservative or not this is. The market how ever doesn't view it as conservative. The earnings forecast "may" be able to tolerate some slippage due to the cost programme. Anyway as a stock that was previously a bullet prove long term multi bagger this is quite the fall from grace and does leave the stock looking a bit vulnerable. I realise no-one feels like being brave at the moment .... the numbers are next Tuesday... so we can read with interest. Like I say ... 10x always winks at me ... guidance needs to be pretty awful to disappoint ... any strong views ?
YouGov (LON:YOU)
I have kep a loose eye on this one - i guess the main unkown is was the large acquisition last year good value or not ? whatever is happening the sums of the parts dont seem to perhaps be as good as one would have expected. Is it possible thye have spent 320 mill euros to only add £10 mill pa to bottom line. Things are much more messy when you spend a wad of funds that amounts to many years profits if there is little evidence that sepnd has moved the buisness forward much. Its not clear to me which poarts of the business are struggling - worst case is that they easy money they were making is not so easy. In summary i suspect the market is neutral to midly concerned about organic growth prospects here. They seem to have had a very decent prior track record so one would hope that they should be able to get back on track.
Agreed... they had this punchy 5 year target that got everyone excited and have struggled for one reason or another to hit it.... but even if they dg to 10% pa ... that would be attractive although a hit to current forecast.
The budget on Wednesday may be as important (or more important) to YOU as its results on Tuesday. The AIM market may or may not turn on its head next week.
Morning,
Applied Nutrition (LON:APN) looks interesting for a new float. Share price of 120-125p may be inte3resting, based on quick back of fag pack calculations..
Personally i never buy IPOs.
If the insiders want to get out, that is not a good time for outsiders to get in.
The problem with retail IPOs where allocations are scaled back is people dump sub scale positions ... esp if it falls below issue price. Best to reassess in a week or two... not a fundamental view, just the technicals.
I'm rather looking at a THG (LON:THG) play once the demerger is settled.
There's a profitable Beauty business.
Then there is Nutrition - competitor to Applied Nutrition. And just completing their big re-branding exercise. Which seems to have been very chaotic, and commercially a bad plan over the last 12 months, but what's done is done and their new branding is stronger. Also, they have a fast expanding retail distribution business into offline stores like supermarkets, which could be a very big growth sales channel.
Yes - lets keep politics out of it and go back to talking about how awful the UK small cap market is at the moment.........
Couldn't be a collolation there could there??
Truly awful, still more pain to come..
Don't be like that John Doe, positive thoughts :)
Ha ha yes you're right. Another day closer to next bull market
Politics?
I watched the interview, Tbf Beth Rigby was just looking for a headline, Kier being a bit thick sometimes gave it to her.
I think we just need to wait for the budget now and see.
I wonder what Paul and Graham think of today's acquisition announcement from Wilmington (LON:WIL)? No details on either the revenues of the acquired business, nor their profits and nor the performance based contingent consideration. All we get is "The initial consideration represents a valuation in line with Wilmington's current trading multiple". No doubt the house broker has the full information and is spreading the merits of the deal to institutional holders right now. This sort of thing makes me really cross. There is simply no reason to withhold the information from small shareholders but instead we are left in the dark. Rant over!
Pain coming...
https://news.sky.com/story/sir...
Rubbish, many working people have shares or pensions based in shares.
So kick the pensioners again because they are no longer working?
The point of this was really just to say raising Capital Gains Tax doesn't count as breaking the manifesto pledge not to raise taxes on working people. We can be pretty sure it will be raised but the balance of opinion seems to have shifted towards a small rise to 24% or 28% on shares , with Keir Starmer specifically calling stories about a 39% tax 'wide of the mark'
"Wide of the mark" is another woolly reply. Maybe Starmer means the reality is far worse, say 50% CGT?
Just joking but FFS (hope I am allowed to use this abbreviation as it is describes the situation well)
So they're using a definition of "working" that no one else would use.
I , for one, will be relieved when this budget is out of the way. Never have I seen such scare-mongering in the press.
Or perhaps they are right?
"Sir Keir said he believed a working person was somebody who "goes out and earns their living, usually paid in a sort of monthly cheque" but they did not have the ability to "write a cheque to get out of difficulties"
He's a Grade A idiot and entering very dangerous territory with comments like this. He's confusing working class people with everyone else. Lawyers go out and earn a living but they can absolutely write a cheque to get out of difficulties, the same goes for any number of professions, particularly traders and those who work in the city.
So apparently he wants a country of only working class people, presumably working in jobs under social ownership, i.e. socialism. Good luck growing your economy & competing with the world if that is the underlying aim.
This is reminding me more and more of what people dreaded if Corbyn & McDonnell had been elected in 2019.
AimingHigher
This is not the place for political rants. Surely a lot of readers of this thread are not remotely interested in your opinion of the Prime Minister or other politicians. There is nothing of investment use in your post. Best to keep your political views to yourself, or post them on the politics thread, and not investment threads?
When next week's budget is going to have a material impact on financial markets it is absolutely relevant to have an opinion. Ps. Paul certainly has had his fair share of political rants on both the weekly podcast & in the commentary on these pages...
No, I always focus on the economics of things like consumer confidence readings, PMI surveys, etc, and have commented on how these have been measurably damaged by the flawed communications from politicians in the last couple of months. Also I'm focused on the damage they're doing to markets through all this uncertainty & speculation. That's very different to general Twitter-style rants.
Until the budget is over and the dust settles, we investors have a right to worry. However, we all know that the systemic leaking is their way of managing the event so that the market doesn't implode al la Kwarzi. Right now I am hurting.
Hear hear, Ken. Not that there’s anything of investment use in this post!
Actually Ken, Starmer indicated that he saw landlords and shareholders as not being working class, this should worry quite a few Stocko members. I would have given you the thumbs up but maybe a broad view needs to be expressed at times.
Edit: re-reading the media, 'working people' were the words used.
I think we should all take note of the PM comments. I work and I own stocks and shares. I have the impression that the PM thinks we are all multi millionaires driving Ferraris and live in Mayfair. Inflation, interests and cost of living doesn’t make any difference to us because we are not working people and are wealthy.
I would say I am pretty ordinary, I work and have a small mortgage but because of the shares I have now been labelled by the PM.
And let’s not forget his comments send the wrong message to working people who do not shares about folks like us.
What it does do is show his true colours and the colours of the party - in that regard voters will make appropriate decisions next time they vote. Personally i see no need ever to cast aspersions like this - its not necessary and will often be wide of the mark. Many hard working working class people (if we are allowed to say they exist) - have 1 or 2 properties as their main savings pot for retirement - being frank its an insult to suggest they are no longer working class due to the fact they have a property - presuming he has said what you say he said (i aint fact checked that)
When the PM says that people who make their income from shares are not the favoured “working people”, I think it is a legitimate investment headache, worthy of comment here. Obviously I am biased, but not having had a defined benefit pension, the work that I did to get a defined contribution lump sum and the work that I do to make my retirement comfortable, seems to be fair to me if not to Starmer, and I resent being a target. One can hope that Starmer did not really believe what he said or was trapped into saying it but since he is a KC , and presumably has some experience of argument and counterpoint, I fear that this may actually betray his true feelings. And is part of an investment decision for me.
You've changed your tune Ken Mitchell, your comment on the Serica thread of ADVFN was worthy of the roasting you got. "People who invest here in shares like we do can manage without a heating allowance and state pensions protected by that triple lock." Do get off that high horse.
Samsgrandad
Not sure it’s right to drag a comment from another BB that’s irked you across to SCVR. Politely suggest you leave the discussion on ADVFN.
Samsgrandad.
Why on earth have you raked up a valid opinion I expressed on another site weeks ago? Just because you don’t agree that people who are comfortably off or rich don’t need the fuel allowance doesn’t mean that opinion can’t be expressed. It’s not me who is on that high horse!
There are strong arguments for and against that cancelling of the fuel allowance, including the fact that it wasn’t in the Labour manifesto, and it doesn’t raise much money and some pensioners who need it won’t be getting it now. But it’s also true surely that rich people including multi millionaires don’t need a £300 fuel allowance.
Hope you are more tolerant of views you disagree with with your share investments. Investors only prepared to see the plus case for a share and not prepared to tolerate any contrary views often come unstuck by holding shares that evidence showed should have been sold. Some are so stubborn that they still believe in that share even after it has fallen 99%!
Sinse you ask why, because you categorised everyone with shares, not those who are rich or comfortably off as you say now.. You have dual standards in your reply today about political comment. Can I politely request you use the red flag to highlight a comment you disagree with and let the moderator decide if it crosses a line instead of appointing yourself as captain of the board. Were you in the teaching profession by any chance?
Wilmington (LON:WIL) has acquired Phoenix HSC (UK) Limited for initial consideration of £30.25m plus “additional contingent consideration payable based on Phoenix Health & Safety's financial performance in each of the three years ending 31 March 2028”.
The Companies House filings show profit for Phoenix in FY to 31.3.22 of £630.6k. Profit more than doubled in FY to 31.3.23 to £1.270m. The presentation of the accounts changed in FY to 31.3.24. We can see that the P&L reserve increased by £738k in FY24, but the earlier accounts show that this increase is stated after accounting for share buy backs and dividends which aren’t stated in the FY24 accounts (but were £1.18m in FY23). However, we can see that the average number of employees in FY24 was 45, up from 24. And today’s RNS says the number of employees is over 50.
The RNS says that the initial consideration (£30.25m) was in line with WIL’s current trading multiple. This is a bit vague because we don’t know what multiple they’re using. But I suspect it’s EV to EBITDA. WIL’s multiple is currently 10.9 (EV of £284m to £26.0m EBITDA forecast for FY to 30.6.25). Applying that multiple to an EV of £30.25m less £2.5m cash as at 31.3.24 gives an EBITDA for the target of £2.6m. WIL converts EBITDA to post tax profit at around 74%. If Phoenix’s EBITDA converts at the same rate, the deal will increase post tax profit by £1.9m or 2.1pps.
By way of comparison, on 22.2.24 Marlowe disposed of its GRC business to private equity for cash of £430m on debt free/cash free basis, a multiple of 16.2x proforma trailing adjusted cash EBITDA. On WIL’s post-merger EBITDA of £26.0m (forecast for FY to 30.6.25) + £2.6m (estimated Phoenix EBITDA), this implies an M&A EV valuation for WIL of 16.2 x 28.6 = £463.3m. WIL’s EV post-Phoenix is £349m – (£65.0m net cash on 30.6.24 - £30.25m initial consideration) = £314m, implying 47% upside.
Wilmington (LON:WIL) - thanks for sharing this excellent analysis. I came up with similar figures but thought the acquisition looked expensive until I saw your comparison with Marlowe. I hold and, based on your work, will continue to do so
Van Elle Holdings (LON:VANL)
Its Canadian rail venture is gaining traction with award of two contracts to a value of 55m Canadian dollars (around £27m) for delivery between 2025 and 2028.
Prospects for the company are positive. It is well positioned across various aspects of construction and infrastructure, house building, water, energy and rail, with falling interest rates and the Government’s much publicised agenda on housing provision, infrastructure and growth.
Van Elle Holdings (LON:VANL) remains cheap with cash on the balance sheet and competent management. Needless to say I hold.
Intercede (LON:IGP) share buy back of up to £1m to take advantage of sell off arising from potential tax changes. This is, IMO, excellent capital allocation. IGP had been gathering cash to support M&A but it absolutely should be tweaking its capital allocation to take advantage of opportunities as they're dished up.
(Franchise Brands did something similar recently: they had been intending to use cash to pay down debt but diverted some to buy back because of the sell off.)
Morning Alistair,
I agree re IGP share buyback. Only small at £1m (they should have done more I think), but if it takes out small sellers nervous about the Budget, then that should help stabilise the erratic price movements of late.
We need to see lots more companies using surplus cash in this way. I think it was the Peel Hunt note recently which suggested companies deploy surplus cash to do buybacks, given that it's obvious small cap markets are considerably unsettled at present from the obvious worries about tax changes.
Another point of view is that, if there's nothing calamitous in the budget, then we could see a buyers stampede to get back into stocks they like, but pre-emptively sold just in case, giving them the option to buy back within 30 days and not trigger a capital gain.
My view, as always, is that it's the fundamentals of the companies that matters the most, and trying to predict what a new Govt will do seems very difficult - should that be driving investment decisions? Depends on your timeframe, and general level of nervousness!
Nice to see that IGP has bounced +6% this morning (at 08:10), so at least in the short term that's helped a bit. Given that the newsflow from IGP is probably limbering up for an ahead of expectations update in H2, then personally I don't want to be out of this share due to trying to be clever about the budget. Am happy to just ride out any volatility, although obviously it's unsettling when prices go all over the place!
Regards, Paul.
Re Intercede (LON:IGP)
"to repurchase shares to hold in treasury for the purpose of satisfying future obligations in relation to its employees' or other share schemes"
If they had cancelled the shares I'd agree. However, £1m of shareholders funds has been spent with the intention of gifting it to directors, employees etc some time in the future. Bargain!!
This is an early stage business. It is not jam for FTSE directors.
The directors and employees will be creating the value from which you hope to gain.
@ David, for which the Directors reward is................. their salary, bonus and myriad other ancillary benefits.
No horse in this race, but I despise LTIP's and director's awarding themselves free shares. Does professional pride in doing a good job no longer exist?
Hi David,
Imo you're conflating 2 different points.
If Intercede (LON:IGP) had awarded the Bod a £1m rise in salaries / bonuses today rather than these buybacks I'm guessing that wouldn't have been referred to as "excellent capital allocation". When as far as shareholders funds are concerned it amounts to the same thing if the shares are not cancelled.
As to your point, then I agree share options, salary rises etc can be very beneficial indirectly to shareholders if that motivates directors and employees to perform to a higher level.
Intercede (LON:IGP)
When as far as shareholders funds are concerned it amounts to the same thing if the shares are not cancelled.
Huh you have completely lost me here
i cant see how on any level buying back shares can be compared to "business expenses"
salary options et al are clearly buisness expenses to me.
buying back shares is clearly not an expense in any manner. At a later date if they give those shares away to directors or any - yes that could end up being an expense but that expense would be notified as approrpiate at te time and be factored in as acost at that time.
But imho at face value on its own i dont think this can be seen as anything other than a standard buy back - with the caveat that we need to be aware of these shares are given away so that they may become costs - those transaction will take care of themselves.
Not sure what the reality is here whether its simply to acount for separately notified "costs/freebies" or its simply saving up shares to be cancelled ata later date.
Whatever way i look at it i dont see this as being a cost end of.
"we need to be aware of these shares are given away so that they may become costs"
Precisely my point - they'll become a cost when they are given away. It's just a matter of timing!
Learning Technologies (LON:LTG) PUSU extended to 22 Nov.
More significantly, IMO the rules of the game have changed.
Today's announcement says General Atlantic want "irrevocable undertakings" from Chair and CEO who have c. 24% between them and LTG has accordingly convened an independent committee to review the offer. The RNS doesn't say, but I assume GA want "hard" irrevocables (can't be withdrawn no matter how high an alternative bid is received). If so, then granting them would make it very hard for any rival bidder.
IMO prior to today, the game for potential rival bidders had been: (1) wait to see if GA bids at 100p; (2) if so, consider whether to bid higher (say 110p); (3) if not, consider whether to bid lower (say 90p) as the market wonders what GA saw that put them off.
Now the game for any rival bidder seems to be: act before any firm bid from GA is announced to persuade the independent committee not to support the bid (which would presumably result in the grant of irrevocables by the Chair and CEO).
This means any rival bidder would need to express interest fairly soon (well before 22 November) in making a possible bid at a higher level conditional on diligence (including equality of information, i.e. they get whatever GA got).
There is a separate question whether and when LTG would announce any other expressions of interest.
And the second order question is how GA will respond. If 10 days go by with no news of any other interest, this will presumably fortify GA in their negotiating position.
Morning Paul - Hope you are well - A quiet news day (it's Friday after all) but there is a new note out on GMS from Panmure which may be worth commenting on if you have time, Tgt raised to 30p from 26p - Have a great weekend
Morning matylda!
Thanks for flagging, that note on Gulf Marine Services (LON:GMS) from Panmure Liberum is excellent, mainly flagging the large opportunity in wind power maintenance. I asked the CEO about this, and he confirmed that GMS's vessels only need fairly minor adaptations to change use from oil & gas sector to wind (and that customers would generally pay for the adaptations, eg some sort of structure to safely carry the large turbine blades). So it definitely improves risk:reward and cyclicality to be able to address two large markets.
Shares remain irrationally cheap in my view (I hold). Waiting is fine though - as the debt is rapidly reducing, so the situation improves over time.
Regards, Paul.
Thanks Paul for your views, much appreciated - It was also good to see that their revised forecastsalso take into account the warrants that were issued at 5.75p - Wishes
I also liked that the Panmure Liberum note on GMS also included some potential risk factors, for balance. One that stood out was the potential for the cycle to swing back again to a surplus of these vessels from new builds in progress. When I asked GMS about this, they seemed much more relaxed about it, saying they thought retiring old vessels and expansion of demand would mop up all the available existing and new ships.
The slide deck from GMS (dated 2/10.2024) has tons of really useful information in it, including very detailed appendices. It's well worth a look, as it comprehensively explains the company and its markets. The CEO pointed out to me that the daily rate has only recovered a relatively modest amount, and is still nowhere near the previous peak. So they think there's plenty of scope for daily rates to continue gently climbing, and that customers are very keen to lock in availability, and nearly always exercise the optional extensions.
In future, I hope GMS can avoid another near-death boom & bust scenario that previous management presided over. Hence why I would much prefer it if GMS can expand its fleet via leasing (hence no covenants or risk of withdrawal of finance) rather than outright purchases and heavy bank debt which has proven to be so dangerous over the last few years, but thankfully now almost completely resolved, with bank debt now at normal levels, and rapidly reducing.
Why are the shares so cheap? I think it's just supply & demand. For whatever reason, some shareholders have wanted liquidity. We're seeing so much of this at the moment in small caps. Some of the selling seems irrational. So if we've done our research properly, then one person's desperate dash for cash, is our buying opportunity. Sometimes anyway.
Thanks for posting the deck, I had previously seen this and agree, it's well worth a good look through, thanks again for the original interview and additional comment today, looks like the note has had some positive impact so far, hopefully this is one to hold through the current pessimism.
My morning smallcap tweet: What's the truth, Kooth?
Kooth (LON:KOO) Boohoo (LON:BOO) Van Elle Holdings (LON:VANL) Adams (LON:ADA) Wilmington (LON:WIL) Intercede (LON:IGP) Learning Technologies (LON:LTG), Celebrus Technologies (LON:CLBS), Record (LON:REC)
◄Kooth (KOO)► re SP fall following a "newsletter article regarding its service in California which contained outdated information that underestimated the uptake and impact of Soluna in California." Article seems to be https://kffhealthnews.org/news... Provides rebuttal. [SP=185 Cap=67m]
◄boohoo (BOO)► reviewing Frasers' attempt to lever heavyweight founder Mike Ashley into CEO seat. "Whilst the Board remains willing to discuss Board representation with Frasers in a constructive manner, it has been clear with Frasers that before any appointment can be made, appropriate governance will be required to protect the Company's commercial position and the interests of other shareholders." [SP=28.5 Cap=362m]
◄Van Elle (VANL)► wins 3 year Canadian contract expected to be worth over CAD$50m. Starts H2 2025. [SP=40.75 Cap=43m]
◄Adams (ADA)► proposes to delist and sell investments to give a return of capital to shareholders over the short to medium term. Will buyback shares at 4p in the meantime. [SP=4 Cap=6m]
◄Wilmington (WIL)► buys Phoenix Health & Safety for £30.25m plus undisclosed contingent. [SP=380 Cap=343m]
◄Intercede (IGP)► buyback of £1m max. [SP=157 Cap=92m]
◄Learning Technologies Group (LTG)► PUSU extended. [SP=92.8 Cap=735m]. I hold.
In line: CLBS, REC
Pity it's not April 1 or POO could have been added to the SCVR Header today with BOO and KOO. Although next Wednesday could be a POO-day too.