Small Cap Value Report (Fri 25 Sept 2020) - BOO, RBG, W7L

Good morning, it's Paul here with the SCVR for Friday.
Timings - TBC
Sorry I didn't manage to finish off yesterday's SCVR, I seem to feel permanently exhausted at the moment. Maybe I'll ask Jack to give me a day or two off next week?
The big news today is;
Boohoo (LON:BOO)
358p (up 10%) - mkt cap £4.4bn
(I hold)
Why is this fashion eCommerce business in a small caps report, newbies might ask? We've followed this share very closely since it floated, because I knew the original wholesaling business from my former employer being a major customer of theirs in the 1990s. Hence the potential of selling direct to the end customer was obvious to me. I, and many readers here, collectively made many £millions from the point where I was raving about it at c.25p per share, all the way up (although I personally sold out ridiculously early, worried about the valuation being too high!). I still haven't learned the lesson to ignore valuation when you find something exceptionally good. Right or wrong, that strategy of ignoring valuation is the one that has worked in recent years. Sooner or later it's likely to go disastrously wrong, but who knows when?
Back to BooHoo. There have been repeated allegations of malpractice (poor working conditions & low pay) in its Leicester supply chain, which combined with a duff shorting dossier from Shadowfall (Matt Earl), has caused the share price to be volatile. I was waiting for a nice buying opportunity in BOO, as I've become more & more convinced of the bull case, as it hoovers up more & more brand names on the cheap, and repeats the same formula to build them up strongly as internet-only businesses, using the BOO infrastructure. That opportunity came in July 2020, with repeated (essentially the same as before) allegations that BOO's suppliers (NB not BOO itself, as all manufacturing is outsourced) were cutting corners, not just with the fabric! I know a lot of readers joined me, buying recently from 209p upwards, and we've cleaned up. So well done to everyone who had the nerve to buy when the share had just been in freefall. And many thanks to the shorters, and so-called ethical funds selling out cheaply, for providing us with this marvellous opportunity.
The independent report commissioned by BOO from a lawyer, was I thought due to come out on 28 Sept, but it seems to have come out early today. My thinking was that the report would possibly contain stuff that might be damaging to BOO in the short-term, so I reduced my position size from humungous, to just large, safety first. The idea was to side-step any spike down in price on publication of the report, and to give me funds to buy another dip.
That plan didn't work, as the report has come out a working day early, and the market seems to like it. That's triggered a rally in the share price this morning, which was not how I imagined things might work. So a bit of a missed opportunity, and I'm kicking myself for not having held my nerve fully. Still, it remains a big holding for me, and with this supply chain issue now probably dead & buried, in terms of stock market impact then I'll be able to buy the dips in future with more confidence.
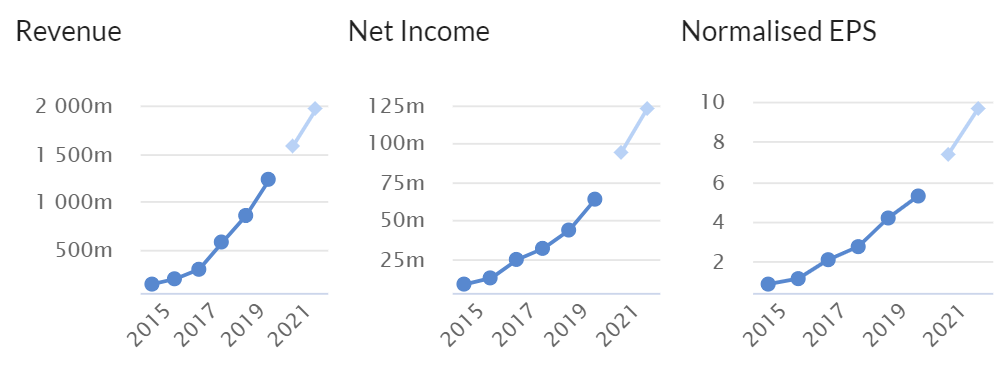
BOO really is a remarkable business. Just look at the EPS growth (below), which is ongoing of course, because more brands are being added. I think this could become one of the world's largest fashion businesses long term. They're just good at everything, and it has the laser focus of being a family business, driven by passion.
.
.
Above all, the lesson for the future, is to just ignore the bears - without exception, they don't understand the business or the sector, I've found. This includes anyone who thinks the PER is too high. The point is that BOO normally beats forecasts, and growth is open-ended due to international expansion running rapidly, and more & more brands being bought up cheaply (it now has 9 brands). Therefore a high PER historically, soon becomes quite low after a few more years' growth & out-performance.
As mentioned previouly, I think EPS could rise in the next few years to c.50p 20p, so put that on a PER of 40-50, and I have a price target of 800-1000p. It's currently 360p. There's no reason to believe that 1000p would be the peak either, I see that as a staging post on a long-term journey that could take it higher still, if the growth continues. Now the group is so diversified with many brands, it's difficult to see what could seriously derail the shares in future.
Here's a link to the full supply chain report, published today, and BOO's response. Since the share price has settled up, then I'll park this, and read it over the weekend. From a quick skim, the key point seems to have been that BOO was previously (before July's allegations) actively trying to improve conditions in its supply chain. Therefore that makes it look genuine, rather than allegations which implied it was ruthlessly taking advantage of workers. That makes it a lot easier for funds to hold the shares - with ethical considerations neutralised, hence selling pressure on the shares has probably now gone, and everyone can instead focus on what a fantastic growth business BooHoo is.
EDIT: some excellent reader comments below on BOO. In particular thanks to MrC for a nice summary. It's quite critical of BOO, but the problems seem to be in the process of being fixed.
.
** BREAKING NEWS **
Revolution Bars (LON:RBG)
9.5p - mkt cap £11.9m
(I hold)
Statement re press speculation (possible CVA)
Here is the announcement in full, which has just come out;
Statement re press speculation
Further to the continuing challenging trading environment and exacerbated by the further COVID-19 related restrictions announced by the Government earlier this week, the Board of Revolution confirms that it has been working with advisers to assess various strategic options for the Group.
The Board is currently evaluating the potential impact of the latest developments on the Group's business before deciding what the next steps should be. One of the potential options being explored is a reduction in the size of the Group's estate by the implementation of a company voluntary arrangement ("CVA").
No decisions have yet been made and there is much further work to complete before the Board decides on any appropriate course of action.
Revolution has a strong balance sheet following the £15m equity fundraising and the extension of its banking facilities announced in June but the Board believes that the long term nature and potential impact of the latest operating restrictions means that it must consider all necessary options to ensure that its business remains viable.
.
I'm pleased to hear this, as the same thoughts were starting to go through my mind. Why keep paying full rent, when operating conditions are so far below usual, that the business would struggle even to breakeven? Particularly as the Govt has indicated this week that restrictions could be in place for 6 months, and that even further restrictions could be introduced.
There have been incidents where people failing to socially distance in pubs has caused covid outbreaks, hence why bars seem to be in the Govt's sights as places to restrict further, e.g. the 10pm closure time announced this week.
Personally, I would prefer it if RBG goes the whole hog, and does a pre-pack administration, which is the cheaper, but more brutal option. Whereas a CVA is more costly. Ultimately though, both achieve the same aim of getting rid of all the loss-making sites, and reducing rents on others. Business can continue as normal during a CVA, and trade creditors are not usually affected.
My opinion - if RBG can do a CVA, that would enable it to reset all rents to an affordably low level. This would be a far better situation than the one we currently have, where shareholders are funding the landlords.
Reading the "Propel" daily email (many thanks to the reader who flagged this up to me, it's very useful), we are seeing CVA and administrations occurring every day from many hospitality sector companies. As mentioned here before, I'm coming round to the view that this is the only way forwards for struggling retailers and hospitality companies. The lease liabilities have to be jettisoned, otherwise businesses are just not viable.
My main worry about RBG doing a CVA (or other) is that it could need another equity fundraise, which inevitably would be likely to occur at an even lower price (e.g. 5p?). I've changed my mind on this. Crunching the numbers, I estimate that RBG could probably proceed with a CVA without needing another equity fundraise, but this might depend on the bank giving covenant waivers, so it cannot be ruled out.
So a positive development I think, as a much better & more profitable business would emerge from a CVA. But in the short term, there is a worry about how it would be funded? Looking forward to 2021, once restrictions are removed, and assuming RBG has ditched all the loss-making sites, and has new, low rents on everything else, then this would become a fantastically profitable business. It's the path of how it gets there, that is problematic.
In the past, CVAs have often just deferred insolvency of failing businesses. However, the covid situation is different. Demand is being artificially suppressed by Govt mandate. Therefore bars are struggling to survive due to this one-off, external factor, not because there was anything wrong with the business prior to covid. This makes the rationale for doing a CVA much stronger, and points to it being a long-term solution, rather than a short term sticking plaster.
.
Warpaint London (LON:W7L)
Share price: 67p
No. shares: 76.7m
Market cap: £51.4m
This is a straggler from my backlog, these results came out on Weds.
Warpaint London plc (AIM: W7L), the specialist supplier of colour cosmetics and owner of the W7 and Technic brands is pleased to announce its unaudited interim results for the six months ended 30 June 2020.
Just to recap, we're going through a unique period where businesses have been often badly impacted by covid/lockdown. Therefore it doesn't make much sense to value companies on a multiple of their 2020 earnings. So we need a different approach. If I think a business is likely to recover in 2021, then I'll probably look back to 2019 pre-covid earnings, and value the business on a sensible multiple of those historic earnings. Alternatively, if there are broker forecasts, then I'll look to 2021 forecasts, but place a low reliance on them, because so many broker forecasts at the moment seem to either be far too optimistic, or far too pessimistic.
Analysts generally have not done a good job in 2020 so far, but I suppose we can't blame them, because so many companies have withdrawn guidance - itself incredibly unhelpful. At times of crisis, we need profit guidance more than ever, not to have it withdrawn. Guidance doesn't have to be exact, but a range of possible outcomes is fine.
Anyway, with the absence of reliable guidance for many shares, I am currently looking for;
1) H1 losses, or reduced profits, in 2020 being tolerable - i.e. not so bad that the company would struggle to recover.
2) Balance sheet strong enough to allow the company to survive & recover, without needing to do an equity fundraising, and
3) Current trading improving strongly (not just bumping along the bottom).
If a company results ticks those 3 boxes, then I would consider a purchase, if the valuation is attractively low.
Onto the H1 results, here are my notes of the key points;
H1 revenues down 29% to £13.5m (split UK down 12%, international down 40%)
Gross margin up a whisker, at 35.1%
Adj operating profit just above breakeven, at £0.4m (LY: £1.3m) - this looks OK to me, so ticks my box no.1 above
Loss before tax is £1.48m, but this is mostly caused by a £1.22m amortisation charge which I am happy to reverse out, so in effect the business lost about £0.2m in H1 - about breakeven, which is fine.
Dividends - this is really positive, for sending a signal about management confidence - the interim divi of 1.5p is maintained, plus an additional 1.3p is being paid, which is the deferred final divi from last year. Talk is cheap, but resuming divis at a meaningful yield, is strong
H2 sales recovering well, but still below pre-covid level, "steadily approaching" it.
Guidance - very pleasing. The company gives us a P&L update to end Aug 2020 (8 months) - revenues £22.8m, which seems to show £9.3m revenues in just July & August. Let me check that, it seems too high. No, I think that's correct. There seems to be a strong H2 seasonal bias to revenue & profit, judging from last year's numbers.
Full year guidance is given too, very helpful indeed, everyone should do this. Revenues expected to be £37m, and >£2.0m in adj operating profit. That's a long way down on £5.6m LY. Poor, but not disastrous, is my judgement for 2020.
Balance sheet - is excellent, the company is very well financed, shareholders can sleep soundly at night, even if conditions worsen in the coming months.
My opinion - the forecasts shown on the StockReport look too high, so are likely to come down, to tie in with the revised guidance given today. Therefore we need to ignore the forward-looking metrics like PER and yield, for now.
I think Warpaint seems to have coped quite well with the crisis this year. It has a very strong balance sheet, is paying divis again, and business is recovering.
What it lacks is brand appeal, and performance in the past has been a bit erratic. Hence why the shares have languished. The valuation looks about right to me at the moment. The downside is nicely protected by strong finances. There could be future upside if a more consistent growth track record could be established.
Management came across well in a recent results video presentation - down to earth, with lots of skin in the game, the type of people I like to back. Overall, I think this is quite interesting, as something that might re-rate in the future, if they come up with some better product. In the meantime, it's trading OK, and paying divis. Quite a nice risk:reward balance. Mildly positive, is my overall view.
.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

133 comments
Re : Boohoo (LON:BOO) Hi Paul, I understand you know BOO inside and out and have made some cracking calls, by now (Sunday evening) you’ve probably read the full report by Ms Levitt. I haven’t, but I did read the “in-depth” article in the FT and a few things really raised a red flag to me.
Among them: “the worst working conditions I’ve seen in the UK” said by the auditors in 2019. From the report : “supply chain had been inadequate for years, well below the standard expected of such a company”, a full list of suppliers and subcontractors did not exist. On one unannounced factory inspection by auditors 10 people left through a fire exit! At another visit 2/5ths of the workforce left during the audit. Ms Levitt said some of the founder’s responses were “a cause for concern” and interviewing him “ a colourful experience”. Major red flags here IMO, a successful business and business model could still be redundant if the ethics of the people running it are allegedly dubious. I’m sure they’re out of the woods governance wise and the results will not disappoint but long term I’m sure it’s a ticking time bomb
Great news on Boohoo (LON:BOO) up 50p ( i hold) . I thank Paul for showing me the way here and the fact he has prior knowledge of this company i am sure helped a look of Stocko folk !
Warpaint London (LON:W7L)
Paul, thank you so much for these daily reports. I am new to Stocko and also new to more active investing and trading, so your reports, as well as the posts from this very knowledgeable group are helping me immensely.
Warpaint London is a company I noticed about a month ago and started to research it. What appealed to me about this company at first was its name. I think it’s a great name for a cosmetic company and didn’t understand why they were selling their products using the W7L brand name. So your comment struck a cord with me:
What it lacks is brand appeal, and performance in the past has been a bit erratic. Hence why the shares have languished.
Cosmetics are basically an exercise is marketing and this company aren’t even using what could be the best tool at their disposal, their name.
Upon further research I discovered 2 more cosmetic companies both called Warpaint, however both were incorporated a couple of years after Warpaint London.
One of these companies is called Warpaintformen, although in all the publicity they are getting they are only referred to as Warpaint. So they are trading on the Warpaint name. This company won investment on Dragon Den and its products are aimed at straight males who might need to cover up a zip or blemish. They are selling in John Lewis and online. The other Warpaint is in the USA and their products are aimed at the BAME market.
To me this shows poor management on 2 fronts. Firstly for not using Warpaint as the brand name for cosmetics aimed at a young market they have missed a massive marketing opportunity and secondly for allowing other companies to use the name and that marketing opportunity, when they had already incorporated.
Could you see Nike (or any other marketing savvy company) allowing someone to set up a company called Nike for men, or Nike USA etc.
I’m finding it very hard to invest in this management team.
Hi gari!
Thank you for your nice positive message. Its great when people introduce themselves pleasantly here, and give some interesting views & perspectives on shares. Much appreciated and to be encouraged :-)
Best wishes, Paul.
@Paul.
Do you see Revolutions around 10p as a calculated/speculative risk now or more of a hold and wait (hope) for a rebound. Fellow holder so curious
Thanks
Hi Lee,
Your guess is as good as mine. Revolution Bars (LON:RBG) is a special situation, we all knew the risks, and so far my view has been wrong, in terms of the covid situation not getting better, but getting worse. We all knew that was the main risk, and we took decisions based on that.
As regards the possible CVA, it seems like a good idea to me. The competition are doing the same thing, it's vital for survival.
Regards, Paul.
Paul,
In £RGB you explain in a CVA there may be tranches offering differing deals for different landlords. At the next suitable moments can you include a paragraph or 2 in your usual lucid prose about why landlords in a case like RGB agree to a CVA if they simply get (an overpriced) lease back - why not make the tenant pay until they go under. Is there typically still a 6 month notice period to work out?
I really appreciate the education through live example approach you deliver - so thanks.
However, any other resources you (or the community) could recommend to learn about CVA's, pre-packs etc. I cant see a Stockopedia ebook for instance. It's going to be a big issue in next 12months!!
Like most on this site, I have some accounting and financial statement reading skills but I am not a professional and most accountancy texts are way to dense to access and anyway, what you write about so clearly are business strategies and decisions under-pinned by accounting rules. This is where the value for stock pickers lies.
Corporate insolvency for dummies (not a personal comment on you)
And another
A Company Voluntary Arrangement is mechanism often used in property lease intensive businesses to manage excessive lease costs. essentially the firm negotiates with their big landlords and reaches an agreement. All landlords vote on it and if a certain proportion agree then it applies by law to all of them eg if the threshold % of landlords agree to a 25% rent cut then they all have to give the company a 25% rent cut.
Administration is when there is a potentially good business with rotten finances, so the Insolvency Practitioner aims to save the business. The calculation is that the business (or parts of it) are worth more if they are operating than if they are liquidated. In this case debts are left behind in the old company and it is the IP's responsibility to pay as many of them as possible from the sales proceeds.
Administration may be planned in advance (a pre-pack administration) or not. A pre-pack inevitably means that the previously previously controlling party buys it back on the cheap. The logic is that this minimises disruption to the business, maximises the value of the business and saves jobs. Presumably this was able to be used by £Quiz because the trading arm was in a separate subsidiary and the debt was non-recourse to the parent. It was only a trading arm which was put in to administration. Otherwise shareholders would have been on the hook for the debt/contracts - very cunning - but I haven't checked this. If the Plc had gone into Administration then the shares would probably by worth nothing.
Winding up by the court, an unpaid creditor petitions the court to wind up; the company in order to get payment on a debt. If a court order is issued the this usually becomes a compulsory liquidation. The biggest user of this is HMRC as they have first dibs on the assets of the liquidated company. Shareholders tend to get nothing.
Liquidation (creditors voluntary) the business is shut down and assets sold off by an insolvency practitioner. In this case unsecured creditors tend to get little and shareholders nothing.
Liquidation (Members Voluntary) is when the company is financially sound but owners decide to wind it up so all creditors are paid out their full owings. This may be sued for example by an investment trust which has plenty of assets but poor performance and shareholders vote to wind it up.
Unless something has changed over recent years Receivership is well-known but rarely used.
I hope it helps.
Thanks for overview of insolvency opens. The more I learn in investing, the less seems certain! I was not aware that small landlords could not hold their corner and could be forced to accept a rental cut in this way. (Also the supervisor in a CVA must be a responsible figure to withstand pressure from big landlords.)
One query left: what happens where leases are 'walked away from' ; does the landlord simply get the keys and an empty property plus fittings? There will be some bargains out there soon to rent if you have the funds and the right project.
Litigation Capital Management (LON:LIT) presentation to an investor audience from earlier this week, followed by Q&A, with CEO, Exec Vice Chairman and the relatively newly appointed CFO. Lays out very clearly where they're at & the growth potential. Worth watching, not only LIT but for other litigation financing companies, especially Burford Capital (LON:BUR), for the read across. Video or Podcast.
This looks like a well-run company with genuinely appealing products, sold in many countries. I'd be a buyer of Warpaint shares - but the daily volume varies between tiny and non-existent.
You win some,you lose some. I bought a load of Boohoo in April and have bought more on weakness. Unfortunately,I also bought a lot of William Hill but sold a few weeks ago !!!
Think a small punt on Revolution Bars is justified very soon.
Thanks as always Paul for your invaluable posts.
Hi Paul,
Any thoughts if Boohoo (LON:BOO) positivity might have impacted Sosandar today? After 2 days of some weak hands off-loading Sosandar (LON:SOS) there seemed to be new support at mid 13p and higher. Those of us in it remain seated on our hands no doubt as online retail 'seems' strong and healthy.
Hi Phil,
To answer your question (always just my opinion), I've never seen any read-across between BOO and SOS. Other than that both are seeing eCommerce growing.
SOS is niche. BOO is mass market.
Regards, Paul.
It's a real shame to see how the pandemic has affected the likes of Revolution Bars (LON:RBG) . It's a share I'm keeping a close eye on and I'll be looking to jump onboard if there are positive signs of a successful vaccine. Let's hope there is some good news in the coming months!
If there's ever a meetup for people from this forum then it's only right to host it at a Revolutions :)
If there's ever a meetup for people from this forum then it's only right to host it at a Revolutions :)
What a good idea!
wow, William Hill (LON:WMH) possible takeover just announced by Bloomberg. Kicking myself for not buying when it was at 150. well done holders
cheers
Francis
Yes William Hill (LON:WMH) was just 30 pence to buy in March and fell below 28 pence. There was also a primary bid placing at 128p (if I remember). Multiple bids it seems. Soared to a current price of about 300p. I hold. My guess is 400 pence plus. Gambling stocks have been a huge winner in Covid times; worries about the shops have given way to an understanding that the internet is the real driver.
Paul, I'm guessing now is a particularly good time to do a CVA for Revolution Bars (LON:RBG) / other companies? No landlord wants a pub back right now.
As the government has outlawed evictions (and just extended this during the week I think), companies have greater negotiating power than ever too (give us what we want or we will occupy and trade and not pay anything until further notice).
Anything you could recommend to read on this? I'd like to learn how the process works/ range of possible likely outcomes for shareholders etc. as I really don't know enough about it.
But there is a lot of bank debt too. At what level of rent would the business be cash flow positive if the current trading conditions are prolonged? If sites are divested how many will remain and will there be sufficient revenue to meet fixed costs and service the debt?
kgb - some of the RBG bank debt facilities are now 80% Govt guaranteed. So not a big issue in overall scheme of things, but DYOR. Also, much bank debt is available, not currently drawn down. It has lots of cash from recent placing. Important distinction after big equity raise. Plus a CVA would wipe out essentially all of the IFRS 16 liabilities. It's got plenty of liquidity, per last TU.
Good questions that you ask re number of sites, etc. I've probed on this, but it's commercially sensitive, so nobody will tell me.
Bottom line, smaller competitors are doing CVAs, so I think RBG will have to follow suit. It's way more solvent than independent competitors. If it's handled well then a terrific business should emerge in 2021.
DYOR as usual.
Paul I’m not an investor in this company or Boo for that matter. I’m interested only as a value investor - someone who looks to invest when they think the intrinsic value of a share is below the share price. So when things change like the potential closure of sites and CVA its worth going back over your assumptions.
On Boo I’ll keep my views to myself as anything that questions it just gets jumped on! It’s quite a good case study on valuing growth companies.
As the Human League used to say, common sense dictated I could never be so blind, and then...
”On Boo I’ll keep my views to myself as anything that questions it just gets jumped on! It’s quite a good case study on valuing growth companies.”
That’s a shame as contrary views are interesting.
I made 44% CAGR on my first foray into Boohoo (LON:BOO) which started late in 2015 at 34p (with top ups), which I held for 4 1/2 years. I am up 34% on second foray started on 17th June this year with seven subsequent purchases. So yes I am a bit of a fanboy but as I cannot see the bear case I would be very interested to hear one.
Kind regards
Michael
Michael it’s not a bear case. It’s that the current price or up to say 400 is quite a full. To get to 20p a share Boo will have to triple its revenue. What assumptions are made as to how they will do this? It’s easier to go from £300m to £1bn than from £1bn to £4bn. At some point PER will revert to the market mean of say 25 which means say 500p in a few years time.
They will require new products / new markets / new skills. Do the founders have the ambition to get there and how will they cope with scaling the business? Will they diversify away from what has been successful? Will they be able to make the right investments in people, systems and processes?
These are the sorts of questions I would be asking myself if I wanted to invest in Boo. I’ve read the accounts and also those of PLT when it was a ‘separate’ company. I’m not convinced and it’s not for me but many others like it. I have Next (LON:NXT) and B&m European Value Retail Sa (LON:BME) and happier with them.
The assumptions are, the world is massive and they have a foothold in most major markets that they can expand. They have a war chest of funds to buy up distressed retailers and turn them around using the Boo management experience and infrastructure.
Who cares if the founders have the skills to get there, that’s why they’ve hired very experienced fashion retailers such as Lyttle.
So, they have the markets, they’re buying in the products (as well as scaling the current ones) and they’re hiring some of the best leaders in the fashion trade.
I’m fully satisfied they have what it takes to be a monster sized company and will keep getting better.
Hi, can anyone enlighten me as to , if Revolution Bars go down the route of a CVA, what does would it mean for existing share holders? Paul I notice in your write up for RBG you do not state if you are still a share holder? Thanks for any info.
Hi lnav,
In other CVAs I've seen, it doesn't impact on shareholders at all, unless the company needs to raise some fresh funding to pay for the up-front cost of the CVA - often it can involve paying say 6 months rent to secure the support of each landlord, or some formula to put sites into different tranches, where landlords of the worst sites just get them back (lease cancelled), and other tranches of sites are given a say 25% or 50% rent reduction ,etc. Each CVA is a bespoke deal. It can often be tied to lenders taking a haircut on debt, and shareholders injecting more fresh capital, as part of a package.
Yes, I hold RBG, sorry I forgot to put in the usual disclosure, so have just edited the article to correct that, with my apologies. Nothing sinister, just an oversight.
Obviously I've got a thumping great loss on RBG, but I can't turn the clock back. I was hoping that business would be back to normal by the autumn, but that's now looking highly unlikely.
If mgt do another equity fundraising, then hopefully they would include another large open offer, like they did last time - to enable long-suffering shareholders to stand our corner, and thereby benefit from the upside in due course.
Regards, Paul.
Many thanks Paul for your reply
Hi Paul, I hope you don’t mind me asking but do you still hold Revolution Bars?
Hi pcr1,
Yes I do still hold Rev Bars. I forgot to add the disclosure in the article, so have corrected it now. Profuse apologies!
Regards, Paul.
I must say, Paul's reports are getting better and better! Absolutely brilliant insight and worth the subscription fee alone
Keep telling this to the boss!# And that miserable sod scobby dooh
Absolutely brilliant insight and worth the subscription fee alone
+27
Cheque in the post, I think we agreed 4.5%
Revolution Bars (LON:RBG)
Personally, I would prefer it if RBG goes the whole hog, and does a pre-pack administration, which is the cheaper, but more brutal option. Whereas a CVA is more costly. Ultimately though, both achieve the same aim of getting rid of all the loss-making sites.
My worry would be that with any administration deal, shareholders could be completley shafted and the company passed onto whoever pays the adinistratiors what they want to get the assets back - being labelled as the best solution for creditors. Am i being to skeptical in my thought here? as they haven't mentioned administration hopefully its a moot point "at present"
Strange in such times if they are going down the "we cant pay cap in hand route" (CVA) - that they would specifically mention the "strong balance sheet".
Hi rmillaree,
I was suggesting that RBG initiates & plans a pre-pack administration itself - this is what Quiz (LON:QUIZ) (I hold) did in June. You line up a friendly administrator, having already agreed with them the terms for buying the business back, minus all the liabilities. It all happens so quickly, nobody else gets a look in. Then you negotiate with all the landlords individually for cheaper rents, or hand back the keys.
This is what QUIZ has done, and has ditched about a dozen sites that weren't viable, and has agreed turnover rents on the rest. Hey presto! Problems solved, and a profitable business emerges in due course. Mind you, management at Quiz have experience of this, as they did the same in the 2008-9 crisis, buying the business back for under £1m. The business was then rebuilt, and partially sold to the City for a valuation of well over £100m a few years later. This is a good example of why it's such an interesting share now, given that the same procedure has been done again. So QUIZ could/should multibag from the current level, in my opinion.
RBG could end up in a similar position. Do a CVA, thereby ditch all the problems, and emerge from the covid crisis with low rents & potentially huge profits once people are allowed to party unfettered again, and with much less competition, as weaker operators inevitably go bust over the next 6 months.
We could see some spectacular investment gains in 2021, from businesses that manage to survive, and restructure now so that they emerge nto better conditions with super-low overheads. Remember it's often during times of crisis, that the seeds are sown for big future profits.
Regards, Paul.
Hi Paul,
Pre-pack worked best for Quiz (LON:QUIZ) because the store estate was a separate limited company and had no parent guarantees.
Do you know if Revolution Bars (LON:RBG) have similar arrangements? I suspect that given that they are discussing CVA not pre-pack that they don't (although they don't have an online business to protect either.)
I think the big risk is that they actually have the cash at the moment but it is rapidly running out. If I was a landlord and I wasn't sure of a viable business anytime soon but they had cash and hadn't fully paid me, I'd be looking at winding up orders to get the back rent now rather than take a risk on future trading in a CVA.
Still a high chance of a zero IMO and for that reason is in punt territory at best.
Paul Your comments and analysis on here day-in day-out are absolutely first rate. Your analysis on Boohoo (LON:BOO) has been a level even above first rate. Congratulations.
Revolution Bars (LON:RBG) just RNS'd possible CVA
I've written up a quick section above on the Revolution Bars (LON:RBG) announcement.
So if anyone had an opinion would they bail out and take circa 50% hit, or tuck in bottom drawer and have a look when covid nightmare over..my head and heart are arguing
....asking for a friend
That's the difficult bit, that you have to decide for yourself!
Thanks for your and others further opinions.
The management are good
They are actively trying to do something about a situation not of their making
They have considerable skin in the game at much larger prices
Mark Ward (whoever he is) keeps buying
My only decision now is to drip feed more in over the next few weeks, or see if new fund-raising is around the corner.
Off to buy a larger bedside cabinet.
New interview with the CEO of Strix (LON:KETL) where he goes into a little more detail of forrecasts, halopure and the 14 new developments, on course for year end....better get his skates on.
https://www.directorstalk.net/strix-group-a-solid-performance-and-plenty-of-opportunity-to-grow-interview/
Thanks to GloucesterBob for pointing out the new Strix (LON:KETL) interview.
The (54 min.) recording of Wednesday's results presentation is now also available here - https://www.youtube.com/watch?v=o1Lng17x6_Q&feature=youtu.be
Hi Paul
Please take care of yourself. Perhaps you are suffering some "Long Covid" effects.
On that front I found this article interesting, and would no doubt find it helpful if I had suffered Covid symptoms...
https://www.thetimes.co.uk/art...
Kind Regards, Martin
P.S. Shame I did not follow you into BOO or BOTB. Well done on both
Interesting (and slightly troubling) read.
Interesting RNS this morning from Keith Ashworth-Lord's Sandford DeLand outfit
intention to float the Buffet Smaller Companies Investment Trust plc
https://www.londonstockexchang...
Thanks for pointing out the intended float of a Buffettology IT. I see the intended MCap range is £20m-£500m. The existing Buffettology fund is open ended and has become so large that Keith Ashworth-Lord sold off holdings where the MCap was less than £100m because even a 20% holding in such a company would no longer "move the dial" as he put it.
Hi Paul, Did you write anything up on W7L in the end? I can't see it on Wed's SCVR. I for one would appreciate it, if you have time.
But please don't if you're exhausted.
Prompted by you, I'm doing a section on W7L now.
Hi Paul, Thanks - super useful and really appreciated. Have a good weekend.
Paul, your advice on Boohoo has been an absolute god send for myself personally. Thank you so much and one day i hope to repay you in copious amounts of beer :)
It's views/opinions here, never advice! If you've done well on BOO, then that's down to your own portfolio decisions, so well done to you!
Best wishes, Paul.
sorry, of course - your views were very well received. I had actually been buying Boohoo on it's downward run and started to doubt my own analysis. With so many bears out there, i really struggled to remain positive about the company. Your comments really helped to put my poor mind at ease. Thanks again.
Hi Mark,
I have been doing this for a few years now and have learnt, the hard way, that bulletin boards can sometimes help inform but often create unnecessary doubt about one's opinion. The Boohoo (LON:BOO) board on ADVFN in particular is one of the most unpleasant places I have ever visited in the last month or so and I've concluded that it is often best not to visit such boards at all when they become very 'lively' like on ADVFN
Well done for sticking to your guns.
cheers
Francis
thanks
Yes from another MARK B I could not agree more !
Remember to look after yourself Paul. You do such a fantastic job here no one would mind you taking the odd day or two off to put your feet up.
Anyone any idea what happened to SKIN integumen yesterday? Seemed like a fabulous rns then a massive fall! Pumped & dumped?
my only guess is that after the recent large price increases, some holders have sold out to take profits (likely substantial for longer term holders).
as you say, the RNS announced was fabulous (in my opinion a potential game changer) and could result in a further material increase in value.
they do already have a number of growing revenue streams (revenues have been revised upwards repeatedly over the last 18 months or so) so I think the market may have misunderstood the potential that this brings on top of an already growing/turnaround situation.
jonnyrotten..What happened ..RNS was brilliant,..followed by a disaster of a presentation...made the BOD of directors look like amateurs...which clearly they now are , after destroying over 50% of Skin & MWG net worth
Whilst there is a lot of noise around the Boohoo report, what I particularly liked was the response by the company in which it sets out measures to very considerably enhance its governance and oversight procedures. Why? Because whilst this of interest now, it is vital to future success for a company that wants/plans to become a very large business indeed. Some very important pieces have been put in place in this very mature, thoughtful and thorough response.
As ever Paul, thanks for alerting me to the Boohoo opportunity earlier this summer.
Following on from yesterday's comments about Capital & Counties Properties (LON:CAPC) [https://www.stockopedia.com/co...], here is Propel's report about Shaftesbury (LON:SHB) this morning. Too soon to know what the result of the September quarter will be (quarter day 24 Sept.).
'41% of rents have been collected: West End pub and restaurant landlord Shaftesbury, which owns a 16-acre portfolio in the heart of London’s West End, has reported 41% of rents due for the six months to 30 September 2020 have been collected, 10% are expected to be subject to deferred collection arrangements, 23% are being waived and 26% remain outstanding at 11 September 2020. The company stated: “Since the relaxation of government restrictions began to take effect from late June, the West End has seen a gradual recovery in footfall with the return of local and domestic leisure visitors and its office-based workforce. After an extended period of closure, most of our 611 restaurants, cafés, pubs and shops have now reopened. Bespoke packages of rental and other measures to support their recovery in place and being extended to the end of 2020. However, responding to the recent sharp rise in UK covid-19 infection rates, the government is now re-introducing national and localised restrictions, with a risk that further measures may be implemented until the situation is brought under control. Enquiries for commercial space continue but at a considerably lower volume than we would normally expect at this time of year.”'
My inner pedant compels me to point out that the Michaelmas quarter day falls on 29th not the 24th September.
Just in case anyone ever reads this and notices my mistake, the September quarter day is Michaelmas, 29th, and not 24th. Duh.
I was wondering if you could write a paragraph or two about a fundraising mechanism called a Subscription Agreement.
Ethernity Networks (LON:ENET) today said they have agreed terms with a fund to raise £1m+ through a mechanism called a Subscription Agreement. I get the gist of what is happening, but is there anything as a private investor I need to worry about such a fundraising mechanism? There's also a few extra terms and structuring in the announcement that I'm struggling to get my head around.
Hi
re Ethernity Networks (LON:ENET), it looks to me like an "of the order of" 30% dilution just to get the working capital for the new, and important, contracts it has been announcing. That's surely quite expensive funding.
Hi.
I'm not going to pretend I understand it in detail, but there was a good discussion on this on the ENET board on LSE amongst some knowledgeable posters today. Just Google 'ENET share chat' and you should find it.
Boohoo (LON:BOO) is being boosted by a short squeeze: 1.65% open interest : I suspect some of that is in the order flow this am
Mothercare (LON:MTC) might too though it is 8.%
Would you mind letting me know what website or software do you use? Seems quite advanced?
Re: Boohoo (LON:BOO) Mothercare (LON:MTC) Price Reaction and Short Interest
@Mort1980, this is my own work; I integrate various data sources and use rules and trading logic to visualise. The above is WIP but will be available in the next week or so on a daily basis at runprofits.com. It's a price reaction to RNS and integrates other catalysts like short interest and broker ratings. If you are interested you can sign up here.
There is a typo in my above comment, Mothercare (LON:MTC) short interest is 0.8% ..
I’m still on a learning curve - could you explain a ‘short squeeze’ for me? Thanks in anticipation.
if the price starts moving up after a downwards move, short holders can be stuck with having to buy back shares to close their position (to avoid losing money) and they add to the existing upwards pressure - virtuous circle - much like shorts being opened on bad news and people selling off their positions is a vicious circle
A short squeeze occurs when shorters get caught out by price moving against them and having to scramble to "cover" their short positions which in turn drives price even higher (owing to supply-demand imbalances)
Shorters borrow shares at price X and sell them in the market on the hope/expectation that they can buy them back at a much lower price, Y, and return them to the original owners. The shorters make their money when Y << X. Given the risks, shorters tend to do a lot of research and often produce reports which they publish to drive the share price down and then take their profits . Muddy Waters/Carson Block has shorted numerous UK shares including Burford Capital (LON:BUR) recently.
The squeeze is shorters minimising their losses as they have been caught out on their shorting premise by whatever news or fundamental change that has occurred in the business they shorted. . Unlike owning a share where your losses are lower bound by the share price falling to zero , shorters' losses have no upper bound and so they tend to try and cover quick. On a share that is heavily shorted , they may actually be competing with other shorters to cover which can make the price action very explosive.
Thank you to all the brilliant replies and your time - I get it now !!!! Onwards up the curve.
“Shorters borrow shares at price X and sell them in the market on the hope/expectation that they can buy them back at a much lower price, Y, and return them to the original owners.”
should read “Shorters borrow shares and sell them in the market at price X on the hope/expectation that they can buy them back at at a much lower price, Y, and return them to the original owners.”
For a fee of course.
Price X is only really relevant for risk purposes to the short sale transaction itself not the borrow transaction (other than as a reference point for initial collateral).
Hi GVB
There are others that will know far better than me as I am several (painful) months into my learning curve.
In my simple words this is where someone has taken a short position in a share, and there are various ways of doing this, and they are predicting that a share price is going to go down and hence make money from a reduction in the share price.
A "Short Squeeze" is where there is a significant number of people/companies who have taken a position that the price is going to go down and in fact the price goes up and looks like it is going to continue to go upwards, and hence they are trying to exit (at almost any cost) to minimize their losses.
Hence those with short positions are scrambling to close them as quickly as possible so you get a situation where the market makers are are actually ramping the price as they know it is the shorters dumping and hence an opportunity to profit. So typically creates a short term upwards spike in price.
Sort of the reverse of a normal "shake down" where the market makers are trying to trigger the stop losses (or fear) of PIs by forcing the price downwards. So typically creates a short term (same day or 24 hours) dip in price.
Cheers
Tommy
In brief, it is when shorts are "forced" to buy back there shorts. There could be two reasons for this:
1) As is being referred to in the Boohoo case, if the price rises a lot, then the shorts are making a significant loss and the monetary value of the short position has increased. Therefore shorts might be "forced" to buy back because either a) the loss is too big (some form of stop loss); b) risk management (the previous short position size is now x% larger and is now too big); or c) some short of margin call (shorters will by definition be operating on margin - if the loss gets too big, they may be a forced unwinder to meet a margin call).
2) If a stock lender recalls the stock. (So not what is being referred to in the Boohoo case). In order to short stock, you need to borrow it. Some shares are harder to borrow than others - it depends on supply and demand (which will be reflected in the fee paid by the borrower). But in a heavily borrowed stock, there might be a limited supply of stock to borrow. Nearly all stock borrowing is recallable on demand. In such a situation if a lender recalls the stock (maybe because they want to sell or to attend an AGM), the borrower may be instructed to return the stock that they have borrowed and sold and the only way to return the stock will be to buy it in the market. The danger for the recalled shorter is they are unlikely to be only borrower recalled, so there could be several different shorters all required to buy back in a limited time limit.
Interesting RNS slipped in on 'take out the trash Friday' news day - Alchemy, who own 29.5% of £NSF and former owners of Everyday Loans its key subsidiary, tightens its grip via appointment of one of their own, Toby Westcott, to the NSF Board from Oct 1st.
His background cited was as a specialist in "mergers and acquisitions in the financial services sector". Prelude to Alchemy forcing through a corporate shake up early in 2021?
Selling off Home Credit has been mooted to raise some cash, leaving Everday Loans (only national face to face bank network and previously owned by Alchemy) and a Guaranteed Lending division whose only major competitor is Amigo (80% segment share) which is facing all sorts of internal issues . Short term in COVID you would be hard pressed to think of a worse business focus!
Share price has slid for years and IMHO is now likely within months to multi-bag, be taken private for peanuts or go bust depending on how bad its impairments are over the next few months and govt action to protect and support distressed borrowers / the low paid. It desperately needs more capital. Segment is super-hated (high risk, high regulatory threat, ethical concerns for some, capital short) but long term I think the business has a great oportunity.
I hold (a lot!) and have watched it closely for years. So far its been a disaster for shareholders through a combination of long term hubris by Chief Exec (over paying for assets to enter the game, failed attempt at reverse takeover of £PFG, and bad luck in the speed of COVID's arrival) Indeed, I bought precisely because I thought it could reprice loans fast in the event of recession!.
However, starting with a clean sheet, now high risk, high return opportunity with catalyst coming into view.
So - Ideal speculation Friday: Any financial engineers got ideas about how a PE company with a 30% share of existing would act to maximise their return and how a private investor should act. I would participate in a Rights Issue but fear being taken private. If I were willing to wait 3-5 years for it to be floated again, is this possible and would I likely be treated equally through the journey.
Boohoo (LON:BOO) and still wait for a, as I predict it on evidence, very strong trading update / interim results next week beating expectations which will cause the share price go beyond 450-470p. Time will tell but I'm on record !!
I see Boohoo (LON:BOO) Broke through the 330p net this morning. Any significant news today? I thought this was to be Monday?
very useful info below. Read through comments as some people have summarised the report etc. very helpfuly.
Those interested in Byotrol (LON:BYOT) Byotrol (as £ doesnt seem to work on iphone)
Investor Meet Company platform on Wednesday 30 September at 16:30. The online presentation is open to all existing and potential shareholders
Asda using a product called Biomaster, for coating trolley handles and I think also involved in anti-microbial food packaging. Seems produced by Addmaster but must be a private company. I got impatient with Tristel Thinksmart (LON:TSL) and haven't looked since.
Sorry Tristel (LON:TSTL) :)
Judges Scientific (LON:JDG) H1 20 results presentation to analysts, including Q&A, by David Cicurel, CEO, Brad Ormsby, Group Finance Director, and Mark Lavelle, COO. (Given 22.9.20).
Resilient profitability and cash generation in spite of CV19. This covers good detail of the financials, including their impressive track record, their acquisition strategy, growth drivers and the outlook. Video & Podcast.
Seperately, here's yesterdays, very popular, piworld interview with Cockney Rebel, AKA Richard Crow. Richard is a retail investor who makes c.30% pa investing returns. Here, he gives insight to how he achieves his outperformance, discussing bowl charts, recovery plays, including Xaar (LON:XAR), De La Rue (LON:DLAR) & Sig (LON:SHI), and more about how he runs his portfolio. A very engaging hour, full of investing insight, with Q&A. Video & Podcast.
We should have the Litigation Capital Management (LON:LIT) FY20 investor presentation, later today, which I'll then post here.
Just listened to Cockney Rebel podcast. very interesting. thanks.
Not sure why he says that De La Rue (LON:DLAR) has no debt though. Stocko Report shows Net Debt is very much present and going up.
Hi R--G, I strongly suspect those figures do not reflect the fact that the company raised substantial amounts of money in July this year.
Yes you are right, thanks. They raised £100m by issuing 90m new shares, I don't see that reflected in the Stockreport which shows Average Shares virtually unchanged from last year. But then I thought the £100m was going to be used for the Turnaround Plan, not to simply cover the debt...
Any idea why this is not reflecting in the StockReport?
Because the shares were issued in July and the latest financials are to March ?
BOO +13% today thus far. Reacting well to the report!
short squeeze? Maybe.
there has been no short position on £BOO. Why on earth would an institution short a high growth cash generative company?! Too dangerous and in fact not happened so far. FCA register records short positions.
Hi Mort1980, you can see the short positions here, 1.65% last reported https://www.shorttracker.co.uk...
cheers
Francis
thanks Francis.
Apology accepted.
There are short positions on £BOO. https://www.fca.org.uk/markets...
See above. It’s not institutions. It’s Hedge Funds.
Probably news to Matt Earl.
My morning smallcap tweet:
Mothercare (LON:MTC) Simigon (LON:SIM) Ceps (LON:CEPS) Digitalbox (LON:DBOX)
Mothercare (MTC) FY(Mar). Current YTD Franchise Partners rev down 39%. 95% of partners' global retail locations now open. [SP=8.32 Cap=31m]
SimiGon (SIM) H1(June) rev down 50%. Pretax -$1.3m (-$433k). Guides moderate improvement in H2. [SP=5.34 Cap=3m]
CEPS (CEPS) H1(June) rev down 38%. Pretax-cont -£162k (+£150k). No current trading figs. Why? Does not expect normalisation of trading until perhaps 2022. [SP=22 Cap=4m]
Digitalbox (DBOX) gets £450k 5 year covid loan to keep the lights on. [SP=4.85 Cap=5m]
In line: £
Hi Paul
Boohoo (LON:BOO) I have read through the RNS at https://otp.tools.investis.com... & as they say bits make for uncomfortable reading but overall I have a positive take away on the statement & if I was not already at a >10% holding I would be a buyer here.
I am indifferent as to whether the market agrees with me today or over the next few weeks but I would imagine over the relatively near term, once the market has properly absorded today's statement, the share price should recover back to its all time highs of Jun 30th. If anything Boohoo (LON:BOO) is a better and stronger company than it was then.
Kind regards
Michael.
That said I have to be honest it is not possible to be indifferent to the Boohoo (LON:BOO) share price when it jumps 21%.
Assume JP Morgan analyst will now review upawards his target price of 416p?
why is it coming down Mike?
I dont really understand you question so if you can expand on it I will try to answer later today.
Kind regards
Michael
Sure. I meant when the short squeeze sent the price to around 400p in the morning, why do you think it started to shoot down so quickly coming back to c.350p? I just want to learn and understand to see if this is something typical when a short squeeze happens or not, and if not, what are the factor / reasons to consider?
Thanks in advance.
Maybe day traders making a quick profit?
Hi Mort1980
I think the trading pattern today for such a high profile and well ramped/deramped stock as Boohoo (LON:BOO) seems entirely normal. My opinion is that there was heavy buying first thing to 395, then traders banked some profits, then more buying to 385 then more banking profits which, as it slid down towards 350, accelerated. I suspect the price will close today somewhere around 350/360 and will hover around that until results next week. I may be wrong but I don't think the short squeeze hasn't actually happened yet as there are 20m shares at least short and the volume today is around 14.5m so far.
Happy to be challenged on the above but this seems logical to me
cheers
Francis
EDIT: Full disclosure - I sold my entire holding at 383 and bought back at 357
Well done Francis! I remember you did the same thing when you said you'd sold all at around 330p and bought back at 305p. Now you sold at 385 and bought back at 357. I guess this can be very profitable strategy, isn't it? I am quite new so will be thankful if you explain more and I learn.
Cheers.
Thanks Mort, if only it worked every time I'd be much better off.
Trading like this is something I've been trying to learn more about as I became a full time investor a couple of years ago but its not all as plain sailing as it might seem.
I trade about 25% of my portfolio (the rest being long-term holds). Unfortunately I have a host of losers that bear witness to my ineptitude and many winners that went on to multi-bag after I sold. For instance I recall buying Boohoo (LON:BOO) at 30 and selling at 40; recently I bought Games Workshop (LON:GAW) at 4700 and sold at 6000.
However what I am getting better at is reading charts, looking at lines of resistance and support to time my buys and sells and trying to judge market sentiment. After the first sell-off I bought Boohoo (LON:BOO) at 220 and sold far too quickly at 260. Then I re bought around 270 and sold at 325 (the line of resistance). Then I re-bought again (far too quickly) at 315 and kept on buying as low as 284 until my recent sell at 383. My thinking was that the SP might get close to the current 415 resistance but would fall back until the results come out. Once the second wave of buying was done this morning (around 385) I decided to sell and wait for it to drop. Luckily it did and I bought back at 357. I will continue to add around 352
A few months ago I decided to record all my buys and sells on Twitter where I admit to all my losses as well as gains using the handle @fwyburd.
FWIW, I am -9.57% down this year
Cheers
Francis
Hi
Well I sold out out £3.68 this morning and decided just to take the (small) profit and wait on the sidelines for a couple of days, early afternoon seemed the right plan but now has bounced again so thinking hmmm that could have been more, similar if I had not been looking after the kids and getting them to school this morning too and sold higher.
But I guess that is the difference to full time to part time, and also those learning and more experienced.
But pat on the back, I was in the game and made a profit, so overall for today I think a "well done son, go get a glass of wine and get tea on the table NOW!"
Tommy
"For instance I recall buying Boohoo (LON:BOO) at 30 and selling at 40; recently I bought Games Workshop (LON:GAW) at 4700 and sold at 6000."
Sounds very black and white. Have you ever considered selling some of the holding and maintaining a holding, allowing you to participate in further upside? Think of overall capital exposure as well as share price.
TheArb
I also, coincidentally bought Games Workshop at £4.60 and sold at £6.
I sometimes top slice as you suggest, but I sold all my GAW stake for investment reasons, and for investment reasons I usually sell the lot. Unfortunately for GAW that turned out to be a big mistake and GAW hit £100 recently!
For years now I’ve tended to sell on bad news or if having doubts. That works more often than not, but several times as the GAW bounced I (wrongly as it turned out) thought that if I hadn’t sold t £6 I would certainly sell now. So with hindsight that would have been just as wrong, albeit at a higher price! Selling decisions are imo more difficult than buying, but being over cautious tends to work better for me than being too gung ho.
I love this approach, but not brave enough to act on it myself. In my limited experience; the market tends to do the opposite to what I am hoping for :)
I know exactly what you mean Andy and suffer many failures when I trade. But I'm getting better at cutting losers and trying to learn patience to hold onto my winners.
cheers
Francis
I think others have answered better than I can.
I suspect another cause will be that market makers having read the report will have marked up the price at the open before assessing demand but to be honest my knowledge on this sort of thing is very limited. Sorry.
Kind regards
Michael
Boohoo (LON:BOO) independent review of it’s supply chain has been released this morning
Report is at https://www.boohooplc.com/sites/boohoo-corp/files/final-report-open-version-24.9.2020.pdf
Summaries:
"(i) Boohoo’s extraordinary commercial growth has been so fast that its governance
processes have failed to keep pace;
(ii) It has concentrated on revenue generation sometimes at the expense of the
other, equally important, obligations which large corporate entities have;
(iii) It has not felt responsible for conditions in the Leicester factories on anything
other than a superficial level; and
(iv) On occasions it has failed to appreciate that with the enormous advantages of
being a publicly-listed company come responsibilities, one of which is on all
occasions to act in the best interests of all the shareholders.
That being said, I have seen material5 showing that, following the publication of the Sunday Times
article, Boohoo’s Chief Executive, John Lyttle, and other Board members spoke privately but
with passion about the importance of leaving “no stone unturned” in this investigation and their
commitment to being “a good corporate citizen”.
...
The problems in Leicester are complex and of long-standing and Boohoo is not solely to blame;
others too are responsible for not having gripped this over many years. It has been alleged that
Boohoo’s business model is dependent on the profits which can be made from the deliberate exploitation
of the Leicester supply chain, safe in the knowledge that there will be little scrutiny.
I do not accept this; I am satisfied that there are sound legitimate business reasons for Boohoo
using Leicester to manufacture clothing but for this to be the case going forwards it may require
a change of approach, not least in terms of how Boohoo educates and trains its buyers.
...
I have reached the conclusion that the true reason that Boohoo did not become more involved
in monitoring conditions in Leicester was that it saw it as being a lower priority than matters
which directly affected the company (such as commercial issues or their own employees). The
Leicester workers are not employed by them and so they are not their responsibility in the way
that their own workforce is.
...
In summary, my findings are as follows:
(1) There is no evidence that the company itself or its officers have committed any criminal
offences;
(2) I am satisfied that the allegations about poor working conditions and low rates of pay in
many Leicester factories are not merely well-founded but substantially true;
(3) Boohoo’s monitoring of its Leicester supply chain was inadequate and this was
attributable to weak corporate governance;
(4) From (at the very latest) December 2019, senior Boohoo Directors knew for a fact that
there were very serious issues about the treatment of factory workers in Leicester and
whilst it put in place a programme intended to remedy this, it did not move quickly
enough;
(5) Boohoo ought to have appreciated the serious risks created by ‘lockdown’ in relation to
potential exploitation of the workforce of the Leicester factories. It capitalised on the
commercial opportunities offered by lockdown and believed that it was supporting
Leicester factories by not cancelling orders, but took no responsibility for the
consequences for those who made the clothes they sold. However, I received no
evidence that the company’s purchasing practices are responsible for an increased
COVID-19 rate in Leicester.
I should make it clear that there is ample evidence that the steps which Boohoo is now taking in
relation to remedying problems in its Leicester supply chain had been embarked on nearly a year
ago. They were a product of processes it had itself put in place and not just a reaction to the
negative publicity in July and August 2020.
My recommendations for the future direction of the company appear in the final chapter of my
report but can be summarised thus. If Boohoo is willing to take a different approach to how it
both views and interacts with the Leicester supply chain, it has it within its power to be a
tremendous force for good. If he chooses to do so, the Chairman could become an icon in the
industry and the company he created will go from strength to strength. There is a clear warning
here though: unless the Board is sincere in its determination to make Leicester better - to use
the language of modern management techniques, to live its values - it is inevitable that these
problems will recur, with the concomitant likely effect on its share price.
It is time for Boohoo to come of age."
[edit] Later on "Boohoo’s monitoring of its Leicester supply chain has been inadequate for many years. Its internal processes were well below the standard which would be expected of a company of its size and status. ...
I am satisfied that Boohoo did not deliberately allow poor conditions and low pay to exist within
its supply chain, nor did it intentionally profit from them. I do not accept that Boohoo’s business
model is founded on exploiting workers in Leicester. ...
Boohoo’s culpability lies not in doing nothing but that they did too little too late. "
an interesting snippet from the report regarding workers being paid less that minimum wage..................
f) A Verisio 2020 spot check of #16: the company’s managing director admitted to paying workers less than minimum wage. He said that he was under pressure to pay below the minimum wage as most workers wanted to claim benefits and would leave if actual working hours were recorded
Thank you MrC for the link to the report. I was struggling to find it.
Whether I can find the time to read the whole thing I am not sure. I know I should....
Hi Michael, link to the full report is in the SCVR above. Also on the website..
https://www.boohooplc.com/site...
Justin.
Thx. Was trying to read it before Paul’s report was published. Still cannot find a link to the report on the plc web site but that could easily be me.
Thank you for the link.
Kind regards
Michael
Mr C - you are so reliable and prompt - great to have you here. EVERY SINGLE DAY. Can you write the this daily SCVR share review column too?
Thanks,
I could write the SCVR - if you wanted something wholly inferior and superficial!
Good team spirit here. Full marks to all involved, Paul, Jack, and the regulars especially Mr. C.
Thanks very much, I love you too. :-/
Chapter 8 shows mgmt in a very poor light eg
"One of the aspects that I have observed is a tendency by the Boohoo Board to treat every piece
of negative publicity about the Leicester garment industry as though it was the first time they had
ever heard it."
"In the middle of the lockdown period, Nasty Gal had placed an order for some jogging bottoms
with Revolution, a design house in Manchester which has no manufacturing capability. Who then
did Nasty Gal think was going to make them? I have concluded that the truth is that they did not
know and did not really care."
"Boohoo’s attitude to the question of whether the Morefray workers were being paid less than the
minimum wage is baffling. I have been told by the Board and by Senior Management that there
was ‘no proof’. When it is pointed out to them that the proof comes from what the journalist says
he was told by the workers, they are sceptical about that and appear to be suggesting that this may
have been invented or exaggerated in order to sell a story. They either have forgotten or regard as
irrelevant that when Verisio conducted the emergency audit on 6th July as part of Boohoo’s
investigation into the Sunday Times story, they were approached by a whistle-blower who told them
that they used to work in that factory and were paid less than the minimum wage.
I am troubled by the fact that there is no acknowledgement by the Board that this evidence should
simply confirm something they already know."
"I have concluded that many of the problems exposed by this Independent Review can be attributed
to the system of sub-contracting."
To put it another way BOO maintained a plausible deniability (that eroded) for years.
I hold BOO but I'm highlighting the worst parts of the report as it's best to be open-eyed about problems in companies we own.
Hi Paul,
I hope you're well!
An interesting RNS from Boohoo this morning. It seems a very mature response which should ameliorate problems in their supply chain. Hopefully this will be reflected in the share price...
Cheers,
Mark
Hi. Do you know why Rm shares tanked 15% late yesterday?
EPS * PE would suggest the share price was overvalued.