Small Cap Value Report (Fri 26 April 2024) - LGRS, DARK, CAR, REC, BRCK

Good morning from Paul!
Today's report is now finished.
Quarterly doom & gloom report from Begbies Traynor (LON:BEG) is published today - saying that insolvencies are heading upwards, particularly in consumer facing sectors. It calls the UK economy "troubled". Expects "thousands of businesses failing in the coming months...". I'm sure they're right, but remember BEG only focuses on the small minority of companies that are in serious financial trouble. It's not necessarily a good indicator of the future outlook for the economy as a whole, in my opinion. The overwhelming number of companies we report on here are hitting, some even beating, expectations.
I've been a little distracted this morning, watching company webinars, here are my brief impressions -
Tortilla Mexican Grill (LON:MEX) (I hold) webinar on InvestorMeetCompany -
- New CEO comes across a lot better than I was expecting. Former CEO felt it was time to step back, at 60, and after 10 years in the role. So looks like it was amicable handover to former CFO as new CEO - who seems energetic & full of good ideas/strategy I think.
- CFO confirmed that it should move back into profit this year, due to consumer recovery and fixing a lot of costs (energy & food) favourably in H2 last year, helped by increased scale.
- Big operational gearing when demand recovers.
- Funding roll-out from own cash (so hopefully no placing!) with focus now on capital-light franchising deals (5 new stores this year), and intention to expand into Europe via franchising route.
- Little good competition, MEX is way ahead of competition in UK & Europe, and purchase of Chilango has done well -took out the best competitor, and a good way to grab some decent London sites at lower cost than doing from scratch.
- More effective marketing to be done this year, as brand awareness is way too low - opportunity.
- Revised delivery strategy is working - negotiated deals with Uber Eats and JustEat only, dropped others (mostly overlapping customers).
- "London is coming back strongly".
- Customer loyalty system, and kiosk ordering both working well, opportunity to expand both.
- Labour deployment being improved.
- Supply chain & inflation easing.
- Food is no.1 priority - best food at best price - good to hear from a bean-counter!
- CEO has taken up running, completed a marathon in under 3 hours (wow!), and did a run round all 28 London sites (shown pictures), good promotional activity and I think demonstrates he's a good leader - prioritises spending a lot of time in stores, seeing how things work, and what can be improved, motivating teams, etc. I like that - this type of business needs a hands-on, energetic manager, not a visionary risk-taker, in my opinion.
Overall - I'm impressed and very happy to sit tight on my shares. I think the bears on this stock are clearly wrong. It's too cheap given the opportunity in a recovering economy, in my view. I'm keeping my personal 100p+ price target. Obviously I'm biased, as I own some shares, but that's my thinking on it, right or wrong. I'm much happier this week than I was last week, that I've got this one right, but only time will tell!
Focusrite (LON:TUNE) - I missed the first 20 minutes, but what I did catch, and in particular the Q&A struck me as very good.
- Both presenters CEO & CFO came across really well to me - absolutely straightforward, they answered questions honestly & directly. Didn't try to gloss over things that had gone wrong (eg problems with new product launch, and resulting excess inventories).
- I asked about excess inventories, suggesting they should get stock turn down to 1-2 months, not >6 months presently. CFO gave good answer, saying yes stock needs to come down, but 3-4 months is their target, as they carry some raw materials at some manufacturing subsidiaries, and supply chain benefits from supporting distributors with more stock.
- All the other answers were clear and seemed fair & balanced.
- I mainly watch webinars to decide if I trust management or not, and to assess their ability & strategy. Being a slick presenter doesn't matter to me, and can actually be a turn-off sometimes.
- TUNE came across well on my criteria, so I'm feeling a bit more positive about its recovery potential than I did yesterday when reviewing the numbers.
I recommend watching both of these webinars when the recordings are up on IMC, as they're both interesting & useful. Let me know what your views are too, I find it interesting to hear opposing views, as they make me think more!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
I've chosen the order to do these sections according to the "Most viewed in the community" widget on the home page here.

Other mid-morning movers (with news) -
Darktrace (LON:DARK) - up 19% to 614p (£4.31bn) - Recommended Cash Acquisition - Paul - PINK (takeover)
Buyer: Thoma Bravo LP (US private equity)
Price: $7.75/share in cash (620p at £1 = $1.25)
Premium: only 20% to last night’s close, but 148% above April 2021 IPO price. Share price had settled at c.350p in last 6 mnths, so this is a 75% premium to that.
Valuation: 34x adj EBITDA for 2023.
Irrevocable undertakings: low, only 14.4%, so it’s not a done deal yet, by any means. Needs a 75% shareholder vote.
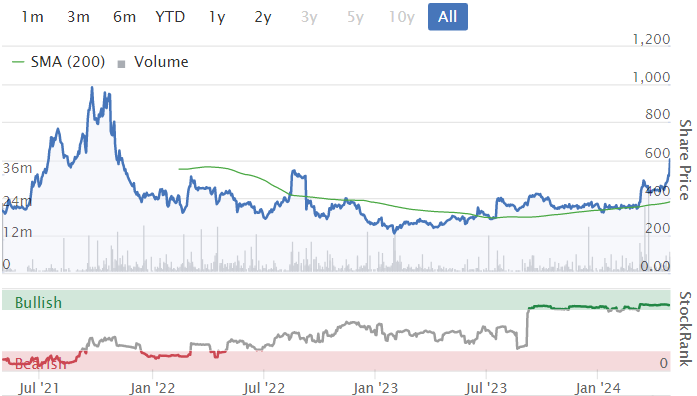
Zooming in -

Carclo (LON:CAR) - up 49% to 11.1p (£8m) - Full Year Trading Update - Paul - RED
Today, Carclo plc, a global leader in delivering high-precision critical components to the life sciences, aerospace, optics, and technology industries, provides an update on trading for the financial year ended 31 March 2024 ("FY 2024").
Encouraging performance, ahead of expectations in H2, and up on H1 (no figures provided). Margins improved, and has restructured. Cash generation also better than expected. It has £9.2m cash/debt headroom, but I see net debt as a big problem at £30.4m (down from £34.3m a year ago) - although it discloses net debt including leases. Excl leases, it’s about £19m I think. Complied with covenants throughout the year - which the bank relaxed in 2023 to expiry in June 2025. It doesn’t mention the giant pension scheme deficit.
H1 results show accounting pension deficit of £37m, with the 2021 actuarial deficit a gigantic £83m! Cash contributions by the company are currently running at c.£3.6m pa. It made a £(2.5)m loss before tax in H1.
Paul’s view - today’s perky sounding update glosses over the seriously bad financial situation. Although that might be an opportunity, possibly? If trading were to strongly recover, then it could further reduce bank debt. Note that it has £23m of land & buildings in fixed assets, which is actually higher than the bank debt. This could explain why the bank has given it a lifeline to turn itself around by June 2025. If that doesn’t happen, then the risk is the bank pulls the plug, and forces the sale of the freeholds to recover its money.
This remains a very high risk special situation. There’s a huge range of potential outcomes for equity, from zero if it ends up in administration or is forced to sell the operating businesses at a value below debt. Or upside cases could be a significant multibagger, if the business starts trading much better, and the bank & pension scheme can be placated. Equity is only a stub at £8m market cap. It has to be a RED here due to the high risk, and massive scale of its financial problems (bank debt and huge pension deficit), which make it very unlikely that shareholders are likely to ever receive any meaningful divis. I’ll keep an eye on it, as this could have exciting leveraged upside if trading improves a lot. So far I can’t see any evidence of that. It’s got breathing space though, so has an opportunity to turn things around over the next year. Clearly shareholders are going to get tapped for a placing, if/when it becomes possible, and the clock is ticking with bank facility expiry in June 2025. Can they pull a rabbit out of the hat, I wonder? I imagine stale bulls likely to snuff out upward price spikes, as has happened before.
Summaries of main sections
Loungers (LON:LGRS) - 231p (pre-market) £240m - Year End Trading Update - Paul - AMBER
Ahead of expectations update for FY 4/2024, with Liberum raising forecast EBITDA by 4% (but no change to EPS), and EPS up 8% for FY 3/2025. I see LGRS as a best in class operator, and an attractive self-funded rapid roll-out of new sites. However, it has little balance sheet support, and only achieves a low 4% PBT margin, whilst shares are priced at over 20x earnings. So it's the valuation that fails to appeal, despite it being an impressive business (albeit in a very tough sector).
Record (LON:REC) - up 3% to 63p (£126m) - Q4 Trading Update - Paul - GREEN
AuM have risen again this latest quarter, to a new record high. Although we're not told how trading overall is performing vs market expectations, a glaring gap. The main attraction is the lovely 8.0% yield. I'm a little concerned that forecast profit has been slipping, despite AuM reaching new highs. Is there an underlying problem possibly?
Brickability (LON:BRCK) - down 3% to 66.2p (£211m) - Trading Update [in line] - Paul - GREEN
A reassuring update. No signs of recovery yet in the building supplies sector, but at least things haven't got any worse. On balance, I think risk:reward could now be looking favourable, for a recovery later this year or early 2025, so I'm shifting up from amber/green to GREEN, in anticipation of cyclical recovery.
Paul’s Section:
Loungers (LON:LGRS)
231p (pre-market) £240m - Year End Trading Update - Paul - AMBER
Loungers, a leading operator of all-day café/bar/restaurants across the UK under the Lounge, Cosy Club and Brightside brands, today announces a trading update for the 53 weeks ended 21 April 2024 ("FY24").
Why have a year end on 21 April? Bizarre, but it doesn’t really matter.
This looks good, ahead of expectations - seems to have been nicely anticipated by the buyers in recent days who have taken the share price higher in advance of this positive update -
Continued strong like for like sales growth allied to an accelerated site roll-out, with 36 new openings in the year, expected to deliver EBITDA ahead of expectations
Key points -
Revenue £354m for the 53 weeks, up 24.7% on LY, or 22.2% excluding the distortion from 53rd week.
LFL revenues up an impressive +7.5% over the 53 weeks (similar to +7.6% LFL reported for first 32 weeks of the year).
“...continued easing of inflationary cost pressures”
“EBITDA for FY24 to be ahead of market expectations.”
(no detailed footnote unfortunately)
Balance sheet - once again LGRS claims it is strong, which in reality it isn't. NTAV was £34m at 2/10/2022, and included only £5m in freeholds. Modest net bank debt of £9.7m, so gearing isn’t a problem.
Self-funding a rapid expansion, with 36 new sites opened (that takes some doing!) - total now 257 sites. New sites have traded well (that tends to happen, as they’re shiny & new).
Diary date - 9 July 2024 for FY 4/2024 preliminary results.
Outlook - encouraging noises about the UK consumer -
"As we start the new financial year we are looking ahead with optimism. Our experience suggests that the UK economy is holding up well and we are well positioned to deliver continued growth."
Broker update - I’m grateful to Liberum for updating us this morning, this helps us quantify the out-performance. Analyst Anna Barnfather increases EBITDA forecast by 4% for FY 4/2024, together with 6% and 7% increases for the subsequent year.
I don’t trust EBITDA, as it’s so deeply flawed after IFRS 16, and ignores a ton of real world costs. However, in the hospitality sector, pre-IFRS 16 EBITDA is actually quite a good proxy for steady state (ie. if no new sites are opened) cash generation.
To demonstrate how ridiculous the post IFRS 16 EBITDA figures are, FY 3/2024 forecast is £54.8m EBITDA, and £13.7m PBT! (adj PBT strips out the rather generous share options costs, and is £17.7m).
I prefer adj EPS as the main measure to value shares, and wish more companies would disclose this figure in their trading updates. It’s 8.9p, which is unchanged on the old forecast, strangely.
This goes up to 10.9p forecast FY 3/2025, and a large jump to 14.1p in FY 3/2026.
What valuation multiple to use? I’d say 20x forward EPS is sensible, for a successful, well-managed business that is self-funding its own store roll-out. That gets me to a target share price of 218p.
It’s already above that, so I don’t see value here. It would need to strongly out-perform forecasts in future to get me interested in wanting to buy the shares.
Paul’s opinion - this is a well-managed business, sector experts have been telling me that ever since it listed, and they’ve been proven right. Self-funding roll-outs of a successful format are often nice investments.
However, this is a very difficult sector, where net profit margins are currently very low. What’s going to change to improve that? Some costs (eg energy) are falling back from elevated levels, and food/drink inflation has moderated. But wages costs are still soaring, with now 2 years of c.10% increases in living wage, which hits hospitality the hardest as it’s by far their largest cost, at typically about 30-35% of revenues. Even though it’s trading well, LGRS is still only going to make a c.4% PBT margin this year, which is a lot of work (257 sites) by lots of people, to only generate £13.7m in PBT.
So I’m struggling to see why I would want to invest in this difficult sector, unless the valuation was extraordinarily cheap, which LGRS isn’t.
Long-term it should do well, but the price doesn’t appeal to me currently. So I’ll go with AMBER.
I’m not sure about its Brightside reincarnation of Little Chef - are these any good? Has anyone mystery shopped them? If so, do leave a comment!

Record (LON:REC)
Up 3% to 63p (£126m) - Q4 Trading Update - Paul - GREEN
Record plc ("Record", the "Company" or the "Group"), the specialist currency and asset manager, is pleased to announce its trading update for the three months ended 31 March 2024 ("Q4-2024") and the financial year ("FY-2024").
This struck me as good (in the context of a persistently weak share price) -

The quarter-on-quarter AuME figure is also good - rising from $99.5bn at Dec 2023, to $102.2m at Mar 2024.
Performance versus expectations? Not stated, which is a glaring gap in what they call a trading update.
Outlook -
AUME continues to grow and now exceeds USD$100 billion for the first time in our 40+ year history… the outlook for our business remains strong…
"Building on our existing proposition and the demand we observe for our services as a specialist asset manager, we are now refining our product range to focus on a select number of best-in-class products which present attractive and meaningful opportunities for us, making Record a stronger, less concentrated, and more robust business.
Paul’s opinion - I would have preferred a clearer overview, saying how the business is performing vs market expectations. Instead we get quite granular detail, which I’ve not repeated here.
There are no broker notes available to us either. Clearly REC needs to improve its communications with investors. With most institutions not interested below £250m market cap, and existing institutional holders possibly facing redemptions, REC needs to focus on selling the shares to private investors - but we’re not getting the information we need (clearer trading updates and broker research). Although to be fair, it is good to see that REC results presentations are available on InvestorMeetCompany.
Note the broker consensus forecasts have been declining -
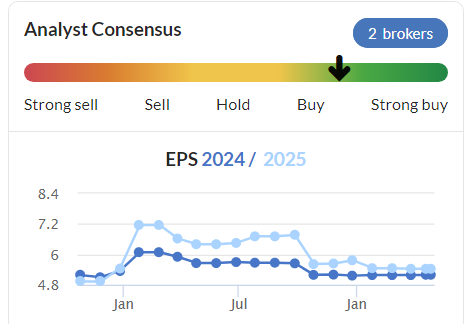
REC is a capital-light, niche business model, that reliably pays out nearly all earnings in divis (8% yield), which is obviously attractive to investors.
I’m going to stick with GREEN, although I’m a little concerned that the positive news on achieving its highest ever AuME has happened alongside falling forecast profitability. Is that telling us that fees are under downward pressure maybe? I recall that some readers might have mentioned that before when we’ve previously discussed REC here, so any reader feedback is welcome.

Brickability (LON:BRCK)
Down 3% to 66.2p (£211m) - Trading Update [in line] - Paul - GREEN
Brickability Group plc (AIM: BRCK), the leading construction materials distributor, provides a trading update for its financial year ended 31 March 2024.
Reassuring -
Full year performance in line with expectations
But depressed conditions continue -
Trading in Q4 was delivered in line with management expectations, and continued to reflect the lower levels of demand in Bricks and associated building products experienced in the first nine months of the year.
Group revenue for the full year is expected to be approximately £594 million, a decrease of c.13% over the prior year (FY23: £681 million) or c.18% lower on a like-for-like ("LFL") basis.
Guidance -
Full year adjusted EBITDA1 is expected to be at least £44.8 million, in line with previous guidance, demonstrating operational resilience with margins consistent with the prior year performance.
What does EBITDA turn into in real money? Isn’t it daft that we have to go to the trouble of finding a broker note, to discover what proper profit is? There’s nothing available, so I’ll have to fall back on the broker consensus numbers on the StockReport -
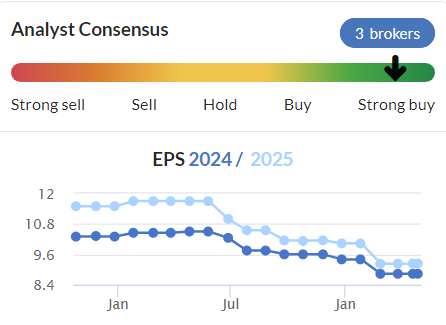
This tells us that the original forecasts about a year ago where somewhat too optimistic, but at least we seem to have found a floor in performance in the last 3 months. Little recovery forecast for FY 3/2025 is also quite encouraging, in that this reassures me expectations are quite grounded, hence any recovery that might begin in late 2024 or early 2025, could be positive for the shares. Risk of another profit warning probably quite modest I’m thinking.
Hence at 66.2p/share, we’re being asked to pay c.7.5x FY 3/2024 earnings, and a slightly lower PER for FY 3/2025. That seems pretty reasonable to me, and this might even become the low point in the earnings cycle. Quite attractive, but buyers/holders at this stage have to take the risk that trading might deteriorate further, if poor macro continues into 2025.
Outlook -
Despite activity levels in the sector remaining subdued, the Board believes that with leading positions across a diverse portfolio offering, the Group enters the new financial year well positioned to benefit materially from a recovery in its end markets.
Balance sheet - it’s done a lot of acquisitions, so this needs careful checking. H1 results showed net bank debt of £30.9m at Sep 2023. That looks fine to me. NAV was £181m, less intangible assets (goodwill, etc) of £149m, and deferred tax of £17m, gives me NTAV (as I calculate it) of £49m. That ‘s fine I think, because note BRCK does a lot of drop-shipping (direct from manufacturer to customer), with BRCK not actually needing to handle or own the inventories during that cycle. Clever! So it only had £34m in inventories at Sep 2023. This is what a relatively light balance sheet actually works fine here, it’s a surprisingly capital-light business model.
Note that debt will have risen somewhat since Sep 2023, due to 2 more recent acquisitions (going well, it says). It says today that leverage is expected to be 1.25x EBITDA at Mar 2024, which is OK I think. Personally I wouldn’t want to see debt go much (if any) higher.
Paul’s opinion - I quite like this, and reckon risk:reward looks quite favourable now, as indeed is I think true for the building supplies sector (if you pick carefully within that). It’s currently seeing soft demand, but that should improve in future. I have no idea when these companies will start reporting the green shoots of recovery, but BRCK is still making pretty decent profits in a depressed market, which I find encouraging, for investors who are prepared to be patient and wait for a recovery.
Downside risk is that things do another lurch down, if demand fails to recover later this year. Although I’d be surprised if that would do lasting damage to the share price, because surely the bad news is already in the price? I like that BRCK is diversifying through acquisitions, so has a wider product range now, not just bricks.
I stuck my neck out and went AMBER/GREEN at 46.5p, when it warned on profits on 11/10/2023, and the price is now up 42% from there without any actual improvement in trading or outlook. This reinforces my view that some of these shares have overshot on the downside, and now present bargain, cyclical upside opportunities.
There was another mild profit warning on 27/2/2024, which only dealt a glancing blow, with the shares down 12% to 67p on the day. Today’s price is almost the same, so this reinforces my impression that the bad news is in the price, and given time, this share looks like it could start rising.
Hence I’ll be bold, and up my view from amber/green to GREEN. After all, we need to get into these things before the green shoots of recovery appear, to bag the full benefit. Caution can mean losing out on a nice initial surge, as people dash to buy on signs of recovery.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

91 comments
Well done to Darktrace (LON:DARK) holders.In there last online meeting hosted on London Stock Exchange (LON:LSEG (first time i've been on one outside of investormeet!), post last update, management came away as very competent imo.Shame they might be leaving as cybersec has massive headwinds, as we increasingly digitalise in all sectors with national and international threats constantly evolving and obviously they have the right product.Thoma Bravo will most probably make out longer term.SentinelOne (NYQ:S) has similar products i think.Currently underwater there especially with the current huge selloff of some megacap favourites and associated indices and US worries about inflation data.But hoping to more than bag longer term if things work out with the company.
Here's the web link for this weekend's podcast. Sorry it's so long, but there's masses of stuff for me to cover!
https://shows.acast.com/paulsc...
Hunt calls Dorneywood summit to boost flagging UK stock market. The chancellor and London Stock Exchange officials will use the May 16 event to court technology companies amid growing concerns about a City exodus, Sky News learns.
https://news.sky.com/story/hun...
Thanks for flagging this, slopsjon.
I've jotted down my initial thoughts on reforms for the UK stock market (GoogleDoc link below), let me know what you think. Maybe I should collate views from SCVR readers, and submit them to Govt?
https://docs.google.com/docume...
Yes Paul. I think it's a great idea for you to forward your ideas on reforms for the UK market to the Government. And I see from your Google document that you have made a good start. I am a member of Sharesoc and will encourage them to do something similar, if they are not already doing it.
Great ideas Paul, and I think you and the likes of Sharesoc, should have some input on behalf of private investors.
Thanks for covering Record (LON:REC) Paul, much appreciated.
Good write-up on Record (LON:REC) by Roland Head.
https://tinyurl.com/yw8cr95j
I like seeing the split of hedging activities, the "dynamic" is almost certainly higher margin but difficult to tell exactly versus the "passive". Feels like the new CEO doesn't like the additional businesses the old CEO (who keeps selling shares) wanted to add. Nice stats on the Record (LON:REC) Stock Report.... net cash, margin and ROCE.
I don't hold but would buy for the yield. No need to rush though.... FY results and hopefully some clarity on future activities in late June, and goes ex div mid July for an August final payout.
Re: Averaging down Argentex (LON:AGFX)
Thanks for all your replies. In the end I decided not to buy more Argentex, perhaps better to wait for some clarity and signs of an uptrend.
Instead, I ended up buying Brickability (LON:BRCK)
Don't. You have to buy the same quantity as you hold to halve your average, hence the expression doubling down. There are many opportunities for your money, pick one that is going up steadily with a rising 200 day average and good value, momentum and quality metrics unless you have super powers which you probably don't.
Darktrace (LON:DARK) Hard to know what to think about this bid. On the one hand as a holder with a fair position I could take the bid, or it may flush out other suitors, and financially I would do well. But really I was planning to have this as a long-term hold. I thought they might do really well over ten years. And, irrationally, I rather liked having someone called Poppy as the CEO.
Wasn't too long ago that I bought Argentex (LON:AGFX) , currently nursing a 21% decline. Any thoughts of what's going on with this company?
Thinking of buying some more to average down the price, or is that a daft idea....
Averaging down = Almost always a bad idea. Averaging down is a way of refusing to admit a poor trade. Cut losses unless you know something the market doesn’t. Be an assassin as they say.
If you are determined to hold on then wait for a bottom to form. You might pay a little more but you will have more certainty.
Are you sure there aren’t better places to put the money?
I have been watching Argentex (LON:AGFX) for a while, l will watch for a while longer, l don't hold. I note Harwood have reduced their stake, maybe they know something, think that is why the shares fell again recently. Believe Harwood have increased their stake in Titon Holdings (LON:TON) . There is also a former director with a large holding who maybe selling.
Averaging down can work, I find it is better on US shares. The more Alphabet (NSQ:GOOG) fell, the more l bought.
UK small caps it is more hit and miss.
Latest fall has been because Harwood reduced their holding a little. They didn't say why. That follows on from the CEO & CFO leaving in short order without any real explanation. CEO was a founder and had a large shareholding. CFO had built up a stake when another founder sold out his holdings a year or two back. So potentially their both reducing their holdings. So all in all there's a real lack of information on what is going on.
I hold and am hanging on for now.
Up to you whether you want to invest more good money in this one or put it somewhere else. There's lots of good shares out there at the moment.
turbo.
I don’t agree with the rather dogmatic definitely don’t average down advice.
There is wise averaging down and unwise averaging down.
Wise is when a quality share (e.g one issuing regular better than expected updates) falls even lower. e.g I averaged down Aviva (LON:AV.) at about 250p in 2020, and Legal & General (LON:LGEN) at 155p. Both are way higher now and the dividend yield at those prices is around 15%.
I sometimes buy half stakes so that I’m “in” if the share has bottomed, but with the intention of averaging down if it hasn’t.
Averaging down mainstream oversold Investment Trusts at much wider discounts than usual and high dividends often works very well.
Unwise averaging down is throwing good money after bad with a failing or iffy share. Why risk more on those ahead of quality that looks way oversold?
So what about Argentex (LON:AGFX)? I don’t follow closely but have just had a quick look at comment from Paul or Graham and a couple of their updates. Does it fall very much in to the unwise averaging down category?
You're in good company Paul. Michael Taylor also likes Tortilla Mexican Grill (LON:MEX) - starts 24:40
&t=620sCeres Power Holdings (LON:CWR) Sudden jump in price..any idea what's afoot?
Oversold?Ceres Power Holdings (LON:CWR) and ITM Power (LON:ITM) are heavily played by shorters under the reporting limit i reckon and both traded on any spikes so far in current market conditions,As they both have massive IP potential imo but green hydrogen is still a way away like EVs were both economically and infrastructure wise.
Brickability (LON:BRCK) I hold
Tend to agree with Paul that the bad news seems to be in the price already. Have no idea when we can expect business to get busier but I think BRCK will be early beneficiaries of any improvement. After all, whether you are building houses or commercial premises or just doing R&M, you need the raw materials before you can begin to do the job and sell what you built or charge the customer.
Shrewd acquisitions that diversify, fill niches and tap in to what demand there is all help.
Dare I say “Bravo” on all the Darktrace (LON:DARK) comments and congrats to any long suffering holders !
Redde Northgate (LON:REDD) Surely "zgp" if they want to keep up with modern trends?
Buying £HL certainly wasn't one of my best decisions and now wondering how much of a potential cost this Woodford investors' claim might be? https://portfolio-adviser.com/...
on Hargreaves Lansdown (LON:HL.)
I hold as well. Nursing a small (6%) loss. from the article.
"To date, RGL’s book has over 7,000 claimants, with an average assessed value of £20,000 per claimant. More and more claimants join the RGL Group every week."
It looks like the case has been fully funded (through burford or equivalent)
Woodford investors join UK lawsuit against Hargreaves Lansdown | Reuters
7k*20k = 140m. Call it about 200m. that is 67% of this years profits. Or the dividend for 2024. Nasty. But still a one off cost of ~40p per share.
from the sep 23 report
"...The Company is aware that the law firm has since filed a claim form with the court against both Link Fund Solutions Limited and Hargreaves Lansdown Asset Management Limited ("HLAM") for an unspecified amount in October 2022. As at the date of issuing these financial statements, the law firm has not yet confirmed that it has secured sufficient funding to progress the claim, HLAM has not been served with the claim form and no timetable has been set for the conduct of any claim.
All such matters are periodically reassessed, with the assistance of external professional advisers where appropriate, to determine the likelihood of the Group incurring a liability. There are inherent uncertainties in the outcome of such matters and it is not practicable to reliably estimate the financial impact if any, on the Group's results or net assets at the period end."
Now HL know the litigation has been funded they will re-assess and if the potential liability is material, will have to disclose
HL is down ~ 20% compared to the FT100 over the last 2 years. Some is competition from AJ Bell etc and some is this litigation.
As with all these things I would expect a settlement (*).
Personally, I intend to follow a policy of "masterful inactivity". On new news I will reassess .
This may run from wishing I had sold today to buying more.
(*) There are many legal hurdles. The one I find most interesting is that HL say all over the site that they do not advise. At the same time they have a "wealth shortlist" or wealth 100.
For any followers of Regional REIT (LON:RGL) you might be interested to know it seems to be breaking out as I type and the chart is also showing some bullish signals. I have taken a punt!
A few suggestions on how to get the best out of the comments on Stocko and how you can help others to find your pearls of wisdom.
To find a post you or someone you remember made, click on the "badge" with your initial or photo and you'll see "activity". Click on this and you'll see posts starting with the latest.
When typing a lengthy post, best to make a copy every so often.
When starting a post, it's helpful to readers if you always start with the @ company even if you are replying to a post, saves time for readers. The "ADD COMMENT" box at the beginning of the comments will start a new thread, using reply to the first post of a thread instead will keep comments on a topic together unless you are specifically addressing one person in which case reply to that person.
If posting a web address, there is a very easy to use way of putting a short link instead, click the chain link symbol on the top row of the box you are typing in or if you are a Radio4 listener, in which you are typing :-) . Similarly when reading a post, there is a chain link symbol which can be copied and posted if you want to refer back to that post. Unfortunately the link only goes to report not the post, so you might want to copy and paste the text instead.
I've recently discovered the time saving benefit of sorting posts by latest and unthreaded when checking later in the day to read new posts. This relies on some adherance to the above by posters otherwise I will skip over posts if I don't see any relevance, I realise using a phone in a hurry is limiting but a post that isn't read is a waste of time.
Thanks
Hello Samsgrandad
Trying to work on this. Followed what you said and my OWN COMMENTS came up. I have made no POSTS to date. You say POSTS made by OTHER contributors can be found in a similar way - can you please expand on this??
Thankyou KBR
You just click on the profile, then go to Activity, you have 7 posts or comments.
With all the Director selling over the last few months, and as recently as March, it is clear that a bid for Darktrace (LON:DARK) must have come as a surprise. Poppy Gustafson and Nicole Eagan both sold significant amounts on March 18th and 19th at 482p and 467p, that’s got to hurt a bit even if you do still have a worthwhile percentage.
It goes to show that even the insiders sometimes don't know the true value of their company! Surprised that they didn't know a bid was in the making back in mid-Mar...
Darktrace (LON:DARK)
Were they planned sales?
Loungers are one of the only ‘chains’ to serve the new Hofmeister, probably the best lager I have ever tasted.
It's a really nice refreshing lager. You can buy it in kegs at hofmeister.co.uk. The brand was brought back in 2016 after two Brits bought it from Heineken....Follow the Bear!
Hofmeister were at Mello in Chiswick last year funnily enough.
It is now a quality beer brewed in Bavaria. No link to the1970s rubbish. Loungers selling it as a premium beer . Follow the Bear
"the new Hofmeister, probably the best lager I have ever tasted."
Ok challenge accepted gotta give that one a go - does it beat a nice plumb porter though ?
Never rmillaree :-) very little beats a good porter…………
very little beats a good porter
Give me an unfiltered hazy craft ale, please. Unfortunately, I’m up in the north of Scotland this fortnight where all they have on tap is big brewery keg rubbish.
If you check out the bottled beers you might find some interesting "heavies" search "scottish heavy beers". Pretty distinctive flavour with a hint of Guiness (but don't let that put you off) from the peat smoked barley malt. Years since a local William Lowe Scottish supermarket was taken over by Tesco and they had a terrific range. It would be rude not to try some while you're there.
Yes Tesco bought Willie Lowes after they opened a flash new store as far south as Loughborough!
Could be worse…..you might have just got off a flight where they served you a can of some cheap lager and no food!!! Only direct flight alas….oh well……
Plum Porter
Here are your market expectations for Loungers (LON:LGRS) Paul.
We've gone with a valuation of 370p, based on 8.0x our new cal 2025 EV/Adj. EBITDA. Brightside is a side note. The majority of new sites are Lounges, and their all day offering gives great utilisation of sites.
https://www.equitydevelopment....
The old classic valuation “adjusted EBITDA”
Isn’t there a well known saying about “replacing EBITDA with bullshit earnings”
I’m sure a much better investor than all of us on here said that ..
I'm surprised someone on here and in videos use EBITDA all the time.
Charlie Munger said that about ENITDA
It is perhaps instructive to note where the EBITDA enthusiasm came from. In the heady days of Leveraged Buy Outs in the US in the 80s, I think Joel Stern and Bennett Stewart were among those who promoted the view of how to view company value.
The target was the ability to find companies that could support a high level of debt in a private company. The potential debt load was the variable so it was irrelevant to consider current debt, the amortisation had no cash effect so tended to disguise the cash flow potential for paying the new debt, and the long term need for new capex purchases would be reviewed anew in the new company structure. The tax was likely to be minimized by the debt taken on, so EBITDA became the quick look thumbnail guide to potential targets.
None of this is remotely relevant to long term investment valuation, but it was never intended to be, unless it is being measured against potential private buyout opportunities. EBITDA can be a useful tool, but it is seriously misused.
Facilities by ADF (LON:ADF) results today highlight an issue with the UK market whereby companies often dont issue guidance directly to investors, but instead seem to do it through brokers/analysts. RNS released at 7am, broker forecast update released later.
This creates at best an inefficient market, potentially subject to abuse.
In Facilities by ADF (LON:ADF) case FY24 forecasts effectively pushed back to FY25 - a material FY24 miss versus broker forecast of £3.1m (£8.1m to £5.0m) at adjusted PBT level.
Not to worry, despite the H2FY24 expected to only return to H1FY23 levels and H1FY24 still recovering from the writer/actor strike of H2FY23, £5.0m adj PBT for FY24 is still a multiple of FY23 adj PBT of £0.9m.
In summary, getting back on track after the strike but slower than expected, but why cant management or even the broker state this directly?
Also, they seem to have scrapped the final dividend without actually mentioning that in the announcement
Are you sure? Cavendish and Stocko reduced their forecasts for Facilities by ADF (LON:ADF) to £5.0mm at the time of the February trading statement. Cavendish have reiterated that forecast today so no change.
My Stocko still showing £7.5m after tax for 2024
Ah, it looks like the database Stocko uses only lowered the EPS figure and didn't move the PAT. Forecasts were lowered to 5.0mm PBT and 5.8p EPS in February and have been reiterated today.
The same for Sharepad.
Facilities by ADF (LON:ADF)
This is a good example example of why companies use EBITDA or the word adjusted. The size of depreciation and interest is very material in this case if I'm not mistaken but I'm an engineer not an accountant. Sorry to rain on anyone's parade but I'm glad that I sold a while ago.
Cuddlesticks
FacilitiesbyADF (I hold)
The answer to your question is that the company employs a PR agency to give management guidance as to how best to present to shareholders. This inevitably means putting a favourable gloss on the results and, as SheriffJEB states below, ignoring the fact that no final dividend will be paid. To be fair to the company, the annual earnings are 0.99p, so covering the interim dividend of 0.5p and I suspect that it wants to have at least 2x dividend cover. Nevertheless, it would have been helpful to mention this.
Looking at the Cavendish forecasts over this year and next, earnings per share are forecast to rebound strongly to 5.8p and 8.8p from which the company is then forecast to pay an annual dividend of 1.6p and 2.3p respectively. At the current price of 52p, this implies a prospective PER of 9 and yield of 3% for this year followed by a PER of 6 and yield of 4.4% in 2025.
There is an Investor Meet presentation for the company on 30th April at 1030, where investors will get an opportunity to listen to management and ask questions. Occasionally I find that ‘awkward’ questions are avoided, so sending an email directly to the PR company does elicit a response albeit that replies can be anodyne.
Kind regards
Phillip
That is why PI World is better than Investor Meets Company, Tamzin choses the questions to be answered not the company.
Loungers (LON:LGRS) (I hold). One of the founders commented the other day that he was disappointed at the low rating of the shares-they have risen a bit since. Founded in 2002 I would not be surprised to see a takeover for the business. Alex Reilly and Jake Bishop still have holdings of just over 6% each. Largest holder is Lion Capital a PE firm with 25.76%. Been too a few Lounges over the years and will be going to a Cosy Club in September for an evening before my daughters wedding in Bristol. They deliver what they say they offer. Not been to a Brightside yet as not passed one of the two.
MPAC (LON:MPAC) Positive news for MPAC as it wins a GBP1.2 m order to deliver a solid state battery assembly line. Funding from the Automotive Transformation Fund, partnered with ilika, Agratas and the UK Battery Industrialisation Centre.
Agratas is a new name as far as I can see that is now associated with MPAC's drive into the clean energy sector. Agratas is part of the Tata motor group.
MPAC (LON:MPAC) this deal is a good demonstration of how innovative deals such as the FREYR automation generates a reference point and market leader status for complex processes that subsequently generates new and diversified orders. I think MPAC (LON:MPAC) has a good long term future.
Any thoughts on a possible counter offer? Or consider selling now (or when it edges up a bit closer towards 620p).
Decided to sell half my holding at 620p, see what transpires
Darktrace (LON:DARK) (I hold), Thoma Bravo had made a bid back in Aug 2022 I believe for a higher amount but they couldnt reach an agreement. My guess is now Mike Lynch has sold down his stake it makes it more palatable to other potential US bidders, hopefully.
Darktrace (LON:DARK) . The bid price is below what the equivalent value would be on NASDAQ. Sad to think that the company is likely to be bought and then refloated in the US. I am holding on for a higher price.
Darktrace (LON:DARK) Just been bid $7.75 about £6.20
Not a huge premium (c.20%) but they are up almost 40% since the start of March
Happy Friday all
I would appreciate your thoughts on Record (LON:REC) as I’ve been having a closer look at it this week
Record AUM & yet shares are close to 52 week lows. Partly explained by being in the unloved sectors of funds & currency. Looks to be having a change of strategy under the new CEO who’s closed their tech business (& subsequent departure of the CTO & her share sale)
Dividend yield, if maintained, is fantastic.
Record AUM & yet shares are close to 52 week lows. Partly explained by being in the unloved sectors of funds & currency. Looks to be having a change of strategy under the new CEO who’s closed their tech business (& subsequent departure of the CTO & her share sale)
Well, on Grahams AUM to Market Cap metric for fund managers it looks cheap. Did he not say Jupiter Fund Management (LON:JUP) was cheap on a ratio of ~120 recently? For Record (LON:REC) the ratio is well over 600 ie. £80bn of AUM on a £130m market cap.
Care needed with Record's AUME, the E standing for equivalent, indicating that they do not manage (invest for a fee) those assets. It is the value of the funds for which they provide currency management services (at a much lower fee to value ratio)
I also look forward to Paul's views on Record (LON:REC). The bull case is that they have a highly profitable and cash generative niche business which, after years of stagnation, has resumed growth either because the eponymous founder, executive chairman and controlling shareholder took a back seat in recent years, reinvigorating a young talented team underneath to pursue new business and products or because the end of years of ultra low interest rates has come to an end, bringing back currency volatility and increasing demand for their products. The bear case is that their first mover advantage in currency management strategies for institutional investors has been and will continue to be eroded, they are too small to effectively compete with much bigger players including the banks either in their core business or in any related areas they try to move into and there are already signs that the new and relatively inexperienced management team may not be as talented as was thought (as evidenced by delays to new product launches and large (for this small company) write off of recently capitalised technology spend (hence departure of CTO).
Faites vos jeux! (I hold)
Record (LON:REC) - yes nice to see a very solid trading update following the IT write-off. Lets see what Paul thinks, but I particularly like this comment and the 2 new fund launches.
"Building on our existing proposition and the demand we observe for our services as a specialist asset manager, we are now refining our product range to focus on a select number of best-in-class products which present attractive and meaningful opportunities for us, making Record a stronger, less concentrated, and more robust business."
I think it means they are focusing on fewer better opportunities, whereas I think the previous CEO maybe had a few too many new projects on the go at the point of leaving. Anyway, strong growth in "AUM" means next year is set up very nicely. Always the possibility that their very profitable currency for return segment may take off again at some point as well.
Brickability (LON:BRCK)
Steady as she goes. The brick market remains challenging, but the shares are cheap and the company not financially stressed. It will be a beneficiary when interest rates come down and the housing market recovers as both will. Its recent sizeable acquisitions of two specialist cladding companies should benefit from the substantial amount of remediation required to address fire safety issues post Grenfell and regulated under the Building Safety Act 2022.
It will be interesting to see how the new CEO, Frank Hanna, who has just arrived from Michelmersh Brick Holdings (LON:MBH) shapes the business going forward.
Happy to be invested.
Was at construction industry event yesterday in London, and the feeling in the room was split. Half think we will see a recovery in H2 , the other half believe it’s going to be 25 post general election. That’s obviously a physical recovery, from a forward looking market we should start to see a further recovery in construction shares later this year as companies guide 2025 earnings over and above current forecasts.
Wilmington (LON:WIL)
"has sold its French healthcare business, APM, for an enterprise value of €26 million in cash, subject to customary working capital adjustments, to Philia Medical Editions SAS, a subsidiary of Europa Group.
For the year ended 30 June 2023, APM had gross assets of €9.6 million and reported a profit before tax of €2.3 million. The proceeds of the sale will be used for general corporate purposes."
Redde Northgate is proposing to change its name to ZIGUP plc.
" The Board believes that a more modern brand and name reflecting these changes will also help shift the narrative with all our stakeholders towards the strategic direction of travel we set out. This is aligned to our updated purpose, 'to keep customers moving, smarter'."
I wonder how much they paid PR people to come up with this daft name?
Richard
Redde Northgate (LON:REDD) . Totally agree, is this the first sign of a company going off the rails again?
Its holding firm this morning but certainly selling was one of the first things I thought of. Been a good performer for me and pays a good dividend but will be keeping a much close eye on it.
Re Redde Northgate (LON:REDD) I wonder if this is a sign of boredom in the boardroom (or boredroom?). It's quite a boring share, not been doing much for a while, pays nice dividends. They mooted the idea of bidding for Halford's a while ago, but that has gone very quiet. So. not much going on, let's rebrand for a bit of excitement.
I'm in a quandry about this one - could sit tight and just take the income, but against some of the gains elsewhere I do wonder whether the money would be better in other places. Results not due until July - will there be a trading update before then?
[edit - looks like there was a trading update in May last year, so might not need to wait until the summer.]
Dave
Redde Northgate (LON:REDD) I've just read the RNS, which wasn't easy, and decided a better name for the company would be DRIVEL plc.
What is wrong with these people?
Very clever Peter, if it were not for ZIGUP I'd not be chuckling at your creative use of the King's English, so not all is lost, we still have your sense of humour...
Yes but ZIGUP scores better at scrabble than DRIVEL
My position before today was that the company is undervalued based on the Key Metrics and that at some point something will happen to wake it up. There was a rumour about a year ago that they could be a takeover target themselves at some point given their SP against results. As you say the Halfords thing was a sign that they clearly have bigger ideas and I hope they don't overpay for something.
Have held this from 180p 3.5Years ago so with the dividends its given me a 160% return whilst yielding 16% now on my initial investment so it would be a wrench for me to sell this one. I will wait for the trading update
Sell on the first sign of rebranding!
At least there are still vowels in the name.
Unlike a certain Scottish financial institution.
( I hold and in a sector where what need to do is not **** up, seeing random letters chosen from the alphabet that may be self referential is worryingly american)
At least they left a couple of vowels in there. Does sounds like it could be the name of a puppet on a children's TV show
or a spice girl's dream !
Well let's assume Redde Northgate (LON:REDD) management know what they're doing, the question is what value the change adds, there's clearly expenditure involved in design and implementation, so what return are they expecting on the investment? We might muse that they decided the answer to that question is 'sod all' as the name won't be used for existing operational brands, so this is a corporate level change (currently) and maybe group-think justifies the costs through the also mentioned management reorganisation perhaps generating savings.
I was also amused that a 514 word RNS didn't actually explain how all the strategic logic of a change ends up with ZIGUP, (I'd think ZIGZAG better sums up modern driving but maybe it was already taken). It's the sort of name you'd expect for an eco brand or an EV charger and the the video here points in the direction of EV and environmental concerns. The new logo even looks a bit like the Polestar EV badge. The current Redde Northgate brand logo is appalling.
[I hold]
Hertz are dumping their EVs so if Reddee thinks that’s the future of vans then perhaps need to talk to Amazon.
Redde Northgate (LON:REDD) I have some sypathy with the desire for the name change, since adding Northgate it's become a bit of a mouthful. But Zigup? In capitals? Or they could have just changed the names of their various operations?
At least they didn't go for Rdd Nrthgt.
A red flag, management have taken their eye off the (operational) ball.
Tracsis (LON:TRCS) H1 results webinar by management today 26/4/24, 1pm. Lots going on with the railways, so it will be interesting to hear their views. Register here. (Results were out earlier this week, H2 weighted, pipeline strong.)