Small Cap Value Report (Fri 26 Aug 2022) - MCRO, HDT, ALU, TRCS

Good morning! It's just Paul here today, as it's Friday (usually quieter). I'll sign off for today, and the week, so today's report is now finished.
Have a lovely weekend, and if you fancy it, do tune in for my next podcast summary of the week, on QualitySmallCaps - it should be up by Sat lunchtime.
Agenda -
Everything is written by Paul today, with it being Friday.
Main sections:
Alumasc (LON:ALU) - announces a disposal of its loss-making Levolux subsidiary, which gets its £2m loss off the books and into discontinued operations for FY 6/2022, which is handy! I have a ponder about cyclical businesses, and conclude that we don't know what happens next at this stage.
Tracsis (LON:TRCS) - I circle back to its positive year-end trading update issued this Weds. It's not cheap, but I think Tracsis looks on a roll, with positive forward-looking commentary. Thumbs up from me, although it's not cheap, but the premium rating looks justified.
Short sections (no further detail):
Micro Focus International (LON:MCRO) [no section below] - not a small cap but… a recommended cash takeover bid has been announced for Micro Focus, at 532p per share. The bidder is a large Canadian software group called OpenText. What is so noteworthy about this, is the bid premium - a whopping 98% above last night’s closing price for MCRO shares! This is the second big premium bid from Canada recently, following on from RPS (LON:RPS) which received a bid at a premium of 76% from Canada’s WSP - a larger consulting group.
I looked at MCRO here in June, concluding that it’s clearly financially distressed, with one of the worst balance sheets I’ve ever seen, including a $3.65bn net debt pile, that it was struggling to reduce. Although as noted in that report, software companies can often attract surprisingly high takeover bids, as we saw with EMIS, and smaller Proactis & Tungsten. Here’s another one, where a bidder obviously sees considerable value in the business, and seems happy to take on its gargantuan debt.
Software does seem to be an active sector right now, and it seems the worse the finances, the better chance of a takeover bid! On that basis, maybe WANdisco (LON:WAND) is the next one to be bid for?!
Holders Technology (LON:HDT) (89p - £4m) [no section below] - too small to cover here, but I’ve just read the interim accounts, so might as well jot down some quick notes. H1 revenues down 40% to £3.45m. H1 loss of £(226)k vs £104k profit H1 LY. Disposed of low margin business in 2021. Positive outlook comments for H2. Strong balance sheet, with £3.9m net current assets (including £2.5m cash). Pays divis, including a small special divi. De-listing risk must be high, as I cannot see any reason why something this small would waste money on listing costs, but it’s been listed for over 20 years! Dominant shareholder with 44%.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section:
Alumasc (LON:ALU)
132p (down 3% at 08:53)
Market cap £48m
This announcement also includes a brief trading update, so why didn’t they include that in the title? Schoolboy error.
Trading update -
Alumasc expects to announce results in line with the Board's expectations for the year ended 30 June 2022 on 6 September 2022 and can confirm that trading in the core activities of the Group during the second half of the year was strong. The activities of Levolux will be shown as discontinued in the 2022 results.
Disposal - of Levolux. This looks a sensible disposal, as performance at this subsidiary company has deteriorated badly. Looking at companies house (co.no. 1834176), it made revenues of £12.7m in FY 6/2021, and £15.9m in FY 6/2020.
Today’s announcement says that Levolux fell to £7.8m revenues in FY 6/2022, incurring a £(2.0)m loss. Therefore it’s a significant problem now, with uncertainty over recovery (Alumasc was making upbeat sounds about Levolux being "well placed to recover", after making a £(1.0)m H1 loss, as reported in the group interim results to Dec 2021, published in Feb 2022, so things have clearly not improved for Levolux since, despite cost-cutting).
It’s being given away for £1 to an investor called Rcapital Partners. There’s another £1m receivable if Rcapital sells it on for a profit of over £1m. That’s unusual.
Alumasc will book a £14.9m impairment charge, mostly (£11.1m) intangible assets like goodwill. Tangible assets of £3.8m are being given away as part of the deal, including £1.4m cash - so really Rcapital is being paid to take Levolux away.
However, this neatly gets Levolux’s £2.0m loss for FY 6/2022 off Alumasc’s figures, as it will be separately disclosed as a discontinued activity, and investors tend to ignore that, valuing the business on continuing activities only. So I can see why they’ve done this, to clean up the numbers, and get rid of a problem subsidiary that’s losing money.
Levolux was acquired in May 2007.
My opinion - it’s not clear from Finncap’s note this morning if the elimination of Levolux’s £2m loss for FY 6/2022 was baked into the current forecasts or not? Although this bit below leads me to imagine that maybe the numbers have not yet been adjusted, so there could be upside on continuing operations forecasts perhaps?
We will adjust numbers for the disposal at the group’s forthcoming results on 6 September. [Paul: Finncap note today, many thanks for that]
Currently Finncap is saying £10.8m of adj PBT, on revenues of £97.0m for FY 6/2022. That’s 23.6p EPS, so the PER is only 5.6, which seems very cheap.
However, as we all know, if we’re going into a recession, or economic depression, then profits in cyclical sectors can quickly disappear. So maybe PER isn’t a safe way to value companies at the moment?
It all depends on what Govts do. Look at the pandemic - it looked as if everything was going to collapse, then Govts introduced such huge stimulus and support measures, many companies saw profits soar, and stock markets quickly recovered the losses. Maybe the same sort of thing might happen again?
Hence how we’re valuing all shares, is fundamentally down to your opinion on what actions Govts take to prevent an economic meltdown this time.
All I can do, is look at the finances, and report whether it looks soundly financed or not, then leave it up to you to decide if you like the shares or not. I do think it’s a great idea to be doing the research, and making a list of potential bargains, then pull the trigger whenever you’re happy to do so. Rallies can happen very fast. Whether they stick or not though, who knows?
Alumasc’s last balance sheet looks adequate, with c.£16m NTAV. There was some net debt, of £4.1m at end Dec 2021. Also note the pension deficit is small in accounting terms, but is sucking in a fair bit of cash (£1.3m of deficit repair payments were paid just in H1). Who knows what the combination of much higher inflation, higher bond yields, and lower asset values might do to pension deficits? So there’s potential uncertainty there.
Overall, this share might turn out to be cheap, if economies bounce back once we’re through this energy crisis. My hunch is that it might be too early to anticipate recovery in building products, before the expected big downturn has even happened. But as always, nobody knows how the future will pan out.
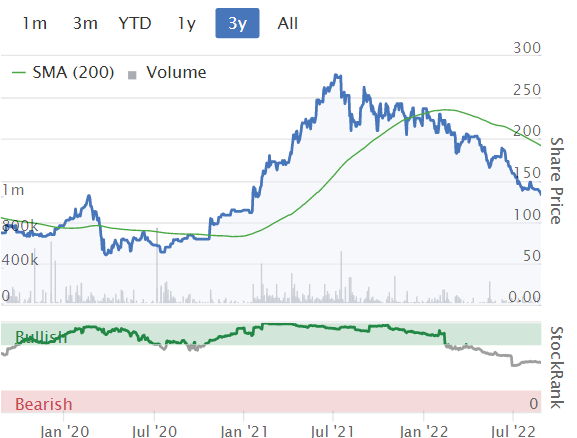
I find it's quite useful to see what level shares bottomed at during the early part of the pandemic. That might give an idea of what level investors found the value irresistible. Although plenty has changed since then, so the individual share's circumstances would also need to be taken into account. It's not easy this shares stuff, is it?!
.
Tracsis (LON:TRCS)
1032p
Market cap £306m
This was published on Weds, but slipped through the net here, so let’s circle back to it, in the absence of anything more interesting today.
Tracsis, a leading provider of software, hardware, data analytics/GIS and services for the rail, traffic data and wider transport industries, is pleased to provide the following trading update for the year ended 31 July 2022.
Key points -
“The Group expects adjusted EBITDA to be ahead of market expectations.”
FY 7/2022 revenues £69.0m (up 37% on LY [last year]) - organic & from acquisitions (no breakdown provided).
Cash of £17.2m (but there is £8.2m of deferred consideration to pay, per Finncap's note today)
Rail division - trading well, high recurring revenues, “fast-growing user base”, “large pipeline of multi-year opportunities”, won US contracts - that all sounds excellent, I like this a lot.
Other division - also doing well, revenues ahead of expectations, driven by post-pandemic recovery in events/travel.
Diary date - 9 November, for FY 7/2022 results. PIWorld results webinar at 13:00 on 11 November - registration here.
Valuation - thanks to Finncap for an update note. It has 34.5p adj EPS for FY 7/2022, rising to 41.1p for FY 7/2023. Given how upbeat the commentary is, and I see Tracsis as a reliable company (that has a track record of being straightforward with its outlook comments), then I think we can probably rely on the 41.1p EPS forecast as being credible.
That would put it on a PER of 25 times - which looks fully priced I’d say.
Balance sheet - looks OK to me. Last reported end Jan 2022, NAV is mainly intangibles (from goodwill on acquisitions), but NTAV remains positive, at £5.8m. We could probably safely eliminate the £8.4m deferred tax creditor too, which would raise adj NTAV nicely to £14.2m. Overall, it's fine nothing to worry about here, given that this is a decently cash generative, recurring revenues type of business.
My opinion - I think Tracsis deserves a premium rating. It’s managing to do that lovely thing - making acquisitions without increasing the share count or getting into excessive debt.
The share count has remained roughly constant at c.29m for the last 6 years.
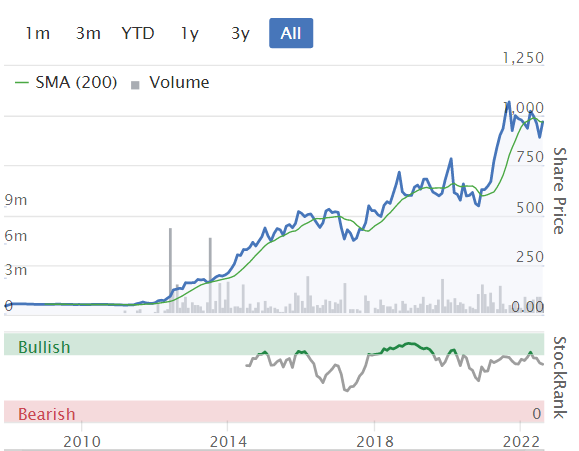
Probably the only drawback, is that historically valuation sometimes got ahead of reality a bit, and it then went sideways for long periods, testing the patience of shareholders.
As something to just tuck away and forget you own it, I suspect the outcome long-term would probably be pretty good. That’s based on its track record to date, and what seems to me a very good update this week. Sounds like there’s more growth to come. Thumbs up from me.
Terrific long-term track record of value creation. Also note TRCS has been a safe enclave during this vicious small caps bear market in the last year.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

18 comments
Tracsis is not expensive. The group's R&D costs go straight through the income statement unlike nearly all their software peers who capitalise the majority of these costs. This makes a huge difference to the profit line of a growing business.
This coupled with the recurring nature of a significant portion of their revenues, the large amount of net cash on the balance sheet and multiple organic short and long term opportunities on the horizon make it a must hold AIM stock.
I hold.
Hi Paul,
Hope you're keeping well! I'm a relatively new subscriber (approx. two years) and have just started to use the comment function ;) Not related to news today but I wondered if you know whether Saga (LON:SAGA) (I hold) have any tax losses to bring forward i.e. to put against future profits?
Thanks for all the great write ups and podcasts. It's been a very difficult year in the markets up to now but really appreciate your writing and recording style and of course the content which I find informative and light hearted and make for very easy reading/listening.
Thanks again and best wishes,
Michael
Hello Michael! (Daddahm), welcome to the comments section!
I'm a generalist, not a tax expert. Bearing that in mind, with Saga (LON:SAGA) (I hold) it has historically been highly profitable, over many years, so I very much doubt there would be any historic tax losses brought forward, other than what might have happened in the pandemic.
As you asked so nicely, and it's out of office hours, I've checked the FY 1/2022 Annual Report here. and note 10 covers corporation tax.
There's this reconciliation from the loss before tax in both years FY 1/2022, and FY 1/2021, which seems to have resulted in a positive tax charge in both years, despite losses before tax, with the main culprits being tax disallowed write-off of goodwill, and something I've never seen before re the cruise business "entering tonnage tax regime". Hence there was an overall positive tax charge, despite losses before tax.
I've had a quick look at the balance sheet, and can't see any tax losses brought forward. But it's a large, and quite complicated balance sheet.
So the honest answer is, I'm not sure, but think there probably aren't any significant tax losses. But you would need to check that out more carefully for yourself.
Regards, Paul.
What a focused, thoughtful and balanced response! This epitomises what we all appreciate about your analysis, Paul, thank you every time.
Oh how kind thanks Westway, one tries ones best ;-)
Many thanks for your reply Paul which I've just seen! I'm not sure how/if the comments can be followed. I've just noticed the chain icon so maybe that's how ;)
I remembered you were a shareholder (and note you still are) so thought it might be an issue that had been covered previously. Really appreciate you taking time to look into this further and respond. I'd had a look through quite a lot of info & data but hadn't found any tax losses being brought forward either (whether from prior to the pandemic or during). As you mention though it is a large and quite complicated balance sheet!
Thanks again and all the best,
Michael
Thanks Paul for the commentary on Tracsis (LON:TRCS) (I hold)
Very much positioned as consultancy/software business, though I suppose the events side of things has a more basic element of providing marhsalls for traffic organisation/co-ordination. However, even there they can layer detailed local traffic flow analysis, which must aide getting local Govt permissions etc. Clearly that side of the business suffered during the pandemic lockdowns, but is bouncing back quite strongly now, helped by the warm weather, no doubt.
The shares have always been fairly illiquid, and this has a part to play in supporting the price. The founding CEO and Finance Director, now moved on, seem to have held onto their original option holding. They set the initial conservative tone on structuring acquisitions, with low dilution, which sensible follow on management have continued. As a cash generative business (particularly from the Railway divisions) they have been able to cross-invest for some diversification.
I guess they see the future as an integrated traffic and people movement analytics business to assist in Town/City and infrastructure planning, as well as offering safety/productivity monitoring software for mass transportation systems.
I suspect there aren't too many joined up businesses in this area, but they remain still relatively small. I could imagine one of the larger consultancies seeing value in this area at some point, but with few other operators, it is probably still below the radar for many.
They do provide a small dividend, which is probably not likely to excite many, but as Paul has said they have been, so far, a relatively safe haven for investors in buffeting times.
There seem to be no new comments in the last four hours?
Surely not.
Carrying on Paul's theme of software company takeovers. Darktrace (LON:DARK) has a market cap is £3.5b but on 15/8/22 it announced that it is in the early stages of discussions with Thoma Bravo, L.P. ("Thoma Bravo") regarding a possible cash offer for the entire issued and to be issued share capital of the Company. Given the news regarding premium offered for Micro Focus International (LON:MCRO) there may be good crossover news regarding the bid for Darktrace (LON:DARK) despite the early stage and lack of bid yet.
Safestyle UK (LON:SFE) Safestyle - any views on today's news of a delayed presentation?
Bank loan and credit facility both expire Oct 23. Currently rate is LIBOR plus 7% (slightly less for undrawn element of credit facility). 2021 borrowing interest cost was £0.6m, so appears relatively modest with regard to profits. Question is the impact, if any, of the cost of living crisis on sales of replacment doors and windows. Increase in future borrowing rate and decline in sales would be a double whammy hit to profitability.
Re: Steve Holdsworth
I posted yesterday about his recent death. If anyone here is on Twitter, there will be a virtual 'homage' to Steve tomorrow (Saturday) where you post a picture of a pint of beer (as he did every Saturday) at 10am with the hashtag #pintofhope. There's also a nice piece from ShareSoc here https://www.sharesoc.org/blog/...
cheers
Francis
"Software does seem to be an active sector right now"
MAYBE be some juice left in AVEVA (LON:AVV), strategic bidder that owns 60% already: Investegate |Schneider Elec. SE Announcements | Schneider Elec. SE: Response to press speculation
Bonhill , Used to have some good shareholders like Gresham but seem to have lost that support looks a bit of a dead duck ?
You should be able to edit your post at least up to 15 minutes after you posted - please correct the typos, get the link working and remove the frivolous and distracting graphic.
you can for up to 59 minutes normally is an edit button bottom right on your post
ps - typos are down to dyslexia so thanks for your feedback, much appreciated .