Small Cap Value Report (Fri 26 Jan 2024) - TET, SYS1, PPH, ZOO

Good morning from Paul!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Paul’s Section:
Treatt (LON:TET) - down 3% to 480p (£293m) - Trading Update (AGM) - Paul - COLOUR
Treatt, the manufacturer and supplier of a diverse and sustainable portfolio of natural extracts and ingredients for the beverage, flavour and fragrance industries, provides the following update on trading for the three month period to 31 December 2023 ("Q1")
This financial year is FY 9/2024.
Q1 revenues is down on last year, “as anticipated”, due to (customer) destocking.
Demand expected to normalise in Q2.
Pipeline “healthy”
Cash generation & debt reduction on track, as expected.
Outlook - is this in line or not? Why didn’t they say either way?
Whilst we are mindful of ongoing macroeconomic pressures, we are encouraged by current trading, underpinning our confidence in our trading performance for the year ahead.
Paul’s opinion - I don’t like this announcement. It’s devoid of any figures, and the fact that they don’t directly say whether trading is in line or not, but use an alternative more vague form of words, raises more questions than it answers. Particularly since Q1 was weak, and they’re hoping to catch up in Q2.
This sounds to me as if the risk of a profit warning just increased.
Not good news for a share that’s rated at 19.9x forward earnings.
The big new factory was supposed to increase production & margins, so Q1 being down on last year for revenues is all the more perplexing to me.
I can’t see any broker updates, so overall I’m left slightly uneasy by this vague update.
For that reason, I’m shifting down slightly from green to AMBER/GREEN.
PPHE Hotel (LON:PPH) - up 3% to 1225p (£521m) - Trading Update - Paul - AMBER/GREEN
PPHE Hotel Group, the international hospitality real estate group which develops, owns and operates hotels and resorts, announces a trading update for the year ended 31 December 2023.
FY23 revenue and EBITDA above previously upgraded expectations
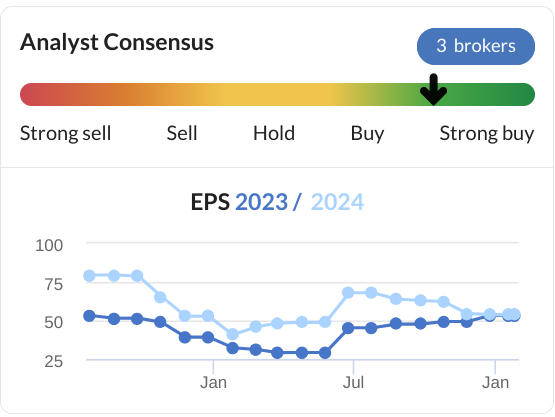
See the wide range of EPS forecasts in recent times - for 2023 and 2024, ranging from 25p to 75p, and currently around 53p for both years -
The commentary sounds upbeat -
Fully recovered to pre-pandemic levels (of what? EPS has not matched 80-90p of 2018-2019).
“Extensive development pipeline” of £300m will begin to produce results in 2024, >£25m incremental EBITDA.
Positive “trading momentum”
“we enter 2024 optimistic for a further strong year for the Group."
Only marginal increase in property values.
Guidance for 2023 guided up -
FY 2023 results are expected to be above expectations with revenue of at least £413.0 million (previously £400.0 million) and EBITDA of at least £127.0 million (previously £120.0 million).
Broker notes - nothing available. So I need to work out myself, using previous accounts, how EBITDA turns into actual profit (after large depreciation charges).
In H1 (to June 2023) it did £45m EBITDA, which became only £3.6m in “normalised” PBT.
Clearly it has a big H2 weighting to profits, as the £127m+ FY 12/2023 EBITDA guidance today implies c.£82m in H2 (vs £45m in H1). Assuming everything else remains the same, then I make that adj PBT of c.£40m in H2, giving c.£44m PBT for FY 12/2023.
Taking off say 23% tax, that gives me earnings of £34m PAT, usefully above the £25.5m PAT (“Net Profit”) shown as broker consensus on the StockReport.
Divide my PAT figure of £34m by 42.4m shares (little changed for the last 6 years), I arrive at 80p/share EPS, which is a long way above broker consensus of c.53p.
Maybe my figures are not right, but it does at least show how highly leveraged profits at PPHE are to occupancy, room rates, etc. This is because the company has a high level of bank borrowings, the finance cost of which consumed most of the operating profit in the slower H1 period.
So checking out the terms (cost, variability, covenants, etc) of the bank borrowings is crucial research here.
Asset backing? Stockopedia shows the price to NTAV of 1.72, so fairly decent net asset backing, but earnings & cashflows are key drivers of the share price I’d say.
Paul’s opinion - it’s ahead of expectations, with EBITDA guidance raised from £120m to >£127m, which is obviously good.
Outlook comments are vaguely positive.
It would need a lot more research to properly understand the company and its prospects, and it has some added complications from historic deals to sell hotel rooms, which I’ve not looked into today.
We warmed to PPHE last year, moving up from amber to green. I’m leaning towards viewing this positively too, as the big operational gearing could see profits considerably improve as the effects of the lockdowns continue to wear off. As Whitbread (LON:WTB) says, there’s also a structural under-supply of branded hotels, with a lot of independent operators having shut down and properties turned to alternative uses in recent years. Hence I think hotels are a good place to look for investors at present, maybe. That depends on your macro outlook (my view is quite positive). If you’re negative on macro, then the operational gearing in this sector (big fixed costs) would obviously make it something to avoid.
Interest rates are also key, but that depends on what hedging or fixes PPHE might have in place, I’ve not looked into that here.
I’ll go AMBER/GREEN overall.
System1 (LON:SYS1) - up 2% to 370p (£47m) - Trading update [ahead] - Paul - COLOUR
System1, the marketing decision-making platform www.system1group.com today issues an update on trading for the quarter ended 31 December 2023 (Q3).
Increase in Full Year Guidance
It splits out revenue growth to highlight the main business (“platform”) is delivering excellent growth of 46% in Q3 and 44% YTD. This is blunted somewhat to 28% YTD (still very good!) by declining revenues from consultancy.
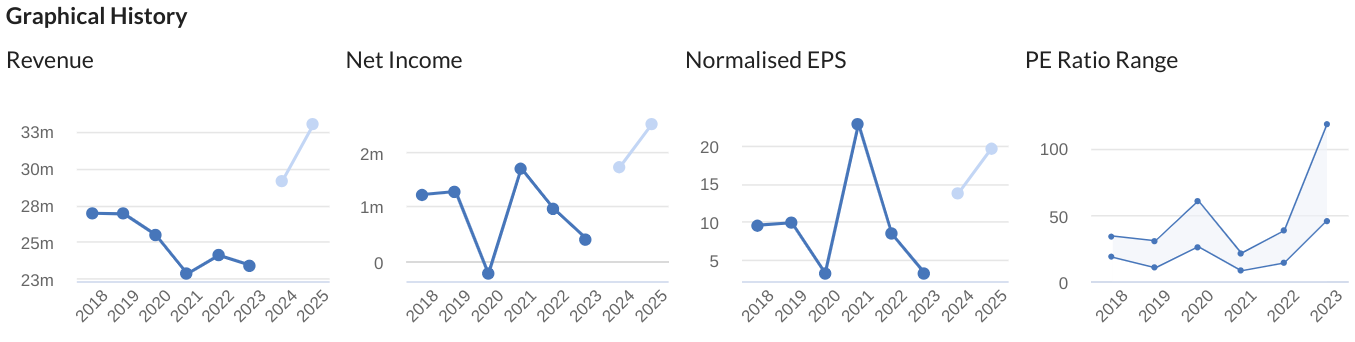
If Q4 is similar to Q3, then it’s heading for c.£30m revenues for FY 3/2024. Good going, but SYS1 has done £24-26m pa revenues over the last 6 years, so it’s good but not a step change overall.
Cash is £6.4m, and we’ve commented in the past how we like the cash position.
I’ve checked the last balance sheet, and it’s healthy, with c.£8m NTAV, mostly cash - because it’s a capital-light business model, using know-how rather than plant & equipment.
Impressive client wins -
System1 won over 60 new clients in Q3, and over 200 new clients in FY24 Q1 - Q3. These new clients include Pfizer, M&S, Tesco, easyJet, Toyota, Muller, B&Q, and Just Eat.
Outlook - sounds good to me, if this momentum can be maintained (performance has been patchy at times in the past) -
The Group enters the final quarter of the year with good trading momentum following a consistently strong December quarter. As a consequence, the Board believes that the Group is now well placed to deliver results ahead of previous expectations. Revenue for the current financial year is expected to be at least £29 million (FY23: £23.4 m) and statutory profit before tax to be comfortably above £2 million and materially ahead of current consensus (FY23: £0.7m).
Brokers - any updates? Yes, thanks to Canaccord. It ups forecast EPS to 13.7p (FY 3/2024) amd 19.6p (FY 3/2025). Those are already on the StockReport, and turn into PERs of 26.3x and 18.4x, pricey but I can see why, given that SYS1 seems to have achieved considerable earnings momentum in recent months.
This is how those forecasts look in historical context -
Paul’s opinion - I’m sorry we were too cautious on this one. Checking our previous notes, we stayed amber despite the company making positive noises on 2/8/2023, then ahead of exps on 27/9/2023, although Graham was warming to it by 6/12/2023 Interim results, suggesting it was worth taking another look, at 218p. Amazingly, it’s soared 70% since then, so well done to anyone who took the plunge.
Have we missed the boat now? I don’t know, it depends if the company can keep this strong surge of performance going, or if it fizzles out again, as has happened previously.
I can’t possibly stay amber after 2 profit upgrades, so it has to be GREEN. Definitely worth doing some more detailed work on the services it offers. I do recall that it has been investing in a new ad platform of some kind for several years, so if that is now paying off, there could be further upside perhaps? Looks interesting, I think it’s worth you taking a closer look. We may be late to the party, but we’ve received a warm welcome, and handed our bottle of Asti Spumante to the hosts!
As always, we very much want to hear reader views on this (and all) shares, as we don’t usually have time to really dig into the detail, competition, etc.
Zoo Digital (LON:ZOO) - 41p (£40m) - Trading Update - Paul - AMBER
ZOO Digital Group plc (AIM: ZOO), a leading provider of end-to-end cloud-based localisation and media services to the global entertainment industry, today provides an update on trading.
Checking our previous notes this dubbing/subtitling company delivered excellent results for FY 3/2023, but then had a series of awful profit warnings, indicating a huge £(13.8)m loss for FY 3/2024. The main issue seems to have been the long-running Hollywood strikes, so we were hoping for a recovery, hence rather too optimistically stayed at AMBER (helped by its healthy cash position thanks to a very luckily-timed equity fundraise just before trading & the share price collapsed).
The latest news is yet another profit warning, but mitigated by reassurance that demand is returning after major disruption from the strikes -
ZOO has now been notified by its largest customer of orders giving a pipeline and confidence of work for the next two quarters which is expected to deliver a strong recovery of revenues, and indicates demand for services and languages that are aligned with ZOO's investment strategy. However, it is now clear that the completion of entertainment products is taking longer than expected. This will result in Q4 revenue being significantly lower than anticipated leading to a greater loss than previously expected for the full year.
The pipeline is consistent with current market expectations for FY25 and a return to profitability.
So this looks like a situation where investors are being asked to write off FY 3/2024 as an annus horribilis, and draw a line under it as things hopefully recover.
Cash doesn’t seem to have run out -
On 31 December 2023, the Group had net cash of $8.9 million and expects to maintain a positive balance with unused debt facilities available at the March year-end and an improving cash balance in the first half of FY25 due to the recommencement of orders.
Paul’s opinion - tricky one. Obviously performance has been dire, but it still has enough cash. Should be hold on at AMBER, expecting a recovery that does at least seem to be credibly in the pipeline? Or should I move down to amber/red, to reflect that I don’t think this is a very good business model at all? It’s also vulnerable to obviously strikes, but also I believe has client concentration risk, and lots of competition. I don’t really believe the bull case. I’ll sleep on it, and decide in the morning!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

150 comments
A day late I know but the Times Tempus (share tips) article yesterday was particularly scathing on the prospects for Vertu Motors (LON:VTU. I note that this share held by many on the SCVR (including myself) dropped a couple of % on Friday but have to hope this tipster has it wrong - again. Evidence of the much mooted acquisition would help!
Based on my experience or research of newspaper share tippers, I'm not unduly worried by this. In my opinion, the recent big drop in the sp has already factored in this information.
I hold Vertu Motors (LON:VTU) and will do so for a little while longer, although I have put a stop loss on.
A 2020 study by Stockopedia put the Tempus tips at the top of the tree and called them "impressive" This is however fairly irrelevant today.
I sold Vertu when a fellow poster on this forum wrote to Vertu directly to clarify their positon on car loans.. There has apparently been no response. Not even a bland holding reply.
Furthermore, the market is collapsing in second-hand cars - so its not a good background.
I still believe that Vertu is fairly good potential for a takeover . I put the risks though at 70/30 against holding.
Same here done exactly the same and I had no response so obviously I got out but still I have a positive view on Vertu Motors (LON:VTU)
Vertu Motors (LON:VTU)
Same here done exactly the same and I had no response
Seems somewhat remiss of the company not answering the question.Unless they actually have any financing arm connections themseles i was expecting it would be a pretty quick repoinse saying we dont dont financing perhaps with wishy washy caveats if there might be soem backround iffy stuff. Obviously if they dont answer one has to make presumptions - not really right if they say nowt you sell then they say there was never an isue in the first place later. dont blame anyone for selling though if they cant treat part owners with the respect they deserve.
Vertu Motors (LON:VTU) sentiment won’t be helped by news around GAP insurance being withdrawn from early Feb at the instigation of the FCA who are concerned about the level of commission being charged
I agree and that’s why I exited from my position especially after I had no response from the company itself about recent events. Still I believe it will be taken over at some stage but simply too risky after recent events.
I still have not received a reply from my enquiry which was sent to Media Enquiries on the Contact Us section of their website. Ordinarily enquiries to businesses are met by an immediate email acknowledging the enquiry and a commitment to respond in due course. Communication is the key for any business and the failure to do so by Vertu is imo a red flag in itself.
Re Vertu
Thank you for the responses. If I was heading up the Vertu PR department I would have been on this straight away. Lack of any replies is very poor.
I also noticed that Martin Lewis was using the word "dealers" in his talks, This might be a slip of the tongue but the likes of Vertu should be countering this if they have no exposure.
Vertu replied to me- took over a week, but they did in the end. Not that they said anything to report.
Are you able to share their response or a brief comment on what they have said.
Thanks
Zoo Digital (LON:ZOO.I came across this brief article on Yahoo finance.I know Paramount's controlling shareholder is supposedly shopping around for a buyer.And there is supposedly a need for consolidation, if it can pass the current antitrust regulations scrutiny in Biden's adminstration as Netflix is the only streaming winner currently it seems.Perhaps business next year won't be as great as projected, even accounting for the delays?
'Media layoffs: Google Paramount, Disney, and others commit to job cuts in 2024'
'The media and entertainment industry's reckoning will continue in 2024 with more layoffs as rising costs and debt-ridden balance sheets continue to weigh on the embattled sector.
Partly in an attempt to appease Wall Street, these companies over the past year have slashed billions of dollars' worth of costs. In addition, under profit pressure, they rolled out ad-supported tiers, bundled their offerings, and raised the monthly prices of subscription plans.'But all of that wasn't enough to satisfy investors.
Valuation levels remain depressed. And streaming profitability still has a long way to go, with virtually all media companies (with the exception of Netflix) losing money on that business. The bottom line: more job cuts.'
https://finance.yahoo.com/news...
Wickes (LON:WIX) v On Beach group (LON:OTB)
Interesting and contrasting signals from these two today imo. Wickes (LON:WIX) sp up nicely, and could go another 10%? PBT to be at top end of expectations despite little change in revenue year on year. DIFM quarterly trend turned negative on Q3, down further in Q4 and is negative already to start the new FY. So of course the sp went up.
On Beach group (LON:OTB) on the other hand reports Winter 23 is up 34% and full year running well ahead of last year, particularly on the upscale and long haul sectors. So customers cutting back on big ticket items but spending loads on hols? Supports some of the other comments today re Saga and cruising clientele spending their hard earned property and pension windfalls. The misery media are really going to struggle with this.
On Beach group (LON:OTB) saw their sp drop as the market embraced the good news. Admittedly they have had a good run and profit taking is inevitable. There are some very bold.claims for what they could reach floating around. Personally I'd be happy to see them head to 250p or so. We'll see. As ever the market will decide. Meanwhile just holiday like a fool!
I work in the travel industry, and it is a very strong consensus trend (backed up by customer research - but obviously biased towards travel questions) that consumers are prioritising travel expenditure over other large "physical item" purchases.
The poor SP performance of On Beach group (LON:OTB) today, in my mind, is due to the fact they have decided to go more top-line growth vs profit in their focus. Investing in lowering prices, to steal more market share and drive more bookings volumes.
Majority of investors these days are looking for profit prioritisation over top-line growth prioritisation, so I suspect a bunch sold out today based on this.
Whether we'll have new investors come in over the next few weeks, I don't know.
(I hold OTB in the Boon Fund)
On Beach group (LON:OTB)
surely investors here would understand and want the company to be pedal to the metal ref growth at present? - i have deffo noticed they seem to be more mainstream that they were a few years ago (perhaps i see because i am looking ?) - surely their market segment could support much higher level of sales from them? - is the best time to push forward not when its easiest to do so. ie now Note i am normally one who prefers profit/margin over growth nowadays but i just see so much opportunity for them to ramp up sales and brand over next 2-3 years that imho they would be silly to not try and make their name familiar to everyone and psuh as far as they can when conditions are benign. Perhaps my thoughts are too simplistic here. Ref poor share price prformance - its been on such a tear should we not be expecting it to head back to that green line on the stock graphs that hopefully it would bounce off?
Big spike for Luceco (LON:LUCE) into the close with one significant trade of £1m+ sparking the rally. Monday's concert party split might have something to do with the action, but only indirectly if that £1m buyer isn't on the BoD. Tempted to sell here as valuation now looking full but operating leverage is good and an insider buy would keep me sweet. Anyone else monitoring?
I've only held Luceco (LON:LUCE) since early Dec BnB, so not a company that I know well .... management have plenty of the skin in the game which is always good , but the chart history makes targets difficult... 200p should be eminently achievable, but maybe cut half, run half ?
anyone know why Supreme (LON:SUP) appears to have fallen recently?
Supreme (LON:SUP) I think it is largely due to market sentiment moving against them, due to the increased likelihood of further regulations within the vaping market. This has been discussed here in detail. It is an industry that very much splits this community.
I am of the view that vaping is a far better alternative to combustion (based on both the health industries opinions and also what limited scientific data is available). I cannot understand why it would be banned or made to be prescription only - while cigarettes remain available - this to me is the height of stupidity - and personally I cannot see it happening. So I assume that this will not happen! Supreme have been very diligent in being a responsible producer and distributor and I think that the stock will re-rate once these concerns subside.
Totally agree MetalMaid
Just imagine the unnecessary extra workload & cost of GPs & pharmacies - if vaping products were made prescription only? Especially as they currently don't do it for Nicorettes, patches or gums?
Plus its pretty tough getting a doctor's appointment already anyway.
Just imagine the unnecessary extra workload & cost of GPs & pharmacies - if vaping products were made prescription only? Especially as they currently don't do it for Nicorettes, patches or gums?
Especially as they currently don't do it for Nicorettes, patches or gums?
errrr you are comparing great medical solutions with mininal side effects against something that clearly causes damage to the body long term - we should be going out of our way to promote anything other than vapes as a solution due to the very obvious fact that vapes damage the body much more than Nicorettes, patches or gums? Not sure how peeps who are pro vapes manage to ignore the obvious elephant in the room so much when making their arguments.
I believe Paul maybe paid to promote Supreme (LON:SUP) amongst others (Paul, please correct me if I'm wrong) although doesn't own shares himself as he notes on PMH Capital website:
Stocks owned : EQLS, AGFX, Pfizer, Bristol Myers, Roche, WATR, MBH, ASTO, TCAP, SND, TR25, ESYS, RWS, GBG, ELCO, IHC, Paypal, PMI & AOM.
Paul is paid for work related to EQLS, ASTO, VRCI, BELL, SED, CSFS, AVG, AVCT, LLAI, VLG, FADL, SUP, ELCO, LORD & ONC.
So I ignore anything he says about these companies.
So shall we ignore on anything you say about companies that you own?
Cause you keep posting about them and their pleasing updates.
Personally I do not ignore anything anyone posts here.
Hi yiannos1.
You have misinterpreted what I meant.
I ignore the comments Paul H makes about the stocks that he doesn't own and probably never will but has a vested interest in promoting for monetary reasons.
I have no issue listening to him talking out stocks where he has put his money where his mouth is and, indeed, I bought into the likes of Northbridge (Crestchic) and Equals (LON:EQLS) after being introduced to them via Paul H's interviews
I have been watching Paul H for ages, admire his work ethic and friendly way he conducts his numerous interviews and picked up some good companies on the back of it but over those years he has repeatedly pushed a number of “Sucker Stocks” as Stocko describes them (mainly on VOX with JW) because he is employed to do so which, to me anyway, devalues whatever he says about them, hence why I ignore them.
I understand but just adding that whoever holds what is irrelevant. They are just ideas and basically information for further research and should be thankful they provide this service for us.
I am fine with Paul psoting his comments.
from my persepctive its very simple Vaping in endemic amounts the youth - it clearly addictive and bad for them - and only a small % of this vaping segment will have been addicted to cigarattes big style befoe taking up vaping big time. Smoking trend was clearly downward before vaping existed so imho although it has its place imho its riciculous to let youth of today have free reaign on something that is clearly badefor long term health - not saying as bad as smoking but is clear there is some non zero level of damage to ones body. Vaping works best as originally intended for people who were long term smokers and were struggling to give up - imho thats not too hard a segment to mange via prescription whats worse ids now then money doing the studies like tat is mostly funded by teh vaping companies who wil only publsi positive spin . I do feel its a fairly polarising argument here though so i am well aware possibly over 50% of peeps who post here simply dont get this simple logic - hey ho , the genie is out the bottle and being spoonfed to young kids as i type.
Large Director sale of Elixirr International (LON:ELIX) today , I hold, but find this to be unnerving especially since there has only been one (small) Director buy since November 2022. Despite some upward trend in the recent announcement this behaviour speaks volumes to me. And today’s market seems to agree.
News on mid-cap Serco (LON:SRP) : according to Sky news, a US firm has put in a £2.5 billion takeover approach.
Edit: article says Serco is worth about £1.9 billion (so above the usual SCVR market cap); it wasn't clear if there was a firm takeover proposal lodged; a person 'close to Serco' says there are no longer active talks but 'the news of an approach from a serious private equity bidder will effectively put the London-listed company in play'. The interest is likely to be from it's fast- expanding American business, including a central role in delivering Obamacare.
Edit of edit: I hold
iShares Bitcoin Trust (NMQ:IBIT)
Never in a million years i thought I would buy Bitcoin but I cannot just sit and watch all these clever people adding this to their portfolio.
Just a 5% of my US portfolio and I am prepared to lose all (don’t think I will).
Have been looking at this and can't seem to buy iShares Bitcoin Trust (NMQ:IBIT) or Fidelity Advantage Bitcoin ETF (TSE:FBTC) through AJB, IG or IKBR without some form thingy. Work in progress.
Was looking at MicroStrategy (NSQ:MSTR) who run a software business with 160,000 bitcoins in storage (but cannot avoid the bad Stocko alerts).
Looked at Grayscale Bitcoin Trust (PCQ:GBTC) who have been around since 2016 and hedge funds cottoned onto to their deep discount and spotted the SEC decision back in Sept 2023. So hedge funds piled in for a 'trade' and then according to the news notes are 'outflowing' as fast as they can.
Not a gambler enough to actually buy the bloody thing, Bitcoin that is, not the lesser cons, although think Etherium is No. 2.
An ETF's seems a good idea from Blackrock, Fidelity GlobalX etc to legitimise and put money into the market and hence increase demand and therefore price and with a halving coming up another dynamic for the gambler.
Let the FOMO games begin.
Have put the following into IG watchlist:
Amplify Transformational Data Sharing ETF (PCQ:BLOK) - hold lots of finance guys PayPal etc
Coinbase Global (NSQ:COIN) - this seems the only 'trusted' exchange out there with several products to play the space. Need to research.
With the institutions changing their tune and accepting Bitcoin as an asset class through ETF's there will be huge competition for Bitcoins.
Apologies SCVR will transfer over to the discussion board.
Some good fund documents on Amplify's website and monthly newsletter on their fund. Not just coins but blockchain technology for data storage and transfer, use in AI. J.P.Morgan and Blackrock both see Tokenisation and Public Digital Property as the future - don't know what that means but gonna have to find out.
Clever people can collectively become induced to do unwary things
Really I should have emphasised that they are clever, vey successful and extremely rich!
Not to anybody’s taste but they will take it where they want (Bitcoin).
All the best
Yiannos1
The UK financial experts are ‘protecting’ me from buying Bitcoin ETFs in my ISAs for now. When they relent I will be looking at this ETP which was launched in Switzerland and combines holdings in Bitcoin and Gold. It may be too ‘safe’ for you 8-)
https://21shares.com/product/BOLD
https://www.bytetree.com/research/2024/01/bytetree-bold-index-january-2024/
The UK financial experts!
But they allow people to buy Versarien (LON:VRS) Chill Brands (LON:CHLL) REGTECH OPEN PROJECT (LON:RTOP) Invinity Energy Systems (LON:IES) and another 100 companies that will end up to a big zero.
No more risky than your average UK IPO. Will follow the herd, with money can afford to lose and watch the chart for signs the big boys are selling out.
Elementis (LON:ELM) continues to tick higher. Maybe there is an end in sight to the ongoing impasse between the company, its frustrated major shareholders and potential bidder(s). Patience, patience, patience and a bit more!
My wife has a moderate holding in her ISA, which she trusts me to manage.
Elementis (LON:ELM) Funnily enough I bought some in my wife's ISA which she trusts me to manage as she has zero interest herself.
Patience and a bit more as you say but I am hoping we are nearing a conclusion to this and would be happy for it to be sold, for a reasonable premium of course, and move on.
Hi Peter
Unfortunately none of my family have an interest in stock market investing so my wife and our son and daughter are happy to delegate the management of their ISA portfolios to dad.
All the best
Saga (LON:SAGA)
My only interest here would be in a short term trade, however for anyone interested in a longer term hold my experience of their car insurance with my mother's and my policies is that they have without doubt the worst customer service of any company I have ever dealt with. Not a personal rant just information to be aware of.
You've obviously not dealt with Virgin Media
They really set the standard!
Taylor Maritime Investments (LON:TMIP) latest quarterly Factsheets suggests the company is making good progress with sale of older vessels and reduction of debt. CE Edward Buttery said:
"We are harnessing the operatingleverage of the Grindrod transaction which has delivered a younger, more efficient combined fleet, an increased carrying capacity and expected synergies and cost efficiencies to drive earnings power into a firming charter rate environment. Reducing debt remains a strategic priority and further progress has seen debt to gross assets fall below 25% at quarter end. We took advantage of strengthening market conditions towards the end of the period with 13 month index highs and locked in higher charter rates on a portion of the fleet.
Tight supply-demand fundamentals for the geared dry bulk segment continue to drive positive forward sentiment. The management team remain closely aligned with shareholders and maintain strong conviction in the Company's prospects as reflected by a purchase by the Principals of the original Taylor Maritime group of a further 3.9 million shares during the period. There remains plenty to do in 2024 and I am confident of achieving our goals." (I hold)
Saga (LON:SAGA) Agree and increased holding this morning
Be interested to hear thoughts on Avon Protection (LON:AVON) . Been following for a while; Cockney Rebel is a big fan, and the trading update today looks encouraging. With the world going to the dogs I can see some significant upside here.
He sent out a big piece on them this morning for those subscribing to his blog (which I do) I already hold Avon Protection (LON:AVON) but am considering buying more.
Hi Peter - same here and I enjoy his blog. It was a thorough write up and I cant argue with the logic. I've had a nibble this morning but I'm considering a larger position. Paul had previously written about the in October 23 but freely admitted he wasn't close to the company so be interested on wider community thoughts.
Cockey Rebel put up a strong case for Avon Protection (LON:AVON) at Mello Monday this week, but it struck me that he had 'fallen in love' with its recovery opportunity.
Avon Protection (LON:AVON) I have emailed them to ask what access private investors will have to the capital markets day so that we aren’t left behind and suggested they do something on PIWorld or IMC.
Nice reply re Avon Protection (LON:AVON) capital markets day:
Many thanks for getting in touch. There will be a live webcast of the CMD, which you can register for at the following link: https://brrmedia.news/AVON_CMD2024
A replay of the day will also be made available on the company's website following the event
If they don’t mess up the production move out of California.
Just my personal opinion on Avon Protection (LON:AVON) with a market cap of £290m , an EV around £360m that it will only fall to £340m in 2026 and with operating margins of 11% and FCF around £15pa it looks like it does not appeal as an investment opportunity.
However in a sector that has potential growth and looks like there has been a consolidation at current prices.
Just not for me.
Check out Pennant International (LON:PEN) then. A tiddler also in the defence sector with a couple of shrewd IIs on board. Mkt cap £13m and EV of £15. p/e of 8.2 and peg of 0.5. Trading update soon
I have seen Pennant International (LON:PEN) and I think planetx mentioned it before. It’s not bad but too illiquid for me to build a position and revenues have been declining from 2018. Can’t see where the growth is coming from.
I will follow it though.
Thanks
Any thoughts on Chemring (LON:CHG), I don't hold at the moment, sold a few weeks ago. I was expecting a pullback but has not happened yet, directors sold a few recently.
Cohort (LON:CHRT) is another defence stock, shares are up recently, one director bought £80k last week, I hold.
Not familiar enough with Chemring (LON:CHG) Cohort (LON:CHRT)
I have added recently Revolution Beauty (LON:REVB) as the last update indicates of FCF of £2.5m on a monthly basis. There is no coverage though but there is an investors event on the 8th February or a date near that. Looks very cheap and can easily double from current prices. Still ongoing issues with the delayed accounts two years ago (published now) and expected fine should not be discounted. Still very cheap on margins and revenues (expect them about £210m).
Started adding Kier (LON:KIE) today after exiting from On Beach group (LON:OTB) and Billington Holdings (LON:BILN lately.
With the chance of a Trump second term looking all the more likely I think any defence companies with significant exposure to potential US government contracts are looking very good investments right now. Once his presidency campaign gets going I am confident there will be huge promise of investment in defence. Chemring (LON:CHG) already have US Navy contracts so those links are established. Personally I have gone for some of the smaller players in the defence market - MS International (LON:MSI) , Pennant International (LON:PEN) and Avon Protection (LON:AVON), my thought process being that if just one of them gets some sizable contracts that could cause the shares to double, if that happens my pot of defence stocks would be running at over 30% annual gain. Divide and conquer!
Do you not think it more likely that Trump would pull out of NATO, reducing America's need to project power in far-flung parts of the world?
Its certainly a possibility. Although I can't imagine Trump taking his foot off the gas in the middle east and that could escalate. If he did dip out of NATO he may feel the need to bolster their own military as a show of strength as they would be less reliant on the rest of the west. It would also be a catalyst for China to invade Taiwan. Either way I think we are about to enter an era of significant unrest over the next decade which will result in profits across the defence sector. At least more so that teapot makers!
BAE Systems (LON:BA.) Is an obvious candidate Ben. You didn't mention it - is that because you want to stick to small caps? Other larger co options Rolls-Royce Holdings (LON:RR.) and Melrose Industries (LON:MRO) who own GKN aerospace.
Spglet - BAE Systems (LON:BA.) is a classic one that got away. I remember having a buy order in about a year ago that never filled. I've "been waiting for a pull back" that has failed to arrive ever since, I've just sat and watched the SP climb ever higher since! A great option but I keep convincing myself I've already missed the boat and hence looking at a few smaller caps as you say.
I agree BenHazz. It seems that defence spending is only set to increase across the world. I have no exposure to the sector but was considering the VanEck Defence ETF although the UK defence giants are not held. Any thoughts on how best to get exposure to the defence sector would be welcomed.
There's no room for complacency and it's still a long time to November, but I think the chances of a Trump 2nd term are slim. He is doing very badly with Independents and more and more Republicans are turning against him. Plus his boasting of over-turning Roe will galvanize the young vote/women's vote.
None of which contradicts your main idea of investing in defense - given the direction the world is heading as the human race circles the plughole, it's a logical position. Good luck. I, too, hold Avon and MSI.
Plan on Trump, hope for Boden (or preferably someone younger). Not sure defense will do well under Trump as he cuts support for Ukraine and potentially pulls out of NATO.
European spending will then have to increase substantially to stop Putin pushing through Ukraine to Moldova and possibly taking the rest of Georgia that he hasn't already. He might not go for the Baltics if he can consolidate non NATO geographies without a full on fight.
Will Europe make up for loss of US demand? I doubt it. Expect the DoD to be placing lots of orders this year in advance!
Coral Products (LON:CRU)
Sometimes it’s just more than numbers and this is why I always read planetx comments.
I was a holder of Coral Products (LON:CRU) and I liked the company having enough cash and no debt and I have bought around 14p and shares it at the time.
But, on an investor event I have seen the then Chairman wearing a colourful shirt (one that you probably wear on a Maldives holiday) trying to persuade me about the prospects of Coral Products (LON:CRU) and having difficulty to answer the simplest questions,
Next day I sold everything around the 16-17p (shares this here as well) and never looked back.
The new CEO today announced a bad trading update after 25 days in his new job.
Sometimes there is more than the numbers.
Re Coral Products (LON:CRU) I understand Chairman Joe spends large chunks of the year at his villa in Spain…so it’s perhaps inevitable that he won’t be quite clear what’s going on back in rainy Manchester
Coral Products (LON:CRU) Those share buy backs last year are looking expensive now! Had been thinking of reducing my holding earlier this week and increasing holding in Saga. Doh!
We may be late to the party, but we’ve received a warm welcome, and handed our bottle of Asti Spumante to the hosts!
Brilliant Paul! Made me chuckle!
Hello Paul,
Thanks for the write-up on PPHE Hotel which I have been following. The brokers do not share research (so cannot access it) but I found this very informative up on their website. Scroll down to equity research and big note there
https://www.pphe.com/investors
Maturing Gilts - I ploughed a large proportion of my portfolio into Gilts last year when yields were above 5%. These were mostly short duration with TN24 maturing at the end of this month and another, TR24 (linker) maturing at the end of March.
My first instinct is to redeploy this money into the kinds of shares discussed on Stocko and wonder how many others think the same (I'm assuming there are others here who also bought gilts when they were going cheap) and what affect, if any, these gilt maturity events have on money coming into the market.
Similar situation. I was hoping to deploy the cash into property; however, the crash that I expected has not yet happened (together with ongoing concerns of additional stamp duty for BTL investors).
The value investor in me is looking at getting an aircooled Porsche (or another bombed out sector watches perhaps?), markets have softened, but there are still some outstanding dividends to grab, so I will be taking my full ISA allowance for me and the family this year for only the 2nd time ever (just bought British American Tobacco (LON:BATS) for a 10%+ div).
But you're right in that I had not considered this cash coming back into equities, could assist any bounce in the market that a lot of people are suggesting may happen in the UK.
Still not sure about British American Tobacco (LON:BATS) to be honest - may look optically cheap, but it is a dying industry and likely to face ever more crippling regulation. Plus a lot of debt. If your main objective is a huge dividend yield then I'd probably rather go for something like Phoenix group (LON:PHNX) or £MNG
Why not all 3?
I just gave 2 examples - I could think of at least another 10 high-yielding companies that I think have better prospects than £BATS not to mention various parts of fixed income that now offer double digit yields (BBB European ABS, AT1s, etc)
I agree, although since I sold out of Legal & General (LON:LGEN) I have not had any big cap exposure. I've got some nice locked in dividends, such as Shoe Zone (LON:SHOE) at last look was giving me circa 26%.
I disagree with your analysis though as through my optics, everywhere I go, people are vaping. Kids are getting hooked. On nicotine based products. With increased regulation on vaping, in my view, companies like British American Tobacco (LON:BATS) who are have had to operate within a strictly regulated business for years, are best placed to deal with hurdles governments place in front of them. In Europe too they can just take out a vaping company like Supreme (LON:SUP) so they can diversify further. There's also the cannabis industry, becoming almost legal in this country by stealth (just google edibles/vapes) which would sit nicely in a portfolio of a smoking related company.
Is it a possibility that BATS could take out a company like Supreme to 'diversify further'?
Just for clarification, BATS, in the latest results, the 'new categories' division which is basically their vaping division, turned over £2.9billion! Supreme probably turned over £100million (and much of that was as a distributor for Elfbar (not their product / ip).
I think we need to have a bit of perspective sometimes when talking about a relative tiddler like Supreme and global powerhouses like BATS. The reality is that a takeover of a company like Supreme could almost be a rounding error. Lets not forget that BATS 'new categories' is still a small part of the business and is already turning over £2.9billion. Supreme is a well run operation and it may well be a takeover target for BATS or the like; but I feel that your post did not really show the actual market dynamics / and differences between these 2 businesses - and thought it necessary to share this viewpoint as others may not realise the relative size of these vaping divisions.
I think you're making my point! The amount of vaping companies out there and similar, could easily be swallowed up by British American Tobacco (LON:BATS) I threw in Supreme (LON:SUP) as it was a company discussed on here often as I don't know many other listed, but in essence my point is - these companies can be taken out in a blink without breaking sweat.
Yes obviously any company can be taken out in the blink of an eye. I was questioning why a company like BATS would be interested in a company like Supreme.
Imo Supreme are mainly a distribution company. They then use this distribution network to try and introduce new lines. Yes they are a terrific manufacturer also, but the core business is now very diversified. They distribute batteries and lighting as a low margin distributor. They produce wellness products (vitamins etc), and then they have a vaping division (which produces 88 Vape and distributes Elfbar within its network). Just looking through their latest numbers - the vaping division delivered revenues of £76m with a gross of £28million. So I cannot see why BATS would be interested in such a small operation - especially when the company is not even strictly a vaping company - what would BATS do with all the other divisions?
Sorry I don't mean to be argumentative, but I just do not see Supreme as a realistic takeover target for a company like BATS. I could envisage it, if Supreme had something special in terms of the vaping liquid. But there really is nothing special about the product- apart from the low price (its a very generic vape liquid, and there are hundreds of similar choices in the market). Just my opinion for what its worth.
I am in same boat but might be safer to recycle into gilts TR25 will give 4.7% tax free
As always diversify.
With the approaching budget on March 6th and the likelihood of tax cuts of some description as a last chance to ‘bribe’ the electorate I suspect gilt yields may yet go back up. Add to that the market reaction when they realise the incoming Labour government’s (a certainty it would seem) spending plans don’t add up whatever Rachel Reeves says to the contrary (unless she does a u turn and hikes various taxes).The result might be a return to gilt yields seen at the time of the Liz Truss debacle and an opportunity to lock in some 5% + yields for the medium term. Definitely not as exciting as some of the SCVR offerings but I guess it depends where you on the retirement journey and your attitude to risk, etc.
With the approaching budget on March 6th and the likelihood of tax cuts of some description as a last chance to ‘bribe’ the electorate I suspect gilt yields may yet go back up.
100% agree this is a ridiculously sad state of affairs and its clearly political grandstanding playing with debt time bomb by peeps who will clearly not be around to pick up the pieces. 1 example being on 1/4/2023 corporation tax rates when up 6% for larger companies and 7.5% for smaller companies making profits betwen 50k and 250k. How on earth can they be raising taxes at the same time of cutting taxes unbelievably crazy.
Just wish there was a party that would promise to live within out means and ensure debt burden reduces in real terms and also ideally in total sixe terms too. Exceptional circumstances excepted - to me in normal/good times we should be paying down debt (saving) so when the bad times come we have some wriggle room. If only we had the dinner ladies party running - they would get my vote in a heartbeat. ok weekend rant over now what goinmg to win the 3.15 at Doncaster - answers gratefully received thanks.
Saga (LON:SAGA) The interesting thing about RNS this morning is that they confirm they are now operating close to capacity in cruise. Assuming the travel business is also firing (which it should be) then in my view the business should be highly cash generative at the moment. That in turn should remove concerns over liquidity following decision not to sell the insurance underwriting arm.
A partnership with another Cruise business that significantly reduces debt due on ships could be a game changer though. Operating leverage should go through the roof once that happens.
The main drag has been insurance but this should also be coming out the other side as policies are re-priced and inflation has dropped significantly, so no reason that too shouldn’t be start to contribute heavily again. Insurance is generally very good at re-pricing so troughs caused by extraneous factors are usually short lived.
Starting to get interesting. I do hold but thinking I should be buying more.
Anecdotally I understand the Saga (LON:SAGA) offering is very good and very well received. I asked some elderly relatives if they’d used them and they said they hadn’t yet but many of their friends had and there was nothing but great feedback. If customers are happy that always bodes well.
Hello davidjhill. I had been noting that the SP had been creeping up recently, and just my luck that it hits the headlines today and the SP heads north for quite different reasons.. Strangely, on the basis that Friday would be a quiet day, I was going to start a comment on Saga (LON:SAGA) today which might have seen the SP head south over time.
We have been Saga customers for some years, across the range of holidays but not yet cruises. In 2022, we were planning to be away for Xmas & NY and thought about the Canaries cruise. However, we then thought about the weather factor, and had had some feedback re a similar cruise on Fred Olsen from Liverpool where the bad weather had hit them near the start of the cruise and followed them virtually all the way, and a good part of the way back.
Although good value, the Saga cruises are not cheap and the thought of spending a good part of the holiday horizontal in our bedroom did not lie well with us...so we went by air instead to Madeira, and did the the same this last time to Tenerife. We were glad we had done that when we noticed the injuries suffered on a Saga liner in November.
The point I was going to make was that with climate change and more uncertain weather patterns (we missed 3 major storms in our two week fly/hotel holiday over Xmas/NY), then cruises starting and finishing in the UK as Saga's do would gradually become less popular over the winter months, with a negative effect on profits. That doesn't seem to be happening currently, but I note that their cruise offerings in the spring and even summer ones are being widely advertised at lower fares......so that doesn't seem to tally with comments about operating at full capacity.
So perhaps my logic is flawed and the demand by better seafarers than us will continue to fill the boats, and hopefully not the lifeboats!
Thoughts, anyone?
PS I am not a holder currently, and have been waiting on the sidelines recently. Sadly, missed out out on the jump today.
ridavies
It would be a good idea to go to the Saga Cruises websites for accurate information. That would include this price promise …so it encourages early bookings when discounts are at their highest.
“Our Cruise Price Promise
Book early for our top savings of up to 35%. And should we ever drop the price in the future, you'll get the value of the difference back.”
Saga cruises website:-
https://travel.saga.co.uk/crui...
SAGA
Also it offers..... "Love your first SAGA cruise -or we will give you your money back"
Yes - it really does say that on the link above.
These are Hoover style promotions. What on earth is the management thinking?
These are Hoover style promotions
oooh showing your age here intuitive6191 ! i had forgotten about that one
So perhaps my logic is flawed and the demand by better seafarers than us will continue to fill the boats, and hopefully not the lifeboats!
i have to presume the amount of affluent brits the right age must be increasing - peeps sailing of into semi retirement in their mids 50's backed up by fully paid house worth perhaps 1/3 - 0.5 mill - seems very popular amongst peeps i know - and most doing that really do have the travel bug again based on my experience.
I would probably give a couple of thoughts
1) If anything was going to kill cruise popularity I would have thought it was Covid but it didn’t. I can’t personally see climate change impacts having any real effect on bookings of cruises, at least in any duration that investors will care about. As you say you have not yet been on a Saga (LON:SAGA) cruise yet they still manage to attract you as a customer to their other travel business. So that probably tells us that they sell a good range of travel with great service. Maybe they convert you to cruise at some point, maybe they don’t……but with the demographic of an ever growing older population there should be more than enough customer base to target.
2) prices are always lower early and algorythmically driven, like the airlines - basically with a view to getting to a target per diem average cost per passenger at each cruise capacity.
For me the Saga (LON:SAGA) play is based on operating leverage. Capacity cruise ships equate to £80m EBITDA, travel could do another £20m+ and insurance/other should be able to do £100m once the re-pricing kicks in. So if you can do a play whereby you remove most of the ship debt (where most investor angst lies) and generate £150m+ of operating cash flow then what’s the business worth? I’d argue many times the current share price.
That, however, does heavily depend on strong execution - I have never really been a fan of the old CEO (followed him at Superdry where I was also unimpressed) but there is an opportunity with a new broom to move the needle. We need to watch for signs of that and the news today suggests things are moving in the right direction. The next thing I’m looking for is the upswing on the insurance side.
Checking in on the bonds - the 2024 is almost back at par so that says the market is certain they will be repaid. The 2026 maturities are at 85c so suggest investors want a 10% annualised return (bonds pay 5.5%) for the risk. That’s pretty low - suggests bond holders are not concerned about solvency.
So all in all feels to me like a decent risk/reward over a 2-3 year timeframe. As I say I am long around the current price but probably looking to add more. Ideally I’d like to wait for a trading update so I get some better visibility on insurance side and also how the strategy is evolving post the CEO departure.
Anyway just my view on the opportunity and risks.
How would most of the ship debt with Saga (LON:SAGA) be removed, hypothetically speaking?
Presumably SAGA sell the ships and pay off a lot of debt with proceeds. Then of course they have to pay to use them which is probably by leasing them.
Thank you. So it would need to be a pretty wealthy 'partner' to do that
Hi rogerh,
In the RNS they talk about a partnership for Ocean Cruise, moving to Capital light model and reducing debt.
To me that says someone buys the ships (or part thereof) thus reducing the debt possibly to zero (given the ships have quite a big positive TNAV). Saga (LON:SAGA) then operate the ships (plus maybe others - branded Saga) and the profits are shared. Benefit to the company is that there is no large “I” for the EBITDA number. Depends on the deal of course but if done right could be transformational for the company in my view.
Thanks David
Saga (LON:SAGA)
hmmm so its the same customer paying and they need to split the profit they currently keep 100% with another party - love the agile thinking of the saga board.
Saga (LON:SAGA) . Yes they will presumably split profit from cruises with another party, but in exchange they don't have to service the debt. That is presumably the sort of scheme they are thinking of. Not really justifying your dismissive tone, is it? And my reading of the hints provided suggested that the potential "partnership" might also provide other opportunities for Saga. But at this time it's all pure speculation, isn't it.
Saga (LON:SAGA)
my comments were probablya bit flippant - the whole investment ethos here from holders was meant to be that "the debt isnt an issues" though. It either is or isnt. If it isnt they shouldnt need to give away any of the pie. If it is then others can perhaps force their pound of flesh.I a
m on the fence here - as long as they make decent profits and have support of the main man then they should be able act from position of strength - the reality of what they have been delivering in "great market conditions" though is poor - my main worry here is that then boad seem abolutely uselss at making wads of cash without a fuss. ? specifically other insurance companies recently have been much more upbeat than saga are - another issue is we have negative future visibility - the board hate doing forecasts and always seem to be looking in the rear mirror. 3 years ago looking at where they should be now - should holders not have expected an easy £50 mill insurance profits and an easy £50 mill travel profits in these current decent conditions ? the reality is 2024 wil deliver 1/3 of that with prospects having started the year low and deteriorated since then despite customer queuing at the door as it went on and there being perfect conditions for cruising.
As you say its very much idle speculation at present - i supect is from anything other than a position of strength based on how highly i rate the bods that run this company.
I agree and I remember around 400p that the debt was not an issue according to the write ups here , although I have disagreed looking at where their bonds were trading at the time.
Still trading at 80p maturity 2026 ; so the ones that believe that Saga (LON:SAGA) will survive should take the approx. 15% yield to maturity!
Saga (LON:SAGA)
to be fair to those saying the debt is not an issue they might end up being right - from my persepctive its that they werent really in a strong position if stuff trended where it has done - if they could boost profits the debt issues may go away again and the shares could easily bounce - heck they could even be lucky enough to get a tie in with the same saudis that value Miguel Almiron at £30 mill. I think the fact the shares are where they are the market does have lingering doubt one just has to lok at mcbrydes to see how it can turn for the better if they could improve the financials - or stike gold elsewhere.
McBride (LON:MCB) revenues are up about 70% at the same time when input costs stabilised and that’s the reason of the 300% upside.
Saga (LON:SAGA) revenue estimates still down on their 2019 actual revenues.
Different things.
Saga (LON:SAGA)
agreed - i was just speculating what could happen if they had reversal of fortunes - who knows if and when that will happen with saga - i do note 2025 profits are expected to trend upwards so perhaps some hope for holders.
Re Saga (LON:SAGA) - I am the very opposite of a climate denier and am investing in building companies for example that are betting on 'green' but climate change is a multi-decade impact; I doubt there will be a material change in bad weather in the next 10 years to drive a change in booking although perception might change faster. (Taxing airline fuel/flights more heavily which you posit as the alternative to a cruise for some might be an offset that comes sooner!)
I live in a south coast cruise-ship city that is winning business in the huge cruise market. £SAGA's 2 x1000 bed ships barely scratch the surface of the volume and its ships are specifically designed for the Uk-based elderly rich. Its a good niche.
My simple thought therefore would have been that if Saga are near or at capacity, the first thing they should do is squeeze up on pricing / drop discounts. I agree that we have a generation of rich elderly sitting on unearned housing wealth who have always spent freely on themselves. No sign of cruising going out of fashion for them. The % of customers that Saga claimed as paper millionaires staggered me (apologies cannot find the exact quoted figure)
If they are doing well, the partnership offer had better be good otherwise it is giving away the upside when the ships are newest - or they are under more financial pressure than they let on. I would have preferred if they had managed to sell the part of the insurance business which was on offer.
I have held since before Covid and the return to normal on interest rates. I still think the group will do OK but the gain is much less now. As ever, only time will tell.
Has anyone else never changed the filters on top of the comments, or is that just me?
Latest and unthreaded saves a lot of scrolling!
Not just you. I've only just realised that clicking the blue comments count at the top of the page automatically scrolls you down past Paul & Graham's reports to the comments.
Isn't that interesting! Thank you for sharing that information. Despite working in UI design, I never knew about this. It reminds me of an old concept called 'discoverability,' where functionality exists but remains unused because people aren't aware of it. I've been using Stockopedia for years, and I never thought to click on that link
I hasten to add that I only scroll past Paul and Graham's reports after I have already poured over them in great detail. Vital insights.
It may also be worth noting that if you've read this page earlier and come back later to see new comments this is what I do. I go to the Discuss sidebar to select Discussions - All Posts/SCVR then on the right hand side by this page title you can see the number of unread comments on the far right hand side. I click on this number and it will take me either straight to the unread comments or at least half way day the page so I'm closer to the unread comments. (Doesn't work every time but more times than not.)
Good morning Paul,
Is it possible to add Lords Trading (LON:LORD) and their FY23 update to the backlog please?
Having previously been flagged as a result of the CFO leaving, there doesn't appear to be any nasties in the update? I think it actually looks quite cheap if these are trough earnings and theres some decent progress on net debt.
Quite an interesting interview with the CEO on VOX- he comes across as pretty sensible and quite boring- which I like!
Also, a monumental effort from the SCVR team this week with all the updates- many thanks!
Superdry (LON:SDRY)
Probably not a lot of interest left in Superdry apart from a bounceback short term trade but they seem to have slipped out their H1 2024 numbers under the radar and the CFO resigns. I cant post a link but it is on the Stocko news page.
Record (LON:REC) had a good Q3 update today with AUME almost at US$100bn showing growth and positive net flows, albeit some internal switch to lower margin products (passive hedging). Much better than Q2. Infrastructure fund being worked on for launch this quarter, but always some risk of delay.
Agree TopVest, looks like they are doing well under the CEO elect Jan Witte following the retirement of Leslie Hill. (I hold)
I was relived to see quite a good update from Record (LON:REC) . After the large fall the day before I was worried some bad news had leaked but thankfully all seems okay. I was looking at the net inflows over the last four quarters and the latest sees a huge jump (US$: 2.5bn, 1.5bn, -1bn, 7.9bn) . As Charles mentioned yesterday, it would seem the retirement of Lesley Hill has not adversely impacted the firm. (I hold).
Decent update from Learning Technologies (LON:LTG), margin improvement, in line abd net debt slashed. Might be in for a trade here
System1 (LON:SYS1) gross margins of almost 90% mean there is spectacular operating leverage here . the broker put through a 12% upgrade to revenue which led to a 50% upgrade in EPS for FY25. Even after the upgrades Cannacord are still only forecasting a modest 13% revenue growth for FY25, if they were to maintain the current growth rates for a few years, EPS will go parabolic. The consultancy side of the business may also stabilise at some point, which would make the growth rate from the platform side more apparent
It was only two years ago that the founder, John Kearon was trumpeting that one day the business might have a market cap of £1 billion or so but the real progress with ad testing has come since they installed James Gregory.
If the business really demonstrates that kind of potential, or even a small fraction of it, then maybe the likes of WPP (LON:WPP) might have to try to get control if only from a self preservation point of view. After all, if you’re an agency, you don’t want your clients telling you that the ads they’ve been buying from you are ineffective. Unless System1 is already working with them of course? Or are big agencies developing their own versions of ad testing? Could go one of several ways.
For clarity, I have held for a while, (since before the name change from Brainjuicer!) and relieved that good progress is now being made -almost back up to my average buying price! Yay! Asti Spumante time -but not Champagne.
As I've worked in marketing for years, I'll add my two cents here.
Large advertisers (and their agencies) have always done ad testing. However, these were more expensive, as done with real customers. This, in fact, is what System1 (in previous names) has done for advertisers historically. Hence why they have this database of how good ads are, over decades. They have then used this historical database of ad performance, to train a DS / ML model to predict the efficacy of a new ad fed into the model.
Because it is now so cheap to do this machine-based Ad Testing, agencies can then feed their draft ads through Test Your Ad, get a score and sense of what is weak. Go back to their video designers and get it tweaked to perform better. Iterate, iterate, iterate and voila, you have a good ad ready to go out to market.
I'm surprised System1 (LON:SYS1) hasn't jumped on the bandwagon of labelling themselves an "AI company". Or maybe they will soon...
I've also had the pleasure of directly working with James Gregory, years ago. Back then he was more junior. I believe this is his first c-suite gig. So well done on him.
(I hold in the Boon Fund)
Treatt (LON:TET) has been affected by a general slowdown in the chemicals market. But flavourings industry leader Givaudan SA (SWX:GIVN) put out an encouraging report yesterday which suggested the destocking that had been ailing the market was coming to an end. Where they lead, Treatt ought to follow. More pertinently Givaudan is on a PER of 33x, “expensive” Treatt is on 20x
Also in flavourings, Fevertree Drinks (LON:FEVR) chairman dipped into his own pocket to the tune of a cool half million. I bought earlier this month hopefully anticipating that the similar disruptions plaguing this former market darling are subsiding. Shares are hard to value but the US growth - now no.1 in ginger ale and tonic - is compelling.
Fevertree Drinks (LON:FEVR)
I have been a big fan of fevertree in the past (used to be my largest holding but i presently have none) - i have been waiting for the tide to turn in their favour the last couple, of years since selling out. I might miss out when things do start to pickup as things stand - the financial woes they have had imho very much mask the good underlying progress they have made ref "worldwide brand" - so at some stage i would expect profits to materially bounceback and revert to how it used to be - where extra sales all fell through to the bottom line to soem degree - in that regard its all been a bit of a disaster financially - world domination aint easy thats for sure.
Its crazy how they have gone from capital light money making machine with £170 mill sales and £45 mill profit to £420mill sales and making less profit !!
In some respects i am surprised there hasnt been a hostile bid here - perhaps the chairman here may be "lucky" with their share purchase.
Did Fevertree Drinks (LON:FEVR) ever cement their market leading position in premium mixers, and lock out the competition?
I think that is the answer why they are structurally making less profits now... they failed to keep their first leader advantage of fat margins, and now its just another commoditised product area with multiple brands all offering similar.
Posh bars and restaurants wanted a premium mixer. But they weren't particular it was a Fevertree mixer.
Did Fevertree Drinks (LON:FEVR) ever cement their market leading position in premium mixers, and lock out the competition?
ref tonic yes - ref mixers in general no. One resounding yes and one little progress.
I would say ref Tonic they are now the Applr/Google of Tonics - so i would have to say in that regard 100% yes , ultimately an investment now while pe is high is as likely to return well with buisness sale as it is with profits catching up so that p/e is good value - thats probably 5 years away.
Fevertree have also done a fantastic job with ROW sales - uk sales are already below 1/3 of total sales now so that company has moved on fantastically ij that regad. Ultimately this is partly where the problem with lower profits stem from imho to grow in far flung places you cant expect to make anything like the same margins they did when they took over the uk marketplace - well certainly not until you are nearing maturity in that marekt.
Note there are other issues like price of glass beig really high blah.
Whether they will keep the market lead have clearly cemented (imho) is another thing - there are plenty of fevtree mini me brands about now - so the danger here aint scheweppes its one of the mini me copycat brands muscling in on their territory - in that regard i suspect medium term they need to keep pricing keener than they did as with stuff like this you could price yourself out of the leading position/business if you are not careful. Ref tonic though i think they are clearly the leading brand and i dont see that changing anytime - think its 2 years since they overtook schweppes in the us and they stail managed to report 25% plus growth us per last results.
What i am not as impressed by is their foray into other lines that i thought could perhaps push the business on more than they have acheived - perhaps that takes time though and the more they grow sales the more customers they have that can try associated stuff so that probably becomes easier when they are a truly worldwide mature number uno tonic brand.
Note its probably a couple of years now since i sold out (thankfuly price was significantly higher then ) so i havent ben paying as close attention as i used to so any of my thoughts above could be outdate or plain wrong - i aint no expert in tonics other than having watched the growth of the brand the last few years - in that rspect i was far too late investiong in the first place - slightly annoyed at myself in that regard bearing in mind how much time i spend pubs !
Record (LON:REC) pleasing update this morning especially after yesterday's SP drop. (I hold)
My morning smallcap tweet: Coral Products finds orders somewhat plastic, bins dividend
Motorpoint (LON:MOTR) Active Energy (LON:AEG) Chill Brands (LON:CHLL) Saga (LON:SAGA) Wickes (LON:WIX) On Beach group (LON:OTB) Coral Products (LON:CRU) Thruvision (LON:THRU) Dar Global (LON:DAR) CT Automotive (LON:CTA) Stelrad (LON:SRAD), Avon Protection (LON:AVON), Learning Technologies (LON:LTG)
◄Motorpoint (MOTR)► warns FY-Mar profit £5m-£6m below expectations due to continued falls in used car prices. Stabilised in Jan. Guides FY25 in line. To buyback up to 5% of shares. [SP=98 Cap=88m]
◄Active Energy (AEG)► disaster as discussions to sort out delays with mfr of its Coalswitch reference plant, Player Design, fail. Latter says its no longer willing or able to commit to contract terms for production date or volumes. AEG retains ownership of some of the production equipment and components being used in the construction of the plant. [SP=1.66 Cap=3m]
◄Chill Brands (CHLL)► £1.2m placing at 3.75p, an 11% discount. to support further growth. Also repays £1.2m debt with shares at 3.75p. "Uptake of our Chill vape products continues to exceed expectations and sustained demand for reorders from our current independent retailers is a clear indicator that our products are resonating well with consumers." What a winner! [SP=4.1 Cap=18m]
◄SAGA (SAGA)► re media speculation: exploring a "partnership arrangement for Ocean Cruise...to move to a capital-light business model to support further growth and crystalise value, reduce debt and enhance long-term returns for shareholders." Ships operating at close to capacity. [SP=146.8 Cap=208m]. I hold.
◄Wickes (WIX)► guides FY-Dec LFL rev flat. Adj pretax "at the upper end of market consensus [sic] range of £44.9-£48.3m". Current Q1: expects delivered sales to be down. How much? [SP=144.9 Cap=363m]
◄On the Beach (OTB)► AGM stmt: FY24 TTV so far up 27%. Co has "has taken the opportunity to price competitively and focus on volume growth" so expects FY profit in line. [SP=164 Cap=273m]
◄Coral Products (CRU)► the plastic product co warns FY rev c. 10% down so profit will be below management and market expectations. Blames customers deferring re-stocking. Cancels H1 div previously announced. [SP=17.5 Cap=16m]
◄Thruvision (THRU)► wns £1.3m of orders for delivery in H2. Guides FY rev in line. [SP=18.5 Cap=30m]
◄Dar Global (DAR)► guides FY-Dec rev $340-360m and EBITDA $80-85m. Consensus is $250m and $62m resp. That's a huge beat. Surely co could have upgraded sooner? [SP=$3.76 Cap=$650m]
◄CT Automotive (CTA)► guides FY-Dec rev $140m+ and U/L pretax c.$8m. In line? Outlook - healthy order volumes. Red Sea shipping situation: no material impact, continues to maintain buffer stocks to mitigate any short-term disruption. [SP=64 Cap=47m]
◄Stelrad (SRAD)► guides FY-Dec rev down c.3% and c.13% LFL. However adjusted operating profit in line with expectations of £28.5m due to price and cost management. [SP=128 Cap=163m]
In line: AVON, LTG
A placing (bookbuild) by Phoenix Copper (LON:PXC) at discount to current sp. I sold out quite a while back (at a small loss) but still monitoring for possible entry point. Are there any holders here at present? I would be interested to hear your views.
I am still holding on although have a relatively small position. Donald Pond is the person who represents Phoenix Copper (LON:PXC) here so hopefully he will give an update . Funding still a major issue .
I’m still holding my Phoenix Copper (LON:PXC) shares and considering participation in the retail offer.
The board have lost a lot of goodwill amongst shareholders currently. The sticking point is funding for the mine. In the last 12 months, we’ve been led to believe that this funding was imminent. Alas, still not forthcoming.
Donald Pond has confirmed that funding is close. A Bonds Issue has already been prepared. If it gets confirmed, I’d like to hope that the share price will recover quite quickly towards 30p.
I think the problem I have (as a holder also) is that the bond funding has been promised as being "close" for quite some time. There was an RNS issued on 24 March 2023 saying that "The Company is finalising discussions with a number of parties with a view to
placing up to $80 million of corporate copper bonds, which were initially
announced on 8 June 2022". The announcements before Christmas referring to two week extensions in respect of the non-convertibility aspect of the Riverfort loan facility sent clear signals that completion of the bond issue was imminent, which has proved not to be the case.
I entirely agree that if the bonds are placed and the Riverfort facility rolled over, the share price should increase significantly. However, given the fact that they have been unable to get the bonds away so far and since I am presently sitting on a large paper loss, I am hesitant to potentially 'put good money after bad'.
Strong update by On Beach group (LON:OTB)
"Winter '23 TTV is currently 34% ahead of the prior year and current trends continue to give the Board confidence that Summer '24 will be significantly ahead of Summer '23."
Good to see them quote analyst consensus:
Based on company compiled consensus ("Consensus") from ten contributing analysts. Consensus FY24E Adjusted PBT is £30.0m.
Full statement- https://www.investegate.co.uk/...
Ties into the discussion yesterday, they have had to reduce margin to stay on target for profit and focus on higher end 5* and long haul
On Beach group (LON:OTB)
"with B2C 3*, 5* and long haul each delivering year to date
growth. B2C 3* TTV is +8%, B2C 5* TTV is +41% and B2C long haul TTV is +86%
versus the equivalent period in FY23"
Their B2B offering is a tough one as I'm not sure why agencies would support an OTA when there are plenty of pure B2B operators offering the same pricing/product.
I wish you could edit a post on mobile ...
Just to clarify in an OTA meta space it's very price sensitive and the quickest way to increase TTV is to reduce margin. Best price wins
On Beach group (LON:OTB)
I wish you could edit a post on mobile ...
You can on iPhone. Try turning your phone on its side.
Ahaa on android too! Thanks.
I thought ‘gamechanger!’ - but it doesn’t work on my iPhone
You may find that you have the lock applied which stops the screen rotating when you move from portrait to landscape. There is a rotation lock button on the pull down where you change brightness, turn on the torch etc.
Thanks, KevinS1, and I didn’t know about that… but it isn’t that. The screen rotates, but the edit pencil doesn’t appear.
Note to self: if it’s a good year, buy a new handset. One that does the fancy stuff my kid’s phone does.
I like the new “unread comment box”. I assume it’s new and I haven’t been very unobservant! :)
If you mean comments you haven't read are in a red box, then sorry to say it's been there years.
Morning Bob, where is this 'red box' for unread comments please? Can't see it on my screen anywhere. Thanks
Here is a screenshot a picture saves a thousand words
Don’t get that on my feed
Thanks - works in unthreaded but not threaded feed.
Nor me. Used to be a red line but it’s disappeared in last few months
I’ve always had a box since I switched to the unthreaded view.
What’s the unthreaded view ?
On my screen you can choose between unthreaded and threaded on the drop down box
Saga (LON:SAGA) floats idea of selling stake ocean cruises arm
https://news.sky.com/story/sag...
As usual Sky News breaking the story. How do they get such inside info legally?
This could reduce debt and allow the same profits to be made. An interesting consideration.
Profit expectations are starting to creep up slightly.
The upcoming trading update will be interesting.
Appears to be something that many businesses do, sell and lease back - perhaps this is what the elusive Eldose Babu is seeking to do?
I hold, at a loss - but the chart looks promising.
Saga plc
Response to Media Coverage
Saga plc (Saga or the Group) notes recent media coverage. Saga is committed to providing best-in-class products and services to its customers across all its businesses. The Board is exploring opportunities to optimise Saga's operational and strategic position in Cruise, where exceptional demand for its boutique ocean cruise offer means it is operating at close to capacity. It has concluded that a partnership arrangement for Ocean Cruise would be consistent with Group strategy to move to a capital-light business model to support further growth and crystalise value, reduce debt and enhance long-term returns for shareholders.
No decision has yet been made and there can be no certainty that any partnership agreement will occur. A further announcement will be made in due course, as appropriate.
Slighly confused about this. I thought the plan was that post covid the cruise ships would be cash cows and throwing off cash, making it easy to service this debt. Load factors for the cruises seem to be near maximum so they should be in a sweet spot right now.